Category: Research

Retail News Asia is committed to providing both local and global retailers with the latest Research throughout the Asian market. This on a daily base.

  • Global AI Data Centre Spending to Hit Thirty Trillion Dollars by 2050

    Global AI Data Centre Spending to Hit Thirty Trillion Dollars by 2050

    Cumulative global spending on artificial intelligence data centres will reach 30 trillion dollars by 2050, exceeding the capital poured into any previous technological transition in modern economic history.

    That outlay projection from PwC puts infrastructure commitments on par with the entire market value of outstanding United States Treasuries. The scale of investment eclipses the capital deployments seen during the nineteenth-century railroad expansion and the late-1990s internet boom, even after adjusting for historical inflation.

    The Capital Equation for Infrastructure

    Tech companies and sovereign funds are committing capital to server capacity, specialised chips, and power generation at a pace that demands rapid commercial returns. The sheer volume of hardware spending means enterprise software buyers now face pressure to prove that automation cuts operating costs faster than the infrastructure depreciates.

    Data centre developers are also running into physical bottlenecks across regional power grids. In major markets, server farms are competing directly with residential housing sectors for high-voltage electricians, base-load electricity contracts, and industrial water allocations required for cooling compute clusters.

    Cost Shifts Across Enterprise Operations

    Corporate adoption is altering cost structures across regional businesses, though initial savings frequently push expenses into other parts of the balance sheet. In retail and supply chain operations, automated inventory tracking and customer service systems reduce direct headcount while increasing technical compliance and software licensing overhead.

    The labour impact has hit external service providers first. Enterprise data compiled by fintech platform Ramp shows companies that spent heavily on freelance contractors cut those budgets by 97 per cent after switching task workflows to generative software. The transition eliminated costs for translation, graphic design, and basic coding without requiring formal corporate restructurings or severance payouts.

    Dispute Volume and Operational Frictions

    Lower barriers to generating technical and legal text are creating fresh operational strains for regulators and public tribunals across the Asia-Pacific region. Australian legal services provider Maurice Blackburn noted in regulatory filings that automated tools alter access costs across the market.

    “AI will let law firms deliver high-quality services at scale,”

    Cheap generative drafting has also driven an influx of poorly verified submissions into administrative bodies. Australia’s Fair Work Commission has recorded an increase in automated unfair dismissal filings, forcing public registries to allocate extra staff time to screening low-quality claims.

    Consumer Agents and Capital Allocation

    New consumer tools are targeting deposit inertia at traditional financial institutions. Meta has introduced its Muse personal assistant, designed to help retail users automatically identify higher-yielding non-bank deposit alternatives and shift balances out of standard accounts offering sub-one per cent returns.

    These consumer-facing agent deployments mark the next phase of enterprise software rollouts following two years of pure model training and server farm buildouts. The Australian Parliament’s Joint Select Committee on Artificial Intelligence is scheduled to deliver its final findings on regional economic impacts in November 2026.
  • Philippine Factory Activity Slips to 49.6 in September

    Philippine Factory Activity Slips to 49.6 in September

    Philippine factory activity contracted in September as the Purchasing Managers’ Index fell to 49.6 from 54.9 in August, according to survey data from S&P Global.

    The drop below the 50-point line separating growth from contraction marks the sector’s first downturn since April.

    Sharp Drop Across Output and Orders

    Data from roughly 400 manufacturing companies across the Philippines showed simultaneous declines across production, new business, export sales, and factory payrolls. Production volumes registered their steepest fall since November 2025, halting a sustained summer run of operational growth.

    Higher input expenses squeezed producers throughout the month. Rising global crude oil prices, spurred by heightened geopolitical friction between the United States and Iran, drove fuel and transportation costs upward and quickly eroded manufacturing margins.

    “Filipino manufacturers reported a notable impact from high oil prices, strong international competition and weak demand during September. Output, new orders and employment all dropped into contractionary territory,” said Siân Jones, principal economist at S&P.

    Inventory Run-Downs and Slower Buying

    Factory operators responded to cooling client demand by slashing their purchasing activity and depleting existing warehouse inventories rather than placing fresh component orders. That shift into defensive retrenchment creates immediate headcounts and volume challenges for industrial suppliers across Southeast Asia that feed Philippine assembly lines.

    For retailers and consumer brands relying on domestic finished goods, production cuts threaten inventory availability ahead of the fourth-quarter holiday sales rush. Consumer goods firms face a dual squeeze: paying more for freight while encountering price resistance from households managing broader inflationary pressures.

    Reversal of Peak Expansion

    The sudden slump reverses a period of rapid industrial growth that lifted the Philippine PMI to near decade highs in August. Factory output expanded steadily through the middle of the year after an earlier soft patch in April, supported by domestic order books before overseas competition and energy shocks altered buying patterns.

    Industrial buyers across Metro Manila and surrounding manufacturing hubs now track fourth-quarter export bookings and regional energy price movements to gauge whether output stabilizes before year-end.

  • Only 50% of Australian Loyalty Program Members Actively Use Accounts

    Only 50% of Australian Loyalty Program Members Actively Use Accounts

    A record 93 per cent of Australian consumers hold loyalty memberships, but only 50 per cent actively used all their cards over the past 12 months, according to a 2026 survey by consultancy The Point of Loyalty.

    The Australian loyalty program market is expanding by 13.5 per cent annually toward a valuation of $1.57 billion in 2026, as rising living costs push shoppers to seek savings.

    The Scale of Inactive Accounts

    A survey of more than 800 customers across Coles, Woolworths, Aldi, IGA and FoodWorks by Edith Cowan University researchers examined why consumers join retail reward programs only to neglect them.

    Researchers Sanjit K Roy and Saalem Sadeque from Edith Cowan University found financial rewards alone fail to retain active users. Fatigue sets in quickly when redemption rules require high baseline spend, such as outlays of $2,000 to earn a $10 voucher. Shoppers abandon programs that demand excessive tracking or complicated checkout app interactions.

    Supermarket Duopoly Dominance

    Two major operators control most of the domestic membership base. Woolworths counts 14 million registered accounts in its Everyday Rewards network. Coles reports more than 9 million active members in Flybuys, which links grocery baskets with Wesfarmers-owned chains including Bunnings, Kmart and Target.

    For retail operators across the Asia-Pacific region, these enrolment numbers look impressive on paper but mask balance sheet liabilities. Unredeemed points sit as deferred revenue obligations. Inactive accounts generate zero incremental basket value. Rivals that rely on upfront shelf discounting, such as ALDI, continue to capture price-sensitive volume without funding complex points administration.

    Trust and Data Exchange

    Shoppers surrender personal details, contact lists and payment patterns in exchange for program benefits. When retail pricing feels opaque or discounts appear trivial, participation drops immediately.

    The university study identified three distinct operational levers that dictate whether a member remains active: institutional trust, relationship commitment and clearly visible return value. Programs that fail to send targeted offers lose out to straightforward discount mechanics. High-frequency users expect direct discounts on regular purchases rather than generic promotions on slow-moving inventory.

    Friction in Reward Redemption

    Security concerns also weigh on consumer willingness to maintain secondary retail memberships. Major corporate data breaches across Australia over recent years raised shopper scrutiny regarding who stores their purchase histories and contact records.

    Competition will test whether broad coalition ecosystems hold an advantage over single-banner apps. Flybuys relies on cross-category earning power across home improvement and department store networks to keep accounts active. Woolworths counters by integrating fuel, insurance and pharmacy tie-ins directly into its digital wallet ecosystem.

    Supermarket executives will watch the active redemption rate per registered member as annual retail data filings land later this year.

  • Indonesia Cyber Attacks Inflict US$6.2 Billion in Losses This Year

    Indonesia Cyber Attacks Inflict US$6.2 Billion in Losses This Year

    Cyber attacks caused an estimated US$6.2 billion in financial damage across Indonesia during 2026, Bank Indonesia Governor Destry Damayanti announced in Jakarta on Thursday.

    Central bank officials linked the losses directly to automated tools and artificial intelligence. These technologies multiply payment fraud, scam operations, and data theft across consumer networks.

    Surging Risks in Digital Payments

    Destry urged government ministries and commercial agencies to tighten payment security standards and enforce direct consumer protections. The central bank holds the statutory mandate to supervise and develop the country’s payment infrastructure.

    Digital networks expand domestic economic output. Still, the governor warned that interconnected systems leave merchant acquiring channels and retail banking endpoints exposed to automated intrusion. Joint security literacy programs with the Financial Services Authority are planned to train consumers and retail operators.

    ISP Group Pushes Security Bill

    Backing the central bank’s warning, the Indonesian Internet Service Providers Association (APJII) demanded swift passage of the Cyber Security and Resilience Bill. Commercial internet providers require uniform technical standards and legal clarity to defend national digital infrastructure against automated threats, according to APJII Chair Muhammad Arif.

    “Indonesian service providers need legal certainty to grow, not disruptive regulations,” said Arif.

    Monitoring data from APJII tracked 246.4 million connections to dangerous IP addresses between June 13 and August 28, 2026. A separate three-day network scan by the association recorded roughly 68 million distinct cyber attack events targeting domestic routes.

    Direct Pressures on Retail and Finance

    For retail merchants, digital lenders, and e-commerce platforms operating across Southeast Asia’s largest market, these financial losses raise basic operating costs. Acceptance of QR codes and instant transfer rails expanded rapidly over the past three years. Back-end defense budgets frequently lagged that growth.

    Platforms now face higher chargeback rates, elevated verification costs, and direct liability when account credentials leak. Operators that fail to upgrade transaction authentication face friction at checkout. Financial institutions risk regulatory penalties if compromised channels disrupt daily settlement flows.

    Escalating Breach Scale Since 2025

    The US$6.2 billion tally reflects climbing attack sophistication following major infrastructure breaches over the previous eighteen months. Regional lender Bank DKI suffered repeated network intrusions that produced over US$15 million in irregular transactions, showing how attackers breach core accounting ledgers.

    Parliamentary debate on the Cyber Security and Resilience Bill now enters committee reviews. Enterprise software providers and payment processors are tracking whether mandatory incident-reporting rules will carry statutory fines before the legislative session closes.

  • 48% Of High-Income Australian Shoppers Plan to Boost Spending

    48% Of High-Income Australian Shoppers Plan to Boost Spending

    Nearly half of high-income Australian shoppers plan to increase retail spending over the next twelve months. In contrast, 43 per cent of lower-income households plan to cut purchases.

    Preliminary data from the OC and C Strategy Consultants Retail Proposition Index shows 48 per cent of affluent consumers expect to spend more across core categories. Only 24 per cent of lower-income buyers said the same.

    This divergence forces Australian retailers to rethink operating models built around uniform discounts. Affluent shoppers want differentiated services over price cuts. In the survey, 61 per cent said they would pay higher prices for superior quality or customer experience. Among lower-income shoppers, only 38 per cent said they would pay more for quality.

    Cost Cuts Collide With Customer Retention

    Widening spending gaps expose the limits of blunt restructuring programmes. Retailers that cut staff and trimmed inventories to protect margins in financial year 2026 often saw foot traffic and repeat visits erode.

    Endeavour Group, operator of Dan Murphy’s and BWS, delivered 70 million Australian dollars in cost savings during FY26. Total retail sales remained flat. Dan Murphy’s dropped 10 positions on the Retail Proposition Index between 2024 and 2026, showing that cost cuts without offer improvements damage market standing.

    Spending cuts alone cannot carry long-term earnings. Stripping labour or narrowing product assortment offers quick margin relief, but prolonged austerity damages shopper loyalty faster than executive teams anticipate.

    Reinvestment Separates Winners in Mass Grocery

    Woolworths paired restructuring with direct operational reinvestment. The supermarket major completed 400 million Australian dollars in annualised cost savings by the first half of FY26.

    Management channelled those funds back into entry-tier price points, shelf availability, and store convenience. OC and C survey metrics show Woolworths lifted its scores on both value for money and product range between 2024 and 2026, keeping customer retention intact while lowering overheads.

    Across the wider Asia-Pacific region, the contrast between Woolworths and Endeavour clarifies capital allocation rules. Removing administrative duplication or automating back-office workflows works only if freed capital protects the core customer offer.

    Loyalty Schemes Fail as Revenue Substitutes

    Reward programmes cannot substitute for competitive baseline offerings. Shoppers consistently ranked price, product value, and underlying quality above loyalty point balances when choosing where to make repeat purchases.

    Department store operator Myer expanded its Myer One loyalty programme to 5.3 million active members in FY26. Even with that larger user base, the company’s equity valuation stayed subdued as core store productivity lagged behind specialist rivals.

    Beauty specialist Mecca captured higher-spending shoppers by investing in store formats and physical services. Its flagship Melbourne store draws approximately 50,000 visitors every week by bundling product trials, consultations, and interactive brand stations into a single footprint.

    Operating Pressures Ahead for Retail Boards

    Executive teams entering the next financial cycle must manage two distinct consumer profiles simultaneously. Value chains need to defend entry price points and inventory availability for cash-strapped households. Premium brands must justify price tags through specialist staffing and exclusive assortments.

    Mid-tier operators that fail to pick an end of the barbell face the steepest risk. Retailers caught between rising store lease expenses and an indecisive store concept face margin compression from both sides of the income spectrum.

    OC and C Strategy Consultants will publish the full Australian Retail Proposition Index later this quarter, detailing brand rankings across department stores, apparel, and grocery.

  • Mecca and Sephora Among Beauty Retail Giants Outpaced by Online Marketplaces

    Mecca and Sephora Among Beauty Retail Giants Outpaced by Online Marketplaces

    Australia’s beauty retail landscape is undergoing a major transformation, with online marketplaces now generating as much revenue as all major specialist beauty retailers combined, according to a new report from global ecommerce accelerator Pattern.

    The 2026 State of Beauty & Personal Care in Australian Ecommerce report shows that Australia’s online beauty market is forecast to grow 47% to US$2.2 billion by 2030. The growing influence of marketplaces like Amazon is reshaping competition, generating approximately A$200 million in online beauty sales in Q4 2025, matching the A$199.3 million collectively reported by specialist beauty and health retailers, including Mecca, Sephora, Adore Beauty and Chemist Warehouse.

    “Australia’s beauty market is growing rapidly, but the balance of power is shifting. Marketplaces are now competing directly with the country’s established beauty retailers, while consumers are becoming less tied to traditional shopping channels and even their favourite brands,” said Merline McGregor, Managing Director for Pattern Australia.

    “While there is significant opportunity for beauty brands, there is also the risk of losing customers to competitors that are easier to discover and purchase online.”

    Influencers Reshape Beauty Product Discovery and Purchasing

    Social media is transforming the beauty shopping journey in Australia, with nearly half (47%) of beauty buyers more likely to purchase a product following a creator recommendation, compared with just 15% of non-beauty buyers.

    Instagram and Facebook each influenced 47% of beauty buyers to consider or purchase products in the past year, followed by YouTube (45%) and TikTok (38%). However, social media discovery is not necessarily translating into purchases on the same platform. When beauty buyers discover a product through social media, 39% say they would most likely purchase it directly from a retailer or brand website, while 32% would head to Amazon.

    “Beauty has become one of the most socially influenced retail categories, as consumers discover products through creators, watching demonstrations and researching ingredients long before deciding where to buy,” said McGregor. “But discovery and purchasing are increasingly happening in different places. A consumer might discover a skincare product on TikTok, research it on Google and then purchase it from Amazon. Brands need to connect these channels to turn consumer interest into sales.”

    Amazon Challenges Beauty Brand Loyalty

    Amazon recorded a A$66.7 million year-on-year increase in Australian beauty and personal care sales in Q4 2025, leading to the marketplace now accounting for 19.9% of Australia’s online beauty market.

    Research also reveals that 71% of Australian online beauty buyers intend to purchase from Amazon in the next 12 months. However, findings uncover a growing challenge to brand loyalty as 43% of consumers say they are open to purchasing a similar product from a competing brand if their first choice isn’t available on Amazon.

    “Brand loyalty has traditionally been a major strength of the beauty industry, but convenience and availability are increasingly influencing purchasing decisions. When more than four in 10 beauty buyers are prepared to switch brands because they can’t find their preferred product on Amazon, that’s a significant commercial risk,” explained McGregor.

    “Consumers aren’t thinking about a brand’s distribution strategy. They simply expect beauty products to be available through the channels they use, and they’re willing to switch brands for that convenience.”

    AI Accelerates the Shift in Beauty Shopping

    AI is impacting the beauty shopping journey in Australia, with 38% of beauty buyers relying more on AI tools to discover products online compared with the previous year. More than a quarter (27%) have used ChatGPT or a similar AI assistant when researching or purchasing products, while 55% trust AI-generated product recommendations.

    “AI, social media and marketplaces are changing how consumers find, research and purchase beauty products. As online beauty sales surge in Australia over the next few years, the brands that grow will be those that understand how shopper behaviour is evolving across multiple touchpoints,” added McGregor.

    “A great product can only go so far if consumers can’t discover it, find credible information about it or purchase it through their preferred channels. Brands need to make themselves visible and available at every stage of the shopping journey to grow their share of Australia’s beauty market,” McGregor concluded.

    For more information and to download the full report, please click here: 2026 State of Beauty & Personal Care in Australian Ecommerce.

    About Pattern Inc

    Pattern accelerates brands on global ecommerce marketplaces leveraging proprietary technology and AI. Utilising more than 91 trillion data points, sophisticated machine learning and AI models, Pattern optimises and automates all levers of ecommerce growth for global brands, including advertising, content management, logistics and fulfillment, pricing, forecasting and customer service. Hundreds of global brands depend on Pattern’s ecommerce acceleration platform every day to drive profitable revenue growth across 60+ global marketplaces—including Amazon, TikTok Shop, Walmart.com, Target.com, eBay, Tmall, JD, and Mercado Libre.  For more information, visit https://au.pattern.com/

    Media Contact

    Paul Manser

    Mulberry Marketing Communications

    pmanser@mulberrymc.com

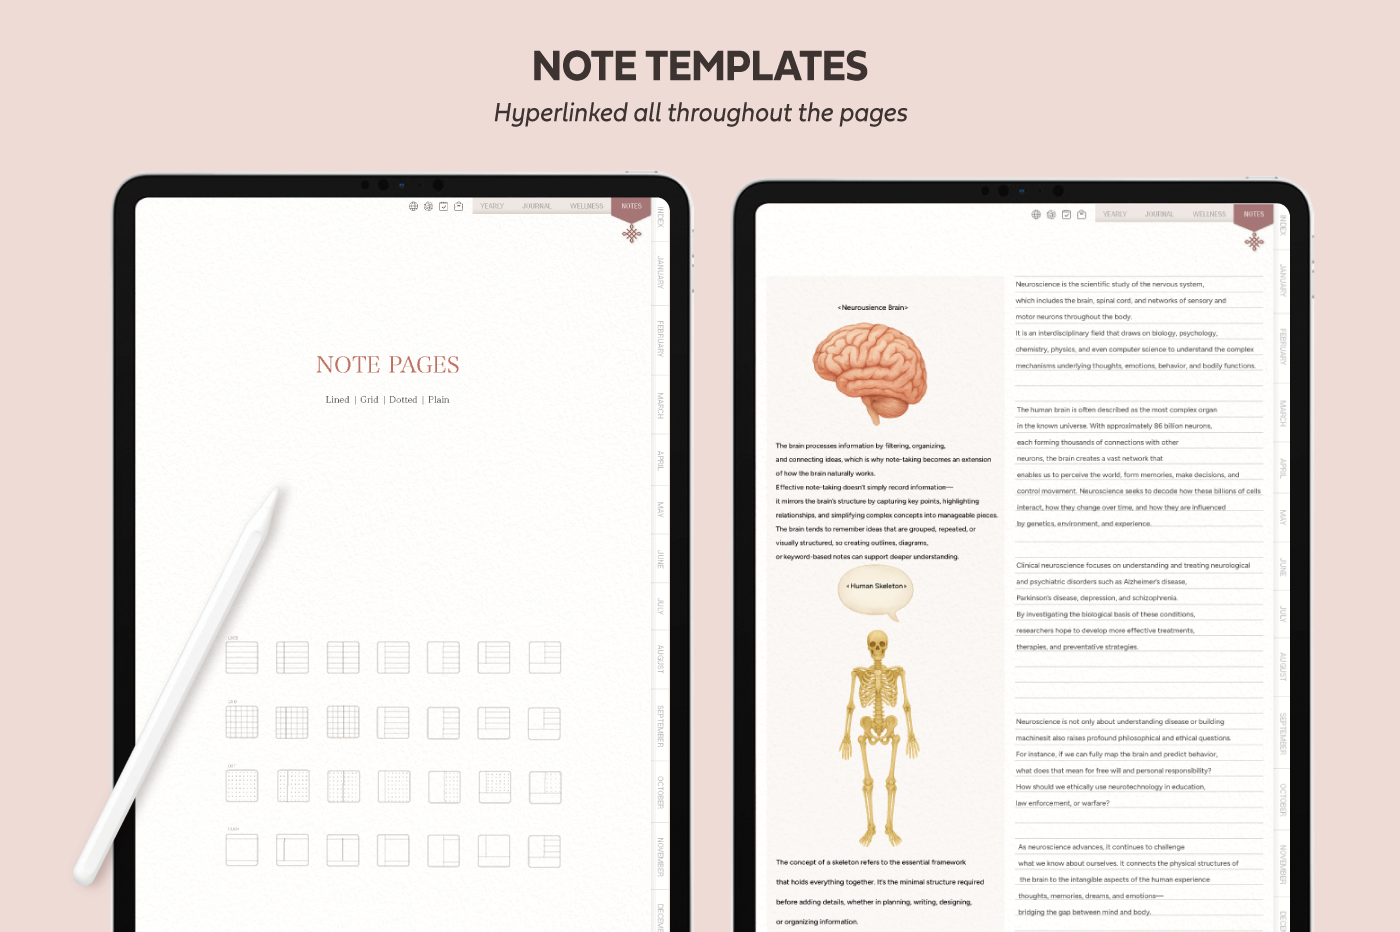
  • Global Planner Notebook Market to Grow 3.2 Percent Annually Through 2035

    Global Planner Notebook Market to Grow 3.2 Percent Annually Through 2035

    The global planner notebook market is projected to expand at a compound annual growth rate of 3.2 percent from 2026 to 2035, according to a report published by IndexBox in September 2026.

    Market value growth is set to outpace volume growth over the forecast period as consumers increasingly opt for higher-priced, benefit-led products, lifting the sector index to 137 by 2035 from a base of 100 in 2025.

    Asia-Pacific will remain the largest consumer market globally, supported by population scale and rising disposable incomes, while North America and Europe lead adoption across premium product categories.

    How Price Tiers Split the Retail Shelf

    The global retail landscape has split into two separate operating tracks. On one side sits a high-volume, commoditized mass-market segment dominated by supermarket distribution, back-to-school promotional discounting, and heavy private-label competition. On the other side is a high-margin premium segment where direct-to-consumer digital channels and specialty bookshops sell brand equity, lifestyle aesthetics, and tactile user experiences.

    Mainstream mid-tier brands face the sharpest margin squeeze. Mass merchandisers and drugstores continue to expand their private-label stationery assortments, undercutting standard branded notebooks on price. To defend gross margins, branded manufacturers are moving upmarket into benefit-led products that combine habit tracking, mindfulness prompts, and bullet journaling layouts that private-label lines struggle to replicate.

    North America holds 25 percent of the global market and Europe claims 20 percent, with both regions leading in average selling price. Latin America and the Middle East and Africa each represent 10 percent of worldwide consumption, where demand remains focused in urban centers and reliant on imported inventory.

    Supply Chain Decoupling and Manufacturing Shifts

    Production models have adapted to this bifurcated retail demand. Basic component manufacturing, standard paper milling, and entry-level binding stay concentrated across large-scale industrial bases in Asia, giving mass-market suppliers the scale required for low-cost volume contracts.

    Finishing, custom embossing, and high-spec packaging for premium lines are increasingly localized or handled through regional direct-to-consumer fulfillment hubs. This split allows stationery companies to manage raw material price swings in paper pulp and shipping freight while selling personalization features at substantial retail markups.

    Direct-to-consumer e-commerce acts as the main customer acquisition engine for specialized brands. Instead of relying purely on physical stationery retail, producers use online platforms to sell accessories, page refills, and digital courses alongside physical books, increasing lifetime customer spending and insulating margins from distributor cuts.

    Japanese Makers Set the Standard in Asia

    Stationery brands in Japan, China, and South Korea have built strong domestic followings that now drive export volume into Western markets. Japanese producers such as Hobonichi, Kokuyo, and Muji established early commercial footholds by treating daily planners as cultural staples rather than basic office supplies.

    Hobonichi built a global cult following around its daily techo planners, proving that premium paper quality and functional layout design command high overseas shipping premiums. Western players like Moleskine, Leuchtturm1917, and Erin Condren must now compete directly against Asian precision stationery brands across both physical specialty stores and international e-commerce marketplaces.

    Digital substitution remains the primary operational threat to paper planners, especially among younger demographics who rely on free smartphone calendar applications. Successful stationery makers counter this attrition by positioning paper as a tactile digital detox tool, while introducing hybrid products featuring QR codes, app syncing, and scannable templates.

    Historical Groundwork and Category Benchmarks

    Between 2012 and 2025, stationery manufacturers weathered repeated waves of digital calendar adoption by transitioning away from utilitarian office pads toward lifestyle and personal productivity systems. That commercial pivot established the pricing tiers that now govern the retail trade.

    Corporate procurement has also stabilized around hybrid work arrangements. While enterprise software handles shared team scheduling, corporate gifting and branded desk merchandise continue to provide steady contract volume for high-end notebook makers.

    Category operators are now locking in their product catalogs and channel allocations for the next academic and calendar cycle, with brands watching whether raw paper input costs stabilize before committing to wholesale discount schedules for 2027.

  • 85 Percent of Consumers Cut Spending After Poor Service, Genesys Finds

    85 Percent of Consumers Cut Spending After Poor Service, Genesys Finds

    A survey by software company Genesys found that 85 percent of consumers globally have either spent less with a brand or stopped buying from it after experiencing poor customer service.

    In the Philippines, a 2025 study by market research and analytics firm Milieu Insight revealed that 55 percent of online shoppers are more likely to buy from sellers who communicate responsively and provide timely updates.

    Top service rankings across retail and hospitality

    Okada Manila, Grand Hyatt Manila and Dior led the overall rankings in the Philippine Daily Inquirer and Statista Philippines’ Best Customer Service 2027 study, which evaluated 306 companies across 78 categories based on more than 90,000 customer assessments.

    Customer recommendation rates drove half of each brand’s overall score. The remaining weight evaluated five touchpoints: system accessibility, customer focus, clear communication, professional competence, and the range of services at checkout and post-purchase resolution.

    The cost of automated service breakdowns

    Automated support systems create retention risks when software fails to track customer history across channels. Twilio research shows 73 percent of Filipino consumers encounter automated systems that lose earlier context.

    Losing that thread carries a direct cost. When bots drop conversational history, 73 percent of affected local shoppers abandon them to find human staff or cancel the purchase. For 4 percent, repeated technical friction prompted an immediate, permanent exit from the brand.

    Operational shifts for Southeast Asian merchants

    Philippine store operators and e-commerce platforms must treat support infrastructure as core merchandise rather than back-office overhead. Merchants who replaced floor staff and help desks with uncalibrated bots face rising cart abandonment.

    Most friction occurs during the handoff between automated triage and live resolution. Front-line human agents remain essential for complex order disputes, returns, and luxury transactions where automated workflows fail.

    Tracking service metrics into 2027

    A divide is widening between premium operators with dedicated channels and discount platforms relying on automated scripts. Tracking retention rates and first-contact resolution speeds will determine which Philippine retail chains hold market share through 2027.

  • Gleneagles Hospital Completes Hong Kong’s First 2 Histotripsy Cancer Trials

    Gleneagles Hospital Completes Hong Kong’s First 2 Histotripsy Cancer Trials

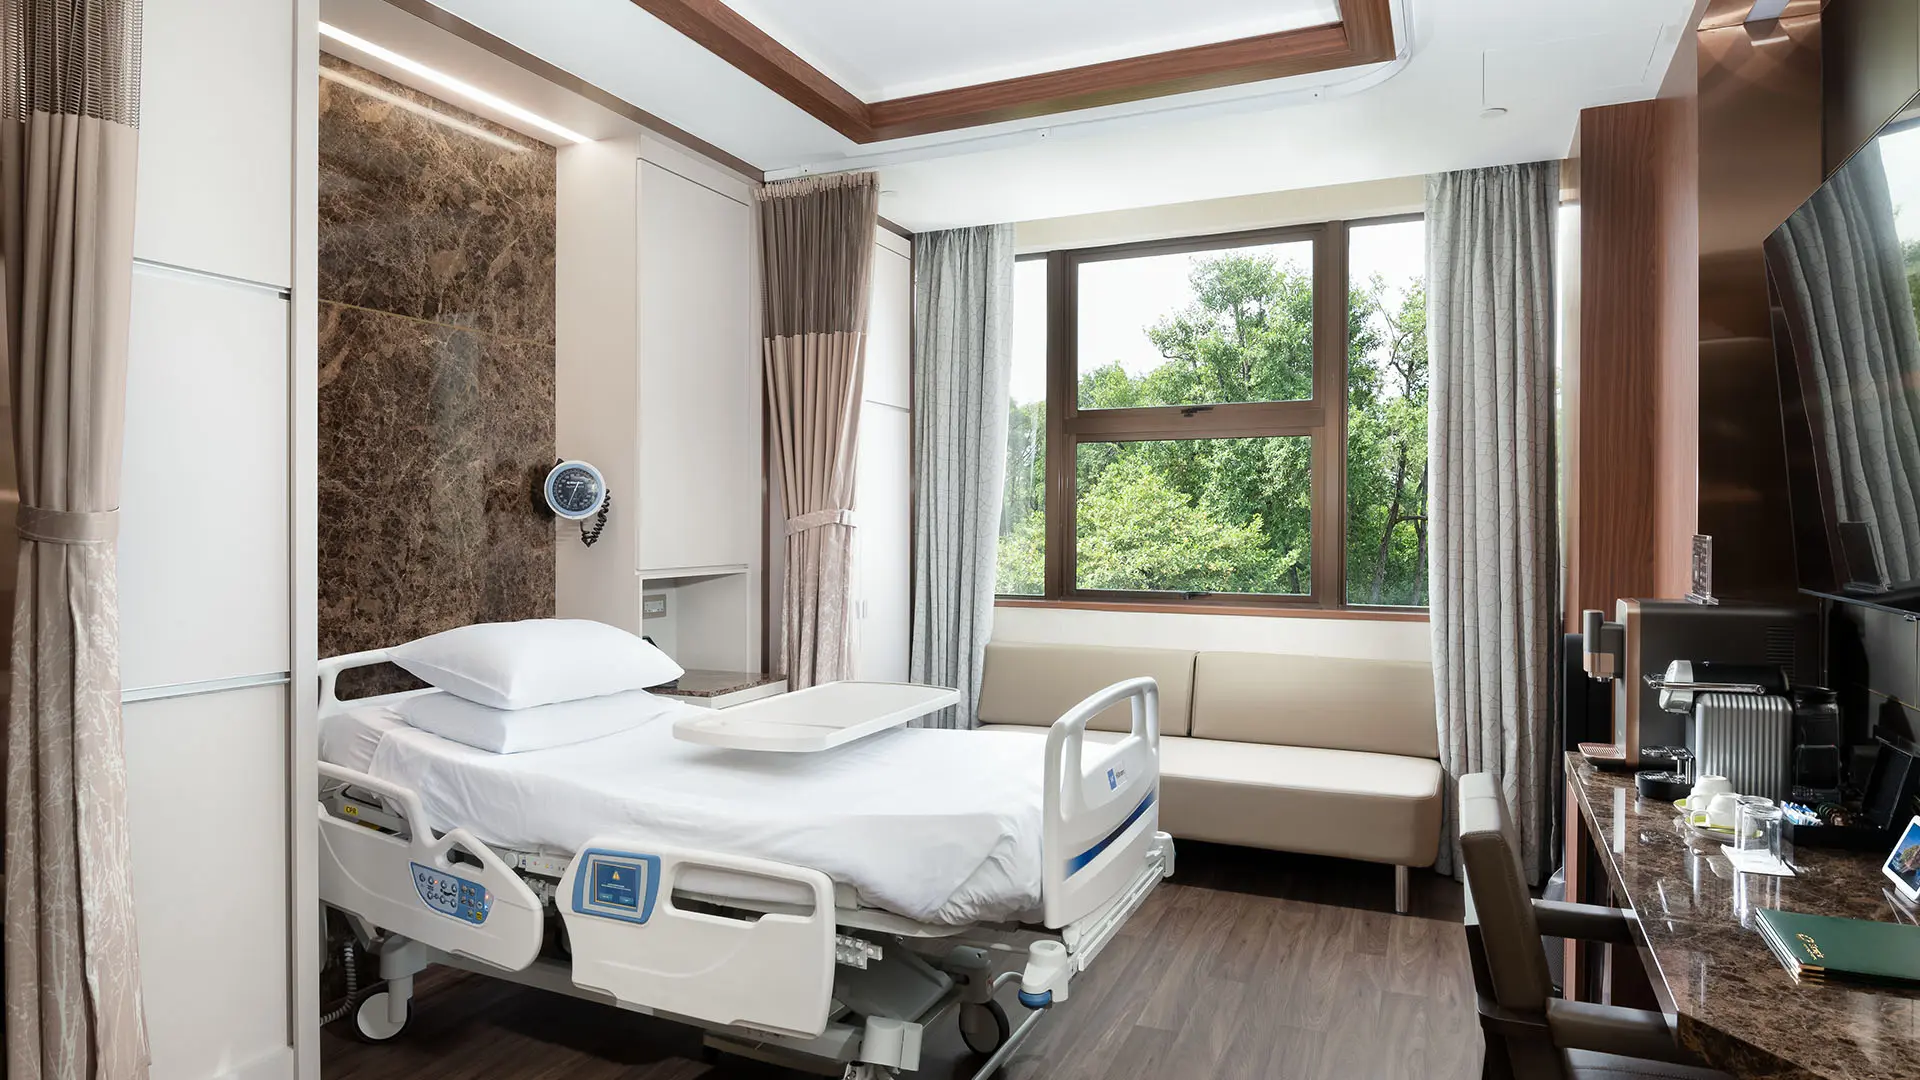
    In April, Gleneagles Hospital carried out Hong Kong’s first two clinical trial procedures using histotripsy to destroy pancreatic cancer tumours in patients for whom conventional surgery was unsuitable.

    In one case, doctors targeted both the primary pancreatic tumour and cancer that had spread to the liver during the same procedure using precisely targeted sound waves.

    Clinical rollouts and equipment targets

    Dr Neal Kassell, founder and chairman of the US-based Focused Ultrasound Foundation, estimated that clinical trial results for pancreatic and brain cancers could emerge in about three years, predicting global machine deployments could rise from roughly 2,000 to 10,000 systems within five years.

    Clinical evidence covers 196 potential medical indications across neurology, oncology, and pharmacology, according to data from the Focused Ultrasound Foundation. Twelve of those indications advanced to first-in-human clinical trials last year. More than one million patients have received focused ultrasound therapies globally to date, with annual treatment volumes reaching approximately 75,000 cases.

    Treatment pricing and hospital economics

    Hospital operators face steep upfront hardware costs and slow physician onboarding. In Hong Kong, treatment access relies heavily on private philanthropy to bridge gaps in public health insurance. Eligible liver cancer patients receiving histotripsy at Gleneagles pay HK$50,000 (US$6,374) under a subsidy funded by the Li Ka Shing Foundation.

    Specialist consultations and preliminary liver ultrasound assessments add between HK$4,300 and HK$5,400 to out-of-pocket patient expenses. Without formal public reimbursement or standardised private insurance schedules, hospital adoption across private healthcare chains in Southeast Asia and East Asia remains confined to flagship research centres.

    Overcoming the blood-brain barrier

    Beyond thermal and mechanical tumour ablation, clinical teams are testing low-intensity sound waves to deliver pharmaceuticals directly into brain tissue. The acoustic waves stimulate microscopic bubbles in the bloodstream, prompting them to expand and contract against capillary walls. This rhythmic motion creates a temporary opening in the blood-brain barrier, allowing chemotherapies and immunotherapies to reach aggressive conditions such as diffuse midline glioma and glioblastoma.

    Opening this barrier allows oncologists to test compounds that previously failed clinical trials simply because molecules could not penetrate the central nervous system. Combining acoustic opening with local immune responses also provides a pathway to turn drug-resistant brain tumours into active targets for immunotherapy.

    Reimbursement pathways and regulatory hurdles

    Commercial viability for medical equipment makers in Asia depends on moving beyond self-pay arrangements. Most private medical centres keep focused ultrasound machinery under capacity because few surgeons have received specialised training on acoustic ablation consoles.

    The critical financial hurdle remains insurance coding. Until state healthcare panels and major medical underwriters establish specific reimbursement tariffs for focused ultrasound oncology procedures, equipment makers will struggle to convert trial successes into steady device sales across regional hospital groups.

    Global trials assessing overall survival rates and recurrence intervals in pancreatic cancer and glioblastoma are scheduled to release primary outcome data within the next three years.

  • Jessica Sepel Tracks Decade-Long Shift to Preventative Wellness

    Jessica Sepel Tracks Decade-Long Shift to Preventative Wellness

    Consumer wellness is experiencing a fundamental change as shoppers move away from reactive remedies toward proactive health routines, according to Jessica Sepel in September 2026.

    Over the past decade, consumers have increasingly prioritized daily habits and preventative measures to safeguard their future wellbeing rather than waiting to address emerging health concerns.

    Surging Adoption Meets Low Shelf Satisfaction

    Shoppers are replacing reactive remedies with preventative routines. They are buying supplements, specialized nutrition, and metabolic support earlier in life. Women in transition stages try an average of 3.3 more interventions than women at other life stages, and 2.9 more than male consumers.

    Retail shelves have failed to keep pace. In the consumables category, 90 per cent of surveyed women in menopause have purchased at least one wellness product. Only 35 per cent report that the product met their health requirements. The shortfall stems from generic formulation strategies that ignore sex-differentiated hormonal aging.

    The Healthspan Deficit Driving Basket Size

    Underlying the commercial disconnect is a structural gap between lifespan and healthspan. Women outlive men by roughly five years worldwide. However, they spend 25 per cent more of their lives managing illness or disability.

    This disparity drives steady demand across Asia-Pacific markets, including China, India, and Japan. Retailers stocking unisex longevity lines miss out on high-spending shoppers seeking targeted hormone, sleep, and metabolic formulas. Brands offering verified clinical efficacy can take market share directly from legacy multivitamin labels.

    Category Shifts Across Asian Pharmacies and E-Commerce

    For health retailers and cross-border platforms, preventative longevity signals a structural break from quick-fix symptom treatments. Wellness brands built on broad lifestyle positioning now face buyers demanding targeted clinical data before committing to repeat subscriptions.

    Supply chain priorities are shifting for vitamin and dietary supplement manufacturers. Formulators who relied on standard herbal blends must invest in specialized compounds for hormonal transitions, bone density, and cellular aging to protect distribution in major pharmacy chains.

    Earlier Baseline and Future Commercial Benchmarks

    The product gap follows years of longevity protocols built on male clinical baselines. Research published in December 2024 by JAMA Network Open documented systematic healthspan-lifespan disparities across 183 World Health Organization member states, opening doors for direct-to-consumer disruption.

    Manufacturers and retail category buyers will review updated demographic conversion metrics at the upcoming St. Moritz Longevity Forum proceedings as brands prepare 2027 product pipelines for key Asian and Western consumer markets.

  • APAC Supplement Sales Reach $76 Billion in 2024, Lubrizol Reports

    APAC Supplement Sales Reach $76 Billion in 2024, Lubrizol Reports

    Lubrizol has published a new white paper assessing women’s health, beauty and nutrition needs across the Asia-Pacific region, finding that 66 per cent of Chinese respondents feel underserved by currently available products.

    The Asia-Pacific supplement market reached approximately $76 billion in 2024 retail sales, accounting for 48 per cent of total global supplement sales as beauty-from-within demand expands.

    Drawing on consumer research across China, Korea and Indonesia following the Vitafoods Asia show, the study found that 87 per cent of women in China prefer health and nutrition solutions tailored to their specific life stage.

    Across the wider Asia-Pacific region, between 40 per cent and 50 per cent of consumers said their existing supplements either did not work or delivered only partial results. That performance gap creates an opening for consumer brands willing to overhaul product lines around life stages rather than broad wellness claims.

    Four Demographics Reshape Formulation Demand

    Consumer priorities split sharply along age lines in the region. Women aged 20 to 39 in the active life and career bracket focus on physical energy, recovery and appearance. They buy primarily from brands they already recognise.

    For women in the family planning and motherhood group, purchasing criteria pivot toward formulation safety and simplicity. In China, 93 per cent of surveyed mothers and expectant women cited a distinct need for specialised pregnancy iron and nutritional products. Consumers also indicated an openness to pay price premiums of up to 50 per cent for goods that remove safety uncertainties.

    Women entering the midlife transition bracket between ages 40 and 55 prioritize hormonal balance, sleep quality, metabolic energy and skin elasticity. Purchase choices in this cohort rely heavily on published ingredient data and clinical evidence.

    The healthy longevity segment, covering women aged 55 and older, showed the strongest appetite for premium pricing. Purchasing here centers on maintaining physical capability, cognitive sharpness and daily independence.

    The Shift to Ingestible Beauty

    Preventive health routines have gained greater commercial traction in China than in neighboring markets. China recorded a proactive wellness score of 34.3 per cent in the research. That outranked Indonesia at 32.6 per cent and South Korea at 30.8 per cent.

    Chinese women ranked personal beauty as their second most disruptive daily lifestyle concern, compared to sixth place in Indonesia and eighth place in South Korea. Commercial demand for ingestible skincare expands with age. While 33 per cent of Chinese women aged 20 to 39 take supplements for long-term prevention, that figure reaches 52 per cent among women aged 55 and older.

    Physical proof remains the core requirement to retain buyers across every territory surveyed. Noticeable physical benefits ranked among the top three triggers to maintain a daily routine for 62 per cent of respondents in China, 74 per cent in South Korea and 76 per cent in Indonesia.

    Consumers are no longer waiting for problems to emerge. They are investing earlier, seeking solutions that help them maintain confidence, vitality and quality of life throughout every stage of their journey.

    Safety Fears and the Bioavailability Bottleneck

    High retail sales mask friction at checkout. In China, 62 per cent of women cited fear of adverse side effects or unproven long-term safety as a top-three barrier preventing them from trying new supplements.

    Shopper trust follows a strict sequence in Asian retail channels. Buyers demand tangible physical results first, verified ingredient science second, and product safety as an absolute minimum requirement. Products relying on marketing claims without clinical backing face immediate drop-off after the first purchase cycle.

    Formulators face technical hurdles delivering active compounds that the body absorbs efficiently without unpalatable taste or digestive irritation. Lubrizol has responded by pushing microencapsulation technologies for sensitive nutrients, including iron, magnesium and curcumin, to improve bioavailability and taste profiles.

    Traditional ingredient delivery formats struggle to sustain subscription renewals across Asian e-commerce platforms. Brands that fail to show measurable outcomes within three to four weeks lose shelf space to clinical brands backed by published ingredient trials.

    Cross-Border Brands Target Reformulation

    Trade show data presented at Vitafoods Asia showed ingredient suppliers documenting rising cross-border orders for nutricosmetics and functional foods. Retailers across Tier 1 Chinese cities have expanded shelf allocations for ingestible collagen, microencapsulated minerals and cellular health compounds over the past two years.

    Suppliers are now bundling topical skincare products with ingestible nutritional packs to lock in higher basket values. For consumer health groups selling through cross-border channels like Tmall Global and JD Worldwide, regulatory compliance and clean ingredient labels will determine which brands capture the aging demographic.

    Teams across formulation and retail face the task of translating these stage-specific consumer datasets into finished products ahead of the 2025 regional exhibition cycle. New clinical trial data on bioavailable ingredients will meet commercial buyers there.

  • Nearly Six in 10 Australian Shoppers No Longer Buy at Full Price

    Nearly Six in 10 Australian Shoppers No Longer Buy at Full Price

    Nearly six in 10 Australian shoppers no longer buy goods at full price, according to a KPMG report released in September 2026. The retail sector is being forced to adapt as consumers learn to wait out price cycles rather than simply weather a cost-of-living downturn.

    This shift has turned sale events into planned buying exercises rather than spontaneous sprees. Rachael Hockaday, managing director of retail performance agency Haeday, told Inside Retail that consumers are increasingly planning ahead.

    Shifting Consumer Timelines

    Consumer price discipline has eroded standard trading periods across the sector. Hockaday said shoppers now arrive at major sales events with a clear idea of what they want and the specific price they are willing to pay.

    “Sales become the time to buy, often with planning in between so they’re prepared,” Hockaday said.

    Margin Pressure Across Supply Chains

    Waiting penalises inventory holders who stock seasonal merchandise. Holding stock past scheduled markdown cycles inflates warehousing costs. It also forces deeper clearance discounts later in the product lifecycle.

    Suppliers and brand owners see their wholesale margins squeezed. Retail buyers demand larger vendor allowances and promotional funding to protect their gross margin targets when baseline shelf prices drop.

    Operational Risks for Landlords and Brands

    Lease structures built on turnover rent clauses face direct exposure to these tighter margins. Volume now concentrates heavily in discounted periods. Top-line revenue may hold, but net merchant profitability shrinks.

    Lower-cost international direct-to-consumer platforms gain an edge over domestic multi-brand stockists under these conditions. Domestic retailers carry heavy store fleet costs. They must compete directly with offshore digital operators running agile, on-demand supply chains.

    Discount Cycles Ahead

    Persistent cost-of-living pressures across major cities have entrenched this cautious buying behaviour. Consumers who adopted promotional tracking tools out of necessity have retained those habits as standard routines.

    Retail operators head into the final calendar quarter with inventory adjusted for heavy discounting. Upcoming peak sales in apparel, footwear, and consumer electronics will test whether full-price trading can recover in the next financial year.

  • When Products Go Viral, Can Your Supply Chain Keep Up?

    When Products Go Viral, Can Your Supply Chain Keep Up?

    For years, retailers have focused on forecasting demand. Today, they’re increasingly trying to keep up with it. Across Southeast Asia, social commerce has fundamentally changed how consumers discover and buy products. Livestream shopping, creator recommendations and short-form video have compressed the traditional purchase journey from days or weeks into minutes. A single piece of content can turn an everyday product into the next bestseller almost overnight.

    The numbers reflect the scale of this shift. According to Cube Asia, combined gross merchandise value (GMV) across Shopee, Lazada and TikTok Shop grew by 22% in 2025, with TikTok Shop recording the fastest growth as social commerce continues to reshape online retail across the region.

    For retailers, however, the challenge isn’t simply handling more online orders, it’s managing a level of demand volatility that traditional retail operations were never designed to accommodate.

    Demand is becoming increasingly unpredictable

    Retail planning has traditionally relied on historical sales data, seasonal patterns and promotional calendars to forecast demand. Social commerce has now completely disrupted that model. Rather than building gradually, demand has the potential to surge within hours of a viral video, influencer endorsement or livestream event. That means products that were moving steadily one day can suddenly attract thousands of orders the next, leaving retailers scrambling to respond.

    It’s not that retailers don’t have enough inventory but it’s that they’re often lacking the visibility to understand where that inventory sits across stores, warehouses and fulfilment partners – or the agility to redirect it quickly enough to meet changing demand.

    Visibility is a competitive advantage

    From a consumer’s perspective, every sales channel should deliver the same experience. Whether they make a purchase on TikTok Shop, Shopee, Lazada or a brand’s own website, they expect accurate stock availability, rapid delivery and clear order updates.

    Meeting those expectations requires retailers to maintain a real-time view of inventory across their entire network. Without that visibility, businesses risk overselling products during periods of high demand, delaying shipments or cancelling orders after customers have already completed their purchase. In an environment where customer experiences are shared instantly across social media, those operational shortcomings can damage brand reputation just as quickly as a successful campaign can build it.

    Fulfilment must become more intelligent

    Visibility is only part of the equation. Once demand spikes, retailers also need to determine the best way to fulfil every order. Modern order orchestration enables businesses to evaluate inventory availability, warehouse capacity, delivery commitments and shipping costs in real time before automatically routing orders to the most appropriate fulfilment location.

    This flexibility allows retailers to balance workloads across stores, distribution centres and logistics partners as demand changes, helping them maintain delivery performance even during sudden sales surges. Rather than reacting to disruption, retailers can make fulfilment decisions dynamically as conditions evolve.

    Social commerce requires connected operations

    One of the biggest misconceptions surrounding social commerce is that it’s simply another sales channel, when in reality, it changes how retailers need to operate. Marketing campaigns, inventory planning, warehouse operations, transportation and customer service can’t function independently when demand can change dramatically within minutes.

    Success increasingly depends on connecting these functions through a unified operational platform, where inventory, orders, fulfilment and logistics share the same real-time information. When every part of the business is working from a single view of operations, retailers can respond faster, make more informed decisions and continue delivering the customer experience consumers expect.

    Turning demand into fulfilment

    Social commerce will continue to reshape retail across Southeast Asia, giving brands more opportunities to connect with customers and drive online sales. But every spike in demand puts pressure on the systems behind the scenes.

    Retailers that can respond quickly to changing order volumes, inventory movements and fulfilment demands will be better placed to take advantage of these opportunities without compromising the customer experience. As social commerce continues to evolve, operational flexibility will become just as important as marketing reach.

    For more information about supply chain solutions, visit https://www.manh.com/

    By Raghav Sibal, Managing Director, Southeast Asia, Manhattan Associates

  • Taiwan Phishing Losses Hit NT$54.5 Million as Scammers Target Shopee and Momo Users

    Taiwan Phishing Losses Hit NT$54.5 Million as Scammers Target Shopee and Momo Users

    Phishing losses in Taiwan surged to NT$54.51 million ($1.71 million) across 505 cases last month, driven by fake merchant alerts and impersonations of leading online marketplaces. The surge came even as overall telecom and internet fraud dropped 22.3 per cent nationwide to 10,652 cases.

    Data released by the National Police Agency’s Criminal Investigation Bureau shows phishing cases doubled from 253 incidents in the same month last year. Financial damages grew more than fourfold from NT$13.05 million over the same period, even while total nationwide fraud losses fell 35.1 per cent to just over NT$4 billion.

    How Scammers Target Online Shoppers

    Fraud networks are shifting tactics from crude mass outreach to targeted retail spoofs. The bureau identified recurring schemes where scammers pose as customer service agents or merchants from platforms like Shopee and Momo. These messages claim abnormal orders, pending refunds, duplicate billings, or mandatory membership profile updates.

    Victims receive links mimicking official digital storefronts to capture payment credentials and credit card details. Other widespread lures involve bogus telecommunications and transport notices, warning consumers about expiring loyalty points or unpaid parking fees.

    Traps also include fake application portals for international travel documentation, including Thailand’s Digital Arrival Card, the US Electronic System for Travel Authorization, and the UK Electronic Travel Authorization. Links frequently direct targets into private chats on the Line messaging app, where scammers instruct users to scan QR codes, initiate ATM transfers, or authorize cardless cash withdrawals.

    The Operational Risk for Marketplaces

    For marketplace operators in Taiwan, rising phishing volumes threaten brand trust and checkout conversion rates. When attackers clone legitimate merchant workflows, consumers become wary of regular notification channels, SMS reminders, and standard email receipts. That friction hurts cart completion and slows customer adoption of direct digital payment flows.

    Retailers face rising support overheads as their customer service teams deal with disputing victims who believe they interacted with verified platform representatives. The fraud shift shows syndicates are abandoning broad investment tricks in favor of everyday transactional touchpoints, raising pressure on platform operators to harden merchant verification and URL defenses.

    Enforcement Push and Tracking Numbers

    Taiwan authorities previously reported fraud losses topping NT$6 billion for the comparable month last year, prompting joint awareness drives with private sector operators and public figures. Deputy Commissioner Chiu Shao-chou outlined the latest operational numbers alongside actor Harry Chang at a bureau briefing in Taipei, urging shoppers to manually type official URLs instead of following unsolicited message prompts.

    Platform operators and law enforcement are now tracking whether cross-agency link-takedown programs can cut phishing figures back below the 300-case mark in the final quarter.

  • Malaysia Q2 Retail Sales Growth Falls Short as Spending Tightens

    Malaysia Q2 Retail Sales Growth Falls Short as Spending Tightens

    Malaysia recorded weaker than expected retail sales growth in the second quarter. Households curbed discretionary spending under persistent cost of living pressures.

    Store operators were caught off guard. They had anticipated stronger post-holiday consumption across shopping malls and high street locations.

    Squeeze on Household Budgets

    Shoppers across urban centers like Kuala Lumpur redirected budgets toward essential groceries and basic utilities. They cut visits to apparel boutiques, specialty food outlets and consumer electronics chains. That left retailers managing slower foot traffic, smaller basket sizes and rising price sensitivity across mid-market categories.

    Department stores and specialty chains felt the sharpest pinch during the quarter. Food and beverage operators also saw customers trade down to cheaper meals and cut back on cafe visits.

    Operator Margins and Inventory Risk

    This slowdown creates inventory friction for regional retailers that built up stock expecting resilient consumer demand. Excess seasonal merchandise forces heavier discounting. Gross margins take the hit while operating overheads, logistics costs and mall service charges stay high.

    Commercial landlords face tougher lease renewal talks as tenant turnover risk mounts. Shopping center operators across Southeast Asia counted on domestic spending to balance uneven tourist arrivals. A local slowdown weakens tenant revenue-sharing agreements and dampens rental reversion rates.

    Broader Southeast Asian Pattern

    Similar patterns are playing out across neighboring markets, including Thailand and Indonesia. Post-pandemic retail rebounds there also gave way to cautious household budgeting. Earlier quarterly gains relied on festival spending, but momentum vanished once promotional cycles ended.

    Retail groups are now recalibrating third-quarter procurement orders and delaying non-critical store refits. Attention turns to upcoming third-quarter performance data and year-end holiday order books to gauge whether revenue stabilizes before 2027.