Blog

  • Retailers take omnichannel path in preparation for Thailand 4.0

    Retailers take omnichannel path in preparation for Thailand 4.0

    Supaluck Umpujh, chairwoman of The Mall Group, said that Thailand 4.0 is an economic model to promote and transform Thailand into a digital economy.

    Digital economy refers to the widespread use of digital technologies, which are rapidly transforming business practices and social interactions.

    According to the Thai Board of Industries, the strategic framework for digital economy promotion consists of four areas: digital commerce, digital entrepreneurship, digital innovation, and digital content.

    In pushing forward this forward-looking agenda, the Ministry of Digital Economy and Society will promote a new generation of entrepreneurs, as well as commercial and industrial innovations. At the same time, it will assist investors in developing new markets for digital content. Entrepreneurs will be aware of the importance of using ICT in enhancing efficiency and reducing production costs. Implementation of the digital economy plan will need the support and involvement of all stakeholders in achieving its stipulated goals.

    “We realised that retail business played a crucial role in Thailand’s economy, and we are also trendsetters in shopping. The first mission that we seek for our customers is to add some online shopping experience into our stores. But we also offer the experience that customers cannot find through digital channels. Currently, we are working on many digital platforms for instance e-commerce, mobile application, Radio Frequency Identification, Near Field Communication and many more,” she said.

    Nicolo Galante, chief operating officer of Central Group, said the group had integrated omnichannels to improve the customer experience. “We [Central Group] expect to move each of its online business units and will launch major e-commerce initiatives such as major partnerships and joint-ventures,” he said, adding that the e-commerce market will have a significant impact on retailers.

    Galante said the Central Group aimed |to be number one in terms of sales across channels. Central Group has stores, customer data and customer knowledge across many different stores, locations and categories.

    Salinla Seehaphan, corporate affairs director of Tesco Lotus, said the Thailand 4.0 economic model stressed on the importance of adding value to traditional products and services using innovation and digital transformation.

    “In our own business, Tesco Lotus has adopted innovation and digital transformation to improve our product and service offerings, as well as our customers’ shopping experience, for example by allowing customers to be able to trace where their fruits and vegetables come from via QR codes. As our core business revolves around fresh food, we have an opportunity to work directly with farmers across the country and help them to become farmers 4.0 in line with the government’s goal for Thai farmers to transform from being simply growers of food to smart farmers who use effective crop management and a market-led approach to farming,” she said.

    We also focus on equipping them with the knowhow that will help them thrive in Thailand 4.0,” she said.

    Punyapon Tepprasit, chief executive of MVP Consultant and lecturer at Sripatum University’s International Trade Department, said the main idea of the Thailand 4.0 economic model focuses on innovation creativity and sustainability. Thai retailers will change definitely in keeping with consumer behaviour. “I have four suggestions for Thai retailers. First of all, retailers must combine the online and offline channel strategy for creating an omnichannel that can help a business generate brand awareness, market share, and sales growth with big data analysis. Online enjoys competitive advantages as it is the fastest, can be available for 24 hours, has low advertising cost, and can track consumer behaviour. Also, businesses can reduce the cost per acquisition for one customer or groups of target customer,” he said.

    “Second, businesses have to build a talent team to create a new creativity strategy. Their new strategy must attract the attention of customers through newness of products and service innovation, or marketing communication via online and offline channel such as the augmented reality technology with an application on smartphone that can boost the emotional connection by experience and relationship creation with customers or target groups. The winner will be the one who can impress the brand on customers’ minds,” added Punyapon.

    “Third is business transformation. Businesses must reshape their organisations into lean entities to minimise wastage in the working process, as well as total cost and lead time. If companies can adjust agilely, they will have a competitive advantage in the volatile environment, because companies have the ability to address the changes in market demand.

    “The fourth is to become a data driven organisation. Businesses have to undertake market research to know the depth of consumer behaviour. Big data is very important, but the tools and data analysis are more important,” he said.
  • Bitcoin drops as South Korea moves to regulate cryptocurrency trading

    Bitcoin drops as South Korea moves to regulate cryptocurrency trading

    Currently, many cryptocurrency exchanges (including South Korean ones like Kucoin) allow trading with little more than your name and an email.

    Bitcoin appeared to find a bottom on Friday, rebounding to $15 000 after moves by South Korea to curb speculation and protect retail customers took the cryptocurrency down more than 8% on Thursday.

    “The government had warned several times that virtual coins cannot play a role as actual currency and could result in high losses due to excessive volatility”, the country’s government said in a statement.

    Those new regulations would include prohibiting anonymous trading accounts and could give authorities the ability to shut down exchanges, Reuters said. Among other concerns, unmasking bitcoin traders would open up owners to taxation, a significant concern now that bitcoin has increased in value exponentially. The virtual currency plunged more than 10% to below $14,000 on Thursday morning in Asia, according to CoinDesk.com, and continued to fluctuate through the day.

    As part of what appears to be a series of updates created to improve oversight of industry practices, the government will also seek to bar banks from issuing new virtual accounts to cryptocurrency exchanges.

    Mati Greenspan, a Tel Aviv-based analyst at investment firm eToro, said it would be too early to gauge the impact of the rules, but they sounded “ominous”. Demand is so high that prices for the unit are around 20 per cent higher than in the United States, its biggest market.

    The country is also home to Bithumb, one of the world’s biggest bitcoin exchanges.

    In comparison, about 11% of Americans polled by student loan comparison website LendEdu in September said they either now own or have owned virtual currencies in the past, while 17.2% said they would invest in bitcoin in the future.

    South Korea may also stop local companies from providing settlement services for virtual currency transactions.

    In a case highlighting the risks of cryptocurrency, a Seoul virtual currency exchange declared itself bankrupt last week after being hacked for the second time this year.

    So far, China is the only country in the world to have totally banned bitcoin exchanges.

    Seoul-based Youbit said it was filing for bankruptcy after hackers stole almost a fifth of its clients’ holdings.

  • Ban on ivory sales in China to take effect on Sunday

    Ban on ivory sales in China to take effect on Sunday

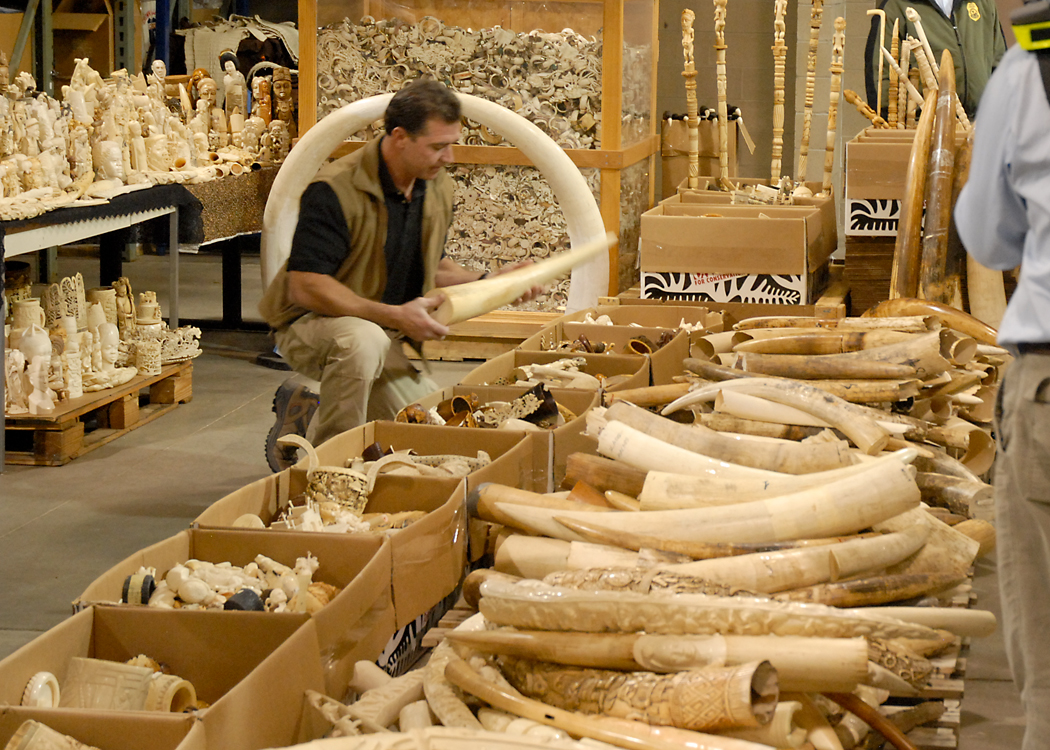
    A ban on ivory sales in China, the world’s largest importer and end user of elephant tusks, takes effect on Sunday. Wildlife activists have described the move as a vital step towards reducing the slaughter of the endangered animals.

    It is estimated 30,000 elephants are killed by poachers in Africa every year. China has made a big push to eradicate ivory sales and demand has fallen since early 2014 due to a crackdown on corruption and slower economic growth.

    Public awareness campaigns featuring celebrities have helped boost awareness of the bloody cost of ivory. “It is the greatest single step toward reducing elephant poaching,” said Peter Knights, chief executive of the conservation group WildAid.

    Legal ivory

    China has allowed the sale of pre-convention ivory, which refers to products such as carvings and crafts acquired before the 1975 Convention on International Trade in Endangered Species of Wild Fauna and Flora (CITES), as long as it is accompanied by certificates.

    The trade in pre-convention ivory has legally thrived in China and Hong Kong since 1975, but environmental activists have long asserted that it has spurred demand for all ivory.

    The ban on all ivory sales has already led to an 80 per cent decline in seizures of illegal ivory entering China as well as a 65 per cent decline in raw ivory prices, according to WildAid.

    Under the ban, China’s 172 ivory-carving factories and retail outlets will also close. Some factories and shops started closing in March.

    This year, ivory prices in China were about 65 per cent lower than 2014 levels, said WildAid, with retailers in some places trying to sell off stocks and offering heavy discounts before the ban.

    Hong Kong

    The Chinese ban has been hailed by activists but they warn that Hong Kong, an administrative region of China, remains a big obstacle to the eradication of elephant poaching.

    China’s ban on sales do not apply in the former British colony, which has the largest retail market for ivory and has traded it for more than 150 years.

    Hong Kong is a prime transit and consumption hub for ivory with more than 90 per cent of consumers from mainland China.

    Since 2003, Hong Kong has intercepted about 40 tonnes (40,000kg) of illegal ivory, only about 10 per cent of what is believed to have been smuggled in, WildAid said in a paper to the city’s legislature in May.

    Hong Kong set a timetable for a ban on ivory trading last year, with a phase-out time of five years. A final vote on the ban is expected in the city’s legislature in early 2018.

    Conservationist Zhou Fei said the Chinese ban could be a catalyst for the closure of ivory markets across Asia.

    However, Kenya-based conservation group Save the Elephants said this year that neighbouring Laos has expanded its retail market more rapidly than any other country.

  • South Korea’s service sector investment focused on wholesale, retail and restaurants

    South Korea’s service sector investment focused on wholesale, retail and restaurants

    South Korea’s investment in the service sector has been focused on low value-added areas, such as wholesale, retail and restaurants, official data showed Monday.

    The gross fixed capital formation for the service sector was tallied at 256.1 trillion won ($239.6 billion) in 2015, the findings by the Bank of Korea and the National Assembly Budget Office showed. This represents a solid 13.9 percent increase to 224.8 trillion won reported in 2006.

    The GFCF refers to the net increase in assets that takes into account both investments and deductions within a set period of time.

    The tally, however, showed investments in high value-added areas, such as cultural and education industries, backtracking.

    An injection of funds into this sector reached 18.1 trillion won in 2015, or a 69.2 percent spike from 10.7 trillion won tallied in 2006.From 2006 through 2015, when investment in the service sector shot up the steepest, investment was centered on restaurants and catering, as well as retail and wholesale.

    The increase rate is five times faster than gains for the entire service industry as a whole in the same time period.

    The central bank said the sharp rise has allowed restaurants and catering businesses, and retail and wholesale to make up 7.1 percent of all service sector investments in 2015 from 4.8 percent in 2006.

    On the other hand, investment in the cultural sector contracted 20.8 percent to 7.6 trillion won in 2015 from 9.6 trillion in 2006, with 15.2 percent drop being reported for education-related outlays in the same period.

    Hong Joon-pyo, a senior analyst at the Hyundai Research Institute , said areas where investment has focused on in recent years is closely associated with self-employed posts.

    “Many people who retire and do not have any skill sets often go into these businesses so there has been a natural rise in investment,” he said.

    The economist said that this trend has led to an over saturation of certain service sectors that has eaten into profits.

    Statistics Korea said operating profits of restaurants and catering industries stood at 13.4 percent in 2015 or down 9 percentage points from five years earlier, while numbers for retail and wholesale correspondingly stood at 5 percent or down 2 percentage points.

    The statistical office said this has led to such stores’ average survival rate three years after opening standing at an average of just 39.1 percent. Such dismal numbers are not conducive to sustainable growth for the economy as a whole.

  • BSP to launch digital payments clearing house in January

    BSP to launch digital payments clearing house in January

    The Bangko Sentral ng Pilipinas (BSP) said individual consumers would be covered by the batch electronic fund transfer (EFT) credit automated clearing house (ACH) starting next month as it pursues greater use of electronic payments by shifting to cash-lite society from cash-heavy society.

    BSP deputy director Raymond Estioko said banks and the clearing house operator are now developing their respective web and mobile applications for the Philippine EFT System and Operations Network (PESONet) as part of the National Retail Payment System (NRPS).

    “Hopefully by January individuals for the common people would be able to experience and see PESONet being offered first by the banks,” he said.

    Estioko, who is also the project head of the BSP’s NRPS, said several banks are now ready to offer the service to individual customers

    “There are several banks which are now ready to offer the service to the public,” he added.

    BSP Governor Nestor Espenilla Jr. led the launch of the PESONet in November to facilitate fund transfer from one account to one or several accounts maintained in different financial institutions.

    PESONet is one of the ACHs prioritized for implementation given its potential to be an efficient channel for government and private business collections and disbursement. PESONet provides an electronic alternative to the still widely used paper-based check system.

    Estioko explained the initial launch of the PESONet only covers corporate transactions.

    Through PESONet, businesses, the government, and individuals will be able to conveniently initiate electronic fund transfers and recurring payments from the sender’s accounts maintained in BSP supervised financial institution (BSFIs), such as banks and other non-bank electronic money issuers, to corresponding recipient accounts in other BSFIs.

    With the ACH, funds could be made available to the recipient accounts within the same banking day or immediately upon clearing.

    Payees receive the funds transferred in full free of charge resulting in greater transparency and to help clients determine which EFT products offer the best value for their money.

    Estioko said a second ACH called InstaPay would be launched toward the end of the first quarter of 2018 to enable 24/7 low value electronic fund transfers.

    The BSP launched the NRPS in December 2015 to provide a safe, efficient, and reliable digital or electronic payment system in the country.

    Digitizing retail payments is critical in the Philippines considering that 99 percent of payment transactions per month are done in cash, with businesses and individuals making only one percent and 0.3 percent electronic payments, respectively, according to a study conducted by the Better Than Cash Alliance.

    The NRSP aims to increase electronic retail payment transactions to 20 percent by 2020 from the current one percent.

  • Japanese, Thai goods reach every corner of Vietnamese market

    Japanese, Thai goods reach every corner of Vietnamese market

    Several years ago, fans of Thai and Japanese goods had only several choices – either buying the products carried across border gates, or going to a few select shops. But now, they can freely choose products at many specialized stores. Specialized shops are mushrooming

    A report from MOIT (Ministry of Industry and Trade) shows that the deficit in trade with Thailand in the first eight months of the year reached $3.5 billion.

    Thai products are available at 9,000 traditional markets, supermarkets and home appliance distribution centers. In large cities, Thai goods account for 30-50 percent of the market share.

    The others are run by world giants such as Lotte, Aeon and Emart. Metro alone has 19 retail points, while Big C has 32.There are about 100 retail points belonging to foreign invested supermarkets in Vietnam, half of which belong to Thai investors.

    Meanwhile, Japanese have been penetrating deep into Vietnam through big retail chains such as Aeon, Ministop, Family Mart, Tokyo Deli, Gyu Kaku, Oshaka Ohsho and 7-Eleven.

    The Sakura chain has opened 10 shops after six years in Vietnam, while Tokyo Life has 18 shops in Hanoi, two in HCMC and 35 in other provinces.

    Pham Chi Lan, a renowned economist, said Thai firms had been following a strategy to enter the Vietnamese market for a long time.

    Thai businesses understand that Vietnam, with high economic growth rate, young population and increasingly high consumption, will be a vast market once tariff barriers are removed.

    They have spent time studying Vietnamese consumer psychology and followed professional methods to win over customers.

    Vietnam imports a wide range of products from Thailand, from household electrical appliances to vegetable and fruits, and CBU cars and cosmetics.

    Vietnam also imports products which are locally made, such as household-use products, computers and plastics.

    Minister of Industry and Trade Tran Tuan Anh once asked why Thais could bring their products to the Vietnamese market but do not do this with other ASEAN countries, including Indonesia and the Philippines.

    Analysts believe the most important reason is the large distribution networks that Thais have set up in Vietnam.

    Thai corporations like Central Group and TCC Group have spent big money to take over the largest distribution chains in Vietnam, paving the way for Thai products to enter Vietnam.

    Meanwhile, a branding expert commented that Thai and Japanese goods can thrive in Vietnam because manufacturers receive support from their government agencies.

    “Japanese agencies have set up dedicated divisions to support small and medium enterprises in their country,” he said.


  • China’s Alibaba on road to deliver $100 million to XpressBees

    China’s Alibaba on road to deliver $100 million to XpressBees

    China’s online commerce giant Alibaba Group Holdings is in advanced talks to pick up a significant minority stake in logistics company XpressBees by making an investment of up to $100 million, said three persons with knowledge of the matter.

    The transaction, which is in the final stages of negotiations, will be Alibaba’s sixth investment in the Indian market as it builds a string of assets to take on homegrown market leader Flipkart and global rival Amazon.

    “The deal is likely to close in the next two-three weeks,” said one of the persons mentioned above. The exact stake Alibaba is picking up in XpressBees could not be determined. Alibaba and XpressBees didn’t respond to queries.

    XpressBees is the logistics business spun out of baby and maternity products retailer FirstCry, known for its acquisition of Mahindra’s Babyoye in 2016. The company competes with other online retail-focused logistics services providers like Delhivery and Ecom Express.

    Talks between XpressBees and Alibaba have been on for about 18 months.

    ET had reported in June 2016 that Alibaba was looking to buy, or invest in, an Indian logistics company specialising in deliveries for online retailers, and toward this end had held talks with Delhivery and XpressBees Logistics.

    If the XpressBees investment goes through, it will help Alibaba build what founder Jack Ma calls the “iron triangle” of businesses in ecommerce (Paytm Mall, Bigbasket), payments (Paytm) and logistics, which can feed off each other.

    In China, the Alibaba Group has online retail businesses called Tmall (B2C, focusing on brands) and Taobao (C2C) and a payments business under affiliate Ant Financial, popularly known as Alipay.

    In September, it increased its stake to a majority in one of China’s largest techenabled logistics companies, Cainiao, which is valued at close to $20 billion. At the time, Alibaba had said it plans to invest over $15 billion in the next five years to develop its global logistics network.

    “Alibaba wants to make Xpress-Bees the Cainiao of India, and over time logistics operations for all companies like Paytm Mall and Bigbasket may get consolidated under it giving it a larger captive customer base,” said the second person mentioned above.

    The impending deals in Bigbasket and XpressBees will take total investments in India by Alibaba along with its payments affiliate Ant Financial to about Rs 11,000 crore, or $1.7 billion, out of which over two-thirds is invested in Paytm. In addition, Ant Financial is also said to be in talks to invest up to $200 million in restaurant discovery and food delivery platform Zomato.

    Shifitng Kaurndia as the portfolio in India grows, Alibaba Group is also likely to move one of its key executives from Hong Kong, senior director Kshitij Karundia, to the country to work more closely with the businesses and look for more investments, said the third person familiar with matter.

    FirstCry entered logistics in 2012 when it decided to start express deliveries of its products and began third-party logistics (3PL) at the beginning of 2015. The company was spun off as Busybees in September 2015 and has ramped up orders significantly since then.

    The business has been built by FirstCry founders Supam Maheshwari and Amitava Saha. After the demerger, Saha has been leading the logistics business as CEO while Maheshwari has been heading First-Cry. XpressBees investors include SAIF Partners, IDG Ventures India, NEA, Vertex Ventures and Valiant Capital, some of which may sell a part of their stake in this deal.

    The company saw revenue go up by 121% in FY17 to Rs 185.42 crore while losses grew 61% to Rs 57.71crore, according to filings with Ministry of Corporate Affairs (MCA).

    Owned by Busybees Logistics Solutions, XpressBees has built the business on about Rs120 crore of capital till now, which is in contrast with competitors Delhivery which has raised Rs 1,600 crore, and Ecom Express, which has racked up around Rs1,000 crore in capital.

    With capital coming in from Alibaba, experts said an XpressBees deal could trigger consolidation. While industry sources pegged Delhivery as the market leader with around 300,000 shipments a day, XpressBees is currently logging 170,000-200,000 while Ecom Express has 120,000-130,000. Large players like Flipkart and Amazon India have also built their own logistics operations, which handle most of their shipments.

    The market for logistics-technology businesses, which include delivery startups, truck aggregators and warehousing firms, is expected to surge to $9.6 billion by 2020 from $1.4 billion in 2015, according to a report by investment bank Avendus Capital. Online retail logistics startups will dominate this space with a market size of $6.6 billion by then.

  • Singapore’s electricity markets – trailblazer or flicker of light?

    Singapore’s electricity markets – trailblazer or flicker of light?

    In the industrialized zone of western Singapore some of the only night owls are electricity traders on 24-hour shifts, bidding prices for a commodity traded at half-hour intervals because it cannot be stored and shipped like oil or gold.

    Singapore has come a long way from a government-regulated power supply era. In 2018, it will have a fully liberalized power market where even household consumers can choose to buy the cheapest electricity from a laundry list of suppliers.

    In addition to competitive wholesale and retail electricity markets, Singapore also has a fledgling futures market in the works.

    The question is where does it go from here?

    Can power trading in Singapore rival mature markets in Europe? Or can Singapore become the template for deregulated power markets within Southeast Asia, possibly underpinning the ambitious ASEAN gas and power grids that have been elusive for over two decades?

    Domestically, will associated carbon and gas trading markets develop fast enough to support the power market? Does great power mean great liquidity — can the paper markets generate enough liquidity and trading interest in the longer term?

    HOW A TINY ISLAND PUNCHES ABOVE ITS WEIGHT

    Singapore has gone from a handful of power producers to 14 generators, 17 wholesale market traders and 16 retailers, totaling 47 market players including a small number of solar power producers as of December 2016. This year the number had crossed 50.

    Currently business accounts, which are consumers with an average monthly electricity consumption of at least 2,000 kWh, account for around 80% of Singapore’s total electricity demand, according to the Energy Market Authority. They can already choose their power supplier and by the second half of 2018 around 1.3 million families will also be able to do the same.

    This is estimated to result in savings of S$435 million ($323 million) over five years for consumers through free market competition, according to a 2016 report published by consultancy Sapere Research Group, for the Energy Market Authority.

    The wholesale trading market itself is fairly sophisticated with algorithms using 50,000 mathematical equations to calculate demand, supply and pricing levels, according to the Electricity Market Company. On the Singapore Exchange, independent retailers can buy and hedge their electricity positions using electricity futures.

    But being on a tropical island has its drawbacks.

    Power trading in mature markets like Nord Pool is possible because of variations in demand-supply caused by intraday peaks, summer and winter demand, storms, cross-border trade between countries and multiple fuels like coal, natural gas, renewables and nuclear.

    In Singapore, most of these variations are non-existent, severely limiting trading arbitrage.

    For instance, 95.2% of Singapore’s electricity comes from natural gas, whereas in Europe renewables have proliferated to the point of annoyance, as wind and solar do not provide stable supply.

    In October, Singapore’s deputy Prime Minister Teo Chee Hean said the city-state has an immediate solar power target of 6% by the end of this decade, and potentially as much as 20% in the long term if new technologies are implemented.

    Compared to electricity consumption of 48.6 TWh in 2016, and generation capacity of 13,348.4 MW as of end-March 2017, Singapore’s grid-connected installed solar capacity remains minuscule.

    Cross-border trading is also absent in Singapore.

    In Europe, countries have an interconnectivity target of 10% of installed capacity in the near term and as much as 15% by 2030 has been proposed.

    But in Singapore, regulators are still conducting feasibility studies with Laos, Thailand and Malaysia for cross-border electricity trading, and only a small amount of electricity is actually traded with Malaysia’s southern Johor state.

    Cross-border trading will remain a difficult proposition in Singapore because of energy security considerations that curb dependence on foreign power suppliers, who may also have access to cheaper fuels and lower capital costs.

    SPARKING TRADING INTEREST

    Singapore has also launched its own electricity futures market.

    As of October 1, 2017, total volume traded in the electricity futures market was 4,744 lots or 5,196 GWh since they were launched in early 2015, according to the Energy Market Authority. Comparatively, Singapore’s actual electricity generation rose by 2.6% to 51.6 TWh in 2016.

    This means traded volumes on the paper market are roughly 5% of actual demand. The ratio of paper versus physical trading volumes is a sign of how active the market is.

    For instance, in oil markets, derivatives volumes are 10-15 times of the physical, in the New Zealand electricity market derivatives trade at around 70% of physical, and in the Australian market derivatives volumes are two to three times that of actual consumption.

    There is clearly room for growth there.

    “The development of the Singapore electricity futures market is being modeled on the New Zealand market due to the similarities between the two markets,” William Prajogo, associate director of oil, power and gas derivatives at SGX said.

    He said the electricity futures market is vital for the success of the Full Retail Contestability of the Singapore power market in 2018 as it lowers the barriers to entry for new independent retailers to enter the market, which in turn will create more retail competition.

    “SGX will consider launching more electricity derivatives products in future depending on market demand and growing liquidity levels,” Prajogo said, adding that he expects more market participants such as trading companies, banks and financial institutions to add liquidity to the market.

     NATURAL GAS AND POWER

    There is also a strong correlation between the gas and power markets. It is also vital to have free markets for the primary fuel to facilitate and incentivize free trading of electricity.

    Products like spark spreads, which measures the profitability of a power plant depending on its primary fuel, are common in mature markets where both the fuel and electricity are actively traded and market participants can hedge the spread between electricity prices and fuel costs.

    In Singapore’s case however, primary natural gas supply is still tightly regulated.

    Most of the gas is piped in from Malaysia and Indonesia at prices pegged to high sulfur fuel oil. Less than 25% of the gas burnt is seaborne LNG, and even that is controlled by the two appointed aggregators at oil indexed prices.

    “None of us can predict the future but the common sense point to make would be that for a vigorous futures market in natural gas and electricity to work you need a market designed for a level playing field for everyone to participate in,” Tilak Doshi, managing consultant at Muse, Stancil & Co (Asia) said.

    “The answer lies in promoting contestability in power and gas markets,” he said.

    “Without further liberalizing market design changes, the outlook for full development of the futures market for electricity will be constrained,” Doshi said.


  • Singapore defers foreign law firms’ licensing decision to 2020

    Singapore defers foreign law firms’ licensing decision to 2020

    The Singapore Ministry of Law has announced it will defer to 2020 its decision on the renewal of the licences of the second batch of Qualifying Foreign Law Practice (QFLP) firms.

    The second batch includes firms such as Gibson Dunn & Crutcher, Jones Day, Linklaters and Sidley Austin. They secured licences in 2013 for a period of five years. The licences were originally due to expire in 2018, but such will be extended to 2020 until the ministry decides on the renewal.

    QFLP licences allow Foreign Law Practices (FLPs) to practise Singapore law, except in domestic areas of litigation and general practice, for example, criminal law, retail conveyancing, family law and administrative law. The QFLPs can practise the permitted areas of Singapore law through Singapore-qualified lawyers with practising certificates or foreign lawyers holding the foreign practitioner certificate.

    According to the ministry, the second batch of firms have contributed to the growth of Singapore’s economy, as they have increased their revenue from offshore work and doubled their headcount of their Singapore offices since obtaining the permits.

    “However, their respective performances have fallen short of the initial commitments they made in 2012, as they have all been impacted by Asian economies’ weaker than expected growth, drop in commodities prices and decrease in mergers and acquisitions which had resulted in weaker demand for legal services in the region in the last two years,” the ministry added.

    It said its decision will allow it to better assess each firm’s performance and contribution to Singapore and their respective proposals for the new licence period.

  • Cryptocurrency Exchanges Investigated By South Korean Fair Trade Commission

    Cryptocurrency Exchanges Investigated By South Korean Fair Trade Commission

    The South Korean Fair Trade Commission (FTC) is reportedly investigating 13 major cryptocurrency exchanges in the country for violations of consumer laws, such as electronic commerce laws and contract laws. The investigations came after the bankruptcy announcement by cryptocurrency exchange Youbit after a major hack.

    The FTC said it will look into whether they should remain under the online retail business category, or fall under different category to enforce stronger measures. It will also check whether there is any unfairness among the terms and conditions used by the business operators and take action in accordance with relevant laws and regulations.

    The investigations is a follow-up on the government’s wide-ranging measures to curb cryptocurrency speculation and crimes. According to the government, previous inspections on crypto exchanges revealed that most of the companies (10 companies) demonstrated administrative and technical security procedures such as the installation and operation of access control devices and encryption measures of personal information. Overall, the measures were found to be inadequate.

    Last week, the Ministry of Science and Technology announced that Bithumb, Korbit, Coinone, and Upbit, which are among the 13 being investigated, are required to receive 2018 Information Security Management System (ISMS) certification, a system that certifies that the information protection system of companies with annual revenue of more than 10 billion won and average daily visitor of over 1 million is appropriate. They have also been urged to strengthen the security of their exchanges.

    Small and medium-sized crypto exchanges that are not required to meet this standard will be subject to the Personal Information Management System, an “autonomous certification system that assesses the comprehensive management system of collecting, using and destroying personal information of companies.” For these exchanges, the Korea Communications Commission (KCC) will be responsible, strengthening the protection of personal information. The Commission will also strictly enforce punitive fines and penalties for exchanges that violate related laws.

    The government also warned that cryptocurrency is not a “legal tender whose value is guaranteed by the central bank” and therefore its prices could fluctuate by a great deal and result in enormous losses.

  • Asian Pac’s diverse and original real estate projects attract Asia-Pacific investors

    Asian Pac’s diverse and original real estate projects attract Asia-Pacific investors

    Touted as Kota Kinabalu’s one-stop premier shopping destination and one of its largest retail establishments, Imago KK Times Square has set the bar for shopping centres in Sabah’s flourishing capital.

    Encompassing 800,000 sq ft of world-class retail, entertainment and dining outlets, the four-level landmark mall forms part of KK Times Square – a modern, vibrant and strategically located 24-hectare mixed-use development project comprised of office, residential and commercial space.

    It is Kota Kinabalu’s first non-stratified retail establishment with wholly management-owned and operated tenant stores. Since its opening in 2015, it has reached a tenant occupancy rate of 90 per cent with more than 300 retail outlets.

    Imago shopping mall and KK Times Square would have been but invisible twinkles on the Kota Kinabalu horizon without the initiatives of industry-leading Malaysian real estate developer Asian Pac Holdings.

    A company that is forging a reputation as the partner-of-choice among Asian and Chinese developers, consultants and contractors, Asian Pac is reputed for its first-mover advantage, strong local market knowledge and industry expertise honed over more than 100 years.

    With a portfolio of projects ranging from landed real estate, strip malls and high-rise residential towers to township developments and niche projects such as industrial parks, Asian Pac’s generalist approach to property development is a key advantage.

    “Being able to tackle a wide range of property types gives us strength in planning wider scale or stand-alone projects effectively,” says managing director Mustapha Buang. “Our differential edge is that we look into areas others tend to overlook with educated research. We focus ahead and look at what the potentials are. To a certain degree, we have a first-mover approach by looking into locations, themes and ideas that people have never tried before.”

    Led by a strong management team of young multidisciplinary professionals, Asian Pac traces its expertise and origins back to 1913. The company entered Kota Kinabalu in the early 2000s through its construction of KK Times Square.

    Apart from Imago, KK Times Square also houses The Loft Residences – Asian Pac’s premier residential address featuring an exclusive and integrated lifestyle experience.

    Nestled within KK Times Square’s vast leisure and recreational space, The Loft Residences offers 631 highly sought-after units ranging from US$413,898 to US$658,739 – and serviced apartments 1,834 to 4,192 sq ft in size.

    Listed on the main board of the Bursa Malaysia exchange, the company’s business interests include investment holdings, property development and investment, mall and carpark ownership and trading in building materials. By focusing on property investments with recurrent income such as the ownership and management of around 2,500 car parking bays in KK Times Square, Asian Pac keeps itself afloat through economic fluctuations.

    “We are able to renew ourselves frequently because we are quite a small team – compact, agile and capable of quickly adapting to changes,” Buang says. “We do everything in-house from leasing to facility management.”

    Asian Pac’s upcoming projects include investments in off-the-radar land banks. It also envisions to expand beyond Malaysia in the future.

    Driven to beget positive change in Malaysia through sustainable modernisation, Asian Pac has also earned the BCA Green Mark for its environment-friendly projects. Certified by Singapore’s Building and Construction Authority, the BCA Green Mark scheme is an initiative to promote sustainability in the construction and real estate sectors.

    “We always see how to make things work rather than see how things can’t,” Buang says. “We’ll still be looking at creating really sustainable projects that work long-term, and we’ll never say no to potential investors and partners who can bring added value to the table in terms of concepts and ideas – not just in the monetary sense.”

  • Chinese brands earn youth’s trust

    Chinese brands earn youth’s trust

    Young people visit a self-service shop in Qingdao, Shandong province. Today’s Chinese youth recognize major domestic brands better than well-known international brands, an AT Kearney report said.

    Chinese millennials, or people born in the late ’80s and early ’90s, and the internet generation, or those born after 1998, recognize major domestic brands better than well-known international brands, according to an AT Kearney report.

    The global consultancy surveyed more than 7,000 consumers in different age-group across China, Japan, India, the United States, the United Kingdom, France and Germany, and found several trends that will drive markets in the future.

    The report found that 71 percent of internet native consumers in China showed an increasing trust in major domestic brands, whereas 57 percent of those showed an increasing trust in international brands.

    “Chinese consumers, especially the young generation, have significantly increased their trust in local big brands. This signals a very positive sign for the rise of Chinese brands,” said He Xiaoqing, partner and head of consumption and retail industry at AT Kearney Greater China.

    “Compared with five years ago, well-known international brands will have an increasingly difficult time to gain or retain consumers’ trust merely by offering quality products and services,” she said.

    In the next 10 to 20 years, young Chinese born in the digital age will become the largest consumer group.

    The report showed that instead of swearing by big brands, about 60 percent of them are expected to prefer brands that commit to social causes, support environmental conservation and have distinctive brand values.

    This trend is particularly obvious in the food sector, with 93 percent of millennials and the internet native consumers willing to pay an extra 5 percent of the price for those products that are environmentally friendly or with a strong sense of social responsibility.

    Young Chinese consumers also tend to pay attention to the history of the brands, the report said.

    The gradual loss of trust in big international brands has been particularly significant in the UK, France, the US, and Germany.

    Now in China and India, they are still able to play the “cool kid” and “quality” cards. In the next few decades, however, it will be a different situation in China, as the younger consumers showed less trust compared to older generations, the survey stated.

    The report found that in today’s age of hyper-connectivity and social networking, individual voices can be amplified to influence the entire market, and companies are facing significant risks of losing their brand values in a short time.

    For instance, in April, a video showing a man being violently dragged off an overbooked United Airlines flight has led to an uproar on social media, and later the market value of the airline shrunk by $1 billion.

    “Consumers in the old world were defined by their possessions, and companies were able to meet their customers’ needs to an adequate degree with static business models and a ‘one size fits all’ marketing strategy that followed major trends,” AT Kearney’s He said.

    “But now, the new business model calls for highly differentiated approaches, which rely on individual influencers and those who are capable of immediately understanding consumers’ signals and translating them into action.”

    In this case, one of the most important steps is to identify the right “influencers”, also known as KOLs, or key opinion leaders.

    The report also introduced the concept of “macro influencer”, such as sports or pop-culture stars with huge number of followers of their social media accounts, as well as “micro influencer”, who are likely to be more segmented.

    For example, “micro influencers” can be bloggers with a fashion sense or foodies. They have fewer followers, but may have more impact than macro influencers because they engage more actively with their followers and therefore build trust more effectively.

  • How China is leading the ‘new retail’ revolution

    How China is leading the ‘new retail’ revolution

    While the past two years may have been brutal for brick-and-mortar stores worldwide, China’s online and offline retailers have witnessed a “new retail” revolution, driving an increasingly stronger national consumption.

    Since China launched economic reforms in 1978, the country’s retail industry has undergone multiple stages of development.

    With foreign retailers flooding in after China joined the World Trade Organisation in 2001, the scene was diversified. Offline retail started to be challenged by Taobao, Alibaba’s online shopping platform, which was founded in 2003 and grew ­exponentially in the following decade. The transaction amount for Alibaba’s “Singles’ Day” 24-hour online sales each November 11 has grown from 50 million yuan (HK$59 million) in 2009 to 168 billion yuan this year.

    With e-commerce booming, businesses have been adopting an “online to offline” (O2O) model, using online channels to attract offline traffic. In the past few years, this phenomenon has evolved into the notion of “new retail”.

    New retail represents a trend of online merging seamlessly with offline, resulting from the prevalence of digital technology, like mobile payment, wireless internet, sensors and artificial intelligence (AI).

    In this model, online is no longer just a sales channel, but provides ubiquitous touchpoints to interact with consumers and their social groups. By contrast, offline retailers are trying hard to keep consumers in their brick-and-mortar stores for longer, offering better customer experiences by leveraging digital technologies.

    From sales and marketing to ­logistics and inventory management, the new retail revolution is transforming the industry. For example, Amazon Go, the pioneer in new retail in the US, tracks purchasing behaviour with sensors placed on supermarket shelves. After consumers choose their products, they can just walk out of the store, with the amount payable automatically deducted from their mobile payment account.

    Some aspects of the retail operation are also becoming less human-led. In China, logistics firm Cainiao is incorporating hi-tech-enabled hardware and software to improve efficiency. In its logistics park, ­Cainiao deploys drones to monitor the security of the venue. Within the warehouse, several robots called “Geek+” work with staff to sort packages. It also uses computer vision to identify, monitor and ­arrange different orders.

    Improved logistics efficiency is contributing to the consumer experience as well. Consumers will not only receive their packages faster, but also with fewer errors and get fresher goods.

    China’s speed and intensity in new retail have gone into orbit

    Whereas in America, Amazon is at the forefront of the new retail revolution, China’s speed and intensity have gone into orbit. Players big and small are experimenting with various forms of new retail, making the industry more dynamic than ever.

    Driven by the huge market ­opportunities and abundant venture capital, start-ups in China are actively participating in this revolution. For example, Xingbianli, a convenience store and vending machine start-up, offers many popular Korean and Japanese products that could mostly only be bought via daigou (individuals who shop overseas and resell to Chinese consumers). More importantly, it is testing the area of unmanned retail.

    Products have their own bar code, which can be scanned by consumers when they choose their shopping and then check out on the Xingbianli app. There is also a mini-library and a ­café within the convenience store, aimed at making consumers linger.

    Traditional local retailers are also incubating their own new retail formats, such as Super Species, a subsidiary of China’s largest supermarket chain, Yonghui Superstores.

    Super Species specialises in selling fresh produce, such as vegetables and seafood, and combines the traditional market with restaurants, ­cafés, florists, and so on. It has also introduced a Yonghui Partnership Plan, allowing staff to present more innovative retail ideas and pilot them within the stores. Super Species itself is becoming an incubator for those innovative ideas, and new retail here is no longer just about changing the store format, but also the mindsets of all staff.

    Tech giants like Alibaba, Tencent and JD.com are heavily investing and competing head to head in the offline battleground. Alibaba ­invested US$2.9 billion in one of China’s largest supermarket chains, Sun Art Retail Group, in November. It aims to transform Sun Art’s offline business of over 400 ­Auchan and RT-Mart branded ­hypermarkets and provides technology to enhance customer data and inventory management.

    In 2015, JD.com invested US$700 million in Yonghui Superstores. This month, Tencent, a close ally of JD.com, acquired a 5 per cent share in Super Species, and made capital injection for a 15 per cent stake in Yonghui Yunchuang Technology, Yonghui’s supply chain and logistics subsidiary.

    To further compete with Alibaba online and enrich their own ecosystems, Tencent and JD.com are ­investing in VIP.com, a Chinese e-commerce platform specialising in discounted products for women.

    They will together own 12.5 per cent of VIP.com and, as they further monetise their traffic, the new retail battle with Alibaba will ­get fiercer.

    Foreign companies are also ­actively piloting their new retail strategy in China. Earlier this month, the world’s largest Starbucks ­Reserve Roastery opened in Shanghai, leveraging Alibaba’s technology to give consumers a more immersed Starbucks journey.

    This is also the first mass offline application of augmented reality (AR) technology. Consumers can use the Taobao app to unlock the AR features in the store, such as learning about the details of the Starbucks coffee brewing process.

    Technologies are enabling these companies to create new business approaches, while intense competition is driving all players to ­become better. They can’t afford to slow down. China’s scale also allows companies to use the market as a business laboratory and to experiment with business models.

    Consumers will ­increasingly be viewed as a ‘segment of one’ and receive more personalised solutions

    Through fast launch and adaptation, players can fine-tune their business model at a rapid pace.

    Beyond retail, the future consumption landscape will be much more complicated and sophisticated. Digital technologies, especially AI, 5G network and the internet of things, are already blurring the boundaries of industries.

    Eventually, retail will be merely one layer of the consumer lifestyle, albeit a high-frequency one. The internet of things will create a new ecosystem that is ubiquitous and interconnected. Also, 5G network development will facilitate this process in the near future and bring about disruption in the retail world.

    Assisted by machine learning and big data, consumers will ­increasingly be viewed as a “segment of one” and receive more personalised solutions, not just in ­retail, but in every facet of their life.

    To that end, China will be at the global forefront of innovation and experimentation.

  • Philippine capital markets need to be more inclusive

    Philippine capital markets need to be more inclusive

    The local capital markets may have had significant developments over the years but it remains relatively small compared to other emerging economies in Asia.

    In a span of five years, Philippine corporations have already raised over P1.7 trillion from five to eight initial public offerings (IPOs) and 10 to 15 corporate bond transactions a year.

    Retail investors have also stepped up, especially for local equity and fixed-income deals, and now account for 50 percent to 70 percent of the volume, compared to previous years where institutions take up around 60 percent to 70 percent.

    Although the scenario has gotten better, the number of IPOs and bond issues in the country still pale in comparison to other emerging economies in the region. And while participation from retail investors has increased, most of the investors are coming from the more affluent retail, leaving a huge untapped market, such as the overseas Filipino workers and the unbanked sector.

    The challenge, according to BDO Capital and Investment Corp. President Eduardo V. Francisco, is to make the local capital markets more inclusive, enabling the ordinary man on the street to invest in stocks and bonds.

    BDO Capital is a full service investment house wholly owned by BDO Unibank that provides securities underwriting and trading, loan syndication, financial advisory, and private placement of debt and equity among others.

    Speaking before capital market participants during the recent Euromoney Philippine Investment Forum, Francisco emphasized there is more to increasing financial literacy in the country to achieve inclusivity and make the local capital markets on a par with the developed countries.

    One of the solutions, he suggested, is not only to digitize but also to rid of too many touch points for IPO or bond subscriptions as these are roadblocks to encouraging many to invest in the capital markets.

    He added subscribing to equities and bonds in the country is too cumbersome due to the numerous documents, forms and identifications required.

    “Our Monetary Board, Securities and Exchange Commission, Philippine Stock Exchange are open to new ways to raise the number of investors and make it more available to the masses. We have seen them liberalize rules but we need to propose new products or solutions,” Francisco said.

    He added the Philippines should also look into new platforms and models from abroad that the Philippines can adopt, particularly innovative solutions that would minimize documentation.

    “Foreign players with platforms abroad are welcome to bring it here. Fintech solutions are also welcome and we can work with the regulators to get approvals,” he said.

  • What Hong Kong should do to boost our tourism sector

    What Hong Kong should do to boost our tourism sector

    People from other places may find it hard to imagine, but Hong Kong, although such a small city, can accommodate more than 50 million tourists each year. Of course, most of them are from the mainland.

    But the government should think of how to overhaul our tourism industry and rebuild Hong Kong into a place for cultural nourishment and entertainment activities, rather than just a big shopping mall.

    Chief Secretary Matthew Cheung said more than 52 million tourists visited Hong Kong in the first 11 months of 2017. That’s a 3 percent increase from the same period last year.

    He revealed in his blog that visitors from the mainland and the rest of the world both registered increases. The number of overnight visitors went up by 5 percent in the first 10 months of 2017, from the same period a year ago.

    More than 70 percent of the tourists came from the mainland, while those from other countries including Taiwan, South Korea, Japan and Europe just accounted for 30 percent.

    Hong Kong’s tourism industry, which employs more than 280,000 people, remains heavily dependent on mainland tourists, even after the sector has been hit hard by Chinese President Xi Jinping’s far-reaching anti-corruption campaign since 2012, which caused big-spending mainland shoppers to stay away from the territory. 

    But there are signs they are returning to the city this year. In fact, tourists from across the border treat Hong Kong as their supermarket rather than a place for leisure activities, given the perception that the quality of products and level of consumer protection in the city are higher than those on the mainland.

    But this over-reliance on mainland tourists has distorted the development of local tourism as landlords turn shopping malls originally intended to cater for the needs of the local community into attractions for mainlanders. Such orientation has not only affected the daily lives of local residents but has also turned Hong Kong into a shopping mall city, with malls housing similar retail shops and restaurants offering the same goods and services in all districts from Central and Mong Kok to Sheung Shui and Tung Chung.

    Chief Executive Carrie Lam’s administration understands the challenges facing the tourism industry, but it has not veered away from its old strategy of pouring money into hardware rather than building the city’s “soft power” to highlight the city’s uniqueness as a former British colony and China’s global gateway.

    One of the government’s biggest mistakes in trying to boost the city’s tourism industry is its decision to invest another HK$5.45 billion in Hong Kong Disneyland for its expansion plan. The investment only benefited Walt Disney while Hong Kong is left holding an empty bag as other Disneyland resorts in the region, i.e., in Shanghai and Tokyo, proved to be tough rivals.

    The government should instead promote its own uniquenes through a light show featuring our old districts.  We could, for example, try to bring back nostalgic memories of the old Hollywood Road in Central, showcasing the old office building of Wah Kiu Yat Po newspaper, the Dr. Sun Yat-sen Historical Trail, and other aspects of our storied past.

    While those buildings no longer exist in the real world, we could make use of new technologies such as augmented reality or virtual reality that allow tourists to visit the past by using their mobile phones or other smart devices.

    Perhaps, the government can partner with the newspaper society to come up with gimmicks like giving away old copies of Chinese newspapers – with the tourists’ pictures published on the front page – as souvenirs as well as a reminder of our rich history of press freedom.

    Such a model can be replicated in other different districts of Hong Kong to highlight the colorful tapestry of our culture and society that is older than the British colonial period.

    Another initiative to revive our tourism industry is to sponsor international sporting, cultural and entertainment events. The West Kowloon Cultural Zone could play a leading role in boosting our tourism industry by promoting Hong Kong as a cultural and entertainment hub.

    The government said it will come up with a comprehensive development plan for our tourism industry with new attractions and offerings. It’s about time we did.