Blog

  • Richemont Revenue Beats Estimates on Japan, Europe Demand

    Richemont Revenue Beats Estimates on Japan, Europe Demand

    Richemont, the world’s biggest jewelry maker, said sales growth accelerated as weaker currencies attracted big-spending tourists to Japan and Europe, spurring the stock’s steepest intraday gain in more than two years.

    Sales increased 4 percent excluding currency shifts in the five months through August, the Geneva-based company said in a statement Wednesday. Analysts expected a 1 percent gain, according to the median estimate in a Bloomberg survey. The shares climbed as much as 7.5 percent.

    Sales rose 48 percent in Japan and 26 percent in Europe, offsetting an 18 percent decline in Asia-Pacific. The results mirror comments by peers in the luxury business, such as Hermes International SCA, which reported higher first-half sales, fueled by an acceleration in Japan. LVMH Moet Hennessy Louis Vuitton SE in July posted strong revenue growth in Europe and the U.S., which helped offset a decline in China, Macau and Hong Kong.

    “Japan and Europe more than compensate for the weak development in Hong Kong,” said Rene Weber, an analyst at Bank Vontobel AG in Zurich. “The strong performance of those markets mean the Swiss watch industry can weather the Asian weakness, at least this year.”

    Shares in the Swiss owner of the Cartier jewelry brand, whose full name is Cie. Financiere Richemont SA, rose 6.4 percent to 76.65 francs as of 11:40 a.m. in Zurich. The report bolstered shares in the luxury-goods industry, with Hermes up 4.8 percent and LVMH gaining 3.5 percent.

    Richemont said sales in Hong Kong and Macau were “significantly lower,” while mainland China returned to growth with retail sales growing at a “strong double-digit rate.” The company reports five-month sales figures each year on the day of its annual meeting with shareholders.

    “Part of the crisis in confidence in the watch industry in Asia-Pacific is fragile confidence by independent retailers amid the problems in Hong Kong and Macau,” said Jon Cox, an analyst at Kepler Cheuvreux in Zurich, adding that Richemont’s comments about China were reassuring.

    Still, Richemont said its wholesale business continues to be weighed down by weakness in the Asia-Pacific region, which is still “extremely challenging.”

    Luxury spending in Hong Kong has been suffered since late 2012 when the Chinese government has been discouraging exuberant spending among officials. Political protests in Hong Kong last year forced some stores to shut and weighed on tourism.

    Among other luxury stocks, Swatch Group AG, the maker of Omega watches, rose 3 percent, and Kering SA, which owns Gucci, rose 4.4 percent.

  • Omni-channel to be the next big play in retail

    Omni-channel to be the next big play in retail

    “I haven’t seen such a behaviour in other South East Asian markets. While businesses in countries like Taiwan, Thailand and Philippineshave adopted e-commerce in a big way, there is a clear focus on bottomline. Money is being made on every transaction and majority of the companies there are gross margin positive,” said Iyer at the inaugural session of the two-day IRF summit in Mumbai on Tuesday.The fast emerging e-commerce sector in India has been talked about in the business world as the next big thing to be in. However, according to Krish Iyer, president and CEO, Walmart India and chairman of India Retail Forum (IRF) 2015, one thing that has hit him in the last year and half isthe whole craze about building valuations while not really looking at the bottomline.

    “I haven’t seen such a behaviour in other South East Asian markets. While businesses in countries like Taiwan, Thailand and Philippines have adopted e-commerce in a big way, there is a clear focus on bottomline. Money is being made on every transaction and majority of the companies there are gross margin positive,” said Iyer at the inaugural session of the two-day IRF summit in Mumbai on Tuesday.

    Defending the valuations game being played in the e-commerce sector in India, Alok Goel, managing director, SAIF Partners, said that India is the only country that offers an opportunity for growth investment in the global scheme of things. “Lot of money is flowing into India looking for opportunities and return on investment. And when lot of money is chasing fewer products out therein the market, the price of that product increases. This roughly explains the rapid price-valuation situation that’s come up in the market,” said Goel, adding that from a valuations point of view, businesses need to be looked at in terms of growth they will register over the next five to 10-year horizon.

    Stressing on the need for Indian retail (online / offline) players to seek profitable growth, Anurag Mathur, retail and consumer goods practice leader, PricewaterhouseCoopers India, said, currently mom-n-pop stores are enjoying operating margins of between 6% and 8%over gross margins of 16% and 18%, while the organised retailers had high gross margins of 20% and 22% though operating margins were as low as 2% and 4%. “The online / e-commerce players are still ages away from getting into the positive space with gross margins anywhere between -3% and -8% and operating margins between -15% and -22%,” he said.

    While the recent past has seen the Indian retail fraternity debate aggressively about retail and omni-channel, Iyer pointed out that a few years ago, it was about retail and e-commerce. “And from what I see on the ground, I can tell you that omni-channel will be the key focus of discussion next year. The brick-n-mortar players will continue to learn from the pure-play e-commerce players and then will be able to drive profitable growth while providing omni-channel experience to the customers. And that to my mind, is the only way to go,” he said adding that retail players, particularly those in the brick-n-mortar space, are clearly focused on profitable growth.

    Iyer stressed that ongoing economic adjustments around the world offered businesses in India a brilliant opportunity to lead global growth. And the fact that India has been a domestic consumption-driven economy has come handy. “We are not an export-driven economy and that’s one of the primary reasons why the economic turmoil and global events haven’t had as much impact on India as we have seen in other BRIC countries viz. Brazil, Russia and China,” he said.

    The next phase of retail revolution, retailers and experts said, will be driven by India and China unlike the past phases that were driven by the West. However, Indian retailers lagged in retaining a black bottomline when compared with their foreign counterparts.

    “Operating margins (ebitda) of Indian retailers have dropped to 2% in 2014 from8% in 2011. During the same period, ebitda of select international retail chains like Walmart, Target, Tesco and Home Depot have maintained 7-11% during the same period,” said Mathur.

    In fact, according to a survey conducted by PricewaterhouseCoopers India, over 65% of Indian retailers are focusing on improving profitability through improvement in revenue throughput as fast-changing consumer behaviour is driving many retailers to rethink their business model. As per the survey, 53% retailers are considering a change in their operating model driven by changing consumer behaviour.

    With the emergence of new formats, distinct paths to sustainable profitability will need to be crafted as retailers in India face a herculean task of reaching out to the customer through a combination of mobile, social and human connect, experts said.

    According to Abheek Singhi, senior partner and director, Asia Pacific leader –consumer and retail practice, The Boston Consulting Group, online and e-commerce with varying digital density along with omni-channel are straining traditional business models in retailing. “Moreover, with consumer companies selling directly via offline and online tools, value chains are also getting disrupted,” he said.

  • China August Retail Sales: E-Commerce Remains Robust

    China August Retail Sales: E-Commerce Remains Robust

    China reported August retail sales that grew 10.8%, which beat the consensus 10.6%. Most encouraging was that online retail sales remain robust, underscoring my bullish view on Alibaba. As for offline retail, jewelry grew off a lower base so we view this of a lower quality while it appears that offline electronic retailers are taking share from online retailers, which is a negative to JD.com. We see China retail numbers to be a good read-through to companies such as BABA and JD as well as North American companies with exposure to China such as Tiffany. We reiterate my bullish view on BABA and Nike and our cautious view on JD and TIF.

    Online retail numbers remain robust for the first eight months of the year, and this is a positive indicator to Alibaba. For the first eight months, online retail sales grew 36% and accounted for 9.8% of total retail sales vs. 8% a year ago. Worth reminding investors is that China leads the world in e-commerce penetration and we expect penetration to continue to grow, driven by mobile device penetration in second and third-tier cities as well as the lack of proper retail infrastructure in those cities. We can easily envision China’s online retail penetration to reach 20% in the next 10 years driven by those two factors as well as higher mobile consumption driven by online-to-offline services that are heavily invested in by BABA, Baidu and Tencent. Looking at the individual segments, online sales of services was up a whopping 41%, as were discretionary items such as food. Apparel grew 27% and other discretionary items grew 39%. All these figures imply that August online sales alone grew 27% y/y, still solid given the near-term weakness of the Chinese economy.

    As for offline retail, jewelry grew 17% y/y vs 14% in July but it was largely due to a lower base from last year. As such, we would not be quick to jump into TIF stock until we see material improvement from the demand side. Interestingly, home appliances and electronics accelerated in the month, up 14% vs. 8% in the prior month. This could potentially be a negative to JD.com given this could imply that BABA and Suning JV may be taking share from JD in the online segment.

    In conclusion, we remain bullish on BABA while cautious on JD and TIF.

  • Korea more active than Japan in Southeast Asian tech

    Korea more active than Japan in Southeast Asian tech

    In a region where masses of users are newly armed with smartphones and more spending power, Southeast Asia is a new gold mine for tech enterprises.

    China’s quickly saturating market for all things tech has pushed Asia-bound start-ups to seek new territory, and global companies like Rakuten, eBay and Rocket Internet are vying over Southeast Asia with no clear winner ― meaning plenty of opportunities still abound for new players.

    Those conditions drew Korean-Japanese entrepreneur Tesong Kim, who led e-commerce at Japanese investor Rakuten’s offices in Tokyo and Jakarta, to launch his own discount retail start-up VIP Plaza for fashion goods in Indonesia, Southeast Asia’s biggest market, in 2014, and recently expand to Malaysia.

    And Korea’s start-ups are joining the rush, he says.

    They seem to be making bigger waves there than in Japan. He cannot list any Korean start-ups with a big presence in the country, a closed, conservative market that is a nut nearly impossible for foreign companies to crack. But in expanding to Southeast Asian markets like Singapore, Indonesia and Malaysia, he says they are far more active than their Japanese rivals.

    “Korea is quite aggressive in Southeast Asia, I think more aggressive than Japan in terms of e-commerce start-ups,” he told The Korea Herald in an interview on the sidelines of tech start-up conference Tech in Asia Tokyo 2015 last week.

    “Korea is very crowded. The population is very small, geographically the landscape is very small, and there’s a lot of start-ups. So it’s quite packed, but I think Japanese investors think Korean start-ups can go global more than Japanese start-ups.”

    Indeed, SK Planet’s e-commerce retailer 11st is seen harnessing the region’s demand for Korean fashion and beauty products, while couples messenger Between and crowdsourcing translation app Flitto are also gaining traction in markets like Indonesia, Taiwan and Thailand.

    Meanwhile, Kim says Japanese start-ups are trapped at home, falling hard when they try to copy and paste their successful domestic strategies into new markets.

    But competition in Southeast Asia is heating up fast. Kim believes Korea’s KakaoTalk lost the messenger app war in the region to rivals like BlackBerry, WhatsApp, LINE ― one successful Japanese exception in the region ― and WeChat because it entered too late.

    That’s why it has pivoted to commercial services such as e-commerce when targeting markets like Indonesia, he said.

    Not that e-commerce is any easier, as Kim knows from his experience with Rakuten’s Indonesian e-commerce venture and starting his own online discount retailer. Handling logistics, acquiring products and dealing with fragmented, cash-based payment systems takes immense effort.

    But due to the region’s overall cheaper costs, he believes Korean and Japanese start-ups underestimate the investments they need to gain ground ― a mistake that will get them steamrolled in the market. “They think that with $1 million-$2 million, they can go to Indonesia, try to develop ― with that kind of mindset, they will never succeed,” he says. “All the very aggressive companies are investing into Southeast Asia with a very big amount of money.”

    Even for Korea’s prized e-retailer Coupang, which received a $1 billion boost from Japan’s SoftBank Ventures this year, it might already be too late to test the region’s waters, he said.

    “What they have is a know-how of how to sell things, of impulse buying. They have a system and good talents, but they are not localizing the region,” he said. “If they tackle some new country now, they need to invest in everything ― the products, warehouse, marketing and user acquisition.”

    But the market is already crowded by Lazada, Elivenia and Rakuten, not to mention 11st and Kim’s own start-up VIP Plaza. “I think it’s already too late in terms of social commerce,” he said. “The better strategy is buying out some local players. It’s not only easier, but much cheaper.”

    Still, Japan’s massive opportunities can’t be ignored, he says. Its app market is the biggest in the world, and gaming companies are seizing opportunities. “So in that sense, I think the market is still very big.”


  • ‘Weak’ Hong Kong and Macau hits Prada

    ‘Weak’ Hong Kong and Macau hits Prada

    Continuing volatility in the market and the exchange rate landscape in Hong Kong, Macau and the Asia Pacific region (excluding Japan) has been blamed for Prada’s overall net profit fall of -23% to €188.6m ($212.7m) in the first half of 2015.

    Despite the big challenges in the Asia Pacific region which is Prada’s biggest market, the Milan-based fashion company first half-year revenue growth of +4.2%, thanks to more positive market performances in Europe, The Americas, The Middle East and Japan.

    Consolidated net current exchange rates on the corresponding period in 2014.

    The luxurygoods company says the increase is entirely attributable to the retail channel, as a result of its selective strategy aimed at further enhancing the of its Directly Operated Stores.

    All other regions reported good growth, although the company adds that the Asia Pacific market (excluding Japan) showed the same negative trend as it did in the first quarter of the year, offset by a positive effect.

    Patrizio Bertelli, COO said: “The luxury goods market is undergoing a period of significant change which must be met with a far-reaching, long-term strategy.

    “Our commitment remains centered on creative dynamics and the spirit of innovation, so that we can constantly increase the levels of excellence of our products.

    “In operational terms, we will continue with our thorough review of business processes in order to make them more efficient.”

    While its wholesale business declined by 13%, sales of the group’s retail network grew by 7.6% at current to €1,552.4m ($1,750.7m). The company reported that its 605 Directly Operated Stores (DOS) also benefited from a general improvement in sales performance.

    The European market grew by +12.4% thanks to a steady flow of tourists, together with a recovery in consumption by domestic customers, while the Japanese market outshone the rest of Asia with a +11.7% constant result. Sales in the Americas and the Middle East also improved considerably (both plus +15%).

    In terms of retail channel by brand, Prada recorded a 5.4% rise in sales thanks entirely to the effect, but was badly impacted by the negative economic situation in the Asian market.

    Miu Miu grew with revenues up at both current (+18.7%) and constant (+6%), enjoying a sales boost in the second quarter. The Church’s shoe business also grew by +18.6% and Car Shoe’s result was in line with the same period last year.

    EBITDA for the first half of the year was €440.1m ($496.3m) or 24.1% of net revenues, while EBIT came in at €293.2m ($330.7m) or 16.1% of consolidated net revenues.

    As mentioned, was reported down -23% at €188.6m ($212.7m) or 10.3% of consolidated net revenues.

  • Lulu Group to enter Indonesia

    Lulu Group to enter Indonesia

    Plans $500mn investment in the country over the next five years

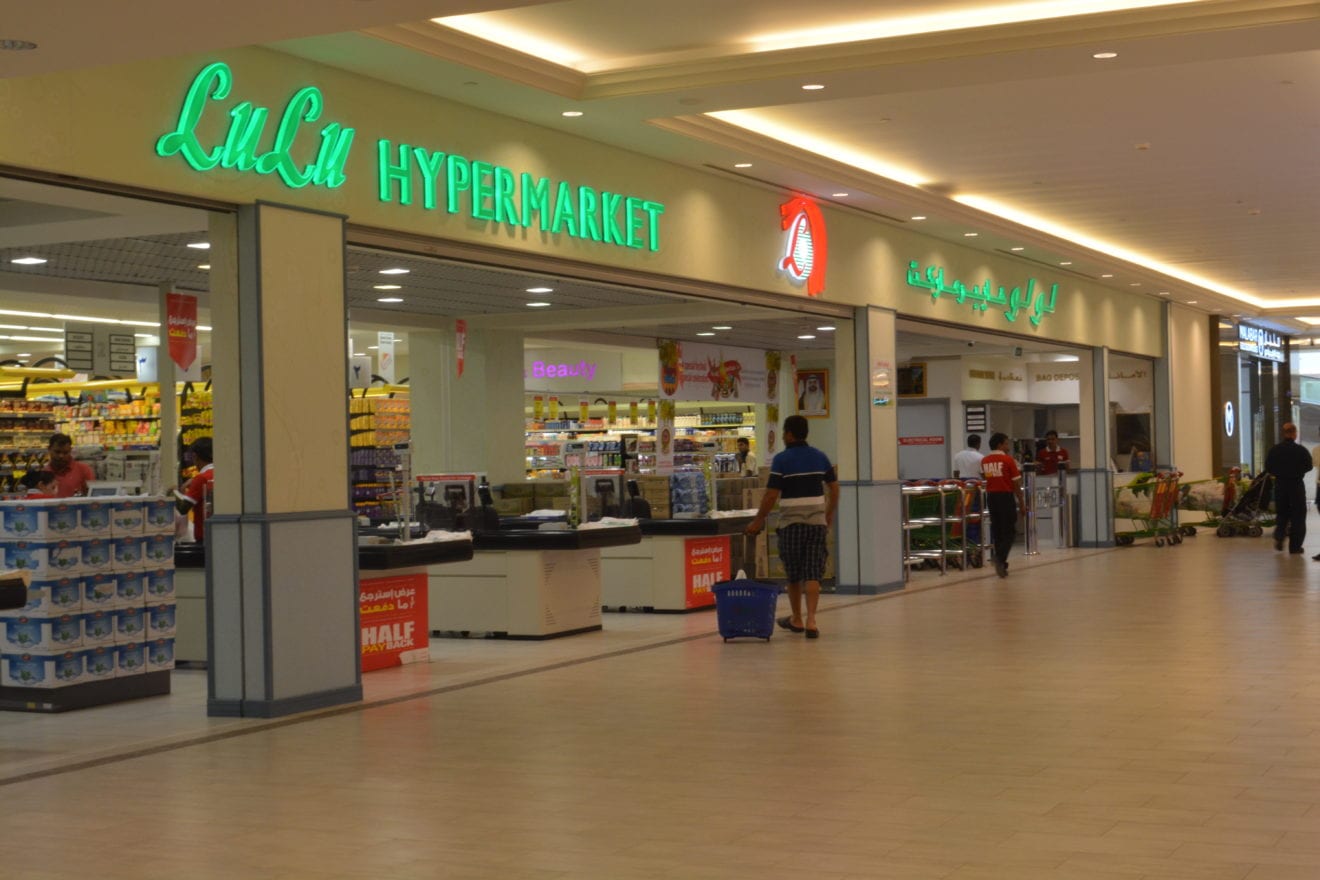
    The first LuLu Hypermarket in Indonesia will be opened in Jakarta by the year-end as the group has announced plans to invest $500mn in the country over the next five years.  The announcement came during the visit of Indonesian President, Joko Widodo to Abu Dhabi. He visited LuLu Hypermarket along with a high-level delegation at Khalidiyah Mall in Abu Dhabi. “With an initial investment of $300mn in the first phase, we plan to open some 15 hypermarkets by the end of 2017 and a central logistics and warehousing facility in Jakarta.

    These projects are likely to generate more than 5,000 job opportunities for Indonesians and help train them at all levels” said MA Yusuffali, LuLu Group managing director. The fact that we are going to Indonesia with our Halal Hypermarket concept, is giving us the encouragement to look for a wider market segment there” Yusuffali said. Apart from Jakarta, LuLu intends to open hypermarkets in Bandung, Solo, Semarang, Surabaya and Yogyakarta. “We also plan to set up contract farming to ensure continuous supply of high-quality products and support the Indonesian agriculture sector,” Yusuffali added.

    The Indonesian president is on a five-day state visit to Saudi Arabia, the United Arab Emirates and Qatar, to boost the country’s ties with the three countries, particularly on investment, trade and Indonesian migrant worker protection.

    Coordinating Minister of Economy Darmin Nasution, Trade Minister Thomas Lembong, Minister of National Development Plans Sofyan Djalil, State Secretariat Minister Pratikno, head of the Investment Coordinating Board Franky Sibarani and Cabinet Secretary Pramono Anung were also part of Widodo’s delegation.  The Indonesian president was given a rousing welcome at the LuLu Hypermarket by Yusuffali; Saifee Rupawala, CEO; Salim MA, director; Rajmohan Nair, director – LuLu (Far East Operations); and a large number of Indonesian expatriates.

    President Widodo and the accompanying delegation were taken to a guided tour of the hypermarket by Yusuffali who briefed him about specialties of the retail store. The president later said his visit to LuLu Hypermarket was to see Indonesian products mainly agricultural products and asked Yusuffali to import more products from villages and towns in Indonesia.  A LuLu release said Widodo inquired about the prices as well of the various Indonesian products imported to Abu Dhabi.

    The LuLu chain currently operates some 117 stores across the UAE, Oman, Bahrain, Kuwait, Qatar, Saudi Arabia, Yemen, Egypt, and India.

  • Lotte chief vows to improve corporate governance

    Lotte chief vows to improve corporate governance

    By Kim Eun-jung

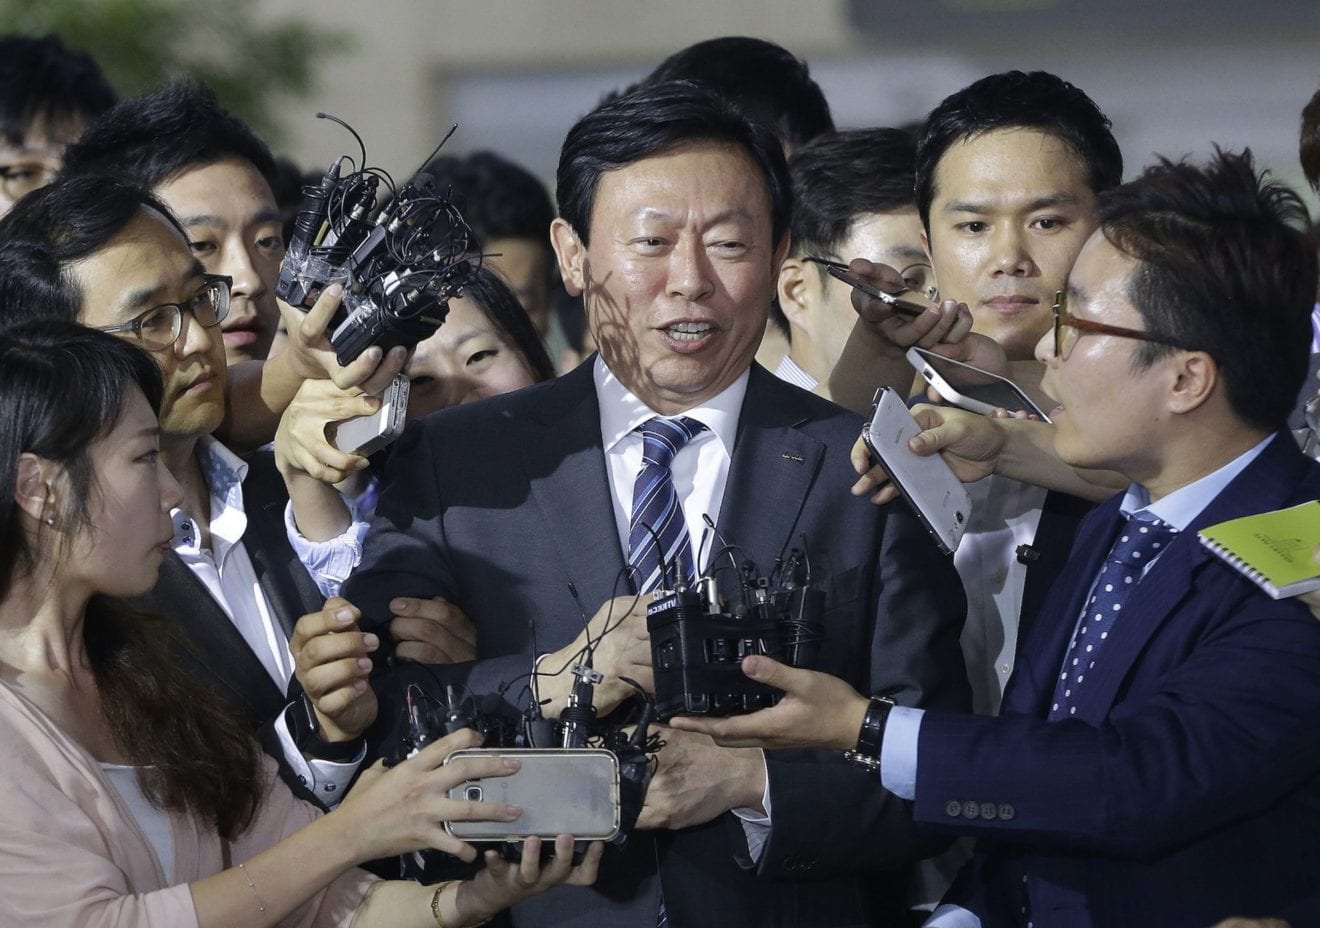
    SEOUL, Sept. 17 (Yonhap) — The chief of South Korean retail giant Lotte Group pledged Thursday to untangle a cobweb of cross-shareholding among its affiliates and speed up the listing process of its hotel unit.

    Testifying before a parliamentary committee, Shin Dong-bin also ruled out the possibility that Lotte, the fifth-largest family-run conglomerate in South Korea, may be embroiled in another family fight over leadership.

    Shin appeared before a parliamentary audit of the antitrust watchdog the Fair Trade Commission, tasked with assuaging public discontent after a bitter fraternal feud over winning control of the nation’s fifth-largest conglomerate.

    After winning the backing of Japanese shareholders last month, the 60-year-old has vowed to improve corporate transparency and list Hotel Lotte, a hotel and duty-free operator.

    During the nationally-televised audit session, Shin apologized for the family feud and vowed to clean up 80 percent of the cross-shareholding structure by the end of October.

    “We formed a task force to improve the governance structure and restore the brand image,” Shin said.

    Lotte has listed only eight companies and the core units are linked through unlisted Japanese units. Shareholders of the small Japanese firms remain largely shrouded in darkness because they are not subject to Korea’s financial disclosure rule.

    As part of reform efforts, Shin bought 35.8 billion won in Lotte Confectionery Co. shares from Lotte Construction on Aug. 28, clearing up about 34 percent of the cross-shareholding links.

    Shin said the task force is working on the initial public offering for Hotel Lotte, with plans to complete it by the first half of next year. Last week, Lotte selected three lead managers for the planned initial public offering.

    Hotel Lotte is 99 percent controlled by Japanese shareholders, including Tokyo-based Lotte Holdings and other unlisted Japanese companies.

    Lotte said earlier the hotel unit is expected to have a market capitalization of around 10 trillion won ($8.5 billion) when it lists, but market watchers estimate it could reach as much as 20 trillion won, considering its large stakes in affiliates and strong earnings.

    When repeatedly asked about the company’s identity, Shin said Lotte is a Korean company that generates most of its sales locally.

    “Lotte is a Korean company because it pays tax according to the Korean law and its employees are Koreans,” Shin said, noting he will maintain the Korean nationality.

    Founder Kyuk-ho was born in the South Korean port city of Ulsan, 414 kilometers south of Seoul, while his sons were born and raised in Japan by a Japanese mother.

    Lotte has tried to allay public discontent over its historic links to Japan as it could deal a harsh blow to the group that heavily relies on the retail, food and travel industries.

    Lotte was first established as a confectionery store in postwar Japan in 1948. It later expanded into Korea when diplomatic ties between Japan and Korea were normalized following Japan’s colonial rule from 1910 to 1945.

    Although lawmakers’ summoning businessmen has been a longstanding ritual as a way to flex their muscles in front of cameras, it is the first time the head of one of the nation’s top 10 family-run conglomerates, called chaebol, showed up before parliament to face acrimonious questions.

    Shin was called in for a 2013 parliamentary audit, but he evaded it, citing overseas trips and instead paid fines. But this time, negative public sentiment and growing government pressure left him no choice but to clarify issues related to the governance structure and other related issues.


  • Swisse bought by Hong Kong company Biostime

    Swisse bought by Hong Kong company Biostime

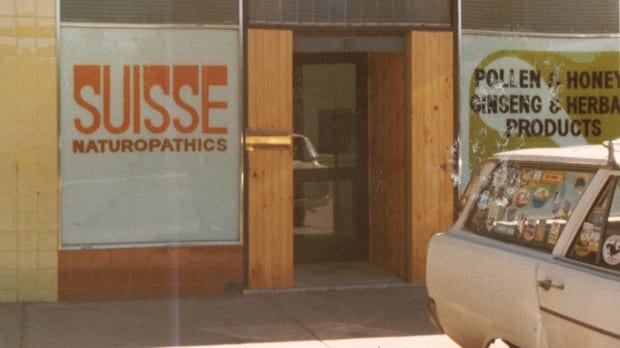
    The first 'Suisse' shop in Airport West in Melbourne in the 1970s.The first ‘Suisse’ shop in Airport West in Melbourne in the 1970s.

    It was the brainchild of organic baker Kevin Ring, who started selling pollen tablets from his St Kilda naturopathics shop back in 1972.

    Ring’s hand-made vitamin tablets, inspired by a trip to Switzerland in the late 1960s, were soon doing better than the bread, and a little shop under the Suisse brand was opened in Melbourne’s suburbs in the early 1970s.

    Later changed to Swisse for legal reasons, that little shop blossomed into the country’s biggest wellness company, and has just been sold to overseas buyers for an astonishing $1.67 billion.

    Hong Kong-listed company Biostime International Holdings on Thursday won the auction to buy Swisse, beating out two Chinese companies, Hony Capital and manufacturer Shanghai Pharma, on the way. Swisse will remain based in Melbourne, with a head office in Collingwood, but 83 per cent of the company is now in the hands of Biostime.

    The deal will lift the fortunes of Kevin Ring’s son, Stephen, and his business partners Radek Sali and Michael Saba. All become some of Melbourne’s richest men, with estimated net worths in excess of $250 million each.

    It’s a long way from the company’s first outlet back in the 1970s, a “naturopathics” shop in working-class Airport West.

    The Swisse deal highlights the demand for Australian brands and products in China, which are regarded as “clean and green” when compared with domestic produce. The share price of rival Australian vitamin maker Blackmores has more than quadrupled in the past year, from $31 a share on the ASX to in excess of $137.50 during trade on Thursday, on the back of massive sales growth in China.

    Australian infant formula brands, such as Bellamy’s Organic and A2 Platinum, have notched windfalls sales thanks to huge demand from China.

    Much of the success has come from internet and grey market sales, with gangs of Chinese students buying up stock from Australian chemists and supermarket shelves to send back home.

    One milk industry CEO recently suggested Australian domestic sales of infant formula were now more than double the actual consumption by Australian babies.

    A2’s Australian chief executive, Peter Nathan, admitted the success of his infant formula was partly based on shoppers sending his product to China.

    “We have had significant growth on online sites such as Alibaba, and also at retail level at grocery and pharmacy where Chinese tourists and nationals are often buying products on trips and taking it back with them,” he said. “We are clearly demonstrating that we are having enormous traction with Chinese nationals. There is no question about that.”

    The deal at Swisse justifies the big-spending strategy of CEO Radek Sali, a former executive at Village Roadshow. His father, Avni Sali, helped to develop the men’s and women’s Ultivite range of multi-vitamins for Swisse, which have been the mainstays of the company for the past decade.

    When Radek became CEO in 2005, he embarked on a massive marketing push. Nicole Kidman and Ellen De Generes were signed as ambassadors, along with a galaxy of sports stars including Cadel Evans, Ricky Ponting and Mark Webber.

    Lavish parties at the Birdcage at Flemington helped push the glamorous image.

    Such was the extent of the marketing push, at one point Swisse’s $50 million annual marketing spend was almost 40 times the cost of the ingredients used in vitamin production. It was all part of Radek’s plan to make vitamins “fashionable and fun”.

    That has paid off.

    “We have grown from small, family-owned business in the suburbs of Melbourne to become Australia’s number one wellness brand,” Sali said after the deal was inked. “We have done it on the back of an unwavering commitment to the highest standards of quality, safety and product efficacy.”

    Founding shareholder Stephen Ring was equally happy after the deal.

    “I am incredibly proud to have been part of Swisse’s journey so far,” he said. “The strength of the business is testament to the hard work, passion and energy of the entire Swisse team and I thank them for their ongoing commitment.”

  • Diesel targets China in copy clampdown

    Diesel targets China in copy clampdown

    Italian lifestyle brand Diesel says it is initiating legal action against an average of three Chinese companies every week in its war against copycats selling copies of its apparel.

    “Hundreds of legal actions are in place against usurpatory brands, especially in China,” the company said in a statement outlining the enormous scale of the counterfeit goods trade and its astonishing campaign to fight back.

    Last year, Diesel says it started a legal action by the US Federal Court in New York, against 83 sites, which were illegally selling counterfeited products by using the cybersquatting technique – registering domain names with “Diesel” in the address.
    So far Diesel closed 3346 sites, sent 4000 ‘cease and desist’ letters, and de-listed 19,000 sites from Google. Just 131 of those sites were in Asian countries.

    “It has been calculated that in this way the company has avoided about 700,000 visits to illegal marketplaces; 9200 bids [from prospective buyers] have been removed completely,” the company said.

    Fake Diesel jeans seized in a raid.

    In Asia, over the past year Diesel obtained to remove 6786 listings on marketplaces, for a total of 1.7 million items.

    Diesel has worked with Customs agencies to seize more than 60,000 items coming from China in 2013, and another 75,000 last year, and more than 80,000 items in the European Community.

    In China, 1300 items have just been confiscated in a factory producing counterfeited t-shirts, and in another factory the police seized 910 pairs of shoes with Diesel logo, along with a quantity of unfinished products worth US$155,000.

    Last month, Diesel successfully closed the case of the ‘Diesel Cluthing’ line, which was signalled by Diesel business partners who found infringing products circulating in the Colombian market. After thorough investigation, the Chinese authorities confiscated 520 jeans infringing the Diesel trademark: the company, who registered this logo, is now under an opposition process.

    On top of these activities, Diesel says it has established a system to register its iconic products and therefore ensure that any potential copy is identified and sequestrated (in the last six months only, four cases have been closed successfully). The latest triumph took place earlier this year, when Diesel finally won back the property of its brand in Indonesia – a legal battle which has lasted 23 years.

  • Fortress Hong Kong flagship opens

    Fortress Hong Kong flagship opens

    Electronics chain Fortress has opened a 10,000 sqft flagship at Times Square.

    The AS Watson Group subsidiary, sells mobile phones and consumer electronics across Hong Kong and Macau. Its new Times Square store is spread over two floors – eight and nine – and split into themed areas.

    Fortress Times Square Hong Kong2

    A dedicated home theatre and TV zone is dominant and there is an area dedicated to demonstrating 3D printing technologies.

    There is also a dedicated Apple space.

    Fortress Times Square Hong Kong1

    Another unique feature of this Fortress Hong Kong store is a cafe serving fresh coffee and offering free WiFi.

    The store was opened by Hong Kong actor and singer Andy Hui.

    It’s been likened to “a digital theme park”.

  • Singapore retail sales stabilise

    Singapore retail sales stabilise

    Real Singapore retail sales rose 2.6 per cent in July over June and by 0.8 per cent year on year.

    That’s according to official government data after the sales of motor vehicles are removed from the figures.

    That follows falls of 3.9 per cent and three per cent in June, respectively.

    The total retail sales value in July 2015 was estimated at $3.5 billion, higher than the $3.3 billion in July 2014.

    Singapore retail chart 1509

    Year on year, sales of watches & jewellery fared the best, up 11.7 per cent. Retail sales of medical goods & toiletries, telecommunications apparatus & computers, recreational goods and department stores all rose between three and 10 per cent.

    In contrast, retail sales of petrol service stations decreased 16.4 per cent; sales of furniture & household equipment, optical goods & books, mini-marts & convenience stores, food & beverages, wearing apparel & footwear and supermarkets declined between 0.8 per cent and 5.5 per cent.

    After seasonal adjustment, month on month sales of wearing apparel & footwear, furniture & household equipment, supermarkets and petrol service stations declined between 0.7 per cent and five per cent.

    Watches & jewellery, medical goods & toiletries and recreational goods increased between 10.6 per cent and 13.4 per cent compared to June. Sales of telecommunications apparatus & computers, optical goods & books, food & beverages, mini-marts & convenience stores and department stores rose between 0.7 per cent and 8.2 per cent.

    Singapore retail chart -1509

    Meanwhile, sales of food and beverage services (seasonally adjusted) increased 3.1 per cent in July 2015 over June, but declined one per cent year on year. The total sales value of food & beverage services in July 2015 was estimated at $640 million, lower than the $647 million in July 2014.

  • Singapore’s Changi seeks retail tenants

    Singapore’s Changi seeks retail tenants

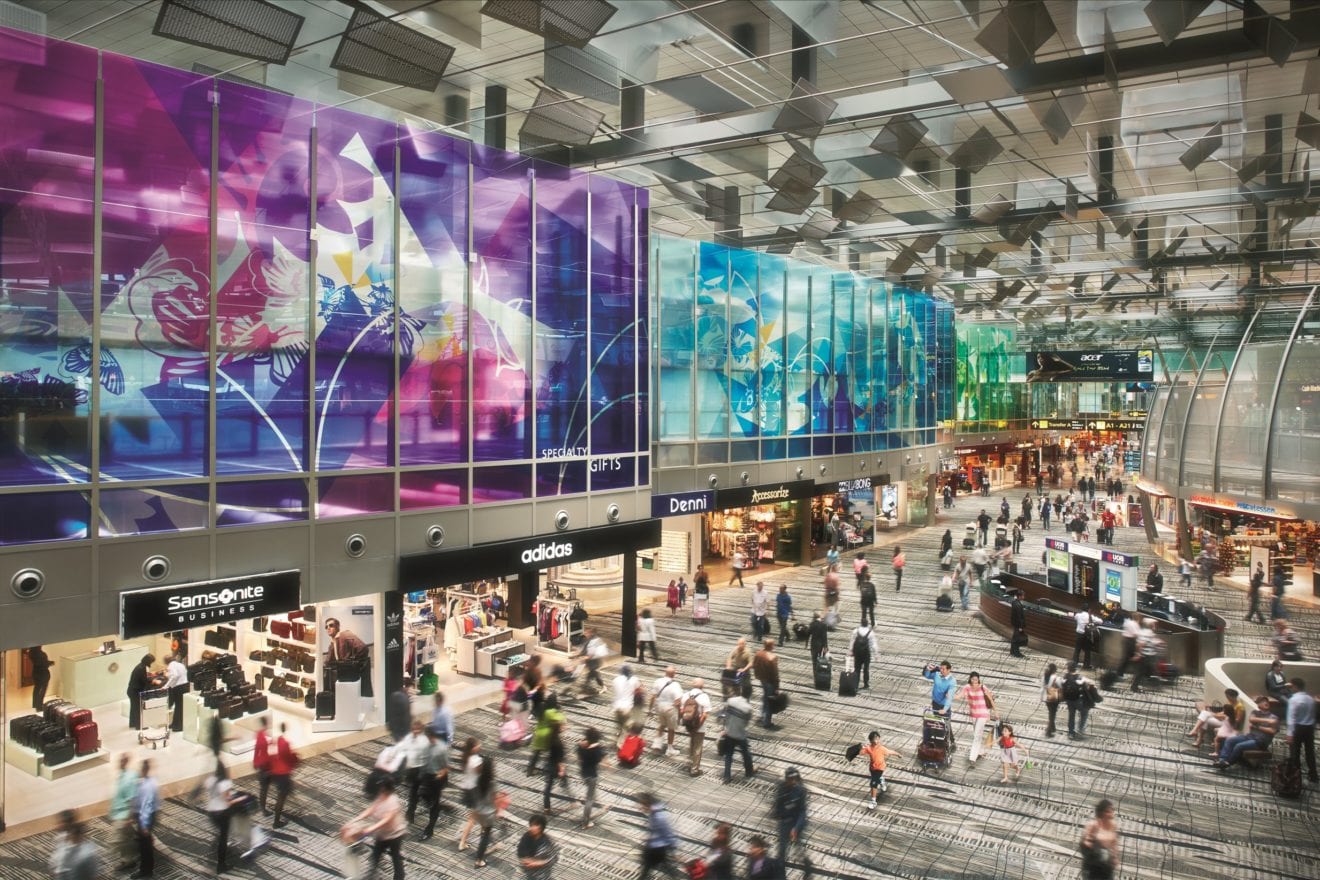
    Changi Airport is seeking new retailers for concessions in Terminals 2 and 3, along with food and beverage operators.

    The airport has a fashion concession available in Terminal 2 within the departure/transit lounge area for which it says it is seeking a multi-brand boutique from a retailer capable of delivering “a luxurious shopping experience”.

    The space is 519 sqm with a contract period of three years. Changi says the space can incorporate store-in-store concessions for individual brands.

    In Terminal 3 it has an open category concession, meaning it is open to approaches from retailers in any category. That 25.4 sqm space is on Basement 2 in the northern end of the terminal, and also has a three year term.

    “We are looking for brands with proven track record over the years that will differentiate the retail offering at Terminal 3,” said CAG in its documentation.

    Submissions close on September 21.

    Meanwhile, the airport is seeking a range of food and beverage operators – including Chinese restaurant, a food court solution and a canteen.

    The deadline for submissions for these spaces range from September 28 to October 15.

  • Indonesian HR startup Talenta snaps up funding from Fenox and East Ventures

    Indonesian HR startup Talenta snaps up funding from Fenox and East Ventures

    Indonesian cloud-based human resources management startup Talenta announced earlier today it raised a bridge funding round of an undisclosed amount. The round was led by Fenox Venture Capital and participated in by existing investor East Ventures. Talenta says the funding will be used to ramp up hiring, bolster sales, and increase marketing efforts.

    Since inception, the startup has managed to garner several tech clients in Southeast Asia, including some well-known firms like Go-Jek, GrabTaxi, TopasTV, FlowerAdvisor, Qraved, MicroAd, Kudo, ShopDeca, and more. “It has been a roller­coaster ride for the past six months for Talenta but we finally managed to get a product­-market fit,” says founder Joshua Kevin. “I believe that the trend is with us. SaaS is going to be the new standard”

    Last September, Kevin told that the company’s original concept was to provide varied services for local startups including public relations, community outreach, and events organization. But soon after, following a seed investment from Grace Tahir and East Ventures, Talenta moved its core focus toward human resource services only. It launched in beta the following February.

    “It’s been exciting to see Talenta’s progress this year. They’re hitting a billion-dollar industry with full force by offering a tool to help tackle one of the biggest verticals most Indonesian businesses struggle with today,” says Anis Uzzaman, partner at Fenox.

    Following the funding round, Talenta plans to expand its monetization method from subscriptions only to include transaction-based revenue. Kevin did not reveal exactly what transactions Talenta will monetize, or what the profit margins could look like, but he did say Talenta will likely work with Jakarta fintech players like CekAja, HaloMoney, and Cermati to help its users apply for products like loans and credit cards.

    “It was a natural movement for us as we grow from product to platform,” explains Kevin. “The subscription-based model has limitations in and of itself while [the] transactional [model] has huge potential.” With more than 1,500 employees on Talenta, the startup is also pushing to partner up with large companies instead of focusing on SMEs only. In the past, Kevin cited Talenta’s focus on small and medium-sized businesses as the company’s core offering.

    Talenta has also launched its software with a new design. It has added more features, including an employee self service option for leave, overtime, and reimbursement requests. Now that Talenta is gunning for larger enterprises, it will likely start to see more direct competition from the likes of international players like Oracle, SAP, DataOn, and SunFish HR.

  • AirAsia flying high again

    AirAsia flying high again

    AirAsia Bhd has been facing strong headwinds lately. The budget carrier’s share price has been on a roller-coaster ride over the past couple of months, fluctuating dramatically.

    The airline’s shares have been under pressure for some time and plunged to 78 sen on Aug 26. Its share price has since rebounded sharply from that recent low, with analysts calling it an overshooting of its price during the selldown. AirAsia became a penny stock at the end of last month and stayed below the RM1 mark for about two weeks. Its share price has since rebounded, closing at RM1.31 yesterday.

    Year to date the counter has lost more than 50%.

    What triggered the quick recovery?

    Analysts say the recent selldown was overdone and the market has ignored the significant value of its portfolio comprising non-airline businesses within the group. In addition, they note that AirAsia’s fundamentals are intact and it is undervalued.

    Maybank Investment Bank Bhd analyst Mohshin Aziz concurs that the selldown was overdone and maintains a “buy” call on AirAsia with a target price of RM2.05.

    “It is a highly beaten down stock. Given the situation, it is the highest candidate (to be picked up by investors),” he tells StarBizWeek.

    Mohshin notes that AirAsia has been very active this year engaging the investment community by having meetings, teleconferences and so forth but to no avail as it shares continued to be beaten.

    “AirAsia is cheap. Cheapest in its history in US dollar terms and also the cheapest airline stock in the world currently,” he says.

    Mohshin says there is no point talking about valuations of AirAsia, as it is beyond fire sale.

    “We derived an alternative and tangible valuation methodology for AirAsia, given that the conventional ones are gaining no traction. We took the latest available appraised value of its fleet, net off its long-term debt and times it by the ringgit at RM4.3 to the dollar and we get an intrinsic value of RM1.34 per share. Basically, the metal value of the business is higher than the current market capitalisation.

    “Shareholders can make a nice 18% gain by just selling off the fleet whilst keeping the RM4.8bil of equity,” he remarks.

    It is worth noting that the US-based Wellington group of companies which had reduced their stakes in the low-cost carrier in June this year have started buying shares in AirAsia.

    According to the latest filings with Bursa Malaysia, Wellington Management International Ltd has 200.74 million shares, or 7.214% stake in AirAsia. Wellington Management Global Holdings Ltd has an indirect 228.19 million shares or 8.2% stake, while Wellington Group Holdings LLP has an indirect 278.99 million or 10.025% stake.

    The Employees Provident Fund (EPF) had on Sept 3 acquired 2.498 million shares in AirAsia but it disposed 892,500 on Sept 9.

    “AirAsia took a beating but it is now a V-shape recovery. Wellington and EPF are back. They have been buying and hopefully the worst is behind for AirAsia. The counter has been attracting high trading volume,” an analyst say.

    The turbulence comes not in just its shares being sold down. AirAsia is also battling with other issues such as the report by accounting research firm GMT Research that raised questions about related party transactions. GMT Research had highlighted problems with the company’s accounting practices and raised concerns regarding the firm’s cash flow, leverage and group structure.

    News that PT Indonesia AirAsia (IAA) may be shut down by the end of July also caused a panic among investors.

    AirAsia’s 49%-affiliate IAA has received a letter from Indonesia’s Transport Ministry laying out terms for it to ensure a positive equity position by July 31.

    Indonesia’s Transport Ministry has ordered 13 airlines to raise funds to reach positive equity positions out of concerns that a negative equity would affect safety oversight.

    Futhermore, the company’s latest quarterly results provided little cheer to investors. In the first six months to June 30, AirAsia’s net profit fell to RM392.36 mil from RM506.87 mil a year ago, with a relatively flat revenue of RM2.6bil.

    AirAsia is also battling the Malaysia Airport Holdings Bhd (MAHB) over its operations at KLIA2. It was reported that AirAsia and MAHB would be having a “peace dinner” at the end of the month to resolve their disputes.

    Analysts, however, are not too optimistic that their differences could be resolved over a dinner. “One dinner cannot bury the hatchet. We will just have to wait and see,” one analyst says.

    Analysts believe that another concern weighing down AirAsia is the continued weakening of the ringgit against the strong greenback as about 70% of operating expenses and 80% of debt are US dollar-denominated. So far this year, ringgit has weakened by about 20% year-to-date.

    “We believe that one overhang over AirAsia’s share price performance year-to-date is the weakening of the ringgit against the US dollar.

    “We estimate that 64% of operating expenses (jet fuel, MRO and aircraft leasing) are US dollar denominated. As 8% of operating costs are hedged to reduce the impact from US dollar over ringgit volatility, the impact of every 5% drop in the ringgit equals to an increase in operating cost by 3%. Separately, 73% of its US dollar borrowings are hedged,” MIDF Research says.

    At 50%, jet fuel constitutes the largest operating cost component for AirAsia.

    AirAsia’s exposure to spot jet fuel is 49% in fourth quarter 2015 (51% hedged) and 100% in FY16 (fully unhedged). Thus, the impact on a 5% drop in jet fuel price reduces operating cost by 1.2% in fourth quarter 2015 and 2.5% in FY16.

    MIDF Research also notes that daily short value on AirAsia has reduced from a daily average of RM706,000 in the first week of September to RM335,000 in the second week of September.

    “This is also a major improvement from RM1mil to RM2mil average seen in previous months. We also believe that short sellers have been covering their positions by buying back the stock as share price rose 60% off its 77 sen low, typical in a short-squeeze situation,” it says.
  • Nearly 40 percent of Asian food retailers unaware of logistics costs

    Nearly 40 percent of Asian food retailers unaware of logistics costs

    More than 1 in 4 food retailers in some of Asia’s fastest-growing economies expect to grow by 10 percent or more this year, according to research commissioned by DHL Supply Chain, the global market leader for contract logistics solutions.

    Based on interviews with more than 300 industry decision-makers in India, Indonesia, Thailand and Vietnam, Hungry for Growth: Logistics Trends in Asia’s High-Growth Food Retail Markets also found that the majority of food retailers – more than 6 in 10 – predict significant growth of 6 percent or more this year as a result of expanding populations and rising income levels.

    DHL_Supply-Chain_Micrographic_04-03

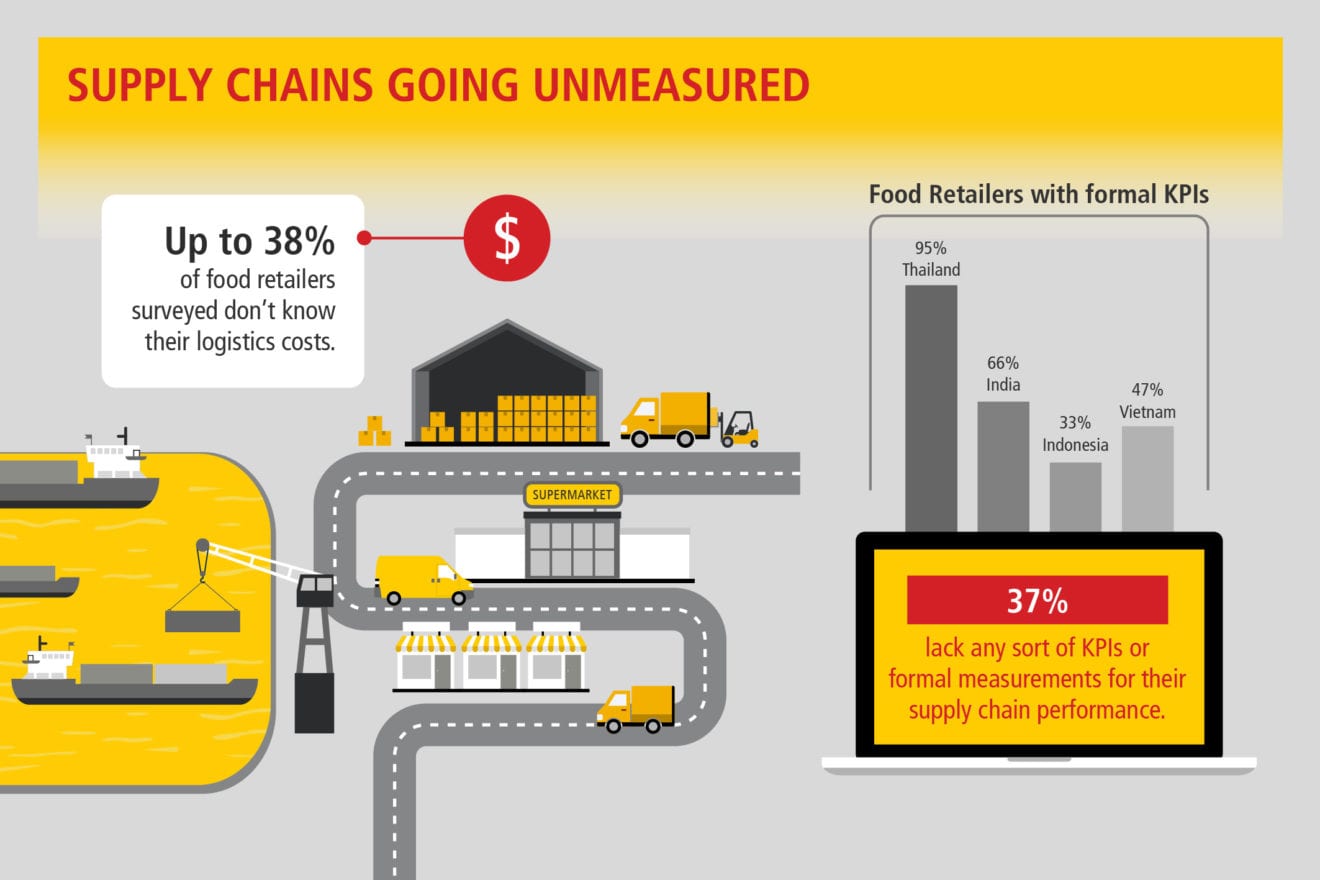
    However, the report also found that up to 38 percent of those surveyed were unaware of their total logistics costs, while 37 percent lacked any KPIs or formal measurements for their supply chain performance – potentially impacting their ability to keep shelves stocked and orders filled as demand and competitive factors grow increasingly complex.

    “Rapid increases in purchasing power, coupled with surges in demand driven by population growth, will yield obvious expansionary benefits to food retailers,” said Dean Eichorn, Vice President – Retail, DHL Supply Chain Asia Pacific. “However, any food retailer’s success is ultimately dependent on the agility of their supply chains when faced with demand volatility, seasonal fluctuations, and other complex market factors. Asia’s food retail industry looks set to undergo significant growth in the next year, and only with greater understanding and control of their logistics operations will companies be able to take advantage of new opportunities.”

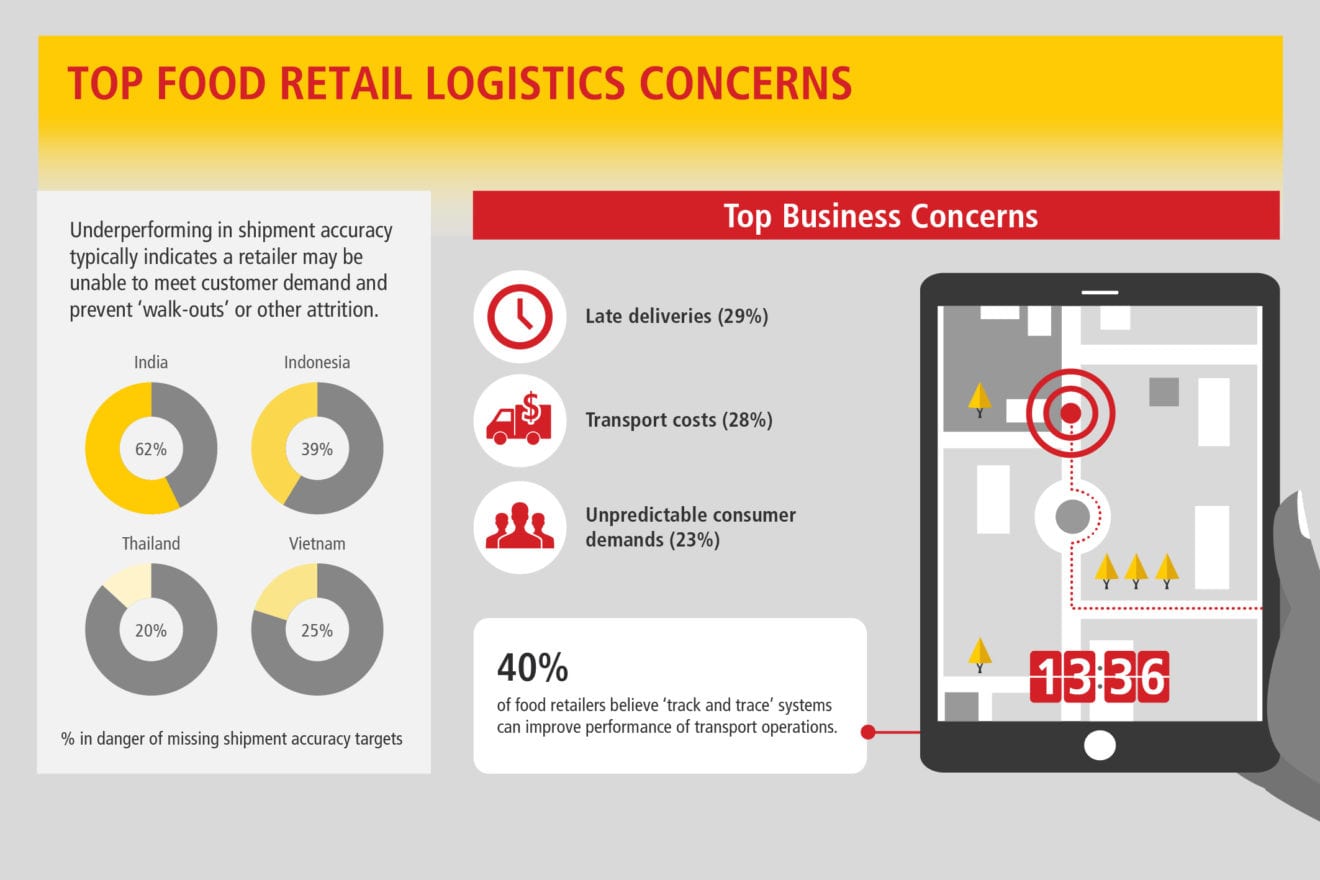
    The research found that food retailers are increasingly at risk from unpredictability on both demand and supply sides of their operations. In the four countries surveyed, late supplier deliveries were most commonly cited as food retailers’ top concern, while 36 percent admitted that demand volatility had a major impact on their businesses. Issues around supply chain performance and costs varied around the region: fuel, labor, and imbalances between supply and demand ranked amongst retailers’ top cost issues.

    “Many of these concerns are amplified because a large number of food retailers don’t have visibility of their logistics operations, let alone the resources or subject expertise to improve and optimize them,” said Eichorn. “Food retailers need reliable, agile supply lines if they’re to focus on their core competencies and compete. At DHL, we believe this agility only comes from being able to manage the supply chain as an end-to-end process across transport, warehousing, and value-added services in a way that’s rapidly scalable without creating extra complexity.”

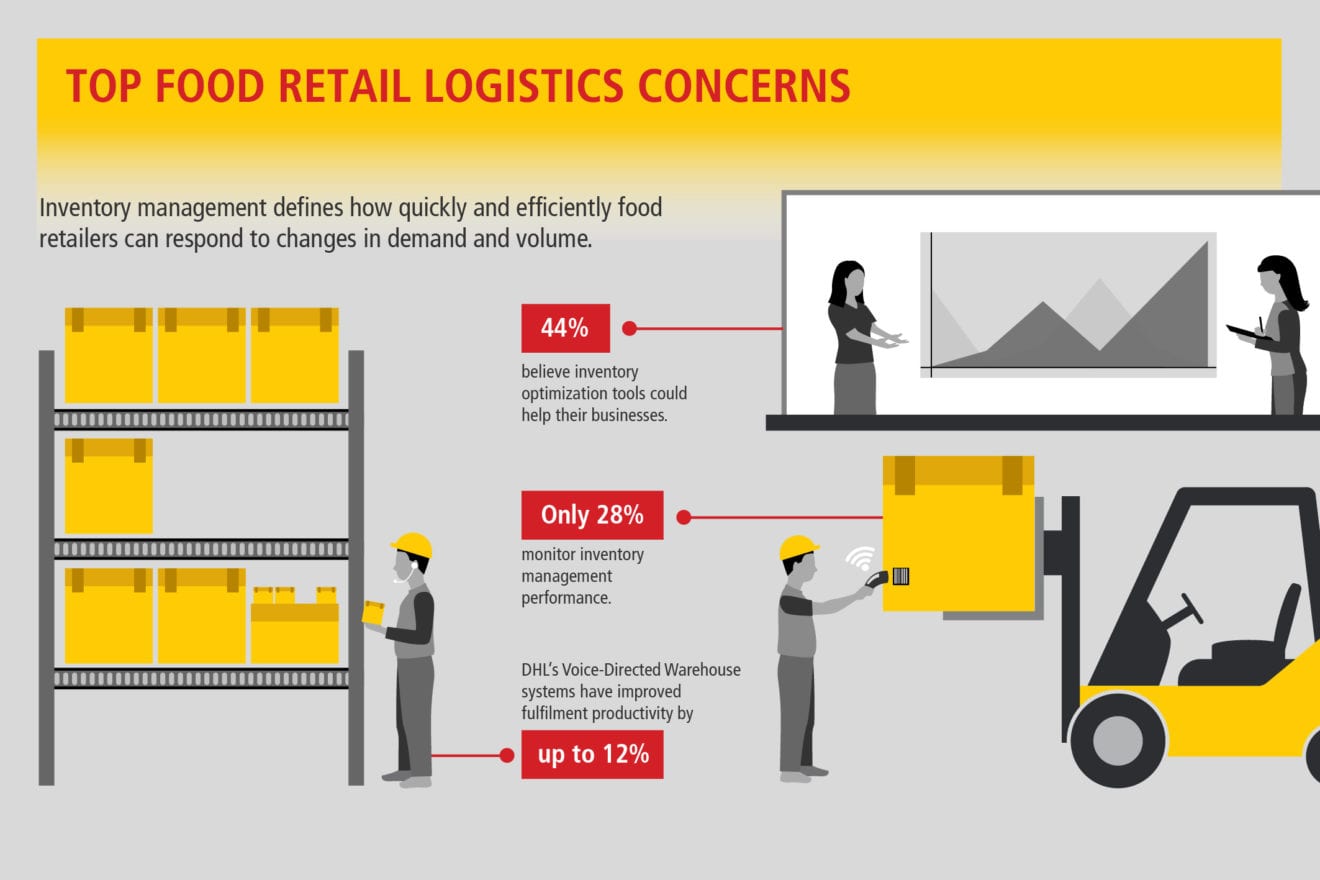
    The research also found that more than 60 percent of food retailers have not outsourced any aspects of their supply chains, suggesting that retailers who actively adopt third-party logistics solutions stand to gain significant “first-mover advantages” against their competition. Of those surveyed, 44 percent believe inventory optimization technologies would be beneficial to their overall performance, while 38 percent see advanced transport management services, like “track and trace”, as helping them improve reliability in meeting demand.

    DHL_Supply-Chain_Micrographic_04-04

    “Asia’s food retailers recognize the need to innovate and change, but the technologies and process transformations required to do so aren’t their domain of expertise – and nor should they be,” said Eichorn. “The key to growth and expansion in Asia’s food retail industry, and those of other developing regions where we’re seeing similar trends, will be how effectively operators can take advantage of third-party expertise and managed solutions in everything from technology to end-to-end supply chain management. For food retailers looking to leapfrog their competition and stay on top of growth’s complexity, the time to embrace advanced supply management principles is now.”

    About the Research:

    Commissioned by DHL Supply Chain and conducted by Redshift Research, the Hungry for Growth report draws on responses collected between December 2014 and April 2015 from more than 300 food retail professionals in India, Indonesia, Thailand and Vietnam. The report defines “food retail” as referring to retailers who sell food to consumers primarily for off-premise consumption, including (but not limited to): grocery stores, convenience stores, hypermarkets, supermarkets, and specialist stores like butcheries and bakeries.

    The full report can be downloaded from https://www.dhl.com/hungryforgrowth.