Tag: commodities

  • MAS Opens 500-Tonne Gold Vault to Foreign Central Banks

    MAS Opens 500-Tonne Gold Vault to Foreign Central Banks

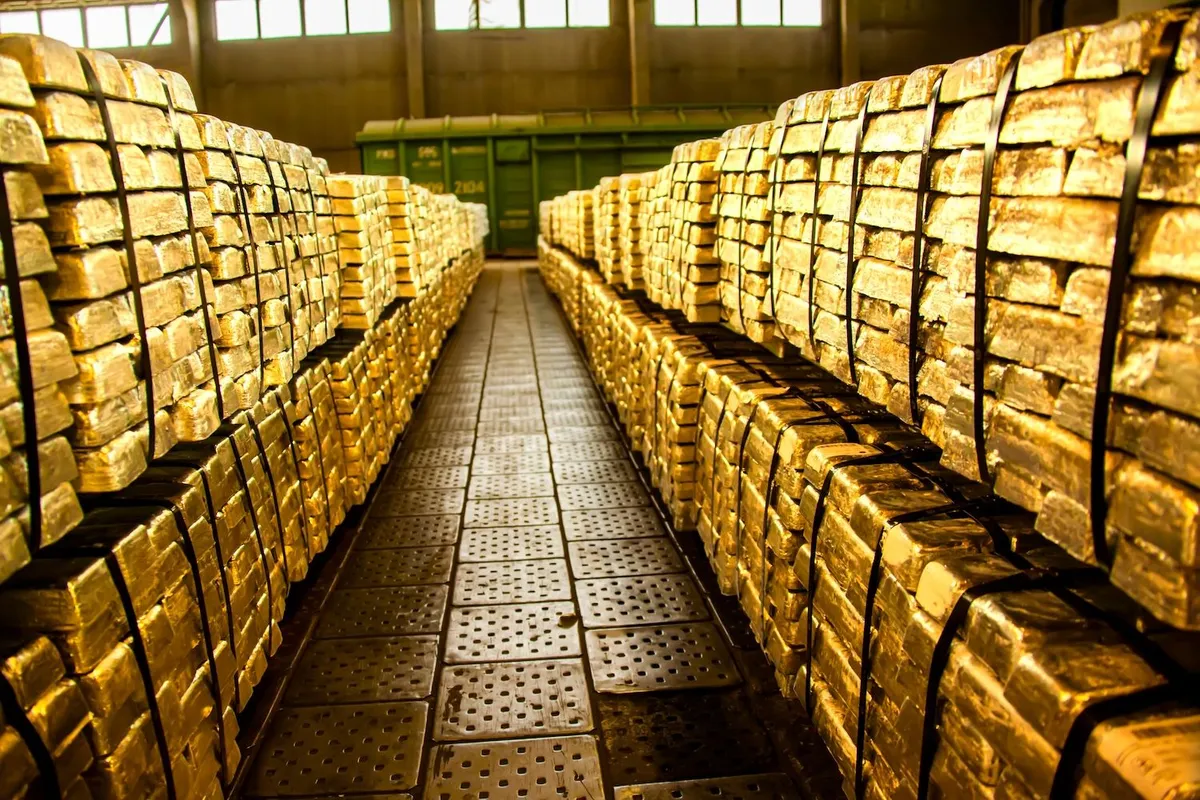
    The Monetary Authority of Singapore launched a gold vaulting service on Nov 10, opening its national currency vault to foreign central banks, international financial institutions and sovereign entities.

    The state facility offers 500 tonnes of storage capacity with scope for expansion as demand grows, adding institutional sovereign space to the Republic’s financial infrastructure.

    This public capacity will complement more than 2,000 tonnes of private commercial vaulting currently operating across Singapore for bullion banks, institutional investors and high-net-worth clients.

    Custody for Sovereign Holders

    Foreign central banks, international financial institutions and sovereign entities can now store official gold reserves inside the national currency vault. MAS will offer gold custody accounts to selected Singapore-based bullion banks that provide liquidity and precious metals services to sovereign customers. The storage site has room to add capacity beyond its initial 500-tonne limit as deposits increase.

    Deputy Prime Minister and MAS chairman Gan Kim Yong confirmed that several foreign central banks have opened confidential discussions to use the facility. Official vaulting infrastructure has remained concentrated in Western Europe and North America, leaving sovereign managers with few state-backed choices in Asian trading hours.

    Exchange Clearing and Bank Participants

    Physical custody is only half the framework. MAS completed industry testing for an over-the-counter gold clearing system operated by the Singapore Exchange, with final operating rules scheduled for release shortly.

    Six commercial lenders will serve as clearing members: DBS Bank, Deutsche Bank, ICBC Standard Bank, JPMorgan, OCBC Bank and UOB. Live settlement operations across the six banks will begin in the first quarter of 2027, clearing wholesale trades for both 400-ounce institutional bars and 1-kilogram bars favored in Asian retail and wealth channels.

    SGX plans to introduce a physically deliverable Gold Kilobar Futures contract in the second quarter of 2027 to anchor pricing between Asian daylight hours and Western paper markets.

    Tax Exemptions for Wholesale Processing

    Commercial viability for physical trading hinges on transaction costs. MAS and the Ministry of Finance plan an enhanced goods and services tax exemption scheduled to take effect in April 2027.

    The reform removes GST charges on business-to-business services between institutional participants, covering vaulting, refining, assaying, recasting and broking for gold not destined for domestic retail consumption. Specific statutory language for the tax relief will appear in the 2027 national budget.

    Building Asian Settlement Liquidity

    Singapore is tackling the structural problem that has capped Asian bullion volumes for decades: regional buyers purchase physical bars locally but clear, hedge and finance them against London and New York balance sheets. By combining sovereign-grade custody with central counterparty clearing through SGX, the city-state aims to keep metal and risk in the same time zone.

    Regional rivalry with Hong Kong, Shanghai and Dubai is intensifying as non-Western central banks reallocate reserve assets away from dollar holdings. Hong Kong continues to push its own physical warehouse and market links with mainland China, yet Gan argued that growing reserve diversification gives room for parallel hubs. The operational test rests on whether global bullion desks commit primary trading capital to Singapore rather than treating it merely as secondary overflow storage.

    The Timeline to Full Trading

    The state-backed facility follows an industry consultation started in March, when MAS convened a working group that brought together global banks, SGX, the World Gold Council, trading houses StoneX APAC and YLG Bullion Singapore, and refiner Metalor Technologies Singapore. Gan first flagged the vault plan publicly in June.

    System integration across the six clearing banks runs through the end of 2026, ahead of the live launch of SGX over-the-counter clearing in the first quarter of 2027.
  • Pakistan Cotton Arrivals Rise 7.5 Percent to 4.08 Million Bales

    Pakistan Cotton Arrivals Rise 7.5 Percent to 4.08 Million Bales

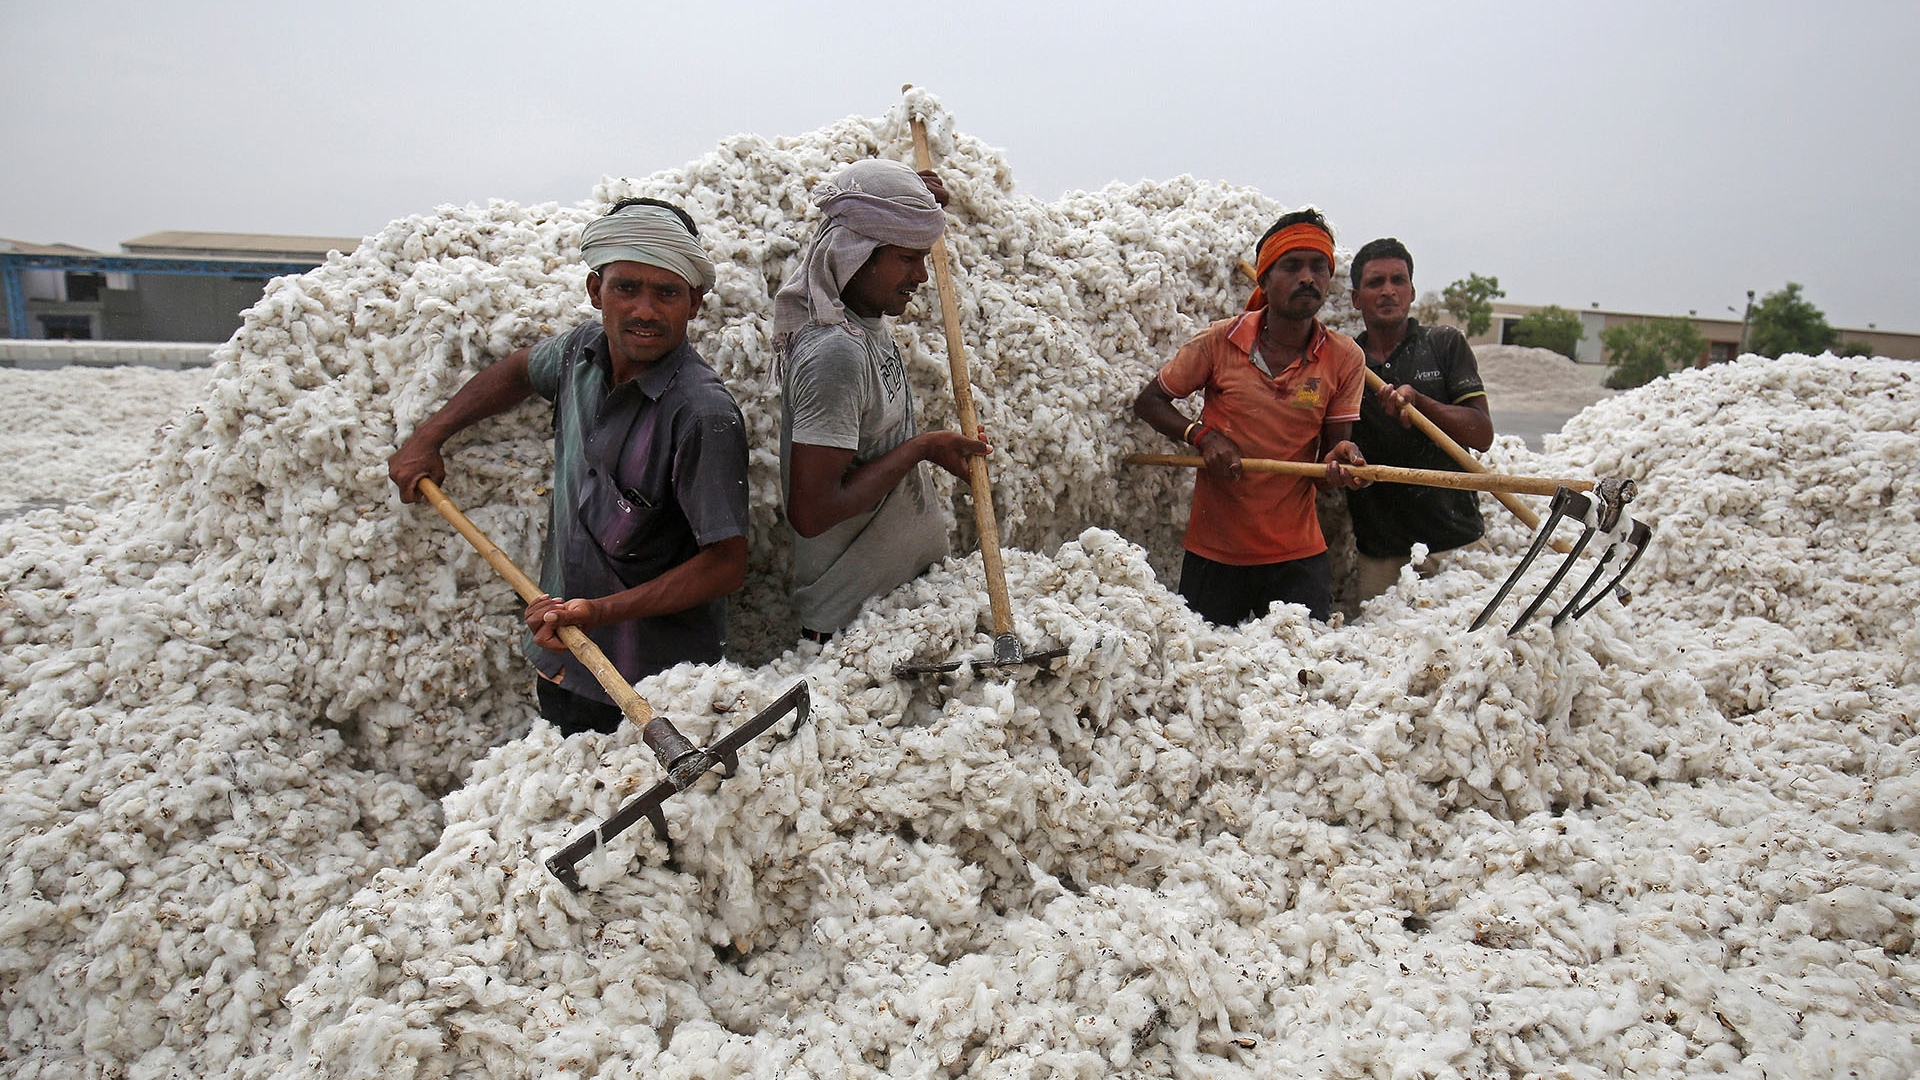
    Cotton arrivals at Pakistani ginning factories reached 4.08 million bales by October 15, rising 7.53 percent year-on-year despite widespread textile plant shutdowns.

    Data from the Pakistan Cotton Ginners Association shows total intake climbed to 4,081,265 bales, up 285,628 bales from the 3,795,637 recorded in the same period last season.

    Domestic mills bought 3.45 million bales and exporters booked 97,000 bales, leaving 531,530 bales unsold across active yards. Total arrivals during the preceding fortnight stood at 872,863 bales, processed by 471 operational ginning facilities nationwide.

    Regional Yields and Mill Disruption

    Sindh drove the bulk of volume with 2.44 million bales, up 7.35 percent from last year, led by Sanghar district at 1.14 million bales. Sukkur followed with 264,500 bales, Naushehro Feroze with 223,200 and Khairpur with 213,900.

    Punjab recorded arrivals of 1.64 million bales, representing a 7.79 percent increase. Bahawalnagar posted 418,750 bales, Bahawalpur delivered 294,606, Dera Ghazi Khan produced 236,514, Rahim Yar Khan reached 169,949 and Layyah logged 122,327.

    The higher volume arrives against severe industrial curtailment. Trade bodies report approximately 500 ginning factories and more than 150 spinning and weaving mills have shut operations, while roughly half of Pakistan’s power looms remain idle.

    Synthetic Influx Distorts Local Pricing

    Local processors blame soaring energy tariffs and leakages under the Export Facilitation Scheme for depressing domestic fiber demand. Under the programme, duty-free imported yarn and fabric intended for export finishing are instead diverted into the local market, bypassing the standard 18 percent sales tax paid by domestic suppliers.

    Import figures from the All Pakistan Textile Mills Association reveal man-made yarn shipments jumped to 12,773 tonnes in the first quarter of the 2026-27 fiscal year, up from 3,056 tonnes a year earlier. Man-made fabric imports surged from 660 tonnes to 8,628 tonnes over the identical timeframe.

    Cotton Ginners Forum Chairman Ihsanul Haq noted that traders brought an estimated 40 million to 50 million metres of fabric from China alone under the concessionary system without generating matching finished garment export growth.

    Crop Estimates and Farmer Margins

    Discrepancies in official output tracking complicate procurement planning for regional apparel makers. The Punjab Crop Reporting Service estimated provincial crop output at 2.983 million bales, creating a sharp divergence against the ginners association tally of 1.638 million bales received by mid-October.

    Central Cotton Research Institute transfer of technology head Sajid Mahmood warned that higher raw output will not stabilize the supply chain if farmgate returns fall below cultivation costs. Farmers facing compressed margins are expected to shift acreage toward competing crops next spring if lint prices fail to cover inputs.

    Karachi Cotton Brokers Forum leader Naseem Usman urged authorities to establish a direct floor price and an official buying mechanism to prevent distressed sales if open-market rates slide further.

    Harvest Run Out

    Picking operations enter their final 15 to 20 days across core farming belts in southern Punjab and upper Sindh. The Central Cotton Research Institute has instructed growers with plants bearing eight to 10 green bolls to apply a foliar spray of two kilograms of urea per 100 litres of water to accelerate boll opening before seasonal temperatures drop.

    Customs authorities have initiated targeted inspections against trading firms suspected of misusing import exemptions, while mills push Islamabad for formal quota caps on incoming synthetic yarn before second-quarter contracts settle.

  • Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global food commodity prices climbed 5.8 per cent year-on-year in September 2026, driven higher by energy shocks, shipping bottlenecks and surging fertiliser expenses across major Asian trade routes.

    The Food and Agriculture Organization Food Price Index reached 136 points during the month, up 1.5 per cent from August, despite worldwide cereal output tracking toward 2.979 billion tonnes, the second-highest harvest recorded.

    Global cereal inventories remain stable at roughly 950 million tonnes for the 2026-27 season, yet distribution costs and input pricing have broken the link between grain abundance and retail shelf prices. The divergence exposes supermarket chains, food processors and institutional buyers to compounding margin pressure as wholesale commodity jumps filter directly into wholesale procurement.

    Input Shocks Ripple Through Maritime Corridors

    Maritime trade disruptions in the Middle East and the Black Sea have inflated transportation and processing overheads throughout the year. Tanker freight rates jumped more than 90 per cent following security conflicts around the Strait of Hormuz, a passage handling one-quarter of seaborne crude and one-third of seaborne fertiliser trade. Bunker fuel costs doubled over the same period, forcing commercial carriers to add war-risk surcharges to bulk grain and oilseed shipments.

    International urea prices climbed 80 per cent between February and April to surpass $850 a tonne, while diammonium phosphate gained over 10 per cent. Those input spikes hit crop economics across South and Southeast Asia just as planting cycles began. Logistical friction in the Black Sea and dry weather in North America lifted global wheat prices 6.3 per cent in September alone. International maize prices rose 5.6 per cent month-on-month, compounded by smaller Brazilian export volumes and lower yields in the United States.

    Vegetable oils and sugar followed a similar upward path. The FAO Vegetable Oil Price Index gained 0.9 per cent in September on firm palm oil buying and dry conditions in Southeast Asian growing basins, while sugar prices jumped 6.1 per cent.

    Indian Retail Shelves Absorb Upstream Inflation

    In New Delhi and across major Indian metropolitan centres, retail food inflation accelerated to 7.74 per cent in September from 5.97 per cent in August. While central grain warehouses held 87 million tonnes of wheat and rice on September 1, shielding staple cereal retail prices to a 3.94 per cent rise, perishable and imported categories recorded sharp increases.

    Edible oils and fats inflation reached 8.35 per cent in September. The combined category for vegetables, tubers and pulses rose 9.18 per cent, while fruits and nuts climbed 10.75 per cent. At the consumer level, Crisil Intelligence calculated that the cost of preparing a standard home-cooked vegetarian meal rose 10 per cent year-on-year to 30.8 rupees in September, driven by higher prices for cooking oil, onions and liquefied petroleum gas.

    India’s trade account shows the scale of the cost transfer. National crude oil imports totalled $74.8 billion between April and August, up 48.4 per cent in value despite import volumes slipping 0.4 per cent. Fertiliser import expenditure jumped 53.25 per cent to $8.21 billion during the five-month span, while vegetable oil purchases grew 11.28 per cent to $9.18 billion. Domestic urea output fell 27 per cent in March to 1.8 million tonnes when feedstock natural gas deliveries dropped to 60 per cent of normal capacity before stabilizing.

    Weather Risks Threaten Export Allocations

    Climate factors are tightening the outlook for the next crop cycle. The National Oceanic and Atmospheric Administration projects an 83 per cent probability that a strong El Nino pattern will persist through the first quarter of 2027. In India, the 2026 southwest monsoon concluded with rainfall 13 per cent below historical averages, marking the driest seasonal performance since 2015. Southern states faced a 24 per cent deficit, while eastern and northeastern territories recorded a 26 per cent shortfall.
    Reduced reservoir levels pose direct operational hurdles for winter sowing. Crisil forecasts a 5 to 6 per cent decline in domestic paddy production due to lower planted area and thinner yields. Because India supplies roughly 40 per cent of the cross-border rice trade, production shortfalls in the domestic basin carry immediate pricing consequences for food distributors across the Middle East, Africa and Southeast Asia.

    Government subsidies have so far absorbed a portion of the shock, with central budget spending on fertiliser support rising 20.7 per cent to 1.03 trillion rupees between April and August. Food manufacturers and commercial retailers nonetheless face higher cold-chain logistics costs, packaging inflation and inventory holding expenses as raw materials turn costlier.

    Trade Metrics to Track Through 2027

    Retail grocers and packaged food companies across the region enter the final quarter of 2026 with little room to absorb further wholesale increases without adjusting shelf prices. Operating margins will depend heavily on whether winter rainfall restores reservoir capacity across key agricultural belts.

    Over the next 6-12 months, I would watch pulses, edible oils and vegetable prices; rabi sowing and soil moisture; reservoir levels; crude oil and fertiliser prices; the rupee; freight costs; and government decisions on food imports, exports and stocks. The key signal will be whether inflation remains concentrated in a few commodities or starts spreading across the wider food basket.

    Market participants are now tracking weekly acreage numbers for India’s rabi crop, alongside monthly palm oil stock levels in Malaysia and Indonesia, to gauge whether retail food inflation stabilizes before the 2027 harvest cycle opens.

  • Semirara Slashes Coal Target to 12 Million Tons as Pit Floods

    Semirara Slashes Coal Target to 12 Million Tons as Pit Floods

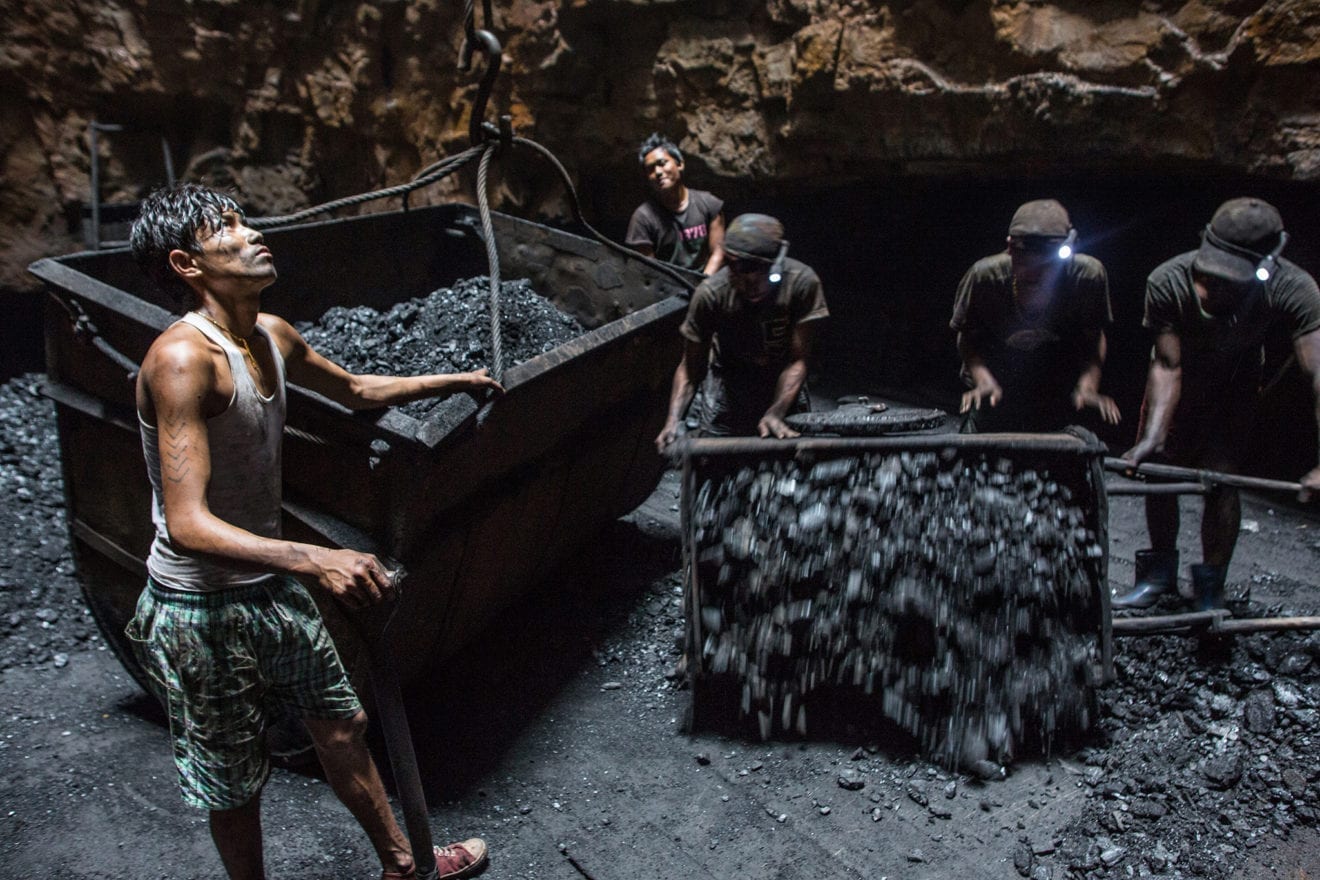
    Semirara Mining and Power Corp. Slashed its 2026 coal output target to 12 million metric tons after uncontrollable seawater flooded its core Acacia pit in the Philippines. Stripping operations are halted indefinitely. The revised target is a drop of nearly 40 percent from the record 19.9 million tons produced in 2025.

    Seawater is surging into the active pit at roughly 30,000 cubic meters an hour. That far exceeds on-site pumping capacity. The structural failure accelerated on September 20 when material from North Block 1 Dam 2 collapsed, sending surface runoff straight into the mining area.

    Crews are attempting to erect another cut-off wall. Meanwhile, the operational breakdown forced SMPC to lay off 1,458 mine-site workers. The company cut an initial tranche of 462 staff before letting go an additional 996 personnel.

    Contract Expiry and Asset Disputes

    Timing could not be worse for the operator or the power grid. Coal Operating Contract No. 5 expires on July 14, 2027. That leaves the Department of Energy scrambling to auction operating rights to the highest financial bidder.

    Energy officials terminated a previous bidding round in September following legal disputes, engineering problems, and operator objections. They now plan to restart the auction between November and December. That gives the winning contractor barely seven months to take over before the current license lapses.

    A legal fight is also playing out in court over more than 55 billion pesos in infrastructure and machinery on Semirara Island. SMPC filed a petition for declaratory relief after the energy department demanded a full inventory of the operator’s property and plant to share with rival bidders.

    State Revenue Versus Engineering Capacity

    Regulators argue that equipment with costs recovered under the operating contract can vest in state hands and pass to the next operator. SMPC counters that cost recovery serves only as reimbursement under Presidential Decree 972. Title and removal rights remain strictly with the company.

    Higher revenue shares and consumer concessions remain the government’s priority, grounded in the state’s ultimate ownership of mineral resources. SMPC notes it contributed 43.4 billion pesos in government share alongside 3.7 billion pesos in taxes between 2021 and the middle of 2026.

    Commercial power users and industrial operators face the threat of electricity cost inflation. Acacia was projected to deliver the bulk of domestic coal supply in 2027. Any prolonged disruption will force power producers to import expensive replacement thermal coal from Indonesia and Australia.

    Spillover to the Local Island Economy

    Fallout has already spread across Semirara Island as payroll cuts hit retail and service trade. Small island businesses report falling daily revenue and customer defaults as families lose their primary income.

    Island social programs face immediate risk as well. SMPC has historically funded about 90 million pesos annually for free tuition at the Divine Word School of Semirara Island. More than 1,500 students depend on that mine-supported schooling.

    The Department of Energy has not issued bid bulletins, prequalification screens, or a model contract clarifying minimum technical requirements for the flooded pit. Restarting the bidding process in late 2026 will test whether the state can secure an operator capable of draining the Acacia pit before the July 2027 handover deadline.

  • Taiwan Weighs $4.4 Billion Stake in Alaska LNG Project

    Taiwan Weighs $4.4 Billion Stake in Alaska LNG Project

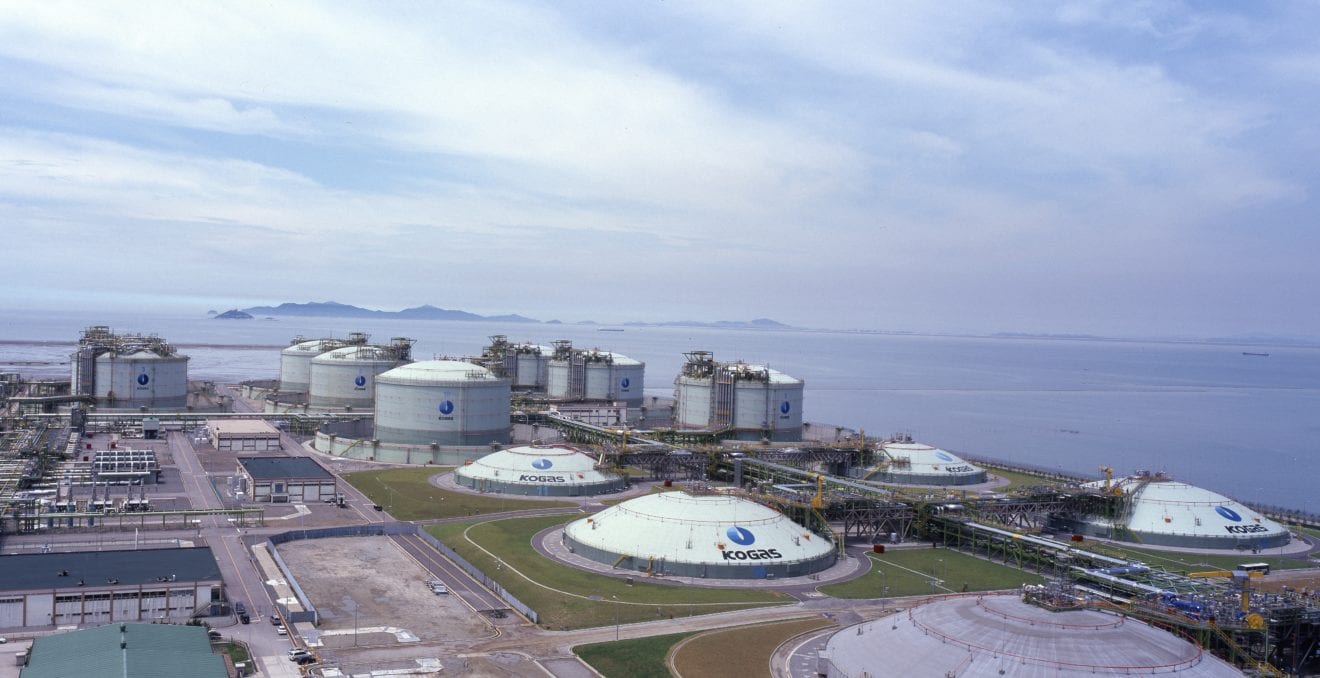
    Taiwan is reviewing an investment of up to $4.4 billion in the Alaska LNG project to buy 6 million tonnes of liquefied natural gas annually once production starts.

    The volume accounts for 30 percent of the planned 20 million tonne yearly output from the proposed $54 billion development on the US northern coast.

    State-owned CPC Corp, Taiwan would take an equity stake in the project, which includes a 1,299-kilometer pipeline running from Alaska’s North Slope to an export terminal in the state’s south. Deliveries could reach Taiwanese terminals as early as 2032 if construction proceeds on schedule. The Ministry of Economic Affairs confirmed that negotiations are advancing following a preliminary letter of intent signed in March last year, though neither side has executed a binding sale and purchase agreement.

    Pipeline Structure and Shipping Logistics

    Alaska LNG gives Asian buyers direct access to North American gas without traversing maritime chokepoints. Tankers sailing from southern Alaska cross the open Pacific directly to East Asian ports, avoiding both the Panama Canal bottlenecks and lengthy diversions around the Cape of Good Hope.

    Shorter transit times reduce voyage expenses and insulate energy shipments from canal draught restrictions or geopolitical conflicts in traditional shipping lanes. For Taiwan, which relies on maritime imports for almost all of its natural gas consumption, a direct northern Pacific corridor provides supply stability for power generation and domestic industrial users.

    Commercial Viability and Financing Hurdles

    Securing long-term off-take commitments remains the main hurdle before project sponsors can lock down commercial debt. Alaska LNG has accumulated agreements covering 13 million tonnes per year from Asian utilities and French multinational TotalEnergies.

    Developers must secure commitments for another 3 million tonnes and convert provisional deals into binding contracts to reach financial close. The developers intend to take a final investment decision on the pipeline by late 2026, followed by a decision on the liquefaction and export plant in 2027.

    Engineering complexities in Arctic conditions and total capital costs of $54 billion continue to draw scrutiny from energy analysts. Taiwan’s willingness to commit capital signals how heavily island economies must weigh physical supply redundancy against cost overruns.

    Taiwan Energy Diversification Strategy

    The Alaska negotiations follow CPC’s broader policy shift toward North American suppliers. CPC chairman Fang Jeng-zen outlined plans in February to raise the share of US-sourced LNG to roughly one-third of the company’s total import portfolio.

    Presidential Office Secretary-General Pan Men-an inspected the Alaska facility site last year to assess progress firsthand. Government officials in Taipei have faced rising domestic pressure to ensure reliable base-load fuel as thermal power units replace retired nuclear generators.

    Regional peers are evaluating similar exposure. While US political leaders recently claimed South Korea had committed funds to the Alaska terminal, authorities in Seoul maintained that their participation has not been finalized.

    Contract Milestones Ahead

    Contract terms, equity allocation, and pricing formulas remain subject to ongoing commercial talks between CPC and the US development team. The project requires binding off-take contracts across 16 million tonnes of capacity before project financiers release construction capital, setting the next major benchmark at the pending pipeline investment decision.

  • Vietnam Gold Prices Slip as SJC Bars Fall to VND143.3 Million

    Vietnam Gold Prices Slip as SJC Bars Fall to VND143.3 Million

    Saigon Jewelry Company lowered its gold bar price by 0.69 percent to VND143.3 million ($5,533.89) per tael on Wednesday morning in Ho Chi Minh City. Gold rings matched the downward step, falling at an identical rate to VND142.8 million per tael as local buyers pulled back from recent highs.

    One tael equals 37.5 grams or roughly 1.2 troy ounces. The drop breaks a multi-session run of elevated domestic retail trading across Vietnamese counters, where retail premiums over international benchmarks have remained wide throughout October.

    Global bullion rates stayed largely steady while the Vietnamese retail market retreated. Spot gold held at $4,165.25 per ounce during early trading hours, while United States gold futures for December delivery added 0.3 percent to reach $4,188.70 per ounce. Front-month Comex gold contracts for October delivery had earlier settled down 0.31 percent, losing $12.90 to finish at $4,152.90 per troy ounce.

    Domestic Margins Under Pressure

    Physical jewelry retail outlets and licensed bullion desks in Vietnam face shifting spreads between raw bar costs and processed jewelry items. With plain rings settling at VND142.8 million per tael, the narrow difference between bars and rings reflects cautious retail sentiment rather than aggressive speculative buying.

    Consumer demand across Asian retail markets often contracts when bullion tests higher price bands. Retail jewelers that built inventory at higher rates earlier in the year now manage tighter inventory turns as shoppers delay major purchases ahead of festival seasons.

    Local currency swings add friction to retail gold trading desks. Even minor fluctuations in the Vietnamese dong alter the import parity calculation for authorized bullion distributors, forcing daily adjustments across shop counters in Hanoi and Ho Chi Minh City.

    Global Rates and Macro Pressures

    International traders kept metal prices in a narrow corridor as financial markets prepared for fresh United States consumer price index data. Precious metals analysts note that wider macro trends continue to limit sharp directional swings in bullion trade.

    “What we’re looking at here is not a big move, it’s within a range. But the fact that we are able to hold ⁠a range while oil is rallying suggests that gold is trying to find a reason to rally,” said Ilya Spivak, head of global macro at Tastylive.

    Alternative safe-haven assets and yield benchmarks maintain pressure on non-yielding physical commodities. The United States Dollar Index traded near 102.4, while 10-year Treasury yields held near 5.23 percent, keeping holding costs for bullion elevated across international trading books. Silver tracked the broader commodities pullback, dropping 1.6 percent to $59.161 per troy ounce.

    Retail Trends Across Regional Counters

    Shifting pricing dynamics across Southeast Asian physical markets highlight how domestic demand patterns diverge from paper contracts. When domestic spot rates drop by nearly one percent in a single morning, local buyers frequently hold cash rather than accumulating inventory.

    Jewelry chain operators must navigate higher financing costs for store stock while counter traffic remains sensitive to ticket prices. Retail groups that expanded their retail store footprints during previous commodity rallies face higher working capital requirements to keep display cases fully stocked.

    Merchant margins on standard gold rings remain thin compared to high-margin fashion jewelry lines. When retail buyers focus exclusively on investment rings and standardized bars, overall retail operating margins compress across regional retail networks.

    Data Releases Dictate Near Term Levels

    Vietnam gold prices previously gained ground earlier in the week before Tuesday morning trading brought an initial dip. That volatility followed mixed sessions where global bullion swung between minor gains and losses without establishing a clear trend.

    Earlier quarterly trading saw major producers realizing prices between $4,400 and $4,500 an ounce before global rates adjusted into the current $4,150 to $4,200 band. The ongoing consolidation test shows physical retail buyers adjusting to a structurally higher baseline price environment.

    Market participants across Asian trading desks now track the release of United States producer price index data and upcoming retail sales reports for monetary policy signals.

  • Australian Retailers Link TradingView to Brokers to Track Currency Swings

    Australian Retailers Link TradingView to Brokers to Track Currency Swings

    Australian retail importers are turning to TradingView to monitor foreign exchange movements and freight-linked oil prices before supply chain shifts impact quarterly margins.

    The software pairs live market feeds with execution accounts at regulated brokers such as EasyMarkets, which has operated since 2001, allowing operators to respond to price swings without switching screens.

    How Live Feeds Connect to Trading Desks

    TradingView operates as an analytical interface rather than a custodian of funds. The platform pulls historical and live pricing data across foreign exchange pairs, freight-sensitive commodities, and equity indices into customizable chart layouts.

    To place market orders, users link the platform directly to third-party brokerage accounts. Regulated brokers such as EasyMarkets, established in 2001 and licensed by the Australian Securities and Investments Commission alongside the Cyprus Securities and Exchange Commission, handle execution through fixed-spread models without charging trade commissions.

    Managing Exposure on Inbound Shipments

    Most retail operators sourcing stock from Asian manufacturing hubs face exposure to the Australian dollar against the US dollar and regional currencies. Freight charges also fluctuate with global crude oil benchmarks.

    Tracking these inputs in real time allows procurement managers to identify price pressures weeks before supplier invoices arrive. Automated tools, including guaranteed stop-loss orders and negative balance protection, give businesses predefined price exits if market movements accelerate against their open positions.

    Risks in Derivative Contracts

    Direct hedging through contracts for difference carries distinct balance-sheet hazards for non-financial companies. CFDs track underlying price movements without conferring ownership of physical commodities or currency reserves, amplifying both gains and losses through borrowed capital.

    ASIC maintains public guidance warning commercial operators about derivative risk controls. Retail businesses using charting software must separate speculative positions from baseline inventory budgeting to avoid unexpected cash outflows during currency sell-offs.

    Balancing Tools Against Central Bank Benchmarks

    The move toward integrated technical charting follows prolonged margin compression across Australian import sectors. Operators that previously relied solely on end-of-month bank statements now monitor daily exchange rate channels to negotiate supplier pricing terms.

    Businesses tracking Australian dollar trends without opening trading accounts can cross-reference platform indicators with official foreign exchange rate datasets published daily by the Reserve Bank of Australia.

  • Diet Coke Cans Reach Record 70 Rupees in India as Aluminium Squeeze Bites

    Diet Coke Cans Reach Record 70 Rupees in India as Aluminium Squeeze Bites

    Coca-Cola bottlers and retailers across India have raised Diet Coke prices to 70 rupees for a 330 ml can, up from 50 rupees, as metal packaging costs climb.

    The 40 per cent jump hits major urban territories, including Delhi-NCR, Mumbai, Bengaluru and Goa. Local stores there charge the new rate even on inventory printed with the earlier 50-rupee maximum retail price.

    Metal costs squeeze bottler margins

    Can-grade aluminium prices surged 30 per cent year-on-year after conflict in West Asia disrupted supplies earlier this year. That inflation forced independent packaging partners to pass costs down the distribution chain.

    Bottlers say packaging economics collapsed under higher procurement tabs for beverage cans. One independent Coca-Cola bottler stated:

    “Yes, we are selling 330 ml cans of Diet Coke at ₹70 now. The increase in prices of aluminium cans is unsustainable,”

    Divergence between store shelves and apps

    Offline retailers and neighborhood grocers applied the 70-rupee price tag across metro markets, triggering consumer pushback on social media. Quick-commerce apps like Blinkit and Zepto still fulfill customer orders at the official 50-rupee price printed on the 330 ml packs.

    This pricing split creates friction across urban retail channels. General trade grocers and supermarkets face customer disputes at billing counters. App-based delivery platforms hold to official price tags to defend basket sizes.

    Coca-Cola stated that company guidance remains tied to package labeling. A company spokesperson said:

    “In line with Indian regulations, our recommendation to all trade partners is to charge the MRP printed on the pack.”

    Surging demand outstrips can availability

    Consumer demand for zero-sugar soft drinks doubled over the past 12 months, draining bottling lines of inventory. High demand and tight can supply allowed distributors to hike rates without hurting sales volumes.

    Independent bottlers operate with separate cost bases from company-owned plants. That makes localized price hikes hard for the brand owner to rein in. A senior beverage industry executive noted:

    “Pricing being taken by independent bottlers and retailers is beyond the company’s control. The decision to hike prices is a direct consequence of demand for the zero-calorie drink having doubled over the last year,”

    The shift from smaller pack sizes

    The latest jump follows a packaging transition that began in July. Coca-Cola phased in 330 ml cans at 50 rupees to replace older 300 ml cans priced at 40 rupees, standardizing can sizes while adjusting price realization per unit.

    Attention now turns to whether quick-commerce platforms raise listing prices to match general trade as new inventory reaches warehouses. Aluminium raw-material prices heading into the next bottling cycle will decide if the 70-rupee level sticks.

  • Japan Veers from Rice Shortage to Glut as Farmers Suffer Whiplash

    Japan Veers from Rice Shortage to Glut as Farmers Suffer Whiplash

    Japan has swung from a severe rice shortage to an oversupply glut after releasing emergency grain stockpiles last year to curb soaring consumer prices.

    Although cheaper grain brings relief to shoppers, the rapid price drop is dealing a sharp blow to agricultural producers nationwide.

    Supply reversal squeezes farm margins

    In Chiba Prefecture, Hiroshi Asano, 59, who farms 38 hectares of rice fields, is among the commercial growers feeling the impact of the sudden surplus.

    Large commercial farms with tens of hectares can absorb cyclical downturns through equipment depreciation and land scale. Family operations and independent growers on small plots lack the capital buffers needed to survive prolonged wholesale discounting.

    Retail price shifts and supermarket supply

    Supermarket chains across Tokyo and surrounding prefectures had spent months rationing bags and passing wholesale surcharges onto consumers. Falling purchase costs allow food retailers to restore inventory volume and stabilize shelf pricing on private-label and branded rice products.

    Food manufacturers and restaurant chains also gain short-term margin relief from cheaper grain inputs. The price collapse creates procurement instability for buyers who rely on long-term supplier contracts with domestic farming cooperatives.

    Policy intervention and stockpile dynamics

    The supply swing stems partly from emergency market measures deployed during the previous pricing surge. Japanese authorities released state reserve stocks to quell consumer frustration over grain inflation and empty retail racks.

    That flood of public reserves, combined with incoming crop harvests, pushed commercial inventories beyond normal distribution capacity. State planners now face the reverse challenge of balancing consumer affordability against rural producer solvency.

    Structural risks for aging growers

    Japan’s agricultural sector already faces demographic pressures, with the average age of farm operators rising and abandoned arable acreage increasing nationwide. Sharp swings between scarcity and surplus accelerate the exit of independent operators from the staple crop sector.

    Distribution networks must now manage excess inventory flows through regional logistics hubs while wholesale auctions establish new baseline prices for the upcoming harvest cycle.

  • At Least 12 Chinese Banks to End Retail Used Precious-Metals Trading

    At Least 12 Chinese Banks to End Retail Used Precious-Metals Trading

    At least a dozen Chinese banks intend to wind down retail used precious-metals trading following directives from the Shanghai Gold Exchange, ending a practice where everyday investors post margin deposits to speculate on gold and silver contracts without owning physical metal.

    Sources at two lenders, including Industrial and Commercial Bank of China, confirmed the retreat was mandated by the exchange amid sharp swings in international gold prices.

    Exchange Mandate Halts Retail Exposure

    Beijing-based China Everbright Bank said on Friday that it would phase out retail used precious-metals trading for gold and silver after October 19, following a comparable notice from Shanghai Pudong Development Bank earlier this month.

    For almost twenty years, domestic banks allowed retail investors to open precious-metals positions using margin ratios aligned with the Shanghai Gold Exchange. That setup granted individual accounts between five-fold and six-fold use. The current directive instructs lenders to shut these channels completely, pushing individual clients toward physical purchases and fixed-price accumulation plans.

    Regulators Eliminate Speculative use

    Market turbulence in precious metals forced commercial banks to tighten trading rules throughout the past year. By the end of the first quarter, state-owned lenders had raised margin requirements for retail precious-metals contracts to 100 percent. That step removed operational use before the formal shutdown.

    Orient Futures analyst Xu Ying said: “This represents an inevitable shift, and I anticipate that all the lenders will eventually exit the business.”

    Shifting Retail Capital Into Physical Bars

    The forced wind-down alters precious-metals distribution across mainland China. Commercial lenders will no longer act as clearing brokers for individual speculative traders. Instead, banks will redirect foot traffic into physical bullion counters, minted commemorative coins, and non-used regular accumulation plans.

    Wealth-management desks will lose fee income generated by short-term contract turnover. However, the closures eliminate retail customer default risks during sharp intraday commodity swings. Retail exposure will transfer directly into settled physical ownership.

    Precedents and Margin Escalation

    Chinese authorities have worked in stages to ring-fence households from high-volatility commodity derivatives. State lenders initiated the first round of account restrictions during previous commodity price spikes. They capped new account openings first, then raised margin thresholds across all retail tiers.

    Member commercial banks and the Shanghai Gold Exchange will now finalize account liquidation schedules, with Everbright Bank carrying out its formal operational cutoff after October 19.

  • China Spends Record $158 Billion to Import 1,141 Tons of Gold

    China Spends Record $158 Billion to Import 1,141 Tons of Gold

    China spent an unprecedented $158 billion to import 1,141 tons of gold, breaking historical spending records for foreign bullion procurement. The volume shows relentless domestic appetite across consumer jewellery retail, private investment, and institutional balance sheets.

    Surging import expenditure reflects both elevated global gold prices and sustained retail demand across mainland commercial centres. Despite operating as the world’s largest gold producer, domestic mining output remains insufficient to satisfy internal consumption requirements.

    Surging Demand Outpaces Domestic Extraction

    Domestic mines yield hundreds of tons annually, yet Chinese fabricators and jewellery operators like Chow Tai Fook, Luk Fook, and Lao Feng Xiang continue to rely heavily on international suppliers. Switzerland, Australia, and South Africa remain primary source markets feeding bullion into Shanghai dealing desks.

    Retail jewellery chains in tier-one and tier-two cities have expanded bullion counters to cater to younger buyers seeking wealth preservation. Small-denomination gold bars, collectable coins, and wearable 24-karat pieces continue to dominate retail floor space across major shopping malls.

    Institutional Buying and Portfolio Hedging

    Institutional accumulation by the central bank and state-linked funds provides a persistent floor for cross-border shipments. Commercial banks hold licensed quotas that allow them to import physical bars directly to service structured wealth management accounts.

    Currency diversification strategies have accelerated corporate balance sheet allocations toward physical commodities. The scale of the $158 billion outlay demonstrates that institutional buyers are willing to absorb elevated international premiums to secure delivery.

    Retail Expansion Across Mainland Hubs

    Consumer jewellery operators like Chow Tai Fook, Luk Fook, and Lao Feng Xiang have adapted inventory lines to emphasize investment-grade purity over complex fabrication markups. Shoppers increasingly treat retail jewellery outlets as asset exchange counters rather than purely discretionary fashion boutiques.

    For retail landlords, jewellery and bullion tenants provide steady footfall and reliable rental yields. Department store operators across Beijing, Shanghai, and Shenzhen have consolidated ground-floor layouts to accommodate dedicated precious metal sections.

    Supply Chain Allocations and Next Quotas

    Regulatory oversight of gold import licences remains tightly controlled through the People’s Bank of China. The central authority adjusts volume allocations periodically based on foreign exchange balances and broader macro trade objectives.

    The critical metric to monitor is the quarterly allocation of commercial import quotas handed to state and joint-stock lenders for the upcoming trading cycles.

  • Black Sea Wheat Shipments Drop 50 Percent as Port Strikes Hit Asian Millers

    Black Sea Wheat Shipments Drop 50 Percent as Port Strikes Hit Asian Millers

    Wheat shipments into Southeast Asian mills dropped sharply this quarter after renewed Black Sea port strikes cut Russian and Ukrainian grain exports by roughly half. Global wheat prices climbed to three-year highs, forcing food processors across the region to replace millions of tonnes of contracted grain.

    Together, Russia and Ukraine account for more than a quarter of the global wheat trade, two-thirds of sunflower oil exports, and 10 per cent of corn shipments. Since July, strikes on maritime terminals, storage silos, and transport vessels across the Black Sea basin have halted bulk cargo loadings and stranded grain intended for Asian and Middle Eastern buyers.

    In Vietnam, Ho Chi Minh City-based flour miller Golden Wheat lost four contracted shipments of Black Sea wheat, representing approximately 20 per cent of its total annual raw grain requirement. Chief executive Tue Vuong secured replacement supplies from Bulgaria for two of the four canceled cargoes, leaving the processing business to source the remaining volume across spot markets at higher prices.

    Millers scramble for replacement cargoes

    Processors across Southeast Asia rely heavily on Black Sea grain to feed commercial flour mills, industrial bakeries, and aquaculture feed production lines. When Black Sea export corridors shut down, buyers face immediate freight penalties to divert purchasing to Australia, North America, or secondary European suppliers. The swiftness of the summer port disruptions caught Asian purchasing desks with lean safety stocks after months of stable pricing.

    Disruptions to regional diesel infrastructure inside Russia have compounded the shipping logjam by pushing fuel prices to record levels. Because diesel represents a primary operating cost for farming machinery, harvesting, and port hauling, transport expenses are flowing directly into export offers. Asian procurement managers now face both elevated commodity benchmarks and expanded freight premiums on spot contracts.

    Higher feedstock costs hit livestock and bakery margins

    Food manufacturers across Asia cannot absorb sustained ingredient increases without altering wholesale pricing. For livestock integrators and aquaculture feed producers in Vietnam, Thailand, and Indonesia, wheat and corn form core dietary inputs. A prolonged disruption in Black Sea bulk shipping will compress processing margins or force consumer-facing price revisions across packaged bakery goods, instant noodles, and animal protein.

    Supermarket operators and packaged food brands are monitoring these wholesale increases closely. While large multi-category food manufacturers carry forward hedging books that cover three to six months of production, mid-sized millers and regional livestock feeders buy on shorter cycles. These smaller processors bear immediate cash flow strain when spot replacement cargoes must be settled under tightened trade terms.

    Port strikes follow collapsed transit corridors

    The current shipping breakdown escalated in July when military attacks targeted Black Sea harbor terminals and loading infrastructure. Previous export arrangements brokered by Turkey in 2022 had allowed Ukrainian crops to transit safely through designated maritime corridors, but those agreements have expired without renewal. At the same time, neighboring European states maintained import bans on Ukrainian overland grain, leaving rail and river routes insufficient to handle standard export volumes.

    Researcher SovEcon estimates that combined Russian and Ukrainian wheat shipments for the July to September harvest period will finish at approximately 50 per cent of their prior-year levels. Major global buyers have already felt the pinch: Egypt, the world’s largest individual wheat importer, received no grain from Black Sea ports for nearly a month following the summer port strikes.

    Contract repricing heads into fourth quarter

    Asian food manufacturers are now reviewing import books for the fourth quarter of 2026. Spot cargo purchases from alternative origins like Bulgaria, Romania, and Western Australia will determine mill gate prices across Southeast Asia as existing warehouse inventories run down through October.

  • Pakistan Cotton Arrivals Rise 19 Percent to 2.39 Million Bales

    Pakistan Cotton Arrivals Rise 19 Percent to 2.39 Million Bales

    Cotton arrivals at Pakistani ginning factories reached 2.389 million bales by September 15. That volume is up 19 percent from 2.004 million bales during the same period last year.

    The early surge lifts industry projections for full-year national output above six million bales. Last season yielded roughly 5.5 million bales.

    Provincial receipts showed uneven growth across primary growing regions. Punjab deliveries jumped 24.73 percent to 860,942 bales, while Sindh processed 1.528 million bales, a rise of 16.25 percent. Active facilities totaled 205 ginning factories in Punjab and 207 in Sindh.

    Regional Splits and Factory Volumes

    Sindh led early harvesting through intensive picking in key southern districts. Sanghar district alone delivered 888,607 bales to local ginners by mid-September. That single district outpaced the combined intake of all ginning units in Punjab.

    Steady field conditions across Matiari, Tando Allahyar, Hyderabad, Mirpurkhas, Nawabshah and Naushahro Feroze supported the southern haul. In Punjab, picking concentrated across Bahawalpur, Bahawalnagar, Dera Ghazi Khan, Multan, Vehari, Rahim Yar Khan, Muzaffargarh and Rajanpur.

    Mill Demand and Price Competition

    Domestic spinning and textile mills secured the bulk of intake, buying 2.035 million bales by the reporting deadline. Raw cotton exporters booked 93,000 bales. Ginners were left holding an unsold inventory of approximately 261,000 bales.

    Spot prices dropped sharply across trading hubs despite steady buying by domestic spinners. Over seven days, lint prices fell by about Rs1,000 per maund. Rates settled near Rs18,600 in Punjab and Rs18,400 in Sindh.

    Lower import parity prices for Brazilian raw cotton prompted several Pakistani mills to place overseas orders, dampening local price support. Cheaper imported fiber caps production costs for downstream yarn and fabric makers. Domestic growers, however, face tighter margins at the farm gate.

    This price squeeze creates supply chain risks for regional fashion retailers who rely on Pakistani mills for yarn and finished garments. Falling domestic lint prices could erode farm profits. That risk threatens to reverse acreage recovery in future planting cycles and drive higher import dependency across the South Asian textile corridor.

    Data Gaps and Acreage Shifts

    Cotton acreage in Punjab faces land competition from sugarcane, which has expanded into traditional cotton tracts. That shift explains part of the volume gap between the two provinces.

    Official production figures also show large reporting discrepancies between agencies. The Pakistan Cotton Ginners Association recorded 860,942 bales in Punjab through September 15. The Punjab Crop Reporting Service estimated 1.483 million bales by September 17. That represents a 72 percent gap between factory receipts and provincial field estimates.

    Pest Control and Final Crop Risks

    Early arrivals do not guarantee an unbroken harvest, field specialists warn. Agronomists have identified pink bollworm infestations in both provinces. Whitefly, jassid and thrips also apply localized pressure.

    Pest management over the coming weeks will determine whether crop yields hold.

    “The next few weeks will be critical,” Mahmood said, stressing continuous monitoring of bolls, timely pest-control measures and picking to protect both yield and lint quality.

    Growers and ginners are tracking pest counts and late-season rainfall across southern Punjab and Sindh. The next fortnightly arrival report will confirm whether picking maintains the six-million-bale trajectory.

  • China Crude Oil Imports Climb to 7.84 Million Barrels Daily as Stockpiles Fall

    China Crude Oil Imports Climb to 7.84 Million Barrels Daily as Stockpiles Fall

    China increased crude oil imports to 7.84 million barrels per day in September, up from 7.25 million in August as refiners slowed stock drawdowns.

    The intake marks the highest buying level in four months, reversing an aggressive inventory clearance that had sheltered domestic transport fleets from global price volatility.

    Customs figures show August imports rose 6.2 per cent month-on-month to 37.9 million tonnes. Buying remains more than 23 per cent below year-earlier volumes, when imports ran at 9.76 million barrels daily. Sourcing patterns shifted sharply this month: shipments from Iraq jumped past 1 million barrels per day from 177,000 in August, while deliveries from Saudi Arabia and Iran dropped.

    Refiners face margin squeeze under state price caps

    Commercial and state stockpiles shrank from 1.25 billion barrels in April to 1.14 billion barrels in September, according to trade intelligence firm Kpler. For five months, Chinese refiners met domestic fuel demand by burning through reserves rather than purchasing expensive seaborne cargoes, muting inflationary pressure across freight networks.

    That buffer is now wearing thin. With stockpiles down by 110 million barrels since spring, processors must step up spot purchases even as international benchmarks hover near 100 dollars a barrel. For freight operators and consumer goods distributors across mainland logistics corridors, higher landing costs for crude will filter directly into road haulage rates and plastic packaging feedstock.

    State retail pricing rules cap fuel price adjustments once international crude tops 80 dollars a barrel. When global prices trade higher, refiners absorb the difference directly on their balance sheets, squeezing operating cash flow at major petrochemical complexes.

    Higher crude prices are now eroding Chinese refining margins, as domestic product prices are regulated above US$80 per barrel.

    Electric fleets limit domestic fuel demand rebound

    Between April and August, Chinese crude purchases trailed 2025 volumes by roughly 3.2 million barrels daily. Beyond inventory drawdowns, structural consumption shifted: new-energy vehicles took more than 65 per cent of total passenger car sales over the summer, permanently removing a slice of urban petrol demand.

    Downstream transport operators in regional logistics hubs will see little relief on diesel prices despite the passenger transition. Beijing holds roughly four to six months of total oil cover across strategic and commercial sites, giving authorities room to restrict refined-product export quotas to protect domestic fuel supply.

    Supply disruptions force shifts to Iraqi crude

    The import pickup coincides with export disruptions across key trade corridors, including strikes on Saudi Arabia’s East-West pipeline and terminal damage at Russia’s Novorossiysk facility. These bottlenecks forced Chinese trading desks to secure alternate supplies quickly, driving the sudden surge in Iraqi crude fixtures.

    Refiners are now balancing fourth-quarter crude intake targets against quarterly product export quotas, with domestic processing runs expected to stay below pre-crisis highs through October.

  • Pakistan Approves 200,000 Tonnes of Sugar Exports Alongside Maritime and Energy Reforms

    Pakistan Approves 200,000 Tonnes of Sugar Exports Alongside Maritime and Energy Reforms

    Pakistan’s Economic Coordination Committee approved the export of 200,000 tonnes of sugar on Monday. The decision followed a submission by the Ministry of National Food Security.

    Safeguards built into the quota aim to prevent supply shortages and retail price spikes in the domestic market. Finance Minister Muhammad Aurangzeb chaired the cabinet committee session in Islamabad. Officials cleared agricultural trade proposals alongside industrial and security funding measures.

    Domestic Price Safeguards For Food Processors

    Local mills can now offload surplus inventory into overseas markets to generate foreign exchange. Shipments, however, will face strict monitoring. The committee designed these checks to protect local consumers and commercial food processors from wholesale price inflation.

    The release adds short-term supply for regional commodity traders and food manufacturers across Asia. South Asian sugar millers balance export earnings against domestic price stability. Sudden export bans often follow retail price surges. Under this mechanism, operational risk falls on millers, who must prove domestic market stability before volumes clear customs.

    Logistics Restructuring And Refinery Upgrades

    Beyond agriculture, the committee cleared a restructuring framework for the state-owned Pakistan National Shipping Corporation. The Maritime Affairs Division presented the plan. It changes ownership and management control based on recommendations from the Privatisation Ministry.

    Energy supply chains also secured regulatory clearance under the Petroleum Division’s Draft Upgrade Agreement. Built on the Pakistan Oil Refining Policy for Upgradation of Existing Brownfield Refineries 2023, the framework gives local refineries five years to modernize with state incentives. Separately, oil marketing companies secured an interim settlement mechanism through the Inland Freight Equalisation Margin to resolve unadjusted input sales tax claims for FY26.

    Vehicle Import Rules Put On Hold

    Ministers deferred an immediate decision on commercial vehicle imports. The Science and Technology Division had proposed new inspection regimes for used vehicles. Officials directed the division to incorporate findings from an Engineering Development Board review committee before resubmitting the standards.

    A 3 billion rupee technical supplementary grant was cleared to buy 15 bulletproof sedans. The vehicles will transport visiting heads of state during the Shanghai Cooperation Organisation Council Summit in Islamabad later this month.