Tag: digital economy

  • Southeast Asia AI User Base Hits 243 Million While Subscriptions Lag

    Southeast Asia AI User Base Hits 243 Million While Subscriptions Lag

    Generative artificial intelligence reached 243 million users across Southeast Asia in less than three years, representing 58 per cent of the region’s working population. Direct software subscriptions capture only 1 to 2 per cent of those consumers, shifting the financial return to e-commerce and marketing channels.

    The joint annual e-Conomy SEA report from Google, Temasek and Bain & Company projects the regional digital economy will expand 17 per cent to $368 billion in gross merchandise value this year. The market is tracking toward $1 trillion by 2035.

    Merchant Operations Absorb Infrastructure Costs

    Consumer uptake is outrunning the early curve of mobile internet by four times. Rather than charging monthly fees for software access, digital marketplaces are monetizing the audience through backend conversion gains, targeted search, and automated customer service desks.

    Shopee routed approximately 80 per cent of its customer inquiries through automated AI chatbots. That shift lowered its customer contact costs by 30 per cent year on year. Across the broader retail sector, early case studies track a 10 per cent year-on-year lift in baseline conversion rates and order basket increases reaching 75 per cent.

    About 69 per cent of shoppers now deploy artificial intelligence tools to evaluate complex retail transactions like consumer electronics. In addition, 75 per cent of surveyed users say they are ready to delegate product sourcing and payment execution directly to automated software agents.

    Shifting Margins for Marketplaces and Merchants

    For marketplace operators, the gap between zero subscription income and higher computing overhead creates a clear operational mandate: platforms must extract savings from headcount and advertising yield. Merchant partners shoulder these costs when platforms bake automated tooling fees into standard transaction commissions and marketing auction prices.

    Regional brands face inventory risks if automated comparison agents direct buyer volume entirely to discounting algorithms. Retailers that rely on brand loyalty rather than programmatic price optimization stand to lose checkout shelf space to rival sellers indexed directly into AI buying agents.

    Sector Shifts Across Transport and Media

    Online media revenue, covering digital advertising and streaming formats, is on track to advance 22 per cent to $44 billion this year as ad engines improve conversion rates. The regional ride-hailing and food delivery segment is forecast to gain 15 per cent to $40 billion in gross merchandise value, backed by voice-assisted booking tools.

    Travel bookings are expanding as well, with the online travel market projected to grow 10 per cent to $59 billion in gross merchandise value this year as travelers build itineraries via automated search assistants.

    Consumer confidence in regional software tools is rising alongside adoption. The study found 62 per cent of respondents trust artificial intelligence applications more than they did twelve months earlier, even as overall per-capita usage in Southeast Asia remains at 10 per cent of United States volume.

    Singapore Leads Deployment as Trillion-Dollar Target Looms

    Singapore is among Southeast Asia’s early leaders in AI adoption.

    The immediate marker for digital commerce leaders remains the year-end shopping quarter, where merchants will test whether AI-assisted search traffic sustains the projected run toward the $368 billion regional digital gross merchandise value milestone.

  • India Average Monthly Mobile Data Usage Passes 31 GB per User

    India Average Monthly Mobile Data Usage Passes 31 GB per User

    Indian mobile broadband subscribers consumed an average of over 31 GB of data per month in 2025, lifted by faster 5G network rollouts and cheaper handsets.

    The figure represents an 18 percent compound annual growth rate over the last five years, according to Nokia’s 13th annual Mobile Broadband Index.

    Total mobile data traffic nationwide crossed 27 exabytes per month in 2025. Fifth-generation network traffic expanded 70 percent year-on-year to hit 12.9 exabytes, generating nearly 47 percent of the total volume carried across Indian carrier networks. Demand centered heavily on video streaming in 4K resolution, cloud gaming platforms, and emerging artificial intelligence applications that require higher bandwidth.

    Metros Lead Fifth-Generation Shift

    Metro telecom circles generated the heaviest concentration of new demand. Fifth-generation networks accounted for 58 percent of all mobile data traffic in metro areas during 2025, up from the prior year. Traffic volume expanded in Category A, Category B, and Category C telecom circles as operators built out base stations beyond tier-one cities.

    Handset adoption accelerated alongside the infrastructure buildout. Active 4G devices in India reached 892 million units in 2025, with more than 383 million of those units supporting 5G connectivity. Over 90 percent of all smartphones shipped across India during 2025 arrived 5G-capable from the factory floor, allowing carriers to shift traffic from legacy bands without subsidizing hardware directly.

    Network Upgrades for Artificial Intelligence

    Carriers are now reconfiguring network backbones to handle heavier uplink loads and lower latency requirements created by distributed computing tasks. Artificial intelligence features integrated directly into consumer applications require faster two-way data transfer than traditional video consumption, which relies primarily on download capacity.

    Nokia country manager-designate for India Vibha Mehra pointed to shifting network requirements as artificial intelligence adoption spreads among mobile users.

    India’s mobile broadband landscape is entering a new phase of evolution, driven by rapid 5G adoption and the growing influence of AI-led applications. As networks transform to support new usage patterns and intelligent services, Nokia remains committed to partnering with telcos to build scalable, high-performance and future-ready connectivity infrastructure.

    Enterprise Pressure on Carrier Returns

    Surging data consumption does not translate automatically into proportional revenue growth for Indian telecom operators. Carriers spent heavily on 5G spectrum auctions and nationwide cell site upgrades over the past three years, yet average revenue per user remains among the lowest of any major global economy. Operators must monetize higher data usage tiers and enterprise services to recoup infrastructure investments.

    Content delivery networks and cloud software vendors face parallel capacity pressures. Retail platforms, mobile payments systems, and digital entertainment services operating in India must optimize delivery infrastructure to serve millions of simultaneous high-bandwidth sessions without degradation during peak evening hours.

    Path to One Billion Connections

    India currently ranks as the world’s second-largest market for total 5G subscribers and total 5G data traffic volume, trailing only mainland China in absolute throughput. The rapid uptake follows aggressive network deployments started in late 2022 by major domestic operators, who rolled out coverage to thousands of towns within twenty-four months.

    Nokia projects India will pass 1 billion active 5G subscriptions by 2031 as older 4G feature phones and legacy smartphones phase out through regular upgrade cycles.

  • Indonesia Targets 6 Percent Economic Growth Backed by E-Commerce

    Indonesia Targets 6 Percent Economic Growth Backed by E-Commerce

    Indonesia is relying on expanding e-commerce activity to push national economic growth to 6 percent by 2027, according to Coordinating Minister for the Economy Airlangga Hartarto. The country’s digital economy reached $100 billion in 2025 as consumer spending shifted increasingly online.

    Speaking at the Ministry of Trade in Jakarta, Airlangga said physical retail continues to account for the bulk of Indonesian commerce, but online transaction volumes are climbing quickly. Growth is concentrating in video commerce, which blends livestreaming and short-form video directly with checkouts.

    Video Commerce and Algorithm Shifts

    Video commerce transactions in Indonesia reached 2.6 billion, rising 90 percent year-on-year. That surge tracks a widening digital audience across the archipelago, where active social media users expanded 26 percent to 180 million.

    Airlangga called on merchants and platform operators to deploy artificial intelligence tools to refine trade algorithms. Sharper algorithmic matching helps online sellers connect products with targeted consumer segments across diverse regional markets.

    For retailers across Southeast Asia, Indonesia remains the primary testing ground for live shopping formats. Platforms operating in the country have spent two years restructuring merchant interfaces and integrating creator-led video tools to protect market share against pure-play marketplaces.

    Harbolnas Shopping Targets

    The government set a sales target of Rp40 trillion ($2.46 billion) for the upcoming National Shopping Day, known locally as Harbolnas. That goal represents a 10 percent increase over the Rp36.4 trillion generated during the event a year earlier.

    Harbolnas 2026 runs from December 10 to December 16, focusing on domestic merchandise, local services, hospitality bookings, and transport tickets.

  • Vietnam digital economy growth expected to be highest in Southeast Asia

    Vietnam digital economy growth expected to be highest in Southeast Asia

    Vietnam will achieve the highest growth in the digital economy in Southeast Asia between 2022 and 2025, a report by Google, Temasek and Bain & Company has forecast.

    It will grow at 31% followed by the Philippines with 20% and Indonesia with 19%, according to e-Conomy SEA 2022.

    Vietnam’s digital gross merchandise volume is likely to reach US$23 billion this year, third highest in the region behind Indonesia’s $77 billion and Thailand’s $33 billion.

    But with the rapid growth projected, it is expected to double by 2025 to $49 billion.

    The main contributors to Vietnam’s digital economy this year are e-commerce ($14 billion) online media ($4.3 billion) and transport and food ($3 billion).

    Vietnam’s high-quality workforce in the technology sector and the increasing penetration of digital services in urban and rural areas promise a strong foundation for the digital growth of the country, Stephanie Davis, vice president of Google Southeast Asia, said.

    billion USDVietnam’s digital economy size1313181823234949Gross merchandise value2019202120222025102030405060

    Vietnam is likely to attract the most investors in the 2025-30 period, according to a survey of venture capital investors in the third quarter by Bain & Company, with 83% of them expecting an increase in deal activity compared to now.

    In a report earlier Meta said eight out of 10 of Vietnamese are digital consumers.

    Vietnam is also among the top countries in future technology adoption such as fintech and metaverse.

    Virtual reality adoption in Vietnam is 29%, the highest in Southeast Asia, it said.

  • India’s digital economy can reach $4tr by 2022

    India’s digital economy can reach $4tr by 2022

    India’s digital economy has the potential to reach up to $4 trillion in just four years, according to India’s tech firms. This outshines the government’s goal of making India a $1 trillion digital economy by 2022.

    IT minister Ravi Shankar Prasad, who chaired a meeting with industry captains to chalk out a growth plan, said the government will formulate a new set of strategies to support growth including a new electronics policy, software product policy and a framework for data security and protection.

    “There was unanimity among all the participants that $1 trillion digital economy is an understatement. India has the immense potential to go to [a] $2 trillion to $3 [trillion] to $4 trillion digital economy,” he said.

    The meeting was attended by top experts such as Nasscom President R Chandrashekhar, Google India’s Rajan Anandan, Wipro’s Rishad Premji, Indian Cellular Association national president Pankaj Mohindroo, NIIT chairman Rajendra Pawar and Hike Messenger CEO Kavin Bharti Mittal, among others.

    The government has projected that Indian digital economy will be worth $1 trillion by 2022, from around $450 billion at present.

    As of now, the Indian telecoms market is estimated to be around $150 billion, its electronics market is worth around $ 100 billion, its IT sector is around $150 billion, e-commerce $30-40 billion. The remainder is contributed by the sharing economy such as taxi hailing services, as well as startups.

    The Ministry of Electronics and IT has projected that the IT and IT enabled services sector will grow to $350 billion by 2025, while the electronics sector is poised to touch $300 billion by the same time.

    Telecoms and e-commerce are projected to grow to be worth $150 billion each, while the sharing economy and digital skilling each presents a further $30 billion opportunity.

    Digital payments, cyber security and Internet of Things — all of which are expanding rapidly — are expected to touch $50 billion, $35 billion and $20 billion respectively.

    It was also projected that the digital economy will generate 30 million employment opportunities by 2024-25, which is double than the current scenario. The ministry has identified digital payments, Make In India, Start-Up India, Skill India among the key drivers of the digital economy.

  • The importance of collaboration in the digital economy

    The importance of collaboration in the digital economy

    What’s the future for the connected car, for digital financial services, or for smart and sustainable cities in the new industrial reality? How are innovations and technical developments in 5G, the Internet of Things and spectrum management impacting on future networks and future businesses? And if meaningful, affordable connectivity is the single best bet for accelerating socio-economic development and meeting the UN’s sustainable development goals (SDGs), how can we ensure we reach the billions of unconnected most in need?

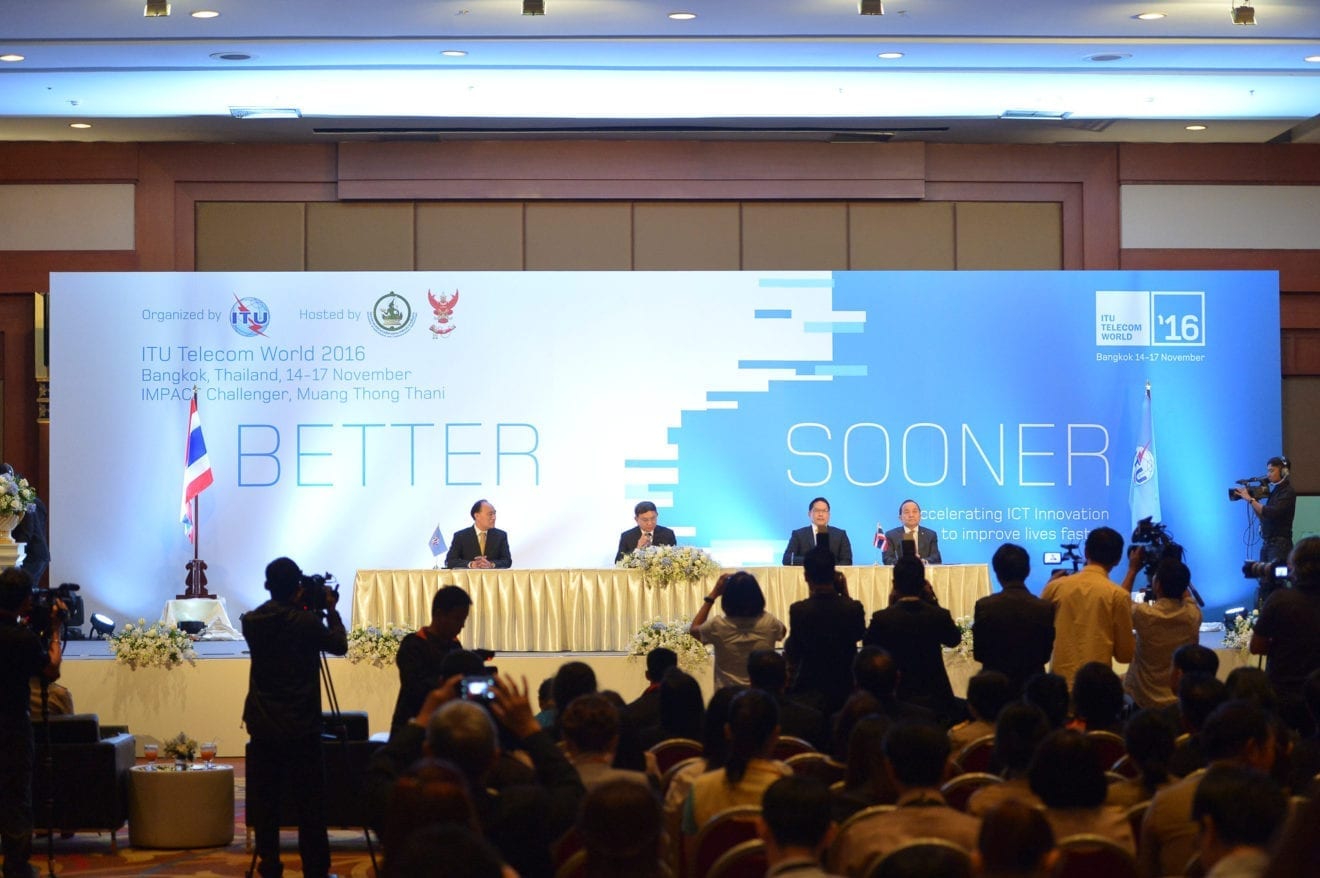
    These are some of the key questions at the heart of the agenda at ITU Telecom World 2016, four days of debate, networking and exhibition on the theme of “Collaborating in the Digital Ecosystem.” In an industry and era of intense transformation, collaboration is essential to make sense of the possibilities – and make a success of it for us all.

    Rapid technological developments, societal changes and radical new business models are enriching and enlarging the ICT ecosystem. Never before has connectivity offered so much potential for economic growth and social development in the digital economy. And never before have the challenges of extending that connectivity to all been so pressing, from providing universal access to technology to meaningful local content, fair and open competition, up-to-date regulation, security and education.

    More and new stakeholders are involved in making it happen. Governments decide policy and shape regulation. Major ICT companies face competition from new internet players and innovative small and medium enterprises (SMEs). New technologies open up new markets, often involving new partners in vertical sectors such as transport, health or agriculture. The borderless world of the digital economy opens up business in developed and emerging markets across the globe.

    Finding the right public sector policies, the business models and market strategies for success may not be easy. It will certainly involve new approaches to cross-sector partnerships, whether between public and private organizations, or between new industries or market players. The benefits of collaboration need to be balanced against competition, commercial interests and embedded cultures.

    A good example is 5G. As the technology evolves and develops to meet the growing demands of societies and economies, so does the potential for new opportunities. Delivering on the promise of effective future networks won’t be possible, however, without some form of collaboration on the standards that take solutions to scale and at speed. The mix of players, established and new, manufacturers, vendors and application developers, may lead to interesting joint ventures to streamline investment. The long-heralded convergence of fixed broadcast and mobile may be given a boost by the new technology. But then again, competition and entrenched mindsets may kill off any new form of shared investment or working together.

    Or take the connected car. Intelligent transport systems and self-driving vehicles are speeding towards widespread commercialization. The focus is on developing communication technologies that use the internet to integrate cars with smart devices – bringing a whole range of new players into the mix. Car manufacturers and suppliers must negotiate and collaborate with app developers, communication technology companies and OS developers. Combining such different industries, cultures, regulatory and business approaches as software and automotive cannot be without challenges. And given the key issues of security, safety, liability and public policy, it’s clear that the government will have an important role to play, too.

    The same balance between opportunity and challenge, between collaboration and competition and between multiple, often new, stakeholders applies to digital financial services. In a world where around 2 billion adults have no access to basic financial services, digital technology has the unprecedented potential to offer secure, cheap and reliable transactions for the unbanked or underbanked. Financial inclusion is a critical step to socio-economic development. Leapfrogging traditional banking to deliver financial services can have a profound impact on the underprivileged throughout the emerging world.

    But success here relies on the creation of a new ecosystem of government, business and individuals – centred around a sound working relationship between financial and ICT sectors. In its early stages of development, the market calls for convergence between mobile network operators, banks, microfinance institutions, payment platform providers and payment services providers. This dizzying array of players and potential partnerships must establish joined-up regulatory approaches, standards to enable cross-market interoperability, and accepted international good practice. All of which is not possible without collaboration.

    The smart integration of manufacturing and advanced information and communication technology – or Industry 4.0 – is making it possible to deliver tailored products to individual customer specifications at low cost and in high quality. The impact on companies, economies and societies across the globe is potentially enormous. But this, too, depends on the harmonious and fruitful coming together of a number of players, orchestrated to different degrees in different markets by committed government leadership.

    The digital economy is the single most important driver of innovation, competitiveness and growth worldwide. ICTs have tremendous potential to improve development outcomes in both emerging and developed markets, from measuring progress and success in the meeting the UN’s ambitious Sustainable Development Goals  (SDGs) to enhancing the efficiency and effectiveness of development initiatives, and providing access to a whole new range of digitally-enabled products and services which strengthen local economies, innovation and communities. Meeting the SDGs through ICTs, however, will only be possible if the industry can work together with corporate social responsibility departments, public sector, non-governmental and development organizations to build feasible business models.

    Any way you look, across all fields of ICT activity, in the macro digital economy and in the detail of each potential future market, it’s all about working together. Finding new partners, exploiting new opportunities, considering new stakeholders and new markets. Using new services, segments, solutions and devices to drive revenue and increase socio-economic development.

    But will there be stronger collaboration or will industry players default to a winner-takes-all approach? How clear are the benefits of working together both within the telco sector and with web players, disruptive market entrants, customers and the open source community, to stimulate and sustain growth in the industry?

    How can public policies and industry incentives attract investment into the network infrastructure and technologies that are the backbone to the digital economy? Can cross-regional, even international, initiatives maximize opportunities at scale? And what are the key innovative technologies and collaborative initiatives focused on expanding connectivity through access, affordability and relevance?

    These are the questions that the Forum debates at ITU Telecom World 2016 will discuss, with expert speakers, international perspectives and a unique audience of public and private sector leaders from emerging and developed markets, from SMEs fresh to the market to established major corporate players. The event itself works on the principle of collaboration, of coming together face-to-face, of meeting, exchanging knowledge, ideas and experiences, debating, working together – the very principle of collaboration on which the future success of the industry, our societies, economies and world may be built.