Tag: etfs

  • China Clears 18 Active ETF’s to Funnel Billions into A-Shares

    China Clears 18 Active ETF’s to Funnel Billions into A-Shares

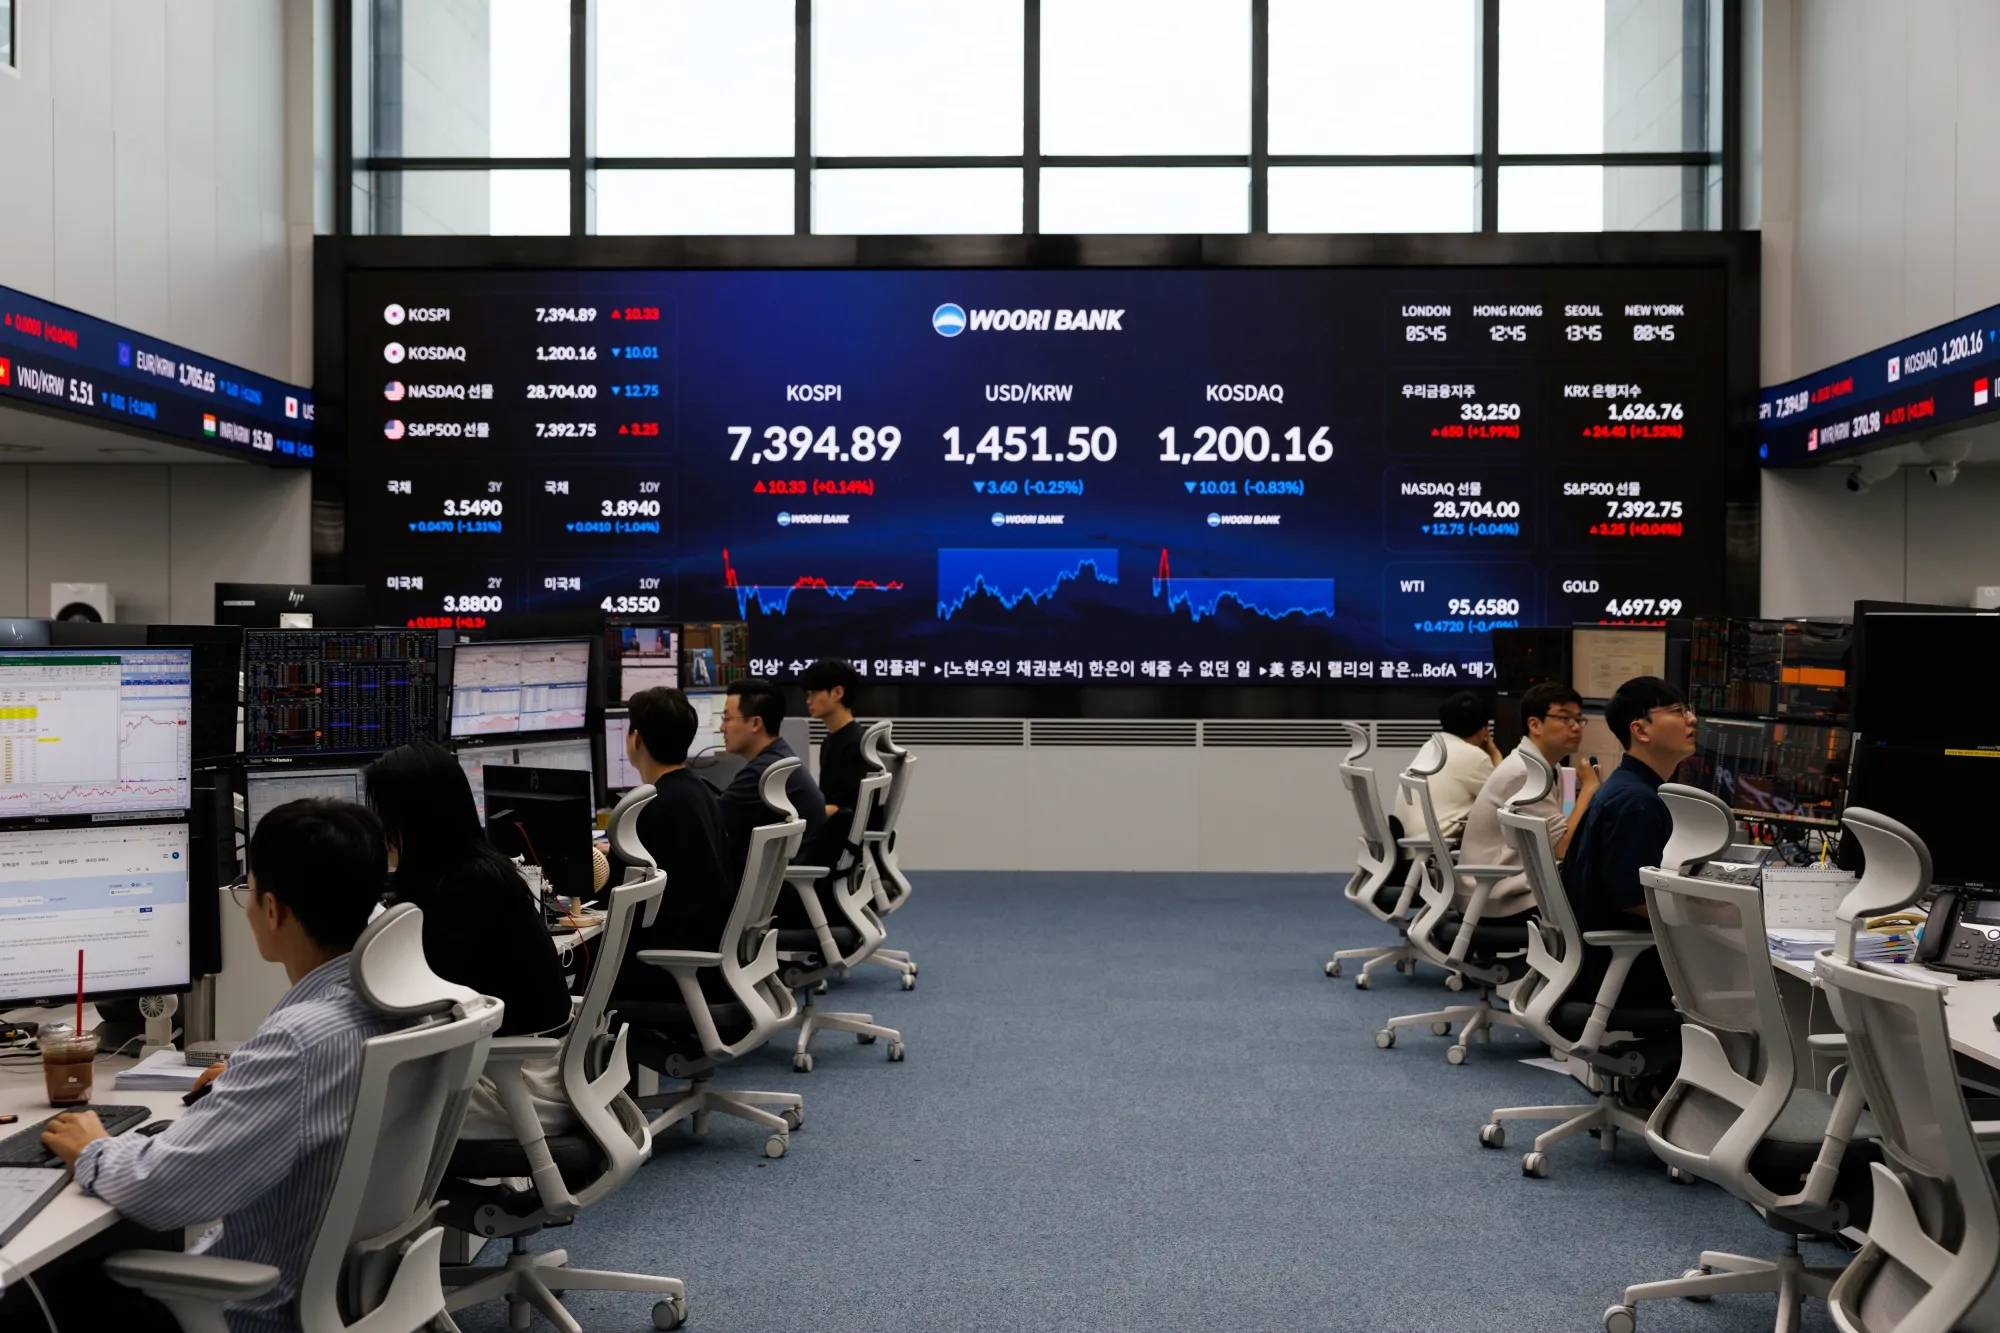
    China approved 18 actively managed exchange-traded funds on Monday, clearing domestic fund managers to channel tens of billions of yuan into mainland equities.

    Each fund could raise around 2 billion yuan, or roughly US$300 million, during subscription drives starting as early as Friday. The China Securities Regulatory Commission cleared the batch from domestic public fund houses after a three-month review. Fund managers may issue initial offer details as early as Tuesday, opening a direct pipeline of institutional cash for Shanghai and Shenzhen listings.

    Terms of the Fund Approvals

    Speaking at the Financial Street Forum in Beijing, CSRC chairman Wu Qing confirmed the approvals while outlining measures to stabilize equity prices. The new batch represents a shift toward active management within the exchange-traded market, giving portfolio managers leeway to select individual stocks rather than mechanically tracking broad equity indexes.

    Unlike passive benchmark trackers that buy across an entire gauge, actively managed funds allow stock pickers to concentrate capital in undervalued names or specific sectors. For domestic institutional investors, this structure offers a mechanism to deploy liquidity quickly without absorbing the broader market drag from troubled legacy sectors.

    State Capital Steps In

    The push follows sharp declines across mainland bourses. The benchmark CSI 300 Index fell 3.4 percent over the five trading sessions through Friday, capping an unprecedented 10-week losing run. Although the index bounced 0.3 percent on Monday following third-quarter growth data, it sits roughly 17 percent below its June peak, flirting with technical bear-market territory.

    State-backed institutional buyers, collectively known as the National Team, have already stepped up purchases. Inflows into leading broad-based ETFs reached their highest levels since July late last week, marked by heavy institutional volume near market close. The rollout of active ETFs expands this liquidity playbook from direct index intervention to discretionary equity allocation.

    Tech Valuations Under Pressure

    Mainland technology companies have borne the brunt of recent equity weakness as global enthusiasm for artificial intelligence hardware shifted. The tech-focused Star 50 Index dropped nearly 40 percent across the half year, turning into one of the weakest major tech gauges worldwide.

    Beijing has relied on equity markets to finance strategic technology developers, but falling secondary valuations threaten primary fundraising. In contrast, Hong Kong has seen growth companies in biotechnology and artificial intelligence rise to 30 percent of its listed pool from 10 percent in 2023, drawing capital that might otherwise seek mainland listings. Funneling fresh fund flows into Shanghai and Shenzhen gives domestic tech counters a valuation buffer at a time when retail sentiment remains fragile.

    Corporate Buybacks and Enforcement

    The regulatory initiative builds on market-support efforts launched in July, when Chinese authorities brought together state funds, domestic insurers, and asset managers to steady trading desks. That intervention curbed outright panic selling but failed to halt the weekly erosion across large-cap benchmarks.

    Regulators are pairing the ETF rollouts with pressure on corporate boards to execute share buybacks, alongside pledges by the CSRC to punish accounting misconduct and illegal trading. Attention now turns to Friday, when fund houses open their books for initial subscriptions to establish how much institutional and retail capital the 18 products collect.
  • S&P Dow Jones Indices Tests New Strategies in South Korea Ahead of Global Markets

    S&P Dow Jones Indices Tests New Strategies in South Korea Ahead of Global Markets

    S&P Dow Jones Indices is introducing its newest investment strategies in South Korea before other markets, using the country as a launchpad for global innovation.

    The index provider is testing products ranging from multi-asset and covered call strategies to thematic indices and blockchain-based versions of core benchmarks such as the S&P 500.

    Cameron Drinkwater, chief product and operations officer at S&P DJI, outlined the expansion in Seoul this week during Korea Premium Weeks. Drinkwater, who joined the firm in 2019 and previously served as chief financial officer, said local investor acumen and inventive financial firms make the country a prime testing ground.

    Tokenised Benchmarks and Retail Crypto Demand

    Digital asset infrastructure anchors the push into Seoul. South Korea maintains one of the highest retail cryptocurrency participation rates in Asia. That creates a consumer base accustomed to 24-hour trading, direct custody inside unified digital wallets and fractional share purchases. S&P DJI plans to match these trading habits by putting traditional benchmark exposures onto distributed ledger networks.

    On-chain indices allow asset managers to offer fractionated index units without the clearing overhead of traditional depository receipts. Tokenised index units reduce settlement friction for institutional distributors in Seoul. They also permit instant rebalancing across multi-asset portfolios. Local brokerages that run separate desks for domestic equities, offshore derivatives and digital tokens can merge those channels into unified mobile platforms.

    “It is a very important market for us not only because it is growing so quickly but also because of the amount of innovation that has been originating here,” Drinkwater said.

    Institutional Infrastructure and Product Design

    South Korean asset managers have become prolific issuers of complex exchange-traded products, particularly covered call strategies linked to major US equity indices. These yield-focused instruments sell call options against underlying index holdings to generate cash distributions for local retail accounts. Local firms frequently modify standard option-writing schedules to maximise monthly payouts. That push forces index providers to supply custom calculation algorithms and dynamic strike selection models.

    Execution plumbing carries the operational risk. Retail appetite for high-distribution strategies is strong, but covered call structures cap upside capital gains during market rallies. If domestic issuers flood the Seoul exchange with overlapping derivative-income products, secondary market liquidity could fragment. That would widen bid-ask spreads during periods of elevated equity volatility.

    Derivatives Expansion and Regulatory Timelines

    Expansion in Korea aligns with a broader buildout of S&P DJI’s global derivatives ecosystem. S&P DJI signed a 25-year extension of its exclusive licensing agreement with Cboe Global Markets through 2051. The agreement preserves Cboe’s exclusive rights to trade S&P 500 Index options while establishing joint work on tokenised option contracts. SPX options trading hit an annual record of 970.6 million contracts in 2025. Average daily volume reached 3.9 million contracts, up 25 per cent from 2024.

    Rollouts for on-chain indices in Seoul depend on final policy guidelines from domestic financial authorities. South Korean regulators are drafting frameworks for digital asset classification and tokenised securities through 2026. Technical operating standards are scheduled for completion in early 2027.

  • Ethereum Falls to $2,694 as BlackRock Outflows Snap Seven-Day ETF Inflow Streak

    Ethereum Falls to $2,694 as BlackRock Outflows Snap Seven-Day ETF Inflow Streak

    Ethereum dropped 1.26 per cent to $2,694.64 in 24 hours as institutional buyers paused after a seven-session run of net inflows into spot exchange-traded funds.

    United States spot Ethereum funds logged $2.81 million in net outflows on September 29, abruptly ending a week of sustained capital allocation.

    Institutional Outflows Snap Buying Streak

    BlackRock’s ETHA led the reversal, recording $8.94 million in net withdrawals in a single session. That outflow broke the momentum that had carried the token through its recent recovery, stripping away the primary source of spot market absorption. Without steady fund buying to soak up sell orders, the market turned defensive as short-term traders took profits.

    Institutional flows dictate price floors in this cycle far more than retail volume. When spot ETF allocations stall, spot books thin out rapidly, exposing used positions across major derivatives exchanges.

    use Flush Triggers Liquidation Cascade

    Derivative markets amplified the downturn within hours of the ETF flow reversal. Forced closures erased $11.88 million in used long positions in a single one-hour window on September 29.

    Total liquidations across all Ethereum trading pairs reached $56.64 million over the 24-hour period. That cascade pushed prices down through intraday bids, creating automatic selling pressure as brokerages closed under-margined accounts. Funding rates and open interest contracted as over-used traders were cleared out of the order books.

    Technical Support Levels Under Pressure

    Ether is now trading below overhead resistance at $2,786. The immediate support zone sits between $2,612 and $2,626, matching the token’s 20-day exponential moving average.

    A failure to hold the $2,612 floor opens a direct path toward secondary support at $2,544. Conversely, buyers must clear the $2,786 level on a daily closing basis to create momentum toward the next resistance target at $2,894.

    Macro Inflation Data Dictates Next Range

    Trading desks have shifted focus to broader macroeconomic indicators to gauge whether institutional allocators will resume spot buying. Risk appetite across digital asset markets remains tied to monetary policy expectations and interest rate differentials.

    Market participants are watching the United States Personal Consumption Expenditures price index release on September 30, with trading desks tracking whether the 20-day average near $2,612 holds through the macro print.

  • Global Used ETF Managers Court South Korea as Retail Assets Hit 25 Percent

    Global Used ETF Managers Court South Korea as Retail Assets Hit 25 Percent

    Global ETF managers are expanding in South Korea. They want to reach retail investors, who now account for up to 25 percent of their total assets.

    Russell Tencer, president of Tradr ETFs, visited Seoul on Thursday to meet investors. His trip followed a promotional roadshow by Tuttle Capital Management last week.

    Direct pitches in Seoul

    Tradr operates as an ETF brand under AXS Investments. It oversees roughly $500 million across about 60 used products, with South Korean retail accounts making up approximately 10 percent of that pool.

    Individual Korean traders took note of the issuer in 2022. That interest followed the launch of single-stock inverse vehicles for Tesla and Nvidia under tickers TSLQ and NVDS. Today, its catalogue covers single-stock used funds tied to Coupang, SK hynix, SanDisk and SpaceX.

    “We want to meet with our investor base,” Tencer said at a press briefing in Seoul. “We would love to meet and educate Korean investors.”

    Tuttle Capital Management holds an even larger share from the country. South Korean accounts represent 25 percent of the firm’s $5 billion in assets across 70 active funds, which include its double-exposure T-REX series. The US firm ran its own investor presentations in Seoul earlier this month.

    Trading volumes eclipse direct shares

    Korean retail activity in used overseas instruments now beats direct equity buying in major global tech firms. Direxion Daily Semiconductor Bull 3X Shares, traded under ticker SOXL, generated $72.64 billion in combined buy and sell volume from Korean traders this year.

    That turnover was nearly six times the $12.6 billion worth of Tesla shares traded locally over the period. High-beta exposure drives these offshore flows across Seoul desks.

    Domestic brokerage houses are aiding the shift. Many host issuer seminars and marketing events for offshore managers seeking local distribution.

    Domestic curbs push capital abroad

    Local regulations helped push retail capital into US-listed instruments. Financial authorities allowed domestic single-stock used funds to trade in late May. However, they attached heavy friction to the rollout.

    Regulators enforced minimum cash deposits and mandatory order-size caps on domestic single-stock used instruments. These rules slowed domestic turnover. Individual accounts turned to offshore equivalents instead, using standard global brokerage accounts to trade higher use multiples.

    Shifts in currency added extra volatility. The South Korean won recently strengthened into the 1,300 won range against the US dollar. That move led some retail traders to trim dollar gains, but overall trading velocity stayed high.

    New products tied to Korean tech

    Appetite from Seoul is reshaping product design in the US ETF market. Foreign managers now build instruments tailored directly to retail demand for domestic tech and semiconductor names listed abroad.

    Filings from Tradr show additional funds coming for the country’s hardware sector. These target active trading in memory chips and display components.

    US regulators will review incoming offshore single-stock filings as foreign issuers test how deeply South Korean retail capital backs specialized tech funds heading into 2027.

  • Exchange Traded Concepts Launches 20-Stock Korea Semiconductor ETF on NYSE Arca

    Exchange Traded Concepts Launches 20-Stock Korea Semiconductor ETF on NYSE Arca

    Exchange Traded Concepts announced Monday it has partnered with Kiwoom Securities (USA) to launch the KICK Korea Semiconductor Index ETF on NYSE Arca under the ticker KCHP.

    The fund tracks an index of 20 semiconductor companies listed on the Korea Exchange across memory, foundry, equipment, materials, packaging, and design, anchored by Samsung Electronics and SK Hynix.

    How the Index Structure Works

    American institutional and retail buyers can now trade direct exposure to South Korea’s chip supply chain through standard brokerage accounts. They do not need local accounts on the Korea Exchange. Because underlying assets trade in Korean won, currency swings against the US dollar will directly affect net investor returns.

    Exchange Traded Concepts uses a modified market-capitalization weighting model to cap exposure to individual heavyweights. This structure prevents Samsung Electronics and SK Hynix from dominating the fund. Beyond the two primary chipmakers, the basket holds domestic producers of specialty materials, design houses, packaging contractors, and manufacturing equipment.

    The Play on Asian Hardware Suppliers

    Most broad Asian equity funds dilute exposure across consumer internet, banking, and conglomerates. That dilution blunts direct participation in the memory chip cycle. Packaging Korea’s specialized fabrication network into a single product targets investors seeking pure hardware exposure tied to global computing infrastructure, bypassing single-stock settlement risk on Seoul’s bourse.

    Earnings power remains heavily concentrated at the top. The supply chain beneath Samsung and SK Hynix relies directly on the capital spending plans of those two anchor tenants. When memory pricing or capital budgets swing in Seoul, ancillary tooling and packaging vendors face sharper revenue volatility.

    Tracking Capital Shifts Across the Pacific

    Yoon Gu Eric Lee, president and CEO of Kiwoom Securities (USA), said the index captures the secondary equipment, materials and design companies built around the country’s memory and foundry sectors.

    Trading in KCHP will test US investor appetite for targeted Asian hardware suppliers. Portfolio managers will have to balance foreign-exchange risk against direct equity holdings in Seoul.

  • South Korean Retail Traders Amass Billions in US Used ETF’s

    South Korean Retail Traders Amass Billions in US Used ETF’s

    South Korean retail investors poured an estimated $10 billion into US used exchange-traded funds during the first half of the year. The buying gave them dominant stakes in several high-risk products. Korea Securities Depository filings show domestic accounts held $5.24 billion in the Direxion Daily Semiconductor Bull 3X Shares alone. That equals 27 per cent of the fund’s $19.3 billion market capitalisation.

    This concentration spreads well past semiconductor tracking. Korean buyers hold 38.8 per cent of the Direxion Daily TSLA Bull 2X Shares and 37.6 per cent of the Direxion Daily MSCI South Korea Bull 3X Shares, alongside 20.9 per cent of the ProShares Ultra QQQ. Net buying of the semiconductor fund reached $2.43 billion this year. That outstripped demand for standard index trackers by a factor of 1.5.

    Regulatory Caps at Home Drive Outflows

    Financial regulators in Seoul prompted the overseas shift by imposing minimum deposit rules and volume ceilings on domestic single-stock used products. The restrictions failed to cool risk appetite. Capital flowed straight to US exchanges, where investors access uncapped daily use across individual equities, semiconductor benchmarks, and international country indices.

    Total Korean equity holdings in the US stand at $112 billion. That is barely 0.2 per cent of total American market capitalization. In specialized used derivatives, however, concentrated buying turned Seoul day traders into the dominant liquidity provider.

    Past retail surges across East Asia followed a similar pattern. Tighter domestic margin rules in markets like Hong Kong and Tokyo pushed speculative volumes into offshore derivatives whenever local platforms restricted margin access.

    Night Trading Halts Force Blind Orders

    Heavy order flow disrupted execution infrastructure on September 1. Alternative trading system Blue Ocean ATS suspended daytime trading for 18 securities, including the top semiconductor and Korea bull funds. The platform acted under the US Securities and Exchange Commission Fair Access Rule. That rule triggers extra regulatory burdens when an alternative venue handles 5 per cent or more of a single security’s volume over four out of six months.

    Local brokerages including Samsung Securities and Toss Securities routed daylight orders to alternative platforms MOON and Bruce to keep order lines open. These backup venues do not deliver real-time quote feeds. Clients had to enter limit orders without viewing bid and ask spreads.

    Blue Ocean reviews trading volumes monthly to determine when the 18 suspended securities can return to its platform. Meanwhile, brokerage houses in Seoul are building backup order-routing networks to prepare for further liquidity limits.