Tag: fashion retail

  • Uniqlo Rolls Out Life Wear Week in Singapore for Fall/Winter 2026

    Uniqlo Rolls Out Life Wear Week in Singapore for Fall/Winter 2026

    Uniqlo rolled out Life Wear Week across its Singapore stores in September 2026, tying local promotions to its global Fall/Winter launch. The campaign spanned the island. It featured in-store installations, consumer styling sessions, and tiered gift-with-purchase incentives for apparel shoppers.

    Activations supported the retailer’s ‘Modern City Feelings’ theme, aimed at urban shoppers tracking digital fashion trends. The Japanese chain built the campaign around social media’s role in spreading local city styles across borders.

    Localizing global seasonal campaigns

    Paulene Ong, marketing director of Uniqlo Singapore, led the islandwide drive. The rollout paired physical floor displays with local wardrobe advice. That helped pull shoppers into stores during the seasonal changeover.

    Apparel retailers in Southeast Asia face a clear challenge with autumn and winter lines. Tropical climates do not require heavy cold-weather coats for daily wear. To counter this, Uniqlo focused its Singapore displays on lightweight layering, versatile city travel pieces, and functional innerwear for local commuters and regional travellers.

    The shifting mechanics of city retail

    This push reflects a wider operational shift across Southeast Asian hubs. Rather than relying solely on standard regional distribution, global fast-retailing brands now use experiential marketing, tailored visual merchandising, and timed gifts to lift basket sizes.

    Competitors across Singapore and Malaysia have also expanded experiential floor space to protect margins against online pure-plays. For mall landlords, interactive setups like styling sessions boost repeat visits and keep shoppers in flagship stores longer.

    What to watch across the network

    Parent company Fast Retailing continues to expand Uniqlo’s Southeast Asian footprint. It uses gateway markets like Singapore to test consumer response to global collection themes before widening regional promotions. Core LifeWear lines remain crucial to keeping up sales momentum across the regional fleet.

    Attention now shifts to sell-through rates for the Fall/Winter 2026 assortment across Southeast Asia as year-end travel demand builds toward the fourth quarter.
  • Esprit Faces US$4 Million Statutory Demand in Hong Kong over European Arbitration Loss

    Esprit Faces US$4 Million Statutory Demand in Hong Kong over European Arbitration Loss

    Creditors have served Hong Kong-listed Esprit Holdings with a statutory demand for nearly US$4 million following an arbitration defeat over its collapsed European operations. The apparel brand manager has three weeks to settle the debt or face a winding-up petition in Hong Kong.

    The claim stems from an ICC International Court of Arbitration award tied to the 2024 failure of Esprit’s European business. Esprit disclosed the liability in half-year results published last month. The formal demand sharply escalates immediate legal exposure.

    The Three-Week Liquidation Clock

    Under Hong Kong insolvency rules, a debtor has 21 days to satisfy or reach terms on a statutory demand. Miss that window, and the creditor can petition the High Court for compulsory liquidation. The law firm owed the arbitration award can start those proceedings if Esprit fails to pay.

    A winding-up petition would freeze asset transfers, disrupt banking relationships, and threaten the group’s listing status on the Hong Kong Stock Exchange.

    European Restructuring Fallout

    Heavy store overheads and sustained losses forced Esprit’s European operating subsidiaries into insolvency in 2024. Management tried to cut those liabilities loose. The board then shifted focus to brand licensing, e-commerce, and joint ventures in Asia.

    Legacy disputes continue to dog the holding company. Unresolved contractual claims from European counterparties remain a direct drain on cash reserves already strained by years of turnaround attempts.

    Mounting Financial Pressure

    The demand arrives as Esprit forecasts another annual loss. Prolonged operational restructuring has failed to reverse revenue declines across core channels, leaving the balance sheet vulnerable to unexpected cash calls.

    Regional retail partners and suppliers face renewed counterparty risk as European liabilities reach the parent entity in Hong Kong.

    Next Steps on the Docket

    Esprit must now decide whether to settle the US$4 million claim in full, negotiate a payment plan, or apply to the court to set aside the demand before the 21-day countdown expires.

  • Converse Opens 2 Next-Generation Stores in Nanjing and Shanghai

    Converse Opens 2 Next-Generation Stores in Nanjing and Shanghai

    Converse opened two concept stores in Nanjing and Shanghai in September 2026 as part of an experiential retail push across mainland China. The footwear brand already distributes through more than 700 locations across the country. Those operations are led by its Star Concept and X-Ing shop formats.

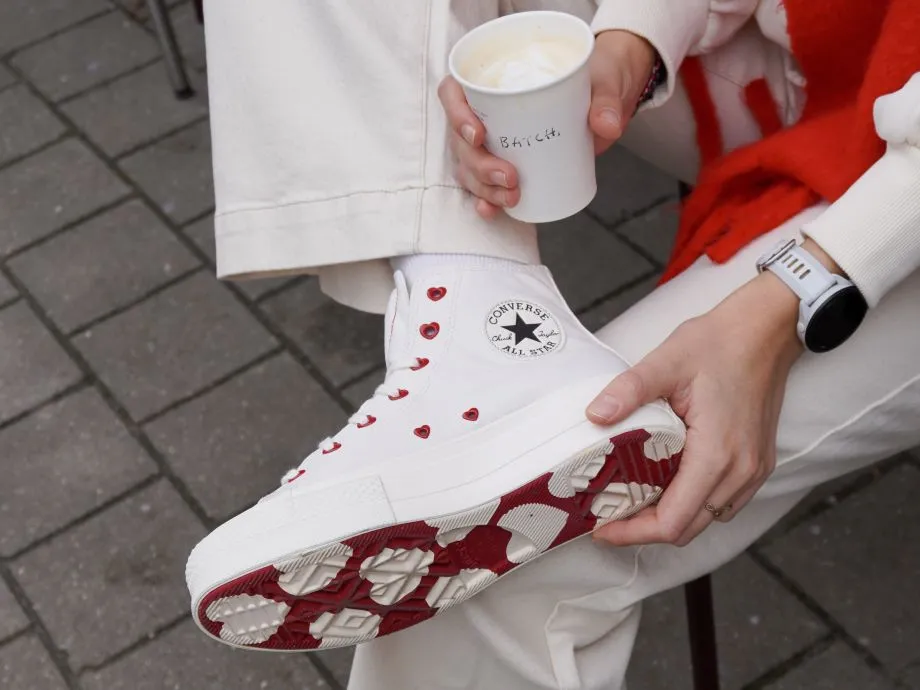
    In Nanjing, the store follows the Converse Star Concept design. It pairs localized city storytelling with premium product allocations. There is also a dedicated Converse Select zone built for early-access releases and top-tier merchandise. The site served as the debut platform for the Chuck 70 X, an updated edition of the core sneaker with an altered structural fit and cushioned insoles.

    Community Formats on Yuyuan Road

    On Yuyuan Road in Shanghai, the brand launched a Converse X-Ing store. The location functions as an interactive hub rather than a transactional shop. It incorporates customisation workshops, art displays, rotating pop-ups, and collaborative workspaces for local designers.

    Converse said in an announcement detailing the Shanghai site that the store invites creators and consumers to connect through community programming.

    Shifting Floor Space to High-Touch Retail

    Sportswear brands in China face heavy margin pressure from domestic e-commerce channels and local rivals. Footwear labels are responding by reallocating capital into prime street locations and major mall units. These spaces serve as marketing assets rather than simple stock rooms. By splitting tiers between core Star Concept stores and creative X-Ing outposts, Converse aims to defend its pricing power and cultural cachet with younger urban shoppers.

    Higher overhead creates real risk for operators. Prime rents on strips like Yuyuan Road add up quickly alongside event production and staffing costs. If programming fails to drive repeat visits and full-price sales, concept spaces turn into costly marketing drains rather than profitable channels.

    Building Out the Asia Network

    These mainland openings follow the rollout of larger formats across Asia, including the launch of the brand’s largest flagship store in India in June 2026. Across the region, the company continues to refine its direct retail tiers. This separates basic wholesale distribution from high-margin specialty releases.

    Market watchers will track how the Chuck 70 X and Select zone lines perform across the wider 700-door mainland network before Converse takes the Star Concept format into secondary Chinese retail hubs.

  • Cue Clothing Loses CEO and CFO as Hilco Puts 51-Store Retailer on Market

    Cue Clothing Loses CEO and CFO as Hilco Puts 51-Store Retailer on Market

    Cue Clothing Co is operating without a chief executive or chief financial officer as owner Hilco Capital attempts to sell the 51-store Australasian fashion retailer.

    CFO Josephine Barbaro departed during the sale process, followed shortly after by CEO Melanie Remai, leaving the Sydney-founded owner of Cue and Veronika Maine without top executive leadership.

    Executive Exits During FTI Advisory Mandate

    Advisory firm FTI Consulting is managing the sale on behalf of Hilco, which placed the retailer on the market just over a year after acquiring it. Both departing executives spent less than two years combined at the company.

    Hilco put the retail network on the market despite a 5 per cent annual sales increase that internal forecasts project will continue. The UK turnaround firm has not issued an official rationale for the rapid divestment.

    Operational losses at the business have narrowed over the past year. They remain substantial enough to weigh on cash flow, while inflexible long-term store leases across Australia and New Zealand restrict further rent reductions.

    Turnaround Friction and Portfolio Track Record

    For private equity buyers and turnaround specialists in the Asia-Pacific apparel sector, the breakdown highlights the structural risk of inherited retail footprints. High street landlords across major Australian shopping centres continue to enforce long lease terms, limiting the room private owners have to restructure cost bases without formal insolvency processes.

    Hilco has run into similar operational friction across its consumer portfolio in recent cycles. The firm placed UK homeware chain Homebase into administration in 2024, and it offloaded accessories brand Cath Kidston to Next Plc in 2025 for 16 million Australian dollars, equivalent to 8.5 million British pounds.

    Legacy Leases and the Next Ownership Phase

    The Sydney fashion house built its reputation over five decades on local design and premium department store distribution before selling to Hilco. The private investment firm took control with plans to stabilise the brand following post-pandemic trading shifts.

    Prospective bidders reviewing the FTI sale memorandum must now price in executive recruitment costs alongside fixed store lease commitments across the 51 operating locations.

  • Heavy Pop Brings Vietnamese Streetwear to Siam Discovery in Bangkok

    Heavy Pop Brings Vietnamese Streetwear to Siam Discovery in Bangkok

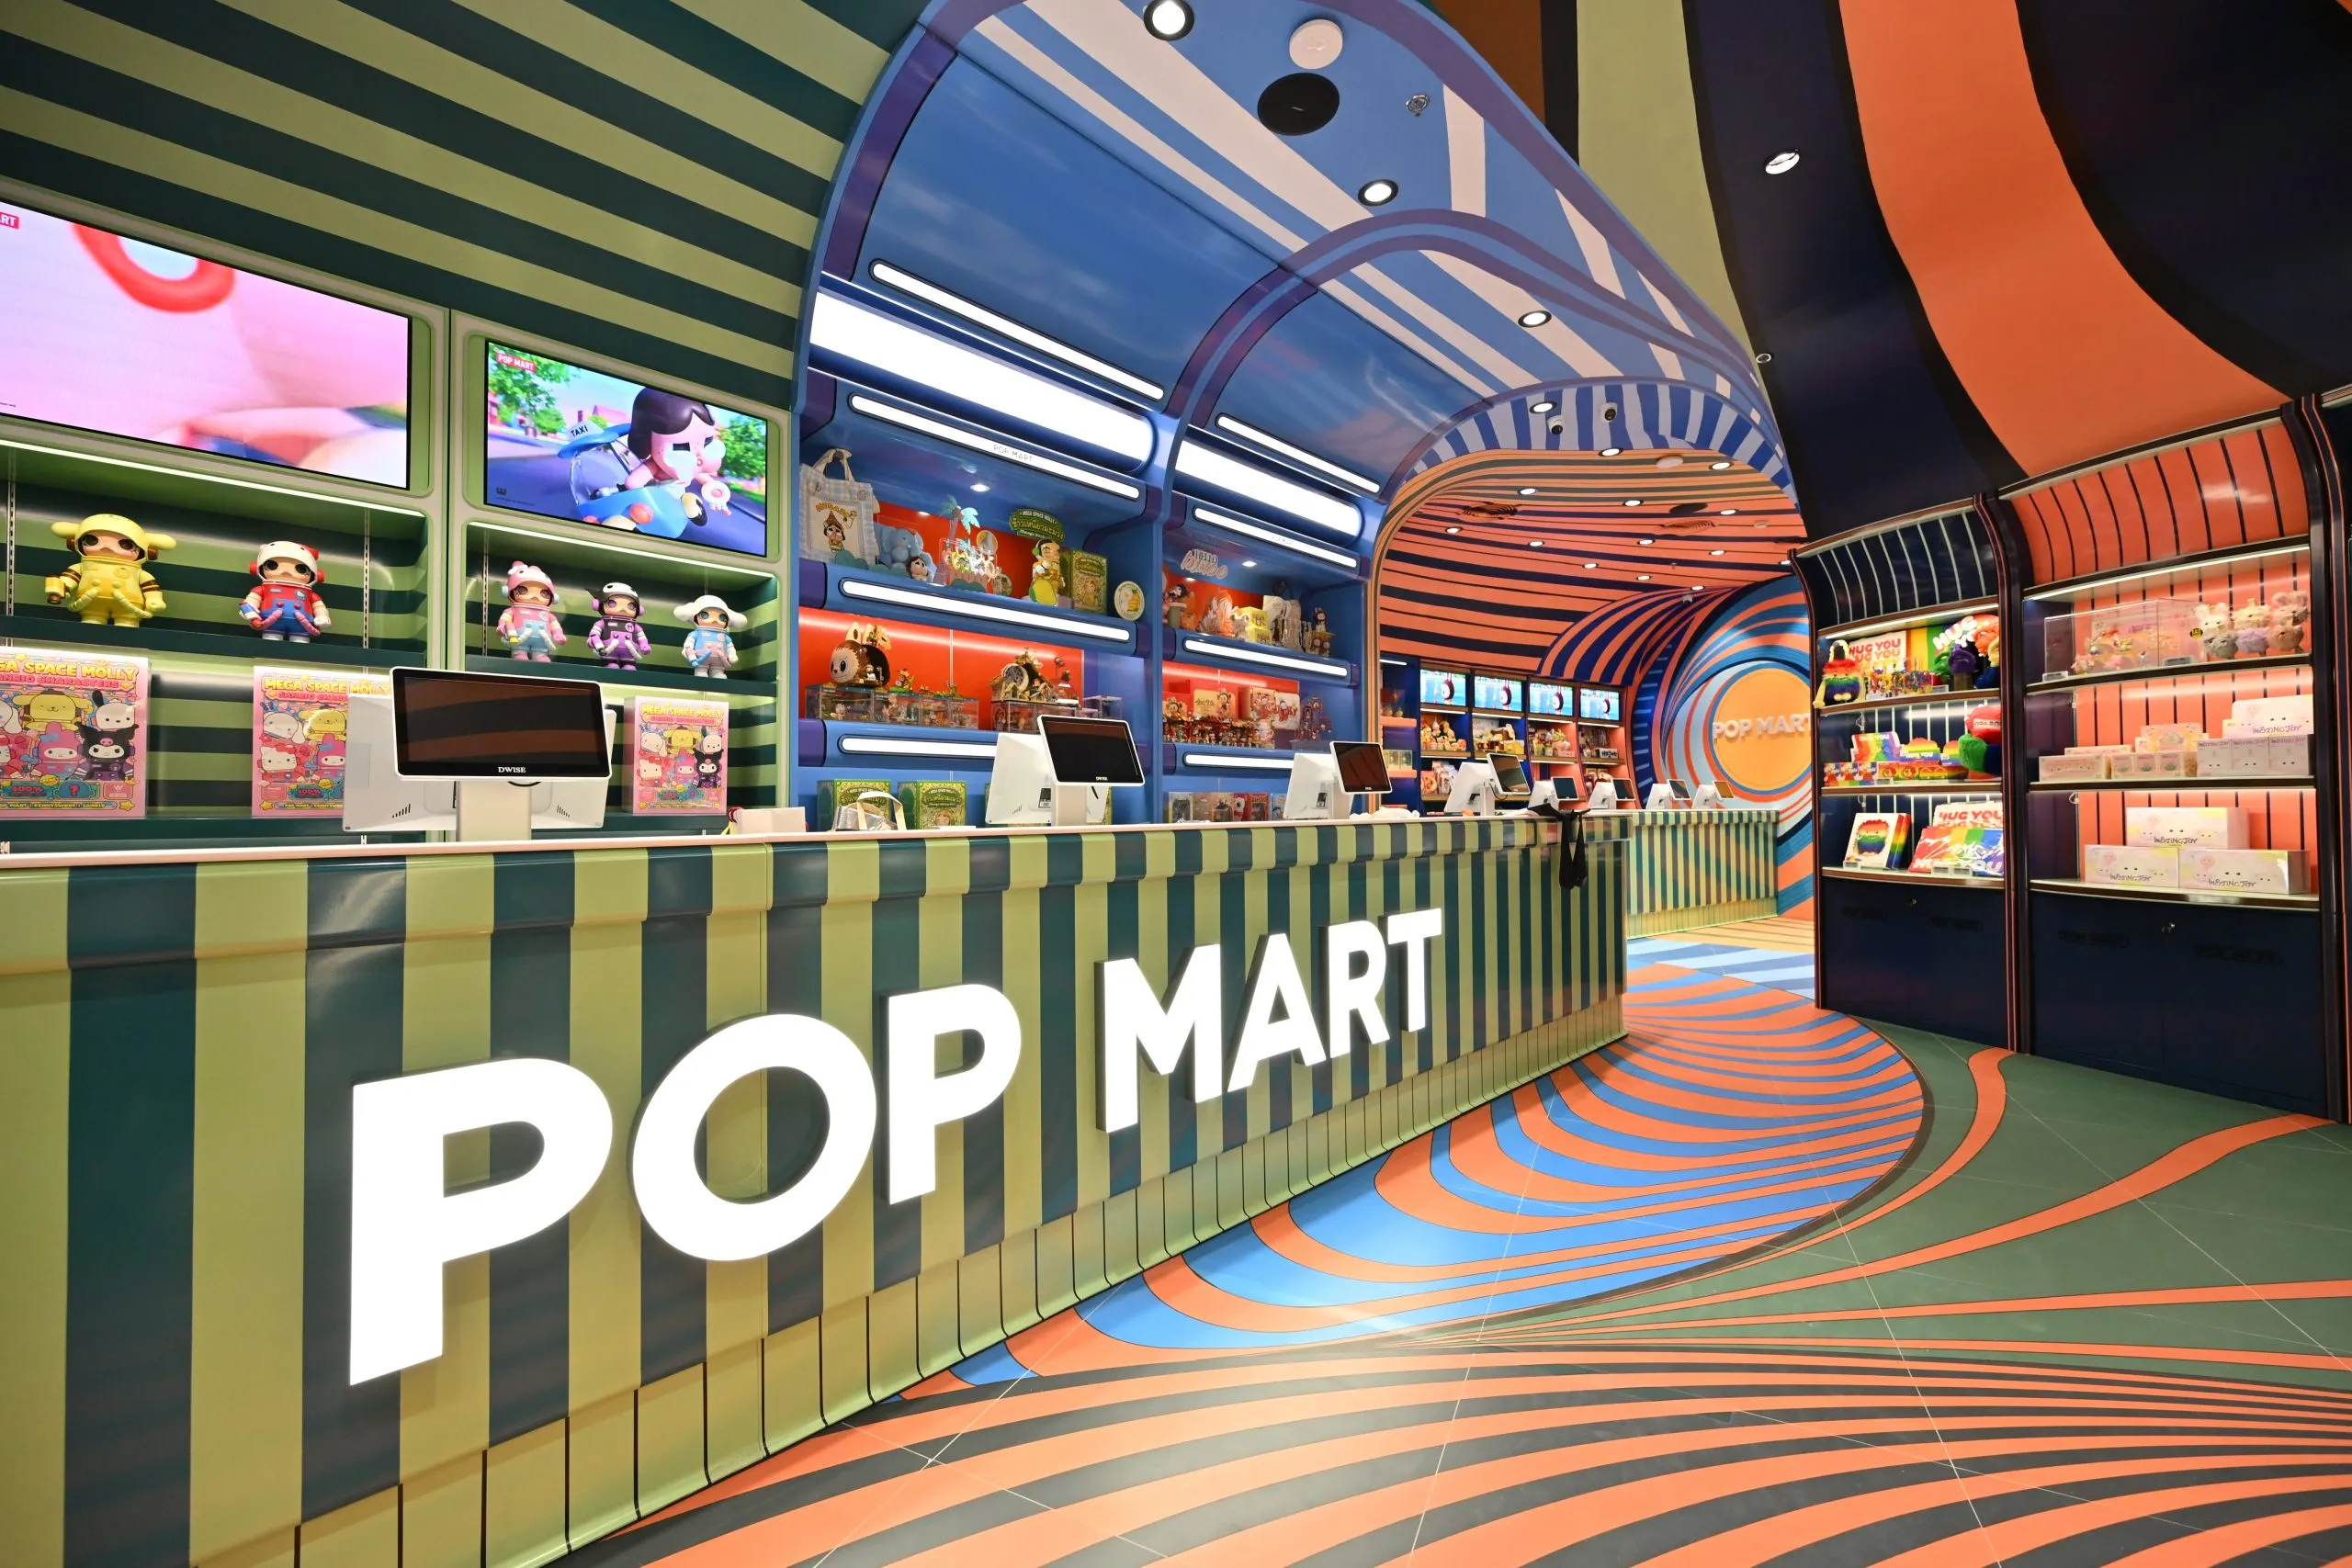
    Vietnamese fashion platform Heavy Pop opened a pop-up store inside Bangkok’s Siam Discovery mall this September. It brings domestic streetwear brands to Thai consumers.

    Labels including Stressmama, DirtyCoins and Hades now sit on the complex’s first floor. Together, the Thai and Vietnamese streetwear markets represent an estimated $1 billion to $2 billion in value.

    Heavy Pop operates without permanent stores. Instead, the curator secures short-term space in busy regional hubs to show Hanoi and Ho Chi Minh City labels. Its Bangkok floor features graphic T-shirts, relaxed shorts and oversized hoodies.

    Contrasting aesthetics drive mall demand

    Mall operator Siam Piwat is dedicating square footage across Siam Discovery, Siam Center, Siam Paragon and Iconsiam to emerging regional brands. It avoids relying solely on global chain tenants. The Vietnamese apparel provides a dark contrast to domestic Thai streetwear, which leans toward vibrant colours, internet memes and Muay Thai boxing references.

    Both markets design for tropical heat with boxy silhouettes and gender-neutral cuts. Streetwear across Asia-Pacific continues to outperform broader retail benchmarks. Fortune Business Insights values global sector revenue at nearly $398 billion in 2026, alongside a projected 7.95 per cent annual growth rate through 2034.

    Regional platforms step in where Western retailers lag

    Landlords gain foot traffic from younger shoppers hunting for limited drops. For the brands, physical floor space in Bangkok offers an essential international testing ground. Western retail chains still lack the direct supply-chain connections to distribute niche Asian streetwear profitably.

    Production scale remains the primary operational bottleneck. Vietnamese streetwear houses maintain brand equity through small, exclusive production runs. That prevents them from fulfilling wholesale inventory minimums required by global department stores or scaling beyond direct-to-consumer e-commerce.

    Siam Piwat accelerates regional brand incubation

    Curated retail initiatives are expanding across Siam Piwat properties. Alongside the Heavy Pop installation, Siam Discovery added ground-floor spaces this month for Vietnamese womenswear labels Cocosin and Mollynista.

    The pop-up runs at Siam Discovery through the end of September 2026. Tenant turnover will follow ahead of fourth-quarter holiday trading.

  • Australian Adaptive Apparel Brand Jam the Label Closes Down

    Australian Adaptive Apparel Brand Jam the Label Closes Down

    Australian adaptive apparel brand Jam The Label will shut down operations after founders Emma Clegg and Molly Rogers declared the business commercially unviable. The company ceased all new product manufacturing following seven years of running an inclusive clothing line that shipped internationally from Australia.

    Former disability support workers Clegg and Rogers founded the business in 2019 to design functional, stylish clothing for people with disabilities. Growth was supported partly through participant purchases via Australia’s National Disability Insurance Scheme (NDIS), alongside appearances on mainstream runway circuits and fashion festivals. Both founders confirmed they will no longer produce inventory as they shift focus to their families following recent births.

    Market Education Burden on Independent Labels

    Specialist apparel brands across Asia-Pacific face heavy acquisition costs when attempting to build niche categories without department store distribution. Jam The Label carried the entire financial weight of consumer education, fit development and specialized manufacturing runs without institutional equity backing.

    Mainstream apparel retailers across the region have largely treated adaptive clothing as occasional capsule lines rather than permanent departments. That leaves independent operators to absorb high fabric minimums and complex design iterations on thin cash buffers. For suppliers and investors, the closure shows that government support schemes alone cannot substitute for high-volume retail distribution.

    The Limits of Specialized Retail Models

    Clegg and Rogers pointed directly to the commercial mismatch between independent brand resources and the demands of market creation. The sector was not ready to sustain a dedicated direct-to-consumer label without broader retail infrastructure.

    “We have put our heart and soul into Jam, but it is tough for small businesses to carry a clothing category and educate a whole market,” the founders said in a joint statement.

    The label gained regional visibility in 2021 and 2022 by securing runway slots at major Australian fashion weeks, demonstrating demand for accessible fasteners and seated-fit tailoring. Those appearances expanded international order volumes but did not lower production costs enough to offset rising operational overheads.

    Clearance of Remaining Production Batches

    Jam The Label will sell through its remaining stock online before formally winding down its corporate entity. Wholesale accounts and disability sector advocates will watch whether larger apparel groups acquire the brand’s technical fit patterns or leave the Australian adaptive apparel space to generalist overseas platforms.

  • Malbon Golf Expands in China with Stores in Shanghai and Beijing

    Malbon Golf Expands in China with Stores in Shanghai and Beijing

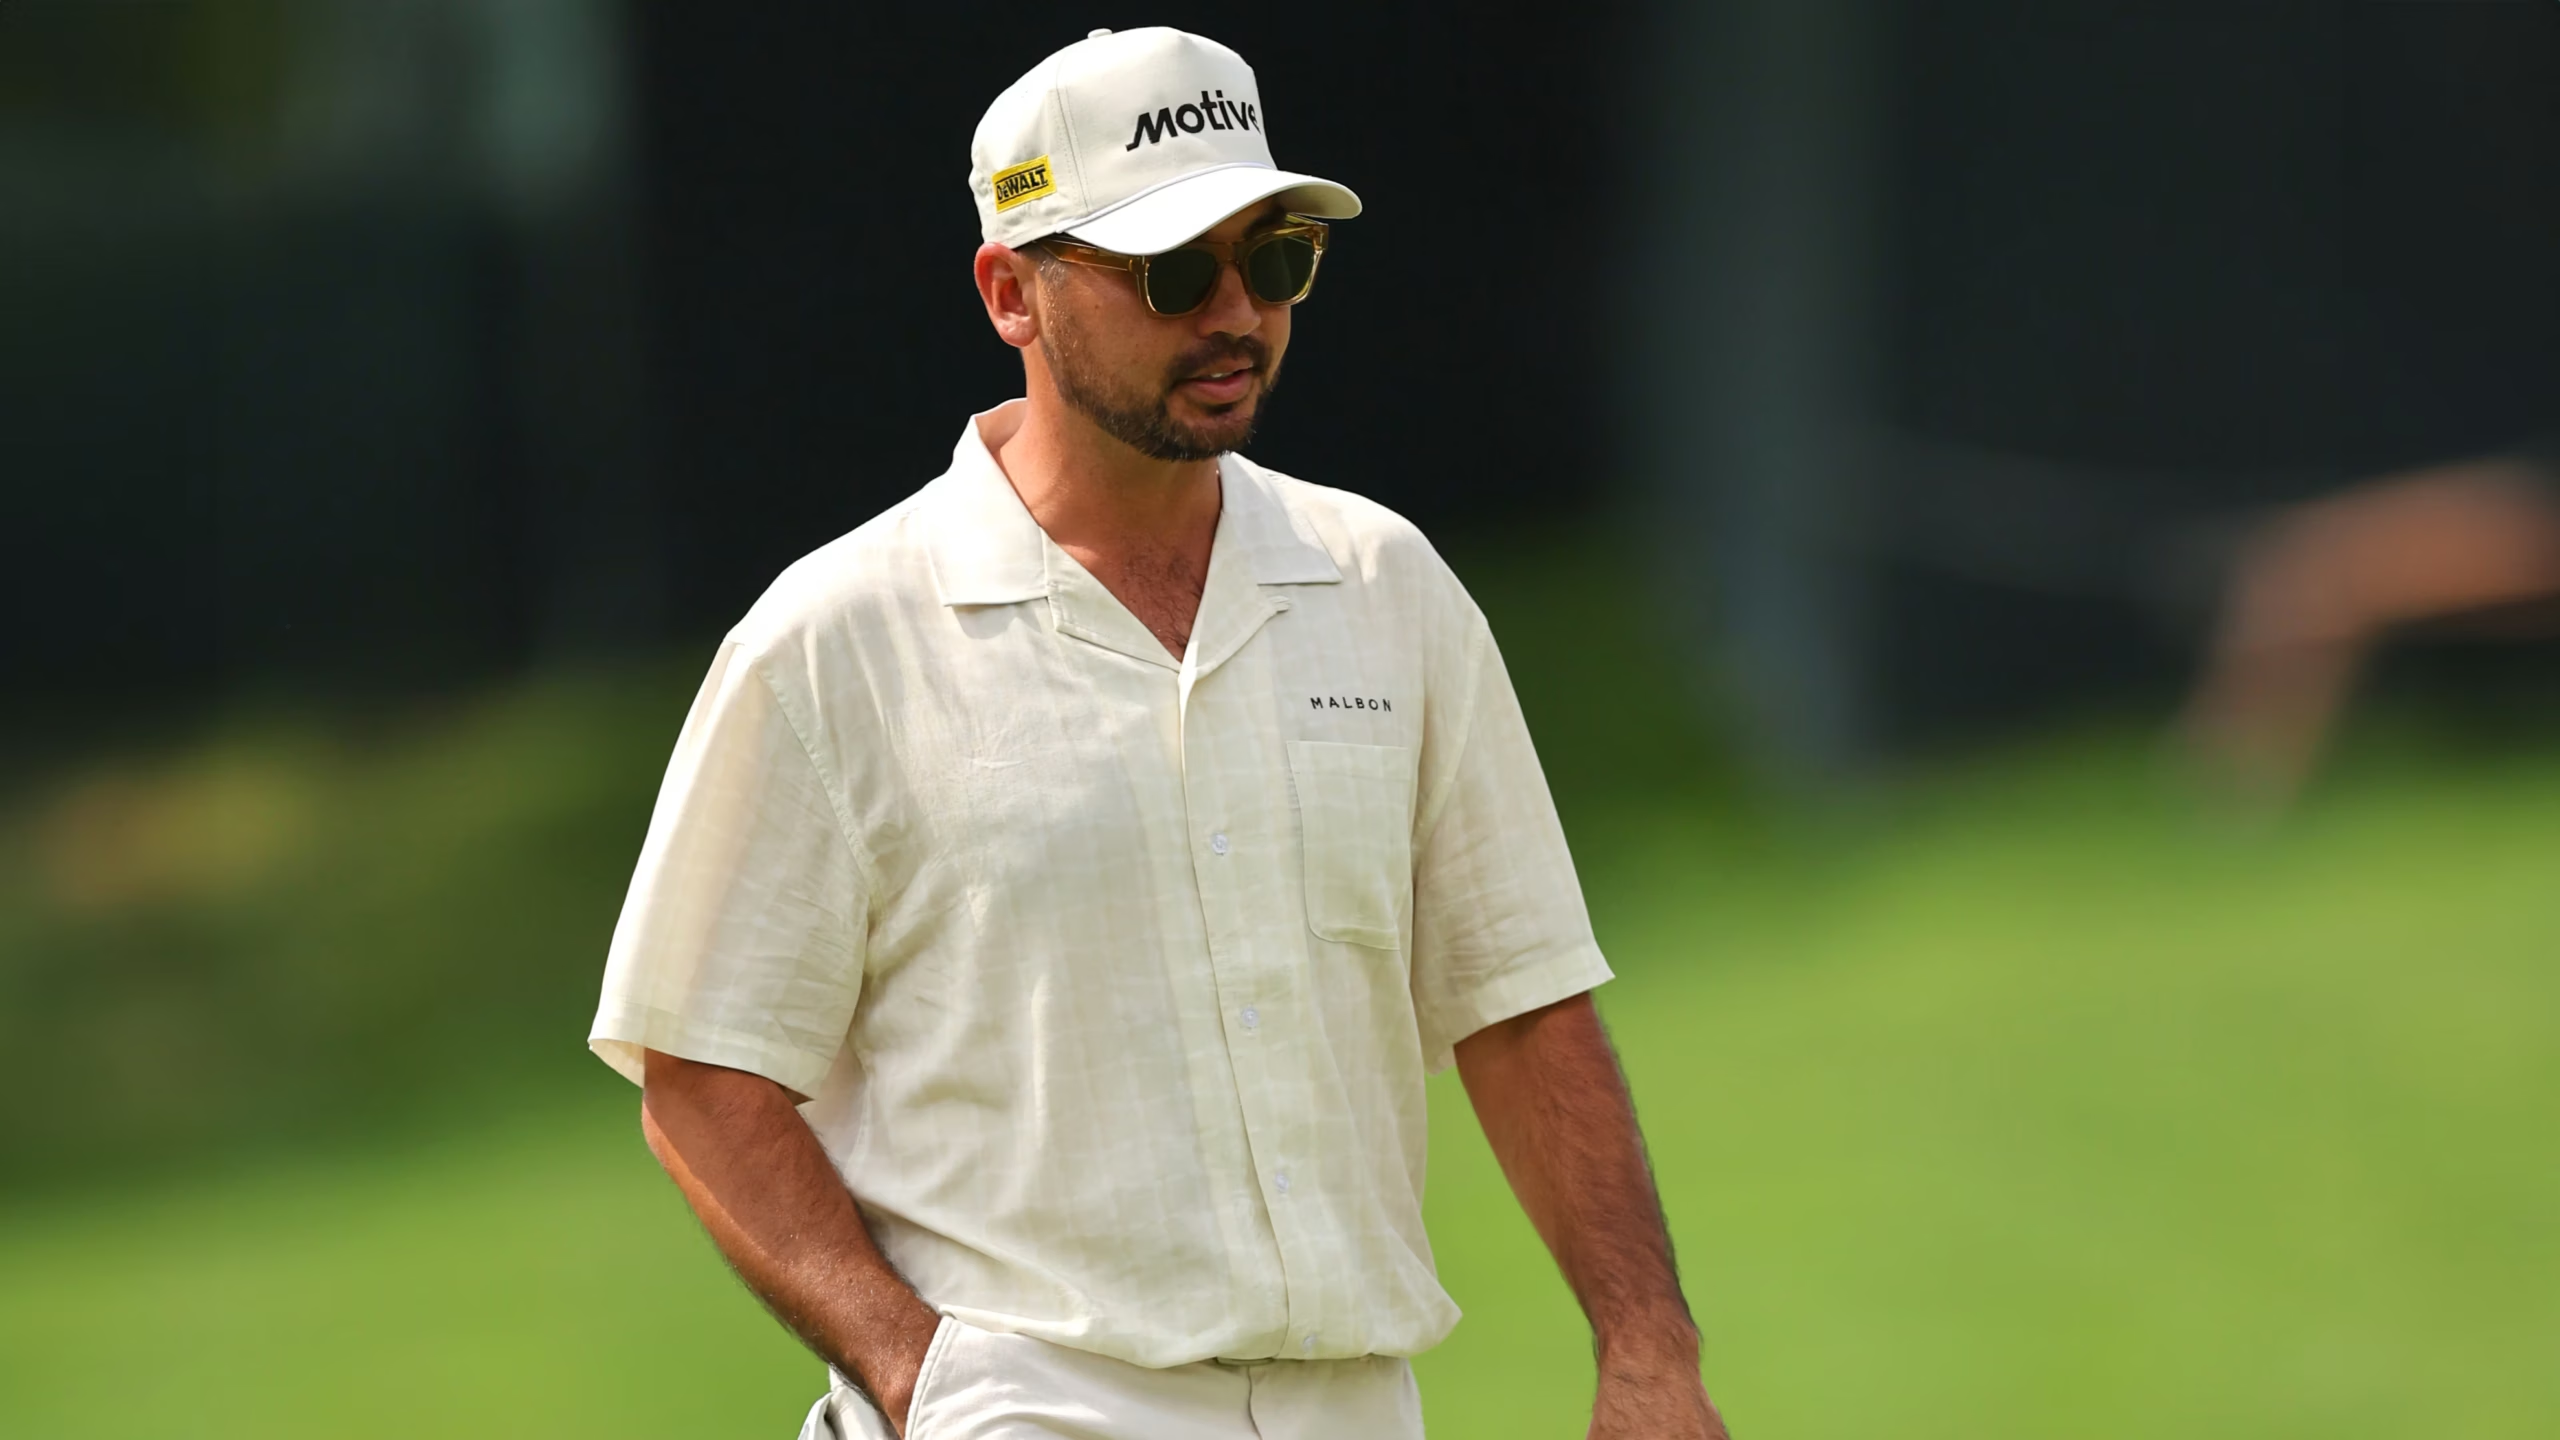
    US golf lifestyle brand Malbon Golf is expanding its retail presence in China with locations in Shanghai and Beijing as part of its broader market expansion strategy.

    Founded in Los Angeles in 2017, the company has partnered with TKG Lifestyle to support its rollout, with Hangzhou and Shenzhen among the next markets in its pipeline.

    Tier-one footprint and localized store designs

    Earlier this year, the brand opened its first Mainland China flagship at Shanghai’s Jing’an Kerry Centre, followed by a second location in the West Bund and a store at Beijing’s Taikoo Li Sanlitun.

    Its Shanghai stores combine golf and streetwear aesthetics with references to local culture, with the West Bund site incorporating vintage imagery, creative elements, and interactive golf features. The Taikoo Li Sanlitun store in Beijing features localized design elements alongside city-specific apparel and lifestyle collections.

    The streetwear crossover in Chinese sports retail

    China-exclusive products form part of the company’s local strategy, with city-specific collections developed alongside its core golf apparel and accessories. Malbon’s partnership with TKG Lifestyle also extends to other regional markets, including Vietnam and the Philippines.

    Earlier expansion steps

    Malbon operates at the intersection of golf and lifestyle fashion, with collections and collaborations spanning apparel, accessories, and cultural partnerships since its founding in 2017. The planned expansion into Hangzhou and Shenzhen will further extend the label’s footprint across major Chinese cities.

  • Fast Retailing Names James Kelly as Global CEO of Theory

    Fast Retailing Names James Kelly as Global CEO of Theory

    Theory appointed James Kelly as its global chief executive officer, elevating the former Fast Retailing executive after two years in senior leadership at the New York-based fashion brand.

    Kelly takes over from Dinesh Tandon, who led the label globally since 2019 and now returns to run Theory China while serving as global co-chief operating officer alongside Serena Peck.

    Leadership reshuffle across two labels

    In his new post, Kelly assumes oversight of both Theory and sister label Helmut Lang. His remit covers global headquarters functions, commercial operations and international expansion.

    Kelly joined Theory in 2022 as chief financial officer before stepping into the global co-chief operating officer role. Prior to that, he spent years inside Japanese parent group Fast Retailing, where he directed store network expansion for Uniqlo across the United States and Canada.

    Sharpening focus on Asian retail operations

    Splitting global commercial control while sending Tandon directly back to helm China operations shows how Fast Retailing is organizing its premium brands around Asian retail demand. Putting an experienced operator on the ground in China gives the Japanese group closer operational control over store productivity, concession partnerships and local inventory allocation in a highly competitive market.

    For competing contemporary fashion labels across East Asia, the management shift signals an aggressive push from Fast Retailing to scale its higher-margin portfolio. Theory provides Fast Retailing with access to affluent office workers who want technical tailoring, a segment where traditional European designer labels face margin pressure at entry-level price points.

    Two decades under Japanese ownership

    Andrew Rosen and Elie Tahari founded Theory in New York in 1997, building the brand on stretch-fabric tailoring and contemporary workwear. Japanese licensee Link International acquired the company in 2003, and Fast Retailing took full ownership of the business in 2009.

    Link Theory Holdings had previously purchased Helmut Lang from Prada Group in 2006, creating the high-end apparel pillar that sits alongside Fast Retailing’s mass-market Uniqlo and GU banners.

    Commercial execution to watch

    Retail observers will track Tandon’s store rollout and comparable-sales performance across mainland China’s department store network, alongside Kelly’s progress in turning Helmut Lang into a steady profit generator.

  • Furla Opens 75Sqm Boutique at the Venetian Macao

    Furla Opens 75Sqm Boutique at the Venetian Macao

    Italian accessories brand Furla has opened a boutique at Shoppes at The Venetian Macao in September 2026, adding more than 75 square metres of retail space to its Asia-Pacific network.

    It carries the brand’s full range of handbags, small leather goods, eyewear, textiles and charms under an updated store format.

    Modular Layout and Interior Fit-Out

    Inside, the boutique features dedicated product zones and a magnetic display wall for seasonal arrivals. The setup lets staff reconfigure floor layouts without structural work.

    Italian materials anchor the interior, mixing natural oak and painted metal with lacquered surfaces, tiles and light gold accents. A palette of ivory, latte, white, grey, burgundy and aqua green runs across the display fixtures and perimeter shelving.

    Casino Footfall and Regional Push

    Casino mall retail relies heavily on mainland tourist traffic. Leases demand steady transaction velocity from transient shoppers rather than local repeat footfall. In this corridor, premium leather goods makers face direct competition from heritage luxury houses upstairs and accessible fashion labels fighting for discretionary travel spend.

    A compact 75-square-metre footprint keeps operating costs down while the brand tests product turnover along high-density casino walkways. Success at The Venetian will depend on converting foot traffic during peak holiday windows when mainland visitor volumes surge.

    Greater Bay Footprint

    Founded in Bologna in 1927, the company expanded its retail presence earlier in the year with a refreshed store format in Hong Kong. That rollout introduced lighter fixtures and revised zoning across urban locations.

    The Macao opening extends that format across the Pearl River Delta, where retail performance tracks incoming visitor arrivals alongside cross-border ferry and bridge volume.

  • Chinasquad Expands Global Cross-Border Sales with Curated Chinese Fashion

    Chinasquad Expands Global Cross-Border Sales with Curated Chinese Fashion

    Chinasquad is scaling international distribution for domestic apparel designers, offering direct deliveries across global markets with a free shipping threshold set at $99.

    The platform has accumulated more than 7,200 verified customer reviews while targeting shoppers seeking curated streetwear, statement dresses, and modern Hanfu-inspired collections.

    To address cross-border fulfillment friction, the operator provides optional DHL Express transport with delivery times between two and four days. Returns operate on a 14-day window supported by a checkout protection add-on that covers return handling and exchanges across multiple international territories.

    Sizing Standards and Cross-Border Logistics

    Cross-border apparel exporters from China routinely face high return rates tied to sizing discrepancies. Chinasquad produces its inventory to Asian sizing specifications, advising international buyers to size up on fitted garments and evaluate flat measurements across shoulders, bust, and waist. Flat garment measurements published on the site account for manual variations between one and three centimetres.

    Discounts on the storefront reach up to 90 percent on clearance lines. The merchandising mix focuses on structured trousers, outerwear, and dresses that emphasize tailored cuts rather than disposable basics.

    The Shift Toward Niche Chinese Aesthetics

    Direct-to-consumer fashion exporters in China are shifting away from pure low-cost volume to focus on distinctive regional aesthetics, including contemporary interpretations of traditional Hanfu tailoring. While mass-market players compete primarily on bottom-tier pricing, specialised curators seek higher basket sizes by pairing distinctive cuts with express air freight.

    Customer service operations and global return intake remain centred on managing cross-border garment fits as the platform tests overseas appetite for contemporary Chinese designer labels.

  • Pomelo Operator KCG Collects 231 Kilos of Garments in Indonesian Take-Back Push

    Pomelo Operator KCG Collects 231 Kilos of Garments in Indonesian Take-Back Push

    PT Kurnia Ciptamoda Gemilang collected 231 kilograms of used clothing across eight Pomelo stores in Indonesia during the first month of its in-store take-back programme.

    The haul more than doubled the retailer’s initial 100-kilogram target despite launching without promotional marketing.

    KCG installed drop-off boxes in every Indonesian Pomelo branch to collect apparel directly from shoppers. Wearable items go to the Cinta Laura Foundation for distribution to orphanages and local communities. Unwearable, damaged pieces head to domestic textile recyclers Lestari and New Factory for industrial processing.

    Haryanto Pratantara, business and operations director at KCG, said the intake relies on repeat donors seeking practical reuse for old apparel. Turning ruined garments into usable raw material carries high processing costs that the company cannot sustain alone. KCG is seeking corporate social responsibility funding and state backing to expand the processing chain.

    High Processing Costs and Policy Gaps

    Pratantara expects garment recycling to shift from a competitive differentiator to standard retail practice within five years. Government policy will dictate how fast that transition happens.

    “The key is the government,” Pratantara said. “Regulation cuts the timeline. Without it, this cannot work.”

    Fashion operators across Southeast Asia frequently launch circularity pilots to retain younger shoppers, but few manage to scale mechanical recycling without state subsidies or formal producer responsibility rules. While donation bins clear closet space and bring foot traffic back into stores, true fibre-to-fibre recycling remains bottlenecked by local sorting and processing infrastructure across the region.

    Expanding Beyond Store Bins

    KCG has not yet measured the direct revenue impact of the programme on overall apparel sales. The operator is now tracking repeat drop-offs while waiting for state policy clarity and corporate partners to fund the next stage of textile processing.

  • LC Waikiki Starts Production at New Apparel Plant in Aleppo

    LC Waikiki Starts Production at New Apparel Plant in Aleppo

    Turkish apparel retailer LC Waikiki has started production at a new manufacturing facility in Aleppo, Syria, initially hiring 150 workers.

    The company plans to expand the plant’s workforce to 1,000 staff over the next three years.

    Scaling up in Al-Rai

    Operations at the facility in Al-Rai Industrial City began in June. The site establishes direct garment assembly capacity just south of the Turkish border.

    Other Turkish manufacturers are now preparing similar cross-border production arrangements in the industrial zone. Lower wage bases and proximity to established Turkish textile supply chains make northern Syrian border zones an emerging manufacturing corridor.

    Cross-border textile shifts

    Apparel groups based in Turkey have faced rising domestic labor and energy expenses, prompting brands to explore assembly hubs across nearby borders. The move mirrors how Asian garment manufacturers established cross-border supply networks between higher-cost domestic hubs and lower-wage neighboring markets.

    The Aleppo facility provides an operational test for cross-border logistics and labor stability in the region. The primary milestone to watch is whether LC Waikiki reaches its 1,000-worker employment target within the three-year window.

  • Giordano Net Profit Drops to HK$108 Million as Asian Margins Lag

    Giordano Net Profit Drops to HK$108 Million as Asian Margins Lag

    Giordano International reported a net profit drop to HK$108 million for the six months to June 30, down from HK$121 million a year earlier.

    Group revenue slipped 1 per cent to HK$1.914 billion as store counts dropped across Mainland China and Indonesia, leaving the apparel retailer heavily dependent on earnings from the Gulf Cooperation Council.

    The geographic split reveals an uneven business. Greater China, Southeast Asia and Australia generated HK$1.572 billion, representing 82.1 per cent of total sales, but produced only 61 per cent of segment results. In contrast, the GCC delivered HK$62 million in segment profit on just 18 per cent of revenue, even after traffic in Gulf stores fell by up to 40 per cent following regional disruption in late February.

    Pruning China and Sourcing Locally

    In Mainland China, Giordano cut its store footprint to 239 doors from 359 a year earlier, halving its directly operated outlets to 48. The downsizing helped narrow the mainland segment loss from HK$16 million to HK$9 million, with constant-currency revenue down 0.9 per cent at HK$334 million. Management cleared older stock through VIP.com and shifted higher-margin product lines to Tmall, intending to rebuild physical retail starting in southern China.

    Southeast Asia and Australia remained the largest regional earnings contributor at HK$86 million in segment results on revenue of HK$699 million. Indonesia, the anchor market, brought in HK$330 million after import restrictions slowed merchandise shipments and forced store closures from 199 locations to 176. The company countered the disruption by shifting production to Indonesian factories, which began delivering local stock in June.

    Taiwan proved the regional exception. Segment profit climbed to HK$21 million from HK$15 million on a 5.9 per cent constant-currency revenue gain, meaning Taiwan generated more profit than Hong Kong, Macau and Mainland China combined.

    Korean Drag and the Next Overhaul

    The company faced additional pressure from its 48.5 per cent-owned South Korean joint venture, where revenue slid 8.9 per cent to KRW59.7 billion and 19 stores closed. Giordano deliberately restricted wholesale shipments into the venture to clear excess stock, causing group wholesale revenue to decline 12.2 per cent and cutting royalty income.

    For years, Giordano relied on high-density physical networks in lower-tier Chinese cities and steady franchised wholesale to support its balance sheet. With those legacy channels retreating under fierce domestic e-commerce competition and supply chain friction, the group is now forced to extract higher gross margins from a much smaller physical footprint across Asia.

    Management plans to launch its Giordano 2.0 concept in the fourth quarter, rolling out revamped store layouts and core product lines in Hong Kong and Singapore before expanding to overseas digital channels in Europe and North America.

  • Lululemon Cuts Full-Year Forecast to US$10.35 Billion as Sales Slide

    Lululemon Cuts Full-Year Forecast to US$10.35 Billion as Sales Slide

    Lululemon Athletica lowered its full-year sales forecast to between US$10.35 billion and US$10.5 billion, posting its second consecutive guidance downgrade in three months.

    Comparable store sales dropped 9 per cent across the second quarter ended August 2, falling below market estimates and marking the company’s first quarterly decline on that metric since the pandemic.

    Shares tumbled 15 per cent in extended trading in New York following the announcement. The activewear maker has seen its equity lose more than 40 per cent of its value in 2026, trading at less than a quarter of its late-2023 record high.

    Slumping Americas and Rising Rivals

    Revenue in the Americas contracted 8 per cent during the quarter, while women’s apparel sales slipped 4 per cent. International revenue offered the lone bright spot, rising 4 per cent across overseas markets.

    Discounts and design missteps have eroded the brand’s pricing power across primary markets, opening space for fast-growing athleisure competitors such as Alo and Vuori. In Asia-Pacific, where premium sportswear demand has remained relatively steady, Lululemon faces a tight battle against agile regional entrants alongside these expanding Western labels.

    “While we continue to navigate some challenging dynamics, we are taking a prudent approach with our revised full-year outlook,” interim co-chief executive Meghan Frank said.

    Leadership Handover and Boardroom Truce

    Former Nike executive Heidi O’Neill assumes the chief executive role next week, concluding a four-month transition period after her appointment. She inherits depleted executive ranks following several senior departures this year.

    O’Neill must also manage relations with billionaire founder Chip Wilson. Wilson entered a cooperation pact with the board in May, agreeing to regular strategy sessions with O’Neill and an 18-month freeze on public criticism.

    Her first major operational milestone arrives with the release of third-quarter earnings in December, when investors will assess whether the product pipeline can arrest the slide in North American foot traffic.

  • Central Retail First-Half Profit Jumps 35% to $155 Million

    Central Retail First-Half Profit Jumps 35% to $155 Million

    Central Retail posted a 35 per cent increase in first-half net profit to 5.0 billion baht ($155 million), driven by grocery gains and aggressive store pruning in Thailand and Vietnam.

    Total revenue from continuing operations rose 2.4 per cent to 123.7 billion baht ($3.9 billion), with grocery accounting for 46 per cent of all sales.

    Store and online sales rose 2.2 per cent across the network, beating a 2.2 per cent expansion in total retail selling area. Gross margins widened by 110 basis points to 24.8 per cent, outpacing operational cost growth. Finance costs dropped sharply, while profit contributions from a newly acquired 40 per cent stake in JD Sports lifted the bottom line.

    Pruning hardlines and shifting to athleisure

    The conglomerate closed 11 branches of Power Buy, B2S, and Officemate over the past 12 months. It also severed 39 stores in April by exiting the NK appliance retail business in Vietnam. Hardlines revenue fell 2.9 per cent during the half, or 0.5 per cent when excluding the NK divestiture.

    Fashion sales edged up 2.1 per cent. Central Retail took its minority stake in JD Sports partly to overhaul sports merchandising at its proprietary Supersports chain, shifting shelf space toward high-turnover athleisure ranges.

    Food delivered the bulk of operating momentum. Grocery sales increased 6.1 per cent, recording same-store sales growth of 2 per cent in the first quarter and 3 per cent in the second quarter. Overall group same-store sales slipped 0.1 per cent for the six months, dragged down by two-year stacked declines of 7.5 per cent in hardlines and 5 per cent in fashion.

    Uneven regional recovery

    Across Southeast Asia, diversified retail conglomerates have spent the past two years ditching fragmented specialty formats to defend supermarket cash flow against inflation. Central Retail mirrors regional peers that expanded fast into bulky non-food retail during low-rate cycles, only to find floor space unproductive once discounters and online platforms undercut consumer electronics and stationery.

    Trading conditions remain split between its two core markets. In Thailand, high household debt and slow tourism recovery continue to curb discretionary spending, even with the central bank lifting its 2026 economic growth forecast to 1.9 per cent. Vietnam provides stronger retail momentum, backed by rising inbound tourism and state efforts to lift domestic consumer spending.

    Central Retail now manages 3,834 stores and 75 shopping centres with 779,000 square metres of net leasable area across both countries. Investors are watching third-quarter same-store sales figures to see whether hardlines and fashion can pull out of negative territory.