Tag: fast-moving consumer goods

  • Spritzer Enters Isotonic Water Market with Ion Launch in Malaysia

    Spritzer Enters Isotonic Water Market with Ion Launch in Malaysia

    Spritzer launched an electrolyte-formulated isotonic water called Spritzer ION across Malaysia on 6 October 2026, targeting functional hydration demand outside pure mineral water.

    The beverage rolls out in 500mL and 1.5L formats across two flavour options, Original and Lime, formulated with lower sugar content than conventional sports drinks.

    Flavour Formats and Packaging Specifications

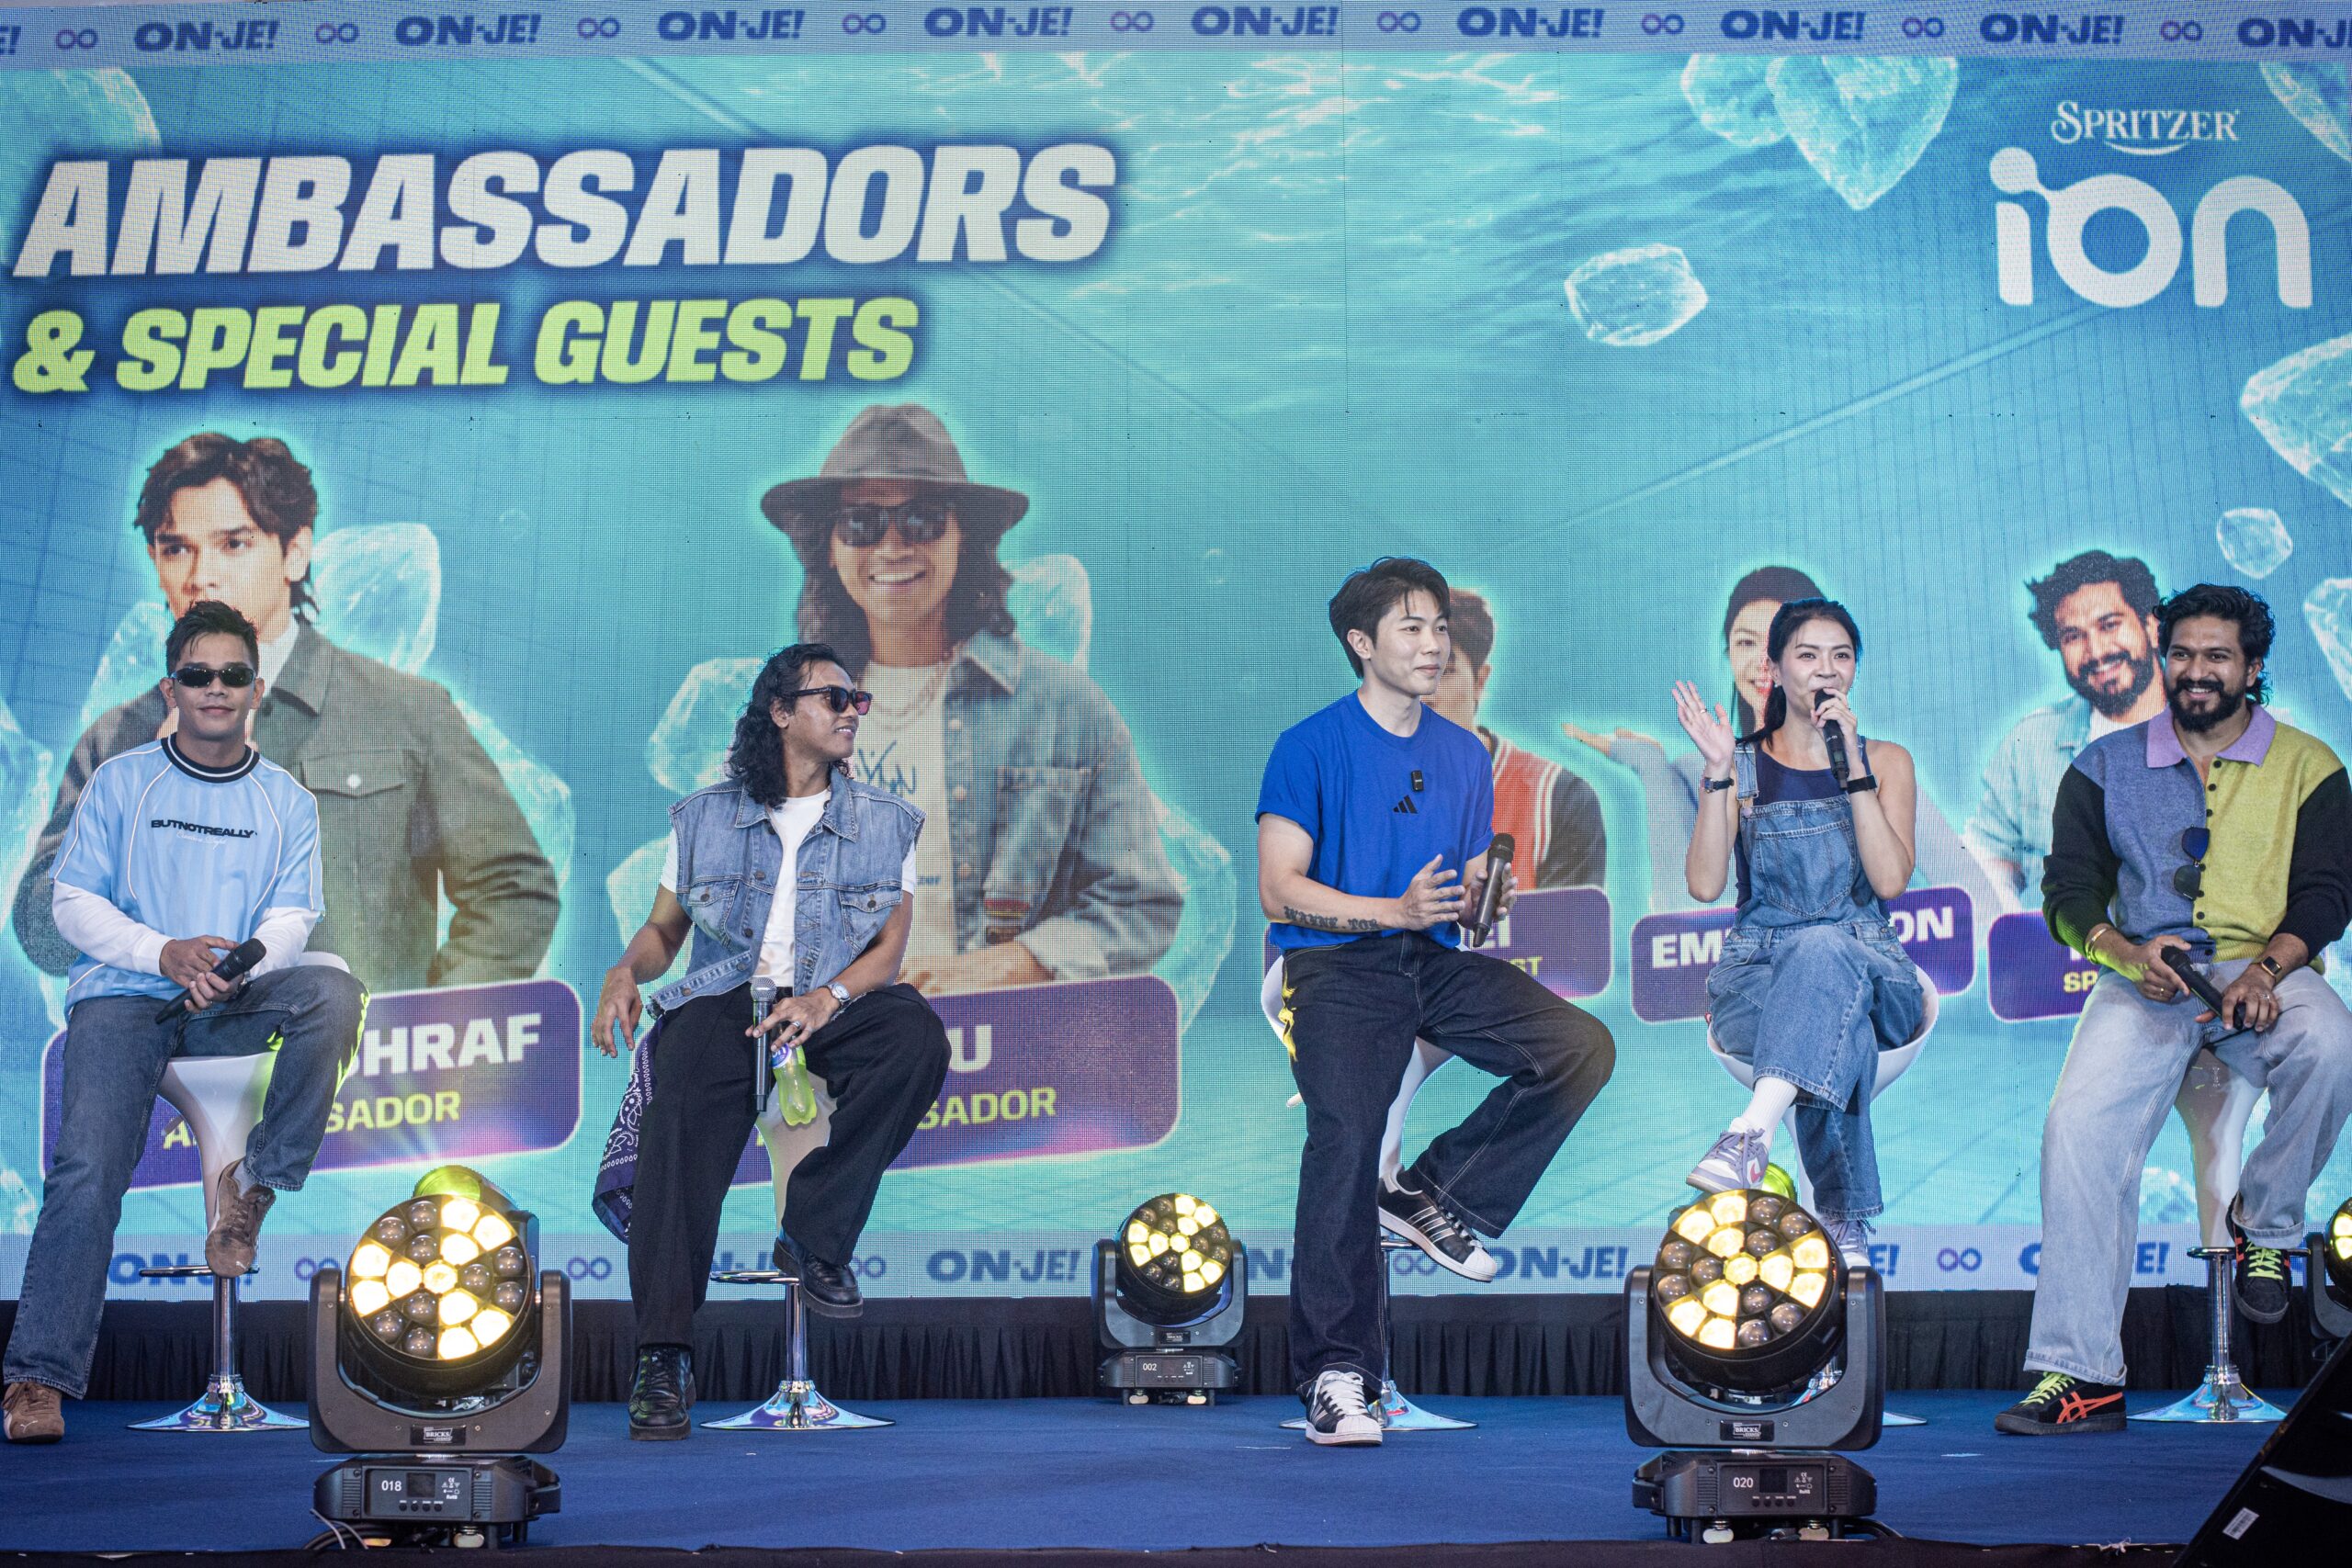
    Group Chief Executive Officer Kenny Lim and Head of Marketing Shiao Chan unveiled the product line alongside brand ambassadors Aedy Ashraf and TUJU. The product uses Spritzer mineral water as its base, blending electrolytes into an easy-grip bottle styled with blue and purple labeling featuring an infinity symbol motif.

    Distribution will target retail channels nationwide, giving convenience stores and hypermarkets an isotonic alternative marketed for everyday work routines as well as athletic training.

    Positioning Against Established Sports Drinks

    Entering the isotonic market pits Spritzer directly against entrenched regional category heavyweights that dominate convenience store refrigerator shelves across Southeast Asia. By positioning ION with less sugar and using its core mineral water brand equity, Spritzer aims to capture health-conscious consumers who avoid heavier carbonated sports drinks.

    For retailers, the line provides higher-margin shelf inventory in the functional beverage category compared to standard bulk mineral water. The risk sits in execution: isotonic drinks rely heavily on habitual purchase cycles, requiring sustained marketing spend to keep retail turnover steady against established players.

    Brand Campaigns and Portfolio Expansion

    Spritzer has steadily diversified its revenue base away from standard still water over the past two years. The company partnered with Gigi Coffee on co-branded drinks in January 2025, introduced Sparkling Sea Salt & Citron line extensions in December 2025, and ran its Flow With Joy consumer campaign in May 2026.

    The launch of ION accelerates that shift into higher-value functional lines designed to lift average selling prices per litre across retail networks.

    Roadshow Rollout and Consumer Sampling

    Direct consumer engagement begins with an underwater-themed activation at Starhill Piazza in Kuala Lumpur running from 9 to 11 October 2026. The three-day event serves as the initial test site for product sampling before Spritzer expands regional retail promotions into secondary Malaysian cities through the fourth quarter.
  • Thai Shoppers Cut Spending as Retail Confidence Declines

    Thai Shoppers Cut Spending as Retail Confidence Declines

    Retail confidence in Thailand saw a notable decline in July, with the nationwide Retail Sentiment Index (RSI) falling 4.9 points to 46.6. This dip was primarily attributed to a sharp reduction in the amount shoppers spent per visit, a trend indicating weakening household purchasing power across the country.

    While consumers maintained their shopping frequency, visits edged down by only 0.4 points, the spending-per-bill component experienced a significant 8.1-point drop, moving from 55.1 in June to 47.0 in July. This divergence suggests that while people continue to visit stores, their spending habits have become more constrained. Confidence in month-on-month same-store sales growth also decreased by 6.4 points to 46.2. All three key metrics now sit below the 50-point threshold, which typically separates expansion from contraction in sentiment.

    Household Spending Under Pressure

    The reduction in basket sizes reflects a broader trend of households limiting purchases to essential goods and cutting back on less necessary items. Consumers are increasingly opting for cheaper brands or private-label products, avoiding discretionary and lifestyle purchases. This behavior points to financial strain rather than a simple shift in preferred shopping channels. Despite government stimulus programs, such as the Thais Help Thais Plus 60/40 scheme, the underlying weakness in household income has not been fully offset. The majority of subsidised spending in July was directed towards fast-moving consumer goods, food, and beverages, leaving little personal spending power for other retail categories.

    Heavy rainfall and localized flooding in July further dampened retail activity by reducing visitor numbers at larger shopping centres. Elevated household debt and high living costs continue to restrain spending on non-essential items like fashion, electrical appliances, and home décor. These categories are crucial profit drivers for department stores, where sales remain subdued. While some recovery has been noted in department stores and lifestyle retailers, their confidence indices are still below 50, with improvements largely concentrated in Bangkok and its surrounding provinces.

    Regional Performance Varies

    Retail formats such as hypermarkets, supermarkets, and convenience stores received some benefit from the government’s stimulus program. However, even these segments experienced lower sales in provincial areas due to reduced customer spending per visit. Construction materials, home improvement, and maintenance retailers saw their confidence recover to 45-48 points after a significant dip earlier in the year, though this sector remains volatile due to its reliance on government budget disbursements and a slow property market.

    Tourism provided a limited boost to confidence in certain regions. Foreign visitors supported the southern Gulf coast and eastern provinces, while domestic travel during holiday periods aided the North and Central regions. Despite these localized improvements, retail confidence remained below the 50-point benchmark across all regions. The Northeast, in particular, faced additional pressure with a fourth consecutive month of declining tourist numbers. RetailNews Asia has observed similar pressures on discretionary spending in other Southeast Asian markets this year, as consumers grapple with inflation and economic uncertainty. The outlook for Thailand’s overall RSI remains cautious, with forecasts for the third quarter of 2026 placing it between 47 and 50, indicating continued hesitancy among retail operators.