Tag: financial services

  • Credit Saison Partners with ADB on Small Business Loans Across Asia

    Credit Saison Partners with ADB on Small Business Loans Across Asia

    Credit Saison has agreed to partner with the Asian Development Bank to expand commercial lending facilities for small and midsize enterprises across developing Asian markets. The Tokyo-based financial services provider plans to take lending models developed through its Indian subsidiary and roll them out into additional regional economies to establish new recurring revenue.

    Multilateral backing provides the Japanese consumer credit group with institutional balance-sheet support as it steps beyond its saturated domestic market. The Asian Development Bank previously participated in a syndicated loan facility announced by Credit Saison’s Indian operating arm in May, establishing the groundwork for a broader regional agreement.

    The partnership targets small business credit across emerging economies, pairing private Japanese capital with multilateral developmental resources as regional non-bank lending activity gathers pace.

    Exporting the Indian Credit Blueprint

    Credit Saison built its offshore corporate lending thesis in India, using automated underwriting systems and local balance-sheet partnerships to service smaller enterprise borrowers. Traditional retail banks often bypass these firms due to patchy documentation and high origination costs. By systematising risk assessment in India, the company created an origination structure that it now intends to replicate across neighbouring frontiers.

    Teaming up with an international development lender shifts the cost profile of cross-border enterprise funding. The Asian Development Bank brings concessional capital structures and local currency syndication capabilities, which insulate private credit providers from foreign exchange swings and sudden offshore liquidity contractions. For small commercial suppliers, merchant distributors and independent retail operators, the entry of Japanese non-bank lenders provides an alternative to restrictive domestic banking collateral rules.

    Balance Sheet Pressures Drive Outbound Expansion

    Consumer credit operators in Tokyo face structural headwinds at home, where an ageing population and stagnant real wages curb revolving credit demand. Credit Saison responded by aggressively diversifying outside Japan, chasing higher-yield commercial books in emerging consumer markets. Extending working capital to supply chain operators and storefront businesses offers margins that domestic credit cards can no longer generate.

    The central risk sits in credit cycle management across disparate legal jurisdictions. India’s digital public infrastructure, including unified digital IDs and corporate tax registries, gave non-bank financiers reliable verification pipelines that do not exist uniformly across other developing Asian economies. Transferring credit risk algorithms to markets with weaker creditor protections or higher non-performing loan ratios will test whether Indian recovery rates can be duplicated.

    Deepening Multilateral Ties

    The formal collaboration follows months of closer financial links between both institutions. In May, the Asian Development Bank took a direct role in a syndicated debt package for Credit Saison’s Indian operations, confirming its appetite for the company’s balance sheet.

    Credit Saison is currently mapping targeted jurisdictions across developing Asia for the roll-out of joint financing structures with the development bank, with capital deployment volumes and local regulatory filings in initial secondary markets serving as the operational benchmark for the expansion.
  • SGX Starts Succession Planning Ahead of CEO Loh Boon Chye Contract End in 2027

    SGX Starts Succession Planning Ahead of CEO Loh Boon Chye Contract End in 2027

    Singapore Exchange began planning for a chief executive transition on Friday (Oct 23), after CEO Loh Boon Chye informed the chairman that preparations for an eventual handover should get underway.

    The announcement followed record financial results for the financial year ended June 2026, when adjusted net profit climbed 24.6 per cent to S$759.5 million on net revenue of S$1.48 billion.

    Speaking at SGX’s annual general meeting, Loh, 62, noted that no departure date has been set, and his contract runs through mid-July 2027 while he continues serving as an executive and non-independent director.

    A Decade Leading the Bourse

    Loh took charge of SGX in July 2015 after serving on its board from 2003 to 2012. His financial career started at the Monetary Authority of Singapore in 1989 as an investment officer, following an engineering degree from the National University of Singapore.

    He spent 17 years at Deutsche Bank, rising to head corporate and investment banking for Asia-Pacific. From 2012 to 2015, he ran Asia-Pacific global markets at Bank of America Merrill Lynch as deputy president.

    Beyond the exchange floor, Loh chairs the World Federation of Exchanges and holds a board seat at sovereign wealth fund GIC. That network anchored his tenure as SGX shifted emphasis toward foreign exchange and multi-asset derivatives.

    Capital Market Headwinds in Equities

    The transition arrives while Singapore works to lift liquidity across its stock market and draw corporate listings. While derivatives and fixed income expanded, primary stock offerings faced persistent regional competition from private capital and alternative exchanges.

    Regional equity platforms have struggled with sluggish initial public offering volumes over recent years. Southeast Asian growth companies frequently deferred public debuts or explored dual listings abroad rather than depending solely on local trading desks.

    Retail and consumer issuers in particular watch the bourse closely for valuation depth. A thin domestic trading float raises the cost of capital for regional operators seeking public funds to build out logistics networks or physical store footprints.

    Regulatory Steps and Listing Frameworks

    Last year, Singapore introduced a 20 per cent tax rebate for primary listings to revive interest among regional enterprises. Officials also instituted a dual-listing mechanism with Nasdaq to keep fast-growing tech and consumer firms tethered to the local exchange.

    Net revenue climbed 13.9 per cent in the 2026 financial year, showing that fee income from foreign exchange desks and multi-asset clearing insulated the exchange against softer stock-trading volumes.

    The outgoing chief’s mandate until mid-July 2027 leaves SGX time to identify a successor, test candidates, and hand over control without disrupting trading infrastructure operations.

  • Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore has launched a whole-of-life protection plan that covers both a child and ageing parents under a single policy, as citizens aged 65 and above exceeded a fifth of Singapore’s population in 2026.

    The insurer introduced the policy amid demographic shifts projecting that more than one in four citizens will be aged 65 and above by 2035, increasing caregiving responsibilities across households.

    How the multi-generation coverage works

    Under the policy, titled PRUActive Family Care, the caregiver’s child serves as the primary life assured. That portion provides lifetime coverage against death, terminal illness, and total and permanent disability.

    Policyholders can attach critical illness riders covering 182 conditions. These riders extend protection across both juvenile illnesses and mental health conditions.

    Parents of the caregiver gain protection up to age 100 without medical underwriting. This component pays out on diagnosis of specific age-related conditions, including Alzheimer’s disease, dementia, Parkinson’s disease, and progressive supranuclear palsy.

    The shift in retail financial products

    Insurers across Southeast Asia are retooling standard life products to address changing household structures. Traditional life policies required separate contracts, multiple administrative fees, and full medical underwriting that routinely screened out elderly parents with pre-existing conditions.

    By eliminating underwriting on designated cognitive and neurological conditions for parents, Prudential shifts the commercial proposition from individual mortality protection to multi-generational risk pooling. For retail distribution networks and financial advisers, bundled policies raise client retention by binding family units to a single provider.

    Demographic pressures on consumer balance sheets

    Household economics are shifting rapidly in aging Asian financial hubs. Singapore’s official demographic forecasts project that more than one in four citizens will reach age 65 or older by 2035, accelerating the dependency ratio on working adults.

    Rising caregiving expenses place direct pressure on household discretionary spending and retirement savings. Financial institutions packaging eldercare contingencies with childhood coverage want to capture premium flows before standalone long-term care costs deplete family budgets.

    What to watch next

    Carriers across Singapore are competing for market share in aging-related protection, adjusting critical illness definitions and riders to match lengthening life expectancies. A key development to watch is whether Singapore’s citizen dependency ratio accelerates before the projected 2035 threshold of 25 percent.

  • Asahi Life to Hire 1,000 Staff in Vietnam MVI Life Acquisition

    Asahi Life to Hire 1,000 Staff in Vietnam MVI Life Acquisition

    Japan’s Asahi Mutual Life Insurance plans to build a sales force of around 1,000 workers in Vietnam following its planned acquisition of domestic carrier MVI Life.

    President Kenichiro Ishijima detailed the expansion plans in September 2026 as the Tokyo-based insurer begins aggressive investment with its improving balance sheet.

    Dual sales channels in Southeast Asia

    Plans call for selling health insurance products tailored to the local market across dual distribution channels. Securing local sales agents forms the operational core of that entry. Direct reach gives the Japanese firm access to households instead of relying purely on third-party broker networks.

    Insurance penetration in Vietnam remains low relative to regional peers. To capture consumer demand, Asahi Life is structuring the unit to handle underwriting and agency distribution under a unified management framework once the purchase formally closes.

    Capital deployment outside Japan

    Demographic decline and low domestic margins continue to squeeze Japanese life insurers, pushing mid-tier and mutual operators to seek underwriting growth in ASEAN markets. Larger peers such as Dai-ichi Life and Nippon Life entered Southeast Asia through multi-billion-dollar joint ventures years ago. Asahi Life is taking a different route, using targeted entity acquisitions to establish operating footprints with lower initial overhead.

    Execution risks center on agency retention and distribution productivity. Vietnam’s life sector has faced regulatory scrutiny over sales practices and agent turnover. Onboarding 1,000 productive sales agents will test the group’s operational controls and local compliance systems.

    Digital systems and operational background

    Behind the regional push are internal technology upgrades in Tokyo. Asahi Life recently deployed the TechTouch digital adoption platform across its internally developed systems. The rollout aims to improve operational efficiency and software accessibility for staff.

    Integrating those digital workflows with an acquired foreign subsidiary will determine how quickly the Tokyo office can standardize cross-border reporting and policy administration.

    Regulatory close and next milestones

    Closing the MVI Life acquisition remains subject to customary regulatory approvals in Vietnam. Once cleared, Asahi Life will begin onboarding the 1,000-member sales organization and filing local health insurance policies for clearance.

  • Singapore Retrenchments Hit Four-Year High of 4,620 in Second Quarter

    Singapore Retrenchments Hit Four-Year High of 4,620 in Second Quarter

    Singapore recorded 4,620 retrenchments in the second quarter of 2026, marking the highest quarterly total of corporate layoffs in the city-state since the end of 2020.

    The increase pushed the island’s retrenchment rate to 2.0 per 1,000 employees, up from 1.6 per 1,000 in the first quarter.

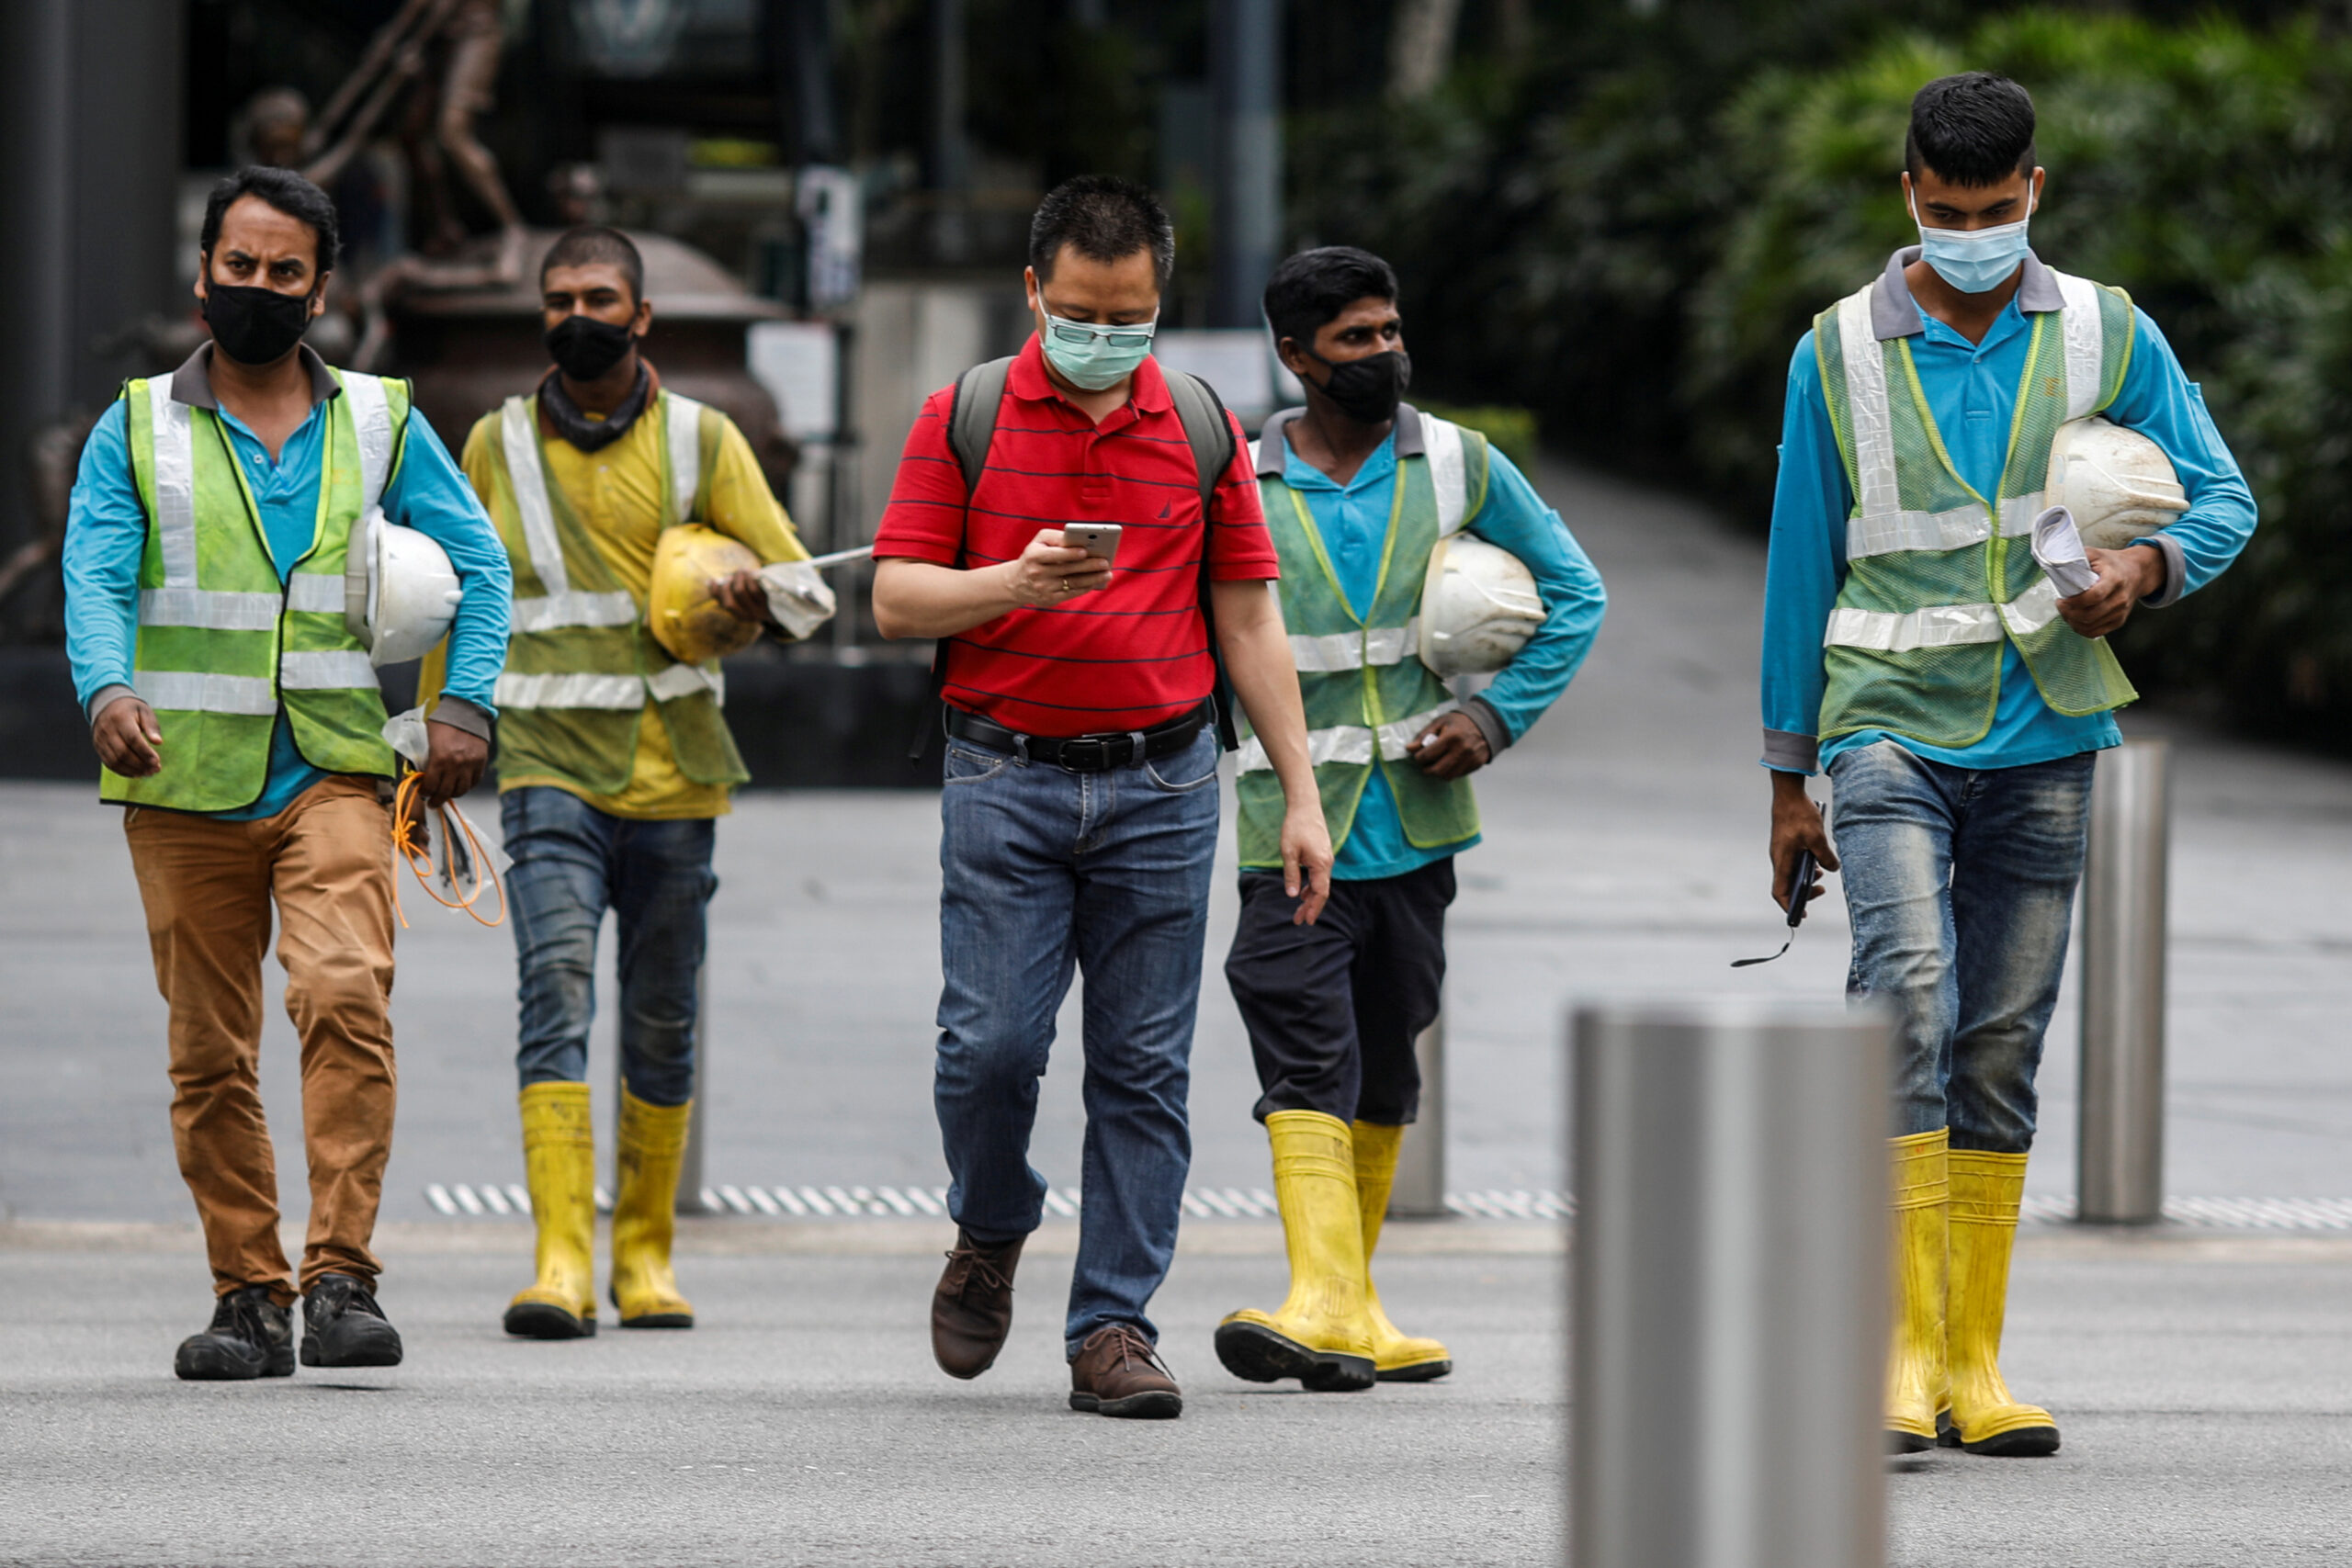
    Restructuring across outward-facing sectors drove the bulk of the job cuts. The Ministry of Manpower identified manufacturing, information and communications, and financial services as the primary areas where corporate reorganisations eliminated headcount. Total employment expanded by 11,400 during the April to June period, but foreign work permit holders in construction and factory operations drove that growth. Local resident employment expansion slowed sharply to 2,200, less than half the 5,400 positions added in the opening quarter.

    Restructuring Hits Tech and Finance

    Corporate streamlining in technology and banking removed higher-paying white-collar positions faster than domestic businesses created them. Total open positions in the economy dropped to 68,600 in June from 73,300 in March. The contraction fell heavily on professional, manager, executive and technician roles in financial institutions and software firms.

    For consumer-facing businesses in Singapore, the concentration of cuts among professionals directly affects discretionary retail spending, food services, and private transport demand. White-collar workers facing extended job hunts pull back on premium purchases and capital outlays. Landlords and retail operators relying on high-density office districts now face a more defensive prime consumer segment.

    Entry-level PMET vacancies stayed relatively flat at 31,700 openings, representing 45.3 per cent of available positions in June. The labor market still holds 1.48 open jobs for every unemployed worker. That buffer continues to prevent severe headline distress across commercial property and basic retail sales.

    Re-entry Rates Slow for Displaced Staff

    Finding replacement work took longer for staff released between April and June. The proportion of retrenched residents finding new employment within six months fell to 54.9 per cent, down from 60.7 per cent in the first quarter. The 12-month re-entry rate held steady at 69.8 per cent.

    Displaced workers taking longer to secure income puts pressure on mid-tier retail brands and food chains across suburban mall networks. Households recalibrate regular spending when severance packages expire before new salaries start. The slowdown in re-hiring also signals that regional tech and finance firms are keeping back-office and regional headcounts lean.

    Overall unemployment held at 1.9 per cent in June, with resident joblessness at 2.9 per cent and citizen unemployment at 3.0 per cent. Long-term unemployment, measuring workers without jobs for at least six months, ticked upward to 1.0 per cent from 0.9 per cent at the end of the first quarter.

    Older PMETs Face Deepening Friction

    Workers aged 50 and older absorbed the heaviest pressure during the quarter. The retrenchment incidence for resident staff in their 50s climbed to 3.6 per 1,000 employees, the highest among all age groups. Unemployment for this cohort rose to 3.1 per cent in June from 2.9 per cent in March, while long-term unemployment reached 1.2 per cent.

    For workers aged 60 and above, the jobless rate climbed from 1.8 per cent to 2.2 per cent. Manpower authorities pointed to specialized career conversion programmes as the primary tool to retrain mid-career staff directly into vacant operating positions rather than generic classroom certifications.

    Fewer job vacancies were added this quarter, and some workers are finding the transition into their next role taking slightly longer. This is a concern for some Singaporeans.

    Cautious Hiring Plans for Third Quarter

    The second-quarter spike follows four consecutive quarters of rising job cuts across the island. Layoffs climbed steadily from 3,540 in the second quarter of 2025 to 3,670 in the third quarter, 3,690 in the fourth quarter, and 3,830 in the first quarter of 2026 before accelerating to 4,620.

    Forward-looking data shows early signs of operational stability. The number of workers placed on temporary layoffs or shortened work weeks dropped to 700 in the second quarter. Employer sentiment surveys conducted in July showed 48.7 per cent of companies plan to hire over the coming three months, up from 43.9 per cent in June. Wage growth intentions softened, with 27.9 per cent of employers planning pay raises compared to 29.3 per cent a month earlier.

    Third-quarter corporate earnings and third-quarter preliminary employment numbers due in late October will confirm whether July hiring intentions translated into actual payroll additions.

  • Japan’s Positive Rates Lift Major Bank Earnings

    Japan’s Positive Rates Lift Major Bank Earnings

    Japan’s return to positive rates is supporting major banks’ ability to generate more sustainable earnings from domestic banking activities, according to Fitch Ratings.

    The positive rates remove banks’ long-standing constraint on profitability and internal capital generation, the credit rating company said in a September 2026 commentary.

    Fitch expects this benefit to outweigh higher bond valuation losses, rising deposit costs and gradually higher borrower debt-servicing burdens over the next one to two years.

    Asset Yields Outpace Funding Costs

    Lenders are reallocating liquid assets into higher-yielding domestic instruments as negative interest rate policies recede. Rising income from domestic loans and newly purchased government bonds provides immediate relief to net interest margins, counteracting the initial portfolio write-downs caused by falling bond prices.

    Deposit costs are edging higher across commercial networks, but the pace of increase remains disciplined. Major lenders retain large pools of low-cost retail deposits that adjust more slowly than wholesale market funding, preserving a profitable spread on new corporate loans.

    “We expect this benefit to outweigh higher bond valuation losses, rising deposit costs and gradually higher borrower debt-servicing burdens over the next one to two years,” Fitch said.

    Corporate Balance Sheets and Debt Burdens

    Borrower balance sheets entering this cycle look stronger than in previous tightening eras. Japanese corporations spent years reducing use, leaving balance sheets insulated against gradual rate increases and enabling them to fund working capital from domestic cash flow.

    Household finances show similar resilience despite the initial repricing of floating-rate home loans. Large household savings balances, combined with real wage increases across major metropolitan employers, prevent an immediate spike in non-performing retail loans.

    Credit costs at the largest financial groups will remain contained, though vulnerability is concentrated in specific corners of the market. Small domestic enterprises operating on tight margins face cash flow pressure, while regional lenders with heavy exposure to real estate and floating mortgages face higher delinquency risks than the national megabanks.

    Shifting Away From Negative Rates

    The transition marks the end of an era where Japanese lenders sought returns overseas to offset stagnant margins at home. For years, domestic institutions deployed capital into foreign syndicated debt and offshore commercial property to sustain profitability, absorbing currency hedging costs that frequently eroded net yields.

    Domestic lending has now reclaimed its role as the primary driver of core banking profits. Higher base rates give institutions the headroom to price credit based on borrower risk rather than competing in a race to zero, reshaping commercial lending across Tokyo, Osaka and regional manufacturing hubs.

    Attention now shifts to the credit performance of used small businesses as quarterly repayments reset, alongside plans by Japanese megabanks to roll out joint digital-currency transaction platforms by March 2027.

  • Sumitomo Mitsui Trust Expands to Vietnam Through Asset Management Joint Venture

    Sumitomo Mitsui Trust Expands to Vietnam Through Asset Management Joint Venture

    Sumitomo Mitsui Trust Group will enter Vietnam’s asset management sector by forming a joint venture with a state-owned bank to capture shifting retail investment flows.

    The Tokyo-based financial group plans to launch the venture as early as next year. The partnership targets domestic household wealth as rising personal incomes push savers beyond cash deposits, real estate, and physical gold.

    Targeting Vietnam’s Retail Capital

    Vietnamese households hold the bulk of their personal assets in traditional savings accounts, bullion, and property. Sumitomo Mitsui Trust expects growing affluence across the country to accelerate demand for mutual funds, equities, and fixed-income products.

    The joint venture will use the state bank’s branch reach and domestic client network to distribute investment vehicles. Japanese asset managers have increasingly looked abroad to deploy capital expertise as Southeast Asian economies expand their domestic financial markets.

    Japanese Lenders Push Into Southeast Asia

    Japanese financial groups continue to seek fee-generating asset management businesses across ASEAN to offset low domestic loan margins. Vietnam remains a focal point for institutional capital because of sustained factory investment and urban wage growth.

    Regulatory approval for the joint venture and the final equity structure between the two banking institutions will dictate the official rollout date next year.

  • Indonesia’s Payfazz and Singapore’s Xfers Join Forces

    Indonesia’s Payfazz and Singapore’s Xfers Join Forces

    Both companies will be part of a newly formed financial entity that aims to provide inclusion through financial services across Southeast Asia.

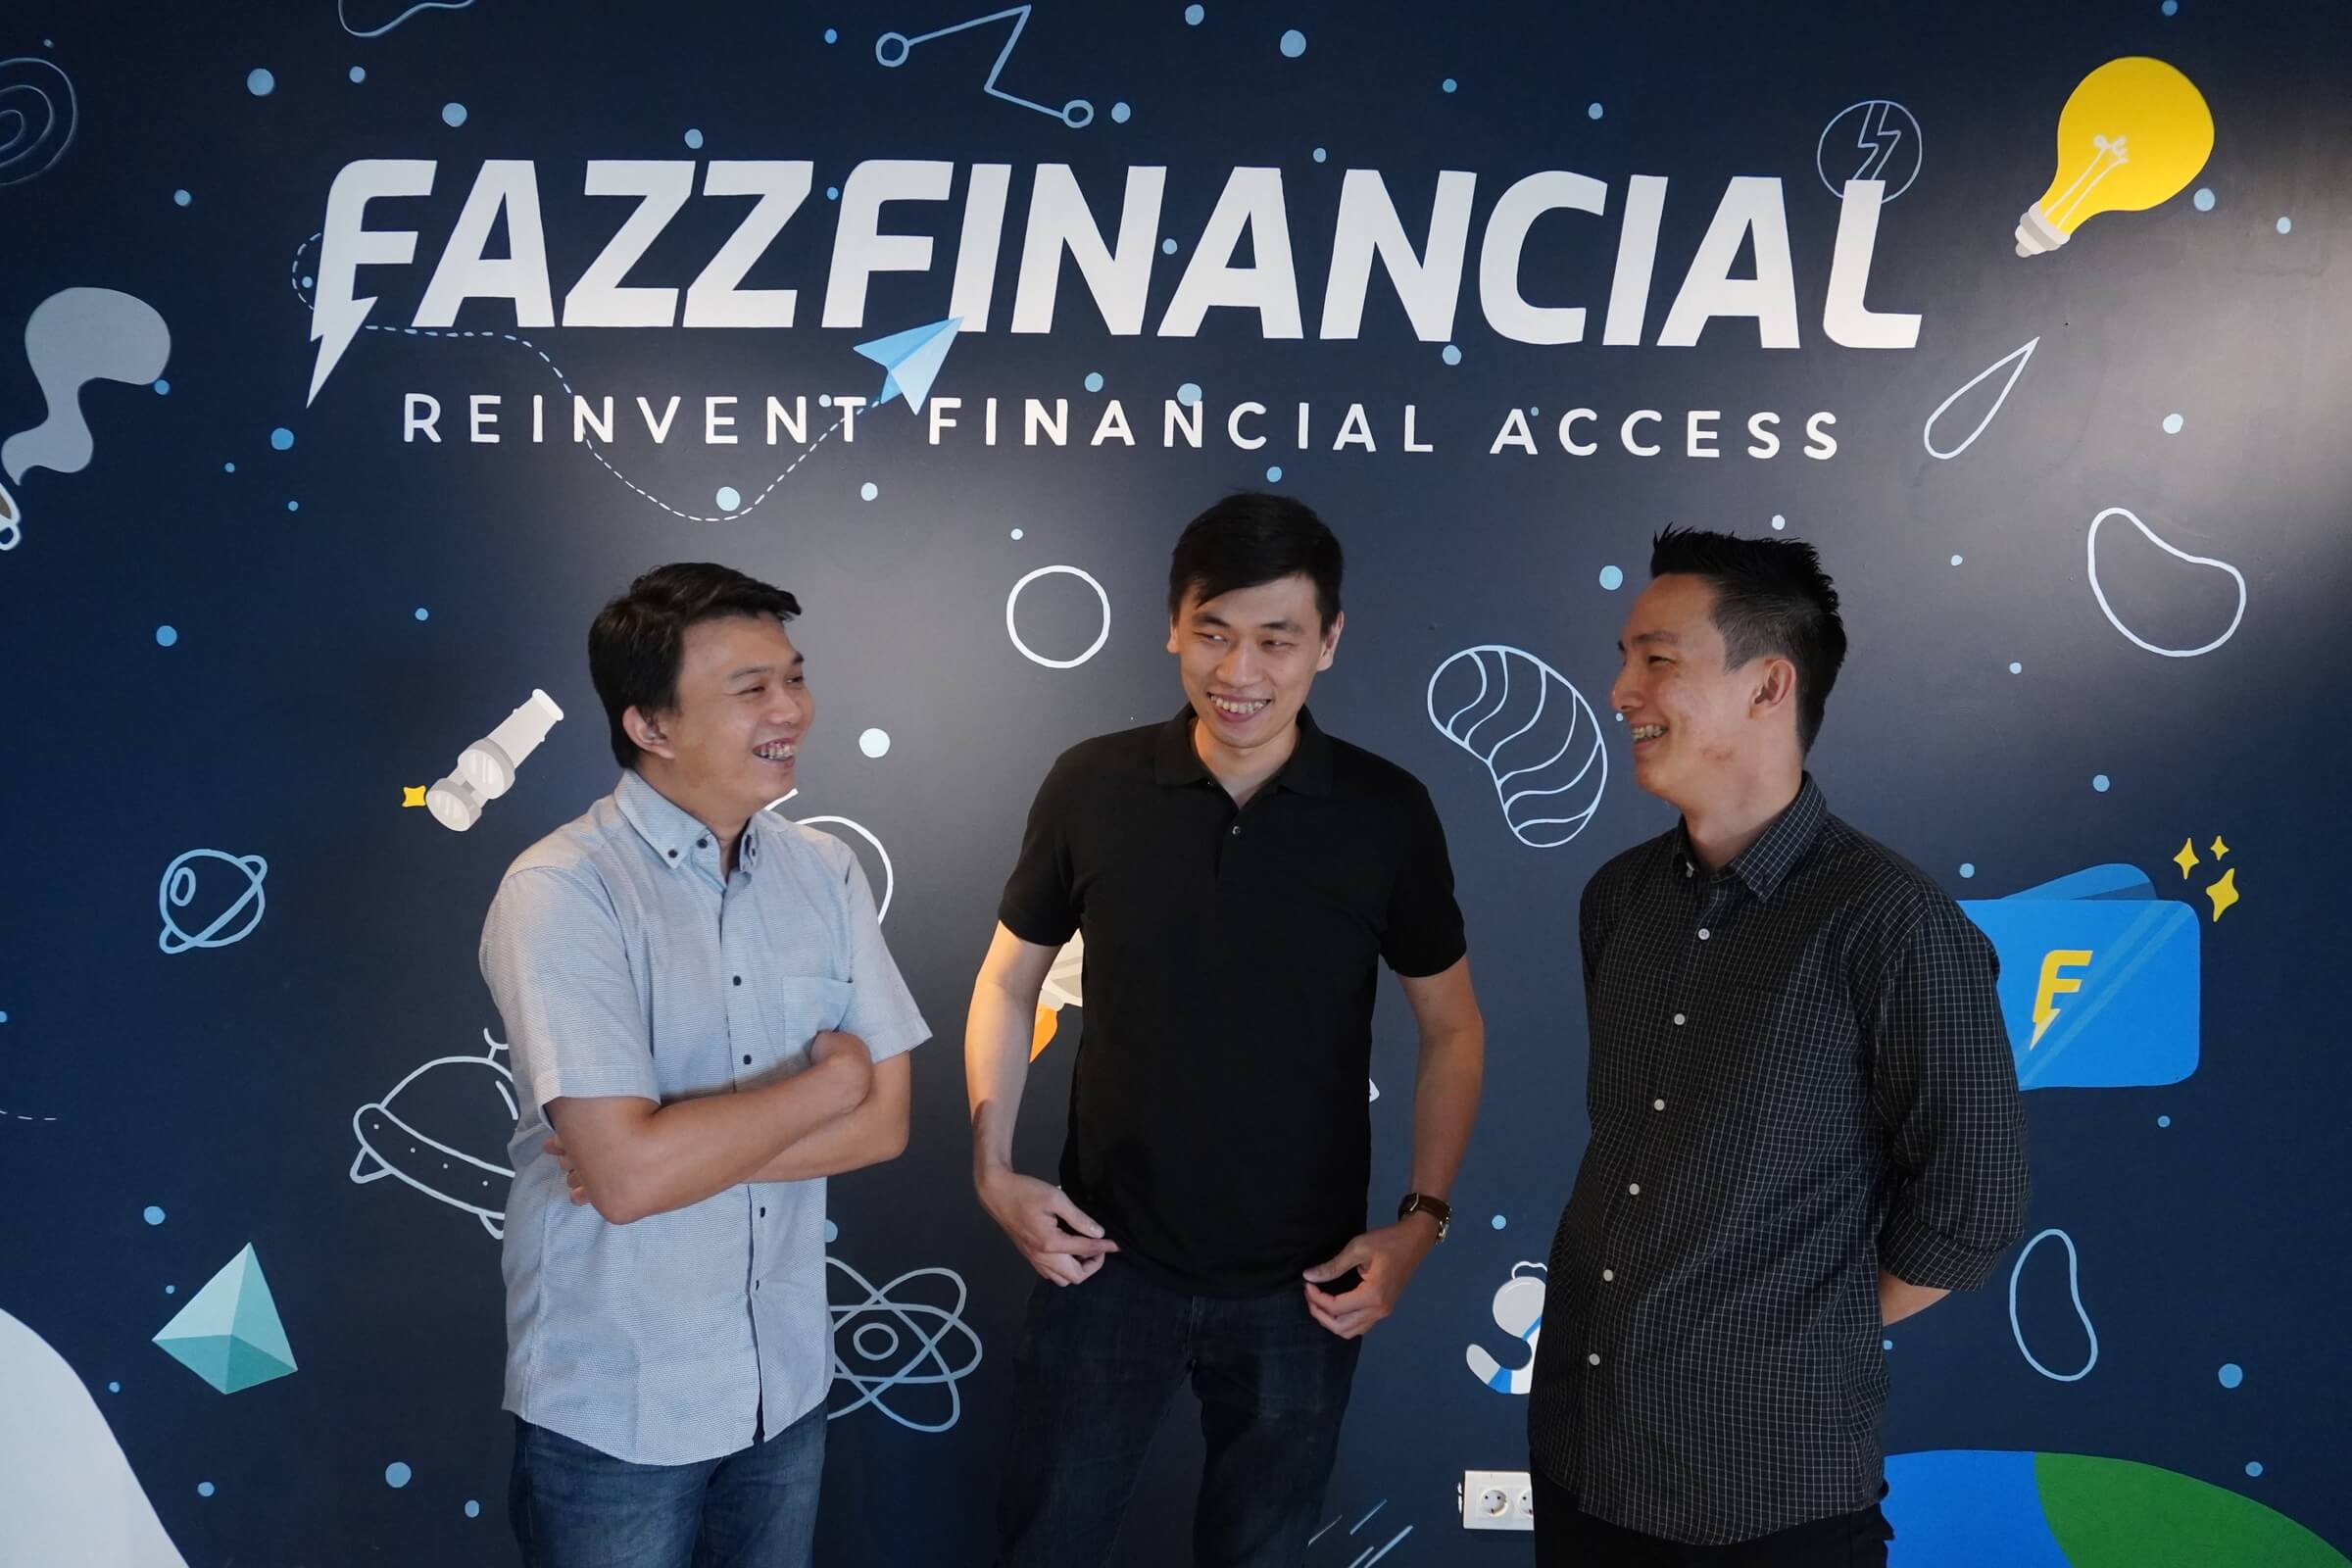
    Singapore’s Xfers has received a strategic investment of $30 million from Payfazz, which operates the largest agent-driven banking network in Indonesia, to form Fazz Financial Group (FFG), according to a statement on Thursday.

    With this investment, Xfers will serve as the designated business-to-business arm of FFG, focused on connecting external merchants to the payment infrastructure and user network amassed by FFG as a group.

    FFG will be led by CEO Hendra Kwik, Payfazz co-founder and CEO, and deputy CEO Tianwei Liu, co-founder and CEO of Xfers. The two will continue as CEOs of their respective companies. The group also appointed Robert Polana, former-CFO of Tiket.com as chief financial officer.

    With more resources on hand, we are also looking forward to helping more brands enter Southeast Asia. Especially for businesses looking to access the underserved consumer segment in Indonesia, Liu said.

    Payfazz and Xfers are both graduates of the Y Combinator accelerator programme.

    Payfazz recently announced a $53 million Series B fundraise, led by B Capital and Insignia Ventures Partners, with participation from Tiger Global, Y Combinator, ACE & Company and BRI Ventures.

    Founded in 2015, Xfers allows individuals to make and receive payments online and helps merchants set up their e-wallet services.