Tag: food and beverage

  • Australian Malls Post AU$118.8 Billion in Turnover as Dining and CBDs Lead Recovery

    Australian Malls Post AU$118.8 Billion in Turnover as Dining and CBDs Lead Recovery

    Australian shopping centres generated AU$118.8 billion in turnover across 516 properties. Food retail, dining and central business district locations drove the post-disruption growth.

    Trading across 14.6 million square metres of gross leasable area and 46,743 tenants stabilized between 2025 and 2026, according to the latest Urbis Shopping Centre Benchmarks. Spending patterns shifted across categories and geographies.

    Dining and Jewellery Drive Tenant Gains

    Food catering delivered the strongest momentum across all centre categories, rising 7.5 per cent year-on-year. Food retail sales gained 6.9 per cent over the same period.

    Discretionary categories diverged. Jewellery sales jumped 11.6 per cent. Entertainment venues rose 8.8 per cent, and retail services advanced 6.2 per cent. Non-food mini-majors expanded sales by 7 per cent. That segment benefited from apparel brands like Uniqlo taking over floor space previously held by traditional department store anchors.

    Central Precincts Outpace Outer Suburbs

    Downtown centres recorded the strongest geographic performance, lifting retail sales by 7.1 per cent. Super-regional malls followed at 5.0 per cent.

    Outer metropolitan centres trailed the national recovery, posting sales growth of 3.9 per cent despite recording the fastest residential population expansion. High mortgage rates and debt servicing costs curtailed spending in suburban family corridors.

    Shifting Floorplates Across Asia-Pacific

    Landlords across Asia-Pacific are cutting department store allocations. They favour high-turnover fast fashion and experiential dining instead. Australian figures confirm that food and beverage tenancies now anchor footfall better than general merchandise.

    Risks remain concentrated in outer suburban assets. If mortgage stress persists, neighbourhood and suburban centres heavily reliant on mass apparel and homewares will face occupancy pressure unless they rebalance toward essential services and food concepts.

    Stabilisation After Years of Pressure

    The 2026 benchmark results follow multi-year trading disruptions marked by rapid interest rate hikes and inflation across the Australian consumer economy. Comparable mall performance over the 2025 to 2026 window points to normalising floor productivity across major retail hubs.

    The shift towards experiences and in-centre consumption also shows the growing social role of shopping precincts and is helping centres remain resilient as e-commerce continues to expand

    Operators now enter the next leasing review cycle with vacancy rates tightest in prime CBD strips and regional assets. Upcoming leasing negotiations will test tenant margins against rising operational costs.

  • Seoul District Expands Corporate Chain Ban Across 232 Seongsu Land Parcels

    Seoul District Expands Corporate Chain Ban Across 232 Seongsu Land Parcels

    Seoul’s Seongdong District will bar large corporate food and beverage franchises across 232 commercial land parcels in Seongsu-dong starting this December. The decision widens municipal zoning controls to protect independent operators.

    Targeted areas include key commercial arteries along Bangsongdae Street and sections of Yeomujang Street. Previous restrictions applied only to Seoul Forest Road.

    Under the revised rules, standard restaurants, cafes and bakeries run by corporate chains cannot open new outlets within designated zones. They must fall below statutory size thresholds or secure approval from a local resident committee. District officials also designated 82 of those parcels for strict architectural preservation. Developers and tenants there must maintain red-brick facades reflecting the area’s history as a shoemaking and auto-repair hub.

    Targeting High Rents and Franchise Homogeneity

    Municipal planners designed the intervention after unchecked commercial rents hollowed out other fashionable Seoul enclaves over the past decade. Garosu-gil in Sinsa-dong and Samcheong-dong near Gyeongbok Palace both lost footfall when corporate flagships displaced independent artisans. Lease rates surged, leaving behind high commercial vacancies.

    Officials intervened early in Seongsu’s core corridors to keep commercial rents manageable for creative tenants. The decision closes off lucrative foot-traffic streets to multi-unit food operators and international retail groups. These companies must now push expansion toward secondary retail nodes or adopt smaller store formats.

    Regulating Pop-Up Retail and Temporary Leases

    The revised Sustainable Community Plan is the district’s first comprehensive policy overhaul in nearly ten years. Beyond standard retail leasing, the framework tackles short-term pop-up shops. Rapidly proliferating pop-ups have driven up temporary rents and created friction with permanent neighborhood businesses.

    District administrators plan to set up public-run pop-up spaces, publish standardized operating rules for temporary venues and inspect commercial corridors weekly. Property management will shift toward a private-led governance structure called Seongsu Town Management. That framework gives local shop owners and residents direct oversight of commercial activity.

    “Seongsu-dong’s core competitiveness lies in the unique personality and diversity built together by its local community,” said Seongdong District chief Ryoo Bo-hwa. “Through these policies, we will ensure that Seongsu-dong retains its distinct charm while allowing the local community and local businesses to grow together sustainably.”

    The Precedent Set for Commercial Real Estate

    Landlords along Yeomujang Street face tighter leasing rules that limit tenant pools to independent concepts and approved small operators. These restrictions prevent sudden rent spikes from corporate bidding wars. However, they also cap immediate yields for property owners who previously relied on corporate F&B chains for long-term leases.

    The policy tests whether municipal zoning can protect artisanal shopping streets from displacement without choking off private capital. Retailers and investors now turn their attention to resident review committees, which will begin processing initial exemption applications when the rules take effect in December.

  • Kyochon Chicken Re-Enters Japan with Arai Shoji Partnership

    Kyochon Chicken Re-Enters Japan with Arai Shoji Partnership

    South Korean fast-food chain Kyochon Chicken signed a franchise agreement with Japanese distributor Arai Shoji to re-enter the Japanese dining market. The plan targets a Tokyo opening in the first half of 2027.

    The deal establishes a multi-unit franchise model that grants regional operating rights across Tokyo. It sets up a pipeline for phased expansion into surrounding cities.

    Multi-unit structure replaces single-store bet

    Kyochon F&B signed the memorandum of understanding with Kanagawa-based Arai Shoji on September 29. Under the arrangement, the Japanese trading house will handle regional store operations, site selection, staff training and local marketing. Kyochon oversees sauce formulation and kitchen preparation standards.

    Arai Shoji brings existing supply chain infrastructure to the rollout. Founded in 1920 as an auction and distribution business, the company acquired Korean food importer Ongane Holdings in 2020. It entered direct food service in 2024 by opening a specialty waffle concept. That network gives Kyochon direct access to established wholesale channels for Korean ingredients rather than building a logistics pipeline from scratch.

    We have laid the groundwork for market entry through collaboration with a partner that has strong local distribution networks and a deep understanding of Korean food products.

    Correcting the 2015 Roppongi missteps

    This venture represents Kyochon’s second attempt to establish a permanent presence in Japan. The chain first entered Tokyo in December 2015 with a flagship store in Roppongi alongside local partner Food Planet. That outlet closed in September 2016 after nine months of trading.

    Misaligned pricing and high real estate costs doomed the initial run. The Roppongi outlet priced an 18-piece wing platter at ¥1,800, roughly $11 at the time. That was nearly twice the retail price charged across its domestic South Korean network. Side dishes such as pickled radish, provided complimentary in Korea, were billed at ¥280. Food Planet subsequently ran into financial difficulties and was delisted from the Tokyo market in 2017.

    Domestic saturation forces regional expansion

    South Korean fried chicken chains face severe margin compression and store saturation at home. Domestic franchise territories are densely packed. Operators have limited headroom to add outlets without cannibalising existing franchisees. Moving into neighbouring Asian markets has become an operational necessity for top-tier Korean fast-food operators looking to sustain system-wide sales growth.

    Japan presents substantial structural hurdles despite growing consumer familiarity with Korean dining concepts. Foreign operators face slim margins. Tokyo brings high prime commercial rents, chronic kitchen staffing shortages across metropolitan centres and entrenched competition from domestic karaage chains. Kyochon’s success rests on whether Arai Shoji can price the menu competitively against local convenience chains and specialty chicken shops while absorbing central Tokyo overheads.

    Next steps for the Tokyo pipeline

    Site selection for the initial Tokyo restaurant is currently being finalised ahead of the planned launch in early 2027. Kyochon and Arai Shoji are reviewing locations. Once the flagship opens, the partners will evaluate operational data and store-level margins before committing capital to secondary locations in adjacent prefectures.

  • Singapore Bakery Big Mouth Bakehouse Shuts Down Nine Months After Rebranding

    Singapore Bakery Big Mouth Bakehouse Shuts Down Nine Months After Rebranding

    Big Mouth Bakehouse has closed permanently nine months after rebranding. The shutdown ends a 13-year run that began under the Fluff Bakery brand.

    At its peak in 2015, the business sold more than 2,000 cupcakes a day. Rising costs and slowing sales later forced a retreat.

    Debt overhang cuts short the January comeback

    Founders Nursyazanna Syaira Mohammad Suhimi and Ashraf Alami launched Fluff Bakery in 2012 to fund their wedding. Strong social media demand led to a physical store opening in 2013. High daily sales of halal cupcakes quickly turned the shop into a staple for local dessert buyers.

    An expansion during the Covid-19 pandemic stretched resources. Heavy overheads and falling footfall forced the founders to shut Fluff Bakery in September last year, carrying unpaid obligations into their next venture.

    Product shift fails to offset operating costs

    The couple attempted a turnaround in January by reopening under the Big Mouth Bakehouse name. Their revamped menu moved away from standard cupcakes toward higher-ticket baked goods, including cakes, bomboloni and shio pan.

    Changing the menu did not generate enough cash flow to cover daily operating expenses and service old debt. By February, the founders were still struggling to clear liabilities accumulated during Fluff Bakery’s earlier expansion.

    Independent bakers face margin squeeze

    Independent food and beverage operators across Singapore face severe margin pressure from climbing ingredient prices, utility tariffs and commercial rents. When momentum cools, single-outlet shops rarely have the capital to absorb prolonged downturns.

    Rebranding without restructuring underlying debt rarely saves small bakeries. Drawing foot traffic in Singapore’s dining corridors demands heavy promotional spending, which punishes boutique shops that lack bulk purchasing power.

    The final exit after thirteen years

    On Instagram, the owners confirmed the closure and said conditions could no longer be managed.

    “Sometimes, despite your best efforts, things happen that are simply beyond your control,” the business said.

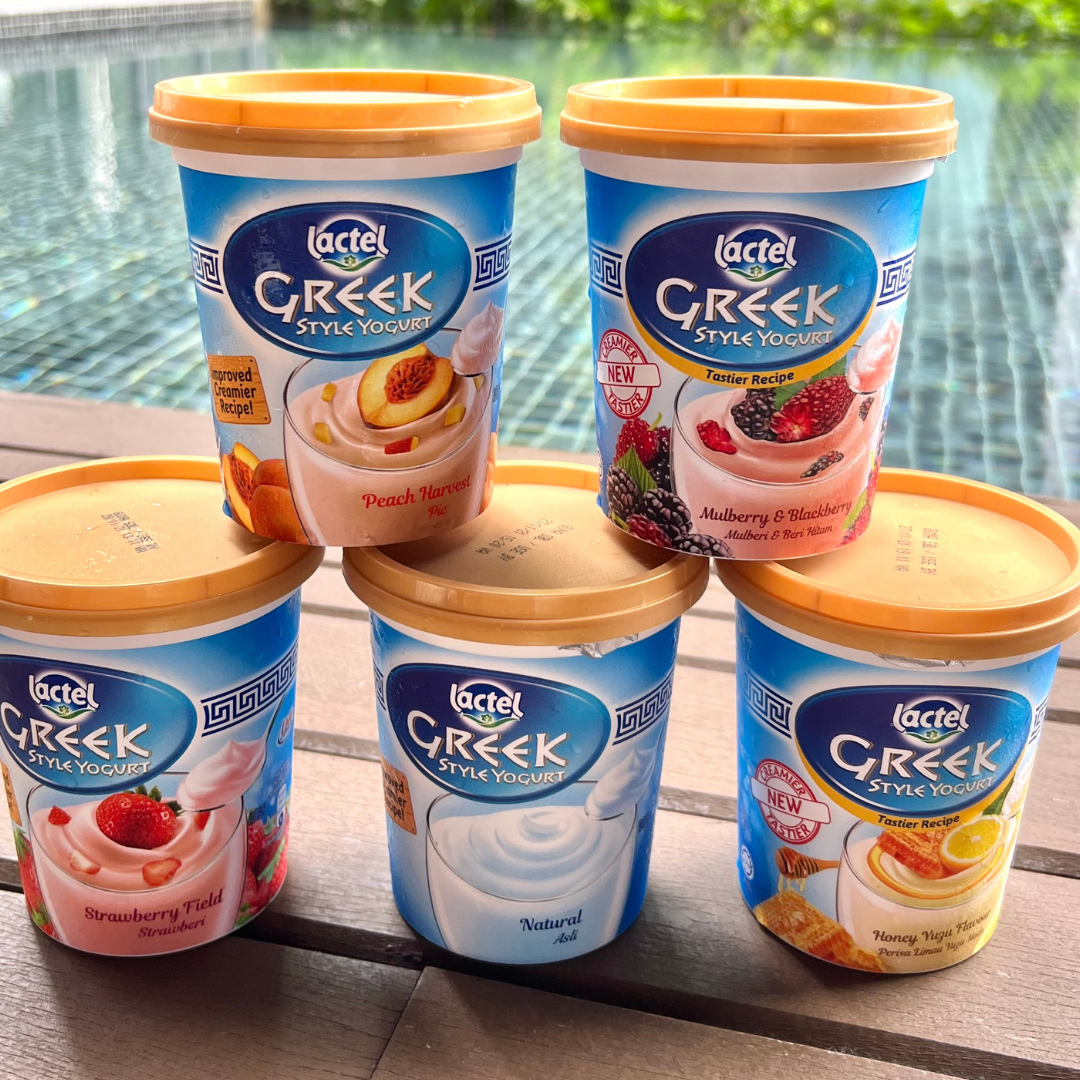
  • Lactel Malaysia Launches Low Fat Smooth Yogurt in Pouch Format

    Lactel Malaysia Launches Low Fat Smooth Yogurt in Pouch Format

    Lactel Malaysia launched its Low Fat Smooth Yogurt in a portable pouch format this week.

    The easy-to-enjoy yogurt is designed for everyday routines, whether heading to work, squeezing in 1 gym session, or snacking on the go.

    Format Shifts in Chilled Dairy

    Each pouch contains live cultures in a low-fat, smooth and silky formulation. Squeeze packaging eliminates utensils. That shifts chilled yogurt into a single-handed snacking format.

    Dairy brands across Southeast Asia continue shifting traditional tub products into flexible pouches to secure convenience store chiller space. Front-of-store cold cases reward grab-and-go packaging. These items compete directly with ready-to-drink flavored milk, RTD coffee, and ambient snacks.

    Convenience Retail Dynamics

    Squeeze pouches give retailers higher refrigerated stock density than rigid plastic tubs. Urban convenience chains in Malaysia gain stock that stacks easily. Units move fast among transit shoppers during morning and evening rush hours.

    Cold-chain distribution remains a hurdle for live-culture fresh pouches. Logistics networks must keep temperatures steady from factory depot to checkout chiller. Any temperature shift can spoil texture and cut shelf life.

    Targeting Cross-Generational Snacking

    Lactel previously restricted its pouch lineup to children’s lunchboxes and infant nutrition. Expanding to adult shoppers targets consumers seeking functional benefits like live probiotics without dessert-level fat content.

    Rival Malaysian dairy producers have pursued similar packaging across drinking yogurts and cultured milk drinks. Introducing a thicker, low-fat spoonless yogurt tests whether adults will embrace squeezable pouches for breakfast and workout fuel.

    Retail Distribution Rollout

    Nationwide distribution covers hypermarkets, supermarkets, and convenience stores. Retailers are merchandising the pouches in chilled dairy bays next to Lactel tubs and bottled drinks.

    Store audits over the coming quarter will track whether pouch sales cannibalize single-serve pots or attract incremental buyers to the chilled dairy aisle.

  • The Capital Grille Opens First Asia Venue on 50Th Floor of Bitexco Tower

    The Capital Grille Opens First Asia Venue on 50Th Floor of Bitexco Tower

    The Capital Grille opened its first restaurant in Asia last month on the 50th floor of Bitexco Financial Tower in Ho Chi Minh City. Diners reach the venue via a dedicated private lift overlooking the skyline.

    Taipei-based Ko Hospitality Group operates the steakhouse under a franchise agreement with parent company Darden Restaurants. The opening gives the Taiwanese family business its first restaurant in Vietnam.

    Steakhouse Expansion into Southeast Asia

    Darden chose Vietnam over traditional regional gateway hubs like Singapore or Tokyo for the brand’s regional debut. Guests walk straight into a dining room overlooking the city below. The kitchen serves American steakhouse staples tailored to local executives and expatriate diners.

    Ko Hospitality Group manages daily floor service, kitchen staffing, and brand standards under the licensing agreement. Securing a space in District 1 puts the operator directly in front of corporate accounts, high-net-worth diners, and private event bookings in the country’s commercial center.

    Operator Strategy and Regional Footprint

    Running an upscale steakhouse in Ho Chi Minh City challenges established independent venues and hotel dining rooms. Global brand recognition gives Darden an immediate footprint in a market where demand for imported beef and luxury dining remains steady.

    Cold-chain reliability and imported meat logistics will test the operation. Serving dry-aged beef and wine at standard requires dependable supply partnerships along international shipping routes. Import clearance delays and tariff structures can quickly squeeze kitchen margins.

    High-Rise Commercial Placement

    Securing the 50th floor of Bitexco Financial Tower anchors the property as a destination venue rather than standard mall retail. High-floor commercial tenancies command steep rents. In exchange, they offer built-in differentiation through exclusivity and panoramic views.

    Expanding into Vietnam takes Ko Hospitality Group outside its home market of Taiwan for the first time. Managing cross-border supply chains and local staffing will show whether the operator can scale Western restaurant concepts across Southeast Asian commercial centers.

    The Pipeline for Regional Dining

    Performance in Ho Chi Minh City will serve as a live benchmark for Darden as it evaluates broader franchise expansion across Asia. Fine-dining concepts carry higher overheads than casual formats. Customer retention and average check sizes will be critical in the opening quarters.

    Watch the operator’s corporate bookings and private dining receipts over the coming months to see whether Ko Hospitality Group pushes the brand into Hanoi or neighboring regional markets.

  • Chagee Adds Live Calorie Calculator to Mobile App in Thailand

    Chagee Adds Live Calorie Calculator to Mobile App in Thailand

    CHAGEE launched an in-app calorie calculator across Thailand on 5 October 2026. The tool gives beverage buyers real-time nutritional breakdowns for custom recipes starting from 4 calories per cup.

    It calculates instant shifts in calories, sugar, fat, protein, carbohydrates and caffeine. Values adjust whenever a customer changes cup sizes, switches between hot and iced preparations, or adjusts sugar levels.

    Real-time nutritional tracking in the ordering flow

    Customers access the tool directly inside the CHAGEE App by tapping the Calorie Calculator icon, picking a beverage category, and opening individual product specifications. The interface updates the total nutritional payload as options change before checkout. This removes guesswork from sweetened or dairy-based beverages.

    The release accompanies the chain’s “Sip Better, Feel Better” marketing push in the Thai market. Lowest-calorie options highlighted on the platform include Da Hong Pao, Osmanthus Green and Peach Oolong brewed teas starting at 4 calories. Milk tea options, including BO-YA Jasmine Green, Osmanthus Oolong and Da Hong Pao, start at 119 calories.

    “At CHAGEE, wellbeing is at the heart. That is why we are committed to providing transparent nutritional information. The ‘Calorie Calculator’ is more than just a tool that displays what is in your cup. It gives people the freedom to customize and choose beverages that best suit their individual needs and preferences, making every sip enjoyable while promoting their wellbeing every day.”

    Store promotions tied to athletic activity

    Alongside the digital rollout, CHAGEE Thailand introduced a physical activity promotion running from 5 to 11 October 2026. Customers receive tiered purchase incentives by showing recorded running or walking activity from smartwatches or tracking apps at store counters.

    A verified 5-kilometre log qualifies for a free drink size upgrade. A 10-kilometre distance yields a THB 30 discount, and a 15-kilometre log unlocks a buy-one-get-one voucher. The promotion applies across the network except at CHAGEE Mahanakhon 74 and Don Mueang Airport branches, with redemptions capped at three vouchers per person through the app.

    Pressure shifts across Southeast Asian tea retail

    Tea chains across Southeast Asia face stricter scrutiny over sugar content and caloric density. Regional regulators are examining beverage labelling standards while consumer habits change. Digital ingredient transparency allows premium tea operators to defend ticket sizes. It also counters perceptions that commercial milk tea is entirely indulgent.

    For mall landlords and competing beverage franchises, embedding health metrics directly into proprietary ordering apps shifts footfall toward operators with robust digital ecosystems. Brands lacking unified digital ordering and dynamic recipe databases face higher barriers in retaining health-oriented consumers.

    Expansion beyond regional milk tea benchmarks

    This Thai app update follows regional product variations across Southeast Asia, including brand collaborations and seasonal market entries in Malaysia and Indonesia. Building functional digital tools into the ordering loop deepens customer lock-in within the loyalty program.

    Under the broader promotional schedule running through 15 October 2026, CHAGEE is distributing double loyalty points on Mondays. The company is also offering 30 per cent discounts on second drinks within curated low-calorie bundles, and allowing CHA Members to redeem accumulated points for fitness and Pilates sessions.

  • Yeo’s Launches Malaysia’s First Canned Teriyaki Tuna

    Yeo’s Launches Malaysia’s First Canned Teriyaki Tuna

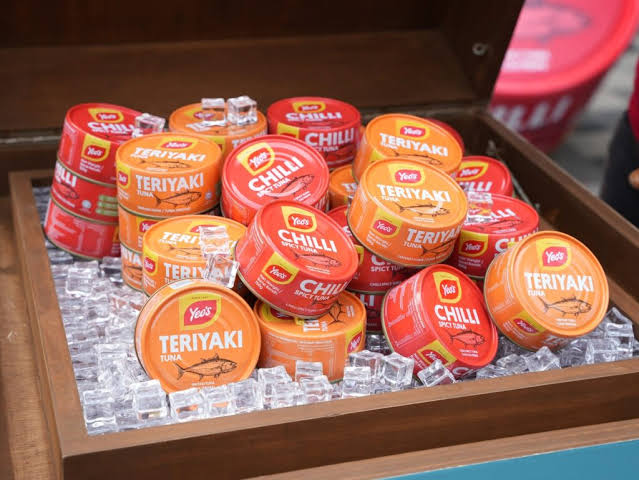
    Yeo’s launched Malaysia’s first canned teriyaki tuna product on October 3, 2026, targeting quick-meal grocery shoppers across modern retail aisles.

    The packaged goods manufacturer debuted the line during a promotional activation titled Yeo’s Itadakimasu, staged in the Bukit Bintang retail district of Kuala Lumpur. The launch introduces Japanese-inspired savoury seasoning to ambient seafood shelves historically dominated by chilli, mayonnaise, and brine preparations.

    Expanding canned seafood lines

    Ambient canned proteins serve as high-turnover staples for grocery chains, convenience outlets, and hypermarkets throughout Peninsular and East Malaysia. By packaging cooked tuna in a teriyaki glaze, the brand seeks to capture urban consumers looking for ready-to-eat meal toppings without additional home preparation. The product format matches single-serving pantry demand among desk workers and young households.

    Yeo’s built the public debut around experiential tasting booths to accelerate initial trial rates before stock fills nationwide distribution channels. On-ground samplings in central shopping precincts allow food producers to gauge shopper response directly before committing additional shelf space allocations across hypermarket chains.

    Shifting shelf space in modern trade

    Supermarket operators allocate substantial linear footage to canned fish because of long shelf lives and predictable gross margins. Adding sweet and savoury teriyaki profiles allows retailers to attract younger buyers who routinely consume Japanese cuisine at fast-casual restaurants. Supermarket buyers frequently use such regional flavour extensions to defend centre-store packaged food sales against rising chilled convenience food options.

    For competing shelf brands such as Ayam Brand and TC Boy, the launch intensifies competition for eye-level merchandising in canned fish aisles. Premium flavour variants typically command higher price points per gram than basic tuna flakes in oil, improving basket values for grocery operators when shoppers trade up.

    Flavour diversification across Southeast Asia

    Regional food manufacturers across Southeast Asia are increasingly adapting East Asian sauce profiles to local ambient categories. Soy sauce, teriyaki, and spicy Korean paste formulations now routinely replace or complement traditional spice blends across canned meats, noodles, and ready sauces. Consumers familiar with imported snack formats expect similar recipe variety in basic cooking ingredients.

    Supply chains for canned tuna rely heavily on regional processing hubs in Thailand, Indonesia, and Malaysia. Introducing pre-seasoned teriyaki lines requires minimal equipment overhaul at canning facilities while generating distinct stock-keeping units that command differentiated retail margins.

    Retail distribution targets for grocery aisles

    The Bukit Bintang public activation represents the initial push in a wider national trade rollout. Merchandising teams are now coordinating delivery schedules to secure prime placement in convenience stores, hypermarkets, and independent grocers across major urban centres in Malaysia.

    Inventory checks across mainstream supermarket chains will establish how quickly the teriyaki line secures permanent shelf allocation alongside legacy canned items. Reorder velocity from retail buyers across the fourth quarter will dictate whether the company expands the Japanese recipe concept across additional canned protein categories.

  • Hello Jello Secures $2 Million Coles Deal for Nationwide Launch

    Hello Jello Secures $2 Million Coles Deal for Nationwide Launch

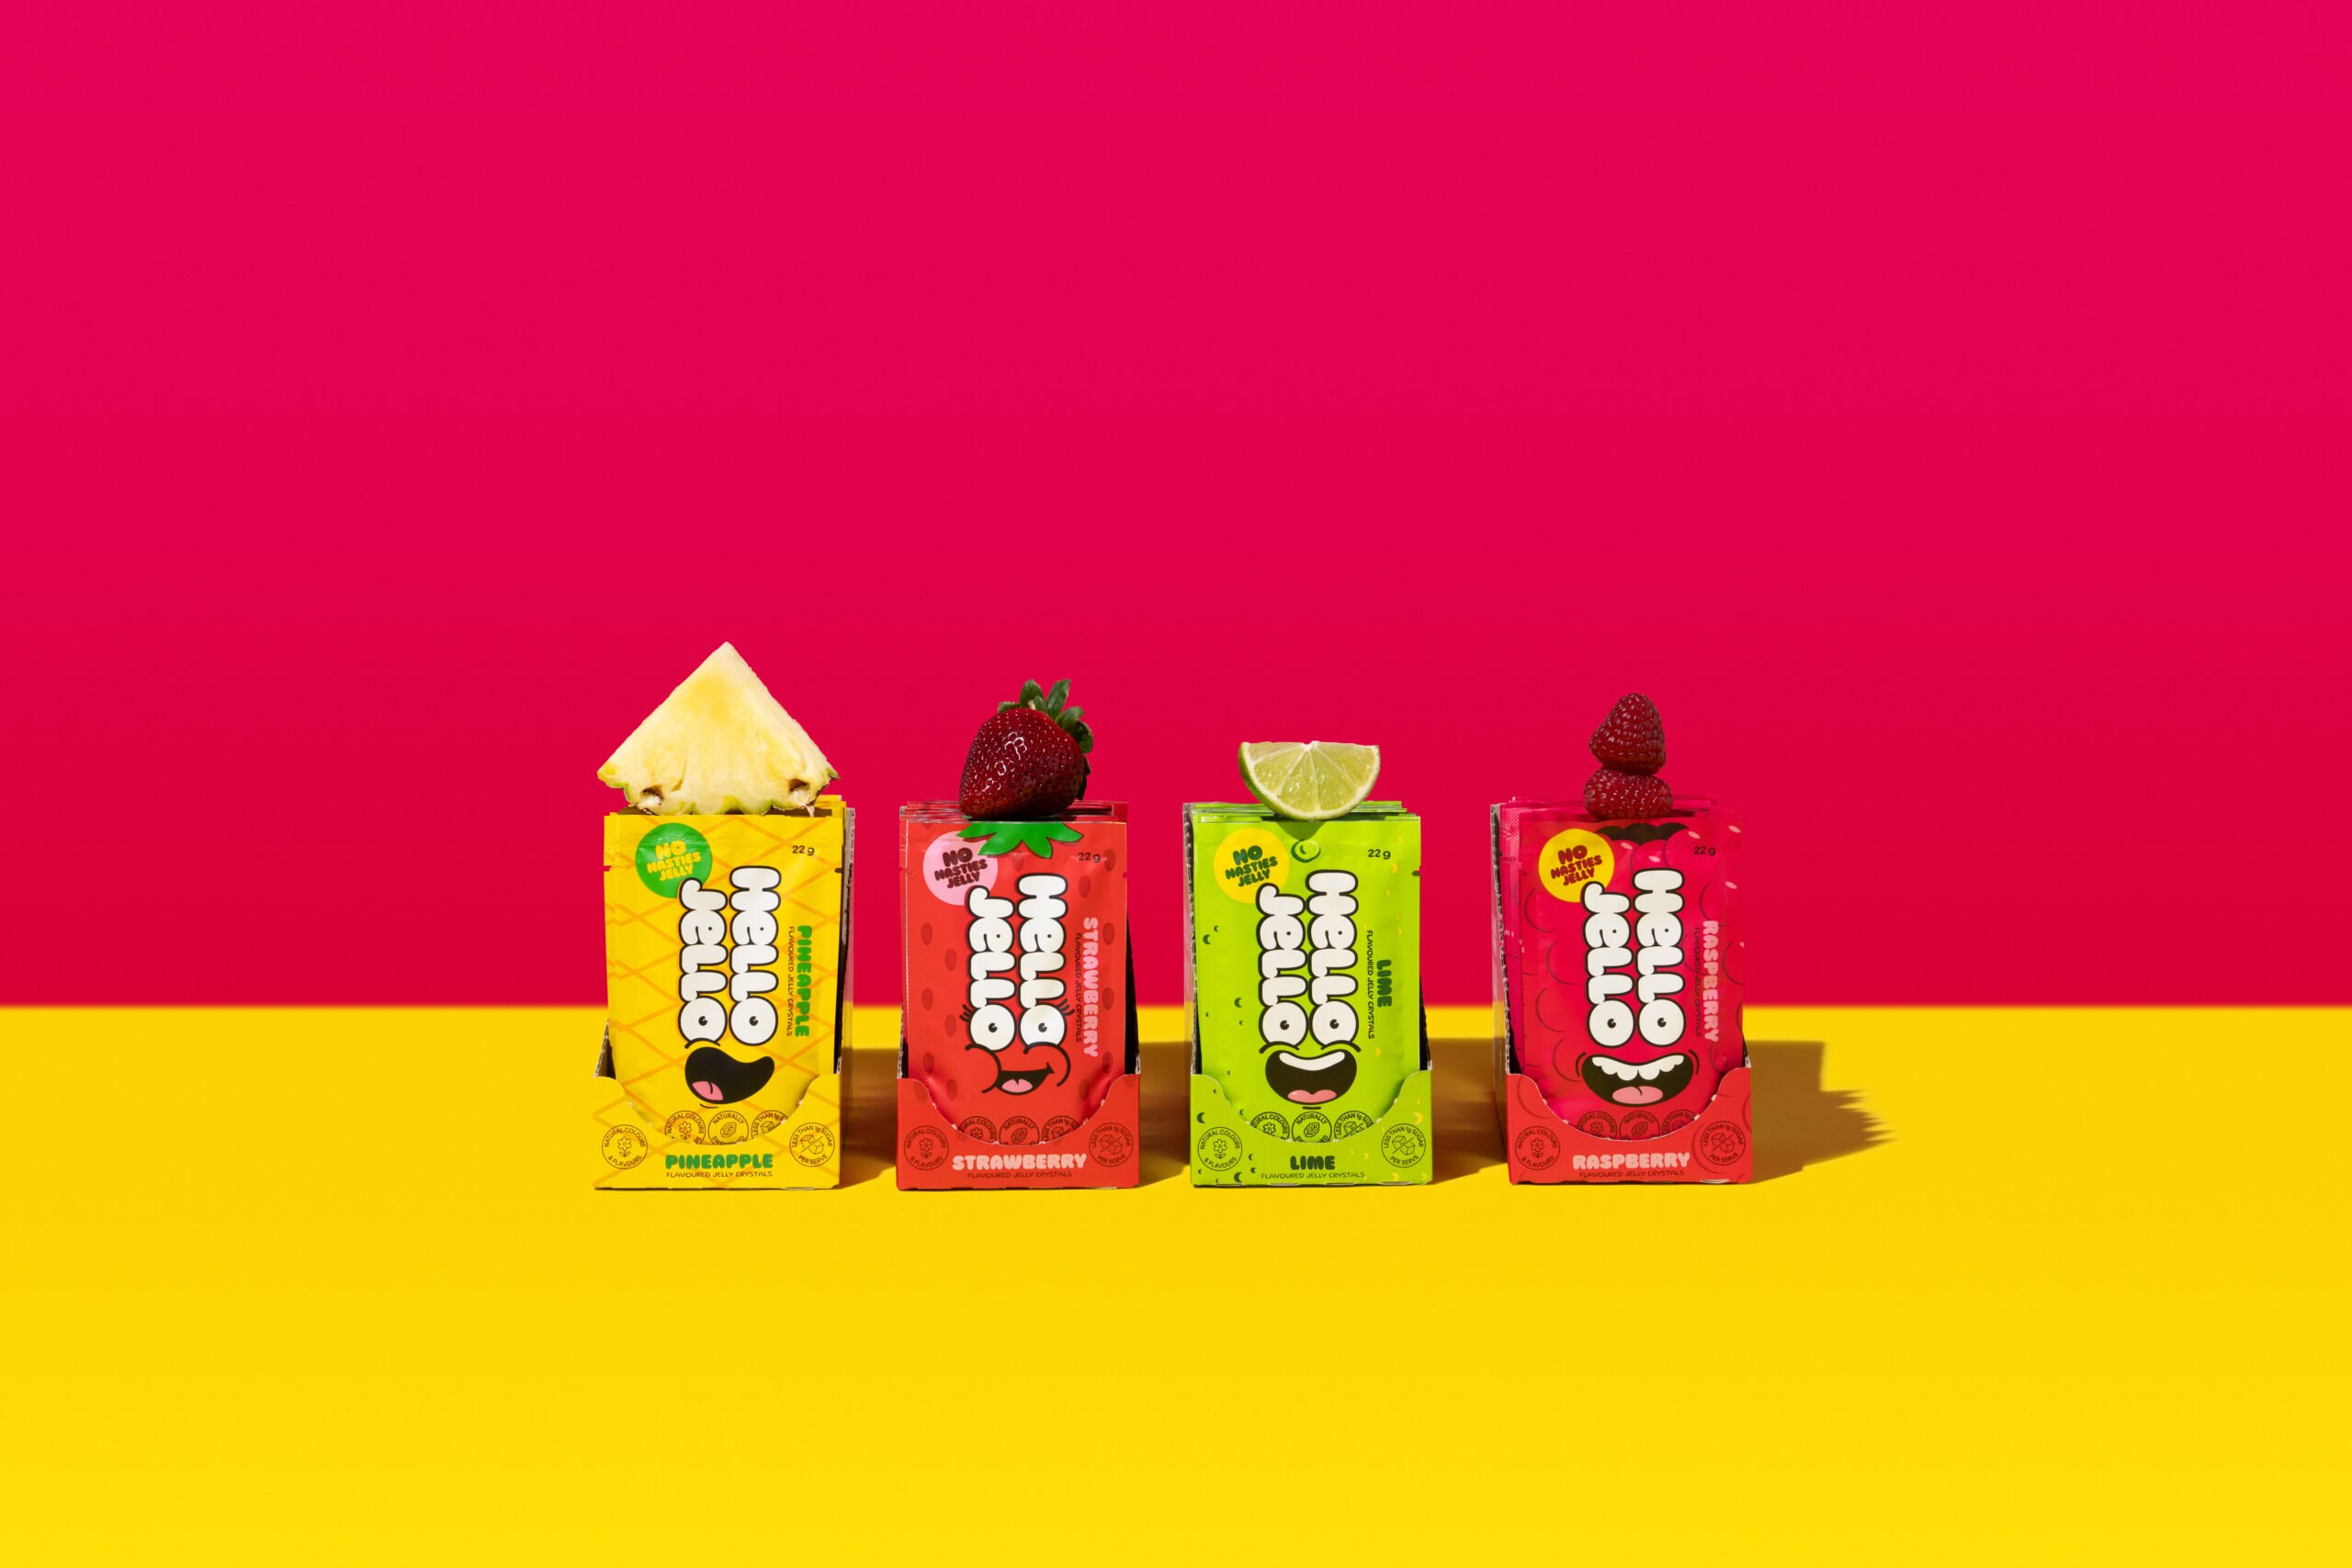
    Australian jelly brand Hello Jello has entered supermarkets nationwide with a better-for-you jelly range after securing a $2 million retail deal with Coles in October 2026.

    The initial retail lineup includes four fruit varieties: raspberry, pineapple, strawberry, and lime.

    Formulation and product specifications

    Founded in Melbourne by Jacqui Roth and Eliza Wallish, the brand enters the packaged dessert aisle with 22-gram sachets of jelly crystals. The lineup includes raspberry, pineapple, strawberry, and lime varieties.

    Each serving delivers 3.7 grams of protein and less than 1 gram of sugar. Sweetness comes from thaumatin, a plant-derived protein extracted from katemfe fruit, allowing the formulation to avoid synthetic sweeteners, artificial colourings, synthetic flavourings, and added sulphites.

    Supermarket shelf space economics

    Securing national distribution with Coles gives early-stage food ventures immediate scale, but retail execution demands tight working capital controls. Upfront shelf commitments across hundreds of stores require manufacturers to maintain consistent supply chain reliability without sacrificing batch margins.

    For major grocers, adding niche clean-label products creates basket differentiation against discount rivals. The commercial pressure now falls on unit turnover speed, where low-sugar alternatives must prove they can match traditional high-sugar volume leaders in weekly category revenue.

    Competition in packaged desserts

    Australia’s shelf-stable dessert category has long remained dominated by legacy sugar-heavy brands and private-label entries sold primarily on price. Upstart brands targeting ingredient-conscious shoppers must justify higher unit prices through functional nutrition claims and natural ingredient sourcing.

    Suppliers competing in this segment face rising raw ingredient costs for specialty natural sweeteners compared to commodity refined sugar. Sustaining shelf placement against established confectionery conglomerates requires steady repeat purchase rates from family households.

    Distribution rollout and sales milestones

    Roth and Wallish developed the concept after seeking packaged treats that eliminated artificial additives while keeping full flavour profiles for household consumption. The resulting retail rollout gives the business direct access to metropolitan and regional shoppers across every state.

    Initial stock allocations are now moving through Coles distribution centres to stock retail shelves across the country. Category managers will track the four-flavour range over the coming quarters to measure initial scan rates against standard confectionery and dessert benchmarks.

  • Lotte New York Palace Appoints Christopher Nez as Food and Beverage Director

    Lotte New York Palace Appoints Christopher Nez as Food and Beverage Director

    South Korea’s LOTTE Hotels & Resorts has appointed Christopher Nez as director of food and beverage at Lotte New York Palace this week. He takes charge of the Manhattan property’s dining and banquet operations.

    His remit covers the hotel’s restaurants, bars, room service, and private event spaces on Madison Avenue.

    Operational Track Record in New York Luxury

    Nez previously managed operations across 5 major New York City properties. His career includes management roles at The Plaza Hotel, JW Marriott Essex House, Park Central, TWA Hotel, and Gordon Ramsay at The London.

    During his tenure at The Plaza Hotel, he won the property’s Leader of the Year recognition in 2018. His background centers on scaling luxury dining programs, managing high-volume banquets, and lifting department revenues.

    Managing High-Margin Banquet and Dining Assets

    Food and beverage brings in a substantial share of total revenue for upper-upscale urban properties. At heritage assets like Lotte New York Palace, banquets and catering often drive overall profitability.

    Banquet margins in prime Manhattan hotels typically yield higher gross returns than room divisions during peak corporate event seasons. Controlling labor costs while maintaining five-star service remains the main operational challenge for luxury operators in the city.

    The Asian Conglomerate Strategy Overseas

    Lotte Group bought the New York Palace Hotel from Northwood Investors in 2015 for approximately 805 million dollars. The purchase anchored the South Korean chaebol’s North American footprint as it expanded beyond East Asia.

    Asian hotel conglomerates face constant pressure to balance local labor dynamics with brand standards set in Seoul. Hiring seasoned New York executives provides the local expertise needed to run unionized, high-overhead city properties.

    Next Steps for Palace Dining

    Luxury hotels across Manhattan are recalibrating their food and beverage programs for shifting corporate travel and event bookings. Nez will lead daily service execution, culinary recruitment, and revenue management across all active dining venues at the Madison Avenue landmark.

  • Exotic Bazaar Expands Middle Eastern Food Range into Coles

    Exotic Bazaar Expands Middle Eastern Food Range into Coles

    In October 2026, Australian food producer Exotic Bazaar secured retail distribution across Coles supermarkets, moving its packaged Persian and Middle Eastern meal bases from regional farmers markets to national grocery aisles.

    The listing gives the Ballarat-founded brand access to millions of weekly supermarket shoppers across Australia.

    Founded by Gilava Pour, Exotic Bazaar produces recipe bases, spice blends and simmer sauces designed to simplify Middle Eastern home cooking. The range includes items such as Tunisian shakshuka bases and traditional Persian meal mixes, targeting consumers who want authentic flavours without sourcing hard-to-find individual spices.

    From Ballarat market stalls to national retail shelves

    The business started by selling directly to consumers at weekend community markets in regional Victoria before building a digital storefront. Growing demand for international pantry staples and convenience cooking drove the brand to expand its wholesale operations, leading to discussions with major supermarket buyers.

    Supermarket operators across the Asia-Pacific region are allocating more shelf space to regional ethnic cuisines as consumer palates diversify. For Coles, adding independent artisan brands helps differentiate its packaged grocery aisles against rival Woolworths and discount chains like Aldi.

    Managing supermarket supply chain pressure

    Transitioning from direct-to-consumer sales to a major grocery chain changes inventory management and cash flow requirements. Fulfilling regular purchase orders for national distribution centres requires strict quality controls, continuous batch manufacturing and reliable freight partners.

    Exotic Bazaar handles e-commerce dispatches from Melbourne alongside its wholesale supply chain. The company pairs retail sales with online recipe resources, including digital guides for dishes like Persian noodle soup, to encourage repeat pantry purchases.

    Pantry demand shifts toward global flavours

    Mainstream grocers historically relegated Middle Eastern ingredients to specialty aisles or small international sections. Mainline shelf placement alongside everyday sauces and cooking bases reflects a broader shift in Australian home cooking habits.

    Suppliers in the specialty food sector face rising packaging costs and ingredient price pressures. Maintaining grocery margins requires steady sales velocity per store, placing the commercial focus squarely on customer retention and shelf turnover.

    Exotic Bazaar continues to dispatch direct orders from Melbourne while monitoring store-level scan rates across the Coles supermarket network.

  • Malaysian Coffee Shops Seek Beer Tax Cuts as F&B Sales Drop 4.6%

    Malaysian Coffee Shops Seek Beer Tax Cuts as F&B Sales Drop 4.6%

    Malaysian coffee shop operators want tax cuts and phased wage adjustments in the upcoming Budget 2027. The demand follows a 4.6 per cent sales drop across cafes and restaurants.

    The Malaysia Singapore Coffee Shop Proprietors’ General Association wants the Ministry of Finance to lower the Sales and Service Tax on alcohol from 8 per cent to 6 per cent. That matches the rate applied to food and non-alcoholic drinks. The group is also urging officials to roll back the beer excise duty increase imposed in the prior budget cycle.

    Licensed food and beverage venues rely on beer sales to subsidise fixed overheads like wages, power, and property leases. Retail Group Malaysia recorded a 4.6 per cent year-on-year sales drop in the first quarter of 2026. It was the first quarterly downturn for the country’s restaurant and cafe sector in nearly three years.

    Operating Costs Outpace F&B Revenue

    Margins are tightening as higher rents and inventory costs hit businesses already suffering from lower footfall. In commercial hubs like Petaling Jaya, monthly retail shop rents jumped from RM6,000 in 2024 to RM12,000 on lease renewals. Keu Kok Meng, Vice President of the Association and Honorary Secretary of the Petaling Jaya Coffeeshop Association, shared the figures.

    Industry cost breakdowns show overheads outpace revenue across high-cost venues. William Lee, owner of Yilo Group and President of Persatuan Pemilik Restoran dan Bistro Malaysia, calculated that goods sold take 40 per cent of gross revenue. Staff costs consume 20 per cent, and rent takes 15 per cent. Utilities, promotional spending, and licensing take another 10 per cent each. Those figures push baseline operating costs to 105 per cent of income before tax.

    Illicit Trade Pressures Regulated Outlets

    Cheaper contraband beer is siphoning trade away from licensed outlets. Smuggled, untaxed stock sells at discounts of up to 50 per cent against legitimate supply. That pricing gap lures customers away from traditional street-corner operators that comply with local licensing and tax rules.

    Local eateries remain tied to the wider brewing supply chain. Data from the Confederation of Malaysian Brewers Berhad 2025 Economic Impact Assessment shows the domestic industry generates an annual average of RM3.3 billion in tax revenue. It also supports roughly 52,400 jobs across production, logistics, and retail hospitality.

    Policy Demands for Budget 2027

    Beyond alcohol taxes, trade groups are pushing back on blanket wage mandates. The association wants future statutory wage increases phased in with adjustments for regional living costs and local trading capacity. Members argue flat national hikes would force small operators to cut staff or shorten business hours.

    Family-run eateries have minimal cash reserves and struggle to pass cost increases to consumers cutting back on dining out. Previous cost shocks after post-pandemic reopenings left neighbourhood outlets with almost no retained earnings to absorb another hit.

    The Timeline for Fiscal Decisions

    Finance ministry officials are currently finalizing allocations and tax measures ahead of the national budget presentation. Coffee shop trade groups are lodging formal memoranda with state and federal ministries to secure excise freezes before the fiscal framework is locked in.

    Parliament will debate the budget measures in October, when lawmakers decide whether to freeze alcohol excise rates and adjust the service tax threshold for licensed food service providers.

  • GS25 Sales to North American Shoppers Jump 131 Percent

    GS25 Sales to North American Shoppers Jump 131 Percent

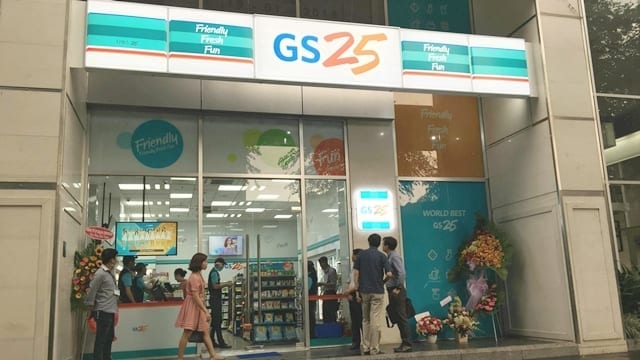
    GS Retail recorded a 131 percent jump in sales to North American visitors at its GS25 convenience stores in South Korea during the first eight months of the year.

    The surge pushed North American shoppers to roughly 30 percent of total foreign customer sales across the network. That leaves them just 10 percentage points behind visitors from Greater China, who continue to hold the largest foreign share at approximately 40 percent.

    Buying beer instead of banana milk

    Spending patterns between the two visitor groups show a sharp split in basket composition. North American customers spend primarily on canned beer, wine and spirits, alongside sports drinks, energy drinks and sodas, spending more on canned beer than any other overseas group. Shoppers from Greater China buy dairy products, instant noodles and baked goods, where blueberry Greek yogurt recently overtook banana milk as the top-selling item.

    Geographic data highlights a similar divide in where travellers spend. Greater China tourists stay clustered around traditional shopping hubs and downtown districts in Seoul, Busan and Jeju Island. North American footfall has concentrated heavily along coastal resort corridors.

    East coast sales outpace Seoul hubs

    Regional revenue from North American buyers saw its fastest expansion in Gangwon Province, where sales climbed 338 percent year on year. The bulk of that volume settled along the province’s beach-lined east coast, driven by seasonal leisure travel.

    For convenience operators in South Korea, this geographic and product divergence changes how individual franchise locations must manage inventory during peak travel seasons. Stores in coastal resort towns require alcohol distribution and cold beverage stock lines calibrated for Western preferences, while urban transit hubs must protect shelf space for packaged snacks and fresh dairy popular with Chinese tour groups.

    GS Retail and rival chains such as CU and 7-Eleven have spent years competing over inbound tourist wallets, yet historical strategies focused almost exclusively on Mandarin-language signage and group tour bus routes. A sustained shift toward Western independent travellers introduces higher margins on liquor and ready-to-drink beverages, but demands different localized marketing at the store shelf.

    Merchandising shifts across 1,000 stores

    Earlier network expansions set the groundwork for tracking foreign transaction data at the point of sale. GS25 introduced foreign card processing upgrades across its domestic estate over recent operating quarters, giving the chain real-time visibility into basket differences by issuing bank and country of origin.

    About 1,000 GS25 stores located in high-traffic tourist corridors have rolled out English-language promotional displays, recipe cards and product preparation guides this year. The company plans to use autumn purchasing data from coastal and metropolitan stores to adjust product distribution schedules ahead of the winter travel cycle.

  • Tealive Launches Orange Coffee Blend from 3 Nations in Sepang

    Tealive Launches Orange Coffee Blend from 3 Nations in Sepang

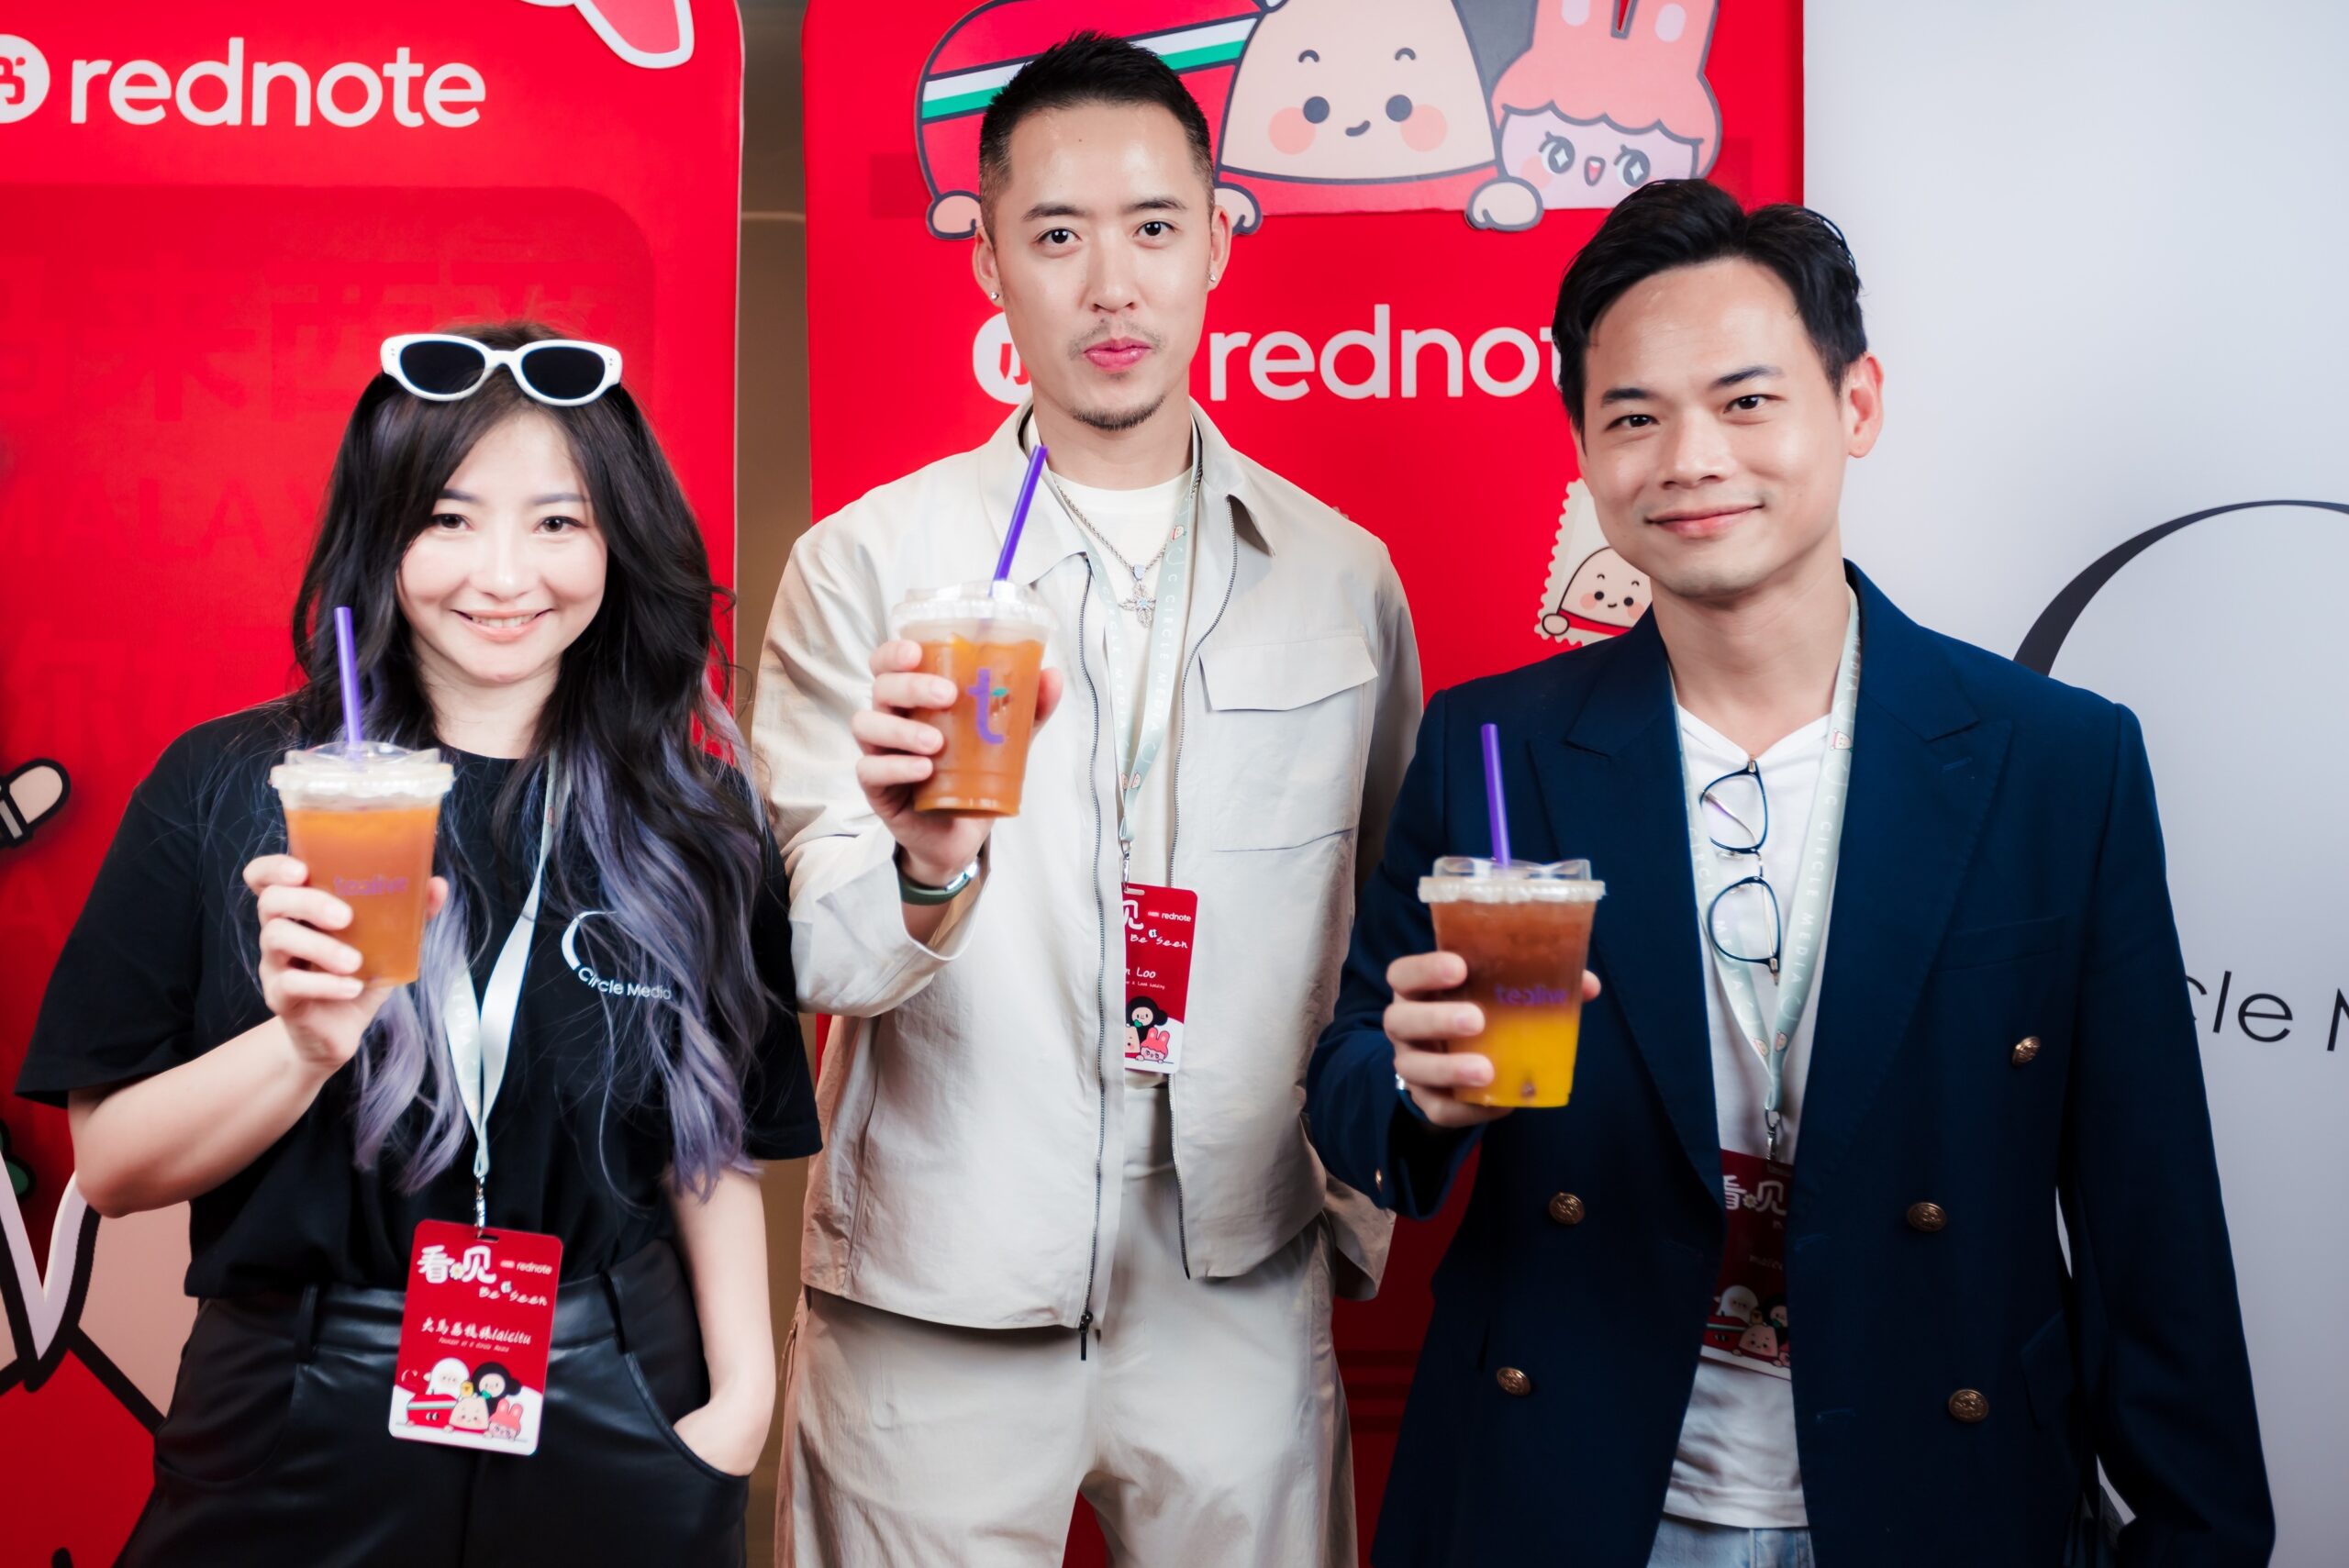
    Tealive introduced a limited-time Orange Coffee line in Sepang on 29 September 2026 to capture a bigger slice of Malaysia’s competitive coffee sector.

    The release uses coffee beans sourced from three nations to target daytime coffee consumers beyond the brand’s established bubble tea audience.

    Tealive aligned the promotional rollout with motorsport gatherings at the Petronas Sepang circuit, pairing the citrus beverage concept with seasonal trackside footfall.

    Branching Beyond Milk Tea

    Bubble tea operators across Southeast Asia continue pushing into freshly brewed coffee to diversify store revenue. Pure-play tea brands face crowded high streets and steep discounting from competing regional kiosks.

    Adding fruit-infused coffee drinks allows front-line beverage retailers to drive higher transaction counts during morning and early afternoon dayparts. It also captures consumers who bypass traditional milk-heavy teas for lighter espresso options.

    Citrus Blends and Menu Variations

    Fruit-forward espresso drinks have become standard offerings in urban cafe markets across Asia. Combining citrus juices with iced coffee appeals directly to younger demographics seeking refreshing, lower-dairy alternatives in tropical climates.

    For operators, cold citrus recipes require minimal back-of-house retooling while commanding premium seasonal price points. Sourcing multi-origin beans gives chain operators room to market quality credentials without moving fully into high-cost single-origin brewing.

    Competition in Malaysia’s Beverage Sector

    Malaysia’s ready-to-drink coffee sector features aggressive rivalry between domestic specialty chains, international franchises, and convenience store counters. Fast product iteration helps major chains maintain consumer engagement against fast-expanding kiosk competitors.

    Limited-edition beverage series serve as low-risk trials for broader product shifts. By testing customer uptake over short campaign windows, brand managers evaluate ingredient sourcing and store-level preparation speed before committing to permanent menu revisions.

    Event Venues and Seasonal Footfall

    High-capacity sporting locations like Sepang offer valuable real-world testing environments for seasonal beverage launches. Peak crowd flows test staff throughput and supply chain resilience under tight operational windows.

    Sales data gathered during the Sepang event window will determine whether citrus coffee blends secure a permanent place across the chain’s wider domestic store network.

  • Baileys and Magnum Launch Six-Pack Non-Alcoholic Mini Ice Cream Bars

    Baileys and Magnum Launch Six-Pack Non-Alcoholic Mini Ice Cream Bars

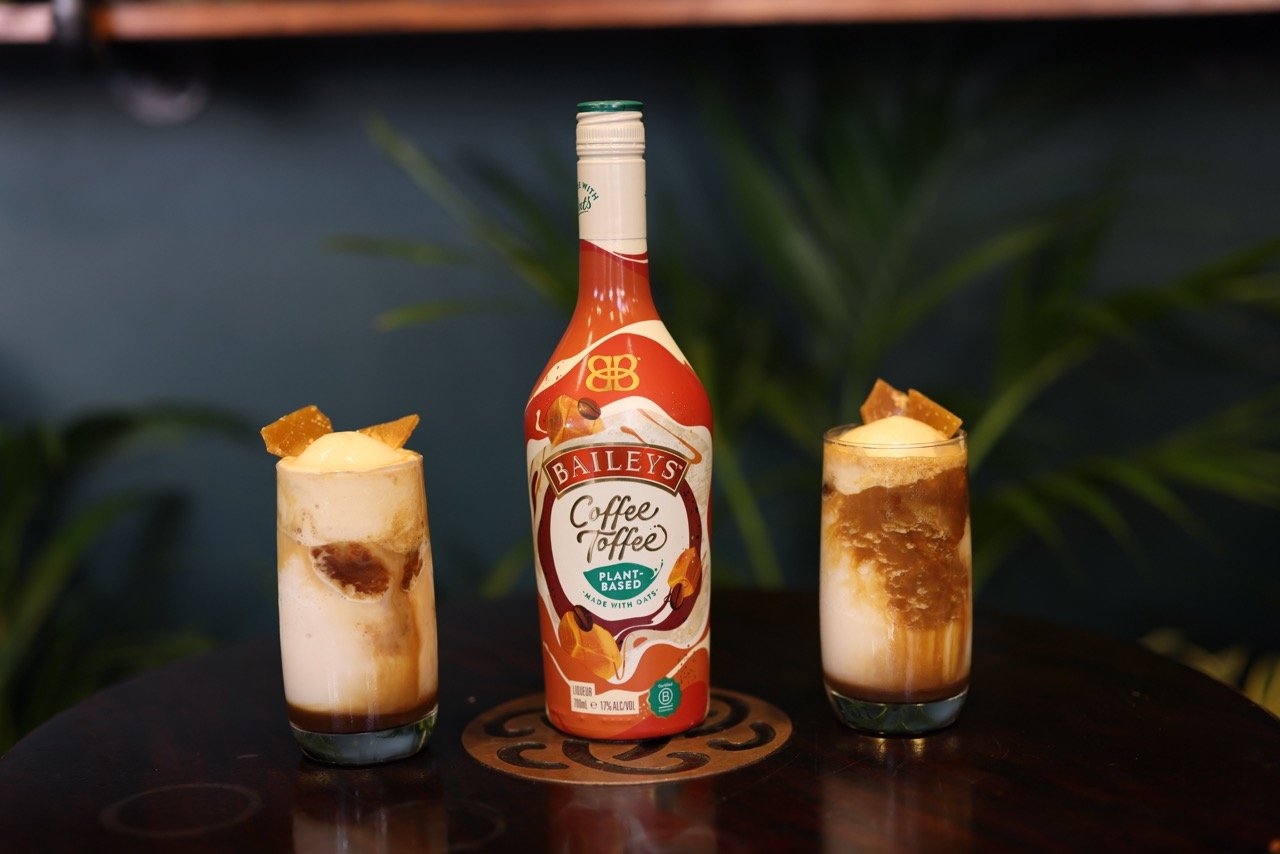
    Baileys Original Irish Cream Liqueur has partnered with The Magnum Ice Cream Company to launch a non-alcoholic ice cream bar in September 2026.

    The six-pack product, Magnum Mini Inspired by Baileys, pairs vanilla ice cream with Baileys flavour, wrapped in Magnum’s chocolate shell and biscuit pieces.

    Brand licensing agency Asembl supported the collaboration, with the treats containing no alcohol and manufactured locally at The Magnum Ice Cream Company’s facility in Minto, NSW.

    Production runs out of the company’s factory in Minto, New South Wales. Brand extension agency Asembl brokered the partnership to broaden the Baileys trademark across non-liquor grocery categories.

    The Non-Alcohol Brand Extension Play

    Liquor brands across the Asia-Pacific region increasingly license non-alcoholic food products to capture everyday consumption occasions. Stripping out the alcohol opens mainstream supermarket shelves, convenience chains, and younger demographics without licensing constraints.

    For Magnum, co-branding provides differentiation in a crowded premium segment where private labels pressure margins. The recipe borrows flavour equity from Baileys while keeping standard production lines at the Minto site.

    Supermarket Freezer Competition

    Licensing deals of this scale rely heavily on novelty to drive initial trial. Sustaining repeat sales in frozen desserts is harder. Freezer space is tightly allocated, and retailers delist slow-moving stock quickly if volume drops once launch marketing ends.

    Competitors across Oceania use similar strategies, pairing legacy bakery or confectionery names with dairy bases to secure premium pricing. Peters Ice Cream recently deployed Lotus Biscoff across its frozen lineup, forcing rival Unilever brands to defend market share with recognizable global partnerships.

    Retail Distribution Timelines

    Asembl previously managed licensing agreements that pushed Baileys into Australian bakery, dessert, and confectionery aisles. Each rollout tests consumer appetite for spirit-inspired flavours in everyday food aisles.

    Sales performance across major Australian supermarkets will determine whether the six-pack format expands into single-serve convenience formats ahead of the southern hemisphere summer.