Tag: glp-1

  • Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan is revamping product development across its beauty and fragrance divisions as weight loss treatments reshape consumer budgets, tracked by 15 generic semaglutide brands entering India since patent expirations began. The ingredient supplier found adult adoption of GLP-1 therapies in the US climbed from 3 per cent in 2024 to 11 per cent in 2026, triggering direct reallocation of discretionary spending.

    Data compiled by the manufacturer from a NielsenIQ Homescan panel revealed American households using the medications increased spending on fine fragrances by 97 per cent while cutting grocery budgets. In Brazil, 47 per cent of buyers reported trimming other expenses specifically to finance treatment doses, signaling a widespread behavioral reallocation away from food toward personal grooming, sports, and travel.

    India Generics Drive Rapid Market Expansion

    Price reductions and the loss of patent exclusivity in markets such as India have dismantled entry barriers for metabolic therapies. The introduction of 15 domestic brands following patent expiries expanded regional supply rapidly, lowering therapy costs and broadening usage beyond narrow clinical segments.

    Lower retail prices combined with the development of oral alternatives to subcutaneous injections are speeding up adoption across emerging economies. For personal care brands operating in Asia, this shift alters the customer base faster than anticipated. Product developers must adjust formulas for consumers managing the physiological consequences of rapid weight reduction.

    Formulations Adapt to Side Effects

    Patients experience specific physiological issues that prompt new topical requirements, notably loss of facial volume, loose skin, barrier dryness, temporary hair thinning, and bad breath. Consumers navigating these side effects prioritize demonstrable performance over brand prestige, checking active concentrations and clinical validation closely.

    Buyers demand formulas that combine medical-grade efficacy with sensory textures. Frédéric Merlin, manager of the Givaudan Digital Factory in Paris, stated: “Faced with these very real concerns, consumers are becoming more demanding: they seek out the right actives, compare concentrations, and check the evidence behind efficacy claims. But they are unwilling to choose between performance and pleasure. They expect visible results, sensorial textures, and an enjoyable experience. Whereas a brand’s reputation may once have been enough to win them over, it is now the efficacy promise, backed by evidence, that makes the difference.”

    Scent Profiles Reflect Appetite Changes

    Social listening data gathered by Givaudan identified two dominant fragrance profiles among treatment users: gourmand compositions and crisp, fresh notes. Appetite suppression does not eliminate interest in rich food-inspired aromas, although nausea risks create sharp aversions to heavy notes, requiring finer calibration by perfumers.

    Energy dips and sleep disruptions linked to these therapies have opened room for functional scents. Givaudan is deploying its patented MoodScentz and DreamScentz platforms, pitching neuro-olfactive formulations that stimulate alertness in the morning or support disrupted sleep cycles at night.

    Digital Factory Tests Commercial Concepts

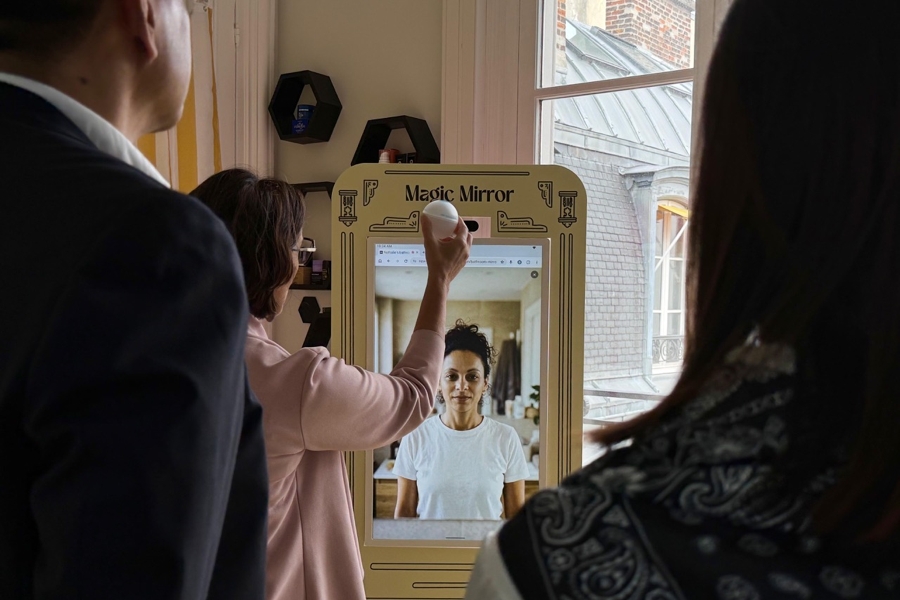
    The company developed an exhibition format called The New Desire at its Paris Digital Factory, built around an artificial intelligence persona named Nathalie to model shifting habits. Brand teams examine over 120 global product rollouts and generate concept packaging tested against simulated consumer feedback.

    Corporate clients have booked repeat sessions at the facility, prompting an operational extension of the program. Fast-moving consumer goods suppliers across the Asia-Pacific region now face parallel realignments on retail shelves: packaged food volumes face headwinds, while functional personal care and premium fragrances capture liberated wallet share.

    Givaudan plans to publish its next wave of field research on GLP-1 olfactory preferences before the end of 2026.
  • Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Pharma Thailand introduced a higher-dose semaglutide option on October 7. The treatment addresses type 2 diabetes and linked cardiovascular risks across the country.

    It targets an expanding patient base. Diabetes prevalence in Thailand climbed to 10.6 per cent in 2025, up from 9.5 per cent in the 2020 national survey.

    The Danish drugmaker presented the formulation to more than 500 Thai medical practitioners at an industry gathering. The therapy targets cardiovascular-kidney-metabolic syndrome. That condition links heart disease, renal impairment, and obesity in diabetes patients.

    Expanding Treatment Beyond Glycaemic Control

    Cardiovascular disease is the leading cause of death among Thai type 2 diabetes patients. Chronic kidney disease also affects up to 40 per cent of diagnosed patients. Diabetes remains the primary driver of end-stage renal failure nationwide.

    Doctors gain an extra clinical tool for weight management and organ protection alongside blood glucose reduction. Most Thai adults with type 2 diabetes are overweight or obese. This compounds their health risks.

    Distribution runs through state hospital tenders, private hospital networks, and licensed retail pharmacies across the Kingdom. The company has operated locally for more than four decades, supplying metabolic and chronic disease therapies through all three channels.

    Commercial Stakes in Southeast Asian Healthcare

    Demand for advanced glucagon-like peptide-1 receptor agonists has surged across Southeast Asia. Lifestyle illnesses now place heavy pressure on state healthcare funds. In Thailand, universal health coverage schemes face rising long-term costs from dialysis and acute cardiac interventions.

    Drug suppliers compete directly for formulary spots in private hospital groups and government procurement lists. Higher dosage strengths help manufacturers preserve revenue per patient. They also defend market share against emerging biosimilars and rival GLP-1 therapies entering Asian markets.

    Premium chronic therapies provide healthcare operators and pharmacy chains with steady prescription volumes. Affordability and public reimbursement access remain the main hurdles. Because of those limits, high-dose therapies rely largely on private payers and self-funded patients.

    Four Decades of Thai Market Presence

    Novo Nordisk established its formal presence in Thailand more than 40 years ago. It built distribution relationships with public teaching hospitals and private medical groups, later rolling out baseline semaglutide formulations across Southeast Asia after global clearances.

    Novo has been at the forefront of diabetes care for more than a century, and we recognise that type 2 diabetes is one of the most pressing public health challenges of our time. In Thailand, it is closely linked to CKM syndrome, conditions that place an enormous burden on families and on the Thai healthcare system.

    Next year, the pharmaceutical producer will hold clinical symposiums across provincial medical hubs. These sessions will train specialists on prescribing protocols for the higher dosage.

  • Hims & Hers Rolls Out Weight-Loss and Prescription Platform in Australia

    Hims & Hers Rolls Out Weight-Loss and Prescription Platform in Australia

    Telehealth group Hims & Hers has launched branded GLP-1 weight-loss drugs and prescription treatments in Australia, chasing a global revenue target of US$6.5 billion by 2030.

    The rollout follows the completed acquisition of Sydney-based digital health firm Eucalyptus, which gave the US provider control of local men’s telehealth brand Pilot. Australian patients can now access treatments for sexual health, cholesterol and weight management directly through the combined digital channel.

    Integration of Pilot and Juniper

    Existing Pilot clinicians are shifting directly over to the Hims platform. A spokesperson for the company confirmed that the weight-loss catalogue includes access to branded GLP-1 medications, mirroring its US lineup of treatments such as Novo Nordisk’s Wegovy and Eli Lilly’s Zepbound.

    Former Eucalyptus chief executive Tim Doyle, who now serves as senior vice president at Hims & Hers, will oversee the Australian rollout. The company plans to bundle consultations and products that consumers previously bought as separate transactions, focusing on suburban and regional areas where physical access to specialists is limited.

    Digital health platforms across the Asia-Pacific region are consolidating fast to capture soaring consumer demand for metabolic care and discreet direct-to-consumer treatments. Local pharmacy operators face stiffer competition as international platforms buy up homegrown startups rather than building customer rosters from scratch.

    International Expansion and Margins

    Expanding across foreign markets has lifted monthly revenue per subscriber by 21 per cent year-on-year. That top-line gain comes with a cost: management told investors during its second-quarter earnings call that gross profit margins will stay below historical levels while international operations scale.

    The Australian launch builds on the 2025 purchase of London-based Zava, which distributes weight-loss drugs across the UK, Germany, France and Ireland. Next on the Australian schedule is the launch of its dedicated women’s health service through Eucalyptus brand Juniper before the end of the year.

  • Sigma Healthcare Profit Jumps 22 per Cent as Annual Sales Top $10.8 Billion

    Sigma Healthcare Profit Jumps 22 per Cent as Annual Sales Top $10.8 Billion

    Sigma Healthcare posted a 22.3 per cent rise in annual net profit to $732.3 million for the year ended June 30, lifted by pharmacy additions and GLP-1 prescription volumes.

    Group revenue advanced 15.5 per cent to $10.8 billion, while normalised earnings before interest and taxes climbed 20.6 per cent to breach $1 billion.

    The results reflect the first full operating cycle since Sigma combined operations with discount chain Chemist Warehouse. Chief Executive Officer Vikesh Ramsunder told investors the business now oversees nearly 1,000 pharmacies worldwide, supported by supply-chain integration across wholesale and retail divisions.

    Chemist Warehouse Drives Domestic Momentum

    Australia generated the bulk of earnings, lifting revenue 14.9 per cent to $10.4 billion and normalised operating profit by 18.3 per cent. Chemist Warehouse added 24 domestic sites to reach 561 stores, generating network sales growth of 15.9 per cent and same-store sales gains of 13.4 per cent.

    Sales of GLP-1 weight-loss medications contributed heavily to turnover across the network. While the high-cost treatments carry lower percentage returns, Sigma maintained its Australian gross margin at 17.6 per cent by expanding front-of-store retail lines, introducing more than 470 private-label products during the financial year.

    For retail pharmacy chains across the Asia-Pacific region, Sigma’s post-merger run shows how high-volume discount models can protect margins even as prescription product mixes shift toward expensive, low-margin therapies. It also demonstrates how domestic retail density provides cash flow stability after walking away from risky international takeovers, including Sigma’s abandoned $14 billion tilt at Britain’s Boots chain.

    Synergies and Franchise Pipeline

    Sigma captured $32.6 million in operational savings during the year as it works toward an annual cost-reduction target of $100 million by the 2029 financial year.

    Wholesale franchise networks Amcal and Discount Drug Stores are also rebuilding footprint after years of store rationalisation. Management has assembled an opening pipeline of 82 stores, scheduled to return both banner groups to net store count growth during the 2027 financial year.

  • Drugmakers Turn to Gyms and Metros to Drive China Weight-Loss Sales

    Drugmakers Turn to Gyms and Metros to Drive China Weight-Loss Sales

    Global and local drugmakers are plastering Chinese metro stations, gyms, and sports stadiums with obesity campaigns to capture a 30 billion yuan weight-loss market. China bans direct-to-consumer advertising for prescription medicines, forcing pharmaceutical companies to sell lifestyle interventions rather than brand names to a population where overweight rates could top 65 per cent by 2030.

    Eli Lilly, Novo Nordisk, Pfizer, and domestic group Innovent Biologics are vying for early dominance in once-weekly GLP-1 injections. In the second quarter, Lilly took the top spot in sales on Alibaba’s Tmall and JD.com, according to Jefferies data. To sustain demand, companies place unbranded warnings about sleep apnoea and fatty liver disease in high-traffic public transit hubs and fitness chains.

    Sidestepping the Ban on Drug Ads

    Regulations permit pharmaceutical brands to discuss disease symptoms publicly, provided they omit specific prescription product names. Lilly ran subway displays in Shanghai’s Jing’an district alerting commuters to the links between snoring and excess weight, while Innovent partnered with delivery giant Meituan on transit billboards highlighting fatty liver reversal. Innovent also promoted weight management messages during football matches in Suzhou and featured a mascot named Madudu, echoing the generic name of its mazdutide injection.

    Pfizer collaborated with gym chain Supermonkey on public workout events in Shanghai. State broadcaster CCTV worked with Novo Nordisk on a public health exhibit in Beijing featuring group dancing. These street campaigns drive consumers directly to hospital consultation rooms. Doctors at clinics in Shanghai and Guangzhou report that patients increasingly ask for specific treatments by name, shifting from Novo’s semaglutide to Lilly’s tirzepatide and Innovent’s mazdutide.

    The Race for a Four Billion Dollar Market

    China’s prescription weight-loss segment generates between 3 billion and 4 billion yuan today. JP Morgan projects that total will hit 30 billion yuan, or roughly $4 billion, within five to seven years. Novo Nordisk started the race with a late 2024 rollout, Lilly entered in January 2025, Pfizer issued its first prescriptions in April, and Innovent rolled out its drug in July 2025.

    RetailNews Asia notes that healthcare brands across East Asia have long used subtle educational pushes to bypass medical marketing restrictions, but the intensity in China now mirrors consumer FMCG marketing more than traditional clinical outreach. Competitors are actively adjusting their public phrasing to match consumer vocabulary, moving budget away from purely hospital-focused sales representatives.

    Regulators in the region are watching the grey area closely. Lilly paused an obesity awareness campaign in India earlier this year after local authorities raised concerns that public outreach coincided directly with the market launch of Mounjaro. In China, market regulators will determine whether mascot branding and metro displays cross into unlawful prescription drug promotion as rollout volumes climb through the end of 2026.