Tag: Krungthai Bank

  • Thai Virtual Bank Clicx Taps Thought Machine Ahead of up to 3 Licensees

    Thai Virtual Bank Clicx Taps Thought Machine Ahead of up to 3 Licensees

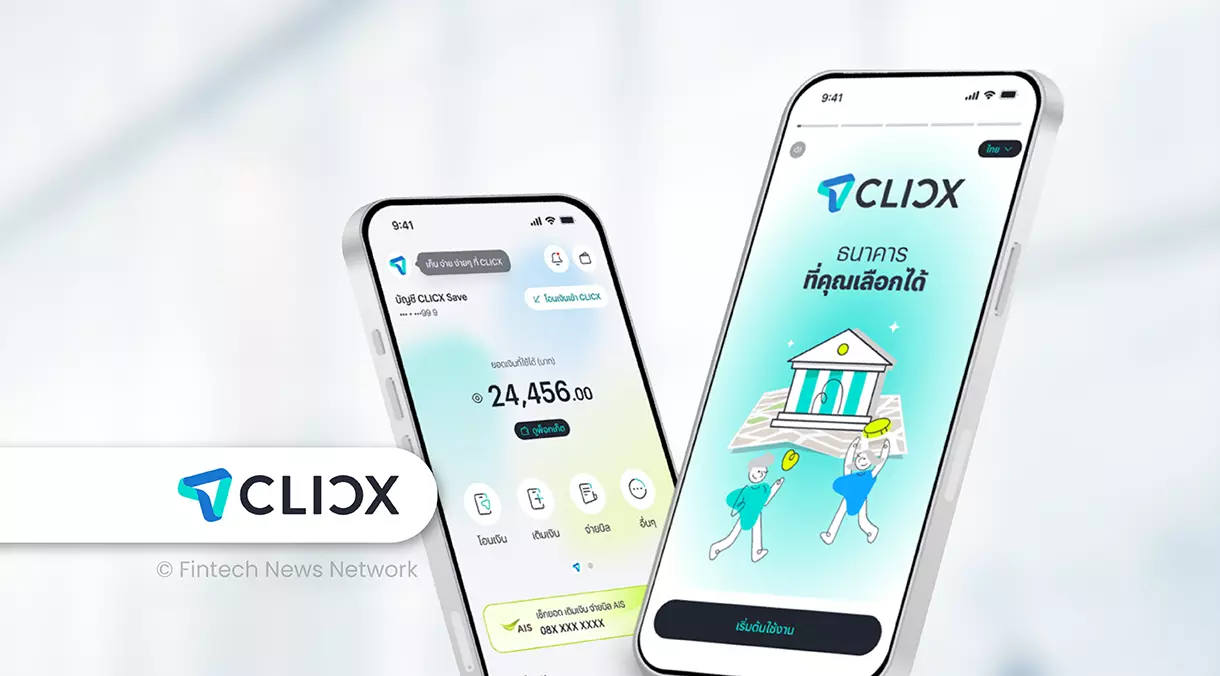
    Thai virtual bank Clicx chose London software vendor Thought Machine on November 3 to run its core banking engine, clearing its infrastructure setup ahead of rival licence holders.

    The consortium, owned by state-controlled lender Krungthai Bank, mobile carrier Advanced Info Service, and fuel and convenience retailer PTT Oil and Retail Business, is the first entrant to claim full operational readiness under the central bank schedule.

    Clicx runs on Vault Core, a cloud system that separates ledger code from product rules. Instead of waiting on an outside vendor to modify backend code when rolling out credit products, the bank can adjust interest rate schedules and repayment periods directly. The bank targets nano-loans and digital personal credit at freelancers, daily wage earners, and mom-and-pop vendors who lack standard salary slips. Risk assessment relies on customer-consented behavioural records pulled from AIS mobile accounts, OR petrol stations, retail cash registers, and Krungthai payment networks.

    How Real-Time Data Replaces Collateral

    Virtual banks routinely promise financial inclusion, but uncollateralised micro-lending often collapses under high non-performing loans when underwriting relies on static quarterly statements. By feeding real-time merchant settlement receipts and telco top-up histories into its ledger, Clicx tries to calculate cash flow before a borrower misses a payment. If a roadside stall owner buys fuel and stock each morning through OR channels and accepts digital payments via Krungthai, the transaction frequency acts as the credit score.

    That cross-ecosystem architecture brings operational friction. Merging customer profiles across three massive consumer databases requires strict compliance under Thailand’s Personal Data Protection Act, which governs explicit user consent, data correction, and deletion. Any technical glitch in how consent tags migrate across corporate systems can halt automated loan approvals at the point of sale.

    The Tech Stack Behind the Build

    Traditional lenders typically buy monolithic cores where a single product update takes months of regression testing. Vault Core operates differently by treating every account balance and transaction as an event-driven ledger entry, leaving the commercial logic in isolated microservices.

    Wannasit Chaiphinan, CTO of Clicx, said: “We selected Vault Core because we needed a core banking platform that gives our team the flexibility to develop products around our customers’ needs. Its cloud-native architecture separates product logic from the underlying core infrastructure, allowing us to configure, test and refine products in-house with less dependence on vendor-led changes.”

    For vendor Thought Machine, the contract adds Thailand to a regional footprint that includes client banks in Singapore, Malaysia, Vietnam, and the Philippines. The British tech firm recently crossed $100 million in annual recurring revenue with positive free cash flow, following a 57 per cent annual revenue gain.

    Pressure on Traditional Branch Networks

    The consortium model poses a clear threat to brick-and-mortar retail banking branches across suburban Thailand. While incumbent commercial banks pay commercial rents and staff teller counters to process small-business loans, Clicx uses the nationwide physical footprint of OR petrol stations and AIS customer service centres as passive marketing conduits.

    Retail merchants who already purchase stock inside the OR retail ecosystem gain an incentive to keep their working capital accounts within the same network. Traditional mid-tier lenders must either compress their loan origination margins or watch self-employed borrowers migrate to platform-native digital lines of credit.

    Consortium Timeline and Licensing Steps

    The Bank of Thailand published its roster of successful virtual bank applicants on June 19, 2025, capping the initial framework at up to three operating licences. Regulatory guidelines required winning consortia to establish secure IT systems, risk controls, and capital cushions before receiving final clearance to open customer accounts.

    The next concrete hurdle sits with the central bank inspectors, who must complete technical audits of the Vault Core integration and data privacy protocols before Clicx can formally accept public deposits and disburse its first commercial loans.
  • Krungthai Bank Announces Upcoming ATM System Maintenance: What You Need to Know

    Krungthai Bank Announces Upcoming ATM System Maintenance: What You Need to Know

    As Asia continues to be a global retail powerhouse, new strategies and trends are emerging that are reshaping the landscape. One of the most talked-about phenomena in the region is the rise of omnichannel retail, which has transformed how businesses engage with consumers. Retailers are increasingly blending online and offline experiences, recognizing that today’s shoppers crave flexibility, convenience, and a seamless journey from browsing to purchasing.

    Unlocking the Power of Omnichannel Retailing

    In major Asian markets, brands are embracing technology to fortify their omnichannel strategies. Retailers are deploying innovative solutions like mobile apps, augmented reality, and personalized marketing to capture the ever-elusive, tech-savvy consumer. In China, for example, businesses are taking advantage of super apps that combine shopping, social media, and payment systems all in one platform, making it easier than ever for consumers to navigate their buying decisions.

    The pandemic has accelerated this shift. Consumers, now accustomed to the convenience of digital shopping, are less loyal to brands that fail to meet their expectations. As a result, retailers are rethinking their strategies, finding ways to integrate their physical stores with digital platforms to create a more engaging shopping experience. This shift is not without its challenges; inventory management, consistent branding, and rapid order fulfillment are just a few of the hurdles that retailers must overcome in this new digital age.

    The Growing Importance of Sustainability

    Sustainability is no longer just a buzzword in retail; it’s becoming a critical factor influencing consumer choices across Asia. As awareness around environmental issues grows, brands are finding that adopting sustainable practices can significantly enhance their appeal. Companies are now looking at everything from ethically sourced materials to eco-friendly packaging, which resonates particularly well with younger consumers.

    In Japan, for instance, retailers are focusing on recycling initiatives and reducing plastic waste, showcasing their commitment to sustainability as a core aspect of their business identity. This trend is more than just ethical; it’s financially savvy, as studies indicate that consumers are willing to pay a premium for products they perceive as environmentally friendly.

    Surprising Retail Innovations on the Horizon

    The future of retail in Asia is not just about adapting to current trends; it’s also about anticipating the next big thing. One surprising innovation gaining traction is the rise of social commerce, where platforms like TikTok are turning into virtual marketplaces. Imagine scrolling through a feed filled with videos and discovering you can buy that stylish jacket or trendy gadget without ever leaving the app—it’s an exciting prospect that could redefine shopping.

    Retailers are also exploring the potential of artificial intelligence and machine learning to predict consumer behavior, manage supply chains, and personalize marketing efforts. This technologically driven approach not only streamlines operations but also fosters deeper connections with customers by offering tailored experiences.

    As the retail landscape evolves, one thing is clear: adaptability is key. Brands that are willing to embrace change and innovate will not only survive but thrive in the dynamic Asian retail market.

    Questions & Answers

    What is omnichannel retailing, and why is it important in Asia?
    Omnichannel retailing refers to the seamless integration of online and offline shopping experiences. It’s crucial in Asia due to the region’s tech-savvy consumers who expect a flexible and convenient shopping journey.

    How are brands in Asia addressing sustainability?
    Many Asian retailers are adopting sustainable practices, such as using eco-friendly materials and reducing plastic waste, to appeal to environmentally conscious consumers, especially younger shoppers who prioritize sustainability.

    What are some innovative trends shaping the future of retail?
    Trends like social commerce, where platforms like TikTok facilitate shopping, and the use of AI to personalize shopping experiences are at the forefront of innovation, promising to transform how consumers interact with brands.

  • Krungthai Bank to transfer tax refunds via Prompt Pay

    Krungthai Bank to transfer tax refunds via Prompt Pay

    Krungthai Bank has announced it is now fully ready to utilize the National E-Payment system ‘Prompt Pay’ and will starting January 4, 2017 use it to transfer senior citizen and disability stipends as well as tax refunds for the public.

    Vice President for Business Finances at Krungthai Bank Songpol Cheewpanyaroj has announced that from January 4 2017 onward, Krungthai, as the bank tasked by the Revenue Department with forwarding tax refunds to citizens signed on to the Prompt Pay system, will begin doling out the funds through the e-payment method. He noted that citizen can continue to register for the system between January 1 and March 31 so that they may use it to receive their refund.

    In February, the bank will also be using Prompt Pay to distribute government stipends to the elderly and disabled and urged those eligible for the assistance to register for Prompt Pay soon.

    At present, over 2.2 million citizens are in the Prompt Pay system, which was already used to disperse low-income earner aid to some 300,000 people.