Tag: loans

  • India’s Consumer Loan Market Poised to Hit $1 Trillion by 2029: Key Insights Ahead

    India’s Consumer Loan Market Poised to Hit $1 Trillion by 2029: Key Insights Ahead

    The Indian consumer lending market is set for an extraordinary leap, potentially reaching $1 trillion by 2029, driven by a robust economic landscape and shifting consumer behaviors. According to projections from GlobalData, this sector is expected to experience a compound annual growth rate (CAGR) of 7.4% between 2025 and 2029, emphasizing the surging appetite for credit.

    Record Growth in Consumer Loans

    As of 2025, the consumer loan market in India is poised at an impressive $758.8 billion, a figure that stands as a testament to the changing financial dynamics in the country. The remarkable 27.6% growth recorded in 2023 highlights a significant rise in consumer income alongside evolving spending habits.

    Government Initiatives Fueling Demand

    Ravi Sharma, lead banking and payments analyst at GlobalData, notes that India’s vigorous economic expansion, bolstered by substantial government investments in infrastructure and rising household spending on real estate, is a key driver behind the surge in consumer lending. “Consumers are enjoying increased disposable incomes, opening the door to more discretionary spending and elevating the demand for various credit products,” he explains.

    Challenges on the Horizon

    However, it’s not all smooth sailing. Global economic uncertainties, particularly those stemming from US tariffs, pose a risk to consumer sentiment, potentially affecting new loan originations across the board. As the market expands, stakeholders will need to navigate the delicate balance between growth and these external pressures.

    In a landscape where rising incomes are bringing dreams of homeownership and new vehicles within reach, one might wonder if India’s consumers will soon be buying their way into luxury as easily as picking up a new smartphone. Perhaps it’s time for retail strategists to shape their offerings to cater to these evolving desires.

    Questions & Answers

    What factors are driving the growth of India’s consumer lending market?
    Robust economic growth, urbanization, and increased disposable income are primary drivers, alongside government investments in infrastructure and rising household demand for real estate and consumer durables.

    How much is the consumer loan market expected to be worth by 2029?
    The consumer lending market in India is projected to reach $1 trillion by 2029, fueled by a compound annual growth rate of 7.4% between 2025 and 2029.

    What challenges could impact the growth of consumer lending in India?
    Global economic uncertainties, particularly the effects of US tariffs, may dampen consumer sentiment, potentially slowing the growth of new loan originations across various products.
  • South Korean Banks See Growth in Deposits and Household Loans in June

    South Korean Banks See Growth in Deposits and Household Loans in June

    In a striking shift within South Korea’s banking landscape, deposits and household loans surged in June 2025, surpassing previous month’s figures, according to the latest data released by the Bank of Korea (BOK). This trend reflects an increasing consumer confidence amid dynamic housing market activities.

    Deposits Take the Lead

    June saw South Korean banks enjoy a robust increase in transferable deposits, which rose by $19.88 billion (KRW 27.3 trillion). This marks a notable jump from the $14.7 billion (KRW 20.2 trillion) expansion observed in May. Such a significant uptick suggests that households are not just saving — they are preparing for something big.

    Household Lending on the Rise

    When it comes to lending, banks extended an additional $4.5 billion (KRW 6.2 trillion) to the household sector in June, continuing from a healthy increase of $3.78 billion (KRW 5.2 trillion) in the prior month. This momentum indicates a thriving demand for loans, particularly in the mortgage market, which has been buoyed by a recent wave of housing transactions.

    Corporate Lending Struggles

    Yet, not all areas of the banking sector are flourishing. In a somewhat ironic twist, corporate lending took a downturn, with banks issuing $2.62 billion (KRW 3.6 trillion) less in loans to businesses. While large corporations faced a setback, small and medium enterprises (SMEs) managed to hold their ground with a slight increase in funding.

    Asset Management Funds Take a Hit

    Adding to the mixed signals, funds managed by asset management companies experienced a decline of $946 million (KRW 1.3 trillion). This drop underscores a cautious outlook among investors, perhaps reflecting a general uncertainty in market conditions.

    As South Korean banks navigate this uneven landscape, the growing consumer deposits and household loans inject a sense of optimism, even as corporate sectors reel from decreased lending. In this balancing act, only time will tell how these trends evolve.

    Questions & Answers

    What drove the significant increase in household loans in June 2025?
    The increase in household loans can be attributed to the rising demand for mortgages amidst an uptick in housing transactions across the market.

    How did corporate lending perform in June 2025?
    Corporate lending saw a decline of $2.62 billion (KRW 3.6 trillion), indicating challenges within the business sector, particularly for large corporations.

    What does the decline in asset management funds suggest?
    The reduction of $946 million (KRW 1.3 trillion) in asset management company funds may point to a cautious investment sentiment among consumers, reflecting broader market uncertainties.

  • Banks hike mortgage interest rates

    Banks hike mortgage interest rates

    Several banks have increased mortgage interest rates by up to 1 percentage point amid credit tightening.

    In mid-June Vietcombank hiked its from 9.2 percent to 9.8 percent for the first three years.

    At least three other banks have increased its rates.

    United Overseas Bank has raised its rate from 6.49 percent to 7.69 percent.

    Vietnam International Bank has adjusted its rate up by 0.2 percentage points since last month to 8.7 percent.

    Bank managements said the pressure of rising deposit interest rates and tightened credit has forced them to hike loan interest rates.

    Trinh Bang Vu, head of retail lending at Shinhan Bank, said since there is little room left for lending this year and the State Bank of Vietnam has not increased quotas, banks have to be selective in their loans.

    Some lenders like Orient Commercial Bank have not yet increased their mortgage rates, but expect to do so by 0.1-0.2 percentage points in the next few months.

    SSI Securities analysts expect home loan interests to continue to rise even if new credit growth quotas are announced.

    KB Securities analysts forecast a 0.4-0.7 percentage point increase in rates this year due to inflation.

  • VietinBank pre-tax H1 profits up 75 pct

    VietinBank pre-tax H1 profits up 75 pct

    State-owned lender VietinBank has recorded pre-tax profits of VND13 trillion ($565.2 million) in the first six months of 2021, a year-on-year increase of 75 percent.

    Its ratio of non-performing loans at the end of Q2 was 1.38 percent, chairman Le Duc Tho said, adding that the targeted non-performing loans ratio for this year was 1-1.2 percent

    The bank’s total assets value at the end of June was VND1.4 quadrillion ($60.8 billion), while its loans outstanding were VND1.06 quadrillion, according to its CEO Tran Binh Minh.

    Capital mobilization as of June reached VND1.2 quadrillion, up 3.4 percent year-on-year.

    The bank plans to increase its charter capital by 29 percent to over VND48 trillion this year by paying dividends in shares.

  • Grab Partners NTUC Income to Launch Micro-Insurance Plan

    Grab Partners NTUC Income to Launch Micro-Insurance Plan

    Grab’s insurance arm and NTUC Income jointly unveiled its first micro-insurance plan designed to help drivers better protect themselves against critical illnesses.GrabInsure has launched a flexible pay-per-trip micro premium and accumulative coverage proposition together with local insurer NTUC Income on Thursday. Known as Critical Illness: Pay Per Trip (CIPPT), the microinsurance plan can be subscribed via Grab’s driver-partner app and allows premiums to be deducted from their in-app cash wallet.

    We know many of them (the driver-partners) worry about falling ill, and the corresponding medical costs. They see the value of insurance protection but are hindered by a lack of affordable options that give them the flexibility in premium payment and coverage. Some of them are also discouraged by the application processes of insurance plans, said Yee Wee Tang, Country Head of Grab Singapore in a media statement.

    CIPPT is a critical illness insurance plan that provides Grab driver-partners the option to pay for premiums on a per-trip basis. Unlike typical insurance plans that call for a commitment to a fixed premium amount over a set period, CIPPT offers greater flexibility on cash flows to maintain the plan.

    For as low as S$0.10 per trip completed, Grab driver-partners can accumulate insurance coverage of a Sum Assured of up to S$200,000 for 360 days, in the event that the insured is diagnosed with a critical illness covered under the plan. There is no minimum trip requirement per day and they can work anytime.

    This micro-insurance proposition for critical illness protection is ground-breaking in the way in which it is purchased and where protection is rendered. The option to stack insurance coverage by paying premiums at micro-quantum is an innovative way to offer Grab driver-partners critical illness protection without incurring a substantial outlay from their monthly income. This approach resonates with people who prefer to have flexible cash flows to see to other financial commitments but yet at the same time, want to benefit from insurance protection,» said Peter Tay, NTUC Income’s Chief Digital Officer, who heads the company’s Digital Transformation Office.

    CIPPT is also the latest digital insurance product offered by GrabInsure, after the launch of Personal Accident Plus (PA+) and Prolonged Medical Leave Plus (PML+) insurance plans in April 2019.

    According to the Life Insurance Association Singapore’s Protection Gap Study, only 20 percent of economically active individuals in Singapore are covered for their critical Illnesses.

  • DBS Inks Sustainability-Linked Loan in Indonesia

    DBS Inks Sustainability-Linked Loan in Indonesia

    The export financing sustainability-linked loan is the first of its kind in Indonesia. DBS Bank Indonesia has signed a sustainability-linked export financing loan with wooden door manufacturer PT Sumatera Timberindo Industry (STI), the bank said in a press release on Wednesday.

    DBS said the loan is evaluated based on a target of obtaining timber and raw materials from sources certified by the Forest Stewardship Council (FSC). Its interest rate will be reduced for each shipment of raw material that has an FSC certification that the raw material is responsibly sourced.

    STI is a FSC-certified company focused on responsible sourcing, manufacturing and exporting of sustainable-certified products. According to director Hidayat Ang, STI’s synergies with DBS in advancing sustainability support the company’s long-term growth and empower the local community to do good for the environment.

  • The popularity of online loans has not increased in Singapore

    The popularity of online loans has not increased in Singapore

    Analyzing statistics of search requests, analysts of the company compared trends of demand for online loans in Singapore, Indonesia, Vietnam and the Philippines. The findings show that the situation in Singapore differs from other countries  significantly. The demand in Indonesia, Vietnam and the Philippines demonstrates a clear ascending trend and fast development. However, in Singapore, with low development of online loans issued by alternative lending companies, there is no significant growth of their demand recorded by the systems for search analytics. At the same time, looking at the frequency of the search request of “online credit”, the increase is observed from late 2007 to 2015 and stops afterwards.
    The reason is the faster economic development and dense area of Singapore, as opposed to its multi-island neighbours. Consequently, the country has an advanced financial sector, which is accessible for all residents. Taking into account the general maturity of the digital sphere, it’s obvious that the fintech services started developing here earlier, but within the traditional banking sector.
    The legislative regulation of lending in Singapore also makes an impact. Limited interest rates make it more profitable for alternative lenders to work with the business community. According to the University of Cambridge, in 2017, 99% of issued alternative loans there fell under the business segment. In the Philippines and Vietnam, the situation is opposite: only 7% and 10% of loans respectively accounted for business sector. In Indonesia, the distribution is more balanced: 72% were business loans and 28% – consumer loans.
    Moreover, the demand for online loans is affected by the age of the population. According to the United Nations, the average age of Singaporeans is 40, Filipinos – 24, Indonesians – 28 and Vietnamese  – 30. The young age and lack of access to banking products are the main driver for the development of alternative lending in Indonesia, Vietnam and in the Philippines. This is confirmed by the statistics on 200,000 online loans issued by the companies of Robocash Group in Southeast Asia (the Philippines, Vietnam, Indonesia), where 49.9% of borrowers are under 30.
  • Indonesian Fintech Launches First Debt Services in Malaysia

    Indonesian Fintech Launches First Debt Services in Malaysia

    A fintech specialized in solving debt problems of consumers and business owners has launched its services in Malaysia, a country whose total overdue consumer loans is second highest in Southeast Asia.

    Indonesian Fintech amalan International announced on Wednesday that it has started operations in Malaysia, expanding its footprints in Indonesia and Singapore. In Malaysia, the total balance of overdue or almost overdue consumer loans is estimated to be $15 billion, the second highest in Southeast Asia.

    «In many cases, amalan is able to reduce the outstanding balance and/or the monthly installments by 50 to 90 percent in Indonesia – this would be also our target for our Malaysian clients. We want to offer a fresh start to our clients so that they can build a better financial future,» says amalan’s founder and CEO, Arne Hartmann in a statement to the media.

    amalan says that its key differentiator lies in working for borrowers to find the best solution with their lenders. As a social enterprise, amalan does not ask for upfront fees and instead uses a success fee model where the borrower only needs to pay after a restructuring plan has been agreed. The amount of the success fee is based on the savings generated through the restructuring.

    So far, the fintech said it has restructured more than 1,000 loans with all major banks in Indonesia and saved its clients more than $800,000 in the process.

    For each borrower, a restructuring plan is generated that takes into account all of the borrower’s loans to then reduce the debt balance and the monthly installments to an affordable level. These debt management programs use proprietary data and technology to get the borrowers out of debt faster, paying less.

    amlan Indonesia was selected as one of the 30 best start-ups in MaGIC (Malaysian Global Innovation & Creativity Center), a business accelerator program of the Malaysian government.

  • Vietnam targets credit growth of 14 pct in 2019

    Vietnam targets credit growth of 14 pct in 2019

    The State Bank of Vietnam targets credit growth of 14 percent this year, the same as last year. The focus of new loans would be priority sectors such as manufacturing, agriculture and small and medium enterprises, Nguyen Thi Hong, Deputy Governor of the central bank, said. Credit growth in the Vietnamese banking sector last year was 14 percent, the lowest rate since 2014.

    The figure announced by the State Bank of Vietnam (SBV) Monday was well short of the 17 percent targeted for the year.

    According to officials from the SBV’s Department of Credit for Economic Sectors, lending grew sharply in the early months of the year before tapering off. It was primarily targeted at priority sectors such as manufacturing and processing.

    Credit to the commercial and services sectors saw the highest growth rate, 16 percent. Lending to industry and construction grew by 12.1 percent and to agriculture, by 8.8 percent.

    Overall, interest rates remained steady despite rising interest rates in global markets. In Vietnam, interest rates are commonly around 6-9 percent a year for short-term and 9-11 percent a year for medium and long-term.

    The non-performing loans ratio was down to 1.89 percent from 1.99 percent in 2017 and 2.46 percent in 2016.

  • Credit growth expected to rise 16.33% in 2017

    Credit growth expected to rise 16.33% in 2017

    The total loans of the banking system are expected to grow by 16.33 per cent in 2017 against December last year, lower than the Government’s limit of 18 per cent.

    The State Bank of Viet Nam released the information this week after conducting a survey on business performance trends of credit institutions in the second half of this year.

    The survey also shows that credit institutions forecast the total capital mobilisation of the banking system to rise 16.02 per cent in 2017, of which dong contributes to a rise of 16.59 per cent and foreign currency 1.14 per cent.

    The General Statistics Office (GSO) has reported that credit growth in the first half of this year was 7.54 per cent, the highest in the past six years. The new record, considerably higher than the previous record of 6.28 per cent set in 2015, reflects the market’s significantly improved capacity to absorb capital, the GSO said.

    Loans in the period were mainly focused on prioritised and large projects as instructed by the Government, accounting for roughly 50 per cent of total outstanding loans. Agriculture and rural industries, and small- and medium-sized firms received around 19 per cent and 22 per cent of the total outstanding loans, respectively.

    Lending interest rates were 6-9 per cent per year for short-term loans, and 9-11 per cent per year for medium- and long-term loans. For customers with transparent finances, short-term lending rates ranged from 4-5 per cent per year.

    The banking system’s capital mobilisation in H1 has risen by 5.89 per cent, and deposit interest rates have been relatively stable. Interest rates for dong deposits were 4.5-5.4 per cent per year for short term, 5.4-6.5 per cent per year for medium term, and 6.4-7.2 per cent per year for long-term deposits.

    The Government has targeted credit growth of 18 per cent for 2017, but at the National Assembly meeting recently, some deputies suggested that this limit be raised so as to support economic growth.

    Analysts at Bao Viet Securities (BVS) also recently forecast that the central bank may consider raising credit growth targets for several banks to aid economic growth.

    The Government has been under intense pressure to loosen its monetary policy as the country is determined to meet its GDP growth target of 6.7 per cent for 2017. However, the fiscal policy has been struggling with disbursement of public investment, the BVS analysts said in a report. By end of May, disbursement of public investments had touched VND88 trillion, equal to only 30.6 per cent of the entire year’s estimates.

    The BVS analysts said when fiscal policy does not support growth well, pressure will intensify on monetary policy. Increasing credit growth targets of several banks may be an option worth considering, the analysts said.

  • Crowdo enters Indonesia market

    Crowdo enters Indonesia market

    Crowdo enters Indonesia market

    Home-grown crowdfunding portal Crowdo has expanded to Indonesia to offer peer-to-peer lending to businesses there.

    Crowdo will use its platform to match Indonesian investors with companies there which need loans for working capital.

    Borrowers repay the principal sum with interest.

    Since Crowdo will offer only collateralised loans, the interest borrowers pay is expected to be lower.

    In a pilot run over recent months, 200 companies were successfully funded and recorded no defaults on payments, said a statement from Crowdo.

    The site will go public later this year.

    Crowdo is inviting select investors seeking higher yields with new investment opportunities to participate in these deals.

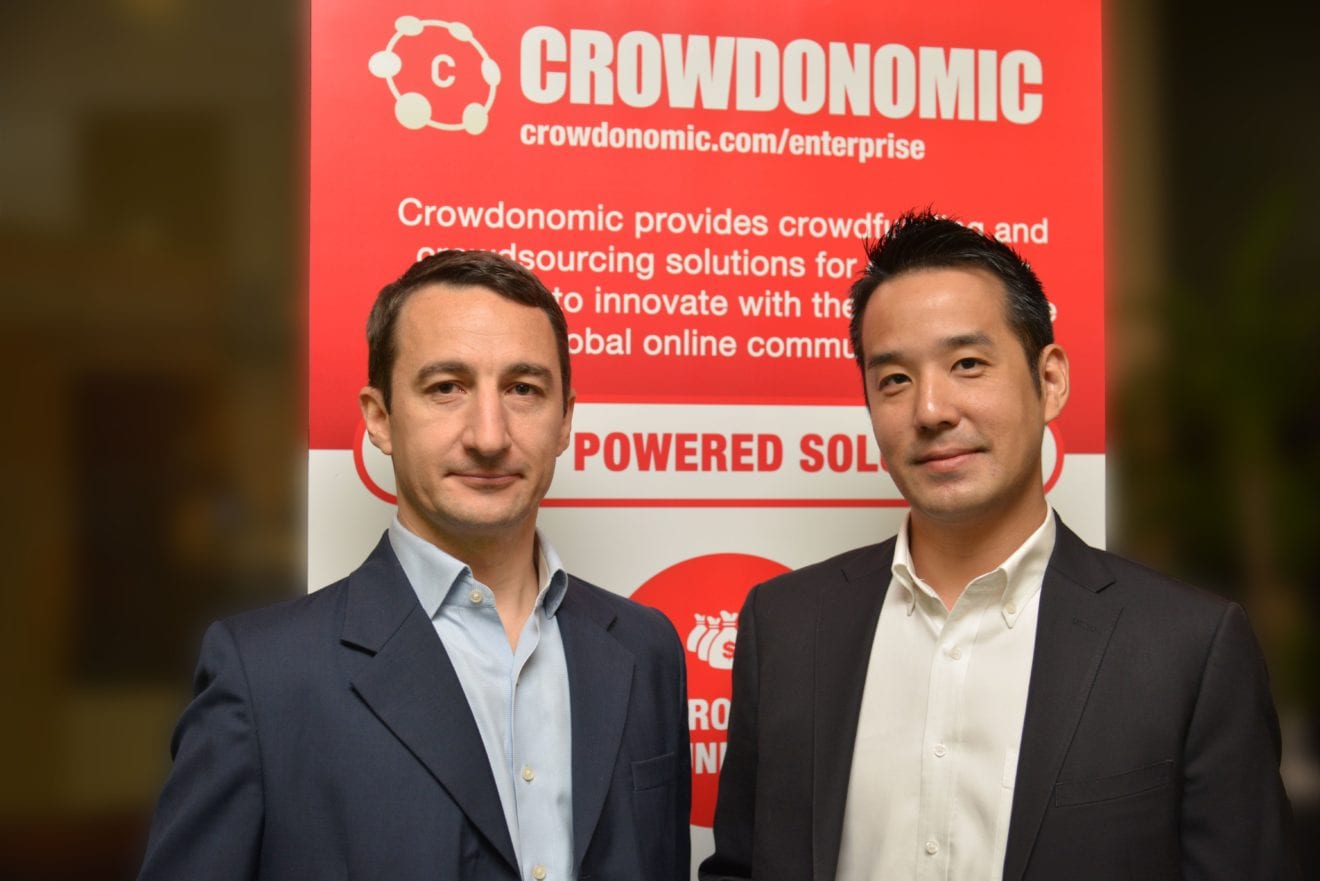
    Co-founder Leo Shimada said: “Our clients have robust businesses with sound repayment capabilities but are unable to access traditional financing systems due to the lack of existing relationships with financial institutions.”

    It is a multibillion-dollar market, he said, as small and medium-sized Indonesian companies are underserved by banks. Last month, Crowdo was licensed by the Malaysian authorities to run an equity-based crowdfunding platform there.

    With its expansion to these two countries, Crowdo, formerly known as Crowdonomic, is the first South-east Asian crowdfunding operator to offer debt-based and equity-based crowdfunding.