Tag: National Australia Bank

  • National Australia Bank to Cut 2,500 Jobs as Lending Slows

    National Australia Bank to Cut 2,500 Jobs as Lending Slows

    National Australia Bank will cut up to 2,500 jobs across its corporate operations in 2027 to lower operating costs as loan demand weakens. The reduction represents roughly 6 percent of the lender’s global workforce.

    Up to 1,500 positions will disappear by the end of 2026. The lender plans to spare customer-facing branch and banking roles while heavily reducing its reliance on outside consultants and contractors.

    The Cost of the Corporate Overhaul

    The restructuring will trigger a pre-tax charge of about A$300 million in 2027. That covers redundancy payouts, redeployment programs, and internal reorganisations. For comparison, pre-tax restructuring charges stood at about A$80 million in each of 2025 and 2026.

    Chief executive officer Andrew Irvine said the changes were aimed at improving productivity, risk outcomes and execution, while making the bank “simpler and more efficient”. NAB reported a total global headcount of 41,880 employees on September 30, 2025.

    Lenders Squeezed by Weakening Loan Demand

    Commercial lenders across Australia face compressed margins as property sales cool and domestic borrowers pull back under elevated borrowing costs. The retrenchment at NAB mirrors steps taken across the Australian financial sector, where institutions are shedding corporate overhead to protect returns on equity.

    Rival ANZ launched its own simplification drive under chief executive Nuno Matos last year, cutting roughly 3,500 roles through September 2026. Both lenders are eliminating administrative layers while trying to preserve frontline lending desks to defend their market share in core commercial accounts.

    Tax Changes and Higher Rates Hurt Housing

    In August, NAB cautioned that residential mortgage growth would decelerate sharply into 2027. Federal property tax revisions reduced buyer appetite, discouraging both owner-occupiers and property investors from taking on new debt.

    Higher domestic cash rates combined with broader geopolitical tensions have created sustained headwinds for retail and business borrowers. Management aims to redeploy cost savings directly into business lending, deposit acquisition, and its proprietary residential mortgage platform.

    Key Targets for the 2027 Deadline

    NAB faces the task of executing the initial 1,500 departures before December 2026 without disrupting risk controls or loan processing times. Progress on contractor reductions and operating expense targets will show in the bank’s upcoming financial disclosures through late 2026.
  • Banks take up Visa Token Service

    Banks take up Visa Token Service

    An extra layer of security for mobile and digital payments has been introduced by Singapore’s United Overseas Bank (UOB) and Australia’s National Australia Bank (NAB).

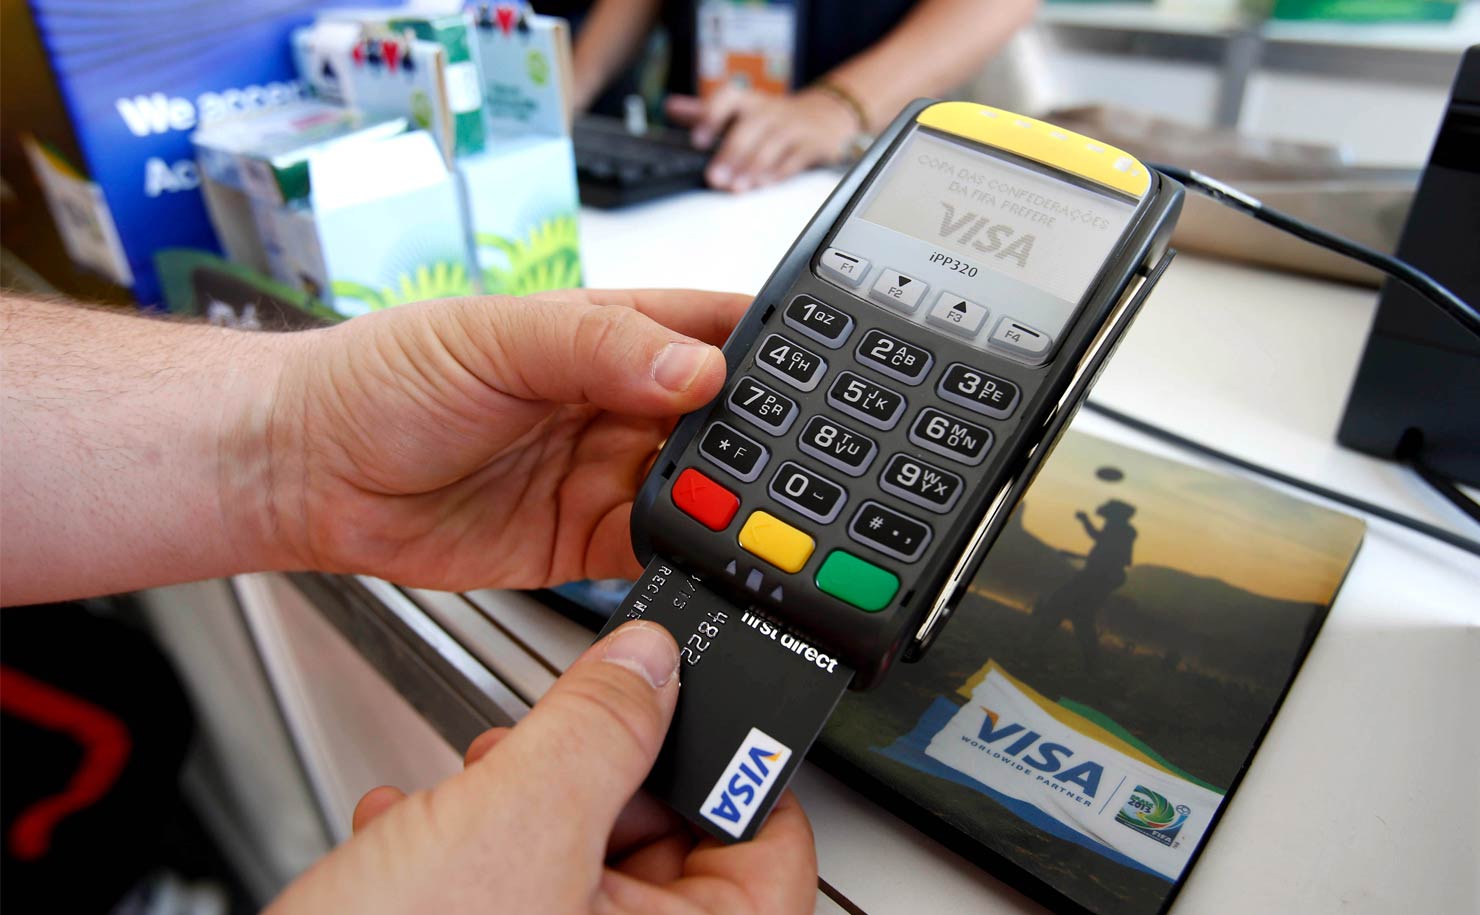
    As well as making transactions safer, the new Visa Token Service also makes instore shopping easier.

    Credit or debit cards are no longer necessary under the Australian bank’s new mobile payment service,NAB Pay, which lets customers use their mobile phone for purchases.

    For UOB customers, the Visa Token Service has been integrated into the UOB Mighty digital wallet. It allows UOB Visa credit or debit card users to make contactless payments via an app on NFC-enabled Android smartphones at selected outlets in Singapore and overseas.

    Visa’s new technology replaces sensitive account information found on payment cards with a unique digital identifier or “token” that does not expose account details during the payment process. Tokenised cards are also domain controlled, meaning they link to the user’s phone or wallet application and are validated in real time by the global payment-processing platform VisaNet.

    Launched in the US, the Visa Token Service is being rolled out in several markets across Asia Pacific over the coming months. As payments shift from plastic to digital, Visa is working with financial institutions, merchants and technology partners to offer consumers a secure and easy way to buy.

    A key benefit of the service is that tokens do not carry the user’s primary account number, so there is less risk of storing them on mobile devices, online (eCommerce merchants) or in cloud-based mobile applications.

    Using ISO standards, the tokens can be processed and routed by merchants, acquirers and issues in the same was a traditional card payments.

    Tokens tied to lost or stolen mobile devices can be instantly reissued, and multiple tokens can be used for a single primary account, each tied to a specific device or service. Tokens can also be exclusive to specific merchants, mobile devices, transactions or transaction categories.

    VisaNet is capable of handling more than 65,000 transaction messages a second, with fraud protection for consumers and assured payment for merchants.