Tag: nielseniq

  • Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan is revamping product development across its beauty and fragrance divisions as weight loss treatments reshape consumer budgets, tracked by 15 generic semaglutide brands entering India since patent expirations began. The ingredient supplier found adult adoption of GLP-1 therapies in the US climbed from 3 per cent in 2024 to 11 per cent in 2026, triggering direct reallocation of discretionary spending.

    Data compiled by the manufacturer from a NielsenIQ Homescan panel revealed American households using the medications increased spending on fine fragrances by 97 per cent while cutting grocery budgets. In Brazil, 47 per cent of buyers reported trimming other expenses specifically to finance treatment doses, signaling a widespread behavioral reallocation away from food toward personal grooming, sports, and travel.

    India Generics Drive Rapid Market Expansion

    Price reductions and the loss of patent exclusivity in markets such as India have dismantled entry barriers for metabolic therapies. The introduction of 15 domestic brands following patent expiries expanded regional supply rapidly, lowering therapy costs and broadening usage beyond narrow clinical segments.

    Lower retail prices combined with the development of oral alternatives to subcutaneous injections are speeding up adoption across emerging economies. For personal care brands operating in Asia, this shift alters the customer base faster than anticipated. Product developers must adjust formulas for consumers managing the physiological consequences of rapid weight reduction.

    Formulations Adapt to Side Effects

    Patients experience specific physiological issues that prompt new topical requirements, notably loss of facial volume, loose skin, barrier dryness, temporary hair thinning, and bad breath. Consumers navigating these side effects prioritize demonstrable performance over brand prestige, checking active concentrations and clinical validation closely.

    Buyers demand formulas that combine medical-grade efficacy with sensory textures. Frédéric Merlin, manager of the Givaudan Digital Factory in Paris, stated: “Faced with these very real concerns, consumers are becoming more demanding: they seek out the right actives, compare concentrations, and check the evidence behind efficacy claims. But they are unwilling to choose between performance and pleasure. They expect visible results, sensorial textures, and an enjoyable experience. Whereas a brand’s reputation may once have been enough to win them over, it is now the efficacy promise, backed by evidence, that makes the difference.”

    Scent Profiles Reflect Appetite Changes

    Social listening data gathered by Givaudan identified two dominant fragrance profiles among treatment users: gourmand compositions and crisp, fresh notes. Appetite suppression does not eliminate interest in rich food-inspired aromas, although nausea risks create sharp aversions to heavy notes, requiring finer calibration by perfumers.

    Energy dips and sleep disruptions linked to these therapies have opened room for functional scents. Givaudan is deploying its patented MoodScentz and DreamScentz platforms, pitching neuro-olfactive formulations that stimulate alertness in the morning or support disrupted sleep cycles at night.

    Digital Factory Tests Commercial Concepts

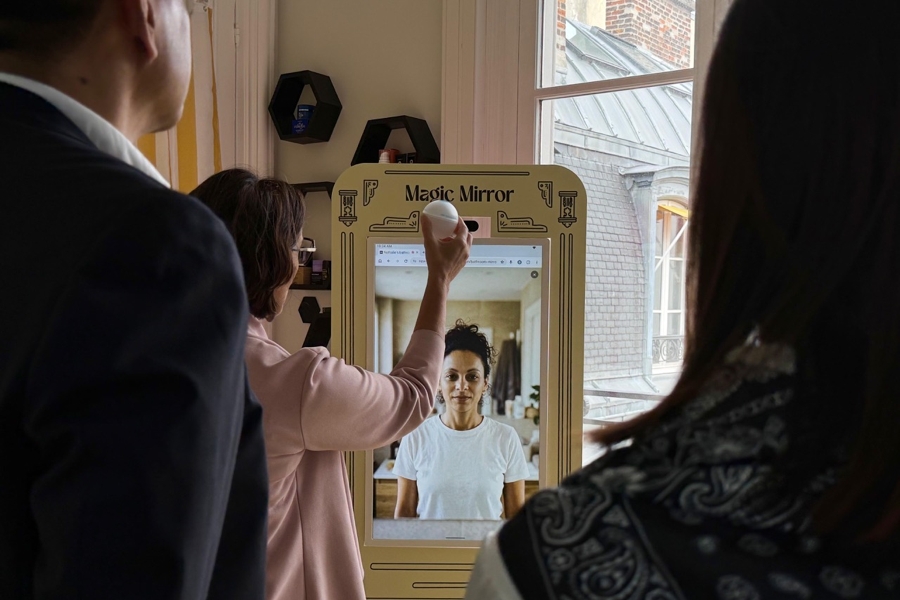
    The company developed an exhibition format called The New Desire at its Paris Digital Factory, built around an artificial intelligence persona named Nathalie to model shifting habits. Brand teams examine over 120 global product rollouts and generate concept packaging tested against simulated consumer feedback.

    Corporate clients have booked repeat sessions at the facility, prompting an operational extension of the program. Fast-moving consumer goods suppliers across the Asia-Pacific region now face parallel realignments on retail shelves: packaged food volumes face headwinds, while functional personal care and premium fragrances capture liberated wallet share.

    Givaudan plans to publish its next wave of field research on GLP-1 olfactory preferences before the end of 2026.
  • Dedicated Men’s Beauty Brands Grew 3% While Wider Market Rose 7%

    Dedicated Men’s Beauty Brands Grew 3% While Wider Market Rose 7%

    Dedicated men’s grooming brands expanded 3 percent globally across 57 countries, trailing the 7 percent growth recorded by the broader beauty and personal care industry, according to retail tracking data from NielsenIQ.

    The divergence emerges despite rising male interest in grooming. In its report The Permission Gap: The Global State of Male Beauty, NielsenIQ found that 36 percent of men say looking their best has become more important to them than five years ago, while 54 percent place greater value on aging well. However, average male household expenditure on personal care remains 28 percent lower than female spending.

    NielsenIQ tracked digital transactions through June 2026 across five European economies, the UK, France, Spain, Italy, and Germany, where men drove approximately 51 percent of online fragrance sales. Tara James Taylor, SVP, Global Beauty Personal Care Vertical at NielsenIQ, noted that brands focusing exclusively on gendered labeling risk missing broader consumer demand.

    India and Emerging Markets Lead Concern Over Appearance

    Attitudes toward personal grooming divide sharply along geographic lines. Concern about personal appearance peaks in developing consumer markets, led by India at 69 percent, Mexico at 63 percent, the United Arab Emirates at 57 percent, and Brazil at 51 percent.

    Developed Western economies register far lower engagement. Only 37 percent of American men, 22 percent of British men, and 17 percent of German men express similar concerns. In Australia, the United States, and Canada, male spending eclipses female spending in only two categories: shaving and fragrance. Across five European markets tracked through June 2026, men accounted for roughly 51 percent of digital fragrance transactions.

    Formulation Replaces Gendered Packaging on Digital Shelves

    Online purchasing data indicates male shoppers actively seek specific treatments rather than gendered marketing. Men increasingly select dermo-cosmetics and Korean beauty brands that emphasize active ingredients and functional outcomes, bypassing products bearing a dedicated male label.

    Sales figures from ten Western European markets reveal dedicated male skincare lines were flat over the past year, while gender-neutral alternatives grew 7 percent. Generational habits reinforce the shift away from conventional branding. Millennial men at 42 percent and Gen Z men at 40 percent view grooming choices as an extension of individual identity, compared to 28 percent of baby boomers.

    Merchandising Risks Mount for Traditional Grooming Brands

    Department stores and health-and-beauty chains face a realigning shelf allocation problem. Brand owners that package identical moisturizer formulas in black or gunmetal-grey bottles risk missing the larger pool of male spenders browsing core skincare fixtures. Retail buyers in Asian hubs who reallocate shelf space from standalone men’s sections to functional K-beauty and clinical ranges stand to capture higher basket values.

    The pressure falls hardest on legacy fast-moving consumer goods suppliers reliant on mass-market men’s ranges. If male consumers continue purchasing active treatments from mainstream skincare fixtures, dedicated sub-brands face diminishing retail footprint and margin compression.

    Brands that focus only on products labeled ‘for men’ may overlook shoppers and opportunities across the wider beauty market

    Tara James Taylor, senior vice president of the global beauty personal care vertical at NielsenIQ, warned that narrow segmentation limits growth.

    Tracking Cross-Category Basket Conversion

    Department store groups and specialty beauty retailers throughout the Asia-Pacific region have spent several fiscal cycles testing segregated male grooming bars versus integrated displays. The latest spending figures provide concrete evidence that floor managers should dismantle isolated men’s corners in favor of functional signage that organizes products by skin concern.

    Retail buyers tracking the sector now look to holiday quarter checkout figures across Asian e-commerce platforms to measure whether male purchasing of ungendered serum and sunscreen lines outpaces traditional male gift sets.

  • China and India Lead Global Quick Commerce with Adoption Past 80 per Cent

    China and India Lead Global Quick Commerce with Adoption Past 80 per Cent

    Quick commerce adoption in China reached 83 per cent and 82 per cent in India, creating a multi-trillion-yuan grocery delivery market that outpaces Western peers. The channel is on track to surpass 1 trillion yuan in China this year, backed by a logistics network that handled 199 billion parcels in 2025.

    Data compiled by consumer intelligence firm NIQ shows ultra-fast delivery has become standard consumer behavior across major Asian economies. The global average adoption rate sits at 48 per cent, dragged down by Western markets where 34 per cent of European shoppers and only 3 per cent of North American consumers use quick commerce platforms.

    India Builds Dark Store Networks

    India represents the fastest-accelerating market for ultra-fast delivery. The sector grew 68 per cent year over year in the fourth quarter of 2025, powered by operators expanding an urban dark-store network projected to exceed 5,000 facilities. Individual micro-fulfillment hubs in the country now process up to 1,800 transactions per day.

    Shoppers in India are also changing how they use the apps. Instead of relying on 10-minute delivery purely for emergency top-ups and late-night snacks, consumers are migrating toward full grocery baskets, driving higher repeat purchase frequencies and larger ticket sizes.

    The structural divergence between Asia and the West comes down to city density, cheap local couriers, and deeply entrenched super-app ecosystems. In China and India, retail platforms solved local delivery economics early by pairing dark stores with dense residential zoning, whereas Western operators struggled with high labor overheads and sprawling suburban delivery routes that broke unit economics after 2022.

    Profitability Lags Channel Expansion

    Surging transaction volumes do not guarantee profitable sales for consumer brands selling through rapid channels. While brand manufacturers allocate an average of 27.4 per cent of their marketing spend to social commerce and related rapid channels, 58 per cent still report a return on investment of less than $1 per dollar spent.

    Growth is accelerating, but sustainable value will come from understanding which consumer missions truly benefit from immediacy.

    Suppliers are now overhauling their inventory allocations to defend margins. The key metric to watch across Asian platforms this year is whether operators can push average order values high enough to offset rising fulfillment costs as dark store networks reach saturation in tier-one cities.