Tag: retirement

  • Malaysia Faces Calls to Raise Retirement Age to 65 as Pension Deficits Grow

    Malaysia Faces Calls to Raise Retirement Age to 65 as Pension Deficits Grow

    Pension advisers and economists in Kuala Lumpur are pushing the government to raise Malaysia’s mandatory retirement age from 60 to 65 through phased adjustments. The current statutory threshold leaves millions of workers exiting the formal labor force with inadequate savings to cover longer lifespans.

    Official data from the Department of Statistics Malaysia released on September 30 shows life expectancy for a newborn in 2026 reached 75.5 years, while residents reaching age 60 are projected to live an additional 20.2 years to 80.2. A retirement age set at 60 requires workers to fund more than two decades of living expenses on savings accumulated over short careers.

    The Proposed Timeline for Phased Retirement

    William Price, chief executive of consultancy D3P Global Pension Consulting, presented a transition framework at the Employees Provident Fund International Social Wellbeing Conference 2026 in Kuala Lumpur. Under his proposal, authorities would add three months of working life for every calendar year, reaching a statutory retirement age of 65 by 2040 without forcing abrupt extensions on staff near departure.

    A worker aged 40 today would retire at 65 under the schedule, while a 50-year-old would work until 62 and a half. Employees aged 59 would take on an additional three months, retiring at 60 years and three months. Price suggested exemptions for manual laborers and low-income staff who entered the formal workforce at age 16, allowing early exit after completing 40 to 45 contribution years.

    Rajen Devadason, a licensed financial planner speaking at the same conference, proposed an accelerated track to lift the threshold by one year every two years. His plan targets a retirement age of 65 by 2035 and 70 by 2050 to keep pace with demographic shifts.

    Depleted Balances at the State Pension Fund

    The push to extend working careers coincides with severe savings shortfalls inside the Employees Provident Fund, which covers more than 18 million members. Figures submitted to parliament reveal that as of May 31, only 38.3 percent of active formal-sector members aged 18 to 60 had accumulated the basic savings benchmark of RM390,000. That baseline is designed to yield a monthly drawdown of RM1,625 over a 20-year retirement.

    Former EPF chief executive Shahril Ridza Ridzuan noted at the conference that low baseline wages prevent households from building assets even when statutory contribution rates remain elevated. Beyond the basic benchmark, the EPF defines adequate savings at RM650,000 and enhanced savings at RM1.3 million, levels out of reach for the vast majority of private sector staff.

    Retaining older staff alters payroll dynamics across retail and service chains that rely on entry-level wages. Companies facing persistent labor shortages in store operations, logistics, and customer support stand to gain experienced personnel, provided contracts offer flexible scheduling such as three-day work weeks.

    Operating Adjustments for Employers and Retailers

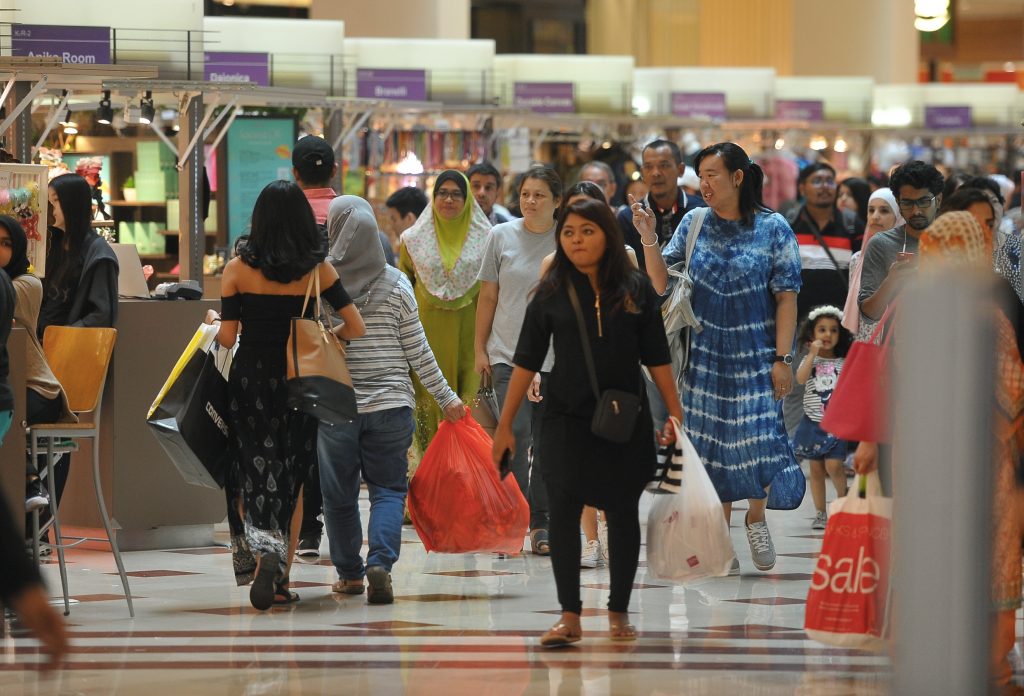
    Consumer spending patterns will shift as older cohorts continue earning regular paychecks into their mid-sixties rather than cutting household budgets at 60. Keeping older workers economically active protects discretionary demand across urban retail centers, dining, and healthcare services that depend on steady domestic consumption.

    The structural risk sits in commercial staffing models and medical insurance costs. Retailers and hospitality groups must restructure compensation from seniority-based pay scales to productivity metrics, ensuring higher minimum ages do not compress hiring budgets for younger entry-level workers.

    Previous statutory changes in Malaysia established the Minimum Retirement Age Act in 2012, which lifted the private-sector retirement baseline from 55 to 60 when it took effect in 2013. The public sector matched that 60-year ceiling, but demographic pressures have intensified as Malaysia transitions toward an aged society status projected by the World Bank.

    Policymakers must now weigh draft amendments to employment statutes against public resistance to delayed access to pension funds. The primary metric to track is whether the human resources ministry tables formal legislation to decouple EPF withdrawal windows from mandatory retirement milestones ahead of the next parliamentary sitting.
  • Singapore’s Affluent Investors Neglect Retirement Plans, Despite Confidence in Financial Future: HSBC Survey

    Singapore’s Affluent Investors Neglect Retirement Plans, Despite Confidence in Financial Future: HSBC Survey

    Affluent investors in Singapore are optimistic about their financial future, though many are overlooking the crucial aspects of retirement and wealth-transfer planning. This is according to recently released data from a survey by HSBC.

    There’s a noticeable contradiction among these investors; despite their confidence in their future financial status, their readiness for significant life-stage events is still lacking. HSBC’s Global Affluent Investor Snapshot 2026 reveals that a mere 20% of affluent investors in Singapore currently utilize retirement-planning services. Even fewer, just 9%, use wealth-transfer planning services, despite both being high on their list of financial priorities.

    Opportunities for Private Banks and Wealth Managers

    The survey’s findings indicate a sizable opportunity for private banks, wealth managers, and family-office advisors. This comes as Singapore’s wealthy population expands and the complexity of portfolios increases.

    The trend of international diversification is being led by younger investors. More than half (55%) of affluent Gen Z investors in Singapore prefer investing outside their home market. This surpasses both the average of 50% for Singapore and the global Gen Z average of 49%.

    However, the confidence of Gen Z investors has significantly declined. This is especially apparent in their medium-term financial goals, with confidence dropping from 73% the previous year to just 48%. HSBC reports that despite this decline, the younger generation remains strongly focused on wealth creation and financial security. The rising market uncertainty seems to be impacting their expectations.

    Investor Confidence Remains Robust

    Despite these concerns, the overall investor sentiment in Singapore is still strong. Confidence in achieving short-term financial goals increased to 78%, while faith in medium- and long-term goals reached 63% and 65% respectively. Retirement planning, wealth preservation and financial security continue to be high priorities for affluent investors.

    International diversification continues to be a crucial strategy. Half of Singapore’s affluent investors are now looking for investment opportunities beyond their domestic market, which is above the global average of 47%.

    Increasing Demand for Diverse Investment Products

    The study also points to a growing demand for a wider variety of investment products. Across the globe, investors plan to raise allocations to insurance products, alternatives and gold over the next year. Ownership of insurance products is anticipated to rise from 39% to 57%, and alternative investments could increase from 27% to 44%. Interest in gold is also on the rise.

    Younger investors are projected to be the main drivers of demand for alternative investments, private equity, and digital assets. Ashmita Acharya, Head of International Wealth and Premier Banking at HSBC Singapore, says the findings underline the necessity for more comprehensive wealth-planning solutions.

    She points out that as portfolios become increasingly international and diversified in nature, many investors are finding it challenging to turn financial ambitions into actionable plans.

    Questions & Answers

    Why are affluent investors in Singapore overlooking retirement and wealth-transfer planning?
    The exact reasons vary, but one possible explanation could be the lack of awareness or understanding of the importance of these financial planning aspects.

    What is the significance of the growing trend towards international diversification among Singapore’s investors?
    This trend indicates that Singapore’s investors are seeking to spread their investments geographically to mitigate risk and potentially take advantage of higher returns in other markets.

    How are financial institutions responding to the growing demand for a broader range of investment products?
    Financial institutions are increasingly offering more diverse and sophisticated products to meet the evolving demands of their clients, including alternative investments and digital assets.

  • Singapore’s Pension System Clinches Top Grade In Global Index, First In Asia-pacific Region

    Singapore’s Pension System Clinches Top Grade In Global Index, First In Asia-pacific Region

    The Central Provident Fund (CPF) of Singapore has been recognized as the leading pension system in the Asia-Pacific region, achieving an unprecedented A grade in a global index. This milestone marks Singapore as the first in the region to receive such a high grade.

    Singapore’s pension system has seen constant improvement since 2009 when it was rated a C, advancing to a B+ in 2023, and finally securing its first-ever A grade in the annual Mercer CFA Institute Global Pension Index. Owing to this breakthrough, Singapore now belongs in the upper echelons of the 2025 ranking alongside the Netherlands, Iceland, Denmark, and Israel.

    The Global Pension Index measures 52 retirement income systems worldwide across more than 50 indicators organized into three essential pillars: adequacy, sustainability, and integrity. Adequacy assesses whether a system can provide sufficient income to maintain a decent living standard; sustainability gauges the system’s long-term ability to fulfill future commitments, and integrity measures trust in the system.

    Singapore’s pension structure hinges on the CPF, a system that encompasses all employed citizens and permanent residents through compulsory contributions from both workers and employers.

    In the latest ranking, Singapore achieved a score of 80.8, the highest in Asia and the fourth highest globally, signifying a considerable upgrade. Notably, no systems experienced a downgrade this year.

    The enhancement in Singapore’s position was primarily due to improved outcomes in sustainability and integrity, which balanced a minor decrease in adequacy. Tim Jenkins, the report’s primary author, noted that Singapore authorities have made substantial efforts to boost transparency in recent years. This enables citizens to have a clearer understanding of their anticipated retirement disbursements.

    He also pointed out the contribution of Singapore’s economy towards achieving this feat. The long-term economic growth has positively impacted the sustainability metric.

    Within the Asia-Pacific region, Australia’s retirement system ranked second with a score of 77.6, followed by Hong Kong at 70.6. Other Southeast Asian countries listed in the ranking included Malaysia (60.6), Vietnam (53.7), Indonesia (51.0), Thailand (50.6) and the Philippines (47.1).

    Interestingly, Hong Kong and Malaysia saw improvements in their systems, moving up to B and C+ grades, respectively.

    Globally, the Netherlands, Iceland, and Denmark continued to spearhead the index with scores of 85.4, 84.0, and 82.3, respectively.

    Questions & Answers

    What grade did Singapore’s Central Provident Fund (CPF) achieve in the Global Pension Index?
    The CPF achieved an A grade, making it the highest-rated pension system in the Asia-Pacific region.

    How does the Global Pension Index assess retirement income systems?
    The Global Pension Index measures retirement income systems using more than 50 indicators organized into three pillars: adequacy, sustainability, and integrity.

    What other countries ranked high in the Global Pension Index?
    Other top-ranking countries include the Netherlands, Iceland, Denmark, and Israel.

  • After 22 Years in Gold Investing, I Embrace Early Retirement

    After 22 Years in Gold Investing, I Embrace Early Retirement

    In a thriving local economy, a young professional reflects on a family tradition of prudent investments in gold and real estate, highlighting the power of strategic financial planning for future generations.

    The Smart Start to a Promising Career

    After graduating with a degree, I set my sights on landing a job with two promising companies: one based in Taiwan and the other in Japan. With limited practical experience, I was thrilled to receive production manager offers from both companies. The opportunity came with a supportive work environment and a salary that outpaced my fellow graduates, setting the stage for future financial growth.

    Building Wealth: The Family Tradition of Gold Investment

    With my first salary, I chose to invest in my family’s time-honored practice of buying gold. My mother managed the finances, using my earnings to purchase small amounts of gold each month—ranging from a few taels to a fraction of a tael (1 tael = 37.5 grams or 1.2 ounces) based on our budget.

    As savings grew, my mother seized the opportunity to buy a 300-square-meter plot of land on the outskirts of Ho Chi Minh City for just a few million dong (around US$384.62 at the time). She promised that this property would pave the way for my future when I eventually marry. Today, that land’s value has skyrocketed into the billions of dong, showcasing the immense potential of long-term investments.

    A Legacy of Financial Wisdom

    My parents often remind me of the saying, “Many a little makes a mickle,” reflecting their risk-averse nature. Over the years, they consistently turned to gold as a secure investment. Their approach was simple yet effective: while land appreciates, gold’s rarity makes it a stable asset.

    They adeptly navigated the real estate market, selling gold to buy homes and land when prices were favorable, and then converting those properties back into gold when the market suited them. Now, as gold prices soar, our family is well-positioned to reap the benefits of those decades of dedication. The freedom to sell gold when needed affords us options, whether it’s acquiring a new home, purchasing a vehicle, or traveling.

    Different Paths: A Tale of Choices

    In contrast to my family’s investment approach, a friend—earning a similar salary—spends freely on indulgences like alcohol and karaoke. This friend continues to live at home, while I find myself on the brink of early retirement, thanks to our family’s strategic decisions.

    Conclusion: The Ripple Effect in Retail and Real Estate

    The success seen in my family’s investment strategy echoes broader consumer trends in the retail sector. As more individuals lean towards conservative investments like gold and real estate, the potential for economic shifts builds. This growing inclination towards thoughtful financial planning not only benefits individuals but could lead to enhanced stability in the retail landscape, influencing how brands expand and connect with consumers.

    The opinions expressed are based on personal experiences and do not necessarily reflect the views of VnExpress.

  • Indonesia raises retirement age to 59

    Indonesia raises retirement age to 59

    Indonesia will raise the retirement age for workers to 59, effective this year, in accordance with a government regulation on the Implementation of the Pension Guarantee Program.

    A regulation issued in 2015 set the retirement age at 56, with a provision for gradual increases. Starting Jan. 1, 2019, the retirement age was raised to 57, with plans for it to increase by one year every three years until reaching a maximum of 65.

    As outlined by the regulation, the retirement age will increase to 59 beginning in January 2025 and remain in effect until 2028.

    The updated retirement age also serves as a reference for workers registered with the Employment Social Security Administration Agency (BPJS TK) to claim their pension benefits.

    The gradual increase reflects Indonesia’s efforts to address demographic and economic changes, ensuring the sustainability of the pension system while promoting the financial security of the country’s aging workforce.

  • StanChart Partners Templeton for Retirement Planning App

    StanChart Partners Templeton for Retirement Planning App

    Available on Google Play and Apple’s App Store, «Autumn» integrates wellness with wealth management on an independent and bank agnostic platform.

    SC Ventures, the innovation and ventures unit of Standard Chartered, has launched «Autumn», a digital wealth, health, and lifestyle solution that provides users with tools, products, and services to plan and manage their financial and physical wellbeing.

    As a strategic partner, Franklin Templeton will provide users with access to financial literacy content and investment insights, which can be customized based on risk profile and financial data. Autumn will also be bringing lifestyle partners on board, including travel services and volunteering opportunities.

    Standard Chartered highlighted that 15 percent of Asia’s population will be over the age of 65 by 2040, citing UN data, and the need for a bundled offering to address all their needs in a holistic and personalized manner.

    By combining digital wealth technology with health, lifestyle, and financial wellness, we’ll help users adopt healthier habits and create a retirement that is personalized for them, Mike Kruger, Autumn CEO, said in the announcement.

    Banks have been quick to capitalize on Asia’s greying population and heightened interest in wealth planning. Launches of similar platforms this year have included Julius Baer, which launched its digital wealth advisory platform in Asia in April, while DBS also rolled out a personal digital advisory to its financial planner.

    Standard Chartered itself debuted a free, do-it-yourself online financial planning app this year.

    Autumn is now available in Singapore, with plans underway to roll out the platform progressively in Hong Kong and other markets in Asia, Standard Chartered said.

  • DBS Chief Information Officer Retires

    DBS Chief Information Officer Retires

    DBS’ Chief Information Officer and Head Of Group Technology and Operations, is leaving the bank.  DBS has confirmed that its group head of technology and operations David Gledhill is departing effective from 1 August. He will return to the United Kingdom, according to his announcement on LinkedIn. The 57-year-old is a British citizen calls his departure a soft Glexit.

    After 29 years in Asia and 11 years at DBS, we decided it’s finally time to move on and replant our roots back in the U.K. So, after almost two years of planning, today we announced my retirement from DBS, and the Packers moved in at home,» Gledhill said in a LinkedIn post.

    Gledhill said he will stay connected with DBS in a part-time advisory role. Also an independent director with Singapore Airlines, Gledhill said he will also be back in Singapore every three months. Before joining DBS in 2008, Gledhill worked at J.P. Morgan for 20 years, holding senior regional positions in technology and operations.

    A DBS spokesperson said that Gledhill has been a leading figure in the bank’s transformation. He has been responsible for standardizing the bank’s systems, creating reliability and resilience, and most recently, taking DBS down the path of agile and cloud.

    Gledhill will be succeeded by Jimmy Ng, who has been deputy group head of technology and operations at DBS since January 2018. Having joined DBS in 2009, Ng started his career briefly as a system analyst in Singtel before joining the technology audit function in J.P. Morgan.

    He subsequently worked in various functions including operations, risk management and product control at ABN Amro.

  • Hong Kong’s millennials plan for retirement earlier than anybody else in Asia

    Hong Kong’s millennials plan for retirement earlier than anybody else in Asia

    Many see Hong Kong millennials as living from paycheck to paycheck and not committing to a long-term plan – but they actually lead their Asian peers in retirement planning, according to new research from BlackRock, the world’s biggest asset manager.

    Four out of five Hong Kong millennials (aged between 25 to 35) have already started preparing for retirement, the highest ratio across Asia-Pacific, with a majority of them betting their financial future on buying stocks, the study shows.

    The young Hongkongers’ high proclivity for retirement savings is against the backdrop of notoriously high living costs in the city and escalating global economic uncertainties, noted the report, which polled 28,000 investors across the world.

    “These findings are contrary to the common view that the city’s millennials would rather splurge on holidays and nice food than save for their long-term future,” said Julia Lee, BlackRock’s head of Hong Kong retail business.

    The study found that 81 per cent of Hongkongers aged between 25 to 35 said they had already begun retirement planning, compared with 69 per cent for their Asia-Pacific peers.

    They are also much more likely to take risks, with more than two thirds pouring money into equities in their investment portfolios, whereas only 42 per cent of their regional counterparts would do the same.

    Hong Kong runs a Mandatory Provident Fund (the MPF), a compulsory pension fund for residents with employees and employers required to contribute monthly.

    “The MPF scheme is good, while we also see local people’s need to achieve good returns from their personal financial investments,” Damien Mooney, BlackRock’s head of retail business for Asia-Pacific, said.

    Hongkongers have the world’s longest life expectancy, thanks to low smoking rates, with the average lifespan for women 87 years, and men 81 years, according to data released by Japan’s health and welfare ministry.

    The average retirement age is 58, meaning residents can be faced with over two decades relying on their savings, in what consistently ranks as one of the world’s most expensive cities to live.

    The BlackRock figures showed 86 per cent of Hong Kong investors, aged between 26-74, had managed to set money aside for retirement, and more are reducing their exposure to cash in the low interest rate environment. In spite of their high awareness, fewer than a half said they were confident in achieving their expected retirement income.

    The MPF delivered its best first-quarter results this year since 2013 with an average gain of 5.89 per cent, but it still lost out to pure stock market investment. For the same period, Hong Kong’s benchmark Hang Seng Index rose 10 per cent.

    That might help to explain why 49 per cent of Hong Kong investors polled by BlackRock said they preferred to buy dividend-bearing stocks, the most favourable asset class over real estate, government bonds and funds.

    When making investment decisions, the majority still rely on advice from online sources, including social media and websites of brokers and asset managers, instead of professional financial advisors that usually come with much higher charges.