Blog

  • Asian E-Commerce Dominates Global Sales as China Hits 13 Trillion Yuan

    Asian E-Commerce Dominates Global Sales as China Hits 13 Trillion Yuan

    China recorded 13.09 trillion yuan in online retail sales of physical goods in 2025, cementing its position as the world’s largest digital market at roughly $1.82 trillion. Physical goods accounted for 26.1 percent of total national consumer retail spending, expanding 5.2 percent year on year.

    Total online transactions across China reached 15.97 trillion yuan when including digital products and consumer services. That scale leaves the world’s next largest digital economy, the United States at $1.23 trillion, well behind in overall volume.

    Asian Markets Pull Away in Scale and Growth

    South Korea generated 272 trillion won, or about $191 billion, across digital checkouts in 2025. Services comprised a heavy portion of that total, with food delivery contributing 15.3 percent and travel and transport booking taking 12.5 percent, leaving physical goods at less than $140 billion.

    Japan generated 15.2 trillion yen, roughly $100 billion, in physical product sales online during 2024. That represented 9.8 percent of all Japanese merchandise sales, up from 9.4 percent a year earlier. Digital services and media expanded total Japanese consumer e-commerce to 26.1 trillion yen.

    India expanded faster than any of the mature East Asian retail hubs. Indian e-retail sales jumped roughly 20 percent to reach between $65 billion and $66 billion in 2025, driven by an online shopping pool that reached up to 300 million people.

    Southeast Asian Platform Volumes Climb 20 Percent

    Southeast Asia reached $191 billion across ten regional markets in 2025, according to e-Conomy SEA data. The six largest economies in the bloc generated $188 billion in gross merchandise value, up 20 percent on the previous year.

    Indonesia led the Association of Southeast Asian Nations with $71 billion in digital platform sales. Thailand posted $33 billion, while Vietnam booked $25 billion in gross merchandise volume. The Philippines and Malaysia followed with $24 billion and $20 billion, respectively.

    Fast logistics formats are accelerating that uptake across developing Asian retail markets. Quick-commerce operators promising deliveries under 30 minutes captured between 16 percent and 17 percent of all e-retail volume across India in 2025. Video-led selling channels similarly represented a quarter of all Southeast Asian digital transactions.

    The Balance Between Phone Checkouts and Store Networks

    Mobile checkouts dominate customer habits throughout the Asia-Pacific territory. South Korean shoppers conducted 211 trillion won of their purchases on mobile phones in 2025, securing a 77.6 percent smartphone share of total online retail spending.

    Japan saw smartphone orders for physical products climb 9.0 percent in 2024, advancing at more than double the pace of overall online merchandise turnover. Globally, mobile devices generate roughly 60 percent of online shopping turnover, creating sharper operational demands on checkout speeds and payment gateways.

    Physical store operators throughout Asia face diverging challenges depending on local channel maturity. In markets such as China and South Korea, where digital penetration sits near saturation, merchant acquisition costs are rising as brands shift budget toward buyer retention and targeted messaging. In India, where online transactions represent only 6 to 6.5 percent of gross retail receipts, traditional distribution networks retain considerable running room.

    Maturing Curves Reshape Capital Allocations

    Western benchmark markets illustrate the saturation ceilings facing Asian retailers. British online sales peaked at 30.7 percent during pandemic disruptions in 2021 before settling between 26.6 percent and 27.5 percent through 2025, suggesting a structural resistance band for pureplay e-commerce penetration.

    Chinese expansion rates reflect a similar cooling trend. Physical goods sales online across China grew 4.3 percent during the first eight months of 2026, moderating after a 5.2 percent rise in 2025. South Korean digital expansion dropped to 4.9 percent in 2025, marking the slowest annual increase recorded since current national accounting began in 2017.

    Regional platform operators now look toward second-tier cities and automated fulfillment to maintain transaction momentum. Projections from Bain and Flipkart place Indian online retail penetration at 10 to 12 percent of gross consumer spending by 2030, targeting a total market size between $170 billion and $180 billion.
  • Striding AI Unveils Two Retail Robots Reaching 99% Autonomy

    Striding AI Unveils Two Retail Robots Reaching 99% Autonomy

    Striding AI unveiled two store-floor robots and an orchestration platform in Singapore on October 8, 2026, targeting autonomous overnight restocking and customer service for 24-hour retail chains.

    Founder and CEO Song Yao introduced the setup at APRCE 2026, where the company reported the system completes up to 99 percent of retail tasks autonomously.

    The suite combines the C1 mobile manipulator with the H1 humanoid robot, designed to automate shelf replenishment, inventory checks, carrying, and patrols while operating in narrow aisles without extensive store modifications.

    The C1 mobile manipulator navigates tight spaces on an omnidirectional chassis with an operational reach spanning 100 mm to over 1,750 mm. Front and rear depth sensors, 360-degree vision, and emergency braking for obstacles detected within 30 cm support safe navigation around shoppers.

    Working alongside it, the H1 humanoid robot handles customer greetings and guidance using multimodal interaction across more than 20 languages, 45 facial expressions, and 36 gestures, supported by open APIs for retailer integration.

    Latent Action Models in Store Aisles

    Both machines operate through Striding AI’s SLM-0.5 latent world action model, which computes decisions in latent space rather than relying on pixel-by-pixel prediction. Under reported evaluation settings, the system achieves 187 ms latency per action chunk, delivering a 98.6% success rate on LIBERO and 91.22% on RoboTwin.

    Real-world operations feed back into a reinforcement learning framework called STEAM, designed to refine operational policies from physical floor experience. Coordinating the fleet is the M1 management platform, which uses edge autonomy so core navigation, task execution, and grasping continue without continuous network connectivity.

    Replacing the Graveyard Shift

    For convenience store operators, late-night staffing remains a demanding operational hurdle. Robots can undertake repetitive overnight work, reducing late-night employee shifts while sustaining 24/7 store operations.

    Deployments are designed to adapt to existing store layouts, workflows, and operating conditions, minimizing remodeling requirements subject to site-specific assessments. As Song Yao noted: “Retail is one of the most complex and dynamic environments for robots to operate in, with diverse products, changing workflows, and frequent human interaction. By bringing Physical AI into real retail environments, we can continuously learn from deployment and turn real-world experience into more capable robotic systems.”

    Expanding to Kitchen Tasks

    Founded in 2026, Striding AI maintains operations across Singapore, Tokyo, Beijing, and Shanghai. Its full-stack team spans foundation models, embodied agents, motion control, embedded software, and humanoid design.

    The company plans to validate the system with global retail chains across hot-food preparation, inventory management, delivery sorting, and packaging before opening commercial services in 2027 through direct purchase or Robotics-as-a-Service subscriptions.

    Striding AI also plans to expand its lineup with heavy-duty models and the A1 precision-manipulation robot for checkout and bagging.

  • Jio Platforms Reaches Fourfold Bookings in $3.2 Billion Mumbai Offering

    Jio Platforms Reaches Fourfold Bookings in $3.2 Billion Mumbai Offering

    Investors placed orders for more than four times the available shares in the US$3.2 billion initial public offering of Jio Platforms on its second day of bidding in Mumbai.

    Retail investors absorbed their full reserved portion inside the first two hours of trade on Thursday, booking 1.29 times the shares set aside for them.

    The listing gives Jio Platforms an equity valuation of up to US$108.3 billion. Institutional investors led the order book earlier in the week, with qualified institutional buyers bidding 9.78 times their allocation by the close of the second day, according to exchange data. The transaction represents the first public share sale from parent Reliance Industries in two decades, ranking as the largest equity offering ever mounted in India.

    Institutional Demand Sets Fast Pace

    Bidding dynamics broke normal patterns for large Indian initial offerings, where institutional buyers typically wait until the final afternoon to commit capital. The overall offering was filled within 90 minutes of opening on the first day, driven by institutions that snapped up their portion within minutes. Demand then spread into the retail tranche, which accounts for approximately one third of the total offering.

    Akash Ambani leads the telecoms business, which generates roughly 90 per cent of total revenue across Jio Platforms. The enterprise expanded on a simple business premise initiated in 2016: give away voice calls, discount wireless data sharply, and force rival networks into retreat. That playbook stripped millions of users away from incumbent operators Bharti Airtel and Vodafone Idea. Jio now counts more than 500 million subscribers, trailing only China Mobile among single-country network operators worldwide.

    Consumer Cash Flows Fund Network Upgrade

    For consumer-facing brands and digital retailers in India, the transaction secures the capital base of the country’s most pervasive digital gateway. Jio Platforms bundles high-speed connectivity with digital payments, cloud hosting, streaming, and retail interfaces. Controlling that digital pipeline gives Reliance use over consumer touchpoints that pure-play retailers and internet startups cannot match.

    The core operating risk rests on business mix. While parent Reliance Industries markets Jio as a digital and artificial intelligence platform, telecoms access fees still provide nine out of every ten dollars entering the business. Expanding into home broadband, 5G services, and cloud products requires sustained capital deployment, exposing the business to prolonged payback cycles if monetisation beyond connectivity lags expectations.

    Building the Conglomerate Consumer Arm

    Reliance chairman Mukesh Ambani flagged the public share sale in June, framing the listing as part of a transformation from refining and chemicals manufacturing toward a consumer, retail, and tech conglomerate. Shares of parent company Reliance Industries have appreciated roughly 330-fold on the Mumbai exchange since 1990, establishing the group as a core holding for domestic retail accounts.

    Public bidding runs through a three-day window before closing. Unconditional trading in Jio Platforms shares is scheduled to start on October 28 in Mumbai, where the market will price the company directly against India’s highest-capitalised corporate listings.

  • Thailand AI Token Usage Jumps 30-Fold as Retail Deployments Expand

    Thailand AI Token Usage Jumps 30-Fold as Retail Deployments Expand

    Enterprise cloud providers are shifting artificial intelligence deployments across Thailand from internal testing into commercial networks, targeting cost reductions across roughly 19,000 retail storefronts run by Charoen Pokphand Group.

    Thai consumption of AI tokens jumped about 30-fold between January and September this year, yet only 12.4 per cent of the domestic working-age population uses the software regularly, compared with 60 per cent in Singapore.

    The data emerged during the CP Innovation Exposition 2026, where cloud vendors framed the gap between raw compute consumption and everyday workplace adoption as the next commercial hurdle for enterprise software in Southeast Asia.

    Agentic Commerce and Store Operations

    Alibaba Cloud operates two data centres in Bangkok and coordinates domestic compute with CP Group through True IDC. The infrastructure footprint gives the Chinese technology vendor direct access to CP Group’s extensive physical footprint, spanning convenience retail, wholesale distribution, and commercial groceries.

    Andy Lee, vice-president for international business and general manager for Southeast Asia at Alibaba Cloud, pointed to agentic commerce as the operating model designed to monetize that footprint. Under this framework, autonomous software agents evaluate competing vendor catalogs, run product searches, and settle transactions on behalf of individual shoppers.

    The projected scale is substantial. Lee cited industry projections indicating agent-driven commerce could reach US$3 trillion to US$5 trillion worldwide by 2030, transforming routine consumer purchasing into automated machine-to-machine procurement.

    Alibaba Cloud is pairing that consumer pitch with back-office energy management. The company reported that its AI Energy Expert system delivered power reductions of up to 15 per cent at Bangkok Hospital, offering a demonstrable cost return that retail landlords and hypermarket chains want to replicate across chilled logistics and store lighting.

    The Cost Trap of Compute

    Running autonomous agents at scale introduces severe operational friction. Global cloud providers warned that early adopters risk wasting capital if automation simply quickens legacy administrative work without yielding commercial revenue.

    Olivier Klein, chief technologist for Asia-Pacific and Japan at Amazon Web Services, warned that companies risk landing in an efficiency trap when they use automation solely to speed up existing routines without plowing efficiency gains into customer-facing innovations.

    Cutting entry-level staff creates immediate operational vulnerabilities for retail operators. Klein pointed out that while software lets enterprises expand departmental throughput without hiring extra workers, shrinking junior roles strips companies of their long-term talent bench. Human workers must instead supervise automated pipelines and vet software outputs.

    Mark Souza, chief technology officer at Microsoft Asia, described this emerging organizational structure as a frontier firm where staff function as agent bosses. Human employees assign workflows, oversee output quality, and set legal parameters while algorithmic agents execute multistep analytical processes.

    Controlling infrastructure expenses dictates whether these agent fleets make economic sense. Token pricing fluctuates based on model depth and output requirements. Businesses can control costs by selecting appropriate models, reusing previously processed information, and monitoring usage, Souza said.

    Sovereign Data and Enterprise Models

    Huawei Technologies is pitching open architectures to counter Western enterprise lock-in across Southeast Asia. Vincent Liu, vice-president of Huawei’s ICT Business Group, argued that commercial gains depend on anchoring open-source base models to localized enterprise data rather than relying purely on proprietary overseas software.

    Huawei estimates this localized approach cuts model scaling costs by nearly 50 per cent. Liu identified manufacturing, finance, government, and healthcare as sectors where broader deployment could convert physical data centre investments into measurable national productivity growth.

    The read-across for regional retailers is direct. Southeast Asian retail conglomerates run thin margins and cannot absorb speculative software licenses. CP Group and regional peers are under pressure to demonstrate that algorithmic supply chains yield tangible gross margin improvements rather than just server bills.

    Enterprise software suppliers must now show that AI agents can balance store-level inventory, prevent shrinkage, and drive direct basket sizes across brick-and-mortar locations. Compute providers that fail to link agent performance to store cash flow will face enterprise spending pushback across ASEAN.

  • Pakistan Construction Growth Surges to 19.2% as Subsidised Loans Spur Housing

    Pakistan Construction Growth Surges to 19.2% as Subsidised Loans Spur Housing

    Pakistan’s construction sector reached 19.2 per cent growth in the first quarter of FY26, rebounding from a negative 3.3 per cent reading recorded in the first quarter of FY25, according to State Bank of Pakistan data. Builders credit the turnaround to a surge in domestic liquidity following the introduction of a federal housing scheme and declining capital outflows to Dubai.

    Hassan Bakhshi, chairman of the Association of Builders and Developers (Abad), noted that middle-class buyers who were previously priced out have returned to the market. This renewed purchasing activity has enabled builders across urban centres to recover capital that had remained locked in unbooked apartments.

    The growth comes despite strict lending constraints from commercial banks, which continue to withhold financing from applicants who lack full documentation or proper approvals from the Sindh Building Control Authority. Even with these documentation hurdles, the State Bank reported that construction expanded 14.6 per cent in the first half of FY26.

    Financing Terms Clear Stalled Inventories

    The state-backed Ghar Ho Tu Apna programme rolled out in September last year to offer loans capped at Rs10 million on extended instalment structures. Markup subsidies absorb borrowing costs above the baseline rate to pull middle-income buyers into the market.

    Property firms used the influx of bank liquidity to recover capital locked in unbooked apartments. Hassan Bakhshi, chairman of the Association of Builders and Developers, confirmed that the release of purchasing funds allowed builders to restart stalled balance sheets across major urban centres.

    Commercial banks continue to enforce strict paperwork requirements, rejecting applications lacking formal clearance from agencies such as the Sindh Building Control Authority. Most self-built residential developments fail those compliance hurdles, keeping retail lending volumes below developer expectations despite broader sector gains.

    Capital Shifts from Dubai Drive Karachi Land Values

    Regional instability, including military conflict involving the United States and Iran, halted retail investment outflows from Pakistan into Dubai real estate. Domestic investors redirected liquidity into home markets, triggering sharp price jumps in prime Karachi neighbourhoods.

    Defence Society property valuations climbed as much as 60 per cent during the initial capital flight before settling. The market underwent a 20 per cent price correction over the past month as initial transaction spikes normalised.

    For retailers, materials suppliers and real estate operators, the shift re-establishes Karachi as the primary repository for private wealth during Gulf market downturns. The domestic concentration of funds provides steady consumer liquidity for local retail developers, even as general inflation strains lower-income households.

    Infrastructure Budgets Accelerate Allied Trades

    Development momentum also stems from central government infrastructure spending. Public Sector Development Programme outlays grew 41.8 per cent during the first half of fiscal 2026, bouncing back from a 1.1 per cent contraction during the prior comparative period.

    Building materials pricing remains disputed between suppliers and contractors. While official figures point to falling wholesale material rates, developer groups maintain that actual project input costs remain historically elevated.

    The broader market faces a nationwide structural shortfall of 10 million housing units, with 48 per cent of the domestic population living below the poverty line. Bank mortgage compliance rates under the 5 per cent financing facility remain the immediate metric to watch as secondary city developers prepare second-half unit releases.

  • Louis Vuitton Unveils Monumental Installation at Hong Kong’s Landmark

    Louis Vuitton Unveils Monumental Installation at Hong Kong’s Landmark

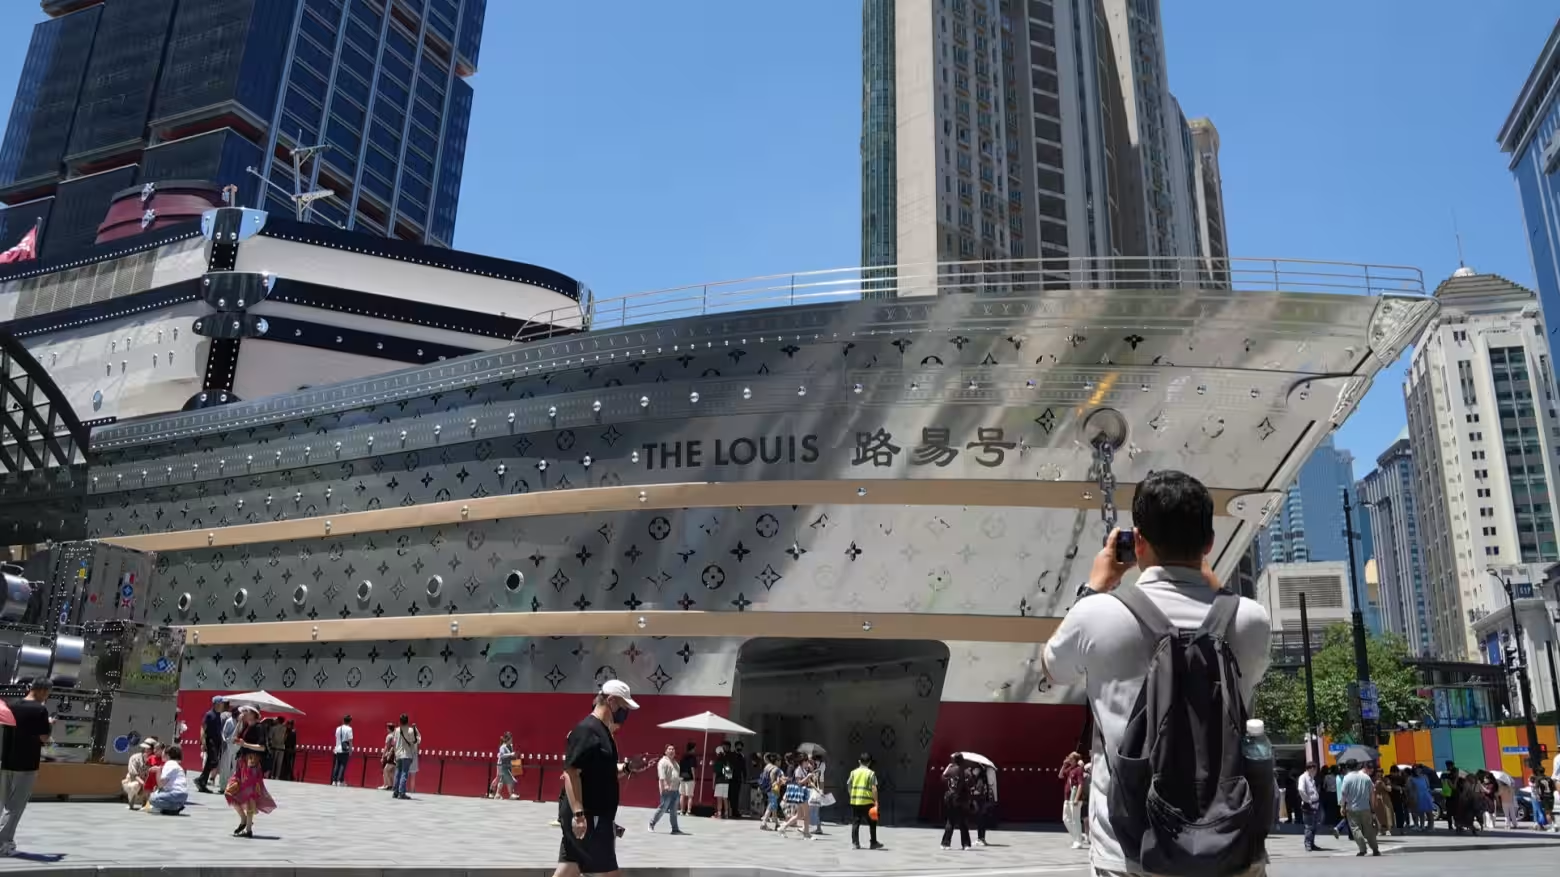
    Louis Vuitton has unveiled a monumental installation at Hong Kong luxury retail destination Landmark on October 23, 2026. The launch coincides with Hongkong Land rolling out Destination Central, a district-wide initiative to attract local residents and international visitors.

    The presentation marks the latest stop in Louis Vuitton’s global rollout of large-scale public shows. Previous editions were held in Paris, New York and Shanghai.

    Drawing inspiration from the maison’s enduring Spirit of Travel motif, the activation arrives as construction continues on its Hong Kong maison, transforming the ongoing site works into a major visual draw.

    Global Sequence of Public Hoardings

    The Central activation follows a sequence of outsized construction wraps the French house mounted across major commercial cities over the past three years. Paris saw the first iteration on the Champs-Élysées in September 2023, followed by a New York installation in November 2024 and a Shanghai presentation in June 2025.

    Each build served to maintain foot traffic and brand awareness around prominent real estate while heavy interior restructuring took place behind the walls. For Hong Kong, the scale of the structure gives Landmark a street-level landmark while primary retail space remains out of service.

    Landlord Strategy and Footfall Defense

    Backing outsized brand takeovers allows prime commercial landlords to treat building sites as visual attractions rather than dead retail corridors.

    The risk sits in the conversion rate. Monogram facades reliably draw spectators and social media attention, but turning passersby outside a construction zone into paying customers inside adjacent mall tenancies requires tight footfall routing. Landlords absorb significant disruption during these overhauls, betting that the eventual multi-floor maisons will restore sales densities once doors reopen.

    Materials and Anniversary Timing

    Louis Vuitton committed to dismantling the installation with sustainable construction practices, stating that all materials used across the temporary exterior will be reused or recycled once building work concludes. The visual scheme centers on the 130th anniversary of the brand’s signature monogram pattern, applied directly across the mock station framework.

    The installation will remain in place while contractor teams complete internal refurbishment of the Landmark maison, with Hongkong Land running coordinated promotions across Central properties throughout the retail district’s renovation cycle.

  • Hermes and Cartier Suffer Double-Digit Sales Slump in Mainland China

    Hermes and Cartier Suffer Double-Digit Sales Slump in Mainland China

    Hermes and Cartier recorded double-digit sales drops in mainland China across August and September, as high-net-worth shoppers joined the broader retreat from luxury spending.

    The contraction also hit the mainland’s top 25 luxury houses, pulling revenue down by double digits for labels such as Louis Vuitton and Gucci over the same two months.

    Foot traffic and store receipts failed to rebound during the seven-day National Day Golden Week in early October, despite an uptick in domestic travel expenditure. That persistent weakness has prompted luxury executives across the sector to brace for a protracted downturn stretching into 2027.

    Top Spenders Join Middle-Class Pullback

    Luxury groups long banked on their wealthiest VIP clients to absorb the blow of an exiting middle class, whose spending power evaporated in a prolonged residential property slump. That insulation has now cracked under the weight of softer equity markets and stricter scrutiny of offshore assets by authorities in Beijing.

    The simultaneous loss of entry-level aspirational buyers and very high-net-worth patrons removes the core financial buffer that protected top-tier European houses. With high-ticket categories bearing the brunt of consumer restraint, retail receipts for jewellery and automobiles dropped as much as 21 per cent in the August-September stretch, even while overall retail sales growth crawled from 0.4 per cent in August to modest gains in September.

    Earnings Divergence Across Greater China

    Hermes reported flat Asia-Pacific revenue for the third quarter on October 22, falling short of the 1.55 per cent growth projected by market consensus. The Asia-Pacific zone, excluding Japan, accounts for roughly 42 per cent of total group turnover for the French saddler, exposing its balance sheet directly to Chinese market softness.

    For Richemont, sustained demand in regional travel hubs like Hong Kong and Macau softened some of the revenue bleed suffered by Cartier boutiques inside the mainland. Yet off-island spending remains insufficient to balance domestic showroom declines, especially as Chinese shoppers reduced their overseas spending by mid-single-digit rates over the quarter.

    LVMH Moet Hennessy Louis Vuitton mirrored the downtrend with a double-digit slide in domestic China sales, dragging its broader Asia region outside Japan down 5 per cent. Kering suffered a 6 per cent drop at flagship label Gucci over the same third-quarter window, missing consensus estimates as Chinese transactions deteriorated.

    The Pivot Away From Conspicuous Labels

    Chinese consumers are actively reallocating personal budgets away from visible status symbols toward hospitality, experiential dining, and domestic travel. Younger demographics in tier-one cities increasingly favour understated craft over prominent monograms, accelerating the shift toward unbranded apparel and pre-owned luxury consignments.

    For landlords holding high-end floor space in prime developments across Shanghai and Beijing, the downturn threatens luxury turnover rent models that depend on relentless retail volume. Department store operators face mounting inventory overhangs and may be forced to negotiate revised concession terms if mainland volumes continue falling.

    The downturn gained momentum after June, when a broader consumer slowdown spread into previously resilient categories. The trend worsened through late summer, confirming that the defensive moats built around heritage brands like the Birkin maker could not deflect local macroeconomic strain.

    Challenging Comparisons Extend Toward 2027

    Eric Du Halgouet, chief financial officer at Hermes, confirmed during an earnings briefing that China’s operating landscape faces head-to-head pressure from sluggish financial markets and ongoing tax-related scrutiny. Rather than an immediate rebound, analysts expect lower baseline figures in 2026 to produce statistical improvements in reported growth by 2027 without resolving structural shifts in domestic consumer confidence.

    Brand heads are now recalibrating store expansion budgets across mainland tier-two cities, while waiting to decide whether to reallocate marketing capital.

  • Apple Starts Selling US$1,999 IPhone Duo

    Apple Starts Selling US$1,999 IPhone Duo

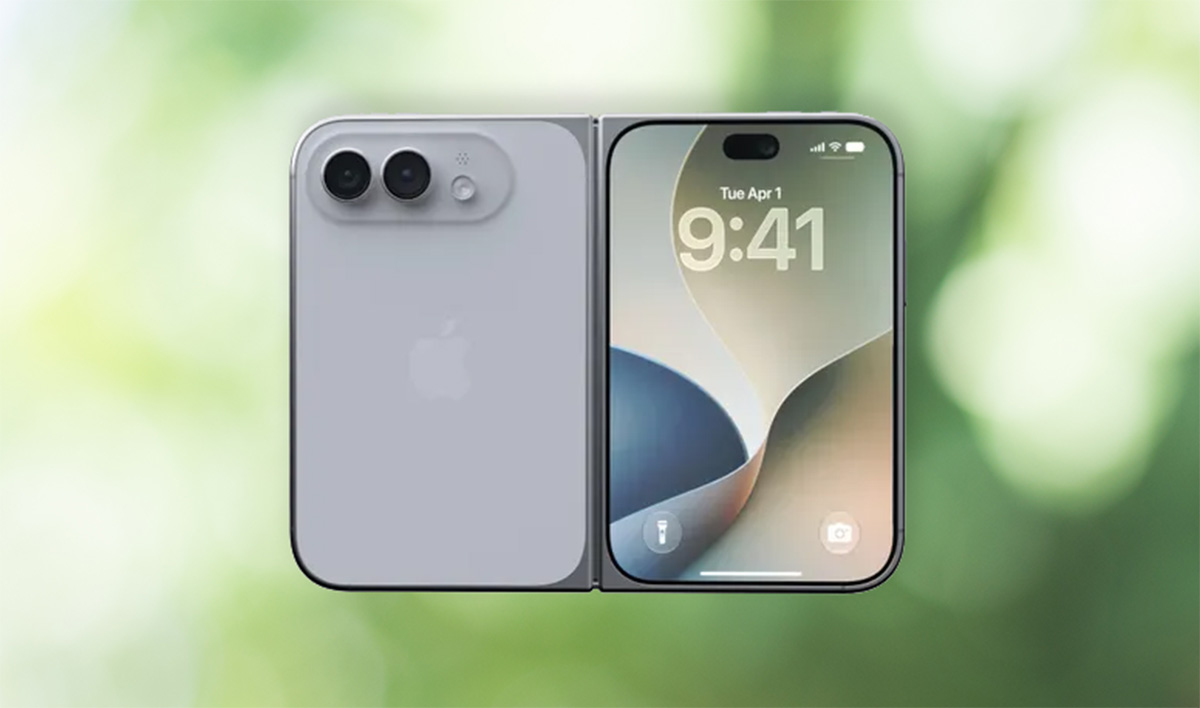
    Apple began selling its first folding phone, the US$1,999 iPhone Duo, on Friday (Oct 23), betting the device can transform the foldables market after nearly two decades of making only incremental updates to the iPhone.

    The launch marks an early trial for new Apple chief executive officer John Ternus, who unveiled the hardware barely a week after taking charge in September.

    Apple enters a niche segment where rivals such as Samsung Electronics and Huawei Technologies have sold premium foldables for years.

    Channel Allocations and Asian Retail Constraints

    Within minutes of pre-orders opening on Oct 16, Apple’s estimated delivery dates for the Duo had slipped to late January as demand outpaced supply. The company called the response from customers “nothing short of extraordinary”.

    The limited supplies could disappoint Apple fans lining up in front of stores to buy the Duo. Apple told Reuters that walk-in availability would vary by country, with limited stocks in the US, Australia, Canada, Mexico and much of Britain and Europe. In China, France, Hong Kong, India and Japan, units would be available only for customers who had ordered online. In the China-governed territory of Macau, where the iPhone Duo will be available for walk-in customers only, fans already started lining up hours in advance, social media posts and media reports showed.

    Rivalry With Incumbents in Regional Markets

    Early reviews have praised the US$1,999 Duo’s premium design as well as its sturdy and barely visible hinge, a major feat for the phones whose prominent creased screen has long been a major drawback and potential deterrent to buyers. But reviewers have also said that camera compromises including the absence of a telephoto lens and third-party apps that still need to be reworked for the new display size could disappoint some buyers.

    They have noted that iPhone Duo in its smaller, folded state is less handy for the litany of quick tasks that most users carry out each day on standard iPhones, leading several prominent reviewers to recommend against the Duo for many Apple customers.

    “Foldables have been an established category for years, but adoption has remained relatively limited compared with conventional smartphones. Apple’s entry could bring the format to a much broader audience,” said Francisco Jeronimo, vice-president at market research firm IDC.

    IDC expects Apple will take 44 per cent of the foldable value in 2026 on 31 per cent of foldable units. By 2027, it will become the market leader in the category both in value and units shipped, according to the firm.

    “Apple has made a convincing case for this form factor,” Jeronimo said after spending a week with the Duo. “Now comes the next test: turning excitement into availability, adoption and a lasting new chapter for the smartphone market,” Jeronimo added.

    Executive Leadership and Product History

    “It’s been a lot of fun trying the Duo out for a week, but it feels like I’ve gotten to use an extraordinarily polished prototype, not a finished product that I’d want to buy and carry,” longtime Apple commentator John Gruber, the author of the blog Daring Fireball, wrote in a review.

    Tech commentator Marques Brownlee, popularly known as MKBHD, said in a YouTube review that “if you’re just a regular person who doesn’t do much more than texting, social media and browsing here and there, then it is probably a no”.

    “But if the US$2,000 doesn’t mean much to you, and you like the idea, after the learning curve and getting used to not having facial identification, it is a really fun phone.”

  • Airlines and Thai Tourism Authority Discount 99,000 Seats

    Airlines and Thai Tourism Authority Discount 99,000 Seats

    Last week, seven domestic carriers and the Tourism Authority of Thailand introduced a joint campaign discounting 99,000 domestic flight seats by 500 baht each to boost spending during the fourth-quarter high season.

    Total bookings reached 47 per cent within days of launch, with Thai AirAsia and Thai Lion Air rapidly exhausting their quotas of 16,000 seats each.

    TAT Governor Thapanee Kiatphaibool said the project seeks to alleviate travel costs for local tourists affected by recent floods. The initiative is projected to generate at least 300 million baht in domestic tourism revenue, alongside a companion scheme targeting tour operators from nine associations that offers daily incentives of up to 10,000 baht to generate another 209 million baht.

    Domestic Capacity Absorbs Cross-Border Softness

    Thai carriers are pivoting seat inventory back home because cross-border demand is failing to deliver projected yields. While fourth-quarter inbound flights to Thailand climbed 5.8 per cent according to Kasikorn Research Center, that expansion trailed regional peers significantly, with Malaysia booking a 15 per cent increase and Vietnam posting 13.6 per cent.

    Airlines cannot afford idle airframes while international feeder markets stall. Thai Lion Air postponed resuming scheduled services to Seoul after Thai AirAsia permanently suspended the same route, exposing lingering vulnerability across secondary Northeast Asian links. Low-cost operators across Southeast Asia face a clear operational split: domestic routes offer thinner margins but immediate cash generation, whereas cross-border capacity ties up balance sheets without guaranteed seat factors.

    For regional airport retailers and provincial hospitality operators, this flight shift changes footfall patterns directly. Instead of high-spending foreign independent travelers filling transit malls at primary hubs, passenger traffic is tilting toward domestic holidaymakers looking for subsidized provincial escapes. Destination businesses in secondary hubs must adjust pricing downward to capture volume rather than waiting for international inbound recovery.

    Thai AirAsia Expands Flight Schedules

    Thai AirAsia commercial head Tansita Akrarittipirom confirmed the airline raised domestic schedules to 135 flights a day for the fourth quarter. That represents an increase of more than 50 per cent from its third-quarter baseline of 88 daily departures, designed to defend a 40 per cent domestic market share.

    The carrier is using dual-hub operations across both Don Mueang and Suvarnabhumi airports to capture varied passenger segments. Earlier this month, Thai AirAsia restored flights out of Suvarnabhumi to Chiang Mai, Krabi, and Phuket with load factors surpassing 82 per cent, reversing service cuts previously made during jet fuel price spikes.

    Network adjustments also target event-driven travel across secondary provinces. The airline is scaling up Bangkok-Udon Thani frequencies to six flights a day alongside four weekly departures each from Chiang Mai and Phuket to support the Udon Thani International Horticultural Expo 2026.

    Rebuilding Regional Route Networks

    The domestic pivot follows selective pruning of non-performing international routes over the past year. Regional carriers have trimmed thin routes to preserve working capital, redeploying narrow-body aircraft onto established business runs and high-density tourist trunks.

    Thai AirAsia maintains direct flights to 46 cities across 53 destinations in Asia, yet its international growth remains tightly focused on proven catchment areas. In India, the airline is reactivating six previously halted routes this quarter, while its Phuket hub is restoring direct services to Siem Reap alongside the resumption of Bangkok-Kuala Lumpur frequencies.

    Operational focus now shifts to whether domestic demand can sustain load factors once state subsidies wind down. The primary metric to track is whether carriers maintain the 135 daily domestic flights past the high season without further tariff discounting.

  • Bank of Thailand Proposes Strict One-to-One Reserves for Baht Stablecoins

    Bank of Thailand Proposes Strict One-to-One Reserves for Baht Stablecoins

    The Bank of Thailand proposed draft rules requiring baht-denominated stablecoin issuers to back tokens 1:1 with bank deposits and prohibited them from paying interest to holders.

    Redemptions must clear within one business day under the central bank’s consultation paper, stripping out speculative yield features to force issuers into functioning strictly as payment tools.

    Cash Reserves and Redemption Rules

    Under the initial phase of the framework, issuers must place all reserve assets in commercial bank accounts. The central bank stated that each issued token requires a full baht counterpart on deposit to guarantee liquidity when users exit to fiat currency.

    Later stages could permit issuers to diversify backing into other high-quality liquid assets such as short-dated government securities. For now, capital remains locked exclusively in standard accounts.

    Holders will receive zero yield. The paper bars issuers from providing direct or indirect incentives, interest payments, or returns calculated against holding duration or token balances.

    The role of the digital payment tool should be clearly distinguished from financial products that offer returns on holdings. The restriction aims to ensure that THB stablecoins function as a means of payment rather than a savings or investment product, the consultation paper stated.

    Licensing Under the Finance Ministry

    The central bank recommended that Thailand’s Ministry of Finance formally designate token issuers and custodial wallet operators as payment service businesses. That designation pulls every participant directly beneath central bank supervision before they can launch commercial services.

    Regulators also want the legal authority to cap the total number of licensed issuers operating in Thailand. Fragmented liquidity across dozens of corporate tokens would weaken settlement stability and leave merchant gateways juggling incompatible digital currencies.

    Wallet providers and token operators must install anti-money laundering controls alongside know-your-customer and know-your-merchant checks. Systems must flag suspicious flows and maintain cyber safeguards equivalent to retail banking networks.

    Automated Settlements and Retail Reality

    Commercial banks and payment aggregators already run PromptPay across Thailand, processing high-volume consumer payments at near-zero fees. A baht stablecoin does not exist to replace that daily point-of-sale infrastructure.

    The central bank pointed instead toward programmable commerce built on distributed ledgers. Smart contracts could automate escrow payments, releasing merchant disbursements only after a freight carrier confirms final delivery of goods.

    For enterprise treasuries, programmable tokens eliminate multi-day corporate settlement delays without taking on foreign-exchange volatility. Yet by banning interest, regulators have eliminated the primary mechanism decentralized finance protocols use to attract commercial liquidity.

    What to Watch Next

    Thailand is choosing a defensive stance that protects retail deposits rather than testing financial engineering.

    The policy document follows years of steady payments modernization in Thailand, moving from paper cash to QR codes under state supervision. Permitting private corporate tokens without strict balance sheet anchors would reverse that consumer protection stance.

    The Bank of Thailand is now gathering public industry feedback on the consultation paper before submitting formal statutory recommendations to the Ministry of Finance.

  • India Issues Notices to Nestle, Zydus and Abbott over Child Product Claims

    India Issues Notices to Nestle, Zydus and Abbott over Child Product Claims

    India’s food safety authority issued formal notices to Nestle India, Zydus Wellness and Abbott Healthcare this week over marketing claims on infant and children’s products that breached national rules.

    The enforcement actions rattle an Indian packaged food market valued at more than $100 billion as regulators intensify oversight of nutritional claims.

    The move comes shortly after officials proposed prohibiting added sucrose and fructose in foods intended for infants up to six months old.

    Evidence Demanded on Formula and Growth Drinks

    The Food Safety and Standards Authority of India ordered Nestle India to produce documented evidence supporting promotional assertions about digestive health and immune system benefits. Those claims appear on labels for Lactogen Pro 1 Powder and NAN Excella Pro Stage 1 infant formula.

    For Zydus Wellness, the regulator demanded scientific substantiation for marketing claims attached to its Complan children’s beverage brand. Regulators singled out promotional packaging using the slogan “grow taller, faster. Clinically proven 2X growth.”

    Enforcement also expanded into digital media distribution channels. The regulator issued separate notices to online influencer Ira Fathima alongside Abbott Healthcare and Nestle India concerning an Instagram reel promoting infant milk substitutes.

    Nestle India stated that the authority’s public notice repeated concerns initially raised on September 18 regarding product packaging labels, adding that it had already delivered an extensive formal response to the food regulator.

    Abbott took a different position, stating it played no role in the social video campaign. “Abbott does not endorse the claims or representations contained in the content,” a company spokesperson said, adding that the healthcare firm only learned of the material after receiving the authority’s notice and had forwarded that explanation to officials.

    Regulatory Pressure Mounts Across FMCG Portfolios

    The enforcement notices show Indian authorities closing off the latitude dairy and consumer health brands historically enjoyed when framing products as quasi-medicinal solutions. For multinational operators, children’s nutritional beverages and early stage formulas command premium shelf pricing in modern trade stores and pharmacy chains across tier-one Indian metros.

    Pivoting marketing messages from clinical outcomes to simple nutritional content carries commercial risk. When brands cannot claim tangible acceleration in height or immune protection, consumer willingness to pay substantial retail markups over standard milk powders drops quickly.

    Packaged goods manufacturers operating in India face a compounding compliance headache. Removing unverified health statements from shelf packaging requires inventory write-downs, packaging redesigns and altered point-of-sale displays across hundreds of thousands of general trade outlets.

    Digital influencer campaigns, long used by FMCG marketing teams as an indirect route around tight infant formula promotion laws, now sit squarely within the regulator’s direct enforcement perimeter. Brands can no longer isolate corporate marketing budgets from third-party social media creators promoting their product categories.

    Stricter Sugar Rules Set the Stage

    The crackdown follows earlier regulatory intervention by the food authority on October 17, when officials proposed an outright ban on adding sucrose and fructose to food products formulated for infants up to six months old.

    That regulatory draft landed as authorities stepped up scrutiny of basic formulation standards across processed food segments and advanced plans for mandatory front-of-pack nutritional warning labels.

    Regulators will decide whether to mandate product label revisions, levy statutory fines, or order affected product batches removed from retail distribution shelves across the country.

  • 7-Eleven Introduces Foodbar Across 16 Singapore Stores

    7-Eleven Introduces Foodbar Across 16 Singapore Stores

    7-Eleven Singapore has launched Foodbar, a fresh in-store counter concept rolling out across 16 stores islandwide as the convenience retailer moves to capture growing demand for quick, convenient dining.

    Introduced in October 2026, the format serves freshly prepared hot meals alongside snack selections, with plans to expand the footprint over time. Layouts adapt to available floor space, customer profiles and footfall, ranging from build-your-own bowl stations to grab-and-go warming cabinets.

    At larger Foodbar branches, customers can customise warm bowls starting from an assortment of bases before choosing proteins and garnishes, while smaller outlets offer hot snack selections. The initiative deepens 7-Eleven Singapore’s operational push into prepared food across its citywide retail network.

    Customisable Bowls and Snack Counters

    DFI Retail Group, which operates the convenience franchise in Singapore, unveiled the concept on Oct 16. Larger locations feature build-your-own bowl counters where shoppers choose a base of rice, penne pasta or noodles, followed by sauces, garnishes and proteins such as roast chicken, hash browns or chicken cutlets. Outlets with tighter footprints carry hot counter selections including pizza slices, croissants, pancakes and waffles for dine-in or takeaway.

    Store formats are tailored to available floor space and local footfall profiles. To accommodate the equipment and dining customers, the operator is refitting selected units to add interior seating and wider aisles. 7-Eleven Singapore managing director Anushree Khosla said the chain is restructuring store layouts to turn outlets into food and shopping destinations.

    Ready Meals Deliver Double-Digit Gains

    Ready-to-eat items already generate a double-digit share of total sales for 7-Eleven in Singapore, while recording double-digit sales growth. An internal survey conducted in August among 1,020 local convenience shoppers who bought prepared food during the preceding month showed shifting consumer schedules and warmer attitudes toward convenience meals over the past three years.

    The chain’s chilled and ambient ready-to-eat inventory now spans 130 items across meals, breakfast, snacks and desserts. Product developments have borrowed directly from formats popularised by convenience networks in Japan, Taiwan and Thailand. Recent launches include halal-certified Korean-style kimbap, onigiri, and pressed toasties inspired by Thai operators.

    Local partnerships have also driven basket sizes. Since 2021, the convenience chain has rolled out co-branded meals with domestic food operators including Andes by Astons, Lau Wang Claypot Delights, Playmade, Chocolate Origin and Nasty Cookie. Sales data showed these branded collaborations outpaced demand for lower-priced budget lines or dedicated health ranges.

    Following the North Asian Operating Model

    For convenience operators across Southeast Asia, moving into hot foodservice is a necessity born of margin compression in packaged consumer goods. Traditional convenience categories such as tobacco, confectionery and bottled drinks face rising wholesale costs and strict regulatory limits. Japanese chains proved decades ago that back-counter food preparation delivers higher retail gross margins, far above packaged groceries.

    The challenge sits squarely in execution. Hot counters require dedicated exhaust, regular oil management, counter staff training and strict hygiene monitoring in compact retail spaces. Singapore’s severe retail labour shortage makes running hot food preparation behind a single cashier till operationally fragile. If lines slow during the midday lunch rush, core grab-and-go shoppers walk out.

    DFI Shifts Capital After Grocery Sale

    The Foodbar rollout follows a broader restructuring of DFI Retail Group’s regional assets. In 2025, the Singapore-listed group sold its Singapore supermarket division, including Cold Storage, CS Fresh, Giant and Jason’s Deli, to Malaysian operator Macrovalue for S$125 million.

    Exiting lower-margin mass grocery freed operating cash to concentrate on high-turnover consumer businesses where the group holds licensed franchise authority. Alongside 7-Eleven’s food transformation, DFI took direct control of Starbucks licensed operations in Southeast Asia and expanded health inventory across its Guardian pharmacy stores.

    The retailer plans to extend the hot-food format beyond the initial 16 locations in phases, tracking average basket spend and kitchen throughput before committing to additional store conversions.

  • Princeton Digital Group to Boost Asian Data Centre Capacity by 200 Percent

    Princeton Digital Group to Boost Asian Data Centre Capacity by 200 Percent

    Princeton Digital Group plans to boost data centre capacity in its core Asian markets by as much as 200 percent over the next 12 to 24 months, chairman and CEO Rangu Salgame said this week.

    The company currently operates and develops 1.8 gigawatts across eight markets, focusing expansion on India, Japan, Malaysia, Singapore and Indonesia while acquiring land in Australia and South Korea.

    Capital demands from hyperscale cloud operators dictate the aggressive schedule. A typical 200-megawatt facility demands roughly $2 billion for property and shell infrastructure, while tenant tech giants commit an additional $6 billion for chips, servers and high-speed networking gear.

    Funding the Hyperscale Buildout

    Warburg Pincus and Stonepeak back the developer, which outlined intentions in March to raise up to $5 billion in debt this year. That debt drive follows $2.5 billion gathered in 2025, anchored by a $1.3 billion preferred equity commitment from Stonepeak.

    Delivery schedules remain rigid because idle semiconductors burn capital without generating revenue. Hyperscalers allocate contracts strictly to builders capable of completing grid connections and cooling systems without slippage.

    Refocusing the Indonesian Footprint

    Asset sales reflect this prioritization of massive wholesale campuses over scattered corporate server rooms. PDG reached an agreement last week to offload five operational Indonesian enterprise sites to conglomerate Sinar Mas for an unstated amount.

    Enterprise colocation no longer matches the firm’s capital allocation model. Retaining roughly 400 megawatts in Indonesia, PDG concentrates resources on its JC2, JC3 and JC4 mega-campuses.

    Expanding South Korea and Australia

    Geographic diversification relies on existing multinational clients asking the operator to follow them into mature markets. The group bought a Sydney location earlier this year, hired former energy executive Scott Thomas as country general manager, and now reviews land parcels in Melbourne.

    North Asian momentum centers on Incheon, where the operator entered South Korea last November by backing a $700 million, 48-megawatt project with ESR. That development forms the foundation of a 500-megawatt domestic rollout.

    Building Out the Pipeline

    PDG entered Indonesia originally in 2019 after acquiring a 70 per cent stake in telecom carrier XL Axiata’s data facilities. Five years of portfolio turnover shifted that regional foundation from telecom integration into pure-play hyperscale real estate.

    Work East of Jakarta continues on the JC3 campus, a $1 billion, 120-megawatt development that broke ground last November. That project and the initial Incheon phase stand as the primary targets before the South Korean asset begins commercial operations in 2028.

  • Mirvac Sells Brisbane Office Complex to Alceon for A$124 Million

    Mirvac Sells Brisbane Office Complex to Alceon for A$124 Million

    Mirvac has agreed to sell a twin-tower office complex and adjoining public car park on the northern edge of Brisbane’s city centre to local investment manager Alceon for A$124 million ($87 million).

    Alceon announced on Wednesday that contracts have been exchanged for 410 Ann Street and the neighbouring Cathedral Square car park at a fully leased yield of 11 percent. The transaction prices the asset at about A$6,000 per square metre, falling below A$4,000 per square metre once the excess car parking is stripped out. Mirvac is exiting the property through a separately managed account.

    Yields Split Between Prime and Secondary Stock

    Marking Alceon’s 15th Brisbane office purchase, the deal expands its bet on secondary-grade buildings as city-centre vacancy dropped to 10.2 percent in July. Prime space in the city saw gross effective rents rise 11.8 percent in the third quarter from a year earlier, lifting cumulative gains since 2022 to 47 percent.

    The pricing gap between institutional prime towers and secondary stock in the city has widened sharply. Institutional buyers have paid roughly double the square-metre rate for premium assets, while secondary properties trade at heavy discounts to replacement cost. With 10-year bond rates hovering near 5.35 per cent, buyers of older stock rely on double-digit yields and hands-on leasing turnarounds to make underwriting hurdles pencil out.

    For office landlords and commercial operators, the transaction demonstrates that capital liquidity remains selective rather than frozen. Private syndicators and high-net-worth capital pools are absorbing secondary buildings that institutional funds are paring back. The core risk rests in capital expenditure demands, as incoming landlords must commit fresh funds to older floorplates to compete against premium stock offering stronger sustainability credentials.

    Car Park and Transit Connections

    The Ann Street property occupies a 4,052 square metre freehold parcel containing more than 20,000 square metres of net lettable area and 139 internal parking bays. Beside the towers, the Cathedral Square facility adds 572 vehicle bays across an 8,949 square metre site held under a leasehold tenure running until April 2108.

    Commuter access sits close to the asset, located 375 metres from Brisbane Central Station and near works on the subterranean Cross River Rail network. The complex holds a 5.5-star NABERS Energy rating and a 3.5-star NABERS Water rating under national benchmarking standards.

    “This is a well-located asset that has been under-managed for some time,” said Todd Pepper, managing director and head of Alceon’s Queensland business. “Our plan is hands-on: invest in the building, lift the tenant experience and lease it up into a market where good space is getting harder to find.”

    Planned Capital Works and Lease Expiries

    Alceon intends to refurbish the entrance lobbies, shared amenities and empty office floors to lift the asset to a contemporary B-plus grade. Existing leases run across an occupancy level of roughly 90 per cent with a four-year weighted average lease expiry, anchored by the Public Trustee of Queensland, First Parking, Mipac, Sonic Healthplus and Dye & Durham.

    The transaction follows a comparable secondary deal completed in September, when Quintessential Equity purchased 133 Mary Street from ESR Group for A$81.8 million, or roughly A$6,200 per square metre. That asset also included retail space targeted for a refurbishment program. By contrast, Barings paid A$700 million for 480 Queen Street in July at A$12,727 per square metre, while GPT Group acquired Central Plaza II at 66 Eagle Street for A$400 million in April at A$12,561 per square metre.

    Brokers Peter Chapple and Bruce Baker of CBRE handled the transaction alongside Paul Noonan and Jack Sullivan of JLL. Alceon financed the purchase via its network of wholesale and high-net-worth backers, pushing its Queensland commercial property portfolio past A$1.25 billion under management.

    Near-term performance now depends on tenant retention, with almost half the total floor space at 410 Ann Street scheduled for contract renewal across 2028 and 2029.

  • Nick Scali ANZ Orders Drop 15 per Cent After Cyberattack and Market Slump

    Nick Scali ANZ Orders Drop 15 per Cent After Cyberattack and Market Slump

    Nick Scali has cautioned investors that first-half revenue across Australia and New Zealand will drop by approximately 11 per cent to 14 per cent compared to the prior corresponding period. The ASX-listed furniture retailer recorded a 15 per cent decline in first-quarter sales orders following a mid-August cyberattack and persistent weakness across its core consumer markets. That contraction contrasts with the first quarter of fiscal 2026, when sales climbed 11 per cent.

    The mid-August intrusion triggered “uncertainty and delays” for shoppers, the company stated at the time. Nick Scali alerted the Australian Cyber Security Centre and the Australian Federal Police, which subsequently investigated the security incident.

    By contrast, the company reported stronger momentum in the UK, where it entered the market through the acquisition of Fabb Furniture in 2024. Ongoing capital expenditure into renovating and expanding British stores helped lift written orders by 29 per cent year-on-year in the first quarter.

    The Cost of Three Weeks Offline

    The operational disruption began in mid-August when unauthorised parties breached internal systems and accessed customer names, addresses, emails and phone numbers. Nick Scali informed the Australian Cyber Security Centre and the Australian Federal Police to investigate the intrusion.

    Enterprise resource planning systems stayed offline for roughly three weeks. Store staff continued writing business manually while technicians contained the incident.

    Cleaning up the breach generated a $980,000 bill for legal advisers and forensic consultants. Management will classify those advisory expenses as non-underlying items rather than counting them against operating earnings.

    Contrasting Fortunes in Britain

    Nick Scali is finding better traction in the United Kingdom, where it acquired Fabb Furniture in 2024 to seed an offshore division. Written orders in the British network jumped 29 per cent year-on-year during the first quarter.

    Like-for-like sales across the UK estate grew 14 per cent. Temporary closures during store refurbishments accounted for the gap between total orders and comparable trade.

    Management plans to launch one new British showroom in late December as it refits existing Fabb sites under the core retail brand. The retailer continues to invest capital to convert British floorspace while protecting group gross margins and cutting administrative overhead.

    Diverging Paths for Bulky Goods Operators

    Big-ticket homeware merchants face a difficult climate as households cut discretionary outlays and housing market turnover moderates. Australian domestic demand has cooled under high interest rates, hitting furniture chains harder than nondiscretionary retailers.

    Retail landlords housing large-format showrooms also face reduced turnover rents and tougher renewal discussions.

    The contrast between Britain and the domestic market exposes the split in modern retail turnarounds. British consumers are taking to newly upgraded store concepts even in a flat economy, while Australian shoppers are staying away from domestic showrooms despite decades of brand loyalty.

    Shifting Consumer Spending Patterns

    The current slump follows an extended boom when post-lockdown home renovations drove furniture sales across Australia and New Zealand. That surge eventually ebbed into an Australian retail recession across 2023 and 2024 before stabilizing.

    Economic forecasts published in September projected national retail turnover growth to ease from 2.8 per cent in fiscal 2026 to 1.5 per cent in fiscal 2027. While that deceleration remains milder than the downturn seen two years ago, big-ticket home goods retailers face the steepest drop.

    Nick Scali operates 132 stores worldwide across its three geographic territories. Despite the order decline in Australasia, the retailer will open two new stores in Australia and New Zealand in late December alongside its British debut.