Blog

  • Sa Sa feels pinch of Chinese policy

    Sa Sa feels pinch of Chinese policy

    China’s policy of one trip a week for mainlanders plus the strength of the Hong Kong dollar against a weaker yen have gouged sales for cosmetics retailer Sa Sa International.

    Both its retail and wholesale turnover dropped 14.2 per cent for the third quarter (October 1 to December 31), the company has announced. Turnover declined by 15.8 per cent in the Hong Kong and Macau markets, where same-store sales dropped 12.2 per cent.

    Overall, transactions were 7 per cent weaker, average sales per transaction fell 9.1 per cent and there was a 12.1 per cent dip in same-store sales. The group’s total turnover in other markets, including Mainland China, Malaysia, Singapore, Taiwan and online, dropped 6.7 per cent.

    Chairman/CEO Dr Simon Kwok says the impact of the “one-trip-per-week” policy had gradually gained momentum, leading to a notable year-on-year decline in the number of same-day visitor arrivals.

    “We expect the negative trend will continue to influence the local retail market.”

    In response, he says the group will optimise its product offering and enhance the shopping experience for its customers.

    Back in October, Sa Sa International Holdings already warned that its net profit for the six months to September 30 would be slashed in half because of the sluggish retail scene.

  • Hong Kong entrepreneur Ricky Wong plans HK$100m ad campaign boost for online shopping

    Hong Kong entrepreneur Ricky Wong plans HK$100m ad campaign boost for online shopping

    Ricky Wong Wai-kay has ambitious plans to boost his online shopping venture with a HK$100 million ad campaign and staff expansion despite a grim economic outlook and still being a long way from breaking even.

    The HKTV boss said that a year after the official launch of his online shopping mall, it had recorded an average of 700,000 to 800,000 unique visitors per month and the number of customers had doubled in the last two months to tens of thousands.

    He said each customer placed orders ranging between HK$400 and HK$1,000.

    “We will broaden the range of goods available. We will soon offer fresh seafood, chicken and vegetables among some 99,000 items available in our online store.”

    Wong said the company had set aside a HK$80 million to HK$100 million advertising budget for e-commerce in the coming year.

    READ MORE: HKTV and boss Ricky Wong win HK$1.3m libel payout from ATV and ex-director James Shing

    He also planned to expand the logistics team from around 300 to 800 or 1,000.

    “The cost will still be much lower than operating a physical shop,” he said. “High rent is killing Hong Kong’s retail sector.”

    Wong cited a recent report from CBRE Research, which named Hong Kong as the world’s most expensive retail market.

    According to the report, rent for retail spaces in Hong Kong had reached US$4,334 per sq ft per year – 3.3 times more than in Paris, ranked at No 3, and 3.6 times more than in London.

    He said some Hong Kong retailers spent nearly 50 per cent of turnover on rent.

    “Tourists who come to Hong Kong won’t shop here. They would rather shop in London or Paris,” he said.

    But he admitted there was still a long way to go before breaking even.

    Wong initially intended to develop a TV business that operated alongside his e-commerce venture with HKTV. But HKTV did not get a free TV licence from the government and his internet TV business did not take off due to lack of advertising.

    But he has not given up his TV dreams completely. He said he was still negotiating with the government on mobile TV development, and a multimedia centre under construction in Tseung Kwan O was expected to be completed by the end of this year.

    However, Wong has no concrete plans to revive any TV productions.

  • Investors sought for top-yielding Oud production project in Laos

    Investors sought for top-yielding Oud production project in Laos

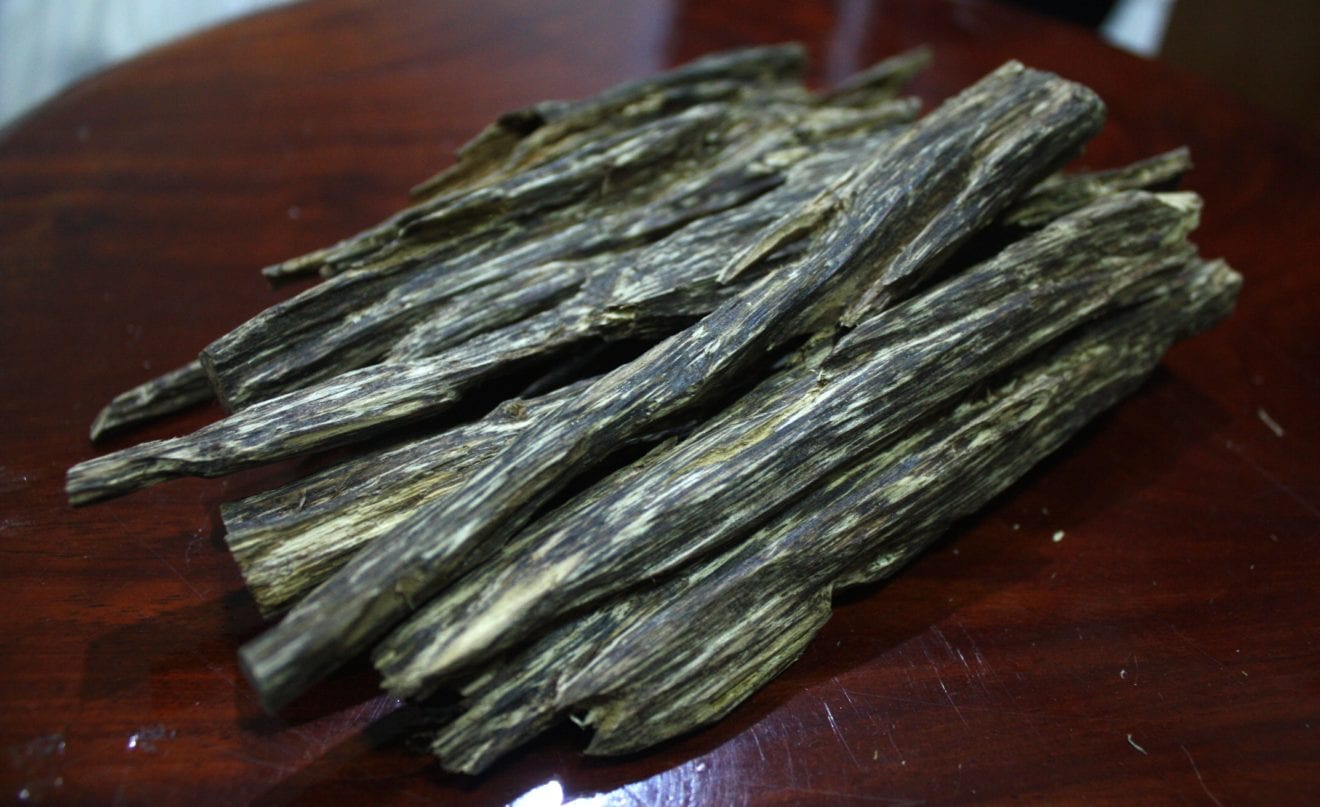
    Two companies from Malaysia are on the lookout for investors to set up a big agarwood tree plantation in Laos to produce Oud oil and other agarwood products for markets in Asia, the Middle East and Europe.

    Agricultural contractor Aseagate on January 6 signed an agreement valued 200mn with forestry management and agriculture technology firm Richwood Capital both companies are based in Kuala Lumpur to operate and run a 2,000-hectare agarwood tree plantation in the central Lao province of Bolikhamsai, one of the largest plantations projects in the landlocked Southeast Asian country so far.

    According to Richwood Capital’s CEO Kendrick Ho Qing Tyat, the project will be implemented in four phases. The initial investment in the first phase is about 18mn for the planting of 200,000 agarwood trees aged between 18 and 22 years at costs of 90 per tree, which should yield a return of 200mn in three years based on calculations that one liter of high-quality agarwood oil fetches at least 14,000 on the wholesale market.Over four phases in the coming six to eight years, with the planting of new trees and new investors on board, the venture’s business plan is to reach a total return of no less than 7.2bn, Tyat said at a press conference in Kuala Lumpur last week. The venture plans to set up its own production plant in Laos or to collaborate with a Lao partner. To produce the resin from which the Oud essence can be distilled, a special technique developed by a Singapore laboratory using a unique and effective enzyme will be deployed to multiply the resin output per tree.

    Main export markets will be the Middle East and China, and also Southeast Asia to tap the big potential that opened up with the recent launch of the ASEAN Economic Community. Top European perfume makers are also on the potential client list. The venture will also sell agarwood leaves, which can be made into tea, and explore ways of producing wood chips from the agarwood trees as well as offer “agriland banking” to investors to tap into the growing ptential of agarwood farming.

    Both companies hailed agarwood as a safe investment, as it was “more resilient to economic fluctuations as compared to stocks and bonds,” and insurance will be purchased to provide protection against possible natural calamities.

    Aseagate has been awarded the sole rights to the management of the agarwood plantation, while Richwood Capital will supply and plant the trees. The plantation concession has been exclusively awarded by the Lao government to the Singapore branch of non-governmental organisation Global Outstanding Chinese 100, or GOC100, an association of international Chinese industrialists, business people and entrepreneurs, which will cooperate with the two Malaysian firms in setting up the plantation and is working out profit-sharing and other details for the collaboration with the Lao government.

    GOC100 in August 2015 signed an exclusive agreement with the Lao Ministry of Agriculture and Forestry for the concession of the plantation which is located within a Lao military base and guarded by the army. Infrastructure-wise, the plantation will benefit from a new railway network linking Laos with China to be set up by 2020.

    Agarwood is increasingly becoming an investment commodity due to its valuable resin of which Oud oil is being distilled. Pure Oud is highly in demand as a natural fragrance throughout East and Southeast Asia, as well as in the Middle East and by global perfume manufacturers. It is a popular fragrance for both men and women in the Arab world, while it is also used in traditional Chinese medicine, by Ayurvedic and Tibetan physicians and as meditation incense by various religious groups. In some Arab cultures, it is also used as inhaled incense as a natural remedy against insomnia.

    What makes investment in an agarwood plantation particularly attractive is the fact that, due to its scarcity, the mature wood is pricier than gold with a retail price of between 5,600 and 10,000 per kilogramme, making it one of the most expensive natural raw materials in the world.

  • Milk producers Lewis Road Creamery eyes up China for exports

    Milk producers Lewis Road Creamery eyes up China for exports

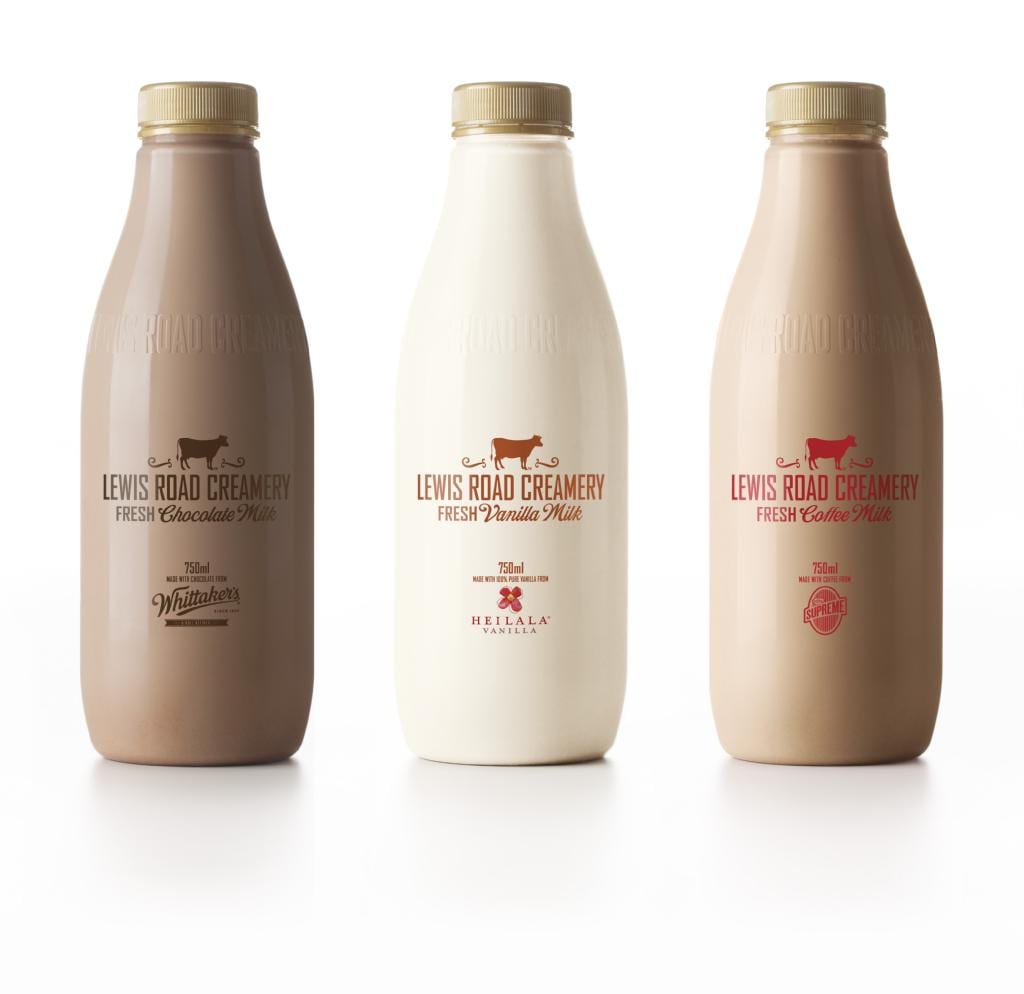
    Lewis Road Creamery, the premium dairy brand organization based in New Zealand, is eyeing on Chinese market to export their products. The company said the final decision would be made this year. The premium dairy brand organization is considering sending out fresh natural milk into Shanghai and likewise wants to release different product extensions. It has already started making baked goods apart from dairy items.

    The Auckland-based brand saw 340 percent development in retail deals to $40 million of its butter, cream, natural drain, and flavored milk items amid 2015; the year of what founder Peter Cullinane calls “the chocolate milk frenzy.” His big choices this year incorporate the exporting decisions and expansion of product range. For the recent months it has been carrying out tests sales of Lewis Road Bakery premium kibbled grain bread in 12 Auckland retail outlets.

    Cullinane said it’s at present exporting butter to Australia and has been researching a more extensive move, specifically fresh organic milk to Shanghai following a trip to China a year ago. Different markets the company plans to export to incorporate Australia, the UK, and the US, however he supposes the last might be past the organization’s current reach.

    The organization’s extraordinary growth in chocolate milk sales, which on its launch in Oct. 2014 saw queues in supermarkets, has decreased from 48 percent between the last quarter of 2014 and first quarter of 2015 to more normal levels.

  • African exports to China descend by 40 percent

    African exports to China descend by 40 percent

    African exports to China fell by 40 percent in 2015, China’s customs office reports. China is Africa’s greatest single trading partner and its interest for African products has fuelled the continent’s recent financial development. The decrease in exports mirrors the recent slowdown in China’s economy. This has, thus, put African economies under weight and to some extent represents the falling estimation of numerous African currencies.

    Exhibiting China’s previous year trading figures, customs representative Huang Songping advised that African exports to China aggregated $67bn (£46.3bn), which was 38% down on the figure for 2014. BBC Africa Business Report editor Matthew Davies says that as China’s economy sets out toward what numerous experts say will be a hard finding, its requirement for African oil, metals and minerals has fallen quickly, taking commodity prices lower.

    There is likewise less funds coming from China to Africa, with direct investment from China into the mainland falling by 40% in the initial six months of 2015, he says. In the mean time, Africa’s interest for Chinese products is rising. In 2015 China sent $102bn worth of products to the mainland, an expansion of 3.6%. A year ago, South Africa facilitated a China-Africa summit amid which President Xi Jinping declared $60bn of aid and loans, symbolizing the nation’s growing part on the Continent.

  • 2 Reasons Why China’s Macro Woes Won’t Affect Apple, Inc. as Much as You Think

    2 Reasons Why China’s Macro Woes Won’t Affect Apple, Inc. as Much as You Think

    The market certainly woke up on the wrong side of the bed for 2016, and most fingers are pointed to troubling macro-economic data out of China along with The Middle Kingdom’s brutal market sell-off. The Shanghai Composite Index is already down 10% year to date, and it’s only been a week. You probably also saw those headlines about the day that the Chinese market was only open for less than 30 minutes before circuit breakers (which have since been suspended) were triggered, ending the day down 7%.

    Meanwhile, pessimism surrounding Apple continues to build as well, in part because China is such an important market for the Mac maker. But there are two important reasons why all of the China-related storylines won’t affect Apple as much as you might think.

    China’s stock market participation is very low
    It’s true that China’s stock market is largely dominated by retail investors instead of institutional investors (a stark contrast to the U.S.), with an estimated 90% of all capital accounts owned by retail investors. Chinese investors also tend to be short-term traders instead of long-term investors, which contributed to heightened volatility.

    But it’s also true that overall stock market participation is fairly low in China, so the gyrations aren’t directly affecting the average consumer. For example, the Southwestern University of Finance and Economics in Chengdu conducts a regular China Household Finance Survey led by professor Gan Li. According to the survey, just 6% of households in China owned stock during the first quarter of 2015.

    So while the volatility of the Chinese stock market makes for some panicky headlines, the average Chinese consumer’s discretionary spending and income is just fine. They can still go out and buy that iPhone.

    China’s slowing GDP growth is not affecting the mainstream consumer
    The other recurring theme is China’s slowing macroeconomy, as evidenced by decelerating GDP growth rates. But again, these GDP figures aren’t directly translating into reduced income or spending on the consumer level. Quite the contrary, in fact.

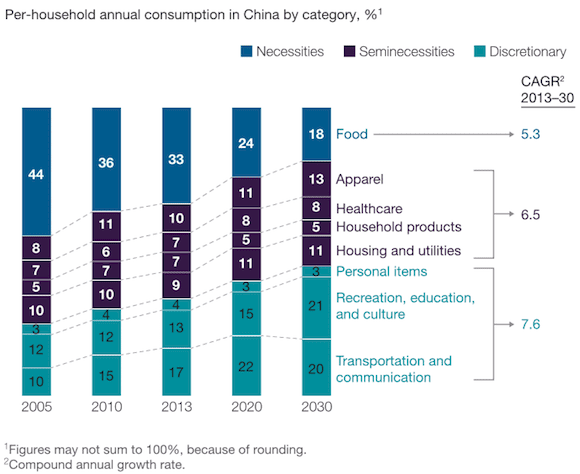
    Much of China’s GDP growth over the past decade has been driven by investing and exports, but China’s economy is now transitioning toward consumer consumption, which will only benefit consumer-oriented companies like Apple. Consider per-household annual consumption by category from 2005, along with forecasts through 2030, where discretionary categories are growing the fastest:

    China Spending

    Source: McKinsey.

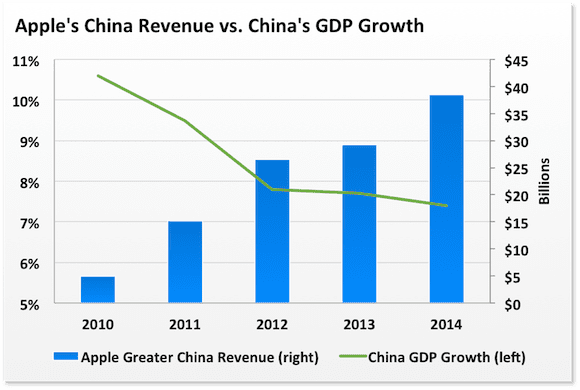
    Or consider the fact that Apple’s China business has grown incredibly against a backdrop of slowing GDP:

    Aapl Gc Vs Gdp

    Source: SEC filings and The World Bank. China GDP growth measured in constant local currency. Calendar years shown.

    The rising middle class in China won’t be stopped, and that’s good news for Apple.


  • Thailand cracking down on foreign-controlled firms using locals as nominees

    Thailand cracking down on foreign-controlled firms using locals as nominees

    The Commerce Ministry’s Business Development Department will this year expand its investigation into the use of Thai nationals as nominees for foreign-controlled companies in nine provinces where it suspects the illegal practice is widespread.

    This year, three additional provinces will be monitored – Krabi, Trat (Koh Chang), and Chiang Rai. Last year, six provinces were focused on – Bangkok, Chon Buri, Surat Thani, Prachuap Khiri Khan, Chiang Mai, and Phuket – and 13 firms were suspected of breaching the Foreign Business Act (FBA) through the use of Thai nominees.

    Pongpun Gearaviriyapun, director-general of the department, said it would tackle this practice vigorously this year through stringent law enforcement in a bid to prevent problems occurring under the FBA.

    She said the department would extend its investigation of nominee cases to 10 business sectors – food and beverages, tourism, property rental, the property trade, car rentals, spas, handicraft and souvenir retail, Internet retailing, direct sales, and education consultants.

    She said those sectors would be targeted because it was believed that a high proportion of their businesses were foreign controlled through the use of Thai nominees.

    She said the department would stringently investigate those businesses in an effort to prevent enterprises and consumers being affected negatively as some foreign-owned businesses were engaged in unscrupulous activities to lure consumers.

    The inspections will focus on a business’ share structure, investment capital, and technology transfer.

    Last year, the department investigated six sectors – food and beverages, tourism, car rentals, property rental, property sales, and spas.

    Meanwhile, to facilitate foreign enterprises doing business in the country, the department is considering relaxing its regulations under the FBA. This would involve them not having to get the FBA board’s permission to operate under the act.

    Businesses that would benefit from the move include representative offices, companies that are state-owned contractors, and subsidiary firms.

    In addition, the department will focus on supporting the starting up of new enterprises and strengthening local business growth under the ASEAN seamless market.

    The department will also develop its electronic services, such as e-registration, e-filing, and e-service applications, to help enterprises register, submit account balances, and update information online so they can save costs and time.

  • Learn to build winning portfolio with new investment series

    Learn to build winning portfolio with new investment series

    Here’s your chance to learn how to build a winning portfolio amid the uncertain market.

    Over the next 12 months, The Sunday Times will feature a new series that will showcase and track the simulated portfolios of three types of retail investors. The year-long Save and Invest Portfolio Series campaign aims to encourage and equip investors with the knowledge to save for the future.

    The initiative will involve the Singapore Exchange (SGX) collaborating with CFA Society Singapore and MoneySense, the national financial education programme.

    Starting next Sunday, the series will feature simulated portfolios of a young working adult, a married couple with two young children and a retiree.

    Their portfolios are guided by a panel of four CFA charterholders who are volunteers with CFA Society Singapore and have 77 years of experience collectively as investment professionals.

    SMART INVESTING

    We are excited about this initiative that showcases real-life investment portfolios of people at different life stages that the average investor can relate to. This series is an extension of SGX’s commitment to educating and engaging our retail investors, and to arm them with skills and confidence.

    MS LYNN GASPAR, head of retail investors at SGX.

    The series aims to guide retail investors in basic investment techniques and how to build a portfolio in accordance with their investment goals and risk tolerance.

    The portfolios will be tracked over 12 months. Different types of investment instruments and choices, including relatively new ones such as the Singapore Savings Bonds, will be introduced.

    Mr Lee Boon Ngiap, Monetary Authority of Singapore’s assistant managing director of capital markets, says it is essential to save and invest for the long term to grow our retirement nest egg.

    He says: “In investing, one should consider one’s goals, investment objectives, existing commitments and risk appetite.

    “We encourage the public to visit the MoneySense website and Facebook page which regularly feature informative guides and useful articles on investing.”

    He adds that the Save and Invest Portfolio Series will help enhance financial knowledge and complement MoneySense in empowering investors to make better-informed decisions.

    Ms Lynn Gaspar, head of retail investors at SGX, says: “We are excited about this initiative that showcases real-life investment portfolios of people at different life stages that the average investor can relate to. This series is an extension of SGX’s commitment to educating and engaging our retail investors, and to arm them with skills and confidence.”

    She adds: “We hope this will set the momentum for more investors to start or progress in their investing journey.”

    The SGX Academy and CFA Society Singapore will jointly host six public seminars that are aligned with themes featured in the series.

    These seminars will allow retail investors to meet SGX Academy trainers and CFA Society professionals.

    Ms Jan Richards, president of CFA Society Singapore, says one of the most fundamental and effective ways to protect investors is to equip them with the knowledge and tools to make informed decisions.

    “This has become ever more imperative as global markets remain uncertain and the investment environment challenging,” she adds.

    “We hope that the Save and Invest Portfolio Series can introduce The Sunday Times readers to a more disciplined way of investing, inspire them to learn more and eventually help them grow their hard-earned savings into a comfortable nest egg.”

    Business editor Lee Su Shyan believes readers will get an in-depth look into how different investing decisions play out in real life. She says: “We at Sunday Times Invest feel very strongly about financial literacy and this series will enhance retail investors’ understanding of investing.

    “Readers are welcome to write in with their views and suggestions to Invest editor Lorna Tan.”

    Watch this space.

  • Singapore retail sales up 4.7% year-on-year, boosted by car sales

    Singapore retail sales up 4.7% year-on-year, boosted by car sales

    ONCE more, a massive double-digit surge in motor vehicle sales pulled up Singapore’s retail sales in November. In year-on-year terms, retail sales grew 4.7 per cent, according to data released by the Department of Statistics on Friday.

    Excluding the significant 59.7 per cent jump in car sales, retail sales would have actually fallen 2 per cent.

    The total retail sales value in November 2015 was estimated at S$3.5 billion, higher than the S$3.3 billion in November 2014.

    Apart from car sales, only two other segments – department stores and medical goods and toiletries – experienced growth. The former rose 1.3 per cent year-on-year in November, and the latter, 9.6 per cent.

    All other segments reported a slippage in retail sales, with the worst-performing category being petrol service stations, with a 15.8 per cent drop. Food and beverages followed, with a 11.4 per cent decrease.

    On a seasonally-adjusted basis, retail sales increased 1.4 per cent in November over the previous month.

    Excluding motor vehicles, however – sales of these fell 0.6 per cent month-on-month – retail sales would have increased a larger 1.9 per cent from October.

  • ‘Don’t blame retail investors for China’s flash crash’

    ‘Don’t blame retail investors for China’s flash crash’

    Picture this: the market plunged 9 percent in around 30 minutes of hectic trading. Regulators raced to contain the damage, that was estimated in the trillions. Later, the plunge was repeated with a market collapse of 6.5 percent as 1,100 points were wiped in about five minutes. Trading was halted multiple times and circuit breakers were praised for preventing a full-on market crash of epic proportions.

    It just goes to show that this is an untrustworthy, poorly developed market that has to be managed externally by imposing trading halts.

    Hang on, there’s just one problem with this assumption. The 9 percent plunge happened on May 6, 2010. It was the infamous Flash Crash on the New York Stock Exchange. The second 6.5 percent fall was the August 24, 2015 flash crash, also on the NYSE.

    And rather than signaling the end of the financial world as we know it, markets simply shrugged their collective shoulders and moved on.

    But analysts seem to apply a different yardstick to the China market and are using this week’s Shanghai Composite flash crash to highlight what they see as China’s economic disaster.

    This is more than easily dismissed as double-standard analysis, because closer examination suggests some alternative explanations.

    Let’s first go back to the US flash crashes. The 2010 crash was widely attributed to the activity of exchange traded funds (ETFs). The 2015 crash was attributed to high frequency trading because sell algorithms cascaded in a falling market.

    The true reasons are certainly more complex, but it’s the nature of these suspects that is interesting because they highlight the connection between the derivative markets and the underlying market.

    One of the key connections is the rapid placement and withdrawal of trading orders that lies at the core of high frequency trading. These are placed in the futures and associated markets. In its subsequent investigation, the Commodity and Futures Trading Commission (CFTC) concluded that this activity was at least significantly responsible for order imbalances in the derivatives market, which in turn affected the stock market.

    The key feature is that these types of extreme and rapid market collapses are most often associated with markets dominated by derivative trading. These crashes are caused by institutional trading from ETFs and HFT. They are not caused by mums and dads trading because mums and dads simply do not act in such a coordinated fashion in such a short timeframe. Mums and dads also do not have the leverage to shift markets in this way within 30 minutes or an hour. That power lies in the hands of large-scale derivative traders.

    So, heres the rub. The onshore China market is dominated by retail traders. The offshore derivative market is dominated by institutional funds and ETFs and trading activity has been facilitated by the Shanghai-Hong Kong Stock Connect that opened in November 2014.

    Chinese authorities have been concerned for some time by allegations of Qualified Foreign Institutional Invetor (QFFI) funds being used in offshore shadow derivative trading. In June 2015 there were claims that the Shanghai index sell-off from the high of 5,176 was preceded by a spike in the placement and rapid removal of sell orders that is typical of HFT activity. It took the CFTC 4 years to deliver a final report on the 2010 Flash Crash so its unreasonable to expect a CSRC report on the June 2015 fall anytime soon.

    The January 1 Shanghai flash crash has all the characteristics of the NYSE flash crashes but in a market that is not dominated by fund managers and institutional trading. It’s the imposition of circuit breaker-thinking, imported directly from the flash crash-vulnerable NYSE market, that stopped this Shanghai flash crash from worsening.

    It’s convenient but far too simplistic to blame Chinese retail traders. The pattern of order placement in the physical and derivative markets need further investigation.


  • Maybank Launches Market Outlook Roadshow Across Malaysia

    Maybank Launches Market Outlook Roadshow Across Malaysia

    Maybank Investment Bank has just kicked off their annual Market Outlook 1H 2016 investors’ roadshow across Malaysia for this year’s investment strategies.

    The Market Outlook is aimed to share stock market views and investment strategies on the Malaysian, Hong Kong, and US markets with their retail equities clients, with the roadshows behind held in the multiple states Johor, Penang, Ipoh, Kota Kinabalu, Kuching, Sibu, Seremban, and Kota Bahru and Kuala Lumpur from 9 to 30 January 2016.

    Present during the launch was Head of Retail Equities (Malaysia) CK Lim, Head of Regional Retail Research Ong Seng Yeow, Regional Chartist Lee Cheng Hooi, Head of Retail Research (Hong Kong) Benny Wong and CEO of i-VCAP Mahdzir Othman.


  • What’s Driving China’s Stock Market Selloff?

    What’s Driving China’s Stock Market Selloff?

    Just as they did when Chinese stocks swooned in July, global investors appear to be learning the right lessons about China for all the wrong reasons. Investors who can see through the haze and confusion can keep picking up bargains in undervalued markets like Indonesia.

    First and foremost, the latest stock-market turmoil does not mean that China’s economy is in a meltdown. Yes, China’s economy is still slowing as investment retreats and exports decline. Spending by China’s emerging middle class remains a bright spot. But the service sector’s growth isn’t powerful enough to counteract the slowdown in China’s industrial sector. Most predictions are for growth of roughly 6.4% this year, slightly below the government’s 6.5% target.

    What’s driving the selloff? Not global investors jittery about China’s growth prospects. China’s markets remain highly restricted to foreigners, who represent a tiny fraction of trading. On the contrary, trading in China is dominated by domestic, retail investors. This makes the market relatively volatile. Retail investors everywhere tend to trade more frequently are more prone to herd behavior. Many in China fled the market after last summer’s turmoil, which has left the market in the hands of an even smaller group of jittery, retail punters.

    That’s why China’s new circuit breakers turned out to be such a bad idea. Intended to halt panics so cooler heads could prevail, the trading curbs proved too narrow for a market as volatile as China’s. In the U.S., a much less volatile market, trading pauses for 15 minutes if the S&P500 drops 7% or more and halts for the day only if the index falls 20%. China’s circuit breaker imposed a 15-minute halt after a 5% drop and halted trading if its CSI300 index fell 7%, a fluctuation all too common last year. So as stocks started falling, retail investors nervous they might be frozen into positions if the circuit breakers tripped joined the stampede to sell. The circuit breakers thus heightened volatility. Realizing this, regulators scotched the breakers Thursday night.

    Most of these domestic, retail investors in the stock market aren’t middle-class consumers. They’re relatively affluent individuals who invest a conservative portion of their net worth in stocks. Volatility in China’s stock market therefore poses little threat to the overall wealth of China’s middle class and its ability to spend.

    So what caused these wealthy punters to take flight? Because China’s economy is so tightly controlled by the government, and the stock market so dominated by big government-controlled companies, investors in Shanghai have long looked to signals on policy, rather than corporate profits, to drive markets. Beijing’s intervention in the stock market last summer has only reinforced this logic. So signals over the weekend that President Xi Jinping might favor painful economic reform over feel-good stimulus measures touched off this week’s selling.

    Does that mean we shouldn’t be worried? Absolutely not. While China’s slowdown by itself isn’t enough to derail global growth, it won’t help. As times get tougher, growing labor unrest is a worrisome red flag. And the more growth slows, the more difficult it will be for China Inc. to service a mountain of corporate and local government debt that by some estimates has swelled to 250% of GDP. China is inching closer to a possible credit crisis.

    That’s particularly true now that China has removed its gloves to join the global currency war already underway between Japan and Europe. It fired a shot across the bow in August with a one-time depreciation of its currency, the yuan. Then in December, the People’s Bank of China started marking the yuan down with the currencies of China’s major trading partners.

    Some economists believe most of that revaluation lower is complete. Not likely. Central banks in Europe and Japan, which are using weaker currencies to try to revive growth, will now likely need to push their own currencies lower still, which will prompt China to nudge the yuan lower with them. That creates a vicious circle of depreciation.

    Worse, China’s decision to move the yuan lower appears to be accelerating what was already a torrent of outflows by Chinese savers eager to get their cash out of the way of the slowing economy and a widening crackdown on corruption. China is trying to discourage the outflows by cracking down on foreign-exchange transactions and even trying to influence rates for yuan offshore. But the vacuum of funds out of banks is pushing up the cost of credit, forcing the PBoC to print yet more yuan to inject into the banking system – a measure that stands to weaken the yuan even further. And Jefferies warns that liquidity is likely to tighten even more ahead of the Lunar New Year holidays a month from now.

    A weaker yuan will ultimately be good for China’s exporters and stocks. But because it inflates China’s economy by exporting deflation, the cheaper yuan is bad for economies that rely on exporting to China, like Australia, or that are using a weaker currency to try to inflate their own growth, like Japan.

    Not surprisingly, stocks in Australia and Japan suffered the biggest declines in Asia outside China this week, falling 5.8% and 5.4%, respectively. Also hit hard was South Korea, which has one of the region’s highest exposures to China’s import demand. Stocks there have dropped 2.8%.

    But the turmoil doesn’t alter the overall outlook for regional markets this column laid out earlier this week. Because it’s most likely to enjoy government support, China’s stock market is still likely to outperform its neighbors’. And stocks in a handful of Asian markets still stand to exceed investors’ rock-bottom expectations. This week’s declines have made stocks in Jakarta, for example, even more attractive.

    Comments? E-mail us at wayne.arnold@barrons.com

    Comments? E-mail us at asia.editors@barrons.com
  • Singapore retail sector kept at ‘neutral’ by OCBC, picks Sheng Siong, Thai Bev

    Singapore retail sector kept at ‘neutral’ by OCBC, picks Sheng Siong, Thai Bev

    OCBC reiterates its “neutral” stance on Singapore’s retail sector, but says opportunities exist in companies that are able to weather the current gloomy sentiment.

    The house notes that the year has started on a bleak note with volatile stock markets and a World Bank report flagging continued fears over developing economies, especially China.

    Singapore reported stronger fourth quarter growth, but the economy logged its lowest pace of growth in six years in 2015.

    OCBC believes its “picks in the sector exemplify stability and are able to ride out the gloomy sentiment.”

    OCBC has “buy” recommendations on Sheng Siong Group, QAF and Thai Beverage.

  • Luk Fook same store sales down 26 pct in SARs for fiscal Q3

    Luk Fook same store sales down 26 pct in SARs for fiscal Q3

    Hong Kong-listed jewellery retailer Luk Fook Holdings (International) Ltd. saw a 26 per cent year-on-year decrease in its same store sales from Hong Kong and Macau shops for the three months ended December 2015, the biggest decline since the final quarter of 2014.

    During the third quarter fiscal, Luk Fook saw a decline of same store sales of 26 per cent year-on-year in gold from its shops in both Hong Kong and Macau, while that of gem-set jewellery fell 27 per cent, the company told the Hong Kong Stock Exchange after trading hours on Wednesday.

    The exact sales revenue figures were not disclosed in the retailer’s Wednesday filing, and the sales performance disclosed by the company only covered sales from its self-operated shops, while the sales of licensed shops and e-commerce business was excluded.

    The same store sales of Luk Fook’s group-wide retail business was down 25 per cent in the fiscal third quarter, as the retailer also saw a drop of 10 per cent in its shops in Mainland China.

    According to the filing, Luk Fook blamed the sales decline in the third quarter on ‘continuing overall sluggish retail sentiment’ and a relatively high base in sales figures.

    As at the end of last year, Luk Fook ran 96 self-operated shops on the Mainland, 47 shops in Hong Kong, 10 in Macau and 6 overseas. The jewellery retailer ran another 1,261 licensed shops on the Mainland and in Korea.

  • Is Amazon moving into the ocean freight business?

    Is Amazon moving into the ocean freight business?

    Amazon has garnered a lot of attention recently for its moves to muscle into nearly all miles of delivery, and this development shows it’s apparently willing to log nautical miles as well.

    An ocean freight forwarder organizes shipments from suppliers to far-flung receivers, which Flexport calls a $350 billion market. An entry into the ocean freight forwarding market could be significant because it could allow Chinese factories a more direct path to American consumers, Flexport CEO Ryan Petersen noted.

    In fact, while Amazon could smooth logistics or make them cheaper for its Marketplace sellers, those sellers aren’t likely to take Amazon up on that. That’s because they’re unlikely to be willing to give Amazon, a rival retailer, the kind of information that an ocean freight company would be privy to, Petersen said. And it’s likely that any full-blown development of Amazon’s ocean freight forwarding capabilities is still months, if not years, away.

    Still, the move could be a boon to Chinese sellers interested in reaching the American market as well as Amazon’s other markets globally, especially considering the expectation that Amazon would keep costs down.

    “I don’t think people realize how threatening this is for their U.S.-based merchants, who are making money selling goods from Chinese factories,” Petersen told Retail Dive. “It makes sense for Amazon, for a company so focused on driving down costs. But considering that 40% of their business comes from their Marketplace, it would have to be a graceful transition and managed really well.”

    The registration means that Amazon China can provide freight forwarding services to Chinese companies looking to move products directly into Fulfillment by Amazon warehouses, or “even cross-docking the goods for direct injection into Amazon’s courier network,” according to Petersen.

    While some may think that Amazon has Alibaba in its sights with such a move, Petersen believes it may, if anything, be an answer to Wish, a mobile e-commerce platform that has built much of its fortunes so far on bringing Chinese sellers to customers in the U.S. and elsewhere.

    “We think we’re going to be the second or third trillion-dollar-a-year marketplace,” Wish CEO Peter Szulczewsk. “We think Alibaba will be first and then it’s either us or potentially Amazon depending on how quickly, or if, they win in India.”

    Taking on the ocean freight market “to create a streamlined, vertically-integrated system for Chinese factories to sell directly through Amazon would be a classic Bezos response to Wish’s threat,” Petersen said, predicting that “Amazon’s ocean freight offering could be a huge hit for Chinese merchants.