Tag: bonds

  • Exploring Barriers to the Growth of Green Bonds in India’s Eco-Friendly Investment Landscape

    Exploring Barriers to the Growth of Green Bonds in India’s Eco-Friendly Investment Landscape

    The trajectory of India’s green bonds is expected to climb steadily as the nation pushes towards a low-carbon economy. However, a new analysis from the Institute of Energy Economics and Financial Analysis (IEEFA) unveils a constellation of challenges that could throw a wrench in this optimistic outlook.

    Obstacles Looming Over Green Financing

    In their latest briefing note, IEEFA identifies several hurdles that threaten to stifle the scalability of green bonds, which are vital for financing sustainable projects. Labanya Prakash Jena, a sustainable finance consultant at IEEFA and co-author of the analysis, emphasizes the need for robust monitoring and reporting mechanisms. Without these, greenwashing becomes more prevalent, potentially undermining the very purpose of green bonds.

    The landscape is further complicated by inconsistent definitions, verification processes, and reporting standards for green bonds in various jurisdictions. While frameworks like the Green Bond Principles from the International Capital Market Association and the Climate Bonds Standard aim to create consistency, Jena’s collaborator, Vandana Vuppuluri, noted that their interpretation can vary widely from one market to another.

    The Cost Conundrum

    Another significant barrier is the high cost associated with issuing green bonds. This financial burden has resulted in an uneven playing field, largely favoring well-resourced corporations and sovereign entities. “It’s crucial to recognize that the green bond market remains relatively small compared to the broader bond market,” Jena states. “This limitation restricts investment opportunities and casts a long shadow on transparency, as securing consistent post-issuance reports about environmental impacts can deter potential investors.”

    While green bonds are not a panacea for climate issues, Vuppuluri insists they hold essential value in financing a transition to a low-carbon future. “Success relies on how well market dynamics, regulatory frameworks, and stakeholder commitment coalesce around environmental objectives,” she asserts. And remember, as challenging as the road ahead may seem, a little creativity can often turn obstacles into stepping stones—just ask any aspiring entrepreneur navigating the bustling streets of Delhi!

    Questions & Answers

    What are the main challenges facing India’s green bond market?
    The key challenges include a lack of robust monitoring and reporting mechanisms, inconsistent definitions and regulations across jurisdictions, and the high cost of issuing green bonds, which limits participation to well-resourced entities.

    How do varying frameworks affect the green bond market?
    While frameworks like the Green Bond Principles and the Climate Bonds Standard exist to establish coherence, their interpretation can differ significantly across markets, leading to confusion and inconsistency in green bond issuance.

    What role do green bonds play in battling climate change?
    Although they are not a standalone solution, green bonds are critical for financing initiatives that support a transition to a low-carbon economy, with their success contingent on effective regulation and stakeholder commitment to environmental goals.
  • Vietnam stocks slip as Asian shares subdued

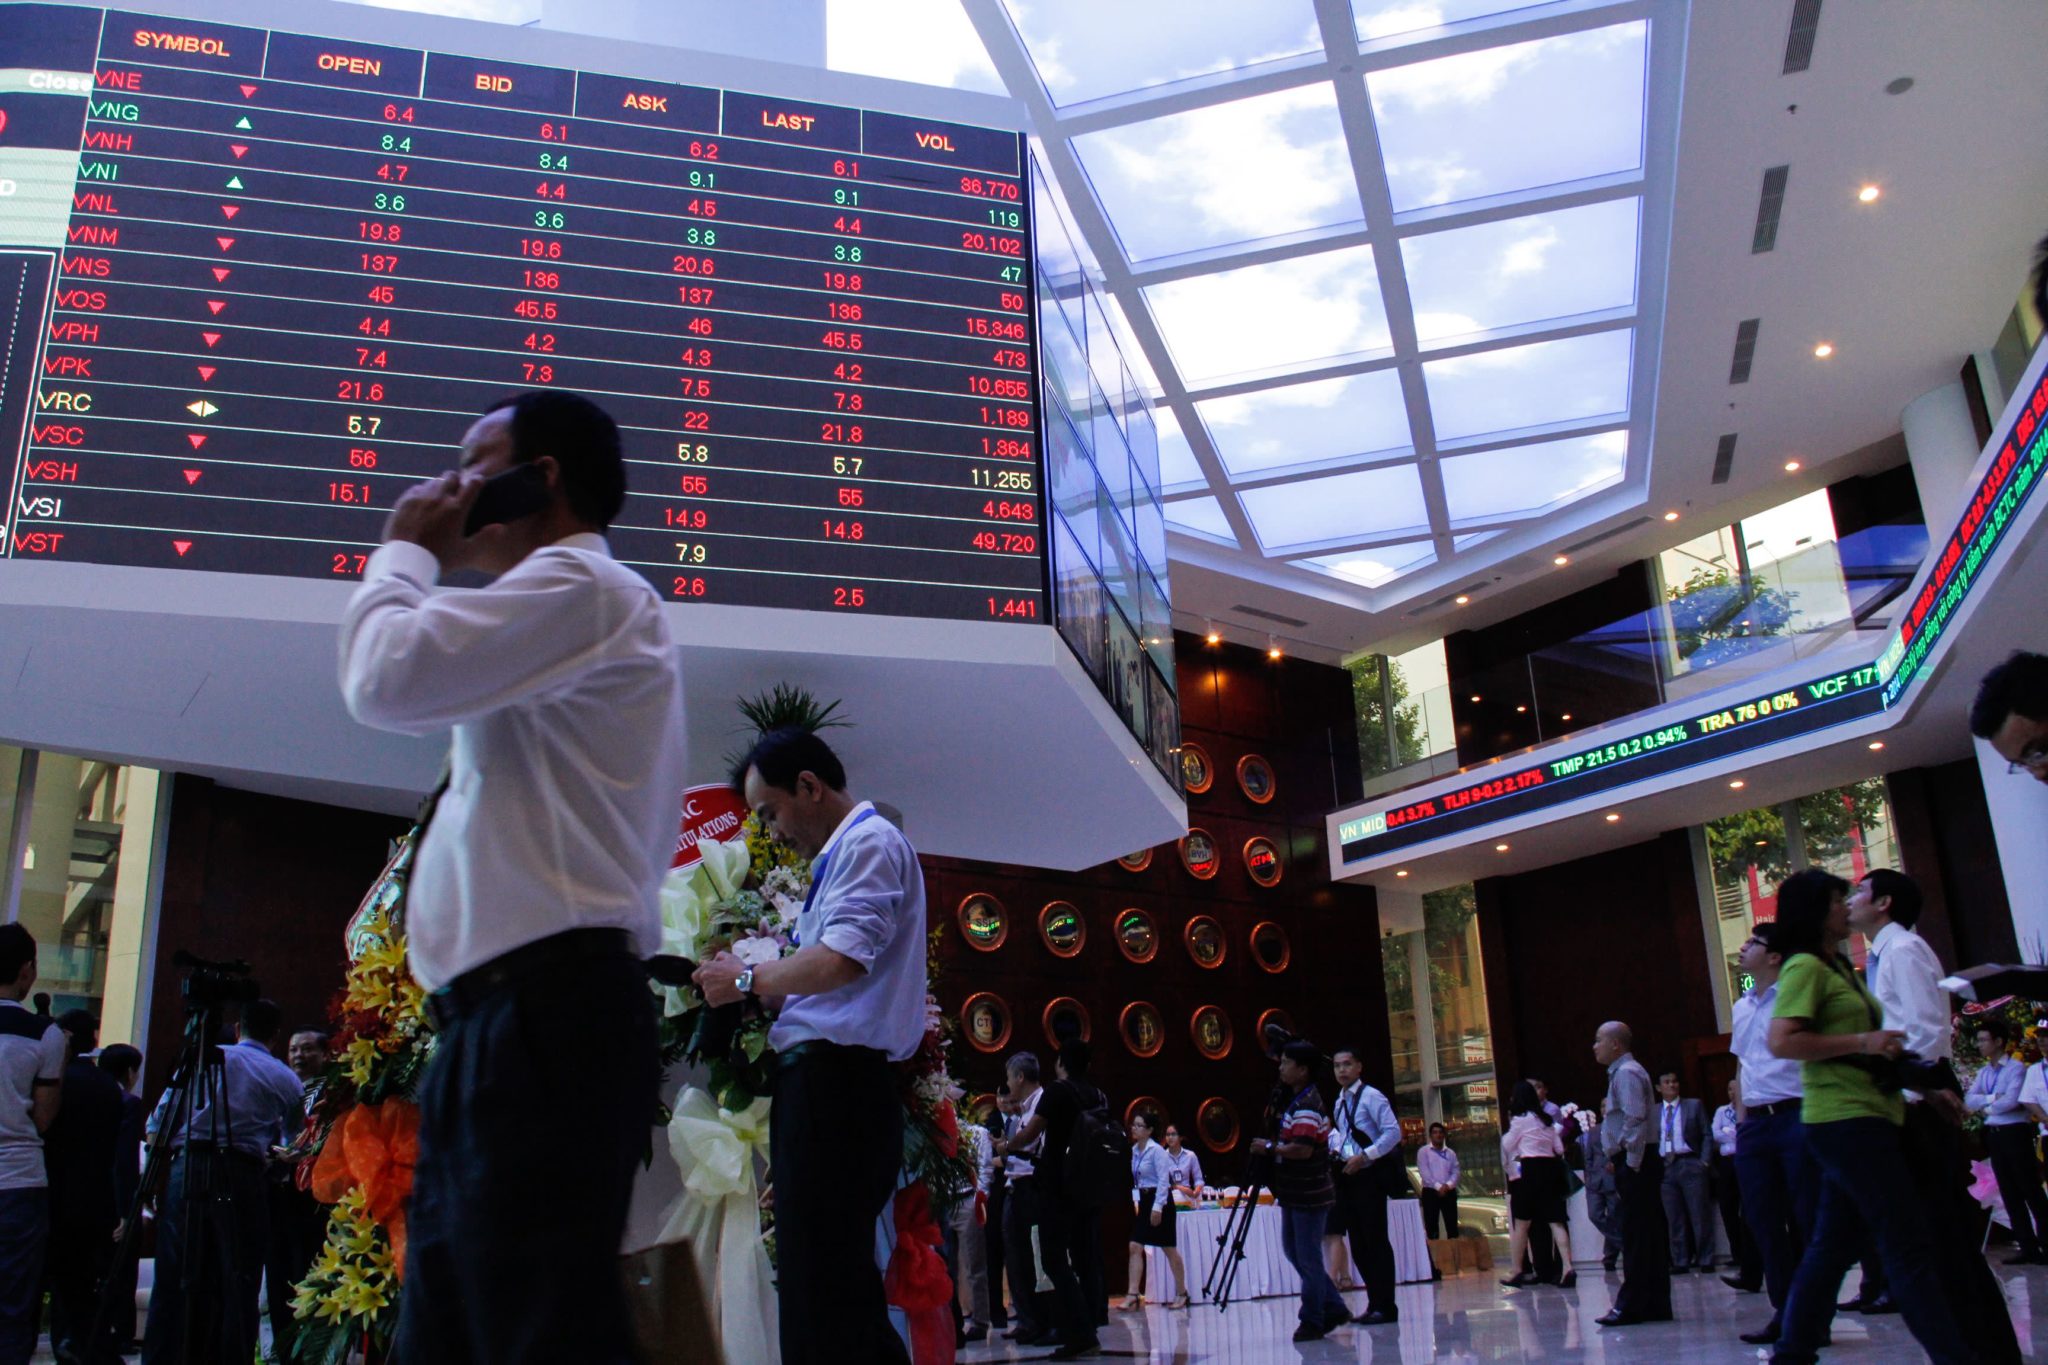
    Vietnam stocks slip as Asian shares subdued

    Vietnam’s benchmark VN-Index fell 0.59% to 1,268.21 points Thursday as other Asian markets were little changed.

    The index closed 7.59 points lower after dropping 8.07 points in the previous session.

    Trading on the Ho Chi Minh Stock Exchange increased by 6% to VND16.59 trillion (US$671 million).

    GVR of Vietnam Rubber Group plunged 2.3%, followed by PLX of fuel distributor Petrolimex, down 2%.

    FPT of IT giant FPT Corporation and MBB of lender MB both fell 1.8%.

    Three blue chips gained, led by VHM of property giant Vinhomes, up 2.9%, and VIC of private conglomerate Vingroup, up 2.4%.

    Foreign investors were net sellers to the tune of VND684 billion, mainly selling FPT and HPG of steelmaker Hoa Phat Group.

    The HNX-Index for stocks on the Hanoi Stock Exchange, home to mid and small caps, fell 0.50%, while the UPCoM-Index for the Unlisted Public Companies Market went down 0.30%.

    Asian shares were subdued on Thursday, with Japanese stocks sliding to their lowest in three weeks as investors sought safety, pushing the yen to a one-month high while U.S. economic worries boosted prospects for the Federal Reserve to cut rates.

    Amid the fragile sentiment, Japan’s benchmark Nikkei slid more than 1% to its lowest in three weeks, while stocks in tech-heavy Taiwan and South Korean stood slightly higher on the day, giving up earlier gains.

    The MSCI’s broadest index of Asia-Pacific shares outside Japan up 0.25%, subdued after having tumbled nearly 3% during a three-day losing streak. The index had risen more than 0.6% but gave up those gains.

  • Sole bond issuance recorded in October

    Sole bond issuance recorded in October

    Only one private bond issuance was recorded in October, indicating that companies remain reluctant to mobilize cash using this channel after recent arrests of alleged fraudsters.

    Nui Phao Mining Company under the Masan Group was the only corporate bond issuer last month with a batch of VND210 billion ($8.45 million) with a five-year maturity.

    This is very unusual as banks and property developers have been the biggest bond issuers in Vietnam for several years now.

    Financial data provider FiinRatings said in a report that the rising interest rates, tightened bond regulations and recent violations in the market have restrained companies from mobilizing cash through bonds.

    The alleged violations of An Dong Investment Group and other companies like property developer Tan Hoang Minh, as well as the arrests of their leaders, have raised red flags for businesses.

    They are now buying back the bonds they have issued. Last month, VND5.8 trillion worth of bonds was bought back.

    Banks accounted for 53% of the buyback value, followed by property developers at nearly 22%.

    The buyback has helped ease payment pressure on companies this year as they only have VND21.85 trillion worth of bonds set to mature after November 15.

    But next year, the value of bonds set to mature will be high, at VND119.05 trillion, and in 2024 it will be VND111.81 trillion.

    FiinRatings analysts expect more debt restructuring moves to be carried out soon. Some of the methods being used are an extension of debt payment with new coupon rates, converting the bonds to long-term loan contracts with new interest rates, or converting them into property units.

    “This is a positive signal for the current liquidity issues on the market as it helps reduce the payment burden in the short term for bond issuers,” they say.

    With mobilizing capital domestically proving very difficult, companies are seeking international loans.

    Ten major loans have been recorded recently with a total value of $1.92 billion, including that of the Masan Group ($600 million), VPBank ($500 million) and SeABank ($200 million).

  • DBS Launches Digital Bond Marketplace

    DBS Launches Digital Bond Marketplace

    The bank is launching a marketplace that for issuers to directly issue their own bonds connect with investors.

    DBS is launching the Fixed Income Exchange (FIX) to digitalize and make the bond issuance process more efficient, the bank announced on Tuesday in a statement.

    FIX allows issuers to directly issue bonds to the marketplace, and fully digitalizes and automates issuance-related documentation. It also supports issuers in generating digital bond-ready transactions, which can be listed and traded on the DBS Digital Exchange (DDEx).

    Keppel Corporation is the first corporate issuer on the platform, with a $1 billion Euro-Commercial Paper Programme.

    With FIX, DBS said it hopes to make capital markets access more time and cost-efficient, while also developing the breadth and depth of Asian bond markets at a faster pace.

    The time is ripe for traditional ways of bond origination to make way for a more digital approach, to do what has been aspired for so long – by taking the first step towards the creation of an independent platform that allows bond issuers efficient and effective direct access to the market place and bond investors, Clifford Lee, global head of fixed income at DBS, said in the announcement.

    Just last week, domestic rival UOB piloted the digital issuance of its latest bond offering on exchange-operated digital asset issuance platform Marketnode, a joint venture between Singapore Exchange and Temasek.

  • Vietjet raises $43.6 mln from bonds

    Vietjet raises $43.6 mln from bonds

    Budget airline Vietjet has raised VND1 trillion ($43.61 million) from a domestic company to expand operations amid the Covid-19 pandemic.

    The bonds are without collateral with a maturity of five years starting from May 24.

    Revenues in the first quarter fell 56 percent year-on-year to VND4.05 trillion. In the same period, the company reaped post-tax profit of VND123.32 billion.

    The profit came from its other investment to make up for the loss in its main business that is taking hits from social distancing.

    It managed to lower operating costs by half and sales and administration costs by 39 percent.

  • DBS Obtains Bond Settlement Agent License in China

    DBS Obtains Bond Settlement Agent License in China

    DBS Bank (China) announced that it received a Bond Settlement Agent license in the China Interbank Bond Market, making it the first and only Singapore bank to be granted such a license.

    DBS Bank (China) has received a Bond Settlement Agent license from the People’s Bank of China to act as a bond settlement agent in the China Interbank Bond Market, the lender said in a statement on Tuesday. Prior to the license, DBS China has been involved in the China bond market as Trial Bond Market Maker in the China interbank bond market for years.

    This license will enable DBS China to serve overseas investors who are interested in the China bond market because from now on, we can provide the bond settlement or custody services to them.

    The China bond market is the largest in Asia and the second-largest in the world and is of significant interest to international investors. With the license, we look forward to introducing more overseas customers to the China bond market and providing our comprehensive service to international institutional investors said Neil Ge, CEO of DBS China in the statement.

    China’s onshore bond market worth was 88 trillion yuan ($13.12 trillion) in February last year, according to the country’s central bank. Since last April, the phased inclusion of Chinese sovereign bonds and debt sold by three key state-owned policy banks into the Bloomberg Barclays Global Aggregate Index has attracted a new group of investors into China’s domestic bonds.

    Up to then, inflows have been dominated by central banks and sovereign wealth funds. With the inclusion of China bonds into such indices, private-sector managers following the index would be looking to join the market.

  • ICBC Singapore Issues Bank’s First Green Bond

    ICBC Singapore Issues Bank’s First Green Bond

    State-owned bank offers green Silk Road bond in three currencies one week after a similar exercise by rival Bank of China. Acting through its Singapore branch, the Industrial and Commercial Bank of China (ICBC), the world’s biggest bank by assets, has issued its first green bond offering in three currencies totalling $2.2 billion equivalent, Reuters reported on Wednesday.

    The U.S. dollar-denominated tranche includes $900 million three-year floating rate notes priced at three-month Libor plus 72 basis points and $600 million five-year floating rate notes priced at three-month Libor plus 83 basis points. They received over $2.4 billion and $1.5 billion in orders respectively, with Asia buying 92 percent of the deal and the rest coming from EMEA in both cases, according to Reuters.

    The 1 billion yuan ($149 million) three-year tranche was priced at 3.3 percent. The 500 million euro tranche received over 1.8 billion euros in orders.

    DBS Bank was the only Singapore bank among the issue’s joint global coordinators, which also include ICBC, Credit Agricole, HSBC and Standard Chartered Bank. DBS was also the joint book runner and joint lead manager of the issue. There were 22 underwriters for the bond issue, which intends to support green projects under China’s Belt and Road Initiative.

    According to Clifford Lee, DBS Bank head of fixed income, said that ICBC Singapore’s successful issuance of its first green bond is underpinned by its commitment to financing sustainable development along the Belt and Road, «The Business Times» reported.

    A week before, Bank of China raised $3.8 billion equivalent across five currencies and eight tranches from its fifth Silk Road bond offering.

  • UOB Prices First Panda Bond

    UOB Prices First Panda Bond

    United Overseas Bank announced it has priced Singapore’s first Panda Bond at 3.49 percent, one of the lowest rates among all Panda bonds. The Singapore based lender UOB said that its three-year, 2 billion renminbi (S$404 million) offering garnered strong demand with a subscription rate of 2.7 times from asset managers and commercial bank investors across Asia. Thirty-eight percent was placed to China’s onshore investors and 62 percent to international offshore investors.

    «Our participation in China’s onshore debt market, one of the largest globally, enables us to grow our presence in China as the country continues to liberalize the renminbi and its financial markets. Further, through this offering, we can diversify our funding sources and continue to tap the increased connectivity between China and ASEAN arising from the Belt and Road Initiative to serve our customers’ needs,» said Wee Ee Cheong, CEO of UOB, said in a media statement.

  • Foreign flows into Asian bonds turn positive, Malaysia leads

    Foreign flows into Asian bonds turn positive, Malaysia leads

    Foreign flows into Asian bonds turned positive in October, in stark contrast to the sharp outflows faced by equity markets due to slowing earnings and concerns over trade. Data from central banks and bond market associations showed overseas investors bought a net US$2.24 billion (RM9.4 billion) in Malaysian, Thai, Indonesian, South Korean and Indian bonds in the last month. That compared with net outflows of US$2.46 billion in September.

    Malaysia’s bond market led the region with inflows of US$1.8 billion in October, the highest in 2018. At the end of last month, foreign ownership of Malaysian government securities rose to 40.7% from 39.5% in September, the data showed.

    Thailand and Indonesian bond markets also attracted foreign money of US$1.07 billion and US$886 million, respectively.

    “Thailand’s large current account surplus and growth recovery have boosted the perception of Thai debt as a relative safe haven in the region,” said Khoon Goh, Singapore-based head of Asia research for ANZ Banking Group in a note.

  • Vietinbank successfully issues bonds at low interest rate

    Vietinbank successfully issues bonds at low interest rate

    Vietnam Joint Stock Commercial Bank for Industry and Trade (Vietinbank) announced it successfully issued non-convertible five-year bonds worth VNĐ2 trillion (US$88.1 million) at annual interest rate of 5.8 per cent.

    Compared with the interest rates of other bond issued recently, the 5.8 per cent rate is considered the lowest rate. It is even lower than the interest rate of 7 per cent per year applicable for deposits of over three years in Vietinbank.

    Previously, in December 2016, Vietinbank also issued 10-year bonds worth VNĐ2.9 trillion at interest rate of 7.5 per cent in the first five years.

    Vietinbank reported a high profit of VNĐ8.25 trillion in 2016, 4 per cent higher than the target set at the bank’s general meeting of shareholders.

    As of December 31, 2016, the bank’s total merged assets were estimated at VNĐ947 trillion, up 22 per cent from the previous year.

    Also in 2016, the bank’s total outstanding loans were VNĐ720 trillion, a year-on-year rise of 18 per cent, while total mobilised capital reached VNĐ862 trillion, up 21 per cent. By the end of 2016, the bank continued to effectively manage the quality of assets with bad debt ratio of less than 1 per cent.

    The bank in 2017 has set a target of a 15-17 per cent rise in total assets and an 18 per cent increase in outstanding credit.

  • UOB Indonesia offers Rp 1.1 trillion in bonds to strengthen lending

    UOB Indonesia offers Rp 1.1 trillion in bonds to strengthen lending

    United Overseas Bank (UOB) Indonesia plans to issue Rp 1.1 trillion (US$84.5 million) in bonds in November. The issuance hopes to raise cash to support the bank’s lending capacity next year.

    UOB Indonesia president director Kevin Lam said Rp 1 trillion in proceeds would come from the senior bond while the remaining Rp 100 billion would come from the subordinated bond. Both will be offered from Nov. 17 until Nov. 22.

    “The bond will enable us to maintain solid funding as we help our customers seize business opportunities arising from increased infrastructure development and consumer demand,” he said during a public expose in Jakarta on Wednesday.

    The senior bond is divided into three series with a buy-back option, he further explained.

    Series A is offered with 370 days of maturity and a 7.4 percent coupon rate per annum. Series B will mature in 3 years with an 8.25 percent coupon rate. Series C will have a 5-year tenor with a coupon rate of 8.5 percent.

    Meanwhile, the subordinated bond has a 7-year tenor with a 10 percent coupon rate. All the coupons will be paid every three months.

    In the first half of 2016, UOB Indonesia saw its interest income increase by 22.32 percent year-on-year (yoy) to Rp 1.73 trillion.

    Net profits rose by 86.81 percent yoy to Rp 281.69 billion.

  • SM Prime’s P10B Retail Bonds Priced at 4.2005%

    SM Prime’s P10B Retail Bonds Priced at 4.2005%

    SM Prime Holdings, Inc. has set the interest rate for its Peso-denominated Series F, 10-year retail bonds at 4.2005% per annum.

    SM Prime will issue an aggregate principal amount of Php10.0 billion of the Series F bonds, which will be offered to investors through underwriters from July 13 to 19, 2016.

    The retail bonds will be issued on July 26, 2016. According to the underwriters, SM Prime received a strong demand for the retail bonds.

    The SM Prime bonds have been rated PRS Aaa by Philippine Rating Services Corporation (PhilRatings), the highest rating assigned by PhilRatings.

    Obligations rated PRS Aaa are of the highest quality with minimal credit risk, and denotes that the Issuer’s repayment capacity is extremely strong.

    This series of SM Prime bonds is the third offering of Peso-denominated retail bonds to the public.

    “The retail bond to be issued will sustain SM Prime’s development roadmap, which is geared towards provincial expansions mostly allotted on malls and offices developments. We remain optimistic on the huge growth potential in the provinces where large areas remain unserved.” SM Prime President Hans T. Sy said.

    The SM Prime bonds’ joint issue managers, joint lead underwriters and joint bookrunners are BDO Capital & Investment Corporation, BPI Capital Corporation, China Bank Capital Corporation and First Metro Investment Corporation.

    East West Banking Corporation, PNB Capital and Investment Corporation and United Coconut Planters Bank are participating underwriters for the bond issue.

    SM Prime remains committed to its role as a catalyst for economic growth, delivering innovative and sustainable lifestyle cities, thereby enriching the quality of life of millions of people.

    SM Prime Holdings, Inc’s stock was up 3.89% in today’s trading at the Philippine Stock Exchange.

    SPMH ended the day with a trade price of P29.40 a share, up P1.10 from the previous day’s trading.

    A total of 41 million SMPH shares, with a total value of P1.19 billion, exchanged hand today.

  • Hong Kong stocks extend sell-off as banking giant HSBC tumbles to 7-year low

    Hong Kong stocks extend sell-off as banking giant HSBC tumbles to 7-year low

    Hong Kong stocks closed at their lowest level since mid-2012 on Friday, extending steep declines from the previous day in a holiday shortened week, as index heavyweight HSBC tumbled to a seven-year low after the company decided to scrap a pay freeze plan aimed at cutting costs due to staff protests.

    The Hang Seng Index was down 1.2 per cent or 226.22 points at 18,319.58, the lowest close since June 2012. The index fell 3.9 per cent on Thursday after returning from the three-day Lunar New Year break, posting the worst loss to start a Chinese new year since 1994.

    For the week, it was down 5 per cent.

    So far this year, the Hang Seng Index has plunged more than 16 per cent, already more than doubling the annual loss of 7.2 per cent it rang up in 2015.

    The Hang Seng China Enterprises Index, or the H-shares index, settled 2 per cent lower at 7,505.37.

    Sino-British banking giant HSBC Holdings, one of the most-widely held stocks by Hong Kong retail investors, tumbled 2.7 per cent to HK$48.1, the worst level it has seen since April 2009.

    HSBC’s chief executive Stuart Gulliver wrote Thursday in a memo that the company would drop a pay freeze announced recently to cut costs, following feedback from its employees.

    Gulliver said the company would use the cash from the 2016 bonus pool to fund the pay rises, while also expressing his concerns for the bank’s revenue outlook in 2016 due to uncertainty around the global growth outlook and the interest rate environment.

    Among other market movers, Asian life insurer AIA Insurance fell 2.4 per cent to HK$37.25, and Chinese online major Tencent Holdings dropped 1.9 per cent to HK$133.3.

    Ben Kwong Man-bun, executive director and head of research of KGI Asia, said the Hong Kong market lacked clear direction and was taking its cue from hobbled overseas markets.

    “The global equity market is still under selling pressure. It’s because of the fearful sentiment of investors. They prefer to hold cash rather than assets,” Kwong said.

    The broader weakness in regional markets also added to the selling pressure on Hong Kong stocks. Japan’s Nikkei Average finished below 15,000 for the first time in 16 months, down 4.8 per cent at 14,952.6, as the yen, a traditional safe-haven currency, soared against the US dollar.

    On Thursday, global stocks entered a bear market, as the MSCI All-Country World Index, a gauge of global stock markets, had fallen more than 20 per cent from its most recent high in May 2015. US and European equities both took a hard hit, spurred by heavy selling in the banking sector on worries negative interest rates and low economic growth could hurt banks’ earnings.

    Going forward, analysts said stock markets still face a battery of threats ranging from slow growth, interest rate uncertainty, emerging market turmoil and heightened bad loan risks.

    “The global economy is really weak. Even after they did quantitative easing, it seems the central banks have failed to stop the slowdown,” Kwong said.

    However, Macau casino stocks bucked the weak trend, after Wynn Macau reported its operating revenues dropped by a less-than-expected 37 per cent in the fourth quarter of fiscal 2015. Shares of Wynn Macau jumped 3.6 per cent to HK$7.77, rival Galaxy Entertainment climbed 3.1 per cent to HK$23.25, and Sands China advanced 2 per cent to HK$24.75.

    Offshore oil producer CNOOC also recovered 0.4 per cent to HK$7.48 after crude futures bounced back in international markets.

    Chinese stock markets were still closed for the holiday on Friday and will reopen on Monday.

    However, some analysts expressed concerns A-shares may catch up with the global stock rout and fall sharply when they start trading next week.

    “It’s concerning,” said Li Tao, an analyst for Citic Securities. “The external markets were quite volatile during the Chinese new year break, particularly in the US, where stocks continued falling. The depressed state of the global economy may have a negative impact on the A-shares market.”

  • Jakarta index closes higher on Friday

    Jakarta index closes higher on Friday

    The Jakarta composite index (JCI) closed 42.61 points higher on Friday on selective buying by market players.

    The index of the Indonesian Stock Exchange rose 0.96 percent to 4,456.74 points with index of 45 blue chips up 1.48 percent to 779.31 points.

    Selective buying of big capitalization shares pushed up the JCI slightly, HD Capital analyst Yuganur Wijanarko said.

    “In addition, share prices in foreign markets generally rose on oil prices being on the increase lately , prompting market players on the domestic market to buy shares< he said.

    The price of WTI on Friday afternoon rose 4.3 percent to S$30.80 per barrel and Brent pri9ce was up 5.09 percent to US$30.74 dollar.

    Satisfaction expressed by the Capital Investment Coordinating Board (BKPM) with the achievement in direct investment to Rp545.4 trillion in 2015 gave positive sentiment to the market.

    In 2016, BKPM set growth target at 9.3 percent for direct investment to Rp594.8 trillion .

    There were 213,493 transactions in the market on Friday with 4.07 billion shares valued at Rp5.25 trillion changing hands .

    Regional markets such as Hang Seng, Nikkei and Straits Times recorded gain in index.

    Meanwhile the national currency rupiah closed stronger trading at 13,834 per U.S. dollar gaining from the previous level of 13,906 per dollar.

    “Rising trend of oil prices propped up the currencies of emerging countries ,” financial market observer from Bank Himpunan Saudara, Rully Nova, said.

  • More retail-friendly bond issues in 2016

    More retail-friendly bond issues in 2016

    Singapore’s fixed-income market next year is tipped to be active, with more retail-friendly issuances. What’s more, perpetuals will continue to be popular even as financial conditions are likely to remain volatile. Retail bond demand is expected to stay healthy and there should be more deals done than in 2015 – thanks to higher yields, said Clifford Lee, DBS Bank head of fixed income.

    Four retail bonds with yields of 3.85 to 5.25 per cent were sold in 2015 by Perennial Real Estate Holdings, Oxley Holdings, Frasers Centrepoint and Aspial Corp. Investors could buy these bonds for as low as S$2,000 per lot, much cheaper than the minimum S$250,000 for most bonds sold here.

    Mr Lee said retail investors are not dumb, unlike your “mom and pop” investors. “The smaller caps have smaller subscription, indicating they do have discretion.”

    While the retail offerings were oversubscribed, he said the oversubscription was not massive – an indication that retail investors know what they are doing.

    The four retail bonds raised S$1.25 billion, against just one issue from CapitaMall Trust in 2014 worth S$350 million.

    “Of the four issuers this year, three may even be ‘high yield’ – although none are rated – which may spur further issuance from other mid-sized firms which could offer higher yields on their retail bond issues,” said Terence Lin, iFast’s regional research manager in the fixed-income division.

    Investors, especially financial institutions and real estate investment trusts (Reits), are expected to still like perpetuals – bonds with no fixed maturity – in 2016, as they did in 2015.

    Seven perpetuals were sold this year which raised S$3 billion, almost double the S$1.8 billion for 2014.

    Mr Lin indicated that issues such as the new Julius Baer, Ascendas Reit perps and FCL perps have so far been among the most heavily traded bonds in the SGD corporate bond market in 2015. “We think their popularity stems from the higher yields offered versus traditional fixed maturity bonds (given the additional maturity uncertainty), while most of the perpetual bonds are still expected to be called on their first call dates (which are usually less than 5 years away), making them good alternatives to traditional short duration bonds,” he said.

    Also, he added, many of the perpetuals are issued by higher-quality names, offering investors a level of comfort.

    While more bank perpetuals are expected to be launched, as banks look to build additional capital, as well as to refinance maturing/callable debt, many non-bank corporate perpetuals are also maturing.

    Firms such as Hyflux, Cheung Kong, Olam International, GuocoLand, Global Logistic Properties, Hotel Properties, Mapletree, Mapletree Logistics Trust and Genting Singapore are some of the existing issuers of perpetual SGD debt which are callable in 2016/2017, making them potential refinancing candidates/perpetual bond issuers come 2016.

    Tan Kee Phong, OCBC Bank’s head of capital markets, estimated that US$33 billion in loans and S$13 billion in SGD bonds are set to mature from syndicated loans in 2016 in Singapore. Yet nothing can be taken for granted, according to Elaine Ngim, Coutts’ he ad of fixed income in Asia. “Two key factors that may determine if 2016 is a bull’s or bear’s year are how fast Fed will hike rates and how slow will China economic growth be,” she said.

    “China’s growth story will be the larger factor for Singapore, as its economy is trade dependant on their growth. As a result, investors may become increasingly selective on quality of issuers and their industry,” said Ms Ngim.

    DBS’s Mr Lee also said China would have the biggest impact on the Asian bond markets, because it accounts for the lion’s share of the Asian G3 (USD, yen or euro) bond arena.

    China-linked issuance in 2015 was 54 per cent or US$91 billion of the US$169 billion Asian G3 bond market. But offshore funding costs have ballooned and a lot of Chinese companies are now opting to issue onshore, Mr Lee indicated.

    “If China continues to issue onshore next year, then it (Asian credit market) could get a kick in the stomach,” he said.

    The SGD bond market was pretty solid in 2015, especially compared with equities. This year has seen 161 deals worth S$22.7 billion done, slightly less than the S$23.5 billion raised in 2014. The highest was S$31 billion in 2012.

    “2015 was comparatively a better year for bonds in Singapore when compared to the STI index, with main drivers being corporate bonds, specifically statutory board issuers in the 5-7-year maturity bucket,” said Ms Ngim.

    Up to Dec 11, the Singapore Fixed Income Indices for 2015 outperformed the STI by 17.64 per cent (1.87 per cent vs. -15.77 per cent).

    Despite the year starting out somewhat jittery, there was no lack of higher risk issuers, Ms Ngim said.

    “Looking back at these issues, 2015 is categorised by several buckets, namely the real estate developers and Reits who are listed on the SGX, shipping and the offshore support vessels, and closing off the year with a few global financial issuers,” she said.

    Still, some have found 2015 a challenging year for the SGD bond market.

    “We believe credit quality of issuers, on average, declined, with particularly significant weakness seen in commodity linked companies and in the offshore marine sector, which is a sizeable part of the SGD bond market,” said Neel Gopalakrishnan, Credit Suisse, director, emerging markets bond analyst, private banking Asia Pacific.

    “Secondary market liquidity was another issue with no meaningful bids available especially for higher yielding bonds, making it almost impossible for bondholders to exit their positions if they were uncomfortable with the underlying issuer,” he said.