Tag: coffee

  • Luckin Coffee Shares Rise to $33.20 After Beating Quarterly Earnings

    Luckin Coffee Shares Rise to $33.20 After Beating Quarterly Earnings

    Shares of Luckin Coffee Inc. Surged before Tuesday’s opening bell after the company reported quarterly earnings of $0.89 per share, beating consensus estimates of $0.83 by $0.06.

    The stock opened at $32.90 following a previous close of $31.20, eventually changing hands at $33.20 with 781,481 shares traded, which lifted the beverage chain’s market capitalization to $9.52 billion.

    Margins and Returns Hold Firm

    The China-based chain posted a net margin of 6.78 percent for the quarter alongside a return on equity of 24.91 percent. The company trades at a price-to-earnings multiple of 19.76, with a price-to-earnings-growth ratio of 0.46 and a beta of -0.34.

    Its 50-day simple moving average sits at $33.68, hovering slightly above its 200-day simple moving average of $33.47. Investors reacted by driving an immediate morning price gap, reflecting operational resilience in a competitive mainland drinks market where rivals continue to slash prices on freshly brewed coffee.

    Digital Fulfillment Anchors Growth

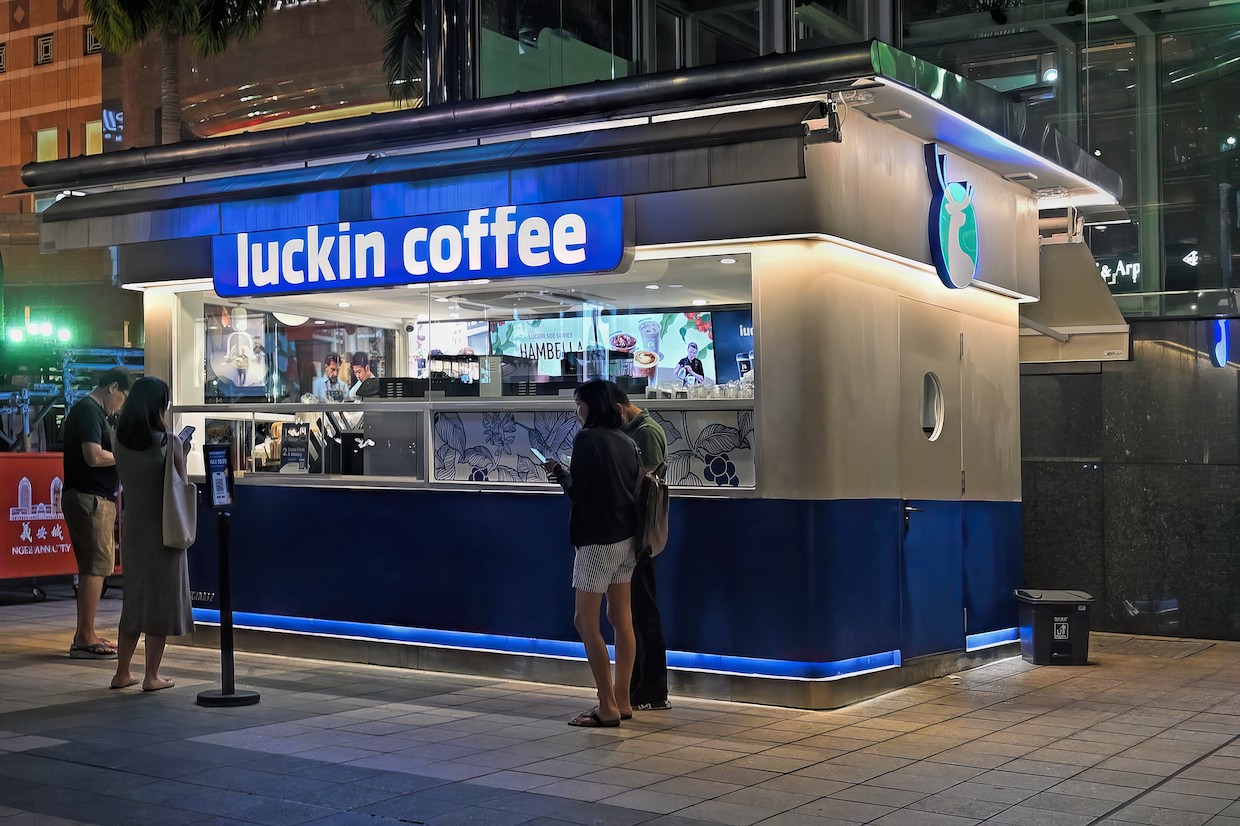
    Founded in 2017, Luckin Coffee built its footprint around small-format pickup booths and app-driven orders. Customers buy freshly prepared coffee, tea drinks, fruit juices and packaged light snacks almost exclusively through mobile software rather than traditional seated cafe counters.

    Fulfillment relies on a dual setup of self-operated flagship sites and franchised partner locations that keep overhead costs low. By sidestepping large floorplans and prime street-level seating, the chain protects unit profitability even when competing beverage chains launch aggressive discount coupons.

    Broker Sentiment Diverges

    Wall Street research desks hold divided stances on the stock’s runway. BNP Paribas Exane upgraded the company to an outperform rating on September 15 with a price target of $48.00 per share.

    Zacks Research moved in the opposite direction on October 5, cutting its view from strong-buy to hold. MarketBeat tracking shows four analysts covering the firm, yielding an average target of $46.87 alongside an overall buy consensus.

    Discounter Pressure on Mainland Operators

    The margin performance creates immediate headaches for competing coffee and milk-tea chains operating in tier-one and tier-two Chinese cities. Retail operators fighting for commercial real estate face high customer acquisition costs, but Luckin’s app ecosystem delivers repeat orders without retail concessions or heavy landlord rent burdens.

    The principal risk sits in domestic pricing fatigue. Sustaining a 6.78 percent net margin requires steady ingredient supply pricing and disciplined wage controls across thousands of pickup points, especially if consumer spending tightens further across China’s urban centers.

    Trading desks now track whether Luckin’s share price can clear its 50-day moving average barrier of $33.68 and push toward the consensus target of $46.87 as year-end transaction numbers roll in.
  • Luckin Store Count Hits 36,310 as Franchisee Margins Squeeze

    Luckin Store Count Hits 36,310 as Franchisee Margins Squeeze

    Luckin Coffee expanded its global network to 36,310 outlets by June 30, 2026. The chain added more than 5,000 net new locations in six months despite falling same-store sales.

    China accounts for 36,087 of those stores, or 99.4 per cent of the total, leaving overseas operations with a negligible share of overall sales. Top-line revenue keeps climbing, but store-level economics are tightening. Same-store sales at self-operated locations fell 5.3 per cent year on year in the second quarter. That widened the decline recorded in the first quarter. Partner-operated units faced even sharper pressure on single-store receipts.

    Store Density Dilutes Franchise Returns

    At the end of the second quarter, the brand operated 23,734 self-managed locations and 12,576 franchised partner stores. Franchises made up 34.6 per cent of the global estate. That stayed close to the 34.8 per cent share logged at the close of 2025, but represents a net increase of 1,762 shops from 10,814 outlets six months earlier.

    Revenue from partner stores reached 36.68 billion RMB in the second quarter, up 27.9 per cent year on year to generate 23.1 per cent of Luckin’s total net revenue. In the prior-year period, partner stores brought in 28.67 billion RMB across 9,238 locations. Store count jumped 36.1 per cent over that span while partner revenue grew only 27.9 per cent, showing dilution on the ground. In dense urban districts, new openings siphon foot traffic from established shops under the same brand.

    This shift alters the math for prospective franchisees. Store construction and fit-out costs remain flat. However, longer payback windows mean operators face limited downside alongside lower profit ceilings.

    Operational Friction in the Tea Shift

    Management has pushed beyond coffee to build a broader ready-to-drink beverage platform. The pivot began in August 2024 when the chain launched Light Jasmine Light Milk Tea with a morning-coffee, afternoon-tea promotion. Diversification gathered pace throughout 2025. The company rolled out more than 140 new products that year and lifted non-coffee sales past 20 per cent of total cups sold.

    Menu rollouts accelerated in the second quarter of 2026 with 28 ready-to-drink items and more than ten snacks. Non-coffee items made up nearly half of all new and returning drinks across the network during the first six months of the year.

    Adding milk tea complicates daily operations for front-line staff. Standard coffee relies on automated, uniform inputs like beans and syrups. Fresh tea requires brewed bases, fruit prep, milk foams, and short shelf-life dairy. That increases waste and inventory oversight. Baristas now juggle dual workflows across morning and afternoon rushes, which pushes up labor hours and training needs. Franchisees also have to buy tea extractors, larger ice makers, and dedicated refrigerated displays.

    Tea Chains Push Fresh Grinds

    The boundary between coffee chains and tea specialists in China has collapsed entirely. While Luckin branches into milk tea, leading tea franchises are installing espresso machines to capture morning commuters.

    Guming installed commercial coffee equipment across roughly 13,500 outlets by June 30, 2026, topping 90 per cent store penetration. The brand introduced 12 coffee items in the first half of 2026, pushing coffee past 20 per cent of total sales volume. Mixue Ice City upgraded to freshly ground coffee across its network, using heavy subsidies to replace older drip drinks.

    Cha Baidao launched 15 coffee items in the first half, installing fresh-grind machines in more than 2,700 locations. Hushang Ayi added espresso stations to its core stores to boost breakfast tickets. Most tea chains sell coffee between 8 and 15 RMB. That overlaps directly with Luckin’s core price band while tapping deeper reach in third- and fourth-tier cities.

    Narrowing Spreads for Store Partners

    For landlords, Luckin remains a high-volume anchor tenant that pulls heavy foot traffic with standardized fit-outs. But the commercial risk has shifted onto operators. Prime business districts still generate steady yields. Outlying suburban sites and lower-tier municipal markets, however, are squeezed by internal cannibalization and tea rivals selling 10 RMB lattes.

    Luckin’s central supply chain protects input costs, but it cannot stop localized sales erosion. Tea rivals use existing counter space to serve fresh coffee at low incremental equipment costs. In contrast, Luckin franchisees spend significantly more retrofitting coffee bars for fruit tea prep.

    With the domestic network nearing 40,000 locations heading into late 2026, management must now protect the returns of its 12,576 franchise partners as store saturation sets in.

  • Nespresso and Swarovski Launch Festive Coffee and Accessories Range

    Nespresso and Swarovski Launch Festive Coffee and Accessories Range

    Nespresso rolled out a festive collaboration with Swarovski in October 2026, launching co-branded coffee blends, machines, and accessories ahead of the holiday season. The seasonal lineup includes Festive Crystal Spark Espresso for Original machines and Festive Crystal Spark Double Espresso for the Vertuo system.

    Packaging across the range adopts Swarovski’s octagonal motif and colour scheme, targeting premium gift buyers during the fourth-quarter retail rush.

    Dual formats and crystal merchandise

    The product release spans coffee capsules, drinkware and seasonal collectables. Both Original and Vertuo systems receive dedicated advent calendars, engineered to reveal two capsules on selected countdown dates rather than the standard single pod.

    Hardware and accessories extend into standalone display pieces. A crystal ornament shaped like the classic Nespresso capsule carries 62 facets with a shimmer effect, finished with a brushed chrome-tone top and pink satin ribbon. The merchandise roster also adds branded travel mugs, mug holders and Pixie Lungo cups designed for the festive sales window.

    Premium positioning in holiday gifting

    Seasonal capsule drops have become standard across the single-serve coffee sector, but tie-ups with luxury jewellers push price points higher. For Nestle, pairing single-portion coffee with crystal glassware helps lift average basket values when discretionary consumer spending faces margin pressure across regional retail networks.

    Department stores and branded boutiques rely heavily on limited-edition packaging to drive footfall in November and December. Swarovski gains direct placement in kitchen counters and home pantries, extending its brand presence beyond traditional jewellery counters into everyday consumer goods.

    Earlier retail collaborations

    Nespresso previously anchored its holiday campaigns around high-profile fashion designers and pastry chefs to generate seasonal momentum. Integrating crystal design elements represents a pivot toward collectible lifestyle items that outlast the consumable coffee supply inside the box.

    Inventory across the Swarovski range rolls out through Nespresso boutiques, online channels and selected retail partners ahead of peak holiday trading.

  • Tealive Launches Orange Coffee Blend from 3 Nations in Sepang

    Tealive Launches Orange Coffee Blend from 3 Nations in Sepang

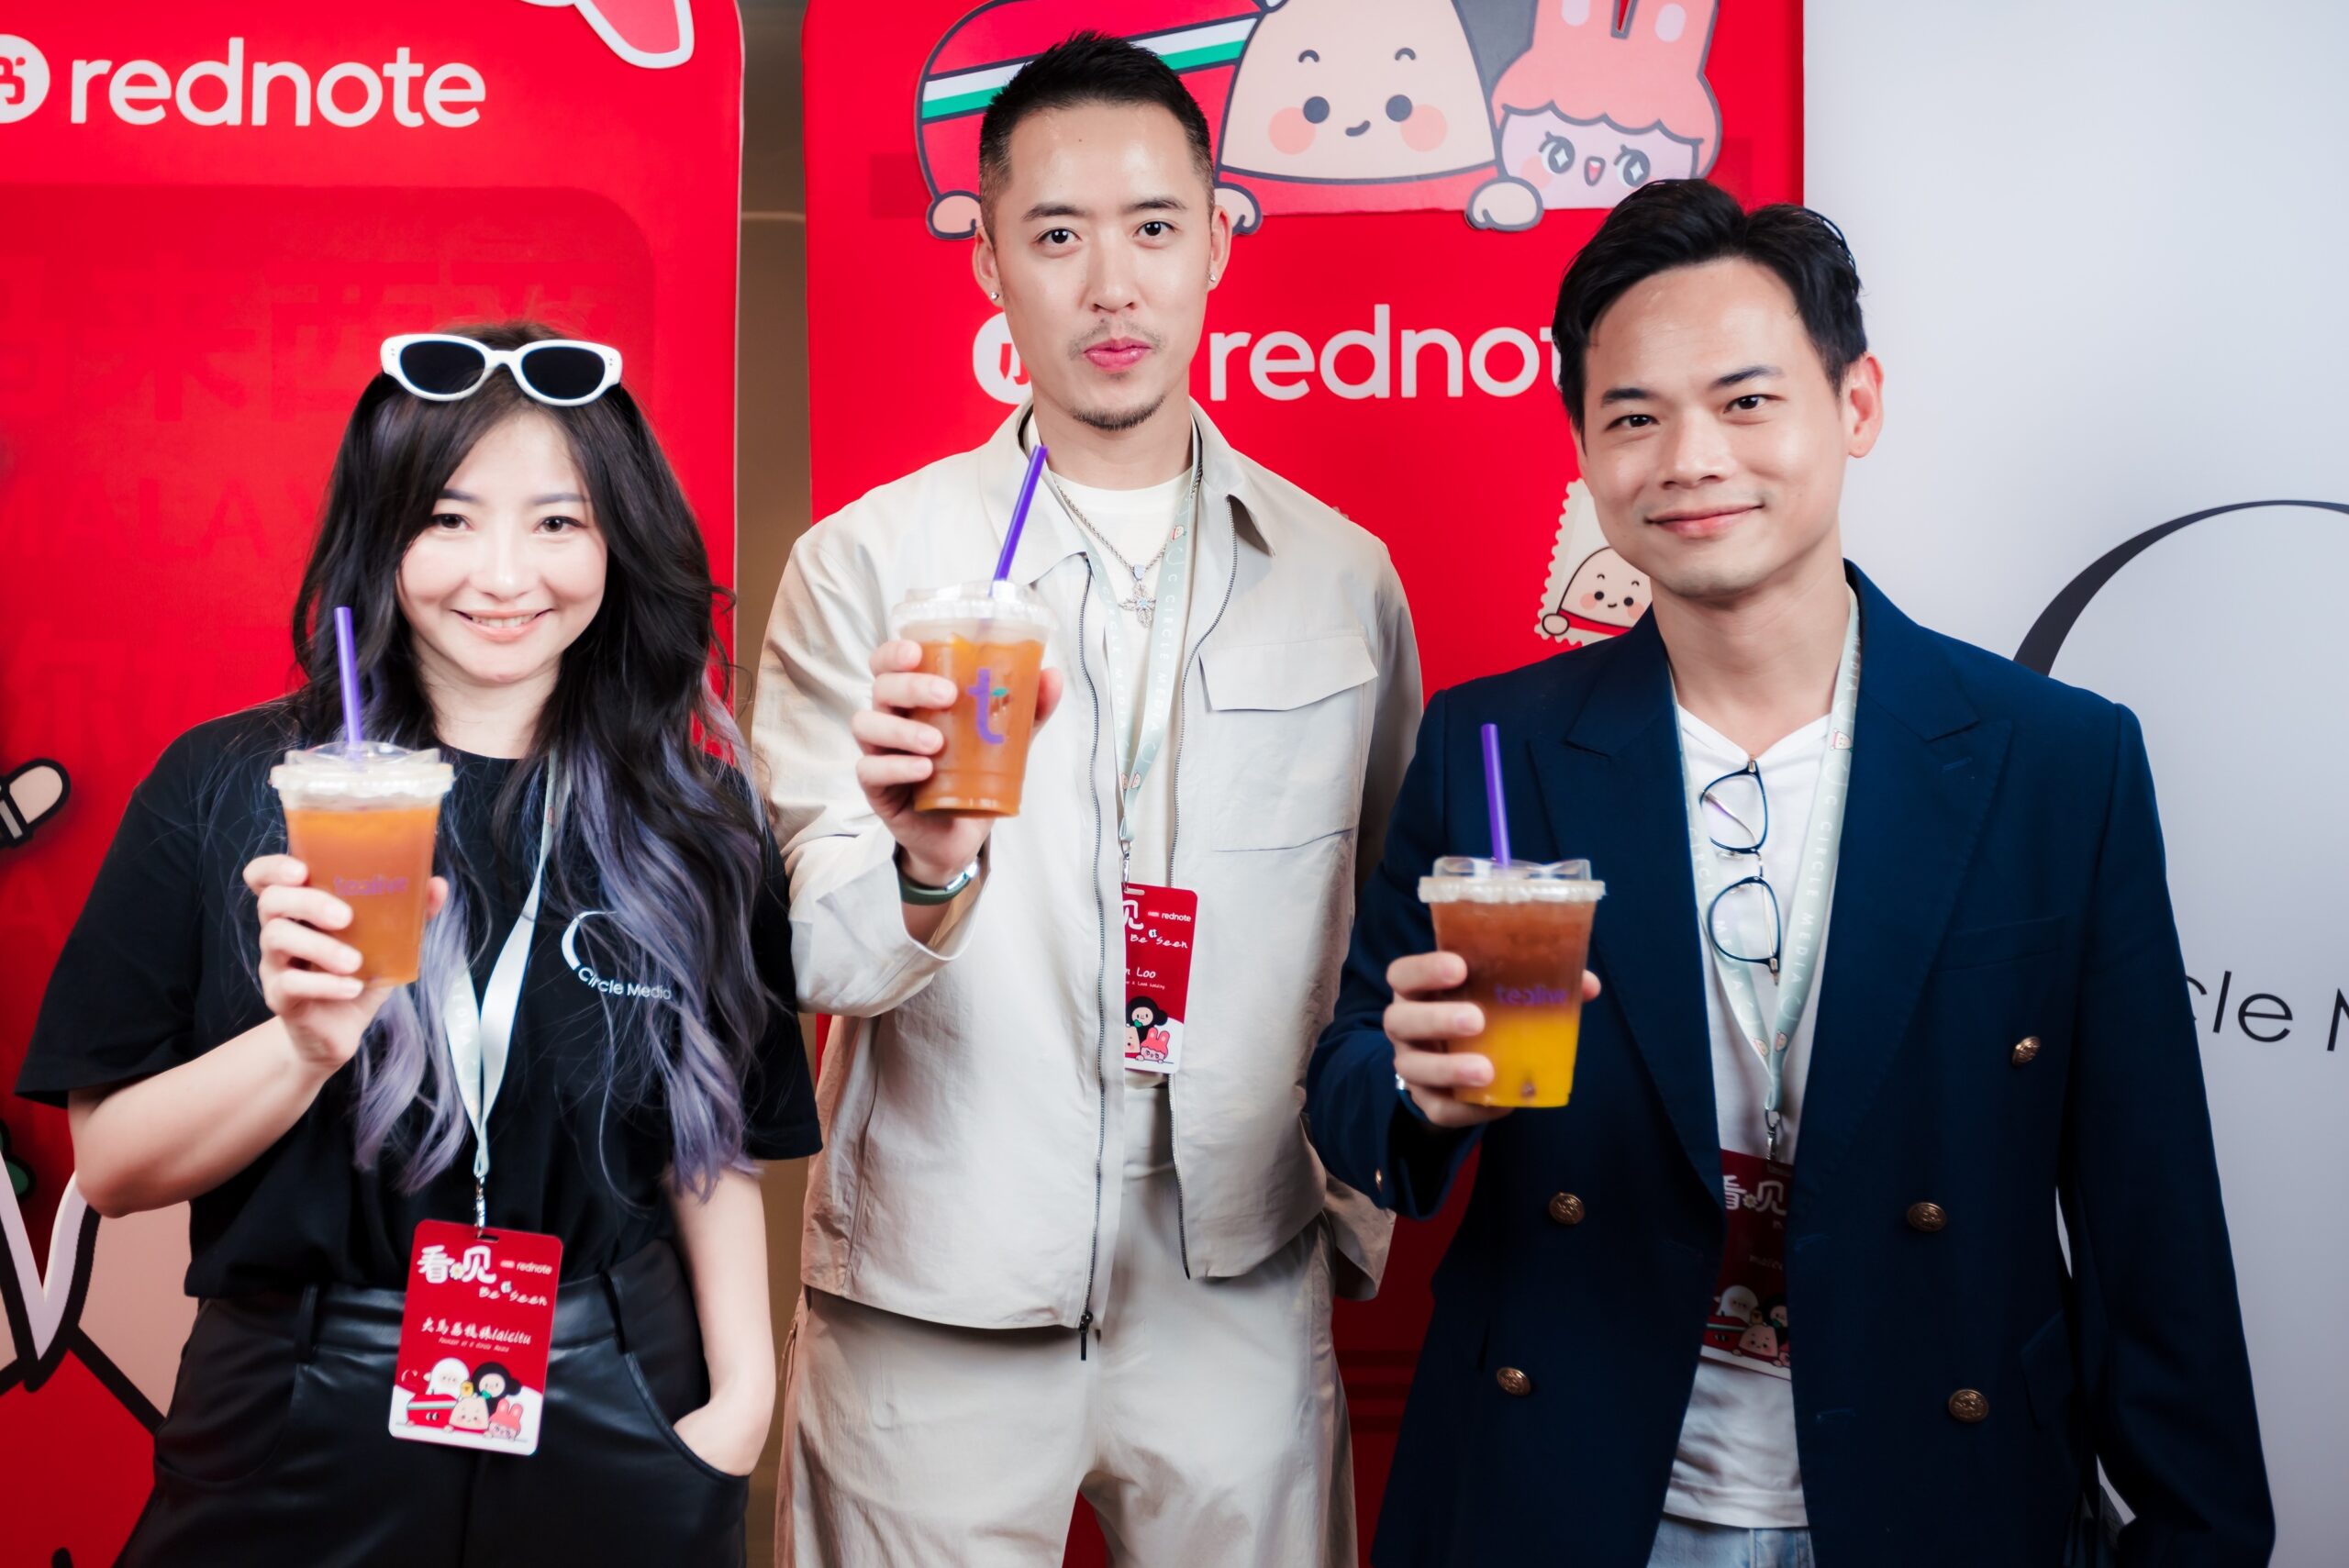
    Tealive introduced a limited-time Orange Coffee line in Sepang on 29 September 2026 to capture a bigger slice of Malaysia’s competitive coffee sector.

    The release uses coffee beans sourced from three nations to target daytime coffee consumers beyond the brand’s established bubble tea audience.

    Tealive aligned the promotional rollout with motorsport gatherings at the Petronas Sepang circuit, pairing the citrus beverage concept with seasonal trackside footfall.

    Branching Beyond Milk Tea

    Bubble tea operators across Southeast Asia continue pushing into freshly brewed coffee to diversify store revenue. Pure-play tea brands face crowded high streets and steep discounting from competing regional kiosks.

    Adding fruit-infused coffee drinks allows front-line beverage retailers to drive higher transaction counts during morning and early afternoon dayparts. It also captures consumers who bypass traditional milk-heavy teas for lighter espresso options.

    Citrus Blends and Menu Variations

    Fruit-forward espresso drinks have become standard offerings in urban cafe markets across Asia. Combining citrus juices with iced coffee appeals directly to younger demographics seeking refreshing, lower-dairy alternatives in tropical climates.

    For operators, cold citrus recipes require minimal back-of-house retooling while commanding premium seasonal price points. Sourcing multi-origin beans gives chain operators room to market quality credentials without moving fully into high-cost single-origin brewing.

    Competition in Malaysia’s Beverage Sector

    Malaysia’s ready-to-drink coffee sector features aggressive rivalry between domestic specialty chains, international franchises, and convenience store counters. Fast product iteration helps major chains maintain consumer engagement against fast-expanding kiosk competitors.

    Limited-edition beverage series serve as low-risk trials for broader product shifts. By testing customer uptake over short campaign windows, brand managers evaluate ingredient sourcing and store-level preparation speed before committing to permanent menu revisions.

    Event Venues and Seasonal Footfall

    High-capacity sporting locations like Sepang offer valuable real-world testing environments for seasonal beverage launches. Peak crowd flows test staff throughput and supply chain resilience under tight operational windows.

    Sales data gathered during the Sepang event window will determine whether citrus coffee blends secure a permanent place across the chain’s wider domestic store network.

  • Luckin Coffee Opens 100Th Singapore Store in Bugis Expansion

    Luckin Coffee Opens 100Th Singapore Store in Bugis Expansion

    Luckin Coffee opened its 100th store in Singapore on September 29, 2026, setting up in the commercial and transit hub of Bugis. The milestone establishes the Chinese chain as the city-state’s second-largest coffee operator by store count three years after its local launch.

    Customer volumes drove the physical expansion. More than 1.9 million cumulative transacting customers have bought drinks through the brand’s app-led ordering system in Singapore since the first outlet began trading in 2023.

    Footprint Strategy in Transit Nodes

    The Bugis site follows Luckin’s standard format across Southeast Asia: compact footprints near high-density commuter pathways and retail developments. Placing locations directly inside transport interchanges and office basements reduces seating overhead while maintaining order throughput during morning and lunch rush hours.

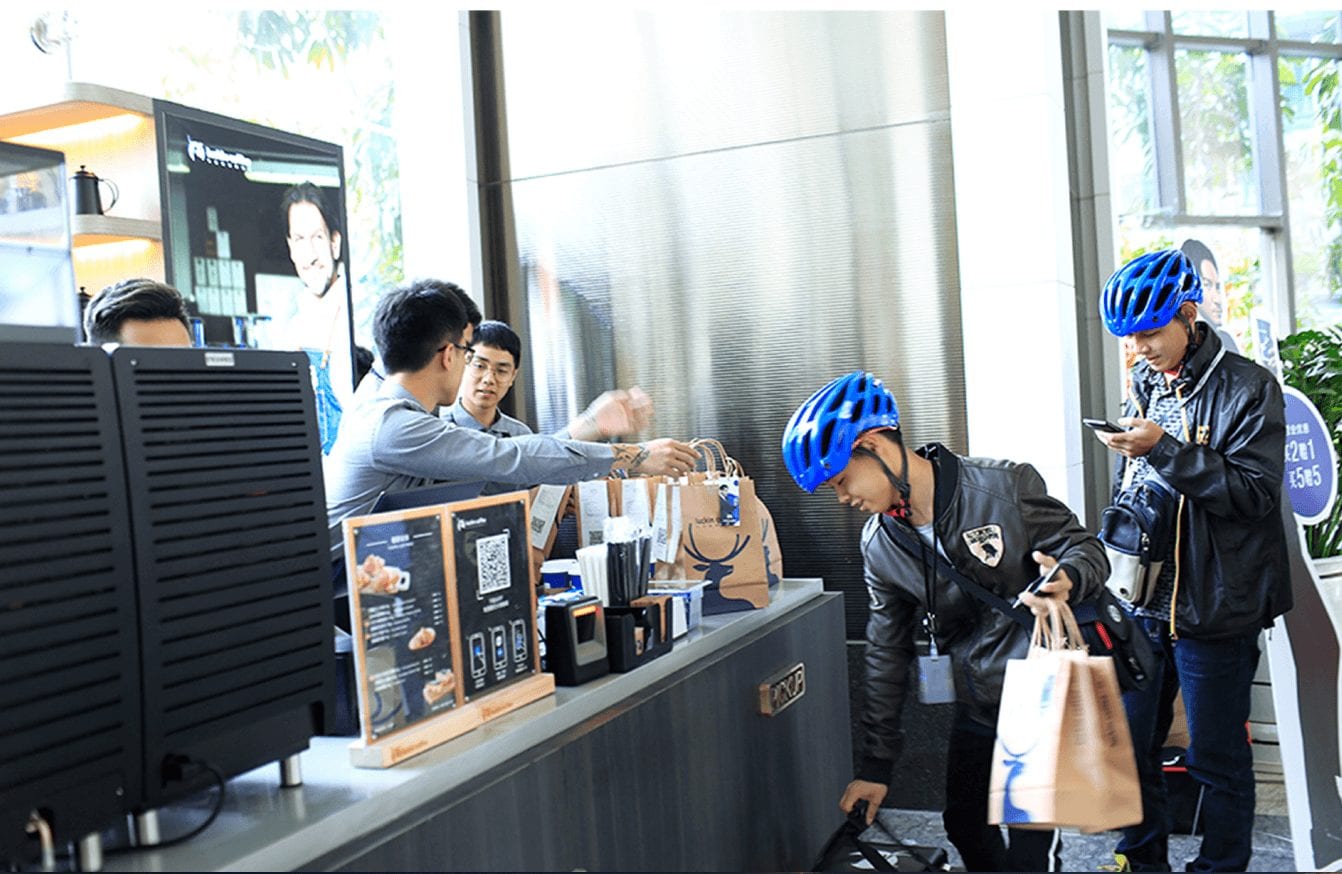
    Digital pickups handle the bulk of transactions. By requiring customers to order and pay via mobile application before collecting at the counter, the chain keeps queue times low and processes hundreds of drinks per hour with small front-of-house teams.

    Shifting Market Dynamics for Local Operators

    Reaching 100 outlets in three years puts immediate pressure on established mid-market chains and legacy regional brands. Fast store rollouts backed by aggressive digital discounting force competing operators to protect market share by upgrading their own mobile ordering apps and matching promotional drink pricing.

    Commercial landlords benefit from the format’s flexibility. Luckin takes micro-units and irregular floor plans that sit outside traditional full-service cafe requirements, generating steady rental income from transit corridors that previously housed service kiosks or sat vacant.

    International Growth Beyond the Domestic Base

    Singapore served as Luckin’s first international testing ground when the company entered the market in early 2023. Building a profitable operating model outside mainland China required adapting supply chains and menu profiles for Southeast Asian consumer tastes while retaining its core low-cost automated store design.

    Sustained transaction growth in Singapore validates the exportability of the grab-and-go model across high-rent Asian cities. The rapid climb to 100 units demonstrates that digital-first coffee retail can secure substantial market penetration even in mature, highly competitive metropolitan markets.

    Next Steps for Southeast Asian Expansion

    Attention now turns to whether Luckin can sustain repeat purchase frequency without deep promotional couponing. As the network reaches saturation in central commercial districts, subsequent sites must extract volume from suburban housing estates and secondary retail malls.

    Market watchers will track upcoming company filings for unit-level margins and regional store target updates across neighbouring Southeast Asian markets.

  • Starbucks Plans to Close 250 North American Stores

    Starbucks Plans to Close 250 North American Stores

    Starbucks announced plans last week to close 250 more underperforming stores across North America.

    The cafes represent about one per cent of Starbucks’ 18,000 US and Canadian locations, which COO Mike Grams argued either offered a poor customer experience or were not performing financially.

    The decision follows a similar move last year, when Starbucks reduced its store count by one per cent while investing in renovations and overhauling its loyalty program in a major turnaround push.

    Culling underperforming real estate

    Trimming the bottom tier of a massive store base reflects standard operating discipline for mature retail networks. In dense metropolitan centers, older cafes often suffer from cramped layouts that cannot efficiently process digital mobile orders or accommodate higher-volume food preparation. Shutting these units protects operating margins and eliminates lease liabilities on drag assets.

    For commercial landlords, the loss of an anchor tenant creates immediate vacancy risk, though prime street corners rarely stay empty long. In urban cores, independent operators and regional bakery chains have moved quickly to claim vacated ground-floor footprints, benefiting from existing plumbing, grease traps, and electrical fit-outs left behind by the outgoing chain.

    Transfers and site takeovers

    In Starbucks’ home market of Seattle, two of the 250 locations are slated for closure. At least six previously shut Starbucks sites across the city have already transitioned into local bakeries and independent specialty cafes, including Petit Pierre Bakery, which took over a former cafe in the Ballard neighborhood for its third retail outlet.

    Secondary operators gain substantial capital expenditure savings by stepping into pre-fitted food and beverage real estate. Taking over spaces with established beverage counters and drainage cuts store setup costs significantly compared to building out a raw shell.

    Previous cuts across Europe and America

    The latest 250 closures follow a larger restructuring drive completed last year, when Starbucks closed 627 stores across North America and Europe. That earlier round also trimmed approximately one per cent of the network while the chain directed capital toward store refurbishments and an overhaul of its customer loyalty program.

    Capital discipline has taken priority over raw store expansion in Western markets as operational costs, wages, and lease renewals rise. By pruning weak units, the company channels investment into higher-yielding drive-thrus, digital order pickup hubs, and renovation programs for top-quartile stores.

    What comes next for the network

    Starbucks will manage staff transfers and lease expirations across the 250 affected North American locations through the coming quarter. Financial impacts from the closures and related severance expenses will appear in subsequent quarterly filings as the portfolio adjustment concludes.

  • Kopi Kenangan CEO and Investors Raise Stakes in Coffee Chain

    Kopi Kenangan CEO and Investors Raise Stakes in Coffee Chain

    Kopi Kenangan co-founder and group chief executive Edward Tirtanata increased his equity holding in the Indonesian coffee chain in September 2026 as part of an ongoing funding round backed by existing investors.

    Tirtanata acquired shares directly from early team members and shareholders to consolidate ownership during the regional expansion of the chain, which was founded in 2017.

    Cap Table Consolidation

    Existing institutional backers joined the transaction to increase their own positions in the beverage operator. Venture firm Alpha JWC Ventures, Tybourne Capital Management and Horizons Ventures participated in the share purchase alongside company leadership.

    The secondary buyout allows early employees and initial angel backers to cash out equity built up since the company started operations in 2017. Bringing those shares back to the core founder and late-stage institutional funds tightens voting control ahead of further capital deployment across Southeast Asian retail locations.

    Regional Retail Pressure

    Grab-and-go coffee formats across Southeast Asia face tighter store-level margins as local competitors and international chains fight for footfall in commercial hubs. Consolidating ownership gives management more latitude to make long-term real estate commitments and manage pricing without friction from early angel investors seeking quick exits.

    For retail landlords and retail competitors in markets like Malaysia and Singapore, better-capitalised flagship operators can sustain commercial rent terms and marketing outlays longer during expansion phases. The backing from long-term capital providers like Horizons and Tybourne keeps the balance sheet steady as outlet networks build density.

    Building Out the Footprint

    Tirtanata co-founded Kopi Kenangan in Jakarta seven years ago to sell espresso drinks tailored to local palates at affordable price points. The brand built an extensive domestic network before introducing grab-and-go outlets outside its home market.

    The latest funding round clears out legacy shareholder blocks while management focuses on store opening targets and regional unit economics across targeted overseas metropolitan markets.

  • Nescafé Pledges RM500,000 to Fund Malaysian Youth Startups

    Nescafé Pledges RM500,000 to Fund Malaysian Youth Startups

    Nescafé will invest up to RM500,000 in seed capital and mentorship to fund youth-led business startups across Malaysia.

    Titled Projek Hidupkan Duniamu, the six-month initiative targets young founders who need direct cash grants and commercial guidance to build viable enterprises.

    Cash allowances and TikTok pitch screening

    Qualifying participants receive a six-month funding allowance, assigned corporate mentors and promotional exposure across Nescafé marketing channels. Applicants must submit a 60-second video pitch on TikTok. In the video, they must explain their commercial ideas and argue why their startup merits direct backing. Submissions open on October 1, coinciding with nationwide International Coffee Month promotions.

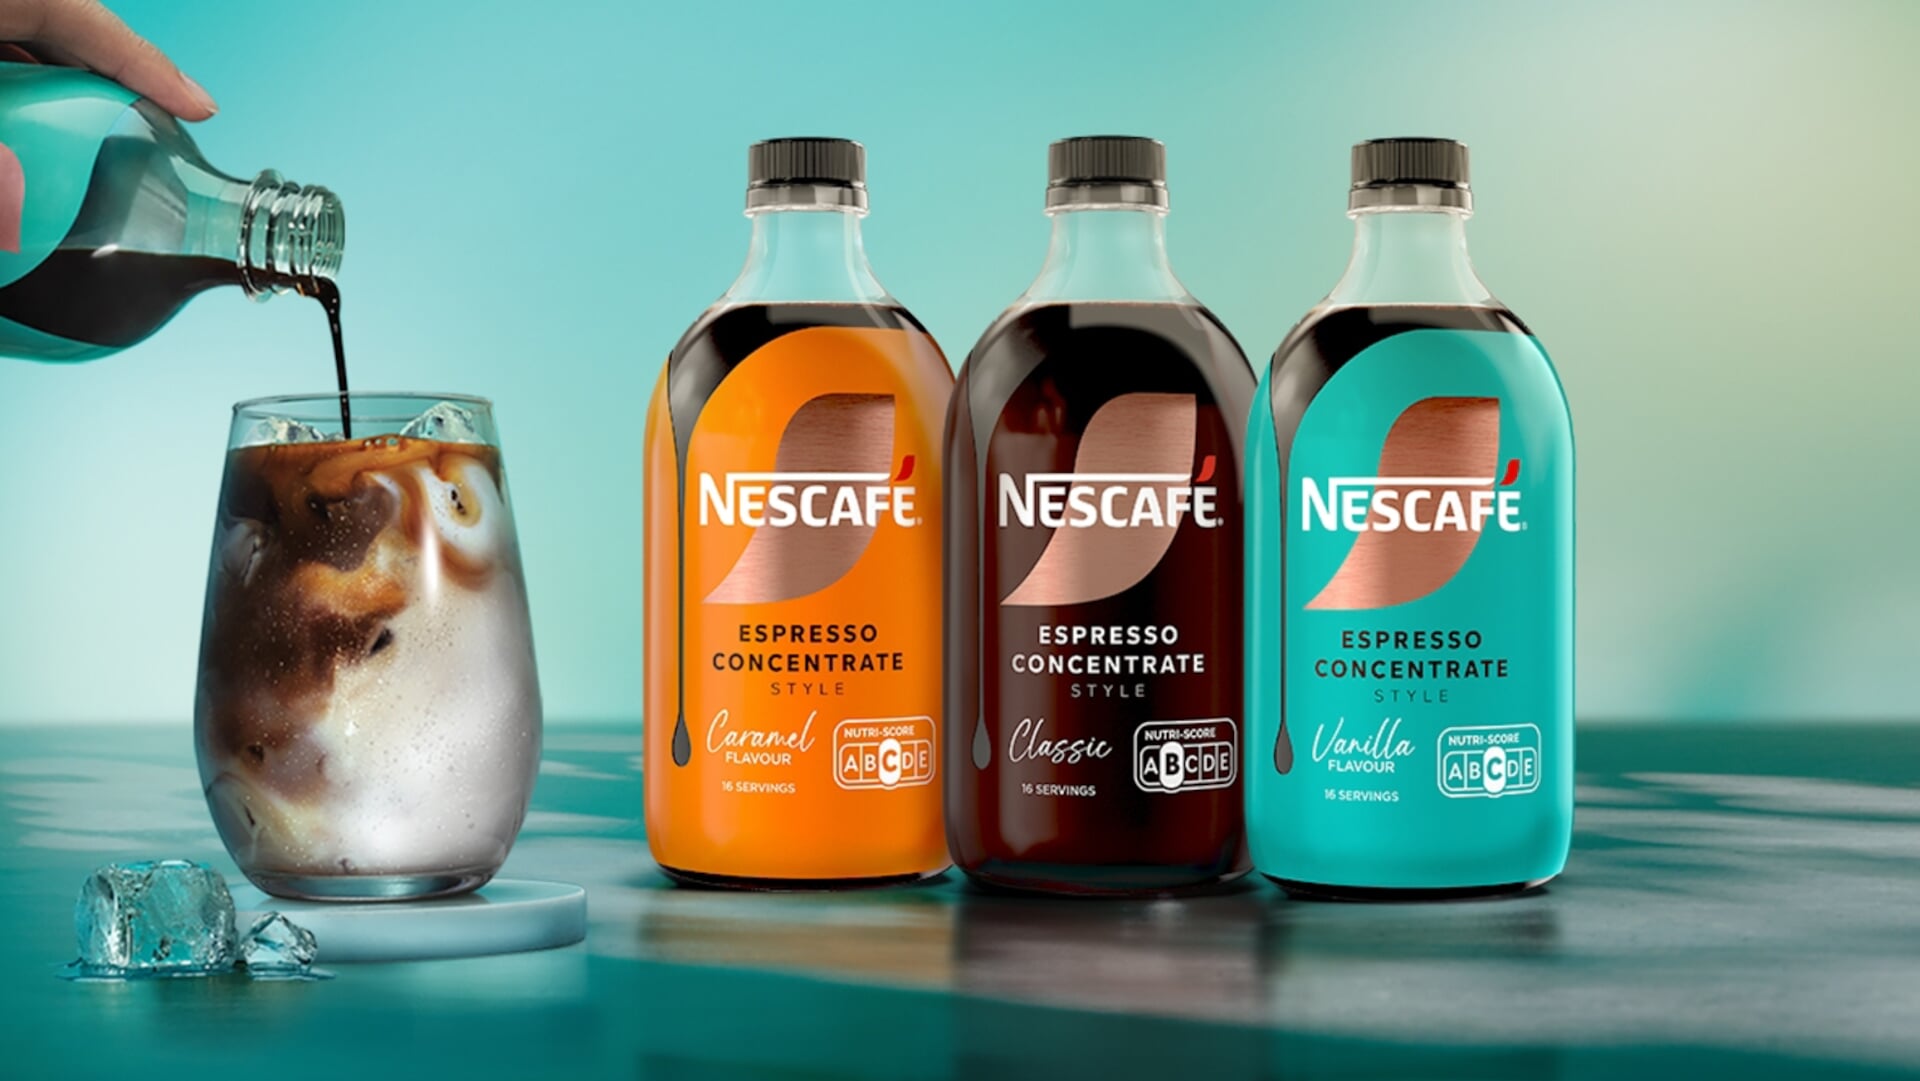
    Nestlé Malaysia showed the project during a six-day consumer exhibition at IOI City Mall in Putrajaya. It also introduced new coffee products at the event. These included bottled espresso concentrate, Spanish latte and tiramisu latte variants, alongside appearances from brand partners Black Hanifah and Yusof Hashim.

    Corporate youth programmes in Southeast Asian retail

    Consumer goods groups across Southeast Asia increasingly rely on venture contests to win young brand loyalists while testing grassroots retail ideas. Packaged goods makers now deploy seed funds rather than spending purely on above-the-line advertising. These micro-grants let them test consumer reception in hyper-local settings. They also generate fast social-media reach among demographics that traditional retail marketing misses.

    For retail mall operators and digital platforms, corporate incubators supply early pipeline activity for food concepts, boutique services and micro-merchandise. Survival rates remain low. Very few early-stage projects outlast the corporate grant period without follow-on funding from commercial lenders or institutional venture funds.

    Evolution from university coffee carts

    This rollout updates the earlier Nescafé Youth Entrepreneurship Programme, which placed coffee vending stands and kiosks on university campuses. That scheme trained undergraduates in point-of-sale management, inventory controls and beverage prep. However, it kept participants tied directly to Nestlé product lines.

    Projek Hidupkan Duniamu expands that brief into independent commercial ideas. The shift follows nationwide outreach campaigns by the brand, such as the Ngopi Dulu tour. That tour examined working conditions among frontliners and gig workers in transport hubs, public hospitals and service centres.

    Their stories reminded us that while ambition is abundant, access to opportunities can often make the difference.

    Roadshows set for Selangor and Penang

    Upcoming roadshows will expand on-ground activations at Sunway Pyramid in Selangor and Queensbay Mall in Penang. Application assessments begin once the October 1 submission window opens. Shortlisted finalists will then advance to mentorship and funding before the end of the year.

  • Nespresso Pilots $5 Doorstep Capsule Recycling Service in Sydney

    Nespresso Pilots $5 Doorstep Capsule Recycling Service in Sydney

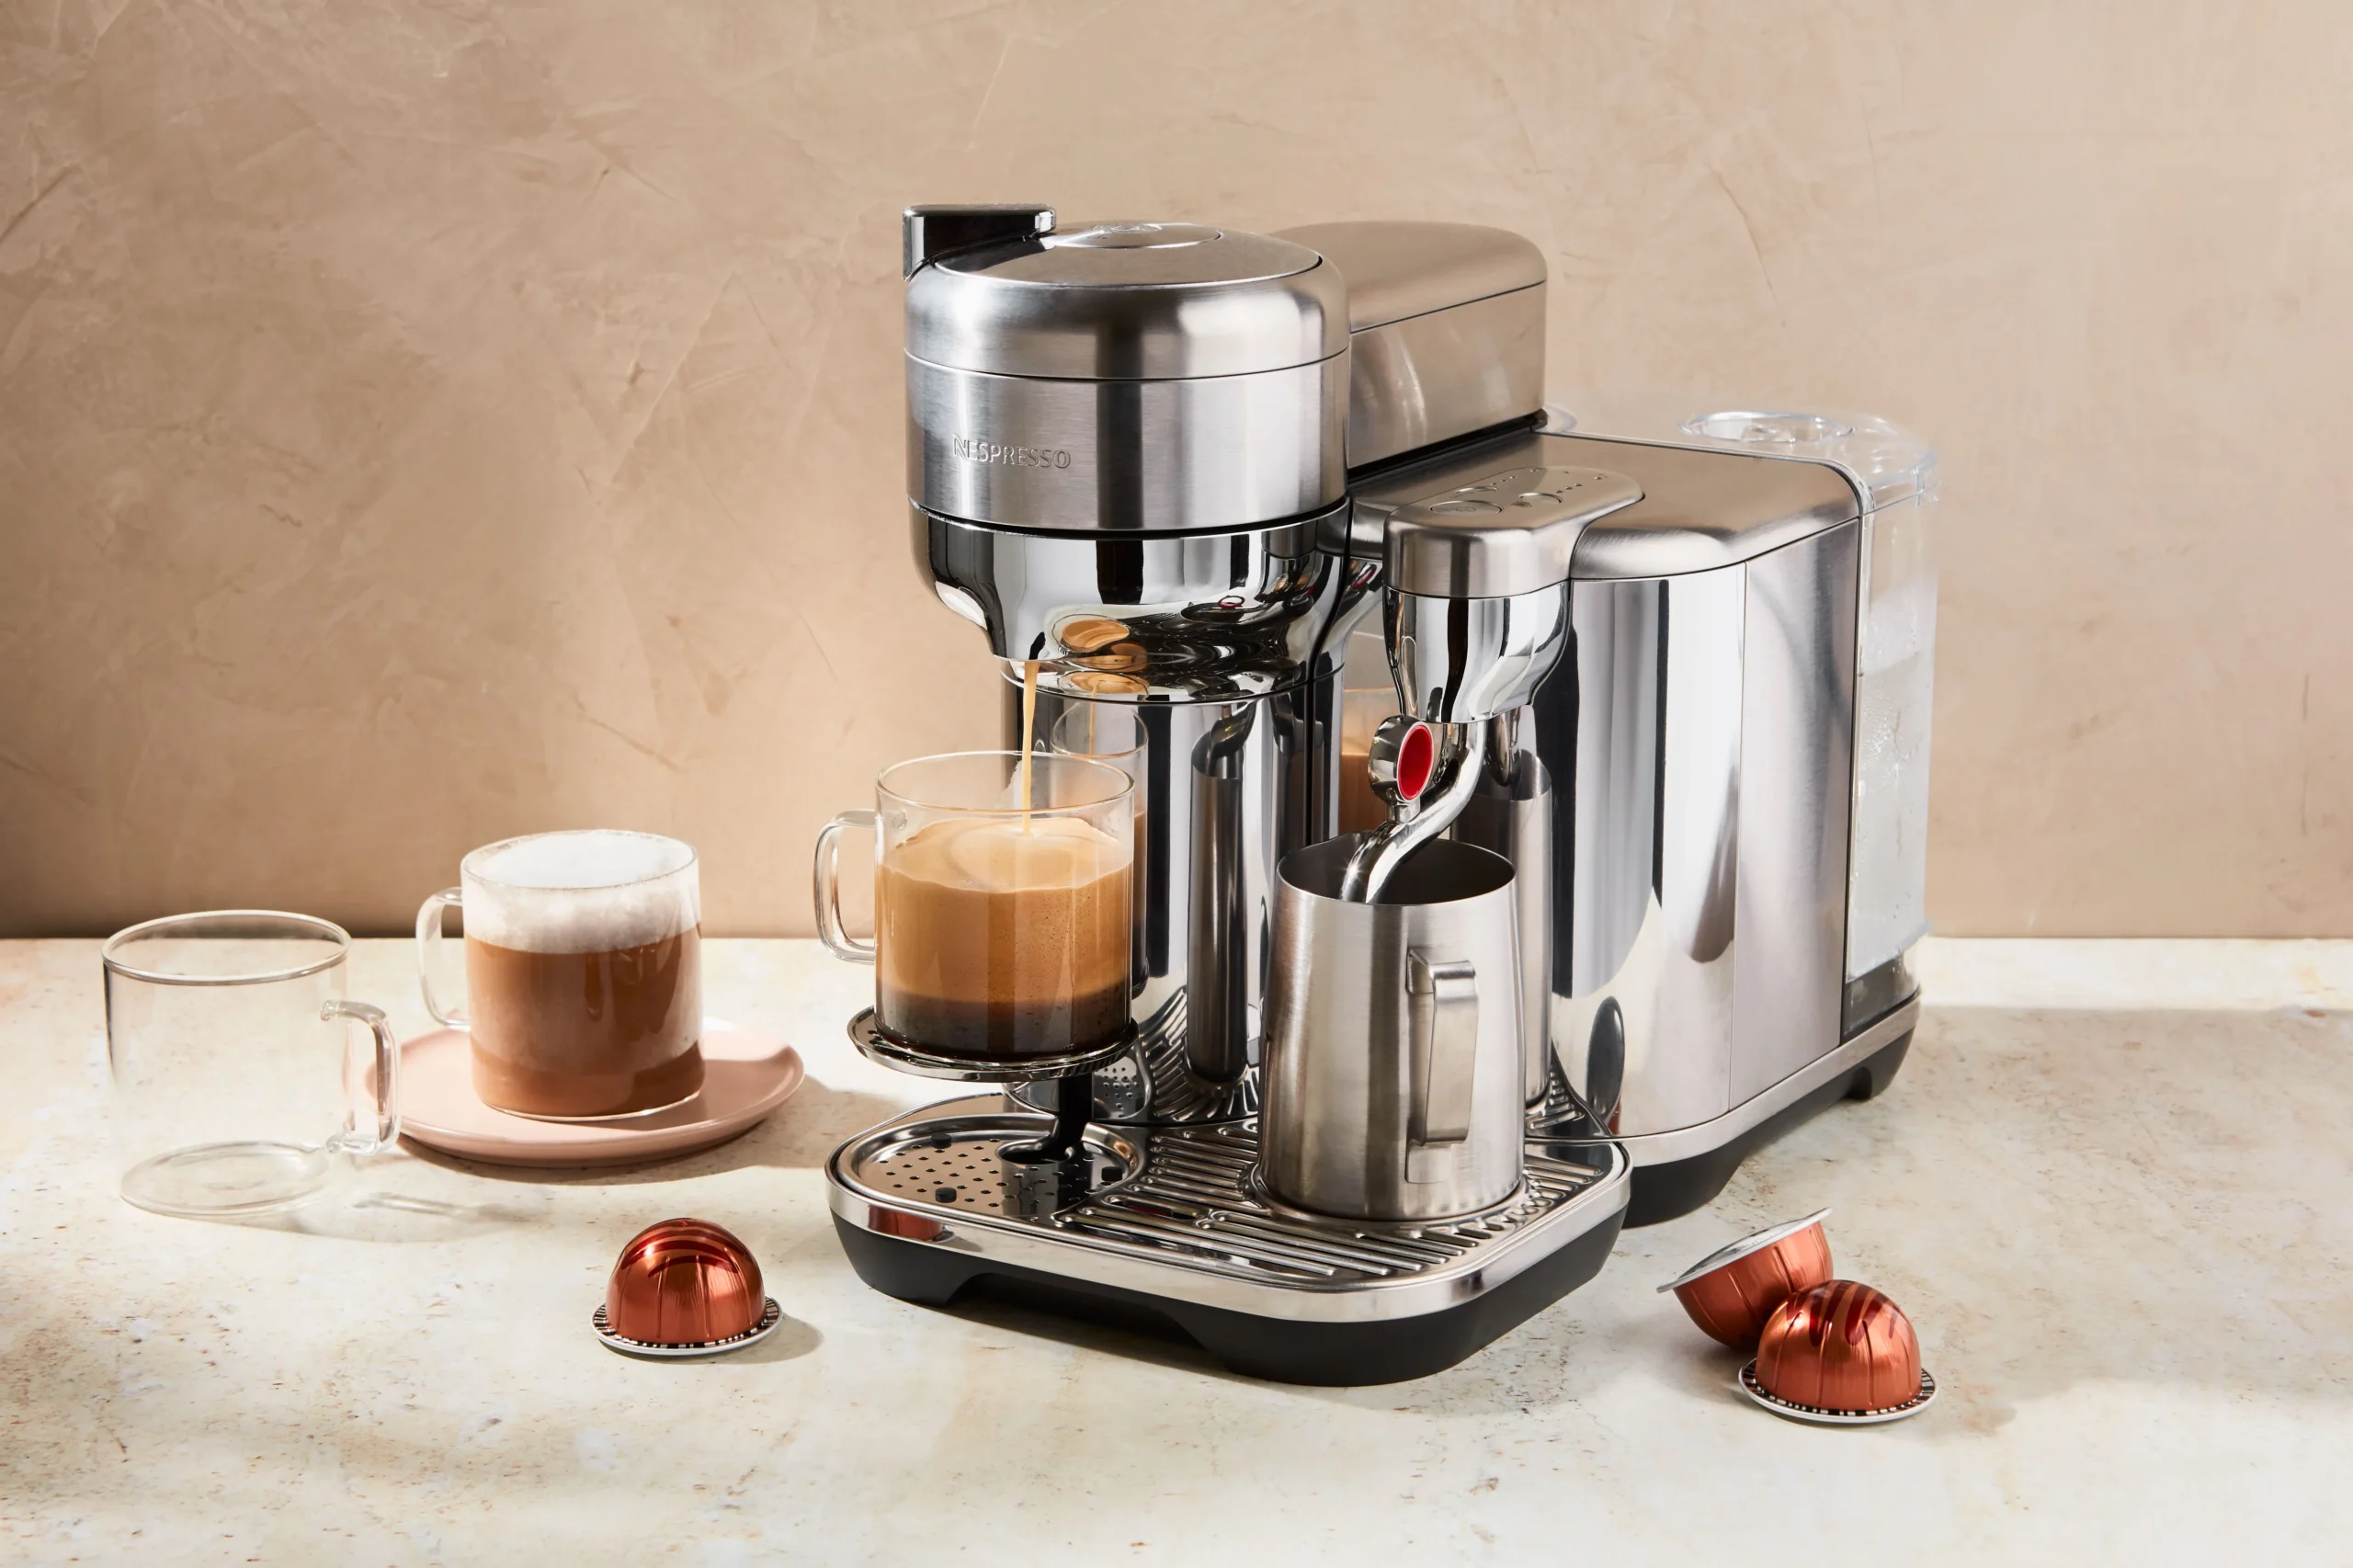
    In September 2026, Nespresso began piloting The Doorstep Collection, a new recycling service across metropolitan Sydney that allows customers to return used coffee capsules directly from their homes for $5.

    Each collection bag holds up to 180 Original capsules or 90 Vertuo capsules. Once filled, users can seal the bag and arrange a collection directly through the Nespresso app.

    How the collection model works

    The pilot tackles the main bottleneck in aluminium capsule recovery. Previously, consumers had to return used pods to brand boutiques or post offices. Folding collection into home delivery channels shifts reverse logistics costs onto willing buyers while defending the closed pod ecosystem.

    Recycling facilities separate the aluminium casings from residual coffee grounds. Smelters reprocess the metal. The organic waste goes to commercial composting facilities.

    Reverse logistics across regional markets

    Single-serve coffee brands across Asia-Pacific face mounting regulatory pressure to fund packaging waste management. In mature consumer markets like Australia, Singapore and Japan, drop-off rates consistently lag behind pod sales volumes without home collection infrastructure.

    Charging five dollars per bag tests how much financial responsibility consumers will shoulder for convenience. Competitors rely on third-party mail-back envelopes or retail bins that place the legwork on the shopper.

    What happens next

    Nespresso previously expanded drop-off points across postal networks and independent grocery stockists in Australia. Sydney now serves as the benchmark trial market ahead of a planned rollout across other Australian metropolitan regions.

  • Oriental Kopi Named Coffee Partner at Palm Garden Hotel Putrajaya

    Oriental Kopi Named Coffee Partner at Palm Garden Hotel Putrajaya

    Palm Garden Hotel Putrajaya partnered with Malaysian café chain Oriental Kopi on September 11, 2026. The brand now supplies the daily afternoon coffee service at the hotel’s Courtyard lounge.

    Guests get Oriental Kopi’s brew alongside local teatime snacks. The service runs daily between 3:30pm and 5:30pm.

    Daily Courtyard Service Details

    The hotel runs the programme under the name Kopi Dulu, drawing on the Malay word’s double meaning for first and the past. Executives from the hotel, property owner IOI Properties Group, and Oriental Kopi launched the offering together on site.

    Attendees included Palm Garden Hotel Putrajaya general manager Marshall Chai and IOI Properties Group property investment chief operating officer Chris Chong. Hospitality assistant general manager Tan Lee Fong and Oriental Kopi chief executive officer Dato’ Calvin Chan also took part.

    Local Brand Tie-Ups In Hospitality

    Hotel operators across Southeast Asia increasingly swap generic food programmes for branded domestic concepts. The strategy pulls foot traffic into underused lobby spaces. Teaming up with recognisable local F&B names also gives property owners a ready-made audience without the overhead of developing in-house menus.

    For domestic chains like Oriental Kopi, hospitality tie-ups secure brand placement in higher-spending leisure and corporate settings. But operational risks exist. External retail partners must match hotel service standards across every daily shift.

    Retail Expansion Footprint

    This tie-up follows other distribution deals by Oriental Kopi across Malaysia, including an August campaign with FamilyMart Malaysia featuring packaged kopitiam food items. Palm Garden Hotel previously ran seasonal activations at the venue, including a dedicated durian lounge in July.

    Oriental Kopi is expanding its retail footprint and corporate distribution channels across Peninsular Malaysia. Next, the chain plans further menu integrations across commercial properties in the Klang Valley.

  • Tealive Unveils Layan Coffee Series with Da Hong Pao Tea in Malaysia

    Tealive Unveils Layan Coffee Series with Da Hong Pao Tea in Malaysia

    Tealive unveiled its Layan Coffee lineup in Malaysia this week. The drinks combine brewed espresso with Da Hong Pao oolong tea across its domestic store footprint.

    That updates the traditional Malaysian coffee-and-tea blend known locally as cham and in Hong Kong as yinyeung, pairing 2 staple beverages.

    Upgrading Traditional Cham Recipes

    The new menu pairs concentrated coffee extractions with steeped Da Hong Pao, a roasted oolong tea cultivar. By substituting standard black tea with specialty oolong, Tealive targets consumers looking for higher-grade drinks at quick-service prices.

    Outlets sell the beverages in hot and iced formats. The rollout expands Tealive’s portfolio beyond core bubble milk tea selections and fruit teas.

    Chasing Value in Malaysia’s Coffee Rush

    Regional low-cost coffee chains continue to crowd Malaysian mall basements and shoplots. Local operators must now compete directly against aggressive discounting from these value brands.

    Leaning into cham allows Tealive to tap familiar domestic taste profiles that foreign rivals rarely prioritize. For store operators, tea-coffee fusions lift ticket averages during morning and afternoon dayparts without adding complex kitchen hardware or extra supply chains.

    Menu Innovation Across Regional Networks

    Expansion through drive-through locations and suburban shoplots established Tealive’s footprint across Malaysia and neighboring markets. Adding specialty tea to coffee follows earlier regional efforts to cross-sell traditional tea drinkers into daily coffee routines.

    Store-level sales figures and repeat purchase rates across Malaysian outlets will determine whether premium tea fusions claim a permanent share on company menus.

  • Mubadala Invests $1 Billion in Luckin Coffee Alongside Centurium

    Mubadala Invests $1 Billion in Luckin Coffee Alongside Centurium

    Abu Dhabi sovereign wealth fund Mubadala Investment Company agreed to invest about US$1 billion for a minority stake in Luckin Coffee. The Chinese chain operated more than 36,000 stores globally by June 30, with customer rolls reaching nearly 500 million transacting buyers.

    Mubadala is injecting the capital alongside Centurium Capital, the private equity firm that holds controlling shareholder control over the retail group. Fresh funding will finance store buildouts across mainland China while bankrolling new retail sites in overseas target markets.

    Gulf Capital Backs China Network

    The transaction directs Gulf sovereign money into high-frequency Chinese retail at a time when global private equity deployment in the country has cooled. Mubadala head of Asia private equity Mohamed Albadr pointed to data integration across product cycles and unit operations as the driver for the commitment.

    “Luckin Coffee has built a differentiated, technology-enabled business with data embedded across customer engagement, product development and store operations,” Albadr said.

    Securing US$1 billion gives the chain a balance sheet buffer that rivals cannot easily match in current fundraising conditions. The cash injection strengthens Luckin against low-price challengers like Cotti Coffee while intensifying lease competition for small-format commercial spaces across regional retail corridors.

    Scale Shifts Pressure to Rivals

    For multinational operators including Starbucks, the capital infusion signals that price competition and unit expansion in secondary Chinese cities will not slow down. Landlords in transport hubs, office basements, and shopping malls gain an aggressive, well-funded tenant capable of taking small footprints on short turnaround schedules.

    Risk now centers on unit-level profitability outside top-tier shopping zones as store density increases in mature urban markets. Expanding into international markets will also test whether the chain’s app-driven, low-labor operating model transfers effectively into markets with higher real estate and staffing overhead.

    International Footprint Next in Line

    The deal follows a rapid store buildup through the first half of 2026, when Luckin crossed the 35,000-location threshold before adding another 1,000 stores by the end of the second quarter. Centurium had previously taken operational control to restructure the company and reorient unit economics around small-format pickup counters and digital orders.

    RetailNews Asia will track the pace of the group’s overseas site selection and store openings over the coming quarter as capital deployment begins.

  • Starbucks Expands in East Asia as Walmart Unwinds Suburban Hypermarkets

    Starbucks Expands in East Asia as Walmart Unwinds Suburban Hypermarkets

    Starbucks continues to scale its store footprint across East Asian metros while Western big-box operators like Walmart have spent years unwinding their suburban hypermarket networks.

    The divergence reveals how high-density Asian urban layouts reward high-frequency beverage retail while penalizing large-format car-dependent grocery models.

    Western retail expansion into East Asia split along structural lines over the past two decades. Big-box hypermarkets required expansive floor plates, suburban road infrastructure, and weekly bulk purchasing routines that never fully aligned with daily fresh food shopping habits in cities across China, Japan, and South Korea. Coffee chains, by contrast, secured small-footprint real estate embedded directly into transit nodes, office towers, and dense residential clusters.

    Urban Density And Real Estate Economics

    Hypermarket operators faced escalating commercial rents on massive suburban plots that could not generate the sales density required to offset real estate overhead. Local convenience store chains and neighborhood wet markets retained daily foot traffic, while domestic e-commerce platforms quickly captured non-perishable consumer goods.

    Starbucks structured its expansion around rapid footfall and premium beverage margins. Store units occupy high-traffic ground-floor positions in office complexes and transit hubs, turning compact footprints into reliable daily transactions. The company positioned its locations as functional meeting spaces for urban workers living and working in tight quarters.

    Localization Of The Consumer Experience

    Walmart relied heavily on centralized global procurement systems and standard supply chains designed to lower unit costs through sheer volume. That formula failed to dislodge regional grocery competitors who maintained direct, daily ties with domestic produce distributors and localized supply channels.

    Beverage operators adapted their product menus and store concepts far more quickly. Seasonal product launches, integration with regional digital payment apps, and localized delivery partnerships allowed coffee chains to embed themselves into daily consumer routines across tier-one and tier-two cities.

    Supply Chains And Digital Delivery Channels

    The rise of on-demand quick-commerce platforms in East Asia further eroded the traditional hypermarket advantage of wide product selections under one roof. When consumers can order household staples on mobile apps for delivery within thirty minutes, the incentive to drive to an out-of-town warehouse store disappears.

    Coffee retail adapted directly to this shift by integrating order-and-pay apps and motorcycle courier fleets into store operations. Compact urban kitchens double as mini-fulfillment nodes for instant delivery without adding significant real estate overhead.

    Western multi-brand retailers entering East Asia now structure their market entries around small-format, experience-driven spaces rather than sprawling suburban warehouses. The next operational test centers on maintaining beverage gross margins as domestic discount coffee brands add thousands of low-cost kiosks across the region.

  • Starbucks Opens Vietnam’s First Signing Store in Ho Chi Minh City

    Starbucks Opens Vietnam’s First Signing Store in Ho Chi Minh City

    Starbucks opened its first Signing Store in Vietnam on Ho Chi Minh City’s Cao Thang Street on Wednesday, expanding a regional format that already runs 26 outlets across four other Asian markets.

    Deaf staff work alongside hearing employees across counter service and daily operations, using visual menus, gestures and written order systems rather than spoken prompts.

    Operations on Cao Thang Street

    The unit sits set back from the main roadway on Cao Thang Street with a garden-style layout planned to lower ambient street noise for staff and guests. It serves the chain’s standard beverage and food menu while changing the service counter workflow to accommodate point-and-sign ordering.

    Chi Nguyen, director of external affairs at Starbucks Vietnam, stated to local media that the location functions as an inclusive space where staff and visitors interact directly through visual methods.

    Format Expansion Across Asia

    Specialised format stores of this type allow multinational food and beverage operators to test altered counter workflows without changing back-of-house supply chains. Starbucks established its first signing outlet in Kuala Lumpur in 2016 before expanding the concept to China, Japan and South Korea, where dedicated customer communication tools were integrated into standard point-of-sale setups.

    For commercial landlords, quiet and garden-style layouts of this type offer ways to activate secondary street frontage and deeper, non-standard retail floorplates that struggle to accommodate high-turnover drive-throughs or standard counter lines. The operational friction sits in staff onboarding and maintaining service speed during peak morning trade, where non-verbal communication systems must process complex drink customisations without causing counter bottlenecks.

    Market Positioning in Vietnam

    Starbucks opened its initial location in Ho Chi Minh City in 2013 and has spent more than a decade building a store network across major commercial hubs including Hanoi, Da Nang and Binh Duong. The brand competes against established domestic chains such as Highlands Coffee and Phuc Long, which operate larger branch networks at lower price points across Vietnam’s urban centres.

    The Cao Thang unit brings the company’s regional signing store count to 27 locations across Asia, with operators watching whether the model will be adapted for additional high-density retail districts in Hanoi.

  • Mega MGC Coffee Approaches 4,500 Stores Across South Korea

    Mega MGC Coffee Approaches 4,500 Stores Across South Korea

    Mega MGC Coffee reached 4,466 outlets in South Korea on August 27, widening its lead as the country’s largest coffee franchise by physical store count.

    The network now sits within striking distance of the 4,500-store threshold in a national market that holds more than 100,000 coffee shops. Founded in 2015, the brand expanded through a low-price, high-volume model built on large drink sizes and small takeaway shop footprints.

    Franchise density and territory controls

    Rapid growth has pushed Mega ahead of older rivals. Domestic competitor Ediya Coffee operates more than 4,200 locations, while Compose Coffee passed the 3,000-store mark last year. Starbucks closed last year with just over 2,000 outlets across South Korea, operating on a corporate-owned model rather than franchises.

    To prevent its own stores from cannibalising sales, the chain analyses pedestrian commercial zones before approving new franchise applications. A company representative said Mega evaluates whether both neighbouring existing units and proposed locations can generate stable returns before clearing an opening.

    Bifurcation in the cafe sector

    The scale achieved by Mega and Compose illustrates how deeply value-tier operators have penetrated South Korea’s daily commuter market. While premium brands focus on seated dining space and elevated menus, budget chains capture weekday takeaway volume through kiosk ordering and lower pricing.

    Foreign chains continue to test the opposing end of the market. Canada’s Tim Hortons is expanding its presence toward 50 locations across South Korea, adding 26 stores this year with larger flagship formats and broader food menus.