Tag: mobility

  • Beijing Auto Show Sets March 2027 Dates for First Odd-Year Exhibition

    Beijing Auto Show Sets March 2027 Dates for First Odd-Year Exhibition

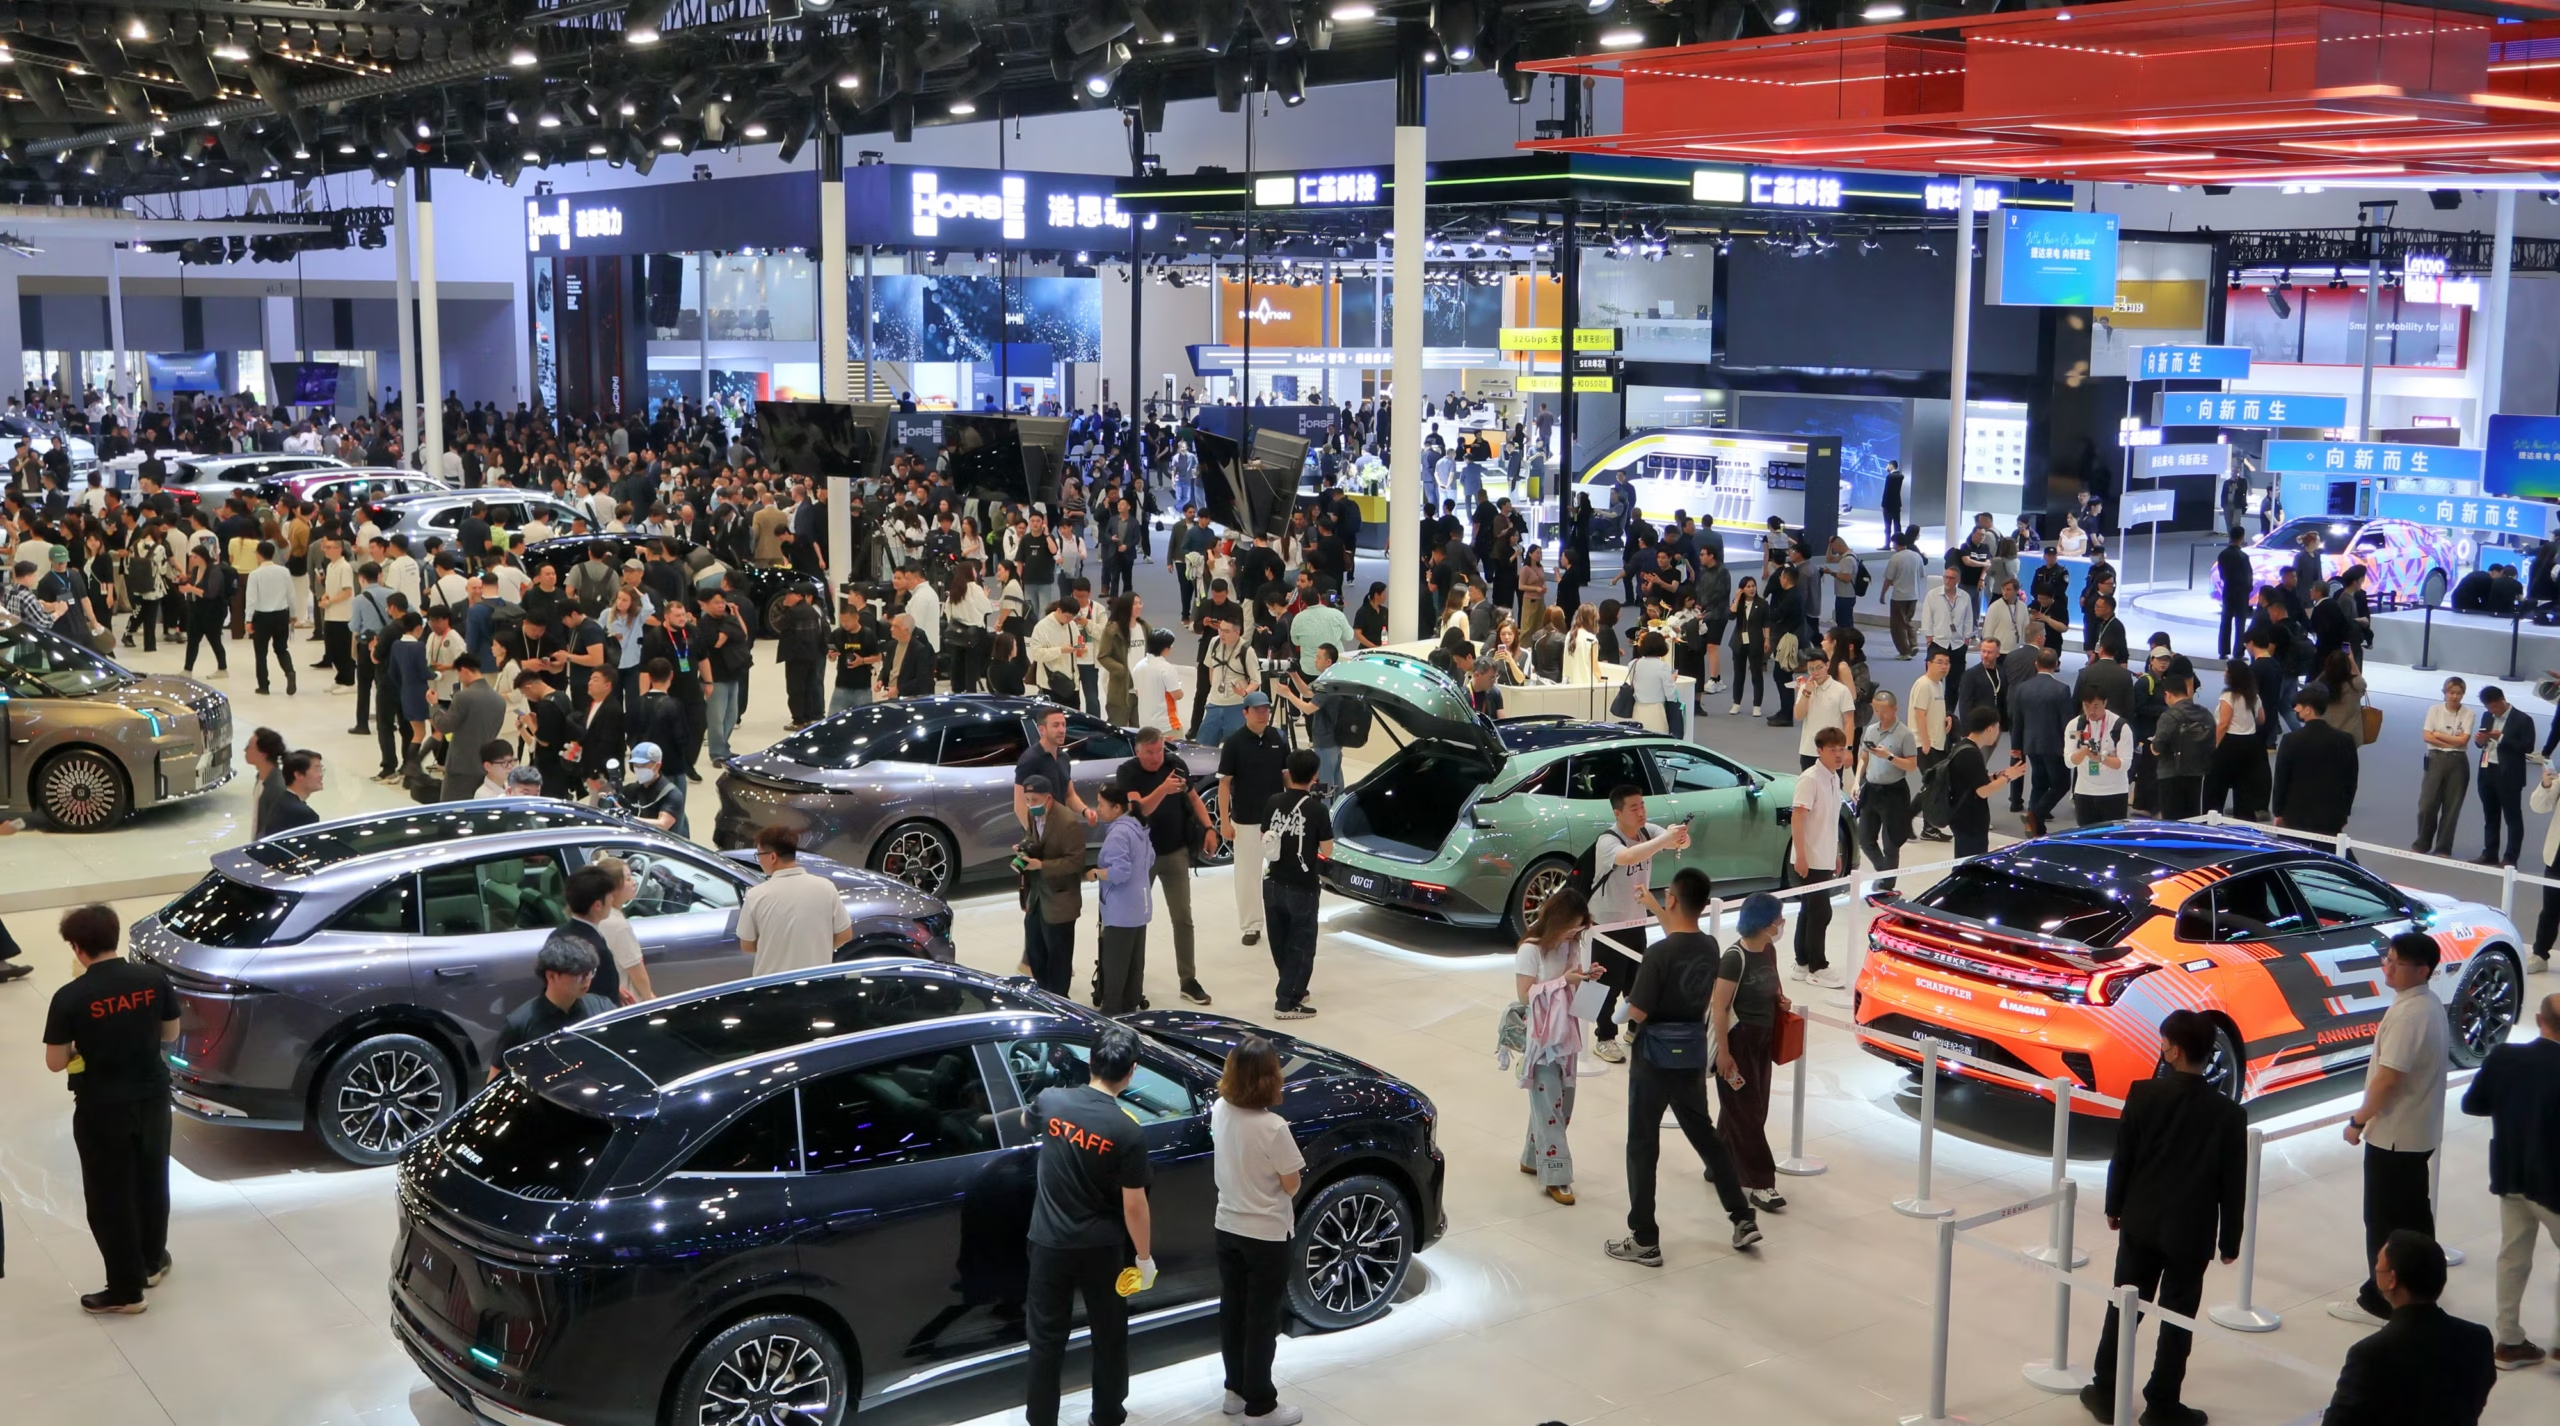
    Organizers have scheduled the next Beijing Auto Show for March 27 to April 5, 2027. The event introduces an odd-year specialized format focused on smart vehicle manufacturing.

    The 10-day event follows a 2026 exhibition that drew 1.28 million visitors. That show filled 380,000 square meters of floor space in the capital.

    Officially named the 2027 Beijing International New-Quality Automotive and Future Smart Mobility Exhibition, the show will use two venues: the China International Exhibition Center Shunyi New Venue and the Capital International Exhibition Convention Center. Media days run on March 27 and 28. Trade days follow on March 29 and 30, before public entry opens from March 31 to April 5. A dedicated auto parts section will operate for four days from March 27 to March 30.

    Schedules and venue allocation

    This schedule runs the Beijing show in an odd-numbered year for the first time since its 1990 debut. It follows months of talks between the Shanghai Council for the Promotion of International Trade and the automotive branch of the China Council for the Promotion of International Trade. Both bodies agreed on September 7 to keep their alternating system for comprehensive vehicle exhibitions. Under that deal, full-scale passenger car shows stay in Beijing during even years and Shanghai during odd years.

    To avoid overlapping with Shanghai’s gathering, Beijing will operate as a specialized trade exhibition in 2027. Exhibits will concentrate on smart manufacturing, digital production lines, artificial intelligence software, smart mobility services, and industrial robotics alongside traditional new energy vehicles.

    Technology race drives exhibition demand

    Automakers in China face compressing model lifecycles and rapid tech shifts. These changes demand more frequent commercial exposure. More than 100 domestic passenger car brands compete inside mainland China, forcing manufacturers to shorten product refresh cycles to keep dealer inventories moving.

    Hardware advances have pushed vehicle launches beyond annual cycles. Domestic suppliers have speeded up the deployment of ultrafast charging technology. Manufacturers including Geely, BYD, and CATL are rolling out systems designed to complete battery charging within five minutes. Meanwhile, factory automation and AI integration have become core commercial selling points alongside vehicle range and chassis design.

    “The real challenge is whether the battery can accept that level of current quickly and repeatedly without overheating, excessive degradation or internal bottlenecks,” said Chris Liu, a Shanghai-based senior analyst at Omdia.

    Export focus and commercial matchmaking

    Organizers will also target export procurement on the show floor as domestic brands look overseas to offset slowing passenger vehicle deliveries at home. They plan to host dedicated matchmaking sessions between Chinese carmakers and foreign dealership groups, component distributors, and regional fleet operators.

    During the April 2026 Beijing show, brands presented 1,451 vehicles across more than 1,000 booths. That lineup included 181 product debuts and 71 concept cars. The 2027 edition aims to convert foot traffic into export supply agreements by prioritizing international procurement delegations.

    Shanghai prepares expanded 2027 floor plan

    Shanghai’s auto show will open less than three weeks after the Beijing event concludes. Its comprehensive exhibition runs from April 23 to May 2, 2027, at the National Exhibition and Convention Center. The event spans 400,000 square meters and includes a specialized area for embodied artificial intelligence.

    Car brands must now split capital expenditures and marketing budgets across two major events within a five-week window in northern and eastern China. Floor space allocations and overseas buyer registrations for the Shunyi exhibition halls will open in early 2027.

  • Waymo Plans Commercial Autonomous Ride-Hailing Service in Singapore by 2028

    Waymo Plans Commercial Autonomous Ride-Hailing Service in Singapore by 2028

    Alphabet subsidiary Waymo will launch a fully autonomous ride-hailing service in Singapore by 2028, deploying an all-electric fleet in its first expansion into Southeast Asia.

    The commercial rollout gives the self-driving unit a regulated beachhead in Asia after building its initial commercial operations across select metropolitan markets in the United States.

    Fleet Deployment and Local Mapping

    Initial batches of all-electric Jaguar I-PACE vehicles will arrive in Singapore in the coming months. Waymo plans to run a structured readiness phase starting next year, using trained specialist drivers behind the wheel to operate the cars manually.

    Manual testing allows the Waymo Driver software stack to map Singapore’s complex road geometry, lane systems, and heavy monsoon downpours. Engineers need that baseline data before removing safety drivers from the vehicle cabin entirely.

    Regulatory Framework with Transport Authorities

    The company formed a direct partnership with Singapore’s Ministry of Transport and the Land Transport Authority to establish the operational framework. The arrangement mirrors Singapore’s broader regulatory approach to autonomous transport, which requires strict staged trials before granting commercial approvals.

    Waymo co-CEO Tekedra Mawakana met Singapore Transport Minister Jeffrey Siow in the San Francisco Bay Area earlier this year to outline the deployment roadmap. Public passengers will eventually book driverless rides directly through the standalone Waymo mobile application once full regulatory clearances clear.

    Implications for Southeast Asian Mobility

    Singapore represents the most structured proving ground for autonomous tech in the region, offering dense urban corridors, high taxi utilisation rates, and clear legal liability guidelines. The entry puts direct long-term pressure on regional ride-hailing incumbents like Grab, which operate traditional driver-dependent platforms across Southeast Asian capitals.

    Autonomous electric fleets shift operating economics from variable driver commissions to fixed capital expenditure and fleet charging overhead. For municipal transport networks, commercial self-driving cars offer supplementary capacity on fixed routes without adding labor bottlenecks.

    Testing Schedule and Next Milestones

    Singapore previously tested smaller autonomous shuttle pilots in restricted areas like Sentosa and one-north, but Waymo’s program marks the first large-scale commercial fleet deployment targeting general public streets.

    Vehicle arrivals in late 2026 will trigger the start of manual data-collection routes across designated public roads in 2027.

  • Renault and Geely Invest More in Brazil for New Electric Vehicle

    Renault and Geely Invest More in Brazil for New Electric Vehicle

    Renault and China’s Geely have increased their investment in Brazil this week to produce a new electric vehicle. The cash broadens their shared manufacturing footprint in Latin America.

    Fresh funds will upgrade local assembly lines. The push targets regional demand for affordable electric passenger models.

    Expanding the Sino-French Production Alliance

    This decision deepens an industrial alliance between the French automaker and the Hangzhou-based automotive group. The two partners already pool engineering, hybrid architectures, and powertrain tech across multiple global markets to cut development costs.

    Local assembly in Brazil lets Geely and Renault reduce exposure to import tariffs on finished Chinese electric vehicles. The hub also creates a launchpad for vehicle distribution across South American trade corridors.

    Competitive Pressures in Latin America

    Chinese electric vehicle makers are accelerating overseas factory commitments. They want to bypass regional trade barriers and counter slowing domestic growth. Rivals including BYD and Great Wall Motor have already bought manufacturing assets in Brazil to anchor regional supply chains.

    Asian component suppliers must now establish secondary delivery routes and local sub-assembly units within South America. The spending shifts component sourcing risk onto local networks. Still, it locks in vehicle platforms designed in China and Europe.

    Platform Strategy and Next Steps

    Geely and Renault have steadily integrated their powertrain and vehicle architecture operations over recent quarters, creating dedicated joint venture platforms for hybrid and pure electric models. The Brazilian project serves as an operational extension of that platform-sharing agreement.

    Factory tooling schedules and regional rollout timelines will determine when the first units leave the Brazilian assembly floor for regional dealerships.

  • Taiwan to Screen 47,000 Drivers Using Government Health Data

    Taiwan to Screen 47,000 Drivers Using Government Health Data

    Taiwan plans to allow road authorities to use health data to identify drivers who might no longer be medically fit to hold a license, affecting about 47,000 motorists.

    The proposed system would cover drivers with visual impairments, epilepsy, and moderate or severe dementia, the Ministry of Transportation and Communications said.

    Under the plan expected to take effect by the end of this year, road authorities will periodically obtain records from government agencies managing subsidies or insurance programs to cross-check against driver registries.

    How the Medical Cross-Checks Work

    Flagged drivers will receive notices requiring a fresh qualification assessment. Those who fail the evaluation must surrender their licenses immediately.

    Data transfers will follow strict minimization rules, according to the ministry. Road agencies may access only records explicitly tied to the three designated conditions.

    Currently, drivers with epilepsy can secure a permit only by submitting medical certification verifying they have remained seizure-free for at least two years. The new protocol closes the gap between renewal cycles by detecting diagnoses that happen after initial licensing.

    Operational Pressure on Transport Fleets

    For commercial transport operators, courier networks, and last-mile delivery services, automated screening increases compliance pressure. Fleet supervisors who rely on independent contractors or aging drivers must prepare for sudden license revocations when medical records trigger reviews.

    Fleet operators must shift from periodic manual checks to continuous monitoring. Companies facing labor shortages will need faster onboarding pipelines to replace workers sidelined by automatic state disqualifications.

    Legislative Backing and Implementation Timeline

    Revisions to the Road Traffic Management and Penalty Act passed in November last year provide legal backing. Those changes mandate qualification reviews whenever a motorist experiences physical or mental deterioration that impairs driving capability.

    Transport officials plan to launch the data-sharing network before the end of this year. Initial review notices will go out immediately after rollout.

  • Chinese Electric Vehicle Makers Prepare Canada Launch with Lower Cost Models

    Chinese Electric Vehicle Makers Prepare Canada Launch with Lower Cost Models

    Chinese electric vehicle manufacturers are preparing shipments to Canada, offering advanced vehicle technology at price points below established North American competitors.

    Domestic assembly plants across China have scaled output to supply overseas export corridors as international distribution plans advance.

    Export expansion into North America

    Production lines inside Chinese EV facilities are shifting capacity toward global specifications. Manufacturers have focused on software integration, high-voltage battery architecture, and cabin electronics to compete directly with legacy marques.

    Canada represents a key entry corridor in North America. Integrated local supply chains and battery manufacturing scale allow Chinese carmakers to price vehicles competitively even after international freight costs.

    Pricing pressure and regulatory hurdles

    Competitive pricing remains the primary lever for Chinese automakers entering developed automotive markets. By controlling component supply, cell manufacturing, and digital operating systems in-house, these plants maintain substantial production cost margins.

    Establishing certified retail networks and securing federal safety approvals in Ottawa remain the operational steps ahead of the first scheduled consumer deliveries.

  • Singapore Quota Prices Cross S$105,000 Ahead of 2025 Diesel Registration Ban

    Singapore Quota Prices Cross S$105,000 Ahead of 2025 Diesel Registration Ban

    Singapore car buyers face quota premiums topping S$105,689 for large vehicles as the city prepares to halt new diesel car registrations in 2025. The policy mechanism keeps private passenger cars to 509,302 units across the island while public transport systems carry the bulk of daily commuter trips.

    Under the Vehicle Quota System managed by the Land Transport Authority, prospective owners must secure a 10-year Certificate of Entitlement before putting a car on the road. Auction prices in May 2024 stood above S$92,700 for Category A cars with engine output under 97 kilowatts and S$105,689 for larger Category B models. Commercial vehicle quotas cleared at S$72,001, while motorcycle permits reached S$9,311.

    Vehicle Quotas and Tax Structure

    Taxes push local retail prices far above global benchmarks. Buyers pay an Additional Registration Fee tiered between 100 per cent and 320 per cent of a vehicle’s open market value, driving total on-the-road costs to roughly five times the level seen in Western markets. The total motor vehicle population stood at 957,006 units in 2018, restrained by administrative caps in place since 1990.

    Fleet operators also face tight structural rules across ride-hailing and point-to-point services. Singapore counted 83,037 taxis and private hire vehicles as of March 2019, with flag-down taxi fares starting between S$3.20 and S$3.90 outside the Central Business District. Private hire vehicles operate exclusively through digital booking platforms.

    Transit Network and Fleet Targets

    Public transport carries the remainder of passenger volume across the territory. Four contracted operators, SBS Transit, SMRT Buses, Tower Transit Singapore and Go-Ahead Singapore, run more than 5,800 buses across 365 scheduled routes under a competitive tendering model that logged over 4.0 million daily trips in 2019.

    Across Southeast Asia, auto brands rely on high-volume passenger car growth in developing markets like Indonesia and Thailand, but Singapore functions purely as a high-margin proving ground for electrification and automated systems. Retailers and fleet managers now navigate a regulatory schedule that bars new diesel registrations starting in 2025, before a binding mandate requires all newly registered cars to run on cleaner energy models, including electric, hybrid or hydrogen fuel cells, by 2030.

  • Uber to Cut 3,300 Jobs in Global Push Toward Robotaxis

    Uber to Cut 3,300 Jobs in Global Push Toward Robotaxis

    Uber Technologies is cutting roughly 3,300 jobs, or 10 per cent of its global workforce, to streamline management and fund an autonomous driving push. The retrenchment is the company’s largest round of dismissals since May 2020, when it shed 6,700 workers during the pandemic.

    Chief executive Dara Khosrowshahi announced the restructuring in a staff memo on September 2. The reductions target middle management rather than operational staff, with the company seeking to eliminate bureaucratic bottlenecks that slowed product decisions.

    Stripping Management Layers

    The overhaul cuts the number of workers positioned seven or more reporting tiers below the chief executive by 20 per cent. Internal teams with only one or two direct reports will shrink by nearly half, while several operational divisions will merge across regional hubs.

    Remote work will also contract sharply. Uber will cap fully remote positions at about 1 per cent of its total headcount while enforcing its existing policy requiring three days a week in the office. The platform finished 2025 with approximately 34,000 global employees.

    Unlike other technology peers cutting headcount this year, Khosrowshahi did not attribute the dismissals to artificial intelligence tools. Industry tracker layoffs.fyi recorded more than 123,000 tech redundancies across roughly 390 businesses in 2026, many citing automated workflow gains.

    Redirecting Capital to Autonomous Fleets

    Savings from the payroll cuts will help finance more than US$10 billion in planned autonomous vehicle investments. Uber wants to secure its position as a central booking marketplace for driverless fleets operated by external partners, countering threats from standalone operators such as Waymo and Tesla.

    Tensions with autonomous developers have escalated as suppliers expand their own direct-to-consumer networks. Waymo currently operates driverless vehicles through the Uber app in Austin and Atlanta, but it is rolling out into additional metropolitan areas independently.

    For mobility operators across Asia and Western markets, the transition to robotaxis threatens the traditional middleman fee structure built on gig workers. While Southeast Asian operators continue to rely on human drivers, platform valuations increasingly hinge on controlling autonomous dispatch software rather than maintaining large administrative headcounts.

    Uber shares gained 2 per cent in pre-market trading following the announcement, after dropping nearly 8 per cent earlier in the year. The company must now deploy its autonomous capital budget while renegotiating fleet supply pacts across key urban markets.

  • GetGo Launches Cross-Border Car Sharing from Singapore into Malaysia

    GetGo Launches Cross-Border Car Sharing from Singapore into Malaysia

    Singapore car-sharing operator GetGo rolled out a cross-border rental feature letting users drive vehicles directly across the Causeway into Peninsular Malaysia. The service gives drivers access to cars pre-registered with Malaysia’s mandatory Vehicle Entry Permit.

    Users can collect a car from local Singapore neighbourhoods and drive across the border to destinations including Johor Bahru and Kuala Lumpur. Unlike point-to-point cross-border taxis and ride-hailing services, the rental imposes no fixed route requirements or designated drop-off points during the booking window.

    How the Causeway booking works

    The feature, branded Drive to Malaysia, handles the regulatory paperwork required by Malaysian transport authorities before drivers leave the city-state. Each eligible vehicle comes fitted with a registered Vehicle Entry Permit RFID tag, avoiding the administrative delays that private vehicle owners face when securing cross-border clearance.

    Drivers retain full control of the itinerary throughout Peninsular Malaysia for the entire duration of their scheduled reservation. They pick up the car at an assigned Singapore bay and return it to the same spot once their trip concludes.

    Shifting border transit demand

    The service targets weekend shoppers, business commuters, and holiday travellers who previously depended on cross-border coach networks, licensed cross-border cabs, or private vehicle ownership. Cross-border transit across the Johor-Singapore Causeway ranks among the busiest land crossings worldwide, yet car-sharing models in the region historically restricted fleets to domestic borders.

    By clearing regulatory permit hurdles in advance, fleet operators open a new revenue line during peak travel weekends. The next operational test for cross-border car sharing centres on fleet availability and user adherence to Malaysia’s digital toll and fuel regulations during peak holiday travel periods.

  • Hyundai Commits to Extended-Range Electric Vehicles

    Hyundai Commits to Extended-Range Electric Vehicles

    Hyundai Motor Group is developing extended-range electric vehicles to broaden its electrified lineup across major automotive markets. The powertrain format pairs electric motors with a small petrol engine acting solely as an onboard generator to charge the battery pack while driving.

    The technology eliminates direct mechanical drive from the combustion engine to the wheels, delivering pure electric driving dynamics without public charging dependency on long journeys.

    How the Powertrain Operates

    Extended-range electric vehicles rely on an electric motor to turn the axles at all times. When battery capacity runs low, an internal combustion engine kicks in to supply electricity directly to the battery and motor. Drivers refuel at conventional petrol stations while retaining the smooth acceleration and regenerative braking of a dedicated battery electric vehicle.

    Automakers increasingly view the technology as a practical interim solution for buyers concerned about charging station availability, high battery replacement costs, and cold-weather range degradation.

    Market Competition and Powertrain Shifts

    Chinese manufacturers such as Li Auto and Seres built substantial domestic market share using extended-range architectures over the past three years. Hyundai’s push into the format brings direct competition from an established legacy carmaker to a powertrain segment previously dominated by Chinese electric vehicle specialists.

    The strategy lets the Seoul-based manufacturer scale electrified production while managing capital allocation across pure battery development, conventional hybrids, and software-defined vehicle architectures.

    Hyundai plans to roll out its initial extended-range models across target regional markets as production schedules and regional regulatory frameworks align.

  • Taiwan Fuel Retailers Freeze Pump Prices for Fourth Week as Currency Offsets Crude

    Taiwan Fuel Retailers Freeze Pump Prices for Fourth Week as Currency Offsets Crude

    CPC Corp and Formosa Petrochemical held Taiwan retail fuel prices steady this week, freezing forecourt rates for a fourth consecutive week despite crude topping US$93 a barrel. The decision leaves domestic transport costs stable across thousands of service stations as logistics networks enter the late-summer freight cycle.

    Retail unleaded gasoline remains at NT$30.5 per liter for 92-octane, NT$32 for 95-octane, and NT$34 for 98-octane at both retail chains. Premium diesel holds at NT$29.3 per liter at state-run CPC stations and NT$29.1 per liter at Formosa pumps.

    Crude Spike Versus Currency Gains

    International crude rallied last week after geopolitical friction between the United States and Iran threatened oil supplies. CPC calculates weekly domestic price adjustments through a floating formula weighted 70 percent to Dubai crude and 30 percent to Brent.

    Under that formula, Taiwan’s baseline import crude basket averaged US$93.01 per barrel last week, up from US$89.84 the week before. Foreign exchange movements absorbed the shock. The New Taiwan dollar appreciated to an average of NT$31.901 against the greenback from NT$32.194 a week earlier, cutting the landed cost of dollar-denominated crude deliveries.

    Pump Rates at the Forecourt

    Price stability at the pump shields commercial delivery fleets and consumers from short-term commodity spikes. Fuel distributors across Southeast and East Asia have faced margin compression over the past two quarters as crude volatility tests state-managed pricing mechanisms and retail price caps.

    Both refiners will review their pricing formula at the close of trading on Friday, with market attention focused on whether the US$93 crude threshold forces an adjustment in next week’s retail slate.

  • Xiaomi SU7 Electric Vehicle Surpasses Half Million Deliveries Amid Strong EV Sales

    Xiaomi SU7 Electric Vehicle Surpasses Half Million Deliveries Amid Strong EV Sales

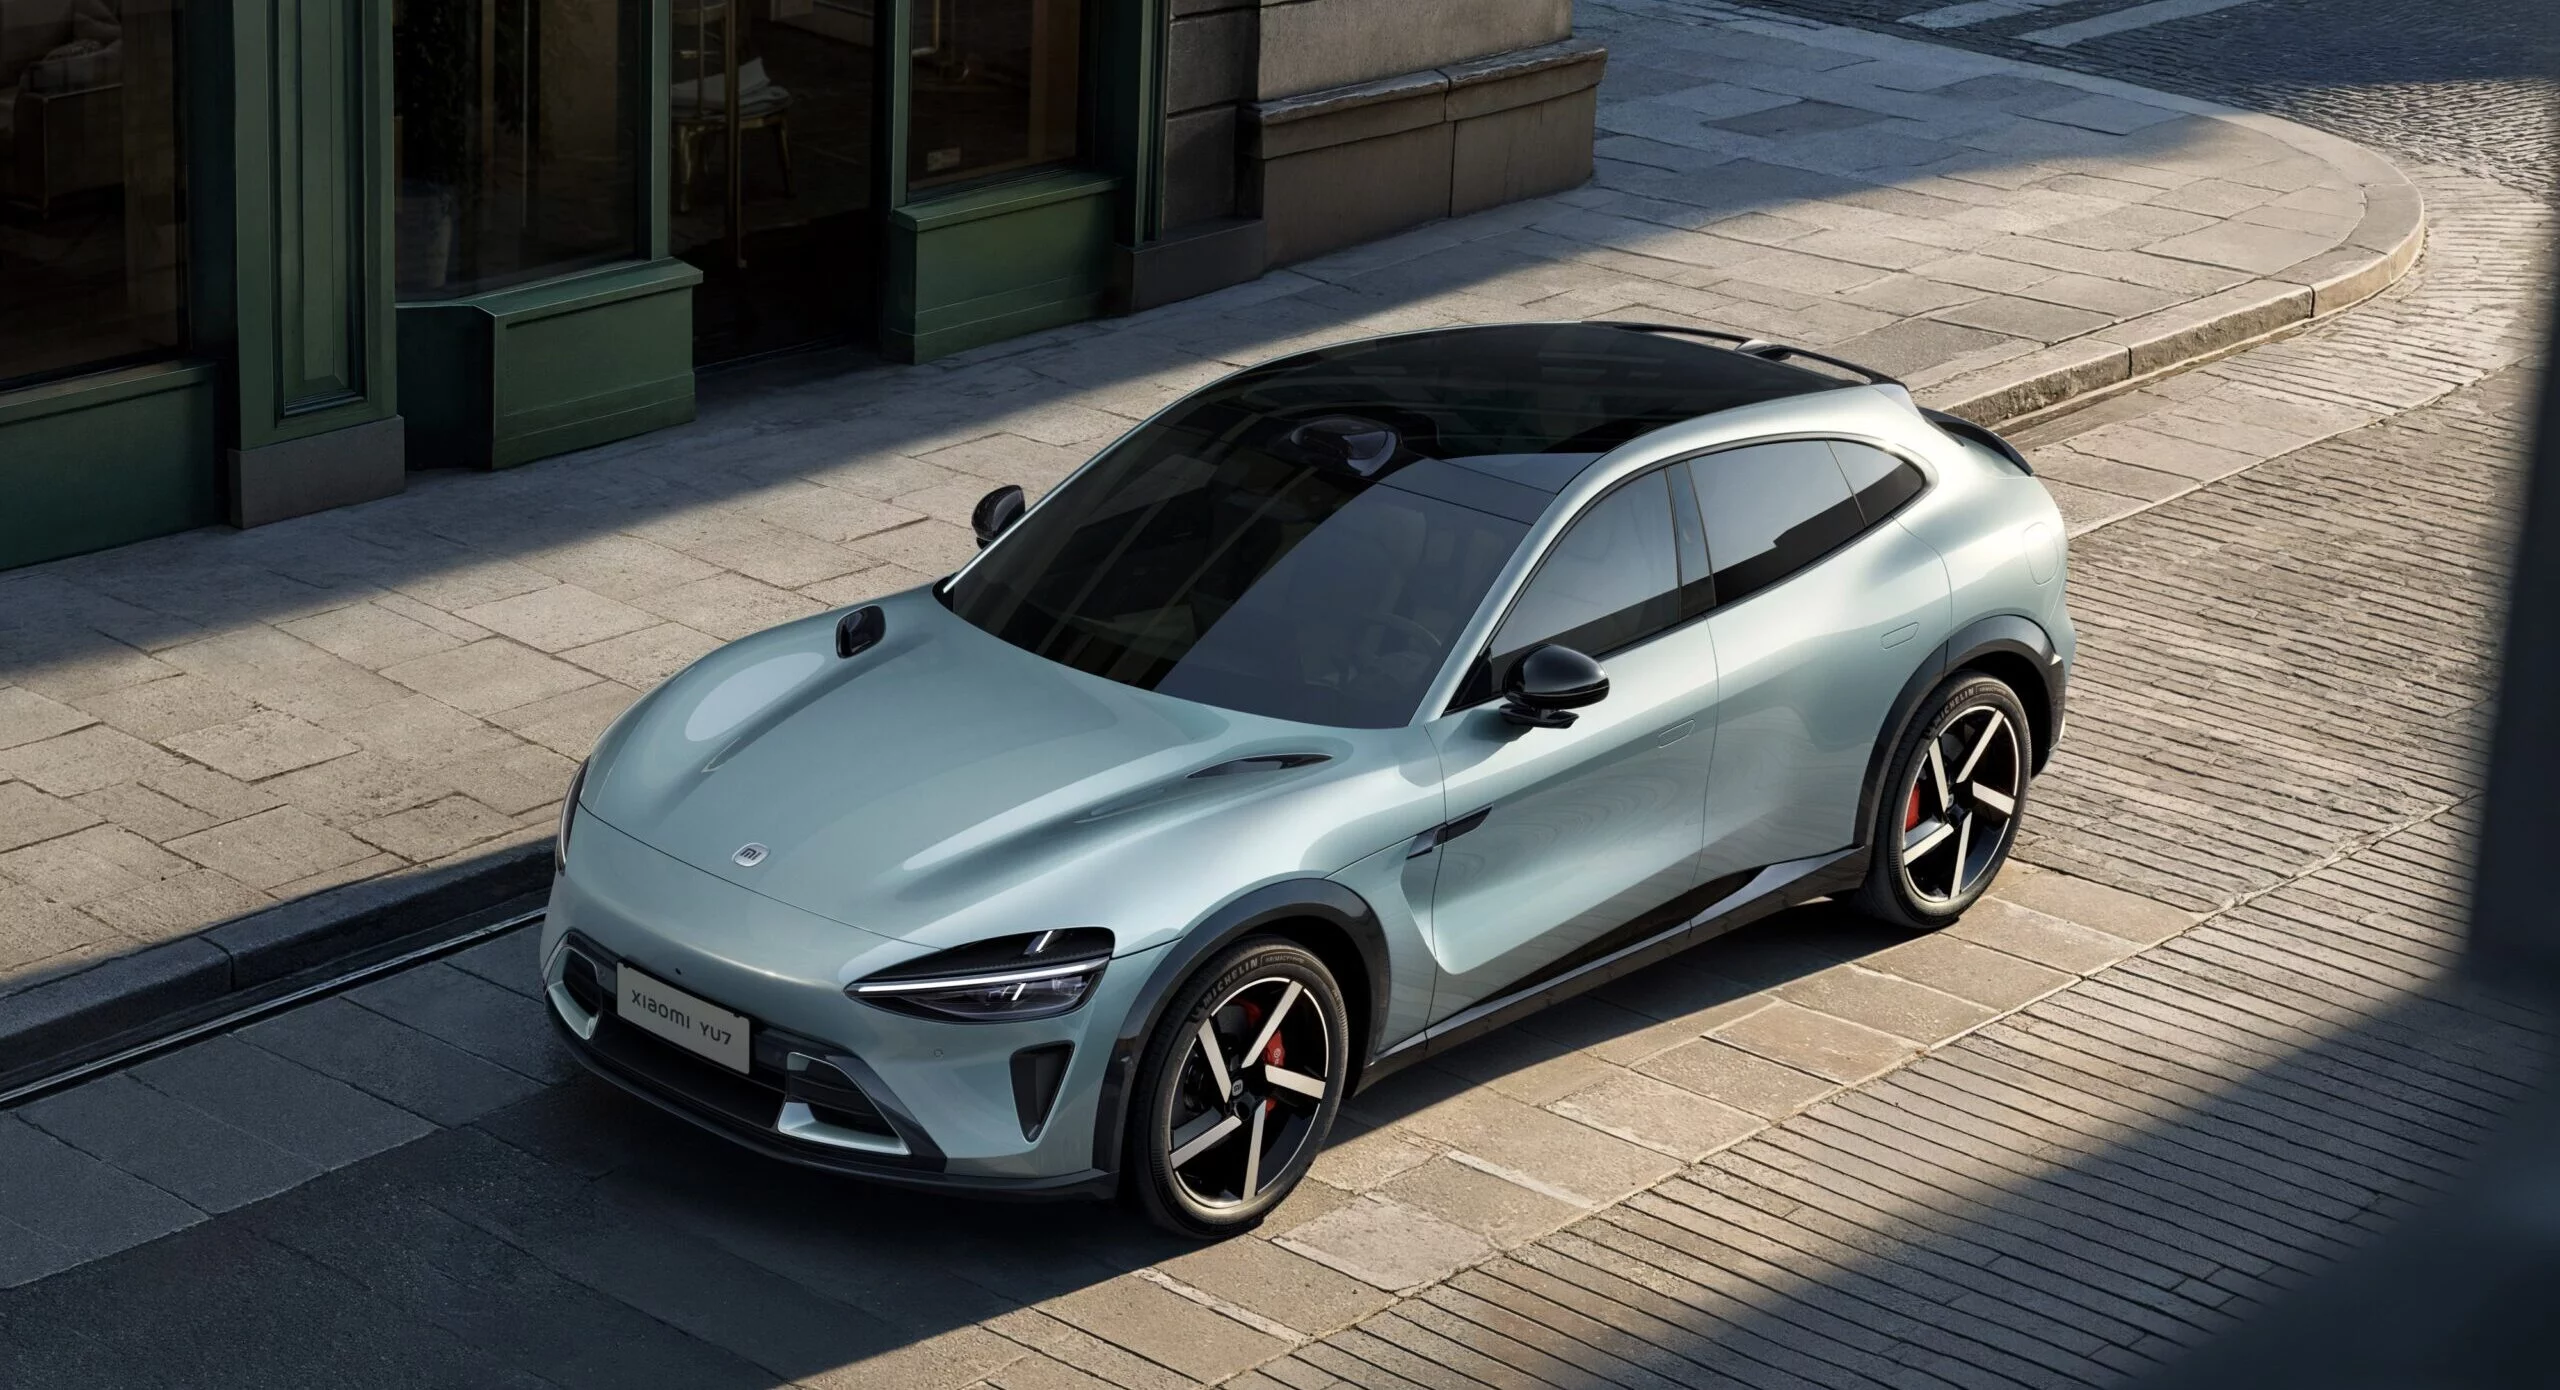
    Xiaomi’s SU7 electric vehicle has reached a substantial delivery milestone, with over 500,000 units now in the hands of customers. This achievement underscores the robust growth in electric vehicle (EV) sales and signals the increasing influence of technology companies in the automotive sector.

    The SU7’s rapid adoption reflects a broader trend of accelerating EV demand, especially within the Asia-Pacific region. As traditional automakers face heightened competition, new entrants like Xiaomi are quickly capturing market share with their tech-integrated vehicles.

    Accelerating EV Market Penetration

    The half-million delivery mark for the SU7 demonstrates Xiaomi’s successful entry into the highly competitive EV market. The company, initially known for its smartphones and consumer electronics, has used its brand recognition and technological expertise to quickly establish a presence in automotive manufacturing. This pivot highlights the convergence of consumer tech and mobility, a trend reshaping retail and consumption patterns across Asia.

    Strong sales figures for the SU7 contribute to the overall surge in electric vehicle adoption globally, with China remaining the largest market. Consumer preferences are shifting towards sustainable transportation options, driven by environmental concerns, government incentives, and advancements in battery technology and charging infrastructure.

    Broader Implications for Retail and Tech

    Xiaomi’s performance with the SU7 provides a clear example for other tech companies considering expansion into new hardware categories. The success in automotive highlights the potential for brand diversification beyond core products, particularly in high-value consumer goods. This move also forces traditional automotive retailers and brands to adapt their strategies, focusing on digital integration, advanced features, and a smooth customer experience that tech-savvy consumers expect.

    The competitive market in Asia’s EV market is intensifying, with both established brands and new startups vying for dominance. RetailNews Asia has been tracking similar moves by companies like Sony, which is also exploring mobility solutions, indicating a strategic shift among tech leaders to diversify their product ecosystems and tap into lucrative automotive opportunities.

  • AI Revolution: The Blossoming Era of Robotaxis Redefining Urban Mobility in Asia

    AI Revolution: The Blossoming Era of Robotaxis Redefining Urban Mobility in Asia

    In Asia, the evolution of urban mobility is accelerating with the advent of robotaxis, which are autonomous vehicles that offer ride-hailing services with minimal to no human involvement. The progress in this field is fueled by advancements in artificial intelligence (AI), machine learning (ML), sensor technology, and supportive regional policies. Due to these factors, Asia is rapidly emerging as a global hub for autonomous vehicle (AV) research, trials, and initial commercial launches.

    Unlike traditional ride-hailing services, robotaxis offer advantages such as reduced operational costs, increased safety, and wider access to transportation. This is especially beneficial for densely populated cities grappling with driver shortage, traffic congestion, and growing transportation needs.

    China: At the Vanguard of Robotaxi Development in Asia

    China is at the leading edge of robotaxi development in Asia, and possibly globally, with substantial governmental support that has elevated autonomous technology to a national strategic priority. As part of initiatives like the 14th Five-Year Plan, Chinese authorities have integrated autonomous vehicles into broader digital economy objectives, promoting pilot programs, regulatory frameworks, and infrastructure development in numerous cities.

    By the middle of 2024, authorities had issued 16,000 test licenses and designated over 32,000 kilometers of public roads for autonomous vehicle testing, marking the largest testing area among all countries.

    Tech behemoths and AV specialists in China, including Baidu, Pony.ai, WeRide, Didi, and others, are fiercely competing to expand robotaxi operations in major cities like Beijing, Shanghai, Guangzhou, Shenzhen, and Wuhan. Baidu’s Apollo Go service has alone completed millions of driverless trips and logged substantial commercial mileage through its app-based ride-hailing service. Similarly, Pony.ai offers commercial robotaxis in multiple Tier-1 cities and has significantly reduced hardware costs for autonomous stacks, a trend influencing scalability.

    The progress of China’s autonomous mobility sector is closely linked to its prowess in AI and data processing. Firms heavily invest in machine learning systems that integrate sensors (LiDAR, radar, cameras) and AI models for perception and decision-making. These systems allow vehicles to navigate complex urban environments, a significant challenge in cities with dense traffic, mixed road users, and variable conditions.

    Singapore: An Incubator for Autonomous Shuttles and Robotaxis

    Singapore is becoming a regional center for autonomous mobility experiments, supporting robotaxi and automated shuttle projects in line with its Smart Nation and sustainable transport strategy. Authorities have teamed up with Chinese robotaxi specialists WeRide and Pony.ai to introduce autonomous shuttle services in residential areas like Punggol, slated to begin in early 2026, pending regulatory approval and mapping preparations.

    These initial services will feature autonomous vehicles navigating fixed routes and providing travel options complementary to existing public transportation. Singapore’s regulatory ecosystem, often viewed as efficient and innovation-friendly, makes the city-state a top pilot zone for AV integration in Southeast Asia.

    Partnerships and Strategic Expansion

    Beyond Singapore, the broader Southeast Asian region is starting to attract commercial robotaxi ventures. Notably, Grab, Southeast Asia’s leading ride-hailing and super app, has revealed a strategic investment in China’s WeRide to expedite the deployment and commercialization of autonomous vehicles across the region, integrating WeRide’s Level 4 robotaxis with its ride-hailing platform.

    The partnership between Grab and WeRide is anticipated to broaden access to autonomous mobility in high-density urban areas, addressing labor limitations and mobility gaps.

    Regional ride-hailing operators are recognizing AI-driven mobility as a supplement to traditional driver-based services, particularly in markets where driver shortages and surging labor costs present challenges.

    Malaysia and Beyond: Commercial Expansion from China

    Key Chinese companies, such as Baidu, are also eyeing cross-border expansion in Southeast Asia. Baidu has declared plans to introduce its Apollo Go robotaxi services to Singapore and Malaysia as early as late 2025, marking the first commercial robotaxi launches in Southeast Asia outside China.

    If executed as planned, these deployments signify crucial milestones in the regional adoption of advanced autonomous mobility services, and illustrate how AI-driven transport can be integrated into existing urban transit networks.

    Japan and South Korea: Testing and Future Markets

    While not as advanced in commercial deployment as China or Singapore, Japan and South Korea are strategically evaluating autonomous technologies and creating ecosystems for future robotaxi operations. In Japan, prominent players like Waymo (operated by Alphabet) have started testing autonomous vehicles in Tokyo, which could be the first step toward commercial robotaxi operations there.

    In South Korea, government-backed pilot initiatives, such as the National Strategic Smart City Program (NSSCP) in Seoul, suggest a growing interest in autonomous solutions, with wider commercialization anticipated in the coming years.

    In Japan, an aging population and robust demand for accessible transportation are driving policy momentum for autonomous mobility solutions, as driverless vehicles can potentially address labor shortages in traditional taxi and delivery services.

    Economic Impact and Challenges

    Market research indicates that the Asia Pacific robotaxi market is poised for substantial expansion. Forecasts predict the sector’s regional value to surge to over USD 60 billion by 2034, growing at a compound annual growth rate (CAGR) exceeding 50%.

    This brisk growth is spurred by strong governmental policy support, particularly in China, coupled with the rise of strategic partnerships between tech companies and ride-hailing platforms. Rising AI capabilities are also reducing hardware costs and enhancing safety, making autonomous mobility more viable. Meanwhile, pressures of urbanization are driving cities toward scalable and efficient transport solutions, whereas labor shortages in driver-based services are hastening the shift toward automation as a practical alternative.

    In spite of the clear momentum, considerable challenges persist across Asia:

    Regulatory Frameworks: Autonomous mobility operates in regulatory gray areas in many jurisdictions. While China and Singapore have established frameworks that encourage testing and limit commercial use, other countries are still formulating safety and liability standards, especially for fully driverless (Level 4/5) operations.

    Safety and Public Perception: AI-powered robotaxis depend on intricate sensor and decision-making systems that must function safely in dynamic urban conditions. Public skepticism about safety, accident liability, and data/privacy concerns can hinder adoption. Effective regulation, robust testing, and transparent reporting will remain key to building trust.

    Infrastructure and Costs: Urban infrastructure, from detailed HD maps to roadside connectivity, must evolve to support reliable autonomous operations. Integration with existing traffic systems and communication networks (vehicle-to-everything technologies) will be crucial for scaling robotaxi services.

    With ongoing progress in AI, machine learning, and regulatory frameworks, robotaxis have the potential to revolutionize how millions of city dwellers commute, creating safer, more efficient, and more accessible transportation networks.

    However, technological advancements must be balanced with inclusive policy development, ethical AI standards, and infrastructure planning to ensure that autonomous mobility benefits society at large. As Asian cities balance swift innovation with public safety and economic impact, robotaxis could not merely reshape transportation, but also redefine urban life in the future.

    Questions & Answers

    What are the advantages of robotaxis over traditional ride-hailing services?
    Robotaxis promise lower operating costs, improved safety, and broader access to mobility, especially in densely populated cities dealing with driver shortages, congestion, and increasing transportation demand.

    Why is China considered a leader in the development of robotaxis?
    With substantial government support, China has integrated autonomous vehicles into its broader digital economy objectives. It has also issued a large number of test licenses and designated a significant amount of public roads for autonomous vehicle testing, which has bolstered its position in the field.

    What challenges do autonomous vehicles face in Asia, and how can they be addressed?</b
  • Vietnam Mobility Show 2025: Pioneering Green Technology In The Automotive Industry

    Vietnam Mobility Show 2025: Pioneering Green Technology In The Automotive Industry

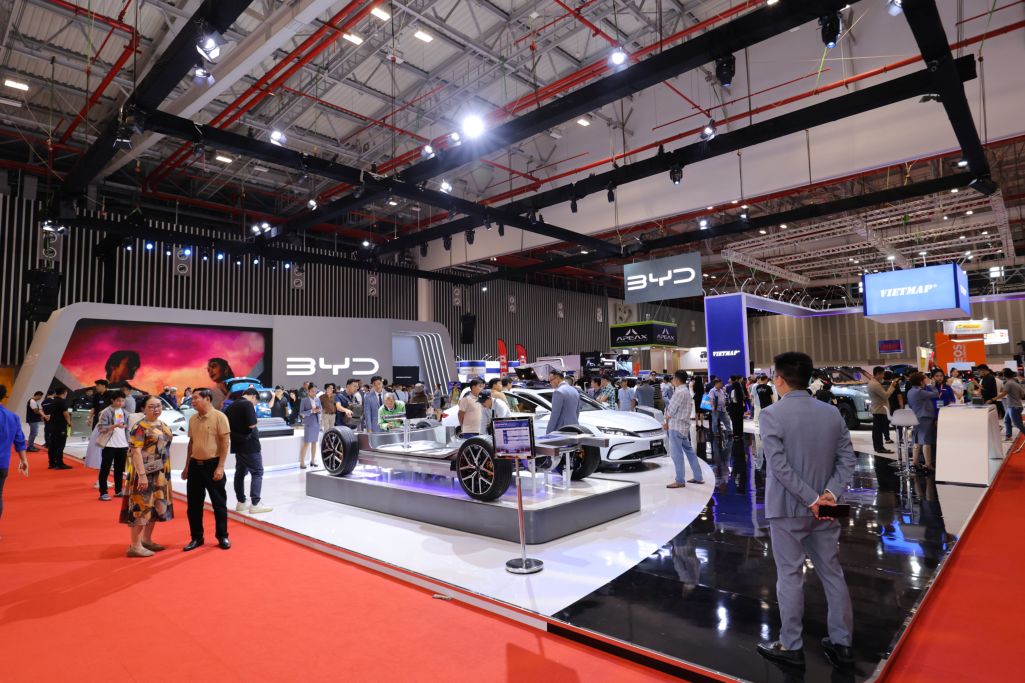
    The Vietnam Mobility Show 2025 is slated to take place in Hanoi from December 26 to 28. This event will present the latest models of cars, motorbikes, and accessories, showcasing cutting-edge technologies and sustainable practices in the automotive industry.

    Eco-friendly Focus

    The show will prominently feature car brands that are employing green technologies and utilizing environmentally friendly materials in an effort to decrease emission and fuel consumption. Aiming to address the pressing environmental issues of our time, the event will also host a seminar titled “Removing Barriers to Accessing Green Vehicles”. This session will gather car manufacturers, distributors, and authorities to discuss viable solutions, goals, and roadmaps for the widespread use and development of electric, hybrid, and other eco-friendly vehicles in Vietnam.

    Experience the Latest Models

    One of the most eagerly awaited components of the exhibition is the test-drive program. Visitors will have the opportunity to experience the latest models, especially those with high performance, on specially designed tracks. Each brand is set to bring a broad range of vehicles for test drives, minimizing wait times for participants.

    Highlighting Electric Motorbikes

    Electric motorbikes will be a vital part of the event, as cities like Hanoi and Ho Chi Minh City are planning to restrict the use of internal-combustion vehicles. This focus on sustainable transportation options aligns with the exhibition’s broader goal of assisting consumers in making educated decisions about their vehicle preferences by blending viewing with test-drive experiences.

    A Celebration for Enthusiasts

    Not just an exhibition, the Vietnam Mobility Show 2025 is also a festival for vehicle enthusiasts and families. The event will feature a dedicated zone for high-performance vehicles, alongside areas for services, accessories, and food. With safety and education in mind, demonstrations on safe charging and how to assist children in escaping from a locked car will be conducted. The event is expected to draw hundreds of thousands of visitors.

    Questions & Answers

    What is the aim of the Vietnam Mobility Show 2025?
    The show aims to present the latest models of cars and motorbikes, spotlighting brands that employ green technologies and sustainable materials. It also seeks to educate visitors, offering test-drive experiences and safety demonstrations.

    What is the focus of the seminar “Removing Barriers to Accessing Green Vehicles”?
    The seminar will bring together manufacturers, distributors, and authorities to discuss strategies, goals, and roadmaps for the development and adoption of electric, hybrid, and other eco-friendly vehicles in Vietnam.

    What experiences will be offered at the event?
    Visitors will have the opportunity to see and test drive the latest car and motorbike models, especially electric and high-performance vehicles. The show will also provide safety demonstrations and various services, accessories, and food options.

  • Hyundai To Take Stake In German Hydrogen Fuelling Group H2 Mobility

    Hyundai Motor will invest in Germany’s H2 Mobility network of hydrogen fuelling station operators, it said on Thursday, as it looks to support infrastructure for fuel cell-powered vehicles.

    A partner in the project since 2017, Hyundai Motor’s German subsidiary will become a seventh shareholder shortly, it said, having received approval from Germany’s cartel office.

    The South Korean company did not disclose financial details.

    It joins investors including France’s Total, Shell, OMV, industrial gas makers Linde and Air Liquide, and carmaker Daimler.

    “In Germany, a lot of money is flowing into the topic of hydrogen through the European Union Green Deal and national funding, and we believe that we are at the forefront,” said Ronald Grasman, vice president of fuel cell business development at Hyundai Motor Company.

    Hyundai, the biggest-selling Asian carmaker in Germany, had a 3.7% share of the market in January-July 2021 supplying a mix of conventional, electric and fuel-cell vehicles.

    Fuel cell cars are far from mass market production.

    But Hyundai, which is introducing fuel cell trucks in Switzerland, believes hydrogen technology could also play a bigger role in small vehicles further down the road.

    H2 Mobility operates 91 hydrogen filling stations and is expanding.

    H2 Mobility Managing Director Nikolas Iwan said the group was looking for anchor customers to bring big volumes to the stations, hoping this will allow them to reach break even within two to three years.

    “This is why Hyundai is so important. They have the lead when it comes to scaling effects, especially in the area of commercial vehicles,” he said.

    Hyundai, the biggest-selling Asian carmaker in Germany, had a 3.7% share of the market in January-July 2021 supplying a mix of conventional, electric and fuel-cell vehicles.

  • Shared services models fuel demand for mobility-as-a-service

    Shared services models fuel demand for mobility-as-a-service

    Shared mobility business models that focus on integrated and digitally connected ecosystems that offer unified multi-modal mobility services and personalized user experiences will find high adoption all over the world.

    “Globally, companies are planning to commercialize autonomous shuttles between 2020 and 2022, backed by favorable government initiatives in North America, the UK, China, Japan, and Dubai,” said Abhishek Iyer, research analyst, Mobility at Frost & Sullivan.

    “There will be an increase in the number of partnerships and rollouts of new technologies such as autonomous shuttles, blockchain, and Artificial Intelligence (AI), which will enhance user experience and operation.”

    Iyer noted that governments across developed cities are building testing infrastructure and piloting autonomous shuttles to evaluate viability and user experience. “Approximately 10 to 15 cities can be expected to conduct autonomous shuttle trials on public roads in 2019. Cross-industry collaborations for connected technologies, integrated payment capabilities, shared mobility insurance and financial services will also prove to be critical for future success,” he commented.

    The researcher suggested that further growth opportunities will come with industry participants partnering with stakeholders from other industries such as banking and financial services (BFS) and insurance to lower costs and generate fresh revenue streams.

    Other opportunities include adopting business models such as vehicle subscription services, demand responsive transit (DRT), ride-hailing and carsharing to create opportunities for data monetization. This will also allow them to leverage their investments and partnerships to develop autonomous and emission-free vehicle technologies.