Tag: New Delhi

  • Temasek Invests S$342M in India’s Godrej Capital

    Temasek Invests S$342M in India’s Godrej Capital

    Singapore state investor Temasek will invest 25 billion rupees (S$342 million) in Indian non-bank lender Godrej Capital through an affiliate, valuing the firm at up to 280 billion rupees.

    Parent company Godrej Industries will retain roughly 80 percent equity ownership in the credit business after the cash injection closes.

    How the Capital Works

    The transaction gives the credit unit fresh equity to underwrite consumer housing loans, property-backed borrowing, and operational funding across commercial hubs. Godrej Capital, launched in 2020, runs branches across more than 100 cities in India.

    Assets under management stood at 350 billion rupees as of October 31, 2026. Subsidiary companies write mortgages, secured loans against real estate assets, working capital lines, construction funding, and unsecured personal credit for merchants and households.

    Institutional Demand for Indian Credit

    Global investors want exposure to India’s retail lending spreads as prime commercial banks turn selective on mid-tier borrowers. Temasek already holds equity in ICICI Bank, India’s second-largest private lender by market value, giving the sovereign fund positions across both balance-sheet banking and shadow lending networks.

    Foreign funds are taking strategic blocks rather than public market paper. Fairfax Financial Holdings picked up a 60.7 percent stake in IDBI Bank earlier in 2026, while Bank of America formed a joint venture to take 49.9 percent of Jio Credit, the lending arm of Jio Financial Services.

    Lending Scale and Operating Risk

    Competition across top Indian urban centres is compressing loan margins. Established non-bank finance companies and digital payment apps compete for the same secured small-business borrowers, raising customer acquisition costs across branch networks.

    For Godrej Capital, real estate links provide a direct pipeline. Property buyers and commercial contractors working with the wider industrial conglomerate offer immediate loan volume, reducing marketing overheads that independent non-bank lenders carry.

    Building the Balance Sheet

    The fresh funds follow six years of retail footprint expansion from Godrej Industries as it built out its financial services division. The group previously relied on real estate development and consumer goods to drive operating cash flows before setting up dedicated lending subsidiaries.

    Group management is using the equity round to establish balance sheet strength ahead of a public market debut. Financial services represents a major long-term growth area of focus for our Group, and our ambition is to build Godrej Capital into a 1 trillion-rupee AUM franchise by 2031, said Pirojsha Godrej, chairman of Godrej Industries Group.

    Godrej Industries plans to list Godrej Capital on domestic stock exchanges within five years, setting up public filings as assets approach the 1 trillion rupee target.
  • Indian Telecom Carriers Face 5G Speeds Squeeze as Data Traffic Surges

    Indian Telecom Carriers Face 5G Speeds Squeeze as Data Traffic Surges

    Mobile subscribers in India are consuming an average of 31.1 gigabytes of cellular data each month, driving monthly mobile network traffic to 27.6 exabytes and squeezing real-world 5G connection speeds across major commercial centres.

    Monthly 5G volume climbed 70 per cent year over year to 12.9 exabytes, now accounting for 46.8 per cent of all cellular data traffic in the country, according to Nokia’s Mobile Broadband India Traffic Index 2026. Network capacity is falling behind that appetite. Even as carrier icons display 5G service on phone screens, users face sluggish response times and reduced throughput across shopping centres, transport hubs and high-density housing developments.

    Traffic Surges Overwhelm Local Cells

    Radio cells in major urban corridors now handle simultaneous demand for video streaming, cloud gaming, digital retail checkouts and video conferencing. When thousands of handsets connect to a single base station, available radio spectrum splits across those devices, causing local throughput to fall sharply regardless of advertised network capabilities.

    The Telecom Regulatory Authority of India reported that total wireless mobile data consumption reached 84,424 petabytes during the April to June quarter of 2026. That represents an 8.30 per cent quarter-on-quarter increase from 77,953 petabytes. Average monthly wireless data usage per subscriber rose 6.32 per cent to 28.39 gigabytes over the same period.

    Reliance Jio reported in its October 2026 financial disclosures that its user base included roughly 300 million 5G customers out of 542 million total connections. Individual monthly data usage on Jio’s network reached 44.2 gigabytes per subscriber, up from 38.7 gigabytes twelve months earlier. Handling that traffic volume demands constant radio densification and high-capacity backhaul lines.

    The Backhaul Bottleneck and Indoor Walls

    Carrier deployments show rapid physical additions, but transmission feeds from base stations to core networks frequently fall short. Fixed wireless access services have intensified that strain. Home broadband products such as Reliance Jio’s JioAirFiber and Bharti Airtel’s Xstream AirFiber now generate more than 25 per cent of all 5G data traffic in India, locking heavy continuous data streams onto cellular masts.

    Physical structural barriers compound the problem. High-frequency 5G radio signals, particularly mid-band 3.3 GHz frequencies, struggle to penetrate concrete walls, metallic cladding and coated window glass in indoor commercial venues. When indoor signal strength falls, base stations downgrade customer devices to more robust but slower transmission modulations, cutting download rates.

    Regulator drive tests conducted in July 2026 across Kolkata, Howrah and Hooghly logged 122 poor-signal samples for Airtel, 181 for Jio, 401 for Vodafone Idea and 3,904 for state-run BSNL across roughly 65,000 samples per operator along 309.7 kilometres of roadways and hotspots. Cellular operators rely on hardware vendors like Ericsson, Nokia, Samsung Networks and Mavenir for carrier aggregation and active antenna arrays, but equipment on towers cannot bypass missing fibre lines.

    Operator Speeds and Consumer Grievances

    Performance gaps between operators remain wide in field measurements. Testing conducted by nPerf across real users between April 2025 and March 2026 showed Bharti Airtel leading average download performance at 113.81 megabits per second, with an upload rate of 16.84 Mbps and latency of 58.98 milliseconds. Reliance Jio recorded 94.22 Mbps down, 8.97 Mbps up and latency of 62.09 milliseconds.

    Vodafone Idea trailed with average download speeds of 75.80 Mbps, higher upload speeds of 14.51 Mbps and elevated latency of 111.60 milliseconds. BSNL delivered 15.11 Mbps down and 5.45 Mbps up, reflecting its reliance on an indigenous 4G network deployed with TCS, Tejas Networks and C-DOT. State filings showed BSNL operated 95,511 active 4G sites out of 97,672 installed units as of January 15, 2026.

    Capital Allocation and Network Expansion

    Private operators have pursued diverging technical strategies to maintain performance. Reliance Jio built its standalone 5G network from the outset, whereas Bharti Airtel expanded via non-standalone 5G configurations while adding infrastructure. Airtel deployed more than 2,900 new 5G sites across Punjab, Haryana, Himachal Pradesh and Jammu and Kashmir over 12 months, covering 77 districts, alongside 2,750 sites in Gujarat.

    Vodafone Idea is executing a phased catch-up strategy. After servicing 43 cities across 17 priority circles, the company mapped out an expansion in March 2026 targeting 90 additional cities to reach 133 municipal markets. Network equipment suppliers including Nokia, Ericsson and Samsung have secured rollout contracts to modernize Vi’s physical gear, but spectrum density in residential districts remains thin.

    Retailers and mobile commerce operators rely directly on cellular network stability at the point of sale. Digital payments, dynamic in-store inventory tracking and rapid logistics fulfillment require low-latency cell handoffs that degraded 5G connections fail to deliver during peak foot-traffic hours. The pressure now shifts to municipal fibre approvals and small-cell indoor installations.

    The next major performance test will come as Vodafone Idea works to operationalize its expanded 133-city footprint.

  • Bata India Names Jasleen Kaur as Head of Marketing

    Bata India Names Jasleen Kaur as Head of Marketing

    Bata India Limited promoted Jasleen Kaur G to Head of Marketing, placing her in charge of consumer positioning across its national store network.

    The promotion hands Kaur direct control of flagship identity and sub-brand positioning across labels including Hush Puppies, Scholl, Bubble Gummers, Nine West, Power, Floatz and North Star. She took over the footwear retailer’s category marketing and public relations in October 2024 before stepping into the top marketing position.

    Portfolio Oversight Across Sub-Brands

    Managing the marketing operations requires balancing Bata’s legacy mass-market reputation against higher-margin labels. Kaur steps into the executive marketing post after directing marketing and public relations across the Indian subcontinent for Benetton Group, where she spent more than seven years covering India, Nepal, Sri Lanka and Myanmar.

    Her retail background also includes a role as Assistant Vice President for Marketing at Reliance Brands Limited. In that post, she managed public relations and marketing programs for international lifestyle franchises including Hugo Boss, Mothercare and Hamleys.

    The Premium Footwear Challenge

    Footwear retailers in India face intense pressure from regional casualwear disruptors and aggressive athletic footwear operators alongside global sportswear names. Bata has relied on expanding premium licensing partnerships like Nine West and modernizing lines like Hush Puppies to lift margins above budget leather baselines.

    Entrusting multiple consumer segments to an executive with experience at Reliance Brands points to a clear mandate: defend market share at entry price points while accelerating the transition toward mall-based premium shoppers. The risk sits in retail execution across tier-2 and tier-3 franchisees, where legacy customer perception frequently resists premium pricing pushes.

    Career Trajectory and Academic Credentials

    Kaur started her career in journalism before shifting into corporate brand management and digital marketing at Canon India and India Infrastructure Publishing. In early 2023, she founded Indiawood Global, an entrepreneurial venture she ran prior to joining Bata’s category marketing team.

    Her academic background includes an undergraduate degree in English Literature from Delhi College of Arts and Commerce between 2006 and 2009, followed by a master’s degree from Jamia Millia Islamia. She completed brand management and digital marketing management training at the Indian Institute of Technology, Delhi, executive education in sustainable development at Columbia University, and an MBA in marketing and strategy from the Management Development Institute.

    Investors and retail operators will monitor how Kaur reshapes promotional spending and product visibility for the Power and Hush Puppies franchises during the upcoming spring-summer selling season.

  • Bharti Airtel Misses Profit Forecast as Network Costs Climb 11 per Cent

    Bharti Airtel Misses Profit Forecast as Network Costs Climb 11 per Cent

    Bharti Airtel reported a second-quarter consolidated net profit of 88.88 billion rupees, equivalent to 940.45 million dollars, missing market expectations as network operating expenses rose.

    Consensus estimates compiled by LSEG projected net profit at 96.73 billion rupees for the three months ended September 30, even as total revenue increased 16.7 per cent to 608.78 billion rupees.

    Network costs jumped 11 per cent during the period, driven by the maintenance and operation of telecom infrastructure across the country. Licence fees climbed 13 per cent, pushing total quarterly expenses up approximately 15 per cent to 259.32 billion rupees. Consolidated profit nevertheless gained from the 67.92 billion rupees recorded in the corresponding quarter a year prior, though top-line growth could not fully cushion operational inflation.

    Tariff Limits and Premium Migration

    Average revenue per user increased 6 per cent year-on-year to 271 rupees, keeping Airtel ahead of domestic peers on unit realisations. The metric gained traction as the carrier added 18.8 million customers to its combined 4G and 5G footprint. Without broad-based tariff increases across the Indian market since July 2024, the business leaned on product pruning to lift receipts. Airtel removed several lower-tier prepaid denominations during the quarter, steering entry-level customers toward costlier recharge tiers.

    That migration strategy reflects the ceiling facing Indian operators until the next coordinated price adjustment takes place. Relying entirely on organic plan migrations carries friction, particularly as inflation pressures lower-income prepaid consumers. Brokerage Centrum projects an industry-wide tariff increase of 12 to 15 per cent across the next four to five months, an intervention that would directly feed operating margins.

    The Market Share Contest With Jio

    Competition across India remains defined by the pricing environment established since Reliance Jio entered the sector in 2016. Airtel closed the September quarter with an Indian customer base of 498.7 million, up 10.9 per cent year-on-year. That total leaves the operator trailing Jio, which commands 542.4 million subscribers.

    For mobile hardware distributors and digital platform operators, the divergence between the two dominant players shapes commercial exposure. Jio continues to capture volume across price-sensitive tiers, while Airtel defends higher-value urban and postpaid accounts through network coverage investments. Maintaining that premium positioning requires elevated capital allocation toward 5G base stations, driving the maintenance overhead that clipped Airtel’s quarterly earnings.

    Regional Support From African Operations

    International operations provided a counterweight to domestic margin compression. Revenue from Airtel Africa, which spans 14 countries across sub-Saharan Africa and delivers approximately one quarter of total group revenue, advanced 37.6 per cent.

    The current operating performance follows a prolonged period of post-auction network rollout across India, where capital spending on 5G spectrum and hardware converted into recurring maintenance obligations. While earlier quarters benefited from initial 5G user migrations, operating expenses have now caught up with network densification.

    Market attention now shifts to the timing of broad-based price adjustments, with operators balancing customer retention against the projected 12 to 15 per cent tariff revision expected before the end of the fiscal year.

  • India Regulator Fines Shangri-La Eros ₹1 Lakh over Service Charge

    India Regulator Fines Shangri-La Eros ₹1 Lakh over Service Charge

    India’s Central Consumer Protection Authority fined Shangri-La Eros in New Delhi ₹1 lakh on 22 October 2026 for automatically adding a 10 per cent service charge to customer bills.

    The penalty targeted Mister Chai, the hotel’s restaurant, after regulatory investigators established that printing an optional disclaimer on a menu does not make an automated charge voluntary.

    Under the order, regulator CCPA held that default bill levies violate consumer protection rules by requiring patrons to actively demand their removal before paying. The hotel had argued that diners retained adequate time to dispute the 10 per cent surcharge, that cashiers could issue refunds on request, and that menus clearly designated the fee as discretionary. CCPA rejected every defense.

    Investigators examined two customer bills dated 30 May and 10 June 2025. In both instances, the hotel added the 10 per cent charge to the food total before calculating Goods and Services Tax, inflating the taxable baseline and the final sum demanded at the counter.

    The Breakdown of Default Billing

    Shangri-La Eros told the regulator it changed its billing description to read “Charges for Voluntary Staff Contribution (optional)” and refunded the complainant. It completely halted collecting the levy on 1 October 2026, after CCPA took cognisance of the matter.

    The watchdog ruled that altering invoice labels solved nothing. Default inclusion creates an opt-out trap where guests must spot the line item, confront floor staff, and negotiate its deduction from the printed check.

    The ruling enforces guidelines published on 4 July 2022. Those rules bar hospitality operators from adding service fees automatically, disguising them under alternate accounting titles, or restricting dining access to patrons who refuse to pay. They also expressly prohibit calculating GST on top of service levies.

    Hospitality Margins and Billing Risk

    For hotel owners and food and beverage operators in India, the penalty removes any lingering legal ambiguity around automated tips. Premium operators long relied on mandatory service fees to subsidize back-of-house payroll and retain floor staff without adjusting headline menu rates. That pricing buffer is gone.

    Operators who continue to default to automated levies face direct exposure under Section 21(7) of the Consumer Protection Act, 2019. The statute allows authorities to calibrate fines according to business turnover, the duration of non-compliance, and the volume of customers billed. Incorporating staff remuneration directly into published food prices now represents the only compliant commercial route, even if higher menu figures dampen casual footfall.

    RetailNews Asia sees the primary operating risk shifting straight to point-of-sale software configurations. Independent operators and hotel chains frequently license billing suites that automatically load standardized service percentages at the final checkout screen. Franchisors and hospitality landlords must audit point-of-sale systems across their networks immediately, because consumer protection enforcement in India is now driven directly by customer invoice uploads to the National Consumer Helpline.

    Court Backing and Enforcement Wave

    The penalty against Shangri-La Eros builds directly on a key judicial precedent delivered early last year. The Delhi High Court upheld the CCPA’s service charge framework on 28 March 2025, confirming that mandatory charges infringe statutory rights and ruling that tips must depend entirely on customer initiative.

    Regulatory pressure intensified throughout 2026 across dining categories. In January 2026, the watchdog pursued suo motu actions against 27 restaurants nationwide, handing down penalties up to ₹50,000 and mandating billing adjustments alongside customer refunds.

    Penalties hit chains quickly. Café Blue Bottle in Patna paid ₹30,000 and Mumbai’s Bora Bora outlet under China Gate Restaurant paid ₹50,000 under orders issued on 10 January 2026. Quick-service tea chain Chaayos received a ₹50,000 penalty on 14 July 2026, followed five days later by orders against Fiesta by Barbeque Nation, FOO Ahmedabad Restaurant, and bakery chain L’Opéra. Japanese curry chain Curry House CoCo Ichibanya drew a ₹20,000 penalty on 19 October for a 10 per cent automated charge.

    Pending Actions Across the Market

    More regulatory orders are due before the end of the quarter. The authority initiated separate suo motu proceedings against 41 restaurants in July 2026 following complaints registered through national consumer portals, with final penalty determinations pending in those dockets.

  • Maruti Suzuki Exports Rose 59.3% in October Despite Shipping Strain

    Maruti Suzuki Exports Rose 59.3% in October Despite Shipping Strain

    Maruti Suzuki exported 49,872 vehicles in October, rising 59.3 per cent from a year earlier despite worsening shipping disruptions across maritime corridors in West Asia.

    India’s largest carmaker, Maruti Suzuki India Ltd., accounts for more than half of the country’s passenger vehicle exports, maintaining shipments even as secondary transport links come under pressure.

    Transit routes through West Asia serve as a vital corridor to Europe and North Africa. Trade lanes around the Strait of Hormuz have suffered recurring delays since conflict broke out in late February following a joint US and Israel operation in Iran.

    Alternate Routes Face Congestion

    Vessels bypassing disrupted passages now face escalating delays as alternative maritime corridors run out of spare capacity. Rahul Bharti, senior executive officer for corporate affairs at Maruti Suzuki, confirmed the logistical friction at a press briefing on Sunday.

    “The Middle East situation has actually slightly worsened. We were using an alternate route, even that alternate route has a bit of a problem,” Bharti said.

    Export demand in destination markets remains stable. That customer appetite is forcing carmakers to absorb complex freight rerouting rather than trimming assembly line targets in India.

    Margins Squeezed Across Automakers

    Higher transit times and elevated commodity prices linked to the conflict took a direct toll on earnings during the September quarter. Maruti Suzuki posted a 26 per cent drop in net profit to 2,466 crore rupees, while rival exporter Hyundai Motor India recorded a 24 per cent decline to 1,196 crore rupees.

    Other vehicle exporters face the same pinch. Two-wheeler manufacturers Bajaj Auto, TVS Motor and Hero MotoCorp have reported higher freight expenses on outbound deliveries to overseas markets, while carmakers including Volkswagen and Nissan manage identical distribution headwinds out of Indian assembly hubs.

    The margin squeeze illustrates the structural vulnerability facing Indian automotive export operations. When maritime chokepoints close, the resulting freight surcharges and insurance premiums land squarely on operating margins, even when consumer order books remain filled.

    Tariffs and Electric Vehicle Strategy

    Maruti Suzuki distributes cars to roughly 120 export markets to avoid overreliance on individual territories. A sharp tariff increase in Mexico, where import duties jumped from 20 per cent to 50 per cent, dragged total volume in that market lower, offsetting gains elsewhere.

    The company is countering regional volatility by expanding electric vehicle distribution into developed markets. Outbound shipments of the electric e-Vitara to destinations such as Europe and Japan are designed to build a buffer against tariff hikes in the Americas and shipping friction across the Middle East.

    Tracking Shipping Costs and Deliveries

    Sustained freight disruptions now test whether expanding overseas sales can remain profitable without prolonged supply chain normalization.

    Automakers will monitor freight rates through the final calendar quarter as Maruti Suzuki prepares additional batches of the e-Vitara for Japanese and European showrooms.

  • India Approves Xavier Niel’s €5.1 Billion Vodafone Stake Acquisition

    India Approves Xavier Niel’s €5.1 Billion Vodafone Stake Acquisition

    The Competition Commission of India on Friday approved French billionaire Xavier Niel’s acquisition of a 16.2 per cent stake in Vodafone Group for approximately €5.1 billion.

    Niel’s family investment vehicle, Vega SAS, bought the holding from Emirates Telecommunications Group, positioning the French executive as the British telecom carrier’s single largest shareholder once the transaction closes.

    Vega SAS operates as a wholly owned subsidiary of French-incorporated Maya SAS. While Vega SAS maintains no direct operating assets in India, the transaction triggered regulatory review due to Vodafone Group’s local joint venture, Vodafone Idea Ltd. Indian merger control regulations mandate clearance for offshore ownership changes that cross statutory revenue or asset thresholds affecting domestic market competition.

    Regulatory Gateways and Domestic Telecom

    The transaction required formal sign-off because Vodafone Idea remains one of India’s three primary private mobile network operators. Any shift in ultimate ownership among its primary foreign backers draws regulatory scrutiny over domestic market structure, spectrum stewardship and corporate control.

    Niel founded French telecommunications group Iliad, which disrupted continental Europe through low-cost mobile contracts and bundled broadband packages. Bringing an aggressive telecom operator into Vodafone’s apex ownership structure introduces a distinct operating philosophy to a carrier balancing heavy capital outlays across its global network.

    Divestments and Portfolio Consolidation

    Vodafone Group has spent recent years unwinding underperforming European operations to cut debt. The group agreed to exit operations in Italy and Spain, sold its 50 per cent stake in a Dutch joint venture, and pursued a merger with Three to form the largest mobile operator in the United Kingdom.

    Those portfolio sales narrowed Vodafone’s geographic focus while leaving its emerging market holdings under persistent capital pressure. India represents Vodafone’s most complex exposure, where Vodafone Idea continues to balance legacy government dues against the need for network equipment upgrades.

    Agreement Terms and Indian Clearances

    The stake purchase formalises an arrangement struck in July, when Vega SAS entered into a binding deal with Emirates Telecommunications Group to take over the position. Emirates Telecommunications had built its holding over successive market purchases before agreeing to transfer the block to Niel’s investment vehicle.

    Alongside the Vodafone decision, the Competition Commission cleared corporate acquisitions in renewable energy and infrastructure. The regulator approved Aditya Birla Renewables’ purchase of Solenergi Power from Shell Overseas Investment BV, alongside Adani Energy Solutions’ full buyout of IntelliSmart Infrastructure from the National Investment and Infrastructure Fund and Energy Efficiency Services Ltd.

    Completion of the transaction now rests on final closing procedures between Vega SAS and Emirates Telecommunications Group following the clearance.

  • Blinkit Adds 308 Stores as Net Order Value Surges to ₹20,940 Crore

    Blinkit Adds 308 Stores as Net Order Value Surges to ₹20,940 Crore

    Blinkit increased net order value by 79.3 per cent year on year to ₹20,940 crore in the September quarter, lifting dark store numbers across India to 2,751.

    The quick-commerce unit added 308 net facilities during the three-month period and turned an adjusted EBITDA profit of ₹184 crore, reversing a ₹156 crore loss reported twelve months earlier.

    Parent group Eternal revealed the operational shift in its Q2FY27 shareholder letter, where Albinder Dhindsa raised Blinkit’s network expansion trajectory. The company now plans to cross 3,500 dark stores by March 2027, up from an earlier target of 3,000, with internal blueprints aiming for roughly 5,000 locations by March 2028. Its adjusted EBITDA margin reached 0.9 per cent of net order value for the quarter.

    Inventory Swells Past Pure Grocery

    Assortment depth is driving the physical footprint expansion. In the Delhi-NCR market alone, Blinkit increased its available catalogue from roughly 80,000 stock-keeping units in Q4FY26 to about 100,000 SKUs by the end of the September period.

    The inventory push moves far past packaged food and household staples. Dark stores are stocking consumer electronics, phone chargers, premium beverages, branded diapers, and gaming consoles, with Dhindsa pointing toward household appliances and gifting items for ten-minute dispatch.

    Handling bulkier merchandise changes the operating mechanics inside each depot. Heavier white goods require dedicated storage racking and altered handling procedures, while high-value electronics mandate tighter packaging controls and loss-prevention security. Sourcing arrangements and consumer return processing also differ fundamentally from non-perishable groceries, forcing local managers to balance slow-turning goods against high-velocity essentials.

    Smaller Cities Match Metro Velocity

    Internal network data from the operator contradicts the long-held industry assumption that rapid dispatch models function exclusively inside affluent tier-one metro districts.

    New fulfillment hubs in smaller regional cities reached 1,000 daily orders at speeds identical to metro openings, with several ramping faster. Average order values in these secondary markets tracked between 85 per cent and 90 per cent of metropolitan baskets, supported by repeat purchasing patterns that mirror core capital zones.

    For regional retail ecosystems, quick commerce serves an availability function rather than simple convenience. Shoppers in tier-two and tier-three hubs turn to dark store apps to secure branded goods that organized physical retail distribution never placed on regional store shelves. Sourcing and transport overheads remain high, however, and management conceded that smaller cities with low population density will stay subscale.

    Mature Hubs Cross Profit Threshold

    Financial durability rests on dark store maturity profiles across specific municipal clusters. Hubs generating roughly 96 per cent of Blinkit’s total net order value are now contribution-positive, while municipal zones accounting for about 70 per cent generate positive adjusted EBITDA.

    Established cities in the network operate above a 5 per cent adjusted EBITDA margin. Group management projects that expanding profits from these older operating zones will absorb the start-up losses generated by new store openings, keeping consolidated margins positive throughout the rollout.

    Discount hunters are receiving less attention in the network allocation model. Dhindsa noted that coupon-dependent buyers consume the same finite dark store packing capacity as regular shoppers but disappear once subsidised incentives stop. Current software algorithms prioritize consumers who generate repeat weekly baskets across multiple categories.

    Working Capital and Rival Retailing

    RetailNews Asia notes that Blinkit’s aggressive category broadenings pit it directly against horizontal marketplace leaders. Amazon and Walmart-owned Flipkart stepped up quick-delivery investments in June, pushing ultra-fast fulfillment networks into regional Indian cities using their existing logistics muscle and supplier balance sheets.

    Holding broader stock lines carries immediate balance sheet friction. Eternal’s cash reserves contracted by ₹1,813 crore during the quarter to settle at ₹16,475 crore, dragged down by seasonal inventory build-ups before peak autumn festive consumption and settlement cycles inside its restaurant delivery arm. The corporate entity also reported 76 per cent growth in consolidated adjusted revenue, beating a 58 per cent like-for-like rate as it assumed direct merchandise ownership across its dark store supply chains.

    Private labels remain off the platform roadmap for now. Blinkit decided against introducing house brands, with Dhindsa concluding that own-label items fail to create incremental basket demand once brand-building expenses are factored in. The firm plans to protect supplier advertising income rather than undercut third-party manufacturers.

    Network eyes now turn to the execution of the 749 additional dark store openings required to hit the 3,500-unit threshold before the close of fiscal 2027.

  • India Plans Stake Cuts in Four State Banks to Meet Float Norms

    India Plans Stake Cuts in Four State Banks to Meet Float Norms

    India plans to trim its equity holdings in four state-run banks to 75 per cent through market offers for sale over the next year. The move targets Indian Overseas Bank, Central Bank of India, UCO Bank, and Punjab & Sind Bank to comply with public shareholding regulations.

    Selling down these holdings addresses mandatory listing requirements while opening a path to strategic privatisation for at least two lenders. The divestments will proceed via offers for sale as market conditions allow, alongside fresh equity sales by the institutions themselves to strengthen their capital buffers.

    Expanding Market Float Across State Lenders

    Increasing the public shareholding threshold from current depressed levels aims to deepen liquidity and improve secondary market valuations. State-owned commercial institutions previously operated under regulatory exemptions from the standard 25 per cent minimum public float rule, a shelter running through August 2026.

    The policy push directly impacts domestic corporate lending dynamics and consumer credit syndication across Tier-2 and Tier-3 commercial markets. Expanding the equity base dilutes state control, forcing these institutions to price retail working capital and commercial loans against sharper market-clearing rates rather than government balance sheets.

    Strategic Exit and Consolidation Blueprint

    Public sector divestment sits inside a broader policy adopted in 2021 to trim the overall number of sovereign-controlled lenders to three or four large institutions. Non-strategic assets face full disposals, while designated strategic financial pillars will retain only minimal state presence.

    NITI Aayog previously highlighted Central Bank of India and Indian Overseas Bank as prime candidates for strategic takeover by private operators. Completing an outright ownership transfer requires amendments to the Banking Companies Acquisition and Transfer of Undertakings Act, leaving legislative approval as the critical hurdle before private boards take control.

    Precedents and the Legislative Path

    The transaction model mirrors the recent clearance granted by the Cabinet Committee on Economic Affairs for Canadian firm Fairfax Financial Holdings to buy 60.72 per cent of IDBI Bank for 52,878 crore rupees. Union Budget 2022 formally established the mandate to privatise two state-owned lenders and one general insurer beyond the IDBI sale.

    Banking regulators and government managers now face the August 2026 expiration of the public float exemption. Progress hinges on whether parliamentary amendments to state banking statutes make it to the floor during upcoming legislative sessions.

  • Volkswagen Halts India EV Investments as It Seeks JSW Deal

    Volkswagen Halts India EV Investments as It Seeks JSW Deal

    Volkswagen AG has halted investments in an electric-vehicle program for India until it gains clarity on a potential partnership with billionaire Sajjan Jindal’s JSW Group. The pause follows an announcement last month by both companies that they are exploring a venture to develop, build and market passenger vehicles in India.

    Volkswagen has finished design work using a low-cost EV architecture originally developed for China, positioning it to scale quickly once talks conclude. However, the German group is withholding additional capital until the partners establish a firmer business plan.

    The investment hold comes amid a worldwide cost-cutting drive that aims to trim group investments by about 15% and cut tens of thousands of jobs. VW had already reduced the costs of developing EVs in India by a third last year as it searched for a partner, and it currently sells no battery-powered cars in the country under either its namesake or Skoda brands.

    Global Headwinds Squeeze Indian Budgets

    Spending cuts at headquarters are dictating the local timetable. Volkswagen is trimming its worldwide capital investments by roughly 15 per cent and eliminating tens of thousands of jobs as it grapples with weak deliveries across Europe and aggressive competition from Chinese producers.

    Those international pressures prompted management to slash its projected Indian EV development budget by a third last year while searching for a local equity partner. The spending freeze now leaves the automaker without an electric passenger vehicle on sale in India under either the Volkswagen badge or Skoda.

    Rivals Lock Down Showroom Space

    The delay hands an open field to domestic incumbents and new Asian competitors. Tata Motors Passenger Vehicles Ltd. And Mahindra & Mahindra Ltd. Dominate existing electric vehicle deliveries, while JSW’s other partner SAIC Motor Corp. Pushes its MG brand across Indian dealerships alongside entries from BYD Co., VinFast and Tesla Inc.

    Stepping back from direct capital spending shifts risk directly onto Volkswagen’s commercial footprint in South Asia. India registered more than 35,000 electric passenger cars in September, nearly doubling sales from the same month a year earlier, and stricter national fuel-efficiency standards make zero-emission models mandatory to protect traditional engine sales.

    Two Years of Search for a Local Ally

    Volkswagen and JSW disclosed last month that they are assessing an alliance to develop, manufacture and sell passenger vehicles in India as well as for export markets. The planned scope spans battery-electric vehicles, plug-in hybrids, traditional hybrids and internal-combustion engines.

    Finding a local partner has proved difficult for the German group. Management spent almost two years scouting an Indian manufacturer to split development costs after earlier partnership discussions with Mahindra broke down.

    Skoda Auto Volkswagen India Pvt. Currently generates only a marginal share of national car registrations. Resolving the partnership structure with JSW is the sole mechanism the German automaker has left to finance a competitive local electric platform before regulatory penalties tighten.

  • India Issues Notices to Nestle, Zydus and Abbott over Child Product Claims

    India Issues Notices to Nestle, Zydus and Abbott over Child Product Claims

    India’s food safety authority issued formal notices to Nestle India, Zydus Wellness and Abbott Healthcare this week over marketing claims on infant and children’s products that breached national rules.

    The enforcement actions rattle an Indian packaged food market valued at more than $100 billion as regulators intensify oversight of nutritional claims.

    The move comes shortly after officials proposed prohibiting added sucrose and fructose in foods intended for infants up to six months old.

    Evidence Demanded on Formula and Growth Drinks

    The Food Safety and Standards Authority of India ordered Nestle India to produce documented evidence supporting promotional assertions about digestive health and immune system benefits. Those claims appear on labels for Lactogen Pro 1 Powder and NAN Excella Pro Stage 1 infant formula.

    For Zydus Wellness, the regulator demanded scientific substantiation for marketing claims attached to its Complan children’s beverage brand. Regulators singled out promotional packaging using the slogan “grow taller, faster. Clinically proven 2X growth.”

    Enforcement also expanded into digital media distribution channels. The regulator issued separate notices to online influencer Ira Fathima alongside Abbott Healthcare and Nestle India concerning an Instagram reel promoting infant milk substitutes.

    Nestle India stated that the authority’s public notice repeated concerns initially raised on September 18 regarding product packaging labels, adding that it had already delivered an extensive formal response to the food regulator.

    Abbott took a different position, stating it played no role in the social video campaign. “Abbott does not endorse the claims or representations contained in the content,” a company spokesperson said, adding that the healthcare firm only learned of the material after receiving the authority’s notice and had forwarded that explanation to officials.

    Regulatory Pressure Mounts Across FMCG Portfolios

    The enforcement notices show Indian authorities closing off the latitude dairy and consumer health brands historically enjoyed when framing products as quasi-medicinal solutions. For multinational operators, children’s nutritional beverages and early stage formulas command premium shelf pricing in modern trade stores and pharmacy chains across tier-one Indian metros.

    Pivoting marketing messages from clinical outcomes to simple nutritional content carries commercial risk. When brands cannot claim tangible acceleration in height or immune protection, consumer willingness to pay substantial retail markups over standard milk powders drops quickly.

    Packaged goods manufacturers operating in India face a compounding compliance headache. Removing unverified health statements from shelf packaging requires inventory write-downs, packaging redesigns and altered point-of-sale displays across hundreds of thousands of general trade outlets.

    Digital influencer campaigns, long used by FMCG marketing teams as an indirect route around tight infant formula promotion laws, now sit squarely within the regulator’s direct enforcement perimeter. Brands can no longer isolate corporate marketing budgets from third-party social media creators promoting their product categories.

    Stricter Sugar Rules Set the Stage

    The crackdown follows earlier regulatory intervention by the food authority on October 17, when officials proposed an outright ban on adding sucrose and fructose to food products formulated for infants up to six months old.

    That regulatory draft landed as authorities stepped up scrutiny of basic formulation standards across processed food segments and advanced plans for mandatory front-of-pack nutritional warning labels.

    Regulators will decide whether to mandate product label revisions, levy statutory fines, or order affected product batches removed from retail distribution shelves across the country.

  • Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global food commodity prices climbed 5.8 per cent year-on-year in September 2026, driven higher by energy shocks, shipping bottlenecks and surging fertiliser expenses across major Asian trade routes.

    The Food and Agriculture Organization Food Price Index reached 136 points during the month, up 1.5 per cent from August, despite worldwide cereal output tracking toward 2.979 billion tonnes, the second-highest harvest recorded.

    Global cereal inventories remain stable at roughly 950 million tonnes for the 2026-27 season, yet distribution costs and input pricing have broken the link between grain abundance and retail shelf prices. The divergence exposes supermarket chains, food processors and institutional buyers to compounding margin pressure as wholesale commodity jumps filter directly into wholesale procurement.

    Input Shocks Ripple Through Maritime Corridors

    Maritime trade disruptions in the Middle East and the Black Sea have inflated transportation and processing overheads throughout the year. Tanker freight rates jumped more than 90 per cent following security conflicts around the Strait of Hormuz, a passage handling one-quarter of seaborne crude and one-third of seaborne fertiliser trade. Bunker fuel costs doubled over the same period, forcing commercial carriers to add war-risk surcharges to bulk grain and oilseed shipments.

    International urea prices climbed 80 per cent between February and April to surpass $850 a tonne, while diammonium phosphate gained over 10 per cent. Those input spikes hit crop economics across South and Southeast Asia just as planting cycles began. Logistical friction in the Black Sea and dry weather in North America lifted global wheat prices 6.3 per cent in September alone. International maize prices rose 5.6 per cent month-on-month, compounded by smaller Brazilian export volumes and lower yields in the United States.

    Vegetable oils and sugar followed a similar upward path. The FAO Vegetable Oil Price Index gained 0.9 per cent in September on firm palm oil buying and dry conditions in Southeast Asian growing basins, while sugar prices jumped 6.1 per cent.

    Indian Retail Shelves Absorb Upstream Inflation

    In New Delhi and across major Indian metropolitan centres, retail food inflation accelerated to 7.74 per cent in September from 5.97 per cent in August. While central grain warehouses held 87 million tonnes of wheat and rice on September 1, shielding staple cereal retail prices to a 3.94 per cent rise, perishable and imported categories recorded sharp increases.

    Edible oils and fats inflation reached 8.35 per cent in September. The combined category for vegetables, tubers and pulses rose 9.18 per cent, while fruits and nuts climbed 10.75 per cent. At the consumer level, Crisil Intelligence calculated that the cost of preparing a standard home-cooked vegetarian meal rose 10 per cent year-on-year to 30.8 rupees in September, driven by higher prices for cooking oil, onions and liquefied petroleum gas.

    India’s trade account shows the scale of the cost transfer. National crude oil imports totalled $74.8 billion between April and August, up 48.4 per cent in value despite import volumes slipping 0.4 per cent. Fertiliser import expenditure jumped 53.25 per cent to $8.21 billion during the five-month span, while vegetable oil purchases grew 11.28 per cent to $9.18 billion. Domestic urea output fell 27 per cent in March to 1.8 million tonnes when feedstock natural gas deliveries dropped to 60 per cent of normal capacity before stabilizing.

    Weather Risks Threaten Export Allocations

    Climate factors are tightening the outlook for the next crop cycle. The National Oceanic and Atmospheric Administration projects an 83 per cent probability that a strong El Nino pattern will persist through the first quarter of 2027. In India, the 2026 southwest monsoon concluded with rainfall 13 per cent below historical averages, marking the driest seasonal performance since 2015. Southern states faced a 24 per cent deficit, while eastern and northeastern territories recorded a 26 per cent shortfall.

    Reduced reservoir levels pose direct operational hurdles for winter sowing. Crisil forecasts a 5 to 6 per cent decline in domestic paddy production due to lower planted area and thinner yields. Because India supplies roughly 40 per cent of the cross-border rice trade, production shortfalls in the domestic basin carry immediate pricing consequences for food distributors across the Middle East, Africa and Southeast Asia.

    Government subsidies have so far absorbed a portion of the shock, with central budget spending on fertiliser support rising 20.7 per cent to 1.03 trillion rupees between April and August. Food manufacturers and commercial retailers nonetheless face higher cold-chain logistics costs, packaging inflation and inventory holding expenses as raw materials turn costlier.

    Trade Metrics to Track Through 2027

    Retail grocers and packaged food companies across the region enter the final quarter of 2026 with little room to absorb further wholesale increases without adjusting shelf prices. Operating margins will depend heavily on whether winter rainfall restores reservoir capacity across key agricultural belts.

    Over the next 6-12 months, I would watch pulses, edible oils and vegetable prices; rabi sowing and soil moisture; reservoir levels; crude oil and fertiliser prices; the rupee; freight costs; and government decisions on food imports, exports and stocks. The key signal will be whether inflation remains concentrated in a few commodities or starts spreading across the wider food basket.

    Market participants are now tracking weekly acreage numbers for India’s rabi crop, alongside monthly palm oil stock levels in Malaysia and Indonesia, to gauge whether retail food inflation stabilizes before the 2027 harvest cycle opens.

  • Ericsson Bets on AI Traffic and 550 Million 5G Users to Drive India Growth

    Ericsson Bets on AI Traffic and 550 Million 5G Users to Drive India Growth

    Ericsson expects artificial intelligence applications and rising monthly data traffic to fuel a second wave of network investment in India, where 5G subscribers reached 550 million by September 2026.

    Monthly data consumption across Indian networks has climbed to between 36 and 37 gigabytes per user, according to company figures presented at the India Mobile Congress in New Delhi.

    The Swedish telecom equipment vendor is seeking fresh revenue after the rapid initial rollout of fifth-generation mobile infrastructure cooled. India accounted for 12 percent of Ericsson’s regional business covering South East Asia, Oceania, and India in 2025, down from 20 percent in 2023 during the peak of initial carrier deployments.

    Network Capacity Over Pure Consumer Use Cases

    Indian operators deployed 5G across 99.9 percent of the country’s districts in less than four years, making it one of the fastest national buildouts globally. The buildout occurred primarily because carriers needed immediate spectrum efficiency and radio capacity rather than waiting for specialized consumer applications.

    Nitin Bansal, managing director for India and head of networks for South East Asia, Oceania, and India at Ericsson, noted that 5G currently reaches roughly one-third of the country’s population. He argued that shifting directly to 5G rather than expanding older 4G infrastructure provided the necessary capacity to handle escalating consumer usage.

    Direct monetization remains the chief challenge for telecom operators Bharti Airtel and Reliance Jio. Both carriers spent heavily on spectrum auctions and radio deployments starting in late 2022 and are now pushing higher-margin services to improve average revenue per user.

    Fixed Wireless and Enterprise Slicing

    Fixed Wireless Access has become the fastest monetization channel for Indian network operators looking to bypass fixed-line broadband delays. Data from the Telecom Regulatory Authority of India showed 13.45 million 5G FWA subscribers active at the end of August 2026.

    Service differentiation is shifting toward premium enterprise and high-tier retail customers. Bharti Airtel introduced commercial 5G network slicing, carving out dedicated network resources to provide guaranteed speeds and lower latency to postpaid retail subscribers.

    For equipment vendors including Ericsson, Nokia, and Samsung, these software-defined features generate recurring software licensing fees rather than purely hardware-driven revenue.

    Artificial Intelligence Shifts Network Requirements

    Emerging artificial intelligence workloads on mobile devices are changing baseline infrastructure demands across Asian markets. Generative AI tools and spatial computing applications require heavy uplink capacity and reduced latency, forcing operators to tune cell sites that were originally configured primarily for downlink video streaming.

    Ericsson expects carriers to reconfigure their 5G standalone cores to handle automated traffic management and machine-learning compute loads. Critical infrastructure monitoring and industrial automation in manufacturing hubs around Pune, Chennai, and Gujarat are also pulling private 5G deployments into commercial operation.

    Vendors face pressure to prove these upgrades deliver real cost savings. Indian telecom operators operate with some of the lowest tariffs in the world, leaving slim margins for speculative infrastructure spending without clear returns.

    Targeting One Billion Subscribers by 2030

    India launched commercial 5G services in October 2022 and has since become one of the two largest mobile data markets alongside China. The central government has set an official target of one billion 5G subscribers by 2030.

    Meeting that target requires converting roughly 450 million additional mobile users from legacy 4G and 2G connections over the next four years. That conversion will hinge on the availability of entry-level 5G smartphones priced below 8,000 rupees, alongside wider rural cell coverage where standalone economics remain tight.

  • GE Aerospace to Double India Supply Chain Spending to $400 Million by 2030

    GE Aerospace to Double India Supply Chain Spending to $400 Million by 2030

    GE Aerospace will increase annual supply chain spending in India to $400 million by 2030. The target doubles its current procurement footprint in the country.

    Annual spending across Indian suppliers reached $200 million in 2025. Surging fleet orders from domestic airlines drove that total.

    Procurement will cover new engine components alongside higher volumes for existing parts. Sourcing runs through 17 global tier-one suppliers in India, including Tata Group, Mahindra, Hindustan Aeronautics Limited, and Godrej. More than 2,000 domestic tier suppliers support the network.

    Expanding Component Manufacturing in Pune

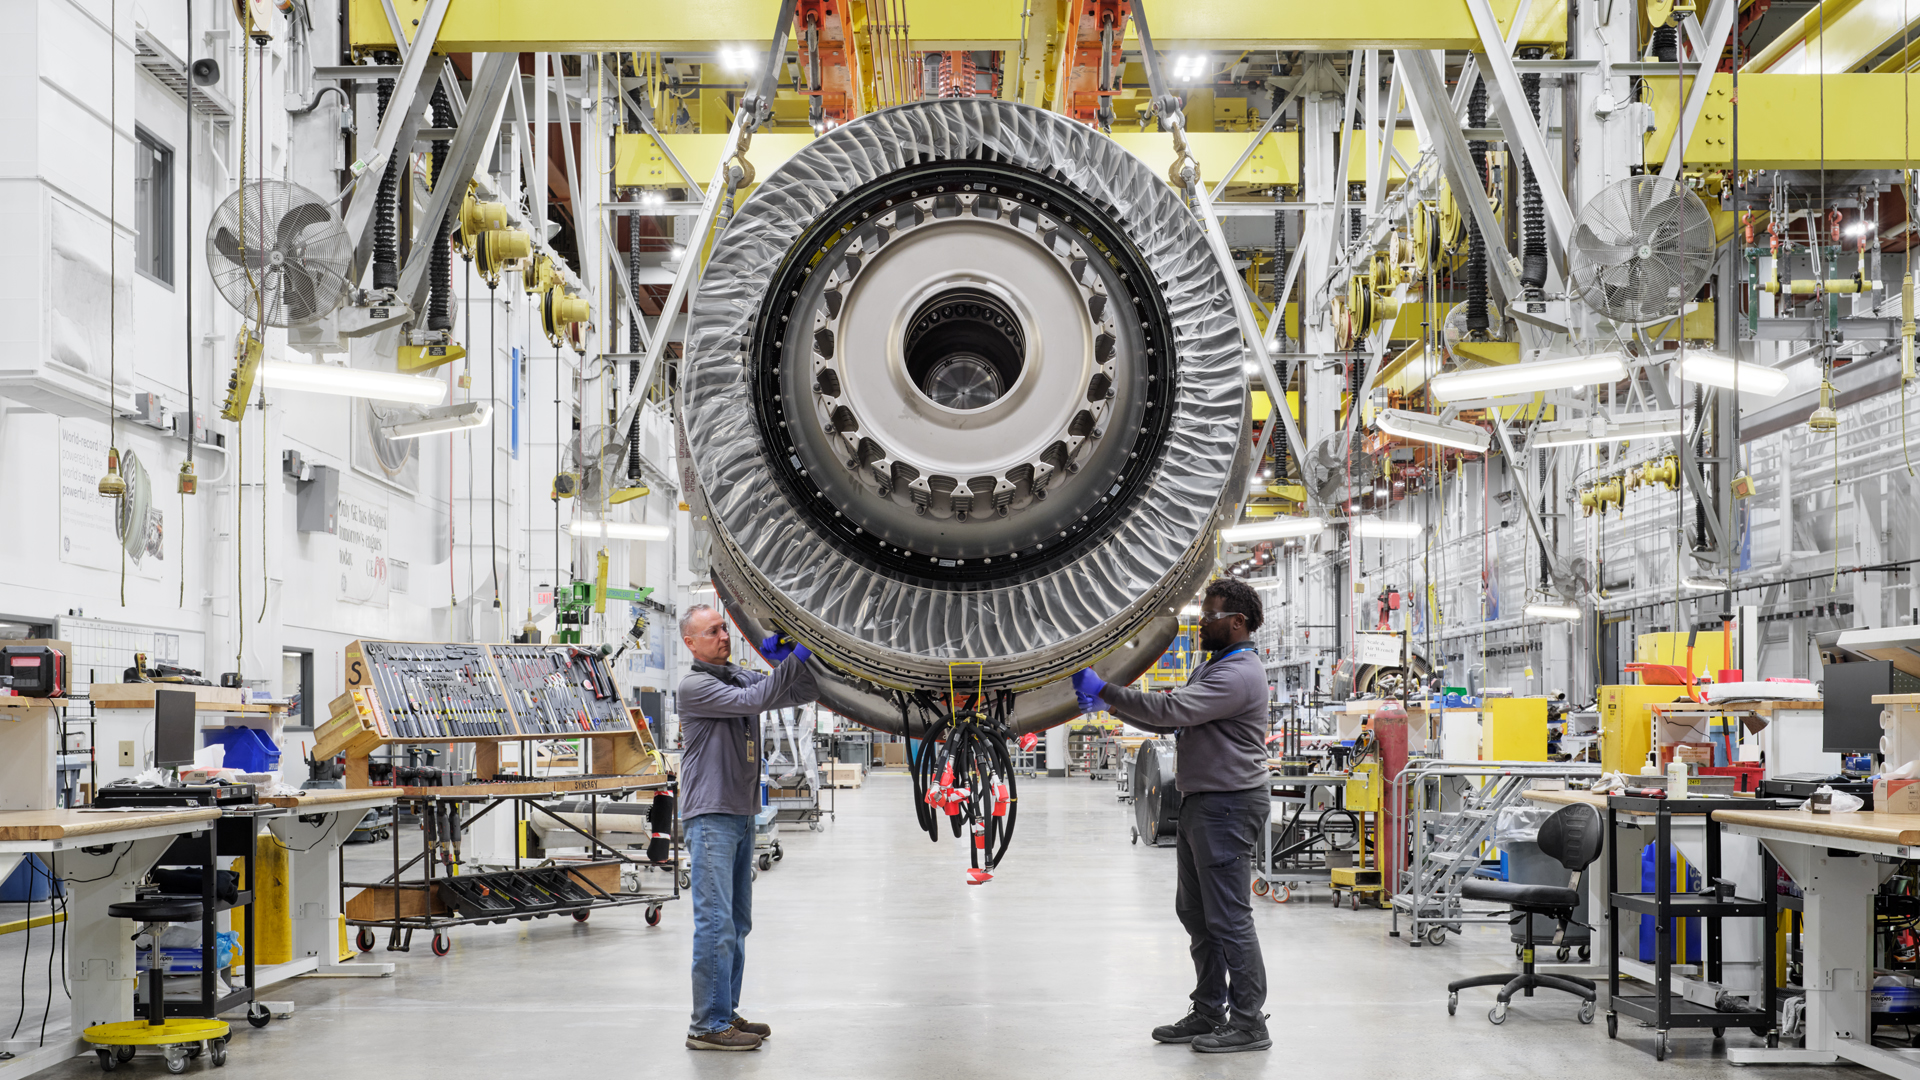
    Manufacturing centers on the multi-modal plant in Pune. It produces engine components for export and domestic integration. Cumulative capital spending at the site stands at $255 million, feeding global assembly lines for commercial platforms.

    Engineering and software teams operate out of the Bengaluru Technology Centre, established in 2000. The site holds over 1,000 patents. It developed the ABM.ai predictive maintenance platform and the Blade Inspection Tool used across GEnx, CFM LEAP, and GE9X programs. The digital unit also serves as a global capability centre for worldwide engine maintenance, sales, and supply chain tracking.

    Backing Aircraft Fleet Expansion

    Domestic passenger journeys reached 340 million in fiscal year 2026 and are projected to reach 1.1 billion by 2040. Indian carriers and armed services currently operate more than 1,400 commercial engines from GE and its partners, alongside over 200 defence engines.

    Local airlines hold firm orders for over 1,700 aircraft scheduled for delivery over the next decade. More than 3,200 engines from GE Aerospace and its joint ventures will power those fleets. Local component production helps the manufacturer maintain delivery schedules against global supply chain bottlenecks.

    Joint Ventures and Maintenance Capacity

    Regional carriers need local maintenance facilities to avoid turnaround delays abroad. Sourcing parts closer to flight hubs cuts transit time for heavy engine overhauls.

    IndiGo signed a memorandum of understanding in July 2026 with CFM International, GE’s 50-50 joint venture with Safran Aircraft Engines. The deal covers more than 1,000 LEAP-1A engines for 510 Airbus A320neo family jets. It also provides technical support to build IndiGo’s dedicated engine maintenance, repair, and overhaul facility.

    Scaling Local Supplier Integration

    Precision manufacturing in India has moved beyond basic aerostructures into complex rotating parts and turbine components over the past decade. Raising procurement from $200 million to $400 million tests whether local suppliers can maintain aerospace quality standards at higher output rates.

    Next, the supplier development program will qualify new part numbers at Pune and integrate higher production runs across the 17 global Indian supplier partners as deliveries ramp up toward 2030.

  • BuyBuyCart Launches BuyBuyWholesale to Digitise Franchise Ordering

    BuyBuyCart Launches BuyBuyWholesale to Digitise Franchise Ordering

    New Delhi supermarket chain BuyBuyCart launched BuyBuyWholesale.com this week to streamline wholesale distribution and franchise operations across its retail network.

    The dedicated B2B portal operates as 1 centralised system for franchise partners to place regular and replenishment orders directly, while tracking SKU-level sales data.

    Centralising store inventory orders

    Led by Director and Co-founder Ashish Pandey, BuyBuyCart uses the platform to monitor wholesale demand, value- and quantity-based analysis, and ground sales performance alongside its physical store and Amazon channels.

    Analytical tracking built into the software breaks down orders by quantity, total transaction value, and specific franchise location. Sales teams continue to handle account support in local territories. Meanwhile, the backend system logs transactional flow.

    Tracking field sales and store demand

    Digital franchise procurement allows supermarket networks in India to cut order turnaround times and reduce inventory stockouts across regional clusters. Centralised visibility on SKU movement helps retail operators identify fast-moving daily essentials early. Teams then route stock to franchise shelves before local inventory runs dry.

    “The launch of BuyBuyWholesale.com is an important step in building a more connected and data-driven B2B ecosystem for BuyBuyCart. We are already seeing orders come through the platform, while our sales team continues to support partners on the ground. Our next focus is to make the platform increasingly useful for our franchise partners by enabling them to manage their regular and refill orders directly. Over time, we see BuyBuyWholesale.com becoming a central platform connecting our wholesale, sales, and franchise operations.”

    Shifting franchise logistics online

    For independent franchise owners, automated replenishment removes friction from weekly distributor negotiations and standardises pricing across territories. Field adoption presents the main operational risk. Regional store managers accustomed to manual phone orders and informal credit terms must adapt to disciplined digital checkout cycles.

    Rival supermarket chains across South Asia increasingly deploy proprietary wholesale portals to bind franchise partners to exclusive supply chains. Locking store procurement into an in-house platform protects private-label volume from third-party wholesale cash-and-carry distributors.

    Expanding private-label distribution

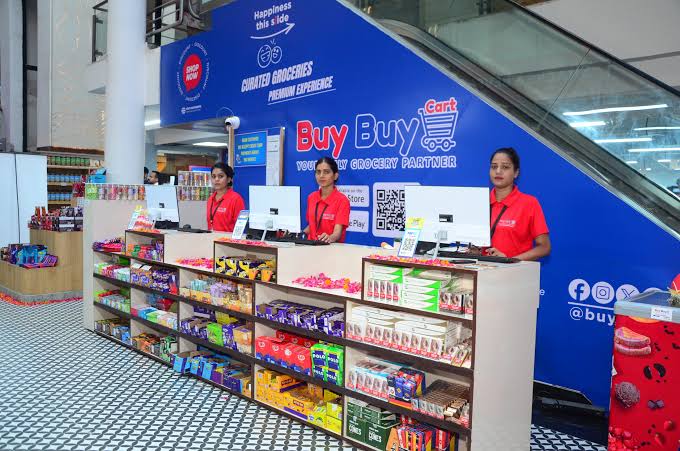
    BuyBuyCart built its core retail operation around a multi-region franchise supermarket footprint, selling packaged groceries, household essentials, and proprietary private-label lines. Alongside physical brick-and-mortar stores, the company distributes goods directly to consumers through its official website and third-party marketplaces including Amazon.

    Next, the rollout will focus on opening direct recurring refill features for all active franchise stores and integrating additional wholesale tracking tools into the live portal.