Tag: real estate

  • Indian Parents Can Tap USD 500,000 Annual LRS Quota for Overseas Property

    Indian Parents Can Tap USD 500,000 Annual LRS Quota for Overseas Property

    Indian parents can remit up to $500,000 jointly per financial year under central bank rules. The funds can cover overseas residential property acquisitions for non-resident children.

    The Reserve Bank of India caps individual transfers under the Liberalised Remittance Scheme at $250,000 across each twelve-month period running from 1 April to 31 March.

    Under the Foreign Exchange Management Act, eligible resident parents can pool quotas to finance offshore real estate alongside their Non-Resident Indian or Overseas Citizen of India children. The scheme applies strictly to individuals. Companies, partnership firms, Hindu Undivided Families and private trusts cannot access the facility. Family offices and high-net-worth buyers must structure offshore capital deployments directly through individual banking channels.

    Structuring Remittances as Gifts or Loans

    Capital sent abroad must be classified either as an outright gift or an interest-bearing debt instrument. Gifts received by non-resident children from resident parents carry an exemption from Indian income tax, regardless of transaction value. Remitters must complete Form A2 at an Authorised Dealer bank branch. They must also verify permanent account number records and maintain documentation including gift deeds and proof of familial relationship.

    Loan structures require formal loan agreements detailing repayment schedules, governing law and applicable interest rates. Sudhakar Sethuraman, Partner at Deloitte India, said that a comprehensive agreement should specify the “tenure, interest, repayment schedule, governing law, etc.” Capital transfers routed as rupee gifts into Non-Resident Ordinary accounts remain legally permissible under the annual quota. However, repatriation hurdles make direct foreign currency wire transfers the preferred conduit for property buyers.

    Tax at Source and Banking Friction

    Outbound capital transfers trigger Tax Collected at Source once remittances cross the threshold of Rs 10 lakh in a single financial year. Authorized dealer banks levy source taxes at 5 percent or 20 percent depending on transaction codes. Buyers can adjust the deduction against total domestic tax liabilities when filing annual returns.

    Cross-border buyers also absorb banking fees, currency conversion margins and foreign exchange spreads that trim net transaction proceeds. Unused annual quotas expire each year on 31 March and do not roll over. Buyers pursuing multi-year overseas asset acquisitions must stage payments across financial calendars.

    Regulatory Compliance for Offshore Buyers

    Indian buyers entering overseas housing markets face dual-jurisdiction compliance checks before closing property purchases. Authorized dealer banks conduct know-your-customer assessments. They scrutinize tax records to confirm the domestic source of funds before approving Form A2 foreign exchange releases.

    Non-resident children receiving the capital must concurrently comply with local asset disclosures and foreign investment filings in the jurisdiction where the real estate asset sits. Cross-border banking compliance teams routinely review source-of-wealth documentation. They verify that offshore transfers match domestic regulatory filings.

    Cross-Border Wealth Flow Dynamics

    The framework mirrors capital controls across emerging Asian markets, where regulators balance private wealth mobility against domestic currency stability. Restricting offshore real estate funding to resident individuals rather than corporate vehicles preserves direct visibility over private wealth outflows.

    Families financing high-value residential assets in gateway cities like London, Dubai and Singapore remain reliant on strict annual remittance windows. With individual caps fixed at $250,000, multi-million-dollar property purchases require combining offshore earnings with multi-year domestic transfers while absorbing upfront source taxes.
  • China Luxury Malls Expand Footprint Despite Retail Gloom

    China Luxury Malls Expand Footprint Despite Retail Gloom

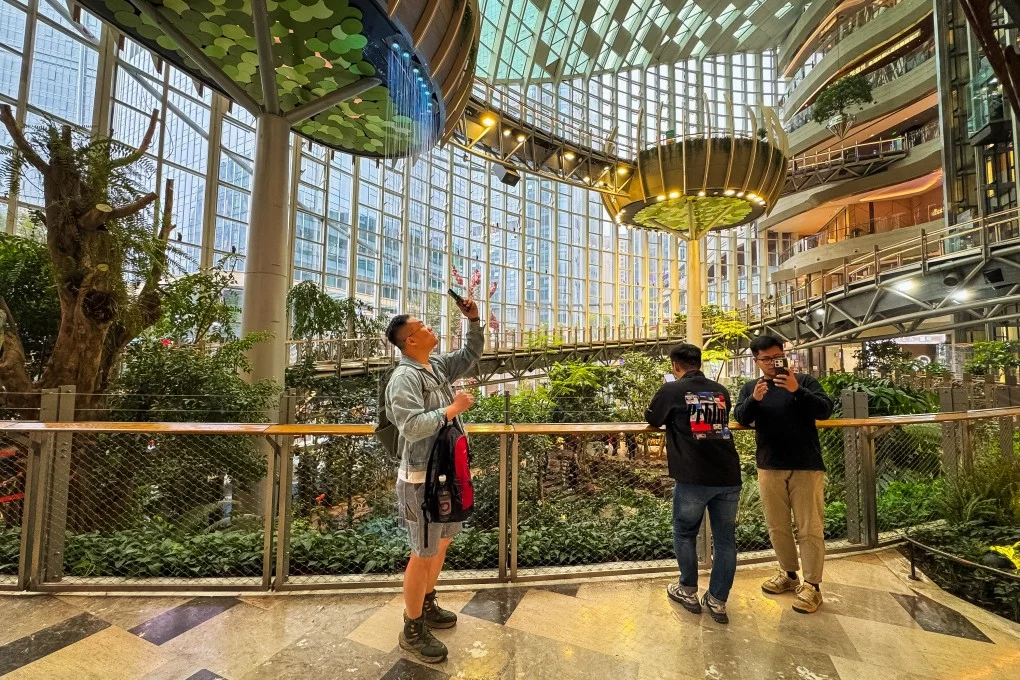
    Luxury mall operators across China are pressing ahead with major retail expansion projects this week despite persistent weakness across the broader consumer economy, Nikkei Asia reported. High-end property developers are securing footprint commitments from top global fashion and jewelry houses across primary commercial centers.

    The physical expansion push comes as top-tier landlords separate their performance from standard mass-market department stores. Premium commercial destinations continue to attract long-term brand commitments because affluent shoppers maintain higher discretionary budgets than middle-market consumers.

    Bifurcation across commercial real estate

    Commercial leasing data across mainland tier-one and tier-two cities shows a sharp split between mass retail centers and destination luxury complexes. While mid-market shopping centers struggle with tenant turnover and rent concessions, prime luxury properties maintain tight occupancy rates and multi-year waiting lists for prime ground-floor frontages.

    Global luxury houses require expansive multi-level flagships with dedicated VIP lounges, private salons, and custom architectural facades to serve high-net-worth clients. Operators of luxury centers are reconfiguring existing floor plans and building new wings to meet these spatial specifications.

    Brand strategy shifts in mainland centers

    International fashion groups are consolidating their retail networks rather than retreating from mainland China. Brands are closing underperforming satellite boutiques in secondary malls to concentrate capital and inventory into larger experiential flagships inside leading luxury complexes.

    For mall landlords, securing anchor flagships from premier European luxury houses guarantees footfall from top-tier spenders. It also allows developers to command premium rental yields on adjacent specialty dining, lifestyle, and beauty spaces.

    Landlord competition and regional exposure

    Competition among high-end landlords is intensifying across regional hubs beyond Shanghai and Beijing. Commercial developers are competing aggressively to bring exclusive boutique concepts and direct-operated flagships to regional centers such as Chengdu, Shenzhen, and Hangzhou.

    The execution risk rests on whether local high-end consumption can absorb the expanded commercial floor space without diluting sales density per square meter. Landlords that overcommit capital to new luxury builds in saturated micro-districts face longer lease-up schedules if brand partners limit their capital expenditure.

    Pipeline targets across major markets

    Earlier retail cycles established luxury retail hubs around historical downtown commercial districts. The current construction cycle focuses on mixed-use commercial developments that combine luxury retail with prime office towers, cultural spaces, and five-star hospitality.

    Commercial developers have scheduled their new luxury mall openings and phased retail extensions through the next several operating quarters. Occupancy rates, flagship delivery schedules, and initial tenant sales productivity across these new developments will determine whether landlords maintain their current expansion pace.

  • Weave Living Acquires 108 Tokyo Apartment Units with Japanese Investors

    Weave Living Acquires 108 Tokyo Apartment Units with Japanese Investors

    Weave Living has acquired three Tokyo apartment buildings comprising 108 units backed by a consortium of Japanese investors to expand its domestic capital partnerships.

    The off-market purchase, announced Wednesday, lifts the Hong Kong-based rental operator’s assets under management in Japan to JPY 120 billion ($764 million) across nearly 50 properties. Weave did not disclose the purchase price or the seller’s identity, but confirmed the investor group includes one of the world’s largest financial services institutions.

    Refurbishment and Digital Leasing Plan

    Two of the assets, Ginza Hatchobori and Yoyogi Uehara, sit in Chuo and Shibuya wards inside Tokyo’s central five districts. The third building is in Taito ward’s Asakusabashi district.

    Plans call for converting the three properties into the Weave Place long-stay furnished accommodation brand. Upgrades will cover common areas and full apartment interiors. Leasing operations will shift to the company’s proprietary mobile app, which bundles utility bills and Wi-Fi into single monthly contracts with minimal upfront costs.

    Furnished units target professional tenants relocating to the Japanese capital. The model bypasses traditional multi-year leasing structures that require heavy initial deposits.

    Institutional Capital in Tokyo Living Sector

    Institutional capital into Japanese residential assets has accelerated as operators look for steady yields backed by urban migration. Furnished formats generate higher revenue per square metre than conventional long-term leases. However, they demand higher operational oversight and carry shorter lease profiles.

    Across the 23 wards, Tokyo residential rents rose 2.8 percent in the second quarter and 5.3 percent year on year to JPY 4,829 per square metre per month. In the central five wards, rents climbed 5.2 percent from a year earlier. Occupancy there edged down 0.8 percentage points to 95.6 percent.

    Weave founder and chief executive Sachin Doshi said the transaction reflects “the continued interest of offshore and domestic capital in seeking a differentiated exposure to the living sector in Japan”.

    Expansion Following KKR Venture Exit

    Recent activity follows a series of programmatic joint ventures across Tokyo. Weave closed its first domestic partnership last November with Mitsubishi UFJ Financial Group anchoring an 11-property, JPY 20 billion portfolio. In January, it added a JPY 22 billion venture with BGO Strategic Capital Partners for 10 buildings.

    In August, Weave partnered with Aberdeen Investments on a JPY 15 billion acquisition of six apartment blocks backed by Dutch pension manager PGGM. On September 7, Weave and private equity firm KKR completed a JPY 55 billion recapitalisation of a 14-property Tokyo portfolio with a Southeast Asian institutional investor. That deal allowed Weave to exit its equity position while keeping long-term management rights.

    Phased unit refurbishments are now underway across the newly acquired buildings. Renovated units are scheduled to roll out onto the company’s digital leasing platform over the coming quarters.

  • Casino Tycoon Angela Leong Sells Sai Kung House for $8.9M

    Casino Tycoon Angela Leong Sells Sai Kung House for $8.9M

    Macau casino billionaire Angela Leong On-kei has sold her detached house in Hong Kong’s Sai Kung district for HKD70 million ($8.9 million).

    The sale closes a 14-year holding period with a nominal capital gain of HKD1.2 million. It follows years of asking-price cuts.

    Fourteen Years for a Marginal Gain

    Located within the Royal Castle development on Pik Sha Road, the detached home covers 210 square metres. The layout includes four bedrooms, a private garden, a swimming pool, and a rooftop terrace. Leong originally bought the property through a corporate vehicle in early 2012 for HKD68.8 million. She is co-chairwoman and the largest individual shareholder of Macau casino operator SJM Holdings.

    Initial listings put the property on the market several years ago at HKD168 million. Securing HKD70 million represents a steep cut from that target. It reflects the concessions wealthy vendors now accept to exit non-core residential holdings in secondary luxury enclaves.

    Discounting Drives Volume in Sai Kung

    Sellers across Sai Kung have adjusted expectations downward to clear stock. Price cuts of up to 10 per cent helped lift deal numbers across high-value residential brackets in recent months as opportunistic buyers moved in.

    Frankie Liu, sales director at Century 21 Goodwin Property, said: “With the batch of discounted luxury homes now cleared, I expect luxury residential transaction activity in the area to slow down in the fourth quarter.”

    Super-Prime Demand Splits Across Districts

    Pricing trends in Sai Kung contrast with demand patterns in traditional top-tier neighbourhoods. Buyers in The Peak and Southern districts continue to focus on established luxury estates. Local business owners there are trading up to consolidate family holdings, according to Centaline Property district sales director Joseph Yan.

    Deutsche Bank ranked Hong Kong as the world’s most expensive residential property market this year, trailing only Dubai in overall super-prime transaction volume. Knight Frank data shows that sales of homes priced at $10 million or higher surged 75 per cent quarter on quarter to $1.67 billion in the second quarter. Purchases in core prime postcodes drove those gains rather than deals in outlying districts.

    Borrowing Costs Loom Over Next Quarter

    Financing conditions remain a headwind for broader turnover. On September 17, the Hong Kong Monetary Authority lifted its base rate to 4.25 per cent in lockstep with the US Federal Reserve. Hong Kong’s three note-issuing lenders held their prime lending rates steady after that adjustment. Another Federal Reserve rate decision in late October could force local commercial banks to increase mortgage borrowing costs before year-end.

  • Japan Benchmark Yield Tops 3.1% as Tokyo Property Prices Drop

    Japan Benchmark Yield Tops 3.1% as Tokyo Property Prices Drop

    Japan’s benchmark government bond yield topped 3.1 percent on Friday morning. The rise accelerated a regional debt sell-off and pushed Tokyo residential property prices lower.

    Average asking prices for existing condominiums in central Tokyo dropped for four straight months through August. Higher borrowing costs chilled buyer demand.

    Sovereign debt selling spread across Asian trading desks as investors factored in prolonged monetary tightening. Energy markets added pressure. Elevated crude oil prices reinforced inflation expectations across importing economies.

    Central Tokyo Condo Market Cools

    Central Tokyo apartment valuations have dropped for four straight months, reversing years of steady price growth. Domestic buyers face higher monthly mortgage payments. Long-term lending rates continue to track government bond yields higher.

    Commercial landlords and retail operators face a similar squeeze on debt refinancing. Property developers that relied on ultra-cheap bank credit are lowering sales targets. Both institutional and retail purchasers are reassessing yield spreads.

    Central Bank Rate Tightening

    Yields surged after the Bank of Japan lifted its policy rate to 1.25 percent. Governor Kazuo Ueda pointed to a formal shift in monetary policy. Currency authorities also conducted foreign exchange rate checks, steadying the yen in the upper-156 range against the US dollar.

    US policy expectations amplified the pressure on Asian debt. Under Chair Kevin Warsh, the Federal Reserve raised interest rates and signaled further tightening. The moves pushed the greenback toward a two-month peak.

    Funding Pressures Mount for Corporates

    Higher sovereign yields are driving up corporate borrowing costs across Tokyo. Prime Minister Sanae Takaichi’s administration faces rising debt-servicing costs. The government is trying to fund fiscal initiatives without issuing fresh deficit-financing bonds.

    Corporate issuers are testing market appetite with higher coupons. SoftBank Group prepared an $11 billion bond offering to fund its investment commitments in artificial intelligence firm OpenAI.

    Asian Real Estate Outlook

    Japanese developers can no longer depend on zero rates to support capital values. Institutional asset managers are demanding wider capitalization rates on central Tokyo assets. That push is forcing a price discovery phase across residential and retail properties.

    Traders are watching upcoming economic data and Tokyo condominium sales figures for September. The numbers will show whether secondary housing prices stabilize or slide further into the fourth quarter.

  • Thailand Resale Condo Transfers Surge 39 Percent in Second Quarter

    Thailand Resale Condo Transfers Surge 39 Percent in Second Quarter

    Thailand recorded a 39.4 percent year-on-year surge in second-hand condominium transfers in the second quarter of 2026, driven by buyers seeking affordable alternatives to costly new builds.

    Total transfer value for resale condos climbed 41 percent over the same period, making apartments the fastest-expanding segment in the country’s housing market, according to the Real Estate Information Center.

    Supply expanded in tandem with buyer activity. Listed resale condo inventory rose 25.2 percent year-on-year to 49,199 units during the quarter, while total listed value climbed 67.8 percent to 285 billion baht.

    Bangkok Captures Bulk of Secondary Trading

    Activity remained heavily concentrated in Greater Bangkok, which accounted for 42.3 percent of all secondary housing transfers and 47.4 percent of transaction value nationwide. Greater Bangkok saw 26,388 second-hand residential transfers, a 35 percent increase from a year earlier, with total value rising 29.4 percent to 59 billion baht. Bangkok proper alone recorded 13,910 transfers, up 38.7 percent, generating 38.3 billion baht in value.

    Condos outpaced all landed residential formats. Single detached house transfers rose 16.8 percent across the country, townhouses gained 24 percent, and semi-detached homes grew 22 percent. Resale condo volume expanded at more than double the pace of detached houses.

    Wage Lag Diverts Demand from Primary Projects

    The pivot to secondary properties reflects structural household constraints rather than a deficit of new construction. New home prices in Bangkok rose at a compound annual rate of 4.3 percent between 2012 and 2025, while labour wages grew just 2.8 percent over the same span, according to research by Krungthai Compass.

    That divergence is pricing first-time buyers out of newly launched developments in central locations. Resale properties offer established transit links and larger floor plans at discounts to primary launches, drawing cost-conscious buyers into older buildings.

    Mid-Priced Units Dominate Buyer Takeup

    Transaction growth clustered tightly around middle-tier price brackets. Units selling between 1.51 million baht and 5 million baht saw transfer volumes jump between 25 percent and 30 percent during the quarter. Condos priced between 2.01 million baht and 3 million baht captured 24 percent of total second-hand transaction value, the largest single share.

    Sub-1-million-baht properties generated 34.8 percent of all secondary unit transfers but represented only 10.2 percent of total market value. While entry-level transactions remain numerous, available stock in that bottom tier is shrinking. Secondary listings priced below 1 million baht fell 9.9 percent in unit count and 7 percent in total value during the period.

    Luxury Listings Expand as Primary Developers Pivot

    Upper-tier supply moved in the opposite direction. Secondary listings priced above 10 million baht jumped 32.4 percent by unit count and 39.6 percent in value, pushing total nationwide resale listing value up 24.9 percent despite a modest 6.1 percent gain in overall listed unit volume. Actual buyers, however, stayed concentrated in the affordable mid-market.

    Primary developers now face direct competition from older inventory in established corridors. With household debt high and borrowing capacity squeezed, builders can no longer rely on broad market expansion to absorb newly launched supply. They face sharper pressure to discount inventory and redesign upcoming pipelines around entry-level price thresholds.

    Krungthai Compass projects total secondary residential transfers in Bangkok will hit 195 billion baht by the end of 2026, accounting for roughly 40 percent of all residential property transfers in the capital.

  • New Home Sales Rise in Shanghai and Shenzhen After Beijing Policy Shift

    New Home Sales Rise in Shanghai and Shenzhen After Beijing Policy Shift

    Sales of new homes in cities like Shanghai and Shenzhen rose in September 2026 after central government moves were introduced to revive buyer confidence in the real estate market.

    Property brokers across China’s major cities, including agents at Lianjia in Shanghai, reported being swamped by inquiries as they try to seal as many deals as possible amid a recovery in sentiment.

    Demand returns to top-tier cities

    Real estate agencies in China’s wealthiest metropolitan markets are managing heavier foot traffic, though brokers like Yang Keju warn that the current high transaction volume could become short-lived.

    The current upturn concentrates heavily in primary tier-one hubs where household wealth remains highest and inventory absorption happens fastest. Developers with projects ready for handover in these locations are taking advantage of the window to offload existing inventory.

    Agency networks push for rapid closures

    Front-line brokerages have redirected agents toward immediate deal execution rather than long-term pipeline building. Agencies want contracts signed before buyer sentiment cools.

    “Government support always holds the key to the performance of the home market,” said Yang Keju, a broker at a Lianjia property agency branch in Pudong, Shanghai. “We are worried that the current high transaction volume could become short-lived.”

    Brokers eye duration of policy effect

    Earlier support packages produced short bursts of buying that dissipated within weeks. For developers and commercial landlords, the critical test is whether this volume spreads beyond premier districts into lower-tier cities where developer cash flow remains constrained.

    Brokers in suburban districts continue to face high unsold supply and cautious households. Without continuous credit expansion or deeper municipal rate reductions, transactions outside core metropolitan zones risk stalling.

    Market watch on upcoming clearance rates

    September transaction registries will provide the first concrete measure of total cleared contracts across Shanghai and Shenzhen following the policy shift. The full impact on developer balance sheets depends on whether transaction numbers carry through the fourth quarter.

  • Nearly 20% of Asia-Pacific Firms Expect AI to Cut Office Space, CBRE Finds

    Nearly 20% of Asia-Pacific Firms Expect AI to Cut Office Space, CBRE Finds

    Nearly one-fifth of surveyed companies in the Asia-Pacific region believe wider adoption of artificial intelligence will reduce their real estate needs, a study by property consultancy CBRE has found.

    More than half, 56 per cent, held a neutral view, believing either that AI had no impact on office space demand or that it was too early to determine its effect, while 25 per cent said AI adoption would require them to expand their office footprint.

    The survey of 651 corporate real estate executives, conducted between May 26 and July 10 across nine regional markets, showed that AI currently has a more significant impact on office operations than on physical space requirements, according to Ada Choi, head of research for Asia-Pacific at CBRE.

    Operational Shift Outpaces Desk Reductions

    Corporate deployment of machine learning in property management expanded sharply over the past two years. The survey, conducted between May 26 and July 10 across nine markets including Hong Kong, mainland China, Singapore, Japan, Australia and India, found that 46 percent of occupiers now classify themselves as active AI adopters in corporate real estate functions. That represents a steep increase from 9 percent recorded in 2024.

    Automation currently assists facility monitoring, leasing analytics, space planning and workplace energy management rather than eliminating core real estate demand. Property teams use algorithmic tools to streamline building maintenance schedules and track daily badge swipes, turning automation into an administrative efficiency tool rather than a headcount guillotine.

    Regional leasing patterns show that companies rebalance rather than abandon their commercial leases. Fifty percent of surveyed occupiers project portfolio expansions through 2029, with 60 percent citing organic corporate growth as the primary catalyst.

    The Flight to Prime CBD Assets

    Commercial tenants are executing a deliberate flight to quality across major Asian financial centres. Eighty-five percent of surveyed occupiers specify Grade A buildings or higher for future commitments, and 48 percent demand space inside central business districts.

    This consolidation into top-tier commercial towers squeezes secondary and decentralised office parks. Landlords holding modern assets with green credentials and flexible floorplates capture leasing activity, while older secondary stock faces structural vacancy as corporate tenants offload low-grade square footage to fund premium addresses.

    The bifurcation penalises owners of dated suburban business parks who banked on decentralisation during earlier cost-cutting cycles. Institutional capital in Asia is now forced to either invest heavily in asset enhancement programmes or accept prolonged rent discounts to retain secondary tenants.

    Stabilised Attendance Anchors Space Requirements

    Physical workplace presence has normalised across the region at levels far higher than in North America or Western Europe. Eighty-eight percent of respondents confirmed their employees work in the office at least three days per week, marking the highest rate recorded since the start of the pandemic. An additional 85 percent stated that desk attendance has reached a permanent equilibrium.

    “With attendance and utilisation largely stabilised at higher levels, companies are no longer focused only on bringing employees back to the office,” said Tom Gaffney, head of leasing for Asia-Pacific at CBRE.

    Space shortages are most acute in Tokyo and major Indian tech hubs, where tight supply limits available Grade A options. In mainland China, corporate expansion continues at a measured pace, led by domestic technology, software development and clean energy enterprises taking advantage of softened prime rental rates in top-tier cities.

    Labour Market Realities and Future Leases

    The resilience of physical leasing contrasts with broader corporate polling on long-term workforce headcounts. A World Economic Forum survey conducted last year across 55 economies found that 41 percent of employers planned to reduce headcount as software automated standard white-collar tasks, raising questions about future desk utilisation.

    Asia-Pacific commercial occupiers have sidestepped immediate floorplate cuts by redirecting automated productivity gains into higher transaction volumes and new service lines. Corporate real estate directors are structuring three- to five-year leases around steady headcounts while monitoring whether generative workplace tools eventually alter administrative staffing models.

    Commercial landlords now watch the final quarter of 2026, when a heavy schedule of prime Hong Kong and Tokyo lease renewals will test whether tenant expansion pledges turn into binding long-term contracts.

  • Sunway Healthcare Starts Work on $196M Hospital in Johor

    Sunway Healthcare Starts Work on $196M Hospital in Johor

    Sunway Healthcare broke ground on an RM800 million ($196.2 million) tertiary hospital in Johor. The project is its first medical facility in Malaysia’s southern state.

    Planned for completion in 2030, Sunway Medical Center Iskandar Puteri will house more than 400 beds. It will employ over 1,400 healthcare staff.

    Located inside Sunway City Iskandar Puteri, the hospital sits within a 2,000-acre development launched in 2014. Around 7,000 residents live in the township today. Developers have completed more than 30 per cent of the master plan and sold roughly 2,000 homes.

    Expanding Footprint Across Johor

    The Iskandar Puteri facility anchors a series of specialized care projects across the state. Sunway Healthcare plans to open the Sunway Fertility Centre at Sunway Citrine in 2027. An ambulatory care centre will follow in 2028 near the upcoming Johor Bahru to Singapore Rapid Transit System link.

    Group leadership is also evaluating dedicated elder-care properties in the area. By 2032, the company intends to operate eight hospitals throughout Malaysia. That network will exceed 3,400 beds.

    Cross-Border Healthcare Demand

    Placing medical assets near the Singapore border targets two patient groups: local residents in suburban corridors and international medical tourists seeking private care at lower currency valuations. The Johor-Singapore Special Economic Zone adds tax and operational incentives to draw cross-border traffic.

    Competition for clinical talent will intensify for regional operators such as IHH Healthcare and KPJ. Medical staffing remains tight across Southeast Asia. Execution will depend on hiring and retaining senior doctors across competing networks.

    Consolidated Balance Sheet Backing

    Funding for the Johor site follows Sunway Healthcare’s debut on the Main Market of Bursa Malaysia in March. The business posted a net profit of RM111.48 million on revenue of nearly RM1.26 billion for the six months ended June 30. Those results represent year-on-year gains of 39 per cent and 27 per cent respectively.

    Sunway Group, led by founder Jeffrey Cheah, controls diversified holdings in construction, real estate, education, and infrastructure. Cheah’s net worth stood at $5.3 billion in April, ranking him eighth among Malaysia’s wealthiest individuals.

    Next Milestones for Delivery

    Site preparations included buying four land parcels within Sunway City Iskandar Puteri for RM45.37 million to accommodate the medical campus. Construction schedules now track progress on the RTS corridor connecting Johor Bahru and Singapore.

    Operations begin with the fertility clinic launch in 2027. That opening will test the southern medical network before the main hospital opens in 2030.

  • Average of 382 Minors Registered as Business Heads in South Korea

    Average of 382 Minors Registered as Business Heads in South Korea

    South Korean corporate registries listed an annual average of 382 minors as company heads between 2021 and 2025. The figure comes from National Health Insurance Service records released on Monday.

    Around 21 of those minor representatives drew annual salaries topping 100 million won ($72,200). That group included at least one child aged five or younger.

    Concentration in property and retail entities

    State health insurance data obtained by lawmaker Moon Jin-seok of the Democratic Party of Korea showed 1,909 total minor registrations over the five-year period. The total reflects workplace enrollments where minors were registered as executive representatives. Individual children may appear across multiple years.

    Older children formed the largest cohort. An average of 151 representatives were aged 11 to 15, while 129 were aged 16 to 18. Another 81 were aged six to 10, and 22 were aged five or younger. Among the 21 minors earning more than 100 million won each year, 12 were aged 11 to 15, six were aged 16 to 18, two were aged six to 10, and one was five or younger.

    Corporate filings reveal the listings sit almost entirely in asset-holding vehicles. Of the 100 highest-earning minors examined across the five years, 95 ran businesses in real estate, leasing and commercial services. Four operated in wholesale, retail and consumer repair. One ran a manufacturing business.

    Capital region dominates executive listings

    Seoul accounted for the vast majority of registrations, averaging 237 minor heads per year. Surrounding Gyeonggi Province logged 69. Incheon recorded 23, and the southern port city of Busan registered 19.

    These figures point to family-owned holding structures in metropolitan property markets rather than operating businesses run by young founders. Wealthy families in South Korea routinely establish corporate entities to hold commercial properties, retail shopfronts and land parcels to manage inheritance and gift tax exposure.

    Scrutiny over family income transfers

    Such practices complicate oversight for tax authorities and corporate regulators tracking intergenerational wealth transfers. Appointing non-working minor children as corporate representatives lets family offices distribute operational cash flow, salaries and corporate dividends across multiple tax brackets.

    Regulators across East Asia are checking whether nominal company heads perform actual management functions. For retail landlords and commercial property developers, dealing with entities fronted by underage representatives creates friction during contract execution, lease renewals and legal compliance filings.

    Calls for joint tax investigations

    Moon called on the National Tax Service and the NHIS to launch joint investigations into the practice. The inquiry would determine whether family-run corporations use representative registrations to disguise taxable gifts and shift parent earnings to children.

    Commercial law does not bar minors from holding corporate representative titles. Even so, tax regulators are weighing audits to test whether salaries paid to underage executives match bona fide operational duties.

  • Greystar Appoints Tom Livelli to Run $3.9 Billion Asia-Pacific Living Portfolio

    Greystar Appoints Tom Livelli to Run $3.9 Billion Asia-Pacific Living Portfolio

    Greystar has appointed former EQT partner Tom Livelli as head of Asia Pacific. He will run a $3.9 billion living-sector portfolio across four regional markets.

    Based in Sydney, Livelli takes up the executive director post in early 2027. He will direct roughly 250 staff managing more than 11,500 rental apartments and student beds across Australia, Japan, South Korea, and mainland China. He replaces Adam Pillay, who has left the firm.

    Executive reshuffle across regional markets

    Livelli spent the past three years in Madrid as head of living strategies for Europe at EQT Real Estate. Before that, he built Greystar’s South American operations between 2017 and 2023. That expansion took the platform past $800 million in assets across 19 investments, alongside eight management contracts covering roughly 6,000 units. His earlier career includes tenures at Boston Andes Capital and Clark Realty Capital.

    The leadership change puts Livelli in charge during a regional shift toward residential formats. Institutional investors across Asia-Pacific have pulled capital from secondary offices and speculative logistics. They are targeting cash-generating living assets instead. Livelli must now consolidate operations and reallocate equity across the firm’s living formats.

    Pivot to purpose-built student beds

    Capital has flowed directly toward Australian student housing. In April 2025, the firm completed its largest deal in the region to date: an A$1.6 billion ($1.1 billion) buyout of a 5,662-bed student portfolio from Singapore sovereign fund GIC and Wee Hur Holdings.

    Student housing offers immediate rental indexation and counter-cyclical cash flows. Pure-play multifamily developments struggle to match those returns under current construction costs. Student accommodation also brings faster tenant turnover and flexible rate adjustments, providing a stronger inflation hedge than multi-year commercial leases.

    Pruning industrial sites and rental developments

    Greystar has simultaneously stepped back from other property sectors in the region. It wound down an Australian infill industrial drive launched in 2022, selling a Sydney logistics development plot to Gateway Capital for A$78 million ($55.9 million) in May 2026.

    Traditional build-to-rent projects have faced similar pruning. Warburg Pincus-backed Kio Investment Management recently acquired a former Greystar development site in Melbourne’s Collingwood neighbourhood. In Japan, Greystar put several apartment assets on the market to test institutional liquidity.

    Expansion in Seoul and regional funds

    The manager first entered Asia-Pacific in 2017 through a partnership with Macquarie Capital. Over the next nine years, it opened six offices across the region. Growth has since expanded beyond Australia and Japan into mainland Asia.

    In May 2025, the group recruited former Samsung SRA Asset Management executive Junghwan Kang to launch its South Korea platform. Around the same time, the Teacher Retirement System of Texas allocated $25 million to the manager’s Asia-Pacific value-add vehicle.

    When Livelli takes over in Sydney in early 2027, the focus shifts to execution. The firm faces decisions on whether to deploy fresh capital into Korean residential assets or accelerate divestments across its Japanese apartment holdings.

  • Taiwan Holds Rates at 2 Percent and Eases Property Curbs

    Taiwan Holds Rates at 2 Percent and Eases Property Curbs

    Taiwan’s central bank kept its benchmark interest rate at 2 percent yesterday for a tenth straight quarter. At the same time, officials eased mortgage caps and land financing rules across the island.

    That decision leaves the collateralized lending rate at 2.375 percent and the short-term lending rate at 4.25 percent. The policy stance has held steady since 2024.

    Alongside the pause, policymakers raised the maximum loan-to-value cap on second-home purchases to 70 percent from 60 percent. They also scrapped a December 2021 rule requiring developers with land-purchase loans to break ground within a strict timeframe. Commercial lenders have enough experience managing real-estate risk now, Governor Yang Chin-long said. That gives the authority room to ease credit curbs without upsetting market stability.

    Cooling Mortgages and Shifting Developer Terms

    Commercial bank exposure to property debt has retreated steadily. Real-estate lending fell to 34.44 percent of total bank credit at the end of July, down from 35.56 percent in March and 37.61 percent in June 2024. Speculation has cooled. First-time buyers now take up a larger share of new mortgages, and builders are shifting capital into urban renewal.

    Dropping the construction deadline lifts a direct penalty on builders facing site bottlenecks. Developers across Taiwan grapple with labor shortages and hurdles disposing of excavated soil, problems that previously put land loans in breach. The change lets firms pace projects to real buyer demand rather than arbitrary regulatory clocks.

    Lenders Regain Flexibility in Construction Financing

    For retail lenders, the higher 70 percent loan cap unlocks credit in the secondary residential market. It helps upgrade buyers who were shut out by the older 60 percent limit. Risk remains under control. Banks still use the strict underwriting standards built over four years of tight oversight.

    Private capital in Taiwan is flowing into commercial and industrial projects backed by tech supply chains. The central bank widened its target ceiling for broad money supply growth to 6.75 percent from a 2.5 to 6.5 percent band, citing heavy spending on artificial intelligence hardware and active stock trading. Residential developers must now compete against high-yielding corporate borrowers for funds.

    Inflation Expectations Anchor Policy Path

    Central bank officials want to rein in price pressures without stifling domestic output. They raised the full-year economic growth forecast to 11.48 percent on robust tech export orders. Consumer price inflation is projected at 2.03 percent this year, with core inflation at 2.16 percent. Both figures remain just above the 2 percent target.

    A board majority voted to hold rates, though two members dissented in favor of a hike to curb persistent costs. Yang said global risks, particularly energy threats from Middle East tensions, warrant keeping borrowing costs steady until inflation cools further.

    Growth Outlook Points to 2027 Moderation

    Growth is expected to slow to 5.82 percent next year as export gains normalize against high base numbers. Consumer inflation should slide below 2 percent over that stretch, setting up the threshold board members will track before moving borrowing rates.

  • Trunk Hotel Expands Outside Tokyo with 107-Room Sapporo Tower

    Trunk Hotel Expands Outside Tokyo with 107-Room Sapporo Tower

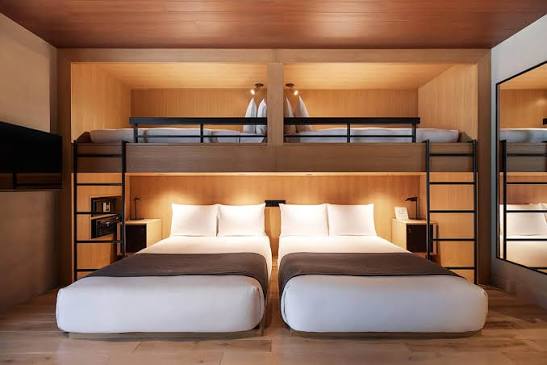
    Tokyo boutique operator TRUNK (HOTEL) will open an 18-story, 107-room property in Sapporo on September 17, 2027. The project takes the brand outside the Japanese capital for the first time.

    Located in the central Odori district, the development is the brand’s fourth property and its largest footprint to date. Tokyo architecture practice GENERAL DESIGN CO., LTD. Designed the building alongside TRUNK Atelier, the operator’s in-house unit. They deployed a concept labeled Midcentury Folklore across 18 suites and 89 standard guest rooms.

    Waterways and Michelin Dining

    Inside the tower, an entire floor houses TRUNK(BATH HOUSE), configured around an urban spa concept. Guests enter through a reception lounge and bar before reaching a 40-meter central waterway. This channel feeds 10 communal bathing spaces, each fitted with dedicated water temperatures, audio setups and lighting profiles. Separate male and female zones each feature saunas, cold plunge pools and open-air decks.

    Dining operations center on a partnership with Michelin-recognized Sushi Saito. The outpost is the restaurant’s first kitchen in Sapporo, featuring a chef counter format that pairs Tokyo preparation methods with Hokkaido seafood. A second all-day dining venue sits on the lounge and bar floor. That room will feature live music performances, an outdoor terrace and heated transparent domes for the winter season.

    Banqueting and Private Event Spaces

    Event facilities occupy two dedicated floors. A private studio level houses a cinema, a karaoke suite and modular rooms for small corporate functions. On the 10th and 11th floors, three distinct banquet halls operate under the names HINATA, MIYABI and KODACHI. Upper levels also incorporate a standalone dessert room, a private sushi bar, an outdoor pizza terrace and a six-meter-tall ceremonial chapel facing park greenery.

    Japanese boutique operators have historically clustered in central Tokyo neighbourhoods like Shibuya and Cat Street to capture dense international footfall. Moving into regional capitals shifts the commercial calculation. Operators must balance domestic corporate travel against peak winter ski flows, using larger food and beverage operations to sustain occupancy when seasonal tourism dips.

    Rival international chains and Hokkaido landlords are expanding across Sapporo and nearby resort nodes like Niseko. TRUNK’s entry accelerates competition for high-spend domestic travellers. The main execution risk sits in building out large-format hospitality real estate with complex amenity footprints in a secondary market. Construction costs and seasonal labour constraints in Hokkaido remain structurally tighter than in Tokyo.

    Portfolio Track Record

    TRUNK built its track record in Tokyo, establishing brand equity through boutique design, high-density public lounges and curated tenant partnerships. Scaling beyond the capital tests whether that neighbourhood-driven model translates to an 18-story greenfield tower.

    Crews continue work in the Odori commercial core ahead of the scheduled opening date on September 17, 2027.

  • Tokyo Inner Ward Population Hits 9.8 Million as Density Reaches 15,600

    Tokyo Inner Ward Population Hits 9.8 Million as Density Reaches 15,600

    Tokyo’s 23 central wards added 1.2 million residents over the past two decades, pushing urban density to 15,600 people per square kilometre, as reported by Paul de Vries for The Japan Times in September 2026. The population in the inner wards now stands at 9.8 million.

    Construction firms and property developers have absorbed this influx primarily through two methods. Builders are erecting high-rise residential towers containing hundreds of units while buying standalone houses with private yards, razing the greenery, and replacing them with multiple narrow homes.

    Subdividing Plots for Housing

    Landed housing subdivisions now supply a steady stream of compact urban properties across residential wards. Replacing a single detached home with two or three townhouses increases plot yield for homebuilders. It also removes private gardens that previously provided urban tree cover and communal wildlife corridors.

    Tower developments concentrate hundreds of households onto single commercial footprints. These buildings offer high floor-area ratios but leave standard rooftops largely bare of functional green infrastructure.

    Pressure on Urban Greenery

    For residential property developers in Japan, plot subdivision remains the fastest way to bring infill housing to market without assembly delays. However, municipal planning offices face mounting heat-island effects in wards where open ground cover has vanished. Residential developers across Seoul and Singapore face similar constraints, but Japanese zoning codes give private landowners wider leeway to maximise structural footprints up to boundary lines.

    Institutional real estate investors holding multifamily residential assets in Tokyo face shifting tenant preferences. Renters and buyers in high-density districts increasingly seek access to private or communal outdoor spaces, creating a pricing gap between conventional concrete blocks and properties that integrate rooftop greenery.

    Rooftop Space Under Scrutiny

    Tokyo’s urban growth runs counter to Japan’s broader demographic decline, which has hollowed out regional prefectures while concentrating capital and labour in the Kanto region. Previous redevelopment cycles focused on expanding transport nodes and commercial office floors around central railway hubs.

    Attention is shifting to residential rooftop retrofits across the 23 wards as developers balance land costs against municipal open-space guidelines.

  • ClubMed Lifestyle Targets 85 Global Resorts by 2030 Ahead of Hong Kong IPO

    ClubMed Lifestyle Targets 85 Global Resorts by 2030 Ahead of Hong Kong IPO

    ClubMed Lifestyle Group plans to expand its global resort network to roughly 85 properties by 2030. The expansion relies on an asset-light model across key international leisure markets.

    Today, the Fosun International subsidiary operates 69 resorts across more than 40 countries and regions. It serves over 1.5 million guests each year.

    Asset-light pipeline spans Asia and Europe

    Since late 2025, the group has secured new resort agreements in China, Indonesia, Canada, Morocco, Brazil, the US Virgin Islands and Italy. Target markets include the European Alps, Mediterranean and North African coastlines, Northeast and Southeast Asia, and the Americas. Early development work is also underway in the Middle East.

    Management relies on management contracts, integrated vacation destinations and cultural-tourism complexes rather than direct real estate ownership. In July, Club Med signed a memorandum of understanding with Microsoft at its Paris headquarters. The partnership applies cloud-native systems and artificial intelligence tools to resort operations and guest services. Microsoft France chief executive Corinne De Bilbao and ClubMed Lifestyle Group co-president Xu Bingbin led the signing.

    Valuation shifts and operator competition

    Resort operators across the Asia-Pacific region are shifting capital expenditure off their balance sheets. The strategy helps defend margins against volatile travel cycles. Rival luxury and leisure operators in Southeast Asia use similar management contracts to scale up without taking construction debt onto their books.

    Brand consistency and service standards remain the central risk across third-party real estate as networks grow. Meanwhile, developers in regional resort hubs face high financing costs. Operational efficiency and direct booking technology will determine whether newly signed properties stay profitable.

    Fosun prepares Hong Kong public float

    This push follows a corporate restructuring by parent company Fosun International. On August 28, the World Travel & Tourism Council admitted ClubMed Lifestyle Group as a global member. The business filed a formal listing application with the Hong Kong Stock Exchange on August 29 to spin off the vacation unit into an independently traded entity.

    Fosun reported total revenue of RMB86.96 billion and a net profit of RMB1.72 billion for the first half of 2026. The upcoming Hong Kong listing will determine how much capital the business secures to add the final 16 resorts needed for its 2030 goal.