Tag: reserve bank of australia

  • Australian Retail Spending Growth Slows to 4.9 per Cent Ahead of Peak Season

    Australian Retail Spending Growth Slows to 4.9 per Cent Ahead of Peak Season

    Australian retail spending grew 4.9 per cent in the year to September, slowing from 5.6 per cent in August as households cut back under persistent mortgage and living costs.

    Total retail trade reached $39.91 billion over the 12-month period, according to figures released by the Australian Retail Council. The drop in momentum comes just weeks before the critical Black Friday and Christmas trading window, which traditionally delivers the bulk of annual discretionary margins.

    Spending Splits Across Categories

    Pockets of non-discretionary and experiential spending held up while general merchandise stalled. Other retailing, covering pharmacies and cosmetics, climbed 8.1 per cent over the year, while cafes, restaurants, and takeaway food services rose 7.4 per cent.

    Discretionary categories showed sharp deceleration. Department stores and large online retailers recorded turnover growth of just 1.7 per cent, pointing to volume contraction once accounting for higher operating costs. Food retail turnover increased 3.3 per cent, running almost flat against the 3.2 per cent jump in food and non-alcoholic beverage prices measured in the September Consumer Price Index. The figure indicates that grocery growth reflected higher shelf prices rather than larger baskets.

    Margin Squeeze Ahead of Black Friday

    Weakening sentiment is already bleeding into register receipts across major shopping precincts. Consumer confidence fell sharply in September and slid again in October, leaving households with little appetite for full-price holiday shopping.

    The Reserve Bank of Australia compounded the pressure by lifting interest rates and downgrading its broader consumption forecasts. Central bank projections now anticipate consumption growth of 1.4 per cent for the years ending December and June, trimmed from an earlier 1.6 per cent forecast.

    “This weaker outlook, combined with yesterday’s interest rate increase, comes at a particularly difficult time for retailers, with Black Friday sales and the crucial Christmas trading period fast approaching,” said ARC chief economist Glenn Fahey.

    Price Restraint Limits Turnover Value

    Merchants face severe margin pressure as they discount stock to stimulate foot traffic. Clothing and footwear prices rose by just 0.4 per cent over the past year, while household equipment, furnishings, and services increased 0.8 per cent. Both categories trailed headline inflation of 4.3 per cent by a wide margin, demonstrating that stores swallowed cost increases rather than passing them on to shoppers.

    For regional supply chains and Asian consumer goods exporters exposed to the Australian market, these figures point to cautious reordering. Importers and local retail groups are keeping inventories tight to avoid forced clearance events in January.

    Attention now turns to preliminary November promotional volumes, where merchants will test whether heavy discounting can shake loose household savings before Christmas.
  • Australian Home Values Slide 1.2% in October as Capital City Slump Accelerates

    Australian Home Values Slide 1.2% in October as Capital City Slump Accelerates

    Australian dwelling prices dropped 1.2 percent in October, registering a seventh consecutive monthly fall that pulled national values 6.7 percent below their March peak. That decline strips roughly A$63,400 ($44,528) from the median home value as borrowing limits bite.

    Capital city markets bore the brunt of the downturn, falling 8.1 percent over the past seven months. That extends the pullback beyond the 7 percent drop seen in 2022 when the Reserve Bank of Australia initiated its post-pandemic rate-tightening cycle.

    Brisbane and Perth Lead Capital Declines

    Mid-sized capital cities that saw rapid value spikes over the last six years registered the sharpest drops during the month. Brisbane property values fell 2.0 percent in October, while Perth dropped 1.7 percent. Over the past three months, values retreated 6.1 percent in Brisbane and 5.7 percent in Perth.

    Sydney dwelling prices fell 1.6 percent in October, bringing the median dwelling price to A$1,178,959. That puts Sydney 10.1 percent below its February peak and 1.5 percent below levels seen in October 2021. Melbourne retreated 0.8 percent, leaving prices 7.3 percent lower than five years ago. Hobart and Darwin recorded modest increases of 0.5 percent and 0.6 percent respectively.

    Property owners retain built-in valuation buffers despite the monthly drops. Brisbane values stand 46.1 percent higher than five years ago, while Perth properties retain a 68.3 percent gain over the same timeframe. Annual price growth in Brisbane flattened to 0.4 percent in October, down from 18 percent in May.

    Transaction Volumes and Auction Clearances Slip

    Buyer demand slowed across major metropolitan areas, with estimated home sales over the past three months down 23 percent year-on-year. Sydney transaction volumes fell 30 percent, while Brisbane dropped 29 percent. Median time on market lengthened to 39 days, the longest period recorded since August 2020, while vendor discounts expanded to an average of 4.7 percent.

    Auction markets reflected similar hesitation entering November. Preliminary clearance rates across combined capitals reached 47.2 percent from 1,735 auctions in the week ending November 1, marking the weakest result since April 2020. Brisbane auction clearances settled at 26.2 percent, finishing under the 30 percent threshold for the fourth time in five weeks.

    Investor activity fell following changes in the May Federal Budget that tightened tax treatment on established rental assets. New investor lending commitments dropped 8.6 percent in the June quarter, marking the sharpest quarterly retreat since September 2022. Because residential rents rose as values fell, gross rental yields across the combined capitals climbed to 3.77 percent.

    Household Wealth Pressures Hit Consumer Demand

    Shrinking home values directly erode consumer balance sheets, hitting household spending on big-ticket homewares, renovation services and discretionary goods. For retail operators and shopping centre landlords across Sydney and Brisbane, declining asset values compound existing household budget constraints created by persistent living costs.

    Retailers face softer foot traffic as mortgage serviceability reduces discretionary cash flow. While tight housing supply and population gains prevent broader systemic liquidations, discretionary merchants must prepare for prolonged margin compression as households prioritize essential grocery and utility outlays over higher-margin merchandise.

    Rate Policy Tightens Squeeze on Borrowers

    The Reserve Bank of Australia raised its official cash rate by 100 basis points earlier this year to 4.60 percent. Financial markets priced an 85 percent probability of another rate rise following the release of September quarter inflation numbers.

    Commonwealth Bank of Australia expects the RBA to lift the cash rate to 4.85 percent before pausing, with bank economists forecasting two rate cuts in August and November 2027. The bank lowered its domestic growth outlook, projecting unemployment to rise to 5.1 percent by late 2027.

    Households will bear the brunt of the needed slowdown in economic activity.

    The central bank meets on Tuesday to review borrowing costs, with retail landlords and commercial property lenders watching whether the cash rate reaches 4.85 percent.

  • Australian Auto Retailers Fetch 11.2X Valuation as Apparel Slips to 6.4X

    Australian Auto Retailers Fetch 11.2X Valuation as Apparel Slips to 6.4X

    Australian automotive retailers traded at 11.2 times earnings in 2026 while apparel multiples slumped to 6.4 times, according to Grant Thornton Australia’s Dealtracker transaction data.

    The five-turn valuation divide reflects an aggressive buyer preference for cash-generative operations with locked-in distribution over discretionary fashion merchants struggling with discount cycles.

    Grant Thornton released the findings in the final installment of its four-part transaction study, warning retail boards that chasing top-line sector expansion will not insulate them from acquisition discounts. Dealmakers are pricing businesses based on procurement controls, balance-sheet resilience, and customer retention rather than broad category growth projections.

    Multiples Split Discretionary Categories

    Valuations across consumer discretionary assets show stark divergence within the same retail spending pools. Automotive businesses commanded double-digit multiples by pairing vehicle sales with parts supply, workshop servicing, and rigid customer replacement cycles.

    Apparel operators faced steep discounts as selective shoppers trimmed discretionary wardrobes and forced merchants into promotional price battles. Brand equity alone no longer commands premium deal pricing without evidence of repeat purchase loyalty that survives inflationary pressure.

    Tam Goldin, financial advisory partner at Grant Thornton Australia, pointed out that category classification accounts for only part of a target’s pricing. “The sector matters, but the underlying business model matters more,” Goldin said.

    Private capital in Australia has pivoted toward specialized operators that scale distribution networks without multiplying administrative overhead. Scaled retailers with integrated inventory pipelines hold pricing power, whereas mid-tier general merchants face margin compression across both physical stores and digital storefronts.

    Capital Discipline Replaces Platform Sprawls

    Technology spending in the sector has shifted from speculative platform rollouts to strict return hurdles. Retailers are halting open-ended artificial intelligence trials to focus on inventory visibility, demand forecasting, and operational productivity.

    Kirsten Ridgway, management consulting partner and head of retail and consumer products at Grant Thornton Australia, stated that board-level technology choices cannot center on software procurement alone. Executive teams must identify specific operational bottlenecks before committing capital to enterprise platforms or machine-learning tools.

    Enterprise cleanups now take priority over front-end digital additions. Merchandisers are overhauling fragmented legacy databases because untested algorithmic tools compound pricing errors when fed inconsistent stock records.

    RetailNews Asia sees this operational retrenchment as a defensive realignment across Australasia. Regional retail conglomerates in Singapore, Tokyo, and Sydney spent three years buying disparate commerce software packages, only to find that operational complexity wiped out expected margin gains.

    Second-Hand Marketplaces Erode Price Power

    Traditional clothing chains face mounting margin erosion from circular commerce platforms. Second-hand marketplace Vinted entered the Australian market and disrupted established local resale channels, drawing cost-conscious consumers away from full-price fast-fashion and mid-market apparel racks.

    Resale platforms operate without inventory carrying costs or physical store lease liabilities. That structural cost advantage lets them reset shopper expectations around everyday apparel pricing, penalizing conventional store operators whose rent and utility charges remain fixed.

    Online commerce penetration continues to anchor these digital shifts. Australia Post eCommerce data recorded that 82 percent of Australian households made online purchases during 2025, with 41 percent shopping online fortnightly or more.

    High e-commerce participation allows overseas circular platforms to scale rapidly across Australian metropolitan centres. Traditional apparel chains unable to justify their price premiums risk losing volume permanently to these asset-light competitors.

    Payment Reforms Squeeze Margin Buffers

    Regulatory mandates are compounding pressures on retail margins. The Reserve Bank of Australia removed payment surcharges on eftpos, Mastercard, and Visa transactions on October 1, 2026, forcing merchants to absorb payment processing fees rather than passing them directly to shoppers at the checkout.

    This surcharge prohibition hit high-frequency merchants immediately, narrowing cash gross margins that were already compressed by wage rises and freight volatility. Operators without volume-based acquiring discounts must now extract operating efficiencies elsewhere in their supply chains.

    Stored-value and loyalty instruments offer partial relief from transaction friction. Australia’s gift card market is projected to reach US$8.22 billion in 2026, expanding 10.9 percent annually as supermarket chains and department stores deploy closed-loop digital balances to defend basket sizes.

    Woolworths integrated its Everyday Gifting system directly into its rewards smartphone application, letting loyalty members buy and redeem electronic cards with stored loyalty balances. Supermarkets and department chains use these closed networks to capture prepaid sales, avoid merchant terminal surcharges, and keep spend locked within their retail ecosystems.

    The Australian Retail Council convenes its supply chain summit on October 27, 2026, where national logistics directors will assess port freight disruption and inventory holding costs ahead of the peak November shopping weekend.

  • Investors Bet on Japan and Australia Rental Housing as Rates Rise

    Investors Bet on Japan and Australia Rental Housing as Rates Rise

    Higher mortgage rates and elevated home prices across Tokyo and Sydney are pushing buyers out of the sales market. Institutional capital is flowing into rental housing instead.

    Australian home values have dropped 5.2 per cent nationally from their March 2026 peak. In Japan, buyers are opting for compact rental units to avoid borrowing costs.

    That split reflects the sharpest monetary tightening cycle across major Asia-Pacific economies in over a decade. Tokyo professionals are turning toward compact apartments with shared amenities, choosing rent over long-term debt as yields shift. Across Australia, the Reserve Bank raised its cash rate from 3.6 per cent to 4.6 per cent over four hikes in February, March, May and September 2026. Borrowing costs now sit at their highest point since 2011.

    Squeezed Borrowers and Dropping Valuations

    Price drops have hit Australia’s major metropolitan centers hardest over the past six months. Sydney values fell 8.6 per cent from their February high. Melbourne prices dropped 7.2 per cent since November.

    Top-tier properties are absorbing the brunt of the downturn. Cotality data shows values in the top quartile across Sydney and Melbourne dropped more than 10 per cent from peak valuations. Seven of Australia’s eight capital cities are recording price declines. Darwin is the lone market where values still rise.

    Household debt has amplified the downturn, standing at roughly 178 per cent of annual disposable income. Most Australian borrowers hold variable-rate loans. That transmits interest rate hikes directly into monthly budgets.

    Tax Overhauls Shake Investor Demand

    Policy changes in Canberra are speeding up the shift away from speculative residential buying. From July 2027, the Australian government will restrict negative gearing deductions strictly to newly constructed dwellings. Buyers will no longer write off rental losses on existing homes against taxable income.

    Federal authorities are also eliminating the 50 per cent capital gains tax discount on investment properties. An indexation system will replace the flat deduction, adjusting initial purchase prices for inflation before calculating taxable profit on a sale.

    Lending data already reflects cooling sentiment among private landlords. Australian Bureau of Statistics figures show lending commitments to property investors fell 8.6 per cent between March and June 2026. That pullback hits a segment of more than 2.2 million individual property owners nationwide.

    Diverging Capital Flows Across the Region

    In Tokyo, institutional operators are scaling up build-to-rent formats and small-footprint units for single-person households in central locations. Shared community spaces help operators preserve net effective rents. Individual unit costs also remain accessible for young tenants.

    Rental housing offers regional real estate funds stable cash generation while residential sales volumes drop. Westpac Banking forecasts Australian home prices will fall 7.3 per cent from peak to trough as tighter credit works through the banking system.

    Developer balance sheets will face pressure across both markets through the rest of the year. Attention now turns to whether the Reserve Bank of Australia holds rates steady at 4.6 per cent, and how quickly private investors recalibrate their portfolios before the July 2027 tax changes take effect.

  • Australian Counterfeit Banknotes Surge to Eight-Year High of 20 Notes per Million

    Australian Counterfeit Banknotes Surge to Eight-Year High of 20 Notes per Million

    Australian authorities detected 40,613 counterfeit banknotes in the 12 months to March 31. That pushed fake cash rates to their highest level since June 2018.

    The detection rate reached 20 notes per million in the March quarter. That is up 277 per cent in 15 months from a low of 5.3 notes per million in December 2024. Reserve Bank of Australia data shows fifty and one hundred dollar denominations accounted for 95 per cent of all seized counterfeits.

    Criminal syndicates are targeting high-turnover consumer businesses to convert fraudulent high-denomination notes into genuine legal tender and merchandise. Retailers receive zero reimbursement for accepted fake bills. Store operators absorb the full direct loss at the point of sale.

    Inflow through air cargo and mail

    Border authorities identified international logistics networks as the primary conduit for the influx. The Australian Border Force reported that counterfeit currency worth millions entered the country through air cargo consignments and international postal streams starting in early 2025.

    Importers are using more sophisticated physical concealment inside regular freight to bypass automated border screening. Law enforcement agencies warned that manufacturing standards have climbed. The higher quality makes fraudulent bills harder for retail cashiers to identify during fast transactions.

    Officials noted there has been a concerning improvement in the quality of counterfeit notes entering distribution channels.

    Retailers bear the frontline losses

    Regional retail stores, independent service stations, and hospitality venues face the sharpest exposure. In August, South Australian police charged a 32-year-old man for allegedly circulating bogus $50 bills across licensed venues, a petrol station, and shops in Mount Gambier.

    Queensland police made a separate arrest in Roma after an individual allegedly passed counterfeit $50 notes across two discount variety stores before trying to use another at a local hotel. Peer-to-peer sellers on online marketplaces have logged similar losses after handing over consumer goods for counterfeit cash.

    Large quick-service restaurant chains hold an operational advantage over smaller operators in managing this risk. Selected McDonald’s outlets and drive-through operators across Australia have run specialized counterfeit detection devices at their registers for more than ten years.

    Upgraded polymer security features

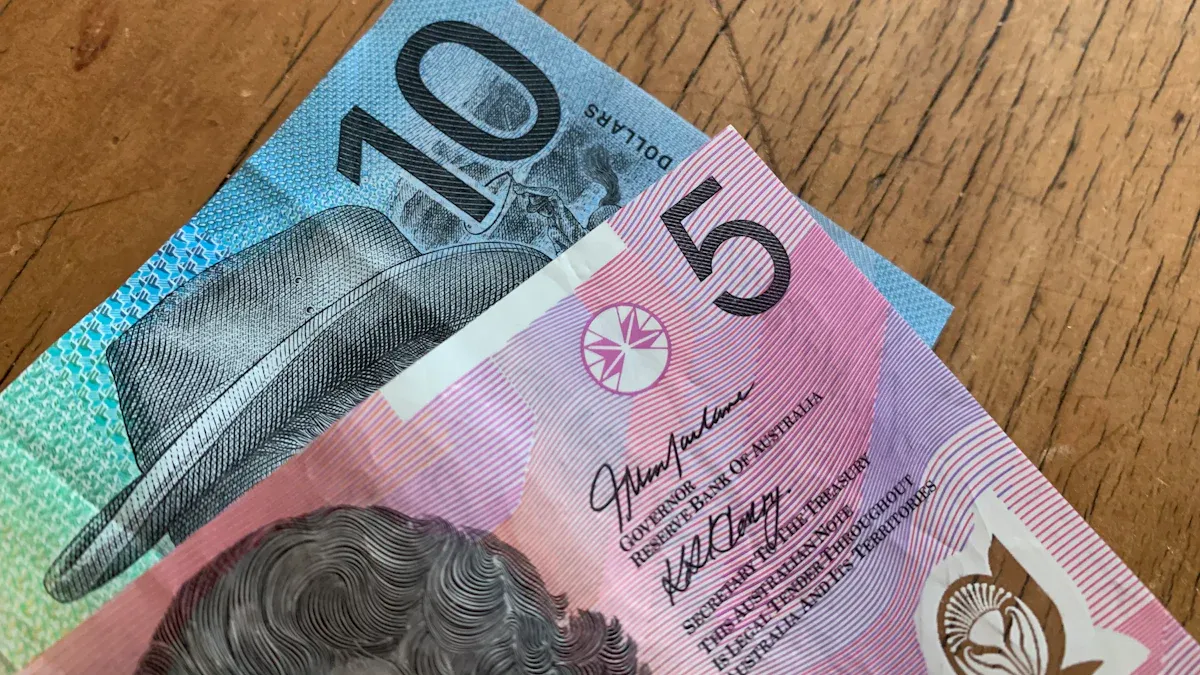
    The circulation spike comes despite Australia’s multi-year investment in polymer banknote security. The Reserve Bank of Australia rolled out its next generation banknote series between 2007 and 2020, upgrading earlier polymer designs first engineered with the CSIRO in the 1990s.

    Those newer notes feature a clear top-to-bottom window, reversing numerals, microprint, and UV-fluorescent patterns. They also carry a dynamic holographic flying bird that changes colour when tilted. Both the original 1990s polymer releases and the upgraded generation remain concurrent legal tender.

    Dual circulation creates an operational loophole. Fraudsters often replicate older polymer formats to bypass the advanced optical elements found on the newer series.

    Manual checks at checkout counters

    Central bank guidance advises retail staff to apply a three-step verification method: feel the plastic texture, hold the note to the light to confirm the clear window elements, and tilt the bill to inspect dynamic colour patches. First-generation polymer bills display a printed star and coat of arms within the window.

    Merchant protocols direct employees to refuse suspicious cash if safe to do so, record transaction details, and hand disputed notes directly to state or territory police. Operators can also file formal counterfeit detection forms through the Australian Federal Police.

    Retail loss-prevention teams are now watching upcoming quarterly Reserve Bank release data to track whether border interdictions successfully curb the circulation rate back toward its 2024 baseline.

  • Australian Retail Spending Climbs 7% as Stronger Dollar Eases Import Costs

    Australian Retail Spending Climbs 7% as Stronger Dollar Eases Import Costs

    Australian retail spending grew 7.0 per cent year on year in July, driven by consecutive monthly gains across all major discretionary merchandise categories.

    Monthly household expenditure expanded 1.1 per cent in July, marking a third straight monthly advance and providing merchant relief ahead of fourth-quarter trade.

    Official Australian Bureau of Statistics data showed apparel and footwear leading the monthly lift with a 1.6 per cent increase, while recreation and culture gained 1.5 per cent. Discretionary spending climbed 7.8 per cent compared to July 2025, even as higher price points accounted for part of the top-line dollar expansion.

    Currency Relief on Sourced Inventory

    Landed costs across consumer electronics, toys, apparel and homewares have eased as the Australian dollar moved above 70 US cents in late September. That contrasts with an average exchange rate near 64 US cents throughout 2025, lowering procurement expenses on goods invoiced in US currency.

    For regional supply chains and Asia-based manufacturers supplying Australian retail networks, a stronger local currency alters order timing and pricing use. Importers that locked in inventory during early 2026 faced compressed margins, whereas buyers placing late-year purchase orders now capture direct landed savings.

    GDP Expansion and Capital Investment

    Broader economic output expanded by 0.4 per cent during the June quarter, bringing annual gross domestic product growth to 2.1 per cent. Across the full 2025-26 financial year, the economy grew 2.4 per cent, outpacing performance recorded across the prior two fiscal periods.

    Capital allocations also widened during the period. Private business investment reached 12.7 per cent of gross domestic product, the highest level recorded in a decade, underpinned by capital outlays in data centres, renewable power installations and commercial aircraft fleets.

    Labour Market Resilience and Household Buffers

    Consumer cash reserves showed slight replenishment as the household saving ratio ticked up to 6.5 per cent in the June quarter from 6.4 per cent. Total employment expanded by approximately 39,000 positions in August, while the national participation rate stood at 67.1 per cent.

    Unemployment rose to 4.6 per cent as additional jobseekers entered the market, a level Reserve Bank of Australia Governor Michele Bullock noted sits within a range capable of cooling lingering price pressures. Headline inflation tracked at 3.5 per cent in July, with the trimmed mean indicator registering at 3.6 per cent.

    Interest Rate Pressures Heading into Peak Season

    Monetary policy remains the primary headwind for merchant balance sheets and household debt servicing. The central bank entered its late September policy review with the cash rate target at 4.35 per cent, having already executed three rate hikes earlier in 2026.

    Department store operator Myer flagged persistent market uncertainty, with executive chair Olivia Wirth noting consumer behaviour is likely to stay volatile across the coming 12 months. Australia’s four largest domestic commercial banks forecast a 25 basis point cash rate increase to 4.60 per cent at the next monetary policy determination.

  • Australia Central Bank Raises Cash Rate to 4.6 per Cent in Fourth 2026 Hike

    Australia Central Bank Raises Cash Rate to 4.6 per Cent in Fourth 2026 Hike

    The Reserve Bank of Australia lifted its cash rate target by 25 basis points to 4.6 per cent on Tuesday. The benchmark is now at its highest level since 2011.

    This is the central bank’s fourth rate hike of 2026, decided unanimously by its monetary policy committee. Higher borrowing costs take effect immediately across the banking sector. Household discretionary budgets across the country now face fresh pressure.

    Energy Costs and Inflation Drivers

    Persistent inflationary pressures and climbing global energy prices triggered the tightening, officials said. Several upside risks identified during the August meeting have now materialised. Conflict in the Middle East also pushed oil markets above baseline projections. The committee said its priority is stopping elevated inflation from becoming permanently embedded in price-setting behaviour.

    Market intelligence firm Circana warned that the rate rise will alter household buying habits immediately. Shoppers will reduce visit frequency and trade down to cheaper goods. They will also concentrate purchases around discount events.

    Tighter Margins Ahead of Peak Season

    Store operators and brand owners face this policy squeeze at a vulnerable time. Discretionary retail chains rely on the fourth quarter, particularly Black Friday and the weeks before Christmas, to generate cash flow and rebuild financial reserves. Higher debt servicing costs and elevated transport fuels directly erode retail operating margins.

    Passing cost increases to value-conscious shoppers is difficult. Merchants must absorb rising logistics and operational expenses through compressed margins, or risk losing transaction volume to cheaper rivals.

    Productivity and Regulatory Debate

    Industry groups are challenging the macroeconomic policy mix behind the repeated rate adjustments. Top-line retail turnover held up through mid-2026, according to the Australian Retail Council. Spending momentum is now showing signs of fatigue under concurrent rate and fuel increases.

    Lagging domestic efficiency is driving inflation rather than demand alone, the Business Council of Australia said. The group called for a 25 per cent cut in regulatory compliance costs. Returning productivity growth to historical averages would provide substantial long-term relief to household budgets.

    The Trajectory Leading to 4.6 Per Cent

    Tuesday’s adjustment follows three consecutive rate increases earlier in 2026, designed to cool domestic price pressures without triggering an outright contraction. Previous policy statements in August had assumed stabilizing energy import prices. Subsequent global supply disruptions invalidated that assumption.

    Analysts will now track fourth-quarter retail sales volumes and November promotional discounting data to determine whether consumer demand can withstand the 4.6 per cent benchmark.