Tag: retail sales

  • Swire Cuts Taikoo Place Office Rents 14 Percent

    Swire Cuts Taikoo Place Office Rents 14 Percent

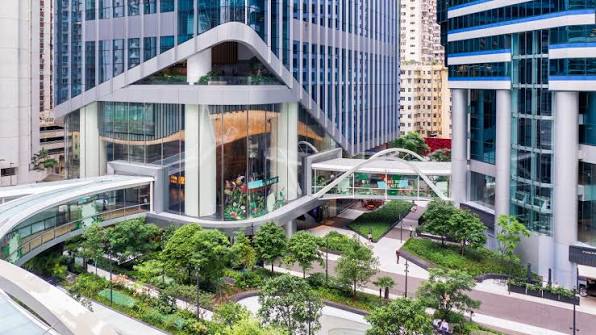
    Swire Properties signed office leases at an average 14 percent discount to expiring rents across Taikoo Place, excluding its newest tower, in the first nine months of 2026, failing to catch Central’s rebound.

    The negative rental reversions covered 934,991 square feet of new and renewed tenancies through September, according to the developer’s quarterly operating statement released on Thursday.

    Occupancy across the established Quarry Bay portfolio edged up to 90 percent from 89 percent at the end of 2025. Two Taikoo Place, the one-million-square-foot tower opened in September 2022, remained stuck at 80 percent occupancy at the end of September. That figure was unchanged from June, though higher than the 73 percent recorded at the end of last year.

    Discounts Spread Across Island Portfolios

    Price cuts were not isolated to Hong Kong East. At Pacific Place in Admiralty, on the edge of Central, Swire recorded negative rental reversions of 12 percent through September, even as occupancy rose to 97 percent from 96 percent at year-end. In leasing terms, rental reversions track the rate difference between incoming leases and expired contracts rather than prevailing headline rates.

    Within Taikoo Place, One Island East and One Taikoo Place together logged negative reversions of 13 percent, with occupancy rising to 92 percent from 91 percent at the end of 2025. Other established towers across the Quarry Bay hub booked average reversions of negative 14 percent, with occupancy moving up a point to 89 percent.

    The landlord secured major commitments during the period, including a 200,000-square-foot renewal by BNP Paribas and a renewal and expansion to 83,000 square feet by Prudential Hong Kong. FWD also committed to 330,000 square feet for ten years. None of those deals prevented contract values from resetting lower.

    Central Pulls Divergent District Numbers

    The pricing drag highlights a sharp geographic split across Hong Kong commercial property. Across the city, Grade A office rents rose 0.7 percent in September from August, driven by a 1.6 percent increase in Central, based on JLL data. Citywide vacancy fell for a fifth straight month to 12.4 percent, the lowest level recorded since May 2023.

    Vacancy in Central fell to 7.2 percent in September from 7.8 percent in August. In Hong Kong East, vacancy widened to 14.3 percent from 14.1 percent.

    Agency figures from Knight Frank show Central net effective rents jumped 22.4 percent year on year in the third quarter. Quarry Bay rents dropped 4.4 percent over the same period, despite inching up 0.2 percent from the second quarter. The gap leaves decentralized landlords exposed to prolonged cash-flow drag while core financial district blocks take the initial tenant recovery.

    Retail Cash Flow Offsets Corporate Leases

    Swire found financial ballast in consumer spending. Across mainland China, tenant sales at Beijing’s Taikoo Li Sanlitun surged 59.8 percent year on year in the first nine months, reaching 100 percent occupancy. Sales at Shanghai’s HKRI Taikoo Hui climbed 52.6 percent, with occupancy at 97 percent.

    Taikoo Li Chengdu recorded an 11.3 percent sales gain, while Taikoo Li Qiantan in Shanghai rose 10.2 percent. Both developments stood at 98 percent occupancy at the end of September.

    Hong Kong retail assets also held firm. Pacific Place tenant sales grew 14.8 percent over the nine months, Citygate Outlets rose 14 percent, and Cityplaza gained 2.3 percent. All three shopping centres maintained 100 percent occupancy.

    Capital Recycling and Redevelopment Timeline

    Consumer gains are steering Swire toward Chinese public investment markets. The developer is actively reviewing domestic real estate investment trusts to unlock cash from mainland properties, with no specific seed assets or public listing timetable determined yet.

    Work also continues on its home turf. Swire and Chinachem Group have detailed a plan to build a 27-storey office tower by combining Swire’s Sea View Building and Hoi Wan Building sites with the adjacent Chinachem Exchange Square. The 35,000-square-foot combined site will support 500,000 square feet of gross floor area, including a retail podium, subject to planning approval.

    Swire and Chinachem scheduled construction to begin in 2027, with completion targeted for 2032. On the mainland, Swire secured an occupation permit for Phase A of CDF Taikoo Li Sanya in August and for the west parcel of Taikoo Place Beijing in September.

  • Nintendo Quarterly Profit Falls 29Pc to 73.5 Billion Yen as Switch 2 Cools

    Nintendo Quarterly Profit Falls 29Pc to 73.5 Billion Yen as Switch 2 Cools

    Nintendo posted a 29 per cent drop in second-quarter net profit to 73.5 billion yen, missing market forecasts as unit sales for its Switch 2 console slowed.

    The Japanese gaming company fell short of the 82.2 billion yen average estimate compiled by Bloomberg for the July-September period.

    First-half net profit still climbed 11 per cent year-on-year, supported by earlier momentum and software purchases. Operating profit jumped nearly 50 per cent across the six months, aided by steady software transactions and a windfall from US tariff refunds.

    Hardware Volume Drops After Launch Year

    Consumer demand for hardware pulled back sharply across global channels. Nintendo sold nearly 6.5 million Switch 2 consoles during the six months, down from almost 10.4 million units in the comparative period a year earlier when the hardware debuted.

    Component costs hit margins across electronics supply chains this year. Higher prices for memory chips, driven by enterprise demand for artificial intelligence hardware, forced Nintendo to raise the retail price of the Switch 2 console.

    Retail buyers now face a more cautious consumer base. Without an immediate pipeline of top-tier first-party games through the summer, store shelves saw console inventory move at a noticeably slower pace than during the record-breaking 2025 launch cycle.

    Divergence Across Tokyo Tech Giants

    The consumer electronics divide widened between Japan’s two premier entertainment hardware makers this quarter. Sony upgraded its full-year earnings outlook to 1.33 trillion yen, powered by games, theatrical releases and music distribution.

    Sony recorded a 44 per cent jump in second-quarter net profit to 449.6 billion yen. While Sony benefited from favourable foreign exchange rates and box office contributions from titles like Spider-Man: Brand New Day, Nintendo remained exposed to single-platform hardware dependency.

    For consumer tech merchants across Asia, Nintendo’s numbers indicate that price increases on maturing hardware require immediate software drivers to sustain floor traffic. Sony gains additional momentum heading into November with third-party software releases, whereas Nintendo must rely heavily on its internal intellectual property catalog to protect device sell-through.

    Holiday Software Push

    Nintendo is turning to legacy catalog revivals to rebuild retail engagement ahead of the critical shopping season. The company rolled out a remake of The Legend of Zelda: Ocarina of Time to coincide with the franchise’s 40th anniversary.

    The title registered a Metacritic score of 96 out of 100 on the eve of release. Management intends to tap the existing hardware base to generate recurring digital revenue while software sales recover.

    Full-year net profit guidance remains unchanged at 310 billion yen. Retailers and suppliers will measure holiday checkout volumes against that target as shopping campaigns open across regional markets.

  • Coles Falls Behind Rival Woolworths as Sales Grow 2.2 per Cent

    Coles Falls Behind Rival Woolworths as Sales Grow 2.2 per Cent

    Coles Group booked first-quarter revenue of $11.2 billion, trailing primary rival Woolworths as shoppers cut spending across grocery aisles.

    Total sales rose 2.2 per cent year-on-year for the opening quarter of fiscal 2027, falling short of the 4.7 per cent expansion delivered by Woolworths over the same stretch.

    Supermarket Volumes Under Inflationary Squeeze

    Supermarket operations at Coles lifted 2.7 per cent on a comparable basis, an outcome that lagged domestic price rises. Headline inflation hit 4.3 per cent in the twelve months through September, according to data from the ABS. With grocery price tags climbing faster than overall register revenue, underlying sales volumes shrank across the store network.

    Customers managed stretched household budgets by splitting their weekly grocery shopping across multiple chains. Shoppers pursued weekly promotions, relied more heavily on loyalty incentives, and selected store-brand goods over premium labels. Leah Weckert, managing director and chief executive of Coles Group, pointed to structural shifts in weekly shopping habits across the country.

    “While supermarket sales growth remained in line with the prior quarter, we know household budgets are under pressure, and customers are shopping more deliberately across retailers and channels,” Weckert said.

    Digital Channels Outpace Physical Stores

    E-commerce delivered the fastest sales momentum across the business, rising 22.9 per cent during the three-month period. Digital grocery orders proved popular among households seeking to monitor running totals and avoid impulse purchases at the shelf edge. The private label range Exclusive to Coles also added sales volume as shoppers turned away from costlier branded goods.

    Elevated operating expenses offset that digital expansion. Coles informed market analysts that higher diesel and transport fuel costs pushed distribution overheads higher across its supply chain. Regional geopolitical tension added shipping volatility, limiting the earnings use the retailer could extract from top-line revenue gains.

    The Margin Gap Widens Between Chains

    Woolworths established a clear sales advantage by generating $19.4 billion during the corresponding quarter. Capturing 4.7 per cent revenue growth allowed the largest grocer to absorb fixed supply chain costs more effectively than Coles. Scale provides Woolworths with superior margin protection when negotiating trade discounts from food manufacturers and logistics contractors.

    Coles faces tough commercial trade-offs leading into the peak December quarter. Matching Woolworths on promotional discounts risks sacrificing retail gross margin, while leaving prices unchanged risks surrendering foot traffic to rival stores. Price competition will compress supplier rebates across fresh produce and packaged groceries through the end of the year.

    Earlier Performance and the Road to December

    Supermarket sales growth tracked at the same modest level recorded during the prior quarter. Household wallets tightened through winter as high interest rates and elevated electricity tariffs reduced discretionary household expenditure across metropolitan areas.

    Focus shifts to the Christmas trading stretch, which historically accounts for the largest share of annual grocery operating profits. Coles plans to adjust its promotional pricing program over the coming weeks to defend customer retention before the half-year fiscal 2027 audit.

  • Prada Holds Organic Revenue Growth at 1% as China Foot Traffic Softens

    Prada Holds Organic Revenue Growth at 1% as China Foot Traffic Softens

    Prada reported a 1 per cent rise in third-quarter organic revenue, keeping group sales steady despite footfall drying up across shopping centres in mainland China.

    Total group revenue reached €1.49 billion including newly acquired Versace, matching analyst consensus estimates compiled by Visible Alpha.

    Organic calculations exclude Versace, which Prada purchased in December last year. Management reported that the integration of the fashion house remains on track ahead of the runway debut of Pieter Mulier, the label’s incoming creative director, scheduled for next year.

    Mainland Footfall Drags on Asia-Pacific Margins

    Sales across the Asia-Pacific territory held flat during the three months. Foot traffic in mainland Chinese luxury malls remained subdued, forcing the group to rely on gains in secondary Asian markets to keep regional top-line figures level.

    The stagnation in greater China tests the regional retail model. Landlords have leaned heavily on premium fashion houses to anchor luxury malls, yet conversion rates are slipping as aspirational consumers pull back.

    Luxury brands face an unforgiving margin squeeze when foot traffic drops in Chinese flagship units. High retail rents and store operations negotiated during peak post-lockdown trading now run against lower volumes, leaving operators to depend on high-net-worth VIP clients rather than walk-in demand.

    Miu Miu Momentum Moderates

    Miu Miu recorded a slower pace of expansion in the third quarter after driving the bulk of Prada’s total organic revenue lift throughout 2025. The brand had previously outpaced the flagship label by wide margins, drawing younger consumers across East Asia with viral accessories and footwear lines.

    Outside Asia, trading patterns diverged sharply. North American operations delivered continued top-line gains, though at a milder pace than in the second quarter, while European sales remained weak.

    “The third quarter unfolded against a particularly challenging industry backdrop. In this context, the Group showed good resilience, underpinned by brand desirability and strong retail execution”, Chief Executive Andrea Guerra said in a statement.

    Integration Roadblocks and What to Watch

    Prada entered the current quarter after completing its takeover of Versace late last year, an acquisition aimed at building a multi-brand Italian conglomerate to counter French luxury groups. Absorbing that business while Asian demand cools raises operational risks across retail networks.

    Attention now shifts to the commercial reception of Pieter Mulier’s first Versace collection next year, which will show whether the enlarged group can generate wholesale and direct-to-consumer momentum outside the core Prada nameplate.

  • China NEV Retail Sales Forecast at 1.07 Million in October

    China NEV Retail Sales Forecast at 1.07 Million in October

    China new energy vehicle retail sales are expected to reach roughly 1.07 million units in October, down 16.5 per cent year-on-year, according to a report released on Friday by the China Passenger Car Association. The decline extends a prolonged cooling period in the automotive market.

    Total passenger car retail volume across the country is projected to drop 28.9 per cent to 1.6 million units over the same period, deepening an annual slide from September’s 28.0 per cent fall. While new energy vehicle retail penetration remains high at an estimated 66.9 per cent, market share dipped by 0.1 percentage points from the record 67.0 per cent achieved in September.

    CPCA analysts noted that traditional seasonal sales boosts have weakened significantly, leaving overall demand sluggish despite high adoption rates for electric and hybrid models.

    Holiday Traffic Fails to Sustain Dealership Momentum

    Showroom traffic rose briefly during the National Day holiday in early October before dropping sharply across major dealership networks. Accumulated holiday orders lifted average daily retail sales to 58,000 units during the second week of the month, but daily volume slumped to 47,000 units by the third week.

    The association projected average daily sales to stabilize around 49,000 units in the fourth week as third-quarter vehicle launches clear delivery backlogs. A final month-end push is expected to lift daily transactions to 79,000 units in the fifth week.

    Between October 1 and October 18, actual passenger NEV retail sales reached 520,000 units, reflecting a 13 per cent drop compared to the same period in 2025 and a 2 per cent decline from September.

    Target Shortfalls and Price Discipline

    An early October survey of automotive manufacturers found that most leading brands achieved less than 60 per cent of their annual sales targets during the first three quarters of 2026. Automakers have grown increasingly cautious regarding final-quarter volume growth.

    Dealer profitability concerns and industry efforts to prevent excessive discounting have restricted further price reductions. Retailers are turning to defensive inventory strategies rather than using heavy dealer-subsidized promotions to generate turnover.

    High pump prices continue to drag on traditional gasoline vehicle sales, keeping consumer preference tilted toward electric and plug-in hybrid alternatives. Even with sustained consumer interest, longer stretches between product debuts, order books, and physical deliveries have stretched purchase cycles.

    Slowing Momentum Across the Sector

    The October forecast reflects a retail market struggling to generate organic foot traffic after aggressive promotional cycles in earlier quarters. Electric vehicle adoption in China has largely stabilized at two-thirds of all passenger retail sales, leaving volume expansion dependent on overall car market recovery rather than pure conversion from combustion engines.

    Retail operators face margin compression as showroom overhead persists while unit sales drop across combustion and electric formats alike. Automotive distribution groups that borrowed heavily to expand exclusive EV brand showrooms must now navigate lower throughput without relying on steep factory-backed consumer rebates.

    Nine Months of Contraction

    Retail sales for NEVs slipped 16.7 per cent year-on-year in September, marking the ninth straight monthly drop. Across the first nine months of 2026, cumulative NEV retail sales stood at 7.758 million units, down 12.8 per cent from the previous year.

    Year-to-date monthly data shows volume peaks in September at 1.084 million units and June at 1.007 million units, compared to much stronger monthly highs above 1.28 million units seen during late 2025.

    Car manufacturers now look to November delivery schedules and year-end showroom clearances to salvage annual volume commitments.

  • Asian E-Commerce Dominates Global Sales as China Hits 13 Trillion Yuan

    Asian E-Commerce Dominates Global Sales as China Hits 13 Trillion Yuan

    China recorded 13.09 trillion yuan in online retail sales of physical goods in 2025, cementing its position as the world’s largest digital market at roughly $1.82 trillion. Physical goods accounted for 26.1 percent of total national consumer retail spending, expanding 5.2 percent year on year.

    Total online transactions across China reached 15.97 trillion yuan when including digital products and consumer services. That scale leaves the world’s next largest digital economy, the United States at $1.23 trillion, well behind in overall volume.

    Asian Markets Pull Away in Scale and Growth

    South Korea generated 272 trillion won, or about $191 billion, across digital checkouts in 2025. Services comprised a heavy portion of that total, with food delivery contributing 15.3 percent and travel and transport booking taking 12.5 percent, leaving physical goods at less than $140 billion.

    Japan generated 15.2 trillion yen, roughly $100 billion, in physical product sales online during 2024. That represented 9.8 percent of all Japanese merchandise sales, up from 9.4 percent a year earlier. Digital services and media expanded total Japanese consumer e-commerce to 26.1 trillion yen.

    India expanded faster than any of the mature East Asian retail hubs. Indian e-retail sales jumped roughly 20 percent to reach between $65 billion and $66 billion in 2025, driven by an online shopping pool that reached up to 300 million people.

    Southeast Asian Platform Volumes Climb 20 Percent

    Southeast Asia reached $191 billion across ten regional markets in 2025, according to e-Conomy SEA data. The six largest economies in the bloc generated $188 billion in gross merchandise value, up 20 percent on the previous year.

    Indonesia led the Association of Southeast Asian Nations with $71 billion in digital platform sales. Thailand posted $33 billion, while Vietnam booked $25 billion in gross merchandise volume. The Philippines and Malaysia followed with $24 billion and $20 billion, respectively.

    Fast logistics formats are accelerating that uptake across developing Asian retail markets. Quick-commerce operators promising deliveries under 30 minutes captured between 16 percent and 17 percent of all e-retail volume across India in 2025. Video-led selling channels similarly represented a quarter of all Southeast Asian digital transactions.

    The Balance Between Phone Checkouts and Store Networks

    Mobile checkouts dominate customer habits throughout the Asia-Pacific territory. South Korean shoppers conducted 211 trillion won of their purchases on mobile phones in 2025, securing a 77.6 percent smartphone share of total online retail spending.

    Japan saw smartphone orders for physical products climb 9.0 percent in 2024, advancing at more than double the pace of overall online merchandise turnover. Globally, mobile devices generate roughly 60 percent of online shopping turnover, creating sharper operational demands on checkout speeds and payment gateways.

    Physical store operators throughout Asia face diverging challenges depending on local channel maturity. In markets such as China and South Korea, where digital penetration sits near saturation, merchant acquisition costs are rising as brands shift budget toward buyer retention and targeted messaging. In India, where online transactions represent only 6 to 6.5 percent of gross retail receipts, traditional distribution networks retain considerable running room.

    Maturing Curves Reshape Capital Allocations

    Western benchmark markets illustrate the saturation ceilings facing Asian retailers. British online sales peaked at 30.7 percent during pandemic disruptions in 2021 before settling between 26.6 percent and 27.5 percent through 2025, suggesting a structural resistance band for pureplay e-commerce penetration.

    Chinese expansion rates reflect a similar cooling trend. Physical goods sales online across China grew 4.3 percent during the first eight months of 2026, moderating after a 5.2 percent rise in 2025. South Korean digital expansion dropped to 4.9 percent in 2025, marking the slowest annual increase recorded since current national accounting began in 2017.

    Regional platform operators now look toward second-tier cities and automated fulfillment to maintain transaction momentum. Projections from Bain and Flipkart place Indian online retail penetration at 10 to 12 percent of gross consumer spending by 2030, targeting a total market size between $170 billion and $180 billion.

  • Nick Scali ANZ Orders Drop 15 per Cent After Cyberattack and Market Slump

    Nick Scali ANZ Orders Drop 15 per Cent After Cyberattack and Market Slump

    Nick Scali has cautioned investors that first-half revenue across Australia and New Zealand will drop by approximately 11 per cent to 14 per cent compared to the prior corresponding period. The ASX-listed furniture retailer recorded a 15 per cent decline in first-quarter sales orders following a mid-August cyberattack and persistent weakness across its core consumer markets. That contraction contrasts with the first quarter of fiscal 2026, when sales climbed 11 per cent.

    The mid-August intrusion triggered “uncertainty and delays” for shoppers, the company stated at the time. Nick Scali alerted the Australian Cyber Security Centre and the Australian Federal Police, which subsequently investigated the security incident.

    By contrast, the company reported stronger momentum in the UK, where it entered the market through the acquisition of Fabb Furniture in 2024. Ongoing capital expenditure into renovating and expanding British stores helped lift written orders by 29 per cent year-on-year in the first quarter.

    The Cost of Three Weeks Offline

    The operational disruption began in mid-August when unauthorised parties breached internal systems and accessed customer names, addresses, emails and phone numbers. Nick Scali informed the Australian Cyber Security Centre and the Australian Federal Police to investigate the intrusion.

    Enterprise resource planning systems stayed offline for roughly three weeks. Store staff continued writing business manually while technicians contained the incident.

    Cleaning up the breach generated a $980,000 bill for legal advisers and forensic consultants. Management will classify those advisory expenses as non-underlying items rather than counting them against operating earnings.

    Contrasting Fortunes in Britain

    Nick Scali is finding better traction in the United Kingdom, where it acquired Fabb Furniture in 2024 to seed an offshore division. Written orders in the British network jumped 29 per cent year-on-year during the first quarter.

    Like-for-like sales across the UK estate grew 14 per cent. Temporary closures during store refurbishments accounted for the gap between total orders and comparable trade.

    Management plans to launch one new British showroom in late December as it refits existing Fabb sites under the core retail brand. The retailer continues to invest capital to convert British floorspace while protecting group gross margins and cutting administrative overhead.

    Diverging Paths for Bulky Goods Operators

    Big-ticket homeware merchants face a difficult climate as households cut discretionary outlays and housing market turnover moderates. Australian domestic demand has cooled under high interest rates, hitting furniture chains harder than nondiscretionary retailers.

    Retail landlords housing large-format showrooms also face reduced turnover rents and tougher renewal discussions.

    The contrast between Britain and the domestic market exposes the split in modern retail turnarounds. British consumers are taking to newly upgraded store concepts even in a flat economy, while Australian shoppers are staying away from domestic showrooms despite decades of brand loyalty.

    Shifting Consumer Spending Patterns

    The current slump follows an extended boom when post-lockdown home renovations drove furniture sales across Australia and New Zealand. That surge eventually ebbed into an Australian retail recession across 2023 and 2024 before stabilizing.

    Economic forecasts published in September projected national retail turnover growth to ease from 2.8 per cent in fiscal 2026 to 1.5 per cent in fiscal 2027. While that deceleration remains milder than the downturn seen two years ago, big-ticket home goods retailers face the steepest drop.

    Nick Scali operates 132 stores worldwide across its three geographic territories. Despite the order decline in Australasia, the retailer will open two new stores in Australia and New Zealand in late December alongside its British debut.

  • Australian Halloween Spend to Hit $510 Million as Shopper Numbers Drop

    Australian Halloween Spend to Hit $510 Million as Shopper Numbers Drop

    Australians will spend 510 million Australian dollars on Halloween costumes, decorations and confectionery this year, according to joint research from the Australian Retail Council and Roy Morgan.

    Total spending will edge up 2 per cent from 500 million dollars last year, trailing domestic inflation even as individual celebrants plan to spend more cash per basket.

    Around 4.4 million Australians plan to celebrate Halloween personally or through their children, down by 400,000 from 2025. National participation dropped to 18 per cent compared to 21 per cent twelve months ago. Those who do take part plan to spend an average of 117 dollars each, a 13.6 per cent increase of 14 dollars on last year.

    Higher prices offset shrinking crowds

    The spending expansion reflects elevated retail prices rather than organic volume growth across checkout counters. Household budgets remain squeezed by sustained borrowing costs and elevated utility bills across metropolitan and regional centres. Among respondents planning to celebrate, 62 per cent said they will keep outlays flat, 22 per cent plan to reduce spending, and 16 per cent plan to spend more.

    Participation split across gender lines shows 2.4 million women and 2 million men planning to mark the event, with both groups shrinking by 200,000 participants compared to 2025.

    Fleur Brown, chief industry engagement officer at the Australian Retail Council, pointed to broader household financial strains. “Those taking part plan to spend more on average, but fewer Australians are joining in this year,” Brown said.

    Young adults drive costume spend

    Younger shoppers between 18 and 34 years old represent the largest demographic cohort participating in the event. This group will spend an average of 134 dollars per person, generating approximately 200 million dollars in gross retail sales.

    Older demographics pulled back sharply. Participation among consumers aged 65 and over dropped six percentage points to 15 per cent. Engagement among shoppers aged 35 to 49 remained steady at 20 per cent, anchored by primary school children and family neighbourhood activities.

    State breakdown and category demand

    Geographic breakdowns show distinct divergences in consumer willingness to spend across eastern seaboard states. Victoria leads the country with the highest projected average spend at 136 dollars per person. Queensland follows at 120 dollars, while New South Wales trails at 109 dollars per person. Together, these three states account for 410 million dollars of total seasonal turnover, up 20 million dollars from last year.

    Merchandise demand concentrates heavily in consumable goods and short-use apparel. Providing treats for trick-or-treaters ranks as the top activity, cited by 45 per cent of participants, followed by dressing in costumes at 44 per cent. Door-to-door trick-or-treating accounts for 40 per cent of consumer plans, while 35 per cent plan to buy home decorations.

    Retail margins ahead of peak season

    For supermarket chains, discount department stores and specialty party suppliers, Halloween operates as the primary operational test run before the critical November Black Friday sales and Christmas peak trade. A Saturday timing provides logistics networks and brick-and-mortar stores clear foot-traffic opportunities, but compressed basket counts raise margin risks for retailers carrying excess themed inventory.

    The benchmark data stems from an SMS survey of 5,237 Australians aged 18 and older conducted between September 29 and October 3, 2026, sampling 877 active Halloween consumers. Merchants now look to inventory sell-through rates across October 31 to gauge consumer price tolerance ahead of final pre-Christmas stock orders.

  • China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    A broader economic slowdown in China has started weighing on LVMH’s core luxury fashion operations across key Asian retail hubs. Weak consumer confidence in the mainland market is curbing discretionary purchases for top-tier apparel and leather goods.

    Shoppers across tier-one Chinese cities are pulling back on aspirational luxury purchases, hitting store footfall and transaction values. The pullback directly affects revenue momentum across flagship fashion houses within the French conglomerate’s portfolio.

    Slowing Momentum in Mainland Stores

    Department stores and high-end shopping complexes in Shanghai and Beijing report softer traffic among local buyers. Domestic consumers who previously drove double-digit retail gains are deferring non-essential purchases or turning toward alternative spending categories.

    Footfall declines have spread into secondary luxury corridors where premium labels expanded floor space over recent years. Landlords operating high-end properties now face slower turnover across fashion and accessories concessions.

    Regional Shifts in Luxury Spending

    Part of the slowdown reflects Chinese travelers shifting luxury purchases abroad rather than buying in domestic boutiques. Currency differences in markets like Japan continue to divert transaction volume away from mainland counters.

    This spending diversion complicates inventory management for regional operators who stocked high volumes across Chinese city flagships. Operators must balance localized retail expenses against shifting consumer travel flows across East Asia.

    Pressure Across Fashion and Leather Portfolios

    Fashion and leather goods represent the largest profit engine for luxury conglomerates operating in Asia. When demand softens in mainland China, the impact spreads rapidly across broader regional wholesale and retail networks.

    Rival European luxury houses face identical headwinds as middle-class consumers reassess discretionary budgets. Price increases implemented over previous quarters have also met increased resistance from domestic buyers seeking value retention.

    Next Steps for Asian Retail Networks

    Luxury groups are reviewing capital spending on new boutique openings across Greater China. Attention is turning toward clienteling programs and exclusive VIP experiences to retain high-net-worth shoppers while mass-affluent spending remains subdued.

    Retail property owners and brand managers will track consumer footfall data through upcoming holiday travel seasons to gauge whether promotional initiatives can stabilize store volumes across the region.

  • Australian Malls Post AU$118.8 Billion in Turnover as Dining and CBDs Lead Recovery

    Australian Malls Post AU$118.8 Billion in Turnover as Dining and CBDs Lead Recovery

    Australian shopping centres generated AU$118.8 billion in turnover across 516 properties. Food retail, dining and central business district locations drove the post-disruption growth.

    Trading across 14.6 million square metres of gross leasable area and 46,743 tenants stabilized between 2025 and 2026, according to the latest Urbis Shopping Centre Benchmarks. Spending patterns shifted across categories and geographies.

    Dining and Jewellery Drive Tenant Gains

    Food catering delivered the strongest momentum across all centre categories, rising 7.5 per cent year-on-year. Food retail sales gained 6.9 per cent over the same period.

    Discretionary categories diverged. Jewellery sales jumped 11.6 per cent. Entertainment venues rose 8.8 per cent, and retail services advanced 6.2 per cent. Non-food mini-majors expanded sales by 7 per cent. That segment benefited from apparel brands like Uniqlo taking over floor space previously held by traditional department store anchors.

    Central Precincts Outpace Outer Suburbs

    Downtown centres recorded the strongest geographic performance, lifting retail sales by 7.1 per cent. Super-regional malls followed at 5.0 per cent.

    Outer metropolitan centres trailed the national recovery, posting sales growth of 3.9 per cent despite recording the fastest residential population expansion. High mortgage rates and debt servicing costs curtailed spending in suburban family corridors.

    Shifting Floorplates Across Asia-Pacific

    Landlords across Asia-Pacific are cutting department store allocations. They favour high-turnover fast fashion and experiential dining instead. Australian figures confirm that food and beverage tenancies now anchor footfall better than general merchandise.

    Risks remain concentrated in outer suburban assets. If mortgage stress persists, neighbourhood and suburban centres heavily reliant on mass apparel and homewares will face occupancy pressure unless they rebalance toward essential services and food concepts.

    Stabilisation After Years of Pressure

    The 2026 benchmark results follow multi-year trading disruptions marked by rapid interest rate hikes and inflation across the Australian consumer economy. Comparable mall performance over the 2025 to 2026 window points to normalising floor productivity across major retail hubs.

    The shift towards experiences and in-centre consumption also shows the growing social role of shopping precincts and is helping centres remain resilient as e-commerce continues to expand

    Operators now enter the next leasing review cycle with vacancy rates tightest in prime CBD strips and regional assets. Upcoming leasing negotiations will test tenant margins against rising operational costs.

  • Superfan Spending Boosts Japan Annual Retail Turnover by 2%

    Superfan Spending Boosts Japan Annual Retail Turnover by 2%

    Superfan spending across Japan lifted the country’s annual retail turnover by 2 per cent, according to figures highlighted by Rick Kelsey on BBC Business Daily on 12 November 2025.

    Economists credit the surge to oshikatsu, the dedicated fan culture of spending money and time to support idols through merchandise, concerts, and streaming, with helping pull retail sales out of a long slump.

    How Superfans Drive Everyday Retail

    The practice stems from the Japanese verb osu, meaning to endorse or support, which evolved into a noun during the 2000s across domestic idol and anime communities. Today, the behaviour extends far beyond live entertainment venues into everyday high-street retail, convenience stores and food service.

    Consumers regularly purchase acrylic character stands, plush toys, key chains and branded photo cards designed to be carried and photographed in daily settings. Food and beverage operators capture direct spend through collaboration menus, where cafes offer themed items linked to character birthdays, anniversaries and content releases.

    Retailers also capture revenue through dedicated colour-coded apparel, accessories and travel packages tied to anime pilgrimages, where fans visit real-world locations featured in specific series.

    What the Shift Means for Store Operators

    For department stores, convenience chains and shopping centre landlords across Japan, the commercial impact alters basic merchandising strategy. Conventional retail relies on broad demographic appeal and seasonal discounting, but fan-driven retail operates on high price tolerance and non-negotiable loyalty to specific intellectual property.

    Operators that secure exclusive licensing rights and limited-run character merchandise generate immediate foot traffic without heavy promotional markdowns. The risk sits entirely in inventory timing and intellectual property selection, because secondary-market saturation or sudden shifts in fan interest leave unpartnered stock stranded on store shelves.

    Supply Chains Adapt to Collectibles Demand

    Capsule toy machines and blind-box collectibles have expanded floor space in major transit hubs and suburban malls to monetise this demand. Manufacturers now design goods specifically for social sharing, turning consumer photography into free marketing that drives secondary store visits.

    Domestic retailers increasingly structure product launches around character calendars rather than traditional shopping holidays. This predictable cadence gives suppliers steady manufacturing runs for small-format plastics, novelty textiles and packaged food collaborations throughout the year.

    From Niche Subculture to Economic Driver

    A 2024 academic study tracking linguistic use documented how the term transitioned from subculture slang in the early 2000s into a mainstream commercial category embraced by corporate marketing desks. What began as fan-club subscriptions and physical compact disc sales now spans digital streaming support, interactive virtual creators and cross-category retail licensing.

    Department store groups in Tokyo and Osaka that previously cut floor space for youth apparel have rebuilt those areas into rotating pop-up zones for licensed goods. The strategy mirrors broader structural changes across Asian consumer markets, where experiential and identity-driven purchases consistently outpace generic consumer staples.

    The Next Test for Fan Consumption

    Retail analysts are watching upcoming quarterly sales prints from major Japanese department store operators and convenience chains to determine whether the 2 per cent turnover lift holds against broader inflationary pressures on household budgets. Corporate earnings releases scheduled across the next reporting cycle will show whether licensed collaboration margins continue to outpace traditional retail lines.

  • GS25 Sales to North American Shoppers Jump 131 Percent

    GS25 Sales to North American Shoppers Jump 131 Percent

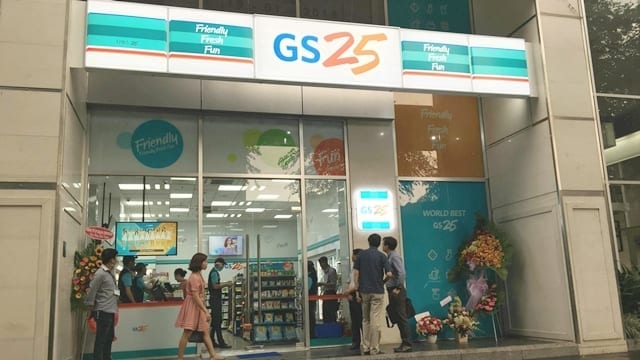
    GS Retail recorded a 131 percent jump in sales to North American visitors at its GS25 convenience stores in South Korea during the first eight months of the year.

    The surge pushed North American shoppers to roughly 30 percent of total foreign customer sales across the network. That leaves them just 10 percentage points behind visitors from Greater China, who continue to hold the largest foreign share at approximately 40 percent.

    Buying beer instead of banana milk

    Spending patterns between the two visitor groups show a sharp split in basket composition. North American customers spend primarily on canned beer, wine and spirits, alongside sports drinks, energy drinks and sodas, spending more on canned beer than any other overseas group. Shoppers from Greater China buy dairy products, instant noodles and baked goods, where blueberry Greek yogurt recently overtook banana milk as the top-selling item.

    Geographic data highlights a similar divide in where travellers spend. Greater China tourists stay clustered around traditional shopping hubs and downtown districts in Seoul, Busan and Jeju Island. North American footfall has concentrated heavily along coastal resort corridors.

    East coast sales outpace Seoul hubs

    Regional revenue from North American buyers saw its fastest expansion in Gangwon Province, where sales climbed 338 percent year on year. The bulk of that volume settled along the province’s beach-lined east coast, driven by seasonal leisure travel.

    For convenience operators in South Korea, this geographic and product divergence changes how individual franchise locations must manage inventory during peak travel seasons. Stores in coastal resort towns require alcohol distribution and cold beverage stock lines calibrated for Western preferences, while urban transit hubs must protect shelf space for packaged snacks and fresh dairy popular with Chinese tour groups.

    GS Retail and rival chains such as CU and 7-Eleven have spent years competing over inbound tourist wallets, yet historical strategies focused almost exclusively on Mandarin-language signage and group tour bus routes. A sustained shift toward Western independent travellers introduces higher margins on liquor and ready-to-drink beverages, but demands different localized marketing at the store shelf.

    Merchandising shifts across 1,000 stores

    Earlier network expansions set the groundwork for tracking foreign transaction data at the point of sale. GS25 introduced foreign card processing upgrades across its domestic estate over recent operating quarters, giving the chain real-time visibility into basket differences by issuing bank and country of origin.

    About 1,000 GS25 stores located in high-traffic tourist corridors have rolled out English-language promotional displays, recipe cards and product preparation guides this year. The company plans to use autumn purchasing data from coastal and metropolitan stores to adjust product distribution schedules ahead of the winter travel cycle.

  • Indian AC Volumes Surge over 25% Ahead of Festive Season

    Indian AC Volumes Surge over 25% Ahead of Festive Season

    Indian consumer demand accelerated during the July-September quarter, with air conditioner shipment volumes surging more than 25 per cent year-on-year, according to manufacturers.

    Sales of refrigerators and washing machines grew 13 to 14 per cent, while departmental store chain Lifestyle and market researcher Bizom tracked strong momentum across apparel and consumer goods.

    Volume gains outpace price rises

    Godrej Enterprises Group business head Kamal Nandi said festival demand expanded in double digits across Independence Day, Onam and Ganesh Chaturthi, noting that retail channels held over a month of stock at earlier prices to absorb recent hikes.

    Branded apparel revenue climbed more than 12 per cent during the three-month stretch. Early discount events, including Independence Day promotions in August along with regional festivals such as Onam and Ganesh Chaturthi, generated double-digit retail turnover across regional hubs.

    Department stores see tier-two traction

    Department store operators recorded steady foot traffic, led by non-metro locations where discretionary purchasing held up better than in the largest cities. Retailers cleared previous seasonal lines without heavy discounting, entering the festive calendar with lean inventory.

    “The July-September quarter was good with early double-digit sales growth and strong single-digit same-store growth,” said Devarajan Iyer, CEO at departmental store chain Lifestyle.

    Lifestyle reported that inventory levels of older lines remained restricted, allowing fresh merchandise to command full retail margins across department store networks.

    Grocery baskets show mixed momentum

    Fast-moving consumer goods recorded a value expansion of roughly 9 per cent through the quarter, according to data from retail analytics provider Bizom. Packaged food categories outpaced home care and personal hygiene products by a wide margin.

    Beverages, packaged groceries, confectionery, dairy products and commodities posted value gains between 10.8 per cent and 16.4 per cent from June through September. Personal care and household goods moved at a single-digit rate, showing that shoppers prioritized immediate food consumption over non-perishable refills.

    Macro tailwinds and monsoon risks

    Macroeconomic indicators provided support for consumption, with Indian gross domestic product expanding 7.8 per cent during the fiscal first quarter. Industrial output climbed 8 per cent year-on-year in August, improving on the 7.4 per cent recorded in July.

    A 13 per cent overall monsoon deficit across 15 states and union territories presents the primary risk factor for agricultural income and late-season rural demand. Consumer goods companies are now tracking whether rural sales channels match urban momentum as Diwali distribution cycles close out in October.

  • South Korea Retail Sales Fall 1.8% as Auto Output Plunges in August

    South Korea Retail Sales Fall 1.8% as Auto Output Plunges in August

    South Korean retail sales dropped 1.8 percent in August from the prior month, dragged down by sharp pullbacks in automobile deliveries and durable goods spending.

    Industrial production contracted 1.3 percent over the same period while facility investment tumbled 9.5 percent, marking the first simultaneous decline across all three economic measures since May.

    Data released by the Ministry of Data and Statistics showed mining and manufacturing output fell 4.8 percent, driven by a 24.8 percent slide in automotive production. The drop in vehicle manufacturing was the steepest single-month decline recorded since May 2020, when output collapsed 34.9 percent during early pandemic disruptions. Component suppliers absorbed direct hits, with rubber and plastic sector production dropping 11 percent as tire orders shrank.

    Auto production slide hits retail

    Auto assembly lines faced dual disruptions during the month from concentrated plant shutdowns and earlier labor actions. Assembly lines slowed after worker walkouts in July interrupted delivery schedules, while domestic automakers clustered annual plant maintenance and worker holidays into August rather than spreading them across two months.

    “In July, workers at some automakers staged strikes, which partly affected output in August. While summer vacations were previously spread across July and August, they were concentrated in August this year.”
    Lee Doo-won, Senior Statistics Official, Ministry of Data and Statistics

    The manufacturing shortfall moved straight through the supply chain into retail showrooms. Recreational vehicle shipments took the largest hit, leaving dealerships short on inventory and curbing consumer purchases of high-ticket items across the country.

    Durable goods lead consumer pullback

    Consumer spending across retail channels showed deep divergence by category. Durable goods sales, which include passenger cars and large household purchases, dropped 4.5 percent month on month. Non-durable goods, covering everyday consumer items such as cosmetics, fell 1.6 percent.

    Softlines provided limited relief against the wider consumer retreat. Sales of semi-durable goods, including apparel and footwear, rose 0.4 percent as seasonal autumn fashion collections entered stores. Total wholesale and retail trade output still finished down 0.7 percent for the month.

    Factory spending drops across sectors

    Capital expenditure among Korean businesses saw severe cutbacks led by fleet and transport orders. Facility investment dropped 9.5 percent in August, driven by a 32.8 percent contraction in transportation equipment procurement.

    General factory equipment investment showed modest resilience despite the broader slide. Machinery investment grew 1.6 percent, and machinery output rose 3.1 percent over the month, though the gains failed to offset the heavier drop across mobility hardware.

    Service sector provides isolated cushion

    Services output expanded 0.5 percent in August, preventing a steeper fall in headline gross output. Gains centered heavily in the information and communication sector, which expanded 4.7 percent to offset contractions in wholesale distribution channels.

    The August figures follow an uneven recovery cycle where strong technology and semiconductor demand masked softer domestic consumer sentiment. Automotive manufacturing normalization in September and third-quarter earnings from major carmakers will show whether the production slump was purely seasonal or reflects softer vehicle export orders.

  • LVMH Stock Falls 40 per Cent as Asia Demand Slows

    LVMH Stock Falls 40 per Cent as Asia Demand Slows

    LVMH Moët Hennessy shares have dropped 40 per cent year to date, touching six-year lows. Luxury demand weakened across key consumer markets in Asia and the United States.

    The sell-off erased 11 per cent of the French group’s market value in September alone. Shoppers pulled back across mainland China and western retail hubs.

    Valuation drops below historical averages

    LVMH now trades at a forward non-GAAP price-to-earnings multiple of 15.8 times. Its five-year historical average sits at 22.4 times.

    Valuation multiples compressed across the sector as high interest rates, inflation and geopolitical tensions cut into discretionary budgets. Institutional buyers have stayed cautious about near-term revenue trajectories.

    Asia ex-Japan pressure mounts

    The United States and Asia ex-Japan together generate nearly 54 per cent of total revenue for the Paris-based conglomerate. Weakness across both territories leaves the group exposed to broader retrenchment.

    Chinese shoppers spent less on high-end leather goods, spirits and watches over recent quarters. Foot traffic in tier-one city flagship stores slowed down. Regional travel retail failed to fill the gap.

    Operating margins face structural shift

    For department store operators and prime landlords across Asia, the valuation slide signals leaner wholesale orders and tougher lease renegotiations. Luxury houses spent three years opening stores and raising prices across Shanghai, Hong Kong and Singapore.

    That pricing power has hit a ceiling. Group brands now face tough inventory decisions, particularly in fashion, leather goods and cognac segments where excess stock demands discounting or production cuts.

    Slowing momentum across core divisions

    Growth rates across the sector slowed early this year after record post-pandemic sales volumes. Consumer sentiment worsened rather than stabilized as property and labor market pressures persisted in mainland China.

    Investors are tracking whether the group can protect gross margins without heavy promotional discounting in regional department stores. Third-quarter organic revenue from Asia ex-Japan will be the critical figure when the next quarterly results arrive.