Tag: shopping malls

  • Thailand Luxury Market Outpaces Singapore as Gen Z and Pop Culture Drive Sales

    Thailand Luxury Market Outpaces Singapore as Gen Z and Pop Culture Drive Sales

    Thailand has overtaken Singapore as Southeast Asia’s fastest-growing luxury market, led by surging demand from domestic Gen Z consumers and entertainment partnerships.

    High-end fashion houses are shifting resources and marketing budgets toward Bangkok as spending by younger Thai demographics outpaces historic regional benchmarks.

    Pop Culture Powers Store Footfall

    Luxury labels have accelerated brand ambassador appointments across both Korean and Thai entertainment industries. Global houses such as Dior, Gucci and Prada now regularly sign Thai actors and musicians, commonly grouped as T-pop talent, alongside established K-pop idols to front regional campaigns.

    These endorsements convert directly into store traffic across Bangkok’s prime shopping corridors. Flagship boutiques in malls such as Siam Paragon, IconSiam and EmSphere report elevated sales of ready-to-wear lines, leather goods and fine jewellery purchased by shoppers under 30.

    Regional Retail Balances Shift to Bangkok

    Singapore long served as the default gateway for luxury groups entering Southeast Asia, relying heavily on international business travellers and high-income expatriates. Bangkok, by contrast, combines resilient domestic demand with a rapid rebound in regional tourist arrivals from across Asia.

    Major European luxury groups are now expanding floor space in central Bangkok developments and revamping VIP salons rather than relying solely on Singaporean outposts. The shift marks a broader recalibration toward markets where pop culture fandom directly drives retail transaction volumes.

    Luxury brands will monitor upcoming mall completions along Bangkok’s Sukhumvit and Ploenchit corridors through 2024 to determine whether new retail square footage matches high-end consumer absorption rates.

  • SM Supermalls Revenue Rises 8% to $667M on Record Occupancy

    SM Supermalls Revenue Rises 8% to $667M on Record Occupancy

    SM Supermalls lifted first-half revenue by 8 per cent to US$667 million across the Philippines as mall occupancy reached a record 96 per cent.

    Same-store sales rose 4.8 per cent to 41.8 billion Philippine pesos during the six-month period, driven by steady foot traffic and resilient food spending.

    Vacant floor space dropped to 4 per cent across the network, with the operator attributing most empty units to planned tenant relocations rather than lease cancellations. President Stephen Tan said shoppers have grown more deliberate about where they spend, favouring better quality and experiential formats over basic discount hunting.

    Casual dining led tenant performance, according to executive vice president for marketing Joaquin San Agustin, who noted that trading held steady across nearly all retail categories.

    Shifting space from apparel to leisure

    To keep mall floors full, the group is reallocating square footage away from traditional apparel racks toward sports, entertainment and social concepts. Recent additions include pickleball courts, running hubs, food halls, game parks and combined dining-and-gaming venues.

    “A mall can’t stay the same,” Tan said. “You have to keep introducing new tenants and new experiences to keep customers coming back.”

    Across Southeast Asia, mall operators face a split market. While department stores in older suburban centres lose ground to online shopping, dominant prime developers in the Philippines, Indonesia and Thailand are converting excess retail capacity into recreational destinations to protect dwell times and rental yields.

    Provincial expansion pipeline

    Growth is now concentrated outside the capital. The company opens SM Nuvali in Laguna this November, installing the country’s first direct-view LED cinema screen to replace traditional projection booths.

    Further openings scheduled in the pipeline include new regional developments in Tagum, General Trias, Bohol and Malolos.

  • Philippine Mall Rents Reach P1,783 per Sqm as Retail Real Estate Leads Market

    Philippine Mall Rents Reach P1,783 per Sqm as Retail Real Estate Leads Market

    Philippine retail rents rose 1.4 percent year-on-year to 1,783 pesos per square meter a month in the second quarter of 2026, keeping prime shopping malls ahead of hotels and data centers.

    The property market absorbed 26,000 square meters of new space during the three-month period, according to JLL data, while quarter-on-quarter rents edged up 0.4 percent.

    Foot Traffic and Large Formats

    Physical mall visits remain the core driver of commercial retail space across the country. SM Supermalls logged 1.4 billion total visits in 2025, reaching 153 million in December when holiday crowds averaged 5.5 million visitors per weekend day and 4.6 million on weekdays.

    Operators continue to anchor their portfolios around these consumer flows. SM Mall of Asia spanned about 497,000 square meters of gross floor area by 2025, while competing networks from the Ayala group and grocery operators like Puregold hold steady tenant rosters in key commercial corridors.

    Supply Pipeline and Experiential Shift

    Across Southeast Asia, mall landlords have struggled with digital channel shifts, but Philippine operators have protected yields by converting floorplans toward dining, entertainment and social spaces. Cushman & Wakefield ranked retail ahead of hotels and data centers in the Philippine commercial real estate market in 2025, noting steady leasing demand from international brands entering prime locations.

    The sector faces an influx of new physical inventory before January, with developers scheduled to complete another 160,000 square meters of retail space by the end of 2026.

  • Regatta Opens Refreshed Flagship at SM Mall of Asia

    Regatta Opens Refreshed Flagship at SM Mall of Asia

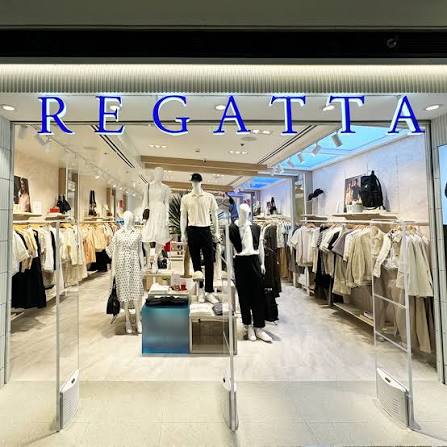
    Filipino lifestyle apparel brand Regatta opened a refreshed flagship store at SM Mall of Asia in Metro Manila, expanding its footprint inside one of the country’s largest retail centers.

    The store occupies space on the third floor of the South Main Mall, introducing an updated coastal retail layout paired with a new apparel sub-category.

    Inside the unit, merchandise is organized into dedicated product zones. A central accessories display carries lifestyle goods, including fragrances, headwear, drinkware, and towels, while an entire wall shows the retailer’s core polo shirt collection next to a customer lounge section.

    Athletic range expands casual lineup

    Alongside the store launch, Regatta introduced Regatta Sport, a product line targeting daily activewear. The collection includes quarter-zip pullovers, polo dresses, sweat shorts, lightweight nylon shorts, and jackets designed to bridge classic country club styling with functional athletic wear.

    The apparel rollout gives the brand broader coverage across technical fabrics and leisure categories as consumer demand for hybrid sportswear grows across Southeast Asia.

    Mall footprints anchor local brands

    Domestic apparel brands in the Philippines continue to renovate key metro flagships to hold floor space against competing international fast-fashion chains. High-traffic centers such as SM Mall of Asia serve as testing grounds for local operators seeking to expand product categories into lifestyle accessories and performance apparel.

    Regatta will monitor sales performance from the sports range at the South Main Mall location before rolling the inventory across its wider domestic store network in subsequent seasons.

  • Moshi Moshi Lifts First-Half Profit 21.5% as Thai Network Expands

    Moshi Moshi Lifts First-Half Profit 21.5% as Thai Network Expands

    Thai lifestyle retailer Moshi Moshi increased its first-half net profit by 21.5 per cent to 352.83 million baht, driven by new store openings and stronger gross margins.

    Operating revenue rose 17.3 per cent year on year to 1,654 million baht across the six months, keeping pace with management’s annual growth target of 15 to 20 per cent.

    During the second quarter, operating revenue climbed 17.2 per cent to 956.1 million baht, while net profit gained 20 per cent to 161.86 million baht. Gross margin widened 140 basis points to 56.4 per cent. Same-store sales grew 4.0 per cent in the quarter, building on a 15.2 per cent jump in the prior-year period.

    The company operated 218 stores at the end of June, an increase of 37 outlets over 12 months. Most of Thailand’s 76 provinces and Greater Bangkok now host at least one location. Management plans 35 net new store openings for the full 2026 financial year, having completed roughly half that target by mid-year.

    Inventory Velocity and Mall Pipeline

    Product turnover drives customer traffic across the chain’s 13 merchandise categories, which span stationery, beauty, plush toys, apparel and home accessories. Moshi Moshi manages an inventory catalogue of more than 25,000 stock-keeping units and releases approximately 1,000 new items every month at accessible price points.

    Physical malls remain the core sales channel. Key landlords Central Pattana, Central Retail’s Robinson lifestyle malls, Berli Jucker’s Big C, and CP Axtra’s Lotus’s offer about 500 commercial sites nationwide. The company is also opening stand-alone outlets near some of Thailand’s 150 universities, including a campus branch at Chulalongkorn University in Bangkok.

    Wholesale revenue, which represents 11 per cent of total turnover, expanded at a slower rate during the half. Disruption from bridge construction near Bangkok’s Platinum Fashion Mall cut pedestrian traffic and limited tour bus access to the company’s wholesale unit. Digital channels accounted for just 3 per cent of total sales across Shopee, Lazada and TikTok.

    Regional Competition and Overseas Targets

    Domestic mall coverage will eventually hit saturation as Moshi Moshi fills out second-tier provincial cities and campus locations. Maintaining double-digit annual sales growth beyond Thailand requires entering neighbouring Southeast Asian markets with matching demographics.

    Competitors are already securing positions across the region. Singapore-based lifestyle brand Oh!some operates stores in Cambodia across three Aeon malls in Phnom Penh, runs outlets in Hanoi and Ho Chi Minh City, and trades from three stores inside Bangkok. For Moshi Moshi, replicating its format in Vietnam, Indonesia and Cambodia represents the logical next leg of expansion once Thai site availability narrows.

    The company continues store renovations and floor-space expansions across its domestic mall network while tracking toward its target of 35 net new store additions by December 2026.

  • Robinsons Malls Adds Accessibility Upgrades Across Philippine Network

    Robinsons Malls Adds Accessibility Upgrades Across Philippine Network

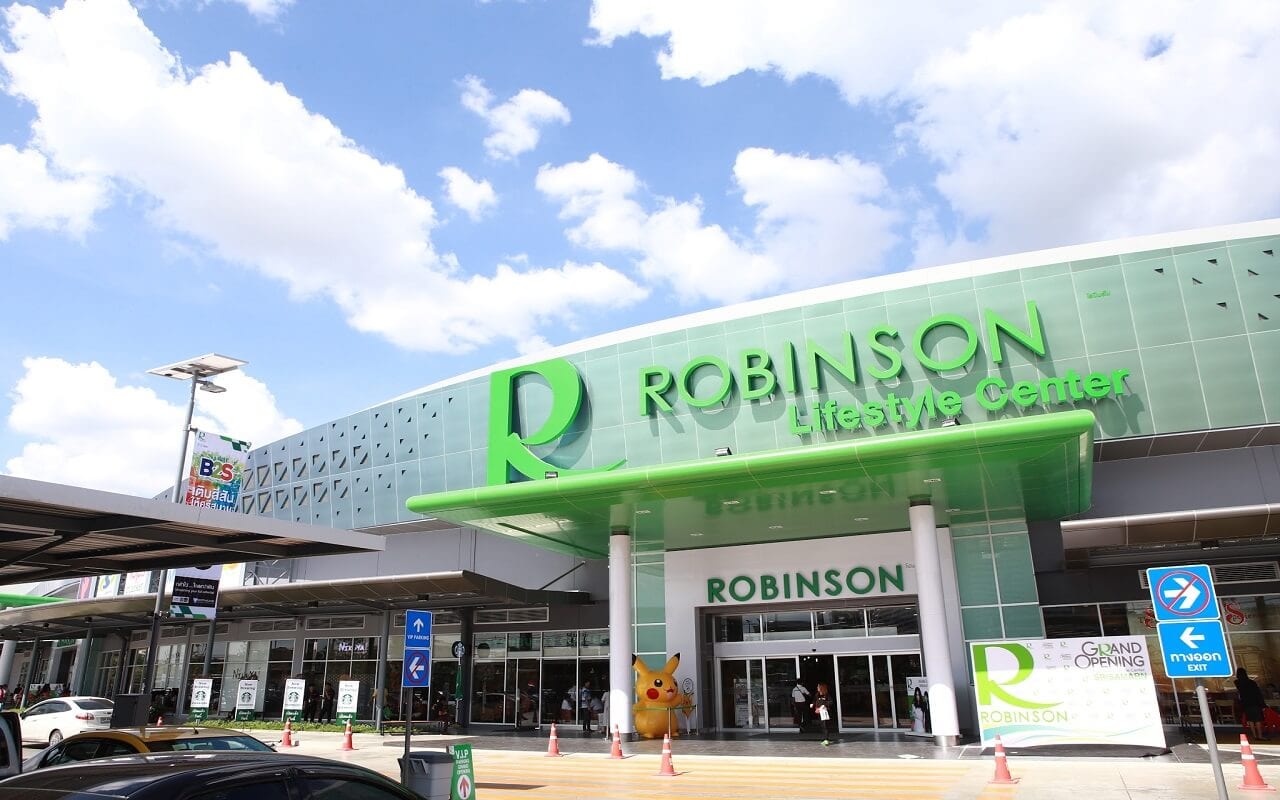
    Robinsons Land Corp. Is rolling out accessibility retrofits across its retail portfolio after Robinsons Las Pinas won a bronze award at the 31st Apolinario Mabini Awards. The recognition evaluated commercial premises on physical design adjustments and day-to-day facilities tailored for persons with disabilities.

    Organised by the Philippine Foundation for the Rehabilitation of the Disabled, the Mabini awards evaluate physical infrastructure, barrier-free pathways, operational assistance, and staff readiness across commercial properties. Robinsons Las Pinas took the Bronze Award in the Disability-Friendly Establishment category.

    Portfolio Retrofits and Building Standards

    Design teams at Robinsons Land Corp. Are adapting architectural layouts across existing properties to align with updated accessibility targets. The program covers ramps, accessible rest areas, dedicated parking bays, transit access points, and service counters designed for wheelchair users and visitors with mobility limits.

    Operational protocols also involve coordination with local community organizations and government agencies to ensure frontline mall personnel handle customer assistance requests correctly. Two other portfolio properties, Robinsons Magnolia in Quezon City and Robinsons Galleria South in San Pedro, Laguna, previously earned Mabini awards under similar operational audits.

    Commercial Footprint in Greater Manila

    Philippine mall developers face rising pressure to modernize older suburban assets as shopping centres evolve into community service centres handling government agencies, clinics, and everyday retail. Metro Manila shopping complexes compete intensely on basic convenience and universal access to retain family foot traffic.

    Property owners that neglect universal design risk losing footfall from multi-generational shopping groups, particularly as suburban transit links bring older shoppers and mobility-impaired visitors directly into retail corridors. Robinsons Malls plans to maintain these design standards as baseline criteria for upcoming renovations and new mall openings across regional provinces.

  • SM Retail Revenue Hits 223.6 Billion Pesos as Network Expands Beyond Manila

    SM Retail Revenue Hits 223.6 Billion Pesos as Network Expands Beyond Manila

    SM Retail posted first-half 2026 revenues of 223.6 billion pesos ($3.7 billion), up 5.6 per cent from a year earlier. Regional consumer spending gathered pace across the Philippines.

    Net income rose 6.0 per cent to 8.9 billion pesos ($270 million). Same-store sales grew 2.9 per cent across a nationwide network of 4,837 stores.

    Food and Speciality Stores Drive Turnover

    Food retail generated roughly 60 per cent of total sales across 2,824 points of sale. It rose 6.1 per cent with same-store gains of 3.3 per cent. SM Store, the group’s 79-location department store chain, grew revenue 3.2 per cent. Speciality store sales expanded 5.9 per cent, even after the operator closed a net 73 outlets to trim marginal locations.

    The company relies on an asset-light format by leasing space within sister developer SM Prime’s commercial properties. Of the 490 physical stores opened over the past year, 80 per cent sit outside Greater Manila. These target provinces where modern retail still represents less than half of household shopping spend.

    Mall Developer Backs Bay Reclamation

    SM Prime lifted first-half revenue 5.3 per cent to 71.7 billion pesos ($1.2 billion). The developer operates 90 malls across the Philippines and nine in mainland China. Rental income provided more than 60 per cent of that total. Revenue from leisure facilities, including cinemas and ice-skating rinks, rose by more than 10 per cent during the same period.

    Expansion into secondary provinces mirrors retail decentralisation across Southeast Asia, where operators such as Central Group in Thailand and Vincom Retail in Vietnam build commercial centers ahead of rising provincial incomes. Remittances from overseas workers feed directly into these regional retail hubs. They underpin Philippine private consumption at 75 per cent of gross domestic product.

    Work continues on Pasay 360, a 360-hectare Manila Bay reclamation joint venture with local authorities. The project will expand the Mall of Asia complex with new commercial, hotel, and residential districts over multiple development phases.

  • Simon Property Group Revenue Jumps 20 per Cent as Retailer Leasing Surges

    Simon Property Group Revenue Jumps 20 per Cent as Retailer Leasing Surges

    Simon Property Group lifted second-quarter revenue by 20 per cent to US$1.79 billion as retailer demand pushed occupancy across its global portfolio to 96 per cent.

    The shopping centre landlord completed more than 1,200 lease deals during the three-month period, up 20 per cent year over year, with rent spreads on new leases gaining 17 per cent.

    First-half revenue reached US$3.548 billion, also up 20 per cent compared to the same period in 2025. Net after-tax income attributable to stockholders fell 13.1 per cent to US$483.1 million in the quarter, leaving first-half profit flat at US$962.7 million. Funds from operations totaled US$1.185 billion in the second quarter and reached US$2.293 billion across the first six months.

    Outlet conversions and tenant mix

    Average base minimum rent across the US properties rose 6.3 per cent to US$62.42 per square foot. The landlord is carving up approximately 1 million square feet of shuttered Saks Off 5th outlet space into smaller parcels, which chief executive Eli Simon said will lift rental revenue on those boxes from US$18 million to US$44 million.

    Leasing demand spanned athleisure, home goods, Gen Z apparel, and Asian beauty and collectables brands entering physical formats. Food and beverage operators form another core target, with incoming restaurant projects expected to generate between US$400 million and US$500 million in incremental sales across regional centres.

    Global footprint and Asia presence

    The company ended June with 175 malls and premium outlets in the United States, 16 Mills properties, and 42 international centres. Its Asian footprint comprises 19 locations, led by 10 properties in Japan and seven in South Korea.

    Asian outlet centres operated through joint ventures continue to capture cross-border retail traffic, serving as low-risk entry points for brands testing overseas demand without committing to high-street flagships. RetailNews Asia tracks how western mall operators increasingly count on Asian beauty, lifestyle, and character-merchandise concepts to fill medium-sized vacancies left by shrinking traditional apparel chains.

    Management allocated all first-half capital expenditure toward densification, hotel additions, and residential mixed-use redevelopments rather than new ground-up mall openings, with re-leasing work on the remaining outlet vacancies scheduled through 2027.

  • The highs and lows of Indian retail real estate in 2018

    The highs and lows of Indian retail real estate in 2018

    2018 saw further liberalization of FDI policies, repositioning Indian retail on the global investment map and attracting a large number of global retailers into the country. In H1 2018, private equity investments into Indian retail swelled to over US$ 300 million, denoting a bracing growth of 54 percent over the previous year.

    Worryingly or encouragingly (depending on one’s viewpoint) online retail also witnessed exponential growth in 2018. In fact, online retailing is now expected to be at par with physical retail over the next 5 years. With India positioned to become the world’s fastest-growing e-commerce market, online retail in the country is driven by robust investments and deepening internet penetration in the country.

    As per ANAROCK data, the top cities with significant retail growth in 2018 included MMR, NCR, Bengaluru and Hyderabad
    New retail supply in 2018 was limited to 5.1 mn. sq. ft.
    Interestingly, apart from the top metros tier 2 & 3 cities played a significant role in India’s retail growth story in 2018

    Saturation of the metros due to limited space availability, mounting rental values and escalating infrastructure issues fuelled retail growth in smaller cities like Ahmedabad, Bhubaneshwar, Jaipur, Lucknow, Thiruvananthapuram, etc. New malls that became operational in the smaller cities in 2018 range from anything between 200,000 to 18,00,000 sq. ft. in size, amply vouchsafing the increasing appetite for organized retail in the hitherto underserved cities.

    In response to the huge potential in these markets, both domestic and international brands made deep forays into them via the online route, followed by more gradual offline presence. This disparity is hard to ignore and sends out a clear signal to investors and mall developers – physical retail deployment must pick up considerable pace in these smaller markets in the coming years.

    Other Sunshine Sectors

    The logistics and warehousing sector transformed rapidly in 2018 after the Government granted the coveted infrastructure status to logistics in November 2017. In fact, warehouse stock supply is expected to see substantial increase over the next two years owing to implementation of GST, the Government’s determined infrastructure push and increased interest from national and international investors. Overall, strong economic fundamentals, proactive reforms and increasing use of technology will continue to boost the sector.

  • Chinese Think Tank Says 1/3rd of Mainland Malls to Close Within 5 Years

    Chinese Think Tank Says 1/3rd of Mainland Malls to Close Within 5 Years

    More bad news for China’s struggling brick and mortar retailers as a recent report from the Chinese Academy of Sciences and Social Sciences Academic Press predicted as many as one-third of all shopping centers in China will close their doors during the next five years.

    With ecommerce heavyweights Alibaba and JD.com dominating the retail sales, some of China’s largest mall operators are already feeling the pinch. Joy City Property and Maoye International posted profit warnings earlier in the year as buyers opt to shop online.

    Change Predicted for All Mainland Retail Centres

    The report by the respected central government think tank predicted change across the board for Chinese shopping centres, foreseeing that, in addition to the malls expected to close, another third will be transformed into experiential shopping centres, while the remaining third will adopt an online to offline (O2O) model that integrates the Internet with physical shopping.

    While two decades ago China had an undersupply of malls, the country has quickly overcome the deficit, with the mainland now home to 4,000 shopping centers — three times the US total. That population of malls is expected to grow to 10,000 by 2025, according to the CASS report. Research from JLL revealed 40 million square metres in new mall space is expected to enter the market between 2015 and 2017.

    Department stores in the country fared still worse than shopping centres, with sales growth contracting 0.7 percent during 2015, according to data from the Fung Business Intelligence Centre.Malaysia-based department store Parkson, which operates 59 outlets in China, announced it was selling assets to offset heavy losses in the country.

    Chinese Shoppers Swap Malls for the Internet

    Jack Ma big mouth

    Jack Ma’s ecommerce empire has been taking a bite out of China’s traditional retail sector

    According to Reuters, Suning, one of China’s largest retail chains, needed 12 months to bring in the same amount of sales that Alibaba’s Tmall website generated in two months. And while the electronics retailer is able to keep the lights on, others have not been so lucky.

    A total of 138 department stores, 262 supermarkets and 9,464 clothing stores closed in China between 2012 and 2015 according to data from the Business Economics Institute under Beijing Technology and Business University. That goes hand-in-hand with findings from the McKinsey Global Institute that showed ecommerce accounted for 20 percent of all clothing purchased and 15 percent of all household goods purchased in 266 cites in China.

    McKinsey predicts ecommerce marketplaces will bring in anywhere from $420 billion to $650 billion in sales by 2020. That is in stark contrast to the slowing sales physical retailers are coping with.

    Data from Fung Business Intelligence Centre showed there was 4.3 percent sales growth last year among China’s top 100 retail chain operators, the lowest total since 2007.

    Physical Stores Not Going Down Without a Fight

    While the mainland’s earth-bound retail sector has been taking a beating, not everyone is ready to give up. China Properties Group, a Shanghai-based developer which owns and operates the Concord City mixed-use project and the World Trade Plaza in Chongqing, took out a full page ad in the New York Times international edition late last year pleading with consumers to boycott online shopping.

    Other retailers are opting for a more modern way to fight back against China’s growing ecommerce sector.

    Of China’s top 100 retail chain operators, 83 currently have their own online stores in 2015. Of this number, 20 also have a mobile shopping app for consumers to use.

    “Physical stores should abandon the old model. They can use online shopping and WeChat to facilitate transactions and provide more convenient service,“ Hong Tao, director of the Business Economics Institute, proclaimed.
  • India malls turning friendly for the disabled

    India malls turning friendly for the disabled

    Malls are doing their bit to make the world a better place for people with disability. With Braille signage, wheelchair on call, disabled-friendly washrooms and specially allotted parking space, malls are looking to increasing footfalls by becoming more socially conscious.

    Interestingly, several States such as Maharashtra, Karnataka and Tamil Nadu have also asked mall managements to remove “infrastructure snags” and create a conducive environment for people with disabilities.

    According to the 2011 Census, the number of disabled in India is 26.8 million — 15 million men and 11.8 million women.