Tag: southeast asia

  • Graas Raises US$17 Million and Buys Trustana to Expand Retail AI Tools

    Graas Raises US$17 Million and Buys Trustana to Expand Retail AI Tools

    Singapore e-commerce technology platform Graas has raised US$17 million in fresh capital and completed the acquisition of product data company Trustana.

    The transaction brings Trustana’s catalogue and product intelligence software directly into Graas’s automated operating system for consumer brands across the region.

    Integrating Product Data

    Graas builds artificial intelligence software designed to optimize inventory, ad spend, and pricing decisions across digital marketplaces. Adding Trustana, an enterprise data startup initially incubated by Temasek, gives the combined entity deeper capability in structuring product catalogues and syndicating retail data across fragmented sales channels.

    Brand operators across Southeast Asia frequently run concurrent storefronts on Shopee, Lazada, TikTok Shop, and standalone web platforms. Managing product data across those channels remains one of the most persistent operational bottlenecks in regional digital commerce.

    Consolidation in E-Commerce Tech

    Software vendors across the region are consolidating capabilities as enterprise clients push to trim their technology vendor counts. Graas previously expanded its footprint by acquiring specialized marketing and logistics analytics companies across India and Southeast Asia.

    RetailNews Asia views the deal as a clear shift away from standalone point solutions toward unified enterprise software suites capable of running daily merchant operations autonomously.

    Integration of Trustana’s data pipelines into the Graas platform begins immediately, with the combined software suite scheduled for enterprise rollout over the coming quarter.

  • Rose All Day Cosmetics Secures US$5.41 Million Series A Round

    Rose All Day Cosmetics Secures US$5.41 Million Series A Round

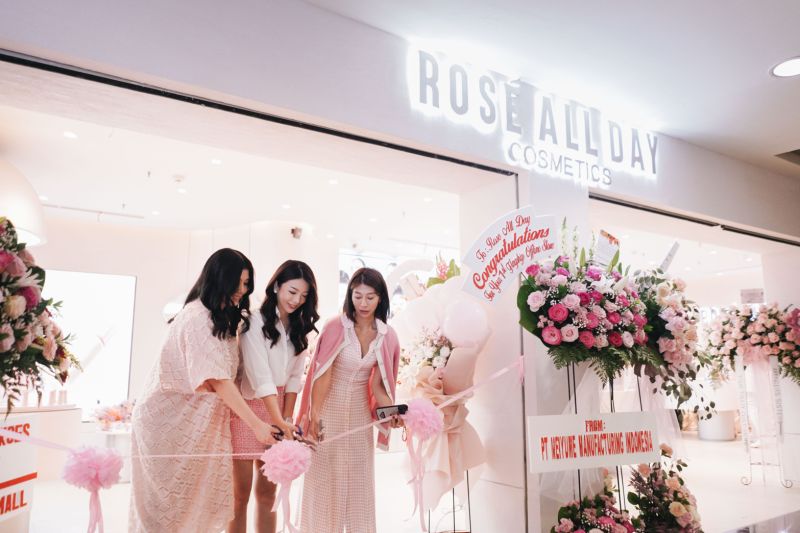
    Indonesian beauty brand Rose All Day Cosmetics raised US$5.41 million in a Series A funding round to finance its retail rollout and product line expansion. The company secured the financing as local cosmetics makers push for larger shares of Southeast Asia’s beauty and personal care market.

    The direct-to-consumer label plans to deploy the capital toward scaling its omnichannel retail footprint, improving product formulation pipelines, and bolstering distribution infrastructure across regional retail channels.

    Capital for regional distribution

    Founded to offer accessible daily beauty and skincare products, the brand built its initial customer base through online channels before expanding into physical retail counters, department stores, and beauty specialty chains. Direct-to-consumer beauty brands across Indonesia increasingly rely on physical shelf space to protect margins against rising digital acquisition costs.

    Offline distribution networks remain essential for consumer conversion in Southeast Asia, where physical storefronts and modern trade outlets still generate the bulk of personal care purchases. Securing shelf space in multi-brand retail chains gives local brands immediate access to foot traffic outside major metropolitan centres.

    Direct brand competition in Southeast Asia

    Venture investors continue backing local beauty startups in Indonesia, betting that domestic brands can defend domestic market share against legacy multinational operators. Similar consumer brand funding rounds across the region have targeted supply chain localization and regional export capabilities into neighbouring markets such as Malaysia and Vietnam.

    RetailNews Asia tracking shows that homegrown beauty labels in Jakarta face steepening competition for floor space in premium shopping malls and modern trade outlets. The next operational test for Rose All Day Cosmetics will be proving its unit economics across physical retail partners while managing regional inventory rollouts.

  • Asia-Pacific Takes 42.5 per Cent of Global E-Commerce Market Heading to $19.8 Trillion

    Asia-Pacific Takes 42.5 per Cent of Global E-Commerce Market Heading to $19.8 Trillion

    Asia-Pacific captured 42.5 per cent of the global e-commerce market in 2025, leading an industry projected to reach $19.83 trillion by 2035. The worldwide sector stood at $7.65 trillion in 2025 and is tracking toward $8.42 trillion in 2026, driven by mobile internet adoption and direct-to-consumer digital channels.

    China, India, and Southeast Asia anchored the regional share, outpacing North America at 24.3 per cent and Europe at 20.1 per cent. Electronics and media formed the largest single product category globally, generating $1.98 trillion in 2025, while fashion and apparel climbed at an 11.3 per cent annual rate.

    Mobile Checkouts and Direct Sales

    Consumer shift to mobile devices altered checkout dynamics across major platforms. Mobile internet access passed 5.5 billion users in 2025, pushing retailers to redesign storefronts around single-screen purchase funnels. Data from platform operator Shopify showed 73 per cent of transactions took place on mobile devices, helping reduce cart abandonment below 55 per cent.

    Brand-owned direct-to-consumer platforms generated $1.42 trillion in 2025, accounting for 18.5 per cent of total e-commerce revenue. Retailers spent more than $22 billion on artificial intelligence recommendation engines during 2024 to lift conversion rates by 15 to 25 per cent. Marketplace platforms retained the largest transaction volume, with projections pointing to 10.6 per cent annual expansion through 2035.

    For retailers across Asia, these numbers reflect a structural transition from basic marketplace storefronts to proprietary apps and conversational commerce tools. Brands that relied entirely on third-party aggregators five years ago are redirecting capital into unified backends that handle social shopping, mobile web, and offline inventories together.

    Payment Infrastructure and Regulatory Hurdles

    Instant payment networks accelerated transaction volumes throughout emerging markets. India’s Unified Payments Interface processed more than 14 billion transactions monthly by late 2024, while digital wallets accounted for over half of all online payments globally.

    Operating costs and compliance mandates continue to squeeze vendor margins. Last-mile logistics represented 41 per cent of total supply chain expenses, amplified by urban fuel and labor costs. Tightening data protection rules, including India’s Digital Personal Data Protection Act, added compliance expenses equivalent to two to five per cent of digital marketing budgets.

    Cross-border sellers now face tighter platform vetting as international agencies track counterfeit goods, which totaled $509 billion in worldwide trade. The next operational test comes as national customs authorities implement revised digital tax rules across regional trade corridors through 2027.

  • Shopee Monetises Marketplace Platform with Tiered Seller Fees and Paid Services

    Shopee Monetises Marketplace Platform with Tiered Seller Fees and Paid Services

    Singapore-based Shopee generates its core income from a multi-tiered marketplace model charging seller commissions between 1 and 6 per cent alongside payment and fulfillment fees across Southeast Asia.

    The platform, founded in 2015 by Forrest Li, reached 1.78 billion dollars in annual revenue during 2020 as it scaled past regional rivals to capture merchant transaction flows.

    Commission Structures and Paid Merchant Tools

    Standard marketplace merchants pay base commissions of 1 to 2 per cent per completed sale. Brands listed on the premium Shopee Mall tier face higher commission rates that climb to 6 per cent depending on the product category and transaction volume.

    Transaction processing adds another 2 per cent fee to cover payment handling. Merchants looking for wider reach buy search visibility through a cost-per-click advertising system, placing sponsored listings across product queries and feeds.

    Warehousing and shipping generate additional revenue through Fulfilled by Shopee, a proprietary distribution program that bills sellers on a per-item rate determined by package dimensions and weight.

    Ancillary Services and Regional Competition

    Beyond traditional retail transactions, the company captures payments revenue through its ShopeePay digital wallet. It also takes merchant commissions and consumer delivery fees on orders processed through its ShopeeFood division.

    The platform established market leadership over Alibaba-backed rival Lazada across Southeast Asia before launching localized operations in Latin American markets including Brazil, Mexico, Colombia, and Chile. RetailNews Asia tracks how marketplace operators in the region steadily adjust take-rates and ad loads as merchant competition tightens across core territories.

    Market watchers are monitoring whether Shopee can maintain seller retention across Southeast Asia while defending merchant margins against regional competitors.

  • Indonesian Trading App Ajaib Raises $270 Million from Japan SBI Holdings

    Indonesian Trading App Ajaib Raises $270 Million from Japan SBI Holdings

    Indonesian online stock trading platform Ajaib has raised $270 million in a Series C funding round backed entirely by Japanese financial services conglomerate SBI Holdings. The transaction delivers one of the largest single equity checks into Southeast Asian retail financial technology this year.

    The capital injection gives Ajaib substantial runway to expand its wealth management and retail brokerage offerings across Indonesia. Jakarta has become a competitive battleground for digital brokerages seeking to convert first-time millennial and Gen Z savers into active market participants.

    Japanese capital targets Indonesian retail investing

    SBI Holdings has built a wide investment portfolio across Asian digital finance, backing regional digital banks, payment rails and cryptocurrency infrastructure. The group led the round directly, cementing a deeper balance-sheet commitment to Indonesia’s domestic capital markets.

    Southeast Asian fintech funding endured two years of compressed valuations and selective dealmaking following the 2021 market peak. A single $270 million commitment signals that large strategic investors are once again willing to write late-stage checks for established market leaders with deep domestic distribution.

    Expanding product lines across domestic markets

    Ajaib launched in 2018 targeting first-time retail investors through mobile-first stock trading and mutual fund distribution. The platform grew quickly during Indonesia’s retail investing boom, securing unicorn status in 2021 before adding digital asset products and margin financing services.

    RetailNews Asia notes that rival platforms across Jakarta and Singapore are racing to consolidate wealth management, bond distribution and consumer credit onto single interfaces. Japanese institutional backers like SBI provide both long-term capital and potential product partnerships as Indonesian regulators tighten compliance requirements for digital asset brokers.

    The company will deploy the capital toward platform security, customer acquisition and new asset management products ahead of scheduled regulatory reviews in Jakarta.

  • Human Connection Remains Key Driver for Purchases in Southeast Asia Retail, Despite AI Growth

    Human Connection Remains Key Driver for Purchases in Southeast Asia Retail, Despite AI Growth

    Personal trust remains the most significant driver for consumer purchases across Southeast Asia’s US$219 billion market, even as artificial intelligence technologies become more prevalent. This human element is proving more influential than advanced technology in motivating buying decisions.

    Retailers and brands operating in the region are observing that customers prioritise relationships and reliable advice. This trend highlights the need for businesses to balance technological integration with strategies that foster genuine human connection and build consumer confidence.

    Trusting Human Connections

    Consumers in Southeast Asia are more likely to make a purchase when they have confidence in the people or businesses they interact with. This human-centric approach to commerce means that recommendations from trusted individuals, word-of-mouth, and established brand loyalty, often built through personal experiences, hold substantial weight. Businesses cannot solely rely on algorithmic recommendations or automated services to secure sales.

    RetailNews Asia regularly tracks how consumer behaviour in this diverse region is shaped by cultural nuances and evolving market dynamics. This focus on human trust mirrors similar findings in other Asian markets, where authentic engagement often translates into stronger customer retention and higher transaction values.

    Balancing AI With Personal Touch

    For retailers, the challenge lies in effectively integrating AI and other digital tools without eroding the trust built through human interaction. While AI can enhance efficiency, personalise experiences, and streamline operations, it should complement, rather than replace, the personal touch. Strategies might include using AI to free up staff for more meaningful customer engagements or to provide data-driven insights that help build better human relationships.

    The US$219 billion market in Southeast Asia is dynamic, with consumers increasingly sophisticated in their choices. Companies that successfully combine the convenience and intelligence of AI with the irreplaceable value of human connection are better positioned for sustained growth in this competitive landscape.

  • TikTok Shop Tracks Toward US$100 Billion in Global GMV by 2026

    TikTok Shop Tracks Toward US$100 Billion in Global GMV by 2026

    TikTok Shop is on track to surpass US$100 billion in global gross merchandise volume in 2026 as its social commerce format expands across Asia and Western markets.

    The projected milestone reflects steep annual transaction volume growth, driven by aggressive merchant acquisition in Southeast Asia and rapid adoption in the United States.

    Challenging Incumbents Across Southeast Asia

    ByteDance built TikTok Shop around short-form video feeds and live shopping broadcasts, funneling consumer traffic directly into merchant checkout flows. In Southeast Asia, the platform has eaten into market share held by Sea Group’s Shopee and Alibaba’s Lazada, particularly in Indonesia, Thailand, and Vietnam.

    Cross-border competition has intensified as PDD Holdings’ Temu and fast-fashion platform Shein push discount goods into the same consumer segments. TikTok Shop countered by integrating local logistics partnerships and offering subsidized shipping to lock in high-frequency buyers.

    Global Footprint and Platform Competition

    Western market expansion provides the second engine behind the US$100 billion trajectory. After scaling up operations in the United Kingdom and the United States, ByteDance began preparing localized rollouts in continental Europe and Latin America to diversify revenue away from single-market regulatory risks.

    RetailNews Asia notes that conventional marketplace apps rely primarily on search intent, while TikTok generates spontaneous purchases by inserting checkout prompts into entertainment feeds. That structural difference forced Shopee and Lazada to invest heavily in their own live streaming hubs to defend market share.

    The key metric to track heading into 2026 will be TikTok Shop’s take rate, as ByteDance lifts seller commission fees to convert platform volume into operating profit.

  • Thai Hypermarket Operators Face Slowing Growth Under Stiff Competition

    Thai Hypermarket Operators Face Slowing Growth Under Stiff Competition

    Thailand’s hypermarket operators face an uphill battle to expand as stiff competition and sluggish market momentum stall growth across large-format stores. The segment contends with difficult trading conditions where incremental gains require heavy operational effort against entrenched local rivals.

    Competition Slows Large Store Expansion

    Retail analyst Michael Baker reported that large-format grocery and general merchandise chains across Southeast Asia, led by Thailand, now operate in a grinding environment defined by slow forward momentum. Operators face intense rivalry that makes physical network expansion costly and difficult to sustain.

    Big-box retailers across the region have struggled to replicate past expansion rates as neighborhood formats, specialty retailers, and convenience networks pull shoppers away from suburban megastores. In markets like Thailand, where retail space per capita in urban centers is already high, winning market share requires squeezing efficiency out of existing floorspace rather than adding square footage.

    Market Headwinds Across Southeast Asia

    Large-format food and merchandise chains must resolve internal operating pressures while adapting store formats to retain foot traffic. Slower retail turnover across broad merchandise categories has forced chains to rethink store layout and inventory deployment.

    The next quarterly retail filings across Thai listed operators will show whether store rationalization and format downsizing can protect operating margins.

  • Human Trust Remains Key Driver for Southeast Asia E-Commerce Amid Rising AI Adoption

    Human Trust Remains Key Driver for Southeast Asia E-Commerce Amid Rising AI Adoption

    Human trust continues to be a primary factor in consumer purchasing decisions across Southeast Asia, even as generative artificial intelligence (AI) tools gain traction in product discovery. A new report by impact.com, Cube, and Dentsu reveals that while AI is emerging as a significant channel, established human connections still hold sway over shoppers in the region’s burgeoning e-commerce market.

    The “E-commerce Influencer and Affiliate Marketing in Southeast Asia 2026” study indicates that recommendations from family and friends are the most influential factor, scoring 2.42 out of four. This outranks online reviews (2.36) and even creators (1.98). However, the report also highlighted the direct impact of creators, with two-thirds (67%) of consumers making a purchase specifically due to a creator’s recommendation. This trend underscores the enduring power of trusted individuals in guiding consumer choices.

    AI’s Growing Role in Discovery and Research

    Generative AI tools such as ChatGPT, Gemini, and Claude are increasingly being used by Southeast Asian consumers for shopping, particularly in product discovery and research. Approximately 24% of consumers in the region currently use these AI tools for initial product discovery, a figure that rises to 28% during the product research phase. Vietnam leads the adoption curve for AI in product discovery at 34%, followed by Indonesia at 31%, while Singapore recorded the lowest usage at 14%.

    Despite AI’s ascent, influencers retain their importance as a research channel, cited by 51% of consumers. YouTube garners the highest engagement for influencer content at 23%, with TikTok at 17% and Facebook at 15%. The report suggests that AI complements the existing commerce ecosystem, rather than replacing it. Consumers frequently navigate between AI assistants, marketplaces, creators, publishers, retail media, and brand-owned channels throughout their purchasing journey. RetailNews Asia has observed similar patterns in other markets, where technology enhances rather than entirely supplants traditional trusted channels, prompting brands to integrate diverse strategies.

    E-Commerce Growth and Influencer Impact

    Southeast Asia’s e-commerce sector is experiencing robust growth, with sales forecast to increase by nearly 15% year-on-year to $219 billion in 2026. This trajectory is expected to almost double to approximately $410 billion by 2031. Indonesia and Thailand collectively dominate the regional market, accounting for 58% of all e-commerce sales, with marketplaces holding an average 72% share. Influencer and affiliate marketing combined are linked to an estimated 32% of the region’s e-commerce sales, translating to about $70 billion in 2026.

    The study, which surveyed 2,400 consumers, also details conversion methods. For purchases made via influencer or creator channels, in-video product tags were the most common conversion route at 56%. This was followed by links in descriptions or comments (43%) and stories (41%). Consumer engagement with various purchasing incentives varies by market. Singapore shows high adoption of cashback and deal sites at 69%, contrasting with Vietnam (28%) and Indonesia (25%) where usage is considerably lower.

  • Coty SEA blends physical and digital space for limitless store access

    Coty SEA blends physical and digital space for limitless store access

    Coty SEA stores offer services that give the same customer experience online.

    There is no telling when one’s favourite perfume or go-to moisturizer runs out, which some shoppers can solve with a quick dash to the store. On days they are not so lucky, shoppers are left waiting for their next store-run, but this does not have to be the case as Coty Sea blends the physical and digital space.

    “If customers have already bought the product and it is running out, they can then just text our beauty advisors to get a replenishment, and the product can be sent to them,” Estella Lau, Country Manager, Singapore & Prestige Distributor, Coty said.

    She said Coty plans to launch a beauty concierge service through which customers can reach their beauty advisors in a call or chat for advice or makeup tips, even when their free-standing store has closed down for the day.

    Lau highlighted the role brick-and-mortar stores play for brands even amidst the acceleration of technological adoption of the industry. Coty SEA strived to use the physical space to complement the company’s digital channel to elevate the customer experience.

    “Brick-and-mortar is definitely not going away. It remains a key platform for us to engage the customers as we say we want to create a community space where customers can come and play with the product or enjoy a makeover or master class,” Lau said.

    Coty recently partnered with Chloé Atelier des Fleurs, which opened its first pop-up boutique in Singapore. The store replicated a Parisian florist’s boutique, where shoppers can mix and match 17 niche scents to whip their own unique fragrance, much like making a bouquet.

    In their Chloé Atelier de Fleur boutique, Coty SEA has assigned beauty advisors ready to help shoppers who prefer face-to-face interactions; whilst those who prefer to shop alone can play with a digital “Bouquet Finder,” which will likewise take customers to a fragrance layering experience.

    Lau said the company has observed a monthly increase in footfall since launching in October 2022. More than this, there is also a noticeable growth in their conversion rates amongst the shoppers coming through their doors.

    This brings to light the significance of having the right investments in place. Lau said retailers need to beef up their operations not just through investments in their digital technology infrastructure, but also by bringing the right people on board.

    “Technology is one thing, but behind all that technology needs competent people with very strong digital marketing skills, digital commercial skills, and someone who can understand consumer needs and consumer shopping behaviour,” Lau said.

    Whilst e-commerce development is critical, she said that retailers need to also invest in creating an experience that is more personal to the consumer; but businesses have to make sure that the experience is reflected in both the physical and digital space. At Coty SEA, stores have a “shop space” to take their clients through the same experience online.

    The Gucci Beauty Flagship store at ION Orchard, for instance, uses augmented reality to bring shoppers to the Gucci Beauty universe, where they can learn and play with beauty products. They also have the option to virtually try-on makeup using in-store gadgets.

    This will need a better understanding of consumers, which retailers can achieve with improved data analytics capabilities that could track the frequency of shoppers’ store visits, or determine the key promotion drivers that shape their behaviour.

    “For customers who want a more bespoke experience, we offer the art of fragrance layering with our ultra-luxe range, the Alchemist Garden, where customers can learn about how they layer fragrance oil with perfume water, and with the fragrance of their choice and really have a wonderful premium experience,” Lau said.

    Investing in people may also be internal as seen in how Coty SEA puts effort into training their beauty advisors. Lau said their people are not just skilled in making transactions, but also in personally engaging with customers through storytelling or even by making them feel more pampered.

    On top of these, Lau said retailers can no longer exist on their own, hence, they need to start looking at partnerships with other brands to offer a different, layered, and more interesting experience to customers. Through partnerships, they can develop limited edition products, or even create ones that shoppers can exclusively get online.

    “If we don’t keep up, we risk losing market share. Now it is not even a choice because this is what the shoppers want. They want to be shopping 24/7. They want to be shopping at their convenience, at their own time,” Lau said.

    “It is really imperative now for retailers to continue to connect and engage with all our multi-generational consumers and new audiences to stay relevant.”

  • Starbucks to open 400 stores in APAC in 2023

    Starbucks to open 400 stores in APAC in 2023

    Its newly-opened 5,000th store is located in Gwanyang-si, South Korea.

    Starbucks is planning to expand further in Asia Pacific by opening 400 stores this 2023 after it opened its 5,000th store in the region in South Korea.

    In a statement, Starbucks said it aims to build on its over 300-store portfolio across 40 cities in India and enter the market of at least five new cities.

    In Southeast Asia, the company plans to build more stores outside the metropolitan areas of Indonesia, Thailand, Malaysia, and the Philippines. It opened its first store in Laos in November in the capital city, Vientiane, and plans to open another this year.

    The company’s 5,000th store in the region opened in Gwanyang-si, South Korea which is located on a major road that connects the residential areas with business districts and features a drive-thru service.

    “Asia Pacific is a dynamic and diverse engine of growth for Starbucks globally. As recovery continues, the region achieved over 20% sales growth year on year, demonstrating the strength and relevance of the brand,” said Michael Conway, group president, International and Channel Development for Starbucks.

    “We are well positioned for further growth with our licensed business partners, who continue to elevate the Starbucks Experience across a range of innovative store formats,” he added.

  • Ninja Van Unveils White Paper on Live Selling in Southeast Asia

    Ninja Van Unveils White Paper on Live Selling in Southeast Asia

    Ninja Van Malaysia, a tech-enabled logistics company, has released its first-ever white paper on Live Selling in Southeast Asia. The white paper introduces Live Selling as one of the up-and-coming Southeast Asia’s e-commerce trends and shares Live Selling insights collected from over 1,000 Ninja Van’s e-commerce sellers across Malaysia, Singapore, Indonesia, The Philippines, Thailand, and Vietnam.

    While Live Selling is still a nascent industry in most Southeast Asian countries, the increase in the number of Live Selling solutions shows that the new retail trend shaping the future of e-commerce is here to stay – and sellers are taking note.

    In Malaysia alone, 40% of live sellers conduct their sessions daily, ranking higher than its regional neighbours Singapore (17%), Indonesia (23%), and Vietnam (27%). Additionally, 47% of live sellers in Malaysia conduct each session for up to 2 hours.

    “Live Selling is an interesting marketing tactic for e-commerce sellers,” says Winston Seow, chief marketing and enablement officer, Ninja Van Group. “It’s the only tactic that can fast-track shoppers’ purchase journeys from awareness straight to conversion. Live Selling also gives e-commerce sellers the ability to build relationships at scale with their shoppers, both new and existing.”

    One in three of the surveyed Southeast Asian e-commerce sellers is now doing Live Selling, spending up to six hours weekly conducting Live Selling sessions. Most of the early adopters of Live Selling are from low-involvement product categories such as fashion, beauty & personal care, food and beverages, as well as home & living.

    While Shopee (27.0%), Facebook (25.5%), and TikTok (22.5%) are ranked as the top three Live Selling channels, the close margins signal that the champion has yet to emerge in Southeast Asia. This could be explained by the fact that on average, the surveyed e-commerce sellers use two channels for Live Selling, presumably to maximise their outreach to shoppers.

    Live Selling also offers e-commerce sellers a new way to better connect with customers. “Since we started Live Selling, we’ve seen an increase in our sales and have built a stronger relationship with our customers.

    “We sell over 1,600 household products made from different materials and through our live sessions, we’re able to engage directly with our customers and answer any questions they may have about our products. I believe this makes for a more positive shopping experience for our customers, allowing them to make informed decisions about their purchases,” says Tan Jie Xian, Digital E-commerce marketing executive at Elianware.

    The white paper also explores the challenges of Live Selling, such as keeping Live Shoppers engaged, preparing on-set logistical requirements, as well as sales and post-sales arrangements. Recommended solutions are included too.

  • Most SE Asia stocks fall in line with broader Asia; Indonesia climbs 1 pct

    Most SE Asia stocks fall in line with broader Asia; Indonesia climbs 1 pct

    Most Southeast Asian stock markets fell on Tuesday, tracking broader Asia after a selloff on Wall Street overnight. As reported, citing sources from both sides, that China’s top trade negotiator Liu He may visit Washington to prepare for the talks between U.S. President Donald Trump and his Chinese counterpart Xi Jinping on the sidelines of the G20 summit in Argentina later this month.

    Philippine shares declined 1.2 percent, extending falls into a third session, dragged by industrial and real estate stocks. SM Prime Holdings declined 2.3 percent, while JG Summit Holdings fell 6.9 percent.

    Singapore shares declined for a third consecutive session, dragged by financials. DBS Group Holdings, the city-state’s largest lender, slipped 0.9 percent, while rival United Overseas Bank Ltd fell 1.2 percent.

    Malaysian shares extended falls into a third session, with IOI Corp Bhd shedding 3.1 percent to a near 11-month closing low and IHH Healthcare Bhd declining 2.8 percent to its lowest close since July 2014.

    Trade tensions between the United States and China will create a “domino effect” and prompt other countries to turn protectionist, said Malaysian Prime Minister Mahathir Mohamad.

    Vietnam shares declined 1.4 percent, dragged by financial and real estate stocks. Joint Stock Commercial Bank for Investment and Development of Vietnam (BIDV) fell 3.7 percent, while real estate investor Vingroup JSC ended 2.7 percent lower.

    Indonesian shares were the top gainers in Southeast Asia with a rise of 1 percent. Consumer staples and financials led the gains with United Tractors Tbk PT and Bank Central Asia Tbk PT rising 5.5 percent and 1.6 percent respectively.

    Thai shares climbed 0.3 percent, helped by consumer staples.

    Glass container manufacturer Berli Jucker PCL rose 1.4 percent, while convenience stores operator CP All PCL climbed 2.6 percent to a more than one-month closing high.

    “Stocks are rising on internal factors like government improving infrastructure and linking of our three airports,” said Teerada Charnyingyong, an analyst with Phillip Capital Thailand.”The government also announced measures to stimulate spending by promoting the tourism sector.”

  • Mobile payment firms struggle to dethrone cash in Southeast Asia

    Mobile payment firms struggle to dethrone cash in Southeast Asia

    Bui Mai Phuong is an avid online shopper, ordering anything from clothing to personal-care products from her smartphone. But she prefers to pay with cash.

    She is among hundreds of millions of people whom firms such as Softbank Group-backed Grab and China’s Tencent want to win over as they try to tap into Southeast Asia’s burgeoning internet sector.

    More than 70 percent of the region’s 600 million-plus people do not use banks – higher than the global average of about 30 percent – and e-commerce is projected to hit $88 billion by 2025.

    But convincing consumers like Phuong, who lives in Hanoi, could be tricky.

    “I have never tried using mobile payments because I don’t know how to use it and it seems a bit complicated to use,” said Phuong, 36, a manager at a construction material supplier in Vietnam.

    Mobile payments are ubiquitous in China; a consumer can spend a day without using cash at all in Beijing or Shanghai, and even some beggars accept mobile payments. But cash remains king in Southeast Asia.

    Hard currency, paid on delivery, accounted for 44 percent of total e-commerce transactions last year and is likely to remain the most popular payment option for at least the next three years, according to data by research firm IDC.

    “The biggest challenge for users and merchants to adopt cashless is the fact that cash remains ubiquitous, easy to use and inexpensive,” said ride-hailing firm Grab, which has ventured into e-wallets.

    And the mobile payment marketplace in Southeast Asia remains wide open, with no dominant players.

    Indonesia’s ride-hailing firm Go-Jek’s Go-Pay, Singapore-based Grab’s GrabPay, Japan’s messaging app Line’s Line Pay, Momo e-wallet owner M_Service in Vietnam and Voyager Innovations, which operates Paymaya in the Philippines, have all entered the fray. The gaming company Razer Inc has also indicated it is eager to play a role.

    Cash on delivery costs e-commerce businesses more than other payment methods, said Alibaba Group Holding-backed e-retailer Lazada Group.

    For example, sometimes a customer does not have enough cash on hand, or is not home to pay for the delivery. In those cases, the product must be sent back to the seller, adding logistical costs, Lazada said.

    Mobile payments address some of those problems. They can also benefit buyers by keeping payment in escrow and releasing it only on delivery.

    But it can be difficult to persuade users to switch from cash when they earn about $200 on average a month in economies like Vietnam and Indonesia, according to economic data provider CEIC.

    “To break habits of using cash, Grab is creating more daily use cases for cashless payment – commuting, food delivery, paying at food and retail stalls – to drive more usage of the GrabPay e-wallet,” Grab said in an email.

    Mobile payment companies bet they can transform their platforms into financial supermarkets, offering everything from loans to insurance on top of payment options.

    Slow going

    At the moment, usage is spotty. E-wallets will account for 16 percent of total e-commerce transactions in Southeast Asia by 2021, up from last year’s 9 percent, according to IDC.

    In countries like Vietnam, where the informal economy has long been a key part of the social fabric, many consumers do not bother to get a bank account.

    Some want to stay under the taxman’s radar or, like Quang Thi Si, simply do not see the need for a bank.

    Si, a 48-year-old scrap collector near Ho Chi Minh City, said her business is all cash.

    “Sometimes I need to send money to my relatives at home, and I often send in cash through my friends,” she said. “I don’t think I will have a bank account in the future because I don’t think I need it.”

    But Si does have a smartphone. More than 90 percent of Southeast Asia’s internet access comes through mobile devices, according to a Google-Temasek study.

    Even so, in countries like the Philippines, which is known for having some of the slowest Internet speeds in Asia-Pacific, connectivity is a major hurdle for digital payments to clear.

    ‘Late to the party’ 

    Such challenges are likely to pose a setback to Ant Financial and Tencent, which are looking outside China for growth.

    Ant, which has 600 million customers and aims to reach 2 billion worldwide in the next decade, has stepped up investments in the region, including a stake in Thai financial technology firm Ascend Money.

    But its services are largely limited to Chinese tourists.

    “Most of our customers are from China and they are usually very happy to know that we accept AliPay and WeChat Pay. This makes them more willing to spend money too,” said Daphne Tan, a staff member at a shop selling durian-flavored coffee and snacks in Singapore’s Chinatown.

    Tencent plans to make its first foray outside China with an e-payment license in Malaysia for local transactions.

    The Chinese players are “kind of late to the party,” said Michael Yeo, research manager for IDC.

    “By the time they come in with a local version, if they do, the local players will have a significant advantage,” said Yeo.

    Razer, which said last month it would buy the remaining stake in payments processor MOL Global that it did not already own, also signed a deal with Singtel to link its e-payments network with that of the telco.

    Other recent deals in the sector include Go-Jek’s acquisition of three financial technology businesses, while Grab’s purchase of a handful of companies as well.

    “It’s a highly fragmented market. Later on, there will be acquisitions, there will be shutdowns, there will be mergers,” IDC’s Yeo said. “The market will consolidate.”
  • Flatscreen TV sales slide in SE Asia

    Flatscreen TV sales slide in SE Asia

    The total sales volume of flat panel TV continues to slow in six key Southeast Asian markets monitored by research house GfK.

    But consumer demand for ultra-high definition (UHD) models has spiked exponentially in the past year to help fuel the strong growth of this segment as well as the overall value growth of the TV market.

    According to GfK’s point of sales tracking in Singapore, Malaysia, Thailand, Vietnam, Indonesia and the Philippines, the 11.8 million TV sets sold in April 2014 to March 2015 marks a 2.9 per cent drop compared with the same period a year ago. However, robust sales of the higher value UHD models managed to drive up dollar value generated by the entire TV market by 2.9 per cent.

    “With the near completion of switchover trend in developing Southeast Asian countries, consumers are now focusing on upgrading to the latest screen technology,” said Gerard Tan, account director for Digital World in GfK.

    “Manufacturers and retailers have been aggressively launching attractive promotions to stimulate take up rates.”

    The six individual countries reported surges in sales value of their respective UHD TV markets in the range of 20 to 77 per cent, with Singapore (77 per cent), Indonesia (67 per cent) and Vietnam (47 per cent) registering the fastest growth. In unit terms, sales volume from a year ago climbed  in the range of nine to 37 per cent – led by Singapore and Indonesia (37 per cent) and followed by Vietnam (23 per cent).

    According to GfK findings, the UHD segment contributed nearly eight per cent of the region’s TV sales dollars; accounting for US$354 million – an increment of 280 per cent over the same period the year before. Penetration is highest in the most developed market of Singapore, where more than one in every 10 (13 per cent) of sets sold UHD.

    The rising share of UHD in the TV market has also resulted in the average price of a UHD TV falling around 61 per cent, from US$5500 to $2160.

    Meanwhile, the most commonly purchased screen size for this segment is 41”-50”, making up 35 per cent in share of the UHD sales volume.

    “TV technology is constantly evolving, and with each new launch, we see the progression of consumers moving from small to big screens, with affordability increasing over time,” said Tan.

    “Moving forward into the rest of 2015, we can expect to see rising excitement in the UHD TV market as manufacturers battle for the consumer dollar with more offerings at more attractive prices; and at the end of the day, consumer s are the ones who get to enjoy the good deals resulting from the fierce competition,” he concluded.