Author: Mei Ling Tan

  • Tokyo’s Umios Buys High Liner Foods for C$804 Million

    Tokyo’s Umios Buys High Liner Foods for C$804 Million

    Tokyo-listed seafood manufacturer Umios announced an agreement on 26 October to acquire Canadian peer High Liner Foods for C$804 million ($573.6 million) in cash.

    Under the terms of the transaction, the Japanese group, formerly known as Maruha Nichiro, will pay C$27 per share to position the Nova Scotia-based processor as its core North American platform.

    High Liner operates three production plants, distributing frozen seafood to retail and foodservice customers across the US and Canada under its namesake label, private-label contracts, and brands such as Mrs. Paul’s and Van de Kamp’s.

    Controlling the Pollock Flow

    The deal ties raw ocean supply directly to grocery freezers. Umios, known as Maruha Nichiro until its recent corporate rebranding, controls approximately 26 per cent of the total allowable catch quota for Alaska pollock in the US Bering Sea. That volume historically moved through third-party processors and trading intermediaries, leaking margin along the chain.

    High Liner gives the Japanese conglomerate immediate processing capacity and shelf access across North American supermarket aisles. The Canadian company generated consolidated net sales of roughly $1.03 billion for the full year through December, converting that into an attributable net profit of $36.5 million. By pushing its raw catch through these facilities, Umios captures processing margins and direct distribution revenue inside the world’s most lucrative consumer market.

    For Japanese seafood majors, the domestic horizon is bleak. Japan faces persistent population decline, aging households, and shrinking fish consumption per capita, forcing legacy ocean operators to seek foreign downstream footholds. Competitors have steadily built up proprietary distribution networks across North America to shield earnings from domestic retail deflation. Umios is executing the same defensive playbook on a heavier scale.

    The Downstream Shift

    Buying downstream retail assets brings inventory volatility that pure-play fishing groups rarely handle smoothly. High Liner faces stiff competition from private-label supermarket lines and volatile cold-storage freight rates across North America. If consumer spending softens in North American grocery channels, branded breaded fillets and fish sticks feel margin compressions quickly, leaving the parent group exposed to retail discounting rather than insulated by wholesale catch prices.

    Umios has promised to preserve High Liner’s corporate headquarters in Nova Scotia, keeping its operational workforce, distribution channels, and commercial labels intact.

    “Combining with High Liner Foods will fundamentally transform Umios.”

    Masaru Ikemi, CEO of Umios, said the merger establishes an integrated supply chain connecting upstream harvest quotas directly to retail buyers. High Liner president and chief executive Paul Jewer noted that joining the Japanese group provides immediate scale and investment backing for expanding value-added product lines.

    From Pet Food to North American Retail

    The Canadian buyout comes during an aggressive acquisition phase across regional food categories. Umios bought a 25.1 per cent stake in Thailand-based pet food and canned seafood producer Pataya Food Industries in September. Three months earlier, in June, it picked up a 51 per cent controlling stake in Malaysian pet food maker Pet World International.

    Those Southeast Asian investments targeted fast-growing pet care categories across emerging Asian markets. The High Liner transaction represents a different lever: locking in mature, high-volume consumer protein demand across developed Western supermarket networks to monetise marine harvest rights.

    The transaction will proceed under a court-sanctioned plan of arrangement, with High Liner’s board voting unanimously to recommend the offer. Shareholders holding 45.4 per cent of outstanding stock, including major backer Thornridge with its 41.4 per cent stake, have pledged their votes in favor. Umios requires 75 per cent shareholder support alongside statutory regulatory clearances to close the transaction by January.
  • AnyMind and Meta Partner to Bring Live Commerce Ads to Asia Pacific

    AnyMind and Meta Partner to Bring Live Commerce Ads to Asia Pacific

    Tokyo commerce technology firm AnyMind Group has teamed up with Meta to funnel social network users from video ads directly into live selling broadcasts across the Asia-Pacific region.

    The integration routes traffic away from social feeds into checkouts hosted on brand websites, proprietary mobile apps, and direct business messaging channels.

    Activations start on Facebook Live video ads in the fourth quarter of 2026, AnyMind said. Instagram rollouts follow in early 2027.

    External Checkouts Replace Native Tools

    Participating merchants will simulcast broadcasts across multiple owned channels simultaneously. Broadcast infrastructure supports human presenters, artificial intelligence avatars, or hybrid presentations featuring both.

    Crucially, the partnership routes consumers out of the social application to finish transactions. Rather than processing payments inside Meta’s walls, the ad format relies on off-platform conversion points.

    Instagram removed its native live shopping features in 2023. By sending shoppers to independent web stores and chat apps, Meta secures advertising spend without taking on inventory management, merchant support, or local payment settlement.

    Rival Pressures in Asian Livestreaming

    For brands and e-commerce merchants across Southeast Asia and East Asia, the partnership offers a direct alternative to closed marketplaces.

    AnyMind gives enterprise brands a way to tap Meta’s massive audience data while retaining ownership of buyer records, customer contact information, and final cart margins. The commercial risk rests squarely on merchant web conversion. Redirecting a mobile user to an external browser or chat app introduces friction that native in-app shops avoid, leaving sellers vulnerable to drop-offs before payment completes.

    Automating Digital Broadcasters

    The push also accelerates AnyMind’s investment in automated retail software across Asia. The company previously moved to integrate Alibaba’s Qwen artificial intelligence models into its live selling tools, giving merchants the ability to run automated multilingual broadcasts without hiring live presenters around the clock.

    Pairing algorithmic hosts with paid Meta ad delivery lets regional retailers test product demand across multiple Asian markets quickly. It lowers the production overhead typically required for live studio broadcasts in regional hubs like Tokyo.

  • Shell Sells 200 Indonesian Fuel Stations to SEFAS Group

    Shell Sells 200 Indonesian Fuel Stations to SEFAS Group

    Shell has completed the sale of its retail fuel business in Indonesia to local partner SEFAS Group, transferring a network of roughly 200 service stations across the country.

    More than 160 of those forecourts are company-owned sites, and all of them will continue trading under the Shell name through a long-term trademark licensing agreement.

    Announced on Friday, October 30, 2026, the transfer hands over operations to SEFAS while preserving Shell-branded fuel products for Indonesian motorists without disruption.

    Transfer to PT Isla Energy Indonesia

    The transaction shifts Shell’s downstream forecourt assets, supply chain infrastructure, and fuel distribution operations into PT Isla Energy Indonesia, which SEFAS now owns entirely. The deal also hands SEFAS full control of a fuel terminal in Gresik, East Java. Neither company disclosed the financial terms.

    Forecourts will keep selling Shell-formulated fuels without interruption, leaving customer loyalty schemes, payment systems, and forecourt retail partnerships intact at store level. Operating fuel retail through local licensees allows foreign energy majors to cut direct capital expenditure while taking high-margin brand royalties from high-volume emerging markets.

    Forecourt Retail Shift in Southeast Asia

    Fuel retailing across Southeast Asia has shifted away from direct ownership by international majors toward local distribution specialists who operate roadside convenience stores, quick-service dining, and vehicle maintenance franchises more aggressively. Running company-owned networks in Indonesia requires heavy working capital to manage import supply chains and land leases.

    For Indonesian forecourt operators and convenience store concessionaires, the ownership change puts site development decisions in the hands of a local distributor with immediate domestic supply ties. SEFAS absorbs the operational risk of managing site inventories and wholesale fuel margin volatility, while Shell collects licensing revenue without carrying forecourt real estate on its balance sheet.

    Lubricants and Manufacturing Kept In-House

    Shell kept its Indonesian lubricants and industrial manufacturing divisions entirely separate from the retail sale. The energy group continues to operate its lubricant oil blending plant in Marunda, Bekasi, which produces up to 300 million litres annually.

    That manufacturing footprint expanded in September 2026 when Shell started commercial operations at a grease plant with an annual capacity of 12,000 metric tons. SEFAS agreed in August 2026 to buy the retail fuel business before working through Indonesian regulatory clearances and closing procedures.

    Forecourt operators will watch how quickly SEFAS expands the network beyond Java and whether it updates PT Isla Energy Indonesia’s convenience retail partnerships across the remaining dealer-owned sites.

  • Leapmotor Launches A10 SUV in Thailand with 30 Outlets Planned

    Leapmotor Launches A10 SUV in Thailand with 30 Outlets Planned

    Leapmotor launched its A10 compact electric sport utility vehicle in Thailand on Friday, sending the model to 19 local showrooms as it chases export volume across Southeast Asia.

    The carmaker plans to expand that sales and service footprint to 30 locations nationwide before the end of the year.

    Showroom rollout and vehicle specs

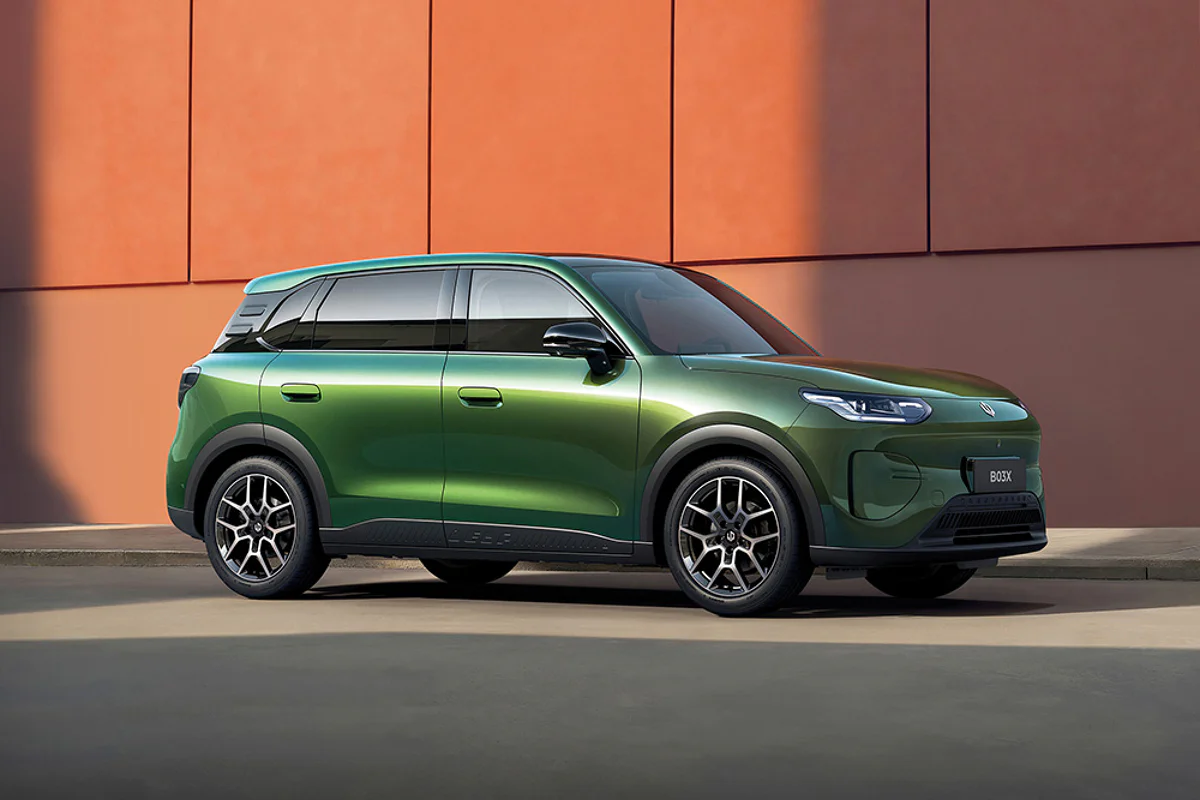
    Known internationally as the B03X, the small SUV features a long-range battery rated for 450 kilometers under NEDC testing standards. It accepts direct-current fast charging up to 133 kW, filling the battery from 30 percent to 80 percent in 16 minutes under test conditions.

    Cabin hardware includes a 14.6-inch 2.5K central display screen compatible with Apple CarPlay and Android Auto. Practical features focus on urban buyers, adding semi-autonomous driver aids alongside a 106-liter washable cargo bin fitted under the rear floorboards. Leapmotor did not release retail pricing or a delivery schedule during the Bangkok presentation.

    Dealership network and parts supply

    Expanding dealership coverage forms the core of the Thai strategy. Alongside the push to reach 30 retail points, the carmaker is building a dedicated regional parts distribution hub and a technical support depot to speed up repair turnaround.

    Chinese brands entering Southeast Asia regularly encounter resistance around replacement component delays and depreciating resale values. Setting up physical maintenance hubs alongside new showrooms addresses that dealer friction directly. It gives fleet operators and individual motorists a clearer operational backing than independent importers can provide.

    The export joint venture

    International distribution runs through Leapmotor International, an operating venture owned 51 percent by Stellantis NV. The European automotive group holds exclusive manufacturing and distribution rights for all Leapmotor vehicles sold outside Greater China.

    That corporate partnership provides instant scale, allowing the Chinese marque to bypass the slow, expensive process of constructing solo distribution networks across developing markets. It also gives the brand an established logistics apparatus to ship right-hand-drive vehicles across ASEAN ports without building regional factories first.

    Expanding product cadence

    Friday’s launch extends a product rollout that began when Leapmotor brought the larger C10 SUV to Thailand in 2024. The carmaker followed that introduction by rolling out the B10 electric SUV in October 2025.

    Deliveries outside China have become central to Leapmotor’s balance sheet. The automaker exported 27,454 vehicles in September, representing a 298.58 percent rise year-on-year and a 50.39 percent lift from August. Over the first nine months of the year, outbound shipments reached 159,572 units, climbing 322.46 percent year-on-year. Global deliveries across domestic and foreign operations reached 105,656 vehicles in September, pushing nine-month output to 666,539 cars.

    Thai retail pricing remains the immediate figure to watch, followed by the planned commercial debut of the refreshed C10 SUV in 2026.

  • Li Auto Builds 200,000 Li I6 SUVs as November Target Reaches 20,000

    Li Auto Builds 200,000 Li I6 SUVs as November Target Reaches 20,000

    Li Auto built its 200,000th Li i6 battery electric SUV on October 30, roughly 13 months after the five-seat model entered the Chinese market in September 2025.

    Assembly lines are scheduled to produce 20,000 units in November before lifting throughput further in December to clear an order backlog running at seven to eight weeks.

    The manufacturing run rate follows the release of the updated 2026 Li i6 on October 28. Deliveries across China started on October 29. Official retail pricing stays unchanged at 249,800 yuan ($37,210), though early buyers securing an order before November 30 receive promotional pricing of 239,800 yuan.

    Hardware upgrades and plant throughput

    Li Auto product line head Li Xinyang outlined the production ramp on Weibo, stating that vehicles for initial fulfillment were assembled in advance to cushion delivery wait times. Buyers placing orders at the end of October are scheduled to receive vehicles before the calendar year closes.

    The refreshed 2026 SUV features the company’s proprietary Mach M100 driver-assistance chip as standard equipment. Energy storage comes from a 96-kilowatt-hour Lianshan 5C lithium iron phosphate battery pack. That hardware gives the rear-wheel-drive configuration a CLTC driving range of 780 kilometers.

    Factory output targets demand that factory shifts run smoothly through the fourth quarter. Hitting 20,000 units monthly requires the assembly line to outpace earlier delivery volumes by a wide margin.

    Deliveries dip ahead of model refresh

    Delivery figures had slowed sharply prior to the refresh as showroom buyers held back for the updated specification. Li Auto handed over 7,379 i6 vehicles in September, representing a 56.54 percent drop from August numbers.

    That volume represented 23.19 percent of all Li Auto deliveries in September. Through the first nine months of the year, the company delivered 160,221 i6 units, which lifted cumulative deliveries since the vehicle’s market debut to 189,192 units by September 30.

    The gap between the 189,192 customer handovers logged through September and the 200,000-unit factory threshold reflects production buffers, test units, and vehicle consignments currently moving through domestic logistics channels.

    Extended range line maintains volume lead

    While Li Auto builds out its pure battery electric lineup, its hybrid powertrains continue to generate the bulk of operational volume. Cumulative output of the Li L6 extended-range SUV reached 420,000 units by late October.

    The L6 held the top sales position among extended-range passenger vehicles in China for two straight months. That steady hybrid volume provides retail cash flow while the company absorbs the capital expenses tied to producing in-house chips and dedicated battery packs for pure electric platforms.

    For automotive component suppliers, the ramp provides operational visibility through mid-winter. Component vendors supplying the battery cells and Mach M100 computing modules face strict delivery schedules to hit the December production target.

    Export timelines and European entry

    Domestic scale forms the base for Li Auto’s overseas ambitions. The automaker announced on October 12 that the vehicle, badged as the Li 6 for export markets, will launch in Europe during the first quarter of 2027.

    Initial sales outside China will focus on Norway and the Netherlands, two markets with established high-speed charging infrastructure. Those territories will test whether Li Auto can convince overseas retail buyers without relying on the extended-range powertrains that drove its domestic rise.

    Factory managers now face the immediate task of hitting the 20,000-unit build rate in November before pushing assembly rates higher in December.

  • Sheng Siong Posts Q3 Profit of $44.6 Million

    Sheng Siong Posts Q3 Profit of $44.6 Million

    Sheng Siong lifted third-quarter profit by 1.9 per cent to $44.6 million for the period ended Sept 30, up from $43.7 million a year earlier, driven by new outlets and stronger comparable sales.

    Revenue rose 6.2 per cent to $441.5 million, compared with $415.5 million in the prior-year period. Earnings per share climbed 1.7 per cent to $0.0296 from $0.0291.

    The Singapore mainboard-listed supermarket chain attributed top-line growth to higher store numbers and improved same-store demand.

    New Floorspace Carries the Top Line

    Revenue growth came directly from new space and gains across existing aisles. The supermarket operator added eight stores in Singapore over twelve months, lifting its domestic network to 92 locations from 84. Total domestic retail space expanded to 799,775 square feet, up from 723,648 square feet in the prior-year period. Its footprint in China stayed flat at six outlets.

    Management acknowledged that discounting remains intense across the island. Sustained promotional campaigns across the grocery sector continue to squeeze receipts and operating margins, capping the flow-through from higher customer traffic.

    Wage Mandates Push Up Operating Costs

    Staff expenses climbed 9.3 per cent during the quarter to $71.6 million, compared with $65.5 million twelve months ago. The increase reflects state wage adjustments designed to lift compensation for lower-income retail staff across the island.

    Sheng Siong raised floor workers’ pay in September 2025 to comply with statutory Progressive Wage Model requirements for the retail industry. Management identified further overhead pressure coming from updated National Wage Council guidelines spanning 2026 and 2027.

    Cross-Border Shopping Threatens Basket Sizes

    Domestic grocers face a shifting competitive perimeter as regional transport links near completion. The Johor Bahru-Singapore Rapid Transit System Link, scheduled to begin passenger service in February 2027, will allow Singapore residents to cross the border into Malaysia in minutes. That connection threatens to siphon off household spending on packaged groceries and personal care goods, where price differentials between the two markets remain wide.

    For mass-market grocers, structural wage inflation combined with cross-border retail leakage leaves little room for pricing missteps. While premium supermarket operators serve a demographic less inclined to haul pantry staples across the Causeway, Sheng Siong’s value-driven shopper base is directly exposed to Malaysian price competition. Defending market share will require tighter inventory turns and selective promotions that protect basket volumes without eroding gross margins.

    Securing Real Estate in Underserved Estates

    The latest performance extends a multi-year push into newly completed residential developments across suburban Singapore. Securing tenancy in public housing commercial spaces has allowed the company to generate steady revenue growth even as older outlets contend with baseline saturation.

    Shares of Sheng Siong fell 1.4 per cent to close at $2.80 on October 29 before the company released its financial statement.

    The retailer continues to target suburban pockets where it lacks coverage.

    Looking ahead, we will continue to prioritise expansion in areas where the group has limited presence, to extend our reach to customers

    said Lim Hock Chee, group chief executive of Sheng Siong.

    Attention now turns to government commercial lease tenders over the coming quarter, where Sheng Siong must secure additional suburban sites to sustain floor-space growth ahead of the 2027 transit link opening.

  • Xpeng Schedules Third-Quarter Results After Delivering Record 118,390 EVs

    Xpeng Schedules Third-Quarter Results After Delivering Record 118,390 EVs

    Xpeng will report its unaudited third-quarter financial results on November 16, following record quarterly deliveries of 118,390 electric vehicles across China.

    Volume rose 2.05 percent from the same period last year and climbed 14.61 percent sequentially from the second quarter, edging past the midpoint of the company’s August target.

    The carmaker plans to host its earnings call at 8:00 pm Beijing time on November 16, prior to regular trading hours in New York. Delivery volume for the quarter sat comfortably inside the projected band of 115,000 to 121,000 units. For the three months ended September 30, Xpeng had forecast revenue between 21.7 billion yuan ($3.23 billion) and 23.4 billion yuan, representing top-line expansion of 6.47 percent to 14.81 percent.

    Margin Pressure Behind Rising Volume

    Expanding assembly lines have yet to eliminate bottom-line losses. During the second quarter, Xpeng booked revenue of 19.74 billion yuan, up 8.0 percent year on year, while its net loss widened 179 percent to 1.34 billion yuan. Overall gross margin climbed to 20.7 percent during that period, but profitability specifically on car manufacturing retreated to 12.1 percent from 14.3 percent twelve months earlier.

    Management linked that automotive margin erosion to production line switchovers and model transitions. For automotive retailers and dealership networks across tier-two and tier-three Chinese cities, those shifting economics matter. Showroom floors face aggressive discounting pressure from domestic competitors, which forces brand operators to balance higher footfall against compressed dealership commissions.

    The Fourth-Quarter Delivery Pipeline

    Operational momentum picked up as the final quarter opened. The company delivered 50,237 vehicles in October, exceeding the 50,000 threshold in a single month for the first time. That tally marked a 19.57 percent increase compared to October 2025 and a 21.77 percent jump over September 2026.

    To sustain that momentum, the automaker began nationwide handovers of the Mona L05 on November 1, following its domestic debut on October 29. Fast handovers will test distribution logistics and regional charging hubs as order backlogs translate into active road registrations.

    Pricing Battles Across Chinese Showrooms

    The earlier part of the year had laid out a choppy trajectory for the business. First-quarter deliveries reached 62,682 units before rebounding to 103,295 in the second quarter. The second-quarter earnings release on August 24 demonstrated that while total vehicle receipts grew, product changeovers continued to drag on net earnings.

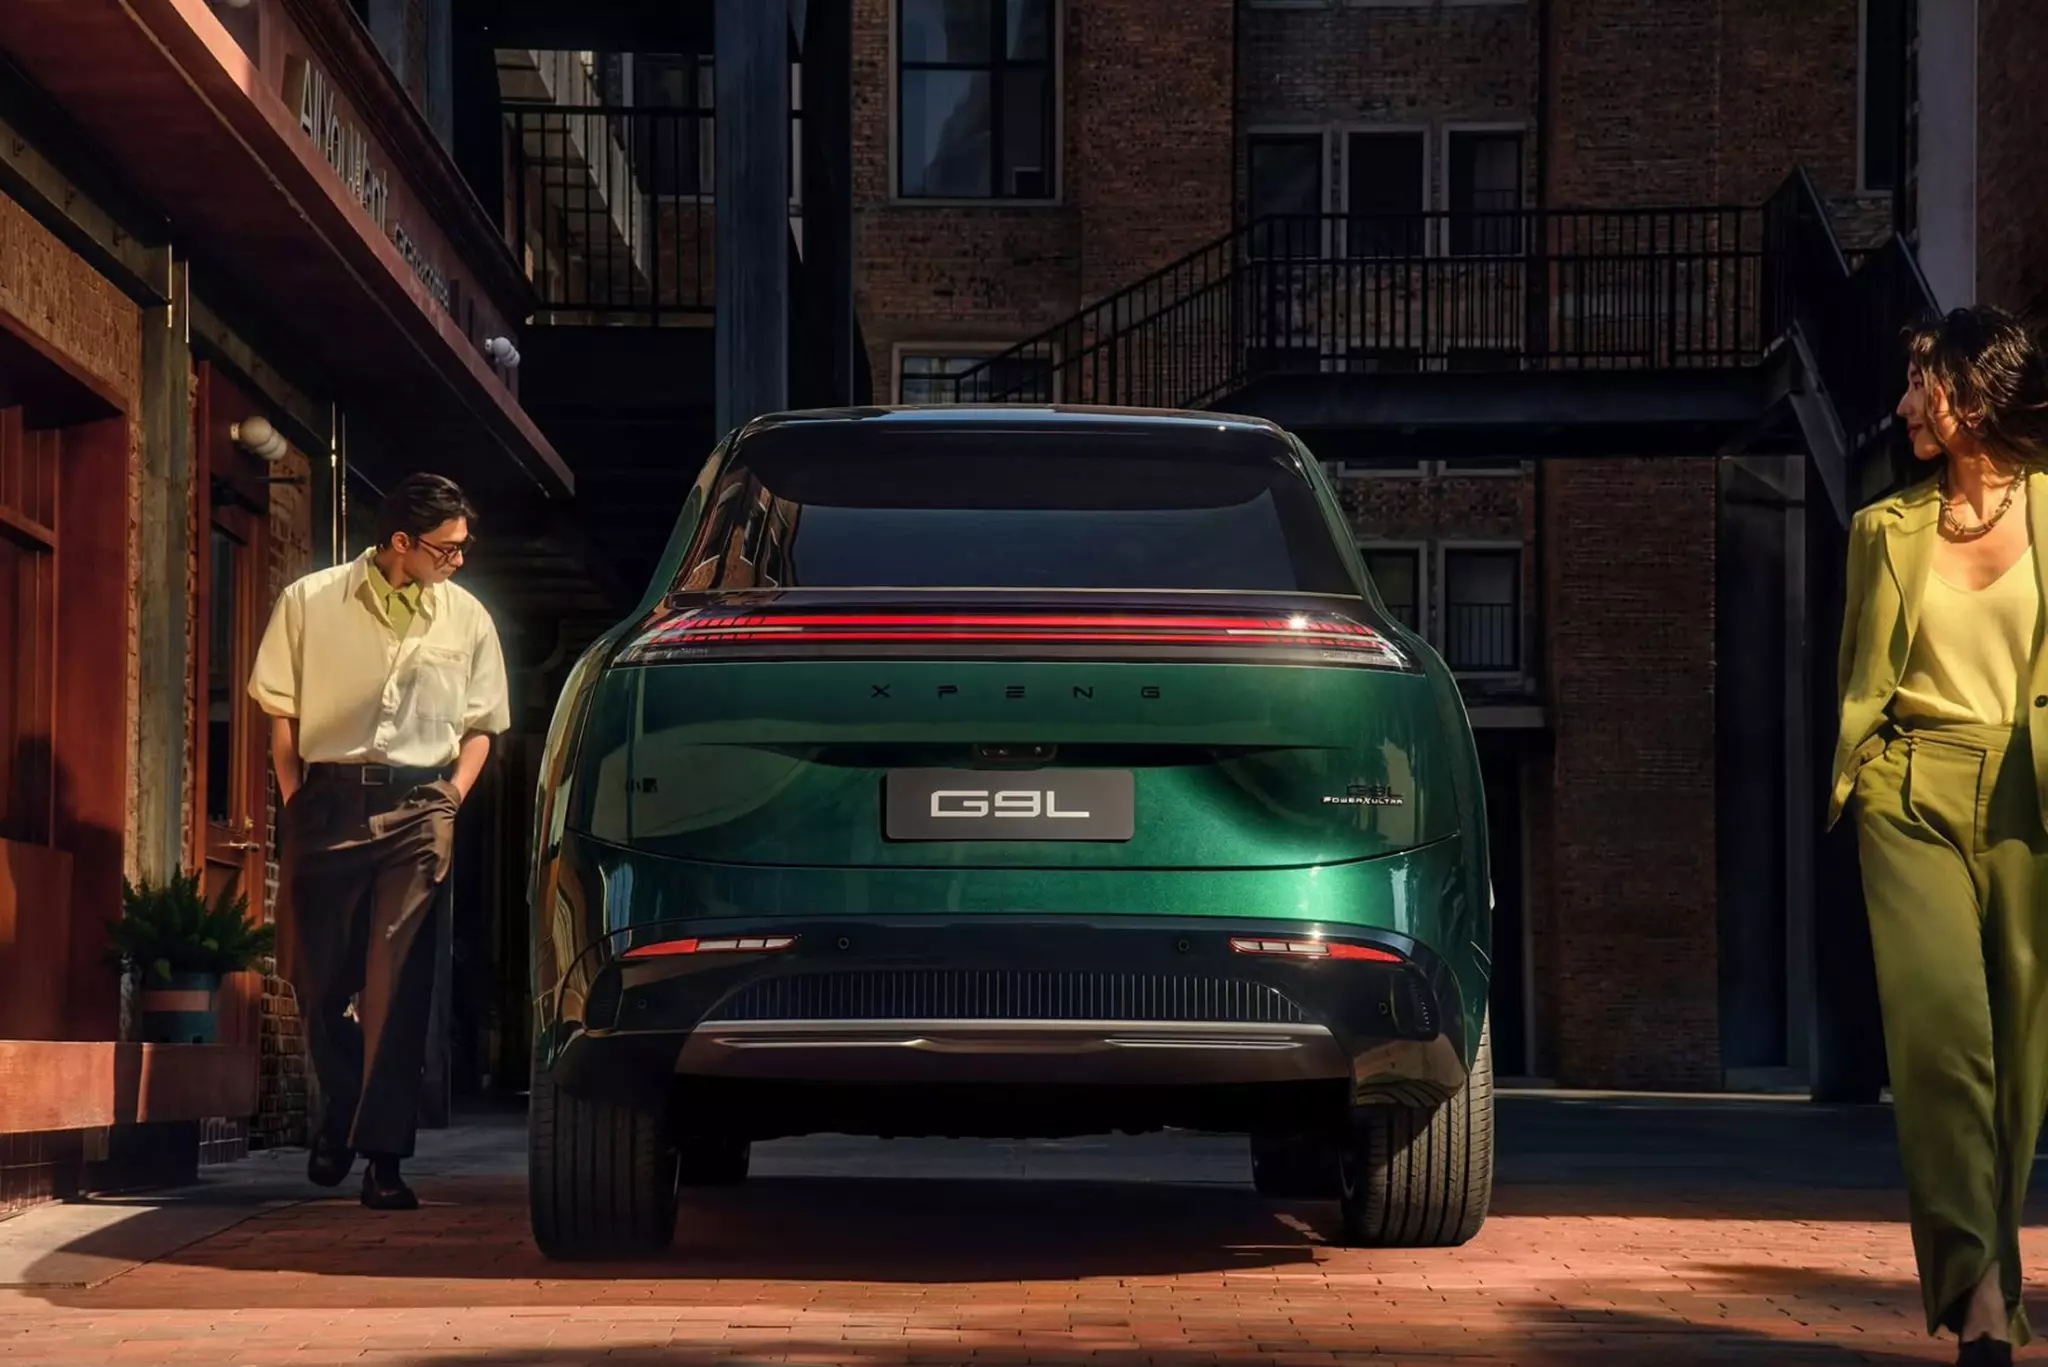
    Investors and regional dealership groups will focus on fourth-quarter delivery guidance when the numbers arrive on November 16. Chairman and Chief Executive Officer He Xiaopeng had previously set an operational target to surpass 60,000 monthly deliveries before the close of the year, relying on mass shipments of the Mona L05 alongside the G9L.

  • Eppo Targets 180,000 Thai State Vehicles for Electric Transition

    Eppo Targets 180,000 Thai State Vehicles for Electric Transition

    Thailand’s Energy Policy and Planning Office (Eppo) has prepared a roadmap to convert more than 180,000 state-owned and leased vehicles to electric power while rolling out workplace charging points across agencies.

    Battery electric models make up only about 1% of all vehicles procured by public departments between 2006 and 2026. Eppo formulated the transition strategy using findings from a consultancy firm’s study to cut public-sector energy costs and lower long-term operating expenses.

    An energy official speaking on condition of anonymity stated that Eppo views the transition as a practical foundation for wider clean-energy adoption across the civil service.

    Rewriting Procurement Rules for State Fleets

    The roadmap requires officials to revise civil service vehicle-leasing and purchasing frameworks to favor electric drivetrains. A dedicated state agency will supervise compliance, monitor progress across ministries, and enforce standardized operational safety measures. Energy planners based the initial framework on a consultancy study, with final implementation rules still being prepared for cabinet consideration.

    Public agencies manage thousands of depots, ministry offices, and municipal yards where staff vehicles sit idle during office hours. Converting these locations requires dedicated commercial charging points, expanding electrical line capacity, and creating unified fleet management contracts for state operators.

    Building Demand for Local Assemblers

    For automakers operating in Thailand, public sector procurement offers guaranteed volume without the marketing overhead of consumer sales. Chinese EV manufacturers and traditional Japanese assemblers competing in Southeast Asia have built local manufacturing capacity to meet domestic production incentives. Long-term fleet purchase agreements give factories stable run rates during seasonal lulls in private retail demand.

    The commercial vehicle ecosystem faces practical hurdles during this transition. State procurement departments historically prioritize low initial purchase prices over total cost of ownership. Battery degradation warranties, salvage values, and maintenance contracts across disparate rural provinces remain unproven at scale in Thai civil service budgets.

    Charging Networks Push for Roaming Standards

    Commercial charging operators stand to gain immediate throughput from centralized fleet operations. Thailand recorded 5,021 charging locations housing 15,290 connectors nationwide as of September 2026. The Energy Policy and Planning Office is running a parallel initiative to integrate these fragmented private charging platforms into a single “EV Roaming Hub” operating on a unified payment standard.

    The shift follows a sharp expansion in civilian passenger electric vehicle sales across the country. Department of Land Transport statistics compiled by the Federation of Thai Industries show Thailand registered 22,587 new EVs and electric motorcycles in September 2026, an 89.7 per cent increase from September 2025. Passenger electric cars accounted for 19,425 of those registrations, rising 98.6 per cent year on year.

    During the first nine months of 2026, total electric vehicle registrations reached 191,273 units, up 83 per cent from the same period in 2025. The Federation of Thai Industries projects full-year 2026 registrations will finish between 200,000 and 220,000 units, compared with roughly 120,000 vehicles registered throughout 2025.

    What to Watch Next

    The Energy Policy and Planning Office must submit the finalized fleet procurement guidelines to the central government for formal policy ratification. Automakers and fleet leasing companies are waiting for the draft to specify annual conversion quotas and the initial budget allocations for civil service charging depots.

  • Vietnam’s PNJ Shuts 30 Stores and Sheds 1,041 Jobs as Losses Mount

    Vietnam’s PNJ Shuts 30 Stores and Sheds 1,041 Jobs as Losses Mount

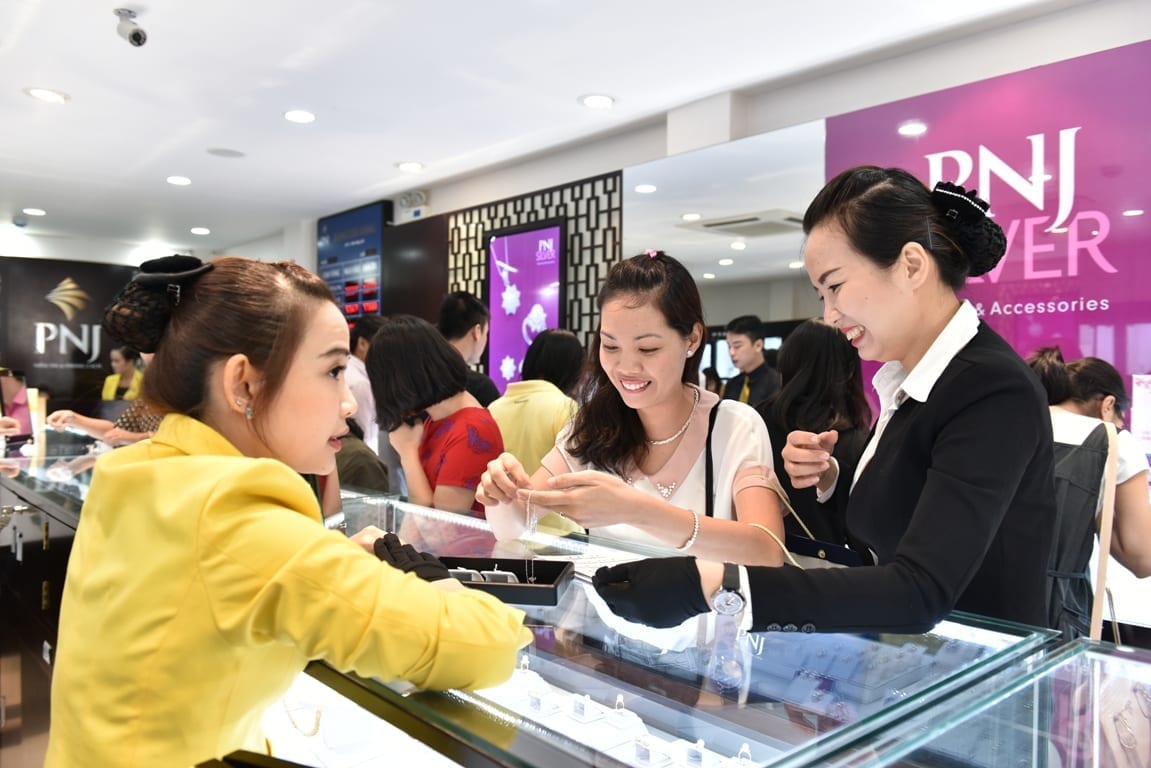
    Phu Nhuan Jewelry incurred a net loss of nearly VND258 billion (US$10 million) during the third quarter of fiscal 2026 as consumer demand softened.

    The financial strain forced the Vietnamese jewellery retailer to scale down operations, trimming its store network to 424 locations by September 30.

    That closure of 30 doors since June accompanied significant staff cuts, with payroll shrinking from 8,164 workers in December to 7,123 employees by the end of the quarter.

    Headcount drops past thousand mark

    PNJ’s payroll contracted alongside the store closures. The company had 7,123 employees on its books at the end of September, compared to 8,164 workers at the close of December, according to its latest financial disclosures. That represents a reduction of 1,041 jobs over nine months.

    Trading conditions across Vietnam’s discretionary retail sector deteriorated through the middle of the year as consumer sentiment flagged. For branded jewellery chains, fixed lease obligations and floor-staff costs turn cash-negative quickly when ticket sizes drop and shopper traffic thins.

    Pruning prime retail footprints

    The swift reversal at PNJ alters leasing dynamics for mall operators and high-street landlords. Retail landlords counted on domestic jewellery powerhouses to anchor regional centres and street corners through earlier retail cycles. With PNJ pruning underperforming locations rather than defending store counts, commercial property owners face lease renegotiations or vacancies in prime retail corridors.

    Competitors face identical consumer belt-tightening across Vietnam. Unbranded gold shops and local chains carry lower real estate overheads, leaving large organised networks exposed whenever discretionary spending retreats. PNJ is prioritising balance-sheet protection and working capital control over market coverage.

    Reversing post-pandemic network scale

    The retrenchment follows years of aggressive retail network expansion across second- and third-tier provincial markets. PNJ had scaled its retail presence beyond 400 branches to consolidate market share away from traditional independent gold stalls, betting on rising middle-income household consumption.

    That momentum reversed sharply during the third quarter. The abrupt shift from network additions to network consolidation indicates that the drop in discretionary spending caught the retailer with surplus floor space and excess store payroll.

    Targets and fourth-quarter demand

    Attention turns to whether fourth-quarter bridal purchases and holiday demand can stem further store closures before the Lunar New Year shopping period. PNJ’s upcoming full-year filing will show whether the network contraction stabilised at 424 branches or extended deeper into secondary cities.

  • Nio Delivers 3,000 ES9 Flagship SUVs in Shanghai as Overall Group Volume Drops

    Nio Delivers 3,000 ES9 Flagship SUVs in Shanghai as Overall Group Volume Drops

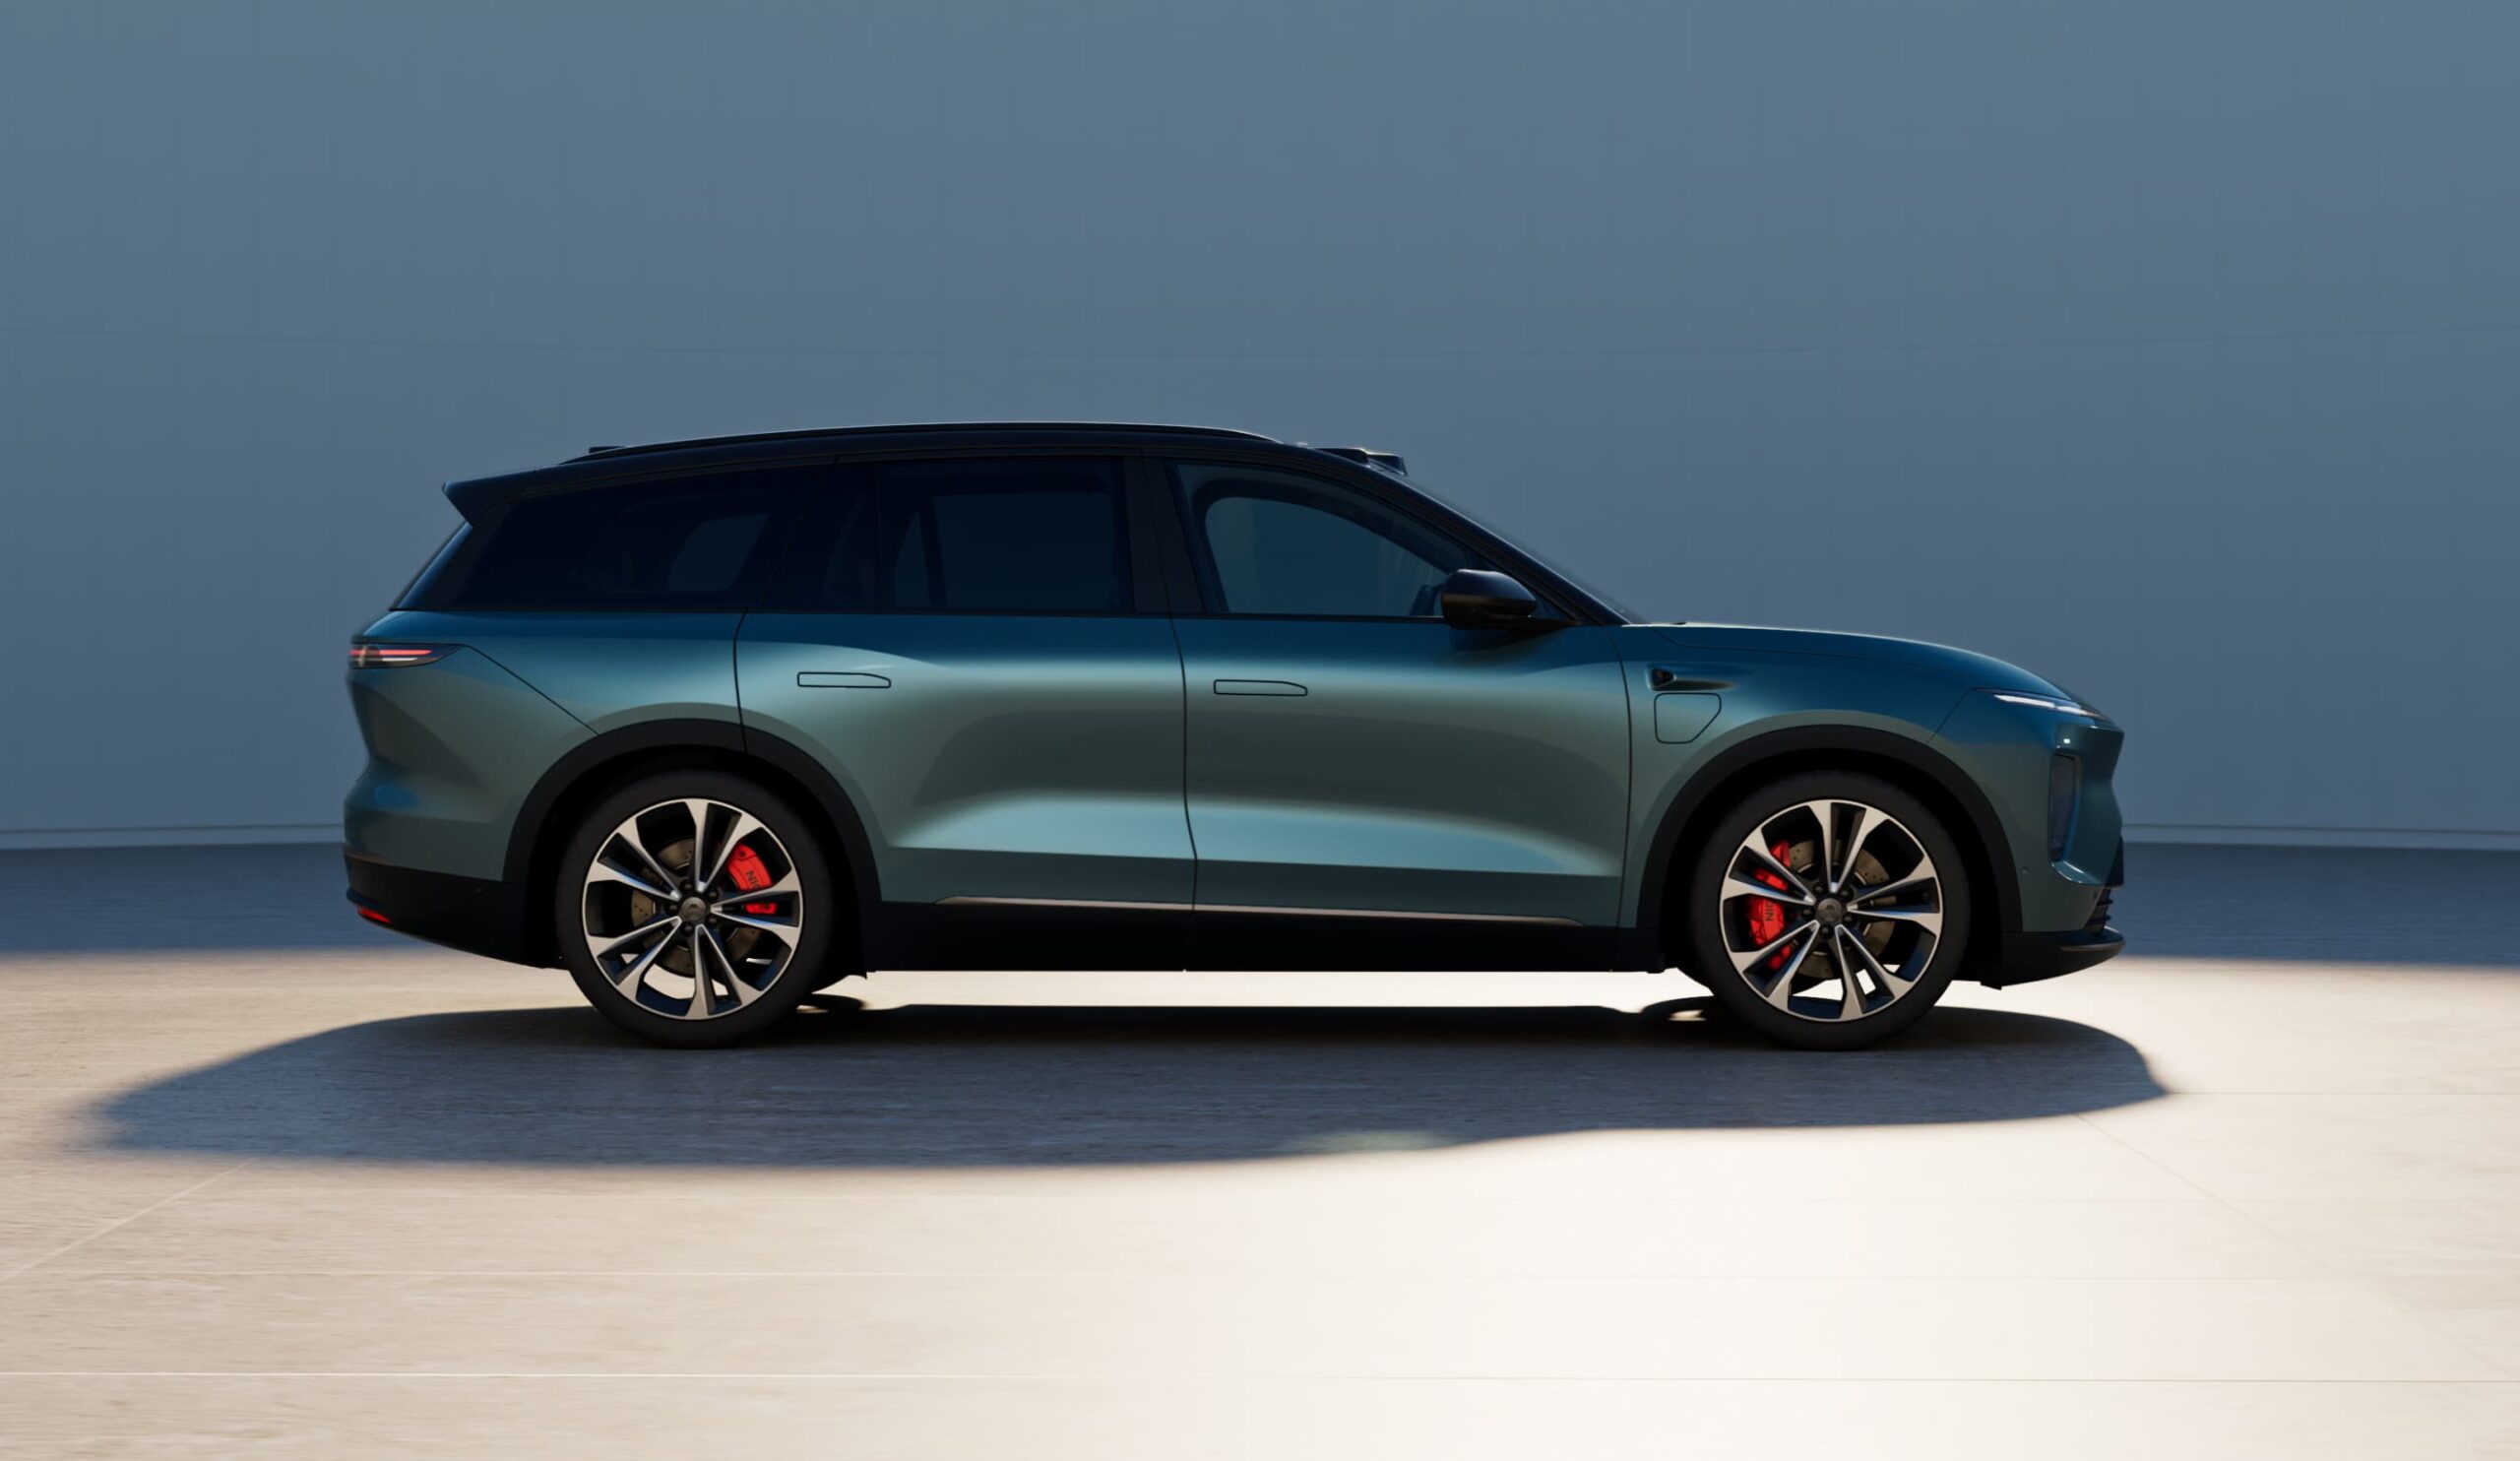
    Nio handed over its 3,000th flagship ES9 sport utility vehicle in Shanghai on November 2, completing five full operating months on the market in its global headquarters city.

    The electric vehicle retails from 498,000 yuan with battery pack included. Handover of the threshold unit took place at the Shanghai leg of the Nio Cup National Golf Invitational to a buyer replacing an internal combustion engine luxury model. Nio stated that the ES9 has led automotive sales for vehicles priced above 500,000 yuan in Shanghai across four consecutive months.

    Premium Traction in the Home Base

    Deliveries for the ES9 began on May 28, exactly one day following its official launch on May 27. The large sport utility vehicle took until July 5 to log its first 1,000 handovers in Shanghai, making the commercial hub the first Chinese municipality to reach that volume. Shanghai functions as a core sales engine for the company. During the first half of the year, Nio logged retail sales of 20,736 vehicles in Shanghai, representing 10.88 per cent of its nationwide retail volume over that six-month span, based on figures from Shanghai Jiading district government channels.

    National production and delivery rates for the model climbed steadily through the late summer. The ES9 posted 7,706 customer deliveries nationwide in September, an increase of 18.94 per cent from August. September represented the vehicle’s second-strongest monthly delivery tally since rolling off the assembly line, bringing total national ES9 deliveries to 32,203 units by the close of the third quarter.

    Large Formats Carry Main Brand Weight

    Top-tier models now account for the vast majority of showroom throughput at the core marque. In September, the ES9 and the smaller ES8 together generated 85.62 per cent of all deliveries under the primary Nio badge. High-ticket sport utility platforms continue to shield the brand from intense price erosion visible in lower consumer tiers, giving dealerships dependable transaction revenue per stall.

    Retail networks face an uneven showroom floor across company sub-brands. While the primary luxury marque logged 18,125 deliveries in October, up 5.73 per cent year on year, gains across that line and the budget-focused Firefly brand failed to counterbalance sharp slippage at mass-market unit Onvo. Relying almost exclusively on 500,000-yuan premium buyers restricts total addressable volume, leaving operational overhead exposed when mass-tier nameplates falter against domestic rivals.

    Widening Split Across Portfolio Divisions

    Corporate deliveries dropped 15.23 per cent year on year in October to 34,246 units across all operations. That monthly contraction snapped a continuous 31-month expansion streak for Nio Inc, dating back to February 2024. Factory allocations and component orders must now adjust to diverging showroom demand between premium sport utilities and entry brands.

    The older third-generation ES8 achieved 160,000 cumulative deliveries on October 23, adding its final 10,000 units over a span of 33 days. That long-term performance demonstrates steady customer retention in large-format battery-electric models. Preserving momentum at that price tier requires constant equipment iterations to deflect pressure from competing domestic executive limousines and family haulers.

    Guangzhou Debut to Test Marque Depth

    Portfolio development turns next to southern trade circuits before year-end financial accounting closes. Nio plans to introduce a special edition of the ES8 at the Guangzhou Auto Show in late November, testing whether upgraded equipment trims can defend high-margin utility sales against newer luxury entries.

  • ShopX Launches Global Retail Media Group Across 27 Markets

    ShopX Launches Global Retail Media Group Across 27 Markets

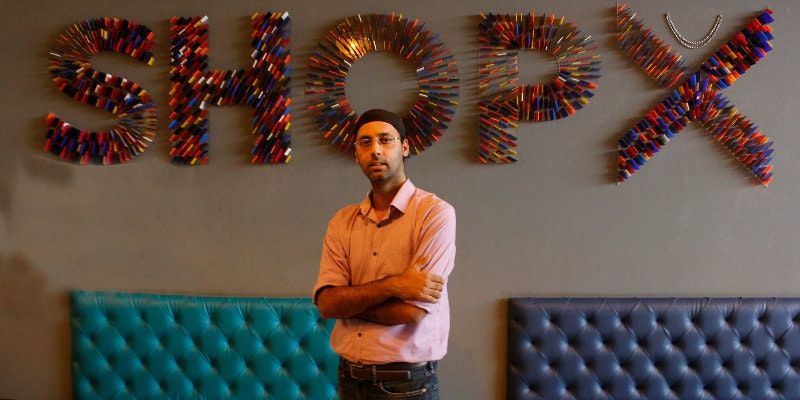
    ShopX has launched as a global retail media group combining Shopfully, Flipp and MEDIA CENTRAL into a unified parent organisation reaching 400 million shoppers across 27 markets, including Australia.

    The combined business employs more than 1,000 people and works with thousands of retailers and consumer packaged goods brands. While the parent entity centralises technology and scale, each of the three regional businesses continues operating under its established commercial brand.

    Led by Group Chief Executive Officer Michael Silverman and Group President and Chief Operating Officer Stefano Portu, the platform targets a USD $200 billion global retail media sector where spending remains heavily tilted toward e-commerce rather than physical checkouts.

    Consolidating Store-Led Ad Spend

    Each of the three regional businesses retains its standalone operating brand and existing commercial accounts. The parent entity pools backend engineering, measurement tools and cross-border audience data.

    Physical shops account for roughly 80 per cent of all retail transactions globally, climbing to nearly 90 per cent for fast-moving consumer goods. In Australia, Shopfully research tracks 83 per cent of shoppers researching products online before completing transactions inside brick-and-mortar stores. Connecting those digital search signals to checkouts remains a central operational hurdle for consumer goods suppliers.

    Global retail media ad spending has reached USD 200 billion, though brands spend most of that capital across e-commerce marketplaces rather than physical storefronts. ShopX aims to capture those budgets by aggregating multi-retailer inventory instead of forcing advertisers to negotiate separate data-sharing agreements with individual supermarket operators.

    Management and Platform Integration

    Group Chief Executive Officer Michael Silverman leads the executive board alongside Group President and Chief Operating Officer Stefano Portu. Jaclyn Welsh serves as Group Chief Financial Officer, while Ingo Wienand retains his position as Chief Executive Officer of MEDIA CENTRAL alongside a board seat at the parent group.

    Aggregators provide consumer brands with scale across catalogue apps, publisher networks and digital circulars that single supermarket operators struggle to replicate independently. The risk sits in data verification, because closed-loop attribution for physical checkouts requires point-of-sale integration that supermarket chains guard closely.

    The Race for Off-Platform Budgets

    Major grocery operators run proprietary retail media units to monetize their first-party loyalty card records. Intermediaries like ShopX offer an alternative channel for mid-tier retailers that lack the software budgets required to build bespoke ad networks.

    Consolidation has driven the company’s expansion to date, with the constituent businesses completing 10 acquisitions prior to unifying under the ShopX umbrella.

    Stefano Portu, Group President & Chief Operating Officer, ShopX, said: “What we have built so far is the starting point. Most shopping still happens in stores, and most of it is invisible to the brands that pay to influence it. At ShopX, we are here to change that by connecting shoppers, retailers, brands, and publishers around physical retail.”

    Expansion Targets

    The operating units previously built independent footprints, including in Australia, through digital catalogue syndication. Unifying them allows global brand manufacturers to run single international advertising campaigns across shared retail networks.

    Management plans to deploy fresh capital into attribution software, enter additional geographic markets and target further acquisitions to absorb fragmented local promotional platforms.

  • Chinese Embodied AI Startups Draw 93.5 Billion Yuan in First Half

    Chinese Embodied AI Startups Draw 93.5 Billion Yuan in First Half

    Chinese embodied artificial intelligence developers raised 93.5 billion yuan ($13 billion) across 322 funding deals in the first half of 2026, according to data research firm ITjuzi. That figure represents a fivefold jump from the same period a year earlier, shifting capital from mechanical hardware into the software models that direct autonomous machines.

    Hardware makers are slashing retail prices on bipedal frames and robotic arms to secure market share, destroying manufacturing margins in the process. The shift forces commercial value into cognitive models capable of handling physical labor without custom engineering for every task.

    Where the Capital Lands

    Three specialist software developers, X Square, Galaxea, and Spirit AI, have each reached private valuations of roughly $3 billion, based on company disclosures. Hong Kong-listed UBTech advertised an executive compensation package of up to 124 million yuan ($18 million), including equity and benefits, to recruit a chief scientist for its AI model team. Hangzhou-based Unitree, one of the world’s largest humanoid robot producers by volume, now maintains a team of roughly 30 researchers dedicated to spatial physics and predictive object behavior.

    Hardware has become a commodity faster than expected across supply chains. Chinese builders can assemble a dynamic bipedal chassis at a fraction of Western production costs, but those machines remain commercially useless if every warehouse shelf or retail counter requires months of custom code. The venture money is now chasing generalist models that allow an off-the-shelf unit to unload pallets, stock pharmacy displays, or thread industrial wiring with minimal training.

    That dynamic alters procurement calculus for logistics networks, retail operators, and assembly plants across Asia. Instead of paying hefty integration retainers to robotics vendors, supply chain directors are testing software subscriptions that deploy across mixed fleets of machines. The operational risk lies in real-world error rates: while simulated environments and human video clips allow rapid laboratory demonstrations, factory floors and convenience stores tolerate zero mistakes.

    Data Collection in Pharmacies and Plants

    Different developers are testing competing training methodologies to feed physical data to their networks. Spirit AI hired roughly 1,000 workers to record routine manual tasks and industrial activities, according to co-founder Gao Yang. ACE Robotics strapped wearable sensors onto store clerks and hotel hospitality staff to record precise grip strength and hand movements during service shifts.

    Ant Group’s robotics unit, Robbyant, trained its model using 160,000 hours of operating material, which included 50,000 hours of human-guided mechanical movements. The group tested its software across 20 robot configurations built by 17 different equipment brands, seeking a cross-platform operating system for physical automation. In Shanghai, Robbyant deployed robots into two commercial pharmacies to pick and organize retail prescriptions, leaving human pharmacists to inspect the items before dispatch.

    Industrial plants demand higher precision than retail counters. Battery manufacturer CATL integrated Spirit AI machines into its Zhongzhou production facility, running flexible wire assembly during pack testing. The battery maker reported an insertion success rate above 99 per cent on that specific line.

    Simulations Meet Hardware Bottlenecks

    Other software houses bypass physical recordings entirely. DexForce uses synthetic computer-generated training environments to prepare robotic arms for precision tasks within six to eight hours, reporting operational success rates above 99.9 per cent on defined factory assignments. However, spatial intelligence developers such as Manycore Tech caution that computer graphics fail to simulate micro-friction, material deformities, and changing warehouse lighting conditions.

    The push into advanced physical modeling faces immediate structural constraints inside mainland laboratories. United States export controls on advanced Nvidia processors limit access to the compute clusters needed to train large vision-language-action models. Chinese startups are turning to synthetic data pipelines, model pruning, and domestic processors developed by Huawei to bypass the compute bottleneck, but the processing gap widens as networks scale.

    Next Steps for Industrial Deployment

    The transition from bespoke factory automations to adaptive common-sense robotics marks the next phase of China’s robotic push. Unitree founder Wang Xingxing reported experimental success testing OpenAI’s GPT-6 model on walking units, setting an operational target where robots complete 80 per cent of assignments across 80 per cent of unfamiliar retail and factory environments via direct voice instructions.

    Whether domestic models can match that benchmark without unrestricted access to foreign silicon remains the central variable for Chinese supply chain tech, and will show whether these 93.5 billion yuan in capital commitments translate into profitable labor replacement.

  • Geely Sells 310,183 Cars in October as Exports Surge 157 per Cent

    Geely Sells 310,183 Cars in October as Exports Surge 157 per Cent

    Geely Auto sold 310,183 vehicles in October, finishing just 245 units shy of its all-time monthly record set in November 2025.

    Strong overseas shipments offset a sharp contraction at home, with export volumes jumping 157.78 per cent year-on-year to 107,153 units.

    Deliveries rose 0.99 per cent compared to October last year and gained 6.17 per cent from September. The performance represented the manufacturer’s second-highest monthly volume on record and its highest total in 2026. However, overall annual sales expansion slowed to roughly 1 per cent because the downturn across mainland China widened.

    Domestic Contraction Deepens in Mainland China

    Home-market demand weakened considerably across Geely’s domestic retail pipeline. The carmaker delivered 203,030 vehicles in China during October, a decline of 23.55 per cent compared to the same month last year. That fall accelerated from a 20.21 per cent decrease recorded in September.

    Sequentially, domestic figures showed modest resilience. Chinese showroom volumes climbed 9.46 per cent from September, logging their best single-month total since January. For the first 10 months of the year, Geely’s cumulative mainland deliveries fell 23.31 per cent to 1,640,841 units.

    Electric Volume Crosses 200,000 Mark

    Electrified drivetrains took a commanding share of total output. Deliveries of new energy vehicles climbed 20.86 per cent year-on-year and 12.64 per cent from September to 214,996 units, crossing the 200,000 mark in a single month for the first time. The category accounted for 69 per cent of all cars sold during the period.

    Battery-electric models drove the segment’s expansion, rising 43 per cent year-on-year to 140,758 units. In contrast, plug-in hybrid electric vehicle shipments declined 6.66 per cent to 74,238 units. The drop broke a flat trend seen in September, when plug-in hybrid volumes held steady against previous-year tallies.

    Brand Performance Shows Divergence

    Brand contributions revealed stark divides across Geely’s corporate umbrella. The core Geely badge, which includes the Galaxy series, delivered 255,742 vehicles in October, rising 4.17 per cent year-on-year and 8.15 per cent from the previous month. Galaxy set a monthly record of 153,385 units, a gain of 20.32 per cent from a year earlier, lifting its year-to-date total to 1,030,569.

    Zeekr registered 32,483 deliveries, up 51.63 per cent from a year ago. That gain ended a nine-month streak where the premium electric badge expanded at or near triple digits. Sequentially, Zeekr dropped 12.72 per cent, suffering its first month-on-month decline since January. Lynk & Co recorded 21,958 deliveries, slumping 45.40 per cent year-on-year for its seventh straight monthly fall, even as volumes climbed 18.74 per cent from September.

    Target Pressures and Export Reliance

    The operational split between local retail weakness and foreign expansion puts structural margin pressure on Geely’s distribution network. Overseas deliveries generated 35 per cent of all volume in October, slightly down from 37 per cent in September but representing an enormous jump from 2025. While foreign distribution commands higher showroom retail prices in developing markets, cross-border freight costs and regional import duties eat into those returns. Chinese dealerships, meanwhile, face persistent price discounting as local buyers pivot away from internal combustion models faster than the core network can adjust.

    Rival domestic manufacturers face similar cross-border dynamics, but Geely has shifted its physical inventory overseas at an accelerated pace. Across the first 10 months of 2026, cumulative exports climbed 167.94 per cent to 904,823 vehicles. That total completed 98 per cent of its full-year foreign shipment goal of 920,000 units, leaving roughly 15,000 cars to ship over November and December. Geely had revised that export target upward on August 17 from an earlier goal of 640,000.

    Total group volume reached 2,545,664 units between January and October, representing an increase of 2.76 per cent from the same period last year. Year-to-date brand tallies show the core Geely line down 1.18 per cent at 2,006,702 units and Lynk & Co down 22.58 per cent to 218,075. Zeekr remains the main volume booster over the 10-month window, rising 94.45 per cent to 320,887 units.

    Meeting management’s overall objective will require unprecedented sales speed. Geely has secured 74 per cent of its full-year target of 3,450,000 vehicles, leaving a deficit of 904,336 units. To clear that benchmark, the company must average roughly 452,000 vehicle deliveries in each of the remaining two months, well above the record 310,428 achieved in November 2025.

  • Oriental Kopi Targets Indonesia and Japan for Overseas Expansion

    Oriental Kopi Targets Indonesia and Japan for Overseas Expansion

    Malaysian cafe operator Oriental Kopi plans to open outlets in Indonesia and Japan, extending its domestic kopitiam model into two major regional consumer markets.

    Founder Calvin Chan established the brand after noticing a shortage of Malaysian food chains while traveling across China, Taiwan, and Hong Kong for his former mobile phone business.

    Currently operating outlets in Kuala Lumpur shopping hubs, the chain relies on halal certification to anchor its entry into foreign markets.

    Targeting Indonesia and Japan

    The company relies on halal certification to support its international expansion, particularly in Muslim-majority Indonesia where regulatory compliance dictates consumer adoption. Japan represents a secondary target where the brand intends to introduce Malaysian breakfast fare, including traditional coffee brews, pastries, and localized street dishes, directly into urban shopping centers.

    Chan previously ran a mobile phone business across mainland China, Taiwan, and Hong Kong. That travel schedule exposed a notable imbalance: while Japanese, Thai, and Vietnamese operators maintained broad real estate footprints across commercial districts, Malaysian operators remained largely absent.

    Operational Hurdles in Foreign Real Estate

    Entering overseas consumer markets tests the unit economics of traditional kopitiam formats. Unlike quick-service beverage stalls that occupy small mall kiosks, full-service coffee and dining concepts require extensive kitchen exhaust systems, larger floorplates, and higher front-of-house headcount. In high-rent hubs, maintaining competitive price points while serving labor-intensive dishes creates immediate margin pressure.

    Supply chain reliability forms the other primary risk. Exporting signature pastry crusts, spice pastes, and beverage bases while satisfying local import standards demands established central commissary arrangements or reliable local manufacturing partners. Without localized sourcing, shipping costs can erode operating margins before store-level profitability stabilizes.

    The Regional Casual Dining Playbook

    Regional operators built cross-border networks over the past decade by standardizing recipes into shelf-stable bases and striking joint ventures with master franchisees. Taiwanese tea brands proved that suburban mall developers across Asia actively seek high-traffic casual dining brands to drive footfall away from e-commerce.

    Oriental Kopi established its initial operational footprint within Kuala Lumpur’s primary shopping malls, drawing domestic consumer queues for signature egg tarts and white coffee before attempting overseas export.

    Next Steps for International Openings

    Management must now secure local operating partners or direct retail leases to finalize its debut overseas store sites.

  • Energy North Pulls June 2028 Target for 1 GW Outback Data Centre

    Energy North Pulls June 2028 Target for 1 GW Outback Data Centre

    Australian developer Energy North dropped its planned June 28, 2028 operational target for a 1-gigawatt outback data campus after the Northern Territory environment regulator suspended its statutory review deadline.

    The referral proposed building the off-grid facility across a 191-square-kilometre cattle station located 683 kilometres from the nearest city, combining dedicated solar arrays with gas turbines.

    Work on the schedule stopped after the Northern Territory Environment Protection Authority issued an October 7 ruling pausing its standard seven-week evaluation period. The regulator stated it will seek guidance from federal authorities, who are drafting national policy frameworks for artificial intelligence infrastructure developers.

    Land Size Meets Regulatory Resistance

    Project Ares stands out as the largest Australian computing site forced to withdraw its commissioning schedule. In regulatory filings lodged four months ago, the company presented the June 2028 connection as an indicative benchmark before the local watchdog raised red flags.

    The agency identified 10 distinct environmental threats, citing possible depletion of local water tables and physical disruption to Indigenous sacred sites. In its formal finding, the regulator noted a low level of confidence in the developer’s proposed risk mitigations.

    Plans for the facility call for self-contained infrastructure, including an airfield, dedicated gas turbines, and temporary housing quarters for 4,300 construction personnel. Company management declined to identify the external lenders providing project finance.

    Grid Constraints Drive Developers Into Remote Basins

    Tech infrastructure investors face worsening bottlenecks near primary metropolitan hubs, driving developers toward isolated acreage despite logistical barriers. Goodman abandoned a planned facility in suburban Sydney following community objections, while NextDC postponed a Melbourne expansion due to power grid limitations.

    Hyperscalers and regional platform operators require continuous baseload power that established urban distribution networks can no longer supply without extensive upgrades. Going off-grid into remote pastoral regions solves metropolitan power queuing, but it exchanges utility disputes for complex cultural heritage consents and environmental oversight.

    Regional enterprise tenants in commerce, logistics, and retail banking face higher hosting overheads as pipeline capacity stalls. Operators competing for regional AI workloads cannot easily bypass standard administrative review simply by choosing empty land.

    Pastoral Leases and Indigenous Approvals

    Northern Territory authorities have pitched the jurisdiction’s 260,000 residents and desert climate to capture part of the $7 trillion in global AI data centre capital forecast by McKinsey by 2030. Commercial gas supplies from Tamboran Resources’ Shenandoah South project in the Beetaloo Basin began flowing to Darwin on September 1, 2026, offering developers a local source of fuel.

    Scale remains a major technical hurdle. A separate proposal from Beetaloo Energy near Darwin aims for 2 gigawatts, a footprint requiring up to 400 terajoules of gas daily, or ten times current production from the basin’s only active project.

    Securing project consent across the Territory requires prolonged community rounds with Indigenous traditional owners, who make up a quarter of the local population. Representatives from the Northern Land Council warned federal inquiries that accelerating consultations fails to yield lawful consent, leaving final project approvals exposed to court challenges.

    The Northern Territory EPA has set no revised date to establish terms for the project’s formal environmental impact statement.