Author: Mei Ling Tan

  • Minor Food Targets 4,500 Outlets by 2029 in Global Franchise Push

    Minor Food Targets 4,500 Outlets by 2029 in Global Franchise Push

    The Minor Food Group Plc plans to expand its network to more than 4,500 food and beverage outlets by 2029, leaning on franchise partnerships to drive cross-border growth. The conglomerate currently runs more than 3,000 stores across 27 countries, meaning the plan requires adding roughly 1,500 locations over the next five years.

    About two-thirds of the group’s current footprint remains concentrated in Thailand. Roughly half of the existing 3,000 outlets run under franchise agreements, and Chief Development Officer Thunyachate Ekvetchavit said the majority of future openings will use the franchise model rather than direct company ownership.

    Targeting High-Density Offshore Hubs

    Management is directing international development toward Indonesia, Vietnam, South Asia and the Middle East. These markets offer favourable consumer demographics and rising discretionary spending on casual dining, giving established multi-brand operators room to scale without committing massive capital expenditure to real estate leases.

    By shifting the capital expenditure burden to local franchisees, Minor Food lowers its exposure to commercial property cycles across volatile emerging markets. The model mirrors the playbook long deployed by global fast-food giants, yet it shifts the primary execution risk directly onto franchisee balance sheets and local supply chain logistics.

    Building Domestic Traffic and Retail Partnerships

    On its home turf, Minor Food is deepening ties with commercial landlords and fuel retailers to secure steady customer footfall. Recent arrangements pair the company with CP Axtra Plc, which operates wholesale brand Makro and hypermarket chain Lotus’s, alongside PTT Oil and Retail Business Plc to place restaurant brands into petrol stations and roadside convenience hubs.

    These tie-ups give the operator captive traffic in non-traditional retail real estate while domestic mall footfall fragments across Bangkok. Securing perimeter retail locations inside high-traffic grocery nodes and highway forecourts shields store margins against rising inner-city commercial rents.

    Scaling Bonchon and Launching Chicho Ramen

    Cross-border scale gained momentum following the acquisition of Bonchon International, which gave the group full control of the Korean fried chicken franchise. Minor Food plans to expand Bonchon into Europe, the Middle East and wider Asian territories, using the established global recognition of the brand to enter territories where its legacy Western fast-food franchises face saturated competition.

    Back in Bangkok, the group is launching a new proprietary concept named Chicho Ramen on 30 October at Lotus’s Sukhumvit 50. Minor Food plans to scale Chicho Ramen to between 90 and 100 stores within three years, seeking to contest a local ramen sector dominated by a single major chain alongside fragmented independent shops.

    Managing Commodity Pressures

    Cost pressures remain contained across the restaurant system despite ongoing geopolitical frictions affecting global shipping routes. Raw material expenses across the supply chain rose about 3 per cent, while logistics costs increased only marginally, cushioned by hedging programs and bulk-purchasing contracts across regional vendors.

    The immediate operational test arrives with the debut of Chicho Ramen on 30 October, which will show whether Minor Food can build another domestic mass-market chain from scratch while hunting master franchisees across the Middle East and Southeast Asia.
  • SIA Buys up to 4,800 Tonnes of Sustainable Fuel from Aether

    SIA Buys up to 4,800 Tonnes of Sustainable Fuel from Aether

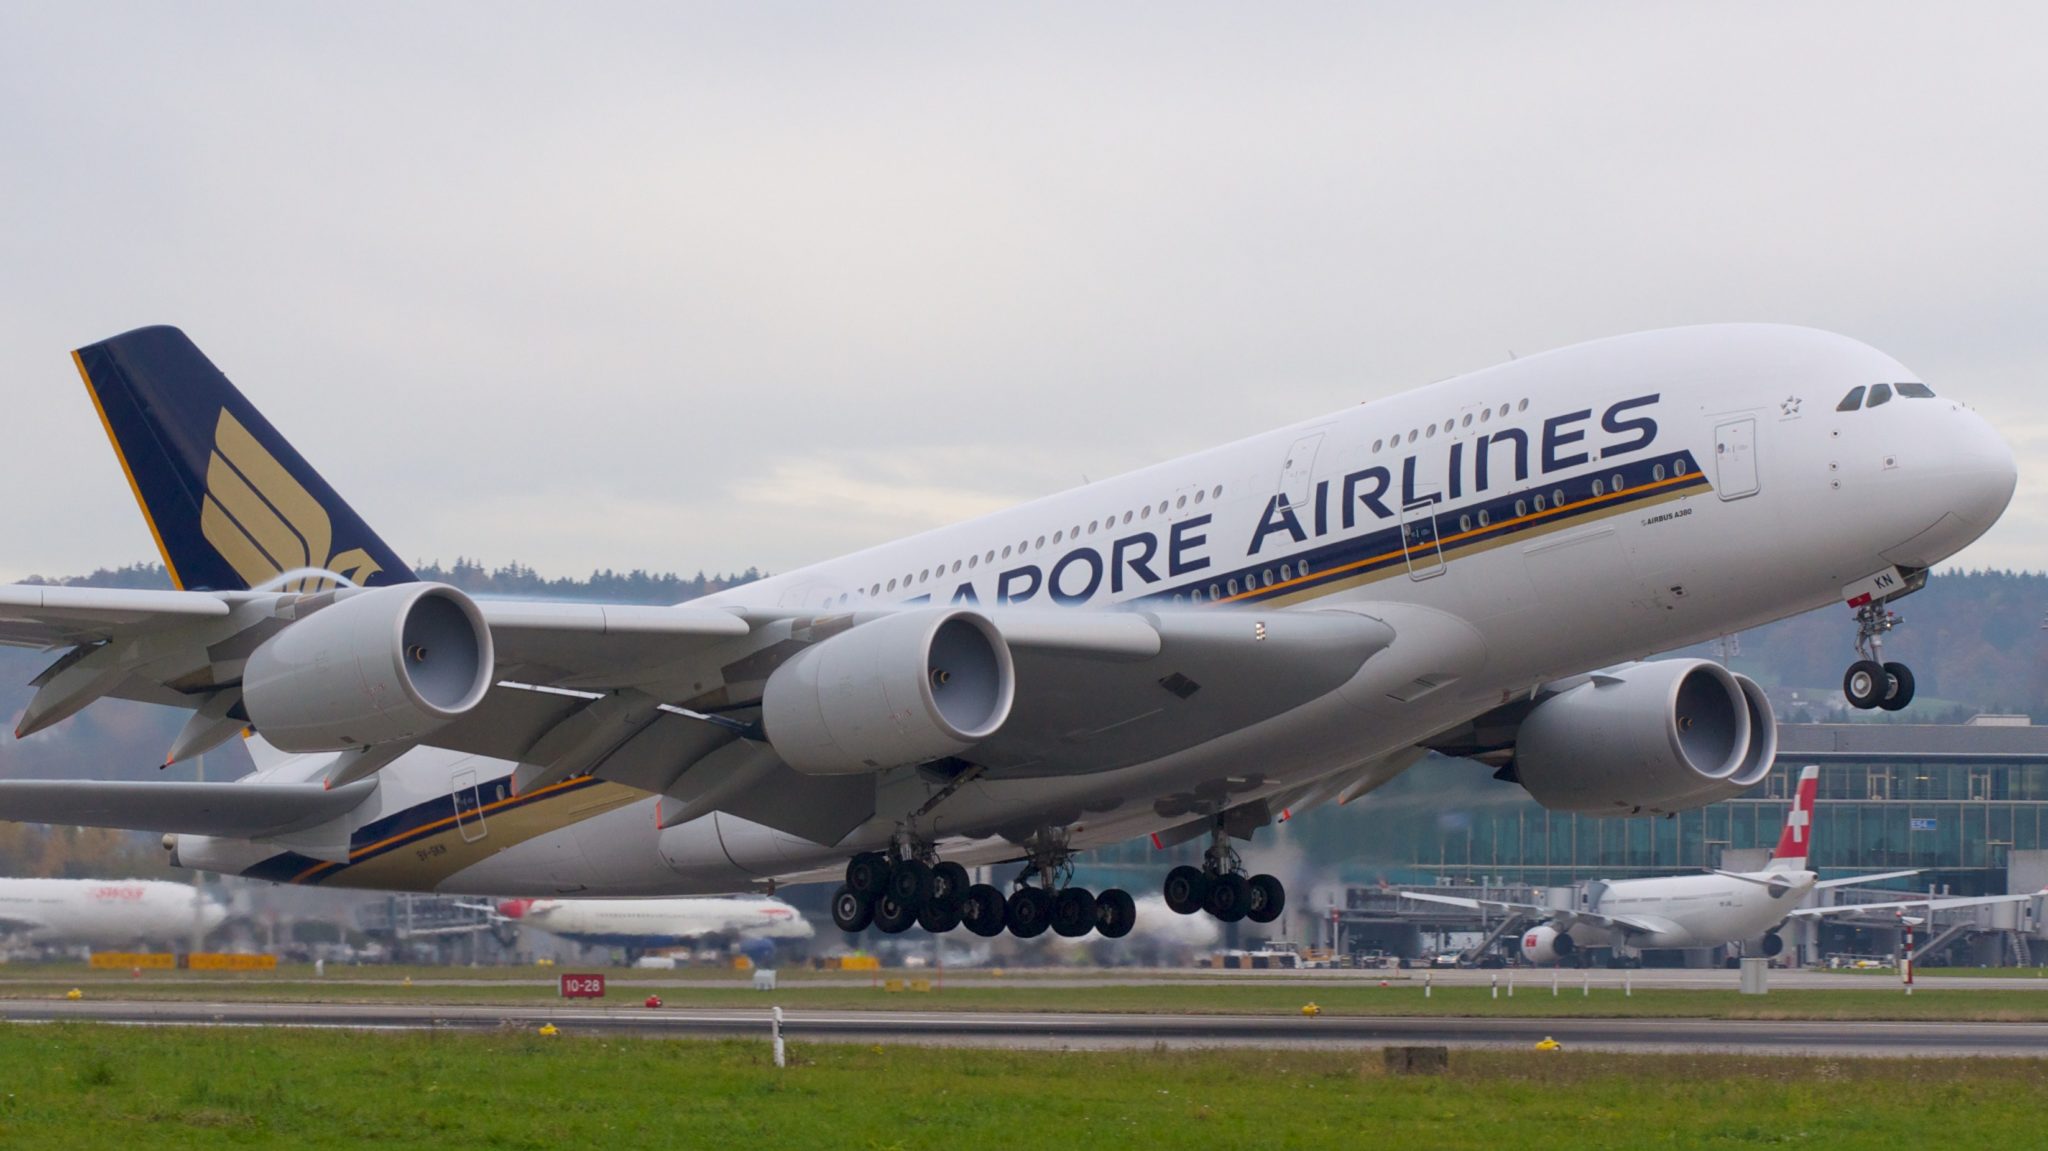
    Singapore Airlines (SIA) has inked a deal to purchase up to 4,800 tonnes of sustainable aviation fuel over three years from Aether Fuels’ Singapore plant, with deliveries starting in 2028.

    The binding agreement, signed on Oct 23, makes the carrier the first buyer of fuel from Project Beacon, which Aether is developing at Aster’s refining complex at Pulau Bukom, according to a joint statement released on Oct 28.

    Under Project Beacon, feedstocks such as biomethane and industrial waste gases will be converted into aviation fuel, marking SIA’s first purchase of sustainable fuel produced via waste carbon technology rather than conventional lipid-based pathways.

    Waste gases replace lipid feedstocks

    This approach offers an alternative to the hydro-processed esters and fatty acids pathway, which relies on more constrained lipid-based feedstocks.

    The agreement builds on the memorandum of understanding (MOU) signed between SIA and Aether in 2025.

    Supply limits and aviation costs

    Since signing the MOU, Aether has established its first commercial facility in Singapore, while also building partnerships across the local value chain.

    “Singapore is building a strong ecosystem for aviation decarbonisation through refining and aviation infrastructure, investment support, sustainability policies, and utilising its position as a global aviation hub,” said Conor Madigan, co-founder and chief executive of Aether.

    Building out the Bukom project

    Lee Wen Fen, chief sustainability officer at SIA, said that supporting the development and adoption of sustainable aviation fuel, as well as securing future supplies, is integral to SIA’s ambition of achieving net-zero carbon emissions by 2050.

    “We will continue to work with partners globally to scale sustainable aviation fuel production, strengthen the aviation industry’s sustainability ecosystem, and support the transition to more sustainable air travel,” she added.

    Target dates and local mandates

    Deliveries under the binding agreement are scheduled to begin in 2028 from the Pulau Bukom site as both companies work toward supporting long-term aviation decarbonisation goals.

  • Samsung Posts Record Tech Profit on Memory Demand but Shares Slide

    Samsung Posts Record Tech Profit on Memory Demand but Shares Slide

    Samsung Electronics delivered the tech sector’s highest quarterly profit on Thursday in Seoul, but its shares tumbled as investors balked at the escalating capital spending required to service artificial intelligence infrastructure.

    The company said on Oct. 29 that heavy appetite for memory products will run through upcoming quarters as hardware vendors and cloud operators build out AI computing clusters.

    Spending Outpaces Dividend Expectations

    Shareholders sold down the stock despite the blockbuster headline figures, reacting directly to the sheer scale of reinvestment needed to sustain technical leadership. Big allocations for fabrication equipment, advanced packaging lines, and server components left institutional investors dissatisfied with immediate capital returns.

    Hardware manufacturers across Asia face the same squeeze. Memory lines require billions of dollars in fresh cash before producing top-tier silicon, shrinking the free cash flow available for payouts even during record quarters.

    Demand from Servers and Personal Agents

    The South Korean manufacturer pointed to accelerating buildouts of enterprise data centres and the arrival of personal AI agents on consumer devices as the dual engines behind memory demand. Server operators continue to soak up high-bandwidth memory chips to keep accelerators fed with data.

    Smartphone vendors and laptop brands across Asia are also preparing their component pipelines for local device processing. That switch requires higher minimum configurations of DRAM in consumer phones, protecting semiconductor makers from typical seasonal troughs.

    The Balance of Supply and Capital Risk

    For component distributors, device assemblers, and electronics retailers across the region, Samsung’s heavy production spending offers both volume security and price uncertainty. If the buildout of personal AI devices stumbles at retail, excessive chip inventories will depress pricing across downstream channels.

    Rival foundries and competing memory suppliers in Taiwan and South Korea are maintaining similar capital budgets to defend client allocations. That leaves the broader electronics supply chain exposed to an oversupply shock if corporate software budgets tighten.

    Earlier Cycles and What to Watch

    Memory markets regularly swing between inventory gluts and acute shortages, with producers historically suffering margin collapses after periods of unbridled factory construction. The current cycle differs only in the customer base, which is anchored by cash-rich cloud titans rather than consumer electronics brands alone.

    Markets now turn to the sustainability of server procurement through the coming quarters, alongside Samsung’s upcoming capital expenditure filings, to see whether production increases outpace corporate orders.

  • Australian Retailers Sound Caution as Early Fiscal 2027 Sales Slow

    Australian Retailers Sound Caution as Early Fiscal 2027 Sales Slow

    JB Hi-Fi reported a 1.4 per cent drop in Australian sales between July and September, leading a batch of warnings across the country’s listed retail sector ahead of peak holiday trade.

    The contraction follows record sales across fiscal 2026, catching investors off balance as early fiscal 2027 trading updates exposed soft consumer sentiment. Three major retail operators, JB Hi-Fi, Wesfarmers, and Super Retail Group, shed a combined 450 points on the ASX after delivering their pre-annual general meeting trading numbers.

    Household Goods Face Margin Squeeze

    Weakness extended beyond consumer electronics into whitegoods and home renovations. JB Hi-Fi reported that sales at its appliance arm The Good Guys dropped 0.4 per cent during the three-month opening quarter. Its kitchen retailer, E&S, fell sharper, booking a 4.5 per cent sales drop over the same period.

    Shoppers across Australia are delaying standard purchases to wait for steep discount cycles. JB Hi-Fi told shareholders that October turnover showed further deceleration, leaving store networks dependent on heavy promotional volumes to salvage the first half.

    “In October, the group has seen sales slow ahead of the important Black Friday and Christmas trading periods. As always, the group will continue to focus on driving demand and growing market share through creating great value offers for its customers and delivering exceptional customer service.”

    Hardware Pulls Back While Discount Stores Hold

    Diversified conglomerate Wesfarmers pointed to uneven conditions across its divisions. Flagship home improvement business Bunnings recorded dwindling sales momentum after years of outsized pandemic and post-lockdown DIY demand. By contrast, budget department store Kmart and office supplies chain Officeworks sustained stable customer transaction levels.

    Super Retail Group Tracks Sector Slowdown

    Automotive and outdoor leisure operator Super Retail Group matched the downbeat assessments from electronics and home improvement sellers. The group runs Supercheap Auto, Macpac, Rebel, and BCF across Australian shopping centres and retail parks.

    Managing director and chief executive Paul Bradshaw stated that like-for-like sales growth moderated across the group during the opening months of fiscal 2027. Discretionary spending cuts and lingering consumer anxiety hit transaction values across sporting goods, camping gear, and vehicle accessories.

    Trading Focus Shifts to November Volumes

    Australian retailers relied on strong pricing power through fiscal 2026 to offset wage rises, high energy bills, and rent increases. That pricing use has evaporated, leaving merchants exposed to discounting wars to protect foot traffic.

    The immediate test for retail margins lands in late November when Black Friday promotions run across physical store networks and e-commerce platforms. Store groups must now balance inventory clearances against margin erosion as annual general meetings continue through November.

  • ByteDance’s PineDrama Enters Top 10 Free iPhone App Charts in Three Countries

    ByteDance’s PineDrama Enters Top 10 Free iPhone App Charts in Three Countries

    ByteDance has taken PineDrama, its overseas short-drama platform, into the top 10 on the iPhone free-app charts in the United States, Brazil, and Thailand, according to a report by Jiemian News published in October 2026.

    Operated independently by a dedicated team inside TikTok’s business division rather than by the group behind Hongguo Short Drama, the application has maintained steady download momentum since its rollout.

    Unlike competing services such as ReelShort and DramaBox that depend on paywalls and micro-transactions, PineDrama adopts the completely free-to-watch ad-monetized structure pioneered by Hongguo Short Drama, capitalizing directly on TikTok traffic to bypass expensive third-party user acquisition.

    Cutting Out the Paywall

    Unlike established overseas short-drama platforms such as ReelShort and DramaBox, which rely on paid viewing models, PineDrama has adopted the free-to-watch approach used by Hongguo Short Drama, monetizing its content through advertising.

    TikTok’s traffic gives PineDrama direct access to a large audience, while its competitors rely more heavily on paid user acquisition through third-party platforms. This creates a gap in user acquisition costs and efficiency.

    Drawing From Online Fiction IP

    Content is another key advantage. Most of PineDrama’s short-drama producers currently come from China, and many have experience operating on Hongguo, Douyin, or TikTok. Meanwhile, the platform is also working to attract local overseas producers and expand its supply of original content.

    ByteDance’s ecosystem also offers a relatively mature IP partnership model. Producers can obtain licenses from the platform’s content library or distribute original scripts independently. For production teams, established cooperation procedures can reduce the time and effort required to negotiate individual deals.

    According to one producer, around 70% to 80% of the IP used in the AI-generated animated dramas made by their team comes from Tomato Novel, ByteDance’s online fiction platform. Compared with relying entirely on original scripts, established IP can reduce uncertainty in content selection. The platform’s tiered authorization system also gives producers a pathway to move from promising titles to premium IP.

    When traffic, IP resources, and production capabilities form a closed loop, ByteDance is building more than just a short-drama app. It is creating an integrated system for content production and distribution.

    The Margin Squeeze on Third Parties

    At the same time, intensifying competition in China’s short-drama market is pushing more production teams to seek growth opportunities overseas.

    One producer noted that computing power accounts for a significant share of AI-drama production costs in China, while paid traffic acquisition also requires substantial investment. On TikTok and PineDrama, some productions can attract considerable viewership without additional spending on promotion, and overseas revenue-sharing returns can be more attractive.

    However, the revenue figures cited by individual producers reflect specific experiences and should not be taken as representative of the industry as a whole.

    From its free viewing model and IP partnerships to its global content strategy, PineDrama is extending the short-drama ecosystem advantages ByteDance has developed in China to international markets.

    The key question going forward is not simply how many downloads the platform can generate, but whether it can consistently produce hit titles and build a sustainable content supply chain and monetization model overseas.

  • Index Living Mall Invests up to 100 Million Baht in Bangkok Sports Complex

    Index Living Mall Invests up to 100 Million Baht in Bangkok Sports Complex

    Index Living Mall Plc (ILM) has invested between 80 million and 100 million baht to launch Talent Sport Academy, an indoor sports complex at The Walk Ratchaphruek in western Bangkok.

    Chief property management officer Ekalak Patamasatayasonthi said the company expects the athletic hub to lift foot traffic at the community mall by 5 to 7 per cent, with consumer spending projected to climb 10 per cent.

    The venue targets annual revenue of 15 million baht directly from the academy, capitalising on rising fitness demand following a year in 2025 when Thailand’s fitness industry revenue topped 12 billion baht.

    Rethinking Community Mall Real Estate

    The Walk Ratchaphruek currently draws about 5,000 visitors a day on weekdays and 8,000 on weekends. The facility features three popular sports — tennis, pickleball and basketball — targeting the “premium mass” segment while also offering customisable training programmes led by professional coaches.

    The location aligns with the Ratchaphruek area’s demographic profile, which comprises high-end families and offers strong growth potential due to robust purchasing power, Mr Ekalak said. The area is also home to international schools, prestigious educational institutions and extensive amenities, with connectivity linking Bangkok to Nonthaburi and Pathum Thani provinces.

    Mr Ekalak said the investment is part of ILM’s growth strategy to develop new revenue streams alongside its core business. The academy will maximise space utilisation and create opportunities to attract new tenants, such as lifestyle brands, apparel retailers, sports equipment stores, and health-focused food and beverage outlets, while broadening the customer base to include sports and wellness enthusiasts.

    The Talent Sport Academy is expected to strengthen the education centre zone, which occupies over 30% of the retail space at The Walk Ratchaphruek, Mr Ekalak said.

    Fitness Sector Momentum

    The academy aligns with the growing wellness trend. The global wellness economy is projected to reach US$7.9 trillion by 2026, with an average annual growth rate of 7.6% over the past three years, according to the Global Wellness Economy Monitor by the Global Wellness Institute.

    Thai consumers are mirroring this trend, with more individuals regularly engaging in physical activities and opting for paid fitness services, Mr Ekalak said. According to Kasikorn Research Centre, Thailand’s fitness industry revenue exceeded 12 billion baht in 2025, an 18% increase, with over 80% of the market concentrated in the Bangkok metropolitan area, which has high purchasing power.

    Pipeline Across Suburban Locations

    The company plans to open 1-2 sports complexes annually in “The Walk” or “Little Walk” projects, initially focusing on high-potential locations with consistent foot traffic. Two additional branches are scheduled to open in 2027 at Little Walk Liap Khlong Song and Little Walk Phran Nok.

    The company currently operates three The Walk and seven Little Walk projects in Thailand.

  • Nike Launches India-Specific Vegam Running Shoe in 55-Day Sprint

    Nike Launches India-Specific Vegam Running Shoe in 55-Day Sprint

    Nike will release the Vegam Run in India on Sunday, launching a road running shoe designed specifically for the country after a 55-day product development cycle. The model sells first through online marketplace Flipkart and selected physical retail stores across the country.

    A full-length foam midsole borrows tooling outlines from the Pegasus 42, combined with an engineered fabric upper and a stacked rubber outsole built to withstand mixed urban terrain. The launch follows Nike’s October kit sponsorship contract with cricket franchise Mumbai Indians and an operational setup in Bengaluru.

    Rapid Prototyping for Indian Roads

    Development teams completed the footwear line in under two months from initial design brief to factory run, sharply cutting the company’s multi-season performance timeline. Deepa Ramprasad, senior director for Nike Road Running Footwear, said the brief aimed to address road conditions and wear patterns specific to Indian runners while keeping the price and cushioning versatile.

    Early production runs include dedicated regional colorways. One variation aligns with the After Dark Tour, an evening 10-kilometer road race scheduled for Mumbai in December.

    Flipkart Distribution and E-Commerce Reach

    Distributing initially via Flipkart gives the sportswear manufacturer immediate digital reach outside tier-one retail corridors. Monobrand sports retail in India faces steep real estate costs in prime shopping malls, limiting offline expansion to affluent pockets of major metros. Digital inventory on large domestic platforms allows the brand to test demand across tier-two and tier-three cities before committing store floor space.

    Competitors have long relied on Indian marketplace partnerships to capture entry-level running volume. By introducing a localized model through third-party e-commerce rather than restricting it to direct-to-consumer digital channels, Nike is trading wholesale exclusivity for rapid volume adoption in an increasingly competitive athletic segment.

    Regional Hub in Bengaluru

    Manufacturing and product strategy for the Vegam Run tie directly into Nike’s expanded corporate campus in Bengaluru. Announced earlier in October, the facility supports the company’s Sports Offense operating model, directing design and regional sourcing for India alongside select export territories.

    Tarundeep Singh, general manager for Nike India, stated that the product line forms an invitation to novice runners while supporting wider sports participation throughout the domestic market.

    Global Rollout After Domestic Debut

    The shoe represents an unusual pivot from global standardization to domestic-first development for Nike. The athletic brand traditionally exports North American and European performance runners directly into Asia without structural alterations to outsoles or uppers.

    Domestic retail availability will expand across additional sports stores in India through the spring, followed by an international rollout to selected global markets later in 2027.

  • Touchland Enters Sephora Australia with 13 Products

    Touchland Enters Sephora Australia with 13 Products

    Touchland entered Australia on October 28, rolling out 13 products across Sephora stores nationwide and online.

    The partnership gives the US brand its first local retail presence in the country, following years of domestic shoppers purchasing its mist sanitizers while traveling overseas.

    Expanding personal care shelves

    Founded in 2018, the US-based brand built its profile around fragrance-led formulations and slim, pocket-sized packaging. The Australian debut focuses on its Power Mist range, placing the sanitizer lineup directly into Sephora’s physical footprint and digital storefront.

    Personal care items in beauty retail have steadily migrated from checkout add-ons into dedicated shelf categories. By securing prime space inside Sephora, Touchland bypasses mass-market pharmacy shelves where utility sanitizers dominate on price rather than branding.

    The premium hygiene play

    The Australian rollout tests whether local consumers will pay beauty-counter premiums for hand hygiene in an inflationary retail climate. For Sephora, stocking the brand expands impulse personal care assortment with products that carry established social media recognition.

    Department stores and specialty beauty chains across Asia-Pacific face tighter consumer discretionary budgets, forcing retailers to rely on lower-ticket basket builders. Touchland gives the retailer a recognized entry-level item that drives foot traffic without demanding high capital outlay from shoppers.

    Retail distribution across markets

    Before securing domestic distribution, Touchland relied on outbound Australian travelers buying inventory abroad. Brand tracking and cross-border demand indicated an addressable audience long before domestic stock arrived on local shelves.

    The initial deployment across Australian retail establishes a southern anchor for the brand in the broader Asia-Pacific region. Inventory performance across Sephora’s network over the final quarter will show whether consumer demand sustains beyond initial launch traffic.

  • DBS Survey Finds 88% of Businesses Use or Pilot Tokenised Money

    DBS Survey Finds 88% of Businesses Use or Pilot Tokenised Money

    Corporate adoption of tokenised money reached 88 per cent among large enterprises deploying or piloting digital asset tools across 11 key markets, according to findings released on October 28 by Singapore lender DBS Bank.

    The study surveyed 422 senior business and treasury leaders from companies generating more than US$500 million in annual revenue across Australia, China, Germany, the UK, and the US.

    Roughly two-thirds of surveyed companies have already put tokenised money to work at scale or introduced it across selected regional operations. Businesses are relying on digital assets to manage cross-border corporate liquidity and open settlement corridors into new geographic markets without relying on traditional correspondent banking rails.

    Stablecoins take the lead in corporate liquidity

    Stablecoins emerged as the single most adopted tokenised instrument in the survey, with 63 per cent of corporate leaders reporting active use. Tokenised commercial bank deposits followed at 53 per cent, while tokenised money market funds accounted for 52 per cent.

    Treasury teams prefer stablecoins because they settle instantly across fragmented networks without waiting for clearing house cut-offs. Lim Soon Chong, group head of global transaction services at DBS Bank, pointed to friction in legacy payment processing as a prime driver.

    “Stablecoins, as you know, offer better fungibility across payment intermediaries, not just across banks. They are less cumbersome from a permissioning standpoint,” he said.

    The speed of liquidity rebalancing gives commercial operators direct control over working capital. Cross-border wholesalers and supply chain aggregators save days of trapped cash during supplier invoicing and customs clearance runs.

    Southeast Asia leads target markets for business expansion

    Corporate expansion strategies remain centred on Asia-Pacific corridors, with Southeast Asia ranking as the top destination for cross-border capital deployment. Australia and New Zealand took the second position for corporate entry, followed closely by India in third place.

    Consumer goods distributors, e-commerce platforms, and logistics operators moving capital across these growth corridors face sharp exchange costs and clearing delays under bilateral banking rails. Tokenised rails allow international firms to bypass batch clearing, running continuous payouts directly to supplier balance sheets across Association of Southeast Asian Nations economies.

    The operational shift changes how multinational retailers fund local inventory. Instead of pre-funding merchant accounts days ahead through intermediary banks, corporate treasurers can keep capital centralised until invoices come due at the point of fulfillment.

    Trade settlement tilts toward the Chinese yuan

    Bilateral payment preferences are shifting alongside tokenisation infrastructure. More than half of corporate executives surveyed in both Australia and the UK stated they are considering settling cross-border trade in Chinese yuan over the next one to two years.

    Recent appreciation in the currency has prompted Chinese exporters to offer improved commercial pricing and credit terms for contracts denominated directly in renminbi rather than US dollars. Exporters in China are actively shifting counterparty terms to avoid foreign exchange volatility on their own domestic books.

    The commercial incentives align with Beijing’s ongoing campaign to widen international adoption of its sovereign currency across key trade routes. Western and regional importers buying goods manufactured in China gain direct supplier discounts by settling directly in yuan, reducing exposure to dollar conversion fees.

    Earlier pilots set the stage for commercial rollouts

    The survey data shows those experiments have moved out of development labs and directly into commercial treasury departments. Multinationals with annual turnover exceeding half a billion dollars are no longer waiting for universal public central bank digital currencies, turning instead to commercially available stablecoins and deposit tokens to fix immediate cash drags.

    Corporate treasurers now face clear execution milestones as Australia and UK companies finalize contract reviews for yuan-denominated billing cycles scheduled across the coming 12 to 24 months.

  • Singapore Wholesale Sea Freight Prices Jump 25.4 per Cent

    Singapore Wholesale Sea Freight Prices Jump 25.4 per Cent

    Singapore transport and storage operators pushed wholesale charges higher in the second quarter, led by a 25.4 per cent quarterly surge in sea freight rates.

    Official producer price figures from the Department of Statistics released on Oct 28 confirm that wholesale freight forwarding costs rose 10.2 per cent over the same period, while postal and courier services climbed 7.1 per cent.

    The price increases hit wholesale markets after an index tracking imported fuels, lubricants and related materials spiked by nearly 79 per cent month-on-month in March. That energy shock followed the outbreak of the Iran war on Feb 28 and the effective closure of the Strait of Hormuz, an export channel that handled roughly 20 per cent of global oil and gas output. Although fuel import metrics eased later in the year, they settled well above their baseline levels.

    Uneven Impact Across Shipping Modes

    Liquid bulk and gas transport absorbed the steepest increases because of their structural dependence on Middle East transit lanes. Crude oil and liquefied natural gas carriers faced direct rerouting requirements, while container shipping lines operating predominantly outside the Persian Gulf recorded milder cost adjustments. Container operators still absorbed indirect pressure through pricier bunker fuel and schedule disruption across regional transshipment hubs.

    Air freight forwarding registered the sharpest immediate shock within forwarding segments. Air cargo handlers dealt with route deviations, constricted capacity and jet fuel premiums. Sea freight forwarders absorbed a combination of higher carrier spot rates, emergency bunker additions and war risk insurance surcharges, whereas domestic land freight forwarding pricing held steady through the period.

    Courier Adjustments and Domestic Storage

    International parcel delivery networks responded by adjusting their baseline tariffs. The 7.1 per cent increase in postal and courier indices stemmed entirely from cross-border traffic, while domestic Singapore delivery tariffs softened over the quarter. Global integrators operating regional sorting hubs in the city-state have passed energy expenses directly to corporate shippers.

    DHL Express has scheduled a general rate increase for January 2027, citing global energy costs and local operating conditions. Upstream handling fees in Singapore also crept higher during the second quarter, with cargo handling charges rising 2.7 per cent month-on-month and warehouse storage fees gaining 0.6 per cent.

    Pressure Mounts on Regional Supply Chains

    For consumer brands and cross-border merchants, wholesale transport cost hikes squeeze gross margins at the inbound inventory stage. Retail businesses often absorb wholesale freight spikes during the initial shipping cycle to defend unit volumes, but prolonged upstream inflation forces retail price tags higher once existing inventory depletes.

    Importers across Southeast Asia face two distinct operational choices. They can absorb degraded margins during upcoming peak sales quarters or pass freight surcharges into final shelf prices. E-commerce platforms that rely on international air parcels face the immediate prospect of higher threshold requirements for free shipping programs.

    The Pipeline of Upstream Costs

    Before the conflict escalated in February, liquid bulk freight tariffs fluctuated within narrow bands and container rates trended lower across major Pacific routes. That period of pricing relief ended abruptly once bunker fuel benchmarks tracked global crude upward. By Oct 23, Brent crude touched more than US$117 a barrel, its highest point since April, after strikes hit commercial tankers near the Strait of Hormuz.

    Commercial shippers now look to the third-quarter producer price indices and DHL Express’s scheduled tariff revision in January 2027 to gauge whether logistics operators will levy fresh baseline increases.

  • SGX RegCo Queries Agribusinesses over Links to 10 Haze-Hit Firms

    SGX RegCo Queries Agribusinesses over Links to 10 Haze-Hit Firms

    Singapore Exchange Regulation issued a fresh round of queries on Oct 28 to listed companies with agricultural operations and plantations in Indonesia, seeking clarity on links to 10 Indonesian companies issued legal notices under Singapore’s haze law.

    SGX RegCo instructed boards to disclose policies and measures implemented to monitor, prevent, and respond to the fires, along with their assessments of whether the fires have a material impact on their businesses.

    The move follows earlier queries sent to eight listed groups, including Wilmar International, Golden Agri-Resources, First Resources, Bumitama Agri, Indofood Agri Resources, Kencana Agri, TSH Resources, and Olam Group, all of which maintained they did not use fire to clear land.

    Tracing Concession Links Across Sumatra and Kalimantan

    The regulatory review targets connections to ten entities singled out by Singapore’s National Environment Agency under the Transboundary Haze Pollution Act 2014. The statutory agency issued preventive measure notices to seven Sumatran forestry operations on Oct 16, followed by three Kalimantan concessionaires on Oct 19.

    Named recipients include pulpwood and palm operators Bumi Andalas Permai, Bumi Mekar Hijau, Paramitra Mulia Langgeng, Sumatera Alam Anugerah, Sebangun Bumi Andalas Wood Industries, Hutan Lestari Raya, Bangakanesia, Buana Megatama Jaya, Mananjung Hayak, and Baratama Putra Perkasa.

    Listed commodity groups must state plainly whether they hold direct equity, joint ventures, or procurement arrangements with any of the sanctioned entities. The directive forces listed boards to look past direct concession boundaries into external supply networks.

    Board Scrutiny Hits Food Commodity Heavyweights

    The regulatory step follows initial inquiries sent on Oct 16 to primary producers and agricultural processors including Wilmar International, Golden Agri-Resources, First Resources, Bumitama Agri, Indofood Agri Resources, Kencana Agri, TSH Resources, and Olam Group.

    Every respondent in that group denied using fire for land clearance, pointing to formal zero-burn standards, internal firefighting crews, and satellite monitoring networks. The market regulator now requires listed boards to document whether those preventative protocols function adequately in practice.

    Corporate boards must also provide formal confirmation on whether foreign or local agencies in Indonesia, Singapore, or elsewhere have launched investigations into their concession sites.

    Supply Chain Risks for Consumer Brands and Processors

    For consumer goods manufacturers and edible oil buyers across Southeast Asia, the regulatory pressure pushes plantation oversight into direct legal exposure. Palm oil and timber products entering consumer supply chains face scrutiny under cross-border clean air statutes that carry civil and criminal liabilities in Singapore courts.

    Institutional investors in regional agribusinesses now face elevated compliance liabilities if listed suppliers purchase raw materials from concession holders named in transboundary enforcement notices. Operational risk shifts from reputational sustainability commitments to formal regulatory non-compliance on the Singapore exchange floor.

    Enforcement Escalates Beyond Voluntary Pledges

    The regulatory exchange notices coincide with parallel enforcement steps by Singapore’s environmental authorities against domestic holding firms. The National Environment Agency served notices on Oct 23 to ten Singapore-registered companies, demanding full concession maps and fire prevention records for Indonesian operations.

    Those separate actions target corporate structures registered in Singapore that retain operational control over Indonesian land parcels. The simultaneous moves by the market regulator and environmental agencies eliminate standard corporate firewalls between offshore holding units and operational plantation sites.

    Agribusiness boards face a tight window to lodge formal written disclosures on the exchange detailing active investigations, concession relationships, and verified impact statements on current crop cycles.

  • Malaysia Seizes 30 AI Chip Servers Worth $12 Million at Kuala Lumpur Airport

    Malaysia Seizes 30 AI Chip Servers Worth $12 Million at Kuala Lumpur Airport

    Malaysian customs officers intercepted 30 server units carrying advanced artificial intelligence chips valued at 49.5 million ringgit ($12.11 million) at Kuala Lumpur International Airport this month. The hardware was falsely labelled as basic electronic parts to skirt international transit rules.

    Authorities discovered the cargo on October 15 during an inspection inside the airport’s free trade zone. The shipment began in an unnamed Asian country and was destined for re-export to another nation in the region without the mandatory trade clearances.

    Inspection at the Free Trade Zone

    Customs officials confirmed that the shipment needed formal regulatory clearance under statutory cross-border rules before transit. Airport customs director Aspalila Ag Tuah said the paper declarations concealed the true nature of the server units.

    “The servers were falsely declared as electronic components… and shipped through Malaysia to ensure there would be no restrictions imposed while being exported to the next destination,” Aspalila said.

    A domestic logistics firm that facilitated the shipment has been summoned to assist investigators with shipping paperwork and chain-of-custody logs. The enforcement arm is tracing the freight forwarders who booked the cargo bays.

    Syndicate Routes Across Regional Hubs

    Investigators suspect the seized hardware connects to an established electronics smuggling operation operating across regional air terminals. Aspalila noted the cargo matched patterns observed in an earlier interception executed at the same airport in June.

    Enforcement records now tie at least five separate cases to this specific network. Total hardware confiscations linked to the syndicate exceed 100 million ringgit across multiple warehouse raids and transit stops.

    The pattern reveals how intermediary air hubs are being tested by clandestine brokers attempting to circumvent semiconductor oversight. Transit points in Southeast Asia face intense pressure to track high-specification gear routed under general electronics descriptions.

    Export Controls and Supply Chain Oversight

    Malaysia imposed explicit export controls last year on the shipment of advanced AI chips originating from the United States, following measures aimed at halting unauthorized semiconductor transfers into China. Those regulations mandate strict transit permits for restricted computational units traversing domestic export processing zones.

    For regional freight operators and warehouse managers, the seizure increases compliance liability on standard electronics manifests. Cargo handlers face heavier penalties if freight declarations fail to specify exact processing capabilities and hardware types.

    Transshipment hubs like Kuala Lumpur rely on fast clearance cycles to maintain air cargo competitiveness. Routine physical inspections of server racks inevitably slow turnaround times for legitimate enterprise hardware distributors.

    Enforcement Track Record

    The October intervention follows a similar raid in June, when customs officials seized roughly $13 million worth of high-end processor units passing through the same airport facility. That earlier operation exposed the operational blueprint of shell forwarders using regional transshipment corridors.

    Enforcement teams are reviewing electronic freight waybills across all five connected cases to identify common corporate handlers. Customs officials have declined to reveal the origin or end destinations while investigations remain active.

    Investigators are now cross-referencing company filings of the local forwarding intermediary against export manifests filed earlier this quarter. Customs authorities are preparing formal charges as forensic analysis of the seized 30 server racks continues.

  • RedMart Now Orders Grow Sixfold in Singapore

    RedMart Now Orders Grow Sixfold in Singapore

    RedMart expanded its express grocery delivery network across Singapore after daily orders for RedMart Now jumped sixfold following its February launch.

    The supermarket arm of Lazada Group S.A. Quadrupled its delivery fleet and launched three fulfilment centres to handle the surge in quick-commerce volume.

    Service expanded into northern and north-eastern Singapore in August and the east in October, while same-day capacity for scheduled deliveries tripled this year under RedMart head Martin Daney.

    Express Logistics and Fresh Food Demand

    RedMart Now operates on delivery windows starting from 30 minutes, relying on localized inventory nodes rather than single centralized warehouses. The express catalogue holds a fraction of the broader platform inventory, which stocks more than 120,000 items.

    Chilled food, meat, dairy, fresh vegetables and seafood represent a larger proportion of express purchases than scheduled runs. Morning shopping begins at 7 a.m. Each day, driven by shoppers seeking recipe ingredients and daily replenishment rather than bulk pantry restocking.

    Delivering groceries in as fast as 30 minutes requires having inventory positioned closer to customers, efficient picking and packing, and having sufficient delivery capacity, including at peak times.

    The Unit Economics of Fast Fulfilment

    Quick commerce models across Southeast Asia routinely struggle with delivery density and high labour overheads. By using existing Lazada warehouse infrastructure and logistics software built over a decade, RedMart limits the steep capital outlays that broke earlier standalone grocery startups in the city-state.

    For brick-and-mortar supermarket chains, faster online fulfilment puts pressure on local store margins. Physical grocers must balance counter service with picking staff in aisles or build costly mini dark stores of their own.

    Capitalizing on Singapore’s Quick Commerce Base

    Singapore’s quick commerce sector reached a valuation of $368.03m in 2025 and projections place it at $502.86m by 2031, according to data from Mordor Intelligence. The expansion follows months of testing routing software to sustain order accuracy as route volumes grew.

    RedMart has not disclosed the precise share of revenue that express drops contribute against its planned grocery run. The scheduled delivery service continues to handle the bulk of overall sales volume.

    The Final Pockets of Island Coverage

    Coverage remains uneven across Singapore, with multiple central and western postal codes still outside the 30-minute delivery zone. The company is directing fleet capacity toward those remaining gaps to complete nationwide reach.

  • Sunscreen Reforms Proposed After 16 of 20 Products Fail SPF Tests

    Sunscreen Reforms Proposed After 16 of 20 Products Fail SPF Tests

    Australia’s Therapeutic Goods Administration is overhauling sunscreen testing rules, requiring brands to conduct repeated SPF verification and lodge data before products reach retail shelves.

    The regulatory shift follows testing conducted last year that discovered 16 out of 20 popular sunscreen formulations failed to deliver their claimed sun protection factor.

    Consumer advocacy group Choice, industry body Accord Australasia and the Australian Sunscreen Association have backed elements of the framework while demanding that the TGA scrutinise the compliance costs and supply availability before codifying the rules. Under the proposed regime, personal care manufacturers must test finished shelf formulations rather than base batches, repeating trials across the stated shelf life of the product.

    Mandatory Testing Shifts Before Shelf Placement

    Brands currently sell sunscreens in Australia without lodging baseline laboratory data with the regulator prior to retail distribution unless specifically ordered to produce records. The updated rules eliminate that gap by forcing suppliers to lodge certified testing dossiers with the TGA ahead of retail launch.

    Laboratory evaluation protocols will also change to accommodate in vitro testing methods conducted on plates rather than relying solely on human volunteer skin trials. The TGA confirmed human testing protocols will remain compulsory for specific categories, including water-resistant claims, to prevent degradation under real-world conditions.

    The regulator decided against establishing an open public registry of brand testing results. Officials cited commercial confidentiality, trade secret protections and the risk that technical testing metrics would confuse shoppers.

    Supply Chain Friction for Beauty and Personal Care Brands

    RetailNews Asia sees this regulatory clampdown reshaping procurement margins for pharmacy chains, beauty retailers, and contract manufacturers across the Asia-Pacific region. Australia represents the strictest suncare compliance market in the southern hemisphere, and Australian compliance frequently serves as the quality benchmark for brands exporting into Southeast Asian retail networks.

    Suppliers face sharp operational cost increases as testing requirements expand from one-off formula verifications to continuous stability batches. Independent indie brands and cross-border beauty labels using third-party contract packagers will bear the brunt of these overheads, creating shelf consolidation in major retailers such as Coles, Woolworths, and chemist chains.

    Fallout from Sunscreen Recalls

    The regulatory overhaul stems from an industry crisis when independent testing showed severe disparities between front-label claims and actual barrier performance. One mineral sunscreen labelled SPF 50+ registered a protection score of just SPF 4 during laboratory trials, triggering a recall of the product alongside 19 sister formulations built on the identical base matrix.

    While products like Mecca Cosmetica’s To Save Body SPF 50+ recorded matching protection levels of SPF 51 in the same trial, the wider category suffered severe reputational erosion. The TGA’s chief medical adviser, Professor Robyn Langham, explained that investigations revealed multiple systemic factors behind failing batches rather than isolated formulation errors.

    Australians expect the SPF on the label to be backed by robust evidence. These proposed reforms put that expectation at the centre of sunscreen regulation.

    Next Regulatory Steps and Compliance Milestones

    The TGA will review submissions from retail and chemical industry groups regarding cost burdens before finalising the regulatory timetable. Consumer advocates continue to demand that the regulator institute an independent government-run batch testing programme rather than relying exclusively on company filings.

    Beauty retailers and FMCG distributors operating across Australia and regional export markets are now auditing supplier dossiers ahead of the binding implementation dates.

  • Chow Tai Fook Dawn Line Reaches HK$2.8 Billion in Sales

    Chow Tai Fook Dawn Line Reaches HK$2.8 Billion in Sales

    Chow Tai Fook Jewellery generated approximately HK$2.8 billion in retail sales from its new signature collection, Dawn, by the end of September. The line, launched in April, brought in more than HK$870 million in its initial three months before adding nearly HK$2 billion in the following quarter.

    The product success unfolded alongside an ongoing contraction of the company’s retail network. Total retail value slipped 0.5 per cent year on year for the three months ended September 30, even as group profit for the fiscal first half jumped between 90 per cent and 100 per cent.

    Accounting adjustments drove the bottom-line expansion: fair value gains recognized on gold loan contracts replaced losses recorded during the prior-year period. These paper gains on bullion hedge positions offset an uneven retail performance across regional channels.

    Pruning Doors Across Mainland China

    The jeweller ran 5,192 points of sale at the end of September, down net 242 locations from June. Across mainland China, the company opened 23 retail points and shut 263, pushing ahead with an estate consolidation plan that discards underperforming doors.

    Directly operated stores in the mainland managed a 2.2 per cent rise in same-store sales during the second fiscal quarter. Franchised locations told a different story, falling 2.9 per cent by the same measure.

    Mainland sales volumes dropped 9.7 per cent on a same-store basis. Higher ticket sizes absorbed part of the traffic decline. Mainland average selling prices for weight-based gold jewellery rose to HK$10,200 from HK$9,500 a year earlier.

    Hong Kong and Macau Rebound

    Mainland operations generate more than 83 per cent of group retail value, leaving total group turnover exposed to domestic mainland demand. Retail value in the mainland dropped 5.3 per cent during the quarter, pulled down by shuttered doors and cautious discretionary spending.

    Hong Kong, Macau and overseas territories counterbalanced that drag. Retail value across those offshore markets grew 33.2 per cent, contributing nearly 17 per cent of group retail value.

    Same-store sales in Hong Kong and Macau gained 29.6 per cent, helped by returning tourists and steady foot traffic. Macau expanded 47.3 per cent on a same-store basis, while Hong Kong climbed 24.0 per cent. Same-store transaction volumes in both cities grew 14 per cent, even as the average selling price for weight-based gold softened from HK$16,800 to HK$15,400.

    New Product Lines Take the Strain

    Product repositioning shielded cash receipts from deeper erosion. The Dawn signature collection, introduced in April, generated more than HK$870 million in its initial three months.

    Demand accelerated through the summer. The Dawn line generated roughly HK$2 billion more across the September quarter, producing approximately HK$2.8 billion in retail sales during its first six months on shelves.

    For mall landlords across secondary Chinese cities, the estate culling signals persistent pressure on jewellery tenancy margins. Chow Tai Fook is abandoning aggressive physical door expansion, a playbook shared by regional peers that flooded lower-tier shopping centres.

    The group added one high-end boutique during the quarter, lifting its mainland total of that format to 13.

    Targeting High-End Formats

    Gold price volatility creates an earnings paradox for jewellery retailers across Asia. Rapid price spikes yield non-cash revaluation windfalls on hedging tools, yet steep metal prices squeeze consumer appetite for physical gram-based ornaments.

    Chow Tai Fook is addressing that squeeze by directing capital toward design-led collections that sell on fixed retail prices rather than strict weight metrics.

    Management retains an active rollout plan for 50 high-end image boutiques in mainland China by the end of fiscal 2027.