Author: Mei Ling Tan

  • China Records 15 Million Cars with Navigation on Autopilot Features

    China Records 15 Million Cars with Navigation on Autopilot Features

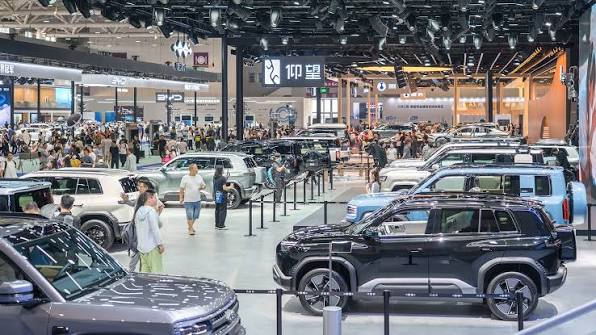
    China counted approximately 15 million passenger cars equipped with Navigation on Autopilot software as of August 2026, according to government academy data released in Beijing.

    Those vehicles account for roughly 25 per cent of the 61 million passenger cars nationwide carrying Level 2 driver assistance systems, reflecting the operational fleet rather than showroom deliveries this year.

    The Fleet on the Road

    Data released at the 2026 World Intelligent Connected Vehicles Conference by the China Academy of Information and Communications Technology showed about 16 million passenger cars in China carried 5G communication terminals as of August, alongside 2 million vehicles with Cellular Vehicle-to-Everything equipment.

    The China Academy of Information and Communications Technology disclosed the operational figures during the conference in Beijing’s Yizhuang area. The Ministry of Industry and Information Technology, the Ministry of Transport, and the Beijing municipal government jointly organized the three-day gathering.

    Hardware installations across the domestic fleet have outpaced urban infrastructure upgrades. Automakers selling in China have turned automated highway driving and urban point-to-point navigation into standard consumer features to protect showroom pricing, forcing suppliers to absorb sensor costs across high production volumes.

    Rewriting Vehicle Standards

    Regulators are moving to codify how these operating systems behave once drivers take their hands off the controls. Guo Shougang, head of the equipment industry department at the Ministry of Industry and Information Technology, released a draft update to China’s connected-vehicle technical standards guidelines for public review on October 21.

    The regulatory framework covers more than 400 existing standards across intelligent vehicles, communications, traffic management, and fleet operations. The 2026 revisions seek to expand safety criteria for core components, standardize system architectures, and set binding rules for operating autonomous driving services commercially.

    For automotive brands and tier-one component makers, the revised rulebook narrows room for proprietary software workarounds. Safety compliance costs will fall heavily on domestic electric vehicle assemblers that have marketed assisted driving capabilities aggressively to private retail buyers.

    Preparing Level 3 Approvals

    Work on the second batch of Level 3 autonomous driving market access pilots is underway, Guo said during the conference. Regulators have not named the participating carmakers, the specific models involved, or the date when commercial sales permits will take effect.

    The current phase builds on early regulatory permissions granted late last year. The ministry awarded conditional Level 3 market access approval to models from state-owned automakers Changan and BAIC in December 2025.

    Those initial vehicles remain confined to designated public test roads and strict operating conditions rather than nationwide consumer use. Regulators will monitor testing outcomes from the first cohort before expanding operational permits to the next group of carmakers.
  • L Catterton Invests in InMobi Subsidiary Glance

    L Catterton Invests in InMobi Subsidiary Glance

    Consumer-focused private equity firm L Catterton has made a strategic investment in Glance, an artificial intelligence shopping agent run out of a subsidiary owned by tech company InMobi. Glance is currently accessible on more than 60 million devices in the U.S. Through an app and hardware partnerships with Samsung, Android TV and DirecTV.

    Scott Dahnke, global chief executive officer of L Catterton, noted that the private equity firm has backed shifts in consumer behavior for nearly four decades. “Agentic commerce is fundamentally changing how consumers discover and shop for products, creating significant opportunities for brands that can make the journey more personal, intuitive and engaging,” Dahnke said. “Glance is uniquely positioned to capitalize on this evolution, combining a differentiated consumer proposition with broad distribution across the screens where people spend their time.”

    Operating like a personal shopper, Glance remembers user preferences, scours the web for deals, offers virtual try-ons, and secures approval before completing purchases. “We have 10 million monthly active users in the U.S.,” said Naveen Tewari, founder and CEO of Glance and InMobi, noting that users average 120 shopping prompts a month and nearly 15 percent make a monthly purchase.

    Screen distribution and checkout mechanics

    Users on the service enter roughly 120 shopping prompts every month, with approximately 15 per cent completing a transaction within thirty days. Glance collects an affiliate cut from final sale totals. For an added fee, the company trains its underlying algorithms on individual brands to make sure those labels surface accurately during consumer queries.

    Naveen Tewari, founder and chief executive of Glance and InMobi, said: “The model does not have a limitation like you and I to remember only a hundred brands. The model can actually remember a million brands. As different brands start to get trained on Glance, they get discovered for the right user at the right time. And especially brands that are smaller, that do really authentic work, but not at scale.”

    Hardware integrations give the system immediate visibility into living rooms and mobile screens. Shoppers watching connected television displays can use prompts to identify clothing worn by characters on screen, search for retail stock, and complete purchases on linked devices.

    The private equity wager on agentic retail

    L Catterton, which manages global consumer investments, is banking on algorithmic agents handling discovery rather than traditional online search boxes. Glance intends to allocate the new capital to accelerate model training runs and expand its distribution network beyond its initial television deployments.

    By backing an InMobi venture, L Catterton wagers that consumer software can control retail discovery funnels in Western markets. Ad-tech operators spent a decade selling display space. Now they want direct conversion cuts from retailer inventories.

    The structural risk for brand owners sits in recommendation control. When an algorithm decides which dress or shoe matches a television prompt, unpartnered labels risk exclusion unless they pay the platform to train its model on their catalog.

    From lock-screens to commerce agents

    Glance built its initial scale by delivering news, media and casual games to Android mobile lock-screens. Its parent InMobi used that installed base to expand abroad.

    The commercial test will be whether Glance can replicate its US hardware conversion rates across its core device base, where average basket values run lower and marketplace apps dominate customer search habits.

  • Charlotte Tilbury Opens First Southeast Asia Flagship in Jakarta

    Charlotte Tilbury Opens First Southeast Asia Flagship in Jakarta

    Charlotte Tilbury entered Southeast Asia on October 27, 2026, opening 1 flagship store at Plaza Indonesia in Jakarta.

    The boutique houses the region’s first Pillow Talk Beauty Bar, anchoring the British cosmetics brand directly in Indonesia’s capital.

    British Embassy officials joined commercial partners, celebrities, influencers, and media for a ribbon-cutting ceremony inside the space, which features an open-plan layout, illuminated signage, burgundy display counters, gold-toned finishes, and interactive product and mirror displays.

    The Plaza Indonesia Footprint

    Plaza Indonesia gives the brand immediate positioning alongside global luxury peers. The boutique focuses heavily on hands-on application, setting dedicated consultation stations around the Pillow Talk colour franchise to encourage on-site testing.

    Interactive mirrors and product testers dominate the sales floor. The layout prioritises direct client trials over high-density shelf stocking, following the physical format the label developed across European department store concessions.

    The Southeast Asian Route

    Choosing Jakarta indicates how premium cosmetics groups now evaluate Southeast Asian purchasing volume. International beauty labels historically routed their regional debuts through other hubs before tackling Indonesia’s complex import rules and distribution networks.

    Indonesia’s affluent middle-income shoppers in greater Jakarta offer immediate scale for prestige makeup. The brand bypasses third-party retail counters to own its customer relationship directly from day one.

    Shifting Away From Department Store Concessions

    Operating a standalone boutique presents different margin dynamics than wholesale beauty counters. Standalone flagships carry higher fixed fit-out and lease expenses, but they allow the operator to capture full retail margins without sharing floor space or paying department store take-rates.

    Direct control over merchandising protects brand equity in an Asian cosmetics market often flooded with parallel imports. The flagship provides a domestic base to satisfy demand that previously flowed through grey-market personal shoppers or cross-border online orders.

    Local Partnerships and Import Approvals

    Entering the Indonesian retail market requires securing local health authority notifications and clearing domestic distribution clearances. The Jakarta opening follows months of setup to align the brand’s full product catalog with local trade requirements.

    RetailNews Asia notes that rival global luxury labels have increased their capital commitments across Indonesia’s modern trade channel, seeking growth outside slowing Chinese retail centers.

    Store traffic volumes across the coming holiday quarter and potential secondary site selections in Jakarta will show how quickly the company plans to build out its physical store network across the region.

  • BIR Suspends QR-Coded Tax Badges for Online Sellers Ahead of Deadline

    BIR Suspends QR-Coded Tax Badges for Online Sellers Ahead of Deadline

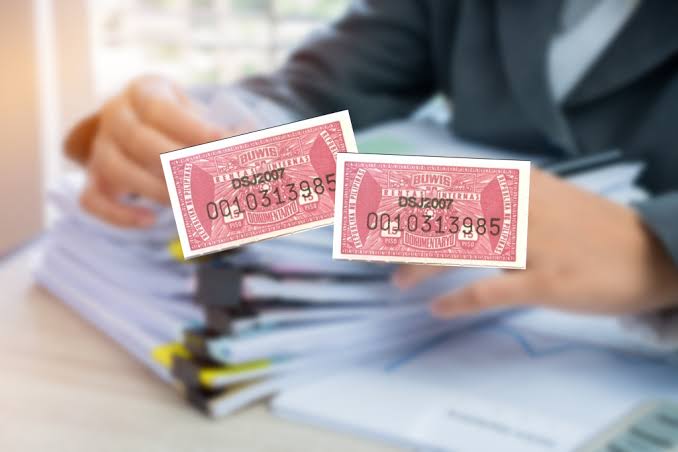
    The Bureau of Internal Revenue (BIR) suspended its requirement for online sellers, freelancers, and content creators to display QR-coded tax registration badges on Monday, October 26.

    BIR Commissioner Charlito Martin Mendoza halted enforcement just five days before the scheduled October 31 compliance deadline, confirming that the agency will not penalize merchants for failing to display the badge during this indefinite suspension.

    Vendors who have already acquired the digital markers may still post them voluntarily, Mendoza noted, as authorities reconsider rules introduced in April to replace public Certificate of Registration (COR) postings.

    Halting the Digital Mandate

    The requirement was introduced in April as an alternative to displaying one’s full BIR Certificate of Registration (COR) online. The badge contains a QR code that customers can scan to verify whether an online seller or service provider is registered with the tax bureau.

    But what was supposed to make registration verification easier has since sparked debate that QR codes could expose personal information. The rollout was also marred by technical difficulties and confusion over who needed to comply.

    “We recognize that protecting personal information online presents different and more complex challenges than displaying a COR at a physical business establishment,” Mendoza said.

    The BIR said it would work with the National Privacy Commission and consult affected taxpayers before deciding how to proceed.

    Burden on Digital Commerce

    Economist and former finance undersecretary Cielo Magno welcomed the suspension but questioned why the requirement was necessary in the first place. Magno pointed out that the BIR already maintains taxpayer registration records and has other mechanisms for monitoring transactions.

    She argued that requiring another badge, without clear evidence that it would improve revenue collection, merely adds another administrative burden onto small online sellers and freelancers.

    “Instead of encouraging people to enter the formal economy, we risk giving them more reasons to remain outside it,” she said.

    Implementation Gaps and Next Steps

    Her criticism comes amid longstanding concerns over the Philippines’ complicated business regulations and excessive red tape .

    In its latest Business Ready assessment, the World Bank found that Philippine business regulations scored nearly as well as Singapore’s on paper, but the country lagged considerably in implementation. Registering a foreign firm in the Philippines takes 76 days, compared with just one day in Singapore, according to the World Bank.

    The international lender has also urged the government to simplify tax compliance, arguing that easier procedures can improve collection by reducing mistakes and encouraging taxpayers to comply voluntarily.

  • Pokémon Company to Open First Permanent Store Outside Asia in London in 2029

    Pokémon Company to Open First Permanent Store Outside Asia in London in 2029

    The Pokémon Company announced on Oct. 23 that it will open its first permanent retail store outside Asia in London in 2029.

    The British opening makes the UK the fourth country worldwide to host a permanent location, joining Japan, Singapore, and Taiwan, where an outpost operates in Taipei.

    Official plans describe the London site as a “Pokémon retail destination” featuring exclusive merchandise and immersive fan spaces, while the Pokémon Company also intends to launch several other branches outside Asia. Japan itself houses roughly two dozen specialty shops running from Hokkaido to Okinawa.

    The Long Shift From Asian Flagships

    Domestic operations in Japan rely on three tiered physical retail formats: large Pokémon Center megastores, mid-sized Pokémon Stores, and smaller Pokémon Center Satellite hubs. Across Japan, the firm runs roughly two dozen specialty locations from Hokkaido to Okinawa.

    Regional Asian expansion outside Japan has moved conservatively over the past decade. Permanent outposts operate only in Taipei and Singapore, leaving Western territories to depend on short-term pop-up installations or third-party wholesale accounts. The London project shifts the company’s real-estate strategy toward full-scale experiential flagship ownership in Europe.

    Pop-Up Metrics and Western Foot traffic

    Direct experiential retail allows franchise owners to extract higher margins from licensed intellectual property while starving grey-market resellers of scarce inventory. London served as an initial testing ground for that demand when the company operated temporary Pokémon Center pop-up shops starting in 2019. Long queues and stock shortages at those temporary sites proved British consumers would absorb dedicated physical units.

    Western retail landlords now face a protracted wait. By anchoring the launch date to 2029, the operator gives itself years to secure prime central London real estate and arrange supply chains, but risks exposing the project to rising prime retail rents and shifting discretionary consumer spending across Europe.

    Testing the Limits of Single-IP Retail

    The company previously attempted a permanent presence in the West when it opened Pokémon Center New York in 2001. That venture lasted four years before parent partner Nintendo folded the footprint into the broader Nintendo Store in 2005, illustrating the operational cost of keeping an isolated character brand profitable on expensive Western high streets.

    Gaku Susai, Chief Product and Experience Officer at The Pokémon Company International, said:

    “We are always exploring new opportunities that help us create unique and memorable experiences for our fans. This new London store will give visitors the chance to step into the world of Pokémon, whether they’re discovering the brand for the first time or have been Trainers for years. We hope it becomes a place where everyone can come together, feel like part of a community and enjoy the magic of Pokémon in a whole new way.”

    What to Track Ahead of 2029

    Retail analysts will track whether the brand’s supply chains can fulfill high-volume character merchandise abroad without cannibalising regional online sales. Securing local suppliers and handling direct imports will determine the unit economics of the flagship.

    The immediate milestone is the property acquisition itself. The Pokémon Company must confirm its British lease location and floor layout before announcing the additional international branches it plans to build beyond Asia.

  • Flipkart Promotes Renuka Singaram to SVP as Revenue Reaches ₹1,45,880 Crore

    Flipkart Promotes Renuka Singaram to SVP as Revenue Reaches ₹1,45,880 Crore

    Flipkart promoted Renuka Singaram from vice-president to senior vice-president in October 2026, placing its quick commerce arm Minutes, non-large supply chain, and design organisation under her expanded leadership. Flipkart Group chief executive Kalyan Krishnamurthy announced the promotion amid several leadership elevations across the business.

    Singaram joined Flipkart in October 2014 following a five-year tenure at Dell India between 2009 and 2014. Her remit includes non-large shipment logistics alongside Minutes, which competes against quick commerce rivals Blinkit, Zepto, and Swiggy Instamart.

    Flipkart Internet, which houses the group’s e-commerce operations, posted an 18 per cent year-on-year increase in revenue from operations to ₹1,45,880 crore in FY26. Consolidated net loss narrowed to ₹8,468 crore from ₹8,646 crore in FY25, according to regulatory filings.

    Building Out Dark Stores in Top Metros

    Minutes operates in an aggressive segment that demands localized dark-store networks, tight picking windows, and sub-15-minute couriers. Handling standard non-large parcel delivery alongside rapid fulfilment gives Singaram direct use over inventory flow and local warehousing costs.

    Quick commerce operators burn working capital on micro-hubs situated within expensive residential catchments. By integrating quick deliveries with its broader non-large parcel network, Flipkart aims to sweat existing urban nodes and cut fulfilment overheads per parcel. Rival platforms run dedicated, standalone dark stores that face rising lease renewals across Tier 1 cities.

    Balance Sheet Pressures and Market Share

    Flipkart Internet reported an 18 per cent increase in revenue from operations to ₹1,45,880 crore for FY26. Consolidated net loss narrowed to ₹8,468 crore from ₹8,646 crore in FY25, according to regulatory filings.

    The margin for error in quick fulfilment remains thin. Quick commerce platforms in India face escalating customer acquisition costs as incumbents discount staple groceries and consumer tech accessories to defend basket share. Singaram faces the task of scaling Minutes without widening operating losses at the core marketplace entity.

    Employee Equity Liquidity Disputes

    Separately, more than 1,000 former Flipkart staff submitted an appeal to parent company Walmart and the Flipkart board demanding access to employee stock option liquidity programmes. The petition challenges current eligibility windows that restrict ex-employees from monetising equity accumulated during their tenure.

    Employee equity serves as a primary retention tool across Indian technology companies, yet privately held platforms often restrict buybacks to current staff. With unlisted equity locked until secondary sales, structured buybacks, or an initial public offering, former staff are pushing the board to open liquidity access uniformly.

    Krishnamurthy must balance rising capital allocation for Minutes with investor returns and employee equity expectations ahead of any eventual public listing filing.

  • Tata Consumer Profit Rises 16% as Salt and New Lines Offset Flat Tea

    Tata Consumer Profit Rises 16% as Salt and New Lines Offset Flat Tea

    Tata Consumer Products posted a 15.6 per cent increase in consolidated net profit to ₹470.14 crore for the September quarter, driven by higher salt volumes and faster momentum in packaged foods.

    Consolidated revenue climbed 14 per cent to ₹5,661.13 crore, matching analyst projections of ₹5,583.2 crore on revenue and ₹469.2 crore on earnings.

    Operating profit grew 18 per cent to ₹794 crore. Operating margins widened by 40 basis points to reach 14 per cent. Underlying volume growth in the core domestic branded business registered at 11 per cent, softening slightly from 13 per cent in the prior quarter. Price revisions took effect across key staples, lifting tea prices by 8 to 10 per cent and salt prices by 6 per cent compared to the first quarter.

    Value Added Lines Expand Operating Cushion

    Packaged staples and functional beverages now insulate the group from flat demand in legacy grocery lines. The company classified 38 per cent of its domestic business as growth portfolios, which surged 40 per cent year on year. Tata Sampann, covering spices, culinary oils and packaged pulses, reported 57 per cent year-over-year growth, driven by volume. Cold-pressed oils and dry fruits generated a combined annual recurring revenue run rate of approximately ₹1,000 crore, while ready-to-drink beverages like Tata Gluco+ and Tata Copper+ grew sales 47 per cent.

    Pricing power in salt proved resilient. Salt revenue increased 15 per cent on 9 per cent volume growth. In contrast, tea revenue slipped slightly as volumes stayed flat, squeezing category turnover despite direct price hikes. That bifurcation mirrors broader supermarket trends across urban India, where branded staples capture market share from unorganised mills while mass hot beverages face spending fatigue.

    Store Footprint and International Pressures

    Joint venture Tata Starbucks generated a 15 per cent revenue increase for the three-month period, marking a multi-quarter high driven by same-store sales. The chain closed September with 505 cafes across 81 cities in India. The rapid cafe rollout places the group in direct competition with international specialty chains and domestic coffee operators bidding for high-street real estate in tier-one and tier-two retail districts.

    Overseas revenue rose 7 per cent reported, but fell 2 per cent in constant-currency terms against a demanding year-earlier base. Prolonged warm weather in the United Kingdom dampened hot beverage consumption. Cost structures face new friction as well, with tea inflation and packaging input volatility balancing out recent declines in global green coffee purchasing costs.

    Building Margins Across Packaged Brands

    Management previously transformed Tata Sampann from negative 5 per cent margins five years ago to between 14 and 15 per cent this quarter, expanding 270 to 280 basis points year on year. In the June quarter, consolidated revenue had risen 12 per cent while net profit jumped 29 per cent, showing consistent volume expansion through the current fiscal year.

    “We had seen a little bit of inflation in Capital Foods as well, and we’ve taken pricing through the quarter, which will again start to flow. So across the board, I think the whole play of price increases has yet to, manifest fully into the P&L,” D’Souza said to analysts in the post-results call.

    Executive leadership has set a target for Indian food and beverage operating margins to reach 17 to 20 per cent over the next three to five years, requiring pricing actions at Capital Foods to flow through inventory cycles without degrading supermarket sales volume.

  • Thailand Selects 44 Medical AI Startups for Commercial Push

    Thailand Selects 44 Medical AI Startups for Commercial Push

    Thailand selected 44 medical artificial intelligence startups for an incubation initiative aimed at driving lab research into commercial healthcare deployments across Southeast Asia.

    More than 80 firms applied for the Medical AI Development for Entrepreneur programme, known as MADE, cutting the field to 44 ventures that now receive hospital access, cybersecurity audits and pitch sessions with regional investors.

    The programme is run jointly by the Artificial Intelligence Entrepreneur Association of Thailand, the Ministry of Higher Education, Science, Research and Innovation, and the Technology and Innovation in Life Sciences National Agency. Its target is direct market placement, building business operational plans and establishing common standards for registering clinical software ahead of show events on 30 Oct 2026.

    Chanwit Boonchuay, president of the Artificial Intelligence Entrepreneur Association of Thailand, said the MADE programme aims to turn research and prototypes into products with practical applications. The association is also building the Medical AI Network, known as MAIN, alongside regulatory guidelines intended to speed up medical product registrations.

    Developers will show their tools at the Global Medical AI Summit at True Digital Park in Bangkok on 30 Oct 2026. Hospital networks and international venture funds will review clinical software, diagnostics and operational automation platforms during matchmaking sessions scheduled throughout the event.

    Closing the gap between prototypes and procurement

    Healthtech across Asia frequently stalls at the hospital door. While Southeast Asian private hospital operators eagerly buy imaging tools and administrative automation to lower operating overhead, strict medical liability rules and lengthy clinical validation cycles often exhaust startup cash reserves long before public procurement begins.

    The bottleneck in Bangkok sits squarely in validation trials. Private chains have historically favoured established global diagnostic vendors over unproven domestic code. By offering clinical testing fast-tracks through university hospitals, the government is attempting to lower the commercial entry barrier for local software creators.

    The target for a domestic unicorn

    The state intervention follows a broader strategic directive set by Higher Education Minister Yodchanan Wongsawat to develop globally competitive deep-tech businesses and create a Thai healthcare unicorn within five years. The ministry wants the life sciences agency to shift away from acting solely as a grant dispenser and operate instead as an active venture builder.

    Seven policy priorities now steer the life sciences agency, including a joint bio-venture builder with the National Innovation Agency, a national biobank, and a unified health data infrastructure designed to link medical schools directly with clinical testing teams.

    Global startup research centre StartupBlink tracks 13,867 healthtech startups across 102 countries, representing 8.7 per cent of all tracked startups globally and an estimated ecosystem value of US$330.5 billion. Thailand wants a slice of that capital pool by using its medical tourism reputation and private hospital infrastructure.

    Next hurdles in Bangkok

    The primary barrier remains the velocity of regulatory approvals. Lengthy trial processes continue to slow down rollouts across both state and university hospitals, even as early product testing wraps up.

    All eyes now turn to the 30 Oct 2026 pitching sessions at True Digital Park, where developers will pitch hospital procurement chiefs and regional venture investors to secure pilot contracts.

  • Thailand Investment Applications Rose 28% to over 1.7 Trillion Baht

    Thailand Investment Applications Rose 28% to over 1.7 Trillion Baht

    Thailand secured 1,954 investment promotion applications worth more than 1.7 trillion baht in the first nine months of the year, a 28 per cent increase driven by artificial intelligence hardware, electronics and food processing.

    Foreign direct investment led the expansion, surging 62 per cent year on year to 1.55 trillion baht across 1,309 proposals.

    Digital ventures drew 139 projects valued at over 1.17 trillion baht, nearly double the intake from a year earlier. Within that segment, 111 projects worth over 1.2 trillion baht tied directly into artificial intelligence supply chains, spanning data centres, cloud hosting, chip design, semiconductor manufacturing and testing, printed circuit boards and hard-disk drives. Major applicants included US-based Analog Devices, Taiwan’s Delta Electronics and California storage-device maker Western Digital.

    Hardware Clusters and Supply Chain Pull

    Electrical appliances and component producers took second place, logging 262 project filings valued at 189.37 billion baht, up 7 per cent. Board of Investment secretary-general Narit Therdsteerasukdi stated that rapid expansion across data hubs is accelerating local orders for power management gear, cooling units, high-speed networking lines and server racks. That procurement loop connects heavy infrastructure directly to domestic tier-two and tier-three parts suppliers.

    The increase reflected both a global shift in investment flows amid geopolitical tensions and rapid technological change

    Singaporean corporate vehicles directed the largest volume of overseas capital, channeling 1.16 trillion baht, followed by manufacturing groups based in China, the United Kingdom, Japan and Taiwan.

    Central and Eastern Industrial Hubs Take 93 Per Cent

    Geographic concentration remains sharp across the country’s established manufacturing corridors. Thailand’s Central region drew the heaviest capital concentration at 955.2 billion baht, while the Eastern region pulled 632.3 billion baht. Combined, the two commercial districts absorbed 93 per cent of every investment baht pledged through September.

    For regional plant managers, the heavy tilt toward Central and Eastern provinces locks in transport advantages close to deep-sea container ports but tightens competition for power grids, industrial water rights and technical plant operators. New facilities entering these corridors must contend with rising land acquisition costs and an increasingly crowded supplier base.

    Agribusiness Gains Behind Farm and Packaged Goods

    Agribusiness and modern food processing generated the sharpest sectoral growth rate outside digital compute. Applications rose 59 per cent to 80.1 billion baht spread across 218 operations. These proposals span commercial animal feed, processed starches, natural plant extracts, rubber goods, packaging manufactured from farm waste and modernized food and beverage packaging lines.

    Other operational segments recorded steady intake. Public utilities and energy groups accounted for 313 applications worth 59.8 billion baht, dominated by solar, wind, biomass and biogas generating facilities alongside industrial water plants. Logistics and commercial services generated 51.8 billion baht in applications, while automotive assemblies and replacement parts manufacturing drew 36.3 billion baht across the period.

    Approved Filings Point to Export Mandates

    The nine-month intake builds on formal factory approvals already working through state pipelines. The Board of Investment approved 1,951 projects between January and September representing 1.51 trillion baht in committed expenditure.

    Approved facilities carry binding production targets once commercial runs begin. According to agency projections, the approved facilities are estimated to generate 1.96 trillion baht in annual exports, absorb more than 693 billion baht in domestic raw materials and parts each year, and open 116,000 factory floor and engineering roles across the industrial estate network.

  • Volkswagen Secures L3 Autonomous Road Test Permit in Hefei

    Volkswagen Secures L3 Autonomous Road Test Permit in Hefei

    Volkswagen has secured a road test permit for Level 3 autonomous driving in Hefei, starting real-world road tests and data collection across the Anhui provincial capital.

    The trial advances the German group toward its target of having conditional autonomous software ready for commercial passenger cars in 2027. Volkswagen China confirmed the permit on Monday, though it withheld the models involved, the route maps and the size of its test fleet.

    The Road From Cariad to Carizon

    Engineering work behind the Hefei testing runs through Carizon, the joint venture established in December 2023 between Volkswagen software division Cariad and Beijing-based Horizon Robotics. Volkswagen committed 2.4 billion euros to set up the unit and retains a 60 per cent controlling stake. Carizon pairs Horizon Robotics’ foundation models with proprietary silicon to build an automated driving stack specifically tuned for Chinese roads.

    Hardware development focuses on the C7H system-on-chip, which remains in development alongside the GAIA world model data system. Carizon intends to run that combined platform across future production vehicles, targeting full software deployment and early customer deliveries in the second half of 2027.

    The Race Against Domestic Incumbents

    Foreign automakers in China face severe margin pressure from local electric brands that already bundle automated highway pilot features into standard trims. To defend showroom footfall, Volkswagen must match the local software pace or risk seeing its volume market share erode further among tech-focused retail buyers. Chinese consumers treat intelligent cockpit functions and urban driving assistance as baseline requirements rather than optional luxury packages.

    Domestic manufacturers hold the regulatory lead on conditional autonomy. The Ministry of Industry and Information Technology approved its first batch of road-use pilot vehicles in December 2025, clearing Changan Automobile’s Deepal SL03 and BAIC Group’s Arcfox Alpha S. Those pilot approvals grant operational use rights on designated public highways, putting local carmakers a full step ahead of test-permit holders like Volkswagen.

    Regulatory Gates and Timelines

    A testing permit allows development vehicles to map routes and log corner cases, but it does not permit serial production sales. Full commercial deployment requires separate product clearance from industrial regulators; an MIIT official said on October 22 that work on a second batch of L3 product approval pilots was underway.

    Frank Han, executive vice president of Volkswagen Group China and chief executive of Cariad China, told an industry conference in April that the manufacturer intends to reach Level 3 capabilities in 2027 before attempting Level 4 autonomous operations in 2029.

    Volkswagen presents its broader platform strategy at its first Hefei Technology Day on October 28, where engineers will outline hardware timelines for the group’s Chinese vehicle pipeline.

  • China Lab-Grown Diamond Producers Shift 2 Million Carats to High-Tech Sector

    China Lab-Grown Diamond Producers Shift 2 Million Carats to High-Tech Sector

    Chinese lab-grown diamond makers are cutting back gemstone production to supply thermal management components for artificial intelligence servers and semiconductors as retail prices drop.

    Around 70 per cent of the 2 million carats produced annually at Feng Canjun’s factory in October 2026 goes into jewellery, but the Chinese entrepreneur is pivoting capacity toward advanced materials.

    Feng plans to raise the share of functional materials at the facility to more than 50 per cent by 2030, reducing gemstone output as industrial demand accelerates.

    At the Jiaruifu factory run by Feng Canjun in Zhengzhou, about 70 per cent of its 2 million carats in annual production currently supplies jewellery retailers. Feng plans to push functional material volume past 50 per cent by 2030, reducing jewellery output to a ceiling of 30 per cent.

    Capital Reallocation to Hardware

    Capital expenditure across central China is shifting away from consumer jewellery cutting lines. Henan Liliang Diamond redirected 1 billion yuan, equivalent to $149.18 million, from an existing gem-grade expansion programme to finance a new functional-diamond manufacturing project, according to a corporate filing.

    The technical driver is heat dissipation in high-performance computing. Data centre electricity demand will more than double to roughly 945 terawatt-hours by 2030, according to an International Energy Agency forecast. That power load concentrates heat on silicon dies, creating bottlenecks for high-density AI clusters.

    Chinese media reported that Huawei and Taiwan Semiconductor Manufacturing Company are exploring synthetic diamonds for chip cooling. Lenovo launched a consumer laptop in China incorporating a diamond-copper composite cooling element, while Intel chief executive Lip-Bu Tan made a personal investment in US diamond-wafer maker Diamond Foundry.

    Thermal Management Supply Chains

    Laboratory testing demonstrates direct hardware gains from the material shift. Research published by the Ningbo Institute of Materials Technology and Engineering showed diamond-copper cooling modules improved chip heat dissipation by 80 per cent and lifted processing performance by 10 per cent.

    This adoption directly targets market share held by established chemical suppliers. Industrial materials groups including Germany’s Henkel, Dow in the US and Japan’s Shin-Etsu Chemical currently dominate chip thermal interfaces with silicones, adhesives and metal pastes.

    Jewellery retailers in Asia face shrinking synthetic gemstone inventory values as factory supply lines pivot. Downstream gemstone retail represents an estimated $100 billion annual global market, but factory operators see better pricing use in high-spec computing hardware than in consumer shopfronts.

    Global Substrate Competition

    Western and Japanese suppliers are building parallel capacity to counter China’s factory dominance in functional stones. Element Six, the synthetic-diamond division of De Beers, teamed up with Japan’s Orbray to manufacture three-inch single-crystal diamond wafers, while preparing two-inch production in Oregon.

    European capital is backing similar efforts. The Spanish government committed €753 million to support a Diamond Foundry manufacturing facility in Trujillo to produce synthetic diamond substrates for European semiconductor manufacturing.

    In the US market, cooling specialist Frore Systems introduced its LiquidJet Diamond component, an integrated coldplate module designed for high-density processors.

    The Manufacturing Hurdle

    Functional diamonds require far stricter purity controls than drill bits or gemstone baguettes. Semiconductor-grade wafers demand precise lattice alignment and minimal defect density, technical standards that many regional Chinese press operators cannot yet hit at commercial scale.

    The near-term commercial volume will stay in thermal heat spreaders rather than pure diamond semiconductor substrates. Heat spreaders tolerate lower purity tolerances while delivering immediate thermal relief to server racks.

    Factory operators in Henan are tracking corporate order volumes from domestic server assemblers as China accelerates local chip packaging buildouts. The transition turns Henan Liliang Diamond’s redirected 1 billion yuan facility into the primary test of whether Chinese gemstone presses can secure sustained industrial orders before 2030.

  • European Luxury Groups Shed €250 Billion as China Demand Slumps

    European Luxury Groups Shed €250 Billion as China Demand Slumps

    European luxury groups shed approximately €250 billion in market value this year as spending across mainland China slowed sharply. The decline forced earnings misses at LVMH, Kering and Hermes after a prolonged property downturn and financial market weakness eroded high-end consumption.

    Europe’s six largest listed luxury houses, including Richemont, Prada and Moncler, absorbed combined market capitalisation losses of €251 billion. LVMH lost €131.6 billion in value, while Hermes surrendered €93.3 billion as Chinese retail sales growth averaged under 0.5 per cent monthly over the past six months.

    Contracting Sales Across Major Houses

    Third-quarter disclosures pointed to widespread deterioration in client demand. Sales at LVMH’s fashion and leather goods division dropped by a mid-teens percentage among Chinese shoppers worldwide.

    Kering experienced an even sharper contraction. Group revenue from Chinese consumers fell between 15 and 20 per cent during the third quarter, worsening from the mid-teens decline recorded in the previous three months.

    Hermes recorded a 2 per cent decline in global ready-to-wear and accessories revenue. The house faced headwinds from falling equity prices in China alongside tighter regulatory scrutiny on overseas capital.

    Tax Pressures and Market Contraction

    Chinese authorities enacted a 20 per cent tax targeting dividends and interest income generated from offshore trusts. The policy took effect this week, adding fiscal pressure on affluent domestic shoppers who drive personal luxury sales.

    Financial markets offered no buffer. The CSI 300 index dropped 19 per cent over four months, erasing more than US$2 trillion in value as investors pulled back over domestic consumption trends and technology equity volatility.

    Broader consumer sentiment weakened alongside personal balance sheets, as the property slump and falling stock markets undermined domestic demand.

    Divergence in Luxury Resilience

    The downturn did not cut evenly across every luxury brand. Hermes expanded sales of Birkin bags and top-tier leather goods by 10.8 per cent globally, sustained by ultra-wealthy buyers.

    Fine jewellery also held up. LVMH’s Tiffany and Kering’s Boucheron produced double-digit percentage revenue increases during the quarter, outperforming ready-to-wear lines and standard footwear.

    Labels reliant on aspirational middle-class shoppers absorbed the heaviest hits. Kering struggled directly as shoppers postponed entry-level purchases, whereas houses anchored strictly to ultra-high-net-worth allocations preserved margin stability.

    Pressures Spread Beyond Asian Borders

    American spending failed to offset the drag from mainland China. Citi credit card transaction figures showed luxury purchasing falls of at least 4 per cent across July, August and September.

    Rising fuel costs and cooling stock performance curtailed discretionary outlays in the United States. Kering confirmed mounting strain on American household expenditure heading into the November elections.

    For luxury operators in Asia, capital allocations will shift from aggressive footprint expansion toward cost controls and productivity gains per square metre.

  • YOTEL Expands Asian Footprint to Four Properties with Bangkok Opening

    YOTEL Expands Asian Footprint to Four Properties with Bangkok Opening

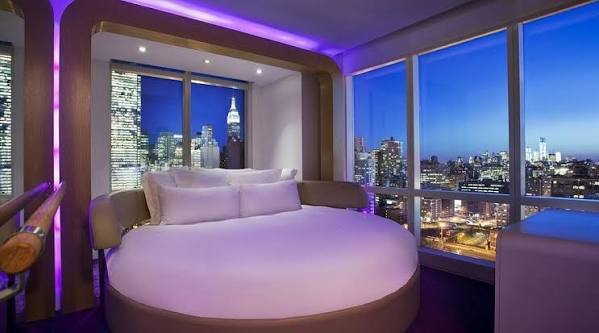
    YOTEL launched its first property in Thailand at Bangkok’s Cloud 11 development in October 2026, anchoring an Asia-Pacific expansion aimed at transit hubs and commercial districts.

    The move brings the company’s operating network in Asia to four locations, following existing outposts in Singapore and Tokyo.

    A debut in Malaysia follows next, with YOTEL Kuala Lumpur City Centre scheduled to open in early 2027.

    Expanding Across Asian Gateway Hubs

    Both additions build on an existing network anchored by YOTEL Tokyo Ginza, YOTEL Singapore Orchard Road, and YOTELAIR Singapore Changi Airport. The company focuses development on high-traffic urban corridors and major transit infrastructure where space constraints command premium yields per square metre.

    Its food and beverage concepts remain central to the floor plans. Properties in Asia feature Komyuniti, a shared multi-functional hub designed for co-working and socialising, alongside casual full-service restaurant Vela and outdoor venue Deck.

    The Micro-Hotel Model Under Pressure

    Compact hospitality models face distinct operating realities across Southeast Asia compared to Western Europe or Japan. In markets like Bangkok and Kuala Lumpur, midscale and upscale four-star rooms frequently trade at lower daily rates, giving corporate travellers and tourists ample full-service alternatives.

    Success for compact pod and cabin operators hinges on non-room revenue and premium real estate integration rather than room count alone. By placing outlets inside multipurpose mega-projects such as Cloud 11, the operator relies on local retail footfall and commercial office tenants to feed its dining and communal areas.

    Transit Hub Lineage and Urban Footprint

    The urban hotel push follows years of building out high-density airside and transit properties globally. The operator established its international transit brand through airport sites at Singapore Changi, Paris Charles de Gaulle, Amsterdam Schiphol, Istanbul, and London Gatwick before pushing further into Asian inner-city commercial districts.

    Outside Southeast Asia, the brand’s global development pipeline includes openings scheduled for Athens in 2027, Belfast in 2028, and NEOM in 2029.

    Next Steps in the Regional Pipeline

    Work now shifts to operational readiness for the Malaysian property due in early 2027. Landlords and retail partners will track occupancy ramp-up numbers from the Sukhumvit property through 2027 to assess whether micro-hospitality concepts can sustain revenue per available room against standard full-service competitors in Southeast Asian capitals.

  • BlackRock in Talks to Sell Shanghai Tower to Rava at 54% Loss

    BlackRock in Talks to Sell Shanghai Tower to Rava at 54% Loss

    BlackRock is in advanced discussions to sell Trinity Place in Shanghai to Hillhouse Investment affiliate Rava Partners for approximately RMB 634 million, taking a 54 percent haircut on the property.

    The prospective deal values the 31,697 square metre tower on Changshou Road at roughly RMB 20,000 per square metre, down from the RMB 1.37 billion the US manager invested in April 2017.

    Trinity Place sits opposite Wuning Road station on metro lines 13 and 14 in Putuo district. Completed in 2006, the asset includes 26,832 square metres of office space across floors 5 through 27, anchored over a 4,865 square metre retail podium occupying the bottom three floors. The transaction remains under active due diligence.

    Rava Plans Residential Pivot

    Rava Partners plans to convert the commercial tower into rental apartments. Claire Tang, now a partner at Rava, oversaw a similar repositioning during her tenure at LaSalle Investment Management in 2022, acquiring a commercial asset in Hongqiao before turning it into multifamily living units.

    Rents in the building currently run between RMB 3 and RMB 5.5 per square metre per day. In 2017, the same space commanded an average of RMB 6.9 per square metre per day. Occupancy inside the tower has dropped to around 60 percent, down from 86 percent at the time BlackRock bought it.

    Yield Pressures Across Fringe Hubs

    Institutional landlords in Shanghai face severe repricing as leasing demand remains concentrated in primary districts. Grade A offices in core Jing An district fetch RMB 258.28 per square metre per month, which works out to about RMB 8.5 per square metre per day. That is nearly double the rental yield achievable at Trinity Place despite the property sitting right on the Jing An district perimeter.

    Peripheral commercial pockets carry vacancy rates hovering near 30 percent, alongside a broader office rent drop exceeding 30 percent across Shanghai since its 2018 peak. Converting older decentralized towers into multi-family housing eliminates dead office stock, but the strategy requires heavy capital expenditure to reconfigure plumbing, fire systems, and floorplates.

    Defaults Preceded Current Divestment

    BlackRock had initially offered Trinity Place for RMB 900 million in March 2025 before lowering its expectations by another 30 percent. The firm originally acquired the property, then known as Shanghai Central Park, from Hong Kong Shanghai Alliance Holdings Ltd.

    The transaction follows earlier distress across BlackRock’s Shanghai portfolio. In January 2018, the asset manager purchased blocks E and G in Waterfront Place from PGIM Real Estate, only to forfeit both office buildings to Standard Chartered in 2024 after defaulting on a RMB 780 million syndicated loan. Standard Chartered subsequently offloaded those Waterfront Place towers to Beijing-based DCL Investment for approximately RMB 695 million in early 2025, a discount of more than 42 percent relative to BlackRock’s initial purchase price.

    Terms to Watch

    Final execution hinges on completion of technical due diligence and local planning sign-offs required to convert commercial zoning into residential operations. Property investors are watching whether closing values fall below the RMB 20,000 per square metre threshold as other institutional owners review decentralized commercial holdings across Shanghai.

  • Blinkit Adds 308 Stores as Net Order Value Surges to ₹20,940 Crore

    Blinkit Adds 308 Stores as Net Order Value Surges to ₹20,940 Crore

    Blinkit increased net order value by 79.3 per cent year on year to ₹20,940 crore in the September quarter, lifting dark store numbers across India to 2,751.

    The quick-commerce unit added 308 net facilities during the three-month period and turned an adjusted EBITDA profit of ₹184 crore, reversing a ₹156 crore loss reported twelve months earlier.

    Parent group Eternal revealed the operational shift in its Q2FY27 shareholder letter, where Albinder Dhindsa raised Blinkit’s network expansion trajectory. The company now plans to cross 3,500 dark stores by March 2027, up from an earlier target of 3,000, with internal blueprints aiming for roughly 5,000 locations by March 2028. Its adjusted EBITDA margin reached 0.9 per cent of net order value for the quarter.

    Inventory Swells Past Pure Grocery

    Assortment depth is driving the physical footprint expansion. In the Delhi-NCR market alone, Blinkit increased its available catalogue from roughly 80,000 stock-keeping units in Q4FY26 to about 100,000 SKUs by the end of the September period.

    The inventory push moves far past packaged food and household staples. Dark stores are stocking consumer electronics, phone chargers, premium beverages, branded diapers, and gaming consoles, with Dhindsa pointing toward household appliances and gifting items for ten-minute dispatch.

    Handling bulkier merchandise changes the operating mechanics inside each depot. Heavier white goods require dedicated storage racking and altered handling procedures, while high-value electronics mandate tighter packaging controls and loss-prevention security. Sourcing arrangements and consumer return processing also differ fundamentally from non-perishable groceries, forcing local managers to balance slow-turning goods against high-velocity essentials.

    Smaller Cities Match Metro Velocity

    Internal network data from the operator contradicts the long-held industry assumption that rapid dispatch models function exclusively inside affluent tier-one metro districts.

    New fulfillment hubs in smaller regional cities reached 1,000 daily orders at speeds identical to metro openings, with several ramping faster. Average order values in these secondary markets tracked between 85 per cent and 90 per cent of metropolitan baskets, supported by repeat purchasing patterns that mirror core capital zones.

    For regional retail ecosystems, quick commerce serves an availability function rather than simple convenience. Shoppers in tier-two and tier-three hubs turn to dark store apps to secure branded goods that organized physical retail distribution never placed on regional store shelves. Sourcing and transport overheads remain high, however, and management conceded that smaller cities with low population density will stay subscale.

    Mature Hubs Cross Profit Threshold

    Financial durability rests on dark store maturity profiles across specific municipal clusters. Hubs generating roughly 96 per cent of Blinkit’s total net order value are now contribution-positive, while municipal zones accounting for about 70 per cent generate positive adjusted EBITDA.

    Established cities in the network operate above a 5 per cent adjusted EBITDA margin. Group management projects that expanding profits from these older operating zones will absorb the start-up losses generated by new store openings, keeping consolidated margins positive throughout the rollout.

    Discount hunters are receiving less attention in the network allocation model. Dhindsa noted that coupon-dependent buyers consume the same finite dark store packing capacity as regular shoppers but disappear once subsidised incentives stop. Current software algorithms prioritize consumers who generate repeat weekly baskets across multiple categories.

    Working Capital and Rival Retailing

    RetailNews Asia notes that Blinkit’s aggressive category broadenings pit it directly against horizontal marketplace leaders. Amazon and Walmart-owned Flipkart stepped up quick-delivery investments in June, pushing ultra-fast fulfillment networks into regional Indian cities using their existing logistics muscle and supplier balance sheets.

    Holding broader stock lines carries immediate balance sheet friction. Eternal’s cash reserves contracted by ₹1,813 crore during the quarter to settle at ₹16,475 crore, dragged down by seasonal inventory build-ups before peak autumn festive consumption and settlement cycles inside its restaurant delivery arm. The corporate entity also reported 76 per cent growth in consolidated adjusted revenue, beating a 58 per cent like-for-like rate as it assumed direct merchandise ownership across its dark store supply chains.

    Private labels remain off the platform roadmap for now. Blinkit decided against introducing house brands, with Dhindsa concluding that own-label items fail to create incremental basket demand once brand-building expenses are factored in. The firm plans to protect supplier advertising income rather than undercut third-party manufacturers.

    Network eyes now turn to the execution of the 749 additional dark store openings required to hit the 3,500-unit threshold before the close of fiscal 2027.