Author: Mei Ling Tan

  • Bangkok Watch Week Attracts 40,000 Visitors to Siam Paragon

    Bangkok Watch Week Attracts 40,000 Visitors to Siam Paragon

    Siam Piwat Group drew more than 40,000 visitors to the second edition of Bangkok Watch Week at Siam Paragon, expanding brand participation past 45 luxury houses.

    The six-day exhibition, held from September 22 to 27 across two floors of the Bangkok shopping complex, doubled its overall attendance compared with its 2025 debut. The turnout included 400 international collectors, while brand participation climbed more than 50 per cent.

    Organised by mall operator Siam Piwat, the event operated across three formats: a public show, an industry symposium, and brand-run boutique workshops. Entry remained free for regular shoppers. The Fondation Haute Horlogerie joined the programme for its Southeast Asian debut, running an academy lounge offering entry-level horology certifications to the public.

    Shifting luxury retail from private salons to mall concourses

    For decades, Swiss and European watchmakers restricted previews to invite-only trade summits in Geneva or closed boutique salons. Bringing 45 maisons directly onto the open concourse of a Southeast Asian commercial mall reverses that playbook. Siam Piwat is betting that footfall conversion no longer depends strictly on closed-door clienteling, but on pulling younger consumers into technical workshops before they buy their first mechanical piece.

    The approach hands luxury tenants direct exposure to high-spending tourist traffic that standard multibrand watch retailers struggle to capture organically. Thai landlords face sharp regional competition from Singapore and Tokyo for luxury spend, making hands-on programming essential to keep international shoppers on-site.

    Siam Piwat targets international collector traffic

    Tourism flows into central Bangkok remain critical to the format. Siam Piwat identified Chinese and Indian travelers as volume drivers for overall mall trade, while shoppers from elsewhere in Asia and the Middle East deliver the highest average transaction values.

    Pavaris Eam-ekpattana, director of strategic luxury experience management at Siam Piwat unit Supremo Co., confirmed that the group separates the show from its older commercial watch events.

    Brand interest expanded beyond the major Swiss conglomerates. British brand Bremont attended for the first time to seek a local distributor, while boutique managers from German maker A. Lange & Söhne reported that multi-brand exposure helped bridge client bases with houses such as Panerai, Jaeger-LeCoultre, and Vacheron Constantin.

    Attendance gains build on initial sales spike

    The operational expansion follows steep top-line gains recorded during the event’s first run. During the inaugural 2025 edition, Siam Paragon attracted 20,000 visitors and 200 foreign collectors. Luxury watch sales inside the mall surged 92 per cent compared with the corresponding period in 2024.

    Caroline Murphy, president of strategic project development at Siam Piwat, said the mall owner does not evaluate the fair purely on short-term sales desks:

    “We do not measure the success of the event in terms of sales as the primary purpose of the fair is not commercial, but to establish Bangkok as a luxury watch capital of the world, by sharing knowledge and insight of the wonderful world of watchmaking to a robust watch community of local Thai and international collectors,”

    Global network plans for third edition

    Siam Piwat is preparing to link future editions into a wider circuit. The organiser is evaluating strategic ties with luxury events in Tokyo and Milan, aiming to create a recurring international calendar stop rather than a standalone Bangkok marketing push.

    Brand retention and floor space allocations across Siam Paragon’s central retail levels serve as the key operational test.
  • Singapore Home Prices Rise 1.4% as Suburban Condos Lead Gains

    Singapore Home Prices Rise 1.4% as Suburban Condos Lead Gains

    Private residential property prices in Singapore climbed 1.4 percent in the third quarter of 2026, registering the fastest quarterly increase in almost two years. Suburban condominium values led the expansion with a 2.3 percent surge, even as primary sales dropped sharply because developers held back major project releases.

    Official numbers from the Urban Redevelopment Authority show the private housing index outpaced the 0.5 percent growth recorded in the second quarter. The acceleration represents the strongest single-quarter gain since a 2.3 percent rise in the final quarter of 2024, extending an upward pricing trend across eight consecutive quarters. Island-wide economic growth of 5.4 percent year on year during the quarter helped anchor overall housing demand.

    Suburban Values Advance while Prime Districts Diverge

    Apartments in the Outside Central Region, the official classification for Singapore’s suburban districts, drove the pricing rebound after dipping 0.1 percent in the preceding three months. Over the first nine months of 2026, suburban non-landed prices rose 4.4 percent, exceeding the 3.2 percent gain registered throughout 2025. Landed property prices across the island rose 2.9 percent, outpacing the 1.0 percent increase recorded across all non-landed homes.

    City fringe non-landed prices in the Rest of Central Region held flat following a 1.2 percent contraction in the second quarter. Growth in the prime Core Central Region moderated to 0.3 percent from 1.8 percent, though transaction volumes in those central districts rebounded 23.5 percent. A US buyer completed the period’s highest-value private residential deal, paying S$20 million, or $15.6 million, for a 3,272-square-foot unit at Sculptura Ardmore.

    Foreign buyers represented only 1.1 percent of all non-landed home acquisitions across the quarter. Singapore citizens accounted for 81.2 percent of purchases, and permanent residents took up the remaining 17.6 percent.

    Primary Sales Slump on Launch Calendar Lull

    Developers sold 1,183 private homes, excluding executive condominiums, between July and September. That total represents a 44.7 percent decline from the 2,141 units moved in the second quarter and sits 64.0 percent below volumes from the same quarter in 2025. Primary supply contracted in tandem, with developers releasing 1,140 units, down 36.1 percent quarter on quarter to make it the quietest third quarter for project launches on record.

    A quiet launch calendar during the lunar seventh month kept prospective buyers on the sidelines ahead of fourth-quarter rollouts. Resale transactions stepped in to fill the gap, totaling 3,801 units and taking 73.9 percent of total secondary and primary market sales. Resale home prices slipped 1.1 percent as buyers used the reduced primary activity to negotiate discounts.

    Fewer private homes were sold as developers paused their launches during the lunar seventh month, while prospective buyers held out for Q4 projects,

    Dunearn House, the initial residential offering on the former Bukit Timah racecourse site at Turf City, sold 237 of its 380 units. Amberwood at Holland in District 10 recorded 24 sales at a median rate close to S$3,000 per square foot, while Lentor Gardens Residences closed the period as the quarter’s highest-volume seller.

    Rental Gains and Completed Inventory Add Pressure

    Private home rents climbed 1.3 percent across the quarter, speeding up from a 0.7 percent increase in the prior quarter to record the sharpest climb since the second quarter of 2023. Suburban apartment rents drove the trend with a 3.1 percent jump, while city fringe rents rose 1.5 percent and prime rentals declined 0.3 percent. Property researchers expect residential rental rates to increase between 2.5 percent and 3.0 percent for the full year.

    Supply deliveries expanded rapidly at the same time. Developers completed 3,559 private residential units and executive condominiums during the quarter, the largest volume delivered since the third quarter of 2024. Completed inventory expanded by 3,491 private units while occupied stock contracted by 305 homes, lifting island-wide private vacancy to 7.2 percent from 6.4 percent.

    For consumer operators, lifestyle retail tenants, and commercial landlords across Singapore, elevated suburban housing costs redirect household spending away from discretionary purchases. High mortgage obligations and rising suburban rents squeeze disposable budgets in satellite towns, while higher vacancy rates in the city fringe point to localized pockets of excess supply.

    Developer Pipeline Readies Fourth-Quarter Tests

    A heavy launch pipeline scheduled through the close of 2026 will test buyer depth under tighter household balance sheets. The 1,268-unit Thomson Reserve on the city fringe anchors this pipeline, led by a joint venture where CapitaLand Development holds 50 percent, UOL Group holds 40 percent, and Singapore Land Group controls 10 percent. The group acquired the former Thomson View site for S$810 million, with units starting at S$1.544 million, or S$2,608 per square foot.

    City Developments tested buyer appetite early in the fourth quarter at Lucerne Grand on Lakeside Drive, shifting 350 of 570 units over its opening weekend ending 4 October at an average price of S$2,480 per square foot. CDL secured the government land sales plot in 2025 for S$608 million, reflecting a land rate of S$1,132 per square foot of gross floor area.

    Full-year primary volumes are expected to reach roughly 7,000 homes against developer launches of up to 6,300 units, marking the first time since 2022 that developer sales outstrip new project supply. With the government’s Confirmed List releasing 9,320 private homes this year, market attention shifts to the opening of bookings at Thomson Reserve on 31 October.

  • Prada Holds Organic Revenue Growth at 1% as China Foot Traffic Softens

    Prada Holds Organic Revenue Growth at 1% as China Foot Traffic Softens

    Prada reported a 1 per cent rise in third-quarter organic revenue, keeping group sales steady despite footfall drying up across shopping centres in mainland China.

    Total group revenue reached €1.49 billion including newly acquired Versace, matching analyst consensus estimates compiled by Visible Alpha.

    Organic calculations exclude Versace, which Prada purchased in December last year. Management reported that the integration of the fashion house remains on track ahead of the runway debut of Pieter Mulier, the label’s incoming creative director, scheduled for next year.

    Mainland Footfall Drags on Asia-Pacific Margins

    Sales across the Asia-Pacific territory held flat during the three months. Foot traffic in mainland Chinese luxury malls remained subdued, forcing the group to rely on gains in secondary Asian markets to keep regional top-line figures level.

    The stagnation in greater China tests the regional retail model. Landlords have leaned heavily on premium fashion houses to anchor luxury malls, yet conversion rates are slipping as aspirational consumers pull back.

    Luxury brands face an unforgiving margin squeeze when foot traffic drops in Chinese flagship units. High retail rents and store operations negotiated during peak post-lockdown trading now run against lower volumes, leaving operators to depend on high-net-worth VIP clients rather than walk-in demand.

    Miu Miu Momentum Moderates

    Miu Miu recorded a slower pace of expansion in the third quarter after driving the bulk of Prada’s total organic revenue lift throughout 2025. The brand had previously outpaced the flagship label by wide margins, drawing younger consumers across East Asia with viral accessories and footwear lines.

    Outside Asia, trading patterns diverged sharply. North American operations delivered continued top-line gains, though at a milder pace than in the second quarter, while European sales remained weak.

    “The third quarter unfolded against a particularly challenging industry backdrop. In this context, the Group showed good resilience, underpinned by brand desirability and strong retail execution”, Chief Executive Andrea Guerra said in a statement.

    Integration Roadblocks and What to Watch

    Prada entered the current quarter after completing its takeover of Versace late last year, an acquisition aimed at building a multi-brand Italian conglomerate to counter French luxury groups. Absorbing that business while Asian demand cools raises operational risks across retail networks.

    Attention now shifts to the commercial reception of Pieter Mulier’s first Versace collection next year, which will show whether the enlarged group can generate wholesale and direct-to-consumer momentum outside the core Prada nameplate.

  • Thailand Caps Retail Credit Terms at 45 Days

    Thailand Caps Retail Credit Terms at 45 Days

    Thailand’s competition regulator has capped trade credit terms at 45 days for large retailers dealing with small suppliers, backing the rule with fines of up to 10 per cent of revenue.

    The Trade Competition Commission of Thailand (TCCT) issued the binding notification in the Royal Gazette this month, taking aim at wholesalers and retailers generating over 500 million baht in annual turnover across department stores, specialty shops, supermarkets, hypermarkets, cash-and-carry outlets and convenience networks.

    Under rules taking effect in November, payment windows between large retail operators and commercial, manufacturing or service SMEs cannot exceed 45 days unless a shorter schedule is agreed. For agricultural produce and basic processed farm goods, settlements must conclude within 30 days. Consignment terms start when agreed volumes sell in full, whereas standard shipments begin the cycle once deliveries arrive complete with proper documentation.

    Violators of this notification could face a fine of up to 10% of their revenue in the year in which the offence occurred, or up to 1 million baht if the offence occurs during their first year of operation.

    Investigating Encroachment on Franchisees

    Beyond payment terms, the TCCT is deploying investigative teams to Phetchaburi and Lampang provinces to inspect convenience store networks and traditional mom-and-pop grocers. Evidence gathered through the regulator’s Mobile Competition Clinic revealed parent chains frequently open company-owned corporate outlets directly beside existing franchisees, cannibalising store traffic after collecting upfront licensing fees.

    Retail operators told authorities that extra units meet high local shopper density that single stores cannot serve. Pol Col Songsak Raksaksakul, vice-chairman at the TCCT, dismissed the contractual defense during preliminary hearings.

    Even if contracts allow this practice, the fairness of such agreements is questionable under fair-trade principles, Pol Col Songsak noted.

    The commission is also scrutinising whether dominant supermarket operators abuse consignment arrangements. Multiple SME groups reported that after their packaged items established strong sales on modern trade shelves, chains launched copycat house-brand alternatives, while the TCCT is examining whether unilateral changes to product shelf positions constitute an unfair trade practice.

    Pressure on Working Capital Models

    Thai retail chains have long operated by funding store rollouts through supplier credit. Forcing payments out within 30 to 45 days removes cheap short-term financing that supported rapid network expansion across provincial capitals. Chains must now decide whether to reallocate working capital or prune marginal product lines to keep cash conversion cycles tight.

    Suppliers gain needed balance sheet relief, but small brands risk immediate pushback from category managers. Supermarket buyers faced with strict payment liabilities often rationalise stock keeping units, favouring larger multinational consumer goods conglomerates that supply higher volumes and absorb rebate deductions without dispute.

    Zoning and Local Sourcing Mandates

    The field investigations in Phetchaburi and Lampang wrap by late November, alongside focus groups scheduled early in the month to measure consumer and merchant sentiment. Data from those sessions will shape an enforceable retail code of practice and feed policy guidance to urban planning authorities and local administrative organisations.

    The Turn from Voluntary Guidelines

    The statutory credit notification replaces voluntary terms that big retailers routinely bypassed. TCCT commissioner Warawan Chitaroon said that while the watchdog published voluntary guidelines previously, extended payment delays persisted because corporate buyers faced no statutory teeth. Formal publication in the Royal Gazette converts credit schedules from advisory best practices into enforceable law.

    The statutory credit rules take effect in November, while the TCCT plans consultations with retail operators before drafting the formal code of conduct on store positioning and franchising practices.

  • Ripple Urges SEC to Finalize Crypto Rules After $150 Million Legal Battle

    Ripple Urges SEC to Finalize Crypto Rules After $150 Million Legal Battle

    Ripple urged the US Securities and Exchange Commission to finalize proposed digital asset rules on October 20, following a legal battle in which the firm spent more than $150 million seeking regulatory clarity.

    Chief Legal Officer Stuart Alderoty confirmed the submission backs the agency’s proposed Regulation Crypto Assets framework, arguing that years of case-by-case enforcement have pushed domestic innovation overseas.

    The SEC introduced the framework in August, outlining clear boundaries to help crypto companies understand their obligations without facing protracted court challenges.

    Safe Harbours and Capital Thresholds

    The SEC proposal introduces exemptions designed to let qualifying digital asset issuers raise capital without full public registration. Startups could raise up to $5 million over four years under one provision, while a separate exemption permits up to $75 million within a 12-month window under stricter financial disclosures.

    A critical piece of the draft creates a safe harbour that releases a token from investment contract rules once an issuer satisfies its original network commitments.

    Ripple Chief Legal Officer Stuart Alderoty argued the agency possesses full authority to implement the framework. Under the standard Howey test, regulatory scrutiny should evaluate specific issuer promises rather than treating secondary token sales or decentralization metrics as automatic triggers for securities status.

    Industry Pushback Across Major Networks

    Ripple joined a broader coalition of blockchain foundations that submitted recommendations before the comment window closed. A joint filing by Chainlink, Hedera, Stellar, Aptos, Avalanche and Cardano urged the commission to explicitly define digital commodities within the formal rule text.

    The push reflects widespread industry fatigue with retroactive enforcement. Ripple spent more than $150 million in legal fees battling the SEC, a figure few smaller Web3 startups can survive.

    The SEC is reviewing the comment letters ahead of a full commission vote on the final language for Regulation Crypto Assets.

  • CP Group Distances Senior Chairman from 4 Holy Basil Patents

    CP Group Distances Senior Chairman from 4 Holy Basil Patents

    Charoen Pokphand Group (CP) issued a statement on Saturday distancing itself and senior chairman Dhanin Chearavanont from controversial patent registrations covering four new varieties of holy basil.

    The agribusiness conglomerate responded after social media posts alleged CP and Mr Dhanin owned all holy basil varieties across Thailand, barring farmers and consumers from cultivating or selling the herb without permission.

    “That is not factual, scares people and affects the reputation of Charoen Pokphand Group and the individual mentioned,” the company stated, noting that subsidiary CPRAM obtained the 4 plant patents independently.

    Corporate Structure and IP Ownership

    CPRAM operates as a subsidiary of Stock Exchange of Thailand-listed CP All Plc. Charoen Pokphand Group holds equity in CP All, but the parent entity stated it maintains no operational authority over board decisions or intellectual property filings conducted by individual subsidiaries.

    The dispute flared after social media claims alleged CP held a commercial monopoly over holy basil, known locally as kaphrao. Rumours claimed growers faced legal penalties without corporate licensing, prompting visible pushback from herb vendors across wholesale wet markets.

    Read Across for Food Retailers and Agricultural Suppliers

    Contract farming and retail ready meal supply chains across Southeast Asia hinge on public goodwill, particularly when major conglomerates patent proprietary seeds for national staple ingredients. Operating companies in Thailand frequently develop crossbred crops to boost yields, uniform leaf sizes, and shelf life for high-volume chilled convenience meals, yet proprietary breeding quickly draws political scrutiny when perceived as corporate fencing of common culinary heritage.

    For consumer operators, food processors, and supply chain managers, the controversy demonstrates that holding standard plant variety certificates can trigger immediate brand friction at retail stalls. CPRAM pursued higher harvest yields and profit margins for partnered growers, but the conglomerate found itself forced into public damage control to prevent broader boycotts against its convenience retail channels.

    Regulatory Scrutiny on Plant Varieties

    Public pushback escalated after domestic television broadcasts featured market vendors criticising corporate control over phat kaphrao, widely treated as Thailand’s staple national stir-fry. In response, government regulators at the Department of Agriculture moved to examine the underlying registration filings covering the specific varieties held by the group’s manufacturing unit.

    The company warned that it reserves legal rights to pursue parties spreading false statements that harm group reputations or executive standing, while state agriculture inspectors conduct their formal registration review.

  • Sydney Opens A$5.6 Billion International Airport to Commercial Passengers

    Sydney Opens A$5.6 Billion International Airport to Commercial Passengers

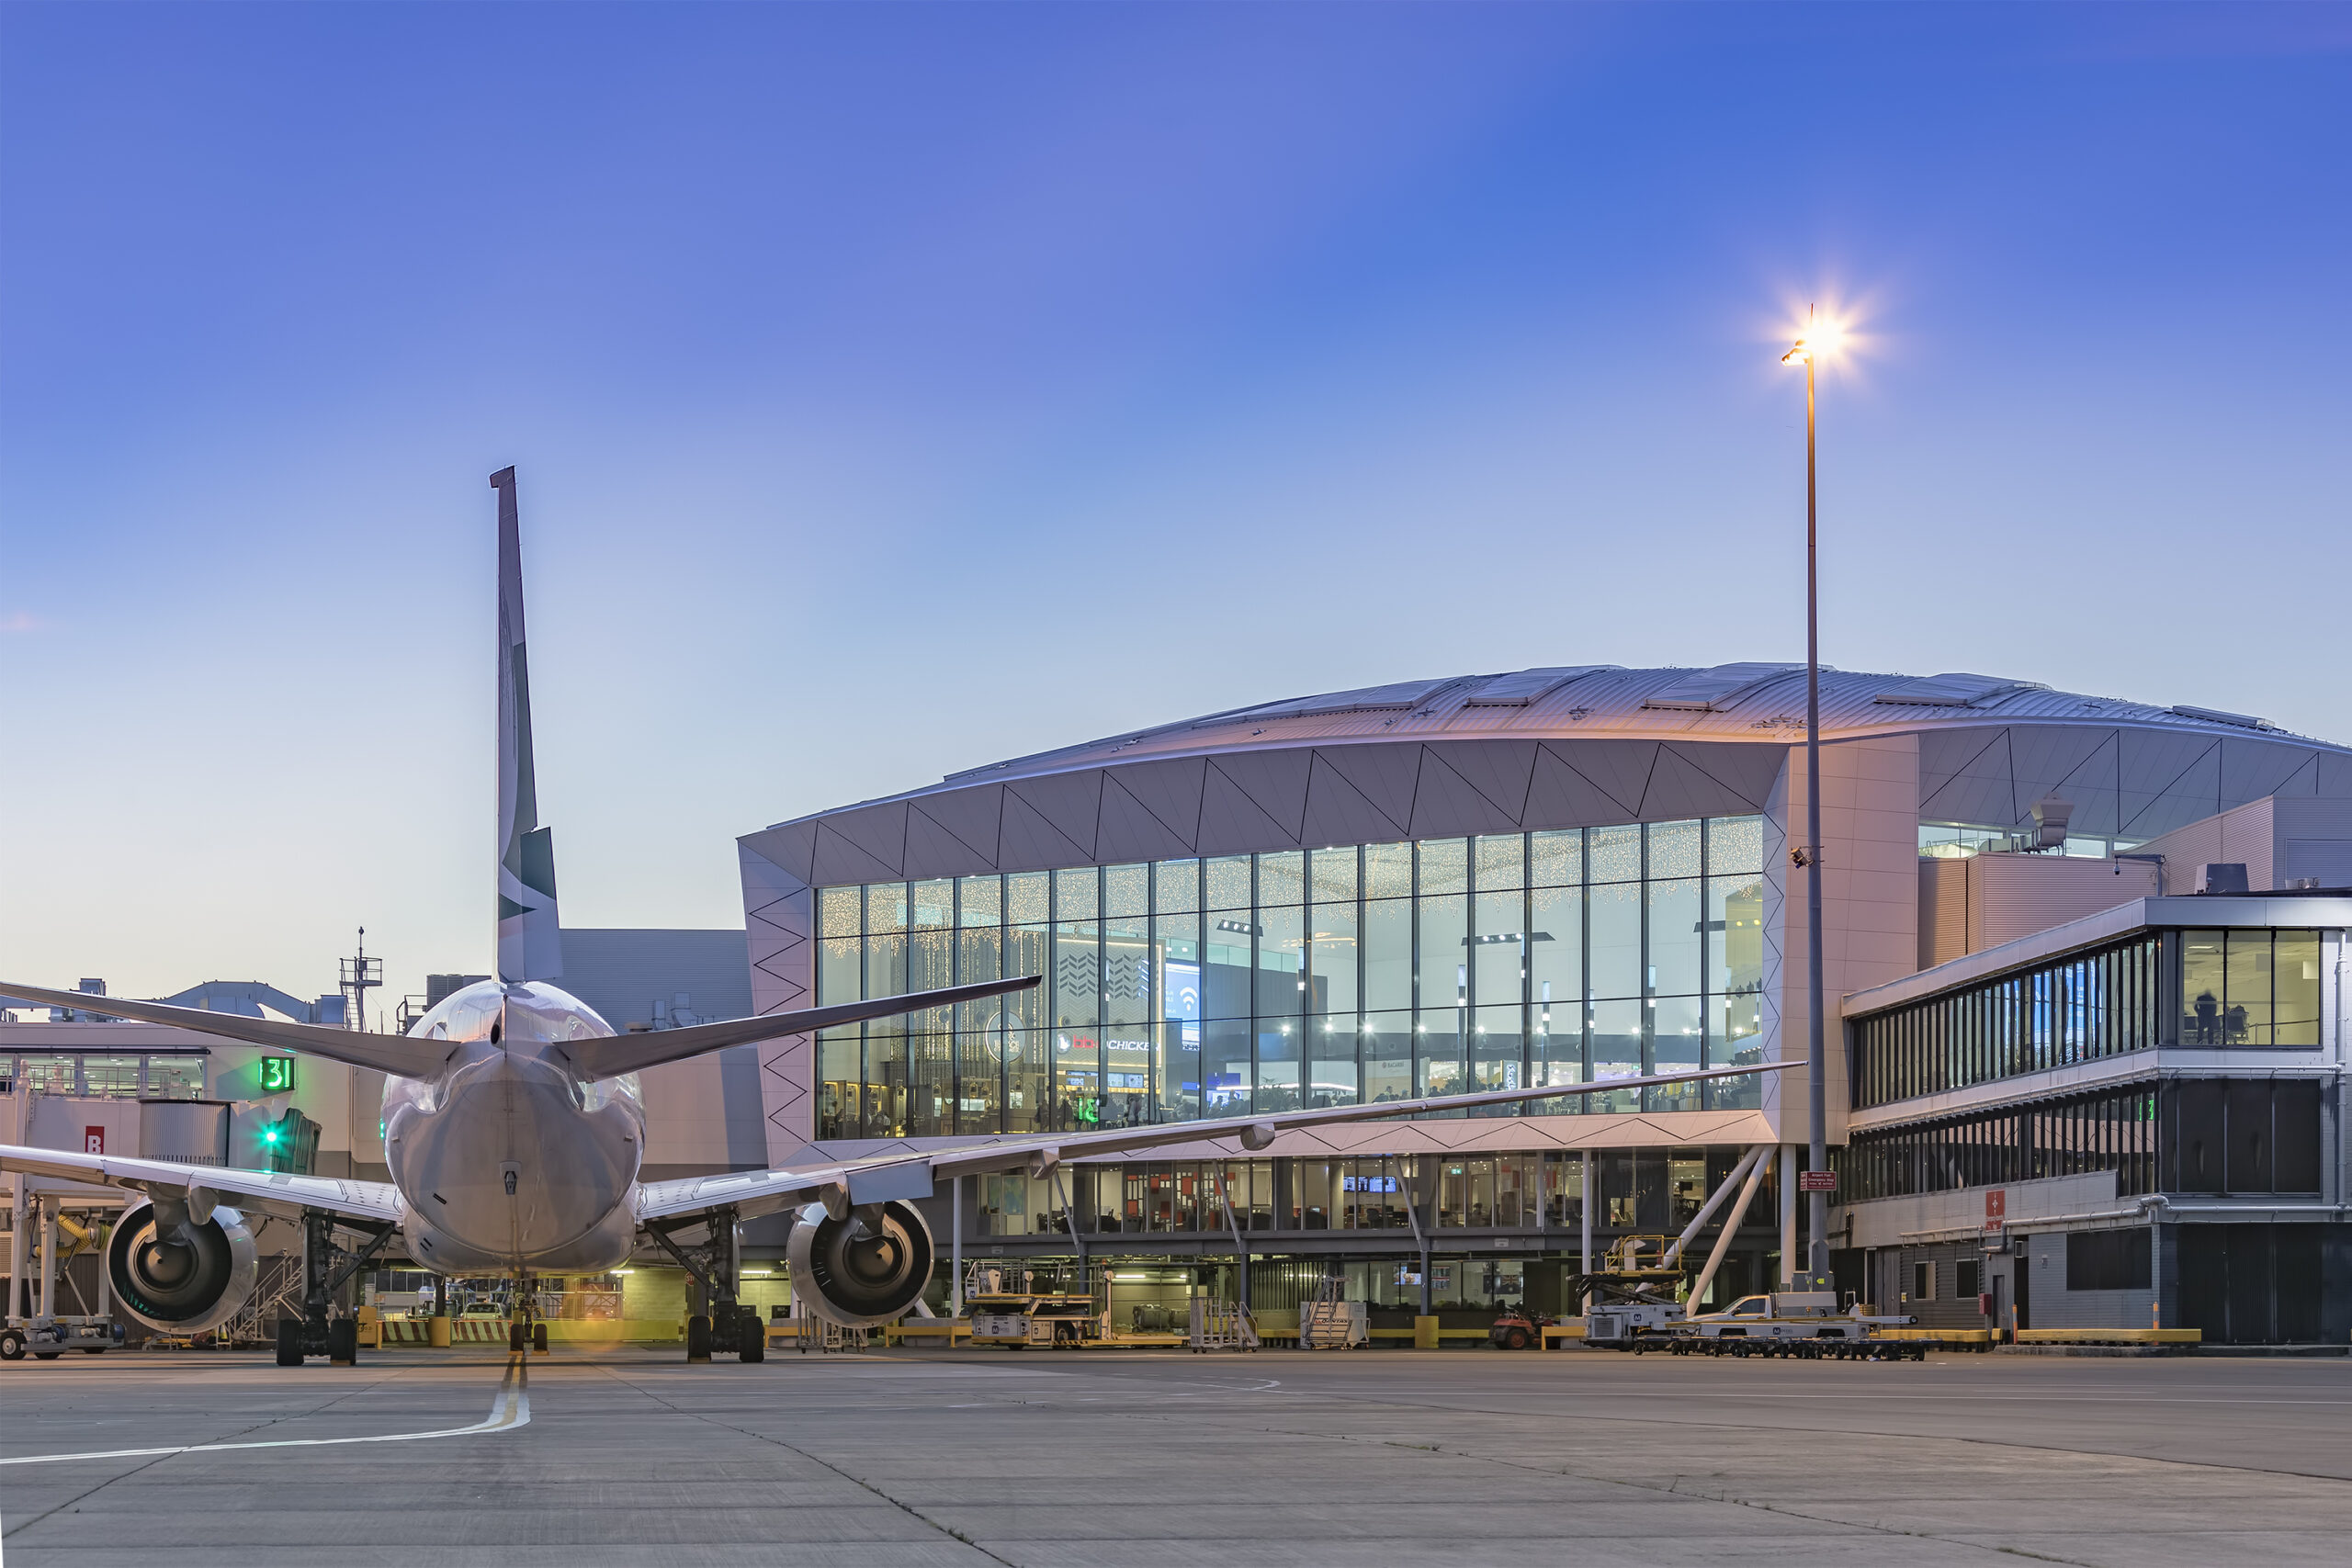
    Sydney’s new A$5.6 billion ($3.94 billion) Western Sydney International Airport opened to passenger traffic on Sunday following more than a decade of planning. Located across a 1,780-hectare site at Badgerys Creek, the facility gives airlines round-the-clock operating capacity 60 kilometres west of the city centre.

    Budget carrier Jetstar was scheduled to fly the inaugural outbound service to the Gold Coast, initiating passenger operations alongside parent group Qantas Airways. Built to serve Australia’s most populous city, the complex holds capacity for more than 80 million passenger movements each year.

    Prime Minister Anthony Albanese hailed the completion of the long-planned infrastructure project as passenger services officially got underway.

    Round-the-clock operations bypass curfew restrictions

    Unrestricted operational hours distinguish the new hub from Sydney’s current airport. The legacy facility enforces a strict flight curfew between 11 p.m. And 6 a.m., which restricts scheduling flexibility and night cargo handling.

    Removing the overnight window alters aircraft utilisation models for domestic and regional carriers. Airlines can now cycle narrow-body aircraft through late-night turnarounds and stage departures to match early morning arrival windows across Southeast Asian hubs.

    Commercial cargo infrastructure and logistics shifts

    Passenger services follow dedicated air freight operations that began at Badgerys Creek in July. Running belly-hold cargo alongside freight aircraft without nocturnal halts allows freight forwarders to bypass highway bottlenecks around the inner-city port precinct.

    For logistics operators and retail importers, late-night processing reduces clearance lags on high-value electronics and cross-border consumer consignments. Distribution hubs situated across Western Sydney gain direct runway access rather than trucking goods across congested arterial motorways to the current airport.

    For the first time in more than 50 years, Australia is opening a major new airport. It’s a milestone that has been decades in the making.

    Prime Minister Anthony Albanese confirmed the project’s delivery in an official statement, noting the prolonged development timeline behind the federal infrastructure asset.

    Project execution spans decades of federal planning

    Federal authorities acquired the Badgerys Creek land parcels in the 1980s, leaving the site dormant before formal planning resumed fifteen years ago. Physical construction commenced seven years ago, culminating in core building delivery in July 2025.

    International carriers will monitor route yields as foreign airlines negotiate future slot allocations against the existing terminal. The immediate commercial test rests on passenger uptake across Jetstar’s domestic network before scheduled international operators begin services from the runway.

  • China NEV Retail Sales Forecast at 1.07 Million in October

    China NEV Retail Sales Forecast at 1.07 Million in October

    China new energy vehicle retail sales are expected to reach roughly 1.07 million units in October, down 16.5 per cent year-on-year, according to a report released on Friday by the China Passenger Car Association. The decline extends a prolonged cooling period in the automotive market.

    Total passenger car retail volume across the country is projected to drop 28.9 per cent to 1.6 million units over the same period, deepening an annual slide from September’s 28.0 per cent fall. While new energy vehicle retail penetration remains high at an estimated 66.9 per cent, market share dipped by 0.1 percentage points from the record 67.0 per cent achieved in September.

    CPCA analysts noted that traditional seasonal sales boosts have weakened significantly, leaving overall demand sluggish despite high adoption rates for electric and hybrid models.

    Holiday Traffic Fails to Sustain Dealership Momentum

    Showroom traffic rose briefly during the National Day holiday in early October before dropping sharply across major dealership networks. Accumulated holiday orders lifted average daily retail sales to 58,000 units during the second week of the month, but daily volume slumped to 47,000 units by the third week.

    The association projected average daily sales to stabilize around 49,000 units in the fourth week as third-quarter vehicle launches clear delivery backlogs. A final month-end push is expected to lift daily transactions to 79,000 units in the fifth week.

    Between October 1 and October 18, actual passenger NEV retail sales reached 520,000 units, reflecting a 13 per cent drop compared to the same period in 2025 and a 2 per cent decline from September.

    Target Shortfalls and Price Discipline

    An early October survey of automotive manufacturers found that most leading brands achieved less than 60 per cent of their annual sales targets during the first three quarters of 2026. Automakers have grown increasingly cautious regarding final-quarter volume growth.

    Dealer profitability concerns and industry efforts to prevent excessive discounting have restricted further price reductions. Retailers are turning to defensive inventory strategies rather than using heavy dealer-subsidized promotions to generate turnover.

    High pump prices continue to drag on traditional gasoline vehicle sales, keeping consumer preference tilted toward electric and plug-in hybrid alternatives. Even with sustained consumer interest, longer stretches between product debuts, order books, and physical deliveries have stretched purchase cycles.

    Slowing Momentum Across the Sector

    The October forecast reflects a retail market struggling to generate organic foot traffic after aggressive promotional cycles in earlier quarters. Electric vehicle adoption in China has largely stabilized at two-thirds of all passenger retail sales, leaving volume expansion dependent on overall car market recovery rather than pure conversion from combustion engines.

    Retail operators face margin compression as showroom overhead persists while unit sales drop across combustion and electric formats alike. Automotive distribution groups that borrowed heavily to expand exclusive EV brand showrooms must now navigate lower throughput without relying on steep factory-backed consumer rebates.

    Nine Months of Contraction

    Retail sales for NEVs slipped 16.7 per cent year-on-year in September, marking the ninth straight monthly drop. Across the first nine months of 2026, cumulative NEV retail sales stood at 7.758 million units, down 12.8 per cent from the previous year.

    Year-to-date monthly data shows volume peaks in September at 1.084 million units and June at 1.007 million units, compared to much stronger monthly highs above 1.28 million units seen during late 2025.

    Car manufacturers now look to November delivery schedules and year-end showroom clearances to salvage annual volume commitments.

  • Japanese Automakers Halve Vehicle Development Times to Under Two Years

    Japanese Automakers Halve Vehicle Development Times to Under Two Years

    Japanese carmakers are moving to cut traditional four- to five-year vehicle development cycles by up to half to counter Chinese competitors that bring new models to market in under two years.

    Toyota Motor, Honda Motor, Nissan Motor, Suzuki Motor, and Mitsubishi Motors are overhauling vehicle platforms, cutting part types, and deploying artificial intelligence to speed up product pipelines.

    The push targets major operational milestones leading up to 2028, when Nissan plans to launch a vehicle developed under its compressed timeline.

    Nissan Shifts to Common Underpinnings

    Nissan plans to reduce development lead time for a new sport-utility vehicle intended for North America in 2028 down to three years and one month. The company will then adapt that base platform for derivative vehicles, reducing subsequent model development time by up to 40 per cent to two and a half years.

    This family-based vehicle strategy will cover 80 per cent of Nissan’s global vehicle volume. Management expects the common architecture will eliminate 70 per cent of its distinct part types.

    “This is a reform to become a company that responds to changes and delivers good cars in a timely manner,” Hidemi Sasaki, deputy general manager of Nissan’s product planning division, said.

    Honda and Toyota Target Cost and Plant Footprints

    Honda has rolled out an internal program called Triple Half to halve development expenditures, lead times, and engineering workloads from 2025 baselines. The automaker plans to rely on artificial intelligence and digital design workflows, applying the compressed schedule to vehicle projects that enter development in 2028.

    Toyota is targeting manufacturing complexity through a program titled Area 35. The world’s largest automaker is cutting part variations based on consumer demand trends to raise plant floor space utilization by 35 per cent.

    Smaller domestic rivals are adjusting schedules as well. Suzuki plans to cut its development cycle in half to roughly two years, while Mitsubishi Motors aims to reduce timelines by 20 per cent to three years by around 2030.

    The Supply Chain Pressure Across Asia

    Legacy development cycles of five years left Japanese original equipment manufacturers exposed in China, where local brands iterate vehicle software, cabin electronics, and battery packs on consumer electronics schedules. By condensing development to 24 to 36 months, Japanese brands are forcing tier-one parts suppliers across the region to standardize tooling and shorten quotation windows.

    This compression carries execution risks for engineering quality control. Chinese automakers accepted higher initial defect rates and relied on rapid over-the-air software updates to compensate for compressed testing windows, whereas Japanese brands built their regional pricing power on mechanical durability and strict pre-production validation.

    The Deficit Forcing Change

    The push follows sharp operational corrections among Japan’s leading vehicle assemblers. Honda posted its first net loss in the previous fiscal year, prompting leadership to seek a swift operational recovery by shedding product overhead and accelerating project delivery.

    Nissan faces similar financial pressure to trim fixed costs after years of fragmented vehicle architectures eroded manufacturing margins across key export markets.

    The first concrete test of these accelerated development timelines arrives with Nissan’s platform debut in 2028, followed by the initial vehicle programs under Honda’s halved development cycle that same year.

  • Australia Post Signs 99-Year Lease to Transform Brisbane GPO

    Australia Post Signs 99-Year Lease to Transform Brisbane GPO

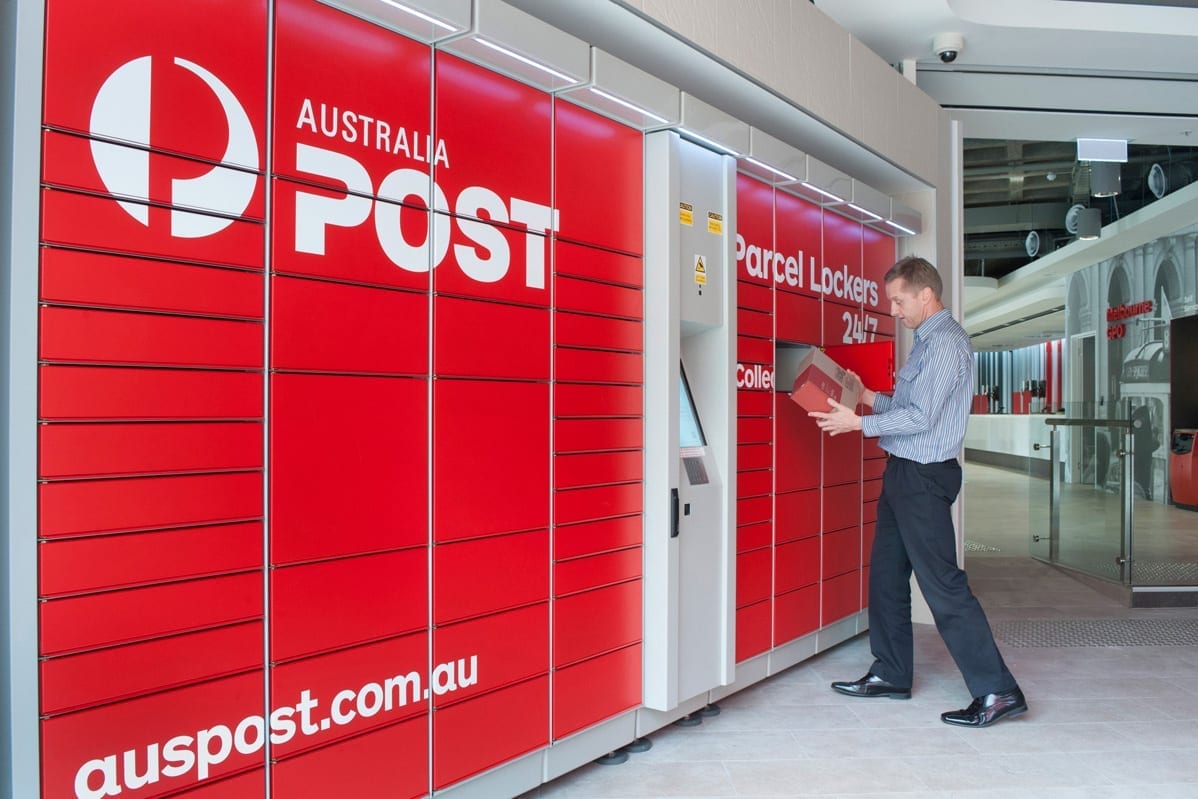
    Australia Post finalized a 99-year leasehold agreement in October 2026 to transform Brisbane’s heritage-listed General Post Office into a mixed-use retail and commercial precinct.

    Real estate investment management and advisory firm Mackwell secured the long-term lease for the 1872 property at 261 Queen Street, marking the first time the site has been offered to the market.

    Under the agreement, Mackwell will reconfigure the historic building into new office accommodation and retail spaces. Australia Post confirmed it will retain its full suite of postal services within the precinct without interrupting regular trading hours. CBRE Capital Markets, Offices, Queensland brokered the transaction.

    Queen Street Mall Link and Commercial Strategy

    The overhaul connects the property directly with foot traffic from the adjacent Queen Street Mall retail corridor. Australia Post Group Chief Financial Officer Craig Roberts said the deal allows the state-owned postal operator to monetize dormant floor area.

    “We know how important our services are to the community and the Post Office will continue to operate from this site, ensuring CBD workers and residents have easy and convenient access,” said Craig Roberts, Australia Post Group’s CFO.

    Mackwell Managing Director John Robson intends to pitch the heritage asset as high-end boutique commercial space. Preserving stone masonry while cutting in modern building services and vertical circulation will form the primary engineering cost.

    Capital Recycling Ahead of the 2032 Games

    State infrastructure authorities and commercial property developers are racing to modernise Brisbane’s central business district before the city hosts the 2032 Olympic Games. Private capital continues chasing inner-city parcels that carry established foot traffic rather than speculative peripheral builds. Long-dated ground leases offer public corporations upfront liquidity while retaining freehold title over crown land.

    For regional retail landlords, the entry of refurbished character space places pressure on standard institutional office towers along Queen Street. Heritage retail tenancies often command rental premiums from luxury fashion and food operators seeking distinct architecture rather than standard mall shells. Mackwell carries the leasing risk if corporate tenant demand for central Brisbane floor space softens during construction.

    Operational Counter Hours and Next Steps

    The building was purpose-built for the Australian postal network in 1872. The public entity has spent the last decade rationalising physical post shops as parcel volumes eclipse traditional letters, offloading or repurposing metropolitan real estate to fund automated parcel hubs.

    Counter operations at 261 Queen Street will maintain existing schedules during early construction work, trading Monday through Friday from 8:30am to 5:00pm and Saturday mornings until 12:30pm. Mackwell will submit formal heritage architectural filings and tenancy configurations to local planning authorities before physical building works commence on site.

  • Indonesia Imposes Record $117 Million Trading Fines on Tycoon-Linked Firms

    Indonesia Imposes Record $117 Million Trading Fines on Tycoon-Linked Firms

    Indonesia’s financial regulator has imposed record fines totaling 2.1 trillion rupiah ($116.67 million) on investment vehicles tied to billionaire Prajogo Pangestu and the Widjaja family over market manipulation and IPO disclosure breaches.

    Announcing the move late Wednesday, Financial Services Authority (OJK) chair Friderica Widyasari Dewi confirmed the penalties are the largest ever delivered by the agency.

    Regulators levied a 1.5 trillion rupiah penalty against an entity identified as SMT for manipulating shares in Dian Swastatika Sentosa, a mining and energy business within the Widjaja family’s $28.3 billion Sinar Mas group. OJK determined that the trades caused an artificial jump in the stock’s price.

    Two other penalties targeted entities involved in high-profile public listings linked to Pangestu, whose wealth Forbes pegs at $12.6 billion. An entity named AH Ltd received a 500 billion rupiah fine for concealing shareholder data during the initial public offering of geothermal operator Barito Renewables Energy, while TC Pte Ltd drew a 100 billion rupiah sanction over similar violations during the listing of mineral firm Petrindo Jaya Kreasi.

    Concealed Share Allocations Before Market Debut

    Parties affiliated with the controlling shareholders inside Barito Renewables and Petrindo hid their connections to secure large tranches of stock prior to listing, OJK said. That practice locked away equity from the open market and constricted the available public float.

    Both firms and Dian Swastatika filed disclosures confirming they respected the regulatory orders and pledged compliance with market rules.

    The enforcement strikes directly at corporate governance practices long tolerated across family-controlled conglomerates in Jakarta. For foreign institutions and fund managers backing regional consumer or retail growth, artificially throttled public floats distort price discovery and inflate capital costs across domestic balance sheets. Tight control over traded stock can drive wild valuation runs, but it leaves institutional capital exposed to sudden regulatory crackdowns.

    The immediate risk sits with public liquidity. Concentrated holdings choke regular market turnover, creating liquidity traps where large investment portfolios cannot exit without crashing the underlying stock.

    Global Index Providers Threaten Market Demotion

    The punitive actions follow a sharp warning from Morgan Stanley Capital International, which put Indonesian equities on notice for a possible downgrade from emerging market status to standalone status. The index provider cited unaddressed, coordinated trading practices as the primary catalyst for the review.

    Indonesian President Prabowo Subianto dismissed the threat during a Cabinet address broadcast on the government’s official channel.

    I simply want to tell MSCI: the Indonesian nation fears no one and will never back down. We have the strength, the courage and we are willing to make sacrifices, and we refuse to surrender.

    Index warnings have battered local equities. The benchmark Jakarta Composite Index dropped 38 percent year-to-date, wiping billions off personal fortunes across the country.

    Pangestu, who held the top spot among Indonesian billionaires at the end of 2025 with $39.5 billion in assets, lost nearly 70 percent of his fortune. Coal operator Low Tuck Kwong saw his net worth cut by over half to $10.9 billion, while tobacco and banking magnate Robert Budi Hartono shed 38 percent to sit at $13.3 billion.

    Enforcement Scrutiny Turns to Jakarta Liquidity

    The clampdown represents a structural break from previous OJK actions, which historically favored private warnings or smaller administrative penalties over multi-million-dollar fines against top-tier tycoons. Global index inclusion criteria have forced Indonesian authorities to address long-standing market distortions directly.

    Watch the upcoming MSCI market classification review dates to see if these enforcement penalties satisfy international index standards or if foreign capital outflows trigger further pressure on the Jakarta Composite Index.

  • Lee Biscuits Shuts Malaysia Factory Cutting 300 Jobs

    Lee Biscuits Shuts Malaysia Factory Cutting 300 Jobs

    Lee Biscuits, a 92-year-old brand founded by Singapore’s late tycoon Lee Kong Chian, is ending production and shutting its factory in Johor by end-October, leaving around 300 workers without jobs.

    Suppliers and customers received notification of the halt last month. A senior manager told China Press that warehouse sales held over the last two weeks have sold out all remaining biscuit stocks.

    Customers attempting to buy products directly from the factory are now being redirected to retail outlets instead. The company has announced no future production plans for the biscuit brand, which is also known as Nam Lee.

    Depleted Stock and Empty Sundry Tins

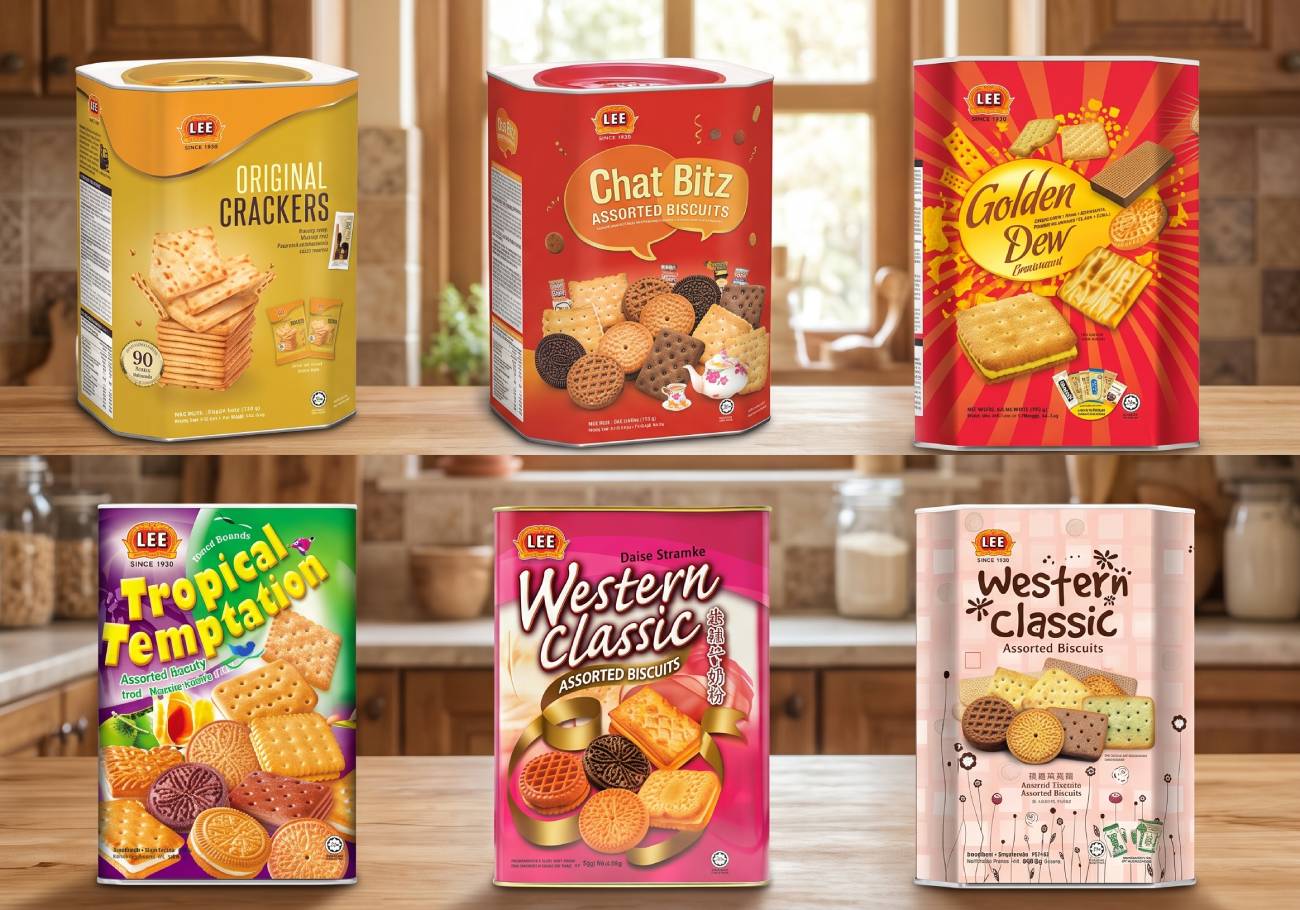
    The manufacturing shutdown removes an established pantry staple from Malaysia’s independent grocers and sundry stores. The brand built its business on bulk tin formats and plastic packs containing soda crackers, Marie biscuits, banana tarts, iced gems, lemon sandwich biscuits, animal crackers, and spirulina whole wheat biscuits.

    Those products filled store displays across both West Malaysia and Singapore for decades, serving as low-cost volume drivers for neighborhood provision shops. With internal warehouse inventory cleared out entirely, distributors face an immediate supply cut once existing shop-floor stock runs dry over the coming weeks.

    Exit from Fast-Moving Consumer Goods

    The shutdown forms part of a broader corporate restructuring by the parent holding group to abandon consumer-facing packaged goods entirely. Capital is shifting back into upstream primary commodities, concentrating operations around rubber processing and palm oil plantations.

    For retailers and shelf planners, the departure opens up shelf space in the value cracker category. Operators relying on traditional sundry distribution face losing a heritage brand that required zero promotional spending to drive volume.

    The Manufacturing Move Across the Causeway

    Tycoon Lee Kong Chian established the biscuit brand in Singapore in 1934 before relocating operations across the border. Lee built the Lee Rubber Company into a regional empire before co-founding OCBC Bank through a three-way merger in 1932.

    Manufacturing ran inside Singapore for over two decades until management shifted the lines to Johor Bahru in 1955 to tap cheaper agricultural raw materials and processing facilities. Operations relocated again within Johor to the current factory site in 2005, where lines ran continuously until this month’s wind-down.

    Sequential Plant Closures in Johor

    The factory shuttering follows an identical retreat from the packaged food sector. The group permanently closed its Lee Pineapple canning facility in Skudai, Johor, in 2023, ending decades of fruit processing to focus resources on upstream estate acreage.

    Retail buyers must now run down their final cases of biscuits before factory gates close permanently by end-October.

  • Diwali Leisure Hotel Bookings Jump 135% on Cleartrip

    Diwali Leisure Hotel Bookings Jump 135% on Cleartrip

    Diwali leisure hotel bookings rose 135% ahead of the festival this season, driven by strong growth in offbeat domestic and overseas getaways, according to data from online travel platform Cleartrip.

    Figures from the company’s PeekABoo travel trends tracker revealed that flight bookings by travellers aged 15-24 surged 60% ahead of Diwali, compared to a 6% increase among those aged 25-34, while bus bookings rose 80%.

    Women’s share of bookings grew 44% over the same festive period, with Cleartrip noting that travel and hotel demand is decentralising as Indian consumers swap traditional metro holidays for regional hubs and non-conventional destinations abroad.

    Budget Accommodations Outpace Luxury Chains

    Budget stays took the biggest share of lodging demand, logging a 201 percent surge in bookings over the festive window. Luxury properties expanded 162 percent, while mid-range accommodation grew 148 percent and premium operators added 114 percent. The widespread distribution of room nights reveals spending broad-based across income tiers rather than concentrated in upper-scale resorts.

    Regional Indian hubs posted the sharpest hotel gains. Udaipur bookings expanded 316 percent, while Bangalore jumped 189 percent and Jaipur climbed 174 percent. Earlier festive benchmarks showed leisure stays had risen 66 percent during the preceding Navratri period, confirming an accelerating volume curve as Diwali approached.

    Secondary Hubs Capture Air Traffic

    Flight volumes to secondary domestic towns outpaced primary transit corridors. Bookings to Agatti advanced 130 percent, followed by Gaya at 98 percent and Dimapur at 80 percent. Additional regional airports logged steady gains: Udaipur grew 59 percent, Dibrugarh 37 percent, Gorakhpur 34 percent, Jabalpur 29 percent, Imphal 24 percent and Dehradun 9 percent.

    Bus transit absorbed the bulk of traditional holiday homecomings rather than leisure trips. Reservations increased 80 percent for journeys into Delhi, 76 percent for Pune, 68 percent for Nagpur, 63 percent for Chennai and 57 percent for Mumbai. The contrast highlights clear market segmentation between migrant commuter travel and discretionary holiday departures.

    International Routes Pivot Eastward

    Outbound flight reservations favoured non-traditional East Asian and European gateways. Taipei recorded the largest percentage increase among overseas stops at 146 percent. Cebu followed at 117 percent, Dublin at 110 percent, Phu Quoc at 106 percent and Osaka at 74 percent.

    Hotel groups and budget airlines positioned along these routes capture direct yield from this shifting holiday calendar. By contrast, conventional holiday destinations across Western Europe and standard regional metros face higher customer acquisition costs as younger Indian consumers seek secondary locations with lower visa barriers and competitive room rates.

    Decentralised Spending Alters Seasonal Demand

    The concentration of travel demand among travellers under 25 alters how hospitality operators must allocate inventory during peak quarters. Hotel operators in tier 2 and tier 3 cities previously relied on wedding groups and corporate stops during the fourth quarter. The entrance of young leisure travellers now forces inventory pricing upward during periods historically dominated by deep local discounting.

    For retailers and food operators in regional airport concourses, higher passenger throughput in hubs like Dimapur, Gaya and Agatti translates into sustained food and beverage spending. The primary risk rests with operators over-indexing on luxury supply: capacity additions must align with the rapid expansion of budget and mid-tier accommodations that dominate young consumer volume.

    Earlier quarters showed festive consumption heavily weighted toward durable goods, electronics and jewellery purchases within home cities. Cleartrip booking metrics point to an accelerating shift where disposable holiday budgets transfer directly into experiential travel platforms and short-haul international flights.

    Air carriers and regional hospitality chains now track outbound seat load factors heading into the winter holiday run to gauge whether high offbeat booking rates persist once festive holiday leaves expire.

  • Bangladesh Plans Rail Shift to Cut Export Logistics Costs

    Bangladesh Plans Rail Shift to Cut Export Logistics Costs

    Bangladesh Railway plans to overhaul its freight operations to lift rail cargo market share from barely 3 per cent to 20 per cent, targeting direct track connections into industrial supply chains.

    The shift aims to reroute bulk consumer freight and apparel exports away from congested national highways into dedicated rail corridors linking Chattogram Port with Dhaka manufacturing hubs.

    Under the Logistics Policy 2025, transport planners want rail to carry a fifth of all commercial freight across the country. To map that buildout, state operators launched the Tk 930 million Green Railway Transport Project Preparation Facility Project, backed by World Bank financing. The study evaluates track lines running from Faujdarhat to the Chattogram Goods Port Yard, alongside future connections into the planned Bay Terminal and the Mirsharai Economic Zone.

    Overhauling Chattogram Port Rail Access

    Chattogram Port handles roughly 90 per cent of Bangladesh’s international merchandise trade, yet rail links across its terminal footprint remain uneven. Older installations including the General Cargo Berth and Chittagong Container Terminal have direct tracks, while newer sites like the Patenga Container Terminal and New Mooring Container Terminal lack equivalent integration.

    That disconnect leaves cargo trains idling while diesel trucks haul containerised freight across jammed access roads. Track gauge fragmentation complicates the network further. Large segments of the eastern railway run on narrow metre-gauge tracks, requiring costly transshipment before rolling stock can connect with broad-gauge lines servicing northern and western trade lanes.

    The feasibility project assesses the rolling stock and yard hardware required to eliminate those delays. Planners are auditing requirements for dedicated freight locomotives, container wagons, shunting yards and loading tracks, alongside modernised maintenance depots in Chattogram.

    Building Inland Terminals Near Dhaka

    Upstream logistics hinges on getting containers quickly into garment manufacturing belts around the capital. The proposed Dhirasram Inland Container Depot in Gazipur serves as the primary inland node designed to clear maritime boxes away from maritime quays.

    Shippers running supply chains between Dhaka and coastal docks currently face unpredictable transit schedules. Road transport delivers flexibility on local spurs, but highway bottlenecks add substantial inventory holding costs for consumer brands, textile mills and bulk distributors. Shifting cargo to scheduled freight trains cuts fuel burn while lowering per-ton haulage expenses on longer runs.

    Railway freight targets extend beyond export apparel boxes. State authorities want long-term freight agreements covering petroleum products, fertiliser, grain imports and construction materials, securing reliable baseline volume through predictable tariff contracts.

    Logistics Realities for Regional Shippers

    For factory operators, retail importers and cargo forwarders, rail is viable only if end-to-end transit times beat road haulage. Shifting cargo off roads requires modern handling machinery, quick digital customs clearance and dependable departure times at inland dry ports.

    Commercial transport planners argue that engineering projects must incorporate freight forwarders and port operators before track laying begins. Without matching first-mile handling and competitive terminal fees, inland container depots risk operating below capacity while trucks continue to command container flows.

    Regional trade corridors present additional operational capacity. Bangladesh Railway forms part of the Trans-Asian Railway framework, offering rail freight routes into India, Nepal and Bhutan. Unlocking those border routes requires harmonised customs systems and unified track standards to eliminate cross-border shunting delays.

    Technical evaluations for the World Bank funded port link project are expected to complete their studies by the end of 2027.

  • BRAC Bank to Issue Tk 1,000 Crore Green Bond

    BRAC Bank to Issue Tk 1,000 Crore Green Bond

    BRAC Bank announced at a press conference in Dhaka today that it will issue a Tk 1,000 crore green bond to channel long-term debt into industrial energy-efficiency and renewable projects.

    The three-year debt instrument carries a face value of Tk 10 lakh per unit and targets a yield of 7.5 percent, priced at roughly Tk 8.05 lakh at issuance under annual compounding.

    Led by Managing Director and CEO Tareq Refat Ullah Khan, the private lender is launching the first debt offering in Bangladesh aligned with the central bank’s green bond policy.

    Structure of the Zero-Coupon Paper

    The issue will be senior, unsecured, non-convertible, fully redeemable and zero-coupon. Rather than disbursing periodic interest, the bank will sell the paper at a discount and redeem it at par upon maturity.

    Corporate institutions, individual investors, and qualifying corporate provident and gratuity funds can subscribe to the tranche. The paper adheres to Bangladesh Bank’s green bond financing guidelines alongside the International Capital Market Association’s Green Bond Principles, backed by a second-party opinion from S&P Global Ratings.

    Proceeds will target factory energy retrofits, rooftop solar arrays, and certified green commercial properties. The lender expects the deployment to align with United Nations Sustainable Development Goals covering clean energy, industry innovation, sustainable cities, and climate action.

    Factory Energy Demands Drive Tenor Mismatch

    Export-oriented manufacturing plants and textile suppliers across Bangladesh face steep domestic power tariffs alongside buyer pressure to decarbonise supply chains. Factory owners frequently seek multi-year capital expenditure loans to replace aging machinery with automated, low-emission lines.

    Commercial banks usually finance those long-term outlays with short-term customer deposits, creating chronic liquidity strains on balance sheets. Locking in three-year fixed capital through non-convertible debt gives the lender a matched pool of cash, though the three-year duration remains relatively short for heavy industrial upgrades.

    This green bond marks an important milestone in BRAC Bank’s sustainable finance journey and represents a meaningful step towards deepening Bangladesh’s capital market, said Tareq Refat Ullah Khan, managing director and chief executive officer of BRAC Bank.

    The zero-coupon structure provides a distinct advantage through domestic tax exemptions supported by the Bangladesh Securities and Exchange Commission. Because taxable income from standard coupon payouts is avoided, institutions holding the debt can preserve effective yields in a high-inflation environment.

    Shallow Corporate Debt Market Faces Test

    Domestic capital markets in Bangladesh remain overwhelmingly concentrated in government treasury bills, leaving private corporate paper thin and illiquid. Most local companies rely on direct bilateral bank loans rather than secondary debt markets to fund operational expansions.

    If institutional pension managers clear the Tk 1,000 crore book cleanly, other commercial lenders will likely package similar trade-finance and manufacturing loans into fixed-income paper. If orders fall short, mid-tier lenders will find themselves locked out of local capital markets and forced back into competitive deposit gathering.

    Lender Expands Sustainable Portfolio

    Sustainable finance currently makes up more than 60 percent of BRAC Bank’s total lending book. The private lender previously issued a dedicated social bond to fund rural micro-enterprises and small suppliers.

    The bank has secured a spot among the central bank’s top-rated sustainable financial institutions for five straight years and holds the leading position among local lenders in Bloomberg’s ESG Rating. Annual audits will track the disbursement of funds to verify that borrowers apply capital strictly to certified sustainable projects.

    Distribution desks are now taking formal indications of interest ahead of official allotment dates, with secondary trading liquidity serving as the real test of institutional appetite.