Author: Mei Ling Tan

  • Mycofeast Buys New Zealand Dairy Protein Startup Daisy Lab

    Mycofeast Buys New Zealand Dairy Protein Startup Daisy Lab

    British biotechnology firm Mycofeast acquired New Zealand dairy protein startup Daisy Lab for an undisclosed sum in October 2026. The buyout secures Daisy Lab’s precision fermentation platform.

    The deal transfers Daisy Lab’s Auckland operations and patent pipeline to the UK group. Daisy Lab’s scientific team will stay intact.

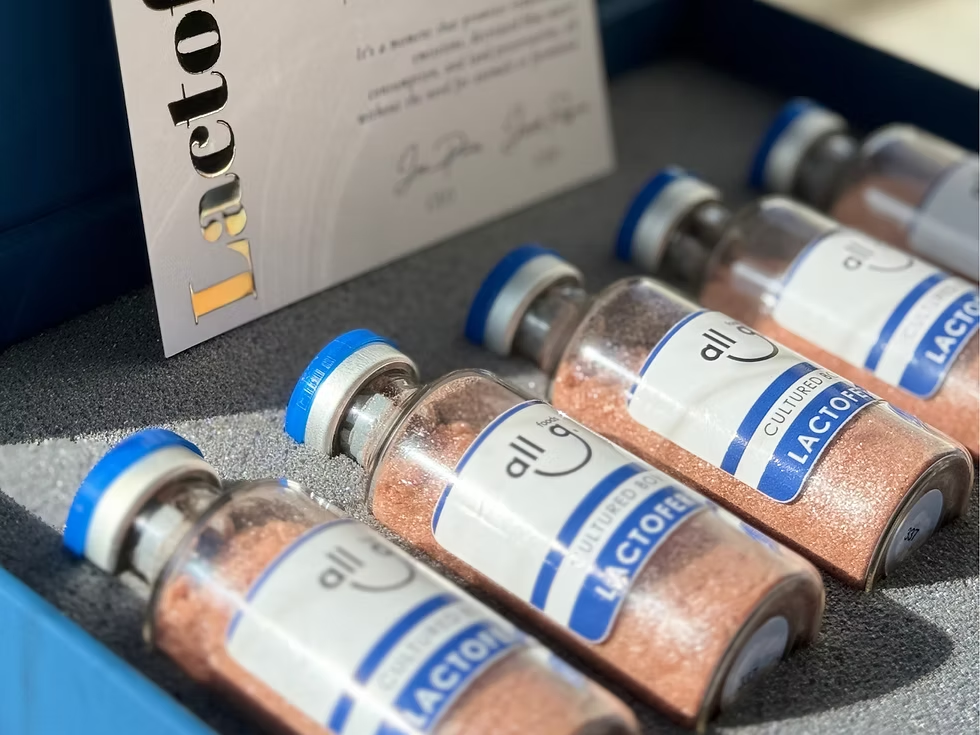
    Daisy Lab uses genetically engineered yeast to produce animal-free dairy proteins, including whey, casein, beta-lactoglobulin and lactoferrin. The company estimates its system cuts greenhouse gas emissions by up to 97 per cent compared with conventional dairy farming. Its most advanced project centres on high-yielding bovine and human lactoferrin. The iron-binding glycoprotein is used in infant nutrition, immune supplements and pharmaceuticals.

    Integration without cuts

    All laboratory staff and founders will keep their Auckland positions. Co-founders Irina Miller, Nikki Freed and Emily McIsaac will take broader operational roles across the Mycofeast organisation.

    Development work from the New Zealand team will link with Evolutia Bio, Mycofeast’s research arm in California. The team will also draw on the parent firm’s industrial processing plants. Daisy Lab had initially engaged Mycofeast as an ingredient customer and commercial partner before talks became a full buyout.

    “There are no layoffs associated with the acquisition. Mycofeast wanted both the technology and people,” Daisy Lab co-founder and CEO Irina Miller said.

    Fermentation economics in focus

    Extracting traditional lactoferrin requires thousands of litres of bovine milk to yield a single kilogram of purified protein. That scarcity keeps market prices between $600 and $2,000 per kilogram. It is one of the most expensive dairy fractions on global commodity markets.

    Precision fermentation bypasses cows entirely by brewing identical proteins inside stainless-steel bioreactors. For ingredient buyers across Asia, synthetic biology offers stable pricing. It also removes exposure to seasonal milk collection swings, farm runoff rules and herd disease risks.

    Capital pressure across alternative protein

    Australasian food-tech startups are turning to offshore trade sales over standalone venture capital rounds. Higher interest rates and tighter funding over the past two years made building private pilot and commercial processing facilities prohibitively expensive for early-stage laboratories.

    Selling to an established biotech operator gives Daisy Lab immediate industrial hardware without raising dilutive scale-up equity. The deal also hands Mycofeast a research base in New Zealand. That puts the British group inside a major agricultural exporter currently overhauling its biotech regulations.

    Next steps for scale

    Daisy Lab incorporated in Auckland in 2021 to engineer alternative proteins for New Zealand’s dairy-heavy economy. The startup focused on high-margin proteins rather than commodity milk powder. It established high-titre yeast strains to prove commercial viability before pursuing international manufacturing partners.

    Teams across both companies are now preparing lactoferrin samples for regulatory clearance dossiers and commercial customer trials across North America and the Asia-Pacific region.
  • Semirara Slashes Coal Target to 12 Million Tons as Pit Floods

    Semirara Slashes Coal Target to 12 Million Tons as Pit Floods

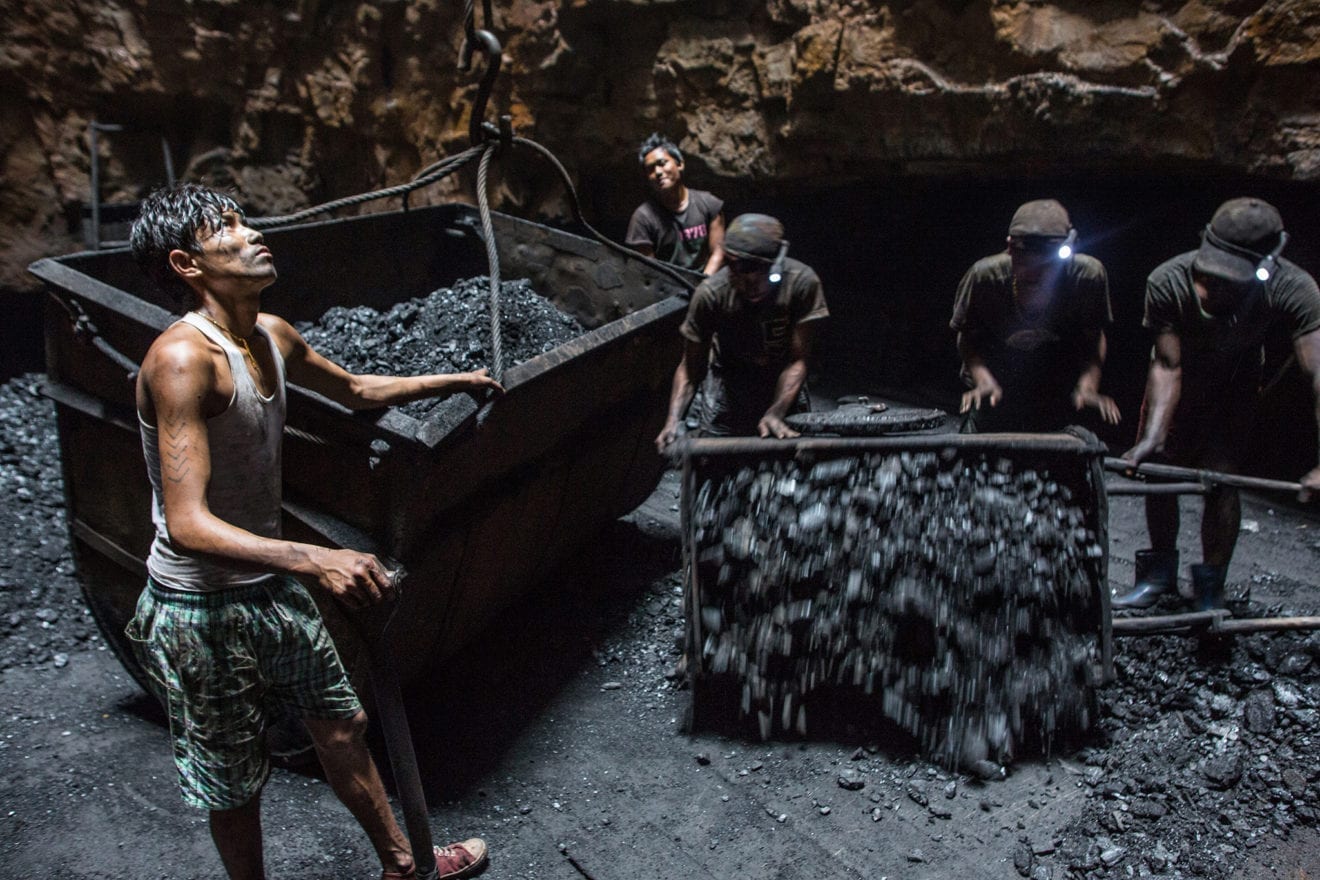
    Semirara Mining and Power Corp. Slashed its 2026 coal output target to 12 million metric tons after uncontrollable seawater flooded its core Acacia pit in the Philippines. Stripping operations are halted indefinitely. The revised target is a drop of nearly 40 percent from the record 19.9 million tons produced in 2025.

    Seawater is surging into the active pit at roughly 30,000 cubic meters an hour. That far exceeds on-site pumping capacity. The structural failure accelerated on September 20 when material from North Block 1 Dam 2 collapsed, sending surface runoff straight into the mining area.

    Crews are attempting to erect another cut-off wall. Meanwhile, the operational breakdown forced SMPC to lay off 1,458 mine-site workers. The company cut an initial tranche of 462 staff before letting go an additional 996 personnel.

    Contract Expiry and Asset Disputes

    Timing could not be worse for the operator or the power grid. Coal Operating Contract No. 5 expires on July 14, 2027. That leaves the Department of Energy scrambling to auction operating rights to the highest financial bidder.

    Energy officials terminated a previous bidding round in September following legal disputes, engineering problems, and operator objections. They now plan to restart the auction between November and December. That gives the winning contractor barely seven months to take over before the current license lapses.

    A legal fight is also playing out in court over more than 55 billion pesos in infrastructure and machinery on Semirara Island. SMPC filed a petition for declaratory relief after the energy department demanded a full inventory of the operator’s property and plant to share with rival bidders.

    State Revenue Versus Engineering Capacity

    Regulators argue that equipment with costs recovered under the operating contract can vest in state hands and pass to the next operator. SMPC counters that cost recovery serves only as reimbursement under Presidential Decree 972. Title and removal rights remain strictly with the company.

    Higher revenue shares and consumer concessions remain the government’s priority, grounded in the state’s ultimate ownership of mineral resources. SMPC notes it contributed 43.4 billion pesos in government share alongside 3.7 billion pesos in taxes between 2021 and the middle of 2026.

    Commercial power users and industrial operators face the threat of electricity cost inflation. Acacia was projected to deliver the bulk of domestic coal supply in 2027. Any prolonged disruption will force power producers to import expensive replacement thermal coal from Indonesia and Australia.

    Spillover to the Local Island Economy

    Fallout has already spread across Semirara Island as payroll cuts hit retail and service trade. Small island businesses report falling daily revenue and customer defaults as families lose their primary income.

    Island social programs face immediate risk as well. SMPC has historically funded about 90 million pesos annually for free tuition at the Divine Word School of Semirara Island. More than 1,500 students depend on that mine-supported schooling.

    The Department of Energy has not issued bid bulletins, prequalification screens, or a model contract clarifying minimum technical requirements for the flooded pit. Restarting the bidding process in late 2026 will test whether the state can secure an operator capable of draining the Acacia pit before the July 2027 handover deadline.

  • Malaysia Faces Calls to Raise Retirement Age to 65 as Pension Deficits Grow

    Malaysia Faces Calls to Raise Retirement Age to 65 as Pension Deficits Grow

    Pension advisers and economists in Kuala Lumpur are pushing the government to raise Malaysia’s mandatory retirement age from 60 to 65 through phased adjustments. The current statutory threshold leaves millions of workers exiting the formal labor force with inadequate savings to cover longer lifespans.

    Official data from the Department of Statistics Malaysia released on September 30 shows life expectancy for a newborn in 2026 reached 75.5 years, while residents reaching age 60 are projected to live an additional 20.2 years to 80.2. A retirement age set at 60 requires workers to fund more than two decades of living expenses on savings accumulated over short careers.

    The Proposed Timeline for Phased Retirement

    William Price, chief executive of consultancy D3P Global Pension Consulting, presented a transition framework at the Employees Provident Fund International Social Wellbeing Conference 2026 in Kuala Lumpur. Under his proposal, authorities would add three months of working life for every calendar year, reaching a statutory retirement age of 65 by 2040 without forcing abrupt extensions on staff near departure.

    A worker aged 40 today would retire at 65 under the schedule, while a 50-year-old would work until 62 and a half. Employees aged 59 would take on an additional three months, retiring at 60 years and three months. Price suggested exemptions for manual laborers and low-income staff who entered the formal workforce at age 16, allowing early exit after completing 40 to 45 contribution years.

    Rajen Devadason, a licensed financial planner speaking at the same conference, proposed an accelerated track to lift the threshold by one year every two years. His plan targets a retirement age of 65 by 2035 and 70 by 2050 to keep pace with demographic shifts.

    Depleted Balances at the State Pension Fund

    The push to extend working careers coincides with severe savings shortfalls inside the Employees Provident Fund, which covers more than 18 million members. Figures submitted to parliament reveal that as of May 31, only 38.3 percent of active formal-sector members aged 18 to 60 had accumulated the basic savings benchmark of RM390,000. That baseline is designed to yield a monthly drawdown of RM1,625 over a 20-year retirement.

    Former EPF chief executive Shahril Ridza Ridzuan noted at the conference that low baseline wages prevent households from building assets even when statutory contribution rates remain elevated. Beyond the basic benchmark, the EPF defines adequate savings at RM650,000 and enhanced savings at RM1.3 million, levels out of reach for the vast majority of private sector staff.

    Retaining older staff alters payroll dynamics across retail and service chains that rely on entry-level wages. Companies facing persistent labor shortages in store operations, logistics, and customer support stand to gain experienced personnel, provided contracts offer flexible scheduling such as three-day work weeks.

    Operating Adjustments for Employers and Retailers

    Consumer spending patterns will shift as older cohorts continue earning regular paychecks into their mid-sixties rather than cutting household budgets at 60. Keeping older workers economically active protects discretionary demand across urban retail centers, dining, and healthcare services that depend on steady domestic consumption.

    The structural risk sits in commercial staffing models and medical insurance costs. Retailers and hospitality groups must restructure compensation from seniority-based pay scales to productivity metrics, ensuring higher minimum ages do not compress hiring budgets for younger entry-level workers.

    Previous statutory changes in Malaysia established the Minimum Retirement Age Act in 2012, which lifted the private-sector retirement baseline from 55 to 60 when it took effect in 2013. The public sector matched that 60-year ceiling, but demographic pressures have intensified as Malaysia transitions toward an aged society status projected by the World Bank.

    Policymakers must now weigh draft amendments to employment statutes against public resistance to delayed access to pension funds. The primary metric to track is whether the human resources ministry tables formal legislation to decouple EPF withdrawal windows from mandatory retirement milestones ahead of the next parliamentary sitting.

  • GE Aerospace to Double India Supply Chain Spending to $400 Million by 2030

    GE Aerospace to Double India Supply Chain Spending to $400 Million by 2030

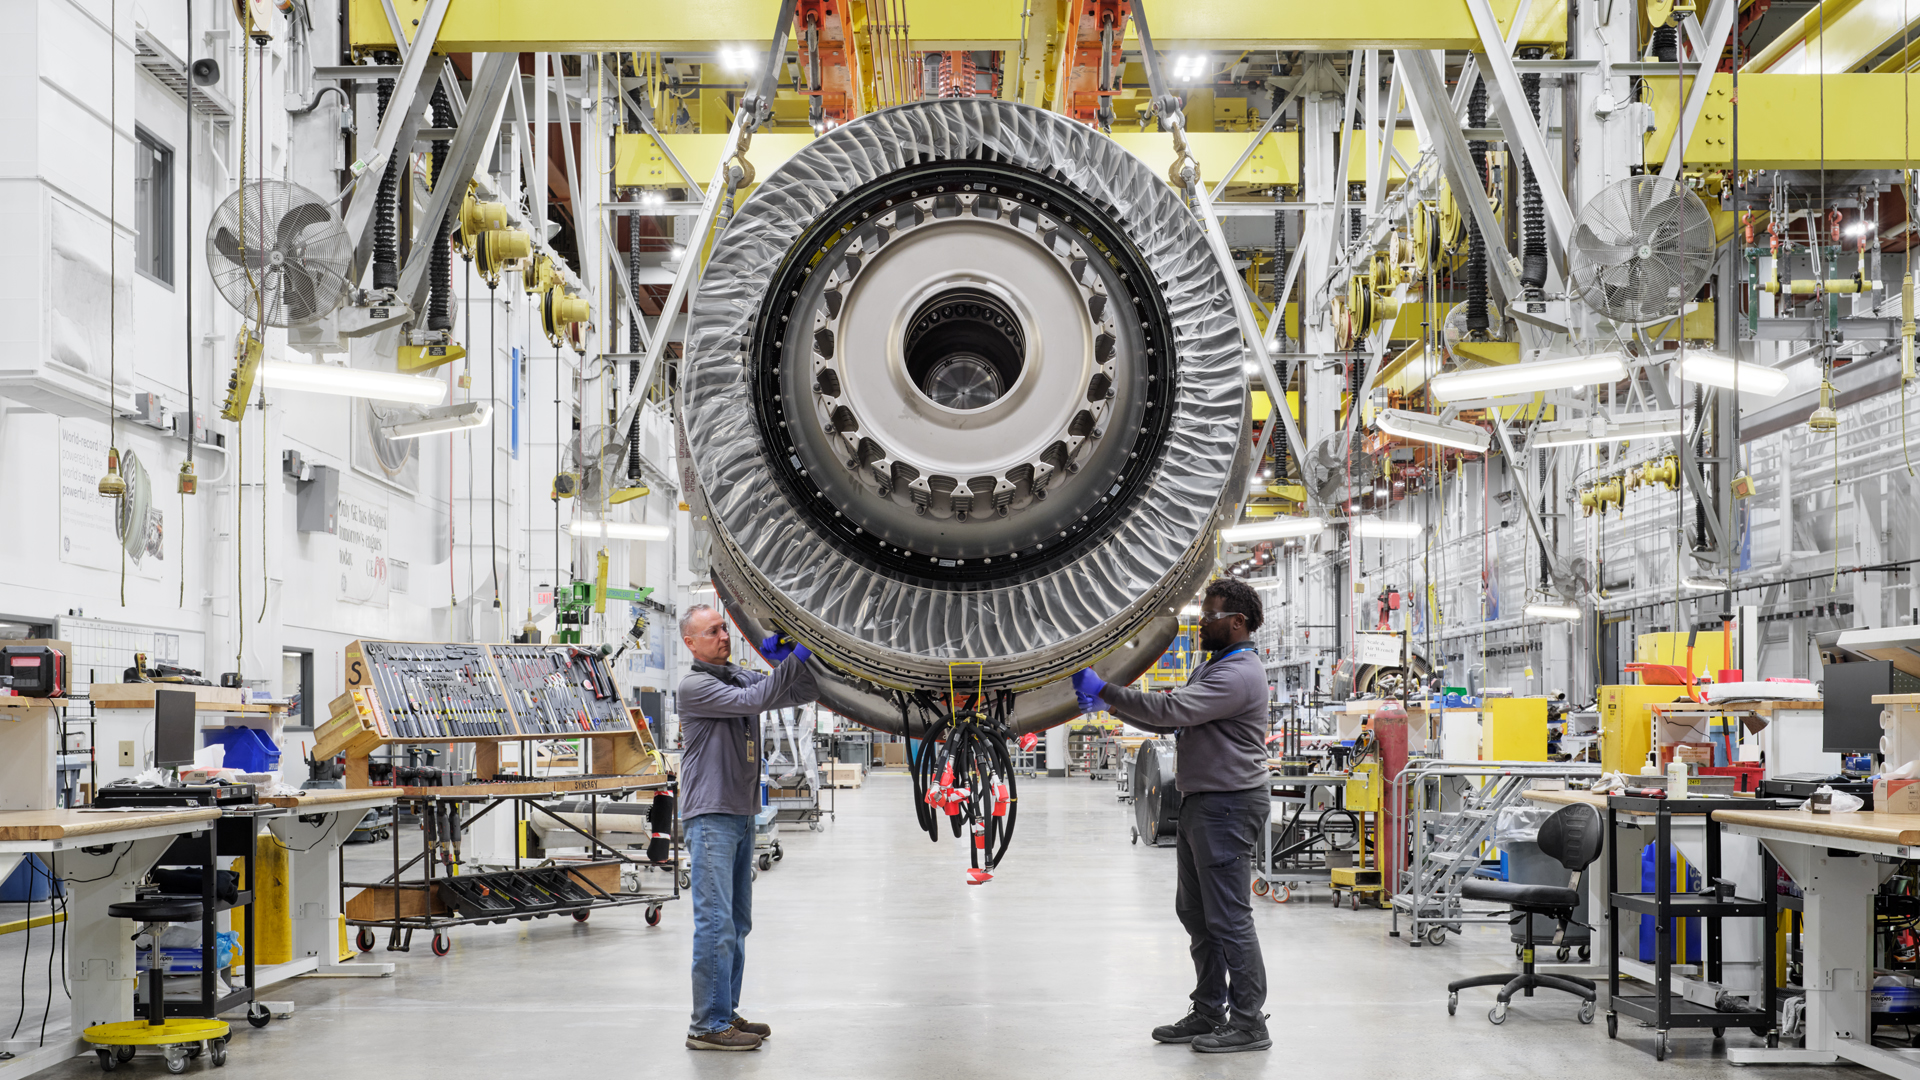
    GE Aerospace will increase annual supply chain spending in India to $400 million by 2030. The target doubles its current procurement footprint in the country.

    Annual spending across Indian suppliers reached $200 million in 2025. Surging fleet orders from domestic airlines drove that total.

    Procurement will cover new engine components alongside higher volumes for existing parts. Sourcing runs through 17 global tier-one suppliers in India, including Tata Group, Mahindra, Hindustan Aeronautics Limited, and Godrej. More than 2,000 domestic tier suppliers support the network.

    Expanding Component Manufacturing in Pune

    Manufacturing centers on the multi-modal plant in Pune. It produces engine components for export and domestic integration. Cumulative capital spending at the site stands at $255 million, feeding global assembly lines for commercial platforms.

    Engineering and software teams operate out of the Bengaluru Technology Centre, established in 2000. The site holds over 1,000 patents. It developed the ABM.ai predictive maintenance platform and the Blade Inspection Tool used across GEnx, CFM LEAP, and GE9X programs. The digital unit also serves as a global capability centre for worldwide engine maintenance, sales, and supply chain tracking.

    Backing Aircraft Fleet Expansion

    Domestic passenger journeys reached 340 million in fiscal year 2026 and are projected to reach 1.1 billion by 2040. Indian carriers and armed services currently operate more than 1,400 commercial engines from GE and its partners, alongside over 200 defence engines.

    Local airlines hold firm orders for over 1,700 aircraft scheduled for delivery over the next decade. More than 3,200 engines from GE Aerospace and its joint ventures will power those fleets. Local component production helps the manufacturer maintain delivery schedules against global supply chain bottlenecks.

    Joint Ventures and Maintenance Capacity

    Regional carriers need local maintenance facilities to avoid turnaround delays abroad. Sourcing parts closer to flight hubs cuts transit time for heavy engine overhauls.

    IndiGo signed a memorandum of understanding in July 2026 with CFM International, GE’s 50-50 joint venture with Safran Aircraft Engines. The deal covers more than 1,000 LEAP-1A engines for 510 Airbus A320neo family jets. It also provides technical support to build IndiGo’s dedicated engine maintenance, repair, and overhaul facility.

    Scaling Local Supplier Integration

    Precision manufacturing in India has moved beyond basic aerostructures into complex rotating parts and turbine components over the past decade. Raising procurement from $200 million to $400 million tests whether local suppliers can maintain aerospace quality standards at higher output rates.

    Next, the supplier development program will qualify new part numbers at Pune and integrate higher production runs across the 17 global Indian supplier partners as deliveries ramp up toward 2030.

  • Gaz Vietnam Enters Cambodia with Commercial Fleet Lineup at Cam Auto 2026

    Gaz Vietnam Enters Cambodia with Commercial Fleet Lineup at Cam Auto 2026

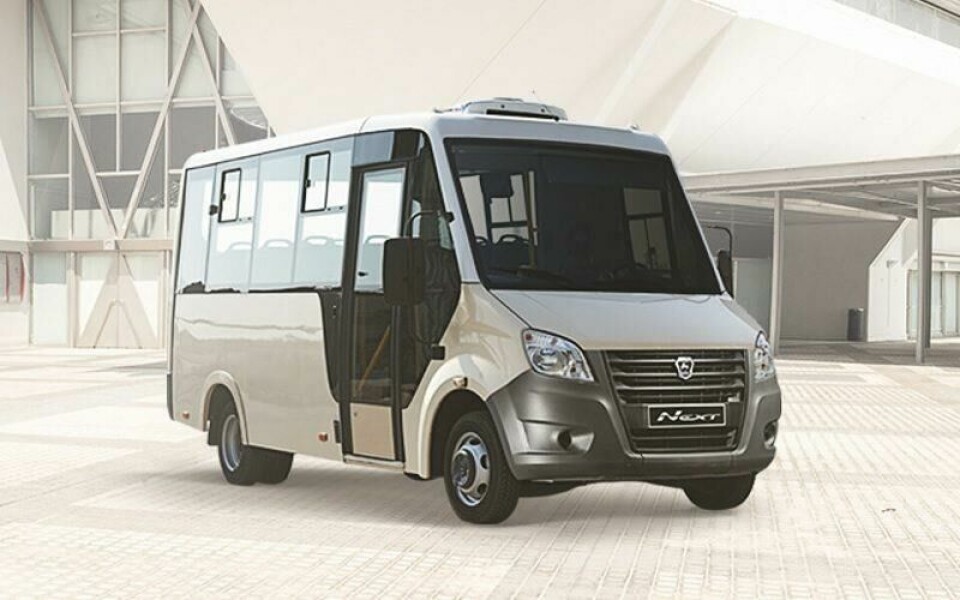
    Gaz Vietnam debuted five commercial and municipal vehicles at the Cam Auto 2026 exhibition in Phnom Penh. The display starts an export push into Cambodia, backed by plans for local dealerships and parts distribution.

    Assembled at its plant in Da Nang, the Russian-designed lineup includes light buses, work trucks and an emergency vehicle. Gaz pitched the platforms directly to Cambodian fleet buyers and transport operators.

    Five platforms pitched to transport and public operators

    Five models on display span the 3.5 to 4.9-ton gross vehicle weight bracket. For public transit routes, the lineup features the Gazelle City. That 26-passenger low-floor bus carries a wheelchair ramp, wide boarding doors, all-wheel disc brakes and an adjustable rear pneumatic suspension. Beside it sits the 20-seat Gazelle Citiline. It targets shorter intercity corridors with a 1.9-meter interior standing height on a traditional body-on-frame chassis.

    For shuttle operators, the display included the 16-seat Gazelle NN. The van runs a 150-horsepower Euro 5 diesel engine paired with a six-speed manual gearbox. Electronic stability control, traction control, brake assist and hill-start assist come standard. Utility crews saw the six-seat Gazelle Double Cab cargo truck, backed by an eight-year anti-perforation warranty on its galvanized cabin structure. Gaz also exhibited a Sobol NN ambulance configured with medical equipment racks and dedicated power feeds.

    Dealership rollout and regional distribution strategy

    Selling across the border requires reliable service. Buyers demand uptime guarantees. Gaz Vietnam plans to establish an authorized dealership network in Cambodia to handle vehicle servicing, technical maintenance and warranty work. A dedicated spare parts supply chain will support the network to limit repair turnaround times for fleet owners.

    Through Cam Auto 2026, Gaz Vietnam aims to offer transport solutions that combine proven durability, operating efficiency, and modern technology.

    These platforms compete directly against established Japanese and Chinese builders that dominate Indochina’s logistics and transport sectors. Japanese brands command fleet loyalty, but rising replacement costs push budget operators toward alternatives. Chinese commercial vans offer low upfront pricing. Gaz Vietnam bets its corrosion-treated steel framing, mechanical layouts and factory warranty packages will appeal to private transport companies and municipal fleets seeking predictable running costs.

    the competitive market in Indochina logistics

    Regional trade integration aids cross-border vehicle sales within ASEAN, but success in Cambodia depends on after-sales execution. Small logistics operators and provincial transport cooperatives cannot afford days of downtime waiting for parts from Vietnam. The manufacturer combines central parts warehousing with local dealer partnerships. This approach aims to counter gray-market importers who sell vehicles without technical backing.

    Government purchasing offers another sales channel. The Phnom Penh exhibition drew official interest from Cambodian government figures, including General Yont Min, Secretary of State at Cambodia’s Ministry of National Defense, and Anatoly Borovik, Russia’s Ambassador to Cambodia. Securing institutional orders for emergency medical transport and municipal utility work provides immediate volume while private dealer sales ramp up.

    Da Nang manufacturing base powers cross-border sales

    Gaz Vietnam opened its Da Nang manufacturing plant in 2019 to build light commercial vehicles, passenger vans and medium-duty trucks for Southeast Asian markets. The Vietnamese operation maintains parts distribution hubs in Hanoi, Da Nang and Ho Chi Minh City. These facilities support an authorized service network spanning 14 provinces.

    This domestic footprint provides the base for cross-border supply. Sourcing vehicles from central Vietnam rather than Russia cuts shipping lead times for Indochina buyers. It also simplifies parts interchangeability between the two countries.

    Next, the automaker must appoint its first certified Cambodian retail partners and confirm delivery timelines for commercial fleet orders booked during the Phnom Penh trade fair.

  • PopBox Introduces Caramel Crunch Microwave Popcorn in Coles

    PopBox Introduces Caramel Crunch Microwave Popcorn in Coles

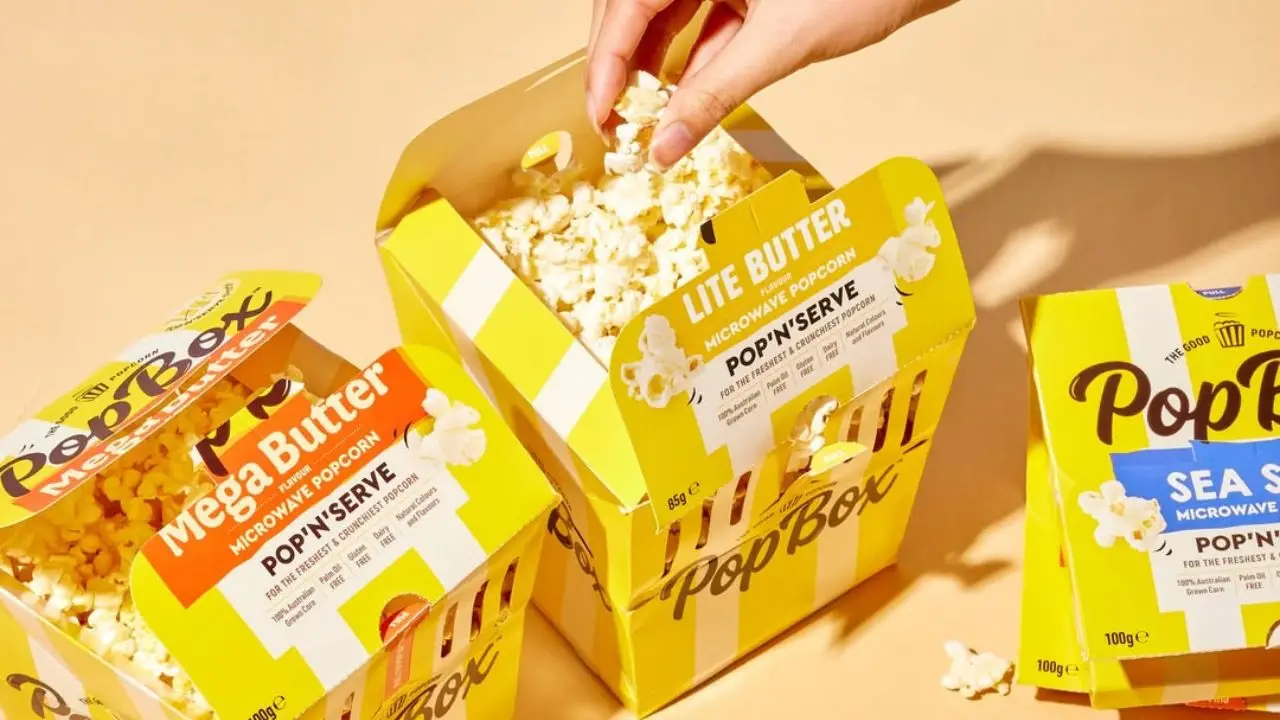
    PopBox secured nationwide distribution for its Caramel Crunch microwave popcorn in Coles supermarkets across Australia in October 2026.

    The rollout broadens the brand’s retail presence, adding to its existing availability at Woolworths.

    Ranging and Formulation Details

    Caramel Crunch comes in a pop-and-serve box designed to cook in the microwave without separate tableware. PopBox sources its corn domestically from Australian growers. The formulation contains no palm oil, dairy, or gluten.

    Production specifications also exclude genetically modified ingredients, making the SKU vegan-friendly. Both the outer carton and inner pack elements use recyclable materials.

    Supermarket Snacking Competition

    Dual distribution across Coles and Woolworths gives emerging snack brands the footprint needed to challenge legacy competitors. In the microwave popcorn aisle, volume has traditionally centered on butter and salt profiles. Sweet and specialty flavors have largely remained in pre-popped ready-to-eat bags.

    PopBox is targeting impulse snackers looking for warm options without artificial additives. Retaining shelf space will depend on stock turn rates against multinational confectionery and snack suppliers that dominate supermarket end-caps.

    Dual-Chain Distribution Footprint

    This Coles rollout follows the brand’s initial traction within Woolworths outlets nationwide. Independent snack manufacturers often launch in one major banner to prove commercial viability before pitching ranging reviews at competing grocers.

    With nationwide distribution now live in Coles aisles, the next test is whether PopBox can maintain full-price sell-through or will rely heavily on promotional discounting cycles during upcoming quarterly category reviews.

  • Pernod Ricard Sales Dip 0.9% as India Boom Cushions Steep China Fall

    Pernod Ricard Sales Dip 0.9% as India Boom Cushions Steep China Fall

    Pernod Ricard posted a 0.9 per cent organic net sales decline to €2.234 billion for its fiscal first quarter. The result beat market forecasts of a 1.7 per cent drop.

    Sales in India jumped 19 per cent, offsetting double-digit slumps across mainland China and the United States. Group net sales reached the equivalent of $2.5 billion in the three months to September 30. Paris-listed shares rose 3 per cent.

    India drives volume as listing nears

    India delivered the strongest performance across the group’s global network, serving as its primary growth engine for premium spirits in South Asia. Demand for Absolut vodka and Martell cognac remained resilient across Indian retail outlets and hospitality venues. Distributors in western markets, by contrast, continued to trim excess inventory.

    Preparatory work is underway for a potential initial public offering of the Indian business. Execution remains subject to board approval and broader market conditions. Finance chief Mauve Croizat noted the listing process will take several months to complete once cleared.

    China consumption shifts behind closed doors

    Revenue in China plunged 25 per cent during the quarter as weak consumer sentiment and distributor destocking took a toll. Wholesalers across tier-one and tier-two cities held back on orders to avoid accumulating slow-moving stock ahead of key promotional windows.

    Croizat told analysts that inventory adjustments in China and the United States will persist throughout the fiscal year. Chinese drinking habits are also shifting toward private gatherings at home. Moving away from nightclubs, banquet halls, and dining out reduced high-margin venue sales for premium cognac.

    Diverging fortunes across regional retail

    Beverage distributors and bar operators in Asia face sharply diverging conditions in India and China. Indian retail channels are expanding rapidly into higher-tier spirits categories, giving brand owners pricing power that has vanished in East Asia. In China, distributors face prolonged margin compression as they discount slow-moving luxury stock to protect working capital.

    Relying on traditional Chinese banqueting channels to sustain luxury valuations carries clear risks. While rival Diageo and regional cognac houses face identical headwinds across East Asia, Pernod Ricard has cushioned the blow through its dominant distribution footprint across the subcontinent. Competing distillers without established Indian bottling networks now risk falling further behind in total regional volume.

    Defending margins in an extended downturn

    Earlier this year, Pernod Ricard made an unsuccessful merger approach to Jack Daniel’s owner Brown-Forman to weather post-pandemic demand weakness. Net sales across the United States fell 10 per cent in the quarter, matching sluggish retail patterns seen across North America over the past eighteen months.

    Management reiterated guidance for broadly stable net sales across the full 2027 fiscal year, relying on strict cost controls to defend organic operating margins. Through 2029, the company expects annual net sales growth to track at the lower end of its 3 to 6 per cent medium-term target range, with investors focused on the board’s formal decision on the timing of the Indian market float.

  • 32,000 Exhibitors Show AI Appliances at Canton Fair

    32,000 Exhibitors Show AI Appliances at Canton Fair

    Chinese manufacturers introduced artificial intelligence-enabled kitchen gear and service robots at the Canton Fair in Guangzhou. The push defends overseas sales against rising factory costs.

    The biannual trade expo drew 32,000 exhibitors and an estimated 310,000 buyers. AI-related shipments generated 38 per cent of China’s total exports in the first half of the year.

    Smart hardware on the trade floor

    Exhibitors used the 70th year of the fair to display consumer appliances designed to automate kitchen tasks. Shaoyang-based Topim Intelligent Manufacturing showed an air fryer that uses an internal camera and image recognition to identify food items. It executes cooking cycles without manual programming. The unit is unreleased, but the company reported early order interest from buyers in the Middle East.

    Commercial coffee equipment supplier Gemilai demonstrated an espresso machine fitted with a touchscreen recipe interface. The system lets cafe staff run precise extraction settings automatically. That replaces manual calibration steps found on traditional European units. Gemilai is distributing compact versions of the format tailored for cafe operators in Southeast Asia.

    Hangzhou robotics firm Rotunbot presented a 185-kilogram spherical security robot designed for facility and police patrols. The hardware drew queues outside the fair’s dedicated service robot pavilion. Organizers first introduced the pavilion in April.

    Margin pressure at the factory gate

    Producers face a widening gap between production expenses and consumer pricing. China’s producer price index climbed 5 per cent year on year in September, driven by higher energy and raw material costs. The consumer price index rose just 0.9 per cent over the same period. That left manufacturers unable to pass wholesale increases to domestic shoppers.

    Export pricing faces equal resistance from international retail buyers. Scale manufacturer Guangdong Winburg Technology kept wholesale prices for bathroom scales at roughly $7.20 per unit despite rising component bills. Price increases risk immediate order losses. Rival domestic suppliers compete for the same international procurement contracts.

    Western trade barriers and regulatory friction

    Adding software, cameras, and connectivity to everyday hardware introduces regulatory hurdles in Western markets. United States regulators have restricted imports of specific Chinese robotics categories. Buyers in Europe face shifting trade policy as European Union officials negotiate to narrow the bloc’s trade deficit with Beijing.

    It seems like AI applications are still in an experimental stage. It’s unclear whether AI will make the coffee taste better.

    Higher-value hardware anchors China’s trade balance. Data from Citi shows AI-related categories, including semiconductors, smartphones, and power equipment, doubled their share of national exports from 20 per cent in 2025 to 38 per cent in the first half of the year.

    The diplomatic calendar ahead

    Premier Li Qiang opened the Guangzhou exhibition by calling on trading partners to lower trade barriers and balance bilateral exchanges. The appeal followed high-level trade discussions in Beijing. There, European Union and Chinese envoys agreed to stabilize commercial ties ahead of a European summit on trade deficits.

    A temporary trade truce agreed between Chinese President Xi Jinping and United States President Donald Trump runs through Jan. 10. The two heads of state are scheduled to hold direct talks in Shenzhen in November. Those discussions will set the immediate operating terms for manufacturers exhibiting through the fair’s close on Nov. 4.

  • Netflix Replaces Content Head Bela Bajaria with Peter Rice Following 1,000 Job Cuts

    Netflix Replaces Content Head Bela Bajaria with Peter Rice Following 1,000 Job Cuts

    Netflix named former Walt Disney television chairman Peter Rice as its chief content officer on Thursday, replacing Bela Bajaria a day after cutting 1,000 jobs.

    The management overhaul follows a six per cent reduction in global headcount, marking the company’s steepest round of layoffs since 2022.

    Rice assumes responsibility for Netflix’s worldwide programming slate on October 26. His remit covers scripted and unscripted television series, feature films, and live broadcasts across all geographic territories. Rice previously ran Walt Disney Television and served as chairman of general entertainment at The Walt Disney Company after earlier leadership roles at 21st Century Fox.

    Executive turnover and restructuring

    Bajaria exits after ten years at the company. She joined Netflix in 2016 following her departure from NBCUniversal, where she ran Universal Television. Netflix co-chief executive Ted Sarandos initially hired her to build an unscripted television slate, alongside licensing deals and co-productions with external studios.

    Her rise through the executive ranks accelerated in 2020 when she became head of global television following the departure of Cindy Holland. Netflix promoted Bajaria to chief content officer in January 2023, placing her in charge of commissioning budgets that produced breakout global titles including Squid Game, Bridgerton, Wednesday, Beef, and Stranger Things. Film projects developed during her leadership included KPop Demon Hunters and Frankenstein.

    The content department restructuring reaches beyond top leadership. Netflix dismissed film vice president Doug Belgrad and film director Sheroum Kim this week as part of the broader staff reduction.

    Content economics and engagement pressure

    Streaming operators across Asia-Pacific face tightening production discipline as subscriber growth slows and returns on commissioned originals decline. Big-budget regional scripted productions carry high upfront risk, forcing platforms to balance expensive local prestige drama with low-cost unscripted formats and live sports broadcasting.

    Platforms such as YouTube and TikTok continue to siphon viewer minutes with user-generated video that costs nothing to produce. That shift leaves subscription video providers carrying heavy production balance sheets at a structural cost disadvantage against ad-supported social video platforms.

    Declining awards and shifting focus

    Prestige recognition for Netflix originals dropped sharply heading into the executive change. The service collected 16 Primetime Emmy Awards in 2026, down from 30 wins in 2025 and well below the record 44 awards it secured in 2021. The tally represents the platform’s smallest Emmy total in ten years.

    Sarandos credited Bajaria with broadening the company’s catalogue into unscripted programming and live events, including multi-year broadcast agreements with the NFL and WWE as well as live specials such as The Roast of Tom Brady.

    “I want to thank Bela for a decade of dedication, innovation, creativity and leadership,” Sarandos said in a statement.

    The schedule ahead

    Rice takes direct operational control of the programming pipeline on October 26 as Netflix finalises its production slate and capital allocation targets for 2027.

  • China Expands Public REIT Framework to Include Hotel Assets

    China Expands Public REIT Framework to Include Hotel Assets

    China is advancing reforms this week to incorporate hotel properties into its domestic public real estate investment trust market. The expansion opens an institutional exit route for hotel owners seeking to shift toward asset-light operational models.

    Regulators in Beijing are broadening the scope of domestic public REITs beyond 3 traditional asset classes: industrial parks, toll roads, and logistics facilities. Commercial hospitality assets can now access exchange-listed equity capital under the expanded framework.

    Opening Listed Capital to Hotel Portfolios

    The pilot program for infrastructure REITs originally restricted listings to municipal utilities, industrial parks, and affordable rental housing. Expanding the eligible asset pool to hospitality properties allows hotel owners to securitize income-generating developments through domestic exchanges.

    To qualify for a public listing, properties must demonstrate stable operating cash flows, clear land ownership rights, and compliant operational histories. Asset managers package selected hotel real estate into closed-end funds sold to institutional and retail investors.

    Shifting Hospitality Owners to Asset-Light Models

    Hospitality groups operating across mainland China have historically carried heavy balance sheets loaded with freehold real estate. Public hotel trusts provide a domestic vehicle to offload physical properties while retaining long-term management contracts.

    For international and domestic hotel operators, the reform creates an avenue to scale footprint without borrowing heavily from state banks. The capital recycled from asset sales goes directly into brand development, technology platforms, and management operations.

    Pricing Risk and Operational Volatility

    Hotel revenues fluctuate with seasonal travel patterns, corporate spending cuts, and tourism demand far more than standard industrial warehouses or rental housing. That volatility directly affects dividend payouts to public unit holders.

    Trust managers face the challenge of structuring lease and operational agreements that absorb cyclical downturns without breaching minimum yield thresholds. Investors will price these instruments against prevailing corporate bond yields and existing consumer infrastructure trusts.

    Broadening Beyond Traditional Infrastructure

    Chinese financial regulators initiated the domestic REIT market to unlock capital tied up in state and private infrastructure projects. Authorities subsequently expanded the program to shopping centers and consumer infrastructure to support domestic consumption.

    Extending the framework to hospitality assets marks the next phase in establishing a comprehensive commercial property trust market in mainland China. Market participants are monitoring the first batch of hotel trust filings submitted to domestic stock exchanges for indicative valuation multiples and target distribution yields.

  • China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    A broader economic slowdown in China has started weighing on LVMH’s core luxury fashion operations across key Asian retail hubs. Weak consumer confidence in the mainland market is curbing discretionary purchases for top-tier apparel and leather goods.

    Shoppers across tier-one Chinese cities are pulling back on aspirational luxury purchases, hitting store footfall and transaction values. The pullback directly affects revenue momentum across flagship fashion houses within the French conglomerate’s portfolio.

    Slowing Momentum in Mainland Stores

    Department stores and high-end shopping complexes in Shanghai and Beijing report softer traffic among local buyers. Domestic consumers who previously drove double-digit retail gains are deferring non-essential purchases or turning toward alternative spending categories.

    Footfall declines have spread into secondary luxury corridors where premium labels expanded floor space over recent years. Landlords operating high-end properties now face slower turnover across fashion and accessories concessions.

    Regional Shifts in Luxury Spending

    Part of the slowdown reflects Chinese travelers shifting luxury purchases abroad rather than buying in domestic boutiques. Currency differences in markets like Japan continue to divert transaction volume away from mainland counters.

    This spending diversion complicates inventory management for regional operators who stocked high volumes across Chinese city flagships. Operators must balance localized retail expenses against shifting consumer travel flows across East Asia.

    Pressure Across Fashion and Leather Portfolios

    Fashion and leather goods represent the largest profit engine for luxury conglomerates operating in Asia. When demand softens in mainland China, the impact spreads rapidly across broader regional wholesale and retail networks.

    Rival European luxury houses face identical headwinds as middle-class consumers reassess discretionary budgets. Price increases implemented over previous quarters have also met increased resistance from domestic buyers seeking value retention.

    Next Steps for Asian Retail Networks

    Luxury groups are reviewing capital spending on new boutique openings across Greater China. Attention is turning toward clienteling programs and exclusive VIP experiences to retain high-net-worth shoppers while mass-affluent spending remains subdued.

    Retail property owners and brand managers will track consumer footfall data through upcoming holiday travel seasons to gauge whether promotional initiatives can stabilize store volumes across the region.

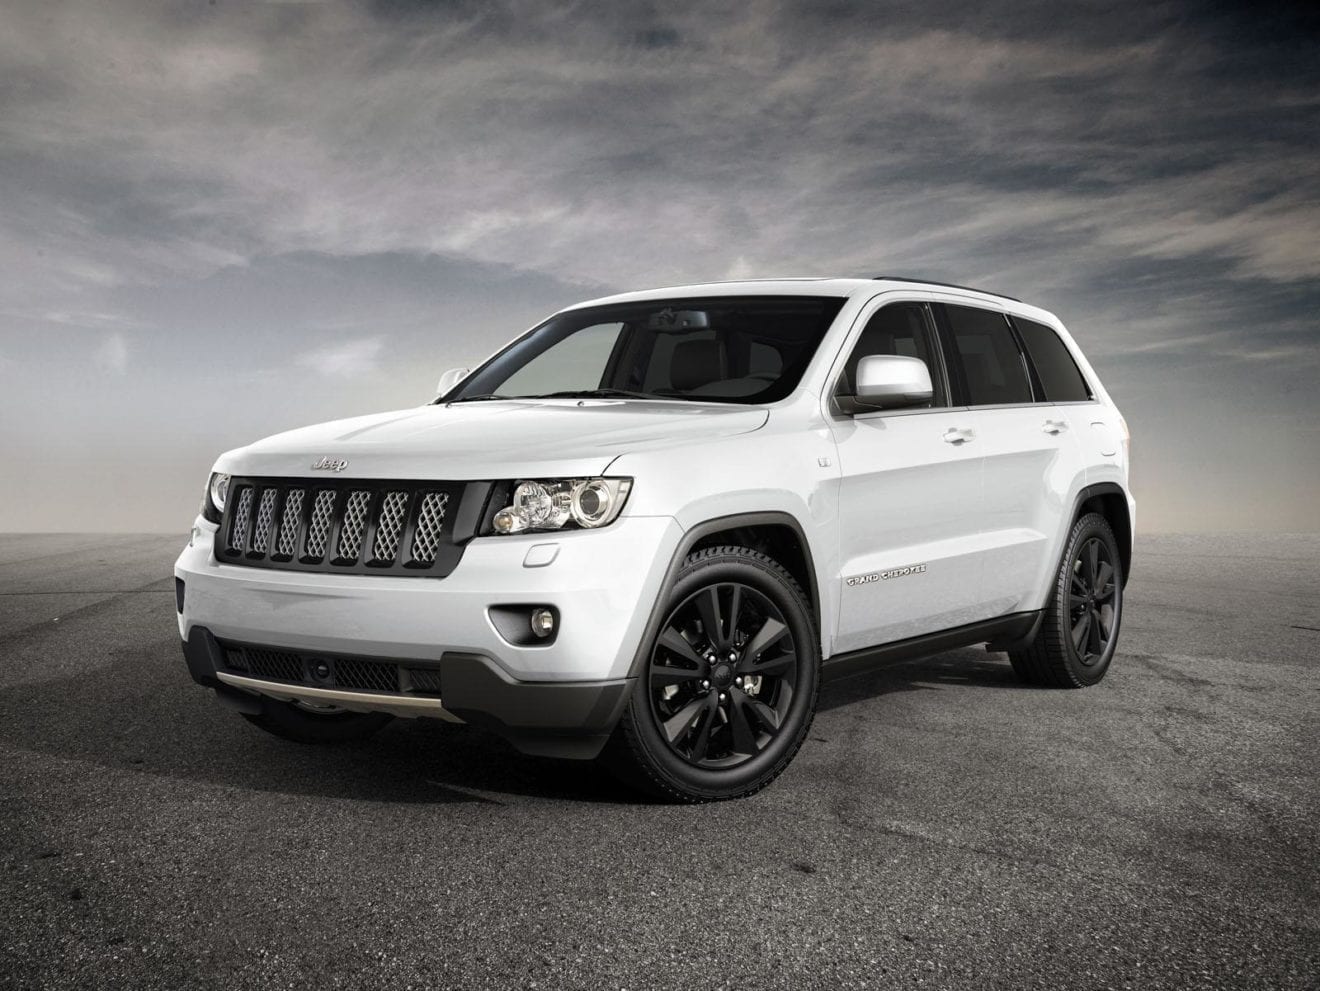
  • Jeep Resumes Production in China for Global Export Excluding US

    Jeep Resumes Production in China for Global Export Excluding US

    Jeep has resumed manufacturing vehicles in China this week to supply export markets worldwide, deliberately excluding shipments to the United States.

    The assembly restart pivots Chinese factory capacity entirely toward international demand across three regions, Asia, Europe and emerging markets, rather than domestic retail buyers or North American showrooms.

    Export Hub Strategy Takes Shape

    Stellantis altered its industrial footprint after winding down earlier local joint venture production. Utilizing Chinese manufacturing capacity purely as an export platform allows the carmaker to benefit from local supply chains and component pricing without relying on direct retail volume inside the competitive domestic market.

    Excluding the American market avoids heightened import tariffs and regulatory hurdles currently facing Chinese-made vehicles entering the US. Sourcing vehicles from China for other regional markets frees up capacity at Western plants while keeping production costs down for competitive export territories.

    Rival Carmakers Expand China Outbound Shipments

    Global carmakers increasingly treat China as a dedicated export base rather than just an end market. Tesla, Volvo and domestic joint ventures operated by European manufacturers already ship substantial volumes from Chinese ports to Southeast Asia, Latin America and Europe.

    Suppliers across China gain steady manufacturing orders from export-focused lines even as domestic price wars squeeze margins at retail dealerships. The primary operational risk rests on potential tariff adjustments in destination markets outside North America, where trade authorities continue monitoring vehicle imports built in China.

    Shifting Away From Joint Venture Woes

    Foreign automakers spent years building vehicles in China primarily for domestic consumers through 50-50 joint ventures. Intensifying competition from local electric vehicle manufacturers shifted that balance, prompting international brands to rethink their asset allocation across Chinese industrial hubs.

    Production runs for outbound markets will determine how efficiently Stellantis scales capacity across its reconfigured assembly lines in the quarters ahead.

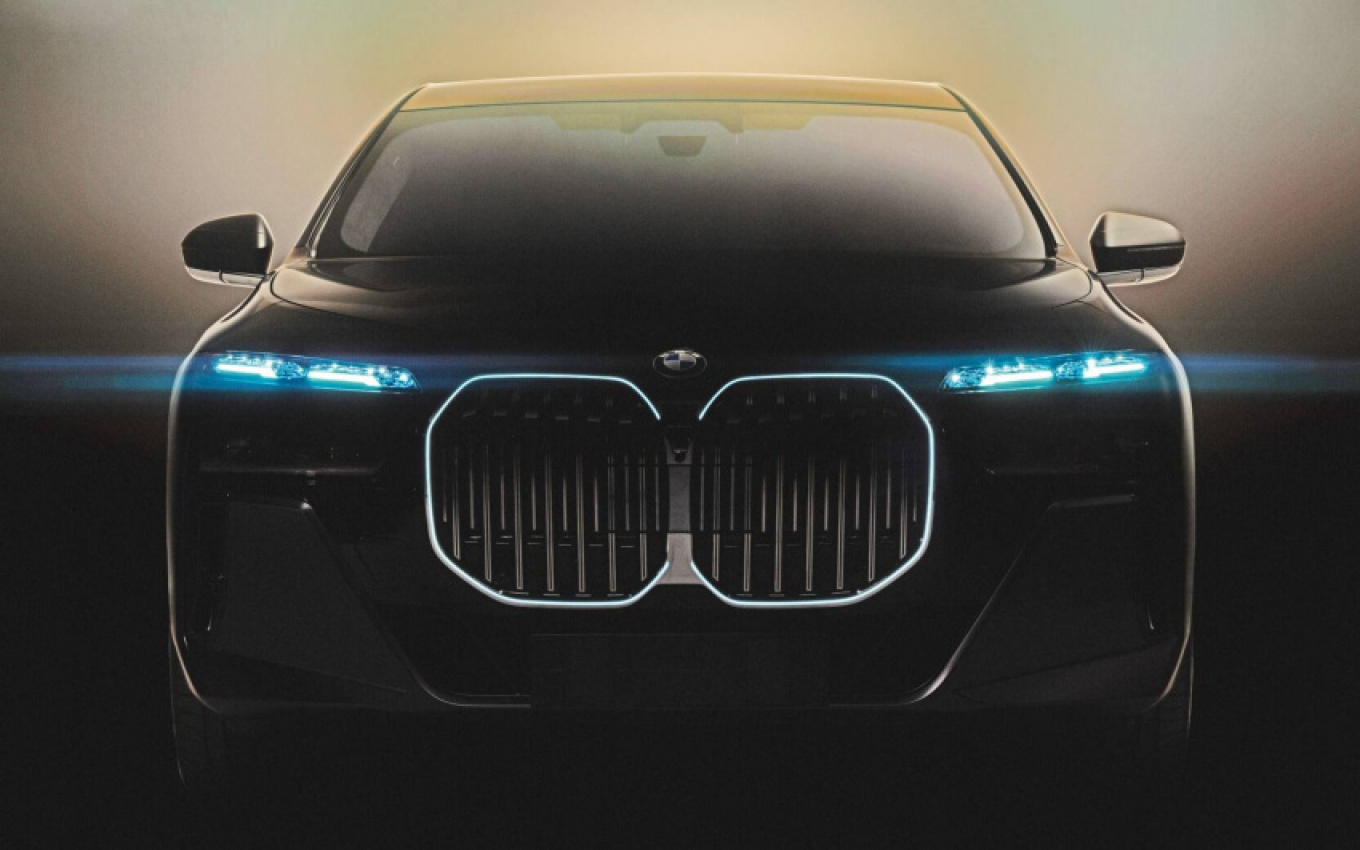
  • BMW Starts Sixth Generation Battery Production at 10 Billion Yuan Shenyang Hub

    BMW Starts Sixth Generation Battery Production at 10 Billion Yuan Shenyang Hub

    BMW started mass production of its sixth-generation high-voltage batteries in Shenyang on Thursday. The company invested 10 billion yuan ($1.49 billion) to supply its upcoming Neue Klasse electric vehicle lineup.

    The 240,000-square-metre facility expands the German carmaker’s battery footprint in Liaoning province to five times its previous size.

    Output will initially feed assembly lines for the China-exclusive Neue Klasse iX3 sport utility vehicle and the long-wheelbase i3 sedan. Shenyang is BMW’s third battery plant globally to build the Gen 6 pack. It joins sites in Debrecen, Hungary, and Irlbach-Strasskirchen, Germany. Outside Germany, the Chinese complex is the only location producing the Energy Master central control unit, an in-house hardware and software module that manages high-voltage power distribution.

    Cylindrical Cells and 800-Volt Architecture

    The new powertrain switches to large cylindrical cells integrated into an 800-volt electrical architecture. BMW tested the setup in a long-wheelbase i3 50L sedan over expressways, national highways, and urban streets. It logged a road-test range of 1,213 kilometres on a single charge with 1 per cent battery capacity remaining. The vehicle carried a 113.4-kilowatt-hour battery pack. It averaged power consumption of 8.8 kilowatt-hours per 100 kilometres.

    Charging hardware on the Neue Klasse platform accepts direct-current rates up to 400 kilowatts. That rate replenishes 400 kilometres of driving range in 10 minutes. Rear-wheel-drive configurations anchored initial trials. Dual-motor all-wheel-drive editions will output 345 kilowatts (463 horsepower) and 645 Newton-metres of torque.

    BMW Brilliance split cell sourcing between domestic suppliers. It secured large cylindrical ternary lithium packs from EVE Energy for top-trim 50L models, alongside contracts with Contemporary Amperex Technology Co. Ltd. (CATL) for standard variants. With battery assembly operational, all three primary hardware elements of BMW’s sixth-generation electric drive system are now built locally in Liaoning.

    Local Software Alliances Shift Premium Dynamics

    Foreign premium carmakers in China face shrinking profit margins as domestic brands capture market share with price cuts and localized digital cockpits. BMW is pairing heavy capital spending in Shenyang with Chinese technology alliances to keep pace. The carmaker outsourced its autonomous driving software pipeline to Beijing-based Momenta. It also integrated artificial intelligence voice controls developed with Alibaba Group Holding and DeepSeek.

    European premium marques historically kept core software development inside corporate headquarters. That model is changing. By embedding Chinese software and local computing platforms into Neue Klasse models before showroom launch, BMW cuts engineering turnaround cycles. It also avoids the software delays that plagued earlier European battery-electric entries in China.

    Commercial risk sits squarely on retail pricing power. Domestic rivals such as Nio, Zeekr, and Li Auto operate at compressed margins. That forces foreign legacy brands to match steep discounting or accept lower factory run rates. BMW Group Chairman Oliver Zipse stated during the Shenyang launch ceremony that local production will account for more than 95 per cent of BMW vehicles sold in China by 2030, leaving little room to retreat if volumes stumble.

    Building Out the Shenyang Production Base

    Groundwork for the battery plant began in May 2023 under a joint venture blueprint to localize component assembly ahead of vehicle assembly. The Shenyang complex now houses casting, combustion engine manufacturing, battery assembly, and power electronics under one operating footprint.

    Pre-sales for the long-wheelbase Neue Klasse iX3 opened on August 21 at a starting price of 269,900 yuan ($39,810). Regulatory filings published in September confirmed the i3 50L sedan rides on a 3,005-millimetre wheelbase. That adds 39 millimetres of cabin space over the outgoing China-built electric 3 Series.

    Deliveries of the Neue Klasse iX3 reach Chinese dealerships in November. The i3 sedan follows with its market launch before the end of the fourth quarter.

  • Penfolds Brand Value Drops 32% to $776 Million as Still Wine Slumps

    Penfolds Brand Value Drops 32% to $776 Million as Still Wine Slumps

    Penfolds suffered a 32 per cent drop in brand value to US$776 million this year. It posted the sharpest decline among top global wine labels in Brand Finance’s Alcoholic Drinks 2026 report.

    The Australian label led a broad retreat across still wine assets for parent company Treasury Wine Estates. Chinese producer Changyu shed 22 per cent of its brand valuation to finish at US$641 million. Beringer dropped 16 per cent, and Yellow Tail declined 14 per cent. Four of the six still wine labels tracked in the top ten lost value over the period.

    Champagne Widens Gap Over Still Wine

    Sparkling wine houses took the opposite trajectory and captured premium trade. Moët & Chandon defended its position as the world’s most valuable wine and Champagne brand. Its value rose 12 per cent to US$2.3 billion, backed by an AAA- brand strength rating and a score of 80.3 out of 100.

    Veuve Clicquot climbed to second place overall after expanding its brand value 39 per cent to US$1.4 billion. Dom Pérignon advanced 21 per cent to reach US$300 million, taking ninth place in the ranking. Prestige sparkling houses maintained pricing power despite softer total shipment volumes across key consumer markets.

    Mass Market Labels Hold Ground

    Everyday table wines held up better than mid-tier and prestige still brands. Barefoot ranked as the strongest overall label in the index with an AAA rating and a score of 85.1 out of 100. Wide retail distribution helped lift its valuation 2 per cent to US$1.3 billion.

    Carlo Rossi gained 8 per cent to reach US$313 million. Value brands retained steady household penetration. Higher-priced still wines felt the pullback in discretionary spending.

    “Meanwhile, declines for brands such as Penfolds and Changyu reflect the broader pressures facing still wine, where changing consumption patterns are making growth harder to achieve.”

    Henry Farr, global sector head of alcoholic drinks at Brand Finance, noted that premium perceptions and emotional ties allowed sparkling labels to decouple from broader category stagnation.

    Asian Demand Reshuffles Portfolio Strategy

    For distributors and retail buyers across Asia, the valuation drop reflects shifting consumer habits in key commercial hubs. Mainland China’s retail wine trade has contracted. Younger urban consumers are diversifying into ready-to-drink beverages, craft beer and spirits, eroding baseline volumes for domestic giants like Changyu.

    Treasury Wine Estates faces a split market reality. High-end allocations still find private collectors, but commercial lines struggle to clear inventory through traditional dining and corporate entertainment channels in Australia and East Asia. Retail shelf space is migrating toward lower-cost daily pours and celebration-linked Champagne labels.

    Consumption Contraction Sets Baseline

    Falling valuations follow consecutive years of cooling volume. Data from the International Organisation of Vine and Wine showed global wine consumption contracted nearly 3 per cent in 2025 to 208 million hectolitres. Demographic shifts in mature markets and tighter household budgets drove the decline.

    Treasury Wine Estates and regional competitors now face their next test in upcoming year-end inventory audits and festive wholesale reorders, which will reveal whether recent price adjustments can stabilise commercial still wine margins.

  • Shell Sued for $108 Million in Brazil over Deadly Floods

    Shell Sued for $108 Million in Brazil over Deadly Floods

    British energy giant Shell is facing legal action in Brazil and the United Kingdom seeking compensation for devastating extreme weather disasters.

    On Friday, Brazilian federal prosecutors and the non-governmental organization Instituto Preservar jointly filed a lawsuit against Shell’s subsidiary demanding $108 million over catastrophic 2024 floods.

    Attribution Science Drives $108 Million Claim

    The disaster in southern Brazil killed nearly 200 people, displaced half a million, and caused widespread destruction, marking the first time attribution science has been used in the country against a major carbon producer.

    Plaintiffs based their legal claim on research published in a Nature group journal, which calculated that climate change increased the intensity of the 2024 rainfall by 12 percent. Drawing on data from think tank Carbon Majors attributing 2.02 percent of historic global emissions to Shell, the lawsuit demands the company pay for two percent of that 12 percent intensification.

    Philippine Typhoon Survivors File in London

    The Brazilian case follows a 2025 lawsuit brought in London by roughly 100 survivors of Typhoon Rai, known locally in the Philippines as Odette. The December 2021 storm killed more than 400 people across several Philippine islands and wiped out entire coastal communities.

    Lawyers at Hausfeld filed the London action against Shell on behalf of the Philippine survivors, arguing that historic emissions and alleged misinformation on climate risks constitute actionable negligence under Philippine law. The legal team cited historical evidence indicating Shell understood fossil fuel impacts as early as the 1960s, alongside an internal 1986 company report detailing greenhouse gas risks.

    Corporate Exposure Shifts Across Asia

    Legal liabilities of this nature create direct financial exposure for multinational energy operators, industrial manufacturers, and their commercial insurers across Asia-Pacific. If courts accept proportional emissions modeling, corporate balance sheets will face recurring claims following major typhoons, floods, and coastal erosion events throughout Southeast Asia.

    Supply chain infrastructure and regional asset valuations face repricing as climate litigation expands beyond state authorities to private corporate targets. Commercial lenders and institutional investors in Asian energy assets must account for potential cross-jurisdictional tort liability in their long-term risk underwriting.

    Precedents Spread Across Emerging Markets

    Shell has rejected claims of covert liability, stating in December that the suggestion the company possessed unique knowledge about climate change was not true.

    Similar cross-border actions are underway across the region, including Indonesian islanders suing Swiss cement group Holcim over rising sea levels and Pakistani farmers pursuing litigation against industrial operators in German courts.

    London courts are scheduled to review procedural filings on the Philippine claims as plaintiffs prepare evidentiary submissions on corporate knowledge from past decades.