Author: Mei Ling Tan

  • Anthropic Commits 5% Stake to New Public Benefit Fund

    Anthropic Commits 5% Stake to New Public Benefit Fund

    AI lab Anthropic, the developer of Claude, announced on Oct 18 that it will commit 5 per cent of its shares to a new public benefit fund to finance donations for the public good.

    The proposed vehicle will be established as a wholly owned limited liability company and could receive an additional 2 per cent of shares for every 50 per cent increase in company value above an undisclosed baseline.

    Anthropic structured the fund to support initiatives including non-profit donations, direct distributions to specific populations, and efforts to address artificial intelligence’s impact on the labour market.

    Scaling equity as valuation rises

    The equity pledge arrives as Anthropic prepares an initial public offering under a public benefit corporation charter. That corporate structure obligates directors to weigh social objectives alongside shareholder returns.

    Tech operators across Asia-Pacific face mounting scrutiny over governance and workplace automation as generative AI tools enter retail and corporate workflows. Anthropic is testing investor appetite. By anchoring equity to public initiatives, the firm wants to see if enterprise buyers and public market investors will accept lower equity claims in exchange for formal safety commitments.

    Standard Silicon Valley structures trigger escalating executive stock grants as valuations rise. Anthropic takes a different route. It redirects milestone equity pools into its public trust, creating a mechanism that dilutes commercial shareholders whenever market capitalization jumps.

    Labor disruption and safety risks

    Anthropic identified labor market stabilization as a primary target for fund disbursements. The initiative expands on an earlier US$200 million commitment. That program focused on studying and mitigating workforce displacement caused by AI deployment.

    Global technology companies have eliminated thousands of jobs following heavy capital spending on automated systems. Research from the International Monetary Fund indicates that artificial intelligence will augment, downgrade or eliminate roughly 40 per cent of jobs globally, rising to 60 per cent in advanced economies.

    Elon Musk, who runs competing artificial intelligence firm xAI, criticized the structure on social media platform X. Musk said he recommended “giving the shares directly to the public”.

    Founding pledges and employee matching

    Company founders committed 80 per cent of their personal equity holdings to public purposes when they established the lab. Anthropic also runs an internal matching program where approximately half of its workforce pledges equity to charitable causes.

    Combining founder commitments, staff pledges and the new 5 per cent allocation places roughly 20 per cent of total corporate equity into public benefit reserves before accounting for future milestone grants. The company stated that no equity held by the vehicle will fund political lobbying or campaign donations in the United States or overseas.

    Safety positioning remains central to the firm’s commercial identity. Anthropic devoted approximately 80 pages of its 261-page prospectus body to detailing operational and societal risks. It warned that frontier models could create catastrophic or existential hazards.

    Governance details and upcoming disclosures

    Regional expansion continues alongside capital planning, following the opening of Anthropic’s Singapore office and an agreement with the Singapore government to deploy safe AI frameworks across local industry. The company plans to publish details on the fund’s governance architecture, advisory leadership and valuation milestones in the coming months, followed by a formal public benefit progress report.
  • Gentle Monster Owner Takes Blue Elephant to Court in 12 Billion Won Copycat Case

    Gentle Monster Owner Takes Blue Elephant to Court in 12 Billion Won Copycat Case

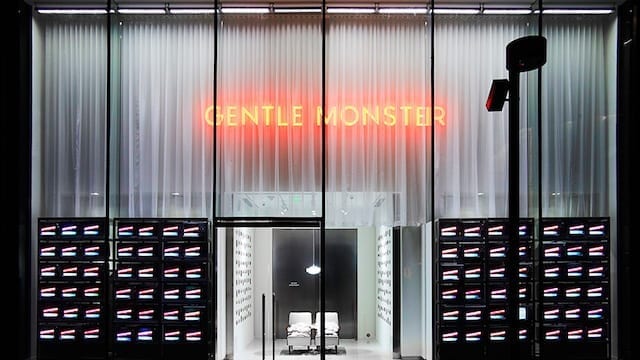
    South Korean prosecutors have indicted Blue Elephant founder Choi Jin-woo for selling 12.3 billion won ($9 million) worth of eyewear allegedly copied directly from Gentle Monster parent IICOMBINED.

    The criminal case in Daejeon District Court is the first in South Korea to test whether unpatented fashion designs receive criminal protection against direct three-dimensional replication.

    Prosecutors allege Blue Elephant sent photographs of Gentle Monster frames bearing its own logo directly to overseas contract manufacturers between 2023 and mid-2025. The company produced and sold approximately 321,000 units across 51 separate models during that window. Forensic 3D scanning commissioned by IICOMBINED showed 29 models matched at least 95 per cent of Gentle Monster contour lines, with 18 exceeding 99 per cent congruence. The comparison matched Gentle Monster’s 2021 JEFF frame to Blue Elephant’s 2023 ZENTA model at 99.9441 per cent.

    Discounter growth collides with premium margins

    The dispute exposes the commercial fault line running through the South Korean optical sector, which expanded 74 per cent between 2022 and 2025 to reach 4.7 trillion won. Gentle Monster built its brand equity on gallery-format flagship stores, celebrity campaigns featuring Tilda Swinton and Stray Kids’ Felix, and luxury partnerships with Maison Margiela and Prada. Its acetate frames retail between 200,000 and 300,000 won.

    Blue Elephant replicated the gallery retail concept in Seoul’s Seongsu-dong shopping district while pricing lookalike acetate frames between 50,000 and 70,000 won. That aggressive pricing lifted Blue Elephant’s revenue 69 per cent last year to 50.7 billion won. Operating profit collapsed 74 per cent to 3.3 billion won as retail overhead climbed.

    IICOMBINED experienced its first revenue contraction in years over the same period, with total sales slipping 2.1 per cent to 772.3 billion won. Overseas business cushioned the domestic slowdown, rising to 332.9 billion won and accounting for more than 40 per cent of top-line revenue.

    Private equity backing against legal exposure

    Despite criminal charges and an active civil damages lawsuit, private capital continues to fund Blue Elephant’s retail footprint. Singapore-based private equity firm Affirma Capital acquired a 25.8 per cent stake in Blue Elephant in August for 100 billion won, a deal that valued the discount eyewear startup at 400 billion won.

    That valuation demonstrates institutional confidence in fast-fashion optical margins, yet it shifts substantial compliance risk onto incoming investors. If courts rule that wholesale imitation of unpatented consumer products constitutes criminal intellectual property theft, low-cost fast-follower brands across Asian retail will face injunctions and sudden inventory write-offs.

    For retail landlords across Asia-Pacific prime high streets, the case determines whether experiential eyewear stores are sustainable standalone formats or short-lived arbitrage plays on designer intellectual property. Flagship rents in Seongsu and Tokyo depend heavily on foot traffic generated by concept showrooms.

    Tech partnerships separate brand tiers

    Gentle Monster has responded to lower-tier copycats by pushing upmarket into connected hardware and global retail real estate. The company operates 86 stores globally, with roughly 50 located outside South Korea, and plans to reach 200 outlets within five years.

    Capital markets have valued the higher-tier positioning accordingly. Alphabet paid roughly 145 billion won for a 4 per cent stake in IICOMBINED last year, valuing the Gentle Monster operator at 3.7 trillion won. That partnership yielded prototype smart glasses developed with Samsung Electronics and unveiled at industry events in London and Mountain View.

    Choi resigned as chief executive of Blue Elephant in February following the initial criminal complaint and secured bail in July after his March indictment. Daejeon District Court will resume witness examination hearings in December and January.

  • Lindt Opens First Southeast Asian Store in Kuala Lumpur with Valiram

    Lindt Opens First Southeast Asian Store in Kuala Lumpur with Valiram

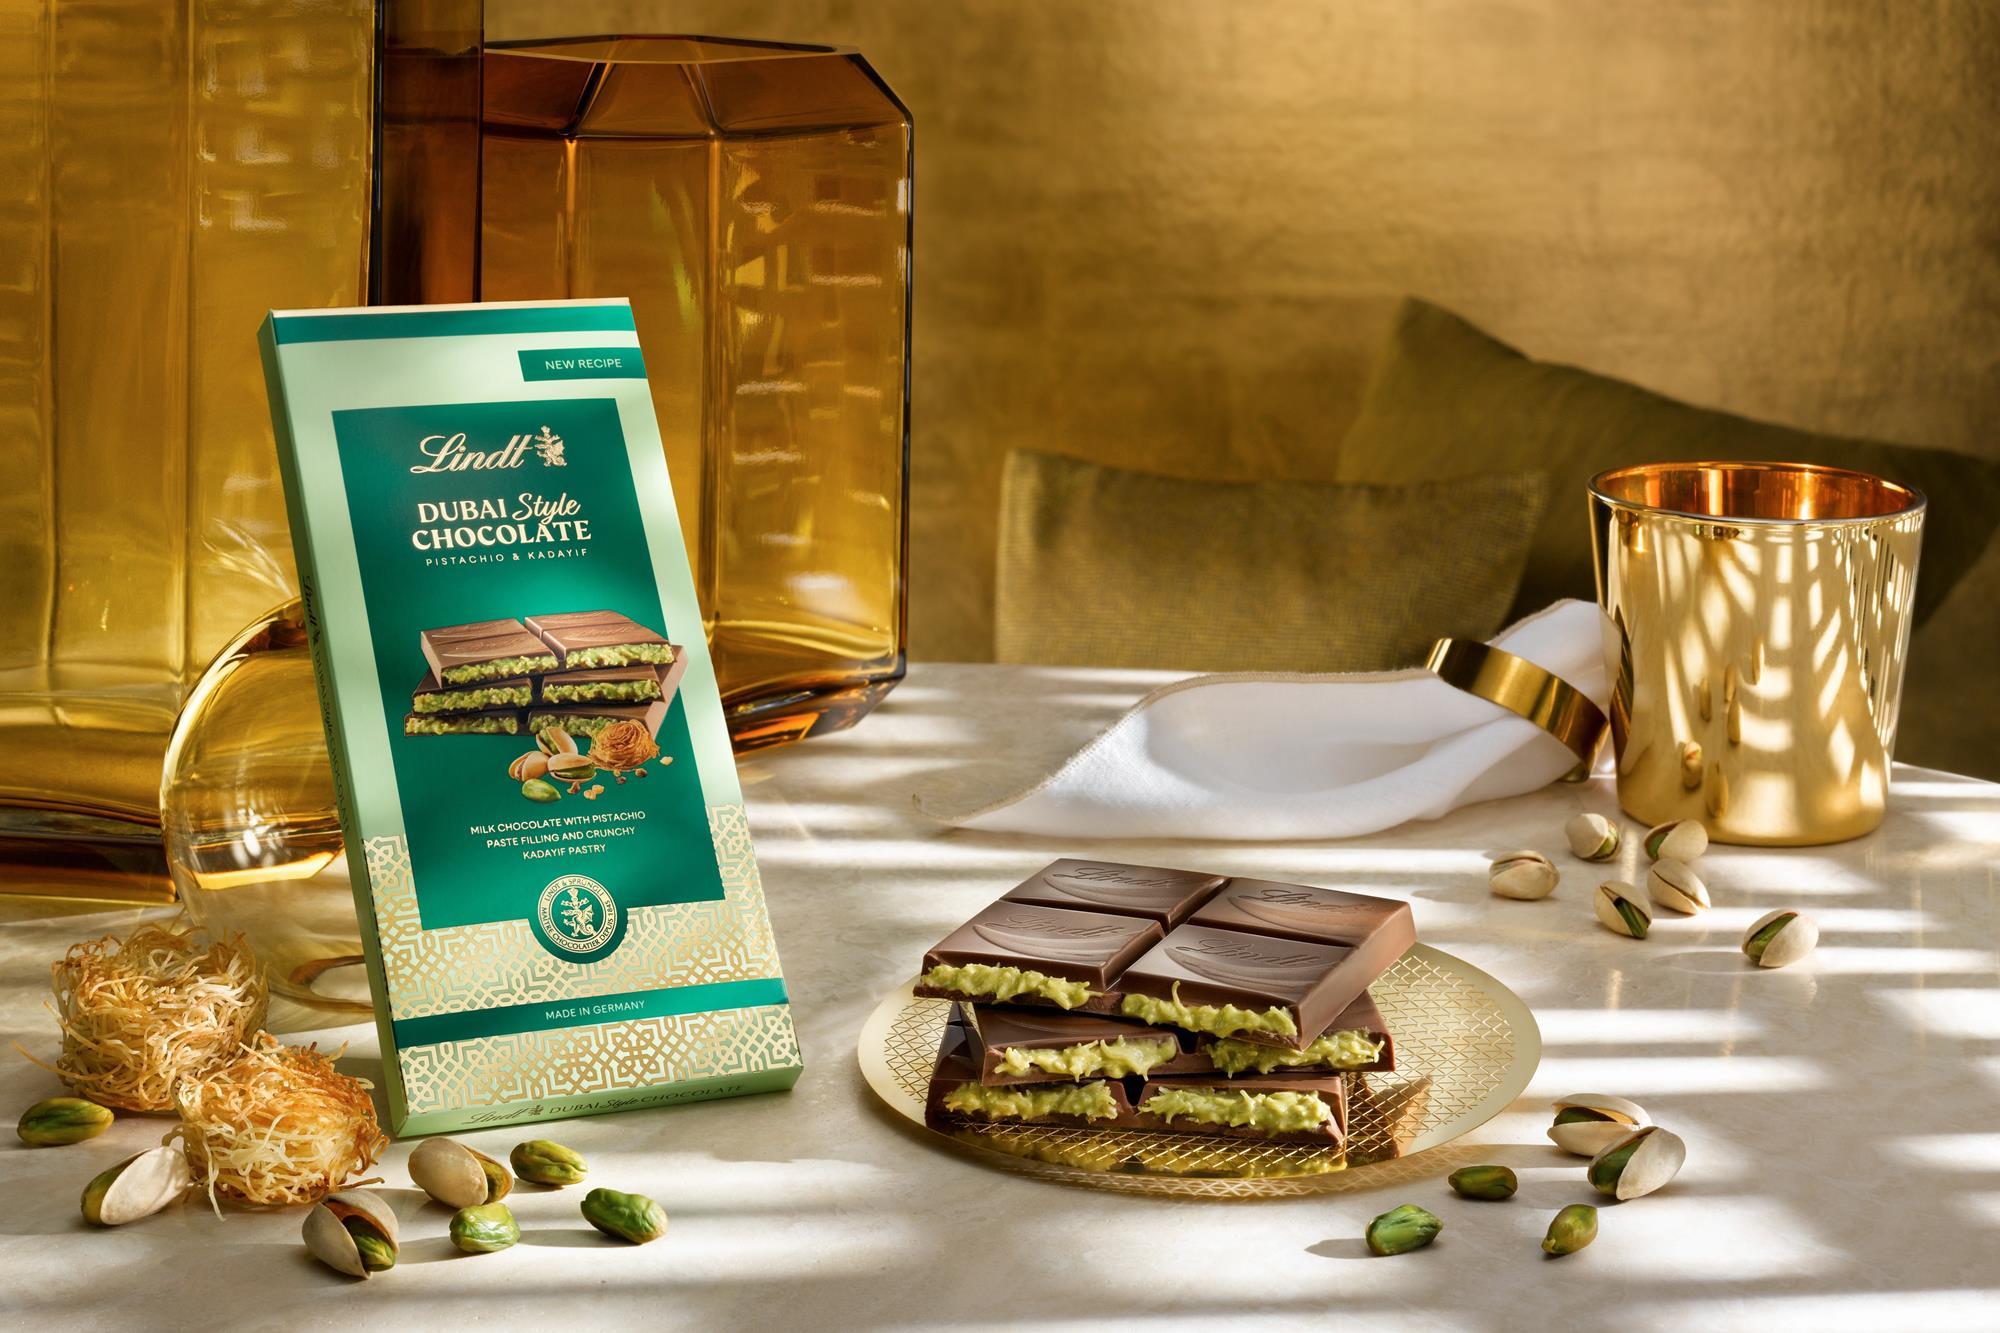
    Swiss chocolatier Lindt opened its first Southeast Asian standalone boutique at Kuala Lumpur’s The Exchange TRX on Friday. The company partnered with luxury distributor Valiram for the launch.

    A dedicated Pick & Mix station inside the flagship stocks 19 Lindor varieties alongside market-exclusive flavours. The installation anchors the brand’s direct retail push across the region.

    Product mix at The Exchange TRX

    Inside, the shop carries Lindt’s full inventory. Lines include the Excellence dark chocolate range, the Extra Creamy milk selection, and the newer wafer lineup.

    With the bulk Pick & Mix fixture, the store replicates the format Lindt runs across European transit hubs and North American city centres. Shoppers choose items by weight instead of buying fixed multipacks. This lifts basket sizes. It also gives the confectionery maker direct control over pricing and display.

    Valiram’s premium confectionery push

    Valiram manages operations on the ground. The Kuala Lumpur-based conglomerate oversees regional networks for international labels across fashion, timepieces, and specialty food.

    Partnering with Valiram gives Lindt immediate access to prime mall space without building local logistics from scratch. Valiram already holds leases in key commercial developments across Malaysia, Singapore, Indonesia, and Thailand. Placing Lindt in The Exchange TRX puts the brand inside Kuala Lumpur’s newest financial district, targeting affluent locals and international travelers alike.

    Direct retail over wholesale distribution

    For decades, European chocolatiers treated Southeast Asia strictly as an import wholesale market. Supermarkets, duty-free airport kiosks, and specialty grocers sold boxed stock through third-party food brokers.

    That model shields margins against tropical heat and supply chain hurdles, but it limits brand control. Supermarkets discount stock, and tight shelf space restricts product range. Standalone boutiques shift the strategy toward experiential shopping. Gifting and seasonal items command higher prices in this format.

    Earlier airport presence paved the path

    Lindt previously relied on airport duty-free counters and travel-retail pop-ups across Southeast Asia. The Malaysian store is its first permanent high-street location in the region.

    Competitors have tested similar models. Godiva built boutique cafes across Asian capitals over the past decade, while Japanese and European artisan producers expanded into major malls. Lindt enters the standalone space focused on packaged volume at lower entry price points than luxury cafe chains.

    Future results at The Exchange TRX will determine how quickly Valiram and Lindt expand into secondary Malaysian markets like Penang, as well as Singapore and Bangkok.

  • Shopee and Magalu Form Marketplace Partnership in Brazil

    Shopee and Magalu Form Marketplace Partnership in Brazil

    Singapore-based e-commerce platform Shopee agreed this week to a commercial partnership with Brazilian retailer Magazine Luiza to cross-list inventory on two online marketplaces.

    The agreement allows Magazine Luiza, known as Magalu, to sell its first-party catalog directly through Shopee while integrating Shopee products into its own digital ecosystem.

    Integrating Distribution Networks

    Shopee operates one of the largest marketplace channels in Southeast Asia and has built a substantial local seller network in Brazil. Magalu brings established national warehousing, electronics retail relationships, and durable goods fulfillment across South America.

    By listing core retail lines on Shopee, Magalu gains immediate exposure to Shopee’s high-frequency mobile user base. Shopee secures direct access to Magalu’s consumer appliance inventory and established local distribution channels without taking on independent inventory risk.

    Shifting Marketplace Alliances

    Marketplace tie-ups between major regional operators reflect a broader change in international e-commerce strategy. Rather than competing head-to-head across every category, platforms are pooling traffic and distribution strengths to protect margin profiles.

    For regional operators in Asia and Latin America, cross-platform merchant access lowers customer acquisition costs while defending market share against global rivals. The operational risk rests on technical integration, fulfillment speed, and commission splits between the two platforms.

    Commercial Trajectory

    Shopee entered Brazil as part of Sea Group’s international expansion outside Southeast Asia, shifting over time from cross-border deliveries toward local merchant networks. Magalu has steadily broadened its digital platform to defend its home market position.

    Platform teams are currently integrating merchant catalogs and seller tools ahead of the combined marketplace rollout.

  • GCash Allocates 60% of IPO Cash to Challenge Informal Lenders

    GCash Allocates 60% of IPO Cash to Challenge Informal Lenders

    GCash operator Mynt will deploy 60 percent of its primary IPO proceeds into consumer lending, targeting the informal loan market across the Philippines.

    The digital wallet counts 41.5 million monthly active users, but only 7.5 million borrow through its platform. Converting the remaining 34 million registered users into active credit customers forms the central growth pitch to equity investors ahead of listing.

    Mynt runs its credit operations through Fuse Financing, offering micro-credit products like GLoan Sakto for sums as low as 100 pesos and Borrow Load for 20 pesos. More than 90 percent of the user base falls within the lower C2DE socio-economic brackets, where daily cash flow needs mirror sachet retail buying habits. Frost & Sullivan data compiled for the listing shows roughly 40 percent of borrowing Filipino adults relied on informal credit in 2025, including unregulated 5-6 money lenders who demand 20 percent nominal interest rates on short-term advances.

    Sachet credit replaces street lenders

    Digital wallets across Southeast Asia have shifted from simple payment rails to balance-sheet lending to offset margin compression on transfers and merchant settlements. Singapore-based Grab, Indonesia’s GoTo and regional digital banks all pursued similar transitions, yet few command the domestic user dominance GCash holds in its home market. By pushing loan sizes down to 100 pesos, Fuse Financing mirrors the Philippine retail distribution model of selling daily goods in small packets.

    This micro-lending model shifts customer acquisition costs almost to zero because borrowers already transact on the core app. Traditional Philippine banks struggle to service sub-1,000-peso tickets profitably due to branch overheads and manual underwriting costs. GCash automates that screening using its proprietary GScore credit assessment and an automated voice bot called GINA to manage collection calls.

    Rising share of digital lending revenue

    Lending generated 28.52 billion pesos in 2025 after expanding at a two-year compound annual rate of 67.1 percent. That performance lifted credit from 35.8 percent of adjusted revenue in 2025 to 41.8 percent during the first half of 2026. Payments generated 50.34 billion pesos, or 63.2 percent of 2025 revenue, but lending expansion now drives top-line momentum as total loan assets hit 70.5 billion pesos in June 2026.

    “There’s money in serving them,”

    Mynt president and chief executive Martha Sazon told investors at an October 6 briefing, pointing to unbanked consumer segments as the primary engine for the next growth cycle.

    Credit loss provisions and default risks

    Rapid loan book expansion brings balance sheet volatility. The company booked 12.62 billion pesos in provisions for credit losses in 2025, absorbing 44.3 percent of its lending revenue that year. First-half 2026 provisions reached another 7.93 billion pesos.

    Non-performing loans stood at 4.9 percent in June 2026, falling from 7.5 percent in 2025 and 9.2 percent in 2023. Fuse Financing chief executive Tony Isidro told brokers he remains comfortable holding delinquent loans within single-digit bands while migrating borrowers away from informal street lenders. Managing those defaults will dictate whether lending remains an earnings generator or becomes a capital drag as net income growth slowed to 7.3 percent year-on-year in the first half of 2026.

    Premium valuation on the trading floor

    The company priced its initial public offering at 6.60 pesos per share, implying an equity valuation of roughly 442 billion pesos. That prices Mynt at 25.7 times its 2025 net earnings, commanding a premium over global peers such as PayPal and Brazil’s Nu Holdings. Institutional demand oversubscribed the offer during the retail bookbuild.

    Market participants will test that valuation when shares begin secondary trading on Tuesday, October 20 under the ticker symbol GCASH.

  • Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global Food Prices Climbed 5.8 per Cent in September Despite Near-Record Grain Output

    Global food commodity prices climbed 5.8 per cent year-on-year in September 2026, driven higher by energy shocks, shipping bottlenecks and surging fertiliser expenses across major Asian trade routes.

    The Food and Agriculture Organization Food Price Index reached 136 points during the month, up 1.5 per cent from August, despite worldwide cereal output tracking toward 2.979 billion tonnes, the second-highest harvest recorded.

    Global cereal inventories remain stable at roughly 950 million tonnes for the 2026-27 season, yet distribution costs and input pricing have broken the link between grain abundance and retail shelf prices. The divergence exposes supermarket chains, food processors and institutional buyers to compounding margin pressure as wholesale commodity jumps filter directly into wholesale procurement.

    Input Shocks Ripple Through Maritime Corridors

    Maritime trade disruptions in the Middle East and the Black Sea have inflated transportation and processing overheads throughout the year. Tanker freight rates jumped more than 90 per cent following security conflicts around the Strait of Hormuz, a passage handling one-quarter of seaborne crude and one-third of seaborne fertiliser trade. Bunker fuel costs doubled over the same period, forcing commercial carriers to add war-risk surcharges to bulk grain and oilseed shipments.

    International urea prices climbed 80 per cent between February and April to surpass $850 a tonne, while diammonium phosphate gained over 10 per cent. Those input spikes hit crop economics across South and Southeast Asia just as planting cycles began. Logistical friction in the Black Sea and dry weather in North America lifted global wheat prices 6.3 per cent in September alone. International maize prices rose 5.6 per cent month-on-month, compounded by smaller Brazilian export volumes and lower yields in the United States.

    Vegetable oils and sugar followed a similar upward path. The FAO Vegetable Oil Price Index gained 0.9 per cent in September on firm palm oil buying and dry conditions in Southeast Asian growing basins, while sugar prices jumped 6.1 per cent.

    Indian Retail Shelves Absorb Upstream Inflation

    In New Delhi and across major Indian metropolitan centres, retail food inflation accelerated to 7.74 per cent in September from 5.97 per cent in August. While central grain warehouses held 87 million tonnes of wheat and rice on September 1, shielding staple cereal retail prices to a 3.94 per cent rise, perishable and imported categories recorded sharp increases.

    Edible oils and fats inflation reached 8.35 per cent in September. The combined category for vegetables, tubers and pulses rose 9.18 per cent, while fruits and nuts climbed 10.75 per cent. At the consumer level, Crisil Intelligence calculated that the cost of preparing a standard home-cooked vegetarian meal rose 10 per cent year-on-year to 30.8 rupees in September, driven by higher prices for cooking oil, onions and liquefied petroleum gas.

    India’s trade account shows the scale of the cost transfer. National crude oil imports totalled $74.8 billion between April and August, up 48.4 per cent in value despite import volumes slipping 0.4 per cent. Fertiliser import expenditure jumped 53.25 per cent to $8.21 billion during the five-month span, while vegetable oil purchases grew 11.28 per cent to $9.18 billion. Domestic urea output fell 27 per cent in March to 1.8 million tonnes when feedstock natural gas deliveries dropped to 60 per cent of normal capacity before stabilizing.

    Weather Risks Threaten Export Allocations

    Climate factors are tightening the outlook for the next crop cycle. The National Oceanic and Atmospheric Administration projects an 83 per cent probability that a strong El Nino pattern will persist through the first quarter of 2027. In India, the 2026 southwest monsoon concluded with rainfall 13 per cent below historical averages, marking the driest seasonal performance since 2015. Southern states faced a 24 per cent deficit, while eastern and northeastern territories recorded a 26 per cent shortfall.

    Reduced reservoir levels pose direct operational hurdles for winter sowing. Crisil forecasts a 5 to 6 per cent decline in domestic paddy production due to lower planted area and thinner yields. Because India supplies roughly 40 per cent of the cross-border rice trade, production shortfalls in the domestic basin carry immediate pricing consequences for food distributors across the Middle East, Africa and Southeast Asia.

    Government subsidies have so far absorbed a portion of the shock, with central budget spending on fertiliser support rising 20.7 per cent to 1.03 trillion rupees between April and August. Food manufacturers and commercial retailers nonetheless face higher cold-chain logistics costs, packaging inflation and inventory holding expenses as raw materials turn costlier.

    Trade Metrics to Track Through 2027

    Retail grocers and packaged food companies across the region enter the final quarter of 2026 with little room to absorb further wholesale increases without adjusting shelf prices. Operating margins will depend heavily on whether winter rainfall restores reservoir capacity across key agricultural belts.

    Over the next 6-12 months, I would watch pulses, edible oils and vegetable prices; rabi sowing and soil moisture; reservoir levels; crude oil and fertiliser prices; the rupee; freight costs; and government decisions on food imports, exports and stocks. The key signal will be whether inflation remains concentrated in a few commodities or starts spreading across the wider food basket.

    Market participants are now tracking weekly acreage numbers for India’s rabi crop, alongside monthly palm oil stock levels in Malaysia and Indonesia, to gauge whether retail food inflation stabilizes before the 2027 harvest cycle opens.

  • Philippine Credit Card Bad Debts Jump to P68 Billion as Inflation Bites

    Philippine Credit Card Bad Debts Jump to P68 Billion as Inflation Bites

    Philippine commercial banks saw non-performing credit card receivables surge 11.8 per cent to P68.28 billion in June as living costs strained consumer budgets across the country.

    Bad loans outpaced overall card lending, which expanded 5.3 per cent over the same period to reach P1.294 trillion.

    Data from the Bangko Sentral ng Pilipinas, presented by First Metro Securities head of institutional research Estella Dhel Villamiel at a forum in Manila, showed non-performing card balances climbed from P61.07 billion in March. The share of distressed balances rose from 4.97 per cent to 5.28 per cent of total card receivables in three months.

    Accelerating Bad Debts Across Bank Books

    The expansion in card debt reflects both broader financial inclusion and growing household reliance on credit to manage monthly overheads. While higher transaction volumes naturally lift gross receivables, bad balances are expanding at more than twice the speed of new lending.

    A typical rollover balance of P20,000 incurs roughly P600 in monthly interest at standard 3 per cent card rates before penalties. When wages fail to keep pace with basic expenses, compounding finance charges absorb disposable income that would otherwise flow directly into retail cash registers.

    Mounting Pressure on Retail Margins

    For supermarket chains, department stores and consumer electronics retailers, deteriorating consumer debt signals a clear shift in shopper behavior. High-ticket discretionary purchases slow first as cardholders exhaust their credit lines on groceries, transport and utilities.

    Retail operators facing elevated freight and import bills cannot rely indefinitely on debt-financed foot traffic to protect their sales volumes. If banks tighten revolving credit limits to contain default ratios, store operators will face immediate downward pressure on average basket sizes across metropolitan malls.

    Slowing Investment and Sticky Price Rises

    Macroeconomic indicators highlight why household balance sheets are cracking under everyday pressure. Philippine inflation climbed to 7.2 per cent in September from 6.1 per cent in August, driven by fuel costs and a weaker peso.

    DBS Bank projects Philippine inflation to average 6.5 per cent in 2026 and 5.5 per cent in 2027, with the currency forecast to slide toward P64 per US dollar by late 2027. Labor market softness compounds the strain: August unemployment rose to 5.3 per cent from 3.9 per cent a year earlier, while underemployment climbed from 10.7 per cent to 11.9 per cent.

    Capital Formation Drops as Consumption Stalls

    Second-quarter national accounts revealed household consumption grew 2.8 per cent and gross domestic product expanded 2.3 per cent, but gross capital formation dropped 9.2 per cent. A sharp contraction in capital formation points to weaker future job creation, limiting the wage growth required to service existing card balances.

    Commercial lenders and retailers will look to fourth-quarter holiday spending figures to measure real demand, before credit statements arriving in January reveal whether repayment delinquency breaches the 5.5 per cent mark.

  • Pakistan Takes 20 Tech Startups to TechCrunch Disrupt in Silicon Valley

    Pakistan Takes 20 Tech Startups to TechCrunch Disrupt in Silicon Valley

    Pakistan brought 20 technology companies to TechCrunch Disrupt 2026 in San Francisco, pitching American venture funds and commercial clients across three days at Moscone West.

    The delegation set up a national pavilion at the annual startup conference from October 13 to 15, seeking direct commercial contracts and cross-border investment.

    Silicon Valley delegation

    Participating firms exhibited enterprise software, digital consumer tools, and custom IT services to early-stage founders and venture capital firms. Pakistan’s Ambassador to the United States, Rizwan Saeed Sheikh, visited the pavilion on October 15 to review commercial pitches and meet founders.

    Sheikh told company delegates that diplomatic missions across the US will provide direct operational support to help Pakistani tech founders establish client networks and corporate partnerships in North America.

    Commercial push in North America

    For South Asian software houses and startup founders, breaking into the US enterprise pipeline remains essential for dollar-denominated revenue. Indian IT exporters established this corridor decades ago, and Pakistani founders are now attempting to replicate that access by presenting engineering teams directly to Silicon Valley buyers.

    The structural challenge lies in conversion rates. Trade delegations and pavilion booths deliver visibility, but landing enterprise software contracts requires local corporate entities, US-based sales leads, and strict compliance structures that early-stage teams often lack.

    Regional export ambitions

    Islamabad has stepped up state-backed trade missions over the past year to lift software and IT services exports. Similar trade delegations pitched digital services in Riyadh earlier in the cycle, following domestic infrastructure drives including new tech parks backed by Prime Minister Shehbaz Sharif.

    Diplomatic missions in Washington and San Francisco will now track follow-up commercial contracts signed by the 20 participating firms as Pakistan prepares its next bilateral investment delegations ahead of the November minerals and industry forums in Islamabad.

  • Alibaba Launches Qwen Glasses N1 for 2,218 Yuan

    Alibaba Launches Qwen Glasses N1 for 2,218 Yuan

    Alibaba Group Holding launched its latest smart glasses series on Tuesday, introducing the Qwen Glasses N1 priced at 2,218 yuan for the standard version.

    An advanced version featuring eye tracking for visual interaction starts at 2,600 yuan, entering a market where 909,000 smart glasses were sold in China in the first half of 2026, according to Luo Tu Technology.

    Hardware prices in China remain lower than foreign alternatives, with Xiaomi AI glasses retailing for about 2,000 yuan (US$298) compared to US$450 for Meta Platforms’ Ray-Ban Gen 3 glasses, according to Mark Natkin of Marbridge Consulting, while Counterpoint reported the global average selling price stood at US$360 in late 2025.

    Tourist Sites Deploy Wearable Audio Guides

    Domestic tourism operators are testing the hardware as automated, hands-free tour guides. Hangzhou Culture, Radio, TV and Tourism Bureau partnered with Alibaba in May to deploy Qwen Glasses for real-time cultural interpretation and navigation. In Shanghai, management at Yuyuan Garden has started running trials using smart glasses to handle multilingual translation and point-of-interest explanations for incoming visitors.

    The devices rely on built-in cameras, microphones and onboard language models to identify landmarks, translate physical street signs and feed spoken itinerary advice into the user’s ears. IDC China data shows the broader smart eyewear category, covering both AI and non-AI models, will reach 18.66 million shipments worldwide by the end of the year.

    Ecosystem Split Limits Cross-Border Utility

    Chinese hardware makers face an immediate structural barrier when marketing these devices to outbound travelers. Domestic models rely on integrations with mainland platforms like Baidu Maps and Alipay. Outside China, those service layers lose accuracy and merchant coverage, leaving travelers with reduced functionality on foreign networks.

    Foreign manufacturers run into the inverse problem. Meta does not officially sell its Ray-Ban hardware in mainland China, and domestic consumers who import the frames cannot easily access the underlying cloud AI servers without virtual private networks. For retail distributors, this division confines each product line largely to its domestic home turf despite the universal appeal of hands-free travel navigation.

    Hardware Constraints Challenge Mass Adoption

    Battery performance and processing limits continue to dictate form factors. Meta states its Ray-Ban Gen 2 and Oakley HSTN frames run for eight hours on an internal charge, relying on bundled charging cases to provide up to 48 hours of total battery life. To achieve deeper mixed-reality computing, Meta built upcoming 1,300-dollar virtual reality glasses by separating the computing unit into a tethered 3.5-ounce module.

    For consumer tech brands, keeping the form factor lightweight means offloading processing to paired smartphones. Analysts point out that until onboard battery density improves and vision processing latency drops, complex tasks such as booking transit tickets and scanning detailed menus will remain anchored to handset screens rather than spectacle frames.

    Alibaba Expands Travel Tech Alliances

    Alibaba has stepped up hardware deployments across municipal cultural programs over the past two quarters to build practical use cases for its proprietary Qwen model. Beyond its Hangzhou municipal project, the group joined a bilateral cultural exchange association with Italy to test cross-border AI translation before rolling out commercial shipments of the N1 frames.

    Supply chain trackers at IDC China project sales momentum to hinge on the holiday travel quarters. Luo Tu Technology will release full-year 2026 smart eyewear sales figures for the China market in January, providing the first comprehensive tally of whether sub-300-dollar price points can turn wearable tour guides into standard consumer gear.

  • Elon Musk Loses $20 Billion in Net Worth Following Tesla Roadster Demo

    Elon Musk Loses $20 Billion in Net Worth Following Tesla Roadster Demo

    Elon Musk lost $20 billion in personal net worth on Friday after unveiling Tesla’s experimental Roadster sports car, pulling his fortune down to $925 billion.

    The 2.11 percent single-day drop tracked a 1.3 percent slide in Tesla shares on Thursday, extending the automaker’s year-to-date market decline to 17 percent.

    Engineering Demo Draws Investor Skepticism

    Tesla presented the new two-seater Roadster with an autonomous demonstration where the vehicle climbed a steep ramp, hung upside down, flipped in the air, and landed using cold-gas thrusters. Musk said the sports car accelerates from zero to 60 miles per hour in less than one second, using 10 nozzles fed by ultra high-pressure air tanks developed with rocket engineers at SpaceX.

    SpaceX shares dropped 2.3 percent following the event, bringing its own year-to-date decline to nearly 8 percent. Commercial mass production for the vehicle is scheduled for 2028, four years behind earlier timelines.

    “It was an engineering flex with no commercial value ⁠beyond embarrassing traditional car makers,” Gene Munster, managing partner at Tesla investor Deepwater Asset Management, said on social media platform X.

    Shifting Priorities from Volume to Halo Tech

    For automotive supply chains and retail distribution networks across Asia, the stunt confirms Tesla’s pivot away from entry-level passenger electric vehicles toward speculative halo hardware. Asian rivals such as BYD, Geely, and Hyundai have consolidated volume sales across Southeast Asia by rolling out practical, sub-$25,000 passenger cars. Tesla instead spent engineering capital on an ultra-luxury niche model that offers no commercial volume for suppliers or fleet operators for years.

    Institutional investors in Asia-Pacific holding tech-heavy portfolios face increased exposure to execution risk. Tesla continues to redirect capital toward autonomous driving systems, robotics, and aerospace-derived concepts while its core passenger car lineup ages without high-volume replacements. The strategy protects brand prestige at the extreme top end of the market but cedes mass-market share to regional competitors in China, Thailand, and Indonesia.

    Regional Groundwork and Historical Parallels

    The original Lotus-based Roadster served as Tesla’s market entry point between 2008 and 2012 before the company built its core business on the Model 3, Model Y, Model S, and Model X. In Southeast Asia, Tesla recently registered Tesla Motors Vietnam with a charter capital of VND77.6 billion, or approximately $3 million, establishing an official corporate footprint in the country as it looks to build out service infrastructure.

    Tesla faces third-quarter financial results in the coming days, where Wall Street will review vehicle delivery numbers, automotive gross margins, and spending on autonomous software.

  • H Mart Names 6 Food Court Restaurants for South Sacramento Store

    H Mart Names 6 Food Court Restaurants for South Sacramento Store

    Earlier this month, H Mart named six restaurant tenants planned for the food court inside its upcoming South Sacramento supermarket at 6366 Mack Road.

    First announced in 2023, the location has experienced construction delays, and spokesperson April Lee stated that an official opening date has not yet been determined.

    The confirmed dining roster includes Oh K-Dog & Egg Toast, Dduk Dabang, Paik’s Noodle, Ippin Teriyaki & Katsu, Daeho Kalbijjim and BB.Q Chicken, bringing South Korean franchises and regional Asian concepts together under one roof.

    The Food Hall Lineup

    Paik’s Noodle brings a network of 36 US locations to the Sacramento site. The concept focuses on Korean-style Chinese staples. Dishes include black bean sauce jajangmyeon and seafood-loaded jjamppong noodle soup in a spicy red pork broth.

    BB.Q Chicken will offer sauced and boneless chicken dishes, ranging from mild golden original recipes to gochujang-based wings of fire. Snack chain Dduk Dabang will sell toppoki rice cake bowls, ramyun and fried chicken. Oh K-Dog provides Korean hot dogs breaded in panko, potato cubes and squid ink.

    Daeho Kalbijjim will prepare traditional braised beef short ribs and bone broths, drawing on historic Joseon Dynasty recipes. Japanese operator Ippin Teriyaki & Katsu rounds out the roster with breaded cutlets and rice plates.

    Grocer Strategy and Regional Competition

    Asian supermarket operators in North America increasingly rely on branded food halls to generate foot traffic and extend dwell time beyond routine grocery runs. Grocers now partner directly with established Asian restaurant brands that carry dedicated followings rather than leasing space to generic cafeteria vendors.

    For South Korean retail groups and franchise operators, grocery partnerships provide immediate customer flow without standalone real estate overhead. The model also cuts buildout risk. Operators share utility infrastructure and central seating areas with the primary retail tenant.

    Project Timeline and Delays

    H Mart first selected the South Sacramento site in 2023 to expand its footprint in Northern California outside the San Francisco Bay Area. Construction complications delayed the buildout over the past three years, pushing back the operational launch.

    Spokesperson April Lee said the company has not finalized an official public opening date for the Mack Road store. Contractors continue work on the interior store layout and food court stalls ahead of final municipal inspections.

  • Philippine Cash on Delivery Share to Stay Above 20 Percent Through 2027

    Philippine Cash on Delivery Share to Stay Above 20 Percent Through 2027

    Cash on delivery will account for more than 20 percent of Philippine e-commerce transactions through 2027. That keeps the country as Southeast Asia’s most cash-reliant online shopping market, according to payments gateway Xendit.

    Physical cash currently represents 23 percent of online transaction value on Xendit’s Philippine platform. That figure outstrips all five other Southeast Asian markets surveyed in its joint report with market research firm Cube.

    Across Southeast Asia, cash on delivery is projected to fall below 25 percent of total e-commerce gross merchandise value next year. The Philippines will remain the only major regional market where paper currency holds over a fifth of checkouts.

    Cash Holds 23 Percent Share

    A persistent unbanked population, limited formal credit, and fear of delivery fraud slow the shift away from cash. In a survey of 6,000 online shoppers across six regional markets, including 1,000 in the Philippines, 12 percent of Filipino buyers said nothing would convince them to stop using cash on delivery. That group is double the size seen in neighboring countries.

    Shopper habits are shifting at the margin. About 33 percent of surveyed Philippine consumers reported using cash on delivery less frequently than a year ago. Discounts and cashback offers prompt them to try digital alternatives. Long-term retention still requires fast refunds and fraud protections.

    “Looking ahead, across the whole Southeast Asia, COD payments will actually fall below 25 percent of all e-commerce payments, but the Philippines will still probably be one of the fewer markets that are going to be above 20 percent,” said Ina Gatan, head of go-to-market at Xendit Philippines.

    QR Ph and Bank Transfers Surge 198 Percent

    Account-to-account payments are capturing what physical cash loses. Transaction volume settled via QR codes and direct bank transfers increased 198 percent between January 2025 and April 2026 across Xendit’s merchant network.

    National payment rails QR Ph and InstaPay drove the surge. QR Ph alone processed roughly 13 percent of total Philippine e-commerce value on the platform during the period. The standard lets merchant QR codes take payments across competing banking apps and digital wallets without custom point-of-sale setups.

    Digital wallets grew by 3 percent over the same 16-month timeframe. E-wallets already dominate Philippine digital checkouts. That leaves little room for rapid percentage gains compared to account-linked instant clearing schemes.

    Cross-Border Retail Lags Regional Neighbors

    Reliance on cash creates an operational barrier for international merchants selling into the country. Cross-border purchases represented only 9 percent of total Philippine online retail volume in 2026. Only Indonesia recorded a lower share at 6 percent.

    Higher digital adoption elsewhere fuels international orders. Cross-border sales accounted for 19 percent of online retail in Singapore, 15 percent in Thailand, 14 percent in Vietnam, and 12 percent in Malaysia. Foreign sellers rarely accept cash on delivery because of return logistics risks. That shuts uncarded Philippine consumers out of international storefronts.

    Southeast Asian cross-border e-commerce is projected to expand between 11 and 19 percent annually through 2030, assuming regional instant payment linkages and customs procedures improve. Merchants relying purely on upfront card or wallet payments will miss a fifth of Philippine demand until alternative rails provide instant buyer protection.

    Roadblocks to Digital Settlement

    Handling cash on delivery imposes heavy costs on logistics providers and retailers. Couriers face higher failed-delivery rates, delayed settlement cycles of up to seven days, and cash-handling risks that drive up freight rates across the archipelago.

    Couriers and platforms have introduced OTP verification at delivery and partial advance deposits to curb return rates. Even so, Valerie Cai, head of marketing at Xendit, estimated that bringing the Philippine cash-on-delivery ratio below 20 percent will require several years of sustained infrastructure rollouts.

    Total Southeast Asian e-commerce merchandise value reached $197 billion in 2025, up from $3 billion in 2012, with Cube forecasting the market to pass $400 billion by 2031. The pace of payment digitization across the Philippine archipelago will determine how much of that regional growth turns into merchant profit rather than delivery losses.

  • Ericsson Bets on AI Traffic and 550 Million 5G Users to Drive India Growth

    Ericsson Bets on AI Traffic and 550 Million 5G Users to Drive India Growth

    Ericsson expects artificial intelligence applications and rising monthly data traffic to fuel a second wave of network investment in India, where 5G subscribers reached 550 million by September 2026.

    Monthly data consumption across Indian networks has climbed to between 36 and 37 gigabytes per user, according to company figures presented at the India Mobile Congress in New Delhi.

    The Swedish telecom equipment vendor is seeking fresh revenue after the rapid initial rollout of fifth-generation mobile infrastructure cooled. India accounted for 12 percent of Ericsson’s regional business covering South East Asia, Oceania, and India in 2025, down from 20 percent in 2023 during the peak of initial carrier deployments.

    Network Capacity Over Pure Consumer Use Cases

    Indian operators deployed 5G across 99.9 percent of the country’s districts in less than four years, making it one of the fastest national buildouts globally. The buildout occurred primarily because carriers needed immediate spectrum efficiency and radio capacity rather than waiting for specialized consumer applications.

    Nitin Bansal, managing director for India and head of networks for South East Asia, Oceania, and India at Ericsson, noted that 5G currently reaches roughly one-third of the country’s population. He argued that shifting directly to 5G rather than expanding older 4G infrastructure provided the necessary capacity to handle escalating consumer usage.

    Direct monetization remains the chief challenge for telecom operators Bharti Airtel and Reliance Jio. Both carriers spent heavily on spectrum auctions and radio deployments starting in late 2022 and are now pushing higher-margin services to improve average revenue per user.

    Fixed Wireless and Enterprise Slicing

    Fixed Wireless Access has become the fastest monetization channel for Indian network operators looking to bypass fixed-line broadband delays. Data from the Telecom Regulatory Authority of India showed 13.45 million 5G FWA subscribers active at the end of August 2026.

    Service differentiation is shifting toward premium enterprise and high-tier retail customers. Bharti Airtel introduced commercial 5G network slicing, carving out dedicated network resources to provide guaranteed speeds and lower latency to postpaid retail subscribers.

    For equipment vendors including Ericsson, Nokia, and Samsung, these software-defined features generate recurring software licensing fees rather than purely hardware-driven revenue.

    Artificial Intelligence Shifts Network Requirements

    Emerging artificial intelligence workloads on mobile devices are changing baseline infrastructure demands across Asian markets. Generative AI tools and spatial computing applications require heavy uplink capacity and reduced latency, forcing operators to tune cell sites that were originally configured primarily for downlink video streaming.

    Ericsson expects carriers to reconfigure their 5G standalone cores to handle automated traffic management and machine-learning compute loads. Critical infrastructure monitoring and industrial automation in manufacturing hubs around Pune, Chennai, and Gujarat are also pulling private 5G deployments into commercial operation.

    Vendors face pressure to prove these upgrades deliver real cost savings. Indian telecom operators operate with some of the lowest tariffs in the world, leaving slim margins for speculative infrastructure spending without clear returns.

    Targeting One Billion Subscribers by 2030

    India launched commercial 5G services in October 2022 and has since become one of the two largest mobile data markets alongside China. The central government has set an official target of one billion 5G subscribers by 2030.

    Meeting that target requires converting roughly 450 million additional mobile users from legacy 4G and 2G connections over the next four years. That conversion will hinge on the availability of entry-level 5G smartphones priced below 8,000 rupees, alongside wider rural cell coverage where standalone economics remain tight.

  • Huat Lai Launches Five Frozen Poultry Products Under Little Farmer Brand

    Huat Lai Launches Five Frozen Poultry Products Under Little Farmer Brand

    Huat Lai Resources Berhad launched Little Farmer in Malaysia in October 2026, entering the retail frozen poultry category with five value-added chicken products processed from its domestic farming network.

    The company is Malaysia’s largest supplier of Certified Humane cage-free eggs and one of the country’s biggest integrated poultry producers, giving the new consumer label immediate upstream supply support.

    The Initial Five-Product Retail Lineup

    Little Farmer debuts with Shiok Mamak Drumettes, standard Chicken Drumettes, Japanese Crispy Chicken Bites, Tempura Nuggets, and Tempura Nuggets Smokey Cheese. The lineup targets home cooks and quick-meal shoppers through supermarket freezer aisles, carrying the sub-brand tagline “Farm Goodness by Huat Lai”.

    Packaging across the range highlights “Nenek Approved” branding alongside the producer’s farm heritage. The push takes Huat Lai directly into value-added, packaged processed meats, a segment that commands higher margins than wholesale fresh broilers and commodity table eggs.

    Value-Added Processing vs Commodity Poultry

    Upstream livestock producers across Southeast Asia face steady margin pressure from volatile feed grain imports and local retail price controls on standard fresh chicken. Moving into cooked and breaded frozen meats lets producers capture processing margins that commodity wholesale contracts do not provide.

    Retail buyers in Malaysia have allocated more freezer space to local, halal-certified processed foods as shoppers look for convenient meal options. Little Farmer enters a competitive shelf already contested by established regional brands, meaning shelf velocity and distribution reach will matter more than brand heritage alone.

    Farm Integration and Certification History

    Huat Lai built its market position as an early adopter of commercial cage-free egg facilities in Southeast Asia, securing third-party animal welfare certification for its layer operations. That farming scale provides complete traceability for its meat processing lines.

    Controlling feed, breeding, and processing under one corporate umbrella protects product consistency across the new retail line. It also allows Huat Lai to absorb wholesale supply fluctuations that pure-play food packagers must buy through open contracts.

    Retail Expansion to Watch

    The company is deploying Little Farmer across Malaysian grocers and modern trade outlets through the final quarter of 2026. Store distribution numbers and potential category extensions into raw chilled cuts will determine how much supermarket market share the brand takes in 2027.

  • Baemin and Coupang Eats Target Olive Young with 30-Minute Beauty Runs

    Baemin and Coupang Eats Target Olive Young with 30-Minute Beauty Runs

    South Korean food delivery platforms Baemin and Coupang Eats are now dispatching couriers with discount cosmetics in roughly 30 minutes. They are using local retail store networks to beat market leader CJ Olive Young on speed.

    Baemin added warehouse outlet chain Off Beauty to its app last week. The partnership covers roughly 4,000 products shipped from 30 outlets across Seoul, Busan and other major cities. Orders arrive faster than Olive Young’s average 55-minute express tier.

    How the Off Beauty Model Works

    Off Beauty buys surplus manufacturer stock, cosmetics in pre-redesign packaging, and near-expiry goods directly from brand owners. This supply chain keeps shelf prices low. In turn, it gives delivery apps a catalog of deeply discounted goods.

    In June, Coupang Eats listed Off Beauty with free delivery for its Coupang Wow subscribers. The discount chain runs about 50 stores today and plans to reach 100 nationwide. That expansion will give couriers more local pickup hubs across metropolitan areas.

    Filling the Gaps Between Meal Orders

    Food delivery platforms suffer predictable order slumps between the lunch and dinner rushes. Cosmetics orders flow in steadily throughout the day. These purchases smooth out rider demand during quiet hours without requiring cold storage or fast expiration controls.

    For couriers, makeup items are light and compact compared to hot meals or grocery bags. Fulfilling a lipstick or moisturiser order costs the same as delivering lunch. Crucially, the inventory does not spoil if a rider hits traffic.

    Taking on the Olive Young Monopoly

    Online channels generated 41.4 percent of South Korea’s cosmetics sales last year, according to government data. CJ Olive Young booked 2.94 trillion won ($2.2 billion) in first-half revenue across its online and offline operations. That gave the chain a 21.5 percent share of the country’s 13.72 trillion won beauty market.

    Back in 2018, Olive Young launched its Oneul Deurim three-hour delivery service from 1,360 stores and urban logistics centres. The service handled 19.35 million orders last year. It also drove nearly half of Olive Young’s total shipments in the first half of this year.

    Mounting Rivalry Across Platforms

    Rapid 30-minute delivery changes the battleground for specialist retailers. Olive Young relies on curated selections, ingredient advice, and AI skin diagnostics. Delivery apps are betting that lower prices and instant drop-offs will win impulse shoppers instead.

    Pressure is building from outside the food delivery sector as well. Other non-traditional competitors are eating into beauty sales across Korea. Online grocer Market Kurly, discount chain Daiso, and fashion marketplace Musinsa, which is opening dedicated beauty flagships, are all chasing market share.

    Whether Baemin and Coupang Eats can take 30-minute cosmetics delivery beyond major hubs hinges on Off Beauty hitting its 100-store target across provincial cities.