Author: Mei Ling Tan

  • Australian Halloween Spend to Hit $510 Million as Shopper Numbers Drop

    Australian Halloween Spend to Hit $510 Million as Shopper Numbers Drop

    Australians will spend 510 million Australian dollars on Halloween costumes, decorations and confectionery this year, according to joint research from the Australian Retail Council and Roy Morgan.

    Total spending will edge up 2 per cent from 500 million dollars last year, trailing domestic inflation even as individual celebrants plan to spend more cash per basket.

    Around 4.4 million Australians plan to celebrate Halloween personally or through their children, down by 400,000 from 2025. National participation dropped to 18 per cent compared to 21 per cent twelve months ago. Those who do take part plan to spend an average of 117 dollars each, a 13.6 per cent increase of 14 dollars on last year.

    Higher prices offset shrinking crowds

    The spending expansion reflects elevated retail prices rather than organic volume growth across checkout counters. Household budgets remain squeezed by sustained borrowing costs and elevated utility bills across metropolitan and regional centres. Among respondents planning to celebrate, 62 per cent said they will keep outlays flat, 22 per cent plan to reduce spending, and 16 per cent plan to spend more.

    Participation split across gender lines shows 2.4 million women and 2 million men planning to mark the event, with both groups shrinking by 200,000 participants compared to 2025.

    Fleur Brown, chief industry engagement officer at the Australian Retail Council, pointed to broader household financial strains. “Those taking part plan to spend more on average, but fewer Australians are joining in this year,” Brown said.

    Young adults drive costume spend

    Younger shoppers between 18 and 34 years old represent the largest demographic cohort participating in the event. This group will spend an average of 134 dollars per person, generating approximately 200 million dollars in gross retail sales.

    Older demographics pulled back sharply. Participation among consumers aged 65 and over dropped six percentage points to 15 per cent. Engagement among shoppers aged 35 to 49 remained steady at 20 per cent, anchored by primary school children and family neighbourhood activities.

    State breakdown and category demand

    Geographic breakdowns show distinct divergences in consumer willingness to spend across eastern seaboard states. Victoria leads the country with the highest projected average spend at 136 dollars per person. Queensland follows at 120 dollars, while New South Wales trails at 109 dollars per person. Together, these three states account for 410 million dollars of total seasonal turnover, up 20 million dollars from last year.

    Merchandise demand concentrates heavily in consumable goods and short-use apparel. Providing treats for trick-or-treaters ranks as the top activity, cited by 45 per cent of participants, followed by dressing in costumes at 44 per cent. Door-to-door trick-or-treating accounts for 40 per cent of consumer plans, while 35 per cent plan to buy home decorations.

    Retail margins ahead of peak season

    For supermarket chains, discount department stores and specialty party suppliers, Halloween operates as the primary operational test run before the critical November Black Friday sales and Christmas peak trade. A Saturday timing provides logistics networks and brick-and-mortar stores clear foot-traffic opportunities, but compressed basket counts raise margin risks for retailers carrying excess themed inventory.

    The benchmark data stems from an SMS survey of 5,237 Australians aged 18 and older conducted between September 29 and October 3, 2026, sampling 877 active Halloween consumers. Merchants now look to inventory sell-through rates across October 31 to gauge consumer price tolerance ahead of final pre-Christmas stock orders.
  • OpenAI Seeks 30 Billion Dollar Round Ahead of Anthropic Public Listing

    OpenAI Seeks 30 Billion Dollar Round Ahead of Anthropic Public Listing

    OpenAI is seeking to raise about $30 billion at a valuation exceeding $1.4 trillion. It plans to close the deal before rival Anthropic lists its shares in mid-November.

    The fast-tracked funding round would give the ChatGPT developer fresh private capital. It would also cut off investor cash flows destined for Anthropic’s public market debut.

    SoftBank Group, Abu Dhabi investment vehicle MGX and other existing shareholders are in active discussions to take part. Talks have moved quickly. They follow meetings OpenAI held with sovereign wealth funds and long-only institutions in mid-October. That push coincided directly with Anthropic’s own institutional investor presentations in New York.

    Rushing to Price Private Equity

    Frontier artificial intelligence labs are competing for a narrow group of institutional allocators. Few funds have deep enough pockets to back trillion-dollar balance sheets. By pricing a private round now, OpenAI can lock in multi-billion-dollar allocations. Otherwise, those budgets could go to Anthropic’s IPO order book.

    Private capital also insulates OpenAI if broader equity turbulence pushes its target 2027 listing date further back. Huge compute commitments require continuous cash injections. Data center buildouts demand heavy upfront hardware prepayments. Raising privately lets the company set terms without facing quarterly public market scrutiny.

    Asian technology investors and institutional funds face a sharp split in capital allocation. SoftBank and Gulf sovereign funds have poured tens of billions into Western foundation models. Debt burdens across AI infrastructure providers are prompting stricter risk assessments. If private valuations outpace public multiples, later-stage backers risk holding illiquid shares priced well above what public markets will tolerate.

    Revenue Claims and Accounting Disputes

    OpenAI pitched prospective investors on expanding revenue following the rollout of its GPT-6 Astra model. Annualized revenue hit $50 billion. The company expects that run rate to reach $70 billion by the end of the year.

    To support adoption, the lab cut prices on smaller models and told investors it intends to reduce inference costs further. In contrast, Anthropic reported third-quarter revenue of $16.8 billion, up from $11.6 billion in the second quarter. It reached an annualized run rate of roughly $65 billion by July. Slower month-to-month growth has led some pre-IPO investors to push Anthropic’s valuation down toward $1.5 trillion, below an earlier $2 trillion target.

    Accounting methodologies remain a primary friction point between both camps. OpenAI calculates revenue on a net basis after deducting partner shares. It claims Anthropic inflates top-line figures by booking gross sales processed through cloud distribution partners. Anthropic maintains that its revenue reporting strictly follows standard accounting rules.

    “OpenAI could want to set its own valuation and not have to worry about a comp (comparison),” said Edward Best, co-chair of capital markets at Willkie Farr & Gallagher. “It’s really a two-horse race in terms of being public.”

    Infrastructure Costs Rattling Public Markets

    Heavy spending on AI infrastructure is rattling public exchanges. The Philadelphia Semiconductor Index lost $1.6 trillion in market capitalization in October. Debt-heavy cloud suppliers have faced steep sell-offs.

    Specialized cloud provider CoreWeave saw its debt and equity drop after investors questioned nearly $50 billion in borrowings tied to data center expansion. That volatility has halted listings across the technology sector. Nuclear power developer Holtec withdrew its US offering in September. Blackstone-backed AirTrunk REIT, Nvidia-backed Firmus and SoftBank-backed SB Energy have all postponed or abandoned planned market debuts.

    Valuation Escalation Since March

    In March, OpenAI raised a record $122 billion round that valued the business at $852 billion. That transaction included a commitment of up to $50 billion from Amazon.

    Anthropic now heads into its November listing window while managing investor feedback on third-quarter growth metrics. OpenAI aims to wrap its $30 billion private round before those public regulatory filings reveal full comparative numbers across both balance sheets.

  • VinFast Cuts Net Loss to $56 Million on Factory Disposals

    VinFast Cuts Net Loss to $56 Million on Factory Disposals

    VinFast narrowed its net loss to $56 million in the second quarter of 2026 after booking a $1.18 billion gain from selling its Vietnam factories.

    Operating losses from continuing operations rose 48 per cent from the previous quarter to $1.24 billion. The carmaker delivered 70,085 electric vehicles during the three-month period, bringing first-half deliveries to 43 per cent of its full-year target of 300,000 units.

    Factory Disposals and Debt Offloading

    The accounting relief stems from a broader balance-sheet overhaul. VinFast sold its two primary assembly plants in Vietnam and transferred $7 billion in debt to entities linked to parent company Vingroup and its founder, Pham Nhat Vuong.

    Vehicles will continue rolling off those domestic lines under long-term contract manufacturing agreements matching company specifications. The restructuring shifts heavy fixed capital off the carmaker’s books while keeping production flowing without direct factory ownership.

    Chief executive Pham Nhat Quan Anh, who took over leadership last month from his father, defended the transition toward an asset-light operating model during his debut analyst call.

    “We continue to hold and operate our plants in India and Indonesia, supporting local production,” Quan Anh said.

    Domestic Reliance and Asian Expansion

    Home-market buyers continue to absorb almost all output. Vietnam accounted for 89 per cent of deliveries in the second quarter, leaving overseas volumes heavily reliant on affiliate fleet deployments rather than direct consumer sales.

    Green SM, the taxi operator established by Vuong that runs exclusively on VinFast vehicles, serves as the primary distribution channel across new territories. The fleet operator expanded into Jakarta with motorbike services and launched operations in India, establishing initial vehicle volume ahead of retail dealer networks.

    Management identified Indonesia, India, and the Philippines as the core drivers for foreign market growth. Keeping physical factories in India and Indonesia allows the company to meet local manufacturing requirements while ducking heavy import duties in high-potential Asian markets.

    Pivot Away From Western Assembly

    The Asian focus follows severe friction in Western markets where direct sales and manufacturing stalled. North Carolina state authorities filed a lawsuit against the carmaker over missed construction deadlines and unmet job creation targets at its proposed US assembly site.

    Direct consumer demand in North America remains weak. Green SM recently launched taxi operations in Los Angeles to put vehicles on roads after private retail sales failed to gain traction, though the company plans to introduce its VF7 compact SUV and electric buses to US dealers later this year.

    Chief investment officer Chien Nguyen indicated that further expansion into the Americas and Europe remains under review, with details expected in the third quarter.

    Targets for the Second Half

    Meeting the annual 300,000-vehicle delivery target will require more than 170,000 handovers across the final six months of 2026. That push depends on ramping up the new VF Wild REEV, a range-extended electric pickup incorporating a backup combustion generator to alleviate range anxiety in developing markets.

    VinFast must now prove whether its asset-light manufacturing setup and captive taxi orders can generate real cash flow once the one-off financial gains from factory sales clear off the ledger.

  • National Australia Bank to Cut 2,500 Jobs as Lending Slows

    National Australia Bank to Cut 2,500 Jobs as Lending Slows

    National Australia Bank will cut up to 2,500 jobs across its corporate operations in 2027 to lower operating costs as loan demand weakens. The reduction represents roughly 6 percent of the lender’s global workforce.

    Up to 1,500 positions will disappear by the end of 2026. The lender plans to spare customer-facing branch and banking roles while heavily reducing its reliance on outside consultants and contractors.

    The Cost of the Corporate Overhaul

    The restructuring will trigger a pre-tax charge of about A$300 million in 2027. That covers redundancy payouts, redeployment programs, and internal reorganisations. For comparison, pre-tax restructuring charges stood at about A$80 million in each of 2025 and 2026.

    Chief executive officer Andrew Irvine said the changes were aimed at improving productivity, risk outcomes and execution, while making the bank “simpler and more efficient”. NAB reported a total global headcount of 41,880 employees on September 30, 2025.

    Lenders Squeezed by Weakening Loan Demand

    Commercial lenders across Australia face compressed margins as property sales cool and domestic borrowers pull back under elevated borrowing costs. The retrenchment at NAB mirrors steps taken across the Australian financial sector, where institutions are shedding corporate overhead to protect returns on equity.

    Rival ANZ launched its own simplification drive under chief executive Nuno Matos last year, cutting roughly 3,500 roles through September 2026. Both lenders are eliminating administrative layers while trying to preserve frontline lending desks to defend their market share in core commercial accounts.

    Tax Changes and Higher Rates Hurt Housing

    In August, NAB cautioned that residential mortgage growth would decelerate sharply into 2027. Federal property tax revisions reduced buyer appetite, discouraging both owner-occupiers and property investors from taking on new debt.

    Higher domestic cash rates combined with broader geopolitical tensions have created sustained headwinds for retail and business borrowers. Management aims to redeploy cost savings directly into business lending, deposit acquisition, and its proprietary residential mortgage platform.

    Key Targets for the 2027 Deadline

    NAB faces the task of executing the initial 1,500 departures before December 2026 without disrupting risk controls or loan processing times. Progress on contractor reductions and operating expense targets will show in the bank’s upcoming financial disclosures through late 2026.

  • Gen Z Shoppers Drive Twofold Surge in Korean Beauty Orders on Myntra

    Gen Z Shoppers Drive Twofold Surge in Korean Beauty Orders on Myntra

    Gen Z shoppers accounted for 55 per cent of Myntra’s beauty growth over the past year, driving a 200 per cent surge in Korean beauty orders and a 78 per cent increase in men’s skincare.

    Spend per customer within the 14-to-29 age bracket climbed 1.2 times year on year, while repeat purchases among these buyers rose roughly 70 per cent, according to data from the Bengaluru-based e-commerce platform.

    The findings, drawn from order data between August 2025 and August 2026, show younger consumers allocating 75 per cent more of their personal care wallet to beauty compared with millennial shoppers. Beauty and personal care now accounts for approximately one in every five units shipped across the marketplace. Myntra expects Gen Z to generate more than half of its beauty customer base over the next three years.

    Active Ingredients and Smaller Regimens

    Younger shoppers are consolidating their daily routines while demanding clinical formulations. Around 80 per cent of Gen Z buyers limit their daily regimen to three products, and 30 per cent buy only one or two items per order. Sales of ingredient-focused derma products climbed 75 per cent, led by targeted searches for active ingredients including Centella asiatica, copper peptides, azelaic acid and panthenol.

    Sun protection has shifted into a year-round staple rather than a seasonal purchase. Orders for sun protection products rose 60 per cent year on year among younger shoppers. Searches for sunscreen sprays increased 80 per cent, ingredient-led formulations rose 70 per cent, and tinted sunscreen varieties climbed 60 per cent, with consumers favouring gel-based and fragrance-free textures.

    Haircare orders reflect a similar turn toward treatments over basic cleansing. Demand for hair masks jumped 110 per cent, outpacing conditioners at 59 per cent growth. Searches for scalp serums rose 50 per cent, dry shampoo searches gained 68 per cent, and styling appliances grew 55 per cent.

    Regional Demand and Premium Sample Formats

    Tier II and tier III cities now generate half of all Gen Z beauty purchases on the platform and account for half of total international brand orders. Urban centres such as Ludhiana, Patna, Bhopal, Indore, Guwahati, Surat, Varanasi and Imphal are driving category expansion. The northeastern states recorded particularly strong volume in masstige and prestige makeup, alongside rising appetite for gourmand fragrances in smaller cities.

    Entry into prestige brands is increasingly happening through travel and trial sizes. Approximately 53 per cent of luxury makeup transactions include a miniature format, representing 14 per cent of all luxury units sold. Prestige labels including M.A.C, Kayali, Smashbox and Salvatore Ferragamo now secure more than half of their new customer acquisitions through mini formats.

    Men’s grooming has expanded beyond basic shaving supplies. Total men’s grooming orders climbed 70 per cent so far in fiscal 2026, while fragrance purchases rose 50 per cent. Among Gen Z men, fragrance demand increased 60 per cent, with bundled gift sets up 125 per cent.

    Catalogue Scale and Fast Fulfilment

    To capture demand, Myntra added more than 30 Korean brands over the past 12 months, taking its K-Beauty catalogue past 1,000 stock keeping units across 90 labels. Platform searches for Korean skincare and cosmetics rose more than 300 per cent over the same period.

    Direct-to-consumer brands are also taking market share. The platform’s domestic portfolio covers 700 dedicated D2C brands and 3,000 emerging labels, with the segment growing 68 per cent in the current fiscal year. Gen Z shoppers proved 25 per cent more likely to purchase an indigenous or D2C product than older demographics.

    Speed of delivery is becoming a decisive channel differentiator. The marketplace’s quick-commerce arm, M-Now, stocks roughly 600 beauty brands, including 107 foreign labels. The rapid delivery service recorded its peak order value at Rs 61,750, with beauty volumes concentrating heavily between 11 am and 2 pm.

    Room for Market Growth

    India’s overall beauty and personal care market is projected to expand from $23 billion to $40 billion over the medium term. Annual per-capita spending on beauty in India stands at approximately $15, compared with $38 in China and $383 in the United States.

    For multi-brand retailers and beauty platforms, the immediate battle lies in capturing younger consumers outside the major metropolitan areas before regional retail chains or dedicated beauty specialists establish physical footprints there. Brand discovery has largely shifted to social channels, where Myntra maintains an active roster of 82,000 beauty creators and saw user-generated content increase 40 per cent year on year.

    Myntra is targeting M-Now to fulfill more than 50 per cent of total beauty order volume in cities where the rapid delivery service currently operates.

  • Bursa Malaysia Edges up to 1,596 Points on Bank Gains

    Bursa Malaysia Edges up to 1,596 Points on Bank Gains

    Bursa Malaysia’s benchmark index edged up 0.36 points to 1,596.11 in early Tuesday trade as gains in heavyweight commercial lenders offset broad weakness across secondary counters.

    The marginal 0.02 per cent advance recovered an opening drop of 3.18 points to 1,592.57, though decliners outpaced advancers 201 to 156 across the broader exchange. Morning volume reached 180.64 million units worth RM90.02 million.

    Trading remained divided between domestic financial counters and export-oriented industrial names. Investors tracking Wall Street overnight gains looked for traction following a 1.11 per cent rise in the Nasdaq Composite and a 0.41 per cent lift in the S&P 500, where buyers returned to artificial intelligence semiconductor and memory hardware producers. That overseas bounce failed to spark a broad rally in Kuala Lumpur, where 302 counters traded unchanged and ten remained suspended.

    Lenders and Consumer Stocks Hold the Line

    Large commercial banks provided the primary support for the headline index during early exchanges. Malayan Banking added four sen to trade at RM9.94, Public Bank picked up one sen to RM4.72, and CIMB Group rose two sen to RM7.17. Hong Leong Bank held steady at RM21.10. Those advances lifted the Financial Services Index by 55.25 points to 18,546.22.

    Consumer and industrial heavyweights also found buyers. Food manufacturing major Nestle climbed 40 sen to RM90.30 to lead the top gainers list. Energy shipper MISC advanced 14 sen to RM9.49, refiner Petron Malaysia added 11 sen to RM3.45, and aluminum producer Press Metal gained five sen to RM6.73.

    Selling pressure hit utilities and infrastructure names, capping the index’s upward room. Tenaga Nasional dropped six sen to RM12.92, while YTL Power slipped five sen to RM5.21.

    Yield Pressure Weighs on Tech and Construction

    Elevated fixed-income yields in the United States continued to cast a shadow over rate-sensitive regional assets. The US 10-year Treasury yield held near 5.15 per cent while the 30-year yield stood around 5.48 per cent, keeping capital cautious toward emerging market equities.

    Technology equipment and assembly counters saw selective selling despite the overnight recovery in US chip stocks. Automated test equipment supplier KESM dropped 15 sen to RM4.54, and engineering solutions group UWC gave up nine sen to RM7.21. In building materials and construction, Kerjaya Prospek shed 10 sen to RM3.22, while ceramic tile manufacturer Kim Hin lost 8.5 sen to 80.5 sen.

    Apex Securities noted the split in investor sentiment as global interest rate pressures collided with domestic capital allocations.

    “the FBM KLCI is likely to trade within a range, with investors remaining selective and favouring domestically driven and defensive counters,”

    the brokerage said.

    Sector Divergence Deepens Across Secondary Boards

    Broader market gauges drifted lower as mid-cap and Shariah-compliant equities failed to mirror the banking index. The FBM Emas Index dipped 1.31 points to 11,908.38, while the FBM Top 100 Index fell 1.18 points to 11,704.04. The mid-cap FBM Mid 70 Index declined 17.71 points to 17,116.03, and the FBM ACE Index eased 1.58 points to 5,391.71.

    Shariah counters faced heavier selling, pulling the FBM Emas Shariah Index down 13.83 points to 11,860.36. The Plantation Index dropped 62.97 points to 8,590.4. In contrast, the Energy Index added 1.67 points to 825.23, supported by global crude prices trading near US$100 per barrel, while the Industrial Products and Services Index crept up 0.40 points to 174.5.

    Speculative retail counters dominated trading volume without driving major index shifts. GIIB rose 1.5 sen to 70.5 sen, and Ni Hsin picked up one sen to 45.5 sen. Zetrix AI and OCR stayed flat at five sen and 4.5 sen, respectively. Medical glove producer Top Glove eased half a sen to 88.5 sen, and healthcare firm LYC fell one sen to half a sen.

    Domestic Defensives Face Real Estate Headwinds

    The morning session shows institutional funds directing liquidity into large-cap balance sheets while avoiding debt-funded expansion plays. In retail, commercial development, and logistics, property developers and real estate investment trusts face higher borrowing costs because US long-term yields remain elevated above 5 per cent.

    Construction contractors linked to hyperscale data center infrastructure maintain a separate stream of domestic order book momentum. Yet the broader real estate ecosystem is operating with tighter capitalization spreads, leaving consumer staples and cash-generative banking operations as the primary defensive refuge for local asset managers.

    Market participants are now watching whether benchmark crude can maintain the US$100 per barrel threshold to support domestic energy counters, while keeping a close eye on the 1,600 psychological barrier for the FBM KLCI.

  • Lactasoy Launches 19G Benefitt Plant Protein Drink in Thailand

    Lactasoy Launches 19G Benefitt Plant Protein Drink in Thailand

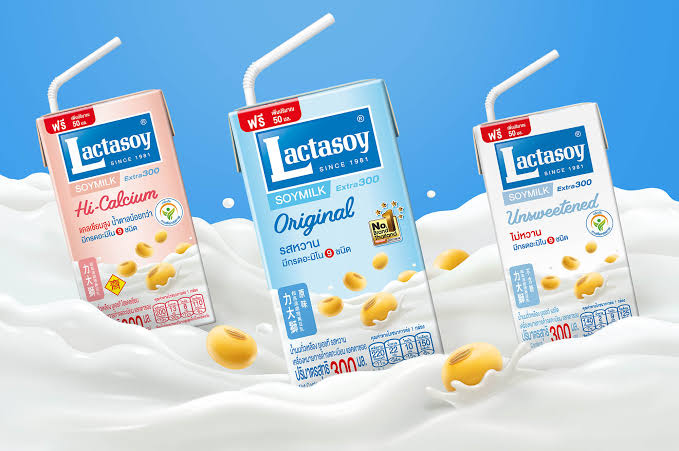
    This week, Lactasoy Co., Ltd. Introduced Benefitt Plant-Based Hi Protein Original in Thailand, delivering 19g of protein in each 250ml carton. Sourced from a blend of soy and pea protein, the beverage is designed for health-conscious consumers seeking a convenient source of high-quality protein.

    Packaged in single-serve cartons, the product is formulated to support muscle health. It expands Lactasoy’s Benefitt soy milk brand into high-density plant protein.

    Formulating for protein density

    Combining soy and pea proteins gives the beverage a broader amino acid profile than standard single-source soy drinks. Delivering 19 grams in a 250ml carton matches levels typically found in dairy whey RTD beverages.

    Single-serve cartons also lower entry barriers for casual fitness consumers who want functional nutrition without mixing powders. That format fits convenience store chillers, where grab-and-go purchases drive daily RTD beverage volume.

    Shifting RTD dairy alternatives

    Thailand’s packaged soy milk sector has long relied on entry-level, sweetened staples sold in volume. Higher ingredient costs and shifting dietary preferences are pushing manufacturers toward functional, premium formulations with explicit health claims.

    Lactasoy is shielding its retail margins by creating dedicated sub-brands like Benefitt. High-protein claims command higher retail price points than commodity soy milk, protecting profitability as baseline ingredient costs fluctuate.

    Retail shelf competition

    Competition in Southeast Asian functional beverages is concentrating in modern trade chillers. Traditional soy brands now face dedicated fitness RTDs, imported oat milk brands, and local plant-based innovators fighting for refrigerated shelf space.

    Suppliers must balance taste and viscosity against higher protein concentrations. Chalky textures and bitter plant notes often deter repeat buyers, making formulation execution decisive for category retention.

    What operators will watch

    Convenience operators and hypermarkets will track whether high-protein plant beverages can build repeat demand beyond dedicated gym-goers. Retail distribution execution across convenience store networks will determine initial sales velocity.

    Reorder rates over the first two quarters will show whether the 19g protein blend can establish Benefitt as a regular purchase or remain a niche alternative on Thai shelves.

  • AmCham Pledges $5 Billion as Bangladesh Seeks US Healthcare Tie-Up

    AmCham Pledges $5 Billion as Bangladesh Seeks US Healthcare Tie-Up

    Bangladesh is courting US medical device makers for local assembly and technology transfer, backed by a national healthcare budget of roughly Tk 70,000 crore. The push aims to draw multinational manufacturers deeper into domestic supply chains rather than relying purely on direct imports.

    State Minister for Health and Family Welfare MA Muhit presented the proposal during an industry roundtable in Dhaka organised by the American Chamber of Commerce in Bangladesh in October 2026. AmCham President Syed Mohammad Kamal highlighted over $5 billion in existing investments and pledged to facilitate another $5 billion over the next five years.

    What Dhaka Wants from US Tech Providers

    Government officials want overseas suppliers to set up local assembly plants, train Bangladeshi engineers, and support equipment across its entire lifecycle. The initiative targets technical institutions including Bangladesh University of Engineering and Technology and the University of Dhaka to build domestic servicing capacity.

    Dhaka is also preparing a national digital monitoring dashboard and e-health system to track how state hospitals use medical machinery. Muhit told company executives that procurement must shift toward transparent contracts and structured after-sales support.

    Regulatory Roadblocks for Device Makers

    Multinational executives at the meeting pressed the government to remove persistent administrative bottlenecks at the Directorate General of Drug Administration. Lengthy approval cycles and import frictions continue to delay shipments of critical hospital equipment and replacement parts.

    AmCham submitted five specific policy demands to streamline market access. The business group called for separate DGDA guidelines for medical hardware, clear registration deadlines with parallel dossier reviews, and predictable maximum retail price formulas aligned with markup rules and the 7.5 percent value-added tax.

    Supply Chain and Tax Reforms

    Device suppliers face high import tariffs on spare components and burdensome customs procedures when sending damaged machinery abroad for maintenance. Industry leaders want tax rationalisation and simpler rules for re-exporting equipment for overseas repairs.

    Country heads from GE HealthCare, Medtronic, and Becton Dickinson attended the discussions alongside US Embassy commercial counsellor Paul Frost and DGDA director general Md Alamgir Hossain. For foreign vendors, local assembly offers protection against currency swings and import restrictions, but high tariffs on sub-assemblies still erode operating margins.

    The Next Regulatory Step

    Dhaka previously lowered select healthcare duties to ease hospital costs, yet device classification rules remain tied to general pharmaceutical standards. That shared framework creates administrative backlogs because diagnostic hardware requires different safety certifications than consumer drugs.

    AmCham is now organising a joint technical workshop with the DGDA and Western medical device manufacturers to draft an international-standard regulatory framework for hospital technology.

  • Pakistan Cotton Arrivals Rise 7.5 Percent to 4.08 Million Bales

    Pakistan Cotton Arrivals Rise 7.5 Percent to 4.08 Million Bales

    Cotton arrivals at Pakistani ginning factories reached 4.08 million bales by October 15, rising 7.53 percent year-on-year despite widespread textile plant shutdowns.

    Data from the Pakistan Cotton Ginners Association shows total intake climbed to 4,081,265 bales, up 285,628 bales from the 3,795,637 recorded in the same period last season.

    Domestic mills bought 3.45 million bales and exporters booked 97,000 bales, leaving 531,530 bales unsold across active yards. Total arrivals during the preceding fortnight stood at 872,863 bales, processed by 471 operational ginning facilities nationwide.

    Regional Yields and Mill Disruption

    Sindh drove the bulk of volume with 2.44 million bales, up 7.35 percent from last year, led by Sanghar district at 1.14 million bales. Sukkur followed with 264,500 bales, Naushehro Feroze with 223,200 and Khairpur with 213,900.

    Punjab recorded arrivals of 1.64 million bales, representing a 7.79 percent increase. Bahawalnagar posted 418,750 bales, Bahawalpur delivered 294,606, Dera Ghazi Khan produced 236,514, Rahim Yar Khan reached 169,949 and Layyah logged 122,327.

    The higher volume arrives against severe industrial curtailment. Trade bodies report approximately 500 ginning factories and more than 150 spinning and weaving mills have shut operations, while roughly half of Pakistan’s power looms remain idle.

    Synthetic Influx Distorts Local Pricing

    Local processors blame soaring energy tariffs and leakages under the Export Facilitation Scheme for depressing domestic fiber demand. Under the programme, duty-free imported yarn and fabric intended for export finishing are instead diverted into the local market, bypassing the standard 18 percent sales tax paid by domestic suppliers.

    Import figures from the All Pakistan Textile Mills Association reveal man-made yarn shipments jumped to 12,773 tonnes in the first quarter of the 2026-27 fiscal year, up from 3,056 tonnes a year earlier. Man-made fabric imports surged from 660 tonnes to 8,628 tonnes over the identical timeframe.

    Cotton Ginners Forum Chairman Ihsanul Haq noted that traders brought an estimated 40 million to 50 million metres of fabric from China alone under the concessionary system without generating matching finished garment export growth.

    Crop Estimates and Farmer Margins

    Discrepancies in official output tracking complicate procurement planning for regional apparel makers. The Punjab Crop Reporting Service estimated provincial crop output at 2.983 million bales, creating a sharp divergence against the ginners association tally of 1.638 million bales received by mid-October.

    Central Cotton Research Institute transfer of technology head Sajid Mahmood warned that higher raw output will not stabilize the supply chain if farmgate returns fall below cultivation costs. Farmers facing compressed margins are expected to shift acreage toward competing crops next spring if lint prices fail to cover inputs.

    Karachi Cotton Brokers Forum leader Naseem Usman urged authorities to establish a direct floor price and an official buying mechanism to prevent distressed sales if open-market rates slide further.

    Harvest Run Out

    Picking operations enter their final 15 to 20 days across core farming belts in southern Punjab and upper Sindh. The Central Cotton Research Institute has instructed growers with plants bearing eight to 10 green bolls to apply a foliar spray of two kilograms of urea per 100 litres of water to accelerate boll opening before seasonal temperatures drop.

    Customs authorities have initiated targeted inspections against trading firms suspected of misusing import exemptions, while mills push Islamabad for formal quota caps on incoming synthetic yarn before second-quarter contracts settle.

  • Chiikawa Drives 1.8 Million Korean Cinema Admissions and Merchandise Frenzy

    Chiikawa Drives 1.8 Million Korean Cinema Admissions and Merchandise Frenzy

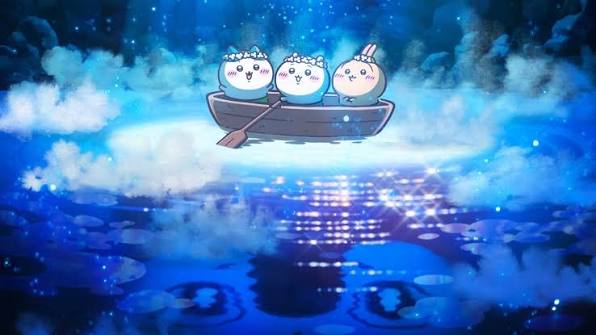
    Japanese character franchise Chiikawa generated 14 million dollars and drew 1.83 million admissions across South Korea within three weeks of its September 30 theatrical release.

    The animated feature captured 42.7 percent of South Korea’s nationwide cinema revenue over the October 16 to 18 weekend, taking 2.8 million dollars across 1,181 screens. Tracking data from the Korean Film Council shows the film led the box office for a third consecutive frame, pulling in nearly triple the weekend audience of second-place political drama The Assassin(s).

    Merchandise Queues and Resale Multipliers

    Consumer demand has spilled directly into physical retail corridors across Seoul. Shoppers have queued overnight outside the official Chiikawa merchandise store in central Seoul for limited-edition product drops, with select character collectibles subsequently trading on secondary resale platforms at ten times their original store prices.

    Multiplex chain CGV reported that customers in their twenties and thirties accounted for nearly 70 percent of all advance ticket bookings. The franchise, distributed locally through CJ ENM and Daewon Media alongside Japanese studio Toho, originally emerged in 2020 as a webcomic created by illustrator Nagano before expanding into short-form television animation in 2022.

    Licensing Resilience in East Asian Retail

    The consumer reception in South Korea reflects an established playbook for Japanese character licensing across East Asia. Mainland Chinese shoppers previously turned Chiikawa into a viral retail phenomenon, adopting the term digital ibuprofen to describe character purchases made during prolonged periods of graduate job competition and wage stagnation.

    Commercial landlords and retail operators face shifting foot-traffic patterns as character pop-ups replace traditional apparel anchors in high-density shopping districts. Retailers that secure official product allocations gain instant access to younger working demographics whose discretionary budgets have retreated from big-ticket luxury items toward small emotional purchases.

    Screen Density and Distributor Returns

    Competition across South Korean cinema circuits remains crowded with domestic and Hollywood releases. Distributor Hive Media Corp generated 23.7 million dollars from 3.25 million admissions for Hur Jin-ho’s period crime title The Assassin(s), while CJ ENM gathered 14.3 million dollars across four frames for franchise entry Tazza: The Song of Beelzebub.

    Chiikawa the Movie: The Secret of the Mermaid Island reached domestic theaters after finishing its Japanese domestic run as the country’s highest-grossing film of 2026. The storyline, directed by Kei Oikawa, sends the titular lead character and companions Hachiware and Usagi on a remote island expedition after chasing an employment advertisement promising inflated wages.

    Target Numbers for Regional Box Office

    Daewon Media and CJ ENM will track the two-million-ticket threshold over the coming week as South Korean theaters adjust screen allocations before November release schedules take effect.

  • China Clears 18 Active ETF’s to Funnel Billions into A-Shares

    China Clears 18 Active ETF’s to Funnel Billions into A-Shares

    China approved 18 actively managed exchange-traded funds on Monday, clearing domestic fund managers to channel tens of billions of yuan into mainland equities.

    Each fund could raise around 2 billion yuan, or roughly US$300 million, during subscription drives starting as early as Friday. The China Securities Regulatory Commission cleared the batch from domestic public fund houses after a three-month review. Fund managers may issue initial offer details as early as Tuesday, opening a direct pipeline of institutional cash for Shanghai and Shenzhen listings.

    Terms of the Fund Approvals

    Speaking at the Financial Street Forum in Beijing, CSRC chairman Wu Qing confirmed the approvals while outlining measures to stabilize equity prices. The new batch represents a shift toward active management within the exchange-traded market, giving portfolio managers leeway to select individual stocks rather than mechanically tracking broad equity indexes.

    Unlike passive benchmark trackers that buy across an entire gauge, actively managed funds allow stock pickers to concentrate capital in undervalued names or specific sectors. For domestic institutional investors, this structure offers a mechanism to deploy liquidity quickly without absorbing the broader market drag from troubled legacy sectors.

    State Capital Steps In

    The push follows sharp declines across mainland bourses. The benchmark CSI 300 Index fell 3.4 percent over the five trading sessions through Friday, capping an unprecedented 10-week losing run. Although the index bounced 0.3 percent on Monday following third-quarter growth data, it sits roughly 17 percent below its June peak, flirting with technical bear-market territory.

    State-backed institutional buyers, collectively known as the National Team, have already stepped up purchases. Inflows into leading broad-based ETFs reached their highest levels since July late last week, marked by heavy institutional volume near market close. The rollout of active ETFs expands this liquidity playbook from direct index intervention to discretionary equity allocation.

    Tech Valuations Under Pressure

    Mainland technology companies have borne the brunt of recent equity weakness as global enthusiasm for artificial intelligence hardware shifted. The tech-focused Star 50 Index dropped nearly 40 percent across the half year, turning into one of the weakest major tech gauges worldwide.

    Beijing has relied on equity markets to finance strategic technology developers, but falling secondary valuations threaten primary fundraising. In contrast, Hong Kong has seen growth companies in biotechnology and artificial intelligence rise to 30 percent of its listed pool from 10 percent in 2023, drawing capital that might otherwise seek mainland listings. Funneling fresh fund flows into Shanghai and Shenzhen gives domestic tech counters a valuation buffer at a time when retail sentiment remains fragile.

    Corporate Buybacks and Enforcement

    The regulatory initiative builds on market-support efforts launched in July, when Chinese authorities brought together state funds, domestic insurers, and asset managers to steady trading desks. That intervention curbed outright panic selling but failed to halt the weekly erosion across large-cap benchmarks.

    Regulators are pairing the ETF rollouts with pressure on corporate boards to execute share buybacks, alongside pledges by the CSRC to punish accounting misconduct and illegal trading. Attention now turns to Friday, when fund houses open their books for initial subscriptions to establish how much institutional and retail capital the 18 products collect.

  • Punthai Coffee Signs Influencer for Five-Drink Matcha Menu in Thailand

    Punthai Coffee Signs Influencer for Five-Drink Matcha Menu in Thailand

    Thailand’s Punthai Coffee has signed social media creator Khun Noey as its first brand partner. Together, they will roll out a five-part matcha drink series across the chain’s network.

    That partnership runs through 2026 and builds on an earlier customisation campaign. It targets younger consumers and specialty tea drinkers in the country’s competitive beverage market.

    A Five-Recipe Rollout Across Stores and Delivery

    The chain will release five exclusive matcha beverages under the campaign banner “The Matcha That Noey Loves”. The first item, named Matcha Latte Rocky Mountain, went on sale on 15 October. It remains on menus through 31 December 2026 across physical outlets and delivery channels.

    This debut drink features two shots of matcha latte over lightly sweetened fresh milk and konjac jelly. Baristas finish the beverage with whipped cream, brownie chunks, crushed Oreo cookies and caramel syrup.

    Targeting High-Margin Custom Additions

    Chains across Southeast Asia lean heavily into dessert-style tea drinks to lift ticket sizes and draw younger foot traffic. Operators use layered toppings, jellies and branded confectioneries to justify premium price points over standard iced coffees.

    For store teams, building complex specialty drinks introduces kitchen friction during peak hours. Punthai is betting that creator-led recipes create enough volume and delivery demand to offset the added assembly time per cup.

    From Social Customisation to Official Menus

    The campaign follows the brand’s Punthai D.I.Y. Promotion, where customers shared their own drink combinations on social media. Turning user recipes into formal menu items gives the chain a low-cost testing ground for flavour trends before committing to seasonal supplies.

    Four additional drinks in the collaborative series will debut over the coming months ahead of the 31 December 2026 cutoff.

  • EV Battery Recyclers Beyond China Struggle as Capacity Sits Underused

    EV Battery Recyclers Beyond China Struggle as Capacity Sits Underused

    Global capacity for recycling electric vehicle batteries sits underused this week as consumer adoption slows and processing volumes concentrate heavily inside China. Total operational capacity now exceeds the actual volume of discarded battery packs available for processing.

    The mismatch leaves recyclers in markets outside China struggling to secure sufficient feedstock to run their extraction plants profitably. Japanese nonferrous metals producer JX Advanced Metals maintains operational facilities engineered to extract three critical metals, lithium, nickel and cobalt, from spent battery packs, but faces a tight raw material market.

    Feedstock Shortages Squeeze Operating Margins

    Recycling facilities rely on steady streams of manufacturing scrap and end-of-life battery packs to maintain baseline utilization. When electric vehicle adoption lags behind initial automotive forecasts, fewer vehicles reach end-of-life status, delaying the volume of scrap delivered to recyclers.

    China controls the majority of existing midstream refining and battery recycling capacity. That geographical concentration pulls available regional scrap toward Chinese processors, leaving independent operators in Japan, South Korea and Western markets to compete for scarce discarded cells.

    Regional Imbalances in Metal Recovery

    Processing plants require high throughput to offset the capital costs of hydrometallurgical and pyrometallurgical extraction systems. Without steady volumes of spent cells, recyclers face rising unit costs while competing against large-scale Chinese refiners that benefit from integrated domestic supply chains.

    For automakers and electronics manufacturers, the imbalance creates supply chain exposure. Slower domestic recycling development outside China delays closed-loop raw material procurement for critical battery metals such as lithium and nickel.

    Slower Vehicle Adoption Shifts Timelines

    Automakers originally calibrated battery recycling investments to meet expected surges in vehicle replacement cycles. Slower customer uptake of purely electric models has stretched the average lifespan of internal combustion and hybrid fleets, postponing the anticipated wave of retired battery packs.

    Facilities built in anticipation of immediate material shortages are now absorbing higher maintenance and holding costs. Companies that built extraction units early must now navigate extended ramp-up periods before regional vehicle retirements generate adequate feedstock.

    Scrap Flows and Supply Chain Realignment

    Industrial processors continue to adjust processing schedules to match actual recovery volumes. Securing reliable scrap contracts from regional battery cell producers and automotive dismantlers remains the primary hurdle for non-Chinese operators.

    The near-term test rests on whether domestic battery scrap yields from local manufacturing plants will rise enough to bridge the feedstock gap before older electric vehicles enter salvage yards in volume.

  • Pepsi-Cola Partners with 7-Eleven Thailand to Launch Lay’s Loaded DIY

    Pepsi-Cola Partners with 7-Eleven Thailand to Launch Lay’s Loaded DIY

    In October 2026, Pepsi-Cola (Thai) Trading partnered with 7-Eleven Thailand to launch Lay’s Loaded D.I.Y., selling customisable snack combinations across the convenience store network and digital channels.

    The promotion lets buyers take bags of chips and combine them with add-ons and toppings purchased directly in-store.

    How the in-store concept works

    Shoppers select participating base chip packets and add savoury ingredients to build custom snack bowls inside the store. The retail mechanic turns standard packaged goods into quick-prep food options without requiring dedicated kitchen equipment or extra staff behind the counter.

    Digital channels handle the same ordering flow. Customers can select their chip base and topping combinations directly through the 7-Eleven mobile application and order them via 7-Eleven Delivery for home drop-off.

    Influencer recipes drive app orders

    To establish baseline recipes, the campaign brought in four Thai key opinion leaders to develop signature combinations based on their personal flavour choices. These recipes serve as default menu items on the 7-Eleven application, giving shoppers direct templates rather than forcing them to invent combinations from scratch.

    Social sharing anchors the promotional push. By circulating specific topping formulas online, the brand aims to convert casual social media viewers into app-based delivery orders.

    Commercial shift for snack makers

    Packaged snack producers in Southeast Asia face stagnant volume growth in conventional shelf placements. Turning standard chip packets into assemble-at-home meals allows manufacturers to lift basket size without reformulating the underlying product.

    For convenience operators like CP All’s 7-Eleven, the mechanic drives cross-category sales. A single snack transaction now pulls in additional high-margin chilled toppings, sauces, and packaged side items from adjacent shelves.

    Earlier product experiments in Bangkok

    The campaign follows several product variations rolled out by PepsiCo in Thailand during 2026. The company introduced Lay’s Light with a 40 per cent sodium reduction in September, alongside a co-branded ice cream crunch stick developed with Nestlé Éxtreme Pop.

    Earlier in May 2026, the brand tested texture additions through Lay’s Max paired with crunchy crab sticks. The latest DIY promotion shifts that experimentation from factory packaging directly to the retail point of sale.

    What to track next

    Retail buyers are monitoring whether the DIY format generates repeatable basket additions beyond the initial social media campaign. The metric to watch is whether 7-Eleven expands the loaded snack concept to other savoury snack categories across its nationwide footprint.

  • South Korean Regulators Face Backlash as Margin Debt Hits 33.7 Trillion Won

    South Korean Regulators Face Backlash as Margin Debt Hits 33.7 Trillion Won

    South Korean financial authorities face mounting criticism after retail margin debt climbed to 33.7 trillion won ($2.53 billion) during a week of violent swings on the Seoul stock exchange.

    The benchmark Kospi tumbled through seven consecutive sessions before rebounding 2.05 percent to close at 5,668.05 on Friday, while retail cash reserves sank toward recent lows.

    Regulators Convene Emergency Session

    Financial Services Commission Chairman Lee Eog-weon convened an emergency review in Seoul with executives from the Financial Supervisory Service, the Korea Exchange, the Korea Capital Market Institute and the Korea Financial Investment Association. Officials reviewed risks tied to artificial intelligence semiconductor valuations, prospective United States interest rate increases and elevated crude oil prices.

    Lee instructed brokerage houses to tighten their lending standards to curb speculative exposure during volatile trading cycles.

    “Financial companies should refrain from extending credit indiscriminately and make every effort to protect customers and manage risks,” he said.

    Margin Loans Surge Above Thresholds

    Outstanding margin loans have remained above 30 trillion won for an extended run, touching a three-month peak by Wednesday. Retail accounts expanded their borrowed exposure even as the Kospi breached the 6,000-point threshold and briefly threatened the 5,500-point mark.

    Cash deposits held by retail investors dropped toward recent cyclical lows over the same period. The divergent metrics reveal that individual traders committed further to used bets rather than holding cash cushions during severe market sell-offs.

    Volatilities spilled into tech equities across North Asia as market participants reassessed capital expenditure on AI infrastructure. In Seoul, Samsung Electronics edged up 0.23 percent while SK Hynix slipped 1.26 percent, tracking broader weakness in semiconductor components.

    Market Participants Demand Concrete Steps

    Institutional desks in Seoul argue that rhetorical warnings fail to alter trading behavior when foreign funds offload local equities. Repeated government sessions without structural measures risk desensitizing domestic market participants.

    Used retail positioning poses liquidity threats to mid-cap listings if forced liquidations accelerate across secondary brokerages. Margin calls triggered during intraday slides drain trading volume from high-growth tech firms that depend on domestic retail capital.

    Index Swings Trigger Circuit Measures

    The Thursday session delivered a plunge of more than 7 percent across the Kospi, culminating in a seven-day losing streak before Friday’s technical rebound. The tech-heavy Kosdaq index jumped as much as 5 percent intraday on Friday, activating a buy-side sidecar mechanism that temporarily suspended automated program trading.

    Investor anxiety remained elevated despite the Friday bounce, with the Kospi 200 Volatility Index recording its third-largest single-day increase on record and hitting a six-week high.

    Brokers now track whether margin balances stay above the 33 trillion won line as third-quarter earnings reports from key tech exporters roll out across the region.