Author: Mei Ling Tan

  • DeepSeek Releases Model V4.1 Flash Update and Opens Serving Framework

    DeepSeek Releases Model V4.1 Flash Update and Opens Serving Framework

    DeepSeek announced an updated V4.1 Flash artificial intelligence model alongside an open-source inference framework, pricing enterprise tasks down to roughly $0.20 each.

    The developer posted a 77 per cent Pass@1 score on the DeepSWE v1.1 coding benchmark, cutting compute demands through shorter operational outputs.

    Its release of V4.1-Flash-1017 on October 17 raised the system’s Terminal-Bench 4.0 score from 31.2 to 42.3, while DeepSWE v1.1 gained almost three points to 77.0. Benchmark evaluations show the system completing tasks for $0.11 to $0.14 when running lower-cost operational settings, scoring between 72 and 73 per cent. Independent tracking on Arena’s Agent Arena leaderboard placed the updated model first among open-weight competitors and 11th overall across 7,498 real-use sessions, with median execution costs between $0.18 and $0.19 per task.

    Open Source Engine for Enterprise Chips

    Three days after the model release, DeepSeek published DeepInfer, the inference engine running its production services, alongside a request-handling library named deepseek-recipe. The framework manages hardware allocation, latency schedules and computing kernels to serve queries at scale. It runs directly on Nvidia SM100 graphics processing units and Huawei Ascend 950 neural processing units, targeting V4.1 Flash deployments.

    The open-source code does not provide an end-to-end service stack out of the box. Production teams still need to supply their own key-value cache infrastructure, load balancing across parallel replicas, and complete disaggregation systems. Developers gain internal scheduling kernels, but enterprise engineering teams will absorb the integration overhead.

    Shifting the Cost of Business Automation

    For online marketplaces, customer support platforms and software houses across Asia, the release attacks the cost ceiling that keeps autonomous agents out of routine commercial workflows. Running thousands of real-time inventory adjustments, code fixes and customer transactions through commercial western models remains too expensive for thin-margin Asian e-commerce. If an open-weight system matches proprietary grade accuracy at 20 cents a task, mid-sized digital retailers will self-host rather than pipe data through expensive closed APIs.

    Hardware exclusivity remains the primary roadblock for regional operators seeking to replicate these results. While support for Huawei’s Ascend 950 gives Chinese domestic firms an alternative to export-controlled American silicon, Southeast Asian developers operating standard cloud setups will face hardware configuration bottlenecks. Running pruned agent frameworks demands deep systems engineering that many consumer brand operators do not maintain in-house.

    Building Out the Infrastructure Layer

    DeepSeek spent the previous quarter trimming resource requirements across its stack. The company cut key-value cache memory to a quarter and solid-state drive storage to an eighth of previous requirements during the September rollout of V4.1 Flash. It introduced off-peak API access at a 50 per cent discount to balance round-the-clock server loads.

    Commercial access expanded in October with Search and Fetch APIs billed at 5 yuan per 1,000 successful queries. The firm is maintaining free API connections for developer platforms including Claude Code and Codex until per-request billing starts on November 1.
  • Samsung and SK Hynix Upgrade China Memory Plants Past 200 Layers

    Samsung and SK Hynix Upgrade China Memory Plants Past 200 Layers

    Samsung Electronics and SK Hynix are upgrading their manufacturing plants in China to produce NAND flash memory chips with more than 200 layers. The retrofits target swelling demand for artificial intelligence hardware and push back against domestic rival Yangtze Memory Technologies Co, which recently took the top position in China’s memory market.

    Yangtze Memory Technologies Co captured 38.5 percent of China’s NAND flash market during the second quarter, rising from 28 percent across all of 2025. That expansion pushed Samsung’s local market share down to 33.5 percent from 36 percent, while SK Hynix dropped to 17 percent from 20 percent.

    Samsung runs its primary overseas memory fabrication site in the northwestern city of Xian. The complex accounts for roughly 40 percent of the South Korean group’s global NAND flash output and currently builds chips stacked to approximately 200 layers.

    Retooling Xian for 286 Layers

    Under an internal project named Monami, Samsung is converting the Xian factory lines to produce 286-layer V9 NAND chips. The plant is scheduled to process 5,000 wafers monthly starting in December this year, stepping up to 40,000 wafers each month by December 2027. Samsung confirmed the plant updates are proceeding in compliance with Washington’s export regulations.

    The upgrade is aimed at meeting growing demand from global customers, including those in the US. The company is not expanding production capacity or constructing new manufacturing facilities.

    SK Hynix Pushes Dalian Operations

    SK Hynix is pursuing a parallel upgrade at its site in Dalian in northeastern China. The facility currently manufactures 192-layer NAND chips, and the company plans to transition lines toward 240 layers or higher.

    The South Korean group took over the Dalian factory in 2021 through its acquisition of Intel’s NAND flash business. The subsidiary, operating under the Solidigm brand, relies on Dalian as its sole NAND manufacturing site while preparing for an initial public offering in the United States.

    SK Hynix holds clearance to assemble chips up to 240 layers at Dalian. The company may request permission from the United States to run research and development on chips with more than 300 layers there, creating technical groundwork for planned manufacturing on American soil.

    Regulatory Pressure and Domestic Competition

    For hardware brands and electronics assemblers operating across Asia, the plant refits determine component pricing and local component availability. Samsung and SK Hynix have faced operational hurdles since the United States rolled out export controls on advanced semiconductor equipment in 2022. Both manufacturers must obtain annual American licences to import specialized tools such as etching gear into mainland China.

    The US Commerce Department’s Bureau of Industry and Security announced in 2025 that it did not intend to authorize technology upgrades or capacity expansions at foreign-owned semiconductor plants in China. Restricting foreign lines gave YMTC room to run. The Chinese manufacturer relies on 160-layer and 232-layer designs for volume shipments, but it already yields limited batches of 294-layer memory and is preparing architectures exceeding 300 layers.

    Fab Limits and the Next Phase

    South Korean chipmakers have kept their most advanced production lines at home to safeguard proprietary designs. Outside mainland China, Samsung sells NAND chips stacked up to 286 layers and showed a prototype with more than 400 layers in August, while SK Hynix markets finished memory chips reaching 321 layers.

    Operating legacy processes in China risks shutting both suppliers out of high-density solid-state drive contracts for mainland data centres and premium smartphone manufacturers. SK Hynix is concurrently holding discussions with the Trump administration regarding plans to build a new NAND factory in the United States. Samsung’s retrofitted Xian facility is aiming for an initial monthly output of 5,000 wafers in December this year.

  • Forever New Reaches $400 Million Turnover as Global Sales Match Australia

    Forever New Reaches $400 Million Turnover as Global Sales Match Australia

    Australian womenswear retailer Forever New lifted annual group turnover to approximately $400 million, driven by international store expansion across Asia, North America and the Middle East. Revenue outside its domestic home market now accounts for half of total group sales, up from an aggregate turnover of $270 million in fiscal 2019.

    Group founder and chief executive Dipendra Goenka confirmed the figures as the Melbourne-based brand completed its twentieth year of trading. The business operates roughly 466 retail doors, concessions and outlets across 24 countries, managed alongside managing director Carolyn Mackenzie. Trading showed improved momentum across Australian stores in the second half of the year, while India, South Africa, Canada and the United Kingdom posted positive trading contributions.

    Shifting revenue beyond domestic territory

    For fashion retailers founded in Australia, crossing the $400 million threshold while generating half of that turnover overseas is an uncommon outcome. Mid-market apparel brands from Melbourne and Sydney frequently stumble when trying to duplicate local shopping mall formats offshore, caught out by opposing seasonal cadences, aggressive rent demands, and supply chain bottlenecks. Forever New counteracted those hazards by designing dual-hemisphere collections and relying on department store concessions before committing capital to full retail leases.

    The commercial risk now sits in margin retention across overseas wholesale partnerships. Concession networks and digital platforms offer fast unit volume, but they extract steep commissions and restrict discounting flexibility when inventory builds up. Competitors targeting identical mid-market demographics have struggled to protect full-price sell-through rates across India and the Middle East, where local department operators command premium mall space and dictate floor productivity terms. The company must keep production volumes tightly matched to regional sell-through curves to avoid eroding margins.

    Sourcing and seasonal coordination present an ongoing operational test. Running physical networks across both Northern and Southern hemispheres requires staggered factory bookings, separate fabric allocations, and split shipping schedules. Retailers that misjudge the volume balance between winter collections in Canada and summer deliveries in Australia face discounting stock before full margin realization takes place.

    Broadening wardrobes beyond occasion dressing

    Product mix adjustments run parallel to the geographic rebalancing. The company built its initial customer base around formal dresses and event wear, but commercial leadership is intentionally reallocating store space to everyday office wear, knitwear, jackets, tailored separates and casual apparel. Internal customer data showed that shoppers unfamiliar with the label still view it purely as an events destination, leaving regular wardrobe categories undersold.

    Occasion dressing delivers high average transaction values but creates lumpy, seasonal foot traffic linked to spring racing and wedding calendars. Transitioning the range toward weekly office wear and casual layers increases repeat customer visits, providing steady store receipts across historically quiet months. Multi-brand department store partners such as Nordstrom and Bloomingdale’s also demand steady replenishment rhythms that single-purpose party wear cannot sustain.

    Format testing and the US standalone entry

    North America serves as the immediate testing ground for the brand’s standalone store model outside its traditional Commonwealth footprint. Trading as Ever New in select international markets, the company launched a dedicated direct-to-consumer online store and a digital partnership with Bloomingdale’s in April 2026. Those platforms build upon existing Nordstrom concession counters and lead into the opening of the retailer’s first standalone American store, located in Texas.

    Store formats under evaluation across global territories range from large flagship units down to compact, curated boutiques intended to maximise revenue per square metre. Management maintains that rapid footprint additions will remain secondary to unit profitability. As Goenka stated:

    “The objective is not to chase a large store count immediately, but to establish a profitable and scalable foundation for the next phase of growth”

    Pruning mature stores for network productivity

    Founded in Melbourne in 2006, Forever New expanded through regional shopping centres across Australia before opening stores in New Zealand, South Africa and India over the following decade. Group turnover stood at approximately $270 million in fiscal 2019, prior to pandemic trade interruptions that compelled store portfolio reviews and accelerated digital concessions. Marking its two-decade milestone on October 13 at The Cutaway in Barangaroo, Sydney, executive leadership outlined a three-year plan to reshape retail real estate.

    Over the coming three-year period, management will review Australian locations to close shopfronts that do not meet store productivity benchmarks. That network trimming is intended to redirect working capital toward store additions in India, the Middle East and North America, where the initial trading numbers from the Texas opening will determine the pace of future standalone roll-outs.

  • Tencent Deploys Retail AI Suite Across 600 Asian Merchants

    Tencent Deploys Retail AI Suite Across 600 Asian Merchants

    Tencent Smart Retail rolled out its artificial intelligence enterprise software suite to 600 retail clients across Asia during an industry summit in Hong Kong. The deployment targets merchants across 30 retail sectors, connecting automated operational software directly into Tencent Cloud and the broader Weixin, WeCom and Mini Programs network.

    Terry Li, vertical general manager of Tencent Smart Retail, detailed the push alongside enterprise partners at the 2026 World Retail Lab Asia event. The software line-up introduces five specialized tools for merchant operations: WorkBuddy for workforce productivity, CodeBuddy for software development, DataBuddy for enterprise data workspaces, Miora for automated creative design, and Ardot for turning design assets into code.

    Connecting Weixin to the shop floor

    The system links merchant back offices directly to front-line sales teams on WeCom and shoppers on Weixin. Rather than forcing store associates to toggle between stand-alone software suites, the setup feeds automated inventory updates, design files and customer prompts into Tencent’s messaging channels. That reduces friction for floor staff who already run client relationships through corporate chat accounts.

    Enterprise software vendors across Asia frequently stumble on floor-level adoption. Tencent is betting that tying generative design and analytics agents to the chat apps clerks already use daily will bypass the standard training hurdles.

    Jewellery chains and supply taggers

    Chow Tai Fook Jewellery Group is using the infrastructure across customer management, store operations and jewellery design. The jewellery retail chain manages a database of nearly 60 million global loyalty members, who generate more than 95 per cent of its total sales volume. The group links unified customer insights to floor operations across its store network to track individual buying habits and stock preferences.

    Industrial supplier SML Group has embedded the software into its product development, market intelligence and supply management. The firm provides RFID tracking, retail identification and digital product solutions to roughly 600 consumer brands across global markets.

    Sinong Duan, vice president of strategy and transformation at SML Group, said: “Customer engagement is one of the areas where we see significant potential for AI. It can help businesses better understand customer needs and improve product recommendations, creating new opportunities to enhance both conversion and service experiences. We have also had the opportunity to work with Tencent WorkBuddy, and its flexibility, user experience and support capabilities have enabled our teams to explore AI adoption more effectively.”

    The platform battle against Alibaba

    The aggressive push into merchant operations pits Tencent directly against Alibaba Group’s cloud and DingTalk ecosystem across Greater China. While Alibaba dominates pure-play e-commerce marketplaces like Taobao and Tmall, Tencent controls private-domain traffic where brands cultivate direct shopper relationships through bespoke Mini Programs. Brand operators increasingly favor private-domain channels because customer acquisitions carry lower marketplace take-rates.

    For consumer brands, committing to proprietary cloud agents locks enterprise data deep inside Tencent’s walled garden. Shifting between competing cloud environments becomes punitive once product catalogs, customer service histories and design archives run on platform-specific models. Retailers gain rapid workflow speed today at the price of long-term software dependency tomorrow.

    Measuring actual returns on automation

    Chinese consumer spending has remained selective throughout the year, forcing retail executives to audit back-office overhead and technology spending closely. Multinationals and domestic retail giants, including Decathlon China, Estee Lauder Group and toy maker Pop Mart, have increasingly trimmed speculative software experiments in favor of tools that cut headcount costs or lift repeat store visits.

    Tencent began assembling its smart retail unit in 2018 to bridge social messaging with physical store sales counters. The group spent earlier iterations refining digital payment terminals and loyalty program Mini Programs for department stores and supermarket chains across tier-one Chinese cities. This latest enterprise suite represents the next operational tier: replacing manual design, coding and inventory forecasting with automated agents.

    Merchant adoption rates for tools such as Miora and Ardot over the upcoming Golden Week and Lunar New Year retail peaks will provide the first real test of whether generative design can shave measurable weeks off corporate fashion and merchandising cycles.

  • Australian Auto Retailers Fetch 11.2X Valuation as Apparel Slips to 6.4X

    Australian Auto Retailers Fetch 11.2X Valuation as Apparel Slips to 6.4X

    Australian automotive retailers traded at 11.2 times earnings in 2026 while apparel multiples slumped to 6.4 times, according to Grant Thornton Australia’s Dealtracker transaction data.

    The five-turn valuation divide reflects an aggressive buyer preference for cash-generative operations with locked-in distribution over discretionary fashion merchants struggling with discount cycles.

    Grant Thornton released the findings in the final installment of its four-part transaction study, warning retail boards that chasing top-line sector expansion will not insulate them from acquisition discounts. Dealmakers are pricing businesses based on procurement controls, balance-sheet resilience, and customer retention rather than broad category growth projections.

    Multiples Split Discretionary Categories

    Valuations across consumer discretionary assets show stark divergence within the same retail spending pools. Automotive businesses commanded double-digit multiples by pairing vehicle sales with parts supply, workshop servicing, and rigid customer replacement cycles.

    Apparel operators faced steep discounts as selective shoppers trimmed discretionary wardrobes and forced merchants into promotional price battles. Brand equity alone no longer commands premium deal pricing without evidence of repeat purchase loyalty that survives inflationary pressure.

    Tam Goldin, financial advisory partner at Grant Thornton Australia, pointed out that category classification accounts for only part of a target’s pricing. “The sector matters, but the underlying business model matters more,” Goldin said.

    Private capital in Australia has pivoted toward specialized operators that scale distribution networks without multiplying administrative overhead. Scaled retailers with integrated inventory pipelines hold pricing power, whereas mid-tier general merchants face margin compression across both physical stores and digital storefronts.

    Capital Discipline Replaces Platform Sprawls

    Technology spending in the sector has shifted from speculative platform rollouts to strict return hurdles. Retailers are halting open-ended artificial intelligence trials to focus on inventory visibility, demand forecasting, and operational productivity.

    Kirsten Ridgway, management consulting partner and head of retail and consumer products at Grant Thornton Australia, stated that board-level technology choices cannot center on software procurement alone. Executive teams must identify specific operational bottlenecks before committing capital to enterprise platforms or machine-learning tools.

    Enterprise cleanups now take priority over front-end digital additions. Merchandisers are overhauling fragmented legacy databases because untested algorithmic tools compound pricing errors when fed inconsistent stock records.

    RetailNews Asia sees this operational retrenchment as a defensive realignment across Australasia. Regional retail conglomerates in Singapore, Tokyo, and Sydney spent three years buying disparate commerce software packages, only to find that operational complexity wiped out expected margin gains.

    Second-Hand Marketplaces Erode Price Power

    Traditional clothing chains face mounting margin erosion from circular commerce platforms. Second-hand marketplace Vinted entered the Australian market and disrupted established local resale channels, drawing cost-conscious consumers away from full-price fast-fashion and mid-market apparel racks.

    Resale platforms operate without inventory carrying costs or physical store lease liabilities. That structural cost advantage lets them reset shopper expectations around everyday apparel pricing, penalizing conventional store operators whose rent and utility charges remain fixed.

    Online commerce penetration continues to anchor these digital shifts. Australia Post eCommerce data recorded that 82 percent of Australian households made online purchases during 2025, with 41 percent shopping online fortnightly or more.

    High e-commerce participation allows overseas circular platforms to scale rapidly across Australian metropolitan centres. Traditional apparel chains unable to justify their price premiums risk losing volume permanently to these asset-light competitors.

    Payment Reforms Squeeze Margin Buffers

    Regulatory mandates are compounding pressures on retail margins. The Reserve Bank of Australia removed payment surcharges on eftpos, Mastercard, and Visa transactions on October 1, 2026, forcing merchants to absorb payment processing fees rather than passing them directly to shoppers at the checkout.

    This surcharge prohibition hit high-frequency merchants immediately, narrowing cash gross margins that were already compressed by wage rises and freight volatility. Operators without volume-based acquiring discounts must now extract operating efficiencies elsewhere in their supply chains.

    Stored-value and loyalty instruments offer partial relief from transaction friction. Australia’s gift card market is projected to reach US$8.22 billion in 2026, expanding 10.9 percent annually as supermarket chains and department stores deploy closed-loop digital balances to defend basket sizes.

    Woolworths integrated its Everyday Gifting system directly into its rewards smartphone application, letting loyalty members buy and redeem electronic cards with stored loyalty balances. Supermarkets and department chains use these closed networks to capture prepaid sales, avoid merchant terminal surcharges, and keep spend locked within their retail ecosystems.

    The Australian Retail Council convenes its supply chain summit on October 27, 2026, where national logistics directors will assess port freight disruption and inventory holding costs ahead of the peak November shopping weekend.

  • Huawei Sets 10 Gbps Microwave Backhaul Target to Support Mobile AI

    Huawei Sets 10 Gbps Microwave Backhaul Target to Support Mobile AI

    Huawei targeted a 10 Gbps capacity standard for microwave backhaul networks in Kuala Lumpur to handle an expected tenfold surge in mobile artificial intelligence traffic.

    The equipment maker projects AI tokens and autonomous agent connections will expand cellular data volumes five to ten times across regional carrier links over the next few years.

    Jason Wang, president of the Huawei Microwave Product Line, detailed the architecture during the 5th Global Microwave Industry Forum on October 14-15, 2026. Meeting that volume requires upgrading backbone links to 10 Gbps while pushing suburban transmission over traditional K-band frequencies from single-channel 1TR to dual-channel 2TR configurations, delivering up to 5 Gbps across distances reaching 10 kilometers. In metropolitan centers, 5G deployments on 100 MHz blocks of C-band spectrum require aggregation hubs that exceed tens of gigabits per second.

    Backup Links for Constant Fiber Cuts

    Physical cable vulnerabilities dictate the push toward dual-media redundancy. Telecommunications operators across Asia record thousands of fiber cuts each month from construction accidents, utility strikes, and weather disruptions. When multiple mobile base stations rely on a solitary severed optical line, entire districts lose coverage, causing instant commercial transaction drops and subscriber defection.

    Microwave transport bridges those physical breaks without requiring civil excavation permits. Pairing wireless links directly with terrestrial glass allows commercial traffic to switch paths immediately when a line fails. For enterprise campuses, ports, and automated logistics warehouses, Huawei is rolling out point-to-point and point-to-multipoint links using unlicensed spectrum, allowing private industrial networks to bypass carrier license auctions entirely.

    Operator Margins and Spectrum Economics

    Asian mobile operators run thin operational margins and cannot easily fund universal deep-fiber trenching across fractured archipelago geographies. Competitors like Ericsson and Nokia have long promoted hybrid fiber-wireless topologies across Southeast Asia, but Huawei remains the dominant volume supplier across developing regional corridors. Bypassing spectrum licensing fees on private industrial campuses gives enterprise clients a faster deployment timeline than public carrier fiber, cutting installation lead times from quarters to days.

    The friction sits in operating expenditure. Adding microwave backup preserves service uptime for mobile commerce and automated logistics hubs, yet managing dual transmission systems inflates routine maintenance budgets. Automation software must handle fault diagnosis, network tuning, and power management autonomously, or the personnel cost of supervising parallel networks will erase the operational savings.

    The Trajectory of High-Band Backhaul

    Regional carriers spent the past four years expanding 5G radio coverage across major metropolitan districts, initially routing suburban base stations through lower-capacity microwave dishes built for basic mobile internet. As autonomous driving pilots, telemedicine platforms, and mobile checkout systems scaled across Malaysia, Thailand, and Indonesia, existing multi-hundred-megabit backhaul links reached saturation during peak commercial hours.

    Equipment vendors responded by shifting development toward integrated multi-band solutions that pair standard high-frequency dishes with automated beam-tracking algorithms. The rollout of 5G-Advanced services across East and Southeast Asia now makes those capacity upgrades mandatory for operators defending their enterprise service contracts.

    Parameters to Track Next

    Carrier uptake across Southeast Asia now hinges on how quickly regional spectrum regulators allocate contiguous high-frequency microwave bands for commercial backhaul. Operators must balance the capital expense of replacing legacy 1TR outdoor units against the recurring revenue generated by guaranteed low-latency service contracts. The pace at which carriers achieve complete 10 Gbps link readiness on core suburban corridors through 2027 will reveal whether commercial mobile AI traffic delivers genuine enterprise returns.

  • Shenzhen Cuts Transit Fares by 50% to Ease Roads for Apec

    Shenzhen Cuts Transit Fares by 50% to Ease Roads for Apec

    Shenzhen will slash subway and bus fares by 50 percent from November 16 to 20 to clear its road network for the Asia-Pacific Economic Cooperation summit.

    The temporary subsidy accompanies an order taking 90 percent of government and state-owned enterprise vehicles off the streets, targeting gridlock across the southern metropolis of more than 17 million people.

    Slashing fares and boosting rail runs

    Municipal transport planners plan to run trains on selected subway lines every two minutes during peak windows. Standby carriages will wait at central depots to absorb crowds diverted away from arterial expressways, while transit operators launch more than 50 feeder bus services linking suburban neighbourhoods directly to metro stations.

    Private drivers face civic appeals rather than outright driving bans. Xu Wei, deputy director of the transport department, confirmed that car owners who register online to leave their vehicles parked will receive commemorative event stickers and a public transport card with a pre-loaded cash balance.

    Pulling fleets and private cars off the street

    State agencies and municipal commercial units will bear the sharpest road cuts. Excluding vehicles assigned directly to summit logistics, 90 percent of the state vehicle fleet will remain grounded through the full five-day event cycle.

    Human resources officials also directed companies across the tech hub to prepare contingency operations. Hao Shifei, deputy head of the human resources authority, said businesses should place eligible employees on remote working arrangements, stagger shift rotas for site-bound staff, or grant paid annual leave for the summit week.

    What remote work orders mean for local trade

    For high-street retailers, food operators and commercial landlords, these mobility curbs create immediate footfall shifts. Office-district restaurants and convenience chains across Nanshan and Futian will see weekday daytime trade thin out as white-collar workers stay home, while neighbourhood grocery stores and delivery platforms absorb the displaced volume.

    Logistics operators must manage severe route restrictions inside core commercial corridors. Freight dispatchers and last-mile couriers face narrower delivery windows around summit venues and luxury hospitality zones, making early-morning and overnight replenishment runs essential to prevent retail inventory stockouts.

    From Beijing and Shanghai to the tech hub

    This summit represents China’s third turn hosting the regional economic forum, following Shanghai in 2001 and Beijing in 2014. Chan Yaodong, deputy secretary general of the municipal government, said officials are balancing foreign affairs obligations with uninterrupted commercial operations.

    Delegates from 21 member economies will arrive ahead of the Apec CEO summit on November 17 and 18, with the leaders’ summit running on November 18 and 19. Transport dispatchers will watch whether the combined metro fare cuts and remote working guidelines successfully prevent supply-chain bottlenecks across the Greater Bay Area corridor.

  • Asian Equities Slide as South Korea Drops 3.6% and AI Spending Faces Scrutiny

    Asian Equities Slide as South Korea Drops 3.6% and AI Spending Faces Scrutiny

    Asian equity markets retreated across the board on Tuesday as South Korea’s benchmark index tumbled 3.61 per cent ahead of major global technology earnings.

    The MSCI Asia ex-Japan index fell 0.93 per cent while Tokyo’s Nikkei 225 dropped 1.28 per cent, reflecting investor hesitation across key regional hardware and semiconductor hubs.

    Seoul and Tokyo Lead Stock Declines

    Selling was heaviest in South Korea, where tech heavyweights dragged the KOSPI down sharply during morning trade. Market debutant Elice Group, a South Korean artificial intelligence infrastructure provider, opened 16 per cent below its initial public offering price after raising 201.1 billion won ($151.12 million) in its listing.

    European index futures pointed lower as well. Euro Stoxx 50 futures fell 0.71 per cent, DAX futures slipped 0.40 per cent and FTSE futures lost 0.44 per cent, while S&P e-minis held flat at 7,734.25.

    AI Spending Faces Heavy Scrutiny

    Investor attention is shifting toward corporate balance sheets as market participants demand direct evidence that enterprise software demand and consumer spending justify elevated capital commitments. Meta platforms, scheduled to report quarterly numbers on Wednesday, is one of five major hyperscalers projected by Goldman Sachs to push collective capital expenditure to $1.2 trillion next year.

    Hardware suppliers face an immediate test as results arrive from Tesla, Lam Research and Texas Instruments later in the week, alongside private operator SpaceX.

    The market is happy to cover shorts and unwind defensive trades, but that’s very different from having the conviction to rebuild aggressive exposure to AI.

    For component suppliers and contract manufacturers across East Asia, the stakes are elevated because regional valuations have priced in continuous quarterly gains. If hyperscalers signal any moderation in data centre buildouts, Asian memory and chip assembly vendors will bear the initial brunt of order adjustments.

    Institutional funds have begun pulling back from aggressive tech exposure, rotating into defensive holdings until earnings prints validate revenue conversion rates. The sharp discount on new market listings like Elice Group reflects shrinking risk tolerance for loss-making infrastructure plays across the region.

    Energy Markets and Trade Directives

    Crude oil prices ticked upward as energy traders tracked political developments in Washington and unrest in Europe. Brent crude rose 0.21 per cent to $109.78 a barrel, while US West Texas Intermediate gained 0.15 per cent to trade at $103.82 a barrel.

    An executive order issued by US President Donald Trump on Friday waived selected sanctions and tariffs on Russian energy exports, including duties on crude shipments and refined goods. Trump stated on Saturday that a final policy determination remains pending, leaving refiners and logistics providers uncertain about trade enforcement rules.

    Gold prices retreated from recent highs, with spot gold slipping 0.51 per cent to $4,118.71 an ounce.

    Currency Flows and Central Bank Signals

    Currency trading showed safe-haven positioning following weekend civil unrest in France that prompted municipal curfews in Paris, Lille and Nice. The euro traded at $1.12 after recovering 0.06 per cent from Monday’s slide, while the British pound held at $1.33 and the Japanese yen weakened marginally to 158.57 per dollar.

    Comments from US Federal Reserve officials, including Chair Kevin Warsh, indicated that monetary authorities see sustained domestic economic momentum and feel little urgency to adjust policy rates immediately. Digital assets followed equity markets lower, with bitcoin dropping 0.67 per cent to $81,386.40 and ether falling 0.54 per cent to $2,385.75.

    Traders now look to upcoming policy speeches from European Central Bank officials Martin Kocher and Olli Rehn, followed by Bank of England policymaker Megan Greene in London, ahead of Meta’s earnings release on Wednesday.

  • Singapore Names 7 Indonesian Firms over Toxic Haze

    Singapore Names 7 Indonesian Firms over Toxic Haze

    Singapore announced in October 2026 that it will issue preventative warnings to seven Indonesian companies identified as responsible for fires sending toxic smoke across Southeast Asia.

    The preventative notices target Sumatra-based pulpwood and timber suppliers, including Bumi Andalas Permai, Bumi Mekar Hijau and SBA Wood Industries, requiring them to immediately halt burning and submit containment plans to the National Environment Agency.

    Notices Issued to Sumatra Suppliers

    Sustainability and Environment Minister Grace Fu confirmed the action after investigations linked smoke blankets over the city-state directly to concessions managed by the operators. The formal notices instruct each business to deploy dedicated firefighting crews, cease setting new fires, and provide operational response roadmaps to Singaporean regulators.

    Authorities retain statutory powers to impose direct fines and criminal charges on entities that fail to comply with transboundary pollution directives. Enforcing cross-border compliance remains legally intricate, requiring administrative coordination with counterparts in Jakarta to execute sanctions against offshore asset holders.

    Commercial Fallout Across City Hubs

    Thick haze pushed Singapore to the top of IQAir global pollution rankings on Friday afternoon, registering an Air Quality Index reading of 230 in the very unhealthy bracket. Kuala Lumpur ranked second worldwide during the same period, while Jakarta placed tenth as dry conditions intensified across the Malacca Strait.

    Severe particulate spikes immediately hit hospitality, retail footfall and outdoor recreation across major commercial corridors. Observation decks, open-air dining precincts and guided city tours reported curtailed tourist activity, shifting consumer traffic indoors as health authorities warned the public to limit prolonged physical exertion outside.

    Peatland Fires and Supply Chain Scrutiny

    Uncontrolled fires across Sumatra and Kalimantan stem from clearing cycles on drained peatlands, compounded this season by prolonged drought linked to an active El Nino weather pattern. Four firefighters died combating blazes on Java, while medical facilities in several Indonesian provinces registered spikes in acute respiratory infections.

    Consumer brands and paper packaging purchasers face renewed pressure to audit upstream raw-material procurement across Indonesian concessions. Land clearances on carbon-rich peat landscapes increase legal and reputational exposure for consumer goods supply chains relying on regional pulp and timber mills.

    Unresolved Precedents from 2015 Crisis

    Cross-border enforcement has proved difficult since Singapore passed the Transboundary Haze Pollution Act a decade ago. Open investigations launched against four Indonesian plantation operators during the 2015 haze crisis remain unresolved, reflecting persistent diplomatic friction over land tenure transparency and corporate accountability.

    Singapore’s National Environment Agency is tracking fire hotspot telemetry and wind trajectories across Sumatra to determine whether further corporate concession holders will face statutory warnings as the dry season continues.

  • Stax Names New CEO and Issues 1.7 Million Dollars in Customer Credit

    Stax Names New CEO and Issues 1.7 Million Dollars in Customer Credit

    Australian activewear label Stax will relaunch online on November 6. The business is offering 1.7 million Australian dollars in store credits to settle 13,000 orders stranded by its collapse. A private syndicate led by Pushas founders Justin Truong and Sandy Li-Truong bought the brand assets after Stax collapsed with more than 24 million Australian dollars in liabilities.

    Former Turo marketing director Anna Cheng steps in as chief executive officer to run the restructured direct-to-consumer business. Former head of product Georgia Bachmann returns as creative director alongside lead designer Jaclyn Benson. Customer service staff completes a lean team of 10 employees.

    Converting stranded orders to store credit

    Reviving the brand hinges on resolving customer backlash from late June. At the time, the original company took payments until lender National Australia Bank appointed receivers from FTI Consulting. Under the recovery plan, Stax is granting full credit balances to affected buyers without assuming formal legal liability for the old entity’s debts.

    Management retrieved transaction records from Shopify and past vendors, emailing affected buyers in late September to confirm balances. Around 8,500 customers have verified their details so far. Remaining shoppers have until December 31, 2026, to confirm accounts. Issued store credits will remain valid until June 30, 2027.

    Orders placed through third-party financing platforms are excluded from the internal credit ledger. Shoppers who used Afterpay, PayPal, Klarna, or Zip must seek resolution through provider buyer-protection programs. Stax customer service agents will supply purchase records to support those claims.

    Lean operating model and new leadership

    Cheng’s appointment establishes an independent management tier apart from Pushas, the sneaker marketplace operated by the Li-Truongs. Her primary focus is tightening fulfillment controls. Supply chain delays and inconsistent production quality damaged customer retention during the label’s prior expansion.

    Bachmann oversees design and inventory architecture after managing product lines during the brand’s peak valuation period. Her team is consolidating suppliers. The push aims to shorten production cycles and ensure consistent garment sizing across manufacturing batches.

    Relaunch collection and product lineup

    The digital storefront resumes trade at 9am on November 6 with the Girls Gone Wild collection. Registered waitlist members receive early access on the evening of November 5.

    Core proprietary textiles return with the range, including high-compression Nandex and lightweight Airlyte fabrics. Sizing spans Australian sizes 4 to 24. Updated garments will also feature a wider, bolder logo as part of the visual repositioning.

    Navigating brand trust in direct-to-consumer fashion

    Don and Matilda Robertson founded Stax in 2015, pivoting from a bankrupt sports supplement venture into apparel that reached a 52 million Australian dollar valuation by 2022. Aggressive physical store expansion, high commercial rents, and falling discretionary retail spending triggered a cash crunch. The company entered receivership in June.

    Across the Asia-Pacific region, the bailout serves as a test case in rebuilding consumer trust after insolvency. Offering store credits rather than leaving shoppers as unsecured creditors represents a direct customer acquisition cost. The strategy aims to convert burnt shoppers into repeat buyers.

    Customer account verifications remain open through December 31, 2026, ahead of redemptions running into mid-2027.

  • China Warns UK of Firm Retaliation over Electric Vehicle Tariffs

    China Warns UK of Firm Retaliation over Electric Vehicle Tariffs

    China’s Ministry of Commerce threatened countermeasures against Britain on Monday if London introduces import duties on Chinese electric vehicles. The warning follows British trade minister Anas Sarwar’s remarks confirming ongoing discussions with European partners over potential alignment with European Union tariffs of up to 45.3 per cent.

    Beijing urged the UK to follow World Trade Organization rules and maintain equal trade terms rather than copying Brussels. Automotive cooperation between both countries relies on complementary strengths, the ministry said in an official statement.

    “China will closely monitor the UK’s actions. If the UK insists on imposing restrictions on Chinese EVs, China will take firm countermeasures to safeguard the legitimate rights and interests of its industry,” the ministry said.

    London weighs European market access

    British officials are balancing domestic trade ties with European supply integration. London wants British manufacturers included in the EU’s Industrial Accelerator Act, a framework giving local production preferential access to public procurement programs.

    Exclusion from that initiative would penalize vehicle assembly operations across Britain. To secure access, EU negotiators asked London to align vehicle tariffs directly against Chinese carmakers, turning trade protection into an entry fee for European industrial policy.

    Retaliation risks for British exporters

    British Business Secretary Jonathan Reynolds acknowledged the friction in September, pointing out that the domestic automotive manufacturing base relies heavily on export markets. Any Chinese tariff retaliation would hit British luxury vehicle shipments hard, slicing into margins for premium brands that count China as their primary profit engine outside Europe.

    For Chinese original equipment manufacturers, losing tariff-free access to Britain would alter dealer pricing models and compress gross margins on mass-market models like the MG4 hatchback. Importers would have to absorb the cost difference or pass price increases to British car buyers, dampening EV adoption rates across consumer segments.

    The fallout from the 2024 duties

    Brussels imposed definitive countervailing duties on Chinese battery electric vehicles for five years in October 2024. Those levies added between 7.8 per cent and 35.3 per cent on top of standard 10 per cent baseline import duties, pushing total import taxes to 45.3 per cent for affected producers.

    Britain chose not to replicate those duties at the time, keeping its market open and becoming an essential European distribution hub for Chinese automakers. The European Commission subsequently urged London in September to eliminate that regulatory gap.

    Expansion plans continue regardless

    Chinese brands are pressing ahead with British retail distribution networks despite the regulatory dispute. Chery plans to introduce its iCar brand into the UK market under the name iCaur with the launch of the V27 in early 2027.

    That rollout will represent Chery’s fifth distinct brand trading in Britain. Whether those vehicles face standard import duties or double-digit countervailing penalties depends on the final terms London negotiates with Brussels over the coming months.

  • Southeast Asian Startups Face Capital Shortage as Investment Shifts to US and China

    Southeast Asian Startups Face Capital Shortage as Investment Shifts to US and China

    Southeast Asian startups face an acute capital shortage as venture funding shifts toward technology markets in China and the U.S. Investors pulled back after the pandemic as capital costs rose, leaving regional operators struggling to expand beyond domestic borders.

    The downturn hits businesses that attracted capital during the early 2020s, when young populations, rapid economic growth, and wider mobile phone use initially drew international funds.

    Global Capital Diverts to Artificial Intelligence

    Venture capital allocations redirected sharply toward artificial intelligence in the U.S. And China, while governance scandals in Indonesia and opaque legal systems compounded the regional retreat.

    Higher global capital costs compounded the contraction. Investors who once funded multi-market rollouts across the region now demand immediate cash flow generation and tighter overhead controls from portfolio companies.

    Regulatory Friction and Market Limits

    Structural barriers inside regional economies limit cross-border scaling for young firms. Founders and investors point to opaque bureaucracy, restrictive legal frameworks, and persistent friction in attracting foreign entrepreneurial talent as recurring obstacles across key markets.

    Regional fragmentation forces businesses to navigate distinct regulatory regimes in each country. That friction prevents local software, retail tech, and platform businesses from reaching the scale required to appeal to global investor syndicates.

    Governance Concerns Dampen Investor Appetite

    High-profile corporate governance scandals, particularly in Indonesia, damaged institutional confidence across the regional startup ecosystem. Due diligence processes lengthened substantially as international funds reassessed risk premiums across Southeast Asian growth assets.

    The current retreat follows an aggressive capital influx during the early 2020s. Cheap capital, young populations, fast-growing national economies, and accelerating smartphone adoption drove heavy valuations across regional platforms during that cycle.

    Scrutiny Centers on Near-Term Profitability

    Venture funds operating in the region are conditioning fresh financing rounds on unit-level profitability rather than top-line transaction volume. Early-stage and growth-stage companies face compressed valuations as they adjust burn rates to survive extended funding gaps.

    Founders across Southeast Asia now face the task of securing bridge rounds and domestic capital before existing cash reserves run out.

  • CP Axtra to Roll Out Five Food Chains Across Makro and Lotus Stores

    CP Axtra to Roll Out Five Food Chains Across Makro and Lotus Stores

    Thai retailer CP Axtra partnered with Minor Food Group in October 2026 to introduce five restaurant brands across select Makro and Lotus stores.

    Under the corporate franchise agreement, CP Axtra will invest in and own the outlets, while Minor Food will manage operations across Dairy Queen, Swensen’s, Gaga Cafe, Bonchon, and The Steak & More.

    Benchawan Ongsri, chief mall officer of CP Axtra, said the partnership deepens collaboration between the two companies under CP Axtra’s Happy & Healthy Mall development strategy.

    How the Corporate Franchise Framework Works

    This arrangement alters standard retail leasing. Instead of acting as a commercial landlord collecting tenant rent, CP Axtra commits capital expenditure directly into restaurant buildouts. Minor Food provides its operational workforce, ingredient supply chains, and management systems across each brand.

    Minor Food operates more than 3,000 restaurants across 25 countries. The group brings established operational protocols to the partnership. In turn, CP Axtra provides prime floor space and immediate customer footfall from its existing grocery shoppers.

    Changing Commercial Terms for Mall Footprint

    Hypermarket operators rarely monetize secondary retail space through this structure. Traditional lease models leave landlords vulnerable to tenant turnover and vacant restaurant units when regional consumption slows. By purchasing franchise rights and paying Minor Food to manage the locations, CP Axtra captures dining sales revenue directly while controlling its tenant mix.

    For Minor Food, the framework secures access to high-footfall grocery properties without burdening its balance sheet with fit-out capital. CP Axtra absorbs the capital risk of store buildouts. Minor Food assumes the operational execution risk across the joint sites.

    Building Out the Happy & Healthy Mall Network

    CP Axtra runs the wholesale chain Makro alongside the Lotus’s supermarket and hypermarket network. The company has steadily remodeled existing properties into lifestyle-focused shopping centers designed to increase customer dwell time beyond routine grocery trips.

    Established fast-casual and dessert brands give CP Axtra dependable footfall anchors. Quick-service dessert concepts Dairy Queen and Swensen’s capture incidental purchases from supermarket shoppers. Casual dining formats Bonchon and The Steak & More draw evening family trade.

    Next Steps for Store Conversions

    Rollout plans begin across high-potential Makro and Lotus’s branches nationwide, prioritizing urban centers with verified footfall data before expanding into provincial hubs. Store opening schedules and initial site selections in Bangkok and key provincial centers will determine the pace of the joint expansion.

  • Coles Adopts MTick Menopause Label Across 200 Products in Australia

    Coles Adopts MTick Menopause Label Across 200 Products in Australia

    Coles will introduce MTick menopause certification across more than 200 items in Australian stores and online, partnering with advocacy group GenM to standardise product labelling for midlife women.

    The agreement covers food, skincare, personal care and dietary supplements across an Australian market where GenM estimates 4.5 million women currently navigate perimenopause and menopause.

    Implementation begins with an online educational hub before purple MTick identifiers appear on physical shelves and digital storefronts early next year. The accreditation scheme checks products against 48 recognized symptoms of menopause, including sleep disruption, skin alterations, dry eyes, cognitive fatigue and intimate health needs.

    Shelf Signage and Digital Hubs

    Physical stores will install dedicated point-of-sale badging to help consumers spot qualifying inventory quickly during routine grocery trips. Online, Coles will index qualifying lines into dedicated search filters linked to informational guides detailing common physiological transitions.

    GenM manages the certification process, vetting third-party formulations against ingredient standards and consumer testing guidelines before clearing items to display the purple symbol. Brand owners pay verification fees directly to the standard holder to qualify individual product lines for placement.

    The GenM Standard and UK Precedents

    British grocers and pharmacies created the template that Coles is now transplanting into the southern hemisphere. Retailers including Tesco, Asda, Sainsbury’s and health-and-beauty chain Boots already display MTick iconography across an international inventory pool exceeding 4,000 certified stock-keeping units.

    For Australian retail operators, category tagging creates margin opportunities in aisles that historically functioned as low-margin convenience stops. Supermarkets can capture wellness revenue by aggregating high-margin items such as targeted serums, magnesium formulations and sleep supplements into visible health sub-categories.

    Pharmacy Competition and Category Margins

    Pharmacy chains built Australia’s baseline market for dedicated wellness merchandising, leaving grocers to fight for basket share. Community pharmacy group TerryWhite Chemmart previously added MTick shelf tags to recruit shoppers seeking guidance on hormonal health transitions.

    By establishing certified shelf space in high-frequency supermarkets, Coles puts direct commercial pressure on independent pharmacies and banner groups that rely heavily on discretionary personal care sales. Suppliers must now balance slotting allowances and certification audits if they want shelf access in both distribution channels.

    Rollout Schedule and Brand Recruitment

    Health and beauty manufacturers in Australia have spent recent years reformulating private-label and branded ranges to satisfy rising demand for transparent personal care claims. Several local brands secured MTick approval ahead of the supermarket launch to guarantee distribution when shelf changes take effect.

    Coles plans to begin deploying the online resource centre in early 2027, followed by storewide rollouts of shelf tags as certified supplier stock enters its distribution centres.

  • Xpeng Begins Mona L03 European Deliveries with First Handover in France

    Xpeng Begins Mona L03 European Deliveries with First Handover in France

    Xpeng handed over its first Mona L03 in Paris, opening European customer deliveries for an electric crossover priced at 35,600 euros. Chairman and chief executive He Xiaopeng presented the keys personally on October 13 before meeting with local dealer partners.

    The Paris handover tests whether European drivers will pay 35,600 euros, or roughly 40,030 dollars, for a Chinese electric vehicle whose base version sells in China for 123,800 yuan, or about 18,420 dollars. European specifications include battery-electric power and the integration of Google Maps Auto SDK for real-time traffic and route planning, whereas domestic buyers also have access to an extended-range electric powertrain option.

    Pricing and the dealer network

    Local dealership partners will manage customer distribution in France, though Xpeng did not reveal how many orders the Mona L03 has accumulated across the country. European dealer groups have embraced Chinese brands to offset slowing consumer demand for domestic European electric models, yet retailer margins remain tightly squeezed by distribution costs and regional tariffs.

    He discussed long-term supply schedules with French dealership executives following the handover. The unnamed first French customer selected the vehicle primarily for its proprietary driver-assistance software suite, according to company statements that omitted the specific trim level delivered.

    Export volumes and showroom strategy

    Chinese electric vehicle makers are accelerating overseas rollouts to escape brutal price discounting across their home market. BYD and Geely have flooded continental showrooms with compact sport-utility vehicles, while Xpeng is betting that driver-assist software and competitive sticker prices will win over mid-tier buyers. The Mona L03 represents Xpeng’s bid to transition from premium niche exporter to high-volume player across 64 planned overseas territories.

    Selling a mass-market badge in Western Europe carries real channel risks. Distributors face established Japanese and European competitors with dense servicing operations, while buyers remain cautious about the resale values of newer Chinese automotive imports. Establishing local fleet and retail networks across France requires steady component shipments and heavy showroom subsidies that will test the Guangzhou-based manufacturer’s operating balance sheet.

    Expanding the overseas footprint

    Munich served as the launchpad for the Mona L03 on July 16, when the crossover became Xpeng’s first product to debut simultaneously in Europe and China. On October 11, the company introduced the model to Australia and New Zealand, making it the third vehicle in those markets alongside the G6 crossover and X9 multi-purpose vehicle.

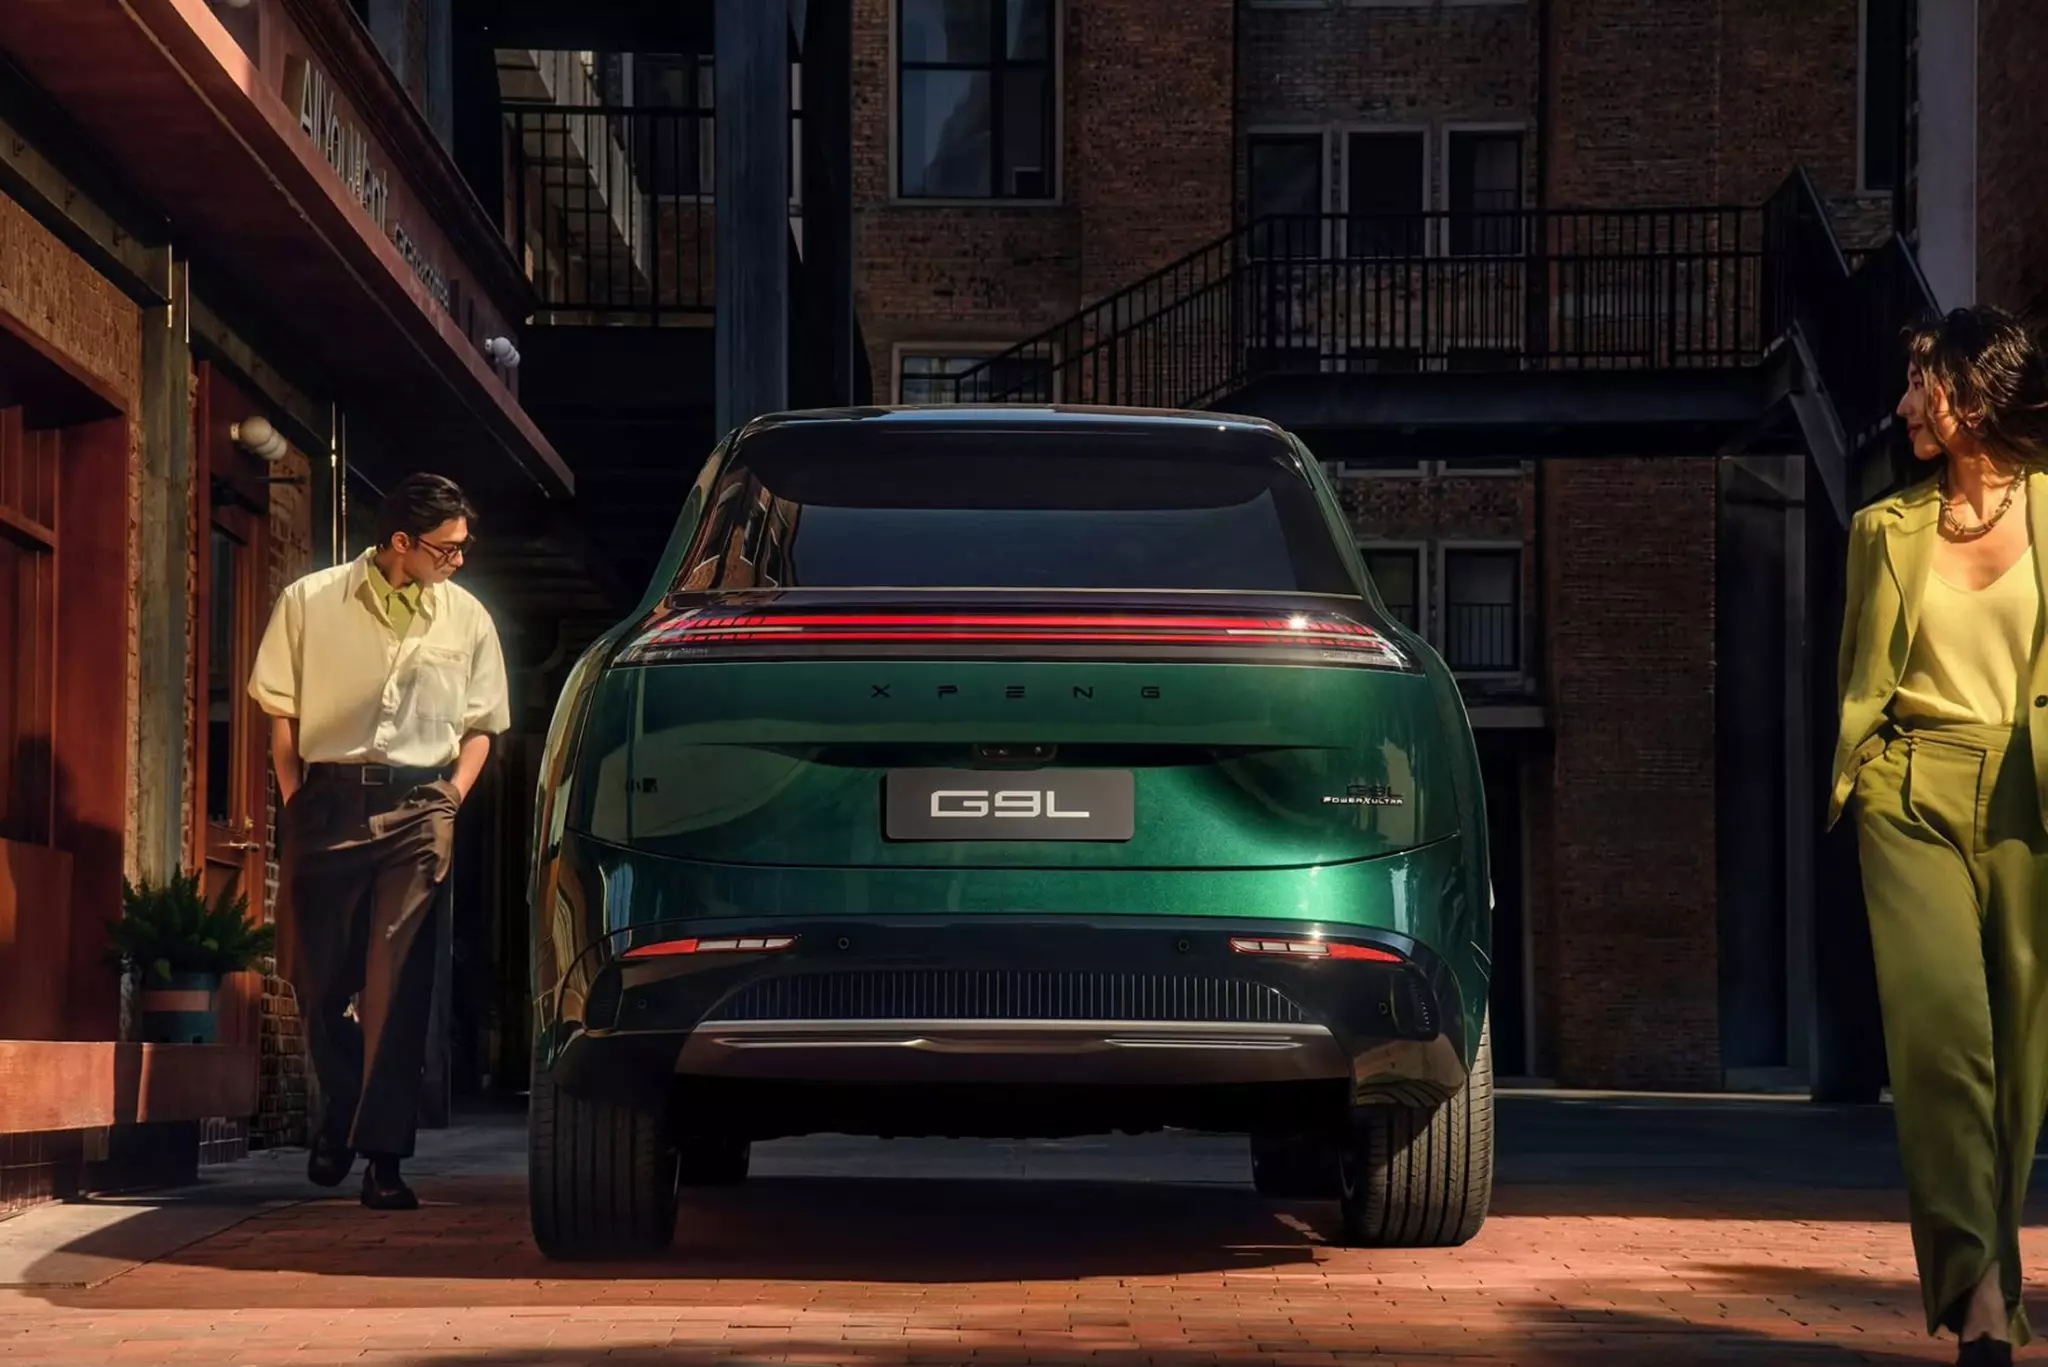
    Global demand helped push Xpeng’s monthly export deliveries past 10,000 units for the first time in September. That overseas surge reflects wider territory gains, including the Middle East where recent GX shipments passed 3,000 units, alongside the European introduction of the larger G9L sport-utility vehicle on October 12.

    The long-term sales targets

    Senior management has set a public target of selling 1 million vehicles annually by 2030, expecting European showrooms to supply half of that total volume. Delivering 500,000 cars a year in Europe requires vast scale across right-hand and left-hand drive territories, backed by dependable service logistics.

    Showroom momentum now shifts to the newer Mona L05, which opened customer pre-sales on October 15 to reinforce fourth-quarter deliveries. The carmaker’s next operational test will be the release of full European delivery figures for the final quarter, showing whether the Paris handover was an isolated photo opportunity or the start of sustained volume.