Author: Mei Ling Tan

  • Samsung Scores 91 Points to Top Consumer Reports TV Rankings

    Samsung Scores 91 Points to Top Consumer Reports TV Rankings

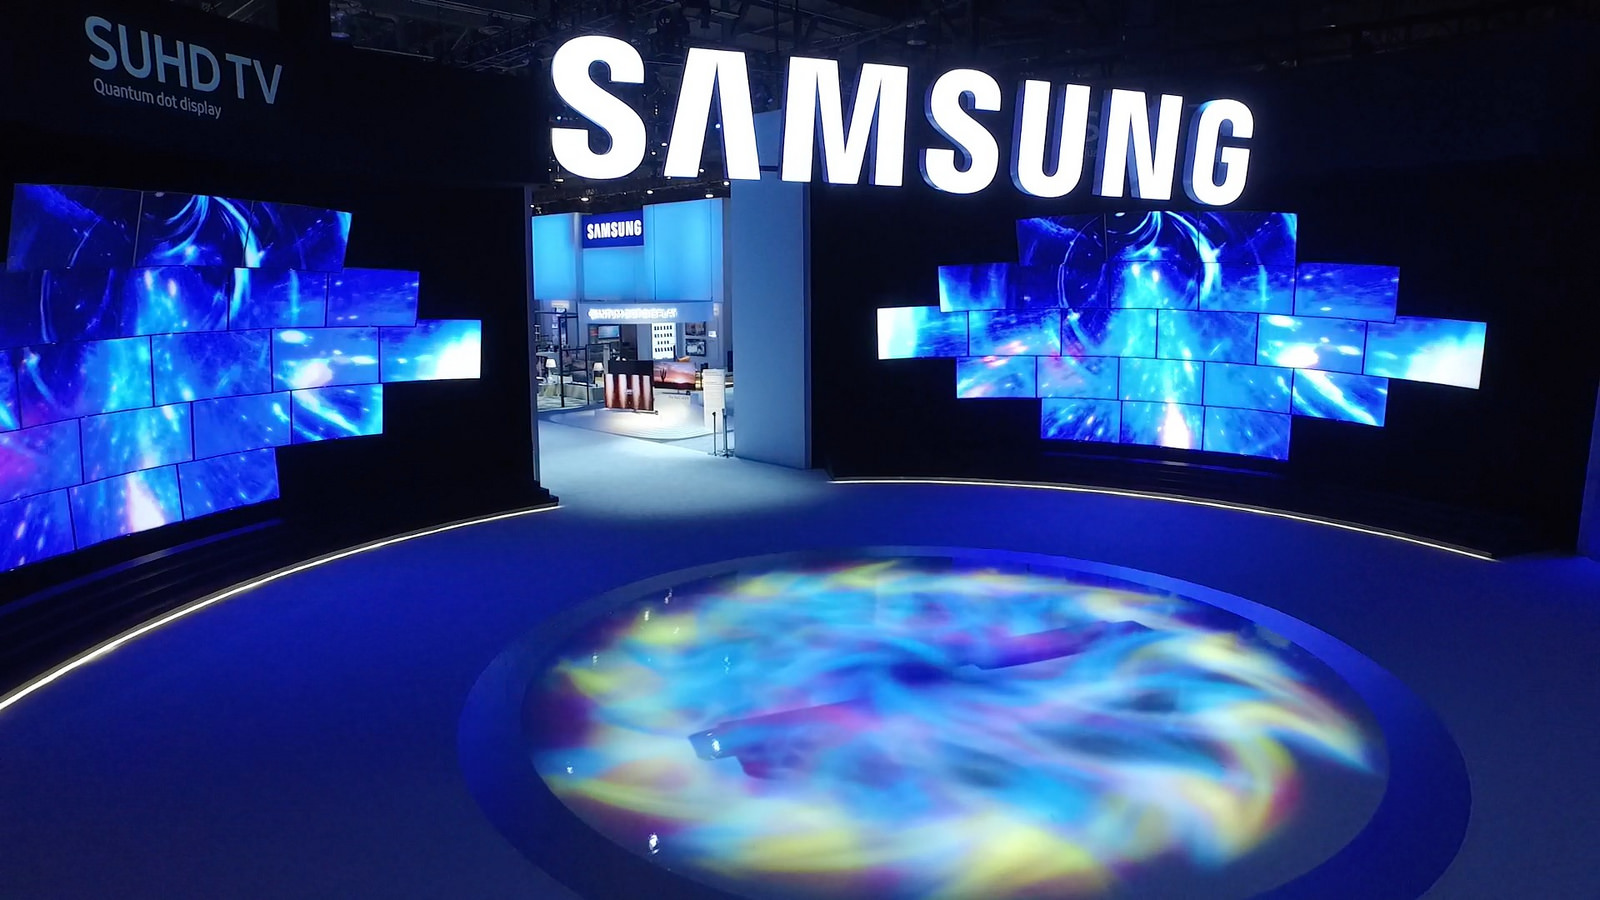
    Samsung Electronics Co. Secured first place across every screen-size category in Consumer Reports’ rankings, spanning sets measuring 70 inches or larger down to compact 32-inch displays.

    The US testing organization assessed 358 television models in its 2026 report, which was released last month to measure resolution, voice recognition and support for streaming services.

    Samsung’s QD-OLED TV, the QN65S95H, led the overall field with 91 points. Consumer Reports described the model as “one of the best TVs consumers can buy today,” highlighting upgraded brightness over its predecessor alongside 165-hertz refresh rates and a 4.2.2-channel Dolby Atmos sound system.

    Premium Panel Economics

    Sweeping an independent test run by an influential North American product testing agency provides critical commercial ammunition for consumer electronics retailers across Western export destinations. Big-box merchants and online storefronts rely directly on third-party assessment scores to defend premium shelf space against aggressive pricing from Chinese manufacturers.

    Maintaining pricing power in large-format OLED panels remains essential for South Korean manufacturers navigating tighter margin pressure across mid-tier liquid-crystal product lines. For retail buyers and showroom managers, an endorsement across both compact 32-inch sets and ultra-large displays simplifies vendor inventory allocation ahead of peak holiday promotional quarters.

    QD-OLED Generation Lineage

    The top-ranked QN65S95H builds directly on the commercial footprint established by its catalog predecessor, the QN65S95F. That older model secured strong purchase recommendations for balancing high dynamic range imaging performance and integrated audio against a competitive shelf retail price.

    The newer iteration gained decisive separation by pairing high-frame-rate processing with higher peak brightness, addressing historical consumer reservations regarding OLED panel visibility in brightly illuminated domestic living rooms.

    Display Margins and Retail Allocation

    Retail buyers now turn attention to fourth-quarter retail shipment volumes and promotional discounting thresholds across North American big-box electronics chains. Storefront inventory splits between QD-OLED units and lower-cost Mini-LED alternatives will determine retail gross margin realization as consumer discretionary spending patterns tighten.

  • Only 35 Percent of Gazipur Garment Factories Open on Friday

    Only 35 Percent of Gazipur Garment Factories Open on Friday

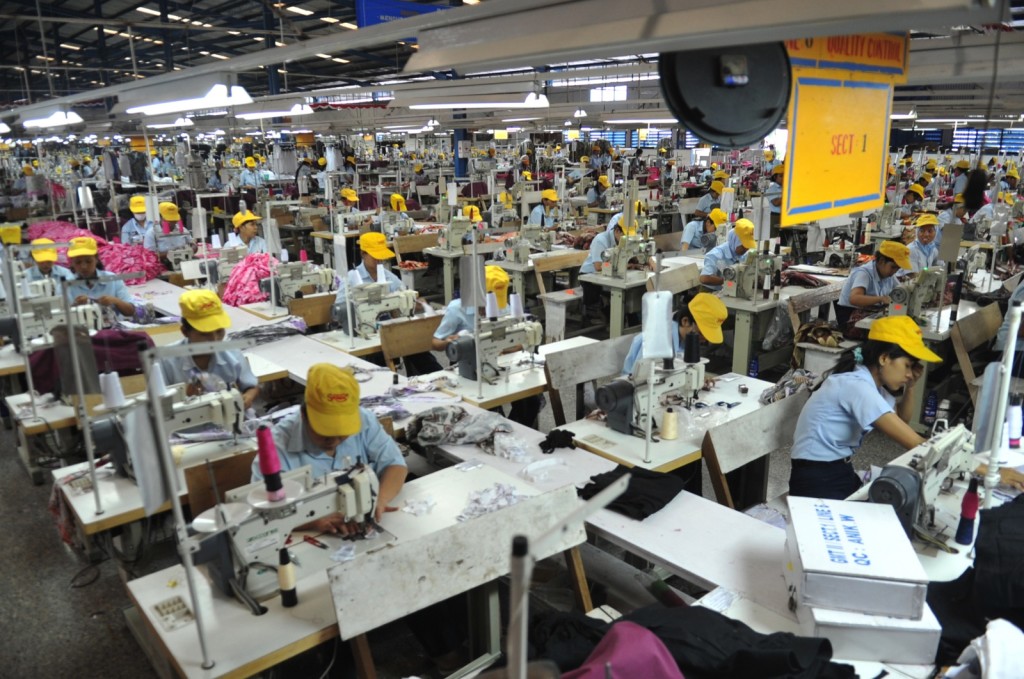
    Garment manufacturers in Gazipur operated only 35 percent of their production facilities on Friday as widespread factory shutdowns sent assembly line workers home across Bangladesh’s core apparel belt.

    Amjad Hossain, superintendent of Gazipur Industrial Police, confirmed the operating rate at 10:00am, leaving roughly two-thirds of the district’s export factories idle along key transport arteries including the Dhaka-Mymensingh Highway.

    Workers emptied out of the Taragachh industrial zone early in the morning after plant managers declared two-day closures. Ananta Garments suspended work at its Taragachh site, directing staff to leave the compound. Matrix Sweater in the Hajipukur area similarly halted operations for two days, citing local tensions.

    Uneven Operations Across the Cluster

    Disruptions remained selective rather than total across the manufacturing cluster. Parkstar Apparels and Parksin Bangladesh kept lines running in Barabari and Gachha, logging standard morning shift arrivals without incident.

    Freight corridors showed little physical obstruction despite the stoppages. Traffic Inspector Tarikul Islam reported clear vehicle movement through the Chandana Chourasta interchange, with commercial freight lanes operating normally throughout the morning.

    Sourcing Risks for International Buyers

    Sourcing directors across Europe and North America face immediate production bottlenecks when Gazipur pauses. The industrial hub accounts for a major share of Bangladesh’s readymade garment exports, serving global mass-market fashion brands that run tight inventory turns.

    When plants declare sudden multi-day shutdowns, delivery schedules for spring collections slip, forcing suppliers to absorb air freight penalties or renegotiate shipment windows. Sourcing desks at global fashion retailers are already monitoring South Asian capacity after months of volatile operating conditions in Dhaka’s satellite hubs.

    Production Continuity in Question

    Factory floors in Gazipur have experienced repeated friction between management and labour over working conditions, wage settlements, and local safety. Industrial police superintendent Amjad Hossain noted that Saturday coincides with a scheduled government holiday, giving operators a natural operational pause.

    A decision on whether garment factories would remain closed on Saturday would be announced this afternoon.

  • Japan Nominal Wages Rise 4.6% in September in Fastest Gain Since 1997

    Japan Nominal Wages Rise 4.6% in September in Fastest Gain Since 1997

    Japanese nominal wages grew 4.6% year-on-year in September, recording the fastest growth rate since 1997 as widespread staffing shortages forced employers across the country to pay higher rates.

    Base pay climbed 3.7%, while a benchmark stripping out bonuses, overtime, and sampling distortions rose by a record 3.1% for full-time staff, according to data from the Labour Ministry released on Nov 6.

    Inflation-adjusted real cash earnings, excluding rent, increased 2.2% from a year earlier. That beat consensus forecasts of 1.3% and accelerated past the revised 1.6% rise logged in August, despite fewer working days during the month.

    Central Bank Tightening on the Horizon

    The acceleration gives the Bank of Japan clear room to raise its benchmark rate at its next policy meeting on Dec 18. More than 80% of surveyed economists anticipate a hike at that session.

    Median forecasts project the terminal policy rate will hit 1.75%, requiring two quarter-point increases. Other institutions, including BNP Paribas and J.P. Morgan Securities, forecast the rate will peak at 2.5%.

    Bank of Japan governor Kazuo Ueda confirmed underlying inflation sits broadly in line with the official 2% target, asking company management and labour groups to build that figure into upcoming negotiations.

    Squeezing the Small Business Operating Margin

    Consumer brands face a divergent operating environment across Japan. Higher take-home pay creates real purchasing power for urban workers who absorbed two years of sticky grocery and utility bills, lifting floor spending at major supermarket chains and suburban convenience stores.

    The cost side tells an entirely different story for independent shopkeepers, franchise operators, and logistics suppliers. Retailers cannot absorb an annual 3% to 4% base salary increase without hiking shelf prices, yet passing those costs along risks alienating cash-sensitive shoppers.

    The financial strain already shows up in business mortality tables. Tokyo Shoko Research counted 240 labour-linked corporate insolvencies in the first half of the fiscal year, a record high. More than half of those cases cited higher labour costs.

    Union Demands for the Next Shunto Round

    The September numbers follow three consecutive years in which Japanese trade unions secured wage increases topping 5%, breaking three decades of flat compensation that followed the asset bubble collapse of the early 1990s.

    The country’s largest labour union federation advised affiliates in October to demand wage increases near 6% for 2027. That stance sets a higher opening bid than the target established for 2026.

    Mitsubishi Research Institute researcher Yasunari Tanaka projected settlements in the next round will settle near 5%, matching the 2026 pace. Sustained pay gains at that level keep upward momentum behind consumer service costs.

    Subsidies and the Winter Retail Basket

    Prime Minister Sanae Takaichi faces a balancing act between supporting household spending power and protecting public finances. The government plans to taper petrol subsidies starting in December while restoring targeted relief for winter electricity and heating gas bills.

    The Bank of Japan’s October Tankan survey confirmed that corporate labour shortages match the tightest conditions on record. With open jobs outnumbering applicants across distribution hubs and retail shop floors, companies have little choice but to bid higher for shift workers.

    The central bank convenes to decide its benchmark borrowing rate on Dec 18.

  • Acer Targets 15% Consumer PC Growth in Taiwan Despite Rising Component Costs

    Acer Targets 15% Consumer PC Growth in Taiwan Despite Rising Component Costs

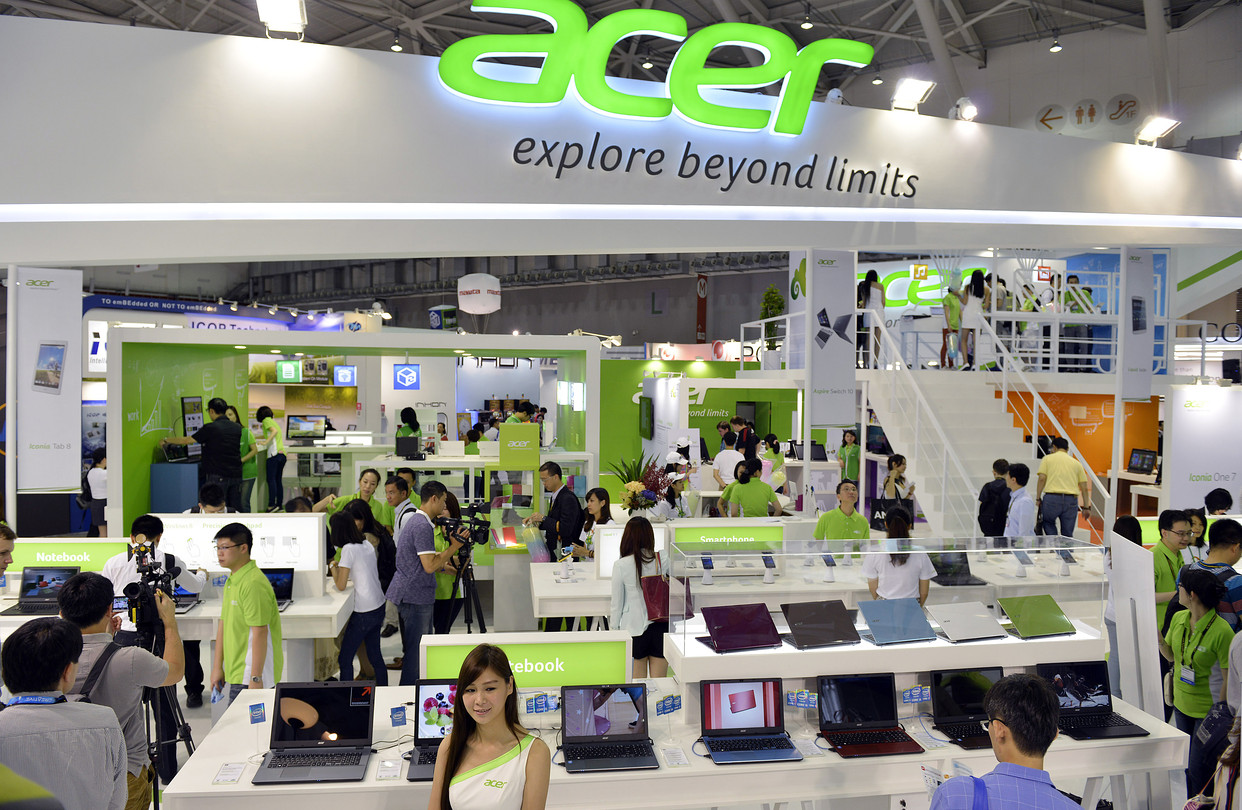
    Acer expects consumer PC shipments in Taiwan to increase by more than 15 percent in 2026, driven by Singles’ Day discount promotions and strong year-end demand.

    The Taipei-based hardware manufacturer matched that run rate through the first 10 months of the year, reporting 15 percent annual volume growth across the local domestic market.

    Rising component prices, particularly for memory and silicon modules, pushed average retail selling prices higher across the sector. Acer Taiwan brand product and marketing manager Wu Ke-chien said revenue growth would outpace unit volume gains as hardware manufacturers pass procurement inflation on to shoppers. The company is maintaining its target for shipment expansion above 15 percent through November and December despite component delivery bottlenecks.

    Component Crunch Reshapes Hardware Margins

    Processors, dynamic random-access memory and solid-state storage expanded to represent about 68 percent of the bill of materials for a 900-dollar mainstream notebook by late 2026, up from 45 percent early last year. Conventional memory contract prices are forecast to rise another 10 to 15 percent in the fourth quarter, while flash storage is projected to increase 15 to 20 percent. Preserving gross margins on comparable consumer hardware under those input cost conditions requires retail list price increases approaching 80 percent.

    Shortages are acute for discrete graphics cards and select mainstream central processors. Acer global headquarters allocates available inventory centrally across world territories, restricting local commercial pipelines. Discrete graphics models generate between 15 and 18 percent of Acer consumer notebook transactions in Taiwan, though company management targets 18 to 20 percent if component allocations improve.

    Assembly Moves Back to Mainland Plants

    Component inflation is forcing Asian electronics brands to reconsider their Southeast Asian manufacturing footprints. Rising memory expenses led brands including Acer, Asus and HP to transfer select consumer laptop assembly back to mainland Chinese facilities from factories in Thailand and Vietnam. The shift unwinds part of the diversified production footprint established across Southeast Asia amid US-China trade tensions.

    Total notebook production outside mainland China is slipping from 24 percent of global volume in 2025 to 21 percent in 2026, with research projections tracking a drop below 20 percent by 2027. Major Taiwanese original design manufacturers like Quanta Computer, Compal Electronics and Inventec are redirecting floor space toward server hardware. Enterprise servers accounted for over 80 percent of Quanta revenue in the second quarter of 2026, freeing PC contract orders for Chinese assemblers such as Luxshare Precision Industry, Huaqin Technology and Longcheer Technology.

    Display Niches and Retail Lineup Expansion

    Consumer demand patterns in retail channels are fragmenting into specialized hardware segments. Alongside artificial intelligence laptops, tablets and ultra-lightweight notebooks introduced for the Singles’ Day retail period, Acer expanded its portable external monitor portfolio with screen sizes between 14 and 23.8 inches. Portable screens secured a 20 percent share of Taiwan’s total external mobile display market, creating an unexpected retail volume driver.

    Securing low-cost silicon remains the deciding factor for regional consumer electronics margins. HP and Dell were qualifying DRAM from Chinese domestic supplier ChangXin Memory Technologies during 2026, while Acer and Asus asked Chinese production partners to source memory for some notebooks.

    Acer reported its strongest second-quarter revenue performance in 13 years earlier in July 2026, followed by a seasonal tablet shipment rebound in September. Full-year local results hinge on whether retail sales volume during the November Singles’ Day promotions and December holiday shopping cycles can hold the targeted 15 percent growth rate against rising shelf tags.

  • Robinsons Retail Expands Network Beyond 4,800 Outlets Across the Philippines

    Robinsons Retail Expands Network Beyond 4,800 Outlets Across the Philippines

    Robinsons Retail Holdings Inc. Now runs over 2,700 branches alongside more than 2,100 franchised pharmacy locations nationwide. Group president and chief executive officer Stanley Co leads the business alongside chair Robina Gokongwei-Pe and director Lance Gokongwei.

    Franchised storefronts under TGP The Generics Pharmacy form the 2,100-door network, while core corporate banners cover food, drugstores, department stores, hardware, appliances and electronics, toys, mass merchandise, beauty, pet retail, lifestyle sneakers and motorcycles.

    The business trace its start to a single Robinsons Department Store launched in Ermita in 1980 by late founder John Gokongwei Jr., who opened the retail location himself after prospective department store tenants declined to lease space in his commercial center.

    Scale Across Formats

    Today the multi-format structure handles volume purchasing across distinct supply chains, from neighborhood pharmaceuticals to shopping mall anchor units.

    Gokongwei-Pe, who entered the business in 1984 as a warehouse receiving clerk, logged 41 years of service alongside James Go at 46 years and Lance Gokongwei at 38 years. Go serves as vice chair, while Lance Gokongwei leads parent conglomerate Gokongwei Group.

    Logistics Realities and Operating Margins

    Running separate formats under one corporate umbrella forces Robinsons Retail to balance differing margin profiles and supply chain complexities. Grocery, pharmacy and mass merchandise demand rapid inventory turnover and tight distribution cycles, whereas fashion, footwear and consumer tech expose working capital to higher holding costs and obsolescence risk.

    Rival operators like SM Retail maintain denser exposure to large-format department stores and hypermarkets, whereas Robinsons has pushed aggressively into franchised medicine counters and neighborhood specialty niches. That pharmacy exposure delivers defensive cash generation when discretionary spending contracts, but franchise networks offer lower revenue per square meter than corporate-owned flagship boxes.

    Early Mechanics at Ermita

    Initial operations relied on basic manual systems and decentralized stock control. At the Ermita depot, manual inventory clerks handled physical receiving and handwritten documentation on carbon paper without automated backup power systems or barcode logistics. The group has since replaced those manual processes with central procurement workflows, integrated vendor management and dedicated inventory tracking across regional distribution hubs.

    Lance Gokongwei began on the department store floor ticketing apparel during the late 1980s before joining executive management. The group recently recognized 85 staff members who have spent 25 years or more with the operating company.

    Next Capital Milestones

    Management attention remains fixed on store expansion density across provincial growth corridors outside Metro Manila, particularly through drugstore additions and community supermarket footprints. Investors will track whether the retail holding firm can lift trading margins across its non-food retail banners as supply chain automation and direct vendor programs roll out nationwide.

  • Bridgestone Pushes Mining Tire Plants to Full Capacity

    Bridgestone Pushes Mining Tire Plants to Full Capacity

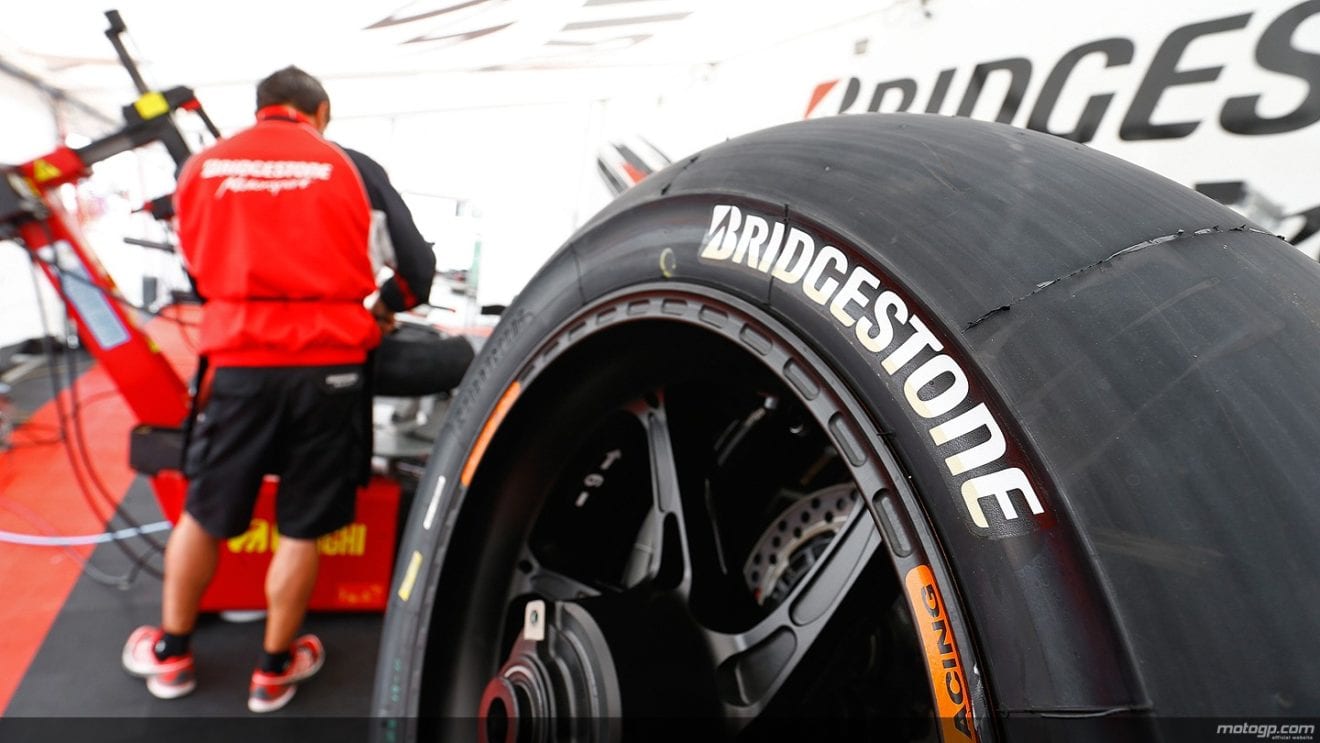
    Bridgestone is operating its specialized factories for large mining and construction equipment tires at nearly full capacity in November 2026, prioritizing high-margin lines to capture demand generated by artificial intelligence infrastructure.

    Output at the Tokyo-headquartered manufacturer’s Kitakyushu plant centers on ultralarge units that stand more than twice the height of an average person, built for heavy haulage operations.

    Management is directing industrial bandwidth toward off-the-road equipment servicing suppliers of copper, a critical conductor for data centers. The allocation links factory scheduling directly to capital expenditure across global digital infrastructure, where data facilities and related power equipment continue to drive raw metal extraction.

    Kitakyushu Capacity and Heavy Mining Volumes

    Industrial machinery tires represent one of the highest-margin categories in the global rubber sector. Producing them requires specialized curing presses and custom tooling, which limits how quickly competing manufacturers can match capacity spikes.

    Bridgestone has centered this production run on vehicles that service open-pit mines, where trucks transport hundreds of tons of ore per cycle. The wear rate on these sites requires steady tire replacement schedules, giving suppliers with immediate factory availability an advantage in long-term fleet contracts.

    By prioritizing massive haulage tires over standard industrial lines, the company protects operating margins against persistent raw material inflation. The specialized compound and steel cord formulations used in Kitakyushu command pricing power that consumer vehicle lines lack.

    Equipment Makers Expand US Support

    Equipment builders linked to the same mining corridors are expanding field support at a matching pace. Komatsu is moving to triple the size of its maintenance hub in the United States to handle repair work for mining machinery deployed across North American copper pits.

    The machinery maker raised its profit outlook on construction and mining demand across the Americas, while its finance leadership confirmed plans to increase equipment shipments into the region.

    Japanese heavy equipment suppliers are consolidating sales operations across regional corridors to protect market share. Trading house Itochu reached an agreement to acquire the Taiwan sales unit of Hitachi Construction Machinery, tightening its control over distribution channels as industrial equipment demand rotates across Asian and trans-Pacific logistics routes.

    Rival Pressures Across Automotive Segments

    Bridgestone is managing this mining ramp-up while its core consumer tire business faces low-cost competition across Asia. Japanese competitors are redirecting capital to counter cost-efficient Chinese manufacturing platforms.

    Yokohama Rubber is setting up lower-cost production facilities targeting BYD and other Chinese electric vehicle manufacturers. That strategy seeks volume at narrower margins, contrasting with Bridgestone’s capital allocation toward specialized, high-tonnage mining contracts.

    Bridgestone has simultaneously pursued alternative commercial formats in its home market. The company put its airless tire technology onto public roads in Japan following nearly two decades of technical trials, looking for durability gains in light urban transport while mining lines absorb heavy industrial investment.

    Capital Allocation and Fleet Exposure

    Focusing plant operations on copper extraction exposes Bridgestone to cyclical risks in metals demand. If data center buildouts slow or power grid procurement stalls, mining fleets quickly idle haul trucks and defer replacement orders.

    For now, lead times on heavy earthmover tires remain extended across North America. The immediate operating risk sits in factory flexibility, as running Kitakyushu near ceiling levels leaves little headroom if machinery failures interrupt production lines.

    Bridgestone’s operating balance sheet reflects the pivot toward high-specification industrial components. Maintaining nearly full utilization at Kitakyushu gives the manufacturer pricing use with global mining houses through the next contracting round.

  • Bitcoin Holds Near $75,600 After 6% Drop

    Bitcoin Holds Near $75,600 After 6% Drop

    Bitcoin held near $75,600 on Nov 6 following a sharp selloff that knocked the token down more than 6% from levels above $80,000. The broader retreat across risk assets followed weak chipmaker earnings and a Democratic sweep of the US Congress.

    Smaller tokens including BNB, Ether and Solana traded broadly flat during the session. Dip buyers emerged as a rebound in semiconductor equities steadied broader financial markets, even as economic figures fueled expectations that the US Federal Reserve will raise benchmark interest rates in December.

    Exchange Breach Rattles Market Liquidity

    Digital asset sentiment remains compromised by an October 29 security breach at Binance that saw $6.3 billion impacted. The incident hit confidence across centralized venues, compounding liquidations when macro market volatility accelerated.

    Mining companies that shifted operational capacity toward artificial intelligence data infrastructure over recent years saw equity routs in tech shares feed straight back into digital asset portfolios. Skepticism regarding the timing of returns on substantial artificial intelligence capital spending helped pull speculative funds away from growth assets across Asian and global trading desks.

    “Bitcoin appears to be finding some relief after yesterday’s sharp selloff, although I would be cautious about calling this a reversal just yet,” Dean Chen, an analyst at crypto exchange Bitunix, said in an e-mail. “I would describe the current move as selling pressure easing, rather than fresh accumulation taking hold.”

    Spot ETF Outflows Surpass $1 Billion

    Institutional investment vehicles absorbed heavy redemptions during the downdraft. US-listed spot Bitcoin exchange-traded funds recorded $430 million in net outflows on Nov 5, with the Fidelity Wise Origin Bitcoin Fund shedding roughly $200 million and BlackRock’s IBIT losing about $105 million.

    That withdrawal followed a combined $1.04 billion pulled from US spot funds over the previous Friday and Monday sessions, where BlackRock’s fund alone posted $405 million in exits. Liquidations erased speculative exposure, with approximately $996 million in used positions flushed from trading books during the market drop.

    Capital Allocation and Spillover Risks

    For financial institutions and regional digital asset desks in Asia, the convergence of security failures at large exchanges and political shifts in Washington alters the near-term regulatory baseline. Institutional capital that entered spot wrappers has demonstrated it will pull liquidity quickly when broader equity valuations wobble.

    The selloff also exposes balance sheet strain at mining operations that committed heavy capital expenditures to high-performance computing facilities. As tech valuations recalibrate, these hybrid operators face margin pressure from both softer token prices and cooling equity multiples.

    Earlier Pressure Across Central Venues

    The stabilization follows days of operational containment at Binance, which moved to cover the bulk of stolen assets before resuming token withdrawals. That intervention prevented widespread secondary failures across regional market makers, though custody risks remain front of mind for prime brokers.

    Trading desks now monitor the $77,000 threshold as the immediate technical mark required to establish forward momentum, while equity weakness leaves the $75,000 floor exposed to retesting.

  • BYD Unveils Yangwang Altior Sedan Priced at 2.08 Million Yuan

    BYD Unveils Yangwang Altior Sedan Priced at 2.08 Million Yuan

    BYD’s ultra-luxury marque Yangwang unveiled its flagship Altior executive sedan in Abu Dhabi on Saturday, opening pre-orders for a limited production run expected to cost 2,080,000 yuan.

    Securing an allocation for the initial four-seat “Shanhe Dingyun” edition requires a 300,000 yuan ($44,660) deposit from buyers in China, with total global deliveries capped at 399 units.

    A subsequent five-seat version will join the lineup later as BYD targets market share held by traditional benchmarks including the Maybach S-Class and Bentley Flying Spur.

    Cabin appointments and dimensions

    The vehicle measures 5,600 millimetres long, 2,030 millimetres wide, and 1,590 millimetres tall, with a wheelbase stretching to 3,500 millimetres. Coach doors open outward to nearly 90 degrees to clear passenger access, incorporating integrated umbrella compartments inside the door structures.

    Two individual rear seats sit divided by a central console, configured with integrated leg rests, champagne glass storage, and a dedicated rear command interface. Symmetrical woodwork, metal accents, diamond-quilted upholstery, and electric privacy sunshades finish the interior. The Shanhe Dingyun edition pairs brown rock and white jade cabin colours with Hetian jade air vent inlays, aramid fibre door panelling, gold speaker grilles, and cloud-patterned emblems.

    Powertrain and battery engineering

    BYD installed its second-generation Blade Battery in the chassis alongside high-output flash-charging systems designed to cut station dwell times. Chinese light-duty test cycle (CLTC) testing yields a driving range exceeding 1,000 kilometres on a single cycle.

    Yangwang has withheld whether the drivetrain relies solely on traction batteries or includes an internal combustion range extender. The exterior uses a two-tone paint treatment over enclosed aerodynamic wheels, floating centre caps, and a dot-matrix gemstone grille framed by Yangwang’s tripod-style front fascia.

    Competition in the top tier

    Choosing Abu Dhabi for the vehicle rollout confirms Yangwang’s intent to sell directly against the Bentley Flying Spur and the Maybach S-Class in high-net-worth hubs across Asia and the Gulf. Ultra-luxury margins provide substantial cash cover, yet buyers in the two-million-yuan segment historically demand generational brand heritage alongside mechanical performance.

    Convincing institutional fleets and chauffeured executives to abandon German and British badges remains an uphill commercial task. The limited run of 399 cars caps early inventory exposure, letting BYD test buyer price tolerance before ramping volume configurations.

    Sales scale and pipeline

    Hu Xiaoqing, general manager of Yangwang’s sales division, previewed the project under internal codename HU on October 21. The vehicle follows the brand’s earlier launches, including the U7 sedan and the four-seat U8L Dingcang Edition sport utility vehicle released in August.

    Scale across the marque remains narrow, with Yangwang delivering 3,546 vehicles through the first ten months of 2026. The production run now heads toward an unpriced five-seat Altior variant scheduled to enter commercial distribution once initial Shanhe Dingyun deliveries conclude.

  • Tada Enters Singapore Driverless Minibus Trial Starting in Early 2027

    Tada Enters Singapore Driverless Minibus Trial Starting in Early 2027

    Singapore ride-hailing company Tada Mobility has joined an autonomous minibus pilot scheduled to launch in early 2027 across the resort island of Sentosa. The initiative deploys driverless vehicles engineered by Chinese developer WeRide, matching moves by regional rival Grab into commercial autonomous services.

    An autonomous minibus destined for the Sentosa route was displayed during a media preview in the city-state on Oct. 29. Singaporean authorities continue to lean on self-contained tourism destinations to evaluate passenger safety, booking uptake and fleet management platforms before expanding trials into busier residential estates.

    The upcoming pilot brings autonomous public transport directly into Tada’s app ecosystem as leisure passengers navigate the island’s attractions. By introducing driverless shuttles to one of the country’s most frequented leisure corridors, the partnership tests whether holidaymakers will embrace automated mass transit for their daily transfers.

    Hardware and Route Rollout

    Vehicles built by China-based WeRide will operate on designated routes across the island resort, where tourist footfall provides dense, predictable transport demand. The platform previewed its autonomous minibus in Singapore on Oct. 29 ahead of route mapping and system certification.

    Tada plans to integrate booking options into its mobility ecosystem to study how leisure travellers interact with driverless public transport. Sentosa already acts as a test ground for private shuttle lines, monorail links and cable cars, giving operators a closed network to run trials without mixing directly into dense urban city traffic.

    The Race Against Regional Competitors

    Grab has pursued its own autonomous vehicle partnerships across Southeast Asia, testing self-driving technology alongside transport research institutes and automotive suppliers. By adding WeRide hardware, Tada avoids the heavy capital expenditure of building proprietary self-driving stacks, relying instead on proven Chinese vehicle platforms.

    For operators, the risk sits in fleet unit economics and battery charging logistics in tropical weather conditions. Driverless shuttles eliminate driver commissions, which form the primary cost line in private-hire operations, but they substitute labour costs with upfront vehicle financing, sensor maintenance and remote tele-operation safety staff.

    Regulatory Steps Across Singapore

    Singapore has tested autonomous buses and road-sweepers over the past decade under regulatory sandbox frameworks. Authorities require physical safety drivers or certified remote monitoring systems during all public demonstration phases.

    WeRide secured Singapore road-testing permits after testing its robotaxi and mini-bus variants on Chinese city streets. The Sentosa pilot represents its most visible commercial show for consumer-facing transport in the city-state.

    Next Steps for the Pilot

    Project engineers are completing route surveys and sensor calibration across Sentosa’s arterial roads ahead of the launch window. The passenger trial will measure route turnaround times, booking frequency and operational uptime across early 2027.

  • Hermès Birkin Fund Returns 24% by Flipping Handbags

    Hermès Birkin Fund Returns 24% by Flipping Handbags

    New York-based asset manager Luxus returned nearly 24 per cent on a $1 million fund devoted to flipping Hermès handbags, exploiting persistent scarcity in the secondary market.

    Over a 15-month span, the vehicle liquidated 52 of the 56 Birkin and Kelly bags it purchased, outperforming shares of Hermès stock, which tumbled more than 33 per cent across the same timeframe.

    Dana Auslander, a former Blackstone executive who founded the firm in 2021, engineered the strategy to capture the price gap created by primary retail hurdles. Because Hermès restricts direct boutique sales of its premier leather models to shoppers who build lengthy client profiles, secondary wholesalers clear inventory to impatient buyers at a markup.

    Sourcing Inventory in Japan

    Luxus runs an explicit secondary market arbitrage. The fund acquires bags at five to 10 per cent above primary boutique retail from Japanese trading houses, where strict legal penalties on counterfeit goods create an authenticated supply chain. It then offloads the stock through auction houses and consignment channels, including The RealReal.

    Japan has long served as the central clearing house for pre-owned luxury leather across Asia. Decades of strong luxury consumption left domestic households with deep reserves of pristine accessories, while strict enforcement by local police and trade bodies gives overseas buyers confidence on authentication.

    Physical custody introduces overhead unfamiliar to traditional liquid portfolios. The fund routes purchases through storage provider Uovo, which holds the inventory in climate-controlled sites. Independent authenticators and platform specialists review every bag before Luxus lists it for resale.

    Resale Yields Versus Boutique Headwinds

    Primary luxury operators face cooling transaction volumes in Mainland China, yet restricted handbag models continue to trade at substantial markups. While broader personal luxury spending contracted, tight workshop production in France guarantees structural scarcity for top-tier leather lines.

    Secondary trading desks capture price disparities that luxury brands deliberately leave on the table. Hermès exclusively manufactures its handbags and leather goods in French workshops, limiting supply and preserving brand equity but leaving secondary channels to monetize immediate consumer demand.

    Risks remain concentrated in exit timing and shifting collector tastes. Fractional platforms like Rally reported losses exceeding 1 million dollars on collectible asset valuations earlier this year, illustrating how quickly illiquid physical investments can sour when consumer enthusiasm cools.

    The Trajectory of Collectible Asset Funds

    Prestige watch values track a cautionary path. Secondary prices for Audemars Piguet, Patek Philippe Nautilus and Rolex references experienced steep contractions following an initial speculative surge during pandemic lockdowns, stranding funds that bought near peak valuations.

    Bernstein luxury analyst Luca Solca observed that while the arbitrage mechanics hold logic, equity markets offer an alternative path without physical carrying friction. Over the past 35 years, Hermès shares delivered a 16 per cent annualized return with total daily liquidity.

    Auslander is raising a 5 million dollar fund with a three-and-a-half-year mandate after rolling out a second vehicle holding 75 bags. Investors watch whether Japanese wholesale supply can maintain current buy-side margins as deployment capital scales up quintuple.

  • Alibaba Buys Minority Stake in Vietnam Beauty Retailer Hasaki

    Alibaba Buys Minority Stake in Vietnam Beauty Retailer Hasaki

    Alibaba has agreed to acquire a minority stake in Vietnamese cosmetics chain Hasaki, securing direct exposure to an omnichannel beauty network with more than 140 physical stores.

    According to a report on November 18, 2023, the transaction gives the Chinese retail giant direct access to a domestic beauty and personal care sector valued at $2.2 billion that is growing at 7 per cent annually.

    Hiep Dinh, founder and chief executive of Hasaki, confirmed the partnership with Alibaba International as modern specialty chains continue to displace independent merchants across Vietnam.

    Terms and Network Scale

    Hasaki operates a retail platform spanning its nationwide branch footprint, an e-commerce website, a mobile application and online store accounts. Ho Chi Minh City-based Koru Capital served as the financial advisor to Hasaki for the transaction.

    Hong Kong venture capital firm Excelsior Capital Asia previously backed the retailer, which was founded in 2016. As of November 2023, the chain counts 3.8 million members and has approximately 750,000 monthly shoppers.

    Modern Trade Displaces Independent Shops

    Vietnam’s beauty trade is shifting away from fragmented street shops and individual vendors toward standardised retail chains. Structured store networks offer verified supply chains, which matter to consumers wary of counterfeit products in personal care.

    Specialty chains also hold bargaining use against international beauty brands seeking reliable nationwide distribution. For commercial landlords, dedicated health and beauty outlets represent steady footfall drivers as shopping centres expand outside tier-one urban cores.

    Strategic Deployment in Southeast Asia

    Alibaba completed the transaction through Alibaba International Digital Commerce (AIDC), the business unit formed during the parent group’s corporate restructuring in March 2023. AIDC runs wholesale platform Alibaba.com alongside regional consumer operations including Lazada, AliExpress, Trendyol and Daraz.

    AIDC lifted its third-quarter 2023 revenue by 53 per cent year-on-year to $3.36 billion. Backing offline networks provides Alibaba with logistics and customer-acquisition infrastructure that purely digital storefronts struggle to duplicate efficiently.

    Competition for organised cosmetics sales in Vietnam has accelerated over the past three years. Mekong Capital backed local chain Beauty Box in 2021, following the market entry of Social Bella with support from L Catterton in 2020.

    Building Offline Reach in Vietnam

    The deal builds on previous capital deployments by Alibaba in Vietnamese consumer infrastructure. In 2021, Alibaba teamed up with BPEA EQT to lead a $400 million cash purchase of a 5.5 per cent stake in The CrownX, the integrated retail subsidiary of Masan Group.

    That transaction paired Lazada’s online channel with Masan’s grocery network, setting a precedent for integrating tech operations with brick-and-mortar shelf space.

    Hasaki has set a target to control at least 35 per cent of Vietnam’s domestic beauty and cosmetics market share by 2027.

  • Temu Joins Philippine Anti-Counterfeiting Pact Across 90 Markets

    Temu Joins Philippine Anti-Counterfeiting Pact Across 90 Markets

    Chinese e-commerce platform Temu has agreed to cooperate with the Philippine government to eliminate counterfeit goods from online marketplaces, signing a memorandum of understanding with the Intellectual Property Office of the Philippines (IPOPHL).

    The voluntary agreement creates a direct mechanism for intellectual property rights holders to report potentially infringing listings and coordinate removals with participating operators.

    Temu, which operates in more than 90 markets globally after entering the Philippines in 2023, joins regional competitors Lazada, Shopee, Zalora and TikTok Shop under the IPOPHL framework following preliminary talks in June.

    How the Takedown System Works

    Under the voluntary framework, rights holders submit suspected knockoffs directly to participating operators. Temu will then coordinate with the regulator and brand owners to verify complaints and take down listings.

    The company enters an arrangement that already binds Lazada, Shopee, Zalora and TikTok Shop. Together, those platforms account for the vast majority of cross-border consumer marketplace volume in the Philippines.

    “E-commerce platforms are a significant driver of consumer activity in the Philippines, making them important partners in protecting buyers and legitimate businesses from counterfeit goods,” IPOPHL Deputy Director General Nathaniel Arevalo said.

    Screening Database and Brand Protection

    Temu built out internal intellectual property controls ahead of the Manila agreement. The platform set up an IP Protection Portal in 2023 and rolled out its Brand Guardian Initiative in 2024, logging regular communication with more than 3,000 rights holders.

    Its backend screening database tracks more than 15,000 brands. That system uses 47 million reference images and 9.5 million keywords to catch infringements before or after products go live.

    Shifting Regulatory Pressure on Low-Cost Marketplaces

    Voluntary pacts give regulators faster takedown use without tying up cases in local courts. For discount platforms relying on direct-from-factory Chinese merchants, policing millions of bargain listings is the price of keeping local market access.

    Signing on brings Temu level with established Southeast Asian rivals on paper. The operational friction sits in enforcement: automatic keyword and image filters often miss rebadged consumer goods, leaving the burden of discovery on local brand owners.

    Timeline Behind the Manila Agreement

    Temu entered the Philippine retail market in 2023, competing directly with regional incumbents on cut-rate apparel, electronics and home goods. Talks with Manila officials gained traction in June during a World Intellectual Property Organization session on digital commerce.

    The next metric to monitor is the volume of formal takedown notices brand owners file through the IPOPHL portal once Temu integrates its notice-and-takedown workflow.

  • Sony Lifts Gaming Sales Forecast to 4.83 Trillion Yen

    Sony Lifts Gaming Sales Forecast to 4.83 Trillion Yen

    Sony increased its full-year sales forecast for its Game & Network Services division to 4.83 trillion yen, up 6 per cent from an earlier estimate of 4.54 trillion yen.

    In financial results released on 5 November for the second quarter of the 2026 financial year, the company also lifted its annual operating profit target for the segment from 660 billion yen to 700 billion yen.

    Higher sales of non-first-party titles, tighter cost management, and expanding revenue from PlayStation Plus network services drove the revision. During the July-to-September period, segment sales rose 9 per cent year on year to 1.21 trillion yen, while operating income jumped 83 per cent to 220.1 billion yen despite a decline in hardware sales.

    Network Software Offsets Console Volume

    Hardware demand moderated across the July-to-September quarter, yet Sony lifted margins by shifting its earnings base deeper into software purchases and recurring subscriptions. The corporate upgrade relies directly on royalties collected from outside publishers rather than its own proprietary game rollouts. Digital purchases eliminate standard distribution fees and physical disc pressing costs, keeping gross margins wider even when unit counts level off.

    Hardware remains the hook that locks consumers into Sony’s ecosystem, but the commercial weight has shifted to digital network access. Rival hardware makers face identical pressures as console lifecycles mature.

    Wolverine Sells 2.4 Million Units

    Sony disclosed opening sales figures for Marvel’s Wolverine, confirming the PlayStation 5 exclusive title sold 2.4 million copies globally across its first 50 days. The title was developed by subsidiary studio Insomniac Games and debuted on 15 September 2026. This release represents a separate superhero project following its Spider-Man series.

    That volume tracks below earlier studio debuts. Marvel’s Spider-Man 2 sold 2.5 million units in its opening 24 hours in October 2023, surpassing 5 million units within 11 days. The gap reflects both a standalone character rollout without established gaming sequel momentum and changing seasonal consumer demand patterns in early autumn.

    The Third-Party Pipeline

    The updated full-year forecast includes anticipated commercial tailwinds from outside studio titles, headlined by Rockstar Games’ Grand Theft Auto 6. Sony secured promotional alignment for the title, using PlayStation 5 marketing slots to pitch hardware features including haptic trigger resistance and spatial audio processing. Rockstar’s public distribution channels list both the PlayStation 5 and Xbox Series X and Series S as launch platforms.

    Consolidated digital storefronts capture a percentage cut of all third-party digital purchases, in-game spending, and add-on content without carrying development overhead. This cut cushions Sony’s balance sheet against volatile development schedules from its wholly-owned creative teams. The publisher carries none of the financial write-down liability if third-party production timelines stretch.

    Earlier Platform Performance

    The quarterly report follows a period where platform hardware volumes peaked earlier in the console cycle.

    The group’s operational attention now shifts to retail store channels and digital fulfillment when Grand Theft Auto 6 launches globally on 19 November 2026.

  • Bharti Airtel Misses Profit Forecast as Network Costs Climb 11 per Cent

    Bharti Airtel Misses Profit Forecast as Network Costs Climb 11 per Cent

    Bharti Airtel reported a second-quarter consolidated net profit of 88.88 billion rupees, equivalent to 940.45 million dollars, missing market expectations as network operating expenses rose.

    Consensus estimates compiled by LSEG projected net profit at 96.73 billion rupees for the three months ended September 30, even as total revenue increased 16.7 per cent to 608.78 billion rupees.

    Network costs jumped 11 per cent during the period, driven by the maintenance and operation of telecom infrastructure across the country. Licence fees climbed 13 per cent, pushing total quarterly expenses up approximately 15 per cent to 259.32 billion rupees. Consolidated profit nevertheless gained from the 67.92 billion rupees recorded in the corresponding quarter a year prior, though top-line growth could not fully cushion operational inflation.

    Tariff Limits and Premium Migration

    Average revenue per user increased 6 per cent year-on-year to 271 rupees, keeping Airtel ahead of domestic peers on unit realisations. The metric gained traction as the carrier added 18.8 million customers to its combined 4G and 5G footprint. Without broad-based tariff increases across the Indian market since July 2024, the business leaned on product pruning to lift receipts. Airtel removed several lower-tier prepaid denominations during the quarter, steering entry-level customers toward costlier recharge tiers.

    That migration strategy reflects the ceiling facing Indian operators until the next coordinated price adjustment takes place. Relying entirely on organic plan migrations carries friction, particularly as inflation pressures lower-income prepaid consumers. Brokerage Centrum projects an industry-wide tariff increase of 12 to 15 per cent across the next four to five months, an intervention that would directly feed operating margins.

    The Market Share Contest With Jio

    Competition across India remains defined by the pricing environment established since Reliance Jio entered the sector in 2016. Airtel closed the September quarter with an Indian customer base of 498.7 million, up 10.9 per cent year-on-year. That total leaves the operator trailing Jio, which commands 542.4 million subscribers.

    For mobile hardware distributors and digital platform operators, the divergence between the two dominant players shapes commercial exposure. Jio continues to capture volume across price-sensitive tiers, while Airtel defends higher-value urban and postpaid accounts through network coverage investments. Maintaining that premium positioning requires elevated capital allocation toward 5G base stations, driving the maintenance overhead that clipped Airtel’s quarterly earnings.

    Regional Support From African Operations

    International operations provided a counterweight to domestic margin compression. Revenue from Airtel Africa, which spans 14 countries across sub-Saharan Africa and delivers approximately one quarter of total group revenue, advanced 37.6 per cent.

    The current operating performance follows a prolonged period of post-auction network rollout across India, where capital spending on 5G spectrum and hardware converted into recurring maintenance obligations. While earlier quarters benefited from initial 5G user migrations, operating expenses have now caught up with network densification.

    Market attention now shifts to the timing of broad-based price adjustments, with operators balancing customer retention against the projected 12 to 15 per cent tariff revision expected before the end of the fiscal year.

  • Stolen Cloud AI Keys Hit Retailers and Tech Groups with Million Dollar Bills

    Stolen Cloud AI Keys Hit Retailers and Tech Groups with Million Dollar Bills

    Intruders who breach corporate cloud accounts are quietly activating dormant artificial intelligence tools and running models at company expense, running up bills exceeding 100,000 dollars in a day.

    Investigations carried out across 2026 by Mandiant and the Google Threat Intelligence Group revealed intrusions across Asia Pacific, North America and South America that reached cumulative costs of up to 1 million dollars before victims spotted the leaks. The compromises struck retail, transportation, financial services and technology companies that had adopted large language model architectures into their systems.

    How Illicit Resellers Drain Foundation Models

    The campaign, dubbed LLMJacking, relies on a distinct commercial division of labour within cybercrime rings. One group specializes in penetrating corporate environments to harvest credentials, while a separate tier operates illicit platforms known as LLM Mixers to resell that raw model compute to third-party subscribers.

    One service, trading under the name Jet Night, offered paying customers unlimited subscriptions for about 60 dollars a month to access premium foundation models. Comparable commercial access carries legitimate pricing between 100 and 250 dollars. Security investigators determined the syndicate could only sustain that price differential by powering the backend with stolen enterprise credentials.

    During a single intrusion linked to the network, an unauthorized actor channeled more than 500,000 queries to foundation models in under eight hours. The targeted enterprise absorbed an unauthorized token bill approaching 1 million dollars before discovering the drain. Jet Night subsequently recorded sudden outages on its Telegram broadcast channels whenever compromised businesses identified the breach and revoked the active keys.

    Another unauthorized syndicate set up a lookalike domain disguised as an internal corporate host, routing the victim organization’s application programming interface quotas into a commercial resale front operating as newapi.pro.

    The Shift From Cryptojacking to Token Hijacking

    Retailers and consumer tech operators have spent years guarding compute fleets against illicit cryptocurrency mining, but model hijacking works at vastly accelerated speed. Cryptojacking trickles away compute slowly to evade system detection, whereas LLMJacking generates massive spikes in fraudulent cloud charges in a matter of hours.

    Investigators noted that actors reach their goals through token proxying, automated model streaming and unauthorized graphics processing unit hardware provisioning. Rather than manipulating consumer-facing chatbots to spit out rogue lines of code, the attackers bypass the store front-end entirely to tap backend infrastructure.

    For retail and digital commerce platforms in Asia that connect real-time product search, automated customer query desks and dynamic inventory to foundation models, the financial exposure sits directly in the operating budget. Cloud quotas linked to corporate credit accounts or open enterprise billing agreements allow perpetrators to cash out instantly through black-market resale while the operator absorbs the invoice.

    Stolen Keys and Exposed Gateways

    Initial penetration rarely requires novel zero-day attacks. Threat groups scrape publicly exposed GitHub repositories for stray application programming interface keys, running minute test queries designed to avoid triggering usage alerts.

    Most intrusions stem from compromised cloud infrastructure credentials, including unprotected service account keys, active session tokens and corporate GitHub authorization tokens. A group tracked as UNC6993 gained access to a commercial cloud instance via a misconfigured service account credential, quickly bridging across into internal model endpoints. The same operators established a fraudulent registration portal for model developers, tricking visiting engineers into submitting live access tokens that circumvented multi-factor authentication controls.

    Once inside a corporate network, attackers search database tables and data warehouse systems for deeper administrative secrets, occasionally disguising backdoor accounts as internal cost-optimization utilities. In another instance, attackers targeted a vulnerability logged as CVE-2026-40217 inside a LiteLLM routing gateway, escalating basic user credentials into root administrative control.

    Dormant Services Turned on by Intruders

    In multiple forensic investigations conducted by Mandiant, the targeted companies had left their high-tier machine learning services deactivated. Intruders used administrative cloud credentials to switch on the dormant model engines, initiating high-frequency automated requests within minutes.

    The findings indicate that monitoring routine endpoint activity is no longer sufficient for digital commerce operators running hybrid cloud stacks. IT departments now face the operational reality that unmonitored API limits directly threaten gross margins, turning routine cloud administration into an immediate balance-sheet liability.

    Enterprises running production workflows across multiple public cloud providers must track anomalous model activation alerts and enforce hard spend caps on machine learning billing accounts to catch breaches before usage tallies reach six figures.