Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • DIBPL wins ‘Best Islamic Retail Bank in Asia’ award

    DIBPL wins ‘Best Islamic Retail Bank in Asia’ award

    The ceremony was also attended by the Presidents and CEOs of other Islamic banks as well. Junaid Ahmed said that Dubai Islamic Bank being the pioneer and leading Islamic banking institution globally is committed to the long-term prosperity of Pakistan and Islamic Finance as a whole.

    Junaid Ahmed said that DIBPL is a wholly owned subsidiary of Dubai Islamic Bank UAE, the world’s first Islamic bank. Alhamdulillah, DIBPL is a Minimum Capital Requirement (MCR) compliant bank that enjoys a short-term credit rating of ‘A-1’ and long-term credit rating of ‘A+’, with a “positive” outlook from JCR-VIS. He further stated that DIB UAE Group is one of the largest Islamic bank in the world total asset base of approximately over Rs 4.5 trillion (US Dollars 41 billion) at September 30, 2015.

    He further said that DIBPL intends to keep this momentum going for 2016 as well, aiming to take the overall branch footprint of over 250 locations nation-wide. This will enable more customer convenience and highlight the Bank’s endeavour for bring world class Islamic Banking at the customer’s doorstep.

  • What if…HSBC sold Hang Seng for BoCom deal?

    What if…HSBC sold Hang Seng for BoCom deal?

    Companies of China are increasingly focused on international expansion, at the exhortation of Beijing. Its desire to expand has helped support the international ambitions of local insurers such as Anbang and Fosun International, or securities firms such as Citic and Haitong. But one vital part of this sector has yet to demonstrate such assertiveness: China’s banks.
    Chinese individuals are remarking upon their meekness. The South China Morning Post reported that Li Ruogo, former chairman of the Export-Import Bank of China and now an executive vice-president at the International Financial Forum, claimed the international capabilities of China’s banks is not suitable for the needs of the nation’s outbound investments and acquisitions.

    Similarly, the newspaper reported that Ma She, deputy director of European affairs at the Ministry of Commerce, as criticising the banks for “underdeveloped” overseas branch networks and poor data sharing management.

    To date China’s banks have embarked on tentative acquisitions offshore, in South Africa and South America. But these have been small, and piecemeal.

    It looks unlikely the banks would ever unveil grandiose plans to buy a Deutsche Bank, or a Standard Chartered. Instead, for a truly transformational purchase they would be most likely to seek targets close to home.

    Hong Kong would be the most obvious immediate candidate, boasting geographic, financial and cultural ties. However, the city has relatively few decent-sized candidates that are obvious acquisition prospects.

    Bank of East Asia might be the most obvious potential target. However, the bank recently issued an exchangeable bond in its shares to Sumitomo-Mitsui Financial Group, effectively raising its stake to around 17.5%. That, combined with the Li family’s 11%, might make a takeover bid highly challenging, particularly given the likely reluctance of the Li family to sell out.

    But there is another possibility: Hang Seng Bank.

    Appealing acquisition

    Hang Seng’s biggest shareholder is HSBC. It bought a 51% stake in Hang Seng in 1965, after the latter was tottering following a bank run, and has subsequently raised this stake to 62.14%.

    As a result HSBC, which is by far Hong Kong’s largest retail bank, was responsible for 52% of Hong Kong loans (HSBC 40% and Hang Seng 12%) and 55% of deposits in 2014 (HSBC 44% and Hang Seng 11%), according to a report by Dagong Securities, published in May.

    The UK-headquartered bank holds Hang Seng at arm’s length, no doubt in order to avoid accusations of monopolistic practices. But it would be very reluctant to sell it. Understandably so; Hang Seng reported a profit of HK$20.05 billion ($2.59 billion) for the first half of 2015, had total assets of HK$1.3 trillion, while it was trading at 1.93 times price to book value on Wednesday, according to Bloomberg. It enjoys strong retail banking and insurance businesses and is growing in wealth management too.

    Acquiring Hang Seng would make a potentially appealing addition to a Chinese state-owned bank. It would offer the lender immediate scale in Hong Kong, North Asia’s leading financial centre. More importantly, Hang Seng would provide expertise in international banking practices and customer services.

    For Hang Seng, the backing of mainland lender with international aspirations would offer it the opportunity to flourish into commercial and retail banking outside of Hong Kong.

    Getting a sale done

    Hang Seng’s strength and financial stability means HSBC would be very reluctant to part with it. Yet it might be persuaded to do so for a large enough incentive.

    As it happens, Beijing could give HSBC what it may want most of all:  ownership of a local nationwide bank.

    The most likely is Bank of Communications. HSBC has owned around 19% of BoCom for years, and hoped to eventually get majority control, but these plans are currently impossible due to China’s 20% foreign ownership limit in its banks.

    Beijing could offer HSBC an exemption to its foreign ownership limits (potentially utilising the idea that HSBC’s local Hong Kong bank unit, The Hong Kong & Shanghai Banking Corporation, is applicable to buy larger stakes in China banks). Then it could sell HSBC enough shares to give it a controlling interest at a competitive rate (following, no doubt, a very thorough audit).

    In return, HSBC would agree to relinquish Hang Seng to a local bank for a similarly competitive valuation.

    The biggest challenge would be building enough political support for such a deal.

    It would likely require sanctioning by the State Council, plus the Ministry of Finance, State-owned Assets Supervision and Administration Commission and the China Banking Regulatory Commission. Additionally, the Chinese bank would need to agree to the purchase of Hang Seng Bank.

    However, if the political will could be found, it should be relatively straightforward to sell shares in BoCom to HSBC. The Chinese government owns 46.3% of BoCom, with the National Council for Social Security Fund owning another 4.78% and Sasac holding a further 4.66%, according to 4-traders.com.

    Securities fast track

    HSBC might ask for another favour in return for giving up BoCom: rapid approval of its new securities joint venture.

    The bank HSBC agreed to establish a joint-venture securities company with Shenzhen Qianhai Financial Holdings, of which it would own 51%, on November 2. However, the deal is subject to regulatory review and approval, which can take a long time – some JV players have been waiting years to get final approval on certain licences.

    Therefore HSBC would likely want fast-tracked approvals that gave its JV full underwriting, trading and wealth management access to China’s local capital markets.

    In addition to offering HSBC incentives, Beijing could also – if it so chose – place pressure on it to divest Hang Seng via the compliant politicians who run Hong Kong’s government.

    For all the operating separation of HSBC and Hang Seng, the fact remains the two comprise a dominant percentage of Hong Kong’s retail banking sector. In most countries this would cause antitrust concerns.

    Coincidentally, Hong Kong’s government introduced a new Competition Ordinance on December 14. International law firm Linklaters noted “the impact of the new law will grow over time, but it will ultimately lead to a more mature marketplace in which consumers will benefit through enhanced competition.”

    Costly acquisition

    Aside from political will, the biggest sticking point of any deal over bank acquisitions would be cost.

    Neither purchase would be cheap. BoCom had a market capitalisation of Rmb416 billion, or $64.13 billion, as of Thursday, giving it a price-to-book valuation of 0.94 times. Assuming BoCom’s balance sheet didn’t raise any major concerns, HSBC might spend $21.8 billion to raise its stake from 19% to 51%, assuming it paid on a par price-to-book valuation.

    Hang Seng is a bit cheaper. Its market capitalisation was HK$281.4 billion ($36.3 billion) on Thursday, giving it a price to book valuation of 1.98 times. At that valuation, a Chinese bank would need to pay $18.5 billion to gain a simple 51% majority stake from HSBC.

    To put those price tags into perspective, the largest banking M&A on record in Asia-Pacific, Westpac Banking Corporation’s $17.9 billion purchase of St. George’s Bank in 2008. Malaysia’s CIMB, RHB and Malaysia Building Society did discuss a three-way merger worth $22.3 billion in 2014, but the plan was scrapped early this year.

    Beijing would need to have a truly unshakeable desire to get one of its banks to expand internationally to sanction such an expensive M&A. And it would be hard for the Chinese government to cajole HSBC into such a sale without giving it in return the sort of local bank control it has thus far been unwilling to allow.

    But China appears keen to get its banks to support the expansion of its companies and the usage of its currency overseas. And HSBC really wants more mainland access.
  • Bank Simpanan Nasional and Cisco Digitise Banking in Malaysia

    Bank Simpanan Nasional and Cisco Digitise Banking in Malaysia

    Malaysia’s premier savings bank, Bank Simpanan Nasional (BSN), is transforming their products and services to appeal to a new generation of digital-enabled customers by deploying Virtual Teller Machines (VTM) across 31 branches. Built on Cisco® Unified Communication and Cisco Unified Computing platforms the VTM helps enable virtual, real-time engagement between customers and tellers in any of the branches, through a highly secure and immersive video platform.

    “The VTM balances the work load between branches, enabling customers in busy branches to perform transactions assisted by tellers in less busy branches nationwide. Customers can now enjoy counter transactions without geographical limitations and experience more comfortable and personalised professional financial services,” said Datuk Adinan Maning, Chief Executive of Bank Simpanan Nasional.

    Key Benefits to Digitised Teller Services

    Virtualising the services provided by in-bank tellers enables BSN to increase resources for the customer, increase bank productivity and most importantly, increase the efficiency of their organisation and the efficiency of service to their customers. Each BSN branch will have three VTM machines and these self-service kiosks that are supported by 450 virtual teller agents placed to assist their colleagues at branches that have higher customer traffic.

    The virtual tellers will be able to attend to customers’ needs, provide advice on banking products and services, and handle account inquiries as well as loan applications.

    The VTMs installed at BSN branches have highly secure features including encrypted electronic signature, thumb print verification, and card identification to ensure customers are protected.

    “The financial services industry is not immune to competition from market disruptors. Non-traditional financial institutions are delivering new digital services that are personal, customised and convenient. Malaysia is committed to transforming the economy through digitisation, and two critical aspects of the Eleventh Malaysia Plan — innovation to drive revenue and productivity acceleration for sectoral growth — are addressed with this implementation at BSN. By leveraging technologies from Cisco to drive a connected banking experience, BSN is leading the way in delivering greater value to their customers, appealing to the digital consumer, improving their productivity and efficiency, while increasing their revenue and customer base. The digitisation of bank branches is an important part of the Omni channel banking experience that transforms the customer’s transaction and increases their engagement with the bank,” said Albert Chai, Managing Director for Cisco in Malaysia.

    Built on the Cisco Business Edition 7000 unified communications platform that includes voice over Internet Protocol (IP), video through Telepresence with Cisco DX 650 and Cisco Jabber for chat functionality and presence, the VTM allows BSN employees to connect to their customers at any time during branch operation hours. The scalable, open and interoperable technologies are hosted on Cisco Unified Computing System foundation.

    “In total, BSN is investing RM30 million to roll out the VTM that provides more than 80 percent of counter services, and is an improvement over current automated teller machines (ATM) and cash deposit machines (CDM). In the near future, the VTMs will also be offering additional services including Account Opening and Debit Card, Customer Information Management and Bills Payment. The VTMs may also allow extended banking hours with the placement of VTMs at public locations,” continued Datuk Adinan.

    BSN customers will be able to use the new banking service in 31 branches, with 93 VTMs serving customers fromDecember 2, 2015.

    According to McKinsey, more than 700 million consumers currently use digital banking across Asia. With digital banking through desktops, smartphones, and tablets becoming much more common, consumers that prefer digital banking are more attractive to financial institutions as they tend to be more educated, have account balances that are two to three times higher, hold multiple banking products and are very active in online shopping. By digitising banking services through VTM machines, BSN is able to optimise technology to improve the customer experience and meet customer demand, while competing with emerging fin-tech start-ups.

  • Myanmar central bank to grant new foreign bank licences

    Myanmar central bank to grant new foreign bank licences

    The Central Bank of Myanmar plans to initiate a second round of foreign bank licencing in early 2016, the monetary authority said.

    The aim is to licence banks from “additional neighbouring and important trading partner economies”, quoted the central bank as saying.

    “The main objective of the second round of licensing is to further promote existing economic cooperation.”

    Foreign banks headquartered in countries that successfully obtained a licence in the first round – namely Australia, China, Japan, Malaysia, Singapore and Thailand – will not be allowed to participate in the second round, the notice said.

    Foreign banks with representative offices in Myanmar or which are in the process of obtaining one will be permitted to participate.

    The licence will be for onshore wholesale banking through a branch, and a call for expressions of interest will be made in early 2016, the Central Bank said.

    In the last, hotly-contested bidding round, nine foreign banks won licences on October 1 last year, and winners were given a year to prepare operations to meet the approval of the Central Bank.

    All of the banks – Bangkok Bank, Australia’s ANZ, Japan’s the Bank of Tokyo-Mitsubishi UFJ, Mizuho Bank and Sumitomo Mitsui Banking Corporation, the Industrial and Commercial Bank of China (ICBC), Malaysia’s Maybank, and Singapore’s Oversea-Chinese Banking Corporation (OCBC) and United Overseas Bank (UOB) have now opened branches.

    The licences came with a number of restrictions – banks are only permitted to lend to foreign businesses and local banks. They may team up with local lenders to offer additional services, but are prohibited from involvement in retail operations.

    This marked the first time that foreign banks have operated in the country for more than 50 years – Myanmar had not allowed onshore banking by foreign institutions since 1963, when 14 foreign banks were nationalised.

  • Hong Kong Regulates Mobile and Contactless Payment Systems

    Hong Kong Regulates Mobile and Contactless Payment Systems

    Hong Kong recently introduced a new regime to regulate stored value facilities (SVFs) and retail payment systems (RPSs) offered by non-financial institutions. The primary new legislation is the Payment Systems and Stored Value Facilities Ordinance (“Ordinance”), which amends and replaces the previous Clearing and Settlements System Ordinance. The Hong Kong Monetary Authority (HKMA) is now responsible for supervising the activities of non-financial institutions operating in this area.

    Issuers of multiple purpose SVFs must now obtain a specific approval and license from HKMA for such SVFs, regardless of whether these are operated through a device or not. However, an SVF which is used only for purchases from a single retailer remain exempt from this requirement. In addition, while there is no automatic approval and license requirement for RPSs, HKMA is entitled to decide on which RPSs will be subject to its regulation.

    The new regime seems to track the increasing use and proliferation of such new payment systems, as well as the increased risk of data loss and theft and fears that unnecessary personal data may be embedded and accessible within the chips in contactless cards.

    Companies operating in this area should check whether the new requirements apply to them and commence applications for licenses if necessary. While there is a grace period until November 2016 before penalties can be imposed, it is unclear how long the administrative processes will take in practice and there is a risk of significant fines or suspension of business for failure to meet the deadline.

  • First Visa token service launched in Asia-Pacific

    First Visa token service launched in Asia-Pacific

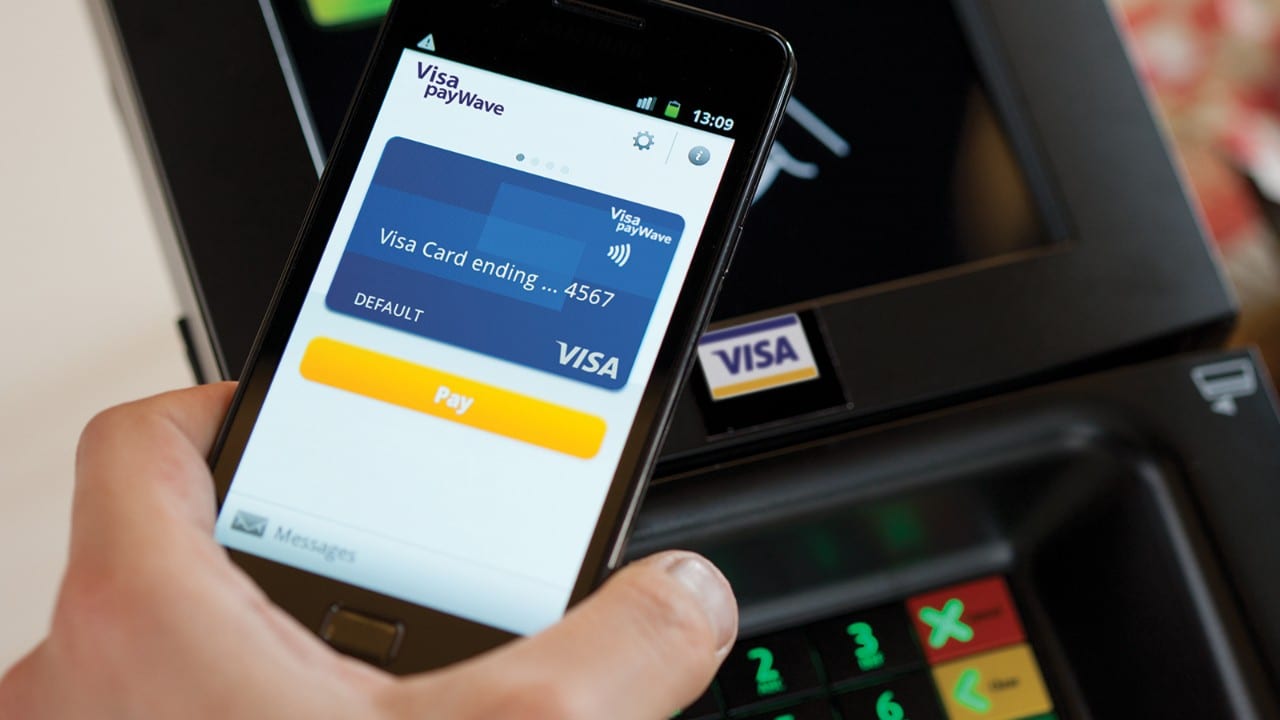
    Visa launched on Monday the first Visa Token Service in Asia-Pacific with the United Overseas Bank (UOB) as the first bank implement the service. 

    The service is a new security technology that replaces sensitive payment account information found on payment cards, such as the 16-digit account number, expiration date and security code, with a unique digital identifier or “tokens” that can be used to process payments without exposing actual account details.

    Visa cards that are tokenized are also domain controlled, meaning the tokenised card is linked to a consumer’s phone or wallet application and is validated in real-time by VisaNet, Visa’s global payment processing platform.

    Tokenisation was first introduced as a new global standard in October 2013 by Visa and other payment schemes to enhance security and simplify consumers’ purchasing experience.

    “We live in a connected world and with the rise of digitization, it is important the payments industry is focused on delivering a safe, secure, simple, and consistent consumer purchasing experience,” said T.S. Anil, Head of Product for Asia Pacific for Visa.

    “The Visa Token Service can help prevent fraud by offering financial institutions, merchants, and third party payment providers, such as digital wallet providers, a secure way to enable mobile and online payments without sharing sensitive account information,” he added.

    United Overseas Bank has implemented the Visa Token Service as part of its digital wallet UOB Mighty. The service allows its Visa credit or debit cardholders to make contactless payments with an NFC-enabled Android smartphone simply by launching the UOB Mighty app, selecting the “Pay” function, entering a PIN and tapping to pay at all NFC-enabled terminals in Singapore and overseas.

    “Consumers are increasingly attached to their smartphones which have become an indispensable lifestyle device. With the Visa Token Service, UOB is able to offer Singapore customers the option of making contactless payments, with tokenised security, through their smartphones at the point of sale – whether it is in a supermarket, coffee shop or at a petrol station,” said Mr Dennis Khoo , Head of Personal Financial Services, Singapore, UOB.

  • More retail-friendly bond issues in 2016

    More retail-friendly bond issues in 2016

    Singapore’s fixed-income market next year is tipped to be active, with more retail-friendly issuances. What’s more, perpetuals will continue to be popular even as financial conditions are likely to remain volatile. Retail bond demand is expected to stay healthy and there should be more deals done than in 2015 – thanks to higher yields, said Clifford Lee, DBS Bank head of fixed income.

    Four retail bonds with yields of 3.85 to 5.25 per cent were sold in 2015 by Perennial Real Estate Holdings, Oxley Holdings, Frasers Centrepoint and Aspial Corp. Investors could buy these bonds for as low as S$2,000 per lot, much cheaper than the minimum S$250,000 for most bonds sold here.

    Mr Lee said retail investors are not dumb, unlike your “mom and pop” investors. “The smaller caps have smaller subscription, indicating they do have discretion.”

    While the retail offerings were oversubscribed, he said the oversubscription was not massive – an indication that retail investors know what they are doing.

    The four retail bonds raised S$1.25 billion, against just one issue from CapitaMall Trust in 2014 worth S$350 million.

    “Of the four issuers this year, three may even be ‘high yield’ – although none are rated – which may spur further issuance from other mid-sized firms which could offer higher yields on their retail bond issues,” said Terence Lin, iFast’s regional research manager in the fixed-income division.

    Investors, especially financial institutions and real estate investment trusts (Reits), are expected to still like perpetuals – bonds with no fixed maturity – in 2016, as they did in 2015.

    Seven perpetuals were sold this year which raised S$3 billion, almost double the S$1.8 billion for 2014.

    Mr Lin indicated that issues such as the new Julius Baer, Ascendas Reit perps and FCL perps have so far been among the most heavily traded bonds in the SGD corporate bond market in 2015. “We think their popularity stems from the higher yields offered versus traditional fixed maturity bonds (given the additional maturity uncertainty), while most of the perpetual bonds are still expected to be called on their first call dates (which are usually less than 5 years away), making them good alternatives to traditional short duration bonds,” he said.

    Also, he added, many of the perpetuals are issued by higher-quality names, offering investors a level of comfort.

    While more bank perpetuals are expected to be launched, as banks look to build additional capital, as well as to refinance maturing/callable debt, many non-bank corporate perpetuals are also maturing.

    Firms such as Hyflux, Cheung Kong, Olam International, GuocoLand, Global Logistic Properties, Hotel Properties, Mapletree, Mapletree Logistics Trust and Genting Singapore are some of the existing issuers of perpetual SGD debt which are callable in 2016/2017, making them potential refinancing candidates/perpetual bond issuers come 2016.

    Tan Kee Phong, OCBC Bank’s head of capital markets, estimated that US$33 billion in loans and S$13 billion in SGD bonds are set to mature from syndicated loans in 2016 in Singapore. Yet nothing can be taken for granted, according to Elaine Ngim, Coutts’ he ad of fixed income in Asia. “Two key factors that may determine if 2016 is a bull’s or bear’s year are how fast Fed will hike rates and how slow will China economic growth be,” she said.

    “China’s growth story will be the larger factor for Singapore, as its economy is trade dependant on their growth. As a result, investors may become increasingly selective on quality of issuers and their industry,” said Ms Ngim.

    DBS’s Mr Lee also said China would have the biggest impact on the Asian bond markets, because it accounts for the lion’s share of the Asian G3 (USD, yen or euro) bond arena.

    China-linked issuance in 2015 was 54 per cent or US$91 billion of the US$169 billion Asian G3 bond market. But offshore funding costs have ballooned and a lot of Chinese companies are now opting to issue onshore, Mr Lee indicated.

    “If China continues to issue onshore next year, then it (Asian credit market) could get a kick in the stomach,” he said.

    The SGD bond market was pretty solid in 2015, especially compared with equities. This year has seen 161 deals worth S$22.7 billion done, slightly less than the S$23.5 billion raised in 2014. The highest was S$31 billion in 2012.

    “2015 was comparatively a better year for bonds in Singapore when compared to the STI index, with main drivers being corporate bonds, specifically statutory board issuers in the 5-7-year maturity bucket,” said Ms Ngim.

    Up to Dec 11, the Singapore Fixed Income Indices for 2015 outperformed the STI by 17.64 per cent (1.87 per cent vs. -15.77 per cent).

    Despite the year starting out somewhat jittery, there was no lack of higher risk issuers, Ms Ngim said.

    “Looking back at these issues, 2015 is categorised by several buckets, namely the real estate developers and Reits who are listed on the SGX, shipping and the offshore support vessels, and closing off the year with a few global financial issuers,” she said.

    Still, some have found 2015 a challenging year for the SGD bond market.

    “We believe credit quality of issuers, on average, declined, with particularly significant weakness seen in commodity linked companies and in the offshore marine sector, which is a sizeable part of the SGD bond market,” said Neel Gopalakrishnan, Credit Suisse, director, emerging markets bond analyst, private banking Asia Pacific.

    “Secondary market liquidity was another issue with no meaningful bids available especially for higher yielding bonds, making it almost impossible for bondholders to exit their positions if they were uncomfortable with the underlying issuer,” he said.

  • Hong Kong Central Bank Lifts Key Rates

    Hong Kong Central Bank Lifts Key Rates

    “Instead of going into the property market, (capital flows) could go out and ease the property market, and that could strike consumers’ confidence and I think the economy next year may not perform so well”, said Paul Tang, chief economist at Bank of East Asia in Hong Kong. As Hong Kong’s currency is pegged to the United States dollar, the city’s monetary policy typically moves in line with the Fed.

    “The normalization of Hong Kong’s interest rate will begin with the outflow of funds from the Hong Kong dollar trigger by high interest rates of the U.S. dollar”.

    A company logo is displayed inside the HSBC headquarters in Hong Kong November 3, 2015.

    The rate hike followed the U.S. Federal Reserve’s decision to raise the range of its benchmark federal funds rate by a quarter of a percentage point to between 0.25 percent and 0.50 percent on Wednesday, its first move in almost a decade.

    “We have seen a relatively slow economic growth this year, which is to a large extent attributed to the weak performance in our foreign trade”.

    Meanwhile, rampant deflationary pressure worldwide, volatilities in the global financial landscape, the growth of regional trade agreements, as well as lingering geopolitical threats and increased terrorist concerns, are the major risks and challenges facing Hong Kong exporters. Data from retail banks, which account for about 90% of the total customers’ deposits in the banking sector, are used in the calculation.It should be noted that the composite interest rate represents only average interest expenses.

  • Rising HK dollar expected to give locals the travel itch

    Rising HK dollar expected to give locals the travel itch

    Cash registers in Hong Kong won’t be ringing merrily next year after the US rate hike, with locals likely to scratch their travel itch with the appreciating Hong Kong dollar.

    The greenback reached a two-week high against a basket of major rivals yesterday after the US Federal Reserve raised interest rates for the first time in nearly a decade.

    The Hong Kong dollar, pegged to the US unit, also rose.

    Hong Kong Retail Management Association chairman Thomson Cheng Wai- hung said the interest hike’s immediate effect on the industry is limited, but further hikes next year would destabilize the market and make tourists further lose their appetite for the SAR.

    “No matter if it is accommodation in hotels or shopping, it would appear more expensive for tourists. Many of them are going to Japan, South Korea and Europe. The trend would worsen,” Cheng said.

    He expects retailers selling high-end products such as jewelry to take a hit.

    According to a survey last month of its members, a single- digit decline in sales this Christmas is expected year-on- year. Most members feel next year’s performance will be worse. Cheng predicted that retail sales this year would drop 3 percent from last year.

    As for local shoppers, some could be attracted to travel overseas due to the strong Hong Kong dollar. “It is not an advantage for local retailers,” Cheng said. The strong US dollar and hence HK dollar would encourage mainland tourists to explore other destinations, CLSA senior investment analyst Mariana Kou said.

    “We believe Japan, Korea and Europe would continue to be beneficiaries,” Kuo said.

    Safety concerns after recent terrorist attacks, however, may affect travel into Europe.

    Miramar Travel saw Christmas bookings jump by 20 percent from last year. But they reminded Hongkongers that despite cheaper shopping, other travel expenses do not necessarily go down.

    The rising popularity of Japan has led to a shortage of hotels and higher costs.

    Travel Industry Council chairman Jason Wong Chun-tat said the hike had been expected and would have limited impact on exchange rates.

    He remained optimistic for inbound tourism, saying hotel occupancy rates are expected to reach 80 to 90 percent during this holiday season.

  • HK braces for economic chill ahead of new rate hike cycle

    HK braces for economic chill ahead of new rate hike cycle

    Hong Kong is bracing for greater economic challenges as the prospect of a new cycle of interest rate rises drives fears of capital outflows that could put further pressure on the Asian financial hub.

    Hong Kong’s property market, which has seen prices more than double since 2008, had already slowed in anticipation of a local rate hike, and analysts say a further slowdown will depend on China, which is facing its weakest growth in 25 years.

    The city’s central bank on Thursday raised the base rate it charges through its overnight discount window to a seven-year high of 0.75%, tracking a decision by the US Federal Reserve to raise the range of its main rate by a quarter point, its first move in nearly a decade.

    The Hong Kong dollar’s peg to the US dollar means the city’s monetary policy follows that of the Fed, which said in its statement on Wednesday it expects a gradual tightening cycle.

    Norman Chan, the chief executive of the Hong Kong Monetary Authority (HKMA), warned of gradual capital outflows as hot money that had flowed in due to loose monetary policy exits.

    “I would advise members of the public to make necessary preparations in terms of managing the credit, liquidity and other relevant risks in order to cope with possible shocks and adjustments that may arise from the normalisation of US and Hong Kong interest rates,” Chan said after the policy decision Thursday.

    And although the immediate impact of policy tightening is likely to be limited, it comes at an increasingly uncertain time for Hong Kong, which is grappling with sluggish economic growth on the back of a slump in tourism and retail spending, as well as a slowdown in China.

    About US$130 billion has flowed into Hong Kong dollar assets since 2008, when the Fed adopted its near-zero rate policy, according to the HKMA.

    Hong Kong property sales slid 41.7% in November year-on-year to a record low, while the city’s property stock sub-index has dropped about 20% from multi-year highs hit in June. The index was up 0.8% early on Thursday.

    Financial Secretary John Tsang, who last week flagged a rate hike as the biggest concern for the city’s economy, said Hong Kong had the ability to cope with large capital outflows, echoing a report from the International Monetary Fund this week that said risks were manageable.

    “Whether Hong Kong will experience capital outflows next year depends not only on the pace of rate hikes by the Fed, but also China’s economy,” said Raymond Yeung at ANZ in Hong Kong, adding the property market faces some pressure in the medium term.

    Commercial banks in Hong Kong will decide separately whether to increase their lending or deposit rates.

    Any increase in rates could add to the city’s household debt to gross domestic product (GDP) ratio, which is already at a record high of around 64%, as repayment obligations rise.

    For homeowners, it could also mean leaner times in a city where the average house price is 17 times household income, according to consultancy Demographia.

    While the city has successfully weathered previous US rate hikes, Hong Kong’s economy is now more vulnerable as it struggles with weaker retail sales as fewer cash-rich mainland tourists stream across the border on shopping sprees.

    Though policymakers have faced a growing chorus of criticism on the burden of holding a currency peg to the greenback, the government reiterated on Thursday that a peg is the best policy option for the city’s mercantile economy.

    Expectations are the city’s economy will expand at 2%-3% rates in the current year, far below the heady rates of nearly 8% seen in the first quarter of 2011.

    Some observers said the property market was still a concern.

    “The key problem with Hong Kong right now is that (property) prices are already well ahead of earnings power and the economic situation,” said Nicole Wong, property analyst at CLSA.

  • Postal Savings Bank of China has raised investment

    Postal Savings Bank of China has raised investment

    Postal Savings Bank of China has raised $7bn from a global group of 10 investors including JPMorgan, an affiliate of Alibaba, and Temasek, valuing the state-owned lender at $41bn ahead of a float that could come as soon as next year.

    The sale of 17 per cent equity marks the largest private fundraising by a Chinese financial institution, and its international collection of investors will be seen as a signal Beijing is more open to outside funds to help with its slow-moving plans to reform its state-owned enterprises.

    Postal Savings Bank is China’s biggest unlisted lender and its sixth largest commercial bank in terms of assets. It has more than 400m retail customers and nearly 40,000 branches, many of them in rural areas where until recently the only alternative was putting money under the mattress.

    A similar pre-float sale of a $17bn stake last year in the retail operations of Sinopec was sold largely to domestic investors — so-called friends and family — in spite of interest from international groups, denting hopes at the time that China was serious about bringing in outside expertise and funding.

    Lu Jiajin, Postal Savings Bank president, on Wednesday described the placement as an “example of mutually beneficial co-operation between China and the world”.

    He added: “This indicates that the world has . . . confidence in China’s financial systems and [the] stability and profitability of China’s banking industry”.

    The international investors are UBS; JPMorgan; Singapore’s Temasek investment fund and DBS, the city-state’s biggest bank; Canada Pension Plan Investment Board; and the IFC arm of the World Bank.

    CPPIB is committing $500m. Mark Machin, head of international business and president of Asia for CPPIB, said the investment met the fund’s strategic goals of investing in less-developed regions of China and increasing exposure to the Chinese consumer.

    Chinese banks have come under pressure in a rapidly shifting landscape, and face challenges including rising bad loans and competitive pressures from the country’s interest rate liberalisation agenda.

    Hong Kong-listed shares in the country’s big four state-backed banks — ICBC, Bank of China, China Construction Bank and Agricultural Bank of China — have dropped at least 17 per cent this year.

    “This isn’t a sector bet, it’s an investment in this bank,” said Mr Machin, adding that Postal Savings Bank’s focus on consumer lending helped isolate it from some of the bad loan issues faced by corporate lenders.

    Ant Financial, the payments affiliate of Alibaba; rival internet Chinese giant Tencent; China Telecom; and insurer China Life have also committed funds.

    A filing with the Hong Kong stock exchange showed China Life is putting up $2bn and its stake will not be more than 5 per cent — implying a valuation of $41bn for Postal Savings Bank.

    Pre-IPO funding rounds are increasingly being used as a way of establishing baseline valuations and demonstrating support for a company before it approaches the public markets.

    JPMorgan said its agreement with Postal Savings Bank covered “multiple levels of collaboration” between the two sides.

    An executive at one of the companies involved in arranging the deal said: “They have reached out to strategic partners who can help them professionalise rather than just have passive investors”.

    Mr Lu said Postal Savings Bank wants to establish itself “as a 100-year bank with steady operations and excellent risk management”.

  • New Banking Fees May Turn Thailand into a Cashless Society

    New Banking Fees May Turn Thailand into a Cashless Society

    Bank fees will undergo changes in the near future to better reflect the actual costs of banking, and may pave the way for Thailand becoming a cashless society.

    According to Veerathai Santiprabhob, Bank of Thailand governor, the current bank fee structure is distorted. He noted that paper-based transactions are cheap compared to actual costs, and banks are subsidizing these costs with fees on electronic transactions. In other words, a check fee may only be Bt15, but the actual cost is far higher. Currently, customers can withdraw money from ATMs, but banks incur huge costs for managing cash at ATMs.

    A new project is helping to reduce cash usage in the country through the introduction of more point-of-sale throughout Thailand. There are currently less than 100,000 points of sale, which is much lower than the 2 million recommended by the Bank of Thailand.

    To maintain retail customers, banks will be expected to reach out to merchants to create their own points of sales. Smaller merchants will also be required to have mobile point-of-sale to support small customers.

    Under the project, companies who are registered with the Commerce Ministry will also be prohibited from denying e-payments.

    The creation of a central system that will oversee cross bank transactions through the Internet, ATM cards and debit cards will help move Thailand to a cashless society. Adoption of the Any ID e-payment model will further help the country make this transition.

  • German start-up Number26 launches pan-European mobile bank

    German start-up Number26 launches pan-European mobile bank

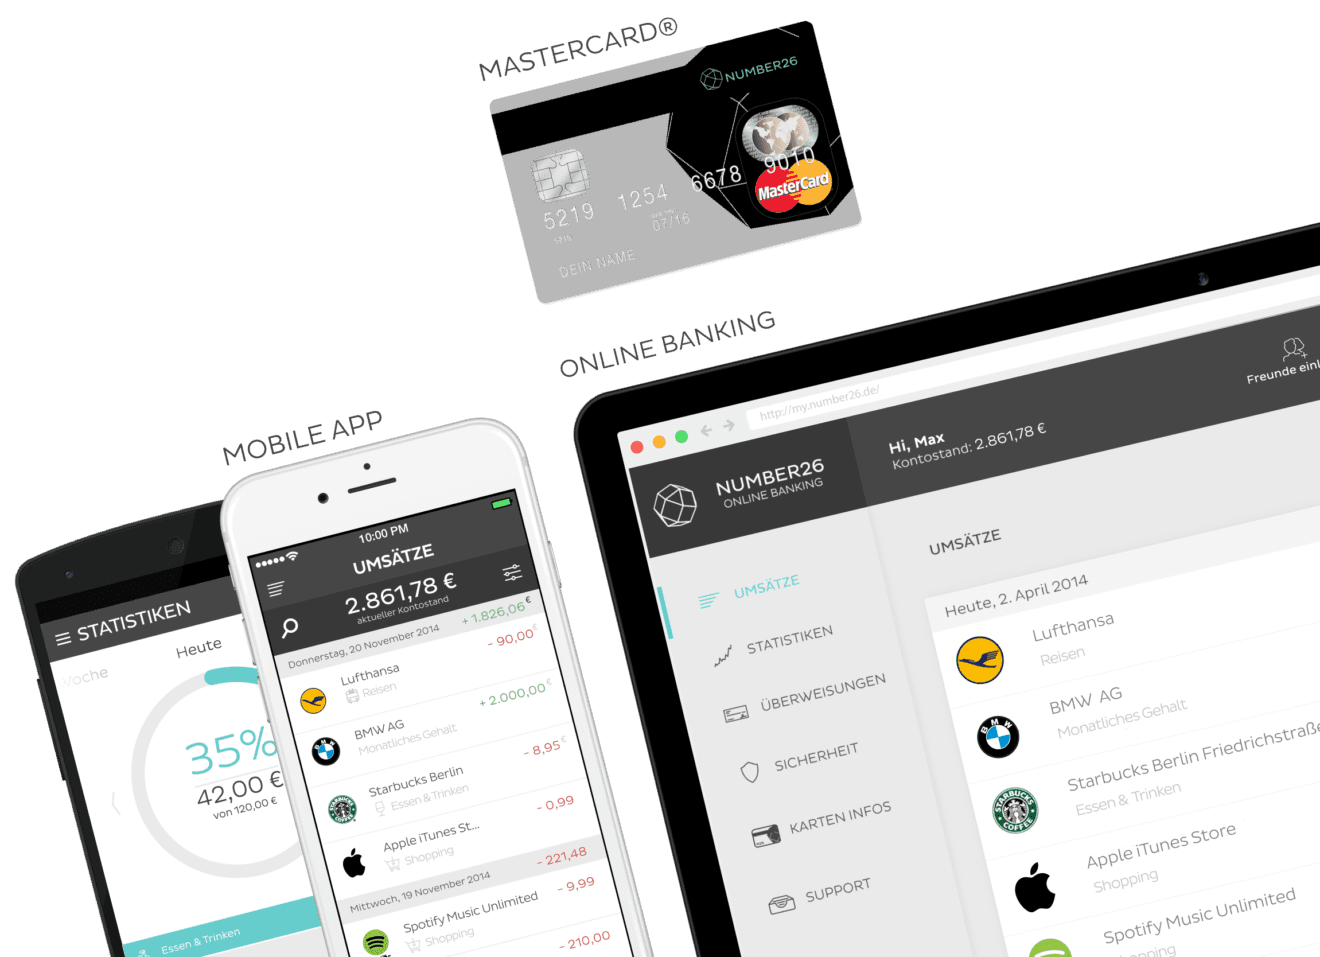
    Number26 is looking to succeed where traditional lenders have struggled, by relying on mobile phones to build a true pan-European bank.

    The German financial services start-up is expanding into six European markets, making it the first mobile phone bank to straddle the region’s borders, it said on Thursday.

    Number26 is entering France, Italy, Spain, Slovakia, Greece and Ireland, the latter being a test for moving into Britain, and eventually plans to develop a continent-wide bank.

    Founded by two Austrians and based in Berlin, the company revealed plans to offer a MasterCard and basic current accounts via a licence from its partner Wirecard Bank of Germany, which guarantees funds using the German Deposit Protection Fund. Its parent, Wirecard, also supplies Number26 with core banking software and transaction processing.

    Without branches, legacy computer infrastructure and by relying on selective outsourcing, mobile-first banks can compete with little up-front capital against big banks, all while promising lower lending rates and higher rates on savings.

    Number26 also has a jump on rival mobile-first banks including Atom Bank which took a UK bank licence in June and Tandem, which received a licence this week. Both plan to start operating in Britain next year. BBVA, Spain’s No. 2 bank, has taken a 29.5 per cent stake in Atom.

    “The model for these mobile start-ups is to compete on fees,” said Andrew Copeman, an analyst with financial research firm Aite Group. “Banks can’t afford to go after those rates because they are saddled with big overhead from branch networks and old systems.”

    Taken by surprise, banks have responded by ploughing more money into fixing creaky systems, rolling out mobile apps of their own and shuttering many branches. Worldwide, banks could cut half their jobs in 10 years as they fight to stay relevant, the former head of Barclays has said. “I don’t see banks at all as my competitors. They just can’t move fast enough,” Number26 chief executive Valentin Stalf, 30, said in an interview.

    The company, which launched this year in Germany and Austria, provides more than 80,000 customers with accounts for cash withdrawals, deposits and overdraft services up to ?2,000 via a slick smartphone app. “We see the current account as just a starting point,” said Maximilian Tayenthal, 35, Number26’s co-founder and chief financial officer. Credit, savings and insurance products will follow, he said.

    It recently began offering a retail checkout-based alternative to ATM machines for cash withdrawals and deposits in Germany.

    It now counts 6,000 cash outlets including supermarket chain Rewe, or more ATMs than Deutsche Bank and Commerzbank combined.

    The Number26 name refers to the optimal number of quarter turns it takes to solve a Rubik’s Cube puzzle and is a play on the most efficient route it can find to reinvent banking.

    Mobile phone-based banks aim to tear up the rule-book of an earlier generation of direct banks, which used online sites and telephone call centres to woo millions of customers away from bank branches starting in the 1990s.

    ING’s DiBa and others are now some of Europe’s biggest retail banks after being spun out of parent banks to offer a wide array of services created within those banks.

    By contrast, Number26 is looking to evolve rapidly into a full-service banking hub, providing not just services of its own but those from third parties. It is in talks to offer money transfers from TransferWise, loans from LendingClub and deposit comparison site SavingGlobal on its platform.

    The 75-employee company has raised ?12.5 million in venture funding. Backers include Peter Thiel, founder of PayPal and one of Silicon Valley’s top investors, Earlybird Venture Capital and Axel Springer Plug & Play, both of Germany, and Swiss-based Redalpine Venture Partners.

  • UOB to help Jakarta draw investments

    UOB to help Jakarta draw investments

    United Overseas Bank (UOB) is linking up with an Indonesian government agency to encourage more foreign direct investment (FDI) into Indonesia.

    Under an agreement signed yesterday, the Investment Coordinating Board (BKPM) will allow UOB clients to apply for what is called a Principle Licence here without having to travel to Indonesia.

    A foreign company must obtain the licence as an initial step to incorporating an entity there.

    BKPM, which is under the direct supervision of President Joko Widodo, supports foreign investment into the country and helps Indonesian companies venturing overseas.

    UOB said it will support Indonesian investors looking to expand overseas through BKPM’s Indonesia Investment Promotion Centre in Singapore.

    BKPM will also help UOB clients take advantage of business opportunities in Indonesia.

    Last year, Indonesia was the second-largest recipient of foreign direct investment inflows into Asean, receiving US$28.5 billion (S$40.2 billion), UOB noted.

    China’s FDI into Indonesia has increased more than fivefold over the past three years, growing from US$141 million in 2012 to US$800 million last year, UOB said.

    Mr Sam Cheong, head of UOB Foreign Direct Investment Advisory, said opportunities in the region will be boosted by the upcoming Asean Economic Community.

    Under China’s “One Belt, One Road” initiatives, trade and investment between China and South-east Asia will likely continue growing, he added.

    BKPM chairman Franky Sibarani said in a statement: “(The agreement) will help to promote investments in Indonesia across major sectors, such as the infrastructure, maritime, import substitution, export-oriented, agriculture, downstream mining, industrial estate and tourism industries.”

  • Singapore sees mild deflation of -0.5% for 2015

    Singapore sees mild deflation of -0.5% for 2015

    Singapore is projected to experience a mild deflation of -0.5% for 2015, according to a forecast adjustment made by Maybank Kim Eng.

    The tweak in its estimate is still within its earlier forecast range of between -0.5% and 0%, the research house writes in a note on Tuesday.

    Maybank Kim Eng’s forecast comes on the back of several macroeconomic headwinds, following the latest inflation figures released on Monday.

    These include the prevailing subdued outlook on transport cost given low global crude oil prices, depressed housing and utilities costs and soft global commodity prices, which should offset the impact of the tight job market.

    Headline inflation eased to -0.8% in October from -0.6% in September, mainly due to the lower costs of oil-related and retail items, the Monetary Authority of Singapore and the Ministry of Trade and Industry said on Monday.

    Core inflation, which excludes accommodation and private road transport costs, eased to 0.3% in October from 0.6% in September.

    For 2016, Maybank Kim Eng expects inflation to nudge up to 0.5% on the receding effect of lower global oil prices.

    The will also be underpinned by budgetary measures such as the reduction in the concessionary foreign domestic worker levy, one year road tax rebates, abolition of national examination fees and the increase in medical subsidies, it says.