Category: Research

Retail News Asia is committed to providing both local and global retailers with the latest Research throughout the Asian market. This on a daily base.

  • Study reveals Asian dining spending trends

    Study reveals Asian dining spending trends

    One in three millennials in Asia are eating at fine dining restaurants at least once a month – more often than those aged over 30.

    The surprise finding is one of a list of revelations uncovered by a MasterCard survey of Asian dining trends away from home. It featured consumers in 17 Asia Pacific markets: Australia, Bangladesh, China, Hong Kong, India, Indonesia, Japan, Malaysia, Myanmar, New Zealand, Philippines, Singapore, South Korea, Sri Lanka, Taiwan, Thailand and Vietnam.

    The most frequent fine-diners in Asia Pacific are millennials (18-29 year olds) from China – on average they visit more expensive establishments two or three times a month. This is higher than the average for millennials across the region and higher than any other age group.

    When choosing where to eat, consumers in Asia Pacific still prefer to rely on word of mouth and recommendations from friends and family (50 per cent). This was applicable for all consumers, regardless of age group, with even millennials trusting word of mouth recommendations (52 per cent) more than online reviews (38 per cent).

    This is despite the fact that more than a third of millennials (36 per cent) post comments and reviews of their dining experiences online. This is especially true of Chinese (61 per cent) and Thai (52 per cent) millennials, where more than half of the young people polled regularly post reviews after a meal.

    Beyond millennials, people in Thailand (39 per cent) and China (30 per cent) are also the most likely to spend more on dining over the next six months with around one in three indicating they plan to eat at more expensive establishments.

    But while consumers may be enjoying fine dining, they are still cost conscious. Sixty-four per cent of consumers in Asia Pacific regularly check for discounts or dining deals from coupon websites, mobile applications or credit card promotions. Sixty-eight per cent of millennials regularly look out for deals before choosing a place to eat.

    Eric Schneider, regional head, Asia Pacific, with MasterCard Advisors, said Asia has always had a strong dining out culture and so it is not surprising that affluent millennials in the region are ‘foodies,’ with many sharing their dining experiences on social media and posting reviews online.

    “While the survey has shown that people are increasingly moving from the hawker centres and into restaurants, young people are still cost conscious, taking a practical and savvy approach by looking for discounts and deals. Young people also still rely on word of mouth recommendations, despite many posting online reviews of dining spots. As Asia’s economies continue to grow, and with technology and social media revolutionizing the dining experience, people will increasingly demand top quality experiences when dining out,” he said.

    Other findings from the survey included:

    • Overall, consumers in Asia Pacific are not looking to make any significant changes to their dining out plans with 61 per cent of all consumers indicating they will look to eat out at the same frequency in the next six months. Twenty per cent plan to eat out more and 19 per cent plan to eat out less in the next six months.
    • The most popular dining option for consumers in Asia Pacific are mid-range restaurants and cafes, followed by fast food outlets and then hawker centres and food courts.
    • Consumers in the Philippines (44 per cent) are looking to tighten their belts with close to one in two planning to eat at less expensive venues in the next six months. Forty-nine per cent also plan to eat out less regularly.
    • A significant proportion of older consumers are going online to check for dining discounts whether on coupon websites/applications or credit card promotions. More than one-third of consumers aged 55 years old and above (36 per cent) indicated they regularly do so before deciding on a dining option.
    • Consumers in China (58 per cent), Taiwan (44 per cent) and Thailand (44 per cent) are the most likely to book dining deals on coupon sites or coupon applications; while consumers in Bangladesh (1 per cent) and Indonesia (11 per cent) were least likely to do so.
    • Diners in Thailand (60 per cent) and China (57 per cent) are most likely to post comments or reviews on social networking sites like Facebook and Twitter with about one in two respondents in these markets reporting that they regularly post comments online following their dining experience.

    The results are based on interviews with 8698 individuals aged 18 to 64 years-old.
  • Digital Push In China: Can This Impact Starbucks’ Revenues In The Region?

    Digital Push In China: Can This Impact Starbucks’ Revenues In The Region?

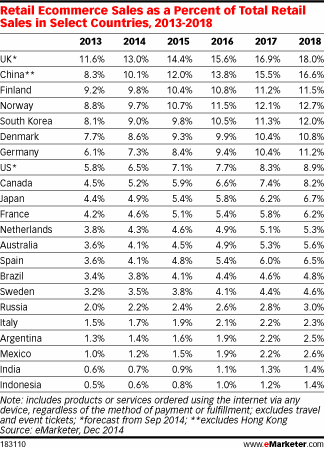
    Recently, Starbucks Corporation China announced the opening of its first online store in China’s popular ecommerce site, Tmall, which will feature unique and specially designed e-cards, Starbucks cards and coffee vouchers providing an easy gifting option. [].While this initiative is part of the company’s increased focus on digital presence, it could tap into the significant growth of retail ecommerce in China. According to eMarketer, retail ecommerce sales in China are projected to grow at more than 30% each year, over the next three years and reach more than $1500 billion by 2018. []. While mobile is expected to account for nearly half of the total ecommerce sales in China in 2015, this figure is expected to increase to 70% by 2019. []. We believe Starbucks’ ecommerce initiative in China should benefit from the growing internet users in the region and the online shopping habits of Chinese consumers.

    More Than 16% Of Total Retail Sales In China Through Ecommerce By 2018

    It is estimated that in 2015, ecommerce sales will account for nearly 7% of the total retail sales in the U.S., while this number is much higher at 12% for China. By 2018, it is estimated that these figures will increase to nearly 9% for the U.S. and more than 16% for China.

    183110

    Given the preference of Chinese consumers towards online shopping, we believe Starbucks’ initiative to expand its digital presence in the region is the right strategy.  China is a growth market for Starbucks. For the fiscal year 2015, comparable store sales in the China Asia Pacific region grew by 9% compared to a 7% number for the Americas. This growth was driven by a 8% increase in traffic while the corresponding number for Americas was 3%. []. The company plans to double its store count in the China Asia Pacific region to 10,000 stores in the next five years, with the store account in China projected to be 3,400 by the end of 2019. As the Chinese economy shifts from an export focussed industrial region to one relying on services and domestic demand, we believe Starbucks will benefit from this trend with the urban middle class increasing and becoming well off. With aggressive expansion plans in China, which the company expects will be its biggest international market; we believe the ecommerce entry could drive growth in the region and also provide a boost to the Starbucks loyalty program.


  • How native apps complement China’s retail experience

    How native apps complement China’s retail experience

    When planning a retail mobile app strategy for China, there are many options available, including developing a mobile-friendly website, setting up a store on any one of the thousands of Chinese e-commerce platforms and developing a native app. So how do you choose which one is best for your brand?

    The big players

    There are a number of key platforms that retail brands in China can consider. The mighty WeChat, for example, has both reach and resonance with a vast audience (more than 600 million monthly users, to be more precise), as well as built-in, trusted payment facilities. Tmall and JD.com are just two examples of the thousands of e-commerce platforms in China. (Even Amazon has a store on Tmall). They offer easy-to-use, well-established e-commerce functionality that can include logistics, warehousing and payment facilities.

    For retailers wanting to take the quickest route to market, establishing a shop on one of these existing services is an easy solution. And of course, investing in a mobile website is also a good alternative.

    Both of these options have a place in the overall marketing mix and should be part of any robust business strategy. But retailers looking to compete in a complex and ever-changing marketplace like China need to consider the advantages of developing a native app and ‘owning’ a space on consumers’ devices.

    What’s so good about native apps?

    While it’s clear that people love to use the major consumer platforms, it’s important not to underestimate the power of an app specifically developed for a brand’s fans and followers.

    According to a report from The Internet Retailer, 42 percent of all mobile sales generated by the world’s leading 500 merchants in m-commerce last year came from mobile apps. Caixin, one of China’s leading business media groups, backs this up, saying that shopping via app in China grew by 168 percent in 2014, with shopping app users making up 39 percent of all mobile users.

    The numbers stack up, but what about the practicalities?

    Native app versus existing e-commerce platforms

    When working with an e-commerce platform, the brand doesn’t have full control over the user experience. Tencent and Alibaba set the rules for look, feel and layout, as well as e-commerce capabilities and payments. Overall functionality is limited to each platform’s abilities. It might not be possible to implement brand-specific features, innovative activities or marketing campaigns that lie outside of its framework.

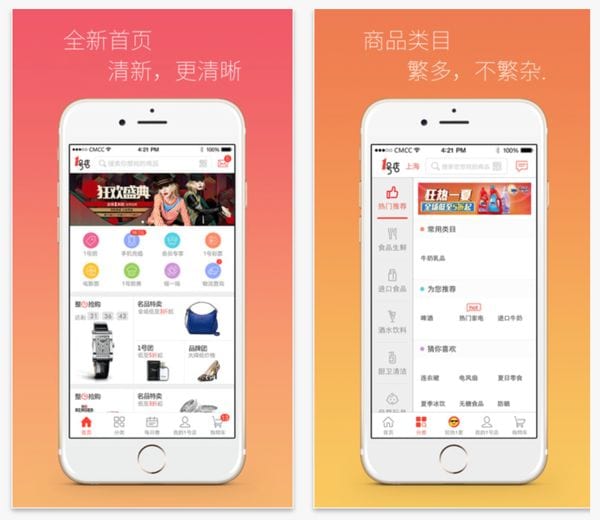
    This app from online supermarket retailer Yihaodian is a great example of how to fully exploit smartphone functionality for an engaging customer experience.

    China_Apps_Yihaodian_600

    While there’s usually a way to open basic storefronts for free, other marketing activities, such as advertising and special promotions, tend to come at a cost.

    China’s existing e-commerce platforms are an excellent way to begin market entry, as they offer an instant, fully functional digital storefront within trusted, well-established parameters. However, a native app which gives retailers the freedom to develop unique features and marketing opportunities will complement these advantages, leveraging multiple platforms for a true omnichannel experience.

    Native app versus mobile web app

    A web app has technical limitations based on the browser it was set up for. The app will not be able to fully access smartphone capabilities.

    For example, the phone’s built-in features cannot access the user’s address book, offer an unrestricted integrated camera experience, use location services and the accelerometer, or access in-store beacons.

    Web apps cannot offer a personalized experience. Whereas native apps can store and apply a wealth of user data to deliver targeted alerts, discounts, promotions and loyalty schemes based on store proximity and previous activity.

    Another issue with web apps is that if the Internet connection is lost, the user can no longer access it. Native apps on the other hand, allow for offline browsing.

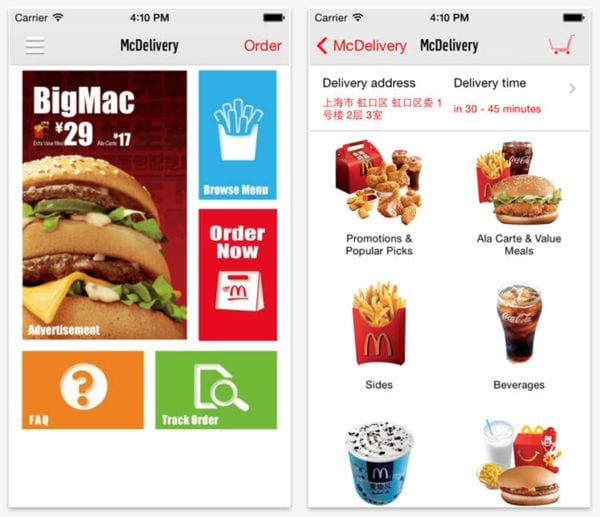
    McDonald’s McDelivery app is a good example of this. It makes a feature of the fact that people can look at the menu ‘any time, anywhere.’

    Apps_China_McDonald's_600

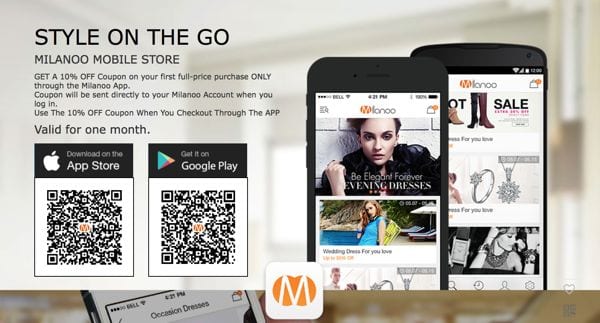
    Native apps allow retailers to send push notifications, an option not possible via a web app. This is an important consideration when it comes to marketing campaigns. Fashion retailer Milanoo makes full use of this in its app.

    Apps_China_Milanoo_600

    Well-made native apps get additional promotion through platform app stores; they may even be featured in top 10 charts and editor picks. This adds to the credibility and popularity of both the app and the retailer.

    Web apps are a viable, speedy way to get content onto users’ mobiles. But they’re not primarily designed for smartphones and while it is essential to make web content available in a mobile-friendly way, smartphone users expect a specific experience.

    Retailers can reap the benefits from this enthusiasm by developing apps for consumers using their phone capabilities to the full.

    The key to success in the world’s biggest mobile market is to have a well-rounded mobile strategy encompassing all trading platforms – and that includes native apps.

  • Singapore Food and Drink Report Q1 2016 Market Report

    Singapore Food and Drink Report Q1 2016 Market Report

    Food consumption will remain modest over our forecast period, registering a compound annual growth rate of 2.1% over 2014-2019.Technological innovations and cost-saving measures by mass grocery retailers will be realised in 2017, and a steady rise in food consumption will be observed. We forecast real GDP growth of 2.5% in 2016, with economic activity remaining tepid over our forecast period.

    A tight labour market will continue to put upward pressure on labour costs, reducing food manufacturing competitiveness. Rising incomes will bode well for the food and drink industry; however, low consumer confidence will partially offset growth in the short term.

    Headline Industry Data
    – Total food consumption growth in 2016: +1.8%; compound annual growth rate (CAGR) to 2019: +2.1%
    – Per capita food consumption growth in 2016: +0.1%; CAGR to 2019: +0.4%
    – Alcoholic drinks sales growth in 2016: +4.5%; CAGR to 2019: 5.1%
    – Soft drink sales growth in 2016: +2.7%; CAGR to 2019: +2.1%
    – Total mass grocery retail sales growth in 2016: +2.7%; CAGR to 2019: +3.0%

    The Singapore Food & Drink Report features Publisher Research’s market assessment and independent forecasts for food and drink expenditure, consumption, sales, and imports/exports and forecasts for the mass grocery retail sector. The report also includes analyses of major regulatory developments, the background macroeconomic outlook and competitive landscape comparing national and multinational companies by leading products and services, sales, investments, partners and expansion strategies.

    Publisher’s Singapore Food & Drink Report provides industry professionals and strategists, sector analysts, business investors, trade associations and regulatory bodies with independent forecasts and competitive intelligence on the food and drink industry and the mass grocery retail market in Singapore.

    Key Benefits
    – Benchmark Publisher’s independent food and drink industry forecasts for Singapore to test other views – a key input for successful budgeting and strategic business planning in the Singaporean food and drink market.
    – Target business opportunities and risks in Singapore through our reviews of latest industry trends, regulatory changes and major deals, projects and investments.
    – Exploit latest competitive intelligence on your competitors, partners and clients via our Company Profiles (inc. SWOTs, KPIs and latest activity) and Competitive Landscape Tables.

    Coverage
    Summary of Publisher’s key industry forecasts and views, covering food and drink manufacturing and consumption and the mass grocery retail market.

    Industry SWOT Analysis
    Analysis of the major strengths, weaknesses, opportunities and threats within the food, drink and mass grocery retail sectors and within the broader political, economic and business environment.

    Publisher’s Food and Drink Risk Reward Index
    Publisher’s Risk Reward Index provides investors (food and drink manufacturers and mass grocery retailers) looking for opportunities in the region with a clear country-comparative assessment of a market’s risks and potential rewards. Each of the country markets are scored using a sophisticated model that includes more than 40 industry, economic and demographic points. These provide indices of highest to lowest appeal to investors, with each position explained.

    Food Forecasts
    Publisher’s food chapter is divided into sections such as meat, fish, confectionary, dairy and canned foods, and provides insight into each market’s food industry, centred on a forecast to end-2019 for the sector.

    The chapter includes the following elements:
    – Industry Forecast Scenario: Historical data series and a forecast to end-2019 for growth of key indicators within a market’s food industry. Indicators include food consumption, food consumption as % of GDP, canned food sales, confectionery sales and food and drink imports and exports, among others.
    – Industry Developments: A summary of corporate developments, including news on M&As, FDI, expansions, closures and financial results, in addition to analysis and explanation of the latest industry events and how these could influence further investment.
    – Market Overview: An overview of the structure of the market, introducing the key players and discussing underlying trends.

    Drink Forecasts
    Segmented the same way as Publisher’s food chapter, the drink section provides insight into each market’s drink industry, centred on a forecast to end-2019 for the sector. Forecast indicators include alcoholic and soft drink sales by value, volume and sub-sector and tea and coffee sales, among others.

    Mass Grocery Retail Forecasts
    Segmented the same way as Publisher’s food and drink chapters, the mass grocery retail section provides insight into each market’s grocery retail industry, centred on a forecast to end-2019 for the sector. Forecast indicators include mass grocery retail sales by format (including supermarkets, hypermarkets, convenience and discount stores) and a breakdown of the organised retail sector versus the traditional sector, among others.

    Competitive Landscape
    Illustration of the mass grocery retail and food and drink industries via rankings tables comparing revenues, number of outlets and number of employees. This chapter also includes data-rich, in-depth regional analysis of the market position, business strategies and investment potential of the region’s leading mass grocery retail and food and drink operators.

    Company Profiles
    – Examines the competitive positioning and short- to medium-term business strategies of key industry players. Strategy is examined within the context of Publisher’s industry forecasts, our macroeconomic views and our understanding of the wider competitive landscape to generate company SWOT analyses.
    – The latest financial and operating statistics and key company developments are also incorporated within the company profiles, enabling a full evaluation of recent company performance and future growth prospects.

    Sources
    The Food & Drink reports draw on an extensive network primary sources, such as multilateral organisations, government departments, industry associations, chambers and company reports.

  • Malaysia is Poised for E-commerce Growth through Better Mobility

    Malaysia is Poised for E-commerce Growth through Better Mobility

    Today, there are a total of 252.4 million Internet users around Southeast Asia, with Malaysia emerging as the third country that recorded the highest percentage of Internet users (67%) after Singapore and Brunei.

    The promising Internet penetration result indicates Malaysia’s enormous potential for e-commerce market growth. Leveraging on the rise of Internet usage, indeed 2015 have been a fruitful year for all online businesses and e-commerce as Malaysia recorded one of the highest online transactions per capita in Southeast Asia.

    Nevertheless, this only represents the tip of an iceberg – Malaysia’s e-commerce market owns approximately 2% of the total retail market and countless opportunities still remain untouched if we look at what has been accomplished by other advanced e-commerce markets such as Korea, which accounts for approximately 15% of the total retail market.

    Over the past five years (2010-2014), Malaysia’s e-commerce market size has seen 31% increase in CAGR. Viewing from a logical standpoint, we anticipate it will follow a similar growth rate and achieve USD 3.1 billion by 2018. As for 2016, we foresee mobility, better Internet and logistics, and security will be the three key drivers to push for the local e-commerce development.

    1) The ‘mobility’ trend will continue to grow

    The mobile penetration in Malaysia has reached 136% this year, and the growth of connected devices have paved the way for a positive increase in the e-commerce sector with 47% of Malaysians using their smartphones to shop online.

    Furthermore, Malaysia ranks third in the rate of growth of mobile shopping in Asia (over 20%; from 25.4% in 2012 to 45.6% in 2014) according to a Mobile Shopping Survey and with these results, it is not surprising to know that more than 50% of traffic to 11street is generated on mobile devices.

    What shoppers can expect next year

    This promising result has encouraged us to make a bigger commitment for mobile users. We believe the ‘mobility’ trend will continue to grow and next year, 11street will put a stronger focus to serve mobile shoppers through a two-pronged approach.

    Mobile shoppers can expect more curated content from 11street’s app, with an improved user interface and user experience designs (UI/UX). Additionally, we will lift it with additional personalized features, and introduce more mobile exclusive deals for an exciting mobile shopping experience.

    2) Internet penetration and improved logistics will further enhance local e-commerce activities

    While the government has allocated RM1.2 billion for Malaysian Communications and Multimedia Commission (MCMC) to offer High-Speed Broadband to rural areas starting next year, we are also pleased with the government’s initiative to improve the logistics – a crucial element to boost the e-commerce development in Malaysia.

    Driven by the progressive e-commerce landscape, the logistic industry, especially the courier segment has seen exponential growth over the past one year. For instance, courier service contributed 60% of POS Malaysia’s total earnings in FY15, as compared to 41% in FY14.

    In preparation to serve shoppers better in 2016, we believe these supportive initiatives suggested by the government will aid sellers to meet future demands, by providing shoppers a seamless online buying experience with more timely delivery service.

    What shoppers can expect next year

    Online marketplaces like 11street place high importance on offering pleasant shopping experiences from the moment a consumer start shopping online, all the way through to the delivery of purchased items. Several measures that the company has been implementing since its establishment include (i) Thoroughly brief and train sellers on product delivery management (ii) Provide shoppers with a tracking system to keep them informed on location, time of arrival, and delivery status of their purchased products.

    With a solid Internet and logistics infrastructure, 11street trusts that Malaysians will enjoy online shopping even more in the coming years.

    3) User confidence, especially safe and secure online shopping is a priority for shoppers

    Security issues discourage shoppers from heading online. Malaysia Computer Emergency Response Team (MyCERT), a department within CyberSecurity Malaysia, reported that the number of online scams in the country is on the rise. A total of 743 fraud cases were received in Q1 2015, of which is the second most reported incidents (25.54%) in total reports.

    Shoppers are always urged to make transactions with only trusted platform that offers product return policies, customer reviews on products, seller’s rate or scoreboard, as well as a trustworthy payment system. Online sellers and marketplaces have to bear this in mind and update their security measures from time to time in order to establish shoppers’ confidence.

    What shoppers can expect next year

    11street implemented the ESCROW system, which is a financial instrument of placing a buyer’s money on hold and releasing it to the seller only when the delivery of the purchased item is fulfilled, thus protecting buyers from frauds. The ESCROW system has helped to prevent many fraud cases and it will continue to be invested by 11street in the future.

    Our website is also strengthened with abilities to monitor all products, transactions from buyers and sellers to detect suspicious activities such as counterfeit product listing. Moreover, a number of other efforts include a stringent application process and regular product quality inspections will be enhanced to provide shoppers a safe & secure shopping experience.

    A budget-conscious year ahead

    2016 will be another budget-conscious year for Malaysians in view of the rising cost of living caused by GST implementation and the ringgit devaluation. To assist consumers to ‘shop smart’, we are gearing up to double our variety of product listings for ‘Shocking Deals’ with the lowest price guarantee by early 2016.

    It is also worth noting that cross-border trading (CBT) trends can be observed from the increasing searches for popular international products on the Internet in Malaysia. However, with the higher exchange rates and international shipping fees, today local shoppers might find it challenging to get their favorite overseas brands or items. In view of this, 11street is committed to bring in more popular overseas product, including cosmetic, fashion, and food items, especially from Korea in 2016. These products will be imported and affordably priced at the online marketplace in order to satisfy Malaysian shoppers’ needs.

    Undeniably, the overall e-commerce market in Malaysia is poised to flourish positively. The next step would be to sustain the market potential and all industry players need to work together to ensure this. As a market expert, 11street is delighted to work with close partners such as Multimedia Development Corporation (MDeC) and Google. We look forward to collaborating with even more industry leaders in the coming year. In closing, we would like to urge sellers to stay alert on the evolving mobile & purchasing trends in the market to give shoppers a satisfactory experience, as this will build upon Malaysia’s vibrancy as a profitable market for e-commerce.

  • China’s growing upper middle class to drive consumption by 2020

    China’s growing upper middle class to drive consumption by 2020

    The dramatic rise of China’s upper middle class and affluent families is expected to become a major driver for domestic consumption, which will grow fast despite the nation’s sluggish economy.

    A report released by consulting firm BCG and AliResearch, the research arm of China’s largest e-commerce company Alibaba Group, said the combined number of upper-middle class households, whose annual disposable income ranges from US$24,000 to US$46,000, and affluent households, with disposable income over US$46,000, would double to 100 million by 2020.

    By then, they will account for 30 per cent of urban households, up from 17 per cent today and only 7 per cent five years ago.

    “During the past few decades, China’s consumer economy has been powered by the ascent of hundreds of millions of people from poverty to an emerging middle class,” said Kuo Youchi, a principal with BCG Greater China who helped draft the report.

    “But China is entering a new era. The real driver for the future will be upper-middle class and affluent shoppers.”

    The report projects that affluent and upper-middle class consumers will account for 55 per cent of China’s urban consumption and 81 per cent of its incremental growth by 2020.

    Compared to tier-one cities like Beijing, Shanghai and Guangzhou, smaller mainland cities would see faster growth in the number of well-off shoppers. Half of the upper middle class and affluent households to emerge during the coming five years were likely to be in fourth-tier or even smaller cities, it said.

    China’s economy has been undergoing a structural transformation while its gross domestic product growth has cooled in recent years. The government hopes domestic consumption willoffset the sluggish export and investment sectors.

    The report is bullish about China’s consumption market, predicting it to grow 9 per cent annually to US$6.5 trillion by 2020, outpacing GDP growth which is expected to remain at around 6.5 per cent over the next five years.

    In addition to an increase in wealthier consumers, another force to boost consumption is from the younger generation of shoppers who were born in 1980s and 1990s.

    A separate BCG survey found that 42 per cent of Chinese aged 18 to 25 disagreed with the statement, “I feel I have enough things and feel less need to buy new ones”. That compared to 36 per cent in the US and European Union and 32 per cent in Japan.

    Meanwhile, e-commerce, as a more important retail channel in China, will also help stimulate demand and is expected to account for 42 per cent of growth in private consumption.

    Alibaba recently announced plans to buy the South China Morning Post and all other media assets owned by the SCMP Group.

  • More than half of Hongkongers surveyed say they plan to buy no Christmas presents

    More than half of Hongkongers surveyed say they plan to buy no Christmas presents

    Christmas holidays are usually the peak consumption season for both tourists and local residents, but this year retailers are expecting a grimmer picture amid the economic downturn affected by the slowdown in China and strong local currency.

    A study shows that Hong Kong people are cutting their Christmas budget to tackle the difficult economic environment this year, with 64 per cent people saying they won’t spend more than HK$1,000 on Christmas shopping and 52 per cent saying they won’t buy any Christmas gifts this year.

    The survey, conducted by Hong Kong Research Association, found Hong Kong citizens are rather cautious about this year’s Christmas consumption, as only 16 per cent of 1,084 interviewees expect spending more money than last year, while 23 per cent said they would reduce spending .

    Adding to the problem, it seems that even if Hongkongers do plan to go shopping for Christmas, they prefer to buy overseas.

    “Even local people wouldn’t buy stuff in Hong Kong ,” said Mariana Kou, retail analyst at brokerage CLSA, adding consumer products are much cheaper in Japan and Korea, as they benefited from weaker local currencies.

    She expected the poor consumption this year will further dampen sales during Christmas, the traditional shopping season, which has already been challenged by the declining tourist arrivals in last six months.

    “The Christmas sales this year will decline for sure” she said, adding the luxury sector would be the one suffering the most.

    Even though most Hong Kong people are cutting their Christmas shopping lists to save money for rainy days, the enthusiasm for shopping is still running high among top earners in the city.

    The same research showed that the wealthiest social class was the only one among the four that has responded with growing budgets for shopping this Christmas, with 13 per cent more interviewees planning to increase Christmas consumption this year than those who plan to reduce spending.

    “Despite the volatilities in the financial and property markets, rich people still have a decent wealth base.” said Wyman Ng, research officer at Hong Kong Research Association, adding “ their behaviour is less affected”.

    Meanwhile, holiday shoppers in Causeway Bay who looked up yesterday would have seen seven people climbing above the huge screen in Times Square to make a statement against the fashion of wasteful consumption during holiday seasons.

    The Greenpeace activists unfurled a huge banner across a big television screen at the iconic shopping mall, featuring the message “Buy Smart Buy Less”.

    The group said Hongkongers trash garments at an alarming speed, which has put a heavy burden on the environment. It urged shoppers to step up and break the cycle of overconsumption

    The Census and Statistics Department also revealed yesterday that the Consumer Price Index (CPI) figures for November rose by 2.4% over the same month a year earlier, the same as that in October 2015.

  • Online data disrupts how consumers buy cosmetics in Singapore

    Online data disrupts how consumers buy cosmetics in Singapore

    The global market research firm TSN just released the results of a study—The Connected Life—that found nearly nine out of every ten shoppers (88%) in Singapore research products before making a purchasing decision.

    “It’s unsurprising that Singaporeans are exceptionally good at shopping,” says retail expert Fabio Trabucchi of TNS Singapore, in his recent commentary piece for the Singapore Business Review. “With more high-end malls per capita than anywhere else in Asia, shopping is now a well-entrenched national past-time.”

    Pre-shopping

    A preponderance of personal care items consumers in Singapore investigates products and prices before actually shopping to buy.

    “Ever keen for a bargain, almost eight in ten (78%) shoppers say they do pre-purchase research for personal care products such as skin care, perfume, and cosmetics, and 66% for hygiene items such as deodorant and shower gel,” explains Trabucchi, referring to data from The Connected Life study.

    This marks a shift in consumer behavior that could inform brand strategy to good effect, aligning packaging, branded content and ingredient information with new consumer preferences.

    “Previously these categories used to be a prime area for impulse buying, but thanks to the ease of the internet, Singaporean shoppers are getting savvier about the products they chose and the rationale behind it,” remarks Trabucchi.

    Information age

    Getting informative content in front of consumers is the key to capturing shoppers’ attention and dollars today.

    Multinational companies are ahead of the game, producing beauty content that resonates with consumers. L’Oréal recently opened an in-house branded content studio in Canada , where employees can create dynamic messaging to reach consumers with information that matters.

    “As consumers in Singapore adopt a more considered approach to their purchases, brand owners and retailers can provide the information – and incentives – they need to make up their minds,” confirms Trabucchi in his post for the Singapore Business Review.

    “Whether online or offline, businesses need to understand researching behaviours and ensure they are providing shoppers with relevant content that informs their purchase decisions,” he believes.

    Concluding, “this means they must stop thinking in terms of advertisements and start becoming content providers that offer relevant information and offers at every stage of the shopper journey.”

  • Expats in Asia-Pacific, including Singapore, highest paid in the world

    Expats in Asia-Pacific, including Singapore, highest paid in the world

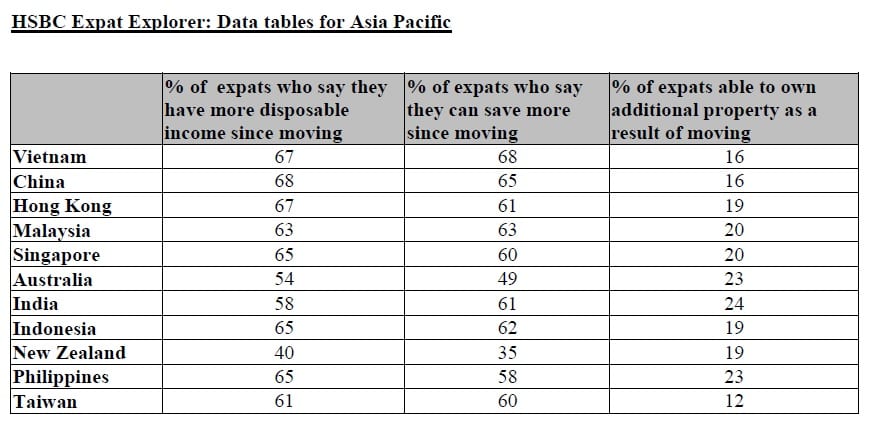
    Expatriates in the Asia-Pacific are among the highest paid in the world, with Singapore in the top five in the region for disposable income and savings, according to HSBC’s latest Expat Explorer survey.

    The region’s appeal for professionals is set to increase further with the formalisation of the Asean Economic Community (AEC). The eight edition of the Expat Explorer survey was completed by 21,950 expats from 198 countries through an online questionnaire in March, April and May 2015 and released on Monday (Dec 21).

    The study found that the annual average salary for expats across the Asia-Pacific is US$126,000 (S$178,000), the highest compared to the global average of US$104,000.

    South-east Asian countries – including Vietnam, Malaysia and Singapore – along with China and Hong Kong, stand out for offering expats the chance to save more money and enjoy greater disposable income.

    According to the survey, 65 per cent of expats in Singapore report greater levels of disposable income (compared to a global average of 57 per cent), 60 per cent are able to save more (global average is 52 per cent) and 20 per cent say they have been able to buy additional property as a result of moving (global average is 17 per cent).

    The ability to save more, enjoy greater disposable income or acquire real estate assets are all important considerations for expats moving to a new country.

    Said Mr Matthew Colebrook, HSBC Singapore’s head of retail banking and wealth management: “Managing finances is a key draw-card for living abroad, whether that be in helping to ascend the housing ladder or opening up lifestyle choices for later life. However, it does come with complexities and often means expats need to consider financial planning not in one, but two or more countries.”

    Apart from the financial incentives, South-east Asia’s appeal will be heightened as mobile professionals will be able to access a wider job market via the formalisation of the AEC.

    The AEC – which comes into effect on Dec 31 – aims to integrate South-east Asia as an economic region by reducing barriers to cross-border trade and investment, and allowing freer flow of professionals to work in other markets in the region.

    Said Mr Colebrook: “Asia offers some of the most rewarding job opportunities, allowing expats to experience and learn skills while at the same time, boost their standard of living and raise lifestyle aspirations. As the Asean countries move closer to economic cohesion, skilled workers will be needed to raise the region’s competitiveness and help companies and sectors to offset locational skill shortages or mismatches.”

    Singaporeans are one of the most globally mobile workforces in the region, with some 212,500 citizens living overseas as of June 2015, according to the Department of Statistics.

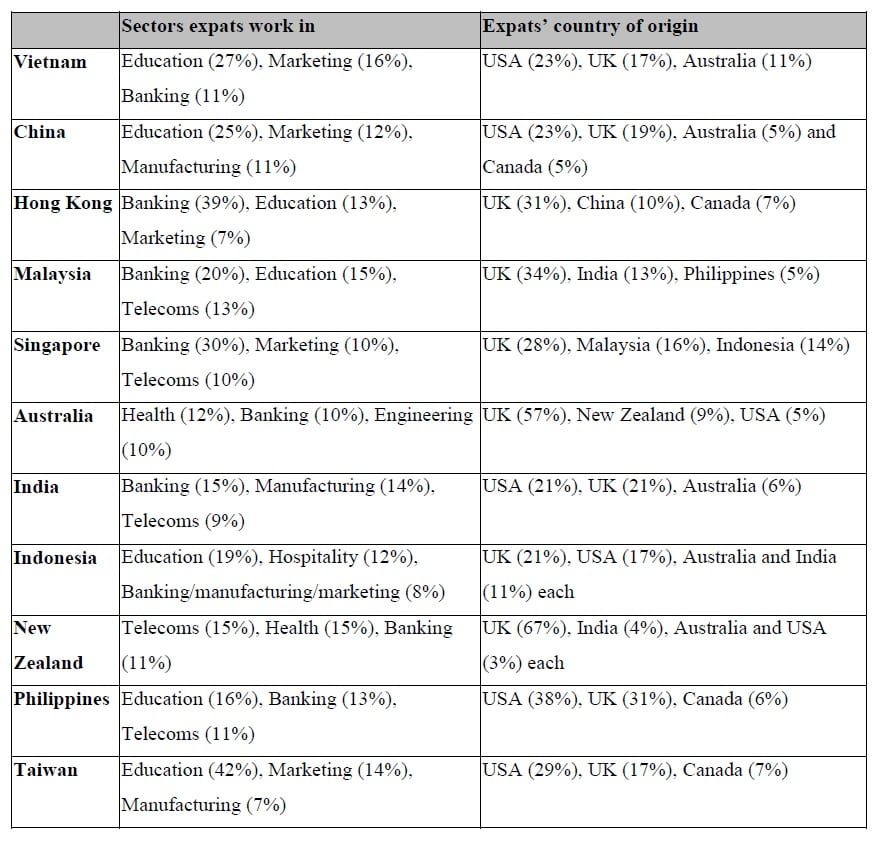
    Based on the sample of respondents surveyed in the latest edition of the Expat Explorer, expats in the Asia-Pacific originate from Australia, Canada, China, India, Indonesia, Malaysia, New Zealand, Philippines, United Kingdom and the United States. They work in industries such as education, marketing, banking, health, engineering, telecommunications, manufacturing and hospitality.

  • Star Wars: A force to be reckoned with on social media

    Star Wars: A force to be reckoned with on social media

    The force has hit Singapore shores and Star Wars: The Force Awakens fans in Singapore could not be more excited. Whether you’re a hardcore Rebel or an Empire henchman, let’s see what’s been going down on social media in the month leading up to this year’s most highly anticipated movie.

    Already, social media is abuzz with anticipation of Star Wars, whether it’s seeing the droids or the Stormtroopers in action.

    Based on conversations from 1 November to 14 December, Digimind Social’s conversation clusters showed immense interest in the merchandise display at VivoCity, as well as the Battlefront game – good news for Star Wars retailers out there.

    StarWars

    The top hashtags feature also showed the ongoing #starwarsatchangi campaign, which features a life-sized T-70 X-wing and TIE fighter, as well as character appearances at Changi Airport, among the top 10 Star Wars related hashtags in Singapore.

    hashtag SW

    The Force awakens on social media

    Conversations about the 7th installment of Star Wars spiked on 16 November, at more than half a thousand mentions. We suspected it had something to do with it being the day movie tickets went on sale.

    Trend

    Who’s ruling the galaxy on social media?

    Out of the ensemble of characters, it was supervillain Darth Vader, droids R2-D2 and BB-8 and newcomer Kylo Ren that garnered the most traction online. Most of the conversations about Darth Vader were related to games and merchandise.

    SW characters

    A new generation comes to the Force

    While the Star Wars series has been around for decades, most of the conversations online belonged to the 18-25 age group. But it looks like this one belongs to the boys, with 71% of the conversations.

    Social medi sw

    War continues in the online shopping arena

    In the online shopping arena, there has been an­­­other type of lightsaber combat for a share of the SG$4 billion Retail Empire in Singapore.

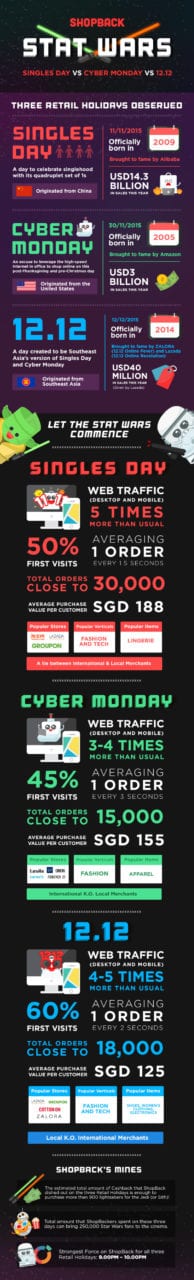
    Thousands of e-retailers such as ZALORA, Taobao, Expedia, Lazada, and Groupon have recently fought for sales on specific days known as the Retail Holidays. ShopBack has observed some interesting numerical movement this Star Wars season and has pitted it  and has decided to pit the three Retail Holidays – Singles Day, Cyber Monday, and 12.12 against each other in an infographic.

    Take a look on which day came out on top:

    INFOGRAPHIC - Stat Wars_Retail Holidays

    May the Force be with you!

  • Are physical stores on their way out?

    Are physical stores on their way out?

    The signs are alarming for brick-and-mortar stores. Recent trends have shown shoppers here are increasingly taking care of their shopping needs online, drawn to the increasing convenience (especially during the dreaded festive seasons).

    Retailers such as Qoo10 and Lazada are a hit because of their wide variety of goods at relatively low cost and reliable delivery services. In fact, a recent survey by Blackbox Research of 800 Singaporeans and permanent residents aged 15 years and above revealed that the majority prefer shopping online.

    As far as this year’s Christmas shopping is concerned, 56 per cent of them said they preferred to do their shopping with online retailers versus the 44 per cent who opted for shopping at physical stores.

    Nevertheless, Retail News spoke to remain upbeat and confident about the value of physical stores, stressing that they have a place in the market, providing a human touch and at atmosphere that websites cannot rival.

    Katie Page, chief executive officer of Harvey Norman, agrees and scoffs at the idea of online stores eventually surpassing physical ones. “You can get information about the product online and the price, but that’s it,” she said, adding how physical contact with the product is crucial, especially with women shoppers. “Women like to see that physical aspect, they will go to the shops to see the product.”

    Stenders fills its store with colourful fresh flowers and prides itself on handcrafted body scrubs and soaps with real natural ingredients such as Lavender. — TODAY pic

    Page also stressed the importance of delivering a great shopping experience, pointing out how some retailers forget that. She added: “You need to invest in the brand, and for that, you need space. Some online stores are now opening brick-and-mortar outlets, right?”

    Agreeing, Christophe Cann, group chief executive officer of Robinsons Group (Asia), said although the company has plans to have an e-commerce function in the future, online shopping is “just another avenue for customers to make their purchase”.

    “We are not worried about the trend as we believe that brick-and-mortar business will remain relevant to customers,” he affirmed.

    “As long as Robinsons continues to entertain our customers and provide an enjoyable shopping experience … I believe we are here to stay.”

    This, he added, is achieved through initiatives such as designer trunk shows, exclusive beauty launches and meet-the-designer events that complement ongoing efforts to constantly bring in new brands and products.

    All about atmosphere and service

    Retailers are confident that nothing beats being at a physical store, as good experiences will ensure customers return.

    “We cultivate a friendly ambiance and treat our customers as friends,” said a spokesperson for skincare and cosmetics store Stenders, which prides itself on handcrafted body scrubs and soaps made with natural ingredients. “Most of our customers love coming back to test, try, and smell and feel the product, and interact with our store associates,” he continued.

    (To boot, customers will also receive a kaleidoscope, as part of its A Kaledoscopic Christmas campaign.)

    The obvious physical connection cannot be overemphasised, as much of the joy of retail, said Darellyn Lau, managing director of candy and gift store Sophisca Singapore, is in touching and feeling the merchandise.

    “The desire for instant gratification is still key with some buyers, who appreciate the ability to touch, feel and buy an item all in the same moment, which is only possible at a physical store.”

    Still, aware that online shopping is time-saving for people with busy schedules, she added that the company is offering free delivery services for purchases above S$250 (RM 760).

    Robinsons, too, said it has had to rethink its strategies to improve its services and in-store experiences.

    “It has motivated us, as brick-and-mortar retailers, to sit up and listen, to observe, learn and adapt … This new platform sheds light on what consumers are looking for, as well as the services they desire,” said Cann.

    Consequently, the company has made arrangements for delivery services with every S$200 nett spend and complimentary personal shopper services at its flagship store at The Heeren.

    “In this day and age … customers need a good reason to visit you,” he added.

    “Retail is not just about transactions but experiences. Hence, we constantly remind our staff from all departments about the company’s vision and mission to ensure that as an organisation, we always put the customer at the centre of everything we do.”

    Online complements, not threatens

    Some retailers say their online stores serve more as a complementary service to give consumers more options.

    Dominic Wong, chief operating officer of beauty-care chain Watsons, said while its new eStore (launched this year) is a quick and convenient option for busy customers, its physical stores “serve as a good platform for customers to discover and try new products, especially for make-up and beauty items”.

    Its in-house pharmacies also provide another touch point for customers who need health consultation and recommendations on supplements.

    This Christmas, it is also offering a free gift-wrapping service for purchases made.

    While the online store’s performance is “growing strongly”, the company “see(s) physical stores flourishing alongside online channels”, he continued, adding that it will continue to be on the lookout for new ways to improve and engage customers better.

    Its recently revamped Ngee Ann City and Bugis outlets, for instance, cater better to the demographics and buying patterns of customers in the area, and give clearer demarcation of the different product categories, said Wong.

    A Uniqlo spokesman, too, said the fast-fashion brand’s online store is an extension of its physical store, giving customers the option of shopping from home and on-the-go.

    However, its staff has been specially trained to provide assistance and recommendations by catering to the needs and queries its customers may have in store, she added.

    “We believe this personal touch is key to create an enhanced shopping experience and will keep customers coming back despite the convenience of online shopping.”

    Clearly, though, the advantages of both platforms remain complementary. “Shoppers are still basing their decision by checking online for reviews and information before stepping into the stores and vice versa. The relationship between off-line and online is, in fact, a symbiotic one … ,” said Publicist PR’s director, Cecilia Tan.

    Pointing out that physical retailers should focus efforts on creating a stronger in-store experience, Tan added: “As a PR and brand consultancy, we recommend that clients focus on their core group of customers … It is important to keep them close through customer perks and in-store activities.”

    She stressed that “retailers need to integrate their communication campaigns through both traditional PR and digital PR; that is the best way to ensure customers will want to visit a physical store, validate their choices, and ultimately (make a) purchase after researching about their brand online”.

    For other stores, online sales serve as a platform to reach out to more people. Men’s Grooming Store WhatHeWants has seen online sales more than double compared with three years ago. Online sales currently make up 30 per cent of its total sales.

    Its founder Tan Seng Hwee said he is excited about the online trend.

    “The online space is not limited to the space it occupies, unlike a physical store. Besides Singapore, my sales revenue comes from Malaysia, Australia and Indonesia,” he noted.

    “The trend of buying online is definitely making big waves with the increasingly tech-savvy crowd, and the widespread use of tablets and mobile phones. Coupled with lower prices and deliveries right to one’s doorstep, buying online definitely has many plus points,” he added.

    Pointing out that physical shops need to maintain a higher margin in order to cover rental and staff costs, he said prices in physical shops “can never be cheaper than online stores”.

    “In the past, retail businesses expanded by opening more physical shops.

    “However, in Singapore, the high rentals and labour crunch limits scalability. For a company to grow further, moving online is the only way to go,” he explained.

    “While retail stores are still important, the retail industry in Singapore has to learn how to adapt to the  new online world.”

  • Hong Kong must step up support for the tech sector

    Hong Kong must step up support for the tech sector

    Hong Kong has established the Innovation and Technology Bureau in a bid to bolster technology and innovation development.

    The IT workforce in the city has jumped nearly four-fold from 3,000 two decades ago, according to a survey from the Vocational Training Council. However, the talent availability for jobs such as program development has been falling while IT managerial jobs have been stagnant over the years.

    IT jobs in Hong Kong are mostly sales, support and after-sales service positions, as product development positions have been contracting over last one or two decades. Simply speaking, Hong Kong’s IT industry focuses more on technical support rather than technology innovation.

    The city’s economic structure is one of the underlying reasons. Hong Kong relies heavily on property, finance and retail sectors which require only technical support services from the industry. As a result, the IT sector has lagged behind in development of high-end technology products.

    Local universities have been trying to nurture talents for the industry. However, secondary school students have very limited interest in either IT or electronic engineering.

    Secondary students who apply for these programs had relatively lower scores in the Hong Kong Diploma of Secondary Education Examination since the 2000 dotcom bubble.

    Why has Hong Kong made little progress in developing the IT industry? Let’s take a look at some places where the IT industry has flourished — Israel and Singapore.

    Many of Israel’s industries are closely tied to its national defense. The Jewish state’s internal and external security work involves national interests. Hence, the country finds it necessary to promote the high-tech sector.

    Its modern national defense industry involves high-technology such as communication, electronics, materials and auto control technology. As technologies are sought to be upgraded continuously, talents have been nurtured, resulting in a huge pool of skilled professionals.

    Also, military enterprises usually have a long supply chain, including upstream and downstream technology and products supply. That creates a spillover effect. Some of the talents might quit their jobs and start up their own companies.

    Meanwhile, technology talents in other sectors might be inspired to become entrepreneurs themselves. They have much more experience and knowledge than young graduates.

    A “visible hand”, or government support, is a key element for nurturing hi-tech companies.

    Park Chung-hee, who led South Korea from 1961 to 1979, had hammered out preferential policies for large tech companies. That has helped create a number of tech giants like Samsung and LG.

    Singapore is even smaller than Hong Kong. However, the city state has managed to become a leading player in recycling used water, thanks to government incentives.

    Favorable government policies are essential for development of hi-tech industry.

    Authorities should provide some protection for the sector in the early stage before it can stand on its own feet. The government needs to take care of the interests of various stakeholders.

  • Meet the man behind EZ-Link cards in Singapore

    Meet the man behind EZ-Link cards in Singapore

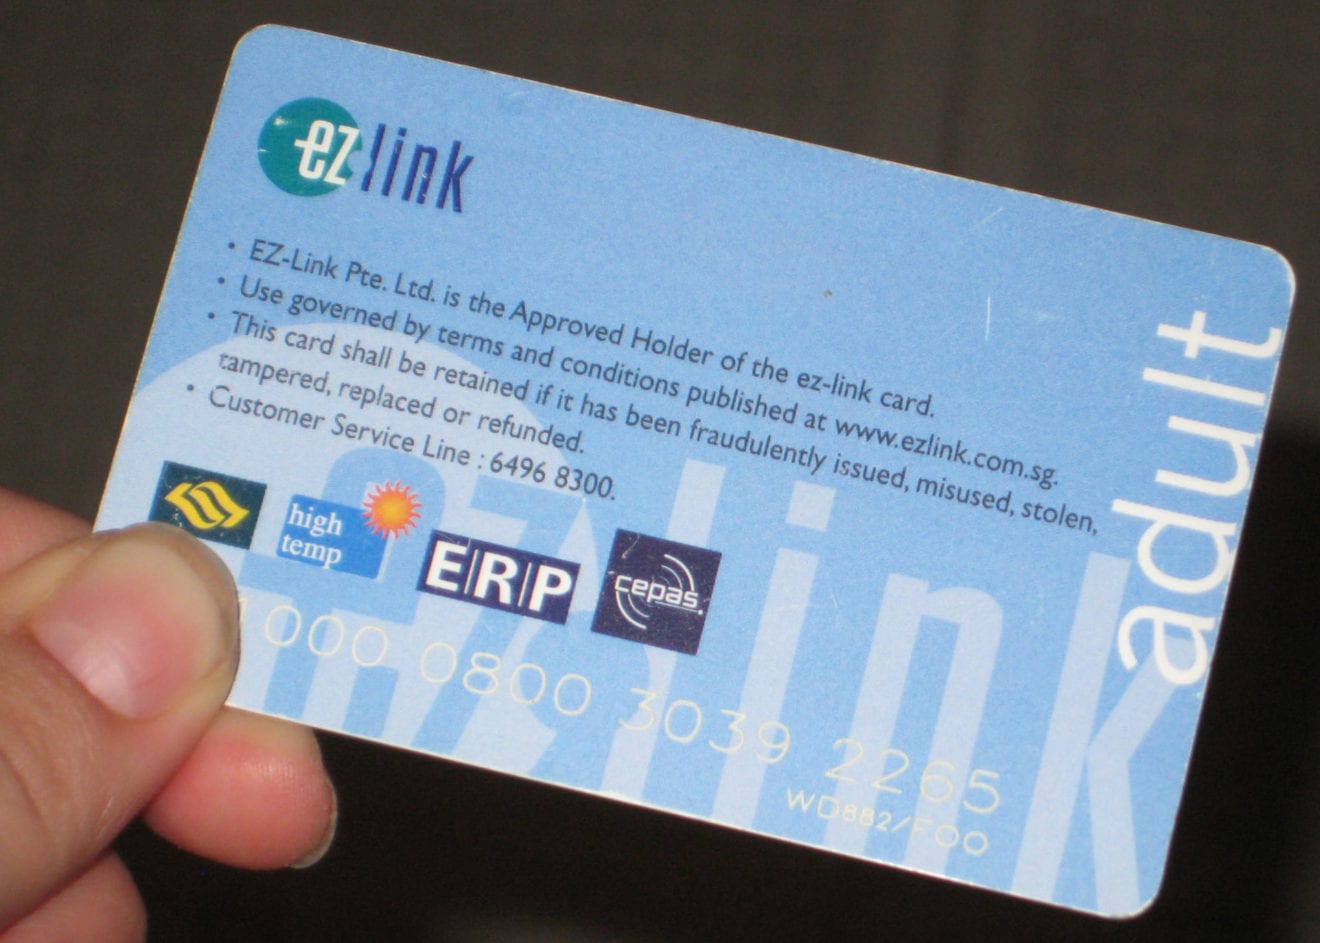
    Nicholas shared his strategies to displace cash totally. Always try and do not be afraid of failure. Every failure is part of our learning experience and must help us improve.This is so that we do not stagnate nor remain in the status quo while the environment around us continues to evolve. Those are the words from Nicholas Lee Tat Meng, the man behind Singapore’s EZ-Link cards, a contactless smart card used for the payment of public transportation fares in the city, with limited use in the small payments retail sector.

    Nicholas started his engineering career as a systems engineer in a local systems integration company prior to joining the Land Transport Authority of Singapore (LTA) in early 1997. In the LTA, he held various engineering portfolios before being seconded to its Policy Division to work on international relations and the development of business models for new transportation projects.

    In 2000, Nicholas was assigned to manage the island-wide implementation of the EZ-Link card. This included the design, development and implementation of a clearing-settlement backend system and the rollout of acceptance terminals across all mass rapid transit and bus transport systems in Singapore.

    Following the launch of the EZ-Link card in 2002, Nicholas then moved on to EZ-Link Pte Ltd, a wholly owned subsidiary of the Land Transport Authority. Over the years, he held several portfolios from developing business models and operating structure to supervising the company’s marketing efforts and corporate communications. On 1 October 2011, he was appointed as CEO of EZ-Link to lead the company to greater growth in adoption, transactions and applications of cashless payments.

    EZ-Link’s humble beginning

    EZ-Link was formed on January 8, 2002 with its core business of clearing and settlement of all EZ-Link card transactions generated in transit and non-transit (retail/merchant) environments, as well as the sale, distribution and overall management of EZ-Link cards. In 2009, EZ-Link became the first card issuer in Singapore to launch the CEPAS-compliant EZ-Link card. Thereby extending the company’s influence beyond the local public transport sector and into the retail and food and beverage industries.

    These new EZ-Link cards are also accepted as a mode of payment for Electronic Road Pricing (ERP) and at carparks fitted with the Electronic Payment System (EPS) when used in the dual-mode in-vehicle unit. To date, more than 17 million new CEPAS-compliant EZ-Link cards have been issued.

    “Over the years, we have been working towards the vision of a cashless society with the launch of several ground-breaking products and services such as the My EZ-Link Mobile, the world’s first and award-winning mobile application for EZ-Link card top-ups; EZ-Charms, the first EZ-Link non-card form factor in Singapore; and EZ-Link Rewards with Perx, the first-in-Singapore rewards scheme for public transport EZ-Link users,” said Nicholas.

    Apart from benefitting the consumers and commuters, EZ-Link is also looking to help businesses in Singapore to enjoy the benefit of cashless transactions through their services. Currently, there are over 30,000 acceptance points island-wide tapping on the EZ-Link card payment system which provides quicker customer service and lower costs related to cash handling.

    According to Nicholas, EZ-Link has the privilege of serving more than 3 million customers using their products and services daily. “This is a huge responsibility for us to undertake as we have to ensure that customers’ expectations are met when they interact with the cards, and the availability of sufficient infrastructure and capability to assist them in using our services,” he said.

    The biggest challenge

    However, the task of transforming Singapore into a cashless society was not that easy. Nicholas shared that their biggest challenge has been in the area of cash or in other words, how they can displace cash and encourage greater use of electronic money via the EZ-Link card. “Of course, our scope is not just limited to usage of the EZ-Link card, but also on topping it up as well. For instance, more than 40% of top-ups of the EZ-Link card are still done via cash.”

    To address this challenge, Nicholas shared that they have introduced schemes such as EZ-Reload to link an EZ-Link card to a bank account or credit/debit card account. In the event when the card runs out of stored value, it will automatically top itself up so that the cardholder will never have to go to a device to do a top-up.

    “We initially charged a $0.25 fee for this service, but have been progressively making it free for all DBS/POSB and Citibank card holders. With EZ-Reload, our customers are able to rely less on physical top-up points, and save themselves from the hassle of queuing up at Ticketing Offices and General Ticketing Machines,” said Nicholas.

    Nicholas shared that the next challenge is displacing cash in the retail/F&B area for small sum payments meaning those less than $20. In the past, the firm have invested into infrastructure to enable merchants to accept the EZ-Link card as a means of payment. However, Nicholas shared that there has been much resistance to this change by consumers and eventually, cash still prevailed.

    The journey ahead

    Moving forward, Nicholas said that they have partnered with various industry players to create a more open and efficient payment infrastructure that will accept all means of payment including the EZ-Link card. This means a collaborative approach with other industry players to enable multiple modes of payment so that consumers have more choice and flexibility in choosing the right electronic payment method to use, as opposed to cash payment. “Hopefully, the EZ-Link card will be the preferred choice of payment for consumers. In doing this, we are working together with the industry to tackle a challenge instead of facing it alone,” he said.

    Furthermore, Nicholas said they are gradually transforming into a new organisation, in terms of how they operate, how they engage with their customers and how their services are delivered.

    “We are looking at new digital services, increased personalisation of services to fit individual consumers, more exciting EZ-Link products that may come in different shapes and sizes and capable of interacting with individuals. With the rapid advancement of technology, we have an opportunity to evolve EZ-Link to another level,” Nicholas adds.

    Nicholas’ guiding principles

    Apart from not being afraid to fail, Nicholas believes that it is important to always question themselves why and how should they remain relevant to their customers and stakeholders. This, he said, ensures continual renewal of practices and business to keep up with the rapid changes in the environment, which is especially important given the rise of various disruptive business models.
    Secondly, he emphasised on the need to stay focused on their core business and do what they do best. “We innovate by collaborating with industry partners through win-win relationships and are always mindful of doing things beyond our capabilities,” he said.

    Meanwhile, in his journey building a cashless Singapore, Nicholas is focused in three goals:

    • To transform the EZ-Link card into a lifestyle product (beyond public transport but also in cars, taxis, private buses, identity card) and make it the preferred choice of consumers in their everyday lives
    • To be a consumer-centric company whereby services and innovation are developed around consumer needs and expectations
    • To contribute substantially towards Singapore’s goal of becoming a cashless society
  • APAC tops retail e-commerce

    APAC tops retail e-commerce

    Retail e-commerce sales in Asia-Pacific will reach $877.61bn in 2015, up 35.7% from 2014, as mobile adoption and the rising middle classes in China, India and Indonesia fuel rapid growth, according to a new forecast.

    Research firm eMarketer said that, for the first time, the region will not only have the largest digital market in the world, but its share of global retail spend will reach a majority of 52.5%.

    China alone will account for more than 40% of global retail e-commerce sales this year, up nearly five percentage points from 2014, and the country is expected to continue growing its share of the worldwide market to more than 50% in 2018.

    By then, the value of retail e-commerce sales in China is forecast to be a massive $1.568 trillion compared to a worldwide total of $3.015 trillion. Meanwhile, Asia-Pacific (including China) will account for $1.892 trillion in three years’ time.

    Online retail sales in China are expected to account for 15.9% of the country’s total retail sales in 2015, compared to a global average of 7.4% and 10.2% in Asia-Pacific.

    Although China dwarfs other Asian nations in terms of online sales volumes – for example, $672bn in 2015 compared with just $14bn in India – the report also highlighted India and Indonesia as other key drivers of growth in the region.

    The latter two markets saw growth of 129.5% and 65.6% respectively in 2015, the report said.

    Monica Peart, eMarketer’s director of forecasting, said rapid online growth in Asia-Pacific, coupled with faster internet service and greater mobile uptake is heating up the competitive landscape.

    “Large local players are increasingly vying for market share by improving their logistics and mobile platforms, and in some cases moving entirely to an app-only service,” she said.

    Finally, eMarketer forecast that overall retail sales in Asia-Pacific would reach $8.57 trillion this year, rising to $11.46 trillion by 2019, or representing 20.4% of worldwide retail sales. Data sourced from eMarketer; additional content by Warc staff

  • How to choose the right smartphone in India

    How to choose the right smartphone in India

    In this modern era, mobile phone is an important thing for every person and its importance cannot be ignored because of the latest technology by which an individual can use the internet on it and can stay in contact with the dear ones. It is obvious that a mobile phone is an expensive product which cannot be changed after a short period of time, so a person should select the mobile phone carefully. Given below are some points which can assist in making a good decision of choosing the best mobile phone in India.

    Know your requirements:

    A person should list down the requirements because it makes the decision making process and selection easy. He or she should figure out what matters most to him/her like if the person uses the mobile for a lot of texting then the focus should be on the keyboard. Some individuals like physical keyboard while others like to use touch keyboard, so it should also be kept in mind that which keyboard he or she finds easy for texting because some people like to use QWERTY keyboard.

    If the person is fond of taking selfies or clicking random pictures then the attention should be paid on the camera. Nowadays, individuals mostly use mobile phones for using social media platforms or for checking E-mails so, if the person wants it for using the internet then he or she should focus on the internet capabilities. One should not ignore the deciding the size of the mobile and the screen size.

    Prior to making the final decision of purchasing the mobile phone, a person should not ignore listing the personal preferences because not paying attention to the desired choices can result in a wrong purchase.

    A vendor speaks on his mobile phone as he waits for customers at his roadside shop selling clothes in Mumbai

    Choose the brand:

    There are many famous brands available in India so, a person should choose the brand before he/she starts looking for the mobile model.

    Find the right design:

    Mobile also reflects the sense of style of the person holding it so one should find the right design that not only looks great when a person carries it, but a person should also be comfortable with the way it looks so a person should pay attention on its design.

    Browse through search engines:

    A person can browse through the search engines to know about the specifications of different models of different brands, which is the best way of selecting the best mobile fulfilling the requirements. One can also see the looks of the mobile phone on the mobile selling websites which he or she has decided to purchase.

    Read reviews:

    Reading reviews on different mobile selling websites is a great way of getting information about the mobile functioning and it is the best way of purchasing the right mobile because one can avoid purchasing a mobile which he or she has selected if the reviews of the individuals using it are not good. Feedbacks of the mobile users assist a lot in making the final decision and helps in preventing the wrong purchase which saves the hard earned money.