Category: Research

Retail News Asia is committed to providing both local and global retailers with the latest Research throughout the Asian market. This on a daily base.

  • Bluetooth Beacons – Malaysia’s Retail Future

    Bluetooth Beacons – Malaysia’s Retail Future

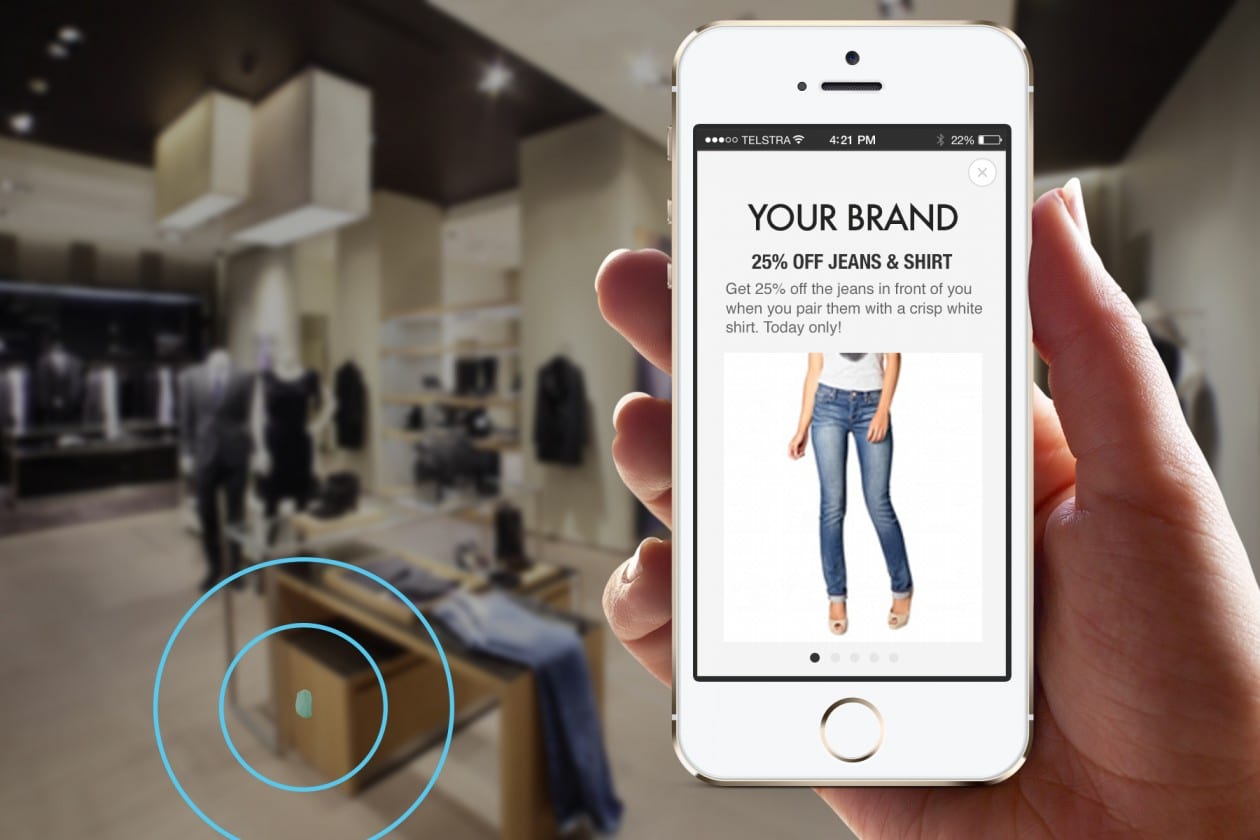
    Picture the following scenario: You walk into your favourite apparel store and your smartphone beeps with a push notification “Welcome back Linda! Only for today, we are giving you a 20% discount on all skirts”. You decide to finally get that blue skirt you have your eyes set on for weeks and decide to take a stroll through the accessories section when you stop to admire a particular necklace, after a few seconds of contemplation, your smartphone beeps again with the message “Hey Linda! Get a necklace to match your outfit, we’ll throw in a 30% discount on any necklace of your choice”. You leave the store with a new skirt and necklace at a bargain.

    You end up a happy customer, and the apparel store makes additional sales –  a win-win situation for all involved.

    The above situation may sound like a utopian future where the Internet of Things (IoT) have become a reality. However, the future is closer than we know it with the arrival of iBeacons by Apple in 2013 and Google unveiling Eddystone Beacons in July 2015.

    What Are Bluetooth Beacons?

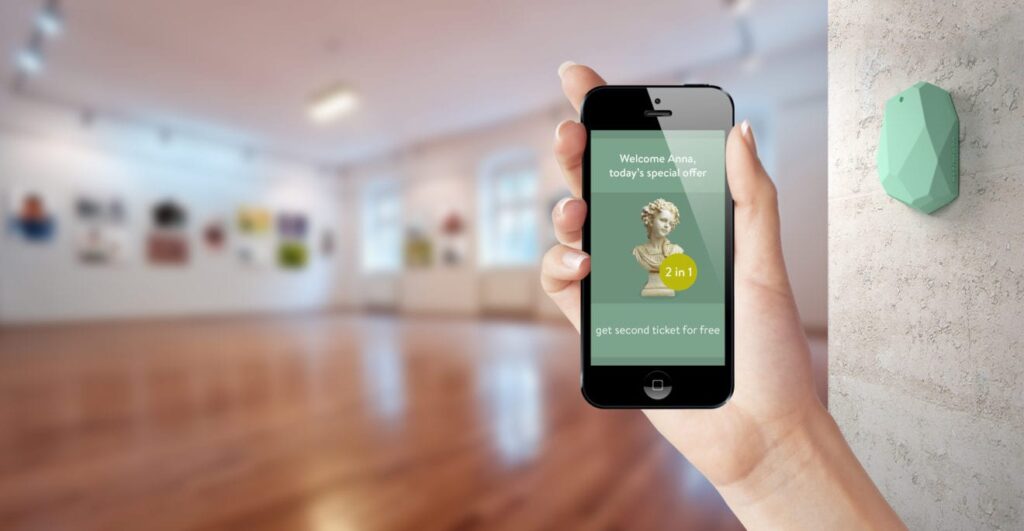
    Beacons are transmitters which have the ability to sense nearby portable smart devices and “talk” to them via push notifications. Beacons are the most accurate form of locational based tracking device and may work with existing GPS and WiFi tracking capabilities to further enhance location tracking via triangulation.

    How Do They Work?

    Beacons use Bluetooth Low Energy (BLE) proximity sensing to broadcast universally unique identifiers (UUID) which are picked up by compatible apps and operating systems (OS). This means that users will need to have beacon-compatible apps (a relatively simple process can enable any app to be beacon-compatible) installed and have their Bluetooth switched on in order for their smartphones to interact with these beacons.

    Why Would Users Leave Their Bluetooth Switched On?

    This is a question which frequently surfaces during discussions with potential beacon adopters. It is true that a majority of smartphone users never and might even hesitate to turn on or leave their Bluetooth switched on due to the concern that the Bluetooth would contribute to a huge drain on their battery life.

    That is until 2011 when the new BLE technology were incorporated into the new iPhone 4S smartphones and subsequently, all smartphones released after that period. With the new Bluetooth Smart standard, worries of Bluetooth drainage on phone battery life were a thing of the past as the power needed to power Bluetooth is now so low that it is negligible.

    Other than that, most smart devices that are making their way into our everyday life such as smart wearables (e.g. Fitbit, Jawbone, Apple Watch), Bluetooth-enabled car audios, and smart kitchen appliances require the use of Bluetooth-enabled smart devices.

    With over 10,000 Bluetooth-enabled products listed with Bluetooth SIG along with the immense growth (>100% in 2014) of the Smart Home, Consumer Electronics and Beacons markets, coupled with the growing number of users coming to understand the new Bluetooth technology as well as the growing need of users to have Bluetooth-enabled to run their everyday smart lifestyles, 24/7 Bluetooth-enabled devices will soon be a lifestyle choice much like the 24/7 WiFi-enabled devices which are part of everyday life now.

    What It Means For Retail Businesses

    With the ability to understand what interests consumers and know when they are in the proximity, brick and mortar retailers can now interact digitally with potential customers to encourage more foot traffic into their outlets and achieve higher sales conversion by sending the right message, to the right people, at the right time.

    However, the use of beacons in retail businesses does not stop at pushing promotional messages and general information. With beacons, retailers are also able to provide a personalised shopping experience to each individual customer as seen in the aforementioned story above. Depending on the nature of the business, beaconised businesses will have a a plethora of uses for beacons such as, helping customers navigate a store and providing in-store concierge services by utilising the tracking abilities of beacons. Think shopping on Amazon or Zappos, but in real life.
    press-beacon-product-2.ae0092e2

    The longer a retailer adopts the beacon technology, the more they will begin to understand their customers – who they are, what their preference is, where they like to shop, are they high or low spending customers. This is all possible as more and more data on these users are collected and analysed -allowing businesses to produce individualised ads and engage in behavioural retargeting.

    With the arrival of beacon technology, retailers with physical outlets will finally be able to gather data on their customers in real life in real time and run the most effective and efficient campaigns to target the most relevant consumer segments while providing a highly personalised shopping experience. The future of retail globally, especially here in the South East Asian region and in Malaysia, is in beacons and any retailer slow to adopt this breakthrough tech as part of their arsenal will be at a huge disadvantage moving into the future.
  • The key transformation of Indonesia’s economy

    The key transformation of Indonesia’s economy

    Industrial production was transformed by steam power in the nineteenth century, electricity in the early twentieth century and automation in the 1970s. These waves of technological advancement did not reduce overall employment, however. Although the number of manufacturing jobs decreased, new jobs emerged, and demand for new skills grew. Today, another workforce transformation is on the horizon as manufacturing experiences a fourth wave of technological advancement: the rise of digital industrial technologies that are collectively known as Industry 4.0.

    The industrial transformation will create a critical juncture affecting almost every country. Countries that allow and incentivize their citizens to invest in new technologies could grow rapidly. Indonesia is still at a relatively early stage of economic development. Its markets have progressively opened, and a lot of basic infrastructure has been put in place, but its business environment is still raw and volatile.

    The government’s Master Plan for the Acceleration and Expansion of Indonesia’s Economic Development (MP3EI) 2011–2025 seeks to address challenges that persist due to Indonesia’s geographical spread and rapid urbanization. Its main goal is to ensure sustainable development of resources and labor, aiming to grow per-capita income to US$15,000. This goal calls for an average economic growth rate of 8-9 percent from 2015 to 2025 while seeking to rein in inflation of 5-6 percent currently to an average 3 percent in the next decade.

    The government recently restated the importance of reorienting future economic development from a consumption-led economy to one driven more by production. That message recognizes that the industrial sector’s contribution to gross domestic product (GDP) has been declining over the past 20 years. Indonesia needs to actively encourage e-commerce, industrialization and entrepreneurship.

    Inclusive economic institutions will enforce economic dynamism and culminate in the industrial transformation. Without changes to the development strategy, there will be little chance for Indonesia to benefit from Industry 4.0 innovation and new technologies. There are at least three challenges to Indonesia’s Industrial transformation: human capital development, financial inclusion as well as political inclusion and bureaucracy reforms.

    The Indonesian school system is immense and diverse. With more than 50 million students and 2.6 million teachers in more than 250,000 schools, it is the third-largest education system in the Asian region and the fourth-largest in the world.

    Indonesia has made impressive progress on many fronts in the education sector since the 1997-1998 Asian crisis, such as coverage of basic education.

    Many challenges remain, including expanding enrolment in secondary and tertiary education, increasing the quality and relevance of subjects taught and making governance and finance more responsive.

    In order to achieve its goal of becoming a developed economy, Indonesia must be an innovation power. While the government commits 20 percent of state budget funds to education, the quality of teachers, the standard of educational facilities and the quality of research and development remains a problem. The ratio of engineers in the population is low compared to other ASEAN countries at only 2,671 per 1 million inhabitants. Neighboring countries have achieved ratios of 3,337 engineers per one million. The Central Bureau of Statistics reports that only 2 percent of business operators in the industrial sector are graduates of higher education, a large group has only junior to high school education, and the largest portion only graduated from elementary school.

    This suggests that the capacity of business people to absorb new science and technology to drive their companies forward is very limited. Only with reliable education and good training can good industrial development be achieved.

    The level of financial inclusion in Indonesia is at a critical level. Fifty-three percent of the Indonesian people are excluded from banking deposit products and 83 percent are excluded from financing products. Micro, small-and medium-sized enterprises (MSMEs) dominate business units with up to 99.9 percent of total business units and employ around 97.7 percent of the total labor force.

    Unfortunately, the contribution of MSMEs to GDP is still relatively low, at only about 57.8 percent. Meanwhile, large enterprises, which account for only 0.01 percent of the total number of enterprises, contribute 42.2 percent to GDP and receive loans of more than Rp 3.2 quadrillion (US$230 billion) or 82 percent of total bank loans.

    Moreover, MSMEs still get a small portion of bank financing. Based on Bank Indonesia data, outstanding loans of MSMEs total Rp 716.37 billion or 18 percent of total outstanding bank financing. Medium-scale enterprise loans dominate MSME credit with a share of 49.51 percent of total MSME loans. Micro enterprises, which account for 98 percent of all business units, take a share of just 3.8 percent of total bank loans, equivalent to Rp 153 trillion.

    Inclusive economic institutions foster economic activity, productivity growth and economic prosperity. Inclusive economic institutions create inclusive markets, which not only give people the freedom to pursue the vocations in life that best suit their talents but also provide a level playing field that gives them the opportunity to do so. Those with good ideas will be able to start businesses, workers will tend to go to activities where their productivity is greater, and more efficient firms can replace less efficient ones.

    Indonesia adopts an economic planning approach under the purview of several competing agencies, notably the National Development Planning Agency and the Office of the Coordinating Economic Minister. Interdepartmental communication has been growing in recent years, allowing for the formulation of coherent long-term planning that takes into account the broad scope of Indonesia’s national economy. However, problems central to economic policymaking remain: a lack of civil service reform, a lack of strong oversight in the planning process, a high incidence of corruption and difficulty in coordinating between the regions and the center.

    The key leadership skill today is the ability to identify long-term, large-scale opportunities and build the capabilities to turn them into reality. Countries differ in their economic success because of different institutions, different rules influencing how the economy works and the different incentives that motivate people.

    The critical juncture of Industry 4.0 has very different effects in different parts of the world. Societies that have already taken steps toward political and economic institutions have taken advantage of these new economic opportunities and started a process of rapid economic growth.

  • E-commerce in Asia grows 32%

    E-commerce in Asia grows 32%

    E-commerce grew to $835 billion in Asia in 2015, the kind of expansion that beckons web retailers around the world. But moving into cross-border e-commerce means mastering the different market conditions from country to country, according to Internet Retailer’s new 2016 Asia 500.

    The lure of Asia, and particularly China, for international merchants is strong and growing stronger: Chinese consumers alone purchased $589.61 billion worth of goods online in 2015, an increase of 33.3% over the same period a year earlier, according to the National Bureau of Statistics in China. By comparison, online retail sales in the U.S. grew by 15.5% per year from 2011 to 2014 and were up by nearly 15% in the first three quarters of 2015, according to the U.S. Commerce Department.

    The largest domestic e-commerce players are driving the bulk of the sales and growth in China. The 266 China-based merchants ranked in the new Internet Retailer 2016 Asia 500—the largest online retailers in Asia as measured by their annual online sales—grew 65.7% in 2015 to $173.69 billion from $104.82 billion, representing 79% of total Asia 500 sales of $220.00 billion and 89% of the growth. By comparison, the 30 United States-based retailers ranked in the Asia 500 grew online sales 24.2% to $21.91 billion last year—the bulk of that for most of them coming from Chinese customers.

    Indicative of e-commerce growth in Asia overall, total 2016 Asia 500 online sales were up 54.5% in 2015 to $220.00 billion from $142.42 billion in 2014.

    When factoring in the roughly $411 billion transacted through the seven largest online marketplaces, including those owned by Rakuten Inc. and Alibaba Inc., Internet Retailer estimates the Asia-Pacific e-commerce market is worth $834.71 billion, up 32.1% from $631.81 billion in 2014.

    E-retail growth in Asia and China remains far ahead of that in the U.S., one reason many U.S. brands and retailers are looking to expand into these markets. For the first nine months of 2015, adjusted U.S. e-commerce sales totaled $251.98 billion or 7.2% of total retail sales (excluding foodservice) of $3.51 trillion, according to U.S. Commerce Department data.

    Such heady online growth isn’t lost on merchants based outside Asia, particularly those targeting Chinese consumers that crave foreign goods. As added incentive for buyers and sellers, the Chinese government in recent years has made it easier for consumers to buy overseas goods via the web. That includes setting up free trade zones in 10 cities where China’s customs service provides fast clearance of small orders from Chinese consumers. Foreign companies can ship the orders from abroad or store goods in these areas without them clearing customs, and then, as orders are received, send them through the streamlined customs process.

    One way U.S. retailers are reaching shoppers in Asia is through marketplaces. For example, when BCBG Max Azria Group LLC wanted to step up its presence online in China, the U.S. women’s apparel manufacturer and retailer decided the best place to start was Tmall Global, Alibaba’s marketplace for imported goods. BCBG previously shipped online orders to China, letting international e-commerce fulfillment specialist Borderfree handle orders. But growing sales justified a bigger investment in China, says Michelle Magallon, senior vice president of digital commerce and omnichannel.

    In November 2015 BCBG signed a deal with VoyageOne to manage its website on Tmall Global, including marketing and fulfillment, Magallon says. BCBG is in the early stages of putting together a multichannel distribution strategy in China, which includes two stores in Singapore. The company also has five stores in Taiwan.

    BCBG isn’t alone among merchants in the U.S. and other countries looking to sell to the growing number of Asian online shoppers, notably the 375 million Chinese consumers who buy online. But those retailers aiming to enter or expand their online sales in Asian countries all face similar challenges, regardless of home country. To succeed online in Asia, retailers in the U.S. and other nations first are assessing the challenges of marketing, logistics, culture and regulations—and associated costs—for conducting e-commerce in each country.

    For companies like BCBG, which is not yet ranked in the Asia 500 but is No. 424 in the Internet Retailer 2015 Top 500 Guide with online sales of $37.9 million in 2014, the key to connecting with online shoppers in Asian countries is understanding what shoppers want and then evaluating the local vendors who can provide the services needed in each market, Magallon says.

  • Myanmar Year in Review 2015

    Myanmar Year in Review 2015

    A decisive victory for the opposition in Myanmar’s general elections in late 2015 generated a fresh wave of investor optimism, raising hopes of increased economic stability in 2016 after a somewhat uncertain year.

    Victory at the polls in November for the National League for Democracy (NLD), under Daw Aung San Suu Kyi, will see greater civilian participation in government, although the military will retain control of the Ministries of Defence, Interior and Border Affairs in the new Cabinet, alongside a minimum of 25% of seats in parliament and substantial economic holdings.

    Growth leaders

    Growth was robust in 2015 despite cooling in the global economy, with Myanmar posting GDP growth of 8.5%, according to the IMF. This ranks ahead of average growth among the five original ASEAN member nations – Indonesia, Malaysia, the Philippines, Singapore and Thailand – which stood at 4.6%, and average global growth, which reached 3.1%. GDP growth is expected to remain relatively steady in 2016, easing somewhat to 8.3%, as per IMF forecasts.

    Strong consumer demand helped drive expansion in Myanmar’s retail sector, while also boosting the appeal of the industry to foreign brands. International brewers like Heineken and Carlsberg opened in-country production facilities through joint ventures with local partners during the year, and Japan’s Kirin acquired a 55% stake in market leader Myanmar Beer for a reported $560m in August.

    The year also saw strong growth in commercial property development, buoyed by rising demand for prime business space, particularly in Yangon, the country’s financial and business capital. Such demand should help sustain activity in Myanmar’s construction sector, which already has several infrastructure projects on its books.

    In a key development for the country’s financial services sector, nine foreign banks granted licences to operate in the market commenced operations, albeit on a limited scale, by early 2016.

    Trade and budget prospects

    However, the incoming NLD government, expected to be formally sworn in this March, will inherit an economy faced with ongoing structural challenges, including a widening fiscal deficit, projected to reach 5.5% of GDP, according to the IMF.

    Rising inflation also weighed on Myanmar’s economic performance somewhat in 2015, having gained momentum on the back of high levels of liquidity, rising demand and food shortages caused by mid-year nationwide flooding. In its latest Article IV consultation with Myanmar, the IMF projected inflation would rise to 13.3% by the end of FY 2015/16, up from 7.4% in FY 2014/15.

    Price increases have been exacerbated by depreciation of the kyat, which lost around 21% of its value against the US dollar over the year, driving up the cost of imports and affecting both consumers and firms that rely on overseas technology and equipment for expansion.

    To ease pressure on the kyat and rein in inflation, the Central Bank of Myanmar announced plans in late November to raise the reserve requirement ratio of banks and increase the value of its fortnightly deposit auction, with an interest rate hike also signalled as a possibility.

    A weaker kyat contributed to a widening of the trade deficit, with the gap between imports and exports reaching MMK3.1trn ($2.4bn) for the first six months of FY 2015/16, up 27% year-on-year.

    Major flooding weakened export trade further in mid-2015, after damage to farmlands led to lower production. To maintain food security and stabilise domestic food prices, the government imposed a six-week freeze on rice exports, one of the mainstays of Myanmar’s foreign trade.

    Investment forecast

    Foreign investment has also slowed somewhat, reaching $4.1bn as of December 2015, according to the Directorate of Investment and Company Administration. By the end of FY 2015/16, foreign investment was expected to reach $6bn, down from $8bn in FY 2014/15.

    The oil and gas sector has attracted the bulk of the investment to date, accounting for more than $2bn of the total as at December, while transportation and communications saw $736m worth of investments and manufacturing received $685m.

    Investment inflows are expected to ramp up again in 2016, with a smooth election in hand and the promised transition of government scheduled in the coming months.

    According to U Aung Naing Oo, secretary of the Myanmar Investment Commission, greater investment from EU countries in particular is forecast during the first six months of 2016.

  • Luxury Retailers Scale Back China Brick-and-Mortar Expansion in 2016

    Luxury Retailers Scale Back China Brick-and-Mortar Expansion in 2016

    As Chinese luxury spending decreased in China, yet rose globally last year, luxury retailers are hitting the brakes on brick-and-mortar store expansion for 2016.

    According to a report on retail in China published this month by UBS, wariness toward store expansion is at an all-time high. It found that 94 percent of retailers surveyed have a “moderate” attitude toward China expansion in 2016, rising from 85 percent in 2015 and 72 percent in 2014. A total of 67 percent said they will expand by less than 10 percent in 2016, while 6 percent said they will expand from 10 to 20 percent. Meanwhile, 22 percent of retailers plan to close stores this year.

    The retailers with the biggest expansion plans are generally department stores, according to the report, but that’s not necessarily due to sales growth. It notes that larger stores generally plan their expansion at least five years in advance, so many department stores were preparing openings happening now during China’s era of rapid growth.

    Among luxury retailers, Louis Vuitton was one of the most highly-publicized brands to halt expansion in China last year as it closed stores in Guangzhou, Harbin, and Urumqi. In addition, Chinese media reported this week that Gucci closed a Chengdu store as it readjusts its flagship arrangement in China.

    Although the shift in spending abroad and online are factors in these decisions, luxury retailers are also focusing on recalibrating their location choices. U.S. think tank The Demand Institute wrote in a report last year that many foreign brands had expanded into smaller cities when they should have been focusing on the first tier. It stated that “overly optimistic growth and consumption projections for China have misled foreign investors” into expanding too far into lower-tier cities.

    This appears to be Louis Vuitton’s position, as it opened stores in Beijing and Hangzhou last year even as it closed its other locations. A report by CBRE last year stated that slowing sales and over-saturation in the mainland “have prompted retailers to consolidate their existing store networks and slow their rate of entry into new markets focusing on operational efficiency.” This includes not only relocation of stores, but revamping design and adding lifestyle elements such as cafes, art exhibitions, and pop-ups.

  • Jack Ma versus George Soros: who do you trust on China’s economy

    Jack Ma versus George Soros: who do you trust on China’s economy

    No one really trusts China’s official statistics. In the past ten days since the government announced the economy grew at the much-slower-but-still-solid pace of 6.9 per cent last year, a roll-up of economists and money managers have been putting forward their own best estimates for growth.

    Billionaire investor George Soros raised Beijing’s ire by claiming last week the current growth rate was probably around half the official figure at 3.5 per cent and said a hard landing was “unavoidable.”

    Other economists say growth is somewhere between four and six per cent, which leaves investors looking around for alternative measures of the economy.

    When it comes to a gauge for consumption, it’s hard to go past the profit result for China’s biggest e-commerce company, Alibaba, which now accounts for about 80 per cent of the online retail market.

    And there was much to cheer about in Alibaba’s better-than-expected third-quarter results, released on Thursday in the United States.

    Revenue jumped 32 per cent to 34.5 billion yuan ($7.4 billion) compared to the same period a year earlier, while profit more than doubled to 12.5 billion yuan, largely driven by consumers shopping on their mobile devices.

    Despite the strong result, there were some signs of China’s slowdown.

    The value of overall product sold across Alibaba’s retail platforms – the so-called gross merchandise revenue (GMV) — rose 23 per cent to 964 billion yuan, much slower than this time last year.

    Still, it’s a strong result and the smaller increase in GMV might be partly due to the company’s efforts to crackdown on the sale of counterfeit goods on its platforms.

    Alibaba said China’s growing middle-class was driving sales especially to younger people, who are more likely than their parents and grandparents to spend money rather than save.

    Alibaba’s founder Jack Ma set up the company in his Hangzhou apartment, an hour’s train trip from Shanghai, in 1999. At the time, it was an online listings service, connecting Chinese manufacturers to potential customers. But four years later he launched Taobao, revolutionising China’s online retail market. He followed Taobao with Tmall, which allows global brands such as Nike and Gap to sell direct to consumers and the company listed on the New York Stock Exchange in 2014.

    More than 400 million people are now active buyers on Alibaba’s retail marketplaces.

    The company is also investing in financial services, video and media content and cloud-computing to diversify its earnings.

    Investors had been betting against Alibaba this year because of China’s economic woes, pushing its shares down 14 per cent before the result came out. Alibaba fell 3.8 per cent to $US66.92 in New York on Thursday.

  • Indonesia’s Low Internet Penetration Rate Curbs Economic Growth

    Indonesia’s Low Internet Penetration Rate Curbs Economic Growth

    Each day the world’s Internet users watch an average of 8.8 billion YouTube videos, share 186 million photos on Instagram, make 152 million Skype calls, purchase 36 million products through Amazon, send 207 billion emails, post 803 million Tweets, and make 4.2 billion searches on Google.

    Although digital technologies have spread rapidly across the globe, the World Bank says digital dividends have lagged behind for part of the global population. The Washington-based financial institution defines digital dividends as “the broader development benefits from using these technologies”. For example, the business community can use digital technologies to expand their business, people can use these technologies to find jobs and the government can use it to enhance services. In other words, digital technologies support financial inclusion, job creation, and overall economic growth.

    However, the fruits of these dividends are unevenly distributed. One of the key solutions in order to let all people enjoy the benefit of digital technologies is to enhance Internet connectivity. But the World Bank also states that well developed Internet access alone is not enough. “Countries also need to work on the ‘analog complements’ by strengthening regulations that ensure competition among businesses, by adapting workers’ skills to the demands of the new economy, and by ensuring that institutions are accountable.

    In essence, two factors are the cause that digital dividends cannot be enjoyed by part of the world population. Firstly, almost 60 percent of the world population still lacks Internet access, hence cannot participate in the digital economy in a meaningful way. Secondly, some of the perceived benefits of digital technologies are offset by emerging risks.

    The first factor should be combated by governments by encouraging (affordable) access to the Internet (and other digital technologies) for its citizens, while creating conducive regulations for the Internet and mobile operators.

    After India and China, Indonesia has the highest amount of people who are not connected to the Internet. The World Bank report stated that the Indonesian government is on the right track to address these aforementioned issues. For example, the Indonesian government is currently finalizing an e-commerce road-map that aims to improve and develop the country’s e-commerce industry. Previously, the Indonesian government said it may allow foreign investors to own a 100 percent stake in Indonesian e-commerce companies in this road-map.

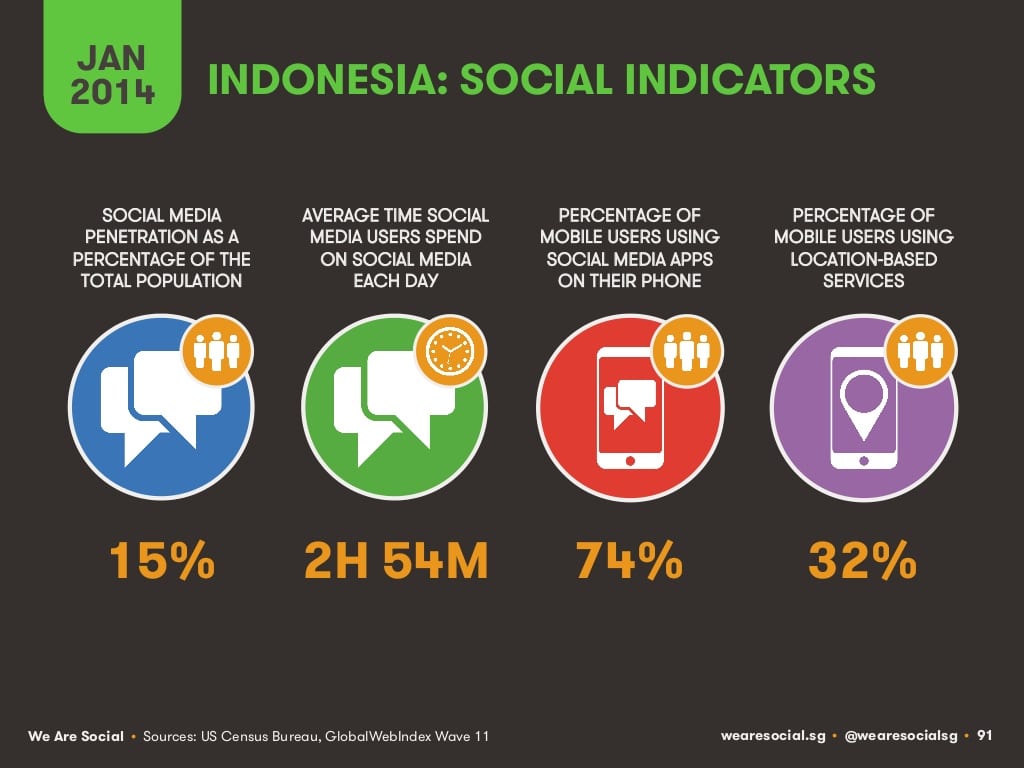
    According to the Association of Internet Service Providers in Indonesia (APJII), Indonesia had around 88.1 million Internet users in 2014, up 22 percent (y/y) from 71.9 million in the preceding year. Given that the total population of Indonesia numbers more than 250 million individuals, Indonesia’s Internet penetration ratio stood at around 35 percent in 2014. This low rate implies there is still ample room for growth in the online business industry.

  • Printed Media Enters Twilight Period

    Printed Media Enters Twilight Period

    In line with the increasing popularity and knowledge of internet in the society, many online media have successfully attract readers and printed media advertisers. “This is what we call the twilight of print media,” said Communications and Informatics Minister Rudiantara on Tuesday, January 26, 2016.

    According to Rudiantara, the progress of online media can be seen from the constantly improving financial performance of the companies. “Just look at their balance sheets in the stock market,” said Rudiantara.

    Rudiantara added that compared to printed media, online media can be considered to have the upper hand in presenting information. By accessing a digital news website, consumers can read texts, see pictures and watch videos almost at the same time. In addition, readers who wish to interact with writers can just leave a comment and immediately receive responses.

    Such advantages also attract advertisers. Rudiantara predicted that more advertisers will prefer to advertise through online media. “For advertisers, online media offer advantages, ranging from placement to payment,” Rudiantara said.Ari Fadyl, head of transformation and innovation at AXA Indonesia, also said that it is easier to attract consumers through online media. Only by clicking links, prospective consumers can enter a company’s homepage or mobile app. “This is important because to buy an insurance, for example, people need to be assured with explanations or ‘experiences’,” said Ari.

    Ari explained that ‘experiences’ can be in the forms of online test to identify a children’s talent in relation to finding the right school, which will eventually attract parents to apply for an educational insurance. Such method, Ari claimed, is proven to be effective in gathering customers. “We just started using digital platform two years ago, and now we have around eight million customers from [online platform],” Ari said

  • China’s overseas luxury spending shifting to the web

    China’s overseas luxury spending shifting to the web

    Changes in spending on luxury goods by mainland Chinese consumers might dictate a revamp in how luxury retailers do business in that market. More shoppers than ever are buying overseas because items are more expensive in China, according to Bain’s 2015 China Luxury Market Study.

    Overall luxury spending by Chinese consumers in 2015 fell 2% to 113 billion yuan ($17.2 billion), driven by falling sales of watches, men’s wear and leather goods. Overseas luxury purchases grew 10%, especially in Japan, where their spending increased more than 200%, but also in South Korea, Europe and Australia, thanks to favorable exchange rates and competitive pricing. Meanwhile, luxury spending of mainland Chinese in Hong Kong and Macau fell 25%.

    Because of crackdowns by the Chinese government designed to tighten imports and bring spending back, including new rules discouraging the use of personal shoppers, or “Daigou” who make duty-free purchases overseas for their Chinese customers, more Chinese are buying their luxury goods via websites and mobile sites instead. “Buying overseas has been a trend for years, but destinations have changed,” Bain partner and report author Bruno Lannes said in a statement.

    In 2014 and 2015, brands with strong fashion heritage and track record of original designs did better in the Chinese market. And, while transitions in China’s economy are causing some turmoil in markets and worry among investors, the general environment for luxury retailers will remain more or less the same—though the still-rising middle class will continue to become more sophisticated about luxury brands, Bain says. Global pricing will become more important, the report notes.

    Luxury brands should strengthen digital platform building and digital content creation, with an emphasis on localization to reflect local market preferences, Bain says. Nearly 80% of survey respondents said they get their luxury brand information from the internet or apps, and 60% said social media sites Weibo and WeChat are their source for that information. That’s why brands on average spend 35%—and growing—of their marketing budget on digital.

    Luxury brands must also emphasize youth and fashion to turn the heads of the next generation of luxury customers in China, Bain said. This year and forward, there will be even more of a focus on “exclusivity” in product design and store footprint, according to the report.

    Some changes are already underway. Luxury retailers in China, for example, have begun streamlining their approach to brick-and-mortar in the country, with a greater focus on fewer, larger and better located stores. Many brands have realized the need to regain a sense of exclusivity, which was marred by too many stores, according to the report.

    “Despite persistent macro, economic and industry challenges in China, all hope is not lost for luxury brands,” said Lannes. “There are plenty of growth opportunities for those with more exclusive and fashion collections, digital platform engagement and digital content creation, as well as with pricing that encourages Chinese consumers to spend locally.”

  • Technology bringing more personalised experience to shopping

    Technology bringing more personalised experience to shopping

    The launch of the second plan aims to build on the same momentum – helping retailers with manpower-saving technologies. But beyond resolving the industry’s manpower crunch, technology is also changing the way retailers sell.

    Stock-taking is the bane of retailers, as it is typically an arduous task that takes hours. But with radio frequency identification (RFID), the same job can now be done in under an hour.

    Home-grown retailer Decks has managed to save more than 2,300 man-hours a month, since it started using the technology for inventory management.

    “In the future we know that the manpower issue will become more serious than it is now. In order to be more attractive to employ better workers, I think we should engage all this technology to help to lighten the workload of every employee,” said Mr Kelvyn Chee, managing director of Decks.

    RFID is just one of the many technologies available to the retail sector, even though they may not be widely adopted.

    PLAYING CATCH-UP

    Industry players and market researchers have said that retailers in Singapore are behind their international peers in technology adoption. Besides cost, another reason is that they have not seen the need to innovate until now, with the e-commerce sector nipping at their heels.

    “The development of e-commerce in Singapore has been at the lower level than many other parts of the world. But that’s changing very dramatically. I think that’s what’s sort of giving rise to some of this tension where the retailers have not needed to change quite as quickly, when e-commerce was falling behind, but it is really taking up,” said PwC Singapore’s digital business leader Greg Unsworth.

    The innovation arm of the Singapore Institute of Retail Studies is helping retailers to play catch-up. It showcases and advises retailers on the various technologies available.

    “Companies want to embark on data analytics because these are things that will help the business going forward,” said Mr James Fong, deputy manager of programme development at Singapore Institute of Retail Studies. “With knowledge, it does help the business to be more agile, it helps the business to be more able to predict the trend and so forth. So data analytics, having said that, is one of the new areas will take some time for this to evolve.”

    Pushing the frontier of data mining is the use of video analytics, a move that Decks has embarked on. The technology solutions company behind the in-store CCTV camera is able to interpret the images and provide critical business intelligence.

    “Examples of what we can provide them in terms of data and insights would be how many people come to the store, when they come to the store what do they do, how they spend their time going through the store,” explained Mr Tan Liong Hai, sales director of Kai Square.

    With this information, Decks has been able to come up with more targeted marketing campaigns, which it says have helped to boost sales by 10 per cent.

    The retailer continues to look at new innovations, for example, having a smart dressing room to enhance in-store experience, or incorporating the Automated Retrieval and Storage System to streamline backend operations.

    Said Mr Chee: “Everybody thinks that all these technology implemented is to replace the human beings but I think otherwise. We just want the staff or the sales assistant to focus more on customer rather than spend time on unnecessary tasks. So we want to make the shopping experience more personalised, more service-oriented.”

    Mr Unsworth added that technology could result in a convergence of physical and online retailers.

    He explained: “I think retail at the moment – you sort of have the established large retailers, who tend to have a mainly physical presence, you have e-commerce companies who tend to have an online presence. I think everything is going to merge in the middle. So you have this sort of convergence of the two coming together where increasingly, it will be a multi-platform approach that consumers are looking for and that retailers will have to provide.”

    While some retailers in Singapore on both sides of the spectrum have started moving in that direction, experts have said they are still in the early stages.

  • Countries must improve ICT sectors

    Countries must improve ICT sectors

    Countries must continue to invest and pursue reforms in information and communication technology (ICT) to serve the nearly 60 percent of the world’s population who remain excluded from the digital economy, a new World Bank report said.

    In its “World Development Report 2016: Digital Dividends” report, the Washington-based lender noted that the internet, mobile phones and other digital technologies were spreading rapidly.

    “Digital technologies are transforming the worlds of business, work, and government,” said Jim Yong Kim, president of the World Bank Group.

    The anticipated digital dividends of higher growth, more jobs, and better public services, however, have fallen short of expectations, the World Bank said.

    To deliver fully on the development promise, it said countries must pursue “analog complements” to digital investments.

    This means regulations must be strengthened to ensure competition among business, adapting workers’ skills to the demands of the new economy, and fostering accountable institutions.

    Digital development strategies need to be much broader than ICT strategies, it added.
    To reap the greatest benefits, countries must create the right environment for technology, with regulations that facilitate competition and market entry, skills that enable workers to leverage the digital economy and institutions that are accountable to people.

    It noted that in the Philippines, business process outsourcing has few entry barriers and that firms use digital technology intensively, which is not the case for the retail sector.

    “The Philippine retail sector has substantial restrictions to domestic and foreign entry and is dominated by a few incumbent firms, while few firms use ICTs,” the World Bank said.

    Foreign retailers that aim to establish a commercial presence need to pass prequalification procedures, meet minimum capital requirements, deal with limitations to foreign equity participation, and have the majority of their boards comprised by Filipinos, it stressed.
    “Only about 20 percent of retail firms (with at least five employees) sell online in the Philippines,” it added.

    In contrast, the Philippine outsourcing sector is characterized by high entry rates and few regulatory barriers to competition.

    “It is intensive in ICT-related services such as software development, animation, contact centers and transcription. These ICT-specific services experienced high productivity growth in recent years and provided about 1.2 million jobs in 2015,” it said.

    Investing in basic infrastructure, reducing the cost of doing business, lower trade barriers, facilitating the entry of start-ups, strengthening competition authorities and facilitating competition across digital platforms were some of the measures suggested in the World Development Report.

    Digital technologies can transform economies, societies and public institutions, but changes are neither assured nor automatic, the report stressed.

    “Countries that are investing in both digital technology and its analog complements will reap significant dividends, while others are likely to fall behind. Technology without a strong foundation risks creating divergent economic fortunes, higher inequality and an intrusive state,” the World Bank said.

  • Singapore male youth burn more money shopping online than women

    Singapore male youth burn more money shopping online than women

    About 5 in 10 say they spend more than $100/month. Singapore male youth spend more than women on online purchases, according to Singapore Polytechnic’s survey of 816 youth aged 15 to 35. About 5 in 10 (50.6%) males say they spend more than $100 per month on online purchases, compared to about 4 in 10 (41.3%) women.

    On the other hand, the survey revealed that women shop online more often. About 2 in 10 (20.4%) female respondents browsed for products and services online daily, compared to 14.5% of male respondents.

    More males (29%) also purchase from stores that stock limited edition items, compared to 32.5% of women. Meanwhile, female respondents (47.6%) purchase from online stores they liked or are subscribed to on social media, compared to 32.5% of male respondents.

    For male youth, the most popular purchase categories include apparel, technology, and movies. Meanwhile, young women’s top purchase categories include apparel, beauty, and travel.

    The survey also showed that Singapore youth prefer to keep their online shopping habits private. Almost 6 in 10 (59.5%) indicated that they shop online to purchase items without their friends or family knowing, while 57.9% do so to keep their identity private. Also, more male respondents (61.8%) agreed that they shop online as it gives them privacy, compared to women (54.1%).

    It was also revealed that young shoppers were more receptive to special online deals, peer influence and social media. Celebrity endorsements appeared to be the least effective sales strategy, as only 11.4% of respondents purchased from stores endorsed by their favorite celebrity.

  • What to expect in 2016 as Singapore economy hits slowest growth since 2009

    What to expect in 2016 as Singapore economy hits slowest growth since 2009

    GDP is seen to likely remain stuck in the 2-3% yoy range. The 4Q15 GDP growth flash estimate was a breathtaking +2.0% yoy (+5.7% qoq saar), which beat market consensus forecast marked a sweet end to 2015. OCBC Bank notes that the surprise factor came from construction which doubled to 2.2% yoy (+7.0% qoq saar) in its strongest showing since 2Q15 due to public sector construction activities, and supported by the still resilient services sector which expanded 3.2% yoy (+6.5% qoq saar) in 4Q15 on the back of wholesale & retail trade and finance & insurance sectors. Manufacturing remained the main drag, contracting for the 5th straight quarter and actually deteriorating further from the 5.9% decline in 3Q15 to -6.0% in 4Q15.

    But 2015 GDP growth is still the lowest since 2009’s -0.6% performance.

    The 4Q2015 GDP figure brought the full year growth to 2.1% which is close to the official growth forecast of “close to 2 percent” but is nevertheless a moderation from the 2.9% growth registered in 2014.

    Here’s what analysts had to say:

    Selina Ling, analyst, OCBC Treasury Research

    Notably, this data set reinforced that growth has likely stabilized since 3Q15 after avoiding a technical recession earlier in the year. The 2015 outperformer remained services which accelerated from 3.2% growth in 2014 to 3.6% last year, followed by construction at 1.1% (2014: 3.0%), whereas the 4.8% drop in manufacturing was the worst since 2001 (-11.6%).

    Looking ahead, 2016 growth will likely remain stuck in the 2-3% yoy range.

    Headline GDP growth may not deviate from the 2+% yoy range in the near-term. We expect that manufacturing may continue to be in the doldrums and shrink 0.2% yoy in 1Q16 and constrain overall GDP growth to 2.4% yoy. Note the latest SME business surveys suggest greater caution for the first half of this year. Our full-year 2016 GDP growth forecast remains at 2-3%, which is at the upper end of the official 1-3% forecast. The downside risks remain the ongoing deceleration and policy risks in China, as well as the sustained US monetary policy normalization (given market perception continues to differ significantly from the median dots graph). It is interesting that the two-track growth trajectory in China, with the service PMI outperforming the manufacturing PMI, heralds a trend towards servitization that could be also apparent for the rest of the region.

    Inflation could remain subdued in 2016, with core inflation picking up slightly. Headline CPI prints may stay deflationary in 1H16 but edge back to positive territory before the year is out. That said, headline CPI inflation may remain flat in 2016 as asset price deflation in housing (especially with private residential prices having fallen for nine straight quarters and official rhetoric hinting at no lifting of cooling measures in the near-term) and private road transport sustains, and the pass-through from the tight labour market into the broader cost environment has been fairly limited. Given the benign crude oil price environment, the CPI basket components that would contribute positively to inflation are likely to be food (due to La Nina), healthcare and education costs. At this juncture, we do not see any game-changers that warrant a third monetary policy easing this year as the 4Q15 flash GDP growth estimate is “water under the bridge” so to speak.

    Policy settings will remain within comfort zones for now. The 3-month SIBOR has been relatively stable post-Oct15 MPS, but the SOR have tracked higher as the US FOMC initiated lift-off with a 25bp rate hike to 0.5% in mid-Dec15. The spread between the 3-month SOR-SIBOR has widened to more than 50bps, which is the largest since March 2009, but we anticipate that the gap will narrow to around 30bps as the SIBOR plays catch-up to SOR. Our end-2016 forecasts for 3-month SIBOR and SOR are 2.03% and 2.05% respectively, assuming that the FOMC continues to hike at a benign pace of 100bps next year.

    Francis Tan, analyst, UOB

    The main support in 4Q came from the robust services sector which grew 3.2% y/y, as the wholesale & retail trade and finance & insurance sectors maintained healthy growth paths. The construction sector also expanded 2.2% y/y, compared to the 1.1% y/y growth in 3Q.

    Singapore’s manufacturing engine remained weak as the sector contracted for the fifth consecutive quarter to register a decline of 6.0% y/y due to the decline in output from the electronics, transport engineering and precision engineering clusters.

    Although Singapore’s manufacturing sector is not out of the doldrums yet, we remain optimistic that there could be some pickup in manufacturing growth in2016 and we are projecting the manufacturing sector to grow by a modest 2.5%, compared to the 4.8% decline in 2015.

    The services sector will continue to be a bright spot, although growth for 2016 may slow to 2.7%, from 3.6% in 2015. This is due to the higher base effects for the wholesale & retail trade to hurdle past; While the finance & insurance sector may grow at a slower pace, resulting from the US interest rate normalization that could impact on the overall loans demand in 2016.

    With this, we maintain our forecast for Singapore’s 2016 GDP to grow 2.7%.

    Regarding monetary policy, we hold to our view that the Monetary Authority of Singapore (MAS) will likely leave the current policy of the “modest and gradual appreciation” of the SGD NEER unchanged at our estimated 0.5% pa rate.

    The monetary policy divergence between the US and Singapore will likely see the USD/SGD continue on a weaker path to reach 1.46/USD by the middle of this year. However, the increased trade and investment flows from a stronger US economy will probably see a direction reversal by 2H 2016, where we forecast the USD/SGD to end 2016 at 1.42/USD.

  • How online and offline will dominate retail in Asia in 2016

    How online and offline will dominate retail in Asia in 2016

    Innovations in technology are predicted to make progressive strides related to online and offline commerce, thus improving the retail experience significantly in 2016.

    With new developments like Google’s Physical Web and Eddystone, we’ve started to get a glimpse of what the future might look like in a perfect online to offline marketing world. But is this futuristic new line of digital marketing really so far away, or are we on the cusp of a new reality?

    Here are major trends that I anticipate will lead to progressive shifts in how online retail addressed this year in the Asia Pacific region:

    1. Full integration of online and offline

    In my last column, I talked about Google’s Physical Web and Eddystone. Technologies like these will enable users and shoppers to communicate via their mobile devices with physical objects, sending their real-time location and behavior to marketers who can now identify them, in exchange receiving more personalized and customized experiences when visiting offline shops.

    With these new innovations, the traditional challenges of user anonymity are being resolved. Therefore, we can expect to start seeing user retail experiences that truly bridge the gap between offline and online (O2O) by the mid-2016.

    2. Deep customer insights meet highly targeted displays

    How to drive traffic the most effective and efficient traffic to your website is an ongoing challenge for marketers. By “most effective traffic,” I mean traffic that comes from the cheapest source, and “efficient traffic” refers to the frequency at which your traffic will eventually convert (ideally instantaneously).

    In the past, one solution was to use a large proportion of marketing budgets to acquire new customers using Google SEM. However, this has proven to be very expensive and less efficient in driving qualitative traffic to a website over time. It is also only focused on capturing demand.

    This has driven marketers and budgets to Facebook, where interest-based targeting could be used to find new users. And what happens when everyone does the same thing? Eventually the channel becomes more expensive and less efficient.

    Publishers can now address this challenge via the use of an Audiences feature. Both Google and Facebook now have Audiences as a core function in their display offerings, allowing advertisers to target more accurately when uploading emails or finding specific audience demographics. Such technology enables advertisers to deliver the right ads, to the right people, across devices.

    Many platforms also use sophisticated look-alike modeling, which lets advertisers target similar profiles of those already targeted, specifically by email. There are also retargeting technologies that can find people that have browsed a particular website, and present them with ads or even specific products from that site.

    To complete the value proposition, marketers are provided with reporting that highlights conversions and contributions to online sales. But here’s a little secret: revenue from abandoned carts contribute significantly to these sales numbers.

    How many times have you been presented with display ads for products that you’ve already purchased? Well, here is how this happens; let’s say someone has a basket full of goodies, but bounces over to a different site momentarily, before coming back to their basket and completing their purchase. This will cause a view-through conversion, which means that revenue will be attributed to the retargeting campaign, even if the purchase occurs without clicking on the display ad. Retargeting companies focused on pricing for cost per click (CPC) or cost per action (CPA) models make a lot of money this way.

    counting money youtube screenshot

    Going back to Google and Facebook, the ability to target someone specifically is great, however it is important to know the context in which a user/shopper is being targeted. How do we link both audiences and standard retargeting to the purchase cycle as well as to the interaction a user has with your brand?

    In 2016, we will start to see the emergence of more quality identification technology that is able to work across mobile devices and computers. Marketers will be able to find users and send contextual display ads that feature the right product or coupon, on the right device, with incentives based upon insight regarding what really makes the user tick. This delivery will also be matched with the right objective based on where the customer is in the lifecycle.

    In the beginning, identification will probably range between 30 and 50 percent of the users, but I predict we’ll see these numbers increase as the technology evolves. Though these advancements are on the horizon, this level of sophistication will only occur once matching email addresses to third-party cookies becomes feasible. More importantly, this cannot happen unless multifaceted user insights are aligned with intelligent advertising platforms.

    3. AI driven marketing

    Artificial intelligence will be one of the hottest topics in the tech industry in 2016. Just recently, Google launched TensorFlow, a very powerful artificial intelligence and machine-learning open source software.

    Added to this is a recent announcement to commit $1 billion to researching artificial intelligence from a group of Silicon Valley entrepreneurs, which includes Elon Musk, chief executive officer (CEO) of Tesla.

    How does all this come into play for the marketing landscape?

    Marketers today are very operative. First, they think about an idea or a campaign, then they automate it with either display ads, email campaigns, push messaging, social releases, and so on. After that, they test against it and continue to optimize. They go through this process again and again and again, and do so because of the vast amount of variables and data sets that need to be taken into account to get the best results. With this process, solutions rooted in artificial intelligence will change the lives of the marketers and their audiences, helping each make more informed decisions.

    Think about the type of software needed to create the customer journey and then execute after uploading all the necessary data and required content; this year, marketers can expect some of the functionality affiliated with this process to be automated. Expect this progress to in ways that will cover most of the operational decisions marketers make today, and for this evolution to continue over the next three to four years.

    4. Messaging dominates media activity

    Over the past five years, messaging has become one of the fastest growing online channels, according to Activate’s Tech and Media Outlook 2016. Messaging has developed more quickly than social media, coming only in second to the time spent online by users globally. By 2018, messaging is expected to grow by an additional 1.1 billion users.

    The global messaging space continues to be dominated by Facebook Messenger and WhatsApp. In the Asia Pacific region, local players include China’s WeChat, Japan’s Line, and Korea’s KakaoTalk.

    Messaging services are now accessible by third-parties, thus resulting in an explosion in of real-time offerings for services, including booking taxis, making payments for practical necessities like utilities bills, music and television entertainment, games, stickers, e-commerce capabilities, video, and live voice calls. The messaging app has transformed into a hub of communication and consumption of services for users, creating monetization possibilities for both for media owners and third-party developers.

    So, what can digital marketers ultimately expect for 2016?

    In conclusion, the integration of online and offline real-time marketing opportunities isn’t something we can hope to see somewhere in the future, as what was once a fantasy is finally materializing into reality. Now that these technological innovations have made linking these contrasting realms much easier, wise marketers and retailers will take advantage of this progress immediately….will you?

  • Why More Retailers Could Default in 2016

    Why More Retailers Could Default in 2016

    Last year was grim for retailers. This year could be even worse. Despite a late surge in holiday sales, companies like J. Crew Group Inc. and 99 Cents Only Stores are struggling under debt they took on in leveraged buyouts years ago. Their bond prices have plummeted — in some cases to as little as 25 cents on the dollar — as investors brace for possible defaults.

    The industry has been limping along for a while now due to a variety of forces. Spending has migrated to the Internet, lenders have turned wary and the debt burdens of pre-crisis buyouts will make it tough to revive struggling merchants. Eleven retailers defaulted last year through Dec. 14, the highest annual tally since 2009, according to Standard & Poor’s data. And the near future doesn’t look much brighter.

    “We expect more retail defaults in 2016 than 2015 and 2014,” said Robert Schulz, an S&P credit analyst.

    The credit market is echoing that sentiment. Bonds of indebted retailers dropped further last year in anticipation that some will need to restructure.

    This wave of distress is different from the tough times of the Great Recession, said Patrick Dalton, chief executive officer of Gordon Brothers Finance Co., an asset-based lender that works with retailers. Now, “it’s an industry issue, not an economy issue,” he said. Shoppers are seeking value and turning away from pricey logos, which is hurting the teen-clothing category in particular. “What looks the same but costs three times less is where everyone’s going,” Dalton said.

    In general, shoppers are spending less on stuff and more on experiences such as going out to eat. They’re also saving more. And retailers that once reigned in America’s shopping malls are losing customers to online rivals like Amazon.com Inc.

    “Amazon is crushing everybody,” Dalton said.

    Buyout Burden

    Bond prices of the most distressed companies reflect those problems. J. Crew’s bonds lost 7.4 percent in December, dropping to a record low of 25 cents on the dollar on Dec. 22, reflecting creditors’ lack of confidence that the retailer will be able to shoulder $2.1 billion of debt from a 2011 leveraged buyout by TPG Capital Management and Leonard Green & Partners.

    Bon-Ton Stores Inc.’s 8 percent notes last traded at 33.4 cents on the dollar on Dec. 23, according to Trace, the bond-price reporting system of the Financial Industry Regulatory Authority.

    Margot Fooshee, a J. Crew spokeswoman, declined to comment. Angela Thurstan at 99 Cents Only and Christine Hojnacki at Bon-Ton didn’t respond to requests for comment.

    Restructuring advisers have already started circulating names of retailers proposing various debt-renegotiation plans as bond prices continue to drop.

    “It’s going to be a busy year of restructuring for retailers,” said Steven Ruggiero, a credit analyst focusing on retail at RW Pressprich & Co. in New York. “Hedge funds and private-equity investors that were taking a pause at the end of the year waiting to see how December sales would pan out and how redemption was for their funds are now ready to pounce.”

    Things could have been a lot worse. Sales during November and December rose 3.4 percent, according to research and consulting firm Customer Growth Partners. An uptick in shopping during the week between Christmas and New Year’s helped mitigate what Craig Johnson, the research firm’s president, called a terrible year for margins, as retailers jockeyed to win over lukewarm shoppers.

    The days when retailers could load up on debt and hope to sell their way out of it appear to be over. In the meantime, obligations heaped on during pre-2008 leveraged buyouts are coming due.

    Refinancing Debt

    Sports Authority Inc., for example, has a $300 million term loan due in May 2017, but its private-equity owner Leonard Green & Partners is already under pressure to refinance it while there’s still more than a year to maturity. Once an obligation passes that threshold, it becomes current, which is considered more difficult to deal with in a restructuring.

    Although the sportswear retailer received a $95 million infusion in late 2015 to shore up vendor confidence, addressing that debt appears to be a challenge. Kellie Kerwin, a spokeswoman for Sports Authority at ICR, didn’t comment.

    Even healthy retailers are posting disappointing results. Bed Bath & Beyond Inc. said third-quarter profit and comparable-store sales will be less than forecast. Department stores including Macy’s Inc. and Nordstrom Inc. have cut their annual forecasts. Some of that is due to record-high temperatures, which have produced a glut of coats, sweaters and other seasonal goods.

    “The merchants that have been lagging don’t have the luxury to lag anymore,” said Jonathan Eyl, a consumer analyst at Nasdaq Advisory Services in New York.