Blog

  • Old Navy Indonesia makes debut

    Old Navy Indonesia makes debut

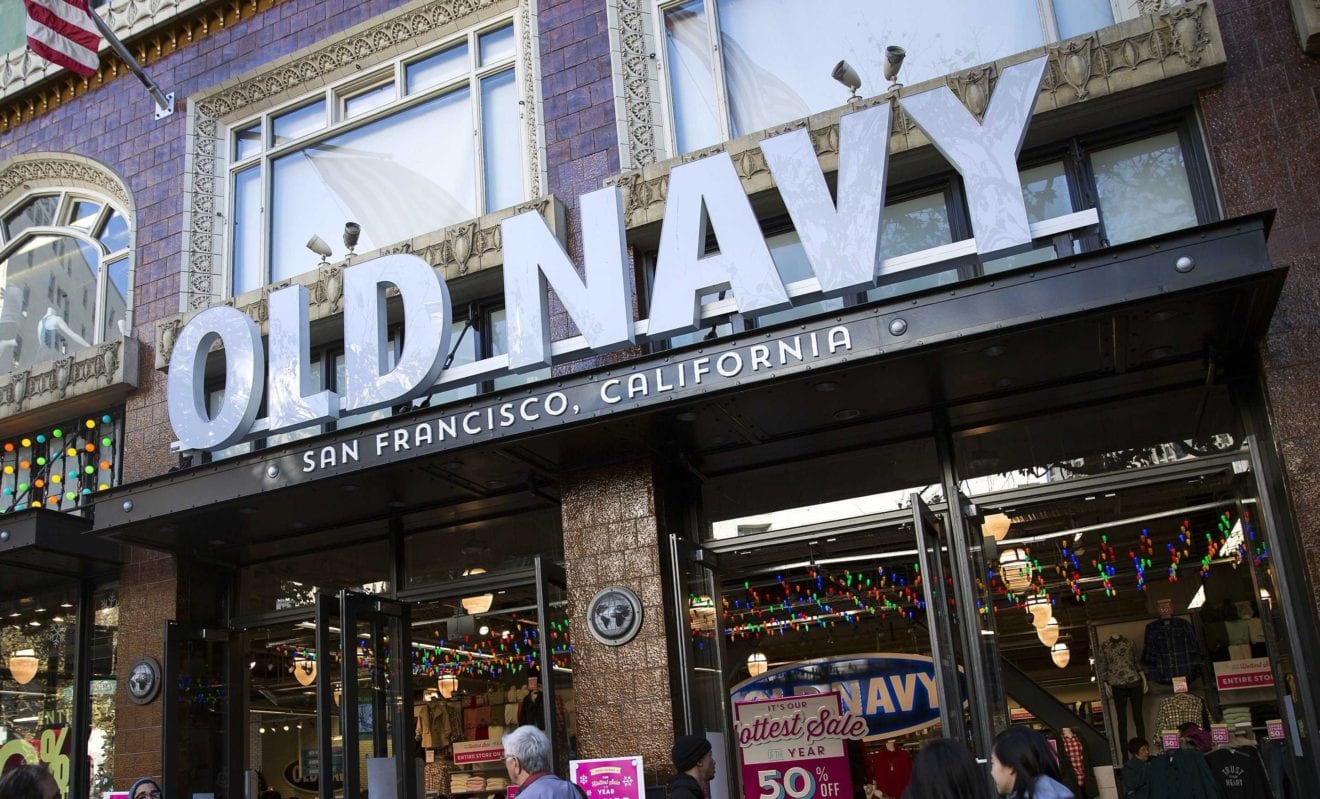
    American apparel and accessories brand Old Navy Indonesia has opened its first retail outlet at the Central Park Mall in west Jakarta.

    Offering American-style basic clothing items, Old Navy is part of the Gap portfolio alongside Athleta, Banana Republic and Intermix. The brand has more than 700 stores and shops-in-shop in 11 countries, including the Philippines.

    Old Navy Central Park mall Indonesia

    “Indonesian customers understand the international retail scene very well,” says Old Navy senior director of franchise buying Michele Chinn Fahey. “There’s a really a high awareness of international retail brands and a growing demand for American fashion.”

    For its Indonesian debut, Old Navy is collaborating with Armaan Retail Indonesia.

    Old Navy Central Park mall Indonesia 1

    “With 250 million people living across 15,000 islands, and three different time zones, Indonesia has huge potential,” says Armaan Retail CEO Benjamin Handradjasa.

    Old Navy’s store covers 1200 sqm and offers clothing and accessories for men, women, children and babies. There is also a special section for maternity clothes.

    Among the store’s first customers on its opening day was Indonesian actress and singer Ana Octarina.

  • Sevenfold growth forecast for Indian eCommerce

    Sevenfold growth forecast for Indian eCommerce

    The Indian eCommerce industry is expected to burgeon in the next four years, according to a report by the Confederation of Indian Industry (CII) and Deloitte Touche Tohmatsu India.

    While the business to business (B2B) segment is expected to more than double from US$300 billion last year to $700 billion in 2020, the business to consumer (B2C) segment will grow more than seven times from $13.6 billion to $101.9 billion, says the report.

    It will be supported by a spurt in number of online shoppers, from 20 million in 2013 to 220 million in 2020, as well as a three-fold increase in average spending by online shoppers, from $147 in 2013 to $464.

    However, there is a price: combined losses for eCommerce companies such as Flipkart, Snapdeal (Jasper Infotech) and PayTM (One97 Communications) last year stood at $557 million, says the report. It notes that most B2C eCommerce companies globally, even after five to 20 years in business, have low profitability.

    “This trend, however, does not hold true for B2B eCommerce companies, which are profitable with greater GMV values.” The report attributes this to lack of heavy discounting, greater emphasis on quality rather than price, and higher volumes of purchases.

    A spurt in internet penetration, especially via mobile devices, is expected to propel eCommerce sales in India, with the report saying the proportion of 3G users among internet users has improved substantially since 2013, when about 28 per cent of the 150 million mobile internet users in India had 3G connections. This year, about 59 per cent of the estimated 371 million mobile internet users in India are expected to have 3G connections.

    According to the report, India had the highest share of mobile based eCommerce sales (41 per cent), ahead of China (37 per cent) and the US (15 per cent). The report also estimates a significant growth in the digital payments segment, from $20 billion in 2014 to $115 billion in 2018, though 60 per cent of transactions in India currently use cash on delivery.

    While payments in instalments and digital wallets account for less than 2 per cent of overall transactions, they will grow faster than plastic money, says the report. eCommerce firms such as Flipkart, Snapdeal and Amazon India are seeking to strengthen their payment offerings.

    Snapdeal bought utility payment service provider FreeCharge for $400 million last year, in the biggest domestic consumer internet deal. Amazon acquired Emvantage Payments for an undisclosed amount in February, and market leader Flipkart acquired payment services start-up FX Mart, which holds a prepaid wallet licence, in September last year. In March, the company launched mobile wallet Flipkart Money, 18 months after shutting down its payment gateway PayZippy.

  • Siam Makro plans $258m expansion

    Siam Makro plans $258m expansion

    Thai cash-and-carry chain Siam Makro plans to invest up to 9 billion baht ($258 million) in opening stores this year in Thailand and overseas.

    Its parent company, CP All, which through its ownership of 7-Eleven Thailand is the country’s largest convenience store operator, plans to sell some of its 97 per cent stake in Siam Makro. It has appointed Siam Commercial Bank as financial advisor for a public share sale.

    It is reported CP All aims to keep a stake of more than 50 per cent in Siam Makro, whose main customers are hotels, restaurants and small convenience stores.

    Siam Makro plans to spend 6 billion baht to open 20 stores in Thailand this year, plus 3 billion baht to expand elsewhere in Southeast Asia. CFO Saowaluck Thitaphant says possible markets include Cambodia, Laos and Vietnam.

    She says the company is also interested in India, and plans a store for Myanmar once the political climate is clearer following elections.

    Siam Makro expects revenue to rise by less than 10 per cent this year.

    CP All, controlled by billionaire Dhanin Chearavanont’s Charoen Pokphand Group, says it will use proceeds of the share sale to repay debt.

  • Does Your Brand Need a Store in China to Succeed?

    Does Your Brand Need a Store in China to Succeed?

    As brands speculate about continued economic buoyancy in China, the necessity of having physical stores has come under increasing scrutiny. The unrelenting enthusiasm for e-commerce shown by Chinese consumers has also given cause for questioning the relevance of physical retail.

    Luxury and fashion brands have scaled back on their original optimistic plans to store expansion in China. Most notably, Louis Vuitton announced the closure of several Chinese stores last November. Also Walmart, has this week, launched a major brand repositioning to offer e-commerce solutions to Chinese consumers.

    Pessimism about store space is becoming endemic. Dangdang.com, a local online bookseller similar to Amazon, has launched an audacious plan to create actual bookstores based on the idea they will receive free-rent in increasingly vacant shopping malls in big cities.

    When a store, is not just a store

    Looking at the importance of a store presence in China requires a specific cultural lens. A key starting point for most, if not all, foreign brands is that they are not inter-generational. That is, the reputation and trust of the brand has not been passed down through family legend. Instead, brands are initiating relationships from scratch with a fresh generation of consumers.

    Taking the case of luxury, consumers have experienced the brand as a personal form of development. A key moment of truth in their relationship with brands is formed through store experiences –the physical inspection and feeling of products.

    When interviewing Chinese consumers, the key difference that strikes me is how emotional the store experience and service are in the stories they tell about their favourite brands. Often, they become aware of a brand through peer recommendation, but their loyalty and ultimate advocacy is created through their retail experience.

    Forgoing or not maintaining a retail presence is like introducing a ‘circuit breaker’ at the most crucial stage of brand adoption. Stores, irrespective of economic forecasts, must be seen as a symbolic, practical and emotional stepping stone for new consumers in China.

    In one particular interview with in Chengdu, the thriving city in the Western part of the country, a Chinese entrepreneur was describing to me that one of his favourite brands was Tod’s (which he could not pronounce, and jokingly called it “potato slices” because it was the closest Chinese word he could find).

    Despite having extreme difficulty in engaging with the brand at the official level, he has become a Tod’s aficionado based on his experience at the store – that he described as “like the home I imagine I would live in Italy”.

    For him, the brand was the retail experience, it was enough to cement this loyalty and enthusiastic promotion to a large group of businessmen, who like himself, were ‘finding their feet’ with luxury brands.

    Beyond a transaction point: Chinese stores as brand equity

    From a broader strategic point of view, brands need to see stores in a wider cultural perspective. Beyond a point of transaction and sales number, stores are the clearest and most uncompromised expression of your brand to new consumers in China.

    In the context of ‘face’, retail presence in new malls and as part of the new middle class’ weekend walkabouts is essential to suggest status and respect to Chinese consumers.

    Once again, using Chengdu and luxury as an example: The way foreign brands were perceived in terms of their premium offering was directly related to their presence in two of the city’s new mall developments –meaning Burberry and Michael Kors enjoyed almost equal rating as early-arriving European brands.

    Adding to perceptions is the way that Chinese consumers share their recommendations with others in-person and online is almost always footnoted with a proof point on quality. Invariably, this is described as the look, feel, or physical appearance of the product materials – the fabric of the dress or the sheen of the casing. In this initial peer-to-peer introduction to brands, physical inspection at a store is an essential part of the purchase journey.

    Forgoing or not maintaining a retail presence is like introducing a ‘circuit breaker’ at the most crucial stage of brand adoption. Stores, irrespective of economic forecasts, must be seen as a symbolic, practical and emotional stepping stone for new consumers in China. Something that e-commerce, or lack of stores, can not address.

  • Central Group wins Big C Vietnam auction

    Central Group wins Big C Vietnam auction

    Thai retail conglomerate Central Group has won the bidding battle for Groupe Casino’s Big C Vietnam business.

    Groupe Casino has confirmed Central paid €1 billion (US$1.14 billion), which will be used to pay down debt.

    That price is as much as $300 million more than the French retailer reportedly expected to get for the business whose value was earlier publicised at around US$800 million.

    One of the rival bidders – Lotte Group of Korea – is believed to have withdrawn from the process when it became clear the price would exceed $1 billion.

    Casino says it will net €920 million after sale costs.

    Central Group is already building a substantial collection of assets in Vietnam, rolling out Robins department stores in main centres and acquiring a controlling interest in the country’s largest electronics retail chain Nguyen Kim. Outside Vietnam it owns department stores in Italy, Germany and Indonesia, amongst other markets. Worldwide it boasts 4400 stores under various brands.

    In an odd twist, Central was a minority shareholder in the Big C Thailand operation which Groupe Casino sold a majority 58.6 per cent stake to rival Thai retailer Berli Jucker last month. Berli Jucker is controlled by tycoon Charoen Sirivadhanabhakdi, who last year paid €3.1 billion for German owned Metro Group’s hypermarket business in Vietnam. Berli Jucker is believed to have bid for Big C Vietnam but lost out to Central.

    The Big C Vietnam operation comprises 43 stores and 30 shopping malls. It turned over  €586 million in 2015.

  • Singapore ponders Paym-style payments platform

    Singapore ponders Paym-style payments platform

    Singapore is looking into the creation of a payments system similar to the UK’s Paym that would let someone send money using only the recipient’s mobile number, email address or social network account.

    The all-in-one addressing system – which would mean senders would not need a recipient’s bank account details – is being explored by banks and the Monetary Authority of Singapore (MAS), the organisation’s managing director, Ravi Menon, revealed during a panel discussion.Menon says that the move would fit in with MAS’s desire to boost interoperability within the industry as a way to promote innovation, arguing that common standards for payments systems would result in seamless transactions across a range of platforms.

    With this in mind, the country is also working towards a unified POS terminal that can read all kinds of cards at retail and hospitality outlets.

    Menon’s remarks came during a discussion on how Singapore can harness the power, and manage the risks, of fintech. The island has been aggressively pushing itself as a major global hub for the fast growing industry – last week it opened a dedicated office designed to help startups set up in the country as a part of a S$225 million, five year plan to build a vibrant ecosystem for innovation.

    Menon says that fintech is fundamentally changing the financial industry, and may well be its best hope for the future. He told the audience that MAS’s job as the country’s regulator is to adopt a risk-based approach to fintech innovation, not front-running but running alongside.

    The watchdog does this by actively engaging with fintech firms and allowing them to experiment with new technologies in a safe environment. This will be boosted soon by the introduction of a “regulatory sandbox” where firms can experiment and launch products or services within controlled boundaries.

    The all-in-one P2P payments platform and unified POS system are also part of MAS’s plan to promote innovation, this time by enabling interoperability. Another aspect of this strategy will see the publication of open APIs, with MAS working with FIs on sharing aggregated data to improve market and risk analyses, forecasts and projections.

  • McDonald’s bares plans to explore growth opportunity in Asia

    McDonald’s bares plans to explore growth opportunity in Asia

    McDonald’s Corporation said it is keen to explore growth potential in Asia and is currently seeking partners who would enhance its competitive advantages in the region.

    “Asia represents a significant area of opportunity for McDonald’s to blend our global quality standards with local insights and expertise from partners who share our vision and values,” said Steve Easterbrook, McDonald’s President and CEO, in a statement.

    This move is expected to allow the fast-food chain to accelerate our growth and scale faster across diverse markets.

    “We’re in the midst of transforming our business and taking a strategic and thoughtful approach to enhance our ability to grow around the world,” Easterbrook said.

    The McDonald’s chief said China, Hong Kong, and Korea collectively represent more than 2,800 of its restaurant locations, the majority of which are currently company-owned. The three countries are considered high-growth markets, which means they have relatively higher restaurant expansion and franchising potential.

    Over the next five years, McDonald’s said it intends to add more than 1,500 restaurants in these three territories.

    The company also recently announced its intent to identify strategic partners in Taiwan and Japan. Last year, McDonald’s committed to strategically evaluate ownership structures in markets around the world with the overall goal of reducing the number of restaurants that the company owns and operates. More restaurants will be placed under local ownership.

  • Bank Negara unit MyClear to set up new retail payment platform

    Bank Negara unit MyClear to set up new retail payment platform

    The Malaysian Electronic Clearing Corp Sdn Bhd (MyClear), a wholly-owned subsidiary of Bank Negara Malaysia (BNM), is developing a new real-time retail payments platform to serve both as a catalyst and enabler for innovative payments in Malaysia.

    BNM deputy governor Datuk Muhammad Ibrahim said the enhancement, which is expected to launch in 2017, would adopt a multi-currency system that leveraged on the SWIFT messaging system for large value payments.

    “The enhanced Real-Time Gross Settlement System (RENTAS) would cater for multiple messaging formats including the internationally-recognised ISO 20022 which supports the transmission of richer remittance data and facilitates interconnectedness with other economies within the region,” he said in his keynote address at the Malaysia E-Payment Excellence Awards (MEEA) in Kuala Lumpur on Monday.

    He said BNM would continue to foster an enabling environment for infrastructure building and network expansion, adding the enhanced platform also promoted effective competition among industry players to spur the development of innovative solutions, provide greater choices and value proposition to the public and, in the process, lower costs.

    Meanwhile, MyClear managing director Peter Schiesser said the retail payment platform initiative is in line the implementation of faster payments in the United Kingdom, Singapore and Sweden.

    The platform has also delivered significant economic benefits, as well as new immediate payment initiatives in Australia, the United States and the European Union, he added.

  • Coffee wars: South Korea’s cafe boom nears saturation point

    Coffee wars: South Korea’s cafe boom nears saturation point


    In fashionable retail and commercial districts of southern Seoul, nearly one in every two buildings boasts a coffee shop – evidence of a boom that has delivered dizzying growth for the likes of Starbucks and local chains.

    But now the market is getting even more crowded, as convenience stores such as 7-Eleven offer 1,000 won (87 cents) cups, and smaller players are feeling the heat.

    “We declared an emergency situation, gathered all employees eight times to debate strategies,” Moon Chang-ki, CEO of mid-priced coffee chain Ediya, the country’s largest operator by location with about 1,800 stores, told reporters recently. “If we sell at that price, our store owners won’t earn any margins.”

    To compete, Ediya says it has instead focused on improving the quality of its coffee, and actually raised prices last year. Other chains have responded to growing competition by cutting back on store numbers and staff, or expanding overseas.

    The number of chain and stand-alone coffee shops in South Korea more than tripled to about 49,600 in 2015 from 12,400 in 2011, according to Korea Contents Media – far faster than overall consumption of coffee, which Koreans have been drinking for decades.

    PEAK COFFEE

    South Korea’s per capita coffee consumption has nearly doubled since 1990 to 2.3 kg (5 lb) per person, according to the International Coffee Organization – still roughly half the 4.5 kg that Americans consume.

    Revenue growth at coffee chains in the country slowed to about 8 percent in 2014, however, from more than 20 percent annually between 2008 and 2012, analysts say. While the number of new coffee shops in Seoul increased, so did closures, according to city data.

    Brewed coffee sales at 7-Eleven, run by Lotte Shopping’s Korea Seven Co Ltd, jumped 88 percent in 2015 after it introduced drip coffee early last year costing about a dollar, almost one-fifth the cost of an average Starbucks cup.

    McDonald’s Corp stores cut coffee prices to 1,500 won from 2,100 won early last year, and have seen sales of the beverage almost triple, the company told Reuters.

    By contrast, local chain Cafe Droptop, with about 225 shops, cut about 20 percent of its workforce at the end of 2015. Another chain, Coffine Gurunaru, with about 100 shops, incurred combined operating losses of 2.5 billion won ($2.2 million) in 2013 and 2014 after being profitable in the previous two years, filings show.

    “Even fried chicken restaurants and pubs are adding coffee, trying to be a cafe, while espresso machines are spreading in offices,” said Lee Kyung-hee, who heads the Korea Business Strategy Institute, a consultancy. “The coffee industry is fighting a war without borders.”

    GOING ABROAD

    Starbucks entered the market in 1999, and is widely credited with starting the country’s habit for splurging on higher-quality coffee and creating a cafe industry SK Securities said was worth about 2.5 trillion won ($2.2 billion) in 2014.

    Starbucks Coffee Korea, a 50-50 joint venture between the world’s biggest coffee chain and South Korean hypermarket operator E-Mart, now has 860 stores, putting the country behind only China and Japan as the company’s biggest markets in Asia, with sales more than doubling between 2011 and 2014.

    It posted a 20 percent increase in net profit to 30.77 billion won in 2014, the most recent year for which results are available, on revenue of 617 billion won, up 28 percent.

    But with industry growth slowing, some chains have been pushing abroad.

    Caffe Bene, which reached 932 domestic stores in 2014 before trimming back to 850 at the end of March, posted a 3.3 billion won net loss in the first three quarters of 2015, according to the latest public data.

    Last month, a joint venture between Singapore’s Food Empire and Indonesia’s Salim Group acquired a 38 percent stake in Caffe Bene, becoming the second biggest shareholder after South Korean private equity fund K3 Equity Partners.

    The chain said it was looking to expand in Southeast Asia to drive growth.

    Zoo Coffee, with 65 domestic shops, has opened about 200 franchise stores in China since entering the country in 2013 and in December announced a tie-up with China’s giant Dalian Wanda Group to open 50 stores per year there.

    Cafe Droptop in November opened its first overseas outlet in Shanghai.
     

  • Gammon India to sell EPC biz to Thailand firm for Rs 250 crore

    Gammon India to sell EPC biz to Thailand firm for Rs 250 crore

    Debt-laden civil contractor Gammon India has accepted the proposal from Thailand-based GP Group to sell a controlling stake in Gammon’s engineering, procurement and construction (EPC) business for R250 crore.

    In a filing to BSE, the company said that the board of the company “considered and accepted the proposal from GP Group, Thailand to invest in the company’s Civil EPC by investing in the company’s wholly owned subsidiary, Gammon Retail Infrastructure Private (GRIPL)”.

    As part of the agreement, GP Group shall invest a sum of R250 crore, of which R26 crore is to be invested on completion of business transfer agreement and balance R224 crore upon completing the scheme of arrangement for acquiring upto 75% stake in GRIPL.

    The sale of EPC business forms part of the company’s efforts to repay the CDR lenders. Gammon India’s CDR package of R13,000 crore in 2013, was among the largest approved in the last two years.

    According to the Master Restructuring Agreement (MRA) dated September 24, 2013 executed by Gammon India with the CDR lenders, the company was required to ensure that either the corporate guarantees issued by the company on behalf of its subsidiaries are released in full or the company monetises or divests its investments in the domestic and overseas subsidiaries.

    However the progress on company’s asset monetisation programme and sale of foreign businesses has remained very slow. The signing of agreement for the sale of EPC business, is the first in a series of asset sales that the company needs to undertake to repay the banks.

    On November 23, lenders had decided to initiate strategic debt restructuring or SDR for Gammon India by converting a portion of its debt to equity. Lenders have 18 months to find a buyer for the firm, failing which the account will need to be classified as a non-performing asset (NPA). In August last year, Gammon India’s board had approved the restructuring and transfer of its EPC business to Gammon Retail Infrastructure (GRIL) and the T&D business to Transrail Lighting (TLL), subsidiaries of Gammon India. In FY14 ending September 2014, GRIL reported a loss of R42,807 and TLL reported a net loss of R89.3 lakh.

    In December, the consortium of eight banks had become the largest shareholder of Gammon India in the public shareholder category. As on March 9, banks stake in Gammon India had gone up to 55.43%, which was further upped to 63.41% as on March 18, according to the shareholding pattern on BSE. The shareholding under financial institutions/banks stood at 2.18% as on September 30.

    The SDR rules allow banks to convert a company’s debt into shares at a price below the current market value or an average of closing prices in the ten trading days before a decision is taken at the Joint Lenders Forum(JLF). They can hold at least 51% of the equity of the company.

    The company’s gross debt at the end of March 2014 stood at R11,061 crore, up 15.4% over March 2013, Bloomberg data showed. In FY14, the company reported a consolidated net loss of R729 crore on the back of R3,763 crore in revenues.

    The finance costs stood at R699 crore. The company has not reported its 2015 earnings numbers.

    The company is promoted by Abhijit Rajan (2.24%) who is also its chairman and managing director and other promoters include Pacific Energy Private (4.93%), Devyani Estate and Properties (3.33%) among others. Their stakes have come down to present levels from 5.99%, 13.20% and 8.93% respectively, at the end of September 2015.

    Gammon India plans to divest 30% in Gammon Infra Projects

    Gammon India will be divesting up to 30% stake in its listed infrastructure arm Gammon Infrastructure Projects (GIPL), held through its wholly owned subsidiary Gammon Power Limited (GPL), said a BSE notice. Company’s board has approved the divestment, which will be done in one or more tranches. “This divestment will be done at such times and in such manner as the board /duly constituted committee of directors, may approve, on the floor of the stock exchanges, at the price prevailing on the exchanges on the date of such sale,” the company said. fe Bureau

  • Starbucks China sales soar 18 per cent

    Starbucks China sales soar 18 per cent

    Starbucks China has recorded a massive 18 per cent increase in sales in the second quarter, fuelled by a 5 per cent increase in transactions.

    The Chinese boost was one of a string of highlights in the quarter in which Starbucks set a new sales record of US$5 billion globally, up by 6 per cent on a same-stores basis.

    The Seattle-based coffee giant served nearly 16 million more customer occasions worldwide in the three months to March 27, 12 million of those in the US where it is experiencing a resurgence.

    Earnings per share rose 18 per cent to a record 39 cents, with US and Americas comp-store sales up 7 per cent. Operating profit rose 11 per cent to a second quarter record $878 million, its operating margin up to 17.3 per cent.

    Starbucks boosted its worldwide store network by 350 to 23,921.

    CEO and chairman Howard Schultz described the Starbucks China performance as “stunning” and said the overall financials underscored the strength of the brand and the resilience of the global retail and consumer packaged goods business.

    “Loyalty, technology and innovation are continuing to fuel our digital flywheel and propel our business forward all around the world.”

  • UBS optimistic on Australia, Japan real estate markets

    UBS optimistic on Australia, Japan real estate markets

    UBS Asset Management is optimistic on the Australian and Japanese real estate markets, according to its latest Asia Pacific quarterly outlook report. Amid a challenging macro conditions, transaction volume for commercial real estate fell 12% y-o-y in 2015. However, Japan and Australia bucked the trend as domestic lenders eased their credit policies on account of improving fundamentals and collateral quality.

    Toh Shaowei, UBS Asset Management director of research and strategy for Asia Pacific, says: “Broadly speaking, the near-term condition in APAC region is still challenging and there is a ‘longer winter’, but the long-term fundamentals remain strong. We see a few macro themes and continue to monitor them.”

    In Japan, household spending is likely to be the main driver of economic growth on the back of ongoing wage rises, healthy job market and lower oil prices. Negative interest rates have also boosted capital expenditures. Notably, these expenditures have focused largely on new product development, R&D and efficiency saving measures to counter aging population and labour shortages.

    Occupancy rates and rents for Japan’s key office markets have also trended up due to limited new supply and steady demand from large corporates. These corporates have benefited from Bank of Japan’s asset purchases, lower borrowing costs and weaker currency which boosted earnings.

    The leasing market in the Japanese logistics sector remains robust on the back of increasing demand for same day deliveries from end users and growth of online shopping. However, rising supply from new developments are likely to restrict overall rental growth.

    In Australia, Sydney and Melbourne led the recovery in the office leasing market as the country shifts its growth model from the mining sector and resource-rich state. Finance and insurance, professional services and the technology, media and telecommunications sector are the key drivers of demand for office space. Meanwhile, net absorption level in resource-rich states of Queensland and Western Australia continue to lag but is gradually stabilising, says UBS.

    Separately, robust demand from international retailers looking to gain exposure to the Australian market have strengthened the rents and occupancy rate of prime retail space. However, secondary retail space is expected to continue to underperform amid subdued wage growth and increasing penetration of online retailers. UBS anticipates near-term rental growth to remain below historical averages as households allocates a higher share of their incomes to healthcare and education.

    On the home front, the outlook for Singapore’s real estate market remains challenging in the near term. The clampdown in foreign labour supply and an elusive labour productivity gain have lifted business costs and dented corporate sentiments. Coupled with a supply onslaught, UBS expects the overall office sector performance to remain depressed over the next two years.

    UBS expects the weakness to be broad-based across all property segments. Singapore’s retail rents are likely to witness a flat to marginal declines over the next 12 months while sluggish manufacturing outlook is clouding the overall prospects for the industrial property sector.

  • Cheap convenience store coffees enjoy growing popularity

    Cheap convenience store coffees enjoy growing popularity

    Low-cost coffees at Korean convenience stores are increasingly popular among price-conscious consumers, posing a threat to coffee shop franchises, industry data showed Monday.

    Local convenience stores have served canned coffee and instant coffee with hot water for years, but they are expanding sales of higher-quality drinks through self-serve coffee bars to get a bigger chunk of the rapidly growing market.

    The nation’s top three convenience store chains, which each have over 7,000 outlets nationwide, offer coffee at around 1,000 won (87 cents), a price one-third or one-fourth that of major franchise coffee shops.

    Helped by affordable prices, coffee sales at major convenience store chains have soared in the first quarter compared to a year ago.

    7-Eleven, operated by Lotte’s affiliate Korea Seven, said sales at “Seven Cafe” jumped nearly four times in the first three months of this year, without elaborating on the specific sales figures.

    GS 25, a chain under GS Retail, also saw coffee sales at “Cafe 25” rise nearly three-fold during the period, and CU, a chain by BGF Retail, said its sales at “Cafe GET” rose 62 percent.

    Convenience stores plan to expand their on-the-go coffee services this year as well as bakery items and ice beverage menus this summer to expand coffee-related sales. The 7-Eleven and GS 25 chains plan to triple the machine to 3,000 this year, according to company officials.

    As major chains are set to expand coffee services to edge out their rivals, industry officials expect the competition to accelerate polarization in the market between mini take-out stores and trendy cafes. Their fast rise poses a threat to franchise coffee shops, which have posted lackluster performances amid a supply glut and rising rental fees in major retail strips.

    Ediya, a homegrown coffee brand that has the largest number of shops nationwide, said the average sales per store slipped 2 percent in 2015 from a year ago.

    “We have been paying keen attention to convenience store coffees. After in-depth discussions with employees late year, we concluded that creating Ediya’s own taste is the most important,” Ediya CEO Moon Chang-ki said during last week’s press conference.

    “Despite the influx of cheap coffee, we will strengthen R&D to improve the quality of our coffee products.”

    The coffee market was valued at 6 trillion won last year and was expected to grow about 10 percent in the next five years.

    Amid the coffee craze, convenience store coffee grew at the fastest pace to snip away the market share of other caffeine beverages. Coffee sales at convenience stores amounted to 40 billion won ($34.7 million) in 2015 and are expected to expand to 100 billion won this year, according to industry data.

  • Gieves & Hawkes exploring RFID route

    Gieves & Hawkes exploring RFID route

    The new Gieves & Hawkes store in The Mailbox, Birmingham is using RFID technology to help the retailer gain a clearer view of stock inventory and to aid the business’s loss prevention strategy.

    Further installations of the technology are being discussed with solutions provider Catalyst, but for now the menswear retailer is solely monitoring results in the West Midlands store, which opened last summer.

    Sam Thompson, regional IT manager for Gieves & Hawkes parent company Trinity Group, said: “The technology has been easy to deploy and the store appreciates the benefits it offers.

    “The data generated is useful in managing store stock levels.”

    Catalyst, which is owned by global supply chain organisation Li & Fung, operates a cloud-based data platform and is providing Hawes & Curtis with handheld readers for scanning products and overhead readers, which are invisible to the customer but offer the company’s staff item level intelligence. The tech range is showcased in the company’s London, New York and Hong Kong showrooms, allowing retailers to walk in and see the solutions in action in a mock-up store scenario.

    We visited the Catalyst London showroom in 2014 and witnessed how the readers can be combined with other technology such as smart changing room systems or digital screens, to boost the customer’s in-store experience.

    Catalyst works alongside Smartrac for the Gieves & Hawes project, with the latter’s UCode 7 Web RFID tags printed, encoded and applied to all garments delivered to the store. The tags are deactivated using Catalyst’s ePay readers at the till point, with the information fed straight into the retailer’s point of sale system, giving the business a real-time view of stock inventory.

    The RFID solution also provides an alternative to electronic article surveillance in the fight against theft.


  • Versace Asia to open Central flagship

    Versace Asia to open Central flagship

    While other luxury brands are scaling back in Hong Kong’s subsiding retail market, international fashion brand Versace Asia plans to open a flagship store in Central in October.

    Shanghai Commercial Bank says the Milan-based fashion house has signed a three-year lease, with an option to renew, for 12,600 sqft (1170 sqm) on the ground and first-floor levels of a redeveloped building owned by the bank in Queen’s Rd.

    “We needed to pick clients in this market,” says the bank’s CEO David Kwok, noting that it interviewed Versace “for quite some time”.

    “Many other players wanted to sign Versace. You can’t miss our tower when driving through Central. It’s a good address for them,” says Kwok.

    “It goes to prove Hong Kong is a true financial centre. We had thought the market would be very bad, so we were quite modest when setting our pricing.”

    Jeannette Chan, JLL regional retail director, said Versace was taking advantage of declining retail rents and the availability of space in Central.

    “Versace sees it is an optimal time to boost its brand presence in Hong Kong.”

    Versace has two retail stores in Hong Kong, in Admiralty and Tsim Sha Tsui. Its new Asia flagship will sell men’s and women’s apparel, jewellery and accessories.