Blog

  • EU Supply Chain Rules Target 37 Percent of Inaccurate Clothing Labels

    EU Supply Chain Rules Target 37 Percent of Inaccurate Clothing Labels

    European Union sustainability and forced-labour laws will penalise apparel brands and their global suppliers, with new packaging rules rolling out in August. Companies must track materials down to individual farms and component mills. Regulators in Brussels are introducing strict enforcement rules, empowering border authorities to seize non-compliant garments and name offending companies publicly.

    A European Commission testing campaign found that 37 percent of clothing labels failed to reflect material composition accurately. That finding has accelerated regulatory scrutiny across Asian textile export hubs supplying European fashion groups, prompting brands like Tod’s to partner with sustainability-data management firm Renoon.

    Forced Labour Import Bans Target Factory Floors

    The EU Forced Labour Regulation gives European investigators direct authority to inspect supply chains. Officials can ban non-compliant goods from entering the single market. Older disclosure laws required only annual corporate reports. The new framework mandates product-level proof of compliance before shipments clear customs.

    Marissa Brock, senior director of policy and government affairs at supply chain software firm Sourcemap, said: The EU has already indicated that it will target large brands and retailers for forced labor enforcement.

    For manufacturers in China, Vietnam, Bangladesh and India, documentation is now a strict condition for export. Ignorance of subcontracting practices or raw material origins no longer shields buyers or vendors from penalties.

    Digital Passports Shift Burden to Component Makers

    Compliance pressure will mount as the Ecodesign for Sustainable Products Regulation introduces mandatory Digital Product Passports. These digital records attach directly to physical goods. They log raw material extraction, chemical treatments and repairability standards.

    Upstream suppliers carry the operational burden. European fashion houses hold legal liability under EU law. Yet Asian tier-two and tier-three vendors must produce and standardize the operational data required for every production batch.

    Fast Fashion Faces Inspection Bottlenecks

    Standard fast-fashion retailers benefit from agile, digitized supply networks when integrating digital passport systems. Ultra-fast-fashion businesses face acute exposure. Compressed production schedules and minimal chemical auditing create immediate risks for their low-cost models.

    Luxury brands face separate hurdles. Milan courts placed Italian operating subsidiaries of major fashion houses under judicial administration after investigations uncovered illegal subcontracting. High price points do not guarantee upstream transparency.

    Tight Timelines for Single Market Access

    Brussels began applying its Packaging and Packaging Waste Regulation in August. Full enforcement of the Empowering Consumers for the Green Transition Directive takes effect in September. Farm-level traceability mandates under the Deforestation Regulation follow by the end of next year.

    Broader requirements arrive next, with full implementation of the Corporate Sustainability Due Diligence Directive and digital product passport mandates taking effect across 2028 and 2029.
  • China Cuts NEV Export Tax Rebates to 9% from 2027

    China Cuts NEV Export Tax Rebates to 9% from 2027

    China will lower its export value-added tax rebate rate for new energy vehicles from 13 percent to 9 percent on April 1, 2027. The four-percentage-point cut reduces the fiscal refund Chinese carmakers collect on every electric and plug-in hybrid vehicle shipped overseas.

    Customs declaration dates will determine whether shipments receive the older 13 percent rebate or the reduced 9 percent rate. The joint directive from the Ministry of Finance and the State Taxation Administration covers pure battery passenger cars, plug-in hybrid models, electric buses, and commercial electric truck tractors. Existing export consumption tax rebate and exemption rules for qualifying vehicles remain unchanged.

    Margin Squeeze for Export-Heavy Automakers

    The policy directly cuts the profitability of shipping cars from Chinese assembly lines to foreign showrooms. Research from Deutsche Bank calculates that the four-point rebate cut will reduce net profit at BYD by roughly 5,000 yuan ($743) on every vehicle exported once the rule takes effect in the second quarter of 2027. BYD shipped 1,342,468 vehicles overseas during the first nine months of 2026, representing approximately 43 percent of its total wholesale volume.

    Other major Chinese exporters face the same margin compression. The change will hit export earnings across a wide group of listed vehicle manufacturers, including Geely Auto, Chery, SAIC Motor, Great Wall Motor, Changan Automobile, Leapmotor, GAC Group, and Xpeng. Automakers exporting directly from mainland factories will either absorb the lost cash refund or attempt to raise retail prices in competitive destination markets.

    Divergence Between Domestic Slump and Foreign Demand

    Beijing is pulling back state fiscal support as export volumes surge while the domestic market contracts. Data from the China Association of Automobile Manufacturers shows Chinese NEV exports jumped 130 percent year-on-year to 4.006 million vehicles in the first nine months of 2026. September exports alone climbed 160 percent to 571,000 units. By contrast, domestic deliveries in China fell 9.4 percent in September to 1.252 million vehicles.

    Total passenger vehicle exports from China reached roughly 919,000 units in September, up 64 percent from the prior year. Weaker consumer spending and reduced purchase incentives at home have forced manufacturers to fill capacity by targeting buyers in Europe, Southeast Asia, Latin America, and Africa. That export surge has intensified price competition in foreign dealerships, accelerating regulatory resistance abroad and prompting Beijing to step back from subsidizing outward pricing wars.

    The Shift to Overseas Factory Floors

    Higher trade barriers and reduced export rebates will accelerate the migration of Chinese automotive capital into foreign manufacturing plants. Chinese electric vehicle production costs run near $20,000 per unit compared to roughly $31,000 for European equivalents, according to estimates by AlixPartners. But with importing jurisdictions raising duties and Beijing trimming domestic tax support, direct exports from China will become structurally more expensive to run.

    Automakers are already shifting assembly footprints closer to their primary regional sales networks. BYD has invested in vehicle manufacturing plants across Thailand, Indonesia, Brazil, and Hungary to assemble cars locally rather than shipping finished units out of Shenzhen. As trade policies tighten, regional factory networks will replace direct mainland car-carrier shipments as the primary channel for supplying Asian and international retail networks.

    Stepwise Rollback of Clean Energy Incentives

    The vehicle rebate reduction follows earlier retrenchments across China’s renewable energy supply chain. Beijing eliminated export VAT rebates for solar photovoltaic equipment on April 1, 2026, while lowering export rebates on battery products from 9 percent to 6 percent. Those battery export tax rebates will drop to zero starting January 1, 2027, three months before the automotive rebate reduction takes effect.

    Manufacturers and logistics operators now face an eighteen-month window before the April 2027 customs deadline to adjust supply contracts, pricing sheets, and overseas factory production schedules.

  • Firefly Halts Subang to Singapore Flights Through October 14 Due to Regional Haze

    Firefly Halts Subang to Singapore Flights Through October 14 Due to Regional Haze

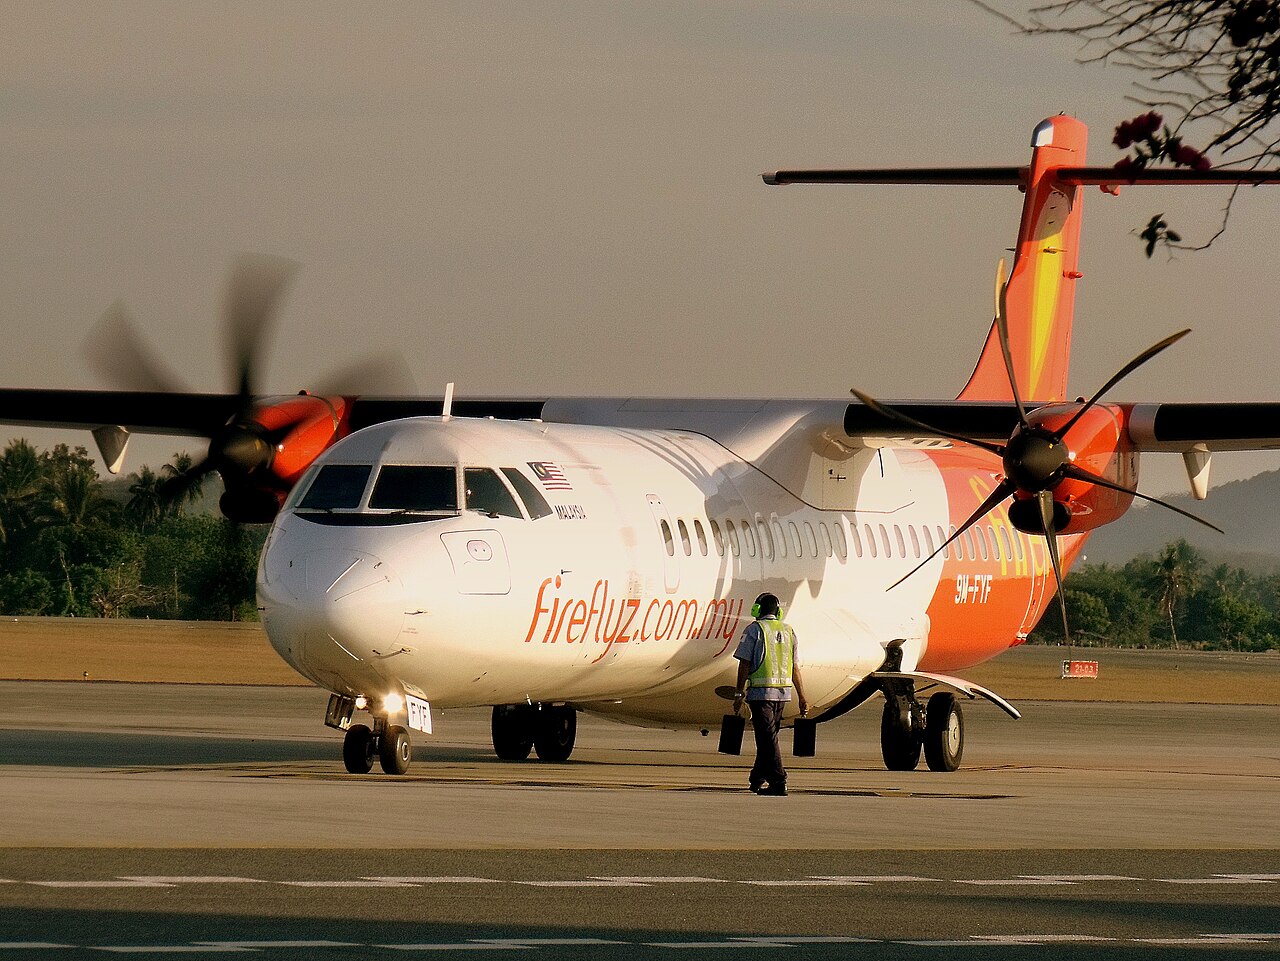
    Firefly has extended the cancellation of all flights between Subang and Singapore through October 14. Thick haze across the cross-border corridor cut visibility.

    The suspension affects six daily return services between Sultan Abdul Aziz Shah Airport and Singapore’s Seletar Airport. The airline initially halted the route from October 10 to October 12. It then pushed the restart date back.

    Disrupted Schedules Across the Causeway

    Grounded flights cover services FY3122 and FY3123, FY3124 and FY3125, FY3126 and FY3127, FY3128 and FY3129, FY3130 and FY3131, and FY3132 and FY3133. Together, the pairings make up the carrier’s daily shuttle between the two secondary hubs.

    Firefly is rebooking affected passengers onto parent company Malaysia Airlines flights out of Kuala Lumpur International Airport, subject to seat availability. Travelers who decline the alternate itineraries can claim a full refund to their original payment channel within 30 working days.

    Air Quality Readings in Singapore

    Pollution levels in Singapore remained in the unhealthy range as operations were paused. Data from Singapore’s National Environment Agency showed 24-hour Pollutant Standards Index readings between 118 and 155 on Monday evening.

    Regional monitoring stations recorded the highest concentration in the central and western districts at 155. Eastern areas registered 139, southern sectors measured 122, and northern districts reported 118.

    Impact on Business Travel Corridors

    Subang to Seletar provides an alternative for executive and short-haul business travel between the two capitals. Halting the route pushes passenger volume back to Kuala Lumpur International Airport and Changi Airport.

    Turboprop operations at secondary city airfields face tighter weather and visibility minimums than major hubs equipped with advanced instrument landing systems. When visibility drops, regional feeder links take the earliest schedule cuts.

    Next Steps for Passenger Operations

    Operations teams continue to monitor visibility along the corridor ahead of the scheduled October 15 resumption.

    Plans call for restoring the six daily return services once air quality clears minimum safety thresholds at both airfields.

  • HSBC Cuts Fixed Pay Allowances to Shift Senior Staff to Wall Street Bonus Model

    HSBC Cuts Fixed Pay Allowances to Shift Senior Staff to Wall Street Bonus Model

    HSBC Holdings will scrap fixed-pay allowances for senior bankers and replace them with variable bonuses starting in 2028. The shift overhauls how the lender rewards top earners across global financial centres.

    Variable pay at the London-based bank reached 3.93 billion dollars in 2025, up 10 per cent from the prior year. Total compensation and benefits stood at 21.5 billion dollars.

    Under the new framework, senior staff lose fixed allowances in favour of discretionary bonuses tied to performance. An internal memo detailed the changes across business units, which the bank later confirmed.

    How the compensation model changes

    British banks introduced fixed allowances more than a decade ago to bypass European Union bonus caps. EU rules capped bonuses at 100 per cent of base salary, or 200 per cent with shareholder approval. Lenders created fixed allowances to remain competitive.

    The bank structured those payouts as immediately vested stock awards with mandatory holding periods. They were non-pensionable and capped at 150 per cent of base salary.

    Britain lifted those remuneration caps in 2025 to help London lenders compete with Wall Street. Barclays made a similar adjustment in July, shifting more compensation into annual discretionary pools.

    Hong Kong executive perks scaled back

    The pay overhaul coincides with operational cuts at the group’s regional hub in Hong Kong. Chief executive Georges Elhedery has targeted legacy executive perks to rein in overheads and enforce cost discipline.

    In Hong Kong, the bank eliminated an education subsidy covering 95 per cent of school fees for children of new hires and relocating senior staff. Managing directors and band-three employees already receiving the benefit will keep it.

    Private club subsidies in Hong Kong were also scrapped. Those memberships were previously worth up to HK$200,000 per executive.

    Dismantling post crisis pay limits

    Tying compensation to discretionary bonuses pushes earnings risk directly back onto dealmakers and division heads. Fixed allowances locked in high overheads that lenders could not trim during market downturns.

    For regional wealth and investment banking teams in Hong Kong and Singapore, variable packages will widen the spread between desks. Top producers gain uncapped upside. Lagging desks face immediate cuts to take-home pay.

    That structure mirrors Wall Street firms. Base salaries stay lean, and annual payouts track deal flow, trading revenue and net interest margins.

    Restructuring under Georges Elhedery

    Broader corporate overhauls have accelerated since Elhedery took charge in September 2024. The lender has cut hundreds of jobs, merged or divested non-core units, and weighed restructuring its Singapore legal entities to streamline governance.

    Investors have backed the overhaul. HSBC shares have more than doubled since Elhedery took the helm. While fixed pay remains the largest component of banker compensation in its latest annual report, the 2028 overhaul will reverse that balance.

    Current fixed allowances stay in place through 2027. The variable bonus framework will take full effect at the start of the 2028 financial year.

  • Nissin Recalls 82G Aburasoba Noodles over Undeclared Milk Allergen

    Nissin Recalls 82G Aburasoba Noodles over Undeclared Milk Allergen

    In October 2026, Nissin issued a recall for its Salt and Sesame Oil Noodles Aburasoba 82g due to the presence of an undeclared milk allergen.

    The products were sold in Asian grocery stores across Victoria and distributed by Sweets & Beverages Australia Pty Ltd.

    Allergen Risk Triggers Distribution Halt

    The affected batches carry a Best Before marking of December 8, 2026, prompting warnings that consumers with a milk allergy or intolerance may experience a reaction and should seek medical advice if concerned.

    Retailers across Melbourne and regional Victoria must remove the product from shelves and clear warehouse stock immediately. Consumers who purchased the 82-gram packs can return them to the original place of purchase for a full refund.

    Compliance Pressures on Imported Asian Groceries

    Specialty importers face strict scrutiny from Australian regulators over mandatory food allergen declarations on packaged imports. Major Asian packaged food brands frequently manufacture localized packaging variants, but parallel import routes and third-party distribution often introduce compliance gaps when domestic labeling stickers fail to list common allergens correctly.

    For independent grocers, product withdrawals disrupt inventory and create immediate administrative burdens at the checkout. Importers absorb the direct cost of reverse logistics, stock write-downs, and customer refunds across distributed networks.

    Cross-Border Supply Chain Oversight

    Japanese food manufacturers like Nissin operate extensive regional supply chains, producing items across facilities in Japan, Hong Kong, and Southeast Asia for export. While core production adheres to strict quality controls, destination-market compliance relies heavily on local distributors translating and adhering to standard food codes.

    Similar allergen-related recalls across Australia over the past year have forced FMCG distributors to tighten third-party verification processes before cleared shipments leave bonded warehouses.

    Next Steps for Retail Networks

    Victorian Asian grocery stores are currently completing stock sweeps to verify that all inventory bearing the December 8, 2026 expiry date has been cleared from sale floors. Sweets & Beverages Australia is managing retailer reimbursements and coordinating with regional food authorities on inventory disposal numbers.

  • Pakistan Textile Exporters Seek 6% to 8% Support Amid Export Slump

    Pakistan Textile Exporters Seek 6% to 8% Support Amid Export Slump

    Pakistani textile makers face a steep decline in goods exports during the second quarter from October to December, driven by weakening Western demand, surging shipping costs, and escalating production expenses.

    According to Pakistan Textile Exporters Association (PTEA) Patron-in-Chief Khurram Mukhtar, ocean freight charges have climbed by 1.5 to 2.5 times, severely squeezing profit margins.

    The downturn is affecting the country’s entire textile value chain, from ginning and spinning to weaving, knitting, and processing, compounded by weak domestic demand amid high inflation.

    Squeezed margins and export rebate demands

    PTEA Patron-in-Chief Khurram Mukhtar said inflation in major Western consumer markets has depressed wholesale orders from international retail brands. Rising input costs and higher transport expenses have also hurt competitiveness. Pakistani apparel and textile goods now struggle against goods from regional manufacturing hubs across South and Southeast Asia.

    To stop factory shutdowns and protect export volumes, the association wants an immediate temporary Duty Drawback of Local Taxes and Levies rebate of 6 per cent to 8 per cent. Exporters are also demanding the quick release of delayed tax refunds across government heads to resolve working capital shortages.

    Mill operators also want authorities to eliminate cross-subsidies embedded in industrial electricity and gas tariffs. They say these surcharges push local production costs above regional rivals.

    Financing bottlenecks hit textile supply chain

    Credit access remains another friction point for garment suppliers. The federal government set a fixed 4.5 per cent financing rate under the Export Finance Scheme in the FY27 Finance Bill. Commercial lenders have not implemented the concessionary rate.

    Banks continue to charge exporters borrowing costs ranging from 5.5 per cent to as high as 8.5 per cent. Mukhtar said approximately Rs200 billion in concessionary financing went to yarn exporters, even though yarn is on the scheme’s negative list. Sugar exporters also received allocations despite operating in a regulated sector.

    Value-added garment producers that beat State Bank of Pakistan mandatory export volume targets by five to six times have been denied loans under the facility.

    Allocations miss export volume reality

    State planners increased credit allocations for small and medium enterprises by Rs300 billion, but industry groups say the qualification rules make the money unusable. Accessing that pool requires incremental export performance of Rs600 billion. Under current global demand patterns, that hurdle is unachievable.

    A previous SME export allocation of Rs100 billion lapsed unused during the prior fiscal year for the same reason. Mukhtar urged the central bank to rebalance credit distribution to match actual trade performance. The country’s top 100 exporters account for up to 60 per cent of total export volume.

    The decline in export trade volume is unprecedented,

    Mukhtar warned that only the most resilient operators will survive current conditions. Lost international retail accounts will prove difficult to recover once global apparel sourcing desks shift contracts elsewhere.

    Modernisation funding and ten-year strategy

    Seeking to prevent broader factory closures, the association proposed a targeted modernisation financing package of Rs140 billion for technological upgrades across four production segments. The plan allocates Rs20 billion each for cotton ginning and sizing, alongside Rs50 billion each for weaving and fabric processing.

    The funds would pay to balance, modernise, and replace aged machinery, deploy automation, and meet international buyers’ sustainability and resource-efficiency standards. Mill groups want the State Bank of Pakistan and the federal government to build this lending framework directly with trade bodies.

    Beyond emergency relief, the association called for a 10-year strategic export blueprint focused on industrial surplus capacity and structural competitiveness reforms. The immediate test is whether the central bank enforces the 4.5 per cent lending cap before second-quarter export data registers the projected downturn.

  • Bandai Expands Tamagotchi Licensing Across Asia Ahead of 30Th Anniversary

    Bandai Expands Tamagotchi Licensing Across Asia Ahead of 30Th Anniversary

    Japanese toymaker Bandai is expanding licensing partnerships for its Tamagotchi digital pet franchise across China and South Korea ahead of the device’s 30th anniversary next month.

    The Tokyo-based company is deploying the intellectual property across apparel, cosmetics and K-pop merchandise partnerships to build recurring revenue streams outside traditional toy hardware.

    Licensing Push Across Key Asian Markets

    Bandai’s regional push relies on third-party manufacturers and retail partners to adapt the egg-shaped digital pet identity into lifestyle categories. Instead of depending solely on standalone electronic device shipments, the company is licensing Tamagotchi character designs and branding to cosmetics producers, fast-fashion brands and entertainment agencies across East Asia.

    South Korea serves as a primary testbed for entertainment tie-ins, where collaborations with K-pop talent connect the vintage Japanese property with teenage and young adult demographics. In China, retail distribution leans heavily on character merchandise concessions and co-branded beauty collections aimed at millennial consumers who grew up with the original 1990s release.

    Shift from Hardware to Brand Royalties

    For toy manufacturers across Asia, hardware cycles carry inventory risk and seasonal sales volatility. Transitioning legacy electronic properties into multi-category licensing deals shifts capital requirements onto licensees while securing high-margin royalty streams for the parent company.

    Retail buyers and department store operators across Seoul and Shanghai gain proven nostalgia properties that drive foot traffic without requiring dedicated electronics shelf space. The primary commercial risk lies in overexposure, where indiscriminate brand placement across low-tier merchandise can dilute character value and shorten the commercial lifespan of anniversary campaigns.

    Building on Global Intellectual Property

    Japanese entertainment groups have steadily reoriented their international operations toward intellectual property monetisation. Bandai Namco Holdings has applied similar playbooks to its Gundam model kit franchise and video game properties, scaling retail pop-ups and branded apparel lines across mainland China, Taiwan and Southeast Asia.

    Tamagotchi first debuted in Japan in November 1996 before becoming a global consumer electronics phenomenon in the late 1990s. Bandai has revived the hardware line periodically with wireless and colour-screen iterations, but the latest regional campaign prioritises third-party consumer goods over device manufacturing.

    Milestones to Watch

    Commercial performance across the autumn retail calendar will show whether licensing revenue can sustain momentum beyond the initial anniversary marketing cycle. Bandai heads into the November 2026 anniversary window with additional Asian retail rollouts scheduled across specialty stores and regional e-commerce platforms.

  • Singapore Bakery Big Mouth Bakehouse Shuts Down Nine Months After Rebranding

    Singapore Bakery Big Mouth Bakehouse Shuts Down Nine Months After Rebranding

    Big Mouth Bakehouse has closed permanently nine months after rebranding. The shutdown ends a 13-year run that began under the Fluff Bakery brand.

    At its peak in 2015, the business sold more than 2,000 cupcakes a day. Rising costs and slowing sales later forced a retreat.

    Debt overhang cuts short the January comeback

    Founders Nursyazanna Syaira Mohammad Suhimi and Ashraf Alami launched Fluff Bakery in 2012 to fund their wedding. Strong social media demand led to a physical store opening in 2013. High daily sales of halal cupcakes quickly turned the shop into a staple for local dessert buyers.

    An expansion during the Covid-19 pandemic stretched resources. Heavy overheads and falling footfall forced the founders to shut Fluff Bakery in September last year, carrying unpaid obligations into their next venture.

    Product shift fails to offset operating costs

    The couple attempted a turnaround in January by reopening under the Big Mouth Bakehouse name. Their revamped menu moved away from standard cupcakes toward higher-ticket baked goods, including cakes, bomboloni and shio pan.

    Changing the menu did not generate enough cash flow to cover daily operating expenses and service old debt. By February, the founders were still struggling to clear liabilities accumulated during Fluff Bakery’s earlier expansion.

    Independent bakers face margin squeeze

    Independent food and beverage operators across Singapore face severe margin pressure from climbing ingredient prices, utility tariffs and commercial rents. When momentum cools, single-outlet shops rarely have the capital to absorb prolonged downturns.

    Rebranding without restructuring underlying debt rarely saves small bakeries. Drawing foot traffic in Singapore’s dining corridors demands heavy promotional spending, which punishes boutique shops that lack bulk purchasing power.

    The final exit after thirteen years

    On Instagram, the owners confirmed the closure and said conditions could no longer be managed.

    “Sometimes, despite your best efforts, things happen that are simply beyond your control,” the business said.

  • China’s 20% Tax Crackdown Piles Pressure on Luxury Brands

    China’s 20% Tax Crackdown Piles Pressure on Luxury Brands

    China’s 20 per cent tax crackdown on wealthy individuals has become the latest headache for luxury brands ahead of third-quarter financial results. Under Beijing’s new rules, affluent citizens who used offshore trusts to shelter assets have until October 22 to declare and pay years of back taxes, threatening spending in a market that generates roughly a fifth of global luxury purchases.

    Shares in LVMH and Birkin bag maker Hermes are both down about 40 per cent this year near multi-year lows, while Gucci owner Kering has fallen 29 per cent. Summer shopping mall data in mainland China pointed to a sharp deceleration in growth, according to Bernstein analysts.

    Tax Deadlines and Retail Liquidity

    The 20 per cent levy is hitting spending by ultra-high-net-worth individuals, a tier that had previously proved more resilient than middle-class consumers affected by China’s prolonged property downturn. Alexis Bonhomme, head of Shanghai-based luxury consultancy Trinity Asia, noted that some shoppers face short-term liquidity constraints before the compliance window closes.

    “Until the deadline to pay the tax, some people may face liquidity issues”, Bonhomme said. “This doesn’t mean they won’t start buying again, but right now, the mood just isn’t there,” he added.

    Quiet Luxury Pulls Ahead in Mall Aisles

    Two industry sources familiar with third-quarter mall trading in mainland China said overall conditions remained weak, although performance varied widely between brands. Smaller “quiet luxury” labels such as cashmere specialist Brunello Cucinelli and LVMH’s Loro Piana are outperforming more conspicuous brands such as Louis Vuitton and Gucci.

    High-end jewellery remains a bright spot. Brands such as Richemont’s Cartier have benefited as wealthy consumers increasingly favour gold and precious materials, which are viewed as offering more enduring value.

    Global Headwinds Compound Asia Weakness

    The slowdown in China comes as luxury demand softens in the United States, the industry’s largest market. US credit card spending on luxury goods tracked by Citi fell for a third consecutive month in September as consumer confidence weakened ahead of midterm elections.

    Luxury houses are also grappling with fallout from the Iran war. Kering has already warned analysts to expect a further contraction at Gucci, prompting brokerages to cut their stock price targets.

    Earlier Strains and Upcoming Earnings

    The $350 billion luxury sector remains mired in a three-year slowdown after pandemic-era demand weakened. In downtown Beijing, Deng Qi, an exporter of ceramic building components, forecast 20 per cent less luxury spending than in previous years, warning that the offshore tax measures undermine confidence across the broader wealthy demographic.

    Investors will receive their first read on the sector when LVMH reports results on Monday, with analysts forecasting quarterly sales of €18.5 billion ($20.7 billion), up 1 per cent from a year earlier. Kering and Hermes report their quarterly performance on October 22.

  • Nine in 10 APAC Consumers to Reconsider Buying from Unsustainable Brands

    Nine in 10 APAC Consumers to Reconsider Buying from Unsustainable Brands

    Around nine in ten consumers across Asia-Pacific plan to stop or reconsider buying from retail brands that fail to prioritise sustainability, Retail Asia reported this week. The regional consumer shift places immediate pressure on consumer goods makers and store operators across major regional markets.

    Shoppers across key Asian metropolitan centres increasingly treat environmental performance as a basic buying criterion rather than an optional marketing feature. Brands that delay operational changes face direct volume losses as regional consumers switch to competitors with transparent practices.

    Shifting Consumer Spending Priorities

    Consumer sentiment across Asia-Pacific retail channels demonstrates a sharp reduction in patience for businesses without visible sustainability targets. Retailers that treat environmental initiatives as secondary risk losing significant portions of their regular customer base.

    The shift affects everyday grocery, apparel, personal care and packaged food categories where substitution is straightforward. In these segments, switching costs remain low and shoppers actively look for clear evidence of responsible sourcing.

    Commercial Risk for Retail Operators

    For store operators and brand owners, customer churn driven by environmental practices creates a direct revenue threat. Retailers operating in competitive urban centres cannot afford to alienate large shares of their shoppers when customer acquisition costs remain elevated.

    Suppliers across regional retail ecosystems must adapt packaging, raw material sourcing and logistics networks to retain shelf placement. Retail chains are increasingly aligning their merchandise assortments with consumer demand for verifiable sustainability credentials.

    Supply Chain and Sourcing Demands

    Consumer pressure now travels directly up the retail supply chain to manufacturers, packaging suppliers and distribution partners. Operators that fail to audit their supply lines face reputational pushback from shoppers who demand accountability across product lifecycles.

    Regional manufacturers that modernise factory operations and reduce waste gain an immediate commercial advantage with retail category buyers. Suppliers slow to provide sustainability disclosures risk removal from mainstream store networks.

    What Retailers Face Next

    Retail networks across the region must balance the capital expense of operational overhauls against the clear cost of customer attrition. Brands that integrate environmental measures directly into product development and store operations will protect market share as consumer criteria tighten across Asia-Pacific.

  • Indonesia Seeks Bigger Role in Asia-Pacific Retail Industry

    Indonesia Seeks Bigger Role in Asia-Pacific Retail Industry

    Indonesia is pushing to expand its footprint and secure a bigger role in the Asia-Pacific retail sector through deeper regional trade ties and cross-border commercial partnerships, ANTARA News reported. The domestic market of over 275 million people remains Southeast Asia’s largest consumer base, giving local operators use as they seek wider influence across regional supply networks.

    Indonesian retailers face direct competition from established operators in Thailand, Malaysia, and Singapore that expanded regional store footprints years ago. Building outward reach requires Indonesian brands to match international standards in supply chain management, inventory systems, and omnichannel fulfillment.

    Cross-border retail expansion across Southeast Asia depends heavily on bilateral trade arrangements and synchronized customs protocols ahead of planned rollouts over the coming fiscal quarters. Indonesian commercial groups want local consumer brands to gain wider shelf space in neighboring shopping centers and digital platforms.

    Regional Trade Integration

    Regional retail groups operate with sophisticated logistics hubs in places like Singapore and Bangkok. Indonesian operators must upgrade warehouse automation and freight links to compete effectively on delivery speed and product freshness.

    Digital Commerce and Store Networks

    Modern trade in Jakarta and secondary Indonesian cities combines physical hypermarkets, convenience store chains, and online commerce. Expanding that model into regional markets requires significant capital commitments from Indonesian conglomerates.

    Foreign retail brands continue to enter Indonesia, attracted by the country’s population of over 275 million people. Local retail groups now aim to reverse that dynamic by exporting homegrown retail concepts, packaged food brands, and lifestyle chains across Southeast Asia.

    Capital Allocation and Expansion Risks

    Entering overseas markets exposes Indonesian retail companies to foreign exchange volatility, varying labor regulations, and shifting local consumer preferences. Capital that goes toward foreign expansion could otherwise fund domestic store rollouts in underserved Indonesian provinces outside Java.

    Landlords and mall developers across Southeast Asia demand proven sales records before offering prime retail space to foreign newcomers. Indonesian brands will need to prove strong unit economics before securing competitive lease terms in prime shopping districts.

    Monitoring the Next Regional Steps

    Indonesian industry associations plan to increase participation in regional retail forums and trade delegations to establish partnerships with overseas distributors. Bilateral retail partnerships and franchise agreements will serve as the primary vehicle for initial store rollouts outside the home market.

    The pace of cross-border expansion depends on regulatory approvals, brand registration timelines, and formal franchise agreements signed over the coming fiscal quarters.

  • Google Defends US$15 Billion Indian AI Data Hub Against Community Scrutiny

    Google Defends US$15 Billion Indian AI Data Hub Against Community Scrutiny

    Google is pushing forward with a US$15 billion artificial intelligence data centre hub in Visakhapatnam despite community protests over power grids and water supplies in southern India.

    The gigawatt-scale development represents the search giant’s largest AI infrastructure project outside the United States and is scheduled to enter service in 2028.

    Local groups and environmental activists in Andhra Pradesh have called for a blanket moratorium on data centre construction across the state until authorities assess collective ecological impacts. The development footprint spans construction sites at Tarluvada village and Rambilli in the Anakapalli district, placing heavy computing loads in an area already experiencing water stress.

    Air Cooling Replaces Freshwater Systems

    Google altered its baseline engineering for the campus after pre-development studies identified acute pressure on the surrounding watershed. The facility will rely on advanced air cooling instead of evaporative water cooling towers to chill server racks, avoiding the millions of litres of daily freshwater extraction typical of large-scale server farms.

    Facility maintenance and non-cooling operations will still draw municipal water. The company has pledged to replenish 120 per cent of the volume consumed by non-cooling facility needs across its operational footprint by 2030.

    Grid capacity presents a parallel bottleneck. While Google declines to publish site-level electricity numbers, company executives state that the group pays for all necessary grid substation and transmission upgrades upfront while funding local renewable energy projects above statutory quotas.

    Subsea Cabling and Regional Edge Networks

    Visakhapatnam offers direct coastal access for international subsea fibre connections linking India to landing stations in Australia and South Africa. That routing establishes Andhra Pradesh as India’s third core subsea landing hub alongside Mumbai and Chennai, giving enterprise networks faster bandwidth to Southeast Asia and Indian Ocean routes.

    Hyperscale cloud operators across the Asia-Pacific region face rising friction over energy allocations. Authorities in mature data hub markets like Singapore have enforced strict sustainability caps, while Finnish regulators recently suspended construction on two Google sites pending mandatory environmental assessments. Digital platforms rolling out enterprise AI models across Asia must now compete directly with residential populations and manufacturing zones for grid access.

    For enterprise software vendors, regional retailers and cloud customers, infrastructure constraints in primary metros make secondary coastal hubs essential. Yet when global operators cluster in emerging tier-two corridors, they import the same resource disputes that delayed builds in Western Europe and Southeast Asia. The financial exposure rests with regional governments that offer tax concessions before local utilities can guarantee steady baseload power.

    Economic Payoffs and Local Employment

    Data centre developments generate large short-term construction payrolls but run with lean permanent staff once servers go live. Google estimates the Visakhapatnam hub will support approximately 4,200 construction workers annually across a three-to-five-year build cycle.

    Company projections place the recurring economic contribution at US$688 million each year through supply chain activity, facility services and maintenance contracts. Alexander Smith, Google’s head of infrastructure and energy for the Asia-Pacific region, defended the long-term community footprint during project reviews.

    “For every job inside a Google data centre we support nine additional jobs in the surrounding community,” Smith said.

    Andhra Pradesh state planning officials must now review activist petitions demanding an environmental audit before granting additional clearances for companion tech facilities scheduled for the same coastal corridor.

  • Vietnam and Cambodia Trade Hits $8.7B as Both Nations Eye $20B Target

    Vietnam and Cambodia Trade Hits $8.7B as Both Nations Eye $20B Target

    Bilateral trade between Vietnam and Cambodia reached 8.7 billion dollars in the first eight months of 2026. That represents an 8.3 percent increase year on year.

    The pace keeps both governments on track toward their target of 20 billion dollars in annual trade. Last year, bilateral trade reached a record 11.3 billion dollars.

    Vietnamese Customs figures show exports to Cambodia rose 13.8 percent to 4.3 billion dollars between January and August. Imports from Cambodia reached 4.4 billion dollars, up 3.4 percent over the same period. Vietnam currently ranks as Cambodia’s third-largest trading partner, its second-largest supplier of imported goods, and its second-largest export destination.

    Supply Chains and Commodity Flows

    Factories in Vietnam supply Cambodia with industrial inputs and finished goods, including textiles, garments, steel, footwear components, fertilizer, animal feed, paper products, plastics, and industrial machinery. Cambodia sends agricultural commodities and raw inputs back across the border. Shipments to Vietnam concentrate in 14 primary product categories, led by cashew nuts, natural rubber, cassava, rice, timber, fresh produce, and textile materials.

    The flow reflects an integrated supply chain rather than simple merchant trade. Cambodian farms provide raw commodities. Vietnamese processors then package and distribute those goods through domestic retail networks or export them overseas. Linking Cambodia’s agricultural base with Vietnam’s processing capacity and transport network yields higher margins than raw trade alone.

    Investment Capital and Manufacturing Footprint

    Companies from Vietnam hold 223 registered investment projects in Cambodia, representing nearly 3.4 billion dollars in committed capital. These ventures span agriculture, manufacturing, and telecommunications. Together, they employ tens of thousands of workers in Cambodian border provinces and industrial hubs.

    Cross-border manufacturing helps firms diversify production risks while keeping freight costs below distant East Asian supply routes. However, regulatory differences remain a hurdle. Customs procedures, technical standards, and clearance speeds still differ across the frontier.

    Transport Links and Border Infrastructure

    Border infrastructure has expanded to handle heavier commercial freight. Officials opened the Khanh Binh-Chrey Thom international border gate on October 3, 2026, linking Vietnam’s An Giang province directly with Cambodia’s Kandal province. That followed the late 2025 opening of the Meun Chey-Tan Nam crossing between Tay Ninh and Prey Veng.

    Planners now focus on connecting the Ho Chi Minh City-Moc Bai expressway to the Bavet-Phnom Penh expressway corridor. The highway link will cut transit times between southern Vietnamese ports and the Cambodian capital. It will also reduce freight rates and support industrial park development along the route.

    Policy Alignment at the Executive Level

    Government leaders reviewed economic ties at the Vietnam-Cambodia Business Forum in Phnom Penh on October 9, 2026. Vietnamese Prime Minister Le Minh Hung and Cambodian Prime Minister Hun Manet agreed to review trade pacts and eliminate border clearance bottlenecks.

    Negotiators will meet again before year-end to review cross-border trucking permits and customs data exchange protocols.

  • Netflix Expands Asia Production Budgets and AI Tools to Tackle Talent Bottlenecks

    Netflix Expands Asia Production Budgets and AI Tools to Tackle Talent Bottlenecks

    Netflix deployed artificial intelligence across 300 titles as it expanded production spending in Japan to bypass local network constraints. Company executives confirmed the strategy in October 2026.

    The streaming platform offers higher budgets and longer development schedules than domestic terrestrial broadcasters to secure original projects in Tokyo. That spending push culminated in the September 17 debut of “Plastic Beauty”, an eight-episode drama probing Japan’s cosmetic surgery sector produced under content executive Shin Takahashi.

    Takahashi served as executive producer on the series. Netflix aims to commission local stories that traditional networks avoid, but an acute shortage of technical production crew across Japan continues to limit project turnaround times.

    Deploying Artificial Intelligence Across 300 Productions

    To ease scheduling bottlenecks and rein in technical costs, the streaming service embedded artificial intelligence workflows across roughly 300 productions in its global catalog. Lee Sung-gyun, senior director of APAC production at Netflix, detailed the deployment at the Busan International Film Festival during an industry panel co-hosted with the Motion Picture Association.

    “Across around 300 Netflix titles, AI has actually been put to use in various ways,” Lee said. Crew teams apply machine learning to pre-visualization, concept art for production design, advance set dressing, editorial assembly, and visual effects.

    Eyeline, the proprietary visual effects studio owned by Netflix, demonstrated the technology. The studio runs hybrid production pipelines that blend live-action photography with generative digital tools. On the Netflix India title “Glory”, production teams used generative visual effects to build extensive crowd sequences that tight delivery dates would have otherwise eliminated.

    Production Cost Pressures and Talent Shortages

    Rising production expenses in Asia force entertainment operators to rethink line-item budgets. In Seoul, director Kang Yoon-sung estimated that generative tools cut 30 percent to 40 percent off standard feature budgets during pre-production testing on his naval action project “The Gulf of Aden”. Kang tested software from Chinese vendor Kling to output high-resolution footage at 4K resolution and 10-bit color, simplifying physical shooting schedules.

    For consumer platforms and production partners across Japan and South Korea, cost deflation at the technical layer shifts commercial use toward intellectual property owners. Studios adopting hybrid generative tools can greenlight complex scripts that previously failed financing hurdles. The bottleneck in Tokyo remains physical labour rather than capital, as terrestrial networks and streaming operators compete for a finite pool of directors, editors, and camera operators.

    Traditional Japanese networks operate on compressed broadcast cycles with lean budgets, leaving little margin for extended post-production. Long production runs bankrolled by streamers differentiate subscription products, but prolonged filming schedules tie up scarce local crew for months at a time.

    Building Out Original Regional Content

    Platform expansion follows a multi-year effort by streaming services to lock down proprietary Asian programming. In October 2025, Kang released “Run to the West”, billed as South Korea’s first feature to apply artificial intelligence across its full production run, co-directing with Kwon Han-seul to replace standard computer graphics.

    Streaming operators across the Asia-Pacific region now treat local drama as their primary customer acquisition engine. Netflix, Disney+, and local rivals continue to bid up regional script rights while investing in technical training workshops through programs such as Creative Asia.

    Next Steps for Asian Production Pipelines

    Netflix is monitoring viewer retention and completion data for “Plastic Beauty” to calibrate its next slate of Japanese live-action commissions. The company plans further technical demonstrations of its Eyeline hybrid visual effects pipeline at regional trade events through late 2026, targeting broader adoption among Japanese and South Korean production partners.

  • Japan Raises Permanent Residency Fees to ¥200,000 and Tightens Rules

    Japan Raises Permanent Residency Fees to ¥200,000 and Tightens Rules

    Japan raised its permanent residency fee to ¥200,000 on Oct. 1, tightening financial screening and retroactive compliance checks for foreign workers across the country.

    The administrative charge represents a twentyfold increase from the previous ¥10,000 fee, taking effect alongside aggressive audits of tax and social security history.

    Under updated guidelines from the Immigration Services Agency, examiners now evaluate five consecutive years of earnings against average Japanese household benchmarks. Officials are also applying these heightened standards retroactively to pending applications submitted as far back as April 2026. Tokyo processing times have expanded to between 18 and 24 months, up from approximately one year during the pandemic.

    Tighter Audits on Taxes and Income

    Immigration screeners have shifted toward strict fault-finding across pension records and health insurance contributions. A single missed payment or late local tax filing during job transitions now leads to outright refusals unless applicants maintain a clean record for at least two consecutive years before filing. The revised policy also requires children of applicants to attend elementary and junior high schools, creating uncertainty for families enrolled in unaccredited international schools or alternative educational programs.

    Job mobility carries new operational risks for foreign professionals awaiting decisions. Leaving an employer to establish an enterprise or shifting to self-employment changes the underlying visa qualification, triggering immediate grounds for denial under the revised framework. Statutory financial exemptions remain intact only for spouses and children of Japanese nationals or existing permanent residents.

    Talent Pressures for Employers and Startups

    Multinational companies and local technology ventures face higher hurdles in retaining senior overseas specialists who rely on permanent status for long-term stability. While regional hubs such as Singapore and Hong Kong maintain defined scoring systems or rapid employment pass routes, Tokyo’s discretionary thresholds complicate corporate talent planning. Startups employing foreign founders or contract specialists now face increased friction when hiring talent away from legacy corporate sponsors.

    Foreign workers in retail, consumer tech, and financial services often use permanent residency to secure residential mortgages and escape restrictive employer visa renewals. The higher fee burden and lengthy review periods force mid-career professionals to delay career changes or self-employment plans. Legal specialists handling visa petitions report standard administrative scrivener fees ranging between ¥100,000 and ¥200,000 per case, pushing total application costs past ¥400,000 for complex corporate filings.

    Shifting Timelines and Policy Steps

    The October policy revision follows months of administrative adjustments by the Justice Ministry aimed at tightening oversight of foreign resident documentation. Earlier statutory frameworks permitted five-year residency pathways for naturalization, which required Japanese language tests, while ten-year permanent residency routes historically omitted language testing. Tokyo immigration offices have begun warning applicants that discretionary approvals based purely on high base salaries without spotless compliance histories are no longer standard practice.

    Screening criteria will tighten further in April 2027, when the Immigration Services Agency introduces mandatory Japanese language proficiency standards for all standard permanent residency filings.