Blog

  • TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop generated US$15.1 billion in gross merchandise value across the United States in 2025, up 68 per cent from the previous year, according to data from Momentum Works.

    The expansion established the platform as a major cross-border sales channel for Chinese manufacturers and domestic sellers, defying regulatory pressure and intense competition from Amazon and Temu. ByteDance built the platform by merging creator live streams and algorithmic product discovery into a direct checkout experience that bypasses traditional search-based retail.

    Expanding Across Core Retail Categories

    Fashion, beauty, and consumer electronics drove the bulk of U.S. Order volumes through short-form video links and creator storefronts. Lower take rates and subsidized shipping helped recruit thousands of merchants who previously depended solely on Amazon Seller Central.

    Supply chain infrastructure handled larger fulfillment runs through partnered logistics networks in California and Texas. The platform shortened delivery windows for local inventory while maintaining discounted direct air-freight routes from hubs in Shenzhen and Yiwu.

    The Content Commerce Blueprint in Asia

    ByteDance perfected this shopping model across Southeast Asia before scaling it westward. Regional content commerce across Southeast Asian markets is on track to reach US$77.9 billion in 2026 as Shopee and Lazada roll out competing live video formats.

    In Indonesia, Vietnam, and Thailand, social video transactions now account for a double-digit share of total online retail spending. Regional logistics networks adjusted their sorting hubs to manage high-volume, low-ticket parcels generated during evening live stream flash sales.

    Competition and Regulatory Targets

    Temu, operated by PDD Holdings, continues to fight for identical budget-conscious consumer dollars with aggressive discount coupons and gamified referrals. Meanwhile, Sea Limited’s Shopee invested heavily in creator incentives across Southeast Asia to defend its core market leadership against ByteDance.

    Merchants face rising advertising costs on the platform as competition for feed placement stiffens. RetailNews Asia tracks whether TikTok Shop can maintain its merchant retention rates through the 2026 holiday shopping cycle while targeting US$20 billion in North American sales.
  • Thailand Water Heater Sales Face 10% Drop as Property Market Slows

    Thailand Water Heater Sales Face 10% Drop as Property Market Slows

    Thailand’s water heater market will shrink by 10 per cent this year. Weak consumer spending and a property glut have stalled home equipment purchases.

    The drop follows a 2025 market valuation of 3.3 billion baht. Regional appliance makers must now lean harder on overseas shipments and replacement fittings. High household debt and tighter urban budgets have pushed shoppers to delay non-essential bathroom upgrades. Meanwhile, an oversupply of unsold homes across Bangkok and neighbouring provinces has choked off bulk orders from residential developers.

    Property Slump Curbs Domestic Demand

    Stiebel Eltron Asia runs three production facilities in Thailand and targets 1.4 billion baht in sales revenue this year despite the slump. Domestic sales make up 77 per cent of that target. Exports provide 21 per cent, while original equipment manufacturing accounts for the remaining 2 per cent. The German manufacturer aims for 2 per cent annual revenue growth by redirecting commercial teams toward home renovations, online retail and new product launches.

    Rising costs have compounded the domestic slowdown. Industrial copper prices climbed alongside electricity tariffs tied to Middle East tensions, driving up per-unit manufacturing costs at local assembly plants. Retail suppliers across Southeast Asia face similar margin squeezes. In response, hardware distributors are trimming inventory holding times and demanding faster stock turnarounds from brand owners.

    Export Buffer Across Southeast Asia

    Foreign markets offer vital relief for factories based in Thailand. Stiebel Eltron ships appliances across the Asia-Pacific region, led by volume shipments to Indonesia, Vietnam and the Philippines. Expanding distribution agreements across ASEAN helps protect regional production lines when domestic housing absorption stalls.

    Competitors in Southeast Asia have taken a similar approach. They balance domestic factory capacity against export demand to keep plant utilisation rates high. Weak Thai consumer credit drove the shift. Brands that once relied on Bangkok condominium handovers must now compete directly for retail shelf space and e-commerce baskets in faster-growing developing markets.

    Weather Takes a Back Seat to Debt

    Climate patterns are also playing a role. In August, the Thai Meteorological Department warned that developing El Nino patterns would drive temperatures above normal through November. Hotter weather traditionally dampens water heater adoption in tropical markets. Even so, factory chiefs view macroeconomics as the real drag on consumer behaviour.

    “In general, I worry more about the economy than the weather,” said Roland Hoehn, chief executive of Stiebel Eltron Asia.

    Manufacturers are now rolling out revised product catalogues for the final quarter, testing whether renovation demand can deliver the 1.4 billion baht revenue benchmark before year-end.

  • Papua New Guinea Ready to Issue 5G Licences in 2.6 GHz and 3.5 GHz Bands

    Papua New Guinea Ready to Issue 5G Licences in 2.6 GHz and 3.5 GHz Bands

    Papua New Guinea’s National Information and Communications Technology Authority (NICTA) is ready to issue 5G spectrum licences in the 2.6 GHz and 3.5 GHz bands to qualified mobile operators.

    The regulator established the framework after completing legal, technical, and market assessments, clearing both frequency bands for concurrent 4G and 5G service rollouts across the country.

    Universal Access and Coverage Obligations

    Licence conditions require operators including Vodafone PNG and Digicel PNG, which completed readiness testing in July, to extend 4G coverage to 20 new sites under the Universal Access and Service Program.

    Under the mandate, carriers cannot confine capital expenditure solely to high-yield cities. Operators must absorb the cost of widening base connectivity across remote provinces while commercialising premium data speeds.

    Carrier Timelines and Network Commitments

    Vodafone PNG pledged to activate 5G services in the National Capital District and at least one additional city within 18 months of licensing. It committed to covering 20 per cent of the national population within 36 months. That expands to 30 per cent within 60 months.

    Digicel PNG confirmed technical preparedness ahead of the awards, completing end-to-end 5G network trials on its existing architecture. Competition between the two operators now shifts toward high-capacity broadband links and enterprise digital connectivity rather than basic voice and mobile data pricing.

    Wider Spectrum and Satellite Reforms

    Planning reviews and technical alignment with international telecommunication standards preceded the release. Digicel established its local network readiness during testing in July. Hardware installation can begin as soon as authorities formally execute the frequency grants.

    Regulators will monitor rollout milestones and enforcement across both assigned bands. Next, the authority will draft allocation policies for additional high-demand spectrum, satellite-delivered non-terrestrial network services, and unlicensed frequency bands for public Wi-Fi infrastructure.

  • Heavy Pop Brings Vietnamese Streetwear to Siam Discovery in Bangkok

    Heavy Pop Brings Vietnamese Streetwear to Siam Discovery in Bangkok

    Vietnamese fashion platform Heavy Pop opened a pop-up store inside Bangkok’s Siam Discovery mall this September. It brings domestic streetwear brands to Thai consumers.

    Labels including Stressmama, DirtyCoins and Hades now sit on the complex’s first floor. Together, the Thai and Vietnamese streetwear markets represent an estimated $1 billion to $2 billion in value.

    Heavy Pop operates without permanent stores. Instead, the curator secures short-term space in busy regional hubs to show Hanoi and Ho Chi Minh City labels. Its Bangkok floor features graphic T-shirts, relaxed shorts and oversized hoodies.

    Contrasting aesthetics drive mall demand

    Mall operator Siam Piwat is dedicating square footage across Siam Discovery, Siam Center, Siam Paragon and Iconsiam to emerging regional brands. It avoids relying solely on global chain tenants. The Vietnamese apparel provides a dark contrast to domestic Thai streetwear, which leans toward vibrant colours, internet memes and Muay Thai boxing references.

    Both markets design for tropical heat with boxy silhouettes and gender-neutral cuts. Streetwear across Asia-Pacific continues to outperform broader retail benchmarks. Fortune Business Insights values global sector revenue at nearly $398 billion in 2026, alongside a projected 7.95 per cent annual growth rate through 2034.

    Regional platforms step in where Western retailers lag

    Landlords gain foot traffic from younger shoppers hunting for limited drops. For the brands, physical floor space in Bangkok offers an essential international testing ground. Western retail chains still lack the direct supply-chain connections to distribute niche Asian streetwear profitably.

    Production scale remains the primary operational bottleneck. Vietnamese streetwear houses maintain brand equity through small, exclusive production runs. That prevents them from fulfilling wholesale inventory minimums required by global department stores or scaling beyond direct-to-consumer e-commerce.

    Siam Piwat accelerates regional brand incubation

    Curated retail initiatives are expanding across Siam Piwat properties. Alongside the Heavy Pop installation, Siam Discovery added ground-floor spaces this month for Vietnamese womenswear labels Cocosin and Mollynista.

    The pop-up runs at Siam Discovery through the end of September 2026. Tenant turnover will follow ahead of fourth-quarter holiday trading.

  • China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China’s physical retailers are retooling floor space into leisure and entertainment hubs to counter entrenched price competition as Beijing targets $8.94 trillion in annual consumer sales by 2030.

    First-half retail sales reached $3.7 trillion, but Bain & Company partner Weiwen Han warns the market will stay muted over the next three years as discounting continues to squeeze operating margins across shopping centres and supermarket chains.

    Experience Costs and Margin Pressures

    Official policy guidelines urge store operators to blend standard shopping with immersive dining, social spaces, and entertainment. The strategy shifts the industry away from chasing raw foot traffic toward extracting higher margins from shoppers who do enter. Transforming selling space into experience zones raises the fixed cost per square metre, penalising operators whose foot traffic fails to convert at the cash register.

    The policy combines experience-led flagships in commercial districts and transit hubs with neighbourhood infrastructure upgrades dubbed 15-minute life circles. These local clusters focus on daily essentials through convenience stores, supermarkets, and wet markets.

    Digital Convergence and Supply Chains

    Pure physical retail has ceased to exist in the Chinese market. With online sales of physical goods rising 4.8 per cent year to date compared to 1.3 per cent growth for total retail sales, shoppers routinely compare shelf prices against live e-commerce listings on their phones within seconds.

    Instead of trying to defeat digital platforms on pricing, operators are adopting automated inventory systems, drone delivery, and private-label merchandise. Developing proprietary private-label lines allows chains to offer price value directly without slashing headline gross margins on national brands.

    “They are asking stores to be worth visiting for reasons beyond price,” said Jotham Lim, head of global marketing at Beijing Taomi Technology Co. Ltd.

    Winners and Structural Consolidation

    Mid-sized domestic grocery, convenience, and food and beverage operators stand to gain the most from planned regional deregulation, which removes long-standing barriers preventing chain retailers from expanding across provincial borders. Independent single-store merchants face steep hurdles absorbing the capital expenditure required for digital traceability and store fit-outs, accelerating industry consolidation into regional chains.

    Financing rules now allow qualifying retail operators to raise capital through asset-backed securities and commercial real estate investment trusts, alongside interest subsidies from commercial banks. Landlords and property-owning retailers can tap these vehicles to fund store refits without burning operating cash flow.

    The retail sector entered this transition carrying heavy overcapacity in commercial floor space following decades of rapid mall construction across second- and third-tier cities. Moojing Market Intelligence recorded a steady increase in consumer discussions regarding in-store price checking against e-commerce platforms between the first half of 2024 and the first half of 2026.

    Market operators now face the rollout of regional licensing reforms and the government target to lift retail sales from ¥24.87 trillion to ¥60 trillion over the next four years.

  • Heytea Expands US Footprint with Philadelphia Store as Chinese Chains Scale Up

    Heytea Expands US Footprint with Philadelphia Store as Chinese Chains Scale Up

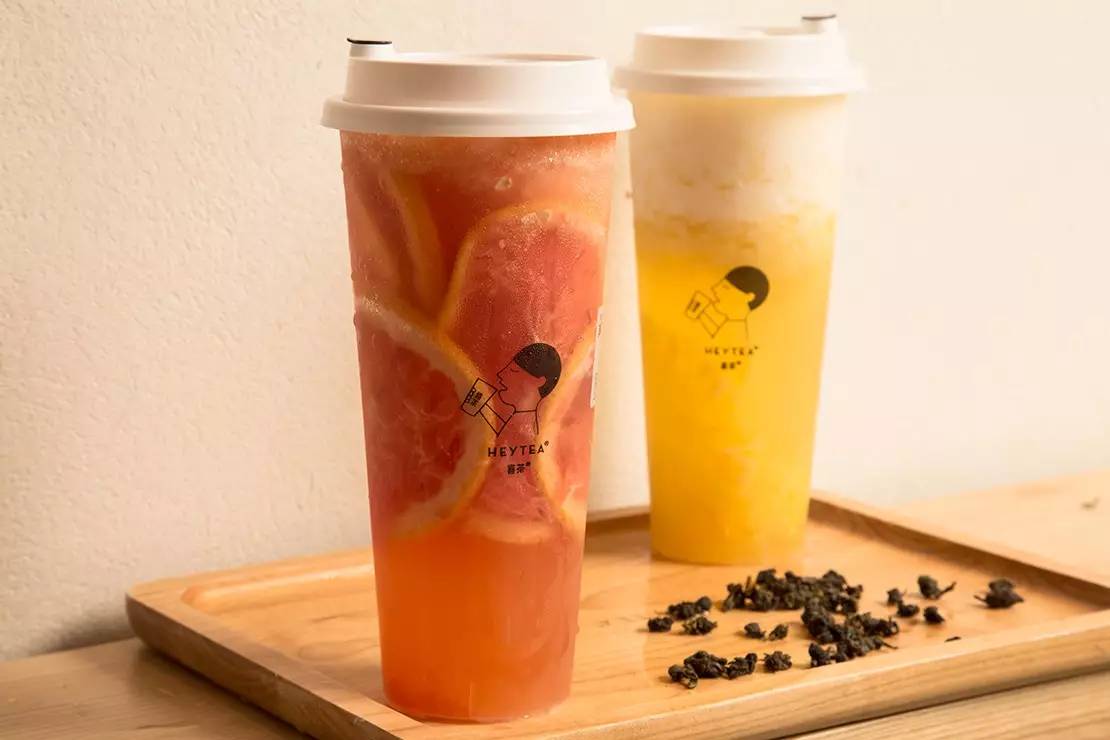
    Staff deployed crowd-control barriers at 10th and Arch Streets as Heytea opened its first Philadelphia store. Lines for its chilled fruit teas stretched down the block.

    Headquartered in Shenzhen, the chain operates more than 4,000 stores worldwide. It sells drinks like King Jasmine Guava tea for $7.99 while ramping up its international footprint.

    That debut follows a launch on New York’s Upper West Side weeks earlier. Heytea press representative Yinnan Shen said more than 600 people lined up across three city blocks for that opening. Founded in Guangdong in 2012, the company specialises in what it calls new-style tea. It blends brewed whole-leaf tea with fresh fruit rather than powdered mixes.

    Challenging the First Generation of Boba Retailers

    This expansion reflects a broader shift across North American beverage retail. Scaled mainland Chinese operators are pushing past first-generation Taiwanese bubble tea concepts. Early entrants like Vivi Bubble Tea, Kung Fu Tea, and Mr. Wish established US footprints between 2015 and 2017, alongside Gong Cha, Chi Cha San Chen, and Tiger Sugar. Most of those networks operate between 80 and 300 locations globally. That leaves them exposed to rivals backed by deeper capital and larger supply chains.

    Mainland brands rely on industrial throughput and heavy digital marketing. Smaller franchise networks and independent operators now face rising rents across prime Chinatown strips. In those corridors, quick-service and beverage chains continue to displace legacy family restaurants, pharmacies, and dry goods merchants.

    The Scale Race Led by Chinese Coffee and Tea

    Scale gives these mainland chains their chief advantage. Luckin Coffee entered Manhattan in 2025 and already operates 25 outlets in New York City out of 36,310 stores globally. Its buyout of specialty roaster Blue Bottle earlier this year strengthened that network. Budget rivals Cotti Coffee and Mixue run more than 18,000 and nearly 60,000 global stores respectively. Both entered New York in 2025.

    Western cafe chains build around seating and customer dwell time. By contrast, these Chinese operators design compact stores for fast mobile app pickups. High transaction volume and lean store footprints allow them to absorb steep urban rents.

    Franchise Proliferation Across East Coast Hubs

    Standardised franchise systems are multiplying across the East Coast. Over the past twelve months, Philadelphia has absorbed a string of mainland franchise concepts. Arrivals include dessert and snack operators Kyo Matcha and Yin Ji Rice Roll, alongside yogurt drink chain Hey I Am Yogost.

    Taiwanese brands spent the past decade establishing Asian tea across Western metropolitan centres. Now, mainland competitors are testing whether volume models built in tier-one Chinese cities can generate profit on expensive American real estate.

    Heytea is scouting further locations across the US Northeast corridor. Future sites will target high-density student and commercial districts in New York and Pennsylvania.

  • Heineken Malaysia Cuts Brewery Emissions 45 Percent and Replaces Secondary Plastic

    Heineken Malaysia Cuts Brewery Emissions 45 Percent and Replaces Secondary Plastic

    Heineken Malaysia cut production emissions by 45 percent at its Sungei Way brewery against a 2022 baseline. On-site solar generation and renewable grid procurement drove the reduction.

    The brewer took top honours in two categories at the ESG Positive Impact Awards 2025. It recycled all 35,637 tonnes of its production waste and eliminated 195 tonnes of single-use packaging plastic.

    Sungei Way Brewery Energy and Water Overhauls

    Power for the Petaling Jaya facility now comes entirely from renewable sources via Tenaga Nasional Berhad’s Green Electricity Tariff programme. An array of 3,500 rooftop solar panels adds roughly 2,600 megawatt-hours annually. For heat, the site relies partly on an upgraded wastewater treatment plant. That RM7 million facility captures biogas during effluent processing to supply approximately 4 percent of thermal requirements.

    Water management forms the other major capital focus at the site. Using flow meters, equipment overhauls and recycling loops, the brewer improved water efficiency by 36 percent compared with 2014 levels. Independent auditor LimnoTech verified the results. In 2025, the company hit 221 percent of its targeted water balancing volume, returning more treated water to the watershed than its operations consumed.

    Value Chain Pressures for Regional Brewers

    Breweries across Southeast Asia face tougher scrutiny from institutional investors and retail off-trade buyers over Scope 3 supply chain footprints. Malaysian beverage makers must balance high excise duties against the capital expenditure needed to electrify thermal brewing. Decarbonising industrial heat remains difficult. To cut upstream emissions, Heineken brought 40 tier-one suppliers into the UN Global Compact’s ESG Start programme, pushing compliance down to local packaging and logistics vendors that lack dedicated sustainability budgets.

    Competitors like Carlsberg Malaysia and Thai Beverage are deploying similar resource reduction programmes to protect operating margins against rising industrial water tariffs and volatile power costs. Packaging penalties loom for laggards. Grocery chains now demand certified recycled content and paperboard alternatives. The steepest financial risk sits in thermal energy replacement: replacing remaining fossil fuel boilers requires heavy capital that cannot be offset by rooftop solar alone.

    Tracking Circularity and Watershed Protection

    At the Sungei Way site, operational adjustments build on long-term capital investments. Heineken Malaysia has routed zero production waste to landfill since 2017. The site sends organic outputs like spent brewing grains into animal feed and agricultural upcycling streams. For packaging, the company switched secondary can wraps from shrink plastic to paperboard, cutting single-use plastic across retail channels.

    Community watershed investments run alongside the plant works. The SPARK Foundation, the brewer’s corporate responsibility arm, has spent more than RM16 million since 2007 on peatland restoration, rainwater harvesting installations and river rehabilitation projects around Selangor’s river basins.

    Managing Director Martijn van Keulen and his supply chain team are aligning the Petaling Jaya plant with the group’s Brew a Better World 2030 roadmap. That plan sets binding deadlines for net-zero carbon production and complete water circularity across all Asian operations.

  • Over 90 per Cent of Luxury Consumers Seek Experiences Beyond Products

    Over 90 per Cent of Luxury Consumers Seek Experiences Beyond Products

    More than 90 per cent of luxury consumers now seek brand experiences outside the product itself, including hospitality, travel, dining, and wellness, according to a 2026 report by MG2 Advisory.

    Craftsmanship remains the primary purchasing driver for 62 per cent of buyers, yet luxury houses such as Hermès, Gucci, and Kith are increasingly evaluated on the ongoing relationships and environments they build around their goods.

    More than three-fourths of respondents associate luxury with rarity and exclusivity, while nearly half expressed interest in private, members-only spaces and repair services that preserve product value.

    Hospitality reshapes flagship formats

    Houses are reacting by building operational ecosystems that extend past apparel and leather goods. Kith opened its members-only Ivy concept to integrate sport, dining, and retail, while Gucci expanded its culinary presence through Gucci Osteria da Massimo Bottura. In London, Hermès opened its sixth Hermès Maison concept store, replicating mixed hospitality and retail formats already operating in Tokyo, Seoul, Shanghai, Paris, and New York.

    For prime landlords across Asia-Pacific, this shift changes leasing economics entirely. Retailers no longer evaluate store footprints solely on sales density per square metre. Instead, top-tier brands require larger floorplates to accommodate private client salons, cafes, and preservation workshops, forcing mall operators in Hong Kong, Singapore, and Tokyo to reallocate prime ground-floor space from transactional sales to experiential services.

    The operational risk sits squarely in execution. Running fine dining, bespoke tailoring, and hospitality requires different supply chains and labour models than selling boxed leather goods. When service levels in brand-run restaurants or repair centres slip, the reputational damage flows directly back to the core fashion label.

    After-care moves to the balance sheet

    Post-purchase services have evolved from back-office cost centres into client retention mechanisms. Hermès and Louis Vuitton have reinforced dedicated repair units to extend product lifespans, while Coach runs its circular (Re)Loved restoration and resale division across major retail markets.

    Physical flagships in major regional capitals will increasingly reflect this split between exhibition and maintenance. The next metric to watch is whether luxury groups maintain capital expenditure for multi-floor experiential maisons as store construction costs and prime commercial rents across Asia climb through late 2026.

  • TPG Telecom Ordered to Pay A$1 Million After Sydney Store Attack

    TPG Telecom Ordered to Pay A$1 Million After Sydney Store Attack

    New South Wales District Court ordered TPG Telecom to pay A$1,006,996.29 in damages after an assailant attacked a store worker with a makeshift blowtorch in Sydney.

    The ruling establishes direct corporate liability for failing to deploy physical security guards at a shop recording five times the national network average for customer aggression.

    The Incident at Macarthur Square

    Proceedings stem from a November 22, 2019 assault on Vodafone store employee Damir Lepan at Campbelltown Macarthur Square. Lepan dealt with an aggressive customer who left the shop. The man returned several hours later carrying an aerosol deodorant can and a cigarette lighter.

    The assailant ignited the spray into Lepan’s face, burning his head and arm. Debilitating psychiatric trauma prevented him from returning to work. Lepan sued TPG Telecom under the Workers Compensation Act 1997 for past and future economic losses, arguing the company breached its duty of care through inadequate physical security.

    Flaws in Remote Monitoring Systems

    TPG Telecom relied on an under-counter duress alarm connected to a remote monitoring centre. Offsite operators reviewed CCTV feeds before contacting emergency services or dispatching guards.

    District Court Judge Paul Fitzsimmons rejected remote monitoring for high-risk retail sites. Evidence showed a 2017 incident at the store, where a customer threatened to slit an employee’s throat, took offsite security up to 15 minutes to respond. TPG Telecom national security manager Michael Jackson conceded during testimony that a uniformed guard deters attackers better than offsite cameras.

    Legal Fallout for Store Operators

    Court findings showed the Macarthur Square outlet was a clear statistical outlier across Vodafone’s national network, making violent encounters foreseeable. Fitzsimmons ruled that store workers were ill-equipped to manage hostile shoppers without dedicated onsite personnel.

    Retail chains relying on remote electronic monitoring to cut costs face direct legal exposure. Landlords and retail operators across Australia risk liability if they fail to staff known problem locations with physical guards, regardless of existing alarm systems.

    TPG Telecom introduced part-time guard coverage for four days across a two-week period following the 2019 attack. The A$1,006,996.29 award covers Lepan’s lost earnings, superannuation entitlements, and compensation tax liabilities.

  • Tokyo Inner Ward Population Hits 9.8 Million as Density Reaches 15,600

    Tokyo Inner Ward Population Hits 9.8 Million as Density Reaches 15,600

    Tokyo’s 23 central wards added 1.2 million residents over the past two decades, pushing urban density to 15,600 people per square kilometre, as reported by Paul de Vries for The Japan Times in September 2026. The population in the inner wards now stands at 9.8 million.

    Construction firms and property developers have absorbed this influx primarily through two methods. Builders are erecting high-rise residential towers containing hundreds of units while buying standalone houses with private yards, razing the greenery, and replacing them with multiple narrow homes.

    Subdividing Plots for Housing

    Landed housing subdivisions now supply a steady stream of compact urban properties across residential wards. Replacing a single detached home with two or three townhouses increases plot yield for homebuilders. It also removes private gardens that previously provided urban tree cover and communal wildlife corridors.

    Tower developments concentrate hundreds of households onto single commercial footprints. These buildings offer high floor-area ratios but leave standard rooftops largely bare of functional green infrastructure.

    Pressure on Urban Greenery

    For residential property developers in Japan, plot subdivision remains the fastest way to bring infill housing to market without assembly delays. However, municipal planning offices face mounting heat-island effects in wards where open ground cover has vanished. Residential developers across Seoul and Singapore face similar constraints, but Japanese zoning codes give private landowners wider leeway to maximise structural footprints up to boundary lines.

    Institutional real estate investors holding multifamily residential assets in Tokyo face shifting tenant preferences. Renters and buyers in high-density districts increasingly seek access to private or communal outdoor spaces, creating a pricing gap between conventional concrete blocks and properties that integrate rooftop greenery.

    Rooftop Space Under Scrutiny

    Tokyo’s urban growth runs counter to Japan’s broader demographic decline, which has hollowed out regional prefectures while concentrating capital and labour in the Kanto region. Previous redevelopment cycles focused on expanding transport nodes and commercial office floors around central railway hubs.

    Attention is shifting to residential rooftop retrofits across the 23 wards as developers balance land costs against municipal open-space guidelines.

  • Astana Panel Explores Hong Kong Capital Routes for Central Asian Firms

    Astana Panel Explores Hong Kong Capital Routes for Central Asian Firms

    In September 2026, financial leaders and exchange executives gathered in Astana to discuss how Central Asian companies can connect with international capital through Hong Kong.

    The panel, titled “Capital Pathways for Central Asia, Dual Listings, RMB Funding, Private Capital and the Astana-Hong Kong Route,” featured Assel Mukazhanova of AIX, Johnson Chui of HKEX, Askar Bilisbekov of Alem Capital Management, and Thomas G. Tsao of Gobi Partners, with SCMP’s Eugene Tang moderating.

    Mukazhanova noted that Kazakhstan’s domestic market cannot fully meet regional financing demand, while Bilisbekov highlighted that Alem Capital Management is operating two funds, including a venture capital fund investing regionally and globally, alongside plans for an infrastructure fund.

    Hong Kong Listing Halo

    Venture capital firms operating between East and Central Asia view Hong Kong regulatory scrutiny as a vetting mechanism for international fund managers hesitant about frontier markets. Thomas G. Tsao, founding partner of Gobi Partners, pointed out that Hong Kong listings provide emerging Central Asian companies with regulatory credibility similar to how early Chinese tech firms used Nasdaq listings to establish trust with global institutional backers.

    For institutional investors across Asia, the channel offers exposure to Central Asia’s tech and natural resources sectors without navigating fragmented local legal structures. The primary operational risk rests on liquidity: smaller Central Asian tech firms must demonstrate sufficient scale and recurring revenue to attract trading volume once listed in Hong Kong, rather than becoming dormant secondary listings.

    Talent and Regional Trade Routes

    Central Asian founders increasingly build software and services designed to interface across Chinese, Russian, and Western commercial systems. Tsao noted that the region’s multilingual, mobile-first workforce gives early-stage companies an advantage in operating across multiple trade jurisdictions simultaneously.

    The push to build financial corridors follows years of physical trade expansion between China and Central Asia along traditional overland freight routes. Financial institutions in Astana now aim to match those physical supply chains with institutional capital flows, moving Central Asian funding beyond bilateral state debt into equity markets.

    Broadening the Investor Base

    Market participants also view the Hong Kong link as a way to diversify capital sources, reducing concentration risk from single-nation strategic investors in resource extraction and mining. Channelling investments through public equity and institutional funds brings a wider mix of global asset managers into Central Asian enterprises.

    AIX and its regional partners are now screening candidate companies for initial dual-listing pipelines and private rounds, with the first wave of cross-border listings targeted as market benchmarks.

  • Sheng Siong Wins Singapore Affluent Shoppers as Consideration Jumps to 52 per Cent

    Sheng Siong Wins Singapore Affluent Shoppers as Consideration Jumps to 52 per Cent

    Singapore grocer Sheng Siong lifted customer consideration among higher-income households to 52 per cent in August 2026, up from 33 per cent a year earlier. That 19-point surge put wealthy shoppers ahead of middle-income consumers for the first time in brand tracking records.

    Across the island, the supermarket chain’s overall consideration score rose 9.1 points to 50.0 between September 1, 2025 and August 31, 2026. Current customer reach climbed 11.2 points to 50.7 per cent, tracking adults who shopped there within the past three months. Total customer satisfaction increased from 39.3 to 49.9 over the same 12-month period.

    Shifting the Customer Base

    YouGov data shows the sharpest demographic realignment occurred among households earning more than 200 per cent of the national median income. That affluent cohort started September 2025 as Sheng Siong’s least frequent customer group at 33 per cent. By August 2026, it became its most frequent at 56 per cent. Middle-income shoppers rose from 41 per cent to 51 per cent, while lower-income patronage reached 51 per cent.

    Higher-income satisfaction showed an even steeper climb. Net satisfaction in that bracket reached 55.7 in August 2026, up from 28.0 a year earlier. That topped the 52.4 score recorded by lower-income households.

    Pricing Staples and Town Locations

    Sheng Siong engineered this shift through steep discounts on core household baskets and real estate expansion outside suburban strongholds. Targeted price cuts included doubling Community Health Assist Scheme discounts in June. The grocer also discounted pantry staples such as eggs and rice by up to 50 per cent through Community Development Council voucher promotions.

    Store location backed the pricing strategy. The company pushed beyond public housing heartlands by opening a town-centre branch at The Cathay in August 2025. The outlet caught central office workers and professional commuters who previously defaulted to premium grocers.

    Margin Pressures on Mid-Tier Rivals

    Competitors in the mid-tier space face immediate pressure, including FairPrice and DFI Retail Group’s Cold Storage network. When budget operators secure affluent volume on everyday staples, mid-tier chains risk margin erosion as they defend market share with matching promotions.

    Operating costs present risks for the value grocer. Serving shoppers in high-rent central commercial spaces lifts baseline overheads, requiring higher spend per ticket to offset narrow margins on discounted staple goods.

    Logistics upgrades and footprint modernization drove these retail gains over the past two financial years. BrandIndex metrics will show whether the numbers hold when government voucher programs taper off ahead of the 2027 fiscal year.

  • The Galeries Launches Retailer Scent Project with Provider Store in Sydney

    The Galeries Launches Retailer Scent Project with Provider Store in Sydney

    Sydney shopping centre The Galeries is running a month-long retail collaboration with local artisan brand Provider Store from September 29 to October 25. The program aims to drive tenant foot traffic.

    Shoppers who spend 300 dollars across the centre in a single day during the campaign receive a complimentary limited-edition candle. The gift represents one of three flagship tenants.

    How the tenant scent program works

    Provider Store founder Tara Bennett designed three distinct fragrances based on the retail identities of Japanese bookstore chain Books Kinokuniya, fashion retailer Incu, and outdoor footwear brand Salomon. The activation operates from a Japanese-inspired market stall under the George Street complex’s ground floor atrium.

    Kinokuniya’s fragrance incorporates hinoki, amber, macadamia, lemon, and frankincense to mirror the bookstore chain’s Japanese heritage. Incu’s candle blends fir needle, oak moss, cedar, and sandalwood. Salomon uses pine, cedarwood, sage, and palo santo. Customers can take empty ceramic vessels to Provider Store’s standalone site in Surry Hills for paid refills from its permanent scent library.

    Tenant marketing across prime central business districts

    Landlords in major Asia-Pacific commercial hubs face sustained pressure to turn central business district foot traffic into register sales. Generic promotional vouchers often fail to lift basket sizes across multiple categories. Tying a physical gift to a 300 dollar single-day spend forces shoppers to cross-shop fashion, books, and sportswear inside the same asset.

    This approach gives specialty lifestyle operators exposure without the cost of building standalone pop-ups. For Japanese operators like Kinokuniya, brand activations inside high-density Asia-Pacific corridors reinforce cultural identity while supporting broader mall dwell times.

    Longer retail track record at the complex

    Centre management launched the campaign as the debut project for The Galeries Presents, an in-house promotional platform designed to bundle tenant marketing into shared on-site installations. The property previously relied on visual art installations and cultural exhibits to anchor ground-floor common areas.

    “Working with Provider Store has allowed us to explore The Galeries Presents in a new way, using scent to capture the distinct character of three of our retailers and bring their stories to life,” said Melanie Vale, centre manager at The Galeries.

    Management will run the ground-floor stall through October 25, then evaluate sales receipts and customer redemptions before scheduling the next tenant collaboration.

  • SM Supermalls Shifts Tenant Mix to 30 Percent Dining as First-Half Revenue Reaches P41.8B

    SM Supermalls Shifts Tenant Mix to 30 Percent Dining as First-Half Revenue Reaches P41.8B

    SM Supermalls raised its food and beverage tenant share to 30 percent while lifting first-half revenue 8 percent to 41.8 billion Philippine pesos. The shift marks a fundamental redesign of floor plans across the country’s largest retail network.

    Dining accounted for less than 5 percent of the group’s leasable space when current president Steven Tan joined in 2004. The operator is now reallocating square meters from apparel and standard department store goods to dining, sports, and live events under a five-year platform called My SM.

    Retrofitting Floor Space for Food and Sports

    Expanding dining requires heavier investments in physical infrastructure than dry retail. Malls require upgraded water connections, higher-capacity electrical systems, grease traps, and expanded kitchen exhaust ducts to handle restaurant tenants at scale.

    Alongside dining, the landlord is adding non-retail recreation to fill communal areas. The group added 41 pickleball courts during the first six months of the year, taking its total to 102 courts across 32 properties. In June, its commercial complex cohosted the Galaxy Manila Marathon, bringing 25,000 runners onto the grounds.

    Internal merchandising direction now runs partly through an internal advisory unit. The operator created a Gen Z Council of junior staff to evaluate pop-culture trends, such as pop-up matcha fairs, before senior managers commit capital to physical rollouts.

    You have to constantly inject freshness to your centers so that you keep the interest in coming back.

    Regional Realignment from Shelves to Social Space

    Mall operators across Southeast Asia face identical pressures as e-commerce captures routine apparel and consumer electronics purchases. Landlords in Bangkok, Jakarta, and Manila are converting between 25 and 35 percent of gross leasable area to food and leisure to defend foot traffic. SM watched Chinese shopping centers retrofit for hospitality a decade ago and applied the template locally before domestic online shopping reached similar penetration levels.

    The operational risk sits in capital expenditure and lease yields. Restaurants and recreational concepts cost more to fit out, consume more utilities, and post higher tenant turnover rates than legacy fashion retailers. Operators must turn over pop-up concepts and specialty dining fast enough to sustain foot traffic without squeezing margins on rental collection.

    Expanding the Footprint Across South Luzon

    Revenue growth reflects solid consumer spending despite inflationary pressures across basic goods. The 41.8 billion pesos generated in the first half of 2026 improved on 38.6 billion pesos recorded during the same period in 2025, driven by steady leasing income and higher foot traffic across metropolitan centers.

    Construction is underway on SM Nuvali in Laguna, which will serve as the company’s 91st Philippine mall. The property will test an upscale store format aimed at higher-income residential enclaves across Cavite, Laguna, Batangas, Rizal, and Quezon.

  • Vietnam Weighs First Sovereign Dollar Bond Sale Since 2014

    Vietnam Weighs First Sovereign Dollar Bond Sale Since 2014

    Vietnam’s finance ministry is in talks with international investment banks to issue its first sovereign dollar bond in over a decade. Proposals on the table include a 10-year note raising between $500 million and $1 billion, carrying an estimated coupon of around 7 per cent.

    Hanoi plans to channel the proceeds into ports, transport corridors and industrial infrastructure to support an official target of at least 10 per cent annual economic expansion through 2030. Officials are weighing borrowing costs against elevated global yields before making a formal commitment.

    Bank Proposals and Pricing Pressures

    One foreign lender pitched a $1 billion 10-year dollar bond during discussions in Hanoi. Another bank recommended a flexible issue size starting at $500 million at roughly a 7 per cent coupon, reflecting current international borrowing benchmarks.

    Domestic debt issuance has reached over $9 billion so far this year. While the total volume matches last year’s pace, the average local 10-year yield climbed to 4.2 per cent from 3.1 per cent, raising the price tag of funding public works purely through local auctions.

    Corporate Borrowing Clears the Path

    State planners have eased limits on external commercial debt while government ministries negotiate terms. The State Bank of Vietnam lifted the annual ceiling for private-sector offshore borrowing to $6.1 billion this year, up from $5.5 billion in 2025, and officials are already reviewing requests to push that threshold higher.

    Commercial borrowers have moved fast to secure offshore liquidity. VPBank closed a $1.44 billion syndicated foreign loan facility in June, while conglomerate Vingroup listed a $350 million five-year bond on the Vienna Stock Exchange in April at a 5.75 per cent coupon. Vingroup has also filed to sell 455 billion won, or about $338 million, in three-year notes yielding 8 per cent to institutional investors in South Korea.

    For supply chain operators and consumer goods distributors across the country, a sovereign benchmark establishes a clear pricing floor for long-term project debt. Without sovereign paper in circulation, corporate issuers face wider risk premiums when raising hard currency for distribution hubs, cold storage networks, and factory expansions.

    Relieving Domestic Lending Strains

    Local commercial banks have carried the load of infrastructure and industrial loans for years. Credit expansion in Vietnam has outstripped domestic deposit growth continuously since 2021, creating balance-sheet friction that constrains private business lending.

    Vietnam last accessed the offshore sovereign bond market in 2014, when it sold a $1 billion 10-year note with a 4.8 per cent coupon. The country has kept public debt low, at approximately 37 per cent of gross domestic product, but bilateral development loans from Germany and Japan signed earlier this year confirmed a shift toward tapping external balance sheets.

    The next signal will come from the finance ministry’s formal syndicate mandate, which will determine whether Hanoi proceeds with the $1 billion issuance before global debt markets close out the fiscal year.