Blog

  • Harrods Develops Bespoke Collaboration with Hong Kong Brand Silk

    Harrods Develops Bespoke Collaboration with Hong Kong Brand Silk

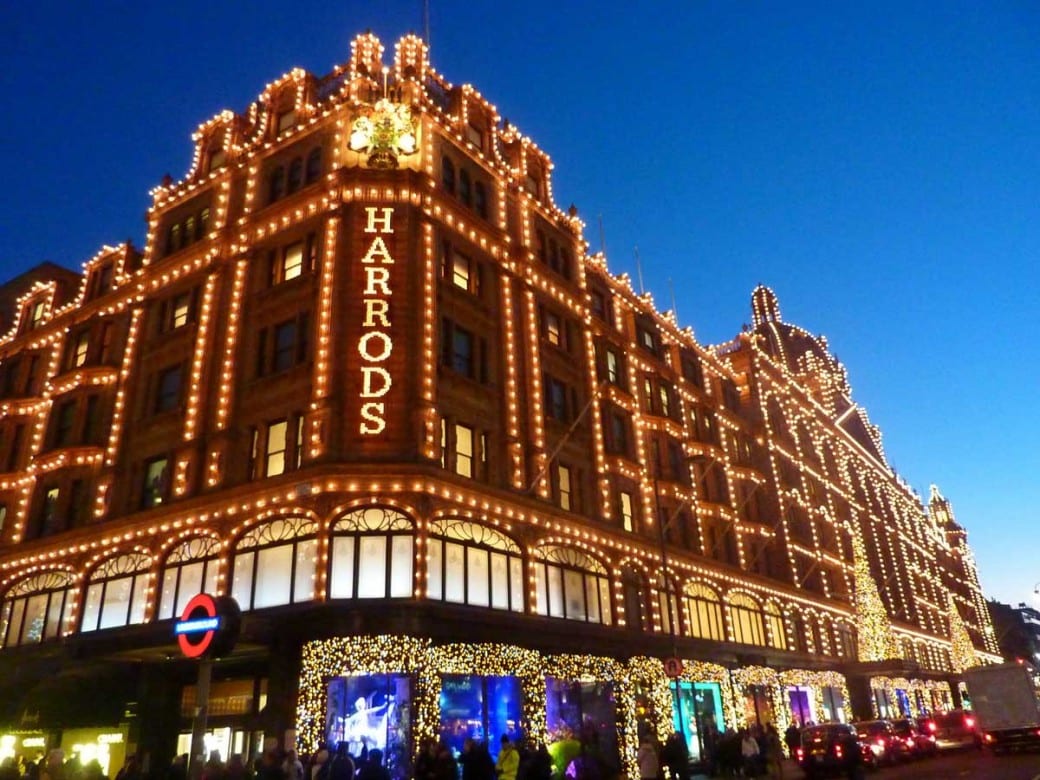
    In September 2026, London department store Harrods flew members of its global marketing team to Hong Kong to develop a bespoke collaboration with Silk, a young local beverage brand. The partnership aims to place Hong Kong-style bubble tea directly into premium lifestyle culture.

    Silk was founded on the conviction that Hong Kong-style bubble tea deserves a place in premium retail. For the young beverage maker, working directly with 1 of the world’s most recognisable department stores confirms its place in high-end lifestyle branding.

    Global Retailers Target Local Asian Culture

    Department stores across Europe and Asia increasingly look past standard licensing deals in favour of direct, culturally rooted partnerships. Securing authentic local products gives established department stores cultural credibility with younger Asian travellers and domestic luxury shoppers.

    For Silk, entering a joint project with Harrods validates a premium pricing and branding strategy for a product category traditionally sold at low street prices. The commercial risk sits in execution: luxury consumers expect elevated ingredients, distinct packaging and narrative depth rather than standard co-branding.

    Shifting Playbook for Independent Beverage Brands

    Regional beverage brands in Asia previously relied on regional franchise networks or overseas store openings to build global scale. Partnering directly with legacy international retailers offers an alternative route to worldwide visibility without the capital expense of offshore physical stores.

    The Harrods project mirrors broader retail shifts where Western heritage operators seek relevance in Asian consumer hubs through high-profile regional collaborations. The development process required London brand teams on the ground in Hong Kong to oversee formula and packaging design.

    Next Steps for the Collaboration

    Harrods and Silk will confirm rollout schedules and retail availability across physical counters and export channels once final product formulations clear development.

  • UGREEN Launches Local AI Smart Home Hubs and Liquid-Cooled Wireless Chargers

    UGREEN Launches Local AI Smart Home Hubs and Liquid-Cooled Wireless Chargers

    UGREEN unveiled its first smart home ecosystem and liquid-cooled magnetic chargers at Gillette Stadium in Massachusetts on September 1. Pre-orders opened ahead of a formal crowdfunding drive in October 2026.

    The Shenzhen-headquartered hardware manufacturer wants to shift smart home processing away from third-party cloud platforms. Running workloads on local hardware eliminates recurring subscription fees for end users.

    Local Processing and NVIDIA Silicon

    Hardware in the new lineup includes the HomeAgent HA100, the HA100 Pro, and the MasterAgent MA100. The MasterAgent runs on NVIDIA’s Jetson Thor T5000 processor and delivers up to 2,070 FP4 TFLOPS of local computing power. That lets it manage multi-device task coordination and voice interactions locally. Household data never routes through external servers. Both HomeAgent models support the Matter interoperability protocol. They connect accessories such as SynCare indoor and outdoor cameras, the Uliya smart speaker, and digital display frames.

    Alongside the computing hubs, the company introduced three 25W magnetic wireless charging devices under its MagFlow badge. A 10,000mAh magnetic power bank priced at $149.99 uses a micro-pump liquid cooling system to control heat during fast charging. Other products include a three-in-one desktop charging stand for $159.99. A foldable two-in-one travel charger sells for $59.99 on Amazon and direct retail channels.

    Hardware Margins Versus Subscription Revenue

    Consumer electronics makers across Asia face slowing replacement cycles for basic charging accessories and cables. Moving upmarket into local computing hubs lets hardware vendors capture higher initial ticket prices. However, this strategy cuts off the recurring software subscriptions favored by Western competitors like Amazon Ring and Google Nest. UGREEN expects customer fatigue with monthly cloud storage fees will drive hardware sales.

    Engineering risks center on software execution. Local AI models demand sustained developer support and reliable edge performance across third-party Matter devices. If on-device image parsing and voice recognition lag behind cloud alternatives, buyers will balk at the upfront hardware premium.

    Expanding Beyond Commodity Accessories

    Founded in 2012, UGREEN built retail distribution across more than 180 countries on fast chargers, cables, and storage enclosures. The push into AIoT hardware follows a rollout of high-end network-attached storage units earlier this summer. The firm also signed an official partnership with the NFL’s New England Patriots in April.

    Pre-orders for the HomeAgent and MasterAgent hubs opened September 3. A $50 deposit locks in a 50 per cent discount before the full Kickstarter campaign launches on October 27, 2026.

  • Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Australian retailers face a structural shift in holiday spending as 57 per cent of shoppers concentrate gift purchases in November after pre-selecting brands in October.

    Data compiled by market research agency Retail Safari and consultancy PwC shows 64 per cent of holiday budgets remain unspent entering November, even as buyers finalise purchase shortlists weeks earlier. Black Friday alone now captures 55 per cent of holiday shoppers, turning the discount window into an execution phase rather than a discovery channel.

    The Split Between Early Planning and Peak Spending

    Consumer research from Mintel indicates more than six in ten Black Friday shoppers choose their target products before promotional events begin. Shoppers use September and October to compare specifications, check customer reviews and track merchant pricing before committing funds. In Australia, research from the Australian Retailers Association and Roy Morgan showed 29 per cent of consumers started browsing earlier in 2025 than the previous year, while only 8 per cent started later.

    The US-based National Retail Federation recorded an identical baseline, with roughly 40 per cent of consumers starting holiday research before November. Shoppers cite three main drivers: managing household budgets over time, avoiding store congestion, and eliminating late delivery risks.

    Big-Ticket Sales Diverge From Headline Retail Growth

    Official figures mask underlying pressure across discretionary categories. Australian Bureau of Statistics data analyzed by investment research firm MST Marquee placed July retail turnover growth at 6.6 per cent year on year, running above the 4.9 per cent historical average. Food services rose 9.3 per cent and clothing gained 7.1 per cent, but major durable goods operators failed to capture that momentum.

    First-quarter trading updates reflect the divide. Online furniture seller Temple & Webster reported sales down 13 per cent across its first seven weeks, department store operator Myer posted a 4 per cent decline, and Accent Group recorded a 2 per cent like-for-like drop. Electronics chain JB Hi-Fi saw comparable sales slip 1.4 per cent, while its home appliance unit The Good Guys declined 1.7 per cent and furniture retailer Nick Scali tracked flat from July 1.

    Household Wealth Pressures Shorten Brand Lists

    For store operators and suppliers, the divergence means consumers are buying smaller items frequently while delaying expensive, considered purchases until deep discounting begins. Retailers that spend their marketing budgets solely on late November discounts risk losing shoppers who eliminated unfamiliar brands during the October evaluation window. Merchant margins face compounding pressure if price cuts merely settle competition among pre-selected names rather than bringing in new foot traffic.

    The shift follows a broader contraction in gift-buying participation. ARA and Roy Morgan figures showed 68 per cent of Australian adults planned holiday gift purchases last year, down 9 per cent from 2024, while average spend per remaining buyer climbed 7.1 per cent to A$757.

    MST Marquee projects household goods demand will soften further through the fourth quarter as property price weakness and potential interest rate hikes from the Reserve Bank of Australia curb discretionary outlays.

  • Goldman Raises Asia Pacific Ex-Japan Index Target to 1,120

    Goldman Raises Asia Pacific Ex-Japan Index Target to 1,120

    Goldman raised its forecast for the MSCI AC Asia Pacific ex-Japan Index to 1,120 from 1,080, projecting a 26 per cent upside driven by higher earnings expectations in Korea and Taiwan.

    Second-quarter earnings across the benchmark grew 102 per cent, with 44 per cent of companies beating forecasts compared with 27 per cent that missed.

    Earnings growth was led by Singapore, Taiwan and Indonesia, while Australia, Malaysia and India lagged, with Singapore and Taiwan recording the highest number of firms exceeding expectations.

    North Asian Tech Dominates the Rally

    The bank assigned an overweight rating to Japan, South Korea, Taiwan and mainland China A-share equities. South Korea’s benchmark Kospi received a revised 12-month target of 12,000, representing a 79 per cent upside from current trading levels, underpinned by heavyweight chipmakers Samsung Electronics and SK Hynix.

    By contrast, Hong Kong, Singapore, Malaysia, India and offshore Chinese equities remain rated at market weight. Southeast Asian markets face a split outlook, with Thailand, Indonesia and the Philippines assigned underweight ratings alongside Australia.

    Consumer Retail and Hardware Divergence

    Sector allocations show a sharp divide between capital-intensive tech manufacturing and consumer-facing retail. Goldman designated tech hardware, semiconductors, capital goods, healthcare and non-Australian, non-Chinese lenders as its most favored sectors.

    Consumer retail, media and property remain ranked at market weight across the region, reflecting steady but unspectacular domestic consumer demand. Transportation, utilities and automotive manufacturers received underweight ratings.

    Earlier Forecast Trajectory

    The revised projections build on earlier upgrades from May, when Goldman set an initial 12-month Kospi target of 9,000 before tech earnings accelerated. The broader index target of 1,120 reflects cleaner investor positioning following recent portfolio unwinds across regional exchanges.

    Investors now track third-quarter tech hardware order books and upcoming United States midterm election policy rhetoric, which remain key external risks alongside elevated bond yields and Middle East tensions.

  • Hong Kong Bakery Brand Builds 30,000 Members Without Retailer POS Data

    Hong Kong Bakery Brand Builds 30,000 Members Without Retailer POS Data

    A century-old Hong Kong bakery and confectionery manufacturer signed up more than 30,000 loyalty members within six months by asking shoppers to scan supermarket receipts instead of relying on retailer point-of-sale data.

    Powered by the KlikNGo loyalty and CRM platform, the initiative took Gold for Best CRM Campaign at the DigiZ Awards 2026 in September after doubling repeat purchases and generating 47 per cent of the brand’s sales uplift.

    How receipt scanning bypasses the till

    Suppliers selling through Hong Kong supermarket chains, convenience stores and neighbourhood grocers have long operated with limited visibility of their end consumers. Trade promotions produce temporary sales lifts without delivering customer intelligence, while retailers typically treat transaction records as confidential. At the same time, younger shoppers have drifted toward artisanal and lifestyle food brands, weakening the impact of legacy brand familiarity alone.

    To capture shopper records directly, the manufacturer rolled out a mobile application built on the KlikNGo loyalty platform. Consumers register, buy goods at third-party retailers, and photograph paper or digital receipts. The software extracts the merchant name, branch location, purchase timestamp, payment method, and transaction number. It verifies purchases against approved retail partners while blocking duplicate claims.

    More than 10 major retail chains in Hong Kong are covered by the system. Members redeem accumulated points for tier perks, vouchers, gifts, and lucky draws. Outlet staff validate reward vouchers in real time using a separate merchant app, eliminating any need to integrate with supermarket registers.

    Customer profiling and media returns

    App downloads crossed 23,000 within three months of rollout. Shoppers uploaded more than 30,000 receipts over five months. Member mission completion rates hit 85 per cent, supplying profile details, purchase occasions, and product preferences to turn raw receipt data into targeted first-party segments.

    Direct data reshaped advertising spend. Targeted promotions to verified buyers improved media efficiency by 49 per cent. That allowed the brand to direct ad budgets against known consumption habits rather than buying broad demographics across Hong Kong media channels.

    The shift in supplier use

    Packaged goods makers across Asia face an altered balance of power with physical grocery giants like Dairy Farm and AS Watson. When brands collect store-level purchasing intelligence independently, trade marketing budgets move away from retailer listing fees and end-cap slots. Funds shift directly into proprietary engagement channels.

    Customer friction remains the primary operational risk. Asking shoppers to photograph physical receipts demands higher rewards than swiping a loyalty card at checkout. Redemption costs rise if mission completion drops or rewards fail to compensate for the manual step.

    Industry recognition followed the rollout. The initiative won Gold for Best CRM Campaign at the DigiZ Awards 2026, while platform provider KlikNGo took Bronze for Best MarTech for CRM. KlikNGo presents the Hong Kong case study at the Digital Marketing Asia conference in Singapore on September 22.

  • Philippine Regulator Clears GCash Parent Mynt for $1.48 Billion IPO

    Philippine Regulator Clears GCash Parent Mynt for $1.48 Billion IPO

    The Philippine Securities and Exchange Commission has approved the initial public offering of Mynt, Inc, the parent company of GCash, for up to $1.48 billion (P92.32 billion).

    The company will list on the Philippine Stock Exchange with an expected initial market capitalization of $10.71 billion (P668.96 billion) under regulatory guidelines established in 2026 for large-scale issuers.

    Under the approved terms, Mynt will issue up to 1.61 billion primary common shares, while a selling shareholder will offer up to 6.42 billion shares, alongside an overallotment option of up to 1.20 billion shares priced at up to $0.16 (P10) each.

    Share structure and float relief

    Regulators granted Mynt permission to list with a 12 percent initial public float rather than the standard 15 percent requirement. SEC Memorandum Circular No. 11 allows this lower threshold for issuers valued above $3.2 billion at listing. With an anticipated market capitalisation of 668.96 billion pesos, Mynt easily surpassed that statutory mark.

    That regulatory waiver protects existing shareholders from heavy dilution while injecting fresh liquidity into the local bourse. The secondary share sale gives early backers a clean exit route. It also keeps excess cash off the operating balance sheet.

    Valuation and market impact

    A $10.71 billion listing immediately reshapes index weightings on the Philippine Stock Exchange, where conglomerates, real estate developers, and traditional lenders dominate trading. The float gives fund managers a direct, liquid proxy for domestic consumer spending and fintech transaction volumes. It also tests local capital depth by absorbing funds that might otherwise flow across regional equities.

    Across Southeast Asia, the float provides a pricing benchmark for consumer fintechs moving from venture capital to public markets. Digital payment operators in Indonesia, Vietnam, and Thailand face similar profitability pressures. Yet Mynt’s multibillion-dollar domestic valuation shows local exchanges can absorb large tech listings when profitability metrics line up.

    Path to the trading floor

    Clearance follows years of rapid expansion for GCash, which grew from a basic telco money transfer tool into an everyday payment utility for Philippine merchants, transit routes, and small businesses. Backed by Globe Telecom and Ant Group, the platform built a lead over domestic rivals by capturing both banked and unbanked retail transactions during the pandemic shift to digital settlement.

    Bookbuilding and domestic retail offer periods will set the final strike price within the approved 10-peso ceiling before trading begins in Manila.

  • TCL Picks up over 30 Product Awards at IFA 2026 Across Displays and Hardware

    TCL Picks up over 30 Product Awards at IFA 2026 Across Displays and Hardware

    TCL secured over 30 product awards at IFA 2026 in Berlin. Its flagship SQD-Mini LED television line and connected smart home hardware led the haul. The Chinese consumer electronics manufacturer operates in more than 160 markets worldwide. It holds the top global market position in Mini LED and displays measuring 85 inches and above.

    Judges awarded the group seven IFA Innovation Award Honoree titles alongside five Global Product Technology Innovation Awards. Consumer tech publications gave top hardware prizes to the TCL X11L SQD-Mini LED television. The companion C8L model and the X3 Series OLED gaming monitor won separate honors for high refresh rates and panel contrast.

    Display Standards and Visual Certifications

    Beyond consumer televisions, the Shenzhen-headquartered group pushed into commercial display validation. TCL and testing agency TÜV Rheinland released a joint SQD-Mini LED Display Industry White Paper in Berlin. The document establishes testing parameters for real-world ambient lighting conditions. Testing firm SGS also granted visual comfort verification under a co-developed natural light standard.

    On the mobile and wearable side, the slim TCL P80 series led the phone division. The P80 Ultra model took an innovation honoree prize for its camera and screen setup. TCL’s augmented reality unit picked up hardware recognitions for two optical products. These included the RayNeo iO smart glasses with built-in voice assistance and the RayNeo GT Max AR glasses with Dolby Vision certification.

    Expanding From Screens into Connected Appliances

    For appliance retailers and electronics distributors across Asia-Pacific, the product spread shows a supplier determined to lock consumers into a broader ecosystem rather than selling standalone television screens. East Asian display makers face tighter margin pressure in budget segments. Proprietary white goods and connected home robotics provide a necessary volume buffer.

    That strategy directly challenges entrenched regional rivals who built their retail dominance on comprehensive living room and kitchen lineups. Competing on standalone panel specifications is no longer enough. Brands need broader catalogs to command prime floor space in modern department stores and multi-brand regional retail chains.

    Smart Home Ecosystem Rollout

    White goods featured heavily in the European show. Honors went to the TCL Solar Series air conditioner, the TwinMag Prime Fresh series refrigerator, and the heyAiMe companion robot. The TCL 5G AI CPE X5 router links the fleet. It took a dedicated innovation prize for automated network management features.

    Chinese hardware manufacturers continue an aggressive multi-year push to trade up from entry-tier pricing into premium display and connected home categories. Retail buyers across European and Asian distribution networks now await commercial release schedules and regional pricing sheets for the X11L display and RayNeo optical lines ahead of peak fourth-quarter consumer shopping cycles.

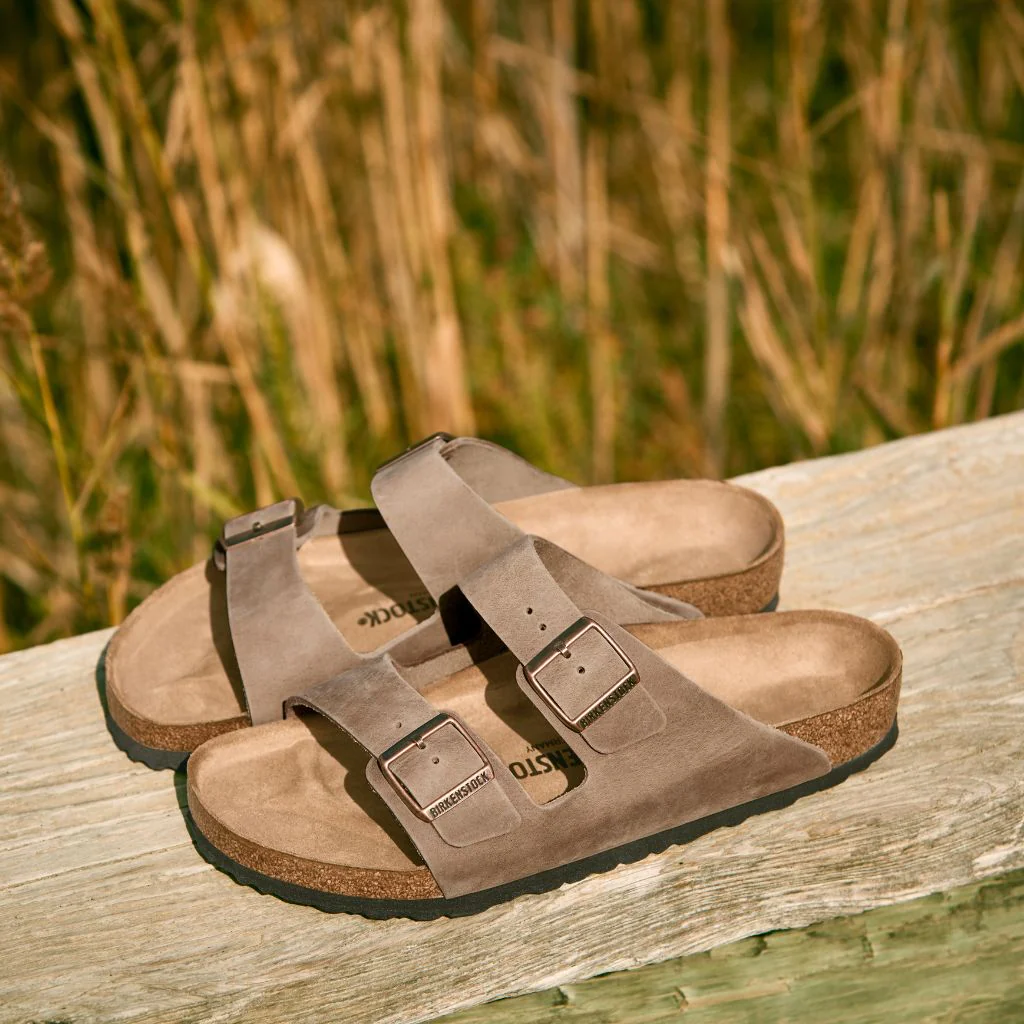
  • Birkenstock Opens First Indonesian Concept Store in Bali with 180-Sqm Community Hub

    Birkenstock Opens First Indonesian Concept Store in Bali with 180-Sqm Community Hub

    Birkenstock opened its first standalone concept store in Indonesia on September 10, adding a two-storey, 180-square-metre community space in Ubud, Bali.

    The location takes the German footwear brand into direct retail in Southeast Asia’s largest consumer market after years of selling exclusively through local department stores.

    Balinese Architecture and Premium Footwear

    Architect Yoka Sara designed the Ubud property around traditional Balinese residential layouts, using the concept of ‘Umah’, the local word for home. Sara placed the store entrance around a kitchen layout, reflecting the traditional first room entered in a Balinese house.

    Retail space on the upper floor carries Birkenstock’s higher-margin 1774 line alongside an exhibition detailing shoe assembly methods and raw materials. Adjoining the sales floor, the two-level community hub hosts sound healing sessions, yoga classes, and craft workshops run by local practitioners.

    We want to strengthen our presence in strategic markets while staying true to what defines us; creating experiences that are relevant to the places and communities we become part of.

    Direct Retail Over Wholesale Shelves

    Choosing Ubud over Jakarta shifts Birkenstock’s commercial entry point away from high-traffic Indonesian shopping malls. Bali gives the footwear maker direct access to international tourist footfall and resident expatriates who already know the brand, keeping customer acquisition costs lower than a ground-up push in the capital.

    The format also protects pricing power. Selling premium lines like the 1774 collection inside department stores limits brand control and exposes inventory to concession discounting, whereas a dedicated venue allows Birkenstock to sell full-price stock alongside experiential programming.

    Regional Expansion Track

    Direct store rollouts across Asia-Pacific have accelerated following Birkenstock’s flagship opening in Tokyo’s Shibuya district in July 2026. The shift reflects a wider push across the region to convert third-party wholesale accounts into owned mono-brand flagships in primary resort and metropolitan locations.

    Store traffic metrics from Ubud will determine whether Birkenstock expands the standalone concept into Jakarta and Surabaya mall developments later in the financial year.

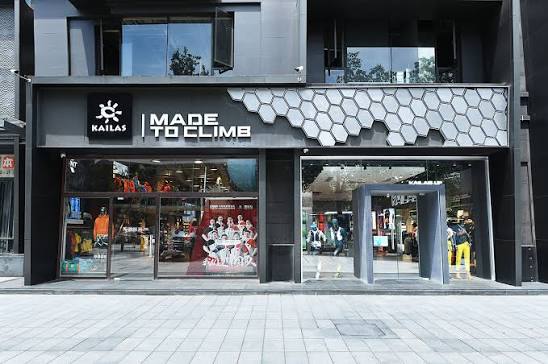
  • China’s Kailas Opens First Directly Operated European Store in Chamonix

    China’s Kailas Opens First Directly Operated European Store in Chamonix

    Chinese mountain sports brand Kailas opened its first European retail store in Chamonix, France. The site gives the brand a direct physical foothold in the continental outdoor hub.

    It is the company’s first directly operated store outside China. Kailas already runs more than 300 wholesale and retail sales outlets worldwide.

    Direct operations replace third-party distribution

    Founded in 2003, Kailas built its business across mountaineering, rock climbing, ice climbing and trail running. The Chamonix store shifts that strategy. Instead of relying on wholesale accounts, event sponsorships and athlete outfitting, the brand now operates its own storefronts in competitive Western markets.

    Inside, the branch focuses on the Kailas Fuga trail-running line and doubles as a community hub for local runners. Kailas used the location to launch its Fuga Ex Pro G shoe. More than 80 runners and ambassadors from its Fuga Team and Fuga Mountain Club attended the debut.

    Challenging established alpine competitors

    Setting up shop in Chamonix puts Kailas in direct competition with European mountain sports incumbents on their home terrain. The French Alps draw dense traffic from elite trail runners and mountaineers. That makes the town an expensive proving ground rather than a high-volume revenue generator.

    For Asian sportswear makers, direct European retail brings higher overhead, strict labour regulations and steep lease commitments compared to domestic operations. Kailas bets that technical validation in the Alps will lift brand equity across international accounts and its core domestic market in China.

    Building on athlete partnerships

    This opening follows years of sports marketing that assembled an international roster of 107 sponsored athletes. Those sponsorships previously fed third-party retail distribution and online orders rather than dedicated company-owned doors.

    Future expansion will show whether the Chamonix location remains a standalone flagship or serves as a template for more direct-to-consumer stores across Western Europe.

  • 91 Per Cent of Australian Consumers Switch Brands for Better Offers

    91 Per Cent of Australian Consumers Switch Brands for Better Offers

    A report by retail industry association Shop ANZ and consumer insights platform Vypr reveals that 91 per cent of Australian consumers have switched brands for a better offer.

    The study found that 79 per cent of shoppers have visited a different retailer to secure an offer, putting sustained pressure on retailers to continue promotional activity.

    According to the findings, 81 per cent of respondents said price has become a more important factor when purchasing a product than it was a year ago, making customer retention increasingly difficult.

    Promotional Cycles Drain Brand Value

    Heavier promotional spending generates short-term transaction spikes, but it fails to secure lasting customer retention once items return to full shelf price. Suppliers that fund continuous price reductions face falling margins without gaining repeat foot traffic.

    Vypr chief revenue officer Sam Gilding noted the structural weakness of relying on perpetual markdowns. “If a brand is recruiting shoppers heavily and then losing them to the next offer on shelf, it’s funding a cycle rather than building a base,” Gilding said.

    Middle-Aged Buyers Drive Shift

    Demographic data reveals acute pressure among mid-career shoppers, with 42 per cent of consumers aged 35 to 44 frequently switching brands because of a promotion. This demographic carries higher mortgage commitments and household expenses, making them faster to trade down than younger or older cohorts.

    Retailers across the Asia-Pacific region have expanded loyalty apps to protect basket sizes, yet Australian consumer behaviour suggests shoppers treat these programs as discount search engines rather than commitments to a banner. When every rival matches the discount, the retailer funding the deepest markdown simply buys temporary volume at the expense of profit.

    Shelf Pricing Faces Margin Test

    Shop ANZ general manager Carla Bridge explained that while shoppers discover promotions across apps, email catalogues, and social media feeds, purchasing decisions are still confirmed directly at the physical shelf.

    The findings follow two years of compounding inflation across Australian consumer staples, which reshaped grocery shopping habits and made weekly catalogue specials the primary driver of household spending routes.

    Packaged goods suppliers negotiating trade terms for the upcoming trading quarters now face demands from major supermarket chains to co-fund deeper price cuts to protect category volume.

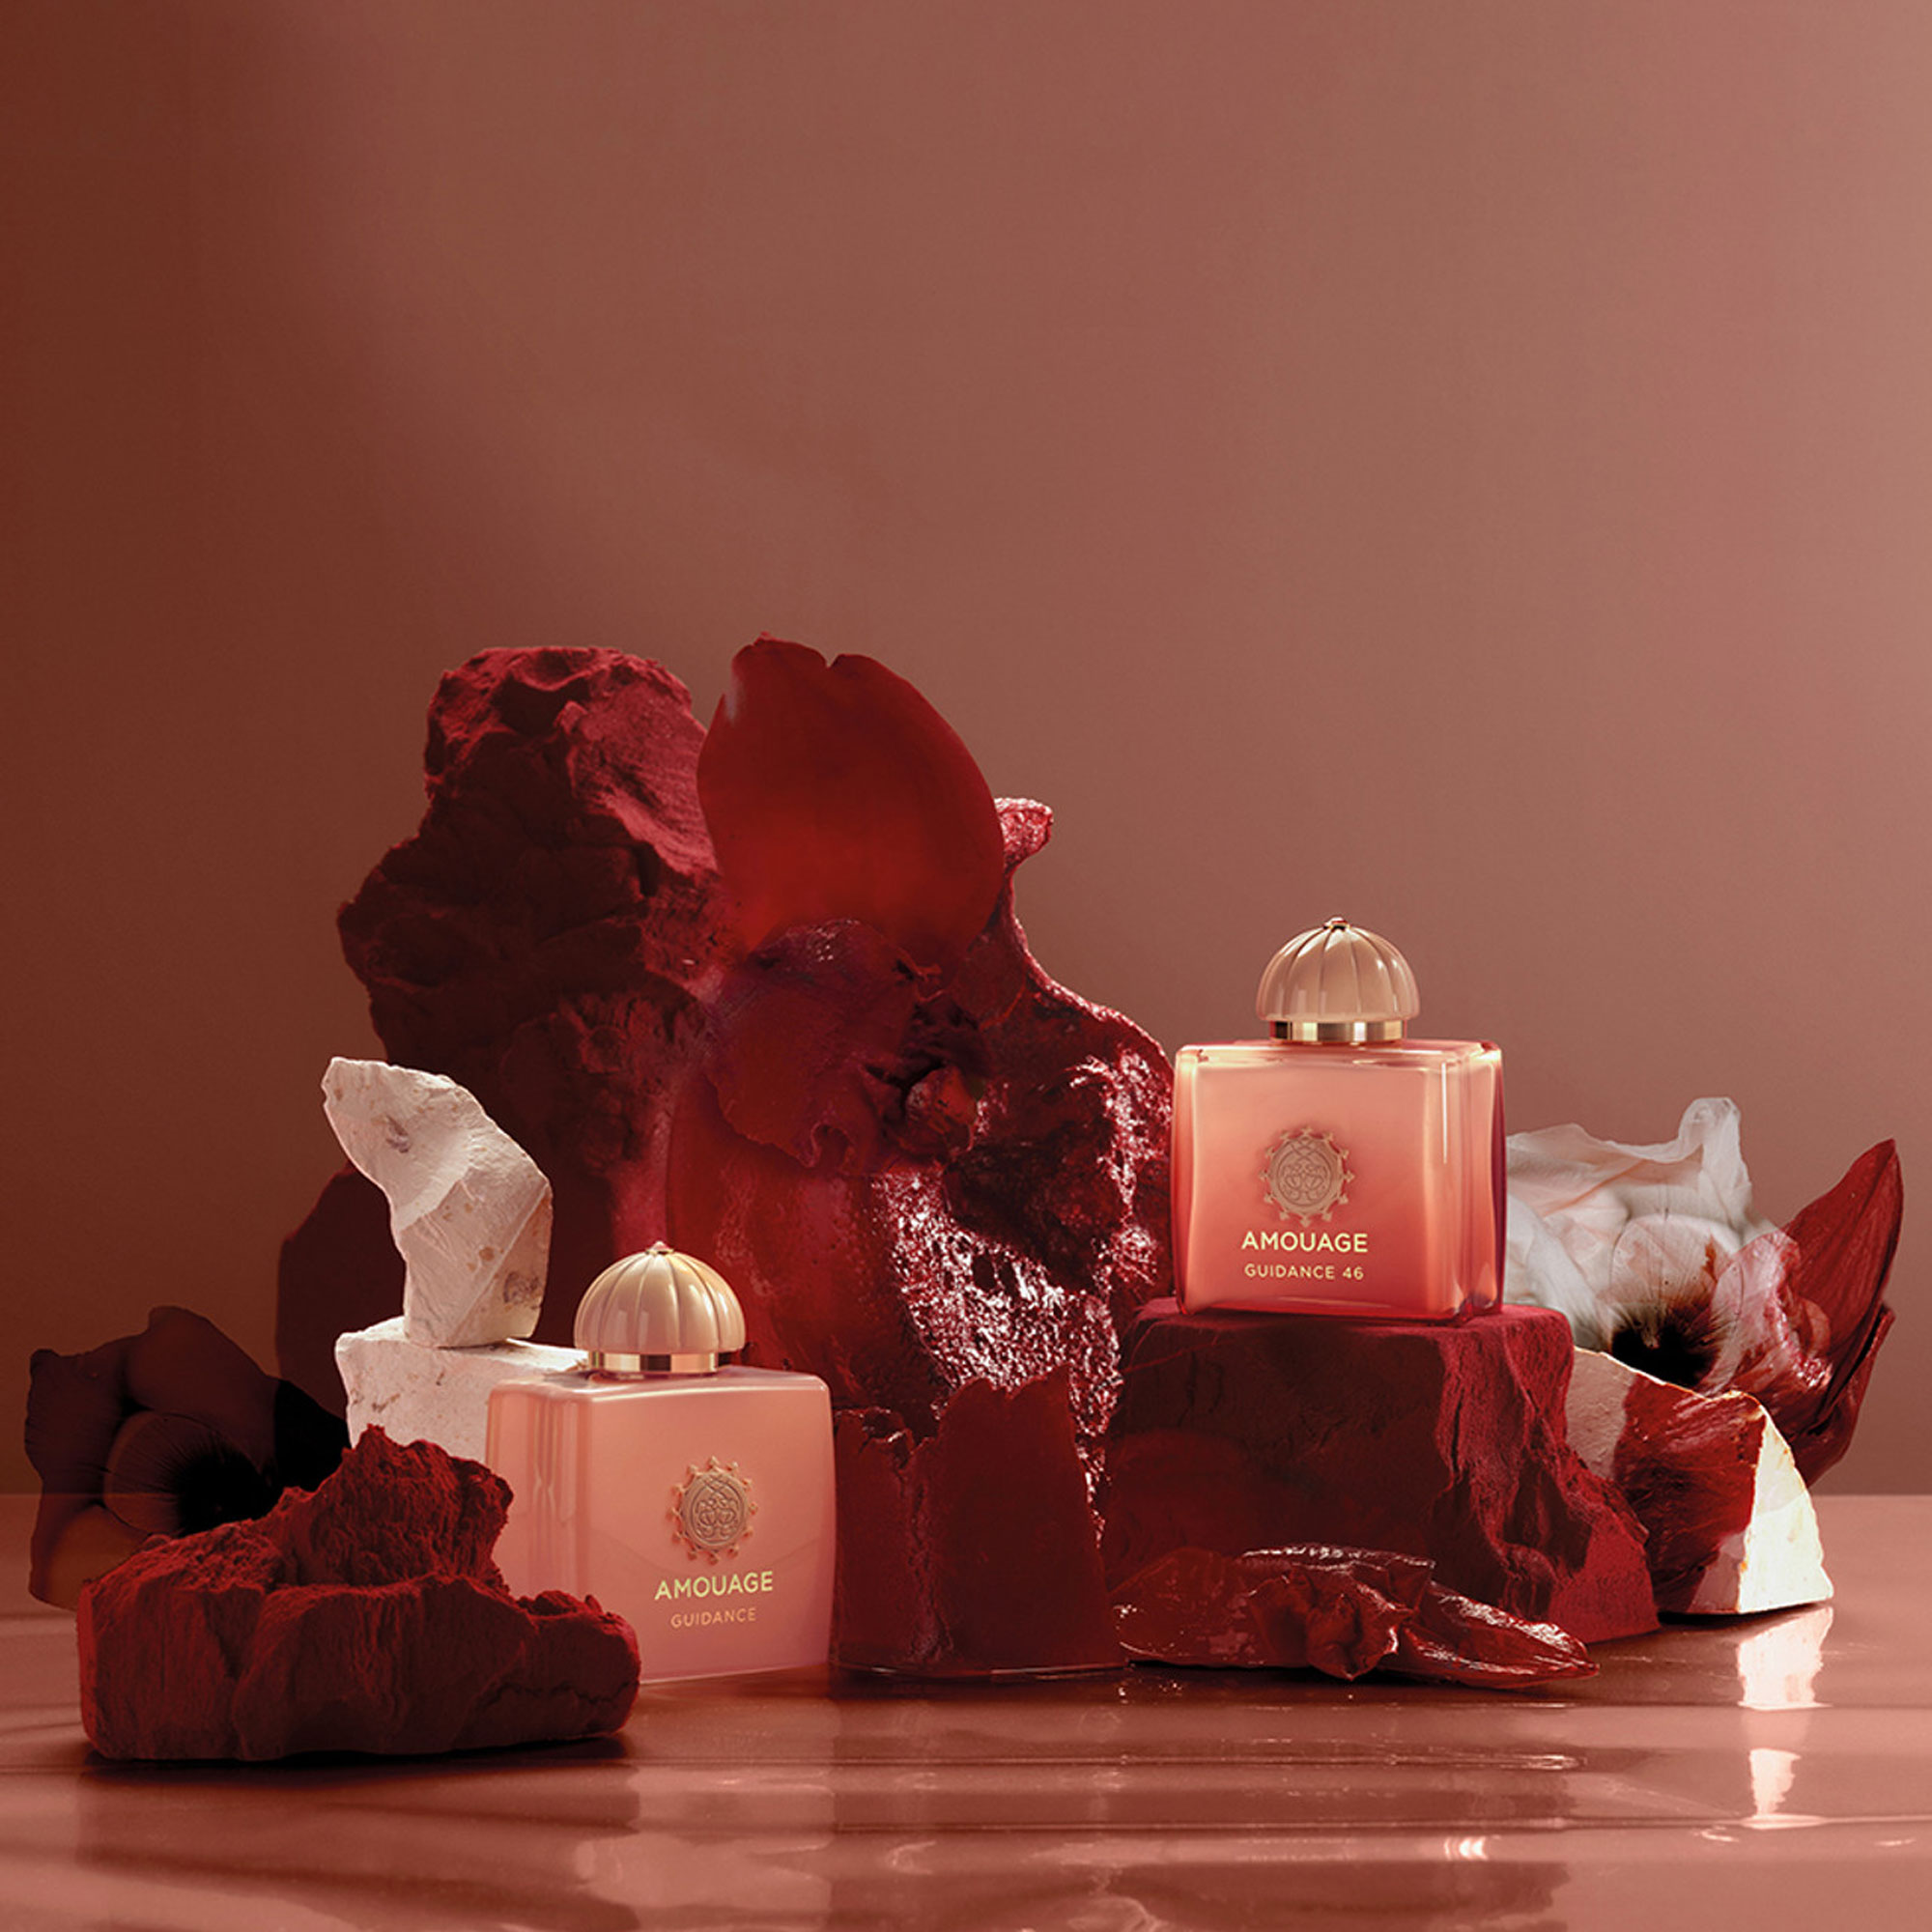
  • Amouage Opens First Standalone Boutique in Indonesia

    Amouage Opens First Standalone Boutique in Indonesia

    Omani perfume house Amouage opened its first standalone boutique in Indonesia at Plaza Indonesia in Jakarta in September 2026.

    Founded in Muscat in 1983, the brand operates in more than 80 countries under parent company Sabco Group.

    Architecture and Store Layout

    Inside the Jakarta boutique, the design draws on Omani geography and traditional building methods. Travertine stone walls, walnut timber, and brushed copper fixtures frame the interior alongside structured, layered arches.

    Display tables shaped like inverted pyramids mirror Oman’s mountain topography. At the center of the sales floor, a dedicated installation titled the Gift of Kings arranges bottles in a radial format beneath an illuminated orb.

    “Indonesia has a deep relationship with scent, craft, and hospitality, and an increasingly sophisticated luxury clientele looking for depth and originality,” said Amouage chief executive Marco Parsiegla.

    Southeast Asian Luxury Demand

    Standalone retail units give niche fragrance makers direct control over pricing, presentation, and customer data. Wholesale department store counters cannot match that access. High-end perfumery maintains strong operating margins in Southeast Asia, where affluent shoppers bypass heritage fashion-house scents for specialized, high-concentration formulations.

    For Indonesian luxury landlords, beauty flagships fill high-yield ground floor units with compact footprints that generate strong sales per square meter. The main operational challenge is sustaining foot traffic and repeat buyers in central Jakarta once opening buzz cools.

    Muscat Heritage and Regional Expansion

    Founded in Muscat in 1983, Amouage built its global business on heavy, resinous perfumes centered on regional ingredients like frankincense, rock rose, and ambergris.

    The Jakarta opening follows an entry into India five months earlier, when the brand launched at Mall of Asia in Bengaluru in April 2026. Amouage is pacing its retail rollout across major Asian metropolitan centers to build a wider network of company-operated doors through 2027.

  • Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian retailers have spent years adding digital touchpoints, but many are now getting slower at producing the experiences those platforms require as teams contend with cautious consumers and margin pressure. The operational challenge has mounted as websites, apps, marketplaces, loyalty programs, social commerce, and digital signage expand alongside physical stores.

    In many retail businesses, marketing teams and developers repeat work by building one version of a product launch for the website, another for the app, and separate material for email, social channels, and in-store displays. This fragmented production process leaves campaigns reaching one channel days after another while increasing the likelihood of inconsistent pricing and outdated product details.

    Ending Repetitive Channel Production

    When turning a single campaign into live assets requires weeks of handovers and developer queues, retail teams lose the capacity to personalize experiences or adapt to local trading conditions. To eliminate duplicated effort and lower costs, businesses are shifting toward composable models where product benefits, imagery, and promotional messages are created once and governed centrally.

    The alternative infrastructure treats product details, pricing banners, promotional terms, and media files as reusable modular components. Central governance teams control core brand messaging and product claims, while regional managers assemble approved components into distinct channel formats without writing custom code or rebuilding entire digital pages.

    Regional Adaptation and Guardrails

    For retail networks spanning diverse state territories and multiple brand banners, modular architectures protect brand standards while allowing localized commercial flexibility. Store managers can adapt pre-approved digital assets to reflect local inventory levels, regional weather events, and suburban community promotions without violating national brand guidelines.

    Across the wider Asia-Pacific retail sector, similar pressures have forced department store operators and convenience chains in Singapore, Tokyo, and Hong Kong to adopt composable technology architectures. Retailers that maintain monolithic content management systems risk falling behind agile pure-play operators who test, deploy, and retire promotional campaigns in hours rather than weeks. The primary operational risk sits in execution, as marketing teams often resist structural changes to publishing workflows without clear internal compliance mandates.

    The Operational Drag of Artificial Intelligence

    The operational shift follows several years of capital expenditure directed toward customer-facing channels, including social commerce integrations, automated locker networks, and mobile loyalty applications. While these investments widened customer reach, they divided digital production resources across disconnected content management software platforms.

    Recent deployments of generative artificial intelligence have highlighted these structural limitations. Retail operations that feed unstructured, fragmented catalogue data into automated generative tools produce inconsistent pricing and conflicting marketing claims at high speed, reinforcing the requirement for structured component databases.

    Merchandising and technology teams are now tracking campaign turnaround metrics and content reuse rates as key performance indicators ahead of the high-volume holiday trading period.

  • Cinnabon to Exit Singapore as Final Ion Orchard Store Closes

    Cinnabon to Exit Singapore as Final Ion Orchard Store Closes

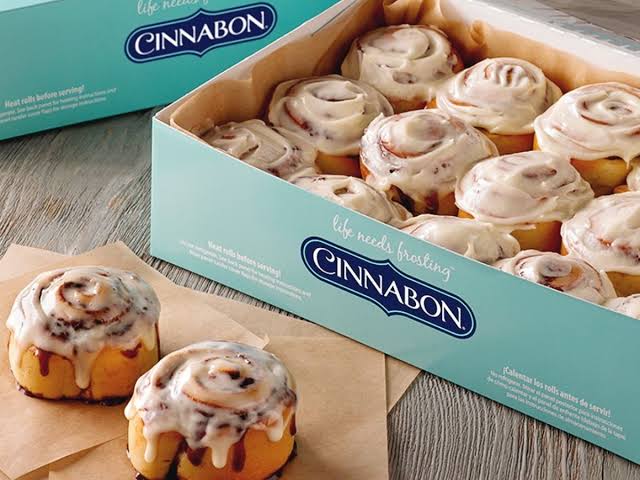
    Cinnabon will pull out of Singapore on September 22, shutting its final Ion Orchard outlet after a three-year comeback attempt failed to gain commercial traction. The closure leaves master franchisee Wabi-Sabi empty-handed against an initial target to build a network of 10 locations across the city-state within five years.

    The American cinnamon roll brand announced the wind-down on September 8, confirming that operations at its sole remaining store in Orchard Road will finish before the end of the month. Outlets at Raffles City Shopping Centre and Jewel Changi Airport have already ceased trading.

    High Rents and Footfall Realities

    Securing high-profile retail space in Singapore demands relentless sales volume to cover overheads. Single-category bakery concepts face a severe margin squeeze when novelty fades and everyday demand fails to match prime shopping mall rental rates. Ion Orchard, Raffles City and Jewel Changi offer heavy pedestrian traffic, but they rank among the most expensive commercial addresses in Southeast Asia.

    For food and beverage operators, relying on a narrow product catalogue creates immediate vulnerability when footfall shifts or local consumer spending tightens. While larger multi-brand operators can cross-subsidise prime leases, standalone single-concept franchisees bear direct exposure to rising mall rents and labour costs. Wabi-Sabi took on substantial lease commitments in premier corridors rather than testing lower-cost suburban clusters first.

    The Second Exit in Two Decades

    This shutdown marks the second time Cinnabon has abandoned the Singapore market. The chain previously operated in the city before closing its retail footprint in 2002. It returned in February 2023 with the Raffles City debut, aiming to build a broader local presence through standard units and smaller kiosk formats.

    Master franchisee Alvin Ng outlined plans at the launch to take the franchise into suburban residential hubs. Those outer-island locations never materialised, leaving the business dependent on tourist-heavy downtown malls where foot traffic fluctuates and local repeat purchases remain harder to lock down.

    Regional Footprint After Singapore

    The retreat from Singapore leaves Cinnabon adjusting its wider Southeast Asian strategy. The brand re-entered neighbouring Malaysia in mid-2024 with a different franchise partner, testing whether suburban mall clusters and lower operating costs in that market can sustain unit economics that proved unviable in Singapore.

    Final trading at the Ion Orchard store concludes on September 22, when Wabi-Sabi hands back the premises and Cinnabon officially vacates the Singapore market.

  • Spate and Vogue Business Track Top 5 Beauty and Wellness Trends

    Spate and Vogue Business Track Top 5 Beauty and Wellness Trends

    The Vogue Business Beauty Tracker, produced in collaboration with Spate, tracks the top 5 brands, trends, and ingredients driving significant year-on-year growth.

    Haircare search data from August 2025 to July 2026 highlighted growing interest in active follicle health solutions, including redensyl, peptide serums, and rice water hairspray.

    Clinical scalpcare leads hair category

    Brand interest centered on science-backed and premium solutions, with Labo-H trending for Korean scalpcare and hair loss prevention, alongside Bare Anatomy, UltraSwim, Iso Beauty, and Bvlgari Beauty.

    Swimming-specific cleansers from UltraSwim and salon-grade styling tools from Iso Beauty recorded steady increases, alongside luxury hybrid cleansers from Bvlgari Beauty. On TikTok, content centered on practical styling and protection gathered engagement, with hashtags for fast curly hair routines and freshwater mineral protection drawing steady viewership.

    Bodycare shifts to clinical active ingredients

    In body treatments, consumer preference moved toward exfoliating and brightening actives typically used in facial skincare during the July 2025 to June 2026 period. Alpha hydroxy acid body lotions, kojic acid formulations and hand exfoliators logged steady volume gains, alongside muscle recovery products such as epsom salt lotions.

    Brand interest concentrated on sensitive skin and barrier support lines. Australian brand QV Skincare recorded rising interest for barrier-repair lotions, while Curology drew search gains for dermatologist-led body acne treatments. Naked Bee expanded visibility for honey and oatmeal formulas, while Luna Daily captured queries for microbiome-balanced intimate care products.

    Functional delivery formats reshape wellness

    Wellness searches reflected demand for targeted, screen-free and non-pill formats over the 12 months to June 2026. Wearable dopamine patches for focus, acupressure wristbands for motion sickness, and screenless fitness trackers outpaced standard health devices in monthly search acceleration. Liquid zinc and male fertility nutritional supplements recorded higher query volumes across preventive health channels.

    Specialist wellness labels captured the shift toward single-benefit nutrition. Artemis Tea gained traction for organic herbal infusions, Nancy’s Probiotic logged search growth for cultured nutrition, and Sparkle Wellness grew search share through collagen powders targeting skin and joint vitality.

    For retailers across the Asia-Pacific region, the data confirms that personal care margins are shifting away from generic beauty counters toward specialized, clinical formulations. Department stores and health-and-beauty chains that allocate shelf space to dermatological actives and targeted scalp solutions will capture higher spend per basket than those relying on standard mass-market shampoos and washes.

    The risk sits with legacy beauty manufacturers that depend on generalized marketing claims without published active percentages. Consumers now search directly for specific compounds such as redensyl and kojic acid, leaving little room for unformulated private-label products to compete on price alone.

    This search acceleration builds on a two-year migration toward functional personal care across Asian metropolitan hubs, where scalp clinics and derma-skincare lines have steadily replaced multi-step cosmetic routines. Retail buyers in Seoul, Singapore and Mumbai spent late 2025 rebalancing shelf inventory toward pharmacy-adjacent brands.

    Merchandisers now look to fourth-quarter procurement orders to see whether high search volumes for topical actives translate into sustained reorder rates across regional drugstores through the first half of 2027.

  • Barambah Organics Founder Ian Campbell and Daughter Die in Plane Crash

    Barambah Organics Founder Ian Campbell and Daughter Die in Plane Crash

    Barambah Organics founder Ian Campbell, 56, and his daughter Hannah, 23, died in a light plane crash south of Brisbane on Monday.

    Campbell founded the dairy business alongside his wife Jane in 2002.

    The Tamara Capital Buyout and Brand Growth

    Private equity firm Tamara Capital bought a majority stake in the business in 2020 in a deal valuing it at $50 million, while the Campbell family kept a minority stake and continued to influence operations.

    Following the buyout, the business expanded distribution across Australian retail channels to supply independent grocers, organic specialists and national supermarket shelves. It established a dedicated processing network and direct farm supply model across regional Queensland and northern New South Wales.

    Dairy Sector Pressures and Market Position

    Australian premium dairy producers face cost inflation across cold chain freight, feed and energy. Premium organic labels rely on tight supply agreements and consistent volume to protect margins against conventional private-label milk pricing.

    Customer retention was built on single-source farm provenance and organic certification standards. Preserving brand equity and operational continuity now falls to the institutional investors and executive management installed following the 2020 acquisition.

    Operational History and Next Steps

    The Campbell family ran the business as an independent operation for 18 years. Outside capital was brought in to fund factory upgrades and broader national distribution.

    Aviation safety authorities continue to examine the site south of Brisbane to determine the mechanical factors and flight conditions surrounding the crash.