Tag: bank

  • Hang Seng Bank Coo Vivien Chiu Breaks Record With $5.14 Million Hong Kong Luxury Apartment Purchase

    Hang Seng Bank Coo Vivien Chiu Breaks Record With $5.14 Million Hong Kong Luxury Apartment Purchase

    Vivien Chiu, the Chief Operating Officer of Hang Seng Bank, has recently acquired a deluxe apartment in Hong Kong for HK$40 million, equivalent to around US$5.14 million. The cost per square foot of the 1,651 square-foot property amounted to HK$24,228, or US$33,517 per square meter, making it a record-setting purchase for the property in the current year.

    Property Details

    The luxury apartment is situated in the Beverly Hill project located in the Happy Valley area of Hong Kong. The property last changed owners in 2014 for a sum of HK$16 million. The recent handover took place on Monday, as per the Land Registry records.

    Chiu previously held positions in various departments at HSBC prior to her tenure at Hang Seng, which began in 2022.

    In a similar vein, Diana Cesar, the CEO of Hang Seng at the time, bought a flat in the upscale Flora Garden complex located in the Tai Hang Mid-Levels area in August, for a sum of HK$26.63 million.

    HSBC to Acquire Hang Seng

    Recently, HSBC announced its plans to acquire Hang Seng Bank for a staggering sum of HK$106.1 billion. Despite the bank’s recent struggles, Hang Seng will retain its own license, governance, and brand after the acquisition.

    This move comes as Hong Kong’s banking sector battles the most significant real estate slump since the late 1990s. Home prices in the city have dropped by approximately 30% from their peak in 2021.

    Housing Sector Recovery

    Despite the downturn, the housing sector has shown promising signs of recovery. According to data from the Rating and Valuation Department (RVD), the official index for second-hand home prices has increased by 1.26% since April. The index saw its fifth consecutive month of growth in August, reducing the overall decline in the year to just 0.24%.

    In August, some 5,291 homes changed ownership, representing an 8.2% decrease from July, but a 44.8% increase compared to the same period in the previous year. The total transaction value reached HK$42.2 billion, a decrease of 8.9% from the previous month but an increase of 48.2% year-over-year.

    Between January and August, the combined sales of new and existing homes increased by 10% from the previous year to 42,379 units. This is the highest level for this period in the past four years, as reported by property agency Midland Realty.

    Questions & Answers

    What is the total cost of the luxury flat purchased by Vivien Chiu?
    The total cost of the flat purchased by Vivien Chiu is HK$40 million, equivalent to around US$5.14 million.

    Who is the former owner of Hang Seng Bank, and what are the terms of the bank’s acquisition by HSBC?
    HSBC is the new owner of Hang Seng Bank. Despite the acquisition, Hang Seng will retain its own license, governance, and brand.

    What are the recent trends in Hong Kong’s housing sector?
    Home prices in Hong Kong have seen significant declines, but recent data shows signs of recovery with the index for second-hand home prices increasing by 1.26% since April.
  • Techcombank brings an AI-powered experience to 13,000 runners at the Hanoi International Marathon

    Techcombank brings an AI-powered experience to 13,000 runners at the Hanoi International Marathon

    The 4th Techcombank Hanoi International Marathon provides an AI-powered video experience for 13,000 runners. For the first time in Vietnam, an AI video generator enabled every runner to create a personalised video to recreate their race experience
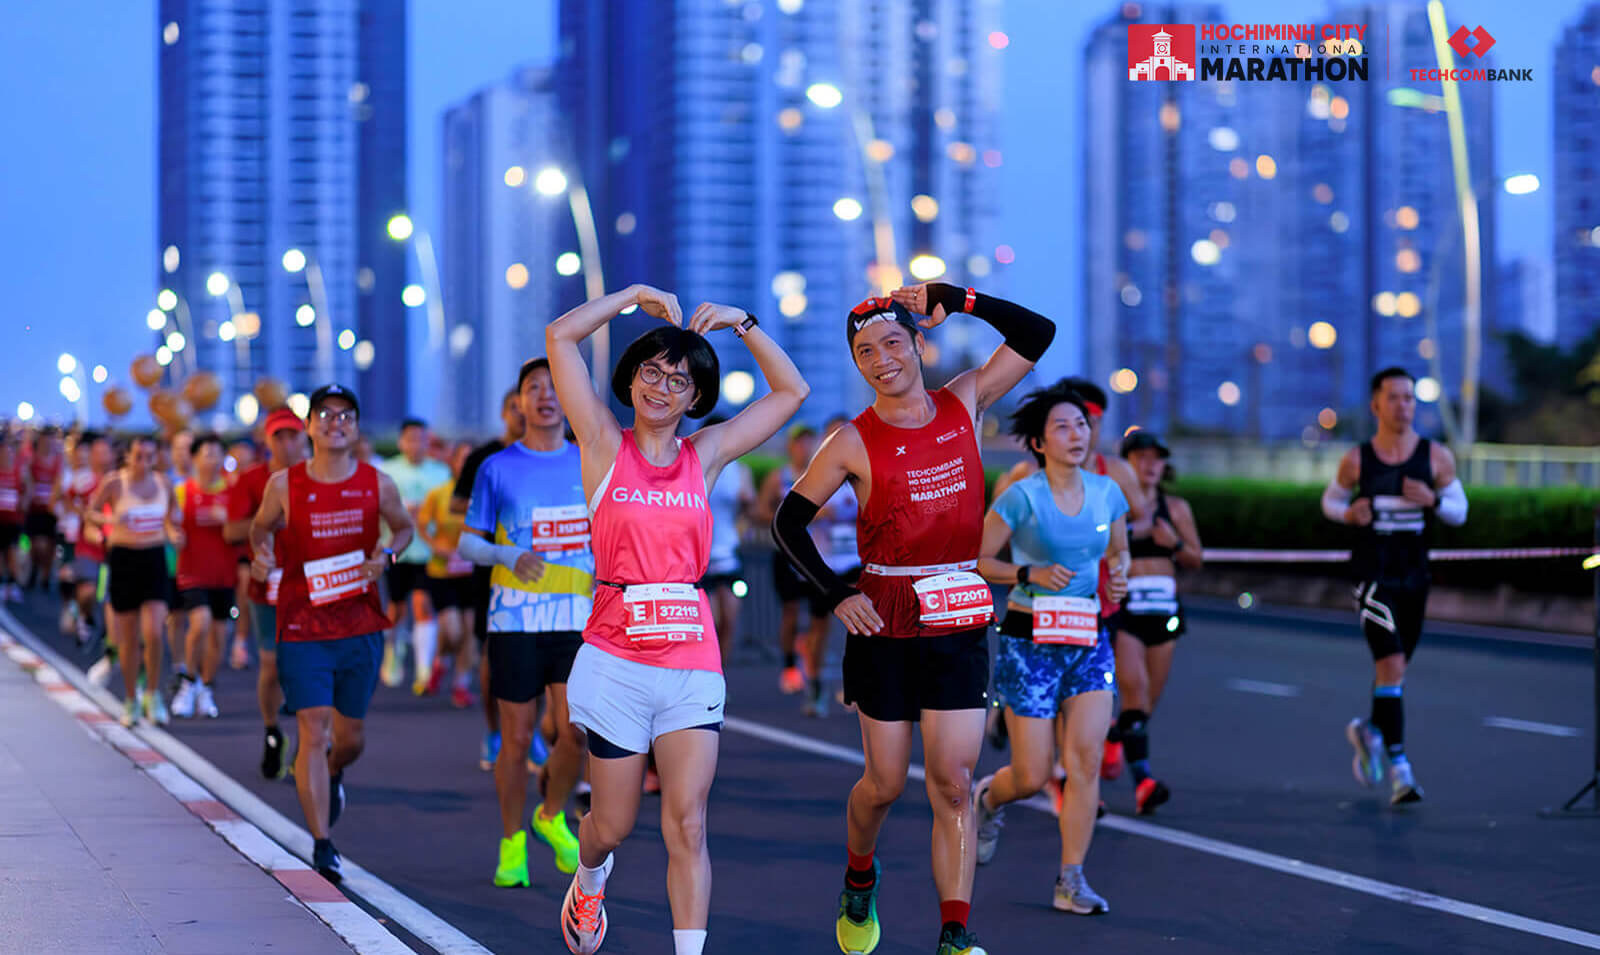
    Hanoi, October 8th, 2025 – Following the success of the previous three seasons, the 4th Techcombank Hanoi International Marathon was held on 5th October 2025 and attracted over 13,000 Vietnamese and international athletes who competed over courses running past many of Hanoi’s most iconic cultural landmarks. For the first time ever in Vietnam, an AI video generator enabled every runner to create a personalised video of their race to celebrate their achievement and spread the spirit of Run for a Greater Vietnam.

    The 4th Techcombank Hanoi International Marathon was held under the direction of the Hanoi People’s Committee, organized by the Hanoi Department of Culture and Sports, in collaboration with Vietnam Technological and Commercial Joint Stock Bank (Techcombank) and Sunrise Events Vietnam (SEV).

    A unique feature of this year’s marathon was the application of AI video generation technology on the racecourse to create personalized highlight videos for every runner. By uploading a photo of themselves to an AI video generator, each runner could receive a video within 24-36 hours that recreated their most memorable moments as they ran past the historic landmarks of Hanoi. These videos enabled every runner to become an ambassador for the Techcombank Hanoi International Marathon and Techcombank’s Run for a Greater Vietnam initiative.

    The 4th season of the Techcombank Hanoi International Marathon attracted nearly 1.5 times as many runners as the previous edition. Offering a well-designed racecourse passing through Hanoi’s most famous historic districts, a unique AI-powered video experience and organized to international standards, the event delivered a world-class experience for its runners.

    More than 13,000 runners from 51 countries and territories competed in the 4th Techcombank Hanoi International Marathon, turning Hanoi into a global meeting point. Participants in the races passed through five historic districts in Hanoi and saw many of the city’s most famous landmarks, including the Ho Chi Minh Mausoleum, Long Bien Bridge, and the National Assembly building. Notably, the half-marathon (21km) featured the oldest ever participant in a marathon in Vientam – an 81-year-old runner.

    Ms. Thai Minh Diem Tu, Chief Marketing Officer at Techcombank, said: “The 4th Techcombank Hanoi Marathon was a fantastic occasion that brought the community together, promoted physical fitness and enabled runners to experience the wonderful city of Hanoi. We believe that a Greater Vietnam is not only built on a strong economic foundation, but also on a healthy, connected, and aspirational community. This is why we continue to support the Techcombank Hanoi International Marathon as part of our long-term strategy to elevate the quality of life for Vietnamese people. For the first time ever in Vietnam AI technology has been used to give every runner a personalised highlights video of their race to enable them to share their experience and spread the spirit of Run for a Greater Vietnam in the community”.

    Techcombank’s Run for a Greater Vietnam initiative encompasses community engagement activities aimed at promoting healthy lifestyles among Vietnamese. These include support for the annual Techcombank Hanoi and Ho Chi Minh City International marathons, which in 2024 attracted over 28,000 runners across the two events.

    In addition to the official races, the 4th Techcombank Hanoi International Marathon event also offered a range of other activities for the community held over three days, from October 3 to October 5, 2025. The highlight of these activities was the KIDS RUN, which comprised two races for young athletes from 5 to 14 years, over distances of 1.5 km and 3 km.

    To coincide with the marathon, Techcombank contributed VND 2 billion to the “For the Poor” Fund of Hanoi to build community houses, the Hanoi Child Protection Fund, and the Hanoi Federations of Basketball, Cycling, and Motorsports. This contribution was part of Techcombank’s long-term strategic mission to create better lives, make a positive contribution to the community, and fulfill its corporate social responsibility for a sustainable future.

  • Asia Commercial Bank Launches Gold Bars as Bullion Monopoly Comes to a Close

    Asia Commercial Bank Launches Gold Bars as Bullion Monopoly Comes to a Close


    Asia Commercial Bank (ACB) is set to make waves in the gold market next Friday, becoming the first player to launch its own gold bar brand since the Vietnamese government lifted its long-standing monopoly on bullion production.

    The private lender is poised to buy and sell its newly branded gold bars alongside products crafted by the renowned Saigon Jewelry Company at select branches. The ACB-branded bullion will be available in various weights, while the Saigon Jewelry Company’s (SJC) offerings will be limited to bars weighing one tael, or 37.5 grams.

    For individuals looking to invest, the purchase and sale of these gold bars will require personal identification, whereas businesses will need to present a trading license. All transactions will be processed through ACB accounts, ensuring that customers receive an invoice for their purchases and are required to issue one when selling back to the bank.

    To enhance transparency, ACB will make pricing information accessible on its website and via the ACB One app. Additionally, the bank will impose certain fees for packaging and processing the metal—because even gold needs a bit of pampering!

    Prior to this shift, SJC enjoyed a monopoly on gold bar production for over a decade, with the government’s recent decision in late August allowing the State Bank to license any qualifying entity for importing and manufacturing gold bars.

    As the dust settles on this changing landscape, Pham Quang Thang, an executive at Techcombank, has revealed that his institution is also gearing up to introduce its own line of gold bars. The bank is already in the process of establishing production facilities and distribution channels, with online sales on the horizon.

    Questions & Answers

    What does ACB’s move into gold bar production signify for the market?
    ACB’s launch marks a significant shift in the Vietnamese gold market, as it is the first private bank to enter this space following the end of SJC’s monopoly, opening the door for more competition.

    How will customers be able to purchase ACB gold bars?
    Customers will need to present personal identification for individual purchases, while businesses must show a trading license. Transactions will be processed through ACB accounts, ensuring a reliable buying and selling experience.

    Are other banks planning to enter the gold market as well?
    Yes, Techcombank is also preparing to launch its own gold bars, highlighting a growing trend among private lenders to capitalize on the newly competitive bullion market.

  • Singapore’s Investment Banking Fees Surge 31.5% in First Nine Months of 2025

    Singapore’s Investment Banking Fees Surge 31.5% in First Nine Months of 2025

    In a remarkable surge, Singapore’s investment banking landscape has shown robust growth, with estimated fees reaching $683 million in the first nine months of 2025, marking a notable 31.5% increase from the same period last year, according to data from the London Stock Exchange Group (LSEG). This uptick is underpinned by a significant rise in equity capital markets (ECM) underwriting and merger and acquisition (M&A) advisory fees, both of which more than doubled.

    Bright Spots in the ECM and M&A Arenas

    Equity capital markets underwriting fees soared to a four-year high of $140.1 million, showcasing the renewed confidence among investors. This rise indicates a flourishing ecosystem where companies are more eager to tap into public capital. Meanwhile, the advisory fees from M&A transactions rocketed 105.3% to reach $238.9 million, illustrating a vigorous appetite for deal-making in the region.

    Debt Market Gains and Lending Declines

    The Debt Capital Market (DCM) also experienced growth, with fees climbing 44.5% to $126.8 million. However, it’s a mixed bag for the syndicated lending sector, which saw fees decline by 29.3%, down to $177.2 million, reflecting a cooling in that particular area of finance.

    Citi and Morgan Stanley Dominate the Landscape

    In terms of institutional leaders, Citi proudly secured the top spot in Singapore’s investment banking fee rankings, commanding an 8.3% share of the wallet with $57 million in fees. Morgan Stanley, not to be outdone, led the M&A league table, with transactions totaling $4.4 billion, representing an 8.2% market share. It’s almost like they are competing for the title of “Investment Banking Champion” in Singapore’s bustling financial arena.

    Singapore’s Banking Giant Takes Charge

    DBS Group Holdings has also made significant strides, topping both the equity and bond underwriting league tables. Singapore’s largest bank by assets reported an impressive $661.3 million in equity-linked proceeds alongside $4.7 billion in bond underwriting proceeds. This solid performance affirms DBS’s dominant position in the financial sector, as it continues to set benchmarks for competitors in the market.

    Questions & Answers

    What factors contributed to the increase in investment banking fees in Singapore?
    The rise in fees is largely driven by a doubling of ECM underwriting and M&A advisory fees, signaling increased investor confidence and a robust appetite for acquisitions.

    How did Citi and Morgan Stanley perform in the investment banking sector?
    Citi led in overall investment banking fees with an 8.3% market share, while Morgan Stanley topped the M&A table, handling $4.4 billion in transactions, showcasing their strong foothold in Singapore’s competitive environment.

    What trend is evident in the syndicated lending fees?
    Syndicated lending fees experienced a notable decline of 29.3%, suggesting a potential cooling off in that segment, possibly due to changing market conditions and investor preferences.

  • Bankers Association Sounds Alarm as UBS Stands Firm on New Big Bank Regulations

    Bankers Association Sounds Alarm as UBS Stands Firm on New Big Bank Regulations

    Rethinking Banking Regulations: The SBA Takes a Stand

    Amid the fallout from the Credit Suisse crisis, the Swiss Bankers Association (SBA) has raised its voice against the Federal Council’s aggressive plans to overhaul capital requirements for foreign subsidiaries. The SBA argues that the issues at play were not the low capital requirements themselves, but rather the extensive exemptions granted by the financial regulator Finma to various institutions.

    “The lesson is clear: we must eliminate these exemptions moving forward,” the SBA stated in a recent announcement. “Yet the Federal Council intends to substantially increase capital requirements for foreign subsidiaries—a move that lacks international precedent and is divergent from practices in other financial hubs like the U.S. and Europe.”

    New Rules, New Risks: Impact on Competitiveness

    The SBA warns that the Federal Council’s proposed changes could diminish the attractiveness of conducting international business from Switzerland—a significant concern given that approximately half of the 9.3 trillion francs in assets managed in the country originates from foreign clients. The association contends that it is naive to think the burden of increased costs can simply be offloaded onto international clients. Ultimately, it would be the entrepreneurs, customers, and local clients who pay the price through more expensive loans and diminished services, triggering a decline in Swiss competitiveness.

    Calls for Deliberation: Assessing Economic Impact

    In light of these proposals, the SBA is advocating for a balanced, internationally coordinated approach to regulatory changes. They insist that a thorough economic impact assessment is crucial before implementing any drastic measures. The association noted that while the Federal Council recognizes regulatory relief as a critical economic objective, this vision must also extend to banking regulations. The message is clear: finance and industry are intertwined, and the SBA pledges its commitment to contribute constructively to this ongoing discussion.

    UBS Takes a Stand: Concerns Over Proposed Capital Increases

    UBS has weighed in on the matter, expressing that while they are reviewing the government’s latest documents, they generally support most of the proposals put forth by the Federal Council on June 6, 2025, provided these changes are implemented in a “targeted, proportionate, and internationally aligned” manner.

    However, UBS draws the line at the proposed hikes in capital requirements, labeling them “extreme” and misaligned with global standards. The bank argues that the lessons from Credit Suisse’s collapse have not been adequately prioritized. UBS elaborated that compliance with the new requirements would mean adding an additional USD 24 billion in CET1 capital to the already mandated USD 18 billion, resulting in a total of USD 42 billion. This scenario would push UBS’s CET1 ratio to around 19 percent, soaring above the average required for globally systemic banks—by at least 50 percent.

    Questions & Answers

    What are the main concerns of the Swiss Bankers Association regarding the Federal Council’s proposals?
    The SBA is particularly concerned that the increased capital requirements for foreign subsidiaries will make international business less appealing, which could ultimately lead to higher costs for entrepreneurs and clients in Switzerland.

    How does UBS view the proposed capital increases following the Credit Suisse crisis?
    UBS firmly rejects the proposed hikes, calling them extreme and not aligned with international standards. They argue that they would force UBS to hold an unsustainable amount of capital, significantly above the average for global banks.

    What does the SBA suggest for future regulatory changes?
    The SBA calls for a comprehensive economic impact assessment before implementing drastic policy shifts and stresses the need for international coordination to ensure that regulatory relief is genuinely achieved in banking.

  • DBS’s Multi-Family Office VCC Reaches Milestone with S$1 Billion in Assets Under Management!

    DBS’s Multi-Family Office VCC Reaches Milestone with S$1 Billion in Assets Under Management!

    In a remarkable feat, DBS Private Bank’s multi-family office has soared to a record S$1 billion in assets under management (AUM) merely two years post-launch. The DBS Multi Family Office Foundry VCC (DBS MFO), which debuted in 2023, proudly claims the title of the world’s first bank-backed multi-family office. Since its inception, this financial innovator has attracted 25 ultra-high-net-worth (UHNW) families from across the globe, according to a press release from Singapore’s largest bank issued on September 23, 2025.

    Intriguingly, many of these families initially contemplated establishing their own single-family offices (SFO) in Singapore. However, DBS has successfully enticed them with appealing features including “cost optimization, manpower benefits, and streamlined administration” offered by the DBS MFO.

    Among the appealing services provided is a “plug-and-play” solution that allows families to set up a sub-fund through DBS. This arrangement automatically qualifies for tax incentives through the Variable Capital Company (VCC) structure. Furthermore, DBS takes care of ongoing regulatory reporting, ensuring that capital is professionally managed within the bank’s robust framework.

    To join this exclusive club, clients need an investment of just S$15 million, and intriguingly, there’s no requirement to invest exclusively in DBS products. This flexibility has clearly resonated with clients: as of September 2025, DBS has a hand in more than one-third of Singapore’s established SFOs, showcasing significant growth as its Family Office AUM has more than doubled in just two years.

    Lee Woon Shiu, group head of wealth planning, Family Office & Insurance Solutions at DBS Private Bank, noted that client interest in succession planning and wealth preservation is surging. DBS is currently engaging with over 15 prospective clients who are exploring the potential of the DBS MFO as an attractive solution to their financial needs. “We are on track to achieve our goal of doubling our AUM by the end of 2026,” Lee confidently asserted.

    Questions & Answers

    What is the DBS Multi Family Office offering that differentiates it from traditional family offices?
    DBS MFO provides a bank-backed model that includes streamlined administration, cost optimization, and a “plug-and-play” sub-fund setup benefiting from tax incentives.

    How much do clients need to invest to qualify for DBS MFO?
    Clients are required to invest a minimum of S$15 million, which opens the door to a range of tailored wealth management services.

    What future targets does DBS aim to achieve with its multi-family office?
    DBS is aiming to double its assets under management to S$2 billion by the end of 2026, propelled by increasing client interest in succession planning and wealth preservation.

  • Revolut Unveils Ambitious Multi-Billion Expansion Plan to Revolutionize Retail Banking

    Revolut Unveils Ambitious Multi-Billion Expansion Plan to Revolutionize Retail Banking

    Revolut Embarks on Bold Expansion Journey

    The British fintech giant Revolut marked a significant milestone this Tuesday with the unveiling of its new global headquarters in London, paired with an ambitious growth strategy that promises to reshape the financial landscape.

    Over the next five years, the company aims to channel a remarkable 11.5 billion euros into its operations, a move set to create 10,000 new jobs worldwide. This investment includes a substantial 3.4 billion euros earmarked for the United Kingdom and an additional billion for France, signaling a strong push in key European markets.

    Europe and Latin America: A Dual Focus

    Revolut is reinforcing its foothold in Europe with a newly established hub in Paris and plans for new branches in Portugal and Belgium. This strategic expansion marks an exciting phase for the fintech, effectively connecting it to a larger audience across the continent.

    Turning its gaze to Latin America, Revolut is gearing up to operate as a bank in Mexico by early 2026, with intentions to extend its reach to Colombia and Argentina soon after. The company is also actively seeking new banking licenses in the Asia-Pacific, Middle East, and African regions. Recently, it secured approval to provide payment services in the United Arab Emirates, a noteworthy step in its global ambitions.

    Innovative Marketing and the Buzz Around Switzerland

    Beyond its financial endeavors, Revolut is making waves in the marketing arena with its newly announced collaboration with the Audi F1 Team. This partnership, which includes plans for limited edition co-branded cards, is likely to create a buzz among motorsport enthusiasts and financial fans alike — imagine driving down the track with your banking details at the speed of light!

    However, the company remains tight-lipped about its plans for the Swiss market. Despite ongoing speculation over the past few years about obtaining a banking license in Switzerland, there’s still no official confirmation from Revolut on this front.

    Questions & Answers

    What is Revolut’s total investment plan over the next five years?
    Revolut plans to invest a staggering 11.5 billion euros worldwide over the next five years.

    Which new markets is Revolut targeting in Latin America?
    In Latin America, Revolut aims to begin banking operations in Mexico by early 2026, with future expansions planned for Colombia and Argentina.

    What marketing partnership is Revolut pursuing?
    Revolut has partnered with the Audi F1 Team, planning to roll out limited edition co-branded cards as part of its marketing strategy.

  • UOB Joins Forces with Hengfeng Bank and Shangao Holdings to Propel Chinese Firms’ Global Expansion

    UOB Joins Forces with Hengfeng Bank and Shangao Holdings to Propel Chinese Firms’ Global Expansion

    UOB has embarked on an exciting collaboration with Hangfeng Bank Co. Ltd. and Shangao Holdings Group Limited, marking a significant stride toward fostering green development and infrastructure. Announced on September 18, 2025, this tripartite memorandum of understanding aims to enhance financial solutions that empower Chinese businesses seeking to extend their reach overseas, particularly in areas tied to sustainable transformation.

    Empowering Cross-Border Trade and Investment

    The partnership will focus on a myriad of financial services, including cross-border trade financing, investment banking, and tailored advisory services that resonate with the goals of the Belt and Road initiative. As the global focus shifts towards sustainability, UOB’s initiative underscores a pivotal blend of finance and environmental consciousness.

    Profiles in Investment: Shangao and Hangfeng

    Shangao Holdings, a subsidiary of Shandong Hi-Speed Holdings Group, has carved a niche in industrial investments revolving around new energy and infrastructure. The company plays a crucial role in managing vital transportation assets like toll roads, bridges, and rail transit facilities. Meanwhile, Hangfeng Bank, rooted in Shandong province, is celebrated for its transaction banking prowess and cross-border capabilities—ideal complements to UOB’s expansive regional network and Shangao’s investment acumen.

    A Remarkable Signing Event

    The memorandum was officially signed at the opening ceremony of the 2025 Singapore-Shandong week held at Marina Bay Sands, a fitting venue for such an ambitious partnership. UOB’s executive director for corporate wealth management, Janice Leong, represented the bank, joined by Shen Zhenghua, general manager of Hangfeng Bank’s transaction banking department, and Li Tianzhang, chairman of Shangao Holdings Group. The trio’s signatures symbolize a commitment to not only growth but also to a greener future, proving that when money talks, it can also advocate for the planet.

    Questions & Answers

    What are the main objectives of the partnership between UOB, Hangfeng Bank, and Shangao Holdings?
    The primary goals include providing financial solutions that support Chinese enterprises expanding internationally, with a focus on sectors aligned with green transformation, such as sustainable infrastructure.

    How will the collaboration benefit businesses in China?
    This partnership will facilitate cross-border trade financing and investment banking services, thereby easing international expansion for Chinese businesses while promoting sustainable practices.

    Where was the memorandum of understanding signed?
    The MOU was signed during the opening ceremony of the 2025 Singapore-Shandong week at the prestigious Marina Bay Sands in Singapore.

  • OCBC Commits to Empower 10,000 Women Entrepreneurs with Social Loans by 2030

    OCBC Commits to Empower 10,000 Women Entrepreneurs with Social Loans by 2030

    In a bold move to empower female entrepreneurship across Southeast Asia, OCBC Bank has set its sights on a big goal: to provide social loans to 10,000 women entrepreneurs by 2030. This initiative, aimed at small and medium enterprises (SMEs), spans Singapore, Malaysia, Hong Kong, and Indonesia, marking a significant commitment to fostering economic growth among women-owned businesses.

    Achievements So Far

    As of June 2025, OCBC has made impressive strides, supporting over 2,000 women-owned SMEs with social loan commitments nearing $600 million. This support is part of a larger vision to increase financial accessibility for women entrepreneurs, who often face unique challenges in securing funding.

    Tailored Programs for Women Entrepreneurs

    OCBC’s initiatives include the OCBC Women Unlimited Programme, which was launched in Singapore in April 2024 and introduced in Malaysia in August 2025. In Indonesia, the initiative takes the form of the Women Warriors Programme, which has been operational since 2020. These programs don’t just provide capital; they aim to cultivate an ecosystem where women entrepreneurs can thrive.

    Understanding the Challenges

    The data paints a compelling picture: one in three of OCBC’s SME customers across Singapore, Malaysia, Indonesia, and Hong Kong are women. However, it also highlights a stark reality — women-owned SMEs in Singapore report approximately 30% lower sales turnover growth in their first three years compared to their male counterparts. Fortunately, those who secure financing through OCBC’s initiatives have shown the capacity to close this gap, demonstrating the transformative power of financial support.

    The Road Ahead

    With ambitious plans to extend its reach and enhance the financial landscape for women entrepreneurs, OCBC is not just banking on numbers; it’s betting on the untapped potential of women-led businesses in Asia. In a future where every woman entrepreneur can dream big, OCBC aspires to be the catalyst that turns those dreams into reality.

    Questions & Answers

    How many women-owned SMEs has OCBC supported so far?
    OCBC has supported over 2,000 women-owned SMEs across Southeast Asia as of June 2025.

    What kind of financial assistance does OCBC offer to women entrepreneurs?
    OCBC provides social loans of up to S$100,000 for women-owned SMEs within their first two years of incorporation, with waived processing fees for these loans.

    How do sales turnovers compare for women-owned SMEs versus male-owned ones?
    Women-owned SMEs in Singapore typically experience about 30% lower sales turnover growth in their first three years compared to male-owned SMEs, however, those that secure financing can bridge this gap.

  • Raiffeisen Unveils Exciting Strategy Extension: A New Chapter for Growth!

    Raiffeisen Unveils Exciting Strategy Extension: A New Chapter for Growth!

    Raiffeisen Delays New Strategy: Aiming for Cohesion at the Top

    Raiffeisen has announced a significant shift in its strategic planning timeline, opting to unveil a new group strategy at the end of 2026 instead of the previously anticipated date. This one-year delay is a strategic move to ensure that both the incoming chair of the board and the newly appointed CEO, Gabriel Brenna, have a hand in shaping the bank’s future direction, as the institution stated in a recent release.

    The new board chair is set to be elected during the general meeting scheduled for June 2026. Current chair Thomas Müller has confirmed he will not seek re-election, leaving the board in search of a successor—a process that is still actively underway. In a game of musical chairs, the position has become particularly crucial, with the leadership baton passing hands in a race against time.

    Turning the page, Brenna will officially step into the CEO role in December 2025, succeeding Heinz Huber, who announced his resignation in December 2024. By synchronizing these changes, Raiffeisen seems keen on building a cohesive leadership team—one that can navigate the complex landscape of the banking sector, perhaps hoping to avoid any hiccups that could lead to strategic misalignment. After all, in the world of retail banking, an indecisive leader can be like an empty shopping cart: lacking direction and prone to drift.

    Questions & Answers

    Why has Raiffeisen decided to delay its new group strategy?
    Raiffeisen has postponed its strategy rollout to ensure that both the new CEO and the incoming chair of the board can participate in the development process, fostering a more cohesive leadership vision.

    When will the search for a new board chair be resolved?
    The election for the new chair is set for June 2026, with the current chair, Thomas Müller, opting not to seek re-election.

    What changes are expected with the new CEO Gabriel Brenna?
    Gabriel Brenna is set to take over in December 2025, succeeding Heinz Huber, marking a pivotal moment in Raiffeisen’s leadership and strategic direction as he shapes the future of the bank.

  • UOB Upgrades Vietnam’s 2025 GDP Growth Forecast to an Optimistic 7.5%

    UOB Upgrades Vietnam’s 2025 GDP Growth Forecast to an Optimistic 7.5%

    Vietnam’s economy is on a remarkable upswing, with the latest data from UOB’s Global Economics & Markets Research unit indicating a booming GDP expansion of 7.52% in the first half of the year—the fastest growth for this period since 2011. This vibrant increase is largely driven by a notable 14% surge in exports, fueled further by a boost in market sentiment following U.S. President Donald Trump’s temporary reduction of reciprocal tariffs to a baseline rate of 10% for 90 days.

    Tariff Landscape and Future Projections

    The elimination of tariff uncertainties in the second half of the year has set the stage for Vietnamese exports, with specific rates now locked in ahead of the August deadline. Vietnam faces a 20% levy but remains hopeful; UOB forecasts a solid 10% growth in exports for 2025, building on last year’s impressive 14% growth.

    Manufacturing and Foreign Investments Flourish

    Additional indicators reflect Vietnam’s economic resilience. The Manufacturing Purchasing Managers’ Index (PMI) rebounded to 52.4 in July, emerging from three months of contraction. Meanwhile, industrial output surged by 9% year-on-year, indicating robust manufacturing activity amidst fluctuating global conditions.

    Foreign direct investment (FDI) has also shown signs of vitality, reaching $13.6 billion as of July, a rise from $12.6 billion the previous year. Analysts suggest that full-year inflows could exceed $20 billion, although this would still trail last year’s total of $25.4 billion.

    A Bold Infrastructure Investment Plan

    In a bid to solidify growth, Vietnam’s government announced an ambitious $48 billion infrastructure investment plan in mid-August, encompassing 250 projects. This plan prioritizes urban development and transport, with 129 projects financed at a cost of $18 billion, while the remaining 121 projects—valued at $30.5 billion—will attract financing from foreign entities.

    Glimmers of Optimism in Monetary Policy

    UOB maintains its outlook for 2026 at a consistent 7% growth rate, with the Vietnamese government aiming for a target GDP growth of 8.3-8.5% for the current year. UOB analysts suggest that the strong second-half outlook, coupled with ongoing pressures on the Vietnamese dong, will likely keep the central bank’s refinancing rate steady at 4.5%. If drastic weakening of business conditions occurs, a reduction to a pandemic-era low of 4% could be considered—though this scenario remains unlikely.

    On the currency front, the dong may find itself struggling to capitalize on a potential weakening of the U.S. dollar, likely to occur once the Federal Reserve begins to cut rates. Nevertheless, UOB forecasts that dollar exchange rates will ease gradually, projecting VND26,300 in the last quarter of this year, VND26,200 in the following quarter, and VND26,000 by the third quarter of 2026.

    Questions & Answers

    How is Vietnam’s GDP growth in the first half of this year compared to past years?
    Vietnam’s GDP grew by 7.52% in the first half of the year, marking the fastest expansion for that period since 2011.

    What are the key drivers behind this growth?
    The robust growth is primarily attributed to a significant 14% increase in exports, supported by positive market sentiment following tariff reductions announced by the U.S. government.

    What steps is the Vietnamese government taking to sustain economic growth?
    Vietnam unveiled a $48 billion infrastructure investment plan covering 250 projects, with a focus on urban development and transport, showing a strong commitment to enhancing economic foundations.

  • Dollar Experiences Slight Dip Against Dong in Black Market Trading

    Dollar Experiences Slight Dip Against Dong in Black Market Trading

    The U.S. dollar fell against the Vietnamese dong on the black market Saturday morning despite a global gain.

    Dollar Moves in Unexpected Ways

    The U.S. dollar dipped by 0.24% to VND 26,950 at unofficial exchange points on Saturday. This drop occurred even as the greenback gained globally, highlighting the fluid dynamics at play in foreign exchange markets.

    Official Rates Hold Steady

    Meanwhile, Vietcombank maintained its official exchange rate at VND 26,476, while the State Bank of Vietnam opted to keep its rate unchanged at VND 25,216. This stability in local rates contrasts sharply with the movements observed in the black market, where traders often respond more acutely to shifts in sentiment and market conditions.

    A Global Context

    In the broader global landscape, the dollar had a mixed day on Friday, recovering slightly after experiencing a downturn fueled by a rise in U.S. jobless claims and a slight increase in inflation. As anticipation builds ahead of next week’s Federal Reserve meeting—where analysts speculate a potential interest rate cut could take place after a substantial pause—the currency faces additional scrutiny.

    Yen and Dollar Dynamics

    The dollar gained 0.2% against the yen, reaching 147.53 yen. This marks three consecutive weeks of growth against the Japanese currency. The latest U.S.-Japan joint statement emphasized the importance of allowing markets to dictate exchange rates, urging against excessive volatility. Traders have keenly absorbed this messaging, further influencing market behavior.

    Trends on the Dollar Index

    The dollar index remained relatively stable at 97.59, yet it is poised for its second straight weekly decline, with a 0.1% drop over the week. This slight shift signals traders’ cautious approach as they navigate uncertainties ahead in the market.

    Questions & Answers

    How did the U.S. dollar perform against the Vietnamese dong on the black market?
    The U.S. dollar fell by 0.24% to VND 26,950 at unofficial exchange points, contrasting with its global gains.

    What exchange rates did Vietcombank and the State Bank of Vietnam set?
    Vietcombank maintained its rate at VND 26,476, while the State Bank of Vietnam kept its rate unchanged at VND 25,216.

    What context surrounds the dollar’s performance globally?
    The dollar experienced mixed results as it recovered from a decline caused by increased U.S. jobless claims and an uptick in inflation ahead of a Federal Reserve meeting that might lead to interest rate cuts.

  • Revolut Taps Former SocGen CEO to Spearhead Expansion in Western Europe

    Revolut Taps Former SocGen CEO to Spearhead Expansion in Western Europe

    In a strategic expansion move, Revolut has appointed banking heavyweight Frédéric Oudéa to chair its newly established Western Europe operation, intensifying its focus on growth in France and beyond.

    The fintech powerhouse, valued at an impressive $75 billion, is ramping up activities in Paris where it is in pursuit of a French banking license. The company plans to hire up to 200 staff and allocate a substantial €1 billion investment to support its expansion efforts.

    From Société Générale to Fintech Innovator

    Oudéa, a seasoned leader who guided Société Générale through 15 transformative years post-global financial crisis, sees his new role as an exciting avenue to participate in a bold venture combining cutting-edge technology with robust financial backing. With ambitions to double its French customer base to 10 million by next year, Revolut is gearing up to launch mortgage and savings products tailored for the French market.

    Globally, the neobank now caters to approximately 60 million customers, eclipsing traditional banking giants like HSBC. The company reported an impressive 72 percent revenue increase last year, which amounted to £3.1 billion. Its bid for a banking license in France adds to its existing EU authorization from Lithuania, though its UK banking license remains under regulatory scrutiny since 2024.

    Swiss Operations Remain Unchanged—For Now

    Despite Oudéa’s new moniker as Western Europe chairman, Revolut reassured that operations in Switzerland will remain unaffected in the immediate term. The company indicated in a communication “For our Swiss customers, nothing changes for now.” With whispers of a possible Swiss banking license in the air, the company is clearly not resting on its laurels.

    The leadership team for Revolut’s Western Europe board is taking shape and currently features Oudéa alongside independent member Brigitte Cantaloube, Western Europe CEO Béatrice Cossa-Dumurgier, group risk and compliance chief Pierre Décoté, group banking chief Siddhartha Jajodia, and independent member Pascal Pincemin.

    Questions & Answers

    What is Frédéric Oudéa’s new role at Revolut?
    Oudéa has been appointed as chairman of Revolut’s Western Europe operation, where he will oversee the expansion of the company in France and other parts of the region.

    What are Revolut’s expansion plans in France?
    Revolut aims to double its French customer base to 10 million next year while launching new mortgage and savings products, supported by a €1 billion investment and the hiring of up to 200 new staff.

    Will the changes in Western Europe affect Revolut’s operations in Switzerland?
    Currently, Revolut has stated that its operations in Switzerland will remain unchanged despite the new Western Europe setup, although there are speculations about a potential Swiss banking license in the future.

  • Philippine Banks Experience Robust 11.8% Surge in Loans for July

    Philippine Banks Experience Robust 11.8% Surge in Loans for July

    Outstanding loans from universal and commercial banks experienced an 11.8% year-on-year increase in July 2025, as reported by the Bangko Sentral ng Pilipinas (BSP). This figure, although slightly tempered, still builds on the robust growth seen in June, where loan growth reached 12.1%.

    Consumer Loans Remain Robust

    Loans extended to residents rose by 12.4% in July, just shy of June’s 12.6% growth. Interestingly, consumer lending, which encompasses credit cards, motor vehicles, and general-purpose salary loans, surged by 23.6% in July, a tad less than the 24% registered in June. Clearly, the appetite for personal credit remains strong—perhaps indicative of consumers gearing up for that much-anticipated summer getaway.

    Business Loans Show Mixed Trends

    However, not all sectors are firing on all cylinders. Loans to non-residents fell by 8.1% in July, a sharper decline compared to the 6.4% drop noted the previous month. On the brighter side, loans designed for business activities saw an increase of 10.8%, cooling slightly from June’s 11.1% growth. Real estate lending also showed resilience, climbing by 10.7%.

    Sector-Specific Lending Insights

    Among the standout performers, loans connected to electricity, gas, steam, and air-conditioning supply skyrocketed by an impressive 30.3%. Additionally, the wholesale and trade sector, along with repairs of motor vehicles and motorcycles, benefited as loans rose by 8.5%. In the spheres of financial and insurance activities, lending increased by 13.1%, while the information and communication sector witnessed an 8.5% growth.

    Questions & Answers

    What was the overall trend in loan growth in July 2025?
    Loan growth in July 2025 was 11.8%, a slower pace than June’s 12.1% growth, but still indicative of a continuing upward trend.

    How did consumer loans perform in July?
    Consumer loans expanded by 23.6% in July, reflecting strong demand for credit despite a slight decrease from June’s 24% growth.

    Which sectors experienced notable growth in lending?
    Lending for electricity and utility services surged by 30.3%, while real estate loans grew by 10.7%. Additionally, loans for financial activities climbed by 13.1%.

  • Over 370,000 Singapore Bank Customers Embrace Innovative Money Lock Feature for Enhanced Security

    Over 370,000 Singapore Bank Customers Embrace Innovative Money Lock Feature for Enhanced Security

    In a striking demonstration of caution, over 370,000 bank customers in Singapore have embraced the innovative Money Lock feature, collectively safeguarding more than $30 billion from potential scams as of June 30. This initiative, highlighted in the Singapore Police Force’s Mid-Year Scam and Cybercrime Brief 2025, marks a significant shift in how consumers approach digital banking security.

    A New Guard Against Cybercrime

    Launched in December 2024 by the Monetary Authority of Singapore (MAS) and the Infocomm Media Development Authority (IMDA), the Shared Responsibility Framework (SRF) seeks to bolster accountability among financial institutions and telecommunications companies. Under this framework, these entities are now directly liable for losses incurred from phishing scams—an essential move in the ongoing battle against digital fraud.

    Enhanced Security Measures on the Horizon

    Recent developments show that the SRF is not just a paper tiger; it comes with actionable measures. As of June 16, 2025, banks have implemented a novel fraud surveillance duty to monitor suspicious transactions more closely, specifically targeting rapid withdrawals from customer accounts. Expect to see major retailers buttressing security further by instituting cooling-off periods for high-risk banking activities, like adjusting transaction limits or altering personal information—steps designed to give users a moment to reconsider potentially risky decisions.

    Brace for Friction: Security Takes Center Stage

    Looking to the future, MAS is partnering with banks to roll out a Fast IDentity Online (FIDO)-compliant hardware token. This device, which customers must insert into their devices for high-value online transactions, may introduce added friction, but the police emphasize that ensuring customer safety is paramount, even if it momentarily complicates legitimate transactions. After all, in a world rife with digital threats, a little inconvenience can go a long way in preserving one’s finances.

    As the financial landscape continues to evolve, authorities remain steadfast in encouraging customers to utilize the Money Lock service, which offers an extra layer of security against potential breaches in their digital banking capabilities. “Banks will continue to champion this service as a crucial tool to limit possible losses for customers whose accounts might be compromised,” a police spokesperson noted.

    Questions & Answers

    What is the Money Lock feature and how does it help consumers?
    The Money Lock feature allows customers to secure a portion of their funds, preventing digital withdrawals and thereby shielding them from potential scams.

    What significant policy was rolled out alongside the Money Lock feature?
    The Shared Responsibility Framework (SRF) was implemented to enhance accountability among banks and telecom firms regarding losses from phishing scams.

    What proactive measures are banks taking to address fraud risk?
    Banks are introducing cooling-off periods for risky transactions and are collaborating with MAS to implement hardware tokens that provide an additional layer of security for high-value transactions.