Tag: Finance

  • Citi Unveils Enhanced Tokenisation and Real-Time Solutions for Corporate Treasuries

    Citi Unveils Enhanced Tokenisation and Real-Time Solutions for Corporate Treasuries

    Citigroup, Inc. is ratcheting up its foray into tokenization and automation, responding to the growing demand from corporate treasuries for real-time access to liquidity and global cash visibility. The bank’s latest suite of digital services is designed specifically to dismantle operational challenges linked to traditional banking cut-off times, public holidays, and regional time zones.

    “The absence of real-time visibility into cash positions across multiple accounts often leads to myriad challenges, such as ineffective cash forecasting and inefficient allocation,” explained Stephen Randall, global head of liquidity management services at Citi, in a recent interview with Asian Banking & Finance. “These issues can increase operational costs, elevate risk levels, and hamper strategic decision-making.”

    According to Citi’s November 2023 research, top-tier treasury operations are characterized by advanced forecasting capabilities and a centralized liquidity pool. This growing expectation from clients has compelled banks to innovate continuously to keep pace. “There is a pressing demand for enhanced speed and greater volumes in cash flows,” Randall added, mentioning clients’ desire for improved visibility and easier reconciliation processes.

    In response, Citi has launched several groundbreaking initiatives, including Citi Token Services (CTS), Real-Time Funding (RTF), and 7-Day Sweeps, all geared towards optimizing cash positioning while reducing operational friction. CTS enables clients to transfer cash instantaneously across borders, free from the typical constraints of holidays or banking hours. “Asia is a focal point for CTS; two of the four markets currently operational are Singapore and Hong Kong,” said Randall.

    Meanwhile, Real-Time Funding stands out as a game changer, allowing clients to transfer funds globally among their Citi accounts in real time. “Imagine a client needing to make an urgent payment from their Citi Hong Kong account today, but their money is stuck in a Citi London account,” Randall said. “With RTF, that funds transfer becomes instantaneous, enabling timely payments without cumbersome manual processes.” Presently, RTF is available in Australia, Hong Kong, and the UK, with plans for expansion into Singapore, Thailand, China, and Taiwan on the horizon.

    Additionally, Citi’s 7-Day Sweeps service automates liquidity management round-the-clock and is now operational in the US, South Korea, and Thailand. Randall pointed out that these sweeps are processed even on holidays, significantly reducing reconciliation challenges and providing a robust liquidity buffer over weekends and public holidays.

    The dynamic landscape of treasury management is shifting, with treasurers moving away from static liquidity structures—often evaluated annually—to more adaptable frameworks that can respond swiftly to cash flow volatility. “Treasurers are looking for liquidity structures that can handle abrupt cash flow changes, especially in light of the market uncertainties imposed by geopolitical shifts and tariff-related disruptions,” said Randall.

    Moreover, as clients confront risks associated with fluctuating interest rates and foreign exchange, they increasingly seek digital solutions and advisory support from Citi. Automation and digitalization offer crucial advantages, providing timely access to vital data on global cash positions—information that is instrumental for informed decision-making.

    Citi Treasury Diagnostics, the bank’s global benchmarking tool, serves to highlight how clients’ treasury operations measure up against best practices. The bank provides advanced programming interfaces such as Balance Inquiry and Payment Status, along with integration support, to enable clients to enhance their treasury systems.

    Randall emphasized that tools like Citi Treasury Diagnostics can assist clients in benchmarking their practices, revealing opportunities for further improvements through automation. He encouraged clients to leverage technology-driven services to minimize dependency on manual processes while refining and automating their operations.

    Questions & Answers

    How is Citigroup addressing the needs of corporate treasuries?
    Citigroup is introducing innovative solutions like Citi Token Services, Real-Time Funding, and 7-Day Sweeps to enhance cash visibility and streamline operations for corporate treasuries.

    What are the benefits of Real-Time Funding?
    Real-Time Funding enables clients to make global fund transfers instantaneously, allowing immediate access to cash for urgent payments without manual intervention.

    How is Citi’s 7-Day Sweeps service beneficial for liquidity management?
    The 7-Day Sweeps service automates liquidity management around the clock, processes transactions on holidays, and helps maintain a healthy liquidity buffer, reducing reconciliation difficulties.
  • AEON Bank and foodpanda Partner to Boost Digital Banking Adoption for Riders and Merchants

    AEON Bank and foodpanda Partner to Boost Digital Banking Adoption for Riders and Merchants

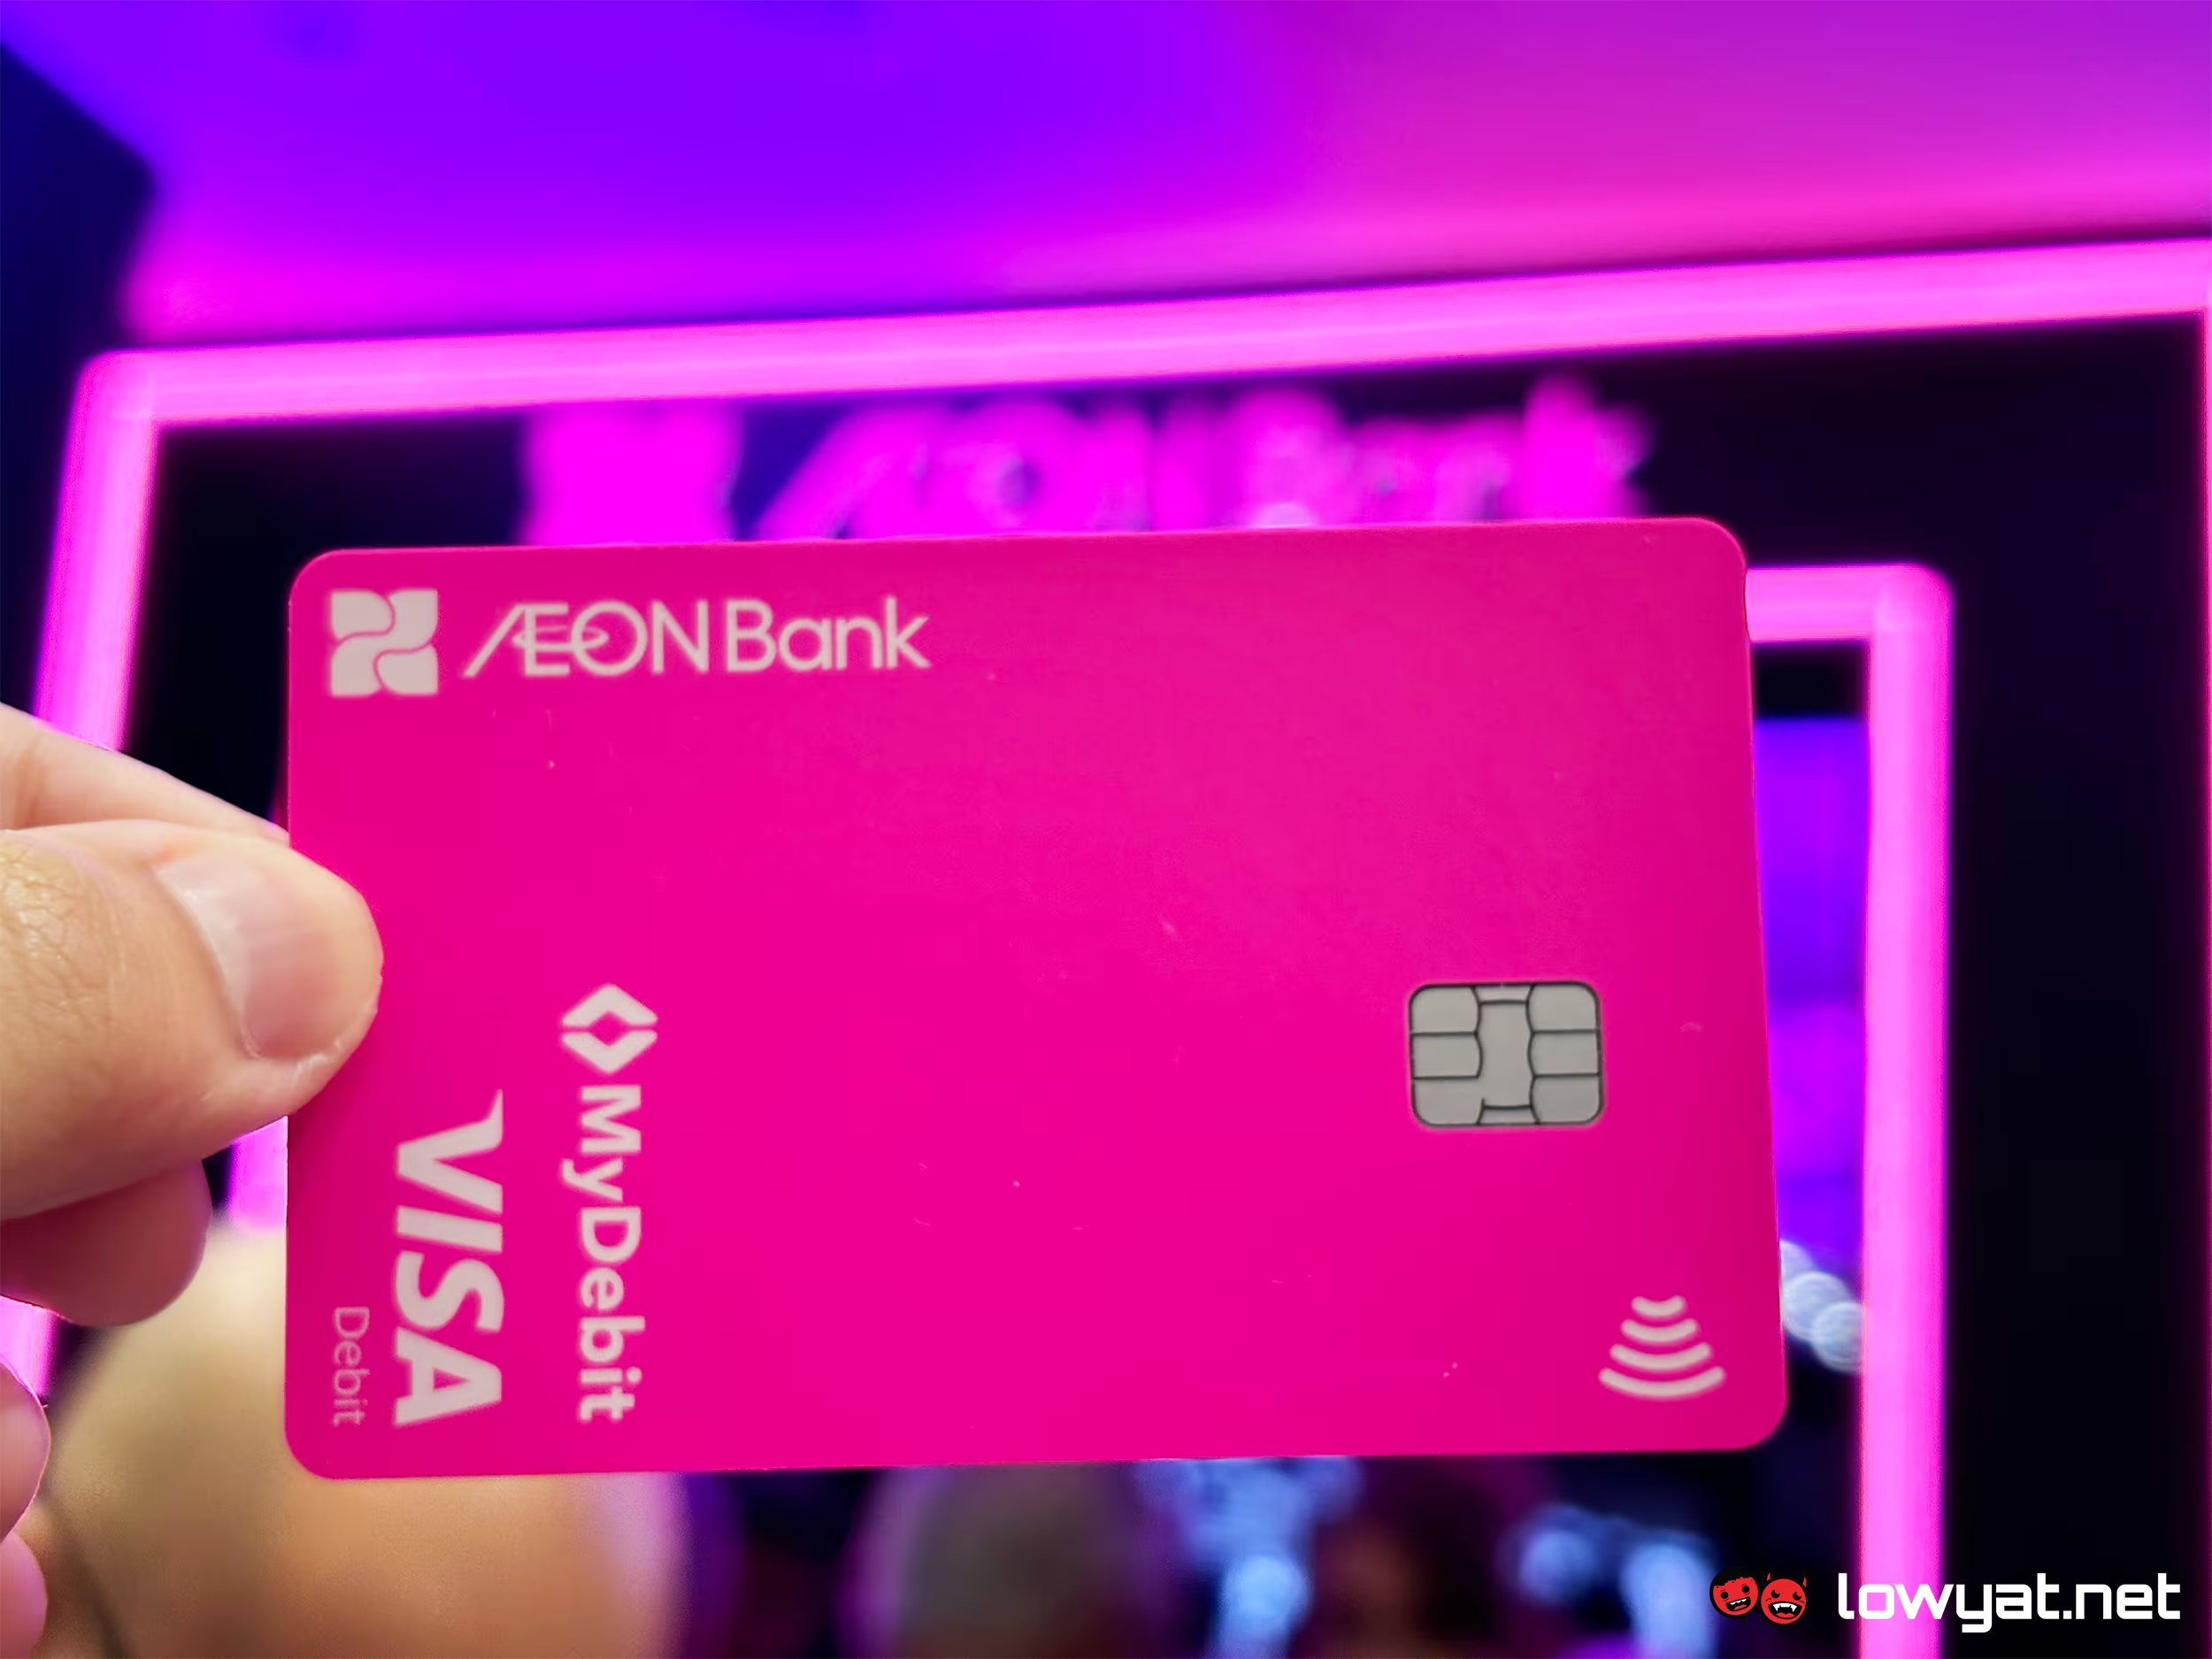
    In a significant move to enhance digital banking access, AEON Bank has announced a partnership with foodpanda Malaysia aimed at boosting financial services among the platform’s extensive user base, which includes customers, delivery riders, merchants, and business partners. This collaboration, formalized under a memorandum of understanding, seeks to combine their strengths in customer acquisition, digital financing, and joint promotional campaigns.

    A Bold Step for Islamic Digital Banking

    As Malaysia’s first Islamic digital bank, AEON Bank stands at the forefront of innovation in finance. “We are excited to bring added value to foodpanda’s riders and merchants by providing them access to digital banking, rewards programs, and services that will enhance their overall experience,” stated YM Raja Datin Paduka Teh Maimunah Raja Abdul Aziz, the bank’s CEO.

    Linking Platforms for Greater Impact

    The partnership aims to utilize foodpanda’s vast network in conjunction with AEON Bank’s Shariah-compliant financial products and AEON Points loyalty program. Teh Maimunah emphasized that this integration will significantly impact target segments, particularly gig workers and micro, small, and medium enterprises (MSMEs). “Our goal is to drive growth and engagement within these communities,” she added, hinting at a future where digital banking and food delivery intersect seamlessly.

    The Future of Food Delivery and Online Grocery Shopping

    Both companies are optimistic about contributing to Malaysia’s burgeoning food delivery and online grocery sector. Projections suggest that user penetration in this market could climb to 34.2% by 2025, translating to over 14.5 million users by 2030. Who knew that a simple meal delivery service could serve as a gateway to financial empowerment?

    Signing the memorandum of understanding were Teh Maimunah and Tan Ming Luk, the Managing Director of foodpanda Malaysia, marking the beginning of a partnership that promises to reshape the digital finance landscape for many in Malaysia.

    Questions & Answers

    What is the main goal of the partnership between AEON Bank and foodpanda Malaysia?
    The partnership aims to enhance digital banking access and services for foodpanda’s wide array of users, including customers, riders, and merchants, while fostering customer acquisition and growth for both companies.

    How does AEON Bank intend to support gig workers and MSMEs through this collaboration?
    AEON Bank plans to provide Shariah-compliant financial products and integrate its AEON Points loyalty program to offer meaningful services that cater to the specific needs of gig workers and micro, small, and medium enterprises.

    What are the projected figures for Malaysia’s food delivery and online grocery sector?
    User penetration in this sector is expected to reach 34.2% by 2025, with forecasts indicating over 14.5 million users by the year 2030.

  • Vietnam Sets Ambitious Goal to Launch International Financial Center by Year-End

    Vietnam Sets Ambitious Goal to Launch International Financial Center by Year-End

    Vietnam is embarking on an ambitious initiative to establish an International Financial Center (IFC), a move poised to attract medium and long-term financial investments that will serve as a cornerstone for the nation’s socio-economic development. In tandem with this effort, the Vietnamese government is committed to finalizing a legal framework for the IFC, promoting a transparent and coordinated environment that will appeal to capital, cutting-edge technologies, modern management practices, and high-caliber talent from around the globe.

    Building Infrastructure for Financial Success

    To power the IFC’s ambitious goals, essential infrastructure and services—including transportation, telecommunications, and logistics—will see significant upgrades in Ho Chi Minh City and Da Nang. With a target of finalizing key infrastructure projects by late 2025, the government aims to create a web of seamless connectivity that supports the IFC’s operations.

    A Vision for a Modern Financial Ecosystem

    The overarching plan includes the development of a sophisticated financial ecosystem—think carbon and commodity exchanges—while championing innovative financial services like fintech and digital banking. The initiative also underscores the importance of establishing international-standard support services in legal, auditing, and technology domains.

    Key Locations Take Center Stage

    Ho Chi Minh City is prioritized for the development of the IFC facility, which will extend across 793 hectares in the Saigon, Ben Thanh, and Thu Thiem wards. The city is also tasked with deploying a 5G network, laying the groundwork for flawless digital transactions that will underpin fintech and digital banking initiatives.

    Conversely, Da Nang is directed to enhance its technological capabilities, focusing on investing in computing server systems and intelligent operational infrastructure at Software Park No. 2. The city will promote the rollout of 5G coverage while also exploring blockchain technologies to pilot digital asset products, all the while establishing national standards for IoT, Big Data, and data management.

    Leadership Driving Change

    Prime Minister Chinh formalized this significant strategy with a decision on August 1, launching the Steering Committee dedicated to shaping Vietnam’s IFC vision. Featuring notable leaders like Permanent Deputy Prime Minister Nguyen Hoa Binh and key figures from the finance and banking sectors, the committee will guide the government’s strategic direction and ensure the IFC operates smoothly amidst Vietnam’s burgeoning financial landscape.

    Who knew a country could be both a tech playground and a financial powerhouse? As Vietnam builds its international financial center, the risk is high but the potential gains are tantalizingly close on the horizon.

    Questions & Answers

    What is the primary goal of Vietnam’s International Financial Center initiative?
    The initiative aims to attract medium and long-term financial investments, laying a foundation for Vietnam’s socio-economic growth while creating a robust legal framework for the financial center.

    Which cities are at the forefront of this financial movement?
    Ho Chi Minh City and Da Nang are the primary locations for the International Financial Center, with each city focusing on enhancing essential infrastructure and technological capabilities.

    Who is overseeing the development of Vietnam’s IFC?
    The effort is being guided by a Steering Committee headed by Permanent Deputy Prime Minister Nguyen Hoa Binh, alongside key leaders from various sectors of government and finance.

  • Singaporeans Boost Gold Investments by 37%, Signaling Strong Market Confidence

    Singaporeans Boost Gold Investments by 37%, Signaling Strong Market Confidence

    Singapore’s investment in gold bars and coins surged by 37% year-on-year, reaching 2.2 tonnes in the second quarter. Although this figure falls short of the record high of 2.5 tonnes observed in the first quarter, the World Gold Council indicates a strong upward trend in gold investments. Meanwhile, in Southeast Asia, gold investment also flourished, with notable double-digit growth reported in Indonesia, Malaysia, and Thailand. In contrast, Vietnam saw a 20% decline in gold investment, a discrepancy that raises eyebrows.

    On the jewelry front, Singaporeans are growing cautious. Gold jewelry demand fell by 8%, totaling 1.5 tonnes, largely influenced by soaring gold prices that restricted consumer purchasing power. This trend mirrors a broader global decline in jewelry consumption, which has dropped to levels reminiscent of the pandemic.

    Globally, investment in gold bars and coins witnessed an 11% uptick, amounting to 306.8 tonnes. Chinese investors led the charge with 115 tonnes, complemented by Indian investors contributing 46 tonnes. Interestingly, European net investment doubled to 28 tonnes, while the U.S. found itself on a different trajectory—demand for gold bars and coins plummeted by half to just 9 tonnes in the second quarter.

    Looking ahead, the World Gold Council cites geopolitical tensions, market volatility, and macroeconomic uncertainty as factors that will continue to fuel investment demand for gold. It also notes that the performance of the U.S. dollar will be crucial for institutional investors moving into the second half of the year. With many analysts predicting a structurally weaker dollar, the stage is set for intriguing shifts in the gold market.

    Questions & Answers

    What percentage increase did Singapore experience in gold investment in the second quarter?
    Singapore’s gold investment rose by 37% year-on-year in the second quarter, totaling 2.2 tonnes.

    How did the demand for gold jewelry in Singapore change recently?
    Gold jewelry demand in Singapore declined by 8%, reaching 1.5 tonnes, largely due to record-high gold prices.

    Which regions showed notable growth in gold investment during the second quarter?
    In Southeast Asia, gold investments increased significantly in Indonesia, Malaysia, and Thailand, all reporting double-digit growth compared to the previous year.

  • Vietnam Gold Prices Approach Historic Highs: What This Means for Investors and the Market

    Vietnam Gold Prices Approach Historic Highs: What This Means for Investors and the Market

    On Saturday, the price for gold bars from Saigon Jewelry Company surged by 1.73%, hitting VND123.5 million (approximately US$4,710.14) per tael, tantalizingly close to the historic peak of VND124 million set on April 22. Gold rings also saw a bump, climbing 1.62% to VND119 million per tael, with a tael equaling 37.5 grams or 1.2 ounces.

    Since January, the price of gold in Vietnam has skyrocketed by 47%, reflecting a broader pattern of investment interest amid evolving economic conditions.

    On the global stage, gold prices surged nearly 2% to reach a one-week high on Friday, driven by disappointing U.S. payroll data that heightened expectations for rate cuts from the Federal Reserve, as well as new tariff announcements that increased demand for safe-haven assets. In fact, spot gold, which peaked at its highest since July 25, saw an impressive rise, adding 1.8% to $3,347.66 per ounce after flirting with a 2% increase earlier in the day. Over the past week, bullion notched a 0.4% gain.

    “Although payroll figures came in below forecasts, they were slightly higher than the market anticipated. This enhances the likelihood that the Federal Reserve will consider rate cuts later this year,” remarked Bart Melek, head of commodity strategies at TD Securities, to Reuters. Indeed, gold, often regarded as a non-yielding asset, tends to thrive in a low-interest-rate environment, leaving investors on the edge of their seats to see how this plays out.

    Questions & Answers

    How much have gold prices in Vietnam increased since the beginning of the year?
    Gold prices in Vietnam have jumped 47% since the start of the year.

    What recent economic data influenced the rise in gold prices globally?
    Weaker-than-expected U.S. payroll data played a crucial role in boosting expectations for Federal Reserve rate cuts, which in turn heightened demand for gold as a safe-haven asset.

    What were the recent price movements for gold bars and rings in Vietnam?
    Gold bars increased by 1.73% to VND123.5 million per tael, while gold rings rose by 1.62% to VND119 million per tael.

  • Hong Kong’s Stablecoin Legislation: A New Era for Wealth Management and Payment Innovations!

    Hong Kong’s Stablecoin Legislation: A New Era for Wealth Management and Payment Innovations!

    Hong Kong’s recently enacted stablecoins ordinance is poised to shake up the local banking landscape, particularly in the realm of digital payments. As these digital currencies emerge, they may create fresh competition for banks while simultaneously providing new opportunities in wealth management. “Stablecoins issued in Hong Kong could increase competition for banks, particularly in wholesale payments, due to potential advantages in cost and speed,” stated Phyllis Liu, a credit analyst at S&P Global Ratings.

    Facing this evolving environment, local banks are expected to proactively participate in the market to mitigate the risk of disintermediation. Liu notes, “Hong Kong banks will seek to participate in the market to avoid disintermediation threats.” The new landscape could also bolster their wealth management services, drawing in more clients from mainland China and beyond.

    Michael Huang, another credit analyst for S&P, elaborates on this potential shift, suggesting that by offering stablecoin-linked products or digital assets, Hong Kong banks may appeal to both local and international customers eager for offshore crypto investments. It’s like a retail revival for the financial sector, where traditional banking meets the digital frontier.

    The interest in Hong Kong’s stablecoin market is described as “very strong,” with the Hong Kong Monetary Authority indicating that it plans to issue a limited number of stablecoin licenses. “We anticipate first movers will likely be big tech companies and large banks that have deep resources and technological skills,” remarked S&P, hinting at an exciting intersection of technology and finance in the city’s future.

    Questions & Answers

    How might stablecoins affect traditional banking in Hong Kong?
    Stablecoins could introduce significant competition for banks, particularly in wholesale payments, by offering advantages in cost and speed, prompting banks to adapt to avoid losing their market share.

    What opportunities do stablecoins present for Hong Kong banks?
    Aside from facing competition, banks could enhance their wealth management services and attract mainland Chinese customers by offering stablecoin-linked products and digital assets.

    Who are likely to be the first movers in the stablecoin market?
    Big tech companies and well-established banks with extensive resources and technological prowess are expected to be the early adopters in Hong Kong’s stablecoin landscape.

  • Malaysia Imposes MYR3.44 Million Fine on Bank Islam for Service Disruptions and Compliance Failures

    Malaysia Imposes MYR3.44 Million Fine on Bank Islam for Service Disruptions and Compliance Failures

    Amidst evolving regulatory landscapes, Bank Islam Malaysia Berhad (BIMB) finds itself in hot water as Malaysia’s central bank, Bank Negara Malaysia (BNM), imposes a financial penalty due to service disruptions and compliance failures. The bank has been penalized a total of MYR3.44 million for a series of unfortunate events that impacted its banking services and risk management practices.

    Unplanned Downtimes Shake Customer Trust

    BIMB drew the central bank’s ire with a fine of MYR1.74 million after experiencing multiple unplanned downtimes between June 1, 2023, and December 31, 2024. These outages severely affected its e-banking channels, debit card services, and online payment transactions. BNM disclosed that these disruptions resulted from BIMB’s delayed response and lack of a robust recovery process, ultimately causing turmoil for customers relying on essential banking services.

    Compliance Breaches Compound Troubles

    In addition to service lapses, BIMB faced a separate penalty of MYR1.7 million for failing to comply with anti-money laundering and combating the financing of terrorism (AML/CFT) regulations. According to BNM, an on-site examination revealed alarmingly inadequate sanctions screening processes within BIMB’s systems.

    The bank’s noncompliance was further exacerbated by its failure to timely screen its entire customer database against the Domestic List following updates published in the Federal Gazette in 2022 and 2023. This oversight delayed the identification of matches for three specified entities, raising significant concerns regarding the bank’s anti-financial crime measures.

    A Wake-Up Call for Financial Institutions

    The penalties imposed on BIMB highlight the critical need for financial institutions to maintain rigorous compliance protocols and ensure their systems are equipped to handle unexpected challenges. While BIMB may have caught a few unfortunate breaks, the overarching lesson remains: in the fast-paced world of banking, a blip in service can ripple out to many unsuspecting customers, making swift mitigation a must. Warning bells ringing, BIMB now has a stern reminder that effective risk management is as essential as delivering seamless service.

    Questions & Answers

    What prompted Bank Negara Malaysia to impose penalties on BIMB?
    The penalties stemmed from a series of unplanned downtimes affecting services and shortcomings in compliance with AML/CFT regulations.

    How much total financial penalty was levied against BIMB?
    BIMB faced a total penalty of MYR3.44 million, which includes MYR1.74 million for service disruptions and MYR1.7 million for compliance failures.

    What were some specific compliance failures identified by Bank Negara Malaysia?
    BIMB failed to conduct timely sanctions screening for its customer database, which led to delays in identifying matches for three specified entities.

  • Exploring Barriers to the Growth of Green Bonds in India’s Eco-Friendly Investment Landscape

    Exploring Barriers to the Growth of Green Bonds in India’s Eco-Friendly Investment Landscape

    The trajectory of India’s green bonds is expected to climb steadily as the nation pushes towards a low-carbon economy. However, a new analysis from the Institute of Energy Economics and Financial Analysis (IEEFA) unveils a constellation of challenges that could throw a wrench in this optimistic outlook.

    Obstacles Looming Over Green Financing

    In their latest briefing note, IEEFA identifies several hurdles that threaten to stifle the scalability of green bonds, which are vital for financing sustainable projects. Labanya Prakash Jena, a sustainable finance consultant at IEEFA and co-author of the analysis, emphasizes the need for robust monitoring and reporting mechanisms. Without these, greenwashing becomes more prevalent, potentially undermining the very purpose of green bonds.

    The landscape is further complicated by inconsistent definitions, verification processes, and reporting standards for green bonds in various jurisdictions. While frameworks like the Green Bond Principles from the International Capital Market Association and the Climate Bonds Standard aim to create consistency, Jena’s collaborator, Vandana Vuppuluri, noted that their interpretation can vary widely from one market to another.

    The Cost Conundrum

    Another significant barrier is the high cost associated with issuing green bonds. This financial burden has resulted in an uneven playing field, largely favoring well-resourced corporations and sovereign entities. “It’s crucial to recognize that the green bond market remains relatively small compared to the broader bond market,” Jena states. “This limitation restricts investment opportunities and casts a long shadow on transparency, as securing consistent post-issuance reports about environmental impacts can deter potential investors.”

    While green bonds are not a panacea for climate issues, Vuppuluri insists they hold essential value in financing a transition to a low-carbon future. “Success relies on how well market dynamics, regulatory frameworks, and stakeholder commitment coalesce around environmental objectives,” she asserts. And remember, as challenging as the road ahead may seem, a little creativity can often turn obstacles into stepping stones—just ask any aspiring entrepreneur navigating the bustling streets of Delhi!

    Questions & Answers

    What are the main challenges facing India’s green bond market?
    The key challenges include a lack of robust monitoring and reporting mechanisms, inconsistent definitions and regulations across jurisdictions, and the high cost of issuing green bonds, which limits participation to well-resourced entities.

    How do varying frameworks affect the green bond market?
    While frameworks like the Green Bond Principles and the Climate Bonds Standard exist to establish coherence, their interpretation can differ significantly across markets, leading to confusion and inconsistency in green bond issuance.

    What role do green bonds play in battling climate change?
    Although they are not a standalone solution, green bonds are critical for financing initiatives that support a transition to a low-carbon economy, with their success contingent on effective regulation and stakeholder commitment to environmental goals.

  • Australian Banks Set to Refund $60.5 Million to Customers Affected by Excessive Fees

    Australian Banks Set to Refund $60.5 Million to Customers Affected by Excessive Fees

    The Australian banking sector is facing significant scrutiny as over 920,000 customers are set to receive refunds totaling more than $60.58 million (A$93 million) for excessive charges on their transaction accounts. This revelation, outlined in a report by the Australian Securities and Investments Commission (ASIC) released on July 29, 2025, highlights an ongoing issue where banks have levied high fees on those least equipped to shoulder them.

    Massive Refunds in the Works

    To date, more than $21.49 million (A$33 million) has been refunded to approximately 150,000 customers, with an additional $39.09 million (A$60 million) earmarked for over 770,000 others. The ASIC report indicates that over 1 million customers have transitioned to low-fee accounts, collectively expected to save around $32.57 million (A$50 million) each year. Talk about a victory for consumer rights!

    A Bank’s Responsibility to Its Customers

    ASIC’s earlier findings revealed a troubling trend: at least two million low-income Australians, many reliant on Centrelink payments, were stuck in high-fee accounts. “It should not take an ASIC review to force A$93 million in refunds or push banks to reassess their practices,” said Joe Longo, chair of ASIC. He emphasized that although some improvements have been made, there’s a pressing need for ongoing vigilance in how banks design and distribute their products.

    Industry Response and Changes

    Significantly, three of the four banks highlighted in ASIC’s initial report have stepped up to extend refunds not just to select customers, but to a wider demographic of low-income account holders facing high fees. In addition, seven banks have revamped their processes, and nine others have made accessing low-fee accounts more straightforward. These changes signal a shift in the banking industry’s approach, but the road ahead remains long.

    This evolving narrative in Australia’s banking landscape raises questions on how much longer consumers will need to advocate for fair practices, but one thing is clear: transparency and accountability are taking center stage.

    Questions & Answers

    What is the total amount being refunded to Australian bank customers?
    Authorities report that more than $60.58 million (A$93 million) will be refunded to over 920,000 customers due to excessive fees.

    How have banks responded to ASIC’s findings?
    Three of the four banks featured in ASIC’s report have committed to extend refunds to a broader range of low-income customers, while several others have improved processes for accessing low-fee accounts.

    What steps has ASIC suggested for banks moving forward?
    ASIC chair Joe Longo has urged banks to regularly assess both product design and distribution to ensure that customers receive appropriate product options and necessary support.

  • UBS Leads the Charge: Transforming Retail with Seamless Integration and Innovative AI Solutions

    UBS Leads the Charge: Transforming Retail with Seamless Integration and Innovative AI Solutions

    UBS has reported impressive financial results for the second quarter and the first half of 2025, showcasing a strategic blend of client account integrations and a bold entry into generative AI. With invested assets reaching a staggering $6.6 trillion, the bank is not just keeping pace but positioning itself as a formidable global leader.

    The bank revealed a net profit of $2.4 billion for Q2 and $4.1 billion for the first half of the year, slightly surpassing analyst expectations. “We sustained robust momentum during a quarter marked by extreme volatility by staying close to our clients and executing our integration plans,” remarked UBS CEO Sergio Ermotti.

    Client engagement has flourished even in a turbulent market, with Global Wealth Management (GWM) attracting $38 billion in net new assets and achieving record revenues in Prime Brokerage. Notably, transaction-based income in GWM rose by an impressive 12 percent year-over-year, driving invested assets to an all-time high of $6.6 trillion. It seems UBS is so good at making money, they might as well come with a “money magician” title!

    On Track for Full Client Migration by Early 2026

    In a significant milestone, UBS confirmed that about one-third of the targeted client account migrations from Credit Suisse to UBS Switzerland have been completed, with the entire migration expected to conclude by Q1 2026. The bank also reported meaningful progress in legal entity simplifications across both the US and Europe.

    “We are positioning for long-term success by further enhancing our global capabilities, investing in our future infrastructure and AI, and actively engaging in the debate on future regulation in Switzerland,” Ermotti stated, indicating an ambitious vision for the bank’s future.

    During Q2, UBS realized an additional $0.7 billion in gross cost savings, reaching a significant 70 percent of its $13 billion savings target. Among reductions, approximately 700 applications, representing 56 percent of the former Credit Suisse systems, have been phased out.

    A Robust Financial Strategy

    The Group also executed $0.5 billion in share buybacks in Q2 and anticipates repurchasing up to $2 billion by year-end. “We maintained a balance sheet for all seasons while delivering on our capital return plans. Our ability to generate capital is funding investments and sustainable shareholder returns,” the CEO emphasized, showcasing confidence in UBS’s fiscal health.

    With a loan-to-deposit ratio standing at a conservative 81 percent and a cost of risk as low as 10 basis points, UBS continues to underline its commitment to the local economy, with credit issuance in Switzerland during the quarter reaching 4.0 billion francs.

    Generative AI: The New Frontier

    UBS is ramping up its investment in generative AI, having decommissioned over 1,100 legacy business applications in 2025 alone. The bank processed an eye-popping 8 million AI tool prompts in Q2, and its proprietary AI assistant, “Red,” is set to be fully implemented across 52,000 employees by early 2026.

    Additionally, UBS has initiated a firm-wide AI leadership campaign in collaboration with Oxford University, focusing on over 250 senior leaders to advance AI integration and promote ethical transformation. With more than 280 active AI use cases in business—an increase of 10 percent since Q1—the bank is clearly committed to staying ahead in the technology curve.

    “This allows us to fulfill our commitment to support all the communities where we live and work,” Ermotti stated, emphasizing a balance between innovation and corporate responsibility.

    Looking to the Future: Stable Outlook Amidst Change

    As UBS gazes into the future, it anticipates stable net interest income in Switzerland along with a modest increase in dollar terms. Despite normalization of trading activities since the turbulence of Q1, UBS expects approximately $0.4 billion in revenues to help offset integration costs.

    With a diversified business model and a focus on growth, integration, and innovation, the bank maintains confidence in achieving its financial targets for 2025 and 2026. “We are actively engaging in the debate on future regulation in Switzerland while fulfilling our responsibility to communities and clients alike,” Ermotti concluded.

    Questions & Answers

    How has UBS’s performance changed in Q2 2025 compared to previous quarters?
    UBS reported a net profit of $2.4 billion for Q2 2025, reflecting solid growth driven by strong client engagement and record revenues in Prime Brokerage, surpassing analyst expectations.

    What are UBS’s plans regarding client account migrations from Credit Suisse?
    UBS has completed about one-third of its targeted client account migrations from Credit Suisse and expects full migration to finish by Q1 2026.

    How is UBS incorporating AI into its operations?
    UBS is significantly investing in generative AI, with plans to roll out its proprietary AI assistant “Red” to 52,000 employees by early 2026 and has initiated an AI leadership initiative in partnership with Oxford University.

  • Bangkok Bank Says Absence of Virtual Bank License Isn’t a Major Setback for Growth Plans

    Bangkok Bank Says Absence of Virtual Bank License Isn’t a Major Setback for Growth Plans

    The future of virtual banking in Thailand appears to be a slow burn, as Bangkok Bank’s prospects in this emerging sector suggest limited revenue potential in the near term. According to CGS International’s analyst briefing held on July 23, 2025, the investment house assesses that significant business revenue from virtual banking is unlikely to materialize within the initial five years of operation.

    Virtual Banking License not a Major Concern

    In light of this outlook, CGS International asserts that Bangkok Bank’s absence of a virtual banking license will not pose a substantial problem for the institution. Their report, published on July 29, emphasizes that the current landscape of virtual banking in Thailand is still in its infancy, and immediate revenues from this venture are expected to be minimal.

    Steady Growth Targets Amid Caution

    This cautious approach comes as Bangkok Bank’s management maintains its financial targets for 2025, aiming for a loan growth of 3% to 4%. They also forecast a nonperforming loan (NPL) ratio of 3%, a net interest margin (NIM) of 2.8% to 2.9%, and modest low single-digit growth in net fee income, alongside credit costs projected between 0.9% and 1%.

    Potential Challenges on the Horizon

    However, CGS International warns of downside risks that could impact these targets, including negative loan growth, a lower-than-expected NIM due to potential policy rate cuts, reduced net fee income, and elevated credit costs. They noted that Bangkok Bank’s loan growth for Q2 2025 was a mere 0.7% from the end of 2024, and a subdued demand outlook is anticipated for the latter half of the year, particularly due to uncertainties surrounding the impact of U.S. tariffs on private investments. More rate cuts could further compress the bank’s NIM, leaving it to navigate treacherous waters ahead.

    Can Virtual Banks Make a Splash? We’ll See!

    While the virtual banking sector in Thailand may seem like a distant wave, observers are curious to see if any competitor can make a meaningful splash before the competition gets out to sea.

    Questions & Answers

    What is the expected revenue outlook for virtual banking in Thailand?
    The revenue generated by virtual banking in Thailand is anticipated to be minimal in the first five years, according to CGS International’s analysis.

    How is Bangkok Bank performing financially in 2025?
    Bangkok Bank is targeting a 3% to 4% loan growth, with a nonperforming loan ratio of 3% and a net interest margin between 2.8% and 2.9% for 2025, while facing potential economic headwinds.

    What risks could impact Bangkok Bank’s financial targets?
    Downside risks include negative loan growth, lower-than-expected net interest margins due to monetary policy adjustments, reduced net fee income, and elevated credit costs.

  • BlackRock Empowers Swiss Investors with New Voting Options in Innovative Move

    BlackRock Empowers Swiss Investors with New Voting Options in Innovative Move

    In a significant move for institutional investors in Switzerland, BlackRock has rolled out its global Voting Choice program, allowing clients to directly influence voting rights in funds valued at approximately $5.8 billion. This initiative, announced on Tuesday, marks a pivotal moment, as it extends voting rights beyond clients with separately managed accounts for the first time.

    Your Investment, Your Voice

    The Voting Choice program enables investors to select from 16 third-party voting policies or to continue relying on BlackRock’s Investment Stewardship (BIS) team for proxy voting. This empowers institutional clients—such as Swiss pension funds that collectively serve more than 4.7 million people—to gain greater leverage in the oversight of their capital.

    A Global Perspective

    Globally, the program encompasses over $2.7 trillion in assets, making up more than 90 percent of BlackRock’s index equity assets under management, with $662 billion actively managed by clients under this initiative.

    Words from Leadership

    Amra Balic, Co-Head of BlackRock Investment Stewardship, expressed enthusiasm about the program’s reception among clients. “We are pleased that Voting Choice resonates with interested clients and are delighted to now extend the program to the Swiss market,” she stated. Dirk Klee, BlackRock’s Country Manager for Switzerland, emphasized the program’s efficiency: “With the introduction of Voting Choice for the institutional share classes of ten Switzerland-domiciled funds, we offer our clients simple and efficient options to actively participate in the voting process according to their preferences.”

    In an age where every vote counts, this initiative reminds us that even the largest players in finance believe in empowering their clients—one vote at a time.

    Questions & Answers

    What does the Voting Choice program allow institutional clients in Switzerland to do?
    The Voting Choice program enables institutional clients to directly exercise their voting rights in selected funds, allowing for greater influence over investment decisions valued at approximately $5.8 billion.

    How does this program enhance client participation in corporate governance?
    Clients can either choose from 16 third-party voting policies or have BlackRock’s Investment Stewardship team manage proxy voting, thus tailoring their involvement in governance according to their preferences.

    What is the global scale of the Voting Choice program?
    Globally, the program encompasses over $2.7 trillion in assets, making up more than 90 percent of BlackRock’s index equity assets under management, with $662 billion actively managed by clients under this initiative.

  • UBS Welcomes New Leader for Wealth Management Operations in Israel

    UBS Welcomes New Leader for Wealth Management Operations in Israel

    UBS Restructures Leadership in Wealth Management for Israel

    Change is afoot at UBS as the bank streamlines its Wealth Management division in Israel. Following the departure of Ido Ben Haim, who is stepping away from the firm to explore new horizons, UBS is positioning itself for a new era of unified leadership.

    The decision comes from an internal memo authored by Katya Lehmann, Sector Head for Wealth Management in Eastern Europe, Israel, and Africa. According to the memo, the integration of business areas necessitated consolidating the leadership under one umbrella to enhance efficiency and strategic alignment.

    Taking the reins as interim Market Head for Wealth Management in Israel is Yariv Shaphyr, a seasoned professional with over 25 years in investment advisory, trading, and structuring under his belt. Shaphyr’s impressive credentials include a decade of experience at Credit Suisse and UBS, where he specialized in servicing Ultra High Net Worth clients across both Europe and Israel. Fluent in both English and Hebrew, he recently held the position of Head of Global Family and Institutional Wealth in EMEA. The memo emphasizes that Shaphyr’s deep expertise will be crucial as UBS navigates this transitional phase.

    As the dust settles on this leadership change, one thing remains clear: UBS is keen to maintain strong client relationships and continue its commitment to excellence in service, ensuring its wealth management remains a competitive force in the region.

    Questions & Answers

    What sparked the leadership change at UBS in Israel?
    Ido Ben Haim’s departure from UBS to explore new opportunities triggered the restructuring in UBS’s Wealth Management division to unify leadership.

    Who is taking over as interim Market Head of Wealth Management in Israel?
    Yariv Shaphyr has been appointed as the interim Market Head, bringing over 25 years of experience in investment advisory and a strong background working with Ultra High Net Worth clients.

    What are the next steps for UBS following this leadership transition?
    UBS plans to focus on integrating its business areas under unified leadership, aiming to enhance operational efficiency and strengthen client relationships in the region.

  • UnionBank Completes Citibank IT Integration in Just Nine Months: A Remarkable Achievement for the Philippines’ Banking Sector

    UnionBank Completes Citibank IT Integration in Just Nine Months: A Remarkable Achievement for the Philippines’ Banking Sector

    UnionBank of the Philippines is making waves in the banking sector after its strategic acquisition of Citibank’s consumer banking operations in the country. In just nine months, the bank has successfully integrated Citibank’s IT systems and unveiled a new Credit Decision Engine (CDE) that is reshaping its customer onboarding and credit approval process.

    This sophisticated new system has automated over 80 percent of applications for credit cards and personal loans, slashing the onboarding time to under 15 minutes per customer. At its peak, UnionBank has been able to book an impressive 50,000 new credit card and loan accounts each month. The seamless blending of systems is a testament to UnionBank’s commitment to enhancing customer experience while maintaining service continuity.

    Since completing the acquisition in 2022 for over SGD 900 million (US$700 million), the bank has absorbed nearly one million new customers. Manoj Varma, UnionBank’s head of consumer banking, acknowledged the pivotal role of the FICO Platform in this transition, noting that it has not only improved operational efficiency but also fostered financial inclusion across the Philippines.

    Credit Decision Engine: A Game Changer for Lifestyle Banking

    The new CDE is a groundbreaking tool designed to evaluate applicants through a combination of bureau data and alternative sources. This advanced system allows UnionBank to extend credit to previously underserved demographics, including gig economy workers and customers with limited credit histories. By implementing risk-based verification, the CDE expedites approvals for low-risk applicants while applying stricter checks for higher-risk segments. The result? Nearly 40 percent of the credit decision-making process has been automated, leading to fewer manual interventions and errors.

    This shift towards automation not only boosts accuracy and speed but is also in lockstep with UnionBank’s mission to promote financial inclusion. “UnionBank has shown how technology isn’t just about algorithms and efficiency, it’s about empowering people,” remarked Nikhil Behl, FICO’s head of software. He further commended UnionBank for building a scalable, inclusive onboarding experience that is both efficient and customer-centric.

    Last year marked another significant expansion for UnionBank, as it extended its use of the FICO Platform to manage credit card limit decisions and real-time authorizations. This strategic move has enhanced its customer management capabilities and fortified its standing as a forward-thinking player in the retail banking landscape.

    Questions & Answers

    What innovations has UnionBank introduced following its acquisition of Citibank’s consumer banking business?
    UnionBank has integrated Citibank’s IT systems and launched a new Credit Decision Engine that automates over 80 percent of credit card and loan applications, significantly reducing onboarding time.

    How does the Credit Decision Engine support financial inclusion in the Philippines?
    The CDE allows UnionBank to evaluate applicants using both bureau data and alternative sources, making it possible to extend credit to underserved populations, like gig workers, and those with limited credit histories.

    What impact has the automation of credit decisions had on UnionBank’s operations?
    The automation has reduced manual interventions and errors by nearly 40 percent, improving accuracy and speed while aligning with UnionBank’s strategy to enhance customer experience and financial accessibility.

  • ECB Adopts Flexible Stance, Exploring All Avenues for Future Monetary Policy

    ECB Adopts Flexible Stance, Exploring All Avenues for Future Monetary Policy

    ECB Holds Steady Amid Economic Whirlwinds

    The European Central Bank (ECB) has decided to maintain its current interest rates, a move that many analysts anticipated given the prevailing uncertainties clouding the economic forecast. In a statement released Thursday, the ECB outlined its intentions to adopt a data-driven approach when making future rate adjustments.

    The most recent data has largely reaffirmed the ECB’s previous outlook on inflation, indicating a gradual easing of domestic price pressures alongside a slowdown in wage growth. Inflation now hovers around the ECB’s medium-term target of 2 percent.

    Navigating Through Uncertainty

    Despite a cautious stance, the ECB highlights a landscape fraught with unpredictability, particularly related to ongoing trade tensions. Nevertheless, the eurozone economy has demonstrated resilience—thanks in part to earlier interest rate reductions that the Governing Council views as a hallmark of its monetary policy success.

    Commitment to Inflation Stability

    The ECB remains steadfast in its goal to stabilize inflation at the target level in the medium term but is careful not to pin itself down to any predetermined course of action. Decisions regarding future rates will be guided by incoming economic data, allowing for flexibility in its approach.

    As it stands, the interest rates in the euro area remain unchanged as follows:
    › Deposit facility rate: 2.00 percent
    › Main refinancing operations rate: 2.15 percent
    › Marginal lending facility rate: 2.40 percent

    Looking ahead, the ECB’s next monetary policy meeting is slated for September, right after the summer break. Economists are already buzzing with debates about whether another rate cut will be on the table. The outcome remains murky, with compelling arguments both supporting and contesting the notion.

    For one, inflation could drop further thanks to base effects from energy prices, while a strengthening euro against the dollar might give a leg up to cheaper imports—delivering a double whammy of influence on price levels.

    The Ripple Effect of EU-US Trade Talks

    The broader economic outlook is closely tied to the ongoing trade negotiations between the EU and the United States. The uncertainty surrounding these discussions could stifle economic growth, hinder corporate investment, and dampen consumer sentiment across the eurozone. A sluggish demand could further complicate the economic picture.

    Whether this current pause in the easing cycle marks a temporary break or the conclusion of a longstanding trend hinges on macroeconomic data as we head into autumn. For the time being, the ECB is keen to keep its options open—a methodical game of chess in the complex world of monetary policy.

    Questions & Answers

    What factors influenced the ECB’s decision to keep interest rates unchanged?
    The ECB’s decision was primarily influenced by ongoing uncertainties surrounding the economic outlook, inflation levels, and trade tensions, along with recent data confirming its previous assessments of inflation.

    What are the current interest rates set by the ECB?
    The ECB has maintained the following rates: Deposit facility rate at 2.00 percent, main refinancing operations rate at 2.15 percent, and marginal lending facility rate at 2.40 percent.

    How might EU-US trade negotiations impact the eurozone economy?
    Uncertainty in trade negotiations could hinder economic growth and affect corporate investment and consumer sentiment, potentially leading to weaker demand throughout the eurozone.