Tag: fmcg

  • Fonterra Annual Profit Jumps to NZ$2.6 Billion on Mainland Sale

    Fonterra Annual Profit Jumps to NZ$2.6 Billion on Mainland Sale

    Fonterra lifted its full-year net profit after tax by 142 per cent to NZ$2.6 billion ($1.6 billion) following the sale of its consumer arm.

    Operating profit jumped 97.6 per cent to NZ$3.4 billion for the fiscal year ended July 31. That figure included a NZ$1.2 billion gain from selling the Mainland Group consumer business.

    The Auckland-based dairy co-operative completed the Mainland sale in March, handing over brands including Anchor, Mainland, Perfect Italiano and Anmum. Stripping out the divestment, underlying operating profit rose 20 per cent to NZ$1.8 billion from NZ$1.5 billion a year earlier. Total cash distributions reached NZ$12.42 per fully shared-up farmer shareholder. That comprised a NZ$10.42 operating payout and a NZ$2.00 capital return from sale proceeds.

    Balance sheet overhaul and debt reduction

    Fonterra used the divestment proceeds and operating cash flow to cut adjusted net debt by NZ$967 million. Total debt fell to NZ$1.7 billion. Gearing dropped to 21 per cent from 24 per cent twelve months prior. Debt to earnings before interest, tax, depreciation and amortisation fell from 1.1 times to 0.7 times, giving the business headroom to absorb farmgate commodity swings.

    Underlying earnings per share rose 31 per cent to 71 New Zealand cents from 54 cents in FY25. Underlying return on capital reached 14.2 per cent. That result beat the co-operative’s target band of 10 to 12 per cent.

    Processing volumes counter farmgate price drop

    Milk collections reached 1,571 million kilograms of milk solids across the season, up 4.1 per cent year-on-year. That set a ten-year processing record for the group. Higher factory throughput spread fixed costs across a larger volume base and improved plant utilisation.

    Higher processing volumes helped shield earnings from softer commodity rates. The final Farmgate Milk Price settled at NZ$9.69 per kilogram of milk solids, down from NZ$10.16 in the previous season. Global milk supply recovered across Europe and the Americas during the period.

    Early recovery against post-sale targets

    The co-operative beat its internal recovery schedule by two years. Management had planned to take three years following the Mainland exit to rebuild underlying operating profit to NZ$1.7 billion. Higher product stream margins pushed the core business past that mark in year one.

    For food manufacturers and retail private-label buyers across Southeast Asia and Greater China, the restructured business now functions strictly as an ingredients and foodservice supplier. It no longer competes as a brand owner on retail shelves. The divestment removed channel conflict with Asian supermarket clients, though it concentrates group revenue on volatile global dairy trade benchmarks and industrial buyers.

    Earnings momentum into the next milk season

    Asset sales in South America and China farming hubs preceded this final exit from overseas retail consumer operations. Fonterra shares traded at NZ$8.30 in Wellington after the release. That put the stock near the upper limit of its 52-week trading range of NZ$6.14 to NZ$8.49.

    Chief Financial Officer Andrew Murray stated that holding product stream returns near FY26 levels would keep earnings on track through the next cycle. Investors and ingredient buyers now look to Fonterra’s opening farmgate forecast update in November to gauge early Southern Hemisphere spring production volumes.
  • PepsiCo Backs Australia Foods Unit with $150 Million Produce Spend

    PepsiCo Backs Australia Foods Unit with $150 Million Produce Spend

    In September 2026, PepsiCo highlighted the scale of its Australian supermarket presence, supported by an annual spend of about $150 million on locally grown produce.

    The company’s domestic foods business spans household snack brands including Smith’s, Red Rock Deli and Doritos, backed by three manufacturing sites and more than 1,700 employees.

    For Alexia Horley, CEO of PepsiCo’s Australia and New Zealand foods business, a key focus is keeping its familiar brands relevant and visible across store shelves.

    Sourcing and Factory Operations

    Local agricultural supply chains form the backbone of the manufacturer’s domestic processing network. The company directs approximately 150 million Australian dollars each year into domestic farm produce, primarily processing potatoes and grains across three dedicated factories.

    Those production hubs include manufacturing facilities such as its Regency Park operations in South Australia. Plant operations run round-the-clock shift schedules covering bulk liquid intake, grain handling, automated frying, seasoning and high-density palletised distribution into national retail distribution centres.

    Rivalry in the Snack Aisle

    Competition in Australian grocery aisles is tightening as supermarket chains Coles and Woolworths push private-label alternatives against multinational branded goods. Discount retailers like Aldi continue to squeeze standard packet pricing across core chip segments.

    Branded manufacturers face pressure on margins from elevated ingredient input costs, transport tariffs and retail listing fees. To defend volume without discounting away brand equity, packaged goods suppliers must push established names into premium formats, alternative grain bases and cross-category pantry lines.

    Supply Chain Priorities

    Sustaining local manufacturing gives multinational consumer groups an operational hedge against international shipping volatility and foreign currency swings. Processing close to farm gates cuts transport lead times and secures direct supply agreements with domestic growers.

    The group has kept its regional manufacturing base intact while many consumer goods competitors outsourced production to lower-cost Southeast Asian packing hubs. That domestic manufacturing base allows fast product turnover and seasonal flavour runs tailored directly to Australian shoppers.

    Next Steps for Retail Distribution

    PepsiCo plans to roll out line extensions under its Smith’s and premium snack banners across supermarket networks over the coming retail quarters. Procurement teams are tracking raw material contracts across eastern state farming districts ahead of the next seasonal harvest cycles.

  • CJ Foods Oceania Names Jamie Henderson Managing Director

    CJ Foods Oceania Names Jamie Henderson Managing Director

    CJ Foods Oceania, a subsidiary of South Korea-based food giant CJ Foods, appointed Jamie Henderson as its new managing director on September 28, 2026.

    Henderson brings extensive commercial and leadership experience across the Australian fast-moving consumer goods sector to the role.

    Local FMCG Leadership

    Henderson joins the Oceania unit following senior leadership roles at poultry producer Inghams. His commercial track record spans several major Australian packaged goods suppliers, including Capilano Honey, Goodman Fielder, and Primo Foods, the smallgoods brand owned by JBS.

    CJ Foods Oceania operates as the regional arm of CJ Foods, the packaged food division of South Korea’s CJ Group. The business distributes Korean packaged staples, frozen foods, and ready meals across Australian and regional retail channels.

    Broader Push Into Western Grocery Channels

    Asian packaged food groups face an ongoing challenge in Oceania: crossing over from specialty Asian grocers into mainstream supermarket aisles at Coles and Woolworths. Bringing in leadership from established domestic suppliers like Goodman Fielder and Inghams directly addresses retail buyer relationships and domestic distribution terms.

    The risk sits in category demand. While consumer appetite for Korean food brands has climbed across Western markets, securing permanent shelf space in Australian chilled and frozen sections requires heavy trade spending and consistent promotional support.

    Commercial Track Record

    CJ Foods has steadily built out dedicated regional subsidiaries across Asia-Pacific, North America, and Europe over the past decade to localize sales and distribution. The Oceania unit handles the company’s retail rollout across Australia and neighboring markets.

    Henderson will oversee retail account growth, supply chain operations, and product placement across Australian supermarket chains as CJ Foods Oceania builds out its product lineup for the coming financial year.

  • Vietnamese Brands Target Thai Supermarkets to Drive 25 Billion Dollar Trade Goal

    Vietnamese Brands Target Thai Supermarkets to Drive 25 Billion Dollar Trade Goal

    Vietnamese consumer brands wrapped up a Bangkok retail show on September 20, chasing shelf space across Thailand. Two-way trade between the nations hit a record 22.1 billion dollars.

    Both governments want annual trade to reach 25 billion dollars. Hitting that target requires Vietnamese manufacturers to turn low-margin bulk crops into finished, branded goods for modern retail shelves.

    Thailand is Vietnam’s top trading partner in ASEAN, and Vietnam ranks second for Thailand. Proximity keeps shipping costs and transit times well below long-haul routes to Europe or North America. That makes Thai chains an accessible testing ground for regional packaged goods.

    Shifting from Bulk Crops to Packaged Goods

    Central Retail acts as the primary conduit through its Vietnamese Week exhibitions and sourcing networks. Central Retail vice president of Vietnam trade promotion Paul Le noted that suppliers are shifting away from basic raw crop exports. They are moving toward finished products with upgraded packaging, dedicated branding, and local regulatory certifications.

    Securing hypermarket shelf space does not guarantee sales velocity. Buyers demand that foreign suppliers fund their own on-ground marketing and understand price elasticity against established local brands. Suppliers must also align promotional calendars with regional holiday shopping cycles.

    “The handshake is only the first step. Businesses need to take responsibility for promoting their own products and making them visible in the target market. A product placed among thousands of others in a supermarket cannot attract consumers without proper marketing.”

    Provincial authorities in Vietnam are restructuring local supply chains around foreign supermarket specifications rather than domestic farm output. An Giang Province, an agricultural hub in the Mekong Delta, is aligning cooperatives with Central Retail. The goal is to establish consistent volume, commercial traceability, and international food safety standards before starting export runs.

    Local Adapters and Product Tailoring

    Trade officials in Da Nang curated specialized items for the Bangkok event, including packaged Ngoc Linh ginseng, instant Mi Quang noodle bowls, and roasted coffee. The city now subsidizes export-grade packaging design. This helps local processors meet Thai import rules on nutritional labelling and shelf life.

    Coffee roaster Ban Me Gold demonstrates how private labels manage regional segmentation. The company already ships to the United States and South Korea, and develops tailored variants for Japan, Dubai, and Malaysia. For Southeast Asian lines, it packages traditional metal drip filters with ground beans. It also tweaks roast profiles and packaging language for each market.

    Niche producers face a longer path through technical import barriers. Sinh Duoc Cooperative, a personal care maker based in Ninh Binh, spent a decade securing ASEAN cosmetic compliance, US FDA registration, and ISO 22000 food safety certifications. It finally presented herbal soap lines to Thai retail buyers this month.

    Cross-Border Distribution Realities

    Regional consumer goods flows are shifting structurally across Southeast Asia. Thai retail operators such as Central Retail and CP Group have spent billions acquiring store networks across Vietnam. That gives them bilateral use: they source Vietnamese specialty goods for Thai stores while filling Vietnamese aisles with Thai manufactured items.

    Suppliers relying solely on domestic distributors risk margin compression as modern retail expands into Tier 2 and Tier 3 Vietnamese cities. Partnering with cross-border supermarket chains provides volume scale. However, producers must absorb slotting fees, mandatory discounts, and strict return policies that eat into gross margins.

    Small-scale producers face real danger if they expand factory capacity without guaranteed re-orders. A seasonal promotion in Bangkok does not guarantee permanent listing status. Undercapitalized producers remain vulnerable if secondary sales lag behind local Thai incumbents.

    The Next Steps for Regional Trade

    Hanoi’s Ministry of Industry and Trade is steering its Go Global trade program toward digital marketplace integration and cross-border logistics partnerships. Bilateral discussions between Hanoi and Bangkok now focus on streamlining customs clearance and sanitary inspections for packaged food items to drive trade toward the 25 billion dollar milestone.

  • Lay’s Thailand Launches 2 Unconventional Potato Chip Flavours

    Lay’s Thailand Launches 2 Unconventional Potato Chip Flavours

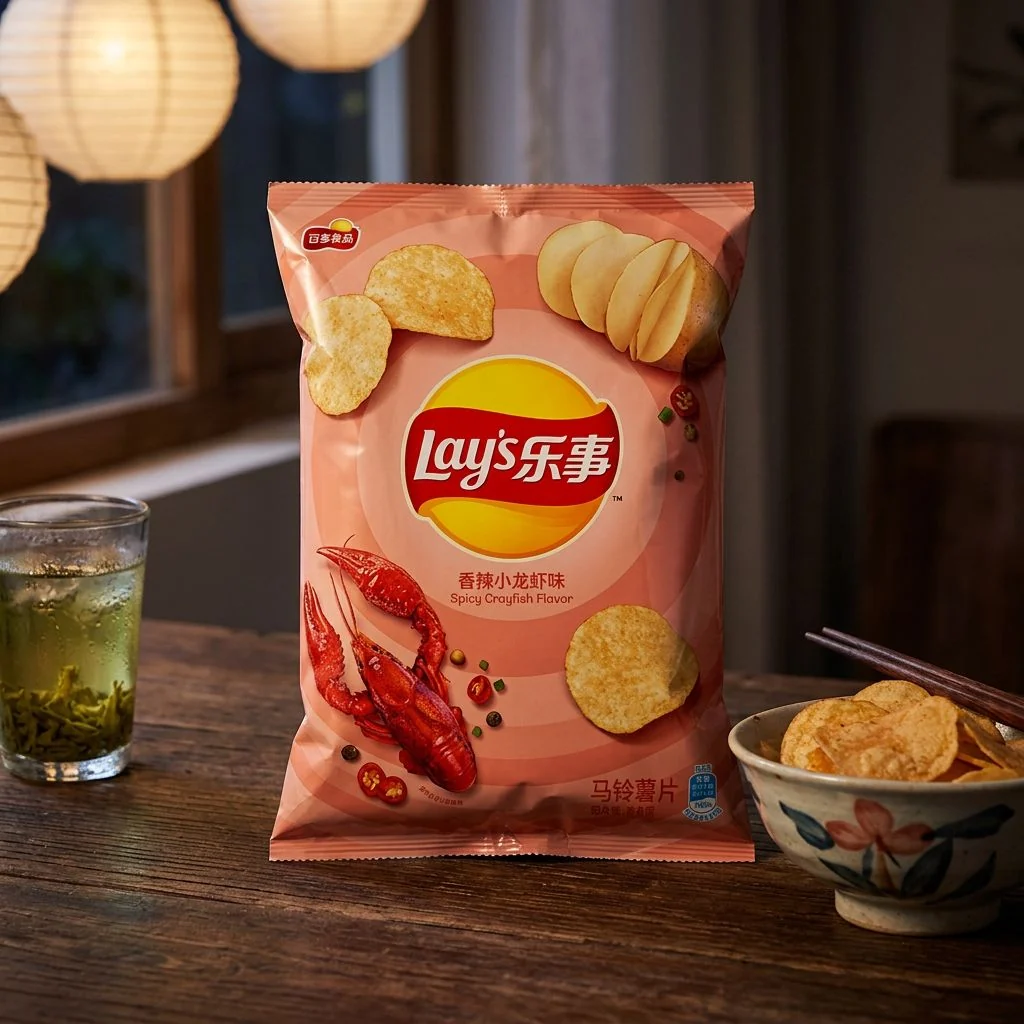
    Lay’s Thailand has launched 2 unconventional potato chip flavours across 7-Eleven convenience stores nationwide. The rollout introduces coriander and durian options to local snack shelves.

    Both items arrived in stores in September 2026 under the Lay’s Coriander Seasoned and Lay’s Durian Delight labels. Bright yellow bags house the durian crisps, designed to stand out against standard savoury snack lines in busy retail aisles.

    Convenience channel distribution

    Lay’s designed the coriander variant to mirror the savoury, aromatic profile of dishes cooked with fresh herbs. It provides a rich, savoury seasoning intended for easy snacking. Meanwhile, the durian edition releases a sweet, creamy aroma immediately upon opening, offering durian enthusiasts a crunchy chip format.

    Distribution relies entirely on the 7-Eleven retail network across Thailand’s provinces and urban centres. Placing the specialty runs directly into the country’s dominant convenience footprint secures maximum visibility at checkout counters.

    Regional taste experimentation

    Consumer fascination with coriander snacks across mainland China and Taiwan paved the way for the launch. Food manufacturers in East and Southeast Asia regularly use regional botanical ingredients for short-run flavour trials. These releases test shopper willingness to try unfamiliar profiles.

    Taiwanese snack makers have similarly tested experimental categories, including century egg crisps and fermented seasonings, to drive social media buzz and trial purchases. Durian remains an established flavour foundation in Southeast Asia. Even so, combining sweet fruit profiles with savoury potato bases continues to divide consumers.

    Portfolio risk and rotation

    Novelty flavours present distinct operational calculations for fast-moving consumer goods manufacturers and retail category managers. These limited batches rarely turn into permanent volume drivers. However, they generate valuable basket conversion when standard potato chip variants hit sales plateaus.

    Inventory risks mount quickly if repurchase rates drop after initial curiosity purchases fade. Convenience operators manage this exposure by running rapid stock rotations. They clear experimental stock before consumer fatigue sets in across key demographic clusters.

    Sales performance across Thai 7-Eleven branches will now determine whether the company pursues wider distribution across Southeast Asian convenience chains.

  • Thailand Rejects 5 to 10 per Cent Consumer Goods Price Hikes for October

    Thailand Rejects 5 to 10 per Cent Consumer Goods Price Hikes for October

    Thailand’s Department of Internal Trade has rejected manufacturer requests for 5 to 10 per cent price increases on essential consumer goods scheduled for October 1. Director-general Wittayakorn Maneenetr confirmed on September 24 that the agency refused to authorise the proposed increases across packaged groceries and household staples.

    Field inspections and supplier audits across major consumer goods manufacturers showed no formal approvals for pending price increases, according to the regulator. The department maintains active surveillance over 16 core consumer products, while the Central Committee on Prices of Goods and Services enforces statutory price caps across 59 controlled categories. These categories include meat, eggs, milk powder, tinned fish, seasonings, soap, shampoo, and washing powder.

    Promotions Rolled Back and Ceilings Tested

    Price increases felt by consumers in recent weeks stem from retailers pulling back promotional discounts rather than statutory ceiling adjustments. Brands have withdrawn multibuy promotions, including buy-one-get-one-free and buy-three-get-one-free deals, which returns shelf prices to their standard retail baseline without altering registered price caps.

    Manufacturers have also adjusted wholesale rates within previously approved statutory bands. A product with a 60 baht ceiling previously selling at 50 baht can shift to 52 or 55 baht without requiring fresh regulatory approval, though suppliers must still notify the department. Department officials stated that competitive pressures continue to discipline store shelves, as brands cutting promotions too aggressively risk ceding volume to discounting rivals.

    Input Pressures on FMCG Brands and Foodservice

    For fast-moving consumer goods suppliers, the refusal locks margins against persistent transport, packaging, and raw material cost inflation. Suppliers unable to lift base prices must either absorb higher overheads or rely on packaging redesigns to defend unit economics across modern trade channels. Retailers face thinner promotional support from suppliers, forcing grocers to balance footfall targets against lower co-marketing allowances.

    The margin squeeze extends directly into the foodservice sector. Sorathep Rojpotjanaruch, president of the Restaurant Business Club, projected selective 5 to 10 per cent menu price increases during the fourth quarter of 2026. Restaurants face steep seafood procurement costs driven by high fuel expenses alongside seasonal vegetable price spikes during the October and November rainy period.

    A Pattern of Incremental Surcharges

    Upward pricing pressure on Thai grocery shelves began building in April 2026 as manufacturers flagged higher energy, transport, and raw material outlays. Secondary price adjustments followed at mid-year, culminating in another round of supplier requests in mid-September.

    Field surveys recorded shelf price shifts across seasonings and staples, with monosodium glutamate rising by 5 to 10 baht per pack and 500-gram grain packets adding 10 baht. Wholesale chicken tenderloin moved from 100 to 105 baht per kilogram, while pork belly traded at 182.50 baht per kilogram and standard table eggs sold between 4.35 and 5.19 baht each.

    The Department of Internal Trade is now preparing joint retail discount programmes under the government’s Thais Help Thais scheme to curb fourth-quarter household living costs.

  • FrieslandCampina Takes Majority Stake in Ultrajaya in 7.8B Share Deal

    FrieslandCampina Takes Majority Stake in Ultrajaya in 7.8B Share Deal

    Dutch dairy group FrieslandCampina is taking a majority stake in Indonesian peer PT Ultrajaya Milk Industry, folding its Frisian Flag Indonesia unit into the Jakarta-listed business ahead of a shareholder vote scheduled for 27 October.

    Under the transaction terms, Ultrajaya will assume ownership of FrieslandCampina’s 78.09% holding in Frisian Flag Indonesia in exchange for more than 7.8 billion new shares priced at Rp2,150 ($0.12) each under a rights issue.

    FrieslandCampina’s partners, Blue Waves Group Ventures and PT Bahtera Wiraniaga Internusa, will also transfer their shares in Frisian Flag Indonesia to Ultrajaya. Once completed, FrieslandCampina will launch a mandatory cash tender offer for the remaining minority shares of Ultrajaya.

    Consolidating Two Distribution Giants

    Folding Frisian Flag Indonesia into Ultrajaya unites two of Indonesia’s most entrenched packaged beverage distribution networks. Distribution across an archipelago of 17,000 islands requires cold-chain infrastructure and wholesale relationships that take decades to assemble. The combined business will pair FrieslandCampina’s dairy formulation capacity with Ultrajaya’s dominant position in ambient shelf-stable drinks. That gives the group greater sway over shelf space in traditional warungs and modern supermarket chains alike.

    Rival dairy processors such as Indolakto and Nestlé now face a domestic competitor with combined annual sales past Rp15 trillion. Both corporate units will keep their consumer product brands, production lines, and independent operational teams intact on the ground. Co-founder Sabana Prawirawidjaja will stay in position as president director. The founding Prawirawidjaja family retains a substantial long-term equity holding in the merged business.

    Production Scale and Financial Performance

    Established in 1971, Ultrajaya produces UHT milk, ready-to-drink teas, and traditional health beverages from two main processing plants in West Bandung and Cibitung, West Java. The manufacturer generated Rp8.77 trillion in revenue last year, compared with Rp8.87 trillion during the prior 12-month period. Operating profit jumped 16.7 per cent to Rp1.68 trillion despite the revenue dip. Net profit grew 19 per cent to Rp1.37 trillion on firmer margins.

    For FrieslandCampina, the Indonesian consolidation follows a period of volume weakness across developing territories. The Dutch cooperative booked annual revenue of €13.4 billion ($15.2 billion), up 3.6 per cent. Group operating profit dropped 3.8 per cent to €507 million because of commodity swings and weaker demand across its Middle East, Pakistan, and Africa divisions.

    Long-Term Bet on Packaged Nutrition

    Multinational food manufacturers in Southeast Asia have spent recent quarters reorganising local subsidiaries into joint ventures with domestic champions. The strategy cuts logistics costs and shields balance sheets from regional currency volatility. FrieslandCampina is trading direct control of a single subsidiary for equity control of a listed platform that manufactures its own packaging and commands local raw milk sourcing.

    “FFI will join a broader, more resilient platform serving consumers across the archipelago. Both companies will continue to operate alongside each other as separate businesses, each with its own brands, portfolios, and organisations.”

    Shareholder Approval and Next Steps

    Shareholders must now give formal sign-off. Ultrajaya scheduled an extraordinary general meeting for 27 October, where investors will vote on the proposed transfer of control to FrieslandCampina and the issuance of the 7.8 billion rights shares.

    Regulatory clearance from Indonesia’s Financial Services Authority and competition authorities will determine the timing of the subsequent mandatory cash tender offer for the minority shares.

  • PepsiCo Launches House of Brands Campaign as Only 18% Know Wider Range

    PepsiCo Launches House of Brands Campaign as Only 18% Know Wider Range

    In September 2026, PepsiCo launched a House of Brands campaign across retail channels after finding only 18 per cent of consumers associate the group with products beyond its core carbonated drink.

    The push highlights major portfolio names such as Lay’s, Cheetos, Gatorade and Quaker Oats under the corporate parent banner.

    Closing the Portfolio Perception Gap

    Consumer recognition remains heavily concentrated in beverages despite decades of multi-category expansion into snacks and packaged foods. The campaign uses hypothetical names such as Lay’s-Co, Cheetos-Co and Quaker-Co to demonstrate the scale of brands operating under the central corporate identity.

    Supermarket retailers across Asia-Pacific traditionally manage these product lines across separate aisle categories rather than as a single supplier block. Grouping savory snacks, sports beverages and breakfast staples under one umbrella strengthens supplier use during retail category reviews and joint promotional scheduling.

    Shifting Consumer Perception on Shelf

    Rival consumer goods conglomerates face similar challenges when corporate holding identities remain detached from daily shopping baskets. Linking individual product equities back to a central masterbrand helps defend shelf placement against store-brand lines across packaged grocery aisles.

    The strategy also introduces distinct exposure risks for the manufacturer. Any consumer scrutiny affecting carbonated beverage categories can transfer more readily to packaged grains or hydration products once corporate links become explicit.

    Retail performance metrics and cross-category purchasing data will show whether the awareness push drives higher basket conversion across Australian grocery chains.

  • Nestlé Koko Krunch Mobilises 11,000 Malaysian Students in Nationwide Campaign

    Nestlé Koko Krunch Mobilises 11,000 Malaysian Students in Nationwide Campaign

    Nestlé drew 11,208 primary school pupils into its Koko Kraf Club nationwide competition in Malaysia. The campaign ended with a grand finale at Kuala Lumpur’s NU Sentral mall.

    Activity spanned 534 schools across 141 districts. Organisers routed finalists through district and state elimination heats before selecting 15 teams for the national show.

    Structure of the School Programme

    Cereal Partners Worldwide, the joint venture between Nestlé and General Mills, ran the programme alongside Malaysia’s Ministry of Education. The competition aligned its brief with the Visit Malaysia 2026 promotional drive. Tasks covered three tiers: district heritage, state identity, and national landmarks.

    Sekolah Kebangsaan Balai Badang took the national title. The winning trio received RM1,500 in cash, while their school secured a RM2,000 grant.

    Classroom Access and Brand Loyalty

    Direct classroom access gives packaged food makers an early route into Southeast Asian households. Putting commercial brands inside co-curricular visual arts modules delivers access to family decision-makers. Standard television or store displays rarely match that reach.

    Retailers and modern trade distributors see steady breakfast category turnover in suburban and regional hypermarkets. When school projects require brand participation, neighbourhood grocers routinely see sales spikes for core stock keeping units.

    Competitive Brand Footprint

    Multinational food producers across the region use similar tactics. Dairy and cereal processors frequently tie promotions to public education initiatives, balancing commercial visibility with sponsorships to defend market share against domestic private labels.

    Children are naturally curious and very creative. KOKO KRAF CLUB is created to give them the space to express their point of view in a creative way.

    Commercial Alignment with National Campaigns

    This tourism link matches broader strategy across the local product portfolio. In September, Nestlé Malaysia launched tourism-themed packaging for KitKat Dark Ice Cream. It also introduced youth enterprise grants under its Nescafé banner.

    Schools in regional areas, including Sabah’s Telupid district, have already begun formalising internal art clubs. They are preparing submissions for the 2027 competition cycle.

  • Farmers Union Unites 3 Yoghurt Ranges Under Single Brand Platform

    Farmers Union Unites 3 Yoghurt Ranges Under Single Brand Platform

    Farmers Union launched its masterbrand platform, It’s A Living Thing, in September 2026. The setup brings 3 yoghurt lines, core, protein, and kids, under a single identity.

    According to the company, the initiative shifts the focus beyond live cultures and product functional benefits toward how yoghurt fits into everyday routines.

    Reframing functional health in the dairy aisle

    Marketing across all three tiers will present yoghurt as an everyday habit rather than an isolated nutritional supplement. Gut health takes a back seat to general lifestyle benefits.

    Consolidating these lines lowers marketing overhead and gives retail buyers a clean pitch. Dairy aisles face relentless pressure from private-label ranges. Branded processors must stand out.

    Brand architecture and product tiers

    Farmers Union grouped its plain yoghurt, high-protein tubs, and children’s pouches under this masterbrand. Each line keeps its distinct formulation while sharing central creative assets and packaging cues.

    Dairy manufacturers across Australia are streamlining portfolio messaging to cut customer acquisition costs. Supermarkets favour suppliers that drive category value across multiple shopper demographics at once.

    Retail pressures and supplier competition

    Australian dairy processors face tight margins and volatile farmgate milk dynamics. That pressure forces brand owners to maximize returns on processed dairy items. Moving from functional claims to lifestyle routines helps protect premium shelf prices against white-label contracts.

    Rivals across the chilled dairy sector are making similar adjustments to chase high-margin fitness and snacking shoppers. Gippsland Dairy recently partnered with Beechworth Honey. Bega also reported that its branded lines provided crucial margin support through the 2026 financial year.

    Category execution in supermarket channels

    Promotions will roll out across retail channels, digital media, and stores nationally. Commercial success hinges on a single question: can the unified look lift protein and children’s sales without hurting core plain yoghurt?

    Upcoming supermarket ranging reviews across major Australian grocery banners over coming quarters will decide if the overhaul wins expanded shelf space across all three tiers.

  • Monde Nissin Releases Two Limited-Edition Lucky Me! Pancit Canton Flavours

    Monde Nissin Releases Two Limited-Edition Lucky Me! Pancit Canton Flavours

    Monde Nissin Corporation rolled out two limited-edition flavours of Lucky Me! Pancit Canton across Philippine retail channels this week. The release pairs Extra Hot Chili with Cheese and combines the brand’s Original seasoning with Barbecue.

    Both variants target instant stir-fried noodle consumers looking for hybrid seasonings. The Extra Hot Chili and Cheese option balances capsaicin heat with a dairy profile, while the Original and Barbecue variant adds smoky sweetness to the base soy-and-citrus profile of the flagship product.

    Flavour combinations for the core line

    Limited-edition extensions allow food manufacturers to generate temporary sales bumps without retooling permanent factory lines. By mixing established spice packets with cheese and barbecue elements, Monde Nissin tests consumer appetite for western-style savoury combinations on its highest-volume dry noodle format.

    Flavour experimentation in the instant noodle segment historically relies on spicy profiles across Southeast Asia. Introducing dairy notes into a hot dry noodle directly counters imported spicy ramen varieties that have gained traction among younger demographic segments.

    Shelf space and convenience retail

    For supermarket chains and convenience operators like 7-Eleven and Ministop in the Philippines, line extensions provide promotional material for end-cap displays. Temporary flavours rotate inventory faster because shoppers treat them as impulse purchases rather than pantry staples.

    Modern trade buyers allocate prominent shelf space to short-run stock from dominant domestic suppliers. The turnover speed of limited batches protects retail margins while testing demand before deciding on permanent manufacturing commitments.

    Managing portfolio risk in instant noodles

    The operational challenge for Monde Nissin sits in inventory balance across traditional trade. In the Philippines, independent sari-sari stores generate the bulk of fast-moving consumer goods volume. If limited-edition stock lingers on wholesale shelves after marketing campaigns finish, store owners discount standard packs to clear inventory.

    Competitors like Universal Robina Corporation and imported Korean brands continue to crowd the instant noodle aisle with specialty sauces. Keeping the Lucky Me! Brand active through rotational flavours prevents volume erosion toward premium foreign alternatives.

    Distribution rollout across regional trade

    Monde Nissin distributed the initial production run to major supermarket operators and wholesalers across Metro Manila before expanding shipments to regional distribution hubs in Luzon, Visayas, and Mindanao. Retail pricing remains pegged close to the core Pancit Canton range to protect everyday volume.

    Stock allocation will run through standard retail cycles until production quotas conclude. Retail sell-through rates across modern grocery channels will dictate whether either formulation enters permanent manufacturing rotation.

  • Universal Robina Launches Great Taste Premium Roast Instant Coffee at PHP 12.95

    Universal Robina Launches Great Taste Premium Roast Instant Coffee at PHP 12.95

    Universal Robina Corporation rolled out Great Taste Premium Roast Coffee Mix across the Philippines on September 23. The single-serve sachets retail at PHP 12.95 each.

    The instant blend offers a bolder roast profile. URC is pitching it to commuters, blue-collar workers and office staff who need extra caffeine during transit and shifts.

    Sachet Pricing and Market Reach

    Each PHP 12.95 pack combines dark roast extract with a creamer base. URC designed the sachet format for neighborhood sari-sari stores, convenience chains and supermarkets across Luzon, Visayas and Mindanao.

    Distribution runs through URC’s nationwide logistics network to reach thousands of micro-retailers. These small shops generate most FMCG sales in the Philippines. Single-serve portions drive local coffee revenue as consumers manage tight daily cash budgets.

    Expanding the Instant Coffee Mix

    This rollout follows the earlier debut of Great Taste White Sugar Free Coffee. That formulation targeted urban consumers who wanted to cut sugar intake without abandoning white coffee.

    Developing high-caffeine and low-sugar options helps the company defend shelf space against multinational rivals. The Great Taste lineup now covers standard three-in-one mixes, sweet white coffee, sugar-free variants and dark roast blends.

    Rivalry in the Philippine Beverage Sector

    Competition in the local coffee aisle remains fierce. Nestlé Philippines holds substantial volume through its Nescafé lines, while PT Mayora Indah’s Kopiko brand commands heavy market share in white and high-caffeine categories.

    For sari-sari stores, inventory turnover hinges on brand loyalty and prices between PHP 10 and PHP 15 per pack. Rising costs for robusta beans and dairy substitutes squeeze margins. Still, producers must keep shelf prices steady so shoppers do not switch brands.

    Product Diversification Across Regional Markets

    Across Southeast Asia, the launch fits a broader pattern of FMCG category expansion. URC has rolled out extensions in snacks, biscuits and ready-to-drink beverages across Thailand, Malaysia and the Philippines in recent quarters.

    Fourth-quarter sales across convenience stores and general trade outlets will show whether Philippine consumers trade up to premium roast mixes in sachet format.

  • Only 17 per Cent of FMCG Launches Achieve Strong Trial and Repeat Buys

    Only 17 per Cent of FMCG Launches Achieve Strong Trial and Repeat Buys

    Only 17 per cent of fast-moving consumer goods launches achieve strong trial and strong repeat purchase, according to a 2025 study by NielsenIQ.

    A new product launch that fails to build a fast rate of sale quickly loses its shelf space, with winning back lost distribution costing even more.

    Marketing agency Social Soup notes that Australian product discovery no longer relies on single large campaigns, but on sequential creator recommendations, feed reviews, and verified trials.

    Data from the Interactive Advertising Bureau shows 58 per cent of Australian consumers now use social platforms for brand and product research. Among shoppers aged 18 to 39, 75 per cent discover products directly from creators. Spending has shifted away from broad television and static outdoor ads into verified sampling and creator-led store traffic programmes.

    The mechanics of retail store pull

    Consumer goods brands now use micro-creator networks to generate physical store visits instead of generic awareness. Beverage maker H2coco sent 100 creators with vouchers to buy its Peach variant inside Ampol service stations. The campaign produced 142 pieces of content showing the purchase and consumption. It delivered 126,600 organic views and a 7.8 per cent engagement rate, beating its 4 per cent target.

    Ampol stores saw a similar mechanic during the brand’s Matcha drink roll-out at 7-Eleven, where 51 creators repeated the purchase process. Shelf space in petrol and convenience channels is limited to immediate consumption. Quick sell-through speed determines whether an SKU earns a permanent spot in the cold vault.

    Tissue maker Sorbent used household sampling to trigger switching from rival paper brands. Its Home Truths campaign targeted 1,000 households that regularly bought competing products, generating 2,900 verified home trials and 2,158 published reviews. The push yielded an 88 per cent post-trial purchase intent score.

    Asia Pacific e-commerce shift

    These Australian figures match broader retail changes across the Asia-Pacific region, where mobile purchasing drives sales. Mobile devices account for more than 60 per cent of regional FMCG online transactions. Digital wallets make up 65 per cent of regional e-commerce settlements, compared to 83 per cent globally.

    Adoption rates vary widely across regional markets. India leads digital FMCG adoption at 90 per cent, followed by China at 86 per cent and South Korea at 60 per cent. By contrast, online penetration in traditional developed retail sectors fell from 60 per cent to 52 per cent over the past year due to price sensitivity and inflation.

    Shoppers across regional platforms track prices closely. Data shows 47 per cent of online shoppers delay buying consumer goods until major platform sales events. Delivery costs also decide basket size, with 93 per cent of shoppers calling free freight essential at checkout.

    Supplier risks and category entry points

    Suppliers carry clear operational risks when customer acquisition costs eat into retail margins. Discounting to trigger early volume damages price perception and rarely builds repeat buying habits. Supermarket buyers now demand proof of sustained demand before allocating floor space.

    Australian store operators have shortened review windows for new lines. An item that misses inventory turn targets within twelve weeks gets cut quickly. Backing launches with verified community trials gives suppliers the sales data they need to protect shelf space during quarterly range reviews.

    Global FMCG revenues, valued at 12.93 trillion dollars in 2024, are projected to reach 21.88 trillion dollars by 2034. Capturing that growth across Asia-Pacific requires brands to connect creator campaigns directly to store aisles rather than relying on stand-alone media.

    What consumer brands track next

    Brand teams in Australia and New Zealand are preparing for upcoming category range reviews across major supermarket and convenience channels. Marketers are shifting funds from slotting fees on end-caps into creator trial programmes.

    Range reviews through 2027 will test whether community sampling can lift that 17 per cent benchmark for 90-day repeat replenishment across supermarket aisles.

  • AB InBev Adds Functional Beers and Smaller Packs to Target Frugal Shoppers

    AB InBev Adds Functional Beers and Smaller Packs to Target Frugal Shoppers

    Anheuser-Busch InBev is rolling out smaller pack sizes and functional drinks with added protein or electrolytes. The brewer wants to win back price-sensitive shoppers and lift global sales volumes.

    The world’s largest brewer by market value also plans to capture more revenue from non-beer categories like energy drinks. Executives value that addressable market at 25 billion dollars.

    Sizing Down for Developing Markets

    Management revealed the strategy to investors at a London event on September 22. The plan targets occasional drinkers who cut back as inflation squeezed household budgets.

    Chief Marketing Officer Marcel Marcondes told investors that reshaping pack architecture offers clear room for growth. In developing markets, the brewer will introduce smaller single-serve containers alongside larger bulk formats that reduce unit costs.

    Data is showing us huge opportunities to make beer more affordable, especially in developing markets.

    Functional Beer and Zero-Alcohol Innovation

    Beyond packaging, the group is reformulating core drinks to meet health trends. Product teams will focus on zero-alcohol beers with distinct flavours, fewer calories and functional ingredients.

    Trials are already under way in Latin America, where the company launched a protein-fortified Spaten beer in Brazil. Electrolyte-infused recipes will follow. Executives want non-alcoholic beer treated as an everyday meal drink rather than an occasional substitute.

    Challenging Beyond Beer Categories

    Growth plans also reach past modified malt drinks. Ready-to-drink canned cocktails, led by Cutwater in the US, and energy drinks now form a central growth pillar.

    Chief Executive Michel Doukeris told shareholders the company acts like an insurgent outside traditional brewing. Strong distribution and retail shelf access give it use against established beverage conglomerates.

    Pressure on Traditional Volumes

    Beer consumption has dropped across mature markets like North America. Younger consumers increasingly turn to spirits, seltzers or sobriety. Rivals face the same headwind, pushing big brewers to diversify away from standard lager.

    Retail buyers and convenience operators will see the resized packs and fortified zero-alcohol lines enter distribution channels ahead of the next financial year.

  • Thailand Extends 43 Billion Baht Consumer Subsidy Scheme for Two Months

    Thailand Extends 43 Billion Baht Consumer Subsidy Scheme for Two Months

    Thailand’s cabinet approved a 43 billion baht ($1.29 billion) consumer subsidy extension on Tuesday. The funding supports household spending through late November.

    Each registered recipient receives 1,000 baht ($30). That injects direct liquidity into local retail checkouts and neighbourhood merchants.

    Under the extension, the state covers 60 percent of eligible purchases. Daily government co-payments are capped at 200 baht per person. Finance Minister Ekniti Nitithanprapas confirmed the decision after a Bangkok briefing. He noted the scheme cushions shoppers against high fuel and living costs linked to Middle East instability.

    How the spending programme works

    Money for the extension comes from unused allocations in the state’s 400 billion baht borrowing programme, originally created for oil-price shocks. Shoppers must pay the remaining 40 percent of each transaction out of pocket. This requirement drives cash through checkout registers rather than letting recipients stash funds in savings.

    Daily caps spread spending across weeks rather than triggering a single-day rush. The 200-baht limit channels steady foot traffic into grocery stores, wet markets and small retailers. Demand centers on packaged food, personal care and household consumables.

    What it means for retail operators

    Suppliers of fast-moving consumer goods and national convenience chains gain a clear sales bridge into the fourth quarter. The co-payment model lifts sales for registered small merchants. In turn, it pulls business away from modern trade formats excluded from government vendor lists.

    Brand owners face promotional risks. Retailers stocking up on subsidised staples could see margins shrink if wholesale input costs stay high after state support ends.

    Earlier phases and growth projections

    An initial phase ran from June through September, giving 1,000 baht a month to roughly 40 million registered citizens. That rollout built the digital systems and merchant network now handling the November extension.

    Ekniti stood by projections that Southeast Asia’s second-largest economy will grow 2.5 percent this year. That matches the ministry’s July forecast. Growth depends on private spending holding up against external trade headwinds.

    The timeline through year-end

    Consumers must spend their allocated funds before the November 30 deadline, when unused balances lapse. Retailers and analysts will track October consumption data next to see if daily checkout volumes match the June-September run.