Tag: healthcare

  • Paras Healthcare Completes USD153 Million IPO

    Paras Healthcare Completes USD153 Million IPO

    Paras Healthcare has completed a USD153 million initial public offering in India, advised by AZB & Partners, Hogan Lovells Cadwalader, and S&R Associates.

    AZB & Partners acted for the issuer alongside promoter selling shareholder Dharminder Kumar Nagar. The firm deployed a team featuring senior partner Agnik Bhattacharyya, partner Sweta Ananthanarayanan, and senior associate Tanaiy Tewari.

    S&R Associates acted for the book-running lead managers, while Hogan Lovells Cadwalader served as international counsel to an underwriting group comprising JM Financial, BofA Securities India, and Nuvama Wealth Management. Hogan Lovells Cadwalader capital markets partner Biswajit Chatterjee led the firm’s advisory team on the issue in late 2026.

    The Listing and Anchor Backers

    Paras Healthcare is a leading clinical specialty-led hospital platform providing tertiary and quaternary healthcare services under the Paras Health brand.

    International underwriters managed the global book-building process, supported by domestic investment banks. The underwriting syndicate comprised JM Financial, BofA Securities India, and Nuvama Wealth Management. AZB & Partners advised the issuer and selling shareholder Dharminder Kumar Nagar, while S&R Associates and Hogan Lovells Cadwalader represented the book-running lead managers and international underwriters.

    Operator Strategy and Regional Expansion

    Capital deployment in India’s regional hospital sector has shifted heavily toward mid-tier metros where consumer purchasing power has increased faster than specialized bed capacity. Operators in secondary cities encounter lower real estate acquisition costs and less direct competition from established national networks.

    Private hospital chains face rising clinical staff recruitment expenses and longer payback periods when installing advanced diagnostic machinery. For regional healthcare operators, converting bed count into sustainable operational cash flow requires maintaining high average revenue per occupied bed alongside steady patient footfall from domestic health insurance schemes.

    Institutional Demand for Indian Healthcare

    Sovereign wealth funds and global asset managers have consistently funnelled capital into specialized hospital platforms across Asia. The participation of Abu Dhabi Investment Authority and BlackRock in the anchor allocation shows institutional appetite for consumer healthcare assets with regional scale.

    Institutional backers prioritize multi-specialty providers capable of building regional referral clusters rather than standalone facilities. By bundling pharmacy operations, outpatient consulting, and diagnostics into physical facilities, network operators insulate operating margins against regulatory price caps on essential medical treatments.

    Preceding Deal Flow and Pipeline

    The transaction follows a steady run of Indian primary market issues across industrial and healthcare segments through late 2026. Domestic capital markets have accommodated substantial liquidity exits for private equity investors and company founders seeking public market valuations.

    Paras Healthcare must now deploy the fresh equity proceeds into planned bed additions and specialty medical technology across its core regional network, with quarterly patient volume metrics and occupancy ratios serving as the immediate operational benchmarks.
  • Asia OneHealthcare Files Draft IPO for 4.38 Billion Shares

    Asia OneHealthcare Files Draft IPO for 4.38 Billion Shares

    Malaysian hospital operator Asia OneHealthcare filed a draft prospectus for an initial public offering of up to 4.38 billion shares on Bursa Malaysia, the Securities Commission Malaysia website showed on Wednesday.

    US-based private equity firm TPG explored strategic options for the hospital group in April alongside Maybank and UBS, examining a domestic float that could value the business at around 30 billion ringgit ($7.4 billion).

    The preliminary filing omits the target offer price, total deal value and debut listing date.

    Structure of the Offering

    The deal relies overwhelmingly on vendor divestment. Controlling shareholder HLT Healthcare Holdings Singapore, the vehicle through which US buyout firm TPG holds its stake, is selling up to 3.86 billion existing shares.

    Asia OneHealthcare itself will issue 521.1 million new shares to raise primary capital. If underwriters do not exercise an over-allotment option of up to 657.1 million additional existing shares, HLT Healthcare Holdings Singapore will retain a 73.9 per cent controlling interest in the group once the transaction closes.

    Institutional buyers will take the bulk of the float. Up to 3.77 billion shares are earmarked for domestic and foreign institutional funds, while the remaining 615.5 million shares are allocated to the managing director, eligible staff, contributors to the business and the Malaysian public.

    Balance Sheet Recovery and Capital Allocation

    Proceeds raised from the newly issued shares will fund physical expansion across the hospital network, routine facility maintenance, medical machinery purchases, partial debt reduction and listing costs.

    The company turned around its bottom line in the financial year ended March 2026. Net profit hit 344.4 million ringgit, reversing a net loss of 85.8 million ringgit logged during the prior twelve months.

    Revenue expanded by 13.6 per cent year on year to reach 3.29 billion ringgit, underpinned by steady patient traffic and broader service volume.

    Asset Footprint and Market Read Across

    Asia OneHealthcare runs 23 private hospitals across Southeast Asia, anchoring 22 medical centers in Malaysia alongside a single hospital facility in Vietnam. Private equity houses and hospital groups across ASEAN continue to treat Malaysia as a primary regional hub for both high-margin medical travel and domestic middle-class elective care.

    For regional healthcare assets, this Bursa Malaysia filing sets a visible valuation benchmark. Private hospital assets in Southeast Asia have traded at steep multiples in private transactions, but institutional appetite on public bourses remains selective around balance sheet use and capital expenditure overheads.

    A public listing establishes a liquid price floor for competing operators seeking consolidation or secondary sell-downs. The heavy weighting of secondary shares signals TPG’s structured partial exit strategy while leaving operational control squarely inside the holding structure.

    The Road to Listing

    The draft submission follows exploratory work initiated in April, when TPG tapped Maybank and UBS to examine liquidity options for the healthcare platform, including the Kuala Lumpur initial public offering.

    The draft document submitted to the Securities Commission Malaysia omitted the final institutional bookbuilding range, the exact offer price, total gross proceeds and the formal listing debut date. Regulators must complete the draft review and clearance process before underwriters publish the definitive prospectus and open retail application books.

  • Thailand Selects 44 Medical AI Startups for Commercial Push

    Thailand Selects 44 Medical AI Startups for Commercial Push

    Thailand selected 44 medical artificial intelligence startups for an incubation initiative aimed at driving lab research into commercial healthcare deployments across Southeast Asia.

    More than 80 firms applied for the Medical AI Development for Entrepreneur programme, known as MADE, cutting the field to 44 ventures that now receive hospital access, cybersecurity audits and pitch sessions with regional investors.

    The programme is run jointly by the Artificial Intelligence Entrepreneur Association of Thailand, the Ministry of Higher Education, Science, Research and Innovation, and the Technology and Innovation in Life Sciences National Agency. Its target is direct market placement, building business operational plans and establishing common standards for registering clinical software ahead of show events on 30 Oct 2026.

    Chanwit Boonchuay, president of the Artificial Intelligence Entrepreneur Association of Thailand, said the MADE programme aims to turn research and prototypes into products with practical applications. The association is also building the Medical AI Network, known as MAIN, alongside regulatory guidelines intended to speed up medical product registrations.

    Developers will show their tools at the Global Medical AI Summit at True Digital Park in Bangkok on 30 Oct 2026. Hospital networks and international venture funds will review clinical software, diagnostics and operational automation platforms during matchmaking sessions scheduled throughout the event.

    Closing the gap between prototypes and procurement

    Healthtech across Asia frequently stalls at the hospital door. While Southeast Asian private hospital operators eagerly buy imaging tools and administrative automation to lower operating overhead, strict medical liability rules and lengthy clinical validation cycles often exhaust startup cash reserves long before public procurement begins.

    The bottleneck in Bangkok sits squarely in validation trials. Private chains have historically favoured established global diagnostic vendors over unproven domestic code. By offering clinical testing fast-tracks through university hospitals, the government is attempting to lower the commercial entry barrier for local software creators.

    The target for a domestic unicorn

    The state intervention follows a broader strategic directive set by Higher Education Minister Yodchanan Wongsawat to develop globally competitive deep-tech businesses and create a Thai healthcare unicorn within five years. The ministry wants the life sciences agency to shift away from acting solely as a grant dispenser and operate instead as an active venture builder.

    Seven policy priorities now steer the life sciences agency, including a joint bio-venture builder with the National Innovation Agency, a national biobank, and a unified health data infrastructure designed to link medical schools directly with clinical testing teams.

    Global startup research centre StartupBlink tracks 13,867 healthtech startups across 102 countries, representing 8.7 per cent of all tracked startups globally and an estimated ecosystem value of US$330.5 billion. Thailand wants a slice of that capital pool by using its medical tourism reputation and private hospital infrastructure.

    Next hurdles in Bangkok

    The primary barrier remains the velocity of regulatory approvals. Lengthy trial processes continue to slow down rollouts across both state and university hospitals, even as early product testing wraps up.

    All eyes now turn to the 30 Oct 2026 pitching sessions at True Digital Park, where developers will pitch hospital procurement chiefs and regional venture investors to secure pilot contracts.

  • Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore has launched a whole-of-life protection plan that covers both a child and ageing parents under a single policy, as citizens aged 65 and above exceeded a fifth of Singapore’s population in 2026.

    The insurer introduced the policy amid demographic shifts projecting that more than one in four citizens will be aged 65 and above by 2035, increasing caregiving responsibilities across households.

    How the multi-generation coverage works

    Under the policy, titled PRUActive Family Care, the caregiver’s child serves as the primary life assured. That portion provides lifetime coverage against death, terminal illness, and total and permanent disability.

    Policyholders can attach critical illness riders covering 182 conditions. These riders extend protection across both juvenile illnesses and mental health conditions.

    Parents of the caregiver gain protection up to age 100 without medical underwriting. This component pays out on diagnosis of specific age-related conditions, including Alzheimer’s disease, dementia, Parkinson’s disease, and progressive supranuclear palsy.

    The shift in retail financial products

    Insurers across Southeast Asia are retooling standard life products to address changing household structures. Traditional life policies required separate contracts, multiple administrative fees, and full medical underwriting that routinely screened out elderly parents with pre-existing conditions.

    By eliminating underwriting on designated cognitive and neurological conditions for parents, Prudential shifts the commercial proposition from individual mortality protection to multi-generational risk pooling. For retail distribution networks and financial advisers, bundled policies raise client retention by binding family units to a single provider.

    Demographic pressures on consumer balance sheets

    Household economics are shifting rapidly in aging Asian financial hubs. Singapore’s official demographic forecasts project that more than one in four citizens will reach age 65 or older by 2035, accelerating the dependency ratio on working adults.

    Rising caregiving expenses place direct pressure on household discretionary spending and retirement savings. Financial institutions packaging eldercare contingencies with childhood coverage want to capture premium flows before standalone long-term care costs deplete family budgets.

    What to watch next

    Carriers across Singapore are competing for market share in aging-related protection, adjusting critical illness definitions and riders to match lengthening life expectancies. A key development to watch is whether Singapore’s citizen dependency ratio accelerates before the projected 2035 threshold of 25 percent.

  • Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Solutions has opened a microbiology laboratory at its sterile injectable plant in Lexington, Kentucky. The project advances an 85 million dollar expansion.

    The new space triples testing floor area. It targets a 50 per cent cut in product release turnaround times.

    Regulators cleared routine Good Manufacturing Practice work on September 11, 2026. Conditional approval for the adjoining sterility suite followed soon after. The lab unit forms the first operational phase of the multi-year capital program.

    Boosting Sterility and Cleanroom Capacity

    Engineers reconfigured the Lexington site to handle higher volumes of sterile drug products for clinical and commercial use. The upgrade adds three biosafety cabinets for concurrent testing. It also consolidates all incubation equipment into a single footprint.

    A dedicated Grade C cleanroom suite houses a Grade A sterility testing isolator. That setup replaces a non-classified zone. It doubles testing throughput by running open and closed filtration on multiple batches at once. Built-in sample pass-throughs connect manufacturing suites directly to analytical benches.

    Cutting Release Bottlenecks for Injectables

    Global sterile injectable manufacturing faces capacity crunches, particularly for antibody-drug conjugates, peptides and high-potency small molecules. Bringing microbiology and sterility testing in-house cuts sample transport delays. It also lowers contamination risks.

    Faster batch clearance gives the company an edge over Asian contract development and manufacturing rivals tied strictly to domestic facilities. Shorter release cycles also help pharmaceutical clients. They trim inventory holding costs and speed market access.

    Indian CDMOs Expanding Global Footprints

    Indian contract manufacturers continue to buy and upgrade assets in North America and Europe to stay close to clinical sponsors. Piramal Pharma Limited trades in Mumbai on both the BSE and the National Stock Exchange of India. It runs 17 development and manufacturing sites across India, North America and Europe, alongside hospital generics and consumer healthcare units.

    Through its subsidiary Yapan Bio, the parent company entered complex biologics manufacturing while keeping fill-finish work in Western jurisdictions. Cleanroom and testing capacity in the United States protects contract volume from overseas trade barriers and inspection backlogs.

    Timeline for Full Commercial Operations

    Nathan Richardson, vice president and site head at the Lexington facility, said: “By enhancing sterility testing and microbiological quality capabilities, we are further strengthening our ability to support clients with high quality, reliable, and responsive services throughout the product life cycle.”

    Crews are now installing commercial-scale fill and finish equipment across the remaining space. Piramal expects the full Lexington plant to reach commercial readiness in late 2027.

  • Singapore Activates Haze Subsidies as PSI Hits 151

    Singapore Activates Haze Subsidies as PSI Hits 151

    Singapore opened subsidized medical care across polyclinics and participating private clinics on October 12 after transboundary smoke pushed the 24-hour Pollutant Standards Index to 151.

    The Ministry of Health activated both the Public Health Preparedness Clinic scheme and the Haze Subsidy Scheme following a sustained week-on-week rise in hospital emergency admissions for respiratory conditions.

    All Singapore citizens qualify for subsidized consultations and treatments for haze-linked ailments at government polyclinics, including allergic rhinitis, asthma, bronchitis, conjunctivitis, chronic obstructive pulmonary disease, and upper respiratory tract infections.

    How The Subsidy Pricing Structure Works

    Patients visiting participating private general practitioner clinics face tiered co-payments based on concession status. Public Assistance cardholders receive treatment at zero cost.

    Pioneer Generation and Merdeka Generation seniors pay no more than S$5 per visit. Other eligible lower- to middle-income citizens, children under 18, and adults over 65 holding Community Health Assist Scheme cards pay a maximum fee of S$10.

    The government reimburses the remaining service costs directly to participating medical operators. Close to 1,000 of the roughly 1,370 private clinics enrolled in the national preparedness network confirmed participation ahead of the Monday launch.

    Hospital Protocols and Urban Foot Traffic

    Hospitals across the island stepped up baseline containment procedures over the weekend. Staff closed ward windows and corridor openings. They ran indoor mechanical ventilators, spot coolers, and commercial air purification systems.

    A surge in influenza A infections coincided with the jump in pollution. The combined caseload drove higher patient volumes into polyclinic waiting rooms and private neighborhood practices across housing estates.

    Extended smoke haze shifts consumer footfall from open-air street precincts into enclosed, air-conditioned retail centres. Operators in suburban transport hubs absorb heavier retail traffic. Meanwhile, outdoor recreation and alfresco food venues face immediate booking cancellations.

    Comparison With Previous Severe Episodes

    Authorities last activated the full Haze Subsidy Scheme in 2015. Prolonged agricultural fires across regional peatlands blanketed the city-state for weeks during that crisis, pushing pollution readings beyond the 300 hazardous threshold.

    Health Minister Ong Ye Kung confirmed that current inter-monsoon wind patterns and low rainfall suggest the smoke haze will linger over the island for several more weeks. Prevailing wind flows prevent quick atmospheric clearing across southern Malaysia and the Singapore Strait.

    Across the border, air quality data tracked parallel deterioration. Environmental stations in Johor recorded index readings reaching 180 in Pasir Gudang, reflecting widespread exposure across the shared industrial and logistics corridor.

    Air Quality Readings Across the Island

    National Environment Agency monitoring stations registered unhealthy air quality ratings across all five island zones on October 11. Readings between 101 and 200 fall under the agency’s unhealthy classification band.

    Western districts recorded the highest 24-hour index at 151. Central commercial zones followed at 149, while eastern residential neighborhoods stood at 135. Northern and southern coastal sectors both recorded readings of 115.

    Health authorities advised residents with chronic heart or lung ailments to avoid outdoor exertion until daily readings drop below the 100 mark.

  • Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Pharma Thailand introduced a higher-dose semaglutide option on October 7. The treatment addresses type 2 diabetes and linked cardiovascular risks across the country.

    It targets an expanding patient base. Diabetes prevalence in Thailand climbed to 10.6 per cent in 2025, up from 9.5 per cent in the 2020 national survey.

    The Danish drugmaker presented the formulation to more than 500 Thai medical practitioners at an industry gathering. The therapy targets cardiovascular-kidney-metabolic syndrome. That condition links heart disease, renal impairment, and obesity in diabetes patients.

    Expanding Treatment Beyond Glycaemic Control

    Cardiovascular disease is the leading cause of death among Thai type 2 diabetes patients. Chronic kidney disease also affects up to 40 per cent of diagnosed patients. Diabetes remains the primary driver of end-stage renal failure nationwide.

    Doctors gain an extra clinical tool for weight management and organ protection alongside blood glucose reduction. Most Thai adults with type 2 diabetes are overweight or obese. This compounds their health risks.

    Distribution runs through state hospital tenders, private hospital networks, and licensed retail pharmacies across the Kingdom. The company has operated locally for more than four decades, supplying metabolic and chronic disease therapies through all three channels.

    Commercial Stakes in Southeast Asian Healthcare

    Demand for advanced glucagon-like peptide-1 receptor agonists has surged across Southeast Asia. Lifestyle illnesses now place heavy pressure on state healthcare funds. In Thailand, universal health coverage schemes face rising long-term costs from dialysis and acute cardiac interventions.

    Drug suppliers compete directly for formulary spots in private hospital groups and government procurement lists. Higher dosage strengths help manufacturers preserve revenue per patient. They also defend market share against emerging biosimilars and rival GLP-1 therapies entering Asian markets.

    Premium chronic therapies provide healthcare operators and pharmacy chains with steady prescription volumes. Affordability and public reimbursement access remain the main hurdles. Because of those limits, high-dose therapies rely largely on private payers and self-funded patients.

    Four Decades of Thai Market Presence

    Novo Nordisk established its formal presence in Thailand more than 40 years ago. It built distribution relationships with public teaching hospitals and private medical groups, later rolling out baseline semaglutide formulations across Southeast Asia after global clearances.

    Novo has been at the forefront of diabetes care for more than a century, and we recognise that type 2 diabetes is one of the most pressing public health challenges of our time. In Thailand, it is closely linked to CKM syndrome, conditions that place an enormous burden on families and on the Thai healthcare system.

    Next year, the pharmaceutical producer will hold clinical symposiums across provincial medical hubs. These sessions will train specialists on prescribing protocols for the higher dosage.

  • AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    Medical costs across Southeast Asia will surge by up to 21 per cent in 2025, forcing insurers and healthcare operators to replace traditional fee-for-service billing models with bundled pricing and tighter network controls.

    Forecasts compiled by Mercer Marsh Benefits show medical trend rates hitting 21 per cent in the Philippines, 19 per cent in Indonesia, and 15 per cent in both Malaysia and Vietnam. These double-digit increases run well ahead of headline consumer price inflation across the region, putting immediate strain on corporate benefits budgets and personal household finances.

    Waste Drives a Quarter of Regional Healthcare Spending

    An estimated 25 per cent of all healthcare expenditure across Asian markets stems directly from administrative and clinical waste. This inefficiency includes unnecessary surgical interventions, prolonged hospital stays, inappropriate antibiotic prescriptions, and inadequate preventive screenings.

    Payor-provider alignment could help eliminate redundant treatment cycles by linking compensation to clinical outcomes rather than the volume of procedures billed. Under the traditional fee-for-service structure, private hospitals and clinics face financial incentives to run additional diagnostic tests and extend inpatient admissions regardless of clinical necessity.

    Addressing these inefficiencies requires insurers and medical providers to standardise diagnostic and clinical data at the line item level. Sharing harmonised laboratory results, procedure codes, and diagnostic files across private networks reduces duplicate testing and accelerates claims adjudication.

    Out-of-Pocket Spending Surges Across Key Markets

    Rising medical costs are shifting directly onto consumers across developed and emerging economies alike. World Health Organisation figures cited by AIA show personal out-of-pocket healthcare expenditure jumped 13 per cent in both Singapore and Australia between 2022 and 2023.

    Emerging markets saw similar spikes over the same twelve-month window. Patients in India and Indonesia experienced a 10 per cent increase in direct out-of-pocket spending, eroding discretionary consumer purchasing power as basic medical treatments absorb larger portions of family income.

    Price opacity in private hospital networks worsens the burden. Transparent fee schedules for standard procedures allow policyholders to compare facilities effectively while enabling insurers to steer patients toward cost-effective treatment pathways.

    Alternative Payment Models and Preferred Panels

    Insurers are pushing private healthcare operators toward alternative commercial agreements, including episode-based bundled payments and risk-adjusted provider networks. Bundled rates establish a single, fixed fee for an entire course of treatment, eliminating unexpected add-on charges for routine post-operative care.

    Payors are also constructing preferred provider panels using verified clinical outcome metrics. Facilities that demonstrate lower complication rates and strict adherence to treatment protocols receive higher patient volumes and predictable fee schedules in exchange for discounted service tariffs.

    This structured collaboration replaces transactional claims processing with multi-year commercial partnerships. Hospitals secure stable patient flows across competitive metropolitan markets, while insurers contain underlying claims volatility.

    Corporate Benefit Pressures in 2025

    Medical trend rates remaining in double digits across Southeast Asia present an operational challenge for corporate employers competing for talent. Companies face the choice of absorbing premium hikes, reducing policy coverage limits, or passing higher deductibles to staff.

    The pressure is acute in markets like the Philippines and Indonesia, where private medical insurance serves as a primary tool for corporate staff retention. Retail operators, commercial landlords, and regional service conglomerates operating across multiple Asian jurisdictions must renegotiate group policy structures to keep benefit plans solvent.

    Attention now turns to the rollout of standardised digital health records and published procedure tariffs across major private hospital operators in Malaysia, Vietnam, and Indonesia ahead of the 2025 contract renewal cycle.

  • Singapore Expands Drug Regulatory Alliances Across Malaysia, Middle East and Africa

    Singapore Expands Drug Regulatory Alliances Across Malaysia, Middle East and Africa

    Singapore’s Health Sciences Authority signed cross-border regulatory pacts with counterparts in Saudi Arabia and Africa. At the same time, Malaysia began piloting Singaporean medicine assessments to speed up commercial drug clearances.

    The pilot with Malaysia’s National Pharmaceutical Regulatory Agency started on 1 September 2026. It establishes a formal reliance framework to eliminate duplicate clinical reviews across both markets.

    Under the bilateral trial, Malaysia’s agency is evaluating whether referencing evaluations by Singapore’s Health Sciences Authority can shorten review timelines without lowering safety or efficacy benchmarks. A successful trial will prompt Malaysia to designate Singapore as an official reference agency. That step would give drugmakers with Singaporean clearances an accelerated registration route in Kuala Lumpur.

    Faster approvals across ASEAN

    For pharmaceutical distributors, biotechs, and consumer healthcare brands, duplicative licensing remains a costly barrier to scaling products across Southeast Asia. Fragmented national registries across ASEAN historically forced manufacturers to submit separate dossiers. Companies then had to wait out multi-year evaluation cycles in each domestic market.

    Singapore’s push to become an international evaluation hub shifts that dynamic for regional supply chains. Under mutual reliance models, regional health agencies replace independent full-scale assessments with shared technical oversight. This cuts administrative overhead for suppliers and speeds up treatment rollouts in retail pharmacies and hospitals.

    Bilateral deals with Riyadh and the African Union

    Beyond Southeast Asia, HSA signed two agreements between 14 and 16 September 2026. The agency inked a memorandum of understanding with the Saudi Food and Drug Authority to exchange pre-market and post-market safety data. The deal also builds regulatory pathways for biotechnology and artificial intelligence applications in healthcare.

    The second agreement, signed with the African Medicines Agency, creates a cooperative framework covering regulatory science, capacity development, and technical reviews. Under the pact, African regulators can use Singaporean approvals as technical benchmarks for national decisions across member states.

    “A medicine or medical device should not have to wait because trusted regulators are repeating the same high-quality work,” HSA CEO Raymond Chua said. “By enabling partners to draw on HSA’s assessments, we can reduce duplication, support more timely access to safe and effective health products, and help innovators reach patients across more markets.”

    Expanding European lab standards

    Ties with European and British authorities also expanded. Following a joint audit, the European Directorate for the Quality of Medicines and HealthCare extended Singapore’s associate membership in the General European Official Medicines Control Laboratory Network to include the city-state’s National Biologics Testing Laboratory.

    The European accreditation allows Singapore to participate in global testing programs for complex biological drugs. At the same time, Singapore and the UK Medicines and Healthcare products Regulatory Agency reaffirmed their Regulatory Innovation Corridor. Opened in December 2025, the initiative gives developers of novel drugs early, iterative regulatory guidance across both jurisdictions.

    The timeline for regulatory convergence

    During its 2026 chairmanship of the International Medical Device Regulators Forum, Singapore delivered an operational playbook for regulatory reliance. It also released technical frameworks for artificial intelligence in medical devices and product cybersecurity. In addition, HSA deployed a large language model tool built with GovTech Singapore to map medical device adverse event reports directly to global classification standards.

    Regulators in Kuala Lumpur will track data from the reference pilot over the coming quarters. Their findings will determine whether to formalize Singapore’s status as a permanent reference agency for Malaysian drug registrations.

  • Gleneagles Hospital Completes Hong Kong’s First 2 Histotripsy Cancer Trials

    Gleneagles Hospital Completes Hong Kong’s First 2 Histotripsy Cancer Trials

    In April, Gleneagles Hospital carried out Hong Kong’s first two clinical trial procedures using histotripsy to destroy pancreatic cancer tumours in patients for whom conventional surgery was unsuitable.

    In one case, doctors targeted both the primary pancreatic tumour and cancer that had spread to the liver during the same procedure using precisely targeted sound waves.

    Clinical rollouts and equipment targets

    Dr Neal Kassell, founder and chairman of the US-based Focused Ultrasound Foundation, estimated that clinical trial results for pancreatic and brain cancers could emerge in about three years, predicting global machine deployments could rise from roughly 2,000 to 10,000 systems within five years.

    Clinical evidence covers 196 potential medical indications across neurology, oncology, and pharmacology, according to data from the Focused Ultrasound Foundation. Twelve of those indications advanced to first-in-human clinical trials last year. More than one million patients have received focused ultrasound therapies globally to date, with annual treatment volumes reaching approximately 75,000 cases.

    Treatment pricing and hospital economics

    Hospital operators face steep upfront hardware costs and slow physician onboarding. In Hong Kong, treatment access relies heavily on private philanthropy to bridge gaps in public health insurance. Eligible liver cancer patients receiving histotripsy at Gleneagles pay HK$50,000 (US$6,374) under a subsidy funded by the Li Ka Shing Foundation.

    Specialist consultations and preliminary liver ultrasound assessments add between HK$4,300 and HK$5,400 to out-of-pocket patient expenses. Without formal public reimbursement or standardised private insurance schedules, hospital adoption across private healthcare chains in Southeast Asia and East Asia remains confined to flagship research centres.

    Overcoming the blood-brain barrier

    Beyond thermal and mechanical tumour ablation, clinical teams are testing low-intensity sound waves to deliver pharmaceuticals directly into brain tissue. The acoustic waves stimulate microscopic bubbles in the bloodstream, prompting them to expand and contract against capillary walls. This rhythmic motion creates a temporary opening in the blood-brain barrier, allowing chemotherapies and immunotherapies to reach aggressive conditions such as diffuse midline glioma and glioblastoma.

    Opening this barrier allows oncologists to test compounds that previously failed clinical trials simply because molecules could not penetrate the central nervous system. Combining acoustic opening with local immune responses also provides a pathway to turn drug-resistant brain tumours into active targets for immunotherapy.

    Reimbursement pathways and regulatory hurdles

    Commercial viability for medical equipment makers in Asia depends on moving beyond self-pay arrangements. Most private medical centres keep focused ultrasound machinery under capacity because few surgeons have received specialised training on acoustic ablation consoles.

    The critical financial hurdle remains insurance coding. Until state healthcare panels and major medical underwriters establish specific reimbursement tariffs for focused ultrasound oncology procedures, equipment makers will struggle to convert trial successes into steady device sales across regional hospital groups.

    Global trials assessing overall survival rates and recurrence intervals in pancreatic cancer and glioblastoma are scheduled to release primary outcome data within the next three years.

  • Malaysia Sends Misleading Online Health Ad Complaints to MCMC

    Malaysia Sends Misleading Online Health Ad Complaints to MCMC

    Malaysia will route public complaints regarding deceptive online health advertisements directly to the Malaysian Communications and Multimedia Commission (MCMC) for regulatory review.

    Communications Minister Datuk Seri Fahmi Fadzil announced the measure on Sept 20 following consultations with medical associations and healthcare industry experts in Kuala Lumpur.

    Referrals to the Communications Regulator

    Under the process, reports of online promotions that violate existing advertising standards or mislead buyers will undergo formal assessment by the MCMC alongside relevant authorities. The regulator holds statutory power over internet service providers, social platforms, and digital broadcast content operating in the country.

    Fahmi stated that direct engagement with medical practitioners and sector representatives was necessary to assess the scale of non-compliant claims across web platforms.

    The matter will be referred to MCMC for review and further action with the relevant parties.

    Scrutiny on Digital Marketplaces and Social Feeds

    Health and wellness categories generate substantial digital marketing expenditure across Southeast Asian e-commerce networks. Unverified supplement promotions, unauthorized medical endorsements, and exaggerated therapeutic claims have multiplied across social media storefronts and live-commerce broadcasts.

    Brand owners, third-party merchants, and advertising agencies operating in Malaysia face tighter scrutiny over consumer product claims. Platform operators will come under greater pressure to remove offending health listings swiftly once regulatory flags are raised.

    Enforcement Across Marketing Channels

    Stricter referral protocols shift compliance risks directly onto digital platforms and marketplace sellers. E-commerce platforms that host non-compliant merchant campaigns risk formal inquiries from the communications regulator if flagged product copy remains active.

    For legitimate consumer healthcare brands, consistent enforcement levels the playing field against unauthorized sellers using unverified medical claims to capture market share. Clearer boundaries also reduce reputational risks for mainstream ad networks carrying merchant inventory.

    Next Steps for Policy Coordination

    Cross-agency cooperation between communications regulators, health authorities, and trade ministries forms the baseline for monitoring deceptive online retail content. Inter-agency reviews often precede formal guidelines detailing takedown timelines and merchant penalties.

    The MCMC is scheduled to begin reviewing referred complaint files alongside partner agencies to establish concrete enforcement steps for active online campaigns.

  • Sunway Healthcare Starts Work on $196M Hospital in Johor

    Sunway Healthcare Starts Work on $196M Hospital in Johor

    Sunway Healthcare broke ground on an RM800 million ($196.2 million) tertiary hospital in Johor. The project is its first medical facility in Malaysia’s southern state.

    Planned for completion in 2030, Sunway Medical Center Iskandar Puteri will house more than 400 beds. It will employ over 1,400 healthcare staff.

    Located inside Sunway City Iskandar Puteri, the hospital sits within a 2,000-acre development launched in 2014. Around 7,000 residents live in the township today. Developers have completed more than 30 per cent of the master plan and sold roughly 2,000 homes.

    Expanding Footprint Across Johor

    The Iskandar Puteri facility anchors a series of specialized care projects across the state. Sunway Healthcare plans to open the Sunway Fertility Centre at Sunway Citrine in 2027. An ambulatory care centre will follow in 2028 near the upcoming Johor Bahru to Singapore Rapid Transit System link.

    Group leadership is also evaluating dedicated elder-care properties in the area. By 2032, the company intends to operate eight hospitals throughout Malaysia. That network will exceed 3,400 beds.

    Cross-Border Healthcare Demand

    Placing medical assets near the Singapore border targets two patient groups: local residents in suburban corridors and international medical tourists seeking private care at lower currency valuations. The Johor-Singapore Special Economic Zone adds tax and operational incentives to draw cross-border traffic.

    Competition for clinical talent will intensify for regional operators such as IHH Healthcare and KPJ. Medical staffing remains tight across Southeast Asia. Execution will depend on hiring and retaining senior doctors across competing networks.

    Consolidated Balance Sheet Backing

    Funding for the Johor site follows Sunway Healthcare’s debut on the Main Market of Bursa Malaysia in March. The business posted a net profit of RM111.48 million on revenue of nearly RM1.26 billion for the six months ended June 30. Those results represent year-on-year gains of 39 per cent and 27 per cent respectively.

    Sunway Group, led by founder Jeffrey Cheah, controls diversified holdings in construction, real estate, education, and infrastructure. Cheah’s net worth stood at $5.3 billion in April, ranking him eighth among Malaysia’s wealthiest individuals.

    Next Milestones for Delivery

    Site preparations included buying four land parcels within Sunway City Iskandar Puteri for RM45.37 million to accommodate the medical campus. Construction schedules now track progress on the RTS corridor connecting Johor Bahru and Singapore.

    Operations begin with the fertility clinic launch in 2027. That opening will test the southern medical network before the main hospital opens in 2030.

  • China Targets 25% Share of Global First-in-Class Drugs Market by 2030

    China Targets 25% Share of Global First-in-Class Drugs Market by 2030

    China has set its sights on capturing at least a quarter of the world’s first-in-class drugs market by 2030 under a new five-year plan to become a global biomedicine powerhouse.

    The plan requires large pharmaceutical enterprises to generate a combined revenue of no less than 3.5 trillion yuan (US$522 billion) driven by technological breakthroughs across critical fields.

    As authorities seek to build scale beyond market leaders like Sinopharm, which generated 575 billion yuan last year, the policy outlines 10 measurable targets, including producing at least 50 drugmakers with annual revenue exceeding 10 billion yuan each.

    Revenue Targets for Top Drugmakers

    Meeting the top-line target requires faster consolidation across state-backed and private drugmakers. Sinopharm, the country’s largest pharmaceutical distributor, generated 575 billion yuan in revenue last year. State planners want to replicate that scale across the manufacturing base.

    Reaching 3.5 trillion yuan across leading firms means turning mid-tier developers into commercial powerhouses. These firms must fund long clinical trials. Capital must also shift away from low-margin generics into novel compounds.

    Building Scale Across the Supply Chain

    Healthcare operators, hospital networks and procurement platforms will see supplier negotiations change. State purchasing programs have spent years cutting generic drug prices. That compressed distribution margins while freeing hospital budgets for innovative therapies.

    Institutional investors face a different risk profile across the sector. Backing early-stage discovery brings higher clinical failure rates than reformulating existing drugs. Capital will concentrate around the 50 major players capable of clearing the 10 billion yuan threshold.

    Shifting from Generics to Innovation

    Commercial drug distribution historically relied on large volumes of off-patent medications to support national healthcare coverage. Domestic intellectual property stayed tied to fast-follower treatments rather than novel biologics.

    Recent regulatory reforms sped up drug approvals and aligned domestic clinical trial standards with international norms. The new five-year plan builds directly on that operational base.

    The 2030 Benchmarks

    Execution hinges on domestic developers clearing late-stage international trials and licensing compounds overseas. Dealmakers are tracking the pace of mergers and pipeline acquisitions needed to build 50 ten-billion-yuan producers before 2030.

  • Herbalgy Launches 27-Year Campaign in Hong Kong with Keung To

    Herbalgy Launches 27-Year Campaign in Hong Kong with Keung To

    Hong Kong topical pain relief maker Herbalgy Pharmaceutical launched an anniversary retail push on September 16. The promotion features 27 per cent discounts and tiered basket incentives on its direct-to-consumer online store.

    The campaign pairs the brand’s 27th year in business with Hong Kong pop idol Keung To. The singer turns 27 this year.

    Discounts and High-Ticket Spend Tiers

    Shoppers face three volume incentives on the brand’s website. A one-day flash sale cut prices by 27 per cent across the catalogue on September 16. A month-long gift promotion runs through October 15. That offer gives customers an exclusive Keung To merchandise gift on net purchases of HK$430 or more.

    To lift order values among regular buyers, the company added an upper tier requiring a single net spend of HK$2,700. Reaching that threshold yields 27 units of 5 ml portable pain relief products.

    The Direct-to-Consumer Push for Traditional Formulations

    Traditional Chinese medicine makers across Hong Kong face steady pressure to turn pharmacy foot traffic into direct digital accounts. Medicated oils and plasters rely heavily on neighborhood dispensaries. In those physical shops, distributor fees and shelf rental costs squeeze profit margins.

    By partnering with a celebrity ambassador, Herbalgy aims to bypass retail intermediaries and secure higher gross margins. Retaining those buyers after discounts expire remains the central commercial risk. That challenge grows when asking shoppers to spend HK$2,700 on everyday topical remedies.

    Roots in Hong Kong Manufacturing

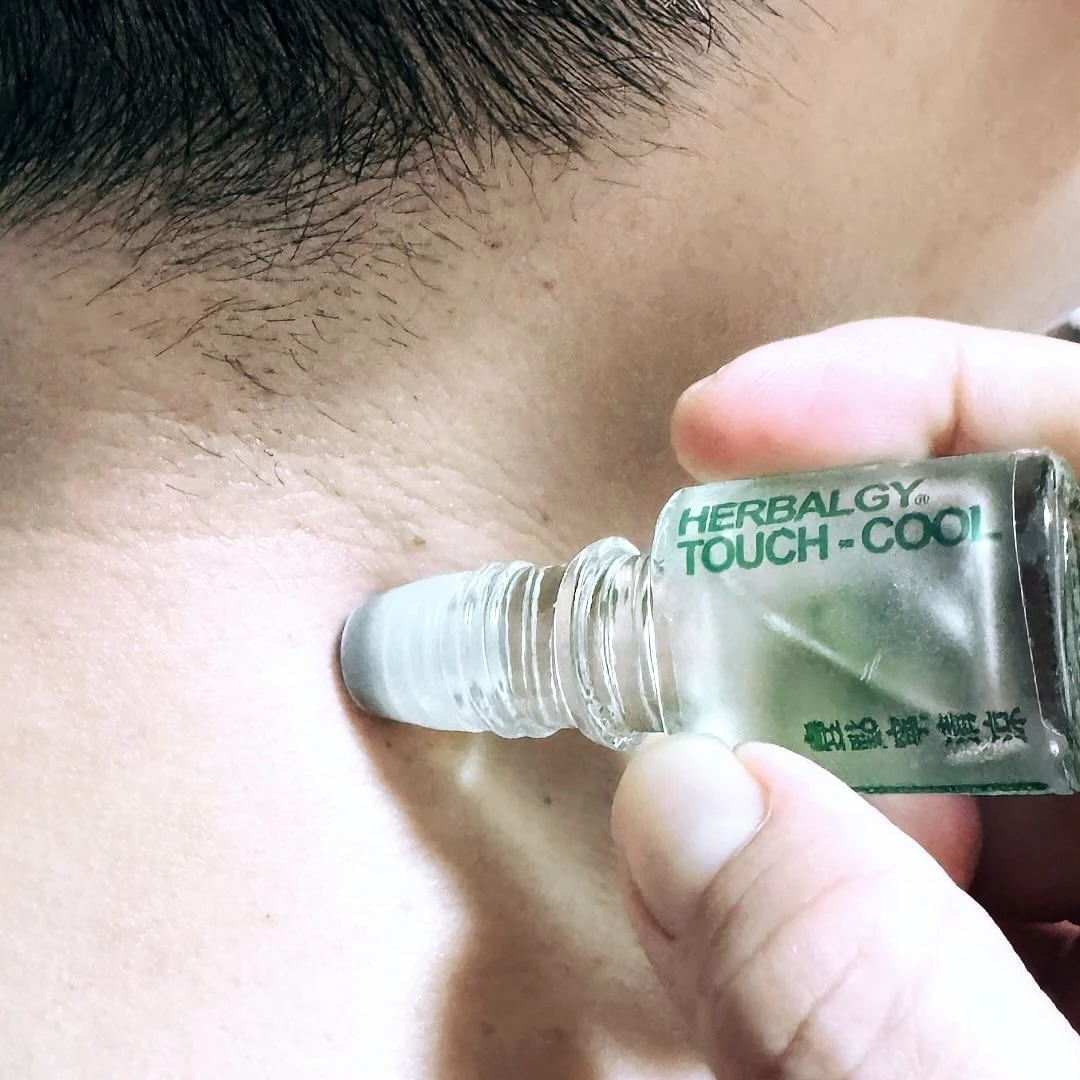
    Chinese medicine practitioner Professor Wong Tin Chee founded Herbalgy in 1999. He built the business on formulas created by his father, medicated oil producer Wong To Yick. Wong set up a Good Manufacturing Practice facility in Hong Kong to make registered proprietary Chinese medicines, later adding brands such as Touch Cool and Tibet Red.

    Digital sales and the Keung To gift promotion continue on Herbalgy’s official storefront through October 15, 2026.

  • Ralph Lauren Partners with Korea National Cancer Center for 2028 Facility

    Ralph Lauren Partners with Korea National Cancer Center for 2028 Facility

    Ralph Lauren will open its first Asian cancer recovery facility in Goyang, South Korea, in 2028 through a partnership with the Korea National Cancer Center Foundation.

    This project extends the New York-listed luxury group’s philanthropy into South Korea. Government registry figures show more than 2.7 million people in the country live with or beyond cancer.

    Inside the Goyang facility

    Plans place the Ralph Lauren Center for Patient and Family Recovery inside the Phase II Proton Therapy Center at the National Cancer Center’s new Innovative Cancer Research Center. The facility will provide recovery rooms, psychological counseling, family education and social welfare support for proton therapy patients.

    Funding flows through Pink Pony, Ralph Lauren’s global oncology initiative founded in 2000. That program currently supports 38 beneficiary projects across 17 countries. The company has funded local cancer programs in South Korea since 2012, but the Goyang project is its first physical center in the region.

    Cancer care should extend beyond treatment itself to helping patients return to their daily lives and improve their quality of life.

    Han-Kwang Yang, president of the National Cancer Center of Korea and chairman of the Korea National Cancer Center Foundation, noted that proton therapy requires extended care. Those long treatment cycles place heavy emotional demands on families, making non-clinical support spaces essential.

    Luxury philanthropy across Asian markets

    Global apparel and luxury houses have shifted corporate giving in North Asia away from generic sponsorships toward long-term civic infrastructure. For luxury groups operating in Seoul’s department stores and duty-free corridors, institutional healthcare partnerships build local goodwill. Transactional marketing cannot match that standing.

    The Goyang facility mirrors Ralph Lauren’s healthcare network in the West. That roster includes facilities at Memorial Sloan Kettering in New York, Georgetown University in Washington, USC Norris in Los Angeles, the University of Chicago and the Royal Marsden in Britain. Adapting that model to East Asia tests whether Western lifestyle brands can anchor specialized public health infrastructure in state-run Asian medical institutions.

    Building out regional healthcare commitments

    Overseas, the retailer recently established the UChicago Medicine Ralph Lauren Center in the United States as part of a wider run of foundation grants. In South Korea, the National Cancer Center has operated under the Ministry of Health and Welfare since 2000. The agency serves as the central coordinator for nationwide oncology research, clinical practice and patient screening.

    Construction on the broader Innovative Cancer Research Center is underway in Goyang. When the complex opens in 2028, the Ralph Lauren facility will begin welcoming proton therapy patients and their families.