Tag: insurance

  • Tokio Marine to Sell AI Robot Insurance Next Month as Market Eyes $80B

    Tokio Marine to Sell AI Robot Insurance Next Month as Market Eyes $80B

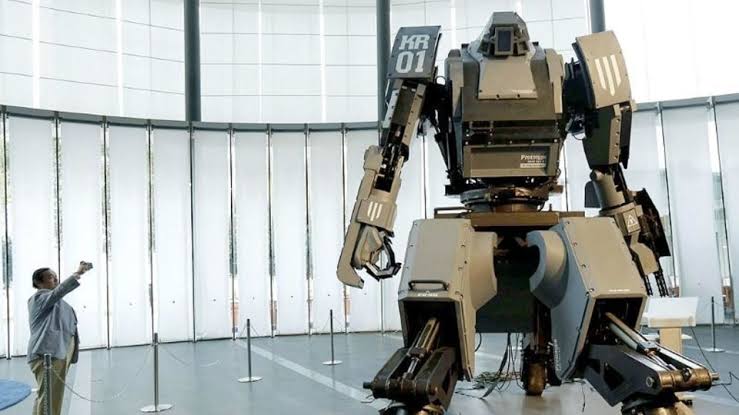
    Tokio Marine Holdings will launch commercial insurance policies for artificial intelligence-powered robots in Japan starting next month, pricing premiums roughly 20 percent higher than traditional industrial equipment coverage.

    The policy targets a sector where the global market for physical AI systems is forecast to pass $80 billion by 2035.

    Premium Pricing for Autonomous Machine Risk

    The insurer becomes Japan’s first property and casualty underwriter to build a dedicated product for machines operating on autonomous AI systems. Tokio Marine sets the baseline cost 20 percent above regular industrial machinery to account for unpredictable software decisions and operational errors.

    Autonomous robots deployed in warehouses, retail distribution centers, and manufacturing plants operate outside rigid pre-programmed scripts. When self-learning hardware damages inventory, injures floor personnel, or halts an entire sorting facility, assigning liability between hardware makers, software coders, and facility owners becomes legally complex.

    Commercial Impact for Logistics and Fulfillment

    Warehousing networks and commercial operators across Asia-Pacific face rising capital outlays to automate sorting and fulfillment amid persistent labor shortages. Adding a 20 percent insurance premium increases the operating cost of adopting autonomous fleets, shifting financial calculations for third-party logistics firms.

    Underwriting standards established by Tokio Marine will likely serve as a benchmark for rival non-life insurers across East Asia. Japanese underwriters have historically waited for clear loss ratios before entering specialized tech segments, leaving commercial operators to absorb unhedged software failure liabilities.

    Shifting Liabilities on Factory Floors

    Earlier enterprise policies treated automation strictly as mechanical failure or fixed electrical breakdown. Those legacy contracts proved inadequate as machine learning systems gained agency to alter their own physical operational paths in real time.

    Japan’s industrial robotics sector has pushed rapid integration of generative and physical AI models, forcing insurers to respond. Tokio Marine structured the coverage to absorb both third-party property damage and operational liability claims triggered by software-driven robotics.

    The Next Regulatory Hurdle

    Japanese competitors face pressure to publish their own autonomous robotics underwriting terms.

    Tokio Marine plans to roll out the first batch of corporate policies across Japanese industrial facilities starting next month, testing whether automated warehouse operators will accept the higher rate structure.
  • Shell Sued for $108 Million in Brazil over Deadly Floods

    Shell Sued for $108 Million in Brazil over Deadly Floods

    British energy giant Shell is facing legal action in Brazil and the United Kingdom seeking compensation for devastating extreme weather disasters.

    On Friday, Brazilian federal prosecutors and the non-governmental organization Instituto Preservar jointly filed a lawsuit against Shell’s subsidiary demanding $108 million over catastrophic 2024 floods.

    Attribution Science Drives $108 Million Claim

    The disaster in southern Brazil killed nearly 200 people, displaced half a million, and caused widespread destruction, marking the first time attribution science has been used in the country against a major carbon producer.

    Plaintiffs based their legal claim on research published in a Nature group journal, which calculated that climate change increased the intensity of the 2024 rainfall by 12 percent. Drawing on data from think tank Carbon Majors attributing 2.02 percent of historic global emissions to Shell, the lawsuit demands the company pay for two percent of that 12 percent intensification.

    Philippine Typhoon Survivors File in London

    The Brazilian case follows a 2025 lawsuit brought in London by roughly 100 survivors of Typhoon Rai, known locally in the Philippines as Odette. The December 2021 storm killed more than 400 people across several Philippine islands and wiped out entire coastal communities.

    Lawyers at Hausfeld filed the London action against Shell on behalf of the Philippine survivors, arguing that historic emissions and alleged misinformation on climate risks constitute actionable negligence under Philippine law. The legal team cited historical evidence indicating Shell understood fossil fuel impacts as early as the 1960s, alongside an internal 1986 company report detailing greenhouse gas risks.

    Corporate Exposure Shifts Across Asia

    Legal liabilities of this nature create direct financial exposure for multinational energy operators, industrial manufacturers, and their commercial insurers across Asia-Pacific. If courts accept proportional emissions modeling, corporate balance sheets will face recurring claims following major typhoons, floods, and coastal erosion events throughout Southeast Asia.

    Supply chain infrastructure and regional asset valuations face repricing as climate litigation expands beyond state authorities to private corporate targets. Commercial lenders and institutional investors in Asian energy assets must account for potential cross-jurisdictional tort liability in their long-term risk underwriting.

    Precedents Spread Across Emerging Markets

    Shell has rejected claims of covert liability, stating in December that the suggestion the company possessed unique knowledge about climate change was not true.

    Similar cross-border actions are underway across the region, including Indonesian islanders suing Swiss cement group Holcim over rising sea levels and Pakistani farmers pursuing litigation against industrial operators in German courts.

    London courts are scheduled to review procedural filings on the Philippine claims as plaintiffs prepare evidentiary submissions on corporate knowledge from past decades.

  • Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore Launches Plan Covering Children and Parents to Age 100

    Prudential Singapore has launched a whole-of-life protection plan that covers both a child and ageing parents under a single policy, as citizens aged 65 and above exceeded a fifth of Singapore’s population in 2026.

    The insurer introduced the policy amid demographic shifts projecting that more than one in four citizens will be aged 65 and above by 2035, increasing caregiving responsibilities across households.

    How the multi-generation coverage works

    Under the policy, titled PRUActive Family Care, the caregiver’s child serves as the primary life assured. That portion provides lifetime coverage against death, terminal illness, and total and permanent disability.

    Policyholders can attach critical illness riders covering 182 conditions. These riders extend protection across both juvenile illnesses and mental health conditions.

    Parents of the caregiver gain protection up to age 100 without medical underwriting. This component pays out on diagnosis of specific age-related conditions, including Alzheimer’s disease, dementia, Parkinson’s disease, and progressive supranuclear palsy.

    The shift in retail financial products

    Insurers across Southeast Asia are retooling standard life products to address changing household structures. Traditional life policies required separate contracts, multiple administrative fees, and full medical underwriting that routinely screened out elderly parents with pre-existing conditions.

    By eliminating underwriting on designated cognitive and neurological conditions for parents, Prudential shifts the commercial proposition from individual mortality protection to multi-generational risk pooling. For retail distribution networks and financial advisers, bundled policies raise client retention by binding family units to a single provider.

    Demographic pressures on consumer balance sheets

    Household economics are shifting rapidly in aging Asian financial hubs. Singapore’s official demographic forecasts project that more than one in four citizens will reach age 65 or older by 2035, accelerating the dependency ratio on working adults.

    Rising caregiving expenses place direct pressure on household discretionary spending and retirement savings. Financial institutions packaging eldercare contingencies with childhood coverage want to capture premium flows before standalone long-term care costs deplete family budgets.

    What to watch next

    Carriers across Singapore are competing for market share in aging-related protection, adjusting critical illness definitions and riders to match lengthening life expectancies. A key development to watch is whether Singapore’s citizen dependency ratio accelerates before the projected 2035 threshold of 25 percent.

  • AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    Medical costs across Southeast Asia will surge by up to 21 per cent in 2025, forcing insurers and healthcare operators to replace traditional fee-for-service billing models with bundled pricing and tighter network controls.

    Forecasts compiled by Mercer Marsh Benefits show medical trend rates hitting 21 per cent in the Philippines, 19 per cent in Indonesia, and 15 per cent in both Malaysia and Vietnam. These double-digit increases run well ahead of headline consumer price inflation across the region, putting immediate strain on corporate benefits budgets and personal household finances.

    Waste Drives a Quarter of Regional Healthcare Spending

    An estimated 25 per cent of all healthcare expenditure across Asian markets stems directly from administrative and clinical waste. This inefficiency includes unnecessary surgical interventions, prolonged hospital stays, inappropriate antibiotic prescriptions, and inadequate preventive screenings.

    Payor-provider alignment could help eliminate redundant treatment cycles by linking compensation to clinical outcomes rather than the volume of procedures billed. Under the traditional fee-for-service structure, private hospitals and clinics face financial incentives to run additional diagnostic tests and extend inpatient admissions regardless of clinical necessity.

    Addressing these inefficiencies requires insurers and medical providers to standardise diagnostic and clinical data at the line item level. Sharing harmonised laboratory results, procedure codes, and diagnostic files across private networks reduces duplicate testing and accelerates claims adjudication.

    Out-of-Pocket Spending Surges Across Key Markets

    Rising medical costs are shifting directly onto consumers across developed and emerging economies alike. World Health Organisation figures cited by AIA show personal out-of-pocket healthcare expenditure jumped 13 per cent in both Singapore and Australia between 2022 and 2023.

    Emerging markets saw similar spikes over the same twelve-month window. Patients in India and Indonesia experienced a 10 per cent increase in direct out-of-pocket spending, eroding discretionary consumer purchasing power as basic medical treatments absorb larger portions of family income.

    Price opacity in private hospital networks worsens the burden. Transparent fee schedules for standard procedures allow policyholders to compare facilities effectively while enabling insurers to steer patients toward cost-effective treatment pathways.

    Alternative Payment Models and Preferred Panels

    Insurers are pushing private healthcare operators toward alternative commercial agreements, including episode-based bundled payments and risk-adjusted provider networks. Bundled rates establish a single, fixed fee for an entire course of treatment, eliminating unexpected add-on charges for routine post-operative care.

    Payors are also constructing preferred provider panels using verified clinical outcome metrics. Facilities that demonstrate lower complication rates and strict adherence to treatment protocols receive higher patient volumes and predictable fee schedules in exchange for discounted service tariffs.

    This structured collaboration replaces transactional claims processing with multi-year commercial partnerships. Hospitals secure stable patient flows across competitive metropolitan markets, while insurers contain underlying claims volatility.

    Corporate Benefit Pressures in 2025

    Medical trend rates remaining in double digits across Southeast Asia present an operational challenge for corporate employers competing for talent. Companies face the choice of absorbing premium hikes, reducing policy coverage limits, or passing higher deductibles to staff.

    The pressure is acute in markets like the Philippines and Indonesia, where private medical insurance serves as a primary tool for corporate staff retention. Retail operators, commercial landlords, and regional service conglomerates operating across multiple Asian jurisdictions must renegotiate group policy structures to keep benefit plans solvent.

    Attention now turns to the rollout of standardised digital health records and published procedure tariffs across major private hospital operators in Malaysia, Vietnam, and Indonesia ahead of the 2025 contract renewal cycle.

  • Taiwan Non-Life Insurers Pivot to Commercial Lines as Market Expands to $19B

    Taiwan Non-Life Insurers Pivot to Commercial Lines as Market Expands to $19B

    Taiwan property and casualty premiums will reach $19 billion by 2036, expanding at an annual rate of 4.8 per cent as non-life business outpaces the mature life sector.

    Health insurance premiums will match that pace with 4.8 per cent annual growth to $25.1 billion, while life premiums expand at a slower 4.3 per cent clip from $65.1 billion in 2025 to $103.5 billion, according to data from Allianz Research.

    Manufacturing and Energy Drive Commercial Demand

    Commercial lines are absorbing capital from high-technology factory construction, offshore wind projects, and state-backed infrastructure upgrades. AM Best noted in a September sector review that consistent premium expansion across retail and commercial lines will support earnings, provided carriers maintain underwriting discipline.

    Motor insurance still generates the bulk of non-life revenue on the island. Premium growth in the category slowed through early 2026 as buyers postponed vehicle purchases during debates over import tariff adjustments.

    In commercial lines, growth could increasingly come from moving beyond traditional risk transfer toward more holistic solutions combining risk assessment, loss prevention, and insurance coverage.

    Regulatory Shifts Boost Reported Capital

    Underwriting profits also benefited from calm weather patterns across 2025 and the first half of 2026, which kept natural catastrophe payouts low. At the same time, carriers completed major balance sheet realignments under new capital and accounting frameworks.

    The adoption of IFRS 17 lifted sector-wide shareholders’ equity by approximately 10 per cent at the end of 2025 compared with older accounting metrics. The local Taiwan Insurance Solvency standard increased the weighting of market risk in required reserves without reducing overall capital buffers.

    For institutional investors and bank-backed financial holding groups in Taipei, the shift in premium momentum creates an operational problem. Life units long provided massive investment floats, but slower volume means management teams must extract higher fee income and tighter loss ratios from general insurance operations.

    Rival domestic insurers are targeting mid-sized commercial clients rather than relying exclusively on large electronics fabricators. Writing modular liability, business interruption, and property coverage for suppliers reduces balance sheet concentration while defending margins against commoditised pricing.

    Pressure Mounts on Underwriting Margins

    The regulatory transition began years earlier as Taiwan’s Insurance Bureau aligned domestic solvency calculations with international standards to prepare carriers for equity market volatility. Insurers spent that period building capital reserves and trimming exposure to high-guarantee savings products.

    Underwriting teams now face the next hurdle: pricing commercial property contracts accurately as extreme climate events become less predictable across East Asia. The next round of statutory solvency filings will show whether smaller non-life carriers can maintain target capital ratios without raising rates on corporate accounts.

  • Allianz Singapore Secures Three Awards for Consumer Insurance Offerings

    Allianz Singapore Secures Three Awards for Consumer Insurance Offerings

    Allianz Insurance Singapore has earned three awards at the Asia Consumer Insurance Awards 2026. The recognition reflects the company’s focus on creating insurance solutions designed to protect Singaporeans from new and changing risks.

    The company received awards for its health and wellness offerings, its critical illness solutions, and its advancements in digital transformation within the insurance sector. These accolades collectively underscore Allianz’s efforts in adapting its product portfolio and service delivery to meet contemporary consumer needs in Singapore.

    Recognizing Industry Leadership

    The awards included ‘Health Insurance Product of the Year’ for Allianz’s health and wellness propositions. Its comprehensive critical illness coverage was named ‘Critical Illness Product of the Year’. Also, the insurer received the ‘Digital Transformation Initiative of the Year’ award, acknowledging its progress in integrating technology to enhance customer experience and operational efficiency.

    These wins indicate a strong market position and product relevance in Singapore’s competitive insurance landscape. The focus on health, critical illness, and digital services aligns with broader industry trends where consumers increasingly seek robust protection and convenient digital interactions. This trend is visible across Asia-Pacific as insurers and financial service providers invest in digital platforms to reach a wider customer base and streamline processes.

    Commitment To Evolving Risks

    The company stated that these awards validate its strategy to address the dynamic risk environment faced by consumers in Singapore. This involves continuous product development and the adoption of new technologies to deliver accessible and effective insurance solutions. The recognition particularly highlights the importance of anticipating future challenges, such as new health threats or economic uncertainties, and building products that offer relevant coverage.

  • HSBC’s $2B Singapore Insurance Unit Sale to Allianz: A Strategic Boost for Both Giants

    HSBC’s $2B Singapore Insurance Unit Sale to Allianz: A Strategic Boost for Both Giants

    HSBC has announced that it will sell its life and health insurance division in Singapore to Germany’s Allianz. The deal, which values the unit at SGD2.7 billion (US$2.09 billion), is expected to produce a pre-tax gain of US$1.8 billion for HSBC and potentially enhance the HSBC Group’s common equity tier 1 ratio by up to 15 basis points.

    Simplifying Operations and Boosting Capital Returns

    This sale signifies another move in HSBC CEO Georges Elhedery’s strategy to streamline operations at Europe’s largest bank and reinvest capital into sectors and markets that promise better yields. Simultaneously, he aims to maintain Singapore’s position as a vital hub for wealth and wholesale banking.

    The deal presents Allianz with a unique chance to expand in Singapore, a wealthy, strictly regulated market where distribution networks and bank-insurance partnerships carry high value. Anusha Thavarajah, Allianz’s Asia Pacific Regional CEO, states that the transaction underscores her company’s confidence in Singapore and recognizes HSBC Life Singapore’s fast-growing business, local expertise, and solid reputation among customers and partners.

    The planned divestment, set to occur in early 2027, will lead HSBC to enter a 15-year bank-insurance distribution agreement with Allianz. This agreement involves selling insurance products in Singapore, supported by an upfront payment of SGD200 million.

    Expanding Insurance Business

    The deal arrives in the wake of HSBC’s broader expansion in the insurance sector. Despite the bank’s ongoing effort to reshape its global footprint and focus on core Asian wealth and corporate banking markets, insurance income has seen a 16% year-on-year rise in the first quarter. This trend has contributed to an 18% boost in quarterly wealth revenue.

    Past investment interests include HSBC Holdings’ acquisition of French insurer Axa’s Singapore assets for US$529 million in 2022. However, the bank is also known for trimming smaller or less scalable retail and insurance operations in parts of Asia, while fiercely vying for affluent clients in the region.

    This sale follows Singapore’s Overseas-Chinese Banking Corp’s announcement in May of its Indonesian unit’s acquisition of certain HSBC wealth and premier banking portfolio assets and liabilities. HSBC is currently also reviewing its retail operations in Turkey, Australia, and Egypt.

    Questions & Answers

    What is the value of the deal between HSBC and Allianz?
    The deal values HSBC’s Singapore life and health insurance unit at SGD2.7 billion (US$2.09 billion).

    What will be HSBC’s strategy after the planned divestment in 2027?
    HSBC plans to enter into a 15-year bancassurance distribution agreement with Allianz to sell insurance products in Singapore.

    What has been the trend in HSBC’s insurance income?
    HSBC’s insurance income has seen a 16% year-on-year rise in the first quarter.

  • Citigroup Bolsters Global Insurance and Specialty Finance Teams with High-Profile Appointments

    Citigroup Bolsters Global Insurance and Specialty Finance Teams with High-Profile Appointments

    Citigroup has announced the appointment of two seasoned bankers to senior roles within its Financial Institutions Investment Banking division. This move forms part of the bank’s strategic initiative to bolster its global insurance and specialty finance advisory services.

    Jonathan Alpert has been designated as the new Global Head of Insurance, effective from September. Alpert boasts an impressive career spanning over 28 years in both the insurance industry and investment banking. His most recent role was as Co-Head of Global Insurance at Bank of America. Alpert will leverage his rich experience and extensive network within the global insurance sector to drive Citi’s growth in this arena.

    Operating from New York, Alpert will team up with Brian Malbacho, Citi’s North America Head of Insurance. Together, they will focus on expanding the bank’s global insurance franchise. Citi expressed confidence in Alpert’s capabilities, noting his record of advising on significant international insurance transactions and his enduring relationships with eminent global insurance groups.

    In a simultaneous appointment, Ryan Willingham will assume the role of Managing Director covering Specialty Finance, come August. He, too, is transitioning from Bank of America where he previously headed the specialty finance sector within the bank’s Financial Institutions group.

    Willingham’s nearly 20-year career has been dedicated to advising a variety of specialty finance firms, including mortgage originators and servicers, mortgage REITs, and government-sponsored enterprises.

    These strategic appointments come at a time when deal activity within the insurance sector is on the rise, particularly in the Asia-Pacific region. Insurers in the area are actively pursuing capital-raising and merger-and-acquisition opportunities. As Global Head of Insurance, Alpert will be instrumental in supporting Citi’s growth ambitions with leading insurers in this dynamic region.

    Questions & Answers

    Who has Citigroup appointed to its Financial Institutions Investment Banking division?
    Citigroup has announced the appointment of Jonathan Alpert as Global Head of Insurance and Ryan Willingham as Managing Director covering Specialty Finance.

    What experience does Jonathan Alpert bring to his new role at Citigroup?
    Jonathan Alpert brings over 28 years of experience in the insurance industry and investment banking. His most recent role was Co-Head of Global Insurance at Bank of America.

    What is the significance of these appointments for Citigroup?
    These appointments come at a time of increased deal activity in the insurance sector, particularly in the Asia-Pacific region. Alpert, as Global Head of Insurance, will play a pivotal role in supporting Citigroup’s growth with leading insurers in this region.

  • Great Eastern Unveils Exclusive High Net Worth Services: Tailored Insurance and Elite Lifestyle Perks

    Great Eastern Unveils Exclusive High Net Worth Services: Tailored Insurance and Elite Lifestyle Perks

    Great Eastern, the insurance division of OCBC, has introduced a new service tailored specifically for high net worth (HNW) individuals and families across Asia.

    Great Eastern Private: A Tailored Experience

    The newly unveiled proposition is named Great Eastern Private. This service aims to bring together custom-designed HNW insurance solutions with a curated panel of expert advice and services spanning seven spheres. These domains encompass next-generation leadership, family advisory and trust services, health and longevity, international tax advisory, legal advisory, philanthropy, and global lifestyle concierge.

    In collaboration with Singapore Management University Executive Development, Great Eastern will conduct a cross-generational family program. This initiative will provide a platform for founders and family members to delve into topics like values, enterprise continuity, leadership transition, and long-term legacy.

    The Hewton Fair Suite: An Exclusive Offering

    Great Eastern is also offering HNW clients access to an exclusive area dubbed the Hewton Fair Suite, a nod to the company’s founder Alfred Hewton Fair. This premium space will feature on-site medical services in collaboration with Raffles Medical Group.

    CEO of Great Eastern, Greg Hingston, commented on the new proposition. He noted that as clients successfully amass wealth, the focus is now shifting to the careful and effective preservation and transfer of wealth. Great Eastern Private, he said, is a strategic move to invest in capabilities and services that meet this evolving customer need. He also affirmed the company’s commitment to remain the trusted insurance partner of customers throughout all life stages and generations.

    Questions & Answers

    What is the Great Eastern Private proposition?
    Great Eastern Private is a new service introduced by Great Eastern, the insurance arm of OCBC, designed specifically for high net worth individuals and families. It offers tailored insurance solutions and curated expert services across various domains.

    What are some of the services offered as part of Great Eastern Private?
    Services offered under Great Eastern Private encompass next-generation leadership, family advisory and trust services, health and longevity, international tax advisory, legal advisory, philanthropy, and global lifestyle concierge.

    What is the Hewton Fair Suite?
    The Hewton Fair Suite is an exclusive area offered to high net worth clients utilizing the Great Eastern Private service. It includes on-site medical services provided in partnership with Raffles Medical Group.

  • Manulife Ignites Responsible AI Revolution: Launches Cutting-edge Center in Singapore to Boost Insurance Efficienc

    Manulife Ignites Responsible AI Revolution: Launches Cutting-edge Center in Singapore to Boost Insurance Efficienc

    Manulife, the multinational insurance corporation, recently launched its Artificial Intelligence (AI) Center of Excellence in Singapore. This move is part of the company’s strategic plan to leverage cutting-edge technologies to streamline its operations and enhance customer experience.

    The insurance giant plans to utilize AI to expedite insurance processes while improving personalized advice and customer engagement, according to an announcement made last Friday.

    According to CEO Benoit Meslet, AI plays an instrumental role in delivering better, faster, and more personalized services to customers. He highlighted the importance of technology in strengthening trustworthy human relationships in the business.

    AI Integration in Various Insurance Processes

    Manulife’s development strategy places a focus on underwriting, distribution, operations, and customer engagement. The development is guided by principles of transparency and security. This approach signifies the company’s commitment to build unique customer service delivery and cost efficiency while preparing its workforce for the future.

    Singapore’s vibrant innovation ecosystem, robust digital infrastructure, and regulated AI governance framework provide the perfect base for experimentation and talent development. Manulife plans to increase its AI-specific workforce over the next three years, with new hires focusing on data science, AI governance, and engineering.

    Expanding Best Practices in the Regional Insurance Market

    Manulife is participating in the Monetary Authority of Singapore’s Pathfinder Programme, among other research partnerships. The company is committed to helping establish industry-wide standards for responsible AI use.

    Chief AI Officer for Manulife Asia, Mark Czajkowski, emphasized that “responsible innovation, governance, and impact” are at the core of the company’s strategy.

    Emphasizing the Role of Technology in Value Creation

    By incorporating advanced analytics and automation into its core operations, Manulife aims to increase productivity and offer more intuitive financial protection solutions. This step highlights a broader industry shift where investing in AI has become a crucial factor for competitive growth.

    Questions & Answers

    What is the primary aim of Manulife’s AI Center of Excellence in Singapore?
    The primary aim is to leverage AI technology to streamline operations and enhance personalized customer service.

    What are the focus areas of Manulife’s AI development strategy?
    The focus areas are underwriting, distribution, operations, and customer engagement.

    What is Manulife’s stance on AI governance?
    Manulife emphasizes the importance of responsible innovation, governance, and positive impact in its AI strategy.

  • Cyber Insurance Market Surges 7% to Reach $15 Billion by 2024: What’s Driving This Growth?

    Cyber Insurance Market Surges 7% to Reach $15 Billion by 2024: What’s Driving This Growth?

    The global cyber insurance market is displaying a mixed bag of results in 2024, achieving a 7% growth to nearly $15 billion in premiums. However, this upward trajectory comes with a caveat: the momentum has decelerated for a second consecutive year, according to a recent analysis by Moody’s Ratings.

    Regional Disparities in Growth

    Interestingly, while growth thrives in regions outside the United States, the American sector is seeing a decline, with premiums dropping 1.5% to $7.1 billion, following a slight dip of 0.7% in 2023. Despite these challenges, the sector has maintained its profitability, demonstrating combined ratios of 79% for primary cyber coverage and 84% for excess coverage.

    Ransomware: The Persistent Threat

    Ransomware attacks continue to dominate the claims landscape, although the total ransom payments slipped by 35% last year to a still-staggering $814 million. Such a significant drop raises eyebrows: are cybercriminals still plotting, or is the market growing more resilient?

    Competitive Landscape Pushes Rates Down

    The rising competition within the sector has led to a reduction in prices. Marsh’s data reveals that U.S. cyber insurance rates fell by 7% during the first half of 2025, while the UK experienced a sharp decline of nearly 19%. In response to this dynamic environment, some insurers are pivoting their strategies, transitioning from quota share to excess-of-loss reinsurance, and exploring innovative options such as catastrophe bonds and industry loss warranties to mitigate systemic risks.

    The Future: Potential Beckons

    Moody’s highlights that while penetration among large corporations remains strong, only about 10% of small and medium-sized enterprises (SMEs) are investing in cyber coverage. This suggests a vast pool of untapped potential that could contribute to future growth. Indeed, Allianz’s 2025 Risk Barometer ranks cyber incidents as the top global risk for the fourth year running, signaling that the appetite for cyber insurance could increase as awareness grows.

    Questions & Answers

    Which regions are driving growth in the cyber insurance market?
    Growth is particularly strong in non-US regions, while the US is experiencing a downturn in premium volumes.

    What is contributing to the decrease in ransom payments?
    The total ransom payments fell by 35% last year to $814 million, indicating a possible shift in the strategies employed by cybercriminals or improvements in defenses.

    What does the future hold for the cyber insurance sector?
    Long-term growth prospects remain robust, especially with only 10% of SMEs currently covered, suggesting significant room for expansion as cyber threats continue to evolve.

  • Asia-Pacific Aviation Insurance Set to Soar with Projected 8.7% Growth by 2032

    Asia-Pacific Aviation Insurance Set to Soar with Projected 8.7% Growth by 2032

    In the rapidly evolving landscape of the aviation insurance market, the Asia-Pacific region is set to take flight with remarkable momentum. The market is projected to expand at an impressive compound annual growth rate (CAGR) of 8.7% from 2022 to 2032, spurred by robust industrial growth and increasing aviation activities in powerhouse nations such as China and India. Such figures are a clear signal of the sector’s dynamic potential as it approaches a valuation of $7.1 billion globally by 2032, up from $4.1 billion in 2022.

    Passenger Liability Insurance: A Market Leader

    In 2022, passenger liability insurance took the lead, generating over one-third of the total revenue in the aviation insurance landscape. This surge is largely driven by regulatory mandates that necessitate coverage for damages related to passengers. When you think about it, it’s as if aviation laws are playing a critical role in ensuring that safety always comes first — because no one wants to be left high and dry!

    Rising In-flight Insurance Demand

    The in-flight insurance segment is emerging as a significant player, expected to witness the highest CAGR of 8.6% through 2032. This growth is influenced by a rising tide of accident risks linked to factors like unpredictable weather and mechanical failures, compelling airlines to fortify their insurance frameworks.

    Airlines Segment Dominates But Aerospace Is Soaring

    Breaking down the market by product type, the airlines segment held a commanding share in 2022, as demand grows for insurance solutions that are custom-made to address airline-specific risks. However, the aerospace segment is poised for the most rapid advancement, enjoying a projected CAGR of 9.0%. Insurers are increasingly adopting advanced technologies to evaluate and price the more intricate risks associated with aerospace, setting the stage for a transformation in how these complexities are managed.

    Commercial Aviation: Still the Heavyweight Champion

    On the application front, commercial aviation insurance remains the heavyweight champion, accounting for over half of the market in 2022 due to the substantial values and liability limits involved. Yet, the general and business aviation segment is not to be overlooked; it is anticipated to experience the fastest growth at 8.0%, spurred by heightened travel demand and increased activities such as skydiving.

    Questions & Answers

    What factors are driving the growth of the aviation insurance market in the Asia-Pacific region?
    The growth is primarily driven by industrial expansion and an uptick in aviation activities, particularly in China and India.

    Which segment of aviation insurance generated the most revenue in 2022?
    Passenger liability insurance led the market, accounting for over one-third of the total revenue, largely due to regulatory requirements for coverage.

    What technologies are influencing the aerospace insurance segment?
    Insurers are leveraging advanced technologies to better assess and price the complex risks associated with aerospace, leading to accelerated growth in this segment.

  • Asia’s Construction Insurance Market Set for Robust Growth in 2024!

    Asia’s Construction Insurance Market Set for Robust Growth in 2024!

    Insurers in the construction sector across Asia are gearing up for a robust year in 2024, as highlighted in Aon’s 2025 Global Construction Insurance and Surety Market Report. The report underscores a growth-oriented atmosphere buoyed by enhanced reinsurance treaty performance, a strong underwriting appetite, and ample capacity.

    Long-Term Stability and Profitability

    While the momentum is palpable, insurers are also focused on achieving long-term profitability and stability, which is fostering greater underwriting discipline, even as some markets soften. A delicate balance of risk and reward is becoming the sweet spot for companies navigating these waters.

    Favorable Conditions in Key Markets

    China, Hong Kong, and India stand out as the beacons of favorable insurance market conditions. These regions have witnessed impressive growth, particularly India, where local and foreign insurers have rallied behind infrastructure expansion efforts. In China, insurers are offering modest premium reductions for low-risk profiles, with reinsurers showing an increased appetite for catastrophe exposures—a vital trend given the region’s vulnerability to natural disasters.

    Challenges in Japan

    Conversely, Japan is undergoing a modest hardening cycle, where regulatory scrutiny has prompted insurers to adopt more conservative strategies, impacting the management of large and complex risks.

    Mixed Signals in Southeast Asia

    In Southeast Asia, markets in Singapore, Thailand, and Malaysia are witnessing moderate conditions, while Australia boasts a surge in construction activity across real estate and infrastructure sectors. The post-pandemic boom in residential development has shifted insurer priorities, sparking a rising demand for latent defects insurance and internal water damage protections. Detailed water management plans and strong contractor risk mitigation strategies are proving essential to securing favorable terms.

    Competition in Real Estate

    The real estate sector remains fiercely competitive with robust local insurer capacity. However, ambitious civil engineering projects, especially those involving underground works or exposure to natural catastrophes, are still testing insurer capacity and pricing structures. These complex and high-risk projects often necessitate international market support or unique risk transfer solutions.

    Emerging Trends in Technology-Driven Construction

    The rise of technology-driven construction—think data centers, battery plants, and semiconductor factories—is emerging as a vibrant growth area. Australia, in particular, is seeing insurers respond enthusiastically to defense-related infrastructure projects, propelled by increasing government investment projected through 2029. While the market remains rich in capacity and competitive for preferred risk types, insurers are proceeding with caution concerning catastrophe risks. Therefore, larger, more intricate projects might require tailored insurance structures like excess-of-loss (XOL) or alternative risk transfer (ART) solutions to adequately address coverage needs. If all else fails, you may need to put on a superhero cape to navigate these complexities!

    Questions & Answers

    What is driving growth in the construction insurance market across Asia in 2024? The growth is fueled by improved reinsurance treaty performance, strong underwriting appetite, and ample capacity within the market.

    Which countries are experiencing the most favorable insurance market conditions? China, Hong Kong, and India have reported sustainable growth, with India showing significant support for infrastructure expansion from both local and foreign insurers.

    How are insurers responding to large-scale civil engineering projects? Insurers are increasingly cautious about these projects, which often necessitate bespoke insurance structures to meet coverage requirements, especially due to the heightened risks associated with natural disasters.

  • India’s Life Insurers Showcase Solid Growth in May Amidst Declining Policy Volumes

    India’s Life Insurers Showcase Solid Growth in May Amidst Declining Policy Volumes

    India’s life insurance industry is experiencing quite the twist, as it reported a year-on-year premium growth of 12.7% in May, bringing the total premiums to a substantial Rs30,463.2 crore. This surge is a welcome improvement from April’s 8.4% growth, although it falls below the impressive 15.1% growth seen in May 2024, largely influenced by the revised surrender value regulations introduced in October 2024.

    Policy Sales Take a Dip

    However, in an unexpected turn of events, the number of life insurance policies sold plummeted by 10.4% during the month. The segment of individual non-single policies suffered a particularly steep decline of 10.5%, totaling at 16.7 lakh. While these figures may sound ominous, private insurers managed to thrive in the individual non-single premiums category. In contrast, the Life Insurance Corporation of India (LIC) faced a 7.8% decrease in this sector. Evidently, private players are enjoying a sweet spot, propelled by a growing preference for higher-value policies.

    Annual Premium Equivalent Sees Impressive Growth

    Amidst this backdrop, the Annual Premium Equivalent (APE) showcased a remarkable uptick of 14.4% in May, compared to a 12.0% rise in May 2024. Over the period from May 2023 to May 2025, the industry’s APE has grown at a steady 13.2% compound annual growth rate (CAGR), with private insurers outpacing LIC at 13.8% versus LIC’s 12.4%. On the other hand, the growth of Unit Linked Insurance Plans (ULIPs) remains subdued, primarily due to market volatility, while group business has become the standout performer this May.

    A Bright Future Ahead

    Looking ahead, industry analysts predict that insurers will intensify their focus on agency channels, especially as banks increasingly prioritize deposit mobilization. Upcoming regulatory changes, such as the proposed Insurance Amendment Act and the Bima Trinity initiatives, are seen as catalysts for market expansion. CareEdge Ratings optimistically forecasts the industry could achieve an annual growth rate of 10% to 12% over the next three to five years, buoyed by innovations in product offerings and enhanced distribution strategies. And who knows? With such promising growth, life insurers might soon find themselves in a healthy competition for policyholder affection!

    Questions & Answers

    What was the growth percentage of life insurance premiums in May? The life insurance industry experienced a growth of 12.7% in May, reaching a total of Rs30,463.2 crore.

    How did private insurers perform compared to LIC? Private insurers saw growth in individual non-single premiums, while LIC recorded a 7.8% decline in this segment.

    What future growth is projected for the life insurance industry? CareEdge Ratings projects a yearly growth rate of 10% to 12% for the industry over the next three to five years, largely driven by private sector expansion and product innovation.

  • Asia’s Insurance Markets Surge in 2024 Driven by Life and Health Sector Growth

    Asia’s Insurance Markets Surge in 2024 Driven by Life and Health Sector Growth

    Asia’s insurance markets showed impressive growth in 2024, especially in the life and health sectors, yet they continue to trail behind North America and Western Europe in overall scale and performance—particularly within the property and casualty (P&C) arena. Globally, the insurance industry expanded by a robust 8.6%, reaching a staggering $7.87 trillion (EUR 7.0 trillion) in total premiums.

    China: The Star of Life Insurance Recovery

    China emerged as a powerhouse in Asia’s life insurance sectors, boasting a remarkable growth rate of 15.4%. This trend outshines the 7.1% increase seen in Western Europe and propelled the global life segment’s overall growth to 10.4%. Driving this surge were higher interest rates, which effectively bolstered premium incomes across markets.

    Health Insurance Booms Amidst Low Penetration

    The demand for health insurance in Asia also proved strong, with premiums soaring by 12.6% in 2024. Low penetration rates—below 1% in most nations except Taiwan—and limited public healthcare coverage contribute to this upward trajectory. Meanwhile, the US holds its ground by dominating the global health insurance market, accounting for approximately two-thirds of worldwide premiums.

    Challenges in Property and Casualty Insurance

    While Asia’s life and health sectors exhibit clear growth potential, the sluggish development of P&C insurance restricts the region’s overall impact on global premium expansion. The term “growth markets” is increasingly put to the test as North America surpasses Asia in key sectors, despite having a smaller population.

    Future Outlook: A Double-Edged Sword

    Looking ahead, economic challenges may pose risks to the regional outlook. Diverging inflation trends and capital market volatility are likely to affect insurer portfolios and strategic planning throughout Asia. As global insurance growth continues to rise, Asia must seize the opportunity to enhance penetration and strengthen its P&C performance to keep pace with its more developed counterparts. Who knows, perhaps the region will surprise us all and redefine what “growth market” truly means!

    Questions & Answers

    What contributed to China’s impressive life insurance growth?
    Higher interest rates bolstered premium income, leading to a remarkable growth rate of 15.4%.

    How does Asia’s health insurance market compare to that of the US?
    Asia’s health insurance premiums rose by 12.6%, but the US dominates globally, accounting for around two-thirds of total premiums.

    What challenges does Asia face in the property and casualty insurance sector?
    Slower development in P&C insurance constrains Asia’s overall contribution to global premium growth, despite significant advancements in life and health segments.