Tag: Shanghai

  • IKEA, A.O. Smith and Moen Reshape China Footprints as Direct Retail Retreats

    IKEA, A.O. Smith and Moen Reshape China Footprints as Direct Retail Retreats

    IKEA China, water-heating brand A.O. Smith, and Fortune Brands, the parent company of Moen, have carried out sweeping operational shifts across China in 2026. IKEA announced in January that it would close seven shopping malls to focus on urban small formats, A.O. Smith agreed in late October to transfer an 81 per cent controlling stake in its local business, and Moen confirmed in early November that it will exit regional commercial operations.

    The moves dismantle traditional consumer-facing retail setups across three distinct home improvement sectors. A.O. Smith’s transaction with private equity firm CPE Yuanfeng carries a 400 million US dollar valuation, while Moen’s parent Fortune Brands is winding down local commercial sales desks through 2027.

    Multinational suppliers are moving away from capital-heavy suburban flagships and company-run showrooms to curb direct commercial overhead. Operators are shifting toward neighborhood boutique stores, long-term brand licensing, or converting mainland production sites entirely into export back offices.

    IKEA Shrinks Store Formats and Accelerates Digital Pilots

    IKEA dismantled part of its traditional suburban destination model in January 2026, closing large retail properties including sites in Baoshan, Shanghai and Panyu, Guangzhou. The Swedish furniture group is replacing them with urban small-format stores ranging between 1,500 and 4,000 square meters.

    The company opened four small-format outlets during the 2026 fiscal year in Dongguan, Changying, Changping, and Tongzhou in Beijing. These downsized urban formats generated roughly 7 million visits, while IKEA’s digital sales reached 29.7 per cent of total China revenue in fiscal 2026.

    Online expansion has supported the network reduction. IKEA established flagship digital channels on Tmall in 2020, opened an official storefront on JD.com in August 2025, and tested an instant retail delivery network through JD.com across nine cities in January 2026. Subsequent rollouts included a Taobao flash shopping trial in July 2026 and a live-commerce storefront on Douyin in October 2026, paired with its proprietary website and WeChat mini-programs.

    Fortune Brands Cuts Asian Sales to Feed North American Supply

    Fortune Brands confirmed an internal directive in early November 2026 to shutter local commercial selling operations for its Moen plumbing and fittings brand across Asia. The group will terminate most of its Asian regional sales and marketing jobs by the end of the second quarter of 2027.

    Remaining commercial cuts will finish by the end of 2027. The brand owner will not close its regional industrial base, choosing instead to retain its manufacturing and logistics facility in Changshu, its research and development centre in Guangzhou, and its regional procurement divisions.

    Those operational assets will shift exclusively to supplying products for Moen’s core North American market. Fortune Brands reported group sales of 1.1137 billion US dollars during the third quarter of 2026, down 3.1 per cent year-on-year, or 2.4 per cent lower when stripping out the Chinese market, prompting headquarters to eliminate low-margin Asian retail overhead.

    A.O. Smith Converts Direct Sales to Private Equity Licensing

    Water-heating and appliance manufacturer A.O. Smith took a separate path to strip out operating risk, agreeing on October 27 to sell 81 per cent of its China business to private equity firm CPE Yuanfeng for 400 million US dollars. Including the net present value of long-term brand licensing, the total valuation tops 500 million US dollars.

    Headquarters retreated after successive sales contractions. Revenue from A.O. Smith’s China operations slid 12.9 per cent year-on-year in 2025 to 690 million US dollars, dropping its contribution to total group turnover down to 18 per cent. Local-currency sales in the Chinese market fell a further 17 per cent in the third quarter of 2026.

    The Shift to Refurbishment and Maintenance Operations

    The simultaneous retreats expose how the end of China’s residential construction boom broke the economics of traditional home retail. Suburban big-box stores and company-owned showroom networks relied on new homeowners buying complete packages of plumbing, water heaters and flat-pack furniture. Today, residential property demand centers on partial renovations, product replacements and aging apartment upgrades.

    Operating single large suburban warehouses carrying high floor-space lease costs makes little financial sense when consumer visits skew toward replacement parts and minor cosmetic changes. Running direct dealership tiers also leaves multinational headquarters exposed to regional receivables and inventory burdens that local buyout funds can manage more aggressively.

    Earlier earnings from global home appliance and fixture suppliers showed steady margin compression in mainland retail channels as domestic competitors captured entry-level and mid-tier renovation budgets. That margin erosion pushed boards to choose between funding complex store overhauls or transferring direct retail execution to domestic distributors.

    The next phase of the transition rests on network execution. IKEA plans to open more than 10 additional small-format urban stores across Beijing and Shenzhen over the next two years, while A.O. Smith and CPE Yuanfeng must resolve distributor terms ahead of their planned mid-2027 closing date.
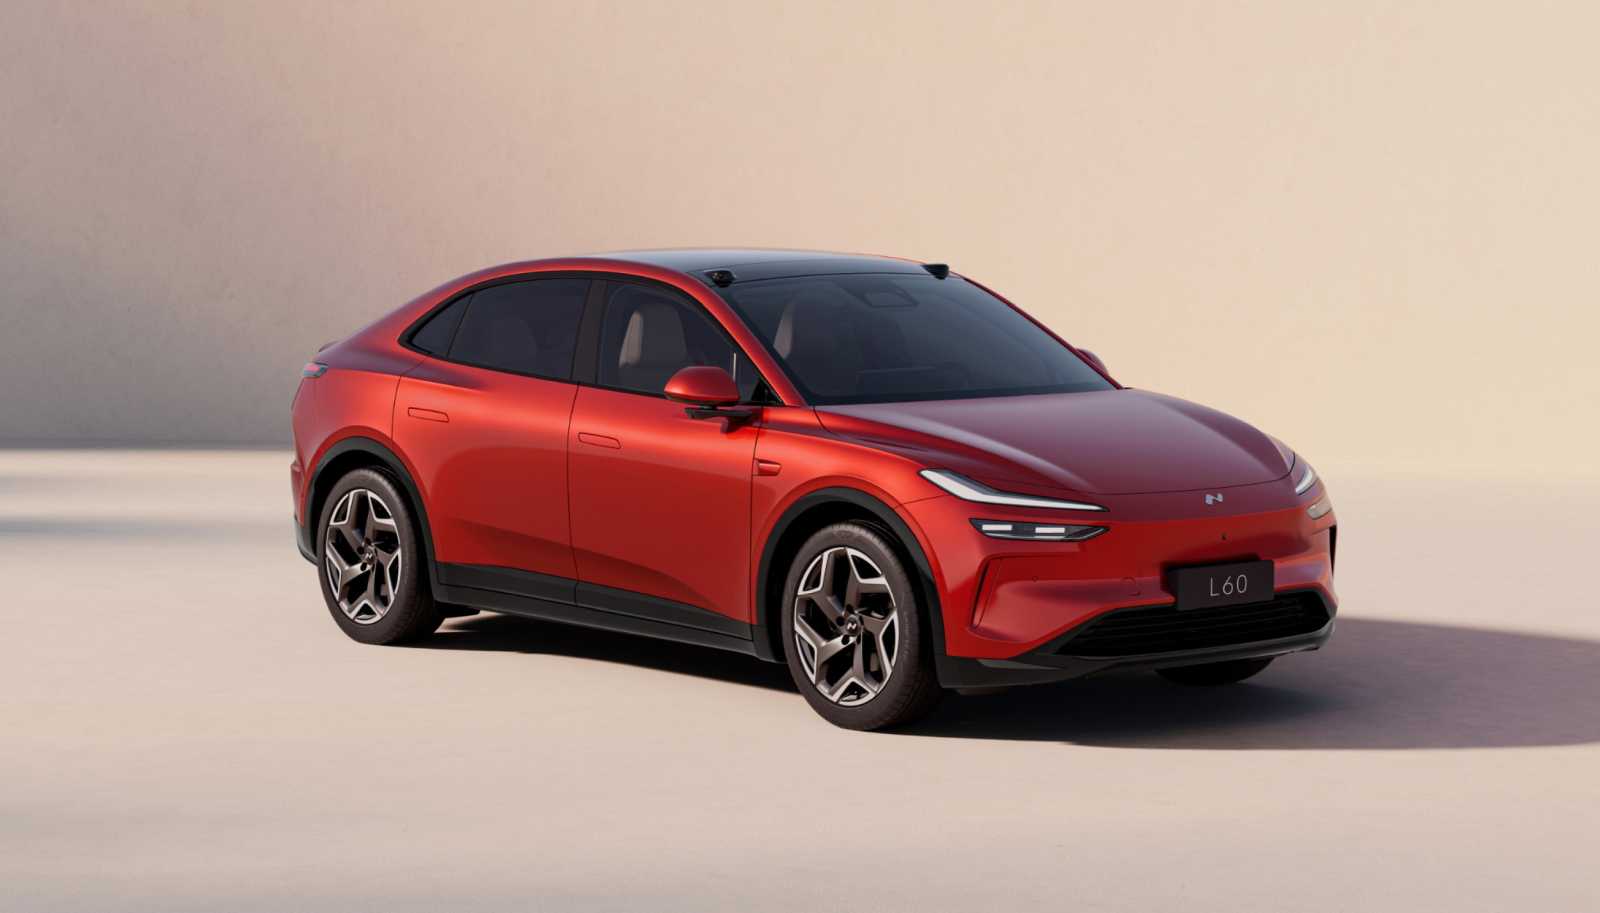
  • Nio Power Signs Poly Property to Expand EV Battery Swap Network

    Nio Power Signs Poly Property to Expand EV Battery Swap Network

    Nio Power partnered with state-backed developer Poly Property Group on November 11 to install electric vehicle battery swap stations and charging points across commercial and residential developments in China.

    The agreement gives the carmaker access to prime real estate footprint, building on a network that already counts 4,252 swap stations and 5,584 charging stations nationwide.

    Signed in Shanghai by executives including Nio chief financial officer and Nio Power head Stanley Qu, the partnership targets existing and pipeline developments. The installations will focus on residential communities, commercial office complexes and industrial parks in major Chinese urban centres. Neither company disclosed the initial capital outlay or the exact station count.

    Inside the Property Agreement

    Beyond concrete foundations and swap bays, the contract links station operations with retail foot traffic. The two groups agreed to coordinate vehicle sales, showroom locations, user services and operational data management. Energy balancing forms the second tier of the arrangement, combining rooftop solar installations, localized battery storage and vehicle-to-grid power distribution across Poly Property communities.

    Poly Property operates as a primary real estate vehicle for China Poly Group. Its holdings span commercial plazas and high-density apartment blocks across multiple Chinese cities, offering Nio pre-cleared land access in zones where retrofitting heavy electrical infrastructure normally faces strict local property board approvals.

    Landlord Strategy and Infrastructure Costs

    For commercial landlords, bringing power swap hardware on site changes consumer dwell time, shifting footfall toward brief convenience purchases rather than long restaurant visits.

    Competitors across China continue to rely on open-access fast-charging partnerships or third-party depot operators. Nio has chosen a heavier route, shouldering the capital footprint of dedicated swap infrastructure to control the ownership experience. Securing state-owned landlord relationships reduces the real estate acquisition friction that slows down rival private charging rollouts.

    Scaling the Battery Network

    External partnerships have become the standard mechanism for Nio Power to spread execution costs. The unit has assembled ties with more than 40 regional partners, including provincial state-owned investment platforms, jointly delivering over 900 battery swap stations across 25 provinces and municipalities.

    Cumulative spending on charging and battery swapping technology and sites has passed 20 billion yuan ($2.98 billion). The system handled its 130 millionth swap on November 3, taking 88 days to run from 120 million to 130 million while processing more than 110,000 swaps each day.

    Hardware upgrades rolled out ahead of the developer pact. In August, Nio activated its first fifth-generation battery swap stations across seven cities, introducing compatibility for its mass-market Firefly brand alongside Nio and Onvo vehicles. Attention now turns to the first batch of operational Poly Property sites, where station commissioning dates will show how rapidly residential utility connections can be cleared.

  • Singles’ Day Spending Lifts Asia-Pacific Merchant Volume 16 per Cent

    Singles’ Day Spending Lifts Asia-Pacific Merchant Volume 16 per Cent

    Online spend across Asia-Pacific merchants climbed 16 per cent above daily averages during Singles’ Day 2025, driven by department stores and apparel sales. The spike measured transaction processing volumes on 11 November compared to daily averages over the previous seven days.

    Department store processing volumes across the region surged 70 per cent during the period, while general retail expanded roughly 20 per cent and clothing transactions gained 16 per cent. Combined volume across those three segments rose nearly 25 per cent in Asia-Pacific, outpacing the 4 per cent increase recorded for identical retail categories in markets outside the region.

    Department Stores Drive Regional Gains

    Payment flows processed by Checkout.com demonstrate that retail drove the concentrated activity across Asian seller accounts rather than services or digital subscriptions. The data tracks seller settlement regions, isolating domestic and cross-border merchant accounts established within APAC territories.

    Clothing retailers operating in the region saw steady gains, matching the wider 16 per cent baseline uplift. The figures show spending stayed focused on physical goods categories, reversing soft pre-holiday volumes reported earlier in November across regional merchant accounts.

    European Spillover Widens Promotional Reach

    The China-born shopping event generated secondary transaction gains for sellers outside its primary Asian heartland. British merchants recorded a 31 per cent gain in general retail, a 23 per cent rise in clothing, and a 37 per cent jump in food and drink spend compared with the prior Tuesday.

    Central and Eastern Europe emerged as the fastest-expanding international territory by cardholder volume, generating a 24 per cent spending bump on the day. Individual cardholder transaction volumes advanced 36 per cent in Poland, 30 per cent in Croatia, 26 per cent in the Czech Republic, and 23 per cent each in Slovakia and Lithuania.

    Western European consumer activity presented sharper geographic divergence across card accounts. Italian card spend rose 19 per cent and Norwegian transactions surged 52 per cent, while surrounding major continental markets registered flat payment volumes.

    Singles’ Day is the first real test of the peak season, and last year’s data shows exactly where shoppers are ready to spend: fashion, department stores and general retail. Merchants who get their promotions and their checkout right will be best placed to turn that early demand into lasting growth through Black Friday and beyond.

    Operational Pressures Shift to Fulfillment

    For APAC store operators and e-commerce aggregators, an early seasonal bump concentrates warehouse packing windows ahead of late-November global discounting periods. Regional merchants relying on cross-border logistics face immediate inventory reallocation demands to satisfy delivery commitments before western peak order books open.

    Aggressive promotion schedules pulled forward consumer outlays rather than simply creating incremental fourth-quarter volume. Merchants balancing discounted inventory clear-outs during early November risk margin compression if logistics surcharges rise before peak year-end shipments conclude.

    Payment Networks Expand Enterprise Footprint

    The annual singlehood event, which began as an alternative university observance in mainland China, now anchors the opening phase of fourth-quarter trade ahead of Black Friday. Checkout.com, which handles payment infrastructure for enterprise clients including Samsung, Sony, and ASOS across more than 150 processing currencies, expects its total platform volume to reach $500bn during 2026.

    Merchant operators now watch conversion rates across Asian checkout gateways as Black Friday approaches on 27 November 2026. Retailers across the region are tracking whether the early 16 per cent promotional bump carries into broader end-of-year inventory clearance.

  • Louis Vuitton Names Hector Muelas Creative Chief After China Dispute

    Louis Vuitton Names Hector Muelas Creative Chief After China Dispute

    Louis Vuitton appointed Hector Muelas to the newly created position of chief brand creative officer on November 1, following a 5 per cent quarterly revenue drop in parent LVMH’s fashion division.

    The appointment follows a dispute in China where a local trademark court ruling against beverage chain Molly Tea sparked consumer pushback and hit sales early in the third quarter.

    Muelas steps into the position after running global creative operations at Tiffany & Co., another LVMH brand, having earlier directed content and brand strategy at luggage maker Rimowa. In his new capacity, he reports directly to Louis Vuitton deputy chief executive Damien Bertrand.

    Leading creative and content execution, he will oversee all brand campaigns

    Bertrand said in an internal announcement detailing the appointment. His remit covers creative consistency and narrative campaigns across all customer-facing touchpoints worldwide.

    The Molly Tea Court Case and Boycott Impact

    Trouble in mainland China surfaced after Louis Vuitton sued domestic tea operator Molly Tea over a four-petal floral design printed on disposable beverage cups. Louis Vuitton argued the graphic copied the flower motif from its heritage Monogram canvas. A Chinese court agreed in a first-instance ruling, ordering Molly Tea to halt use of the emblem and pay CNY 10.3 million, equal to roughly US$1.5 million. Molly Tea announced it would appeal the decision.

    Winning in court did not protect the label on the street. Online discussions in China quickly took issue with the decision, with consumers arguing that four-petal floral designs belong to historic Chinese decorative arts rather than a 19th-century French luggage maker. Independent estimates pointed to an initial 30 per cent drop in Louis Vuitton boutique sales in China during July as consumers turned away from the label.

    Quarterly Fashion Division Contraction

    Financial fallout appeared in group accounts shortly after. LVMH reported a 5 per cent organic revenue decline for its global Fashion & Leather Goods division during the third quarter of 2026, pointing to softer demand across mainland China. The reported figure covers the wider division rather than standalone Louis Vuitton boutique receipts in China.

    Speaking on an October 12 earnings call, LVMH finance chief Cécile Cabanis told investors that the Molly Tea dispute likely hurt business at the start of the quarter, though the exact financial impact remains difficult to isolate from broad luxury belt-tightening.

    Speculation also circulated regarding the future of Louis Vuitton chief executive Pietro Beccari, following French media commentary that his position was under scrutiny. Beccari remains in his role, which he has held since February 2023, while simultaneously leading LVMH’s Fashion Group since January 2026. Muelas was brought in to steer brand storytelling rather than reshape corporate governance.

    Physical Retail Push Across East Asia

    For store operators and luxury property landlords in Asia, the appointment highlights the operational friction between brand protection and commercial goodwill. Luxury houses have spent three decades using aggressive intellectual property litigation to clear Asian markets of copycats. Yet using identical tactics against a homegrown tea chain proved counterproductive, transforming a routine trademark defence into an argument over cultural entitlement.

    LVMH cannot rely on trademark lawyers to restore foot traffic. Instead, the company is leaning on heavy physical retail spending to anchor prestige in primary regional markets. Louis Vuitton continues to operate its travel-themed retail destination in Shanghai and recently unveiled a large trunk-themed experiential installation in Hong Kong, betting that scale and craftsmanship can steady customer perception.

    The creative overhaul comes after several quarters of shifting consumer spending patterns across Chinese tier-one cities, where local shoppers have become far more selective. Molly Tea is now preparing its appeal before the Chinese appellate court, while Muelas takes charge of the French house’s upcoming global marketing releases.

  • China Eastern Signs Skagen Salmon Deal as Direct Food Arteries Expand

    China Eastern Signs Skagen Salmon Deal as Direct Food Arteries Expand

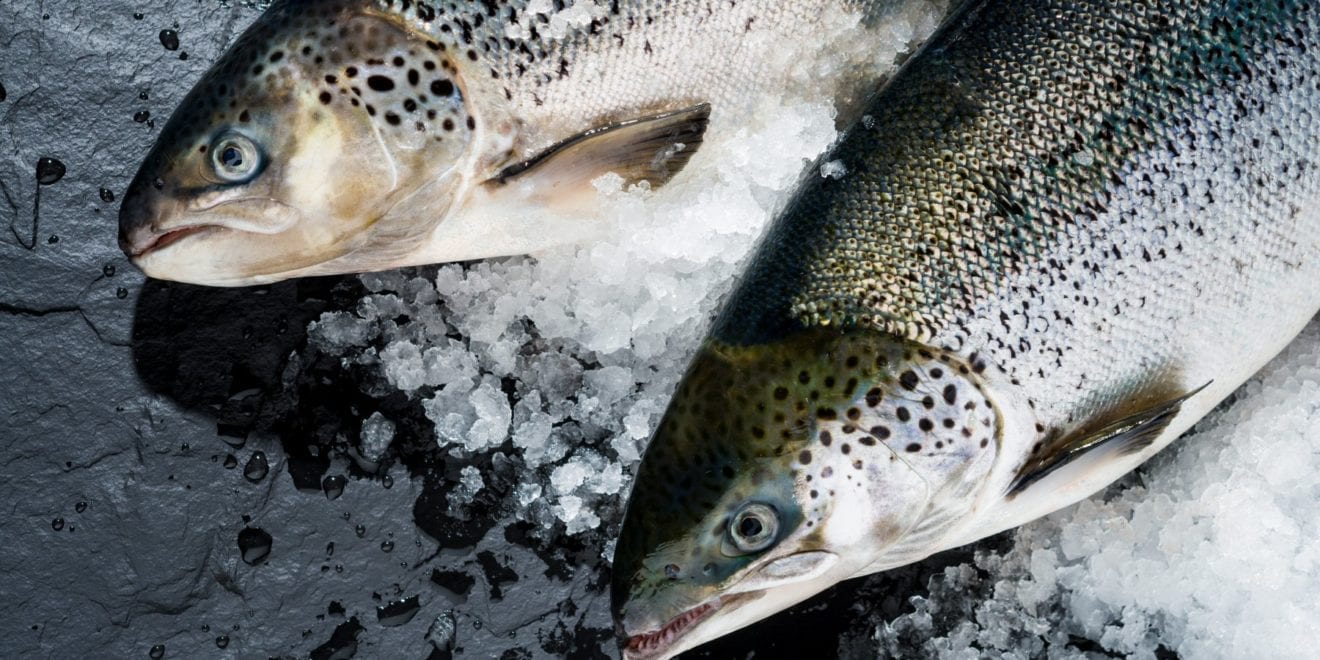
    China Eastern Airlines’ logistics subsidiary signed a salmon supply agreement with Denmark’s Skagen Salmon at the China International Import Expo in Shanghai.

    To support the flow, China Eastern opens a dedicated cargo route connecting Shanghai with Copenhagen during November, establishing a direct air artery between northern Europe and mainland retail networks.

    The agreement taps surging Chinese consumer appetite for fresh seafood, pairing European farm output with China Eastern’s dedicated cold chain infrastructure and direct retail distribution channels.

    Cold Chain Monitoring and Livestream Shelves

    The carrier’s logistics unit built an end-to-end corridor covering origin transit, customs clearance, domestic warehousing, and processing at localized fresh-food hubs. It uses proprietary in-pack temperature loggers to record full transit curves, pinpointing environmental breaches across thousands of flight miles.

    Finished stock heads directly to physical supermarket counters and livestream e-commerce operators, stripping traditional layers of import brokers. That immediate link matters as domestic consumer appetites shift toward traceable chilled seafood over frozen blocks.

    Zespri Scales Direct Maritime Access

    Direct maritime routing shows parallel efficiency gains across produce aisles. New Zealand marketer Zespri dispatched the chartered vessel Kowhai from the Port of Tauranga on March 17 carrying 4,750 tons of new-season fruit, docking in Shanghai 12 days later.

    Its first shipment of more than 3,000 boxes reached a Shanghai agricultural trading hub on April 2 and cleared out before the end of the day. The brand projects global sales of 260 million standard retail trays and NZ$6.3 billion ($3.5 billion) in total revenue for the 2026/27 season.

    China accounts for NZ$1.4 billion of that projected total, equal to more than 1.5 billion individual kiwifruit moving across 34.37 million domestic households. The company expanded its retail presence from 35 Chinese cities in 2019 to 82 cities in 2026.

    “We will keep innovating, sustain our steadfast partnerships in China, and keep Zespri at the forefront of the kiwifruit category here,” said Michael Jiang, president of Zespri China and APAC South.

    South American Transit Times Drop

    Direct maritime infrastructure in South America is altering port economics for trans-Pacific fresh cargo. COSCO SHIPPING Ports Chancay Peru expects its terminal to handle close to half of its 1 million twenty-foot equivalent unit capacity this year, general manager Wang Bin reported on Sunday.

    Direct transit between Chancay and Shanghai now takes 23 days, cutting freight expenses by more than 20 percent. The port runs five regional feeder routes gathering shipments from neighboring markets, funneling avocados and blueberries onto fast trans-Pacific services.

    Data from the State-owned Assets Supervision and Administration Commission shows Chancay handled 62 percent of Peru’s agricultural exports to China between January and September, delivering roughly $210 million in trade value.

    The Margin Squeeze on Traditional Distributors

    State carriers and volume fruit marketers are increasingly taking operational control of origin packing, temperature logging, and regional distribution. For independent importers and regional wholesale dealers, this consolidation cuts off trading margins on premium items.

    Large supermarket chains and rapid-delivery platforms gain predictable arrival dates and reduced spoilage rates, giving them room to discount premium fresh categories. The operational risk falls on port clearance velocity: when high-value perishable volume converges on single terminals, any processing pause damages expensive stock.

    China Eastern’s cold chain unit established its integrated model after identifying Denmark as a supply node that fit spare European belly and freighter capacity. The Copenhagen flight schedules beginning this November will test whether air freight yields can hold steady through winter perishable cycles.

  • FedEx Adds Four Weekly China-US Cargo Flights for AI Hardware

    FedEx Adds Four Weekly China-US Cargo Flights for AI Hardware

    FedEx has added four weekly Boeing 777 freighter flights connecting Shanghai and Guangzhou with its United States hubs, expanding transpacific capacity for semiconductors and artificial intelligence infrastructure.

    Three flights depart Shanghai with a scheduled stop in Osaka before flying to Anchorage and Memphis, while a fourth flight operates from Guangzhou to the same American transfer points.

    The express carrier confirmed the extra air cargo space on November 9, explicitly designating the routes for advanced industrial manufacturing, chip components, computing infrastructure and high-end cross-border e-commerce.

    Routing Through Japan’s Component Belt

    Inserting Osaka into the Shanghai rotation reflects the dense interdependency of East Asian technology manufacturing. Japanese suppliers provide essential semiconductor fabrication equipment and chemicals, meaning freighters can consolidate sub-assemblies before crossing the Pacific.

    Air transport commands premium rates over ocean freight, yet high-value processors and server racks demand rapid delivery schedules that maritime shipping cannot match. For suppliers and logistics planners, dedicating long-range widebody aircraft to specific technology corridors shortens transit cycles between manufacturing centers and American integration hubs.

    Physical Cargo Defies Equity Jitters

    Financial markets pulled back sharply from artificial intelligence shares last week following concerns over potential policy limits on data center construction in the United States. Physical freight volumes tell a different story.

    Carriers do not fuel Boeing 777 freighters on speculation. Increasing scheduled capacity between Chinese assembly plants and American distribution bases demonstrates that hardware procurement orders remain fully funded on factory floors.

    Export Momentum Ahead of Bilateral Talks

    Chinese outbound trade figures for October projected exports to climb roughly one-third in dollar terms compared to the prior year, driven largely by global procurement of specialized electronics. That outbound volume delivers critical revenue to integrated air freight operators while keeping cargo yields firm.

    Trade balances and advanced technology access also frame diplomatic talks between US President Donald Trump and Chinese President Xi Jinping at the Asia-Pacific Economic Cooperation meeting in Shenzhen in mid-November.

    Official customs figures released on Tuesday will verify whether air-eligible technology shipments kept pace with cargo allocations.

  • DP World Launches Weekly China-Africa Shipping Route Across 8 Ports

    DP World Launches Weekly China-Africa Shipping Route Across 8 Ports

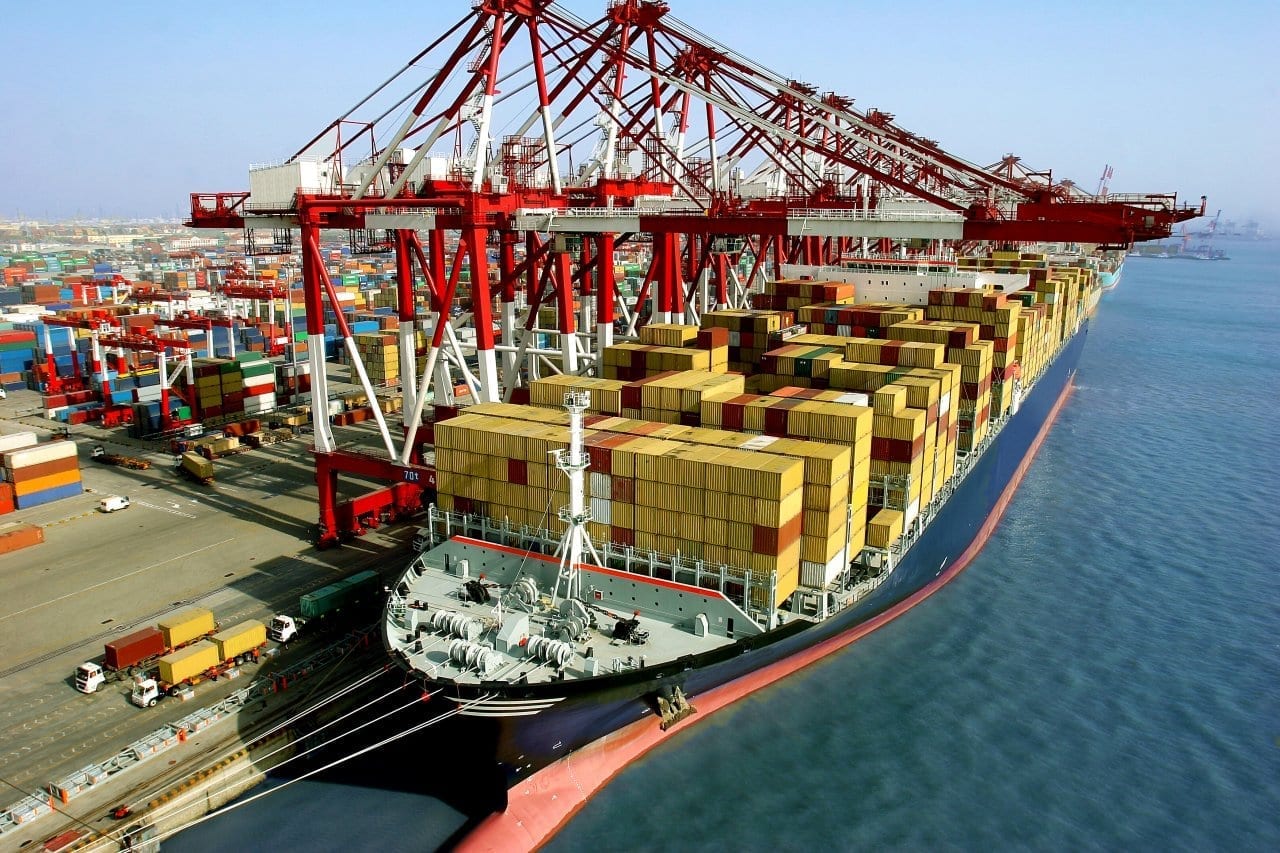
    DP World will launch a weekly container service linking export hubs in China and Southeast Asia directly with East and Southern Africa in late November 2026.

    Operated by DP World’s Shipping Solutions AMEA unit, the China Africa Link connects three mainland Chinese gateways and two Southeast Asian transshipment hubs to Dar es Salaam and Maputo.

    The scheduled rotation covers eight port calls, moving goods between Asia and African markets where DP World is spending $165 million to expand handling capacity in Mozambique.

    Rotation Details and Port Calls

    The scheduled port rotation runs Shanghai, Ningbo, Nansha, Port Klang Westport, Dar es Salaam, Maputo, Singapore, and back to Shanghai. DP World Shipping Solutions AMEA will operate the weekly rotation to provide fixed-day departures for exporters across the region.

    Cargo moving westbound will center on manufactured goods including electronics, construction materials, automotive components and industrial machinery. Eastbound vessels returning to Asia will load African mineral commodities and agricultural goods destined for Chinese processors and Southeast Asian regional distribution centers.

    “Global trade is changing, and our customers need more than shipping capacity. They need reliable connections, greater choice and the flexibility to adapt as trade patterns evolve,” explains Ganesh Raj, Global COO, Marine Services at DP World.

    Direct Access for Consumer Supply Chains

    For Asia-Pacific electronics manufacturers and automotive component exporters, the dedicated loop bypasses ad-hoc feeder transshipment at congested intermediate hubs. Direct calls at Port Klang and Singapore give shippers in Malaysia and surrounding ASEAN markets an immediate option to tap African buyers without secondary re-handling delays.

    The service also tightens export pipelines for retail and wholesale merchandise leaving the Pearl River Delta via Nansha and the Yangtze River economic belt through Shanghai and Ningbo. Shippers gain reliable transit times for seasonal consumer inventory, cutting the buffer stock requirements typically carried for emerging market distribution.

    Terminal Investments in Maputo and Dar es Salaam

    DP World is tying the vessel rotations directly to its captive terminal infrastructure on the African east coast. The group is spending $165 million to expand the Maputo container terminal in Mozambique, a project aimed at doubling its existing container throughput capacity.

    In Tanzania, DP World is modernizing the Port of Dar es Salaam through a $500m investment. Combining port ownership with proprietary maritime line strings lets the Dubai-based terminal operator manage berth windows and landside transfers internally, shielding its cargo from third-party terminal bottlenecks.

    Global Footprint and Next Milestones

    The network expansion builds on DP World’s broader capital deployment across global transport corridors, where it has committed more than US$10bn into logistics infrastructure. The company currently manages handling operations across 85 countries with a global capacity of 110 million TEU, handling approximately 10% of global trade every day.

    With vessel rotations finalized, the China Africa Link begins its maiden voyages in late November 2026, when terminal operators in Shanghai, Ningbo, and Nansha begin accepting first export bookings for the maiden westbound loop.

  • Awinic Plans Controlling Stake in Yutai Semiconductor as Profit Drops 61%

    Awinic Plans Controlling Stake in Yutai Semiconductor as Profit Drops 61%

    Awinic Technologies suspended trading of its shares and convertible bonds on November 10 as it plans to buy a controlling stake in Yutai Semiconductor through shares and cash.

    The chip designer holds nearly CNY 3.783 billion in cash-like reserves, giving it the balance sheet capacity to fund a transaction that may constitute a major asset restructuring.

    Awinic plans to issue new shares, pay cash, and raise matching funds to secure all or part of the target business. Trading will halt for no more than 10 trading days. The four initial selling partnerships named in company filings are Shanghai Yubo, Shanghai Jinweili, Shanghai Yitiai, and Shanghai Yuzong. Together, Shanghai Yubo and Shanghai Jinweili hold a combined 38.43 percent of Yutai. No formal agreement is signed, and the final valuation and transaction ratio remain unset.

    The Sticking Point at SG Micro

    The deal immediately runs into an awkward structural problem. SG Micro, a direct competitor in analog chips, sits on Yutai’s register as the second-largest shareholder with a 25.95 percent holding. That stake gives SG Micro the use to either block a clean sweep or demand terms that alter the economics of the buyout. Awinic cannot absorb Yutai cleanly without addressing whether its chief domestic rival exits or stays embedded in the cap table.

    For hardware suppliers and brand procurement teams, consolidation among domestic analog suppliers reduces bargaining use. Phone makers and consumer gadget assemblers often rely on fragmented domestic chip shops to keep component costs low. If Awinic absorbs Yutai’s catalogue, buyers face a more consolidated supplier base across low-voltage and medium-voltage power lines. Competitors will watch whether SG Micro tenders its stock or uses its minority position to slow the integration.

    Balance Sheet Buffer Against Dropping Profits

    Awinic needs product diversification because its core consumer electronics business is stalling. In the first three quarters of 2026, the company posted revenue of CNY 2.117 billion, down 2.75 percent from the previous year. Net profit attributable to shareholders plunged 61.08 percent to CNY 107 million, while operating cash flow dropped 93.18 percent to CNY 22.66 million. Tight memory chip supply held back production schedules at smartphone factories, while mature-process foundry capacity squeezed gross margins.

    Cash reserves provide the only real protection for the buyer. Awinic entered October with CNY 703 million in monetary funds and CNY 3.08 billion in trading financial assets. Paying part of the acquisition in cash prevents excessive equity dilution at a time when Awinic’s valuation multiple is depressed by falling earnings. Issuing too much stock when net profit excluding non-recurring items fell 87.53 percent would trigger resistance from institutional investors.

    A Tortuous Path to Liquidity

    Yutai has tried and failed to reach the public markets twice before. SG Micro originally purchased 28.7 percent of the business for CNY 115 million in December 2018, before launching a CNY 1.07 billion bid for the remaining 71.3 percent in late 2019 that collapsed in October 2020. Yutai then filed for an independent listing on the STAR Market in 2022 to raise CNY 750 million for research and industrialization facilities, but the application stalled before tutoring restarted in 2023 without an outcome.

    Founded in November 2017 in Nantong by former Maxim Integrated designers, Yutai sells more than 500 power management products across 10 categories, including DC-DC converters, battery management chips, and interface protection circuits. Backers across four funding rounds include Transsion Holdings, SK Hynix Semiconductor (China), SMIC Capital, Longcheer Technology, and Leishi Investment. Its parts sell into smart meters, routers, power banks, and security cameras, giving Awinic a path beyond saturated smartphone sockets.

    Regulators and investors are now waiting for the restructuring framework before trading resumes at the end of the 10-day halt.

  • PrimeBOT Produces 10,000Th Personal Robot as Output Doubles in 14 Days

    PrimeBOT Produces 10,000Th Personal Robot as Output Doubles in 14 Days

    PrimeBOT produced its 10,000th personal robot on November 8, doubling its cumulative factory run after assembling 5,000 units over a 14-day stretch.

    Parent company Swancor Advanced Materials reached the production milestone following an initial build of 5,000 units completed on October 25, according to operational disclosures reported by Sina Technology.

    Alongside the factory output, Liu Dongfang, co-president of the robotics business and head of its Q business division, claimed a monthly user activity rate above 98 percent, three hours of average daily connection time, and over 100 daily interactions per user. Liu also reported peak concurrent online connections above 40 percent, though the company provided no independent audit, sample sizes, observation periods, or definitions for what constitutes an active interaction.

    Factory Throughput Diverges From Retail Checkout

    Assembly line speed does not measure consumer sell-through. PrimeBOT began mass manufacturing whole units in October, yet the disclosures give no figures for retail sales, channel inventory, distributor deliveries or product returns. The 10,000 units represent machinery exiting the manufacturing line rather than active domestic installations.

    Retail buyers and consumer electronics merchandisers face an unverified supply pipeline. Factory output tells purchasing desks what a manufacturer can assemble, but without audited register data or warehouse turnover metrics, the commercial demand for companion robots remains speculative. Production yield rates and warranty provisions also stay undisclosed.

    Hardware operators in consumer tech know that claimed software engagement often obscures low functional utility. An active connection status requires only an open network socket or a charging dock handshake, which does not prove that a consumer is actively using the machine. Daily online metrics give no indication of physical tasks accomplished or sustained household utility beyond initial novelty.

    Companion Hardware Built for Low Barriers

    PrimeBOT builds two small consumer units: the Q1, an 0.8-meter-tall humanoid that folds into a backpack, and the T1, which converts between a wheeled humanoid and a four-legged chassis. Neither unit performs household domestic labor. Both designs focus on home companionship, interactive play and educational programming.

    The joint venture behind the hardware pairs industrial materials maker Shangwei New Materials, also known as Swancor Advanced Materials, with domestic robotics developer AgiBOT. By building the Q1 as an open-source system with customizable, 3D-printable outer shells and user-designed personality software, the venture aims at hobbyists, students and entry-level buyers rather than commercial service sectors.

    Physical form factors dictate retail price ceilings. Standard industrial and service humanoids run into tens of thousands of dollars, limiting personal household adoption across Asia. PrimeBOT aims to compress hardware unit costs through compact components and automated line testing, though the company has not published official retail pricing sheets for open channel sales.

    The Manufacturing Ramp From October

    Initial distribution started weeks before the factory doubled its run rate. PrimeBOT launched first customer handovers for both the Q1 and T1 units in October, leading into the factory ramp that reached 5,000 total finished units on October 25. That cadence accelerated to 5,000 additional units during the subsequent 14 days.

    Earlier releases positioned the Q1 platform as a customizable entry point for personal robotics, with software hooks permitting non-technical buyers to alter speech traits and behavior. The subsequent factory disclosures moved executive commentary away from product customization toward high-volume manufacturing throughput and claimed engagement statistics.

    The next metric to monitor is retail sell-through and channel inventory levels across Asian retail partners as the holiday sales quarter progresses. PrimeBOT has yet to release audited delivery counts or confirm sustained household retention rates past the initial handover phase.

  • Aldi to Reach 150 China Stores by End of 2026

    Aldi to Reach 150 China Stores by End of 2026

    Aldi is doubling its store expansion pace in China to reach 150 outlets nationwide by the close of 2026. The German hard-discount chain expects to launch around 60 locations this year, roughly twice its annual total from earlier years, China chief executive Jacqueline Chen said in an interview published this week.

    Expanding from Shanghai into Jiangsu

    The company operates more than 70 stores in Shanghai and over 50 across the southern region of Jiangsu province. Most locations run on a compact footprint of roughly 1,000 square meters, carrying about 2,000 stock-keeping units. Over 90 percent of those goods are private labels, allowing the retailer to bypass third-party distributors and strip out wholesale markups.

    To support that density, Aldi recently brought online its third major warehouse in East China, located in Nanjing. Supply chain capacity must be built before entering a new market, Chen said, pointing out that the distribution hub will let the company launch regional branches faster while balancing logistics costs, speed and inventory resilience.

    The Psychology of the Ten Yuan Anchor

    Price architecture drives the operational model. Between a quarter and a third of all products on Aldi shelves in China sell for less than CNY10 (USD1.49). Merchandise buyers identify the band between CNY9.90 and CNY12.90 as the critical psychological threshold to secure impulse basket additions, with shopper conversion dropping steeply once single-item pricing crosses CNY13.

    Domestic rivals including Kinglomo, Mart Fresh and Sanjiang Shopping Club are competing aggressively around the same ten-yuan price point. Across Chinese retail, discount formats and membership warehouse clubs remain the sole grocery models gaining share in an otherwise strained consumer environment. Warehouse clubs serve mid-to-high-income households buying in bulk, leaving discount supermarkets to mop up high-frequency foot traffic with low-cost daily necessities.

    Supplier Margins and Format Risk

    Aldi is betting that intense urban density inside the Yangtze River Delta can insulate it from the deflationary price battles hurting conventional hypermarkets. Big-box grocery chains across eastern China have struggled with large physical footprints and costly vendor fees, creating opportunities for smaller neighborhood stores. By leaning on local manufacturing for proprietary labels, the chain protects gross margins that traditional grocers lose to national brand allowances.

    The risk sits in category depth and supplier stickiness. Regional domestic operators have copied the limited-assortment private-label model with faster localized sourcing cycles, while suppliers face shrinking margins under Aldi’s cost-plus purchasing contracts. If identical ten-yuan staple goods saturate local wet markets and convenience chains, retaining customer traffic will require constant product rotation rather than price cuts alone.

    Building Out East China Footprint

    Aldi entered the Chinese mainland market in 2019, initially using cross-border e-commerce before setting up physical neighborhood locations across Shanghai. Over the subsequent five years, it calibrated its assortment from imported European specialty foods toward domestic hard discount, steadily pushing out of Shanghai’s central wards into secondary cities across Jiangsu.

    The immediate benchmark is the completion of the 2026 expansion schedule, which requires delivering the remaining pipeline of the planned 60 openings to hit the 150-store fleet total before the close of December.

  • China Tech Stock Slide Wipes Out 3 Trillion Dollars in Household Wealth

    China Tech Stock Slide Wipes Out 3 Trillion Dollars in Household Wealth

    Chinese equities entered a bear market after shedding more than $3 trillion in market value, wiping out a year of tech-driven gains for approximately 250 million domestic retail traders.

    Trading volumes dried up across mainland exchanges following the longest unbroken selling streak on record, pulling major benchmark indices back toward levels recorded before Beijing introduced stimulus support in 2024.

    Individual accounts hold roughly 30 percent of Chinese equities by value but generate approximately 70 percent of total market turnover. That structural imbalance magnified swings throughout 2026, when millions of day traders rushed into initial public offerings tied to artificial intelligence, robotics, and semiconductors. Many of those listings were oversubscribed thousands of times over during the initial surge, before aggressive institutional selling quickly cut valuations.

    The Industrial Policy Trap

    State priorities continue to trigger aggressive capital allocation into targeted technology fields, but that factory floor expansion rarely safeguards margins for public shareholders. Local administrations across China race to fund identical supply chains, creating rapid manufacturing capacity that strips operating companies of basic pricing power.

    For consumer brands and retail operators, the equity retreat removes a vital support for household balance sheets already pressured by a multi-year property contraction. Domestic consumers who turned to equity trading to recoup residential real estate losses now face dual balance-sheet erosion, restricting discretionary spending across major metropolitan centres.

    Returns Lag Global Peers

    Over the past decade, the benchmark CSI 300 Index generated an average annual return of 4.2 percent, compared to 15.6 percent for the US S&P 500 Index. That performance trailed despite China expanding its nominal gross domestic product by roughly 7 percent annually over the same ten-year window and producing global manufacturing leaders like BYD and DeepSeek.

    “Policy support can build capacity without giving companies the pricing power to protect margins. It began as an earnings problem and has become a confidence problem.”

    Individual traders burned by volatile momentum trades have cut exposure dramatically. Allen Sun, a cross-border trade professional, reduced his domestic stock portfolio from a peak of 1 million yuan down to 100,000 yuan ($14,990), citing structural distrust in primary fundraising practices that favour early founders over secondary market participants.

    State Intervention Stalls

    State-backed funds known as the national team resumed direct equity purchases this week to halt the decline, while financial regulators deployed cheaper funding channels to encourage share buybacks. The response proved tepid, lifting the CSI 300 by less than 3 percent over the week as institutional managers continued unwinding positions.

    Professional domestic funds operate under tight quarterly performance cycles, prompting portfolio managers to dump speculative tech holdings at the first break in momentum rather than holding through extended drawdowns. Short-selling restrictions leave few hedging tools available, reinforcing sharp one-way selloffs across onshore bourses.

    The benchmark CSI 300 remains pinned near multi-month lows as market participants assess whether state capital purchases will expand beyond current intervention levels before the end of the final trading quarter.

  • Yum China Lifts Store Target to 2,400 Outlets After Net Profit Rises

    Yum China Lifts Store Target to 2,400 Outlets After Net Profit Rises

    Yum China raised its annual store opening target to more than 2,400 outlets after reporting an 8 per cent rise in third-quarter revenue to US$3.5 billion.

    Operating profit climbed 13 per cent to $451 million as the company added a net record of 692 restaurants, lifting its total estate across mainland China to 19,989 locations.

    The previous target stood at 1,900 net new stores for 2026. Chief executive Joey Wat confirmed the operator will pass the 20,000-store mark before the end of the year, backed by a 20 per cent rise in diluted earnings per share. In constant currency terms, system sales grew 3 per cent while core operating profit rose 6 per cent. That performance represented the company’s tenth consecutive quarter of concurrent growth across system sales, operating profit and operating margin.

    Margin Defense Against Lower Ticket Averages

    Same-store sales slipped to 97 per cent of prior-year levels during the quarter. The company faced adverse weather in August alongside tough comparisons against heavy third-party delivery platform subsidies disbursed in the prior year.

    Customer traffic offset that pressure. Same-store transactions grew 3 per cent, marking the fifteenth straight quarter of volume gains. Diners spent less per visit, but more of them came through the doors.

    Restaurant margins widened 50 basis points year on year to 17.8 per cent, matched by a 40 basis point rise in operating margin. Management attributed the margin resilience to negotiated rent reductions, automated kitchen processes, centralized operations support and lower delivery-rider expenses per completed order. Profitability also received a clean lift from the full buyout of the Pizza Hut mainland China business, which permanently extinguished brand royalty and licensing fees payable on those locations.

    Smaller Formats Target Unpenetrated Counties

    Rapid store openings now lean directly on downsized footprints designed for lower overheads. During the first nine months of the year, Yum China rolled out 1,888 net new locations, with chief financial officer Adrian Ding confirming that more than half were opened in new cities, strategic locations or trade zones without existing dine-in or delivery coverage.

    To penetrate smaller settlements without cannibalizing revenue, the operator rolled out formats including KFC Small Town, Pizza Hut WOW and dual-branded KFC-Pizza Hut Gemini sites. These smaller templates accounted for over half of all openings across lower-tier cities this year, holding store payback periods between two and three years.

    The white space remains substantial. Wat noted that KFC has no presence in roughly 1,000 Chinese cities, while Pizza Hut remains absent from 1,500 cities. In another 1,500 locations where KFC already trades, Pizza Hut has yet to open a single kitchen. KFC’s footprint passed 14,000 restaurants during the quarter after adding more than 500 net units.

    Rival Pressures and Digital Takeaways

    Yum China’s physical push contrasts sharply with regional competitors that are slowing development pipelines to protect cash reserves. Local Chinese fast-food challengers and Western franchisors alike have struggled against discounting wars in tier-one and tier-two shopping malls, where consumer caution has dragged down average spend. By steering capital expenditure into lower-tier cities with compact layouts, Yum China secures cheaper commercial leases while spreading its central supply chain costs over larger sales volumes.

    Landlords in lower-tier markets face high vacancy rates and are granting substantial rent concessions to secure anchor fast-food tenants. For Yum China, the primary operational risk shifts from retail rental inflation to consumer price elasticity, since secondary-town shoppers demonstrate little loyalty if ticket prices creep up. Digital platforms continue to command consumer access: delivery revenue increased 7 per cent in the quarter to generate 54 per cent of all company sales, making unit-level economics increasingly sensitive to rider logistics costs.

    Earlier quarterly results showed the company holding a conservative opening pace before accelerating installations through the late summer. The group generated $362 million in shareholder capital returns during the third quarter alone, maintaining a broader plan to return $1.5 billion across 2026. Active digital loyalty members across the KFC and Pizza Hut ecosystems exceeded 278 million.

    Management reiterated its target for 2027 of zero to 2 per cent same-store sales growth alongside double-digit diluted earnings growth, with full-year 2026 network counts scheduled to clear the 20,000 threshold in the fourth-quarter filings.

  • Estee Lauder Targets Mid-Single-Digit Growth Through 2030 as China Sales Rebound

    Estee Lauder Targets Mid-Single-Digit Growth Through 2030 as China Sales Rebound

    Estee Lauder targets mid-single-digit organic net sales growth through fiscal 2030 as it revamps operations in mainland China, following four consecutive quarters of positive organic revenue expansion there.

    Chief executive Stéphane de La Faverie, who took leadership in 2025, also aims to lift adjusted operating margin to between 16.5 per cent and 18.5 per cent by the end of that period, backed by double-digit annual gains in adjusted earnings per share.

    The company laid out the targets during its Capital Markets Experience event in Shanghai on Wednesday. Mainland China accounted for US$3.1 billion in net sales during the group’s most recent fiscal year, delivering roughly 20 per cent of worldwide revenue. In the latest quarter, China generated US$614 million, beating consensus analyst forecasts of US$579 million, while group fragrance sales led overall demand.

    Exporting the Mac Playbook to Aveda

    Management plans to apply the commercial turnaround strategy tested at Mac Cosmetics across slower brands in its stable, specifically identifying haircare label Aveda for the overhaul. That shift relies on faster product cycles, increased store-level marketing, and expanded merchant shelf space inside Sephora retail shops and on the TikTok Shop platform.

    Product formulations will lean heavily on the company’s dedicated innovation centre in Shanghai, which crafts formulations and commercial campaigns tailored directly to East Asian consumer preferences.

    “When you understand the local consumers and you put yourself into their culture and you give them their product, the experience, the claims that they want to hear that matters to them, then that’s how you build brand love,” he said.

    Chief technology and transformation officer Brian Franz told investors in Shanghai that the company is rewiring its distribution and inventory planning to match domestic Chinese platforms, including Tmall, Douyin, JD.com and WeChat.

    The Gray Market Bottleneck

    Global beauty conglomerates operating in Asia face structural changes in Chinese retail that standard marketing budgets cannot fix alone. Domestic Chinese brands have taken market share across mid-tier skincare, while multinational groups have faced intensifying competition. Accelerating research through local hubs in Shanghai is now mandatory for any international group seeking to protect its gross margins.

    A steeper operational hurdle sits in regional clearance channels. Unauthorised resellers accumulated genuine imported stock during pandemic border controls, subsequently discounting products on third-party marketplaces. That shadow trade eroded official retail price floors across tier-one Chinese department stores and damaged brand equity for prestige skincare labels such as La Mer. Estee Lauder must tighten wholesale supply discipline across duty-free operators if it wants to sustain price points inside mainland boutiques.

    Correcting Pandemic Inventory Overhang

    The current operational reset follows years of sluggish financial metrics across North Asia. Pandemic travel restrictions left Estee Lauder with excessive inventory piled inside airport concessions, while international passenger traffic recovered far more slowly than corporate planners anticipated.

    De La Faverie responded by launching the Beauty Reimagined restructuring program upon taking the top job in 2025, cutting excess stock and decentralising commercial decisions to regional operating units. Estee Lauder shares traded up 0.6 per cent through Tuesday’s close following the revised corporate guidance.

    Department store buyers and platform operators will test that pricing discipline during the upcoming fiscal quarters, as the company rolls out initial product lines formulated specifically by its Shanghai laboratory for Aveda and Mac across Asia-Pacific storefronts.

  • Danone Launches 5,200 M² Research and Innovation Center in Shanghai

    Danone Launches 5,200 M² Research and Innovation Center in Shanghai

    Danone officially launched a 5,200 m² research and innovation center in Shanghai on Nov. 2, advancing its work on nutritional solutions for early life, healthy aging, and longevity.

    A centerpiece of the complex is the 900 m² Danone OneBiome Lab, the group’s third such site following openings in Paris-Saclay and Singapore. Isabelle Esser, chief research, innovation, quality and food safety officer, noted that the unit uses bacterial DNA extraction and analysis to decode individual gut profiles influenced by age, diet, and lifestyle.

    Alongside the laboratory, the hub incorporates a 700 m² pilot plant and a 300 m² science experience and consumer engagement space. This integrated footprint enables Danone to pair consumer feedback with sensory testing, prototyping, packaging design, and digital health tech development under one roof.

    Targeting Formula and Healthy Aging

    The technical work focuses on two ends of China’s demographic curve: infant nutrition and healthy longevity. In infant milk formula, researchers examine human breast milk composition among Chinese mothers to reformulate Danone’s Aptamil product lines to match natural gut flora development.

    For older consumers, the Shanghai team is working on products under lines like Ganmai, a brand Danone rolled out with timed probiotic fibre powders aimed at immune and digestive maintenance. The company had previously established an exploratory research venture with Qingdao University three years ago to study microbiome changes across life stages.

    “Some of the most important scientific areas on which we at Danone are investing are related to gut health and to biotics,”

    Said Isabelle Esser, chief research, innovation, quality and food safety officer at Danone.

    Competing on Science in a Shrinking Baby Market

    Danone faces a structural squeeze in China’s infant formula trade. Falling national birth rates have tightened total volumes across the sector, forcing international formula makers into direct shelf competition against domestic champions such as China Feihe.

    Foreign dairy brands can no longer rely purely on imported prestige to clear inventory in lower-tier cities. Winning supermarket shelf space and mother-and-baby store distribution now requires hyper-localised scientific claims, especially around gut tolerance, digestion, and ingredient profiles matching local mothers’ milk.

    Localised trial work also speeds regulatory filings, meaning on-the-ground pilot facilities cut the lead time between laboratory formulation and commercial retail distribution.

    Building Out Regional Digital Health Tools

    The Shanghai hub also takes over digital health software testing designed to tie retail customers into the brand’s ecosystem. Danone previously rolled out diagnostic applications from its Singapore lab, including digital iron monitors, infant growth trackers, and stool analysis tools that guide parents toward specific formulas.

    Taous Lassel, vice president for research and innovation in Asia-Pacific and China, leads the regional R&D digital and artificial intelligence team operating out of the site.

  • Zhang Yiming Tops China Wealth List with Nearly $100 Billion Fortune

    Zhang Yiming Tops China Wealth List with Nearly $100 Billion Fortune

    ByteDance founder Zhang Yiming has regained the top spot on China’s wealth ranking with a fortune of nearly US$100 billion, driven by artificial intelligence deployment across his consumer technology empire.

    His net worth surged 43 percent over the past year, displacing bottled water magnate Zhong Shanshan after consumer goods company Nongfu Spring saw its founder’s valuation drop 23 percent to $61 billion.

    The annual Hurun China Rich List, published Tuesday by the Shanghai-based Hurun Research Institute, tracked 1,529 individuals holding fortunes above 5 billion yuan ($750 million) as of Sept. 1. Mainland real estate operators dropped entirely out of the top 100 ranks, completing a decadelong transformation in the engines driving Chinese capital.

    Artificial Intelligence Reshapes Top Ranks

    About 160 individuals on the roster, roughly 10 percent of the total cohort, generated their primary wealth through artificial intelligence applications and foundational hardware. ByteDance accelerated that momentum through consumer-facing tools, deploying the Doubao chatbot into China’s most active automated assistant alongside video-generation software Seedance.

    Newer entrants took immediate command of the top ten. DeepSeek founder Liang Wenfeng, 41, entered the ranking at seventh position with $41.7 billion. Chen Tianshi of semiconductor designer Cambricon Technologies broke into the top 10 for the first time with $30.5 billion, climbing 14 percent.

    Both men now share the distinction of being the youngest self-made entrepreneurs inside the top tier. Zhang, 43, previously held that position.

    Consumer Tech and Hardware Displace Real Estate

    Traditional manufacturing and tech heavyweights shuffled positions behind the top two. Contemporary Amperex Technology founder Robin Zeng Yuqun took third place at $57.3 billion, advancing 17 percent as energy storage demand expanded. Tencent founder Pony Ma Huateng slipped to fourth after his holdings dropped 26 percent to $51.5 billion.

    Appliance manufacturer Midea lifted co-founder He Xiangjian into fifth place. He displaced Xiaomi founder Lei Jun, whose personal valuation dropped by roughly half following market volatility across consumer device lines.

    Hurun Report chairman and chief researcher Rupert Hoogewerf documented the disappearance of residential real estate developers, who accounted for one-third of the top 100 a decade ago. Mainland property names vacated the elite threshold, leaving traditional landlord representation almost solely to established Hong Kong dynasties.

    Today, for the first time ever, not a single mainland property developer remains in the Top 100, the only property names left at the top are the Hong Kong landlord families

    Shifting Capital for Retail and Commercial Operators

    For Asian retail brands and commercial operators, the complete exit of mainland developers marks an irreversible shift in balance-sheet power. Shopping mall construction and commercial master leases across top-tier Chinese cities no longer lean on aggressive land-banking syndicates. Capital flows instead follow software ecosystems, high-efficiency appliances, and hardware components.

    Retail brands across Asia-Pacific face direct exposure to this realigned influence. ByteDance, Tencent, and hardware players dictate consumer acquisition costs and social commerce funnels, leaving commercial landlords with diminishing use over brand tenants. Commercial real estate in Greater China now answers to digital platform power rather than physical site scarcity.

    Hong Kong real estate magnate Li Ka Shing, 98, alongside his son Victor Li Tzar-kuoi, retained a presence in the upper tier with $37.6 billion, up 8 percent. Their persistence reflects mature, diversified infrastructure holding models that survived the residential developer debt unraveling on the mainland.

    The Long Unwind of Property Fortunes

    The transition began after regulatory tightening dismantled debt-fueled expansion strategies among mainland developers. Wealth figures tumbled over multiple assessment cycles, dragging property founders off the boards as credit channels dried up and homebuyer transactions slumped.

    Zhang last held the top position in 2024 before brief market contractions reordered the roster. ByteDance expanded its global digital commerce revenue alongside domestic video and messaging traffic throughout the intervening period, shielding its equity value from regional property fallout.

    Commercial landlords and retail chains will watch ByteDance’s commercial monetization pacing across Doubao and enterprise AI tools in the coming quarters, alongside Nongfu Spring’s ability to protect core beverage shelf pricing against domestic discounters.