Tag: trend

  • Walmart bets on India despite change in FDI norms

    Walmart bets on India despite change in FDI norms

    American retail giant Walmart and its Indian e-tail major Flipkart are betting big on India despite the revised norms for Foreign Direct Investment (FDI) in e-commerce, the companies said. “Walmart’s and Flipkart’s commitment to India is deep and long term. Despite the recent changes in regulations, we remain optimistic about the country,” the regional Chief Executive Officer of Walmart Asia and Canada Dirk Van den Berghe told IANS in a statement in New Delhi.

    The companies will continue to focus on creating “sustained economic growth and bringing sustainable benefits to India, including employment generation, supporting small businesses and farmers, and growing Indian exports to Walmart’s global markets”, added Berghe, who is also the retail giant’s Executive Vice President.

    Walmart’s assertion on the company’s commitment to India came after American investment bank Morgan Stanley in a report on Monday said the former might exit the country after the new FDI norms in e-commerce came into force on February 1.

    “An exit is likely, not completely out of the question, with the Indian e-commerce market becoming more complicated,” the New York-based financial services firm said in its report titled “Assessing Flipkart Risk to Walmart EPS (earnings per share)”.

    In May last year, Walmart bought 77 percent equity stake in Flipkart for a whopping US$ 16 billion (Rs 1,16,256 crore).

    The revised FDI norms in e-commerce, however, have tightened the noose around the businesses of the country’s leading e-tailers – Walmart-owned Flipkart and Indian arm of American e-commerce giant Amazon.

    The policy revisions, issued by the Ministry of Commerce and Industry on December 26, 2018, barred e-commerce platforms providing a marketplace from exercising control or ownership over the inventory and forbids any company to sell its products exclusively on an e-commerce platforms alone.

    The e-tail companies are now working towards changing the ownership of their inventory, so as to comply with the norms.

  • How technology shape the future of retail in India

    How technology shape the future of retail in India

    The Indian Retail Industry is considered one of the fastest growing industries in the world and technology has emerged as a helping hand to the industry. The world has seen a transition in retail planning –with the industry going from being product-centric to being customer-centric – and retailers are leveraging technologies to reach the modern shoppers.

    Over time, retail technology has transcended from an aspiration to an expectation and has wedged itself securely between consumer and experience to create an everyday interface. While it has definitely made life easier for consumers, retailers in India have spent a better part of the last decade on their heels, reacting to profound changes throughout the sectors of the industry.

    Retailers today are not fighting with retailers anymore; instead they’re fighting with different technological interventions in order to be the most competitive in the world. With growing competition, it has become extremely vital for retailers to innovate continuously and implement cutting-edge technologies to fulfil today’s demanding customers’ need.

    In order to stay relevant in a highly competitive market, every retailer needs to stay on top of technological advances and also learn how to exploit these technical innovations to forward their business goals.

    Over the past few years, a number of technology trends have evolved and dramatically altered the retail industry. The emergence and the transformational growth of the new economy has unleashed powerful forces which are eventually and successfully reshaping the retail industry at a transformational speed. In order to succeed, today’s retailers have to offer a seamless shopping experience across all channels – and should not lose track of their customers.

    Today, the entire retail ecosystem has smartened with technology. There are so many things one can experiment with if a retailer uses technology, for example: smart displays, in-store services, smart shelves, home delivery, brand optimization options, supply chain optimization, logistics automation to name just a few.

    Then there are wallets, point of sale data, social networking – where you can home in on complaints as well as get appreciated. All this is driven by the retailer into applications where the consumer sees, feels, asks the retailer questions and eventually buys the product.

    Giant players of the retail industry have accepted technology with arms wide open to captivate and secure customers and have made optimum use of technology to optimize their business. Whereas small retailers, most of them belonging to the unorganized sector, are yet to adopt technology to be adept with the changes and technological innovations taking place in the retail market. If the entire unorganized retail trade, which is 80 percent of the entire retail trade, adopts technology, the retail industry will usher in a new era providing a much-needed thrust to the Indian economy. Technology is the knight on the white horse that will ride the retail market towards prosperity and triumph.

    What took the year 2018 by storm is phrase ‘Experiential Retail’. It became the code of the moment; delivered through convenient accessibility, in-store features, customer engagement through ATL and BTL animation or out-of-the-box blends of the physical and digital shopping universe.

    Some other trends that impacted the retail industry in a big way in 2018 are:

    IoT (Internet of Things)

    IoT has big implications for in-store marketing efforts of retailers and brands. Connected devices aren’t just changing the way consumers live, work and play – they’re dramatically reshaping the entire industry. The IoT movement offers retailers opportunities in three critical areas: customer experience, supply chain and new channels-revenue streams.

    Leading retailers across the globe are already investing heavily in IoT. They are beginning to transform their business practices and recognize that, in time, IoT will touch nearly every area of retail operations and customer engagement. In the IoT of today, everything has the potential of coming under the IOT umbrella. From the lighting system in the store, the PoS (Point of Sales) system, to the electric switches and even garbage disposal units…IOT is at the heart of retail transformation. It connects people, machines, items, and services to streamline the flow of information, enable real-time decisions, and heighten consumer experiences.

    While the IoT may still seem like science fiction, it is becoming reality faster than most of us can comprehend. Retailers that hesitate to develop and execute an IoT strategy will open the door for competitors – old and new alike – to swoop in and capture early IOT mind and market share.

    SMAC (Social, Mobile, Analytics & Cloud)

    The relationship between consumers and enterprises has never been as intrigued as in the 21st century. As digital technologies augmented by SMAC are creating new touch points for enterprises to awe their consumers, there has been an evolution in consumer experiences. Social, mobile, analytics and cloud or SMAC are the nexus of forces, which are reshaping how consumers experience a brand.

    SMAC are currently driving business innovation. It creates an ecosystem that allows a business to improve its operations and get closer to the customer with minimal overhead and maximum reach. Digital is now an essential part of the whole shopping experience and the entire business of retail, inside as well as outside the store. You don’t need to leave a physical store to get your digital fix. Instead, retailers are leveraging a wide array of in-store technologies meant to draw consumers in the door. As the impact continues to increase, the way retailers think of digital and invest in it, besides addressing the digital wants and needs of their customers is changing dramatically.

    Big Data

    Today, retailers are constantly finding innovative ways to draw insights from the ever-increasing amount of structured and unstructured information available about their customers’ behaviour.

    Data gathering, and analytics are playing a key role in evolving business models in retail. Usage of data and analytics to better understand consumers in the form of branding, product management, leveraging loyalty card information to tracking customer buying behaviour and making better pricing decisions are the key factors. Collecting and leveraging customer information to provide personalized recommendations is the norm going forward.

    Retailers – large and small – have been reaping the benefits of analysing structured data for years but are only just starting to get to grips with unstructured data. There is undoubtedly still a great deal of untapped potential in social media, customer feedback comments, video footage, recorded telephone conversations and locational GPS data. Great benefits have come to those who put it to best work, and the best solutions have more likely come from innovative thinking and approaches to analytics, rather than those who simply try to collect as much data as possible and then see what it does.

    Omnichannel Retail Adaptation

    Omnichannel is a term that extends and supersedes multi-channel. Multi-channel (or cross-channel) refers to delivering content and considering consumer experience on more than one channel. Omnichannel is about understanding and optimizing for the entire journey across all channels.

    Omnichannel today is a necessity. Brick-and-mortar retailers have been left with no option but to add online channel to their offline operations in a bid to reach as many customers as possible, and quickly. Omnichannel retailing creates benefits for consumers and opportunities for retailers. For consumers, it empowers connected consumers by making it easier for them to access information and compare product details; by increasing choice; and by increasing convenience and the range of options for shopping. For retailers Omnichannel creates opportunities, ranging from potential extension of sales and increasing brand awareness and loyalty.

    A poorly executed Omnichannel or personalization strategy, however, can do more harm than good. Handling one or two channels discretely but satisfying expectations is better than disappointing your consumers when you fail to deliver added value — or worse still, confuse or frustrate — while tackling all channels. Personalization can be even more dangerous because of very real risks that your brand can be given the dreaded creepy label.

    To be successful at delivering a personalized experience in Omnichannel marketplace, adaptive content is a requirement. It is content that is designed for both personalization and delivery across many channels.

  • Luxury goes local as Chinese shoppers gravitate towards home-grown brands

    Luxury goes local as Chinese shoppers gravitate towards home-grown brands

    Affluent Chinese consumers have for years shown a preference for global, well-known brands and labels. But with growing sophistication in tastes and a penchant for unique styles, the well-heeled are now increasingly gravitating towards high-end Chinese designers.

    “While global forces will continue to impact China’s luxury market, domestically there’s this whole new wave [of Chinese designers] that is coming through and is transforming the market,” said Simon Tye, executive director of Hong Kong-based market research company Consumer Search Group (CSG).

    In a report released last month along with US and China-based public relations company Ruder Finn Group, CSG found that 74 per cent of affluent Chinese consumers are aware of at least one Chinese designer, and 45 per cent intend to buy more Chinese designs over the next 12 months.

    According to report, titled “The 2019 China Luxury Forecast”, a shift in purchasing attitude from buying to “show-off to outsiders” to a “reflection of personal taste” is evident in 76 per cent of Chinese consumers. These respondents said they buy luxury items that reflect personal taste, up by about 30 per cent since 2012, according to the report.
    According to Mintel China, another market research company, niche luxury brands are particularly popular among women between the ages of 20 and 24, who are single and have a postgraduate or higher degree.

    Karen Zhang, 24, a banking professional from Beijing, said: “I still like my Gucci and Dior bags, but nowadays I like to explore luxury brands that have interesting stories and doesn’t shout extravagance. I also like to buy products by Chinese brands that have a unique twist.”

    The growing interest in Chinese designers is illustrated by a fivefold increase in the number of such brands featured by Hong Kong-headquartered luxury goods store chain Lane Crawford in recent years, according to strategy consultancy OC&C. Comme Moi, a brand founded by Chinese model Lu Yan, is among the fastest growing brands in Lane Crawford stores in China.

    JNBY, regarded as the most commercially successful Chinese designer brand, has more than 1,500 stores worldwide. Angel Chen, known for her colourful approach to fashion and fusion of eastern and western aesthetics, is stocked internationally by 30 retailers, including Lane Crawford, Luisa Via Roma, H. Lorenzo and Dong Liang. She is part of the “new wave” making an impact locally and globally, according to CSG.

    Unlike traditional brands, which spend on large-scale marketing and advertising campaigns, these new brands rely more on their unique designs and the power of celebrities and “key opinion leaders” for publicity.

    “For instance, Chictopia, founded by a local designer, Christine Lau, offers innovative and high-quality products with a clear story theme for each season,” said Veronica Wang, associate partner at OC&C. “The brand is followed by a group of top local celebrities, such as Fan Bingbing and Angelababy, which helps to establish awareness among the young generation.”

    The brand launched an official website in 2016, which provides an online sales channel and allows for the sharing of the brand’s latest collections through WeChat.

    Wilson Li, 28, a Chinese designer, said: “This is a very interesting time [for Chinese designers] right now. Around 20 years ago, Chinese clothing companies produced items that were extremely cheap, and they didn’t care much about quality. But this isn’t the case any more.”

    Li said the US-China trade war was pushing the market to improve its offering: “The only way for Chinese designers and companies to break out is to improve their standards.”

    Li, founder and head designer at Wilson PK, is known for his innovative fabrics and creative knitwear. He said a growing number of Chinese companies had been investing more in research and development as well as quality control over the past 10 years, with the aim of shaking off the image being of “cheap”.

    His brand, which has been around for five years, can count celebrities such as American singer Lady Gaga and British musician Lianne la Havas as its fans.

    “For custom fashion pieces, which are priced between US$960-US$3,830, we usually reach our target consumers through our online look book and stylists,” said Li. “Mass market customers can shop the ready-to-wear collection on our website, with prices starting from US$50.”

    Li, a fashion design graduate of Central Saint Martins Art and Design College, added: “Nowadays, Chinese consumers don’t just want luxury, they want the stories that come with it.”

    Industry experts say it is important for niche luxury brands to maintain a sense of exclusivity and rarity through storytelling. Scarlett Zhao, associate research analyst at Mintel China, said: “Niche brand lovers tend to be better informed and are willing to pay more for a brand’s unique meaning.”

    According to these experts, the biggest competitive edge Chinese designers have is their understanding of local preferences. And according to Wilson PK’s LI, while it is too early for local designers to be considered as rivals to established global fashion houses, there are more opportunities for Chinese brands in the current market.

    “Let’s be honest, calling it a competition would be too difficult. But as a Chinese designer, I definitely want to liberate my own culture,” he said.

  • Online grocery space likely to witness traction: Nielsen

    Online grocery space likely to witness traction: Nielsen

    With consumers being increasingly preferring digital channels for their purchases, the online grocery space is likely to witness traction, according to market research firm Nielsen. Grocery is definitely going to start seeing traction as e-commerce picks up, Nielsen Executive Director Ajay Macaden said at the India Food Forum here. He, however, did not quantify the size of online grocery market.

    As per reports the online grocery market in India is expected to be US$ 5 billion by 2020, from US$ 1 billion in 2017.

    Macaden noted that packaged grocery is 40 percent in India versus a global average of 30 percent, while fresh groceries is around 41 percent against a global average of 26 percent which indicates that people are definitely picking up food online.

    Rs 3.4 lakh crore Indian FMCG industry is growing at 14 percent, is largely dominated by food that accounts for 55 percent (Rs 2.2 lakh crore growing at 15.1 per cent).

    In terms of contribution, general trade accounts for 90 percent of FMCG sales, growing at 13 percent, while the remaining 10 percent is from modern trade that is growing at 22 percent.

    In the food category, general trade accounts for 90.1 percent at a growth rate of 14.7 percent, while modern trade is growing at 19 percent.

    He observed that the FMCG industry which grew at 13.8 percent growth in 2018 was largely a volume led growth that was 77 percent of the total growth.

  • Optimistic about Indian market despite changes in new FDI policy: Walmart

    Optimistic about Indian market despite changes in new FDI policy: Walmart

    US retail major Walmart, which invested $16 billion in Flipkart, Wednesday said it is committed to the Indian market and is optimistic despite recent changes in the FDI policy for e-commerce firms in the country, according to a PTI report. The Bentonville-based retailing major’s statement came after a recent report by global consultancy firm Morgan Stanley, which had hinted that Walmart may quit Flipkart as the new foreign direct investment (FDI) policy came into effect, which would lower its profitability in the long run.

    Morgan Stanley, in a report titled ‘Assessing Flipkart Risk to Walmart EPS’ dated February 4, claimed that “an exit is likely, not completely out of the question, with the Indian e-commerce market becoming more complicated.”

    “Walmart’s and Flipkart’s commitment to India is deep and long term. Despite the recent changes in regulations, we remain optimistic about the country,” said Dirk Van den Berghe, Executive Vice President and Regional CEO Walmart Asia and Canada.

    He further added, “We will continue to focus on serving customers, creating sustained economic growth and bringing sustainable benefits to the country, including employment generation, supporting small businesses and farmers, and growing Indian exports to Walmart’s global markets.”

    Tightening norms for e-commerce firms having foreign investment, the government, from February 1, barred online marketplaces like Flipkart and Amazon from selling products of companies where they hold stakes and banned exclusive marketing arrangements that could influence product price.

    The revised policy on FDI in online retail, issued by the commerce and industry ministry, also said that these firms have to offer equal services or facilities to all its vendors without discrimination.

    Last year on August 18, Walmart had completed acquisition of 77 per cent stake in Flipkart for about $16 billion (Rs 1.05 lakh crore), a deal which gave the US retailer access to the Indian e-commerce market.

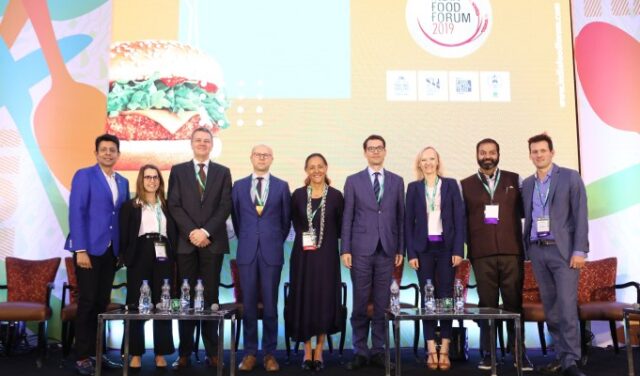
  • India Food Forum 2019: Alliance avenues with foreign partners to expand food market in India

    India Food Forum 2019: Alliance avenues with foreign partners to expand food market in India

    India Food Forum 2019 identified avenues for partnerships in food, beverages and food service industry with Ambassadors, Trade Commissioners and Consul Generals of several countries and highlighted how Embassies and Trade Commissions can play a more pro-active role to facilitate such alliances. Emerging as major market of the world, India offers huge opportunities for manufacturers, producers and providers of products and services from across the globe to sell here or partner with Indian companies to serve this market.

    Acceptance of multinational culture, a growing taste for foods from across the globe, increasing inflow of foreign nationals, willingness to experiment new cuisines and more over avenues to market new products further add to the opportunity.

    The session was moderated by Amit Lohani, Convener, FIFI.

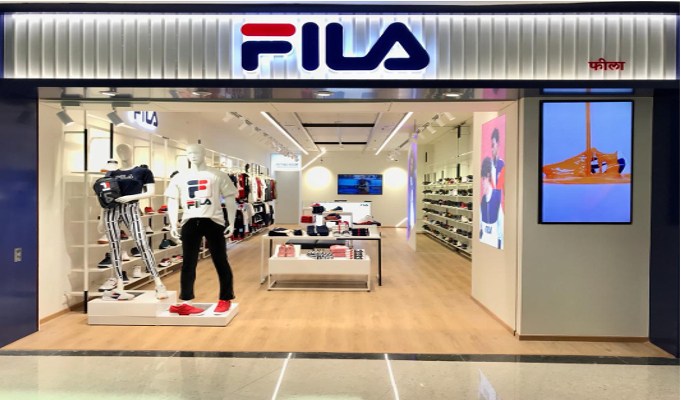
  • Fila to open 100 exclusive retail stores in India over the next 5 years

    Fila to open 100 exclusive retail stores in India over the next 5 years

    Fila India, owned by Cravatex Brands Limited, the Indian arm of the $150 million Batra Group, is adopting an aggressive expansion strategy in India. 2018 saw the comeback of sports brands, both globally and in India, due to the shift in consumer preference towards sports inspired athleisure clothing. A key player in the Indian market, Italian sports and fashion brand Fila has planned to capitalize on this trend and strengthen its presence in the country with an aggressive expansion strategy. The brand is projecting sales to grow more than 50 percent by the end of this financial year.

    As part of the new Heritage Store format, Fila has been opening one store a month and expects to keep this momentum going in 2019. The next 3 months will see stores coming up in Mumbai, Bhubaneswar, Baroda and Chennai among other cities. The focus will be skewed largely towards Fila Heritage format stores, driving fashion lifestyle imagery in the premium sportswear segment with a global Heritage collection across footwear, apparel and accessories.

    Aside from main metros and mini metros, Fila has set its sights on the North Indian market with a focus across Delhi, Gurgaon, Noida, and the entire region of Punjab; followed by South India. While company owned stores will be the primary objective, the brand is identifying some key partners to pursue a franchise model.

    Maintaining uniformity across layout and design, the average store size is expected to be between 1000-1200 sq feet carpet area with larger flagship locations in metros.

    Speaking on the strategy, Rakesh Singh Kathayat, Chief Operating Officer, Cravatex Brands said, “The resurgence of sportswear in mainstream fashion is the most relevant conversation in the industry today, particularly among millennials and Gen Z. Fila’s retro aesthetic and nostalgia-tinged DNA has thus, gained relevance and this conversation has supplemented its evolution into a sports fashion label. While we’re steadily making this progression in perception, supplementing consumer demand with supply is the need of the hour. Our offline retail growth in India focuses on strengthening our pan-India presence to create easier access and increased engagement with our growing consumer base.”

    Fila India is a licensee held by Cravatex Brands Limited which is a part of the Batra Group, a Global Retail, Brand Licensing, Distribution and Sourcing company with a presence across the Indian Subcontinent, United Kingdom, Europe, North Africa and the Middle East.

  • Ride-Hailing Firms Enjoy Growth in Indonesia, but Face Fraud Challenge

    Ride-Hailing Firms Enjoy Growth in Indonesia, but Face Fraud Challenge

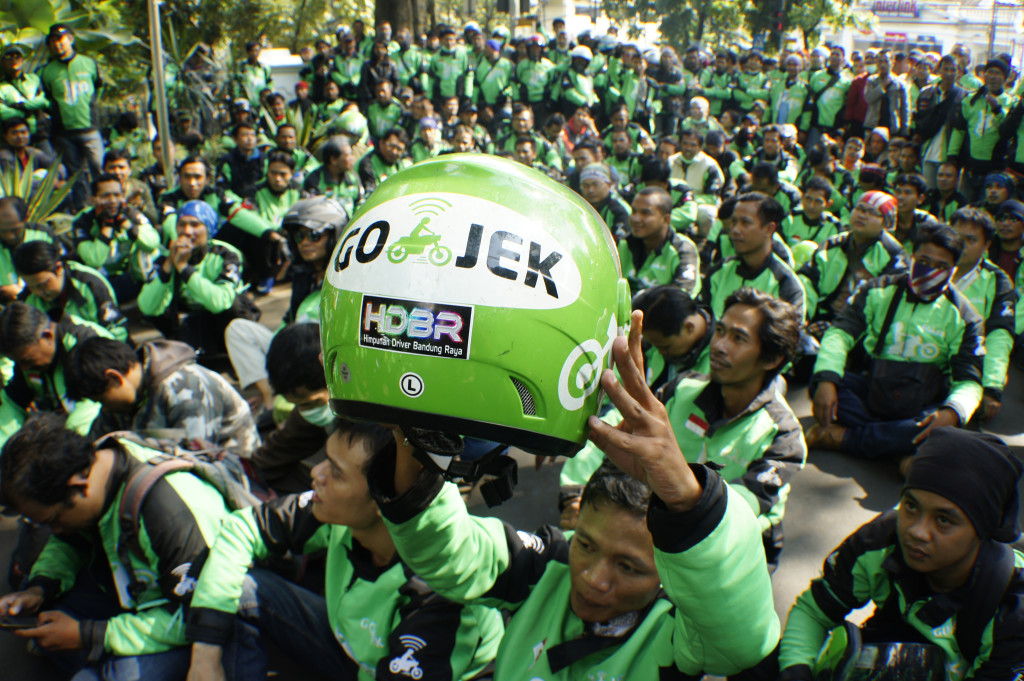
    Grab and Go-Jek, two of Southeast Asia’s biggest technology startups, have successfully grown their food delivery and ride-hailing services, but both must pay special attention to better detection of fraudulent orders, a recent study by Spire Research and Consulting Indonesia showed.

    The local unit of the Tokyo-based research company surveyed driver partners and customers to establish what ride-hailing services they prefer, based on various criteria, including consumer awareness, usage frequency and the use of e-money.

    Grab Leads in Product Usage

    Based on Spire’s consumer awareness survey, 75 percent of respondents said they used Grab’s services over the past six months, while 61 percent indicated that they had done so in the past three months.

    For Go-Jek, it was 62 percent and 58 percent, respectively.

    “Regardless, 50 percent of respondents agree that both Grab and Go-Jek are their favorite brands,” the consultancy said.

    Regarding product usage frequency, customers more often used Grab’s services than those of Go-Jek in the last quarter of 2018.

    The survey also found that 34 percent of GrabCar customers were more likely to use the service three to four times a week on average, while for Go-Car, 25 percent of customers were more likely to use the service once or twice a week on an average.

    Grab Leads in Four-Wheel Segment, Go-Jek Leads in Two-Wheel

    On the other spectrum of the survey, it found that Go-Jek’s Go-Ride was still the customer favorite, with 64 percent saying that they use the service once or twice a day, while for Grab it was 58 percent.

    “When it comes to food delivery, Go-Food is in the lead with 35 percent of respondents saying Go-Food was the brand they most often used, but Grab is catching up quickly with 27 percent saying they used GrabFood the most,” Spire said in a press release on Tuesday.

    E-Money

    As of 2018, both services introduced the use of e-money to facilitate digital payments.

    Grab launched an e-payment service in cooperation with OVO, while Go-Jek established its own, Go-Pay.

    “Based on the survey results, OVO usage exhibits strong O2O [online-to-offline] usage, while Go-Pay’s strength is in Go-Jek’s mobile app ecosystem. For example, OVO is the preferred payment for offline items like phone balance, parking bills and bills for nonfood merchants, while Go-Pay is used to pay food-merchant bills [Go-Food] and electricity bills through the Go-Jek app,” Spire said in the statement.

    Natural Selection

    Indonesia has seen monumental growth in the ride-hailing sector over the past few years, with the mergence of dozens of startup companies. However, natural selection resulted in only two surviving and dominating the market.

    Indonesia is still a magnet for tech companies, including ride-hailing services, thanks to the high consumption rate and mobility of its citizens.

    The two survivors have seen intense competition, with both drastically increasing their product offerings.

    Their services such as food delivery and ride-hailing are similar in nature, but the two companies’ more unique offerings are distinguishing factors.

    Fraud

    Spire said the most interesting finding of its study was the prevalence of fraud.

    “The most interesting finding by Spire is the existence of fraud and how the drivers perceive it,” Jeffrey Bahar, group deputy chief executive of Spire Research and Consulting, said in the statement.

    Spire said fraud in online ride-hailing services is an open secret among drivers and that most who commit it gave similar reasons for doing so, which is to increase their monthly earnings.

    Fraud is seen as a major threat to the industry as it results in economic losses to the companies and highlights vulnerabilities in their systems.

    Spire’s research showed that nearly 30 percent of Go-Jek’s total transportation orders might be fraudulent, compared with 5 percent for Grab.

    “This is based on an estimation of fraudulent orders against total orders. This is a systemic problem for both companies and one that Go-Jek needs to address,” Spire said in the statement.

    According to Spire’s driver survey, “as of 2018, nearly 60 percent of Go-Jek’s drivers say they commit fraud on a daily basis to boost their order numbers, which affect their bonuses and daily income.”

    The drivers who were surveyed said Go-Jek’s system was easier to trick by using applications that modify their location data. On the other hand, less than 10 percent of Grab’s drivers admitted to committing fraud.

    Grab’s drivers said the company’s system was not easy to trick and that the sanctions imposed for such offenses was a deterrent. Drivers also commented that both companies had been improving their systems to better detect fraud.

    “Overall, both companies are growing rapidly in food delivery and ride-hailing but special attention must be paid to the issue of fraud to ensure the healthy development of the technology ecosystem in the country,” Spire said.

  • Snapdeal bats for new FDI policy in e-commerce from Feb 1

    Snapdeal bats for new FDI policy in e-commerce from Feb 1

    Leading Indian e-tailer Snapdeal on Tuesday supported the implementation of revised Foreign Direct Investment (FDI) policy on e-commerce from February 1. “Snapdeal supports the immediate implementation of the current FDI policy on e-commerce so that marketplaces are not misused to run inventory operations,” Delhi-based Snapdeal told IANS in a statement.

    The Ministry of Commerce and Industry on December 26 issued revised policy guidelines on FDI in e-commerce.

    The policy revision, which will be in force from February 1, dictates that e-commerce platforms providing a marketplace will not exercise control or ownership over the inventory.

    E-tail majors Flipkart and American online retailer Amazon’s Indian arm, however, sought an extension on the implementation of the new norms, amid protesting voices from retail traders’ bodies against granting the extension.

    “Government policy changes will have long-term implications in the evolution of the promising sector and the whole ecosystem,” American retail giant Walmart-owned Flipkart told IANS through a statement earlier.

    The new norms also barred e-tail firms from allowing any company to sell its products exclusively on their e-commerce platforms alone.

    While Amazon India had said in a statement to IANS that “it has always operated in compliance with the laws of the land”, it did not respond to queries on the changes it may have to make to its business model to suit the new norms.

    On the other hand, the Confederation of All India Traders (CAIT) has asserted that delaying the execution of the policy will allow the e-tailers to continue with their “dominance over retail trade”.

    “The modus operandi of these e-commerce companies for seeking extension (on implementation of new FDI norms) is to keep delaying fair execution of the policy,” CAIT wrote in a letter to the Ministry of Commerce and Industry this month.

    “They (e-commerce platforms) may continue with their sinister designs of operating all kinds of malpractice including predatory pricing, deep discounting and exclusivity, in order to ensure their control and dominance over retail trade and wipe out the competition,” the letter said.

    The Ministry, however, has not indicated any possible extension of deadline to implement the new norms.

  • SUVs, Crossovers dominate high-end segment in Vietnam

    SUVs, Crossovers dominate high-end segment in Vietnam

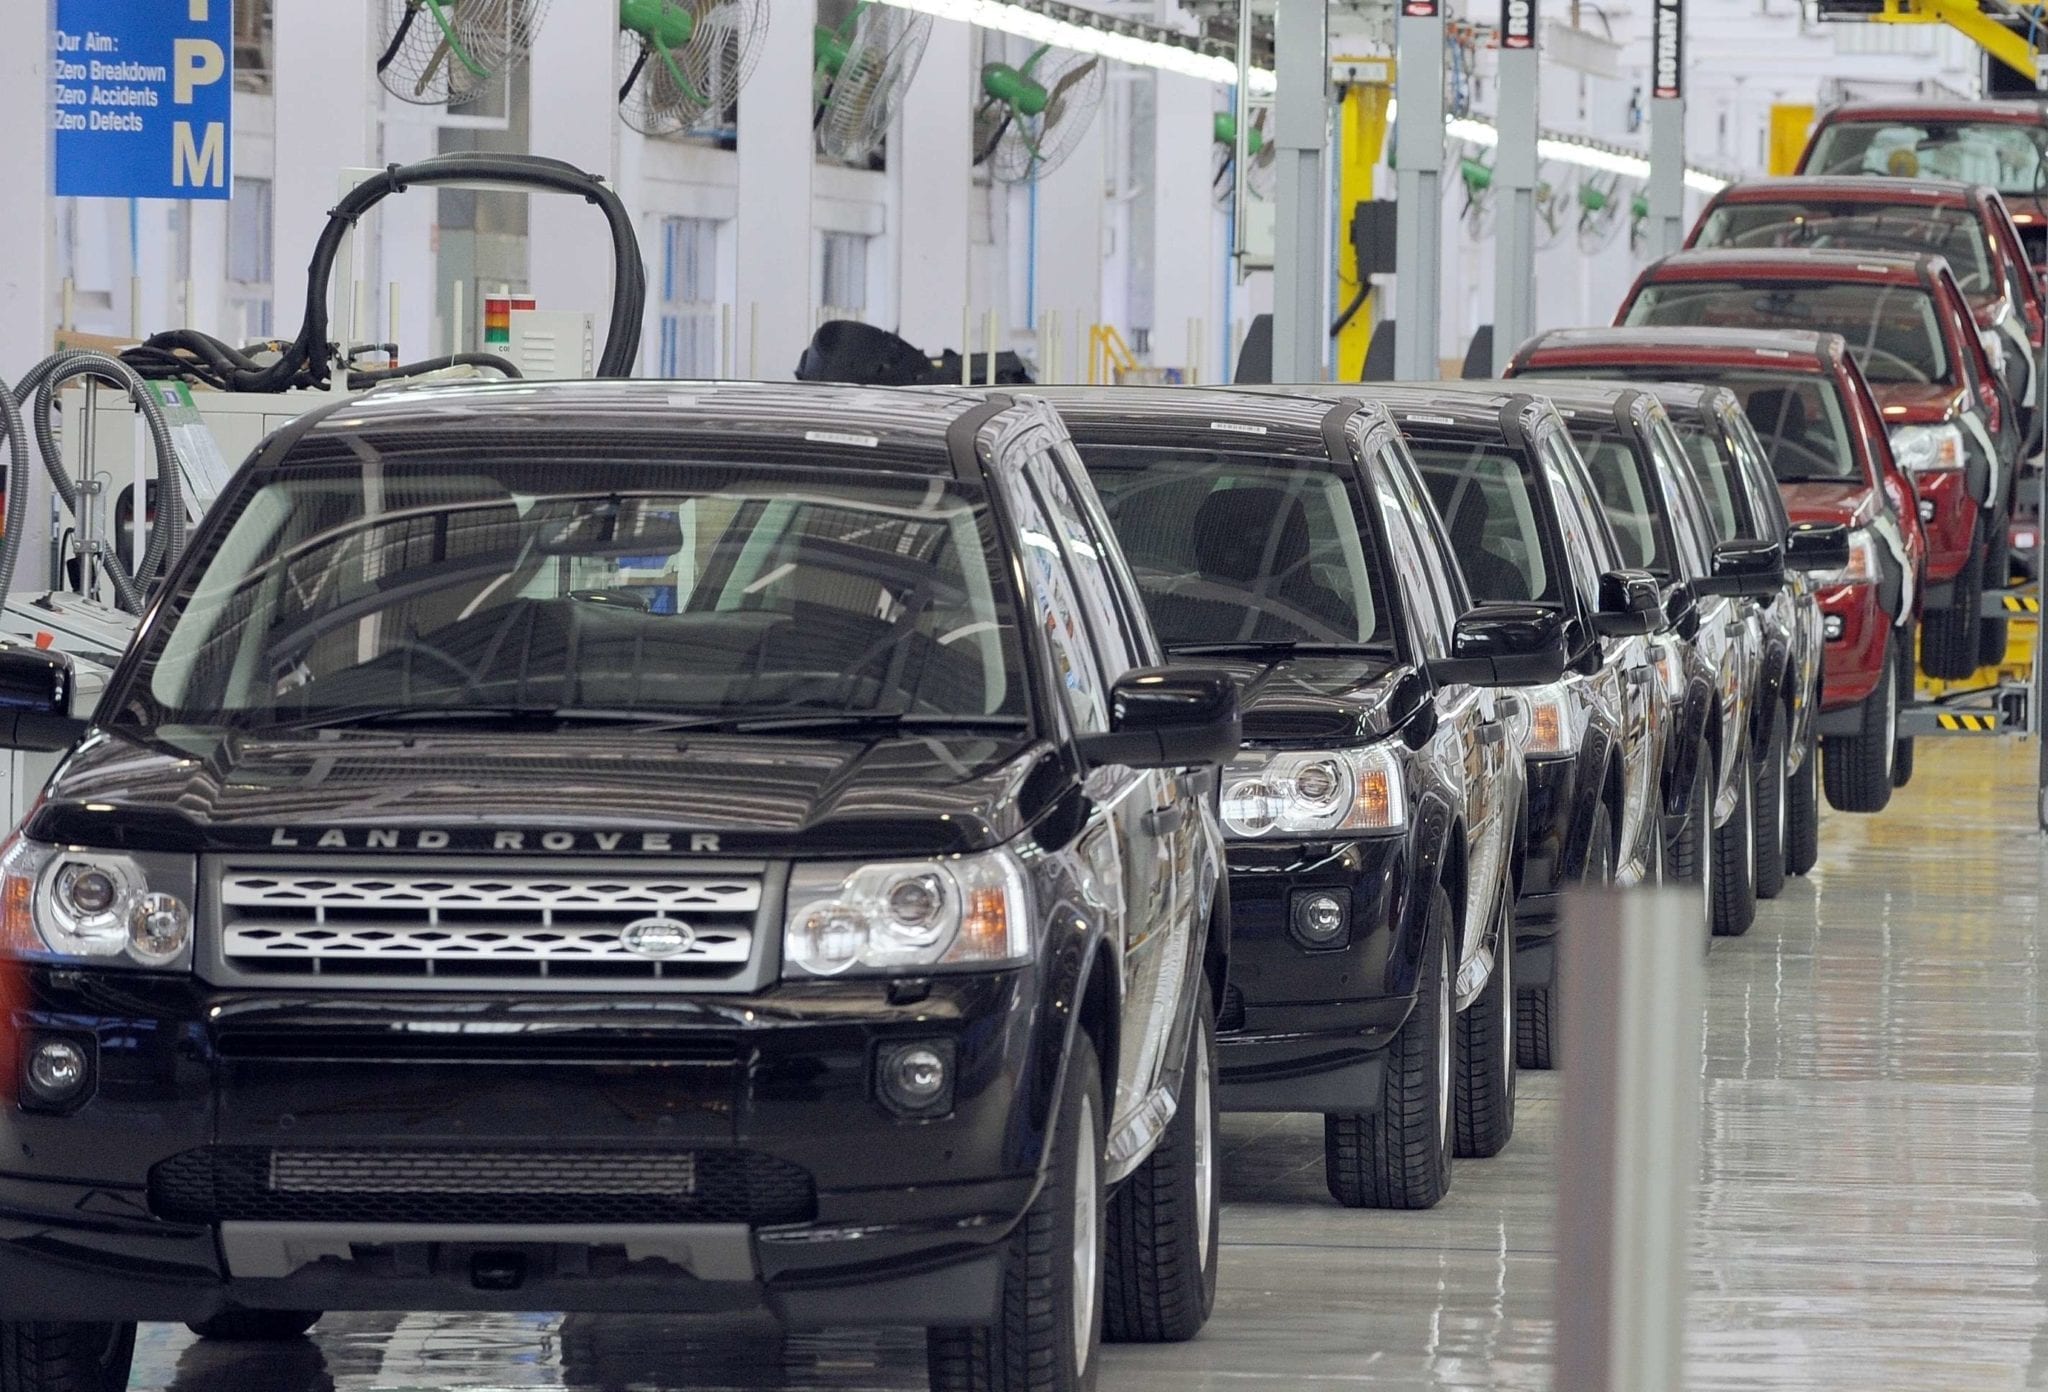
    Among consumers willing to spend at least VND1 billion ($43,135), the preference is for SUVs and Crossovers over sedans. In recent years, high ground clearance vehicles have gradually become the number one choice for the majority of Vietnamese consumers, having grown steadily in number sales and variety over the years. In contrast, the D-class sedan segment has seen low demand and limited variety.

    Sales of SUV and Crossovers (CUV) vehicles around the price of VND1 billion ($43,135) have risen steadily over the years. While 2014 saw only around 13,000 units sold, sales had more than doubled by 2018 at 24,264 units. 2018 only saw a slight increase over 2017, but this was because a decree on import conditions prevented many firms from importing these vehicles for most of the year.

    According to the Vietnam Automobile Manufacturers’ Association (VAMA), consumers have a choice of 10 SUV/CUVs in the VND1 billion price range. Car dealers have noted that almost all brands in Vietnam have at least one product in the SUV/CUV segment.

    Average sales per model was around 3,100 vehicles a year.

    Th SUV/CUV segment is predicted to boom in 2019, as firms get used to the new regulation and find stability in importing new vehicles.

    Meanwhile, from 2014 up to now, the D-size sedan segment has featured the same models, namely, Toyota Camry, Mazda6, Honda Accord, Nissan Teana and the Kia Optima, which was introduced last year.

    In the last 5 years, sales of D-size sedans reached a peak in 2016 at 8,148 units. The introduction of the Kia Optima in 2018 raised the number of models in the segment to 6, but annual sales fell to only 7,612 units.

    In 2018, Toyota Camry dominated the D-segment at over half of the 4,503 units sold, while the remaining models saw little growth. Total sales have nevertheless been fairly stable, hovering around 6,000 or 7,000 over the years.

    Vietnam’s total car sales increased 5.8 percent to 288,683 units in 2018 from a year ago, according to the Vietnam Automobile Manufacturers’ Association (VAMA).

  • 5 Tips for Digital Transformation

    5 Tips for Digital Transformation

    Retailers know they need to evolve, even though they cannot do it overnight. But while there’s no silver bullet for transforming culture, collaboration, and workflows inside a large organization, there are steps you can take to make sure your business is receptive to the change it’s about to undergo.

    Understand performance goals

    Before you start, you need to understand the business problem and the role that technology is going to play. Solving complex organizational issues needs the relentless management of changes in behavior, process, and technology all working together to support your performance goals and objectives.

    Collaboration is not a KPI

    Decide how you’re going to measure your KPIs. And remember that collaboration is not a KPI – it’s a means to an end. KPIs could include customer satisfaction, getting products to store faster, selling more products per visit, or retention. You need to get down to that granular detail.

    Shut things off

    If you have an existing tool which people did not like and you invest in something new to overcome those challenges and frustrations, you need to have a path to turning that tool off or at least turning off the elements that are now conflicting. This will impact adoption of new tools and ways of working.

    Educate, educate, educate

    Launching a tool is the easy part, the real work begins when people use it. People need to be educated on what they should be using it for. Show some examples of what ‘good’ looks like, and also what the tool should not be used for. Design an internal marketing campaign and treat it exactly the same as an external campaign. A product-driven approach could help here. Think about how companies try to refresh products in the market over time to improve adoption.

    Put somebody in charge

    For any system, and especially for a collaborative experience, you need someone who can get employees to use the tool in the right way at different times. That might be a community manager who understands the business cycle. Putting up content is the single most important driver of getting people to use the platform and to entice them to contribute their own.

  • Who visited Korea in 2018?

    Who visited Korea in 2018?

    Chinese visitor arrivals in South Korea rose 14.9 percent year-on-year in 2018 to 4,789,512, according to new Korea Tourism Organization figures. Chinese arrivals in December 2018 rose 25.2 percent year-on-year. The results confirm a sustained recovery in Chinese tourism from March 2018 as Korean-Chinese relationships improved in the wake of the THAAD anti-missile system dispute that had devastated Chinese tourism for the previous year.

    For the first two months of 2018 Chinese arrivals slumped 43.7 percent, heavily influencing the year-end result.

    However, the 2018 performance was still far short of pre-THAAD levels. In 2016, 8,067,722 Chinese visited South Korea, 68 percent more than the 2018 tally and a 46.8 percent share of total arrivals, compared to last year’s 31.2 percent.

    Japanese market buoyant but political concerns rise

    The Japanese tourism market was buoyant in 2018, rising 27.6 percent to 2,948,527, a 19.2 percent share of arrivals. December saw a 33.5 percent rise year-on-year.

    The combination of concerted Japanese visitor growth and a strong yen has been reflected in increased duty free spending. A report by The Korea Herald said that January 2019 sales to Japanese consumers at Lotte Duty Free’s flagship store in Myeong-dong, Seoul (the country’s biggest travel retail door) had surged 31 percent year-on-year, compared to 15 percent for all nationalities.

    The same report said that Shinsegae Duty Free’s Myeong-dong store posted a 53 percent rise in sales to Japanese shoppers during the same period, while overall turnover at the flagship fell 1 percent.

    But prospects for a continued boom in Japanese tourism may be marred by a worsening political dispute, this time between South Korea and Japan. A military row began on 20 December following an encounter between a Japanese plane and a South Korean destroyer.

    The Japanese claimed that the South Korean warship aimed its fire-control radar at the aircraft while the Koreans contend that the ship was rescuing a North Korean ship drifting in international waters.

    Several more ‘fly-buy’ incidents since then have escalated tensions, leading to fears that the row could “snowball into crisis”, as CNN wrote.

    Departures of Korean nationals (along with Chinese and Japanese the key components of the Korean travel retail industry consumer mix) rose 8.3 percent year-on-year in 2018 to 28,695,983 and 3.8 percent in December to 2,495,279. The year ended much weaker than it began – five of the first six months saw double-digit increases, all of the final six months were under 6 percent.

  • Place to reate your own watch

    Place to reate your own watch

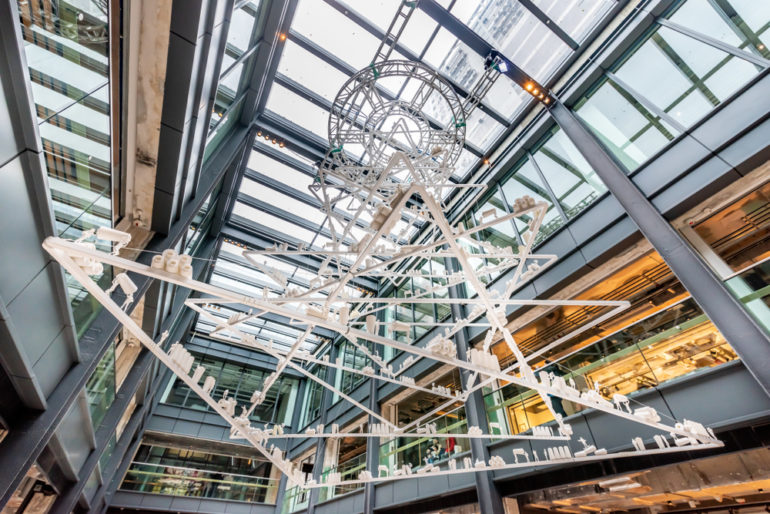
    The Mills officially opened at the end of 2018, becoming a new landmark that combines historical and cultural retailing, attracting a number of local brands in Hong Kong. The Mills is a revitalization project from Nan Fung Group scheduled for completion and actually completed in 2018. A destination consisting of a business incubator, experiential retail, and a non-profit cultural institution may be relatively unfamiliar to Hong Kong people; yet The Mills’ vision and history is a purely Hong Kong story.

    It witnessed the manufacturing heyday in the 1960s, and now it carries the legacy towards a future of applied creativity and innovation. Visitors can explore the continuity of an authentic Hong Kong story, where themes of textile and industry are woven into experiences of innovation, culture, and learning.

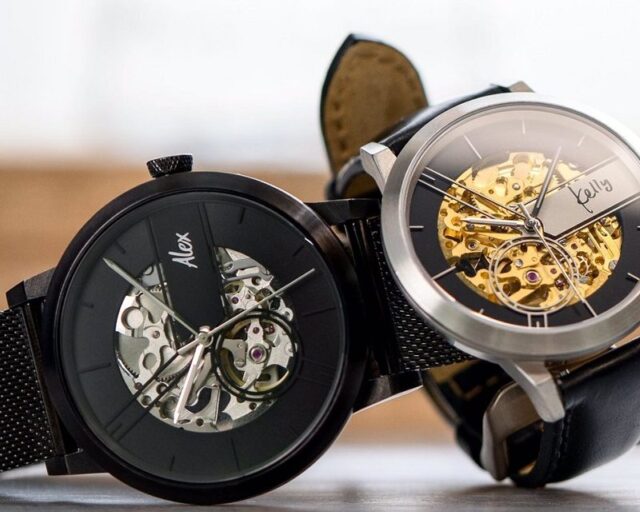
    Eoniq successfully raised funds for launching a project a few years ago on the Indiegogo crowdfunding network, which is for customers to make their own personalized unique watches at The Mills. Through engaging in different workshops such as designing automatic tourbillon, printing dial and burning blue steel pointer, customers may experience the watchmaking process.

    In recent years, Swiss watchmaking brands have opened shops all over Hong Kong, however, the Hong Kong local watch industry has also had a glorious history during the 1950 – 1980.

    Although local watchmaking has already faded out, Li Junguo (Quinn), one of Eoniq’s founders, decided to set up his own brand with two partners in 2014.

    “I started building up the brand after I left my work at McKinsey since 2011. It is because I am interested in watchmaking, so I find some fine caliber factory online, and  contact the French freelancer to help me ordering from France as the people from Swiss watch factory usually only speak in French,” he said.

    After buying the caliber from the factory, the brand will assemble the watch according to the custom design of the guests.

    In fact, Eoniq had opened stores in Sheung Wan and Tsim Sha Tsui K11 before, but the shop could hardly afford a monthly rental fee of 1 million HKD in Tsim Sha Tsui.

    In terms of online sales, Eoniq’s customer profile is diversified and located in different regions, namely, Taiwan, Malaysia, Australia, the United States, and Europe.

    “The Mills was interested in Eoniq, knowing that we were assembling the watchmaking on our own, and asked if we could make the watchmaking process transparent so that the visitors could see the process of watchmaking. Thus, we have been given a space on the ground floor at The Mills, which became our current flagship store.”

    For the Automatic Tourbillon design workshop, customers can engrave their name, special phrase, signature or pattern on the watch. With the assistance of a watchmaker, guests can assemble the watch by themselves.

    Guests can also add personal elements to the dial, such as handwritten words or patterns, and there is a traditional printing machine to allow customers experiencing the traditional printing method on the surface of the watches.

    “Our brand is getting bigger, so I hired more masters in watches, including a watchmaker who had previously worked in Omega. In addition to allowing our guests to design their own watches, we want to let more people understand the value of watchmaking.”

  • Handsome markets brands in Paris Fashion Week

    Handsome markets brands in Paris Fashion Week

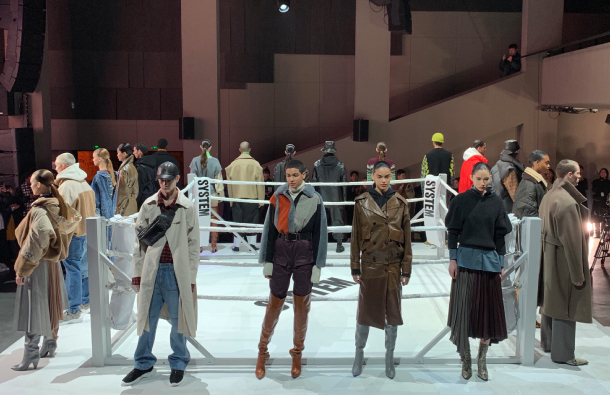
    Handsome, a Korean fashion brand owned by Hyundai Department Store, brought two of its labels to Paris Fashion Week in an effort to expand on the global stage. System for Women and System Homme, the two Handsome brands, showcased their fall and winter collections in a rented showroom for eight days starting from Jan. 17. The Handsome event included a presentation of the collections followed by showroom events, where item were modeled for clients.

    The brands are presenting their new collection one season early to major buyers in the fashion industry.

    In addition to 180 buyers, the event was attended by the Wall Street Journal, Vogue and GQ as well as by fashion influencers.

    It was the first time Handsome has taken its brands to a foreign showroom since being founded in 1987.

    System for Women debuted in 1990 and System Homme in 2008. The company has also introduced other names, including Time, Mine and SJSJ.

    Handsome was acquired by Hyundai Department Store Group in 2012.

    At the Paris event, which featured 200 items for men and women, around 40 department stores from 14 countries participated. Samples were purchased ahead of possible quantity orders.

    It was a buyers’ who’s who. The list included representatives from Bloomingdales, France’s Le Bon Marche, Hong Kong’s Lane Crawford, Japan’s Isetan and Shanghai’s 10 Corso Como. Inquiries also came in from parties in Switzerland and Israel.

    “We predicted the number of businesses that would visit our showroom would be 40 at maximum. But since System Homme was introduced via major media outlets and social media after the presentation on Jan. 18, a great number of fashion businesspeople visited,” said a source from Handsome.

    The company said that visitors appreciated the designs as being unique and set apart from other major Asian brands.

    “In the case of businesses that received the samples, they will decide on quantity purchases in February, and in June, the main products of System [for Women] and System Homme will be sold at department stores and in multibrand shops of each country,” said a source from Handsome.

    Handsome is planning to use the Paris showroom event as a stepping stone for its international expansion efforts.

    In line with the strategy, it will complete its product development earlier and present new design concepts to the market one season ahead.

    It is rare for a ready-made brand to utilize this sort of advanced development.

    “Our brand is still new in the global fashion market, but we will elevate awareness to the point where we could open an exclusive fashion show at a foreign fashion week,” said Kim Hyung-jong, the CEO of Handsome.

  • Grofers crosses Rs 300 cr sales in single month

    Grofers crosses Rs 300 cr sales in single month

    Grofers, the low price online supermarket, announced the record revenue of Rs 310 crore in January 2019. With this, Grofers became the first online grocer to cross Rs 300 crore in monthly sales and also became the largest e-grocery company in the fast growing space. Aligned with its aim to drive the next wave of growth for e-commerce sector, the company has brought 2.5 lac new customers to its platform in January. The brand is eyeing a revenue target of Rs 2,500 crore for FY 2019.

    On the back of the industry’s biggest grocery sale – Grand Orange Bag Days, Grofers recorded an average of 14 lakh visits per day on the app. During this period, a total of 1.81 crore items worth Rs 207.5 crore were sold. With an average ticket size of Rs 2,640 and 20 items per cart, Grofers recorded highest customer engagement in Delhi NCR followed by Mumbai and Bengaluru.

    Speaking on the success Albinder Dhindsa, Co-Founder and CEO, Grofers said, “We are excited to emerge as India’s favourite e-grocer. We have received a tremendous response in the Grofers Orange Bag Days sale and we will sustain the momentum going forward. We are geared to bringing better priced grocery products to 100 million customers and this is just the start.”

    Customers received jaw dropping offers during Grofers Grand Orange Bag Days sale. Grocery and staples were the highest selling items followed by household items (detergents and dishwash bars) and personal care products. During this time period, Grofers recorded a 80 percent increase sales of Grofers branded products as well.